

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The China paraxylene market is projected to grow at a CAGR of 6.50% between 2026 and 2035. The market is being driven by the thriving textile sector in the country.
Compound Annual Growth Rate
6.5%
2026-2035
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The textile sector in China represents more than 20% of the nation's overall industrial production Additionally, the textile sector contributes over 7% to the national GDP. Paraxylene plays a crucial role in this sector as it is used to produce PTA, which is essential for the manufacture of polyester fibres. These fibres are vital for a diverse array of textile products, ranging from everyday apparel to specialised industrial materials. Furthermore, advancements in recycling technologies and sustainable practices are increasingly influencing the utilisation of paraxylene within the textile sector.
The packaging sector in China is anticipated to significantly grow in the forecast period. The growth of the e-commerce sector is anticipated to further enhance the expansion of the packaging sector in the region. As the largest e-commerce market in the world, China accounts for nearly 50% of global transactions. Paraxylene plays a crucial role in the packaging sector, as it is utilised in the production of PTA, a fundamental component in PET. The advantageous characteristics of PET, including its clarity, strength, and barrier performance, render it suitable for a diverse array of packaging applications, ranging from beverage containers to flexible films. The increasing emphasis on sustainability and recycling is influencing the future utilisation of PET within the packaging sector.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
China’s paraxylene market saw operating rates recover in September as several production units returned from maintenance. PX operating rates reached 78.7% by September 17, up 1.9 percentage points week on week, according to industry data. Urumqi Petrochemical’s 1 million tonnes/year PX unit restarted on September 17, while Yangzi Petrochemical’s 890,000 tonnes/year unit was scheduled for phased restarts in late September and October. Hainan Refining’s 1.66 million tonnes/year unit was expected to restart around mid-October. The restarts are increasing domestic PX availability after extended maintenance.
China increased paraxylene imports in July as extensive domestic maintenance reduced local availability. PX imports reached 512,621 tonnes, rising 6.4% month on month, as PTA producers relied more heavily on overseas material to meet operating requirements. Domestic PX capacity offline for maintenance reached approximately 1.133 million tonnes during July. Major affected facilities included Shenghong Petrochemical’s 4 million tonnes/year, Dongying Weilian’s 1.96 million tonnes/year, Fujian Fuhaichuang’s 1.6 million tonnes/year and Ningbo Zhongjin’s 1.6 million tonnes/year plants. The maintenance-driven supply gap directly increased China's short-term dependence on imported PX.
Sinopec settled its May paraxylene contract price at CNY 9,530 per tonne, representing a 2.4% month-on-month decline, as weak downstream polyester demand offset concerns over tighter PX supply. Sinopec had initially nominated the May PX contract price at CNY 9,900 per tonne because of planned PX plant maintenance, naphtha shortages and potential shipping disruptions. However, Chinese polyester plant operating rates averaged only 81.8% at the end of May, 11 percentage points below the previous year. Domestic PX prices also declined 12.2% month on month to CNY 8,785/tonne on May 29.
China’s Zhengzhou Commodity Exchange introduced overseas trader participation in paraxylene futures and related polyester-chain contracts from May 22, 2026, following approval from the China Securities Regulatory Commission. The programme covers PX futures from the PX2606 contract onward, along with subsequent PX options. Overseas traders can also use US dollars as margin, subject to a 5% valuation haircut based on the RMB central parity rate. The development expands international participation in China’s domestic PX price-discovery mechanism and provides overseas market participants with a more direct route to manage exposure to Chinese paraxylene prices.
With more new projects in the area of integrated refining and petrochemical industry taking place, China is gradually heading towards increasing self-sufficiency in domestic paraxylene production. However, the process is gradual due to large amounts of excess capacity in PTA compared to PX capacity. At the beginning of 2026, China had approximately 45-50 million tons of PX capacity and 87-88 million tons of PTA capacity. In spite of the increase in domestic capacity, China imported 9.61 million tons of PX in 2025, which was an increase of 2.41% from the 9.38 million tons of 2024.
A notable feature of China's PX market is the divergence between upstream and downstream capacity conditions. PTA capacity expanded more rapidly than PX production in recent years, keeping PX fundamentals comparatively tighter even as the PTA sector faces overcapacity. China's polyester operating rate averaged 90.11% during 2025 through mid-December, supporting substantial consumption of PTA and, consequently, PX. At the same time, Chinese PTA margins declined to approximately CNY 180-200 per tonne in mid-December 2025, compared with an average of CNY 280 per tonne in 2024. This imbalance is keeping PX supply-demand fundamentals firmer than those of downstream PTA.
The PX industry in China is still going to prefer building large scale integrated complexes where crude oil processing, aromatic extraction, PX and PTA production will be integrated. This gives more control for producers to have feedstock supply and optimize production on several stages of the value chain. It becomes especially critical because capacity of petrochemicals keeps growing although domestic demand remains weak. ICIS reported that China's broader petrochemical capacity expansion remained strong in 2026, while producers were increasingly focused on supply-chain optimisation amid geopolitical disruptions. For PX producers, integration can reduce exposure to external feedstock purchases and improve flexibility when crude, naphtha or aromatics prices become volatile.
China's paraxylene market continues to maintain substantial international trade flows because domestic consumption remains large relative to available production. PX imports increased from 9.38 million tonnes in 2024 to 9.61 million tonnes in 2025, despite China's substantial domestic production base. The persistence of imports reflects the scale of China's polyester and PTA industries and the timing mismatch between new PX capacity and downstream requirements. S&P Global expects China's import appetite to remain significant through 2026, even as new domestic plants are scheduled to come online. This creates continuing opportunities for overseas PX suppliers while gradually changing China's position within the Asian aromatics trade.
China's PX producers are becoming increasingly vulnerable to changes in their crude oil, naphtha and other aromatics feedstocks as geopolitical shocks impact the supply chain. In 2026, disruptions relating to Middle East oil and naphtha supply added to the uncertainties for Asian petrochemical manufacturers. Naphtha is especially significant since the aromatic extraction process generates PX that goes into making PTA and PET. ICIS reported that Chinese downstream aromatic-derived polymer prices, including polyester fibre and PET, had risen 25-40% by April 22, 2026, compared with pre-conflict levels. Such feedstock volatility is increasing the importance of procurement flexibility and integrated production economics for China's PX industry.
The increasing demand for polyethene terephthalate in packaging, particularly for beverages and food items, drives the necessity for paraxylene, a key raw material in the production of PET. As the global market for consumer goods and packaged products continues to expand, the requirement for PET correspondingly rises, leading to a significant uptick in the demand for paraxylene.
The textile sector plays a crucial role in enhancing the consumption of paraxylene. The growing consumer interest in fashion, coupled with evolving trends that emphasise sustainability and performance, has led to increased use of polyester fibres, which are derived from PET.
The automotive sector is another significant contributor to the demand for paraxylene. Paraxylene-derived purified terephthalic acid (PTA) is utilised in the manufacture of high-performance plastics and resins that are essential for modern vehicle production.
China Paraxylene Market Report and Forecast 2026-2035 offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
Market Breakup by Application
Market Breakup by Sales Channel
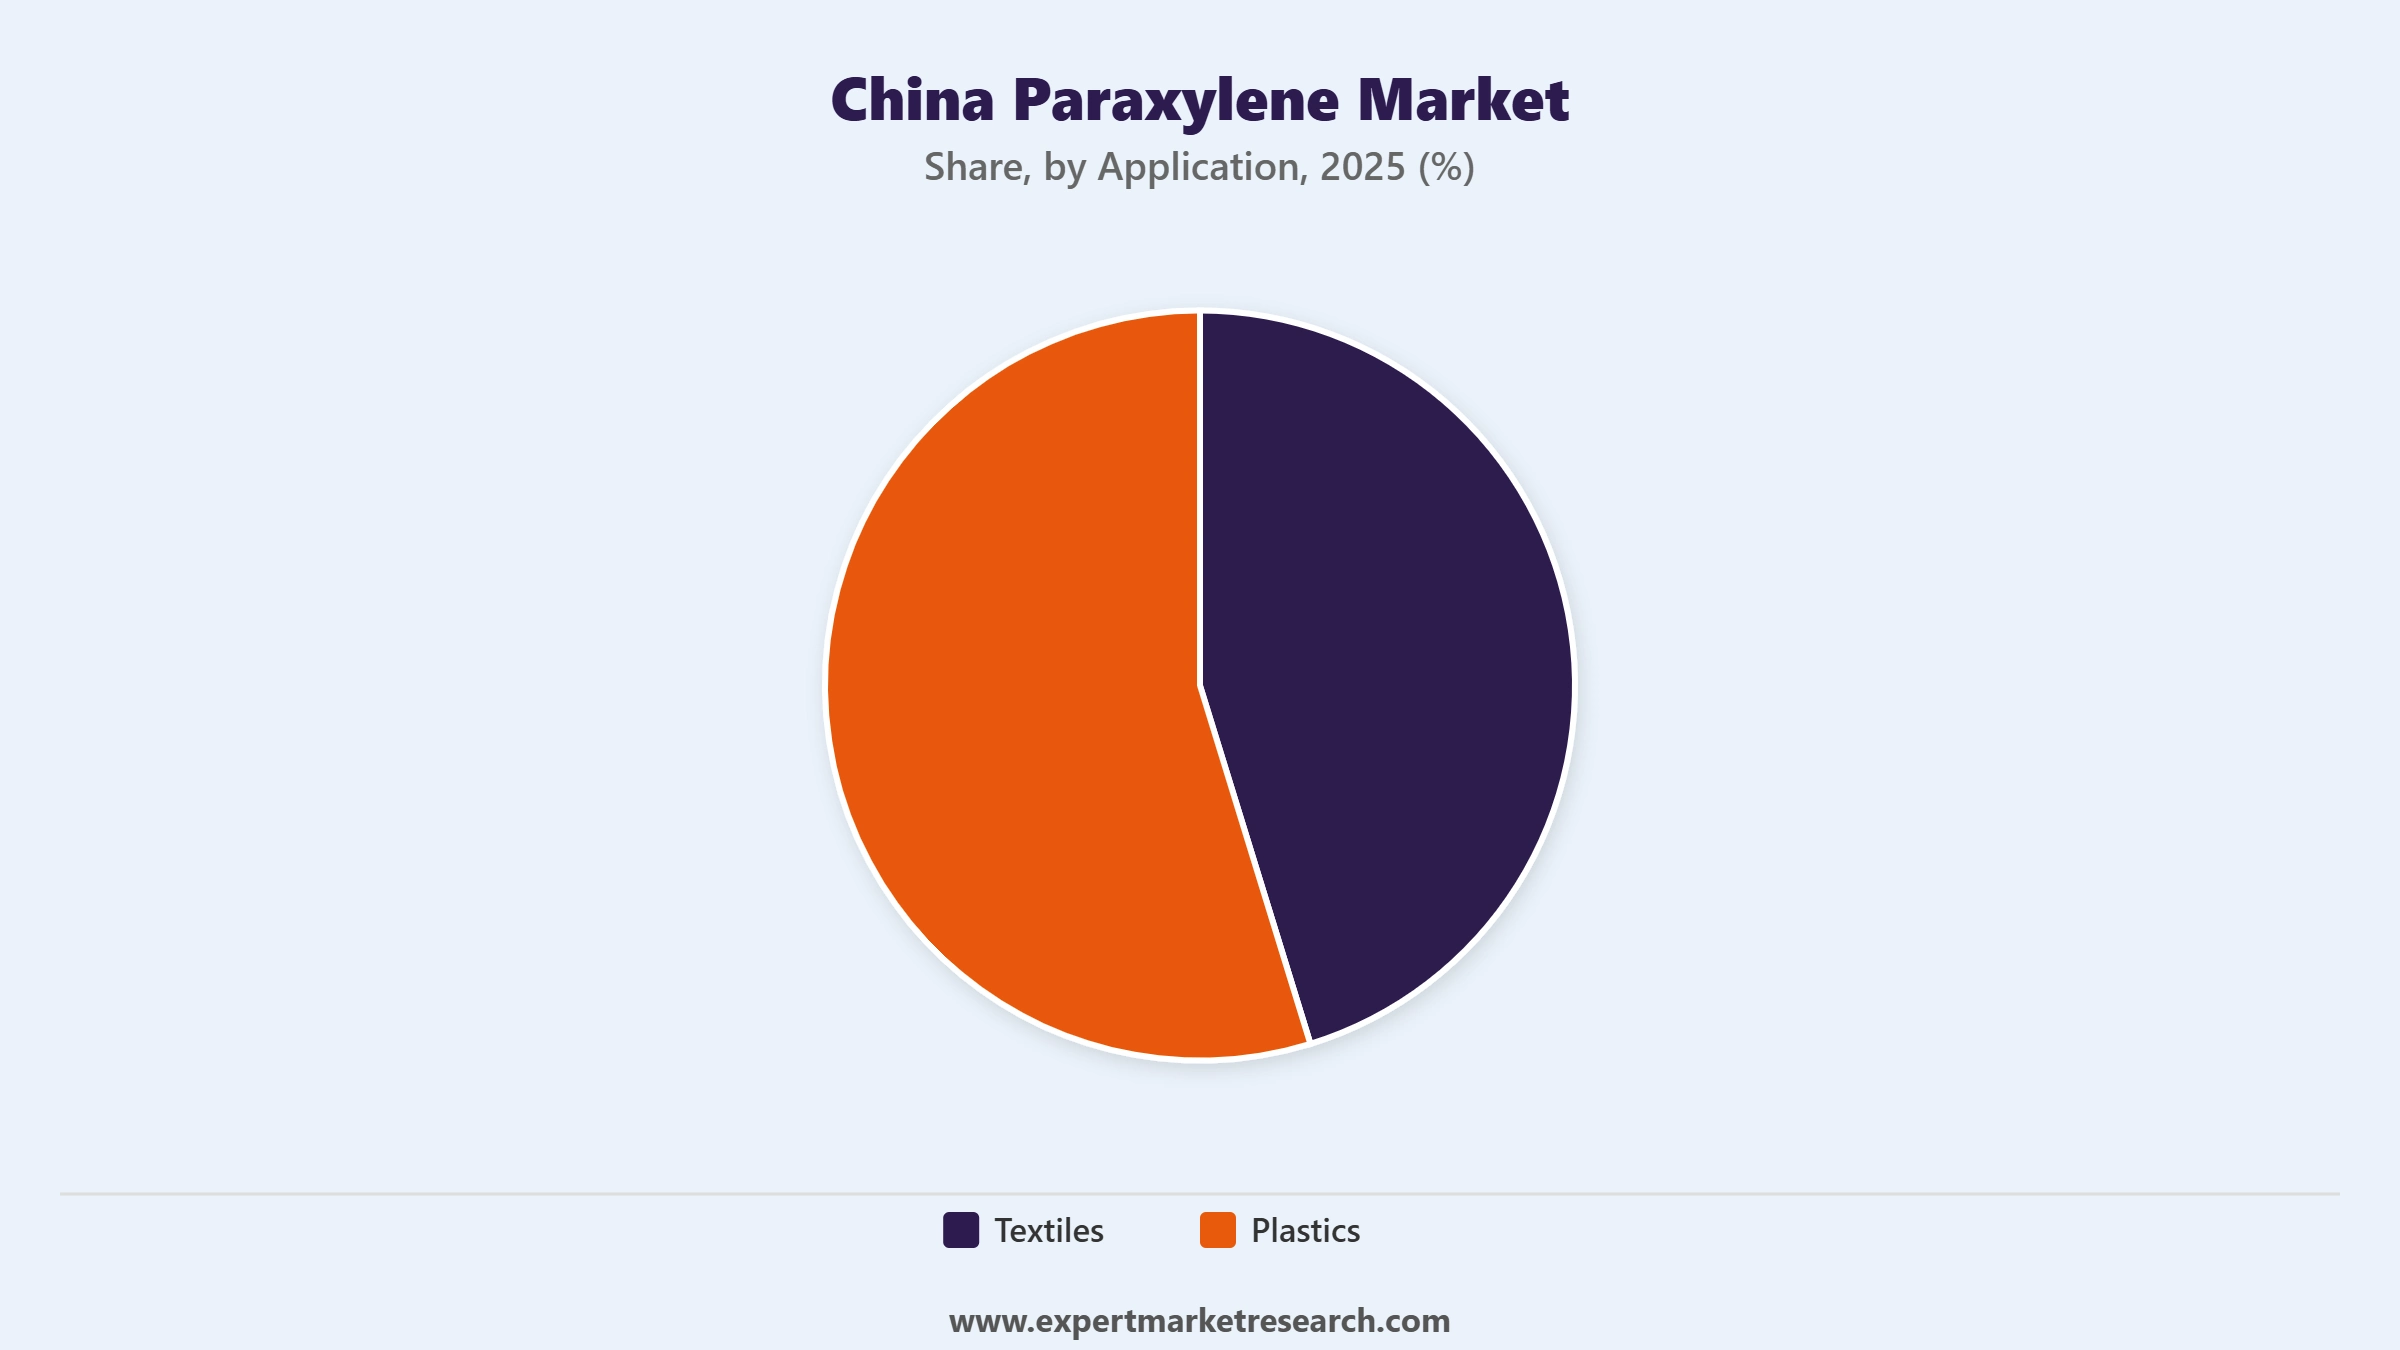
Based on application, the market is segmented into textiles, plastics, and others. The textile segment is projected to grow at a CAGR of 7.3% during the forecast period of 2026-2035. Paraxylene plays a crucial role in the textile sector, mainly due to its wide use in the manufacturing of polyethene terephthalate (PET), a synthetic fibre that is extensively utilised.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Major players are focusing on the adoption of technologically upgraded production practices to gain a competitive edge in the market.
The comprehensive report looks into the macro and micro aspects of the market. The EMR report gives an in-depth insight into the market by providing a SWOT analysis as well as an analysis of Porter’s Five Forces model.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is assessed to grow at a CAGR of 6.50% between 2026 and 2035.
The market is being driven by the wide application of paraxylene in the textile sector and the rising packaging sector in the economy.
The key trends aiding the market expansion include rising sustainable initiatives in the country and continuous economic expansion.
The major applications of paraxylene are textiles and plastics, among others.
The major distribution channels in the market are direct and indirect.
The major players in the market are China National Petroleum Corporation, Sinopec, Hengli Petrochemical Co. Ltd, SK geo centric Co., Ltd., and SINOCHEM GROUP CO., LTD., among others.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment
|
| Breakup by Product Type |
|
| Breakup by Application |
|
| Breakup by Sales Channel |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




