

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
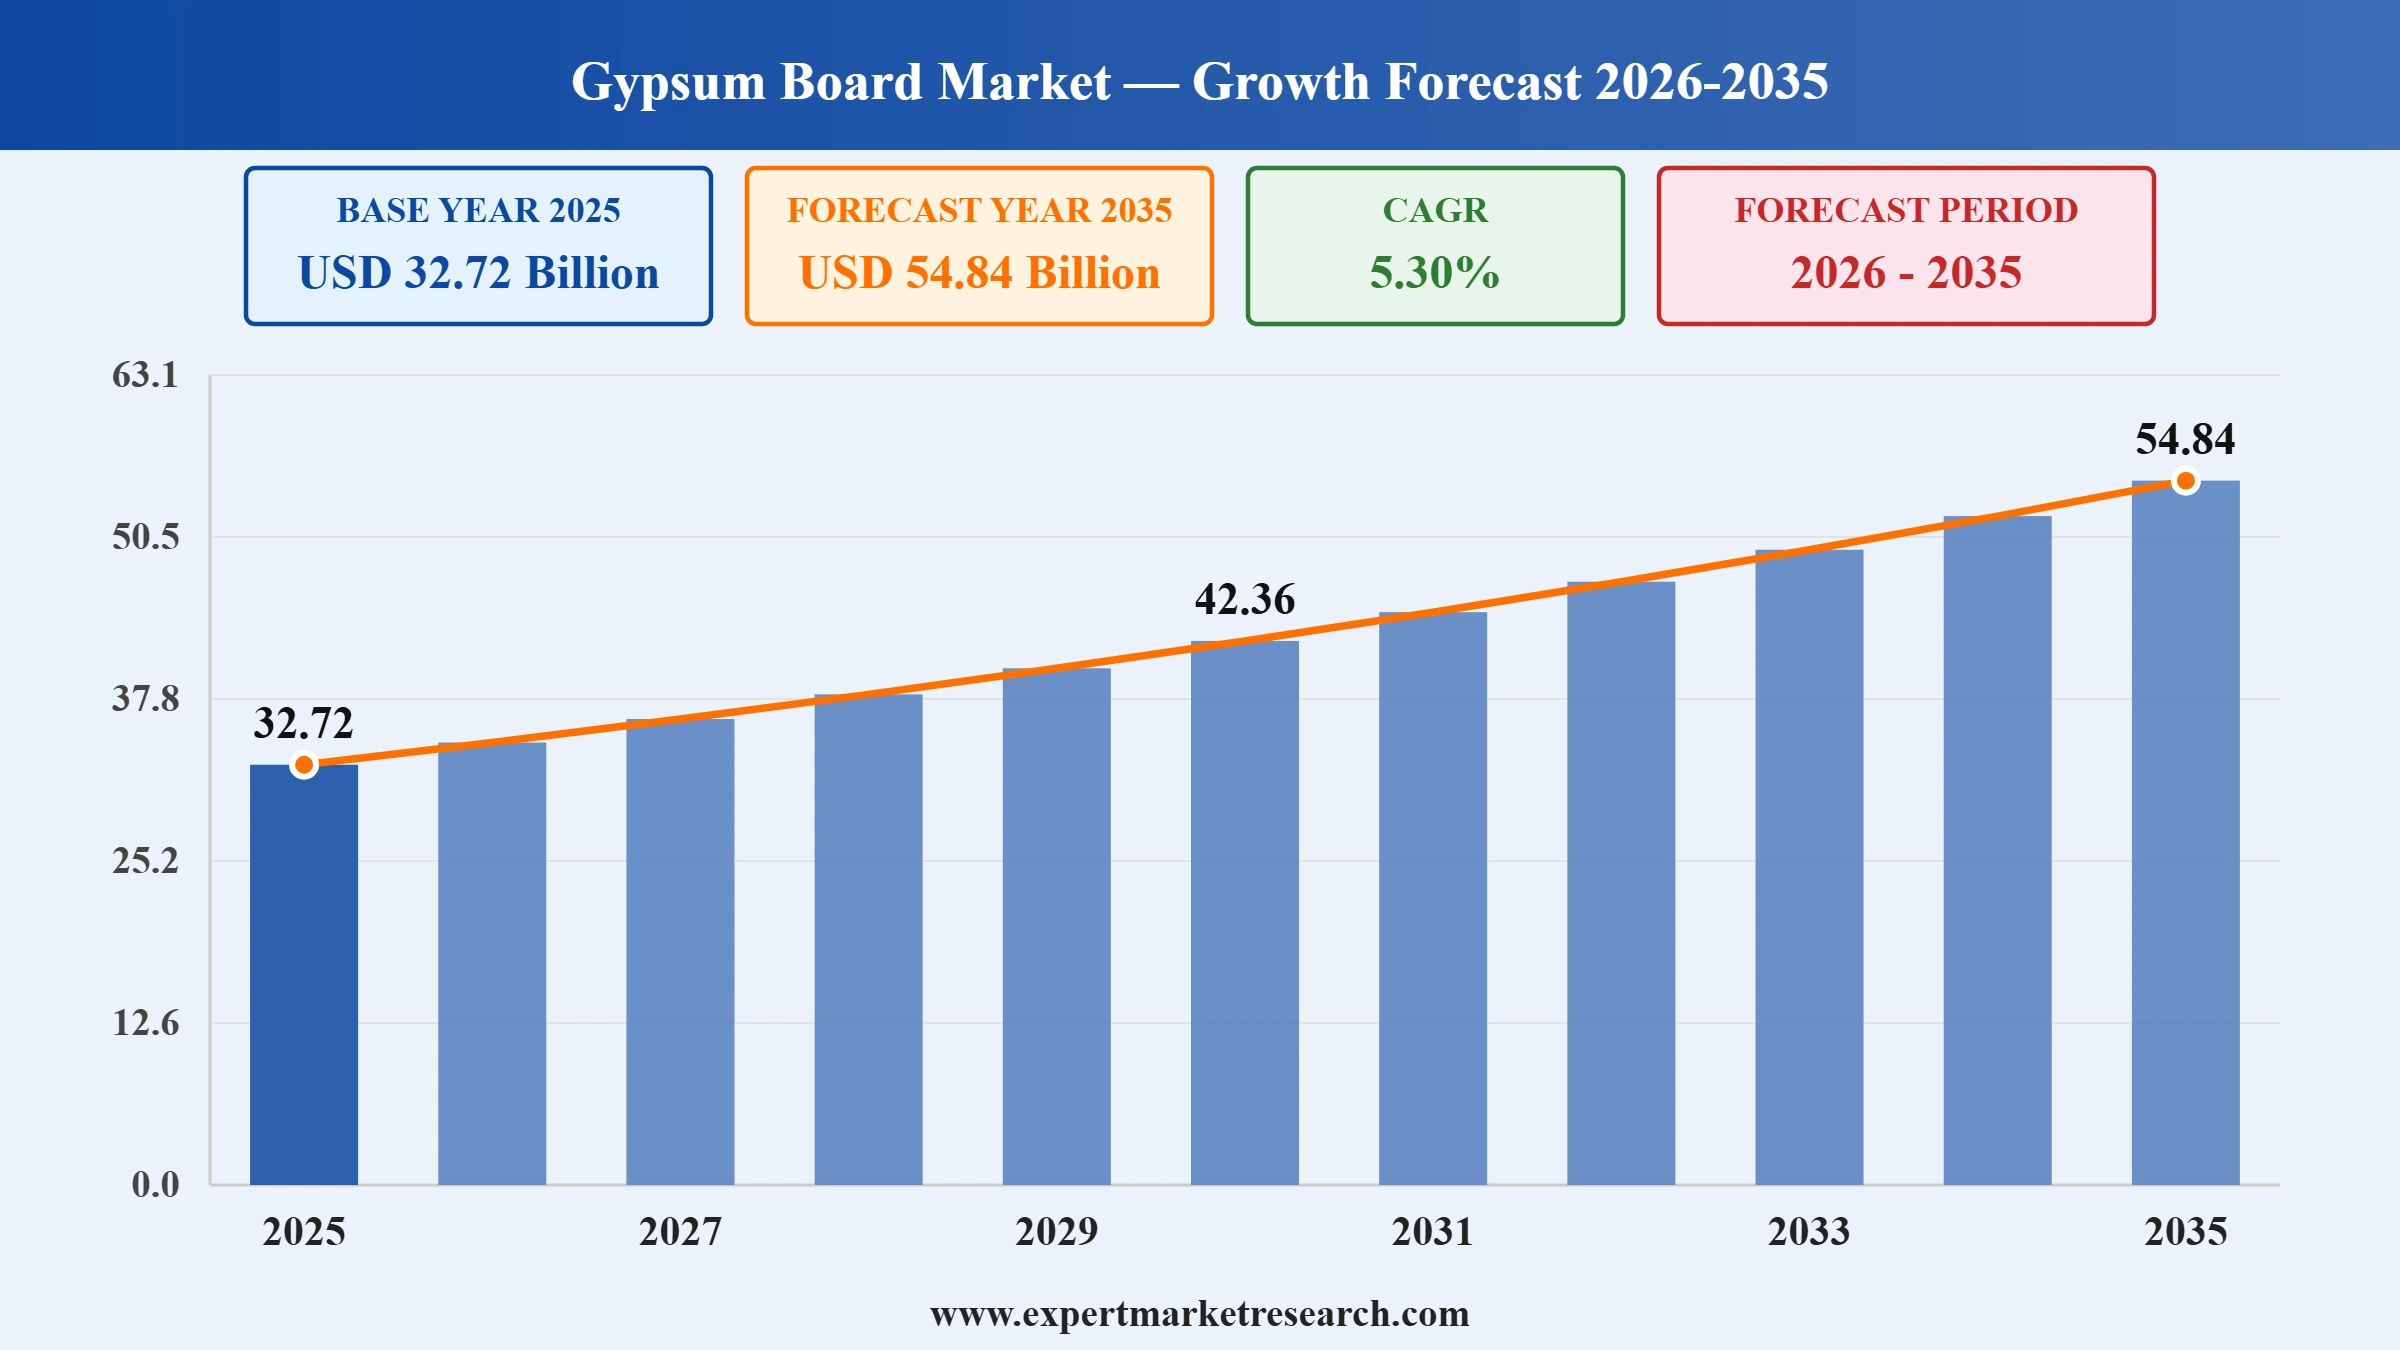
The global gypsum board market attained a value of USD 32.72 Billion in 2025 and is projected to expand at a CAGR of 5.30% through 2035. The market is further expected to reach USD 54.84 Billion by 2035, as rising urbanization, tightening fire- and moisture-resistance building codes, and expanding commercial and institutional construction activity continue to lift demand for lightweight interior wall and ceiling systems worldwide.
Growth across the forecast period is anchored in tightening fire- and moisture-resistance building code requirements and the continued substitution of traditional plaster and masonry partitions with lightweight gypsum systems. Asia Pacific alone accounted for an estimated 43.6% of global volumes in 2025, reflecting the scale of ongoing urban housing and commercial fit-out programs across the region's fastest-growing construction economies.
Consolidation among regional producers is also reshaping supply. Knauf Gips KG's May 2026 acquisition of a 63.2% controlling stake in United Mining Industries, the Saudi wallboard producer, for SR504.5 million illustrates how established European manufacturers are moving to secure manufacturing footprints in faster-growing Middle Eastern demand centers rather than relying solely on organic capacity additions.
At the same time, softer repair-and-remodel activity in mature markets is prompting capacity rationalization: Georgia-Pacific LLC's September 2026 decision to permanently close its Tacoma, Washington wallboard plant, affecting 125 employees, was attributed directly to existing home sales sitting near a 30-year low, underscoring how uneven the demand recovery remains across otherwise-growing regional markets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Lafarge Group's Iraqi operating unit appointed Tarek Sharobime as Chief Executive Officer in October 2026, succeeding Medhat Ismail, whose tenure the company credited with advances in sustainability, innovation, and circular construction practices. The leadership change comes as Holcim Group affiliates continue to support gypsum and building-materials demand tied to Iraq's reconstruction pipeline. Companies can leverage experienced regional leadership transitions to maintain continuity in fire-rated product specification programs across active reconstruction markets.
Knauf Gips KG launched a SR293.5 million (US$78 million) tender offer in September 2026 for the remaining publicly held shares of United Mining Industries, following its May 2026 purchase of a 63.2% controlling stake, bringing total committed investment to roughly US$213 million for full ownership of the Saudi wallboard producer. Companies can leverage full-ownership consolidation of regional producers to secure dedicated manufacturing capacity ahead of Gulf construction demand.
Georgia-Pacific LLC announced in September 2026 that it would permanently close its Tacoma, Washington gypsum wallboard plant, affecting approximately 125 employees, citing a prolonged decline in home repair and remodeling activity since 2022 and existing home sales near a 30-year low. The company pledged job-placement support across its wider Koch Industries network. Companies can leverage disciplined capacity rationalization to protect margins when regional renovation demand softens.
Saint-Gobain announced in August 2026 that it would build a fourth plasterboard production line at its Bahia, Brazil facility, which already added a third line in 2024, making the expanded site South America's largest single plasterboard production line once operational. The move accompanied a parallel strengthening of the group's construction-chemicals platform in Peru. Companies can leverage concentrated regional capacity expansions to meet rising South American lightweight-construction demand efficiently.
Etex Group confirmed in July 2025 a combined EUR 65 million investment across Peru, Chile, and Argentina to expand plasterboard capacity and improve energy efficiency, including EUR 32.5 million for its Gyplac facility in Huachipa, Peru, and EUR 21.4 million for its Santa Rosa plant near Santiago, Chile. Chief Executive Bernard Delvaux framed the program as part of Etex's ambition to grow alongside regional customers. Companies can leverage phased multi-country capacity programs to deepen presence across adjacent Latin American markets.
United Mining Industries reported in December 2025 that a new gypsum board production line at its Yanbu, Saudi Arabia plant had started commercial production, with the associated financial impact expected to register from the first quarter of 2026 onward. The milestone preceded Knauf Gips KG's subsequent moves to acquire full ownership of the company during 2026. Companies can leverage newly commissioned regional lines to capture incremental Gulf construction demand ahead of competitors.
Balrampur Chini Mills announced in June 2026 plans for a gypsum wallboard plant at Kumbhi, Uttar Pradesh, designed to produce roughly 7.6 million boards annually using lactogypsum sourced from an adjoining polylactic acid facility, with operations targeted for late 2027. The project reflects diversification by non-traditional entrants into India's building-materials sector. Companies can leverage byproduct-based feedstock integration to lower input costs when entering new regional wallboard capacity.
Alongside its Brazilian plasterboard-line expansion, Saint-Gobain used its August 2026 announcement to confirm the acquisition of QSI Productos para la Construccion in Peru, broadening the group's construction-chemicals brands such as Weber and Soquimic in the Andean region. The combined moves signal a coordinated push to pair plasterboard capacity with complementary building-materials platforms. Companies can leverage bolt-on acquisitions alongside capacity expansion to deepen regional construction-materials portfolios.
This Expert Market Research Report titled "Global Gypsum Board Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
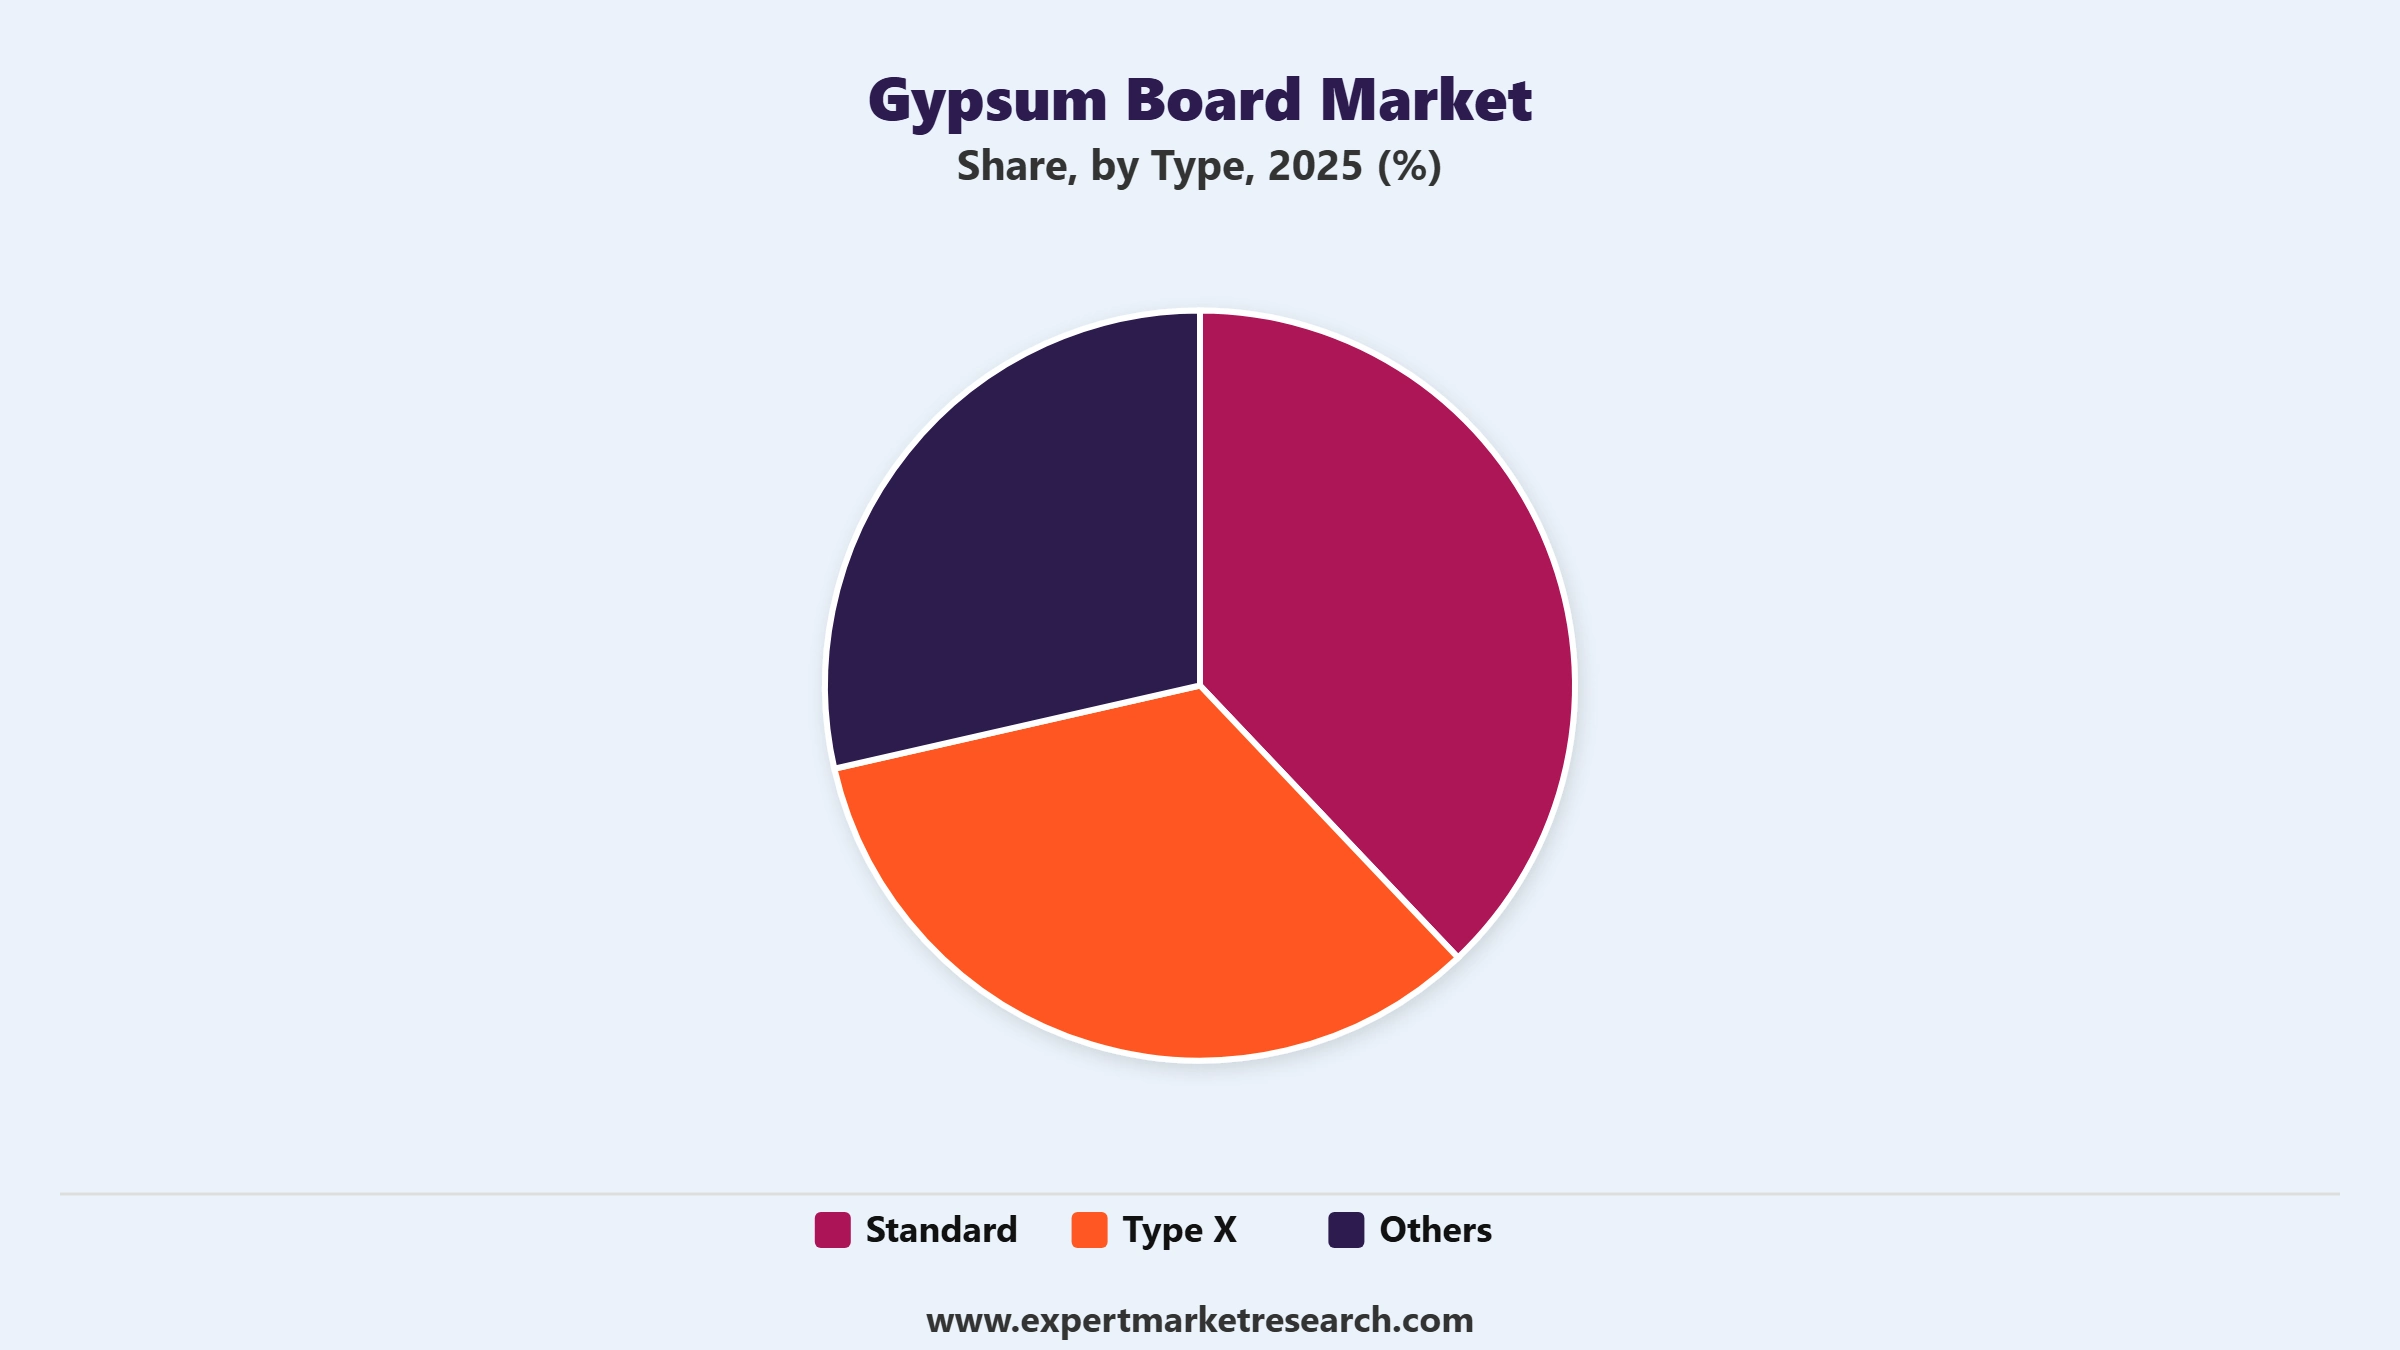
Market Breakup by Type
Key Insight: Standard boards lead the type mix with an estimated 55% share of 2025 volumes, reflecting their cost advantage in applications with no fire-rating requirement, while Type X boards are the fastest-growing category at an estimated 7.2% CAGR as building codes increasingly mandate fire- and moisture-resistant specifications in multifamily and commercial projects; Others, covering specialty and flexible boards, remains a small niche category.
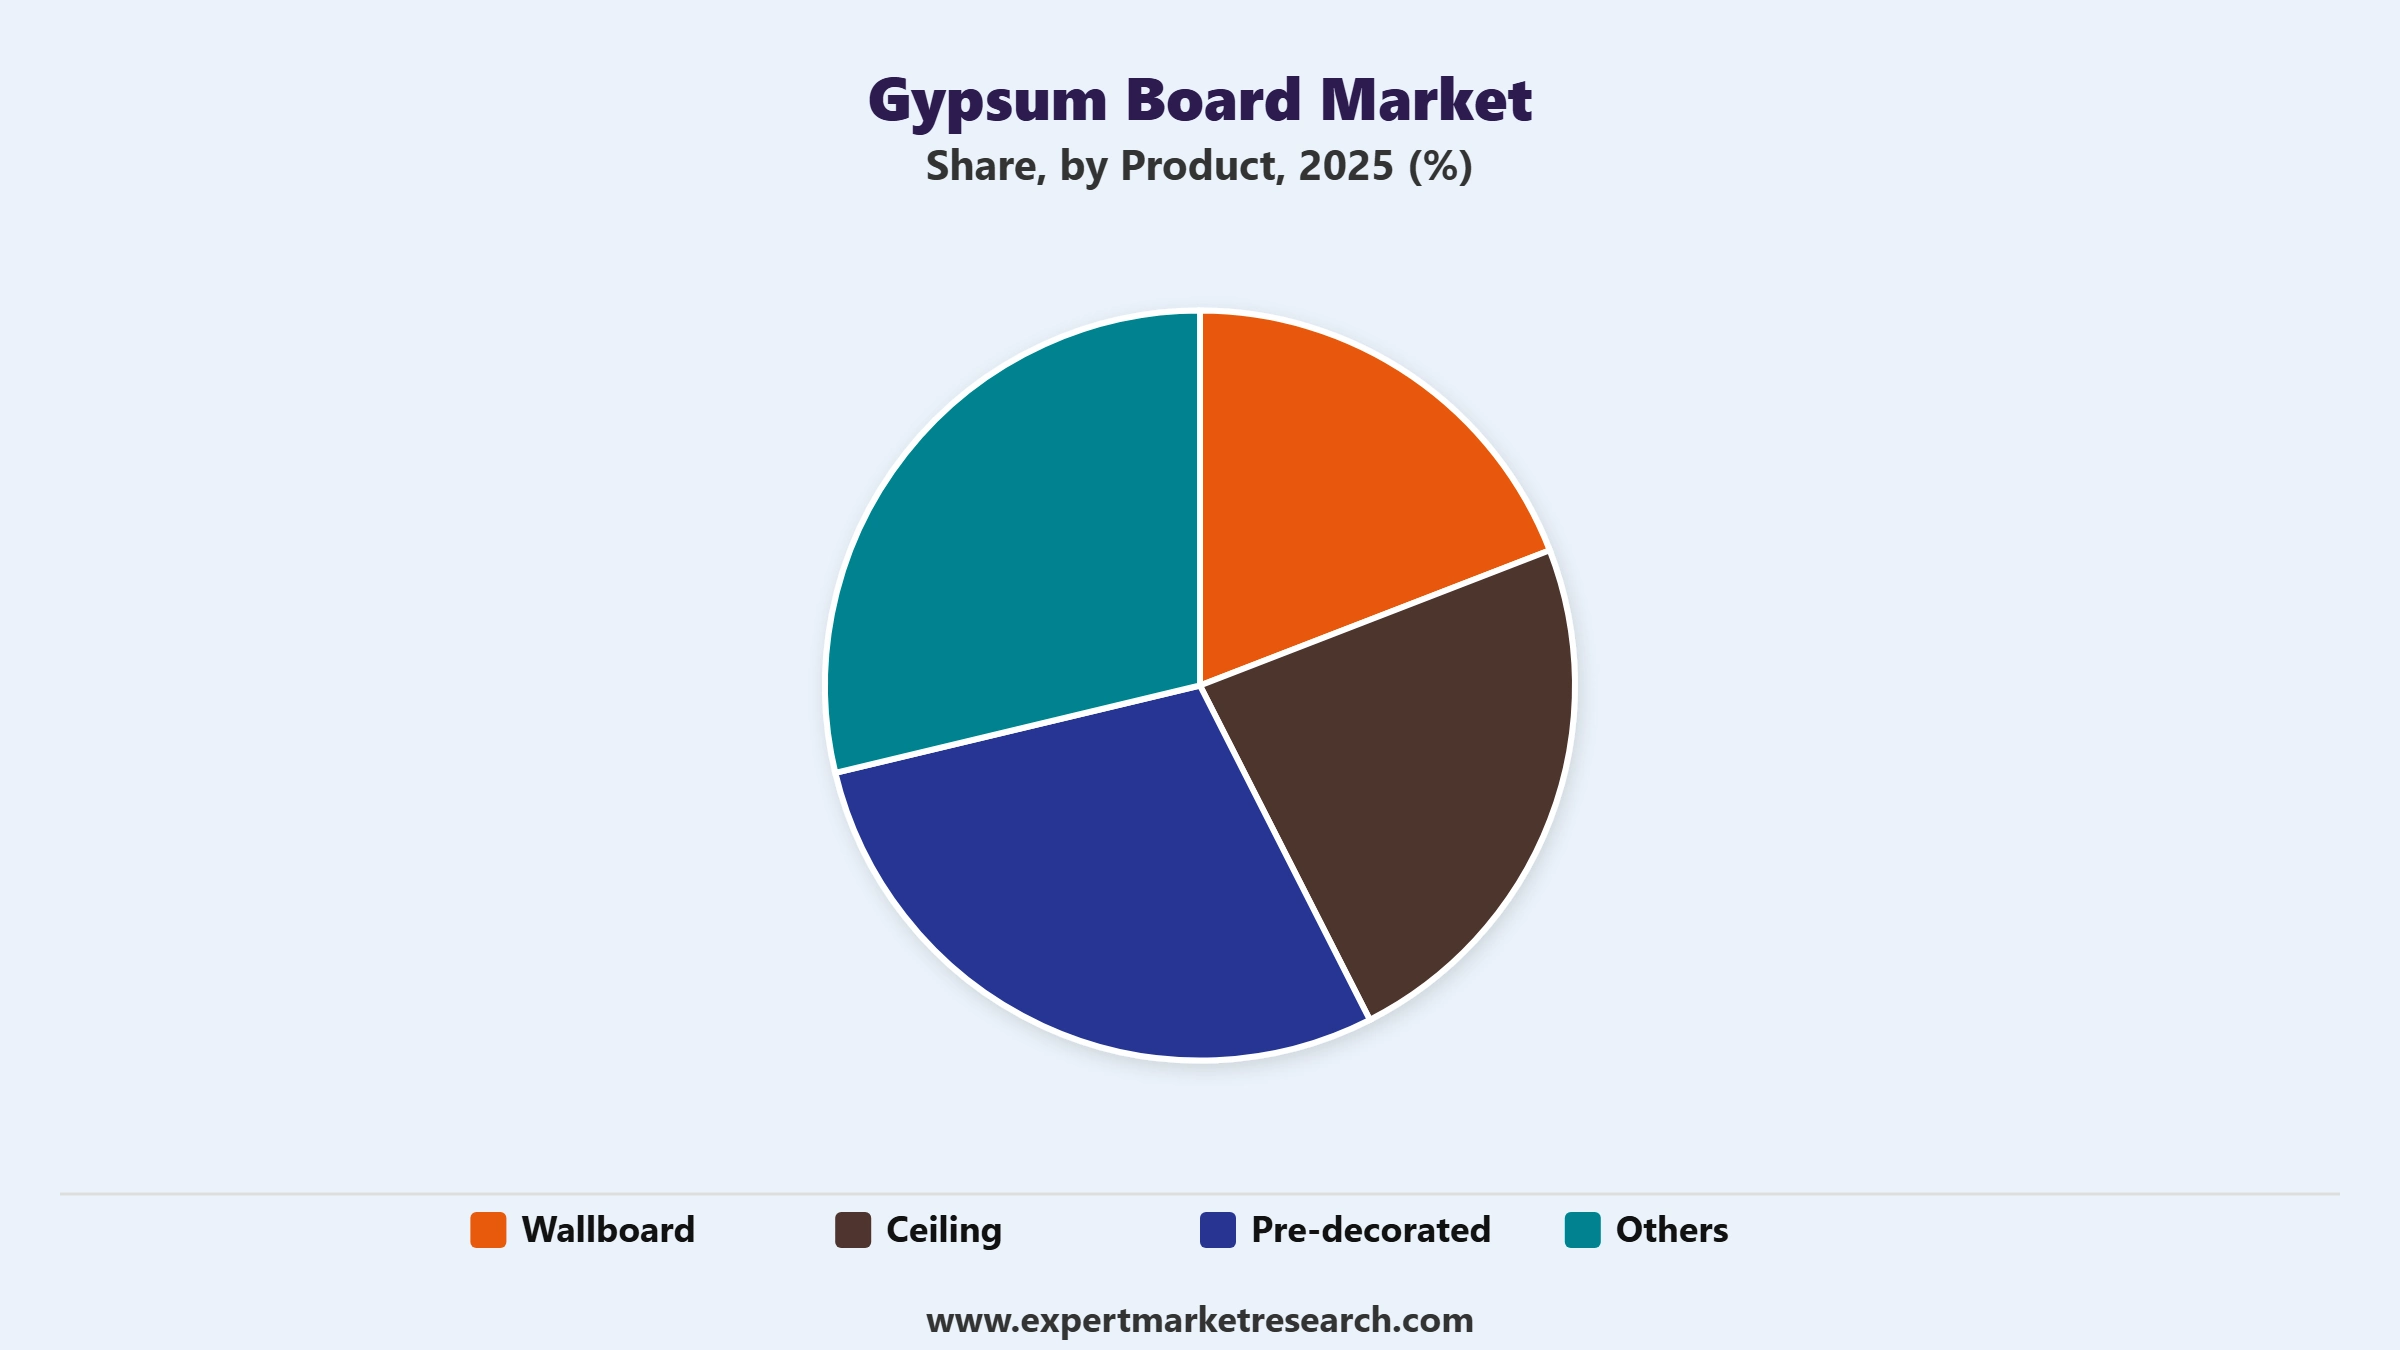
Market Breakup by Product
Key Insight: Wallboard remains the leading product category at an estimated 58% share of 2025 volumes given its use across almost all interior partition and lining applications, while Pre-decorated boards are forecast to grow fastest at an estimated 8.1% CAGR as developers of mid- and high-end residential and hospitality projects favor ready-to-finish surfaces that reduce on-site labor; Ceiling boards hold a steady share in commercial fit-outs, and Others covers niche and composite board formats.
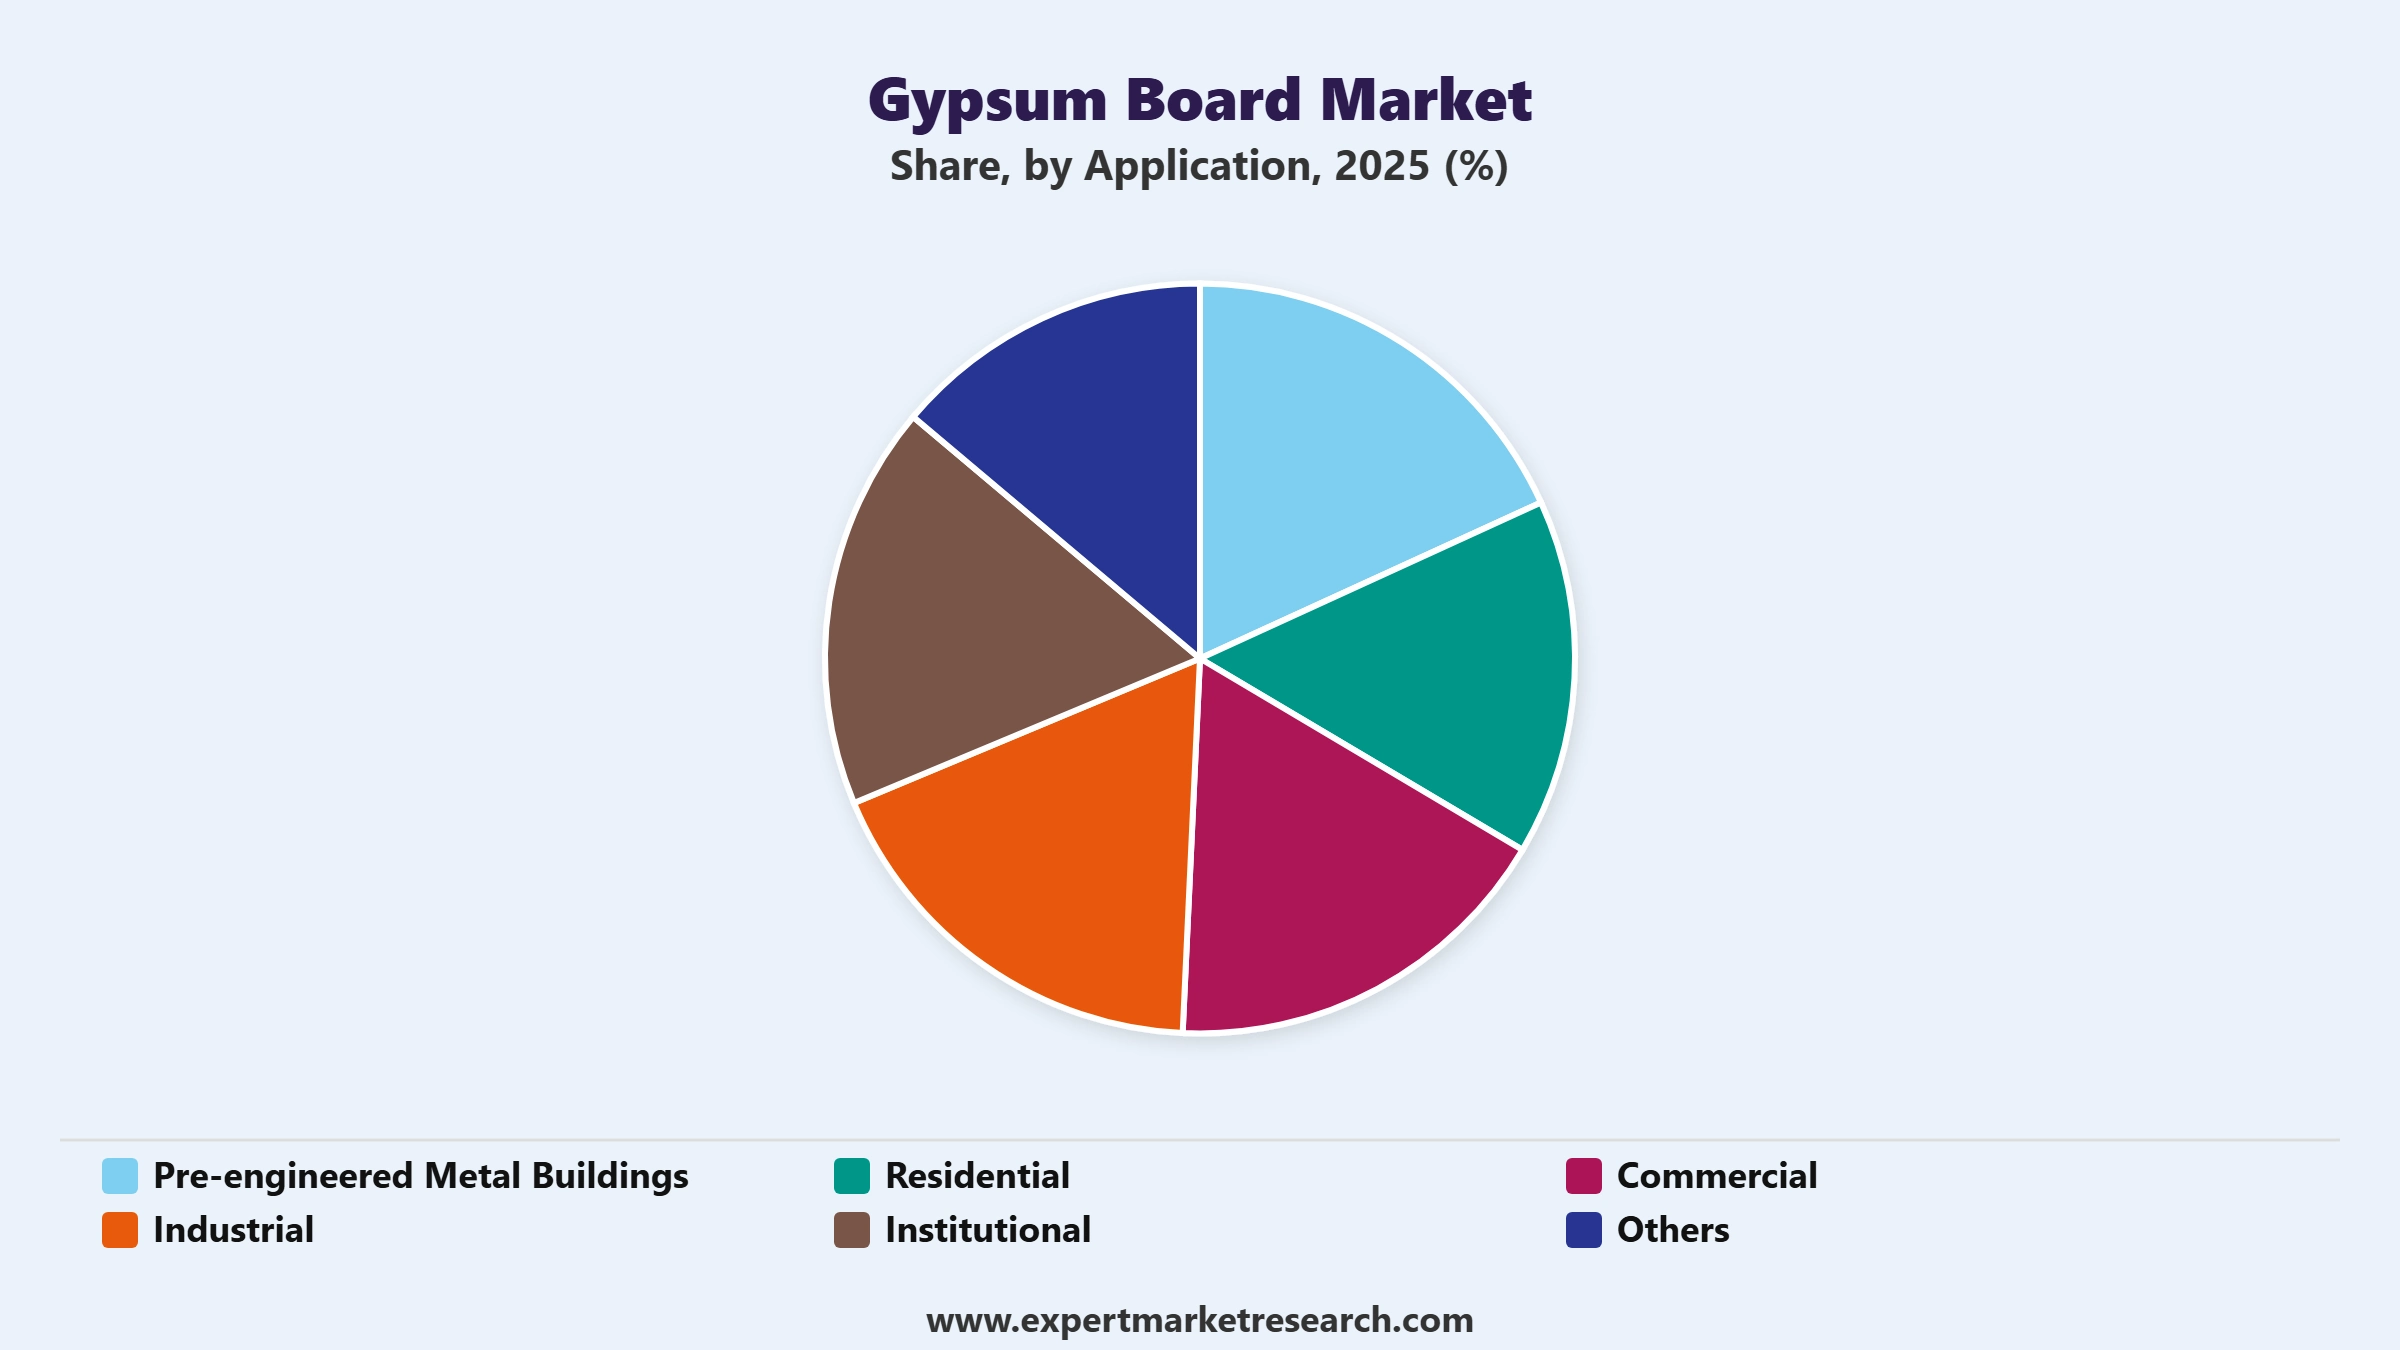
Market Breakup by Application
Key Insight: Residential construction leads application demand at an estimated 54% share of 2025 volumes on the back of sustained household formation and renovation spending, while Pre-engineered Metal Buildings is the fastest-growing application at an estimated 7.6% CAGR as warehousing and light-industrial developers specify gypsum lining for fire separation; Commercial and Institutional projects add steady mid-single-digit growth, Industrial applications remain a smaller specialized category, and Others captures mixed-use and temporary structures.
Market Breakup by Region
Key Insight: Asia Pacific leads regional demand with an estimated 43.6% share of 2025 volumes on the strength of large-scale urban housing and commercial fit-out programs, while North America is the fastest-growing region at an estimated 6.1% CAGR on data-center and institutional construction activity; Europe and Latin America continue to grow steadily on renovation demand, and the Middle East and Africa region is adding significant new wallboard capacity.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By Type, Standard leads the market while Type X grows fastest because tightening fire- and moisture-resistance code requirements are accelerating adoption across commercial and multifamily construction
Standard boards remain the type-mix leader, supported by broad-based capacity additions from established producers. Knauf Gips KG's June 2026 announcement of an EUR 88 million wallboard plant at Huedin, Romania, targeted for operation by end-2027, illustrates how incumbent manufacturers continue to invest in conventional board capacity to serve cost-sensitive renovation and new-build volumes across Central and Eastern Europe, reinforcing Standard's position as the highest-volume category even as specialty boards gain share at the margin.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Type X demand is accelerating as reconstruction and institutional-building programs increasingly specify fire-rated systems; Lafarge Group's October 2026 leadership change at its Iraqi operating unit, where incoming Chief Executive Tarek Sharobime succeeds Medhat Ismail, coincides with continued reconstruction-linked demand for fire-separation building systems in the country. Regulatory tightening around fire and moisture performance in multifamily and healthcare construction is expected to keep Type X the fastest-growing type category through the forecast period.
By Product, Wallboard leads the market while Pre-decorated boards grow fastest because developers are increasingly specifying ready-to-finish surfaces that reduce on-site labor and project timelines
Wallboard's leadership is reinforced by large single-site capacity investments; Saint-Gobain's August 2026 decision to add a fourth plasterboard production line at its Bahia, Brazil facility, which will become South America's largest single plasterboard line, underscores how producers continue to concentrate wallboard capacity in high-growth regional markets rather than spreading investment across smaller sites, keeping Wallboard the dominant product category by a wide margin.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Pre-decorated boards are growing fastest as hospitality and mid-to-high-end residential developers favor finished surfaces; Etex Group's July 2025 confirmation of a combined EUR 65 million investment across its Peru, Chile, and Argentina plasterboard operations included efficiency and technology upgrades at facilities that also supply decorative and finished board lines, supporting the segment's above-market growth trajectory across Latin American markets specifically.
By Application, Residential leads the market while Pre-engineered Metal Buildings grow fastest because warehousing and light-industrial developers are specifying gypsum lining systems for fire separation
Residential demand remains the largest application category, sustained by renovation and remodeling spending even as some producers rationalize underperforming capacity; Georgia-Pacific LLC's September 2026 closure of its Tacoma, Washington wallboard plant was attributed specifically to softer home repair and remodeling activity rather than to any structural decline in residential demand's overall market-leading position.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Pre-engineered Metal Buildings is the fastest-growing application as logistics and light-industrial construction expands; United Mining Industries' December 2025 start of commercial production at its new Yanbu, Saudi Arabia gypsum-board line added capacity directly into a region where pre-engineered steel-building construction has been expanding rapidly, supporting continued above-average growth in this application category specifically.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific commands the largest share of the global gypsum board market, accounting for approximately 43.6% of volumes in 2025, shaped by large-scale urban housing programs, rapid interior fit-out activity, and expanding commercial construction pipelines across the region's fastest-urbanizing economies
This is supported by Balrampur Chini Mills' June 2026 announcement of a new gypsum wallboard plant at Kumbhi, Uttar Pradesh, designed to produce roughly 7.6 million boards annually using lactogypsum sourced from an adjoining polylactic acid facility, illustrating the scale of new regional capacity entering the market to meet rising construction-sector demand across South Asia.
North America is forecast to expand fastest among all regions, at an estimated 6.1% CAGR through 2035, driven by data-center, industrial, and institutional construction activity even as some producers rationalize underperforming capacity, illustrated by Georgia-Pacific LLC's September 2026 closure of its Tacoma, Washington plant amid softer repair-and-remodel demand. Europe, Latin America, and the Middle East and Africa continue to grow at a steadier pace, supported by renovation demand and new capacity such as United Mining Industries' Yanbu production line in Saudi Arabia.
The global gypsum board market is moderately consolidated, with a small number of multinational producers holding substantial combined share alongside a long tail of regional and national manufacturers concentrated in the Middle East, South Asia, and East Asia. Scale economies in mining, calcining, and board-line manufacturing favor large, well-capitalized groups, while regional players compete primarily on logistics proximity and local building code familiarity.
Competitive dynamics are increasingly shaped by capacity consolidation, cross-border acquisitions, and targeted investment in fire- and moisture-resistant product lines rather than by price competition alone. Producers are also rationalizing underperforming sites in mature markets while redirecting capital toward faster-growing regions, a pattern that is reshaping the geographic footprint of global supply even as overall industry concentration continues to rise.
Founded in 1665 and headquartered in Courbevoie, France, Saint-Gobain is a global leader in light and sustainable construction materials, producing plasterboard, insulation, glass, and mortars through brands including British Gypsum and Gyproc. In August 2026, the group announced a fourth plasterboard production line at its Bahia, Brazil facility, set to become South America's largest single plasterboard line once operational.
Founded in 1932 and headquartered in Iphofen, Germany, Knauf Gips KG is a family-owned manufacturer of gypsum board, drywall systems, and insulation with production operations across Europe, the Middle East, and Asia. In September 2026, the company launched a US$78 million tender offer for the remaining shares of United Mining Industries, following its May 2026 purchase of a 63.2% controlling stake, to secure full ownership of the Saudi wallboard producer.
Founded in 1927 and headquartered in Atlanta, Georgia, United States, Georgia-Pacific LLC is a Koch Industries subsidiary that manufactures gypsum wallboard under its ToughRock brand alongside building products, pulp, and paper. In September 2026, the company announced the permanent closure of its Tacoma, Washington gypsum plant, affecting 125 employees, citing a prolonged downturn in home repair and remodeling demand.
Founded in 1905 near Brussels, Belgium, where it remains headquartered, Etex Group manufactures plasterboard, fibre cement, and passive fire-protection systems through brands including Siniat, Promat, and Durlock across roughly 190 sites worldwide. In July 2025, the group confirmed a combined EUR 65 million investment across its Peru, Chile, and Argentina plasterboard operations to expand capacity and improve energy efficiency.
Other key players in the gypsum board market include USG BORAL, LafargeHolcim Ltd, USG Zawawi Drywall LLC SFZ, Gypsemna, Global Mining Company LLC (GMC), Gulf Gypsum Co. (ASK Gypsum Factory Ltd.), National Gypsum Company, Beijing New Building Material (BNBM) Public Ltd Co., Extex Group, United Mining Industries (UMI) Company Ltd., Lafarge Group, Ahmed Yousef & Hassan Abdulla Co. (AYHACO), and Yoshino Gypsum Co. Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Organizations evaluating capacity, product-mix, or market-entry decisions in the gypsum board market can access EMR's full report for detailed, region-specific insights covering the forecast period beginning 2026, along with competitive benchmarking and actionable strategic recommendations.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The Gypsum Board Market was valued at USD 32.72 Billion in 2025.
The market is projected to expand at a CAGR of 5.30% from 2026 to 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 54.84 Billion by 2035.
Leading players are consolidating ownership of regional producers, concentrating capacity in large single-site expansions, investing in fire- and moisture-resistant product lines to meet tightening building codes, and rationalizing underperforming plants in slower-growing markets while redirecting capital toward higher-growth regions.
The key trends in the market include the increasing government investment in infrastructure, especially in the emerging economies.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
The major types of gypsum board are standard, type X, among others.
The significant products of gypsum board are wallboard, ceiling, and pre-decorated, among others.
The major end uses include residential, commercial, industrial, and institutional, among others.
Key players in the gypsum board market include Saint Gobain, Knauf Gips KG, Georgia-Pacific LLC, Etex Group, USG BORAL, LafargeHolcim Ltd, USG Zawawi Drywall LLC SFZ, Gypsemna, Global Mining Company LLC (GMC), Gulf Gypsum Co. (ASK Gypsum Factory Ltd.), National Gypsum Company, Beijing New Building Material (BNBM) Public Ltd Co., Extex Group, United Mining Industries (UMI) Company Ltd., Lafarge Group, Ahmed Yousef & Hassan Abdulla Co. (AYHACO), and Yoshino Gypsum Co. Ltd., along with several smaller regional producers captured under Others.
Asia Pacific accounted for the largest share of the market.
Key challenges include volatile input costs for gypsum and energy, softening repair-and-remodel demand in some mature markets that has prompted plant closures, logistics constraints for bulky board products over long distances, and the capital intensity of adding new calcining and board-line capacity.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Product |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




