

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
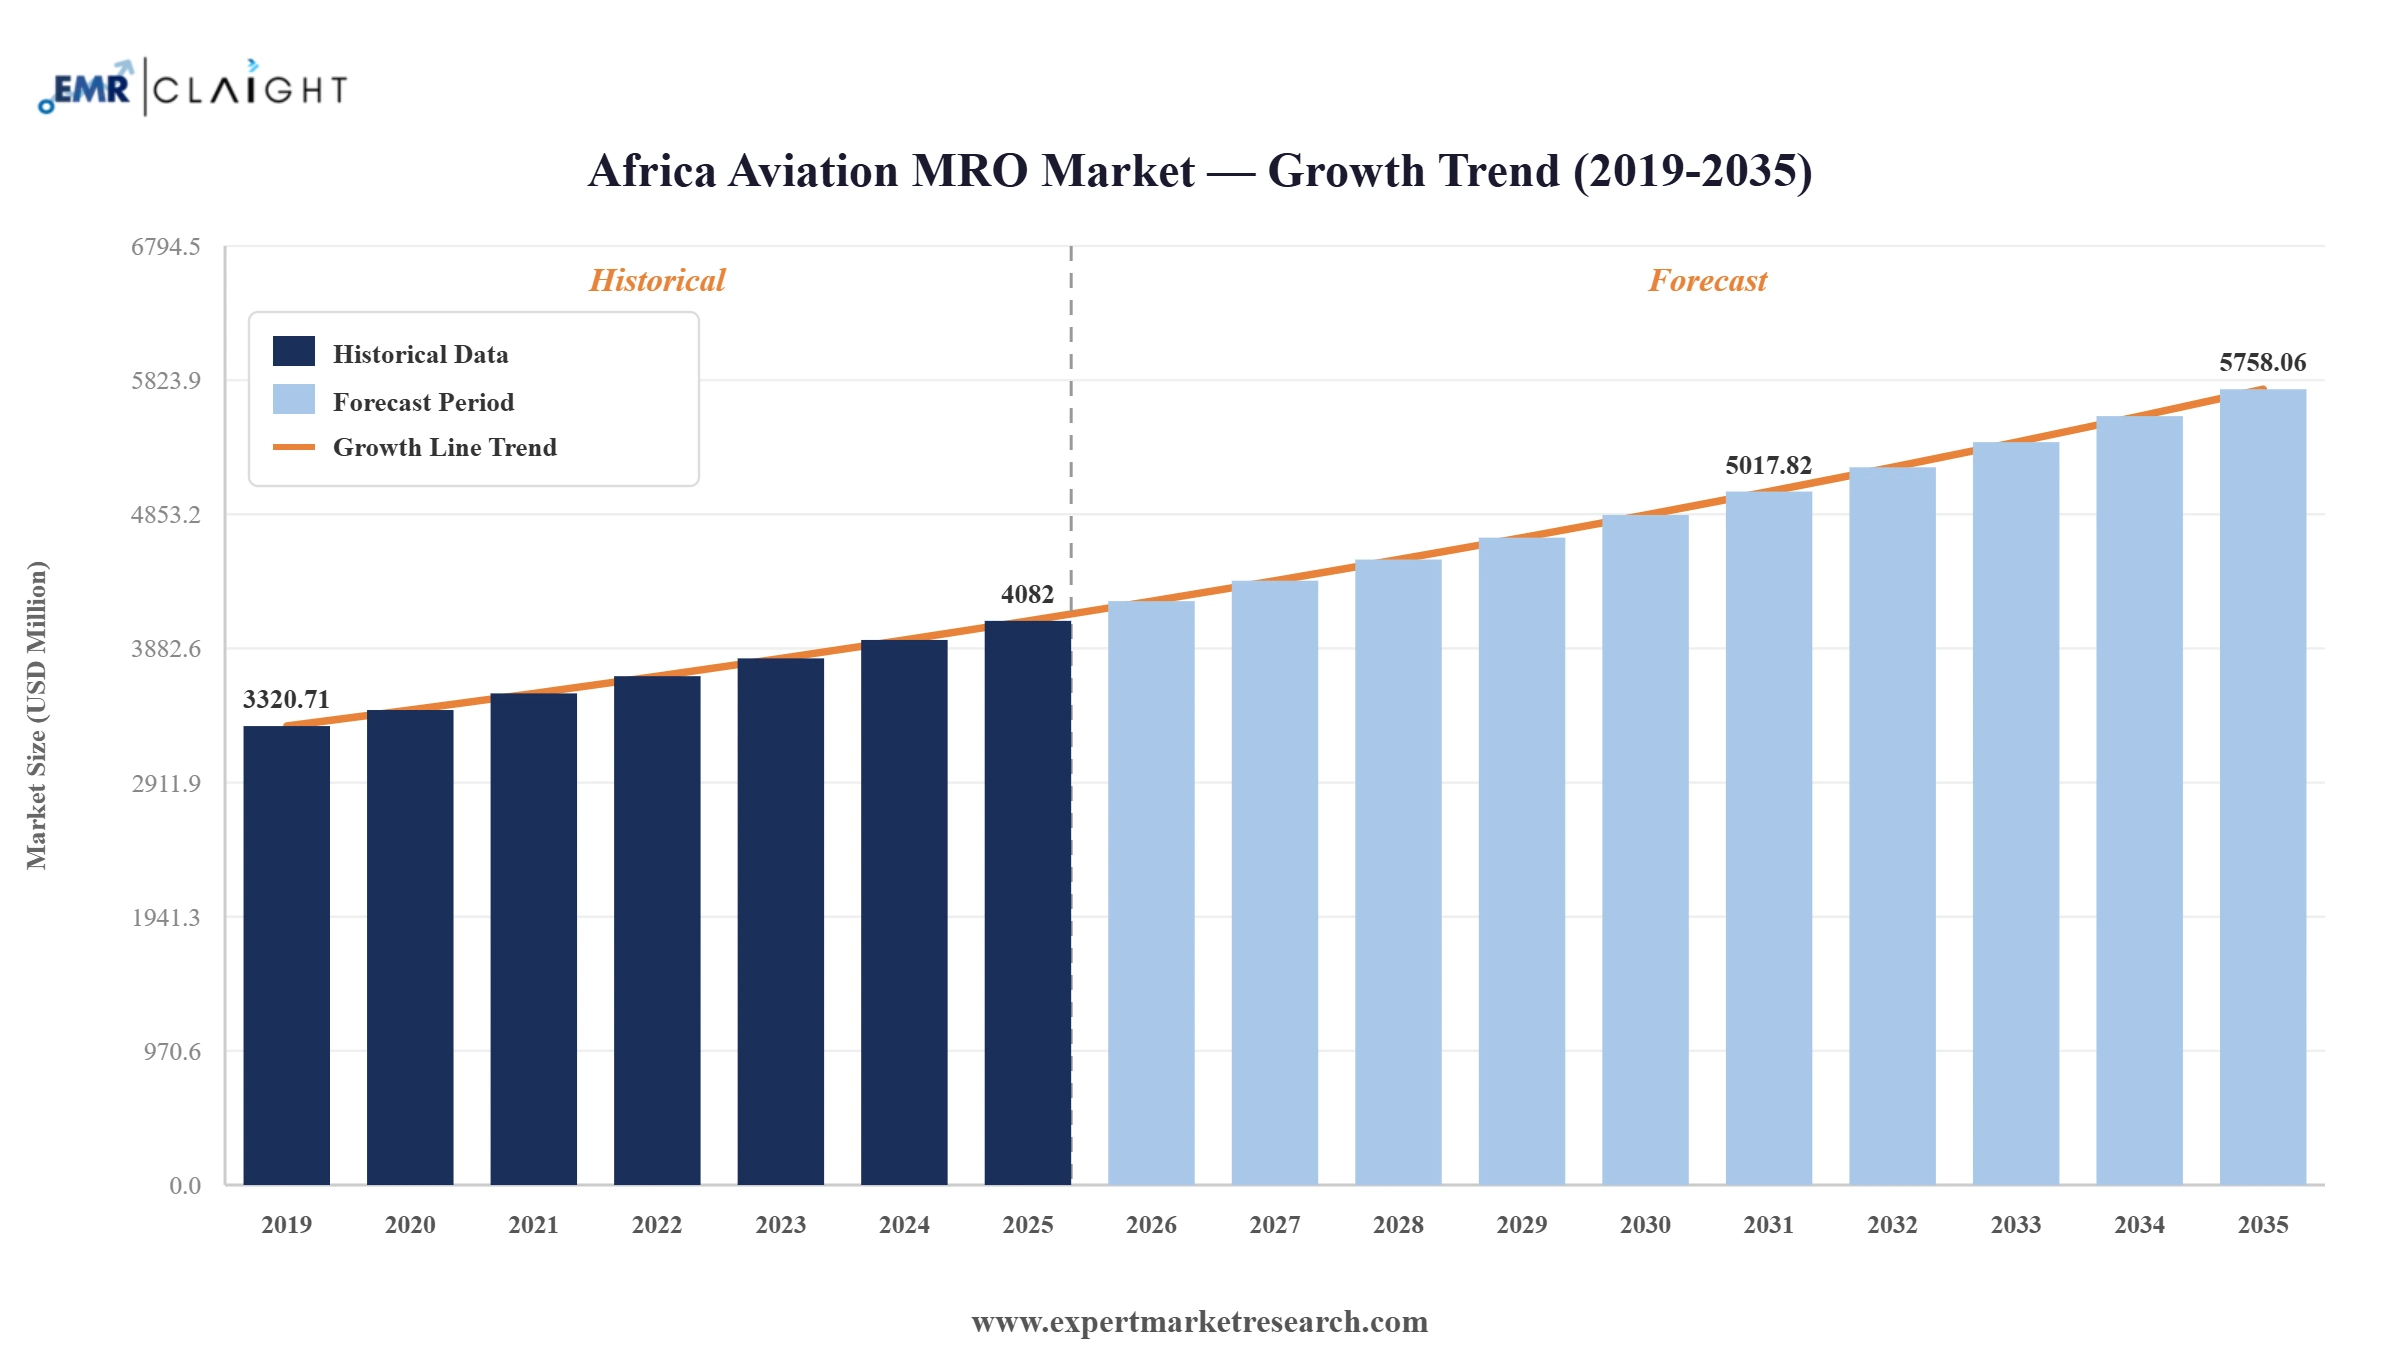
The Africa aviation MRO market attained a value of USD 4082.00 Million in 2025 and is projected to expand at a CAGR of 3.50% through 2035. The market is further expected to reach USD 5758.06 Million by 2035. Ageing fleets, rising air traffic, and growing government focus on aviation infrastructure are helping providers differentiate their service portfolios and reduce reliance on maintenance conducted outside the continent. Growing emphasis on local certification, component repair capability, and fleet modernisation is further encouraging established operators to expand capacity across South Africa, Egypt, Nigeria, and Algeria.
Africa aviation MRO refers to the maintenance, repair, and overhaul activities required to keep aircraft, components, and associated equipment safe and airworthy across passenger, cargo, and military fleets. Fixed-wing aircraft represent a substantial share of the market owing to the greater number of such aircraft operating across the continent compared with rotorcraft. Aircraft operators in Africa maintain some of the oldest airline fleets in the world, and limited capital reserves for new aircraft purchases continue to widen the buyer base for maintenance, repair, and overhaul services across the Africa aviation MRO market.
Demand is concentrating around providers able to combine certified local capability with international technical partnerships. In October 2025, Morocco secured Safran's first non-French LEAP engine assembly line and MRO shop, a combined 320-million-euro investment near Casablanca creating over 900 jobs and integrating the country into the global supply chain for A320neo and 737 MAX engines. This locally anchored, partnership driven positioning is converting rising demand for domestic maintenance capacity directly into expanded regional facility investment across the Africa aviation MRO market.
Providers across the market are converging on a common development direction, widening from standalone airframe maintenance toward integrated component, engine, and certification services. Operators are increasingly pursuing international accreditation and cross-border cooperation agreements, allowing African carriers to attract third-party maintenance customers rather than depending entirely on providers based in Europe or the Middle East. This consolidated approach is reshaping provider selection criteria across the region, favouring operators who can demonstrate internationally recognised certification and multi-service capability over those offering only basic line maintenance.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Global helicopter dealership Rotortrade strengthened its East African support capabilities through cooperation with Helicopters International, a Nairobi based maintenance provider, enhancing local access to rotorcraft maintenance across the region. The partnership lets Rotortrade extend regional coverage without building a standalone facility. Providers across the Africa aviation MRO market can use local partnerships to widen regional support networks faster than direct facility investment allows.
Maintenance Aero Maroc, Sabena Engineering, Lockheed Martin, and MEDZ Maroc broke ground on a 15,000 square metre maintenance centre in Benslimane, designed to service the Royal Moroccan Air Force's C-130 Hercules and F-16 aircraft. The facility, expected operational in late 2026, aims to reduce reliance on maintenance performed outside Morocco. Smaller air forces can use such partnerships to access OEM grade sustainment without exporting aircraft abroad.
Air Peace began construction on what it described as Nigeria's largest maintenance, repair, and overhaul centre in Lagos, partnering with Embraer for technical support and local technician training over a planned 12-to-15-month construction period. The facility is intended to reduce overseas maintenance downtime for the carrier. Carriers across the Africa aviation MRO market can use anchor MRO investments to reduce overseas maintenance dependency and attract regional third-party business.
Kenya Airways' Approved Maintenance Organisation in Nairobi achieved European Union Aviation Safety Agency Part 145 certification, strengthening its credentials to attract third-party maintenance customers from across the region. The certification broadens the range of aircraft types and maintenance checks the Nairobi base can perform under internationally recognised oversight. Carriers across the Africa aviation MRO market can use international certification to compete for cross-border maintenance contracts beyond their own fleets.
African pilot training academies across the Africa aviation MRO market are increasingly consolidating through acquisitions and fleet renewal, rather than each smaller school competing independently for the same student pipeline. This is reshaping the training landscape, favouring larger, multi-brand academies with standardised fleets over fragmented smaller providers. Following its 2025 acquisition of Aeronav Academy and Skyhawk Aviation, South Africa's Excellentia Airline Academy has grown into one of Africa's largest flight training groups, with roughly 100 students in training and a transition underway to a standardised fleet of modern glass cockpit trainers.
Nigerian private aviation investors across the Africa aviation MRO market are increasingly partnering with domestic financial institutions to fund new maintenance facilities, rather than relying solely on foreign capital or government funding alone. This is reshaping how smaller Nigerian carriers plan capacity expansion, favouring locally financed facilities over dependence on international investors. In January 2025, XeJet launched a maintenance, repair, and overhaul facility and flight support centre in Abuja, developed in collaboration with indigenous Nigerian banks as part of a push to reduce dependence on foreign aviation services.
European flight training academies across the Africa aviation MRO market are increasingly extending ab initio pilot training partnerships into African and Middle Eastern markets, rather than limiting cadet programmes to their home regions. This is reshaping how first-time pilot training capacity is built across the continent, favouring partnered academy networks over standalone national schools. In November 2025, Airbus Flight Academy partnered with Tunisia's The Aviator Institute to deliver ab initio training locally, with the first cadets beginning in March 2026 and a ramp-up to over 80 cadets annually.
Global helicopter manufacturers across the Africa aviation MRO market are increasingly marking milestone deliveries to East African operators, reflecting the growing scale of rotorcraft fleets serving tourism, conservation, and medical evacuation missions across the region. This is reshaping how manufacturers approach the African market, favouring sustained fleet growth over isolated one-off sales. In May 2026, Kenyan operator Rotorjet Aviation received the 1,000th Airbus H130 helicopter built, growing its fleet to three of the type and supporting its charter, safari, and medical evacuation operations across the Rift Valley and Maasai Mara.
National carriers across Southern Africa are increasingly building in-house maintenance capacity in partnership with international aerospace groups, rather than continuing to outsource heavy checks entirely abroad. This is reshaping capital planning for smaller national carriers with limited existing MRO infrastructure. TAAG Angola Airlines is developing an in-house MRO facility in Luanda in collaboration with the Aviation Industry Corporation of China, with the first of three prefabricated hangars scheduled to become operational by June 2026.
The Expert Market Research's report titled "Africa Aviation MRO Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Service
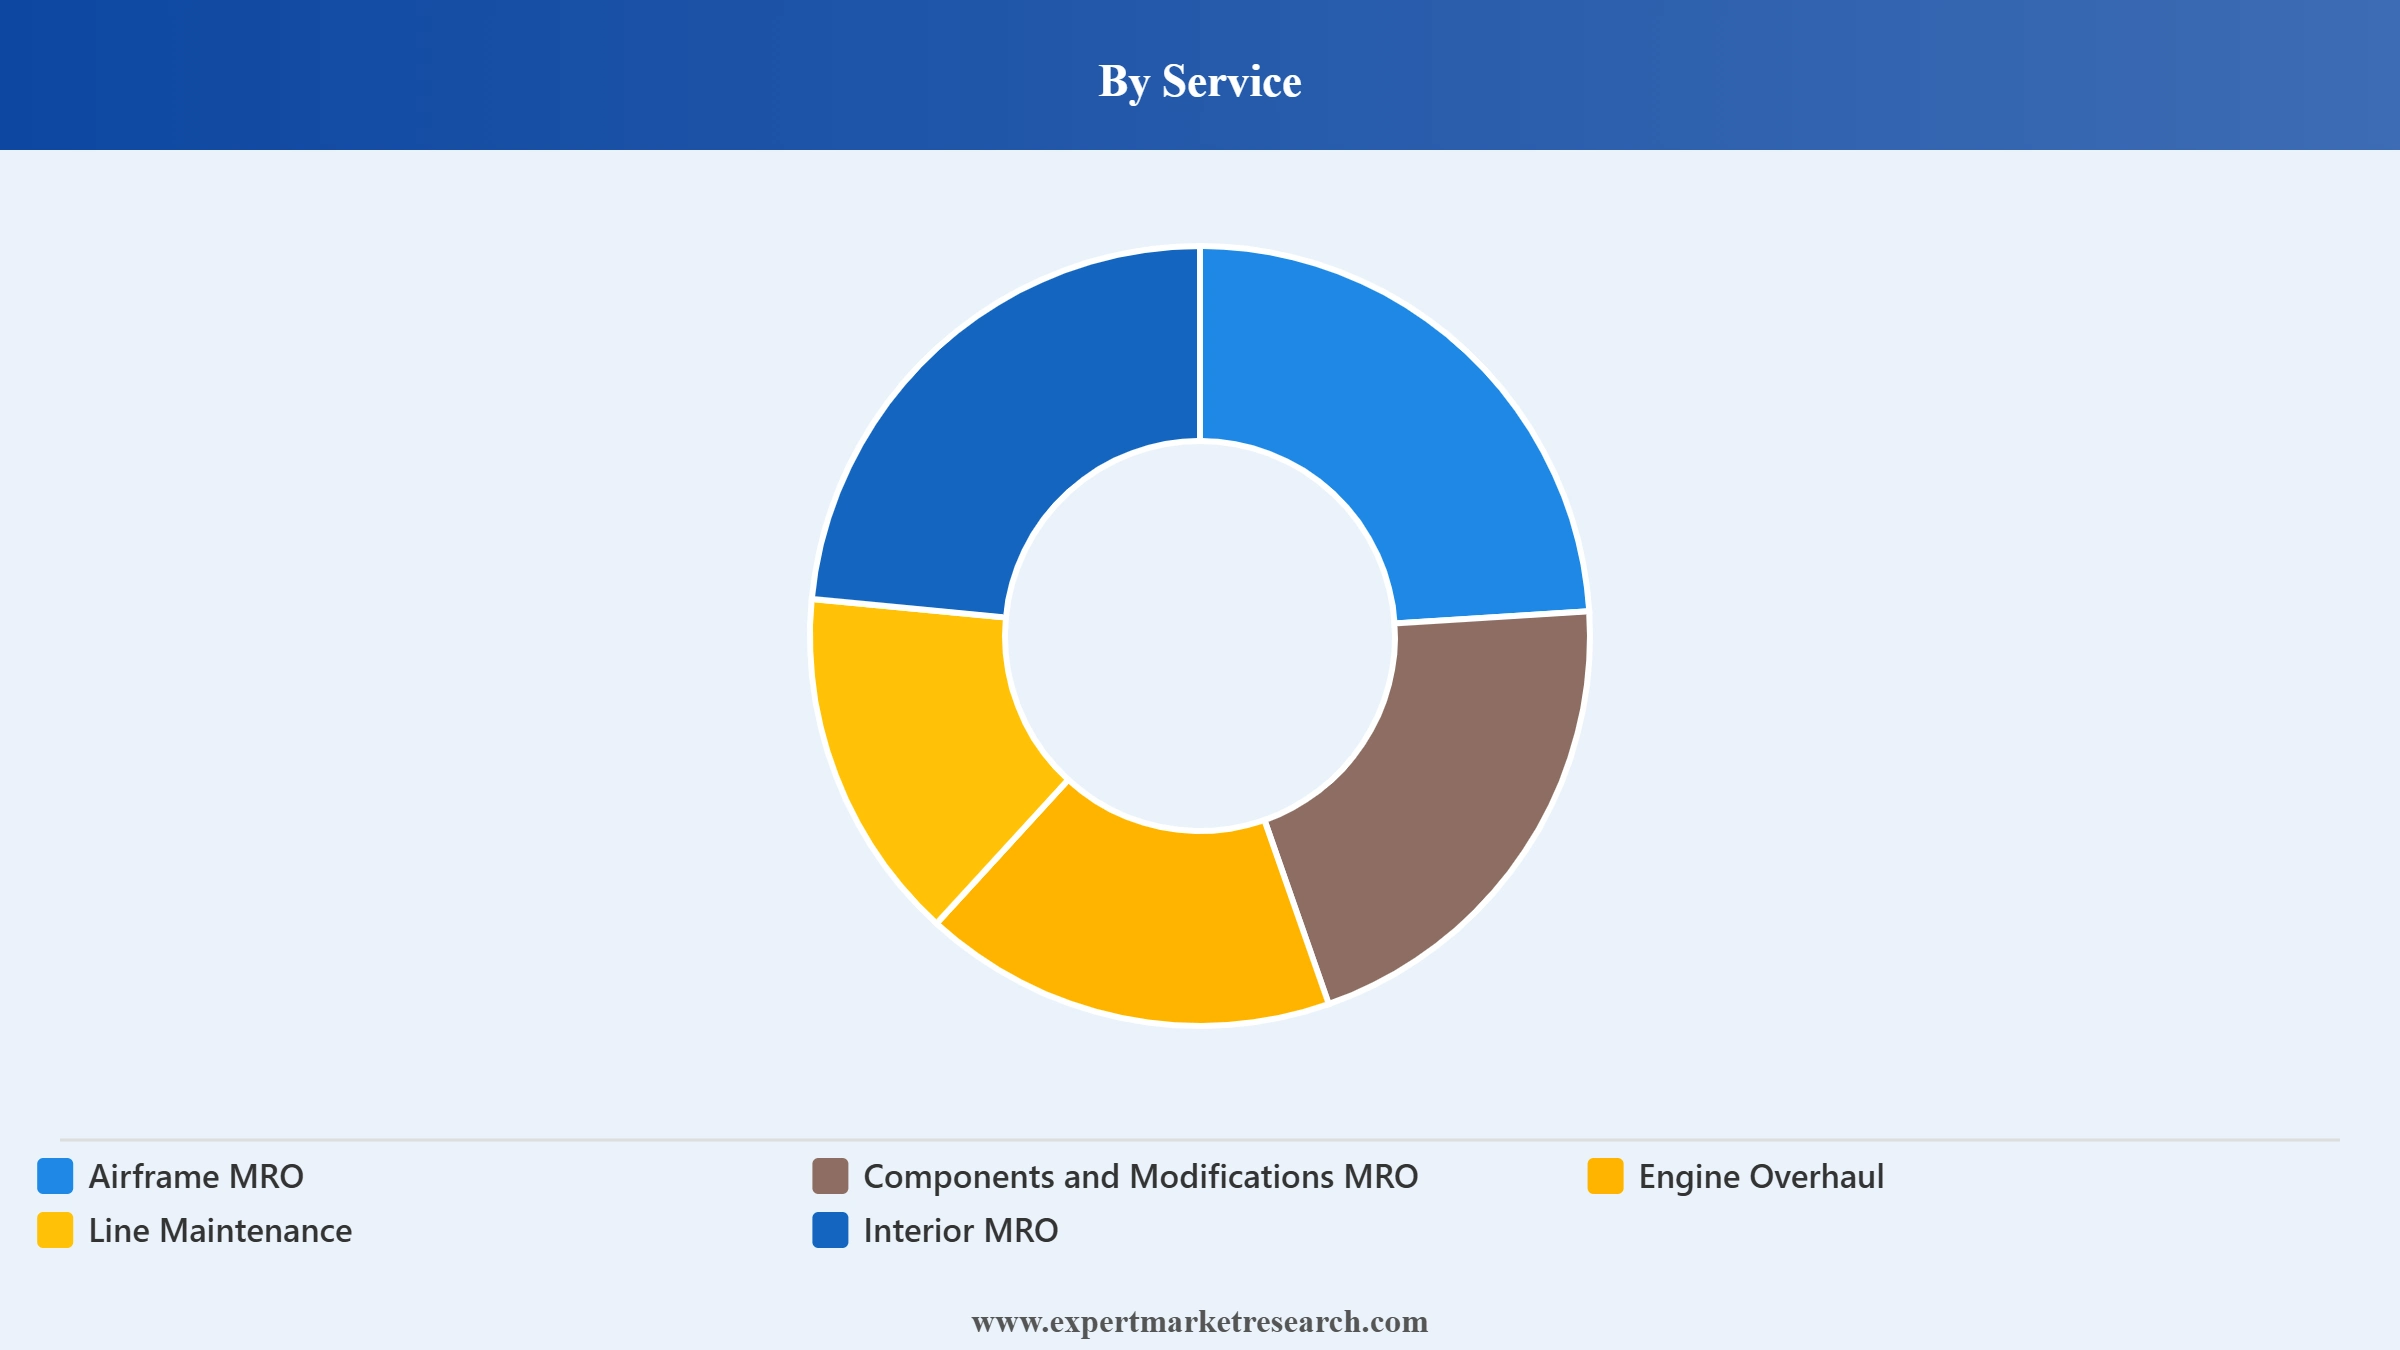
Key Insight: Airframe MRO accounts across the Africa aviation MRO market for a substantial service share as ageing African fleets require sustained structural inspection and repair to remain airworthy. Line maintenance forms a recurring revenue base for providers through routine inspections at every major hub airport. In October 2025, AAR CORP was named an authorised service centre for Eaton's commercial aerospace hydraulic components across Europe, the Middle East, and Africa, illustrating how components and modifications MRO increasingly runs through OEM authorised regional networks. Interior MRO addresses cabin refurbishment demand as carriers modernises ageing interiors to remain competitive.
Market Breakup by Aircraft Type
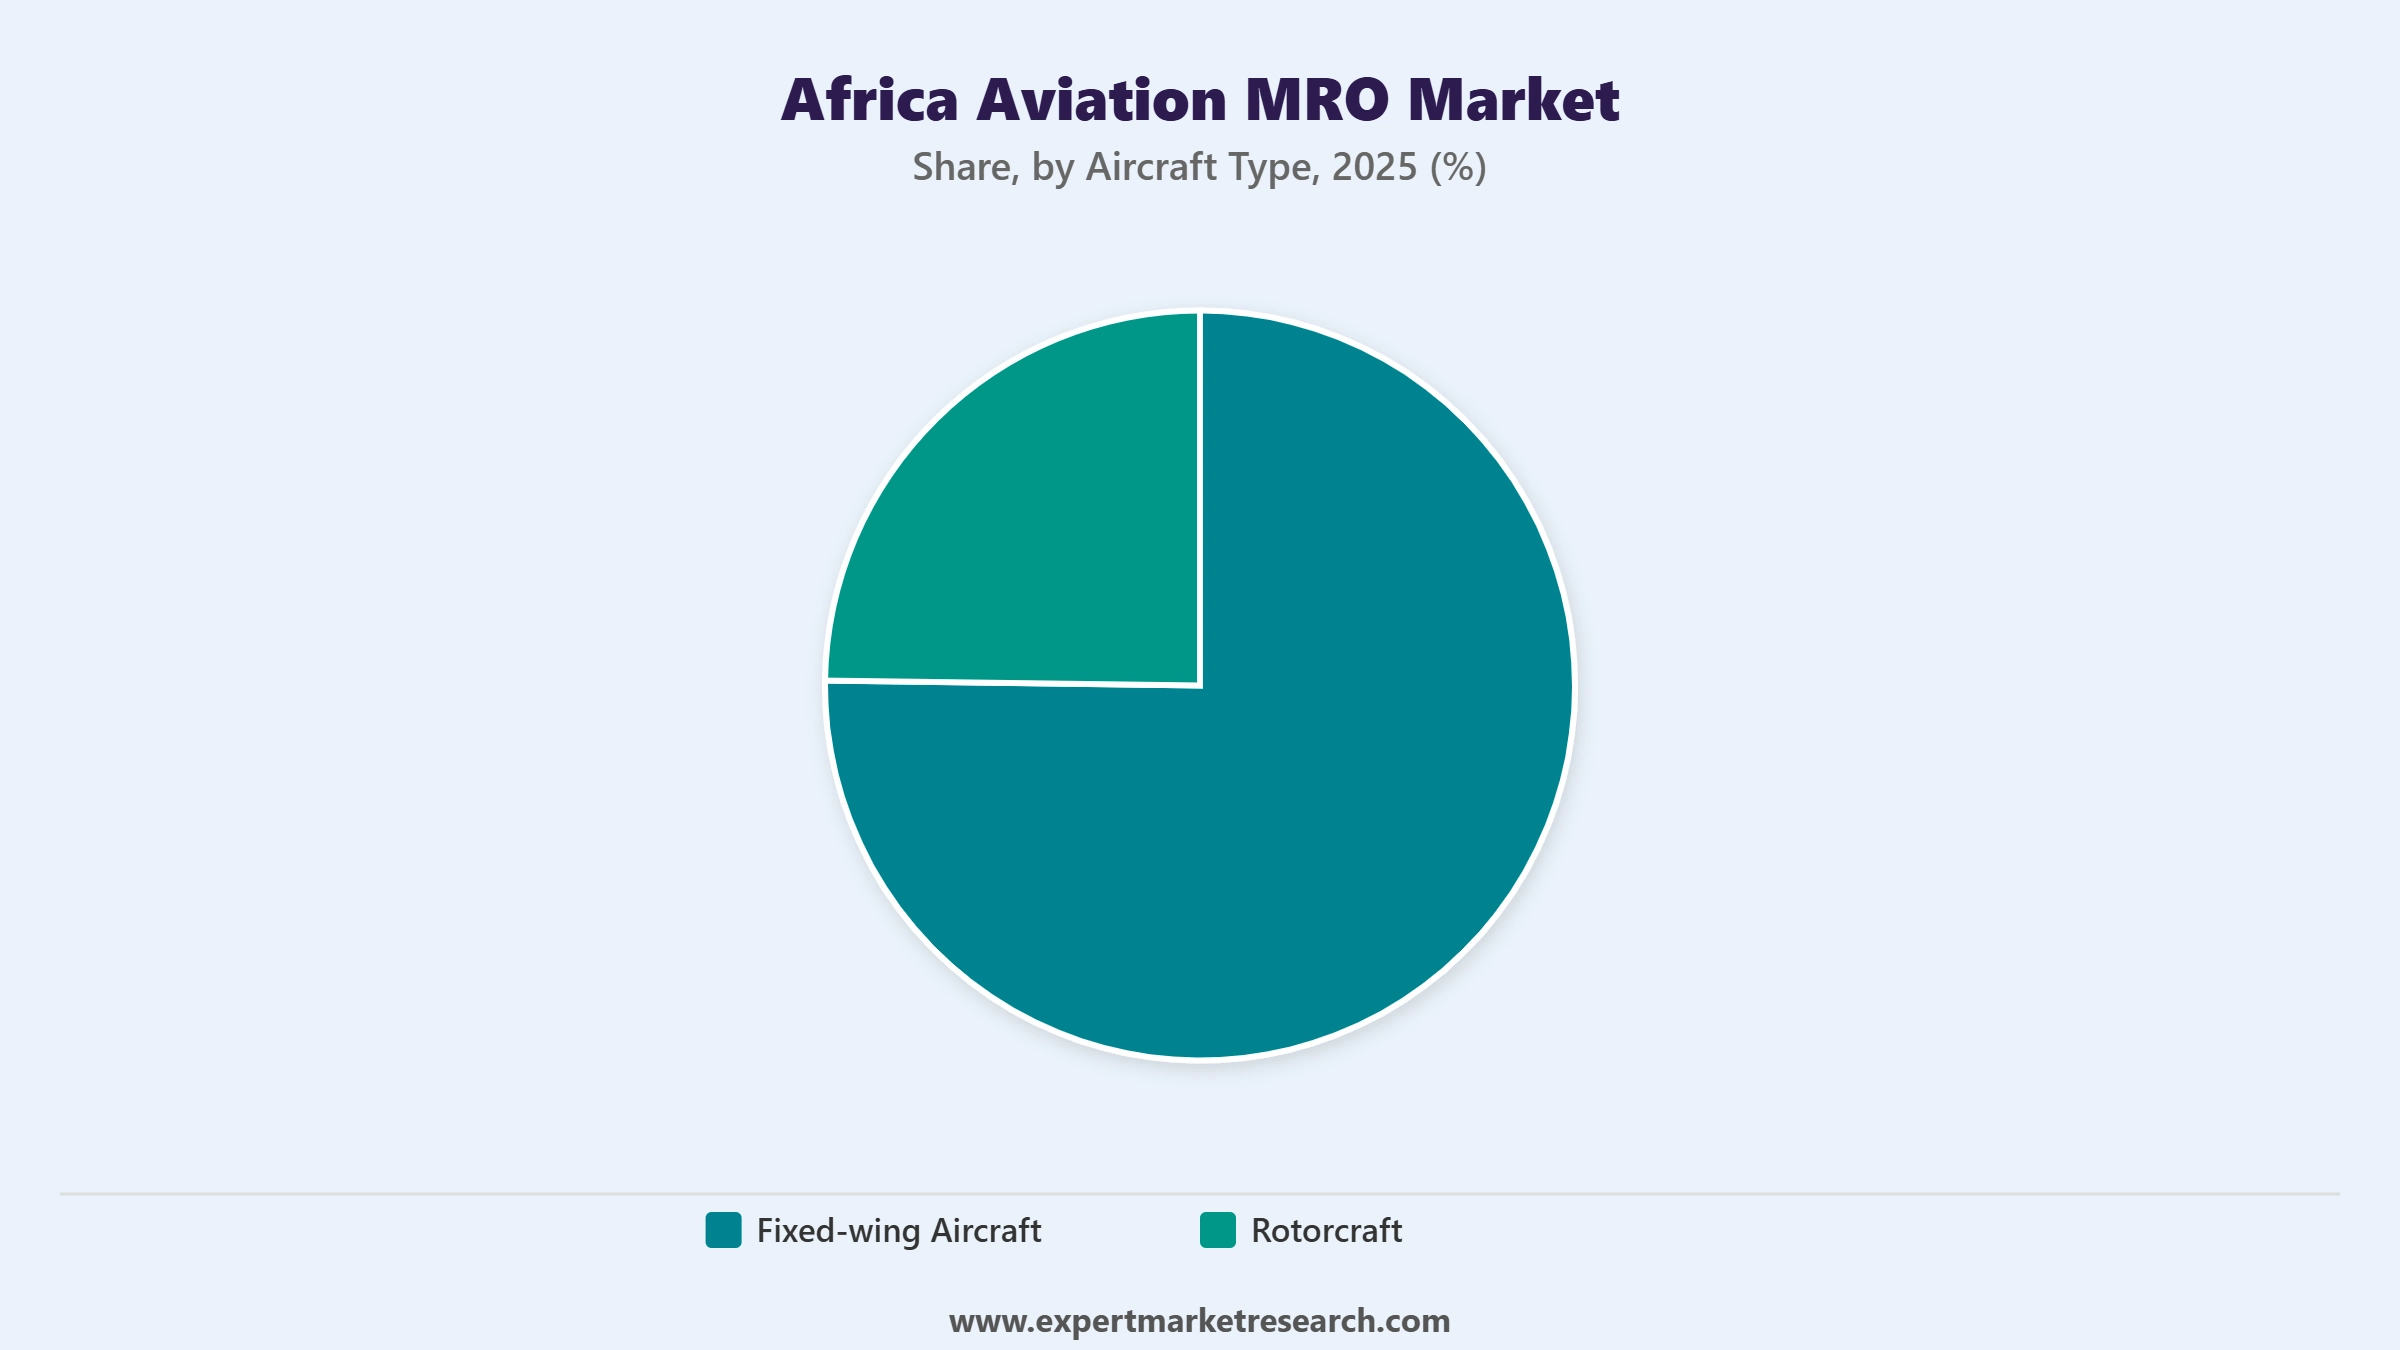
Key Insight: Fixed-wing aircraft represent a substantial share of the Africa aviation MRO market owing to the greater number of such aircraft operating across the continent for passenger and cargo transport. Rotorcraft is registering the fastest growth as offshore oil and gas support, medical evacuation, and law enforcement missions expand across West and East Africa, requiring specialised rotorcraft maintenance capability distinct from fixed-wing servicing.
Market Breakup by Organisation Type
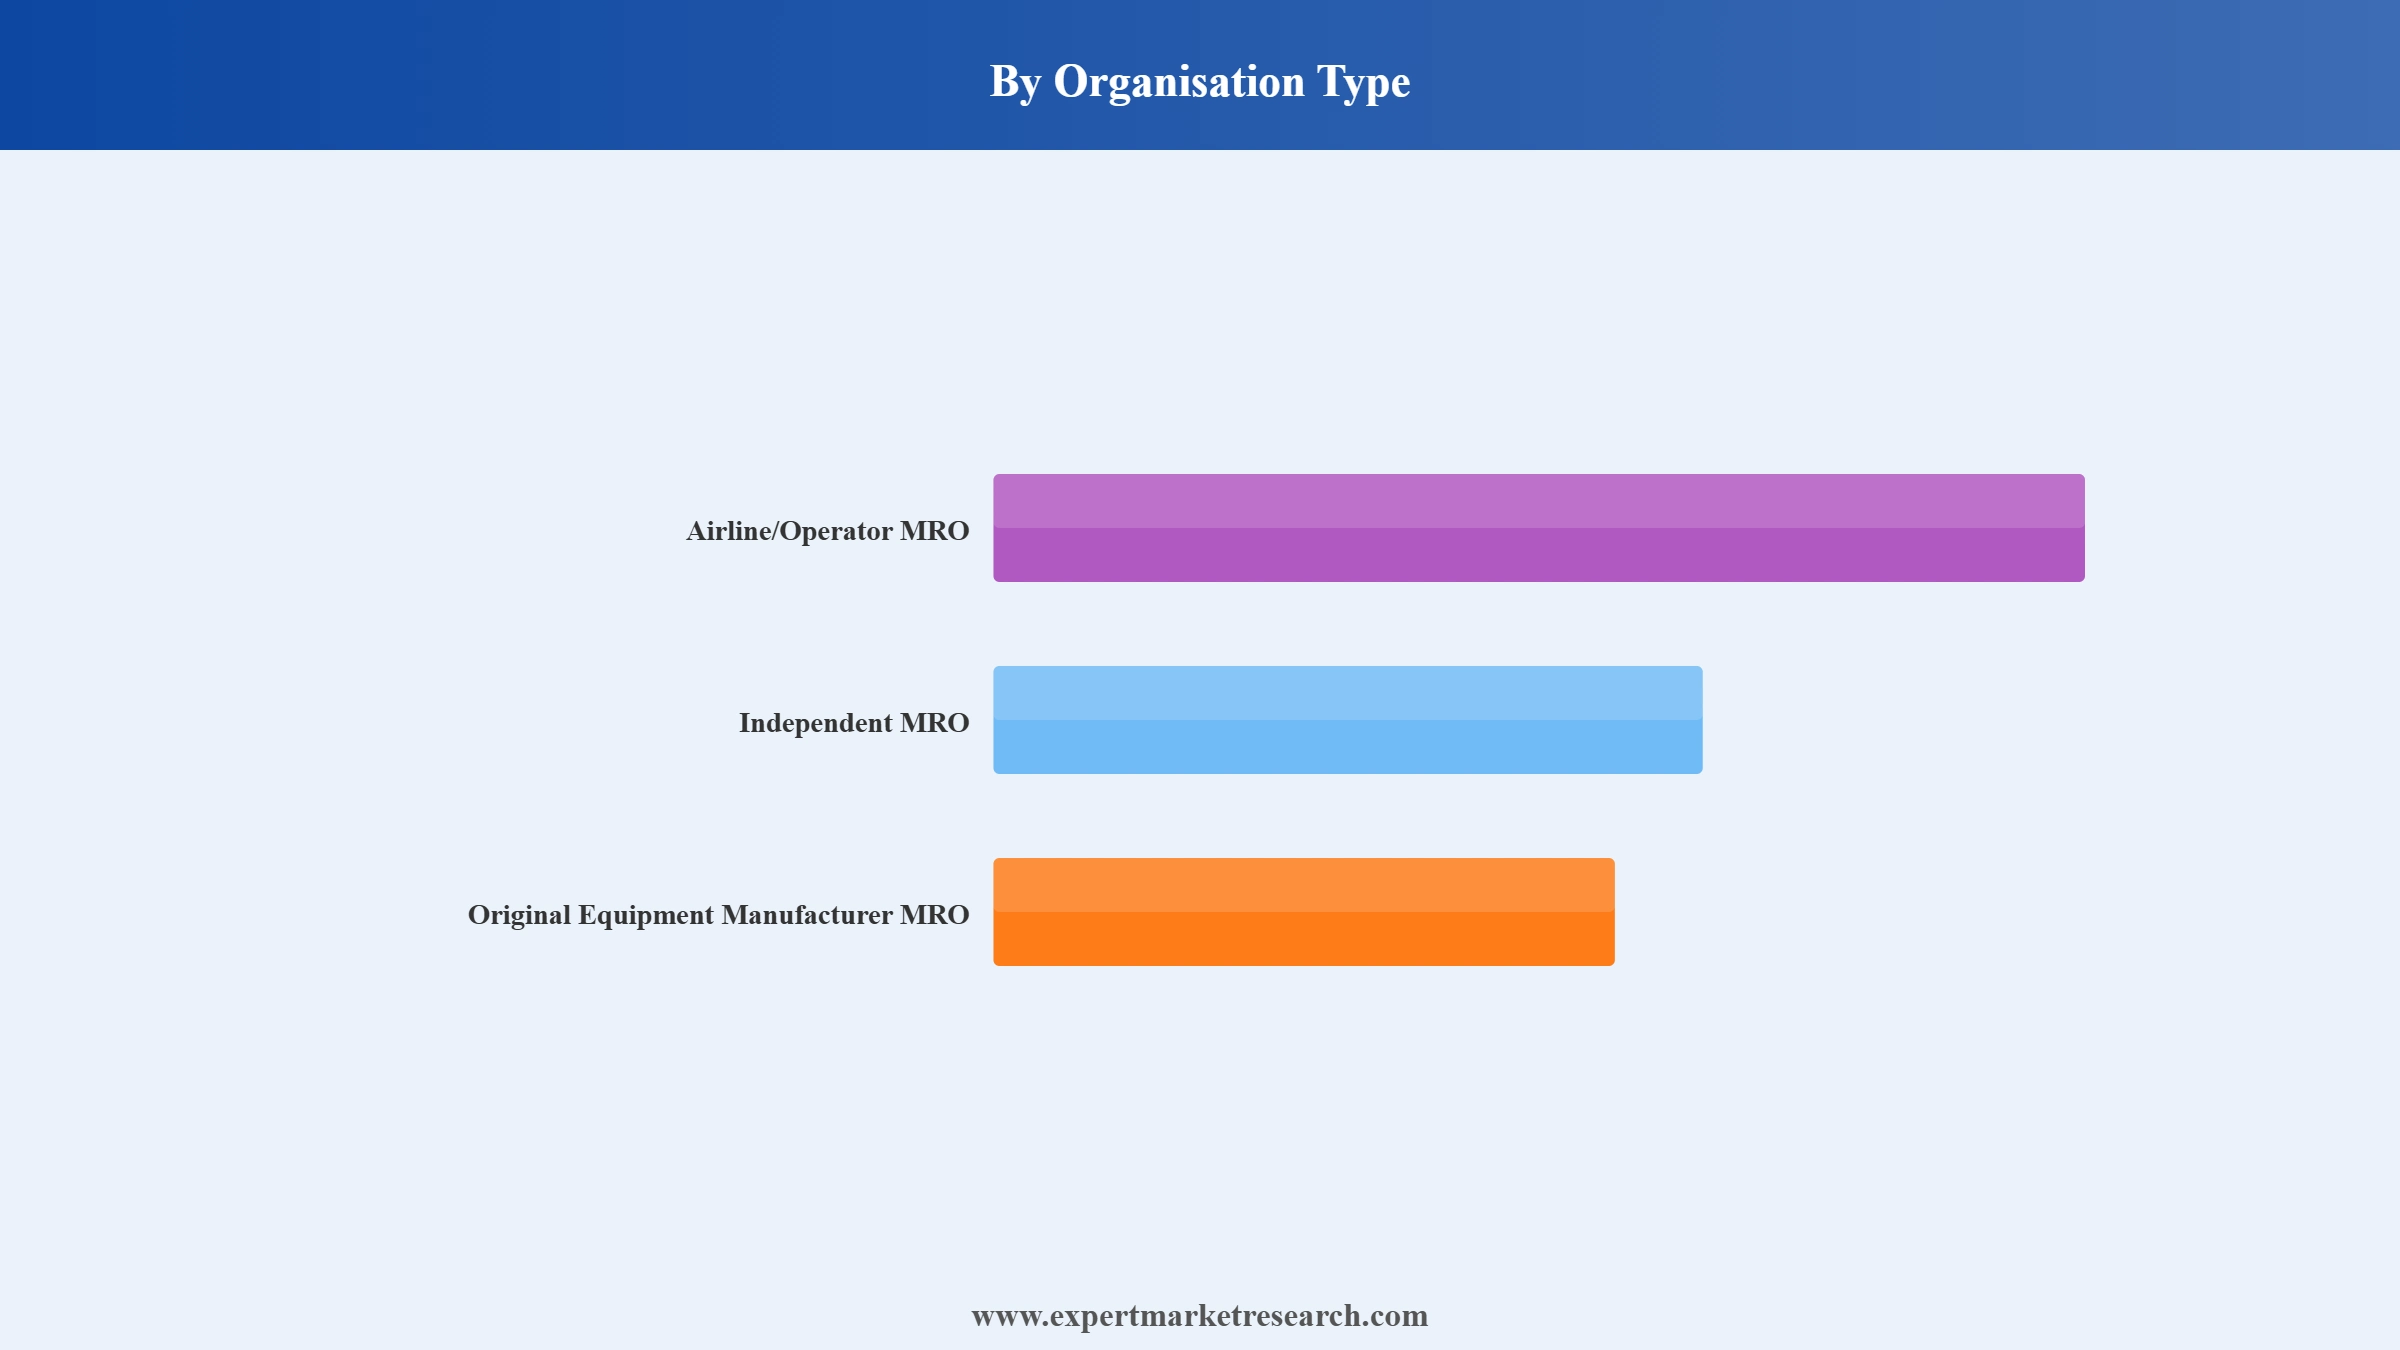
Key Insight: Airline and operator MRO accounts for a significant share as national carriers increasingly maintain their own fleets in-house to control costs and turnaround times. Independent MRO providers across the Africa aviation MRO market are gaining share as third-party maintenance demand grows across smaller operators lacking in-house capability. In August 2026, the African Airlines Association admitted component specialist Global Airtech as a Partner to strengthen aviation component supply chains across the continent, illustrating how original equipment manufacturer backed support networks are expanding to serve independent operators.
Market Breakup by Aviation Type
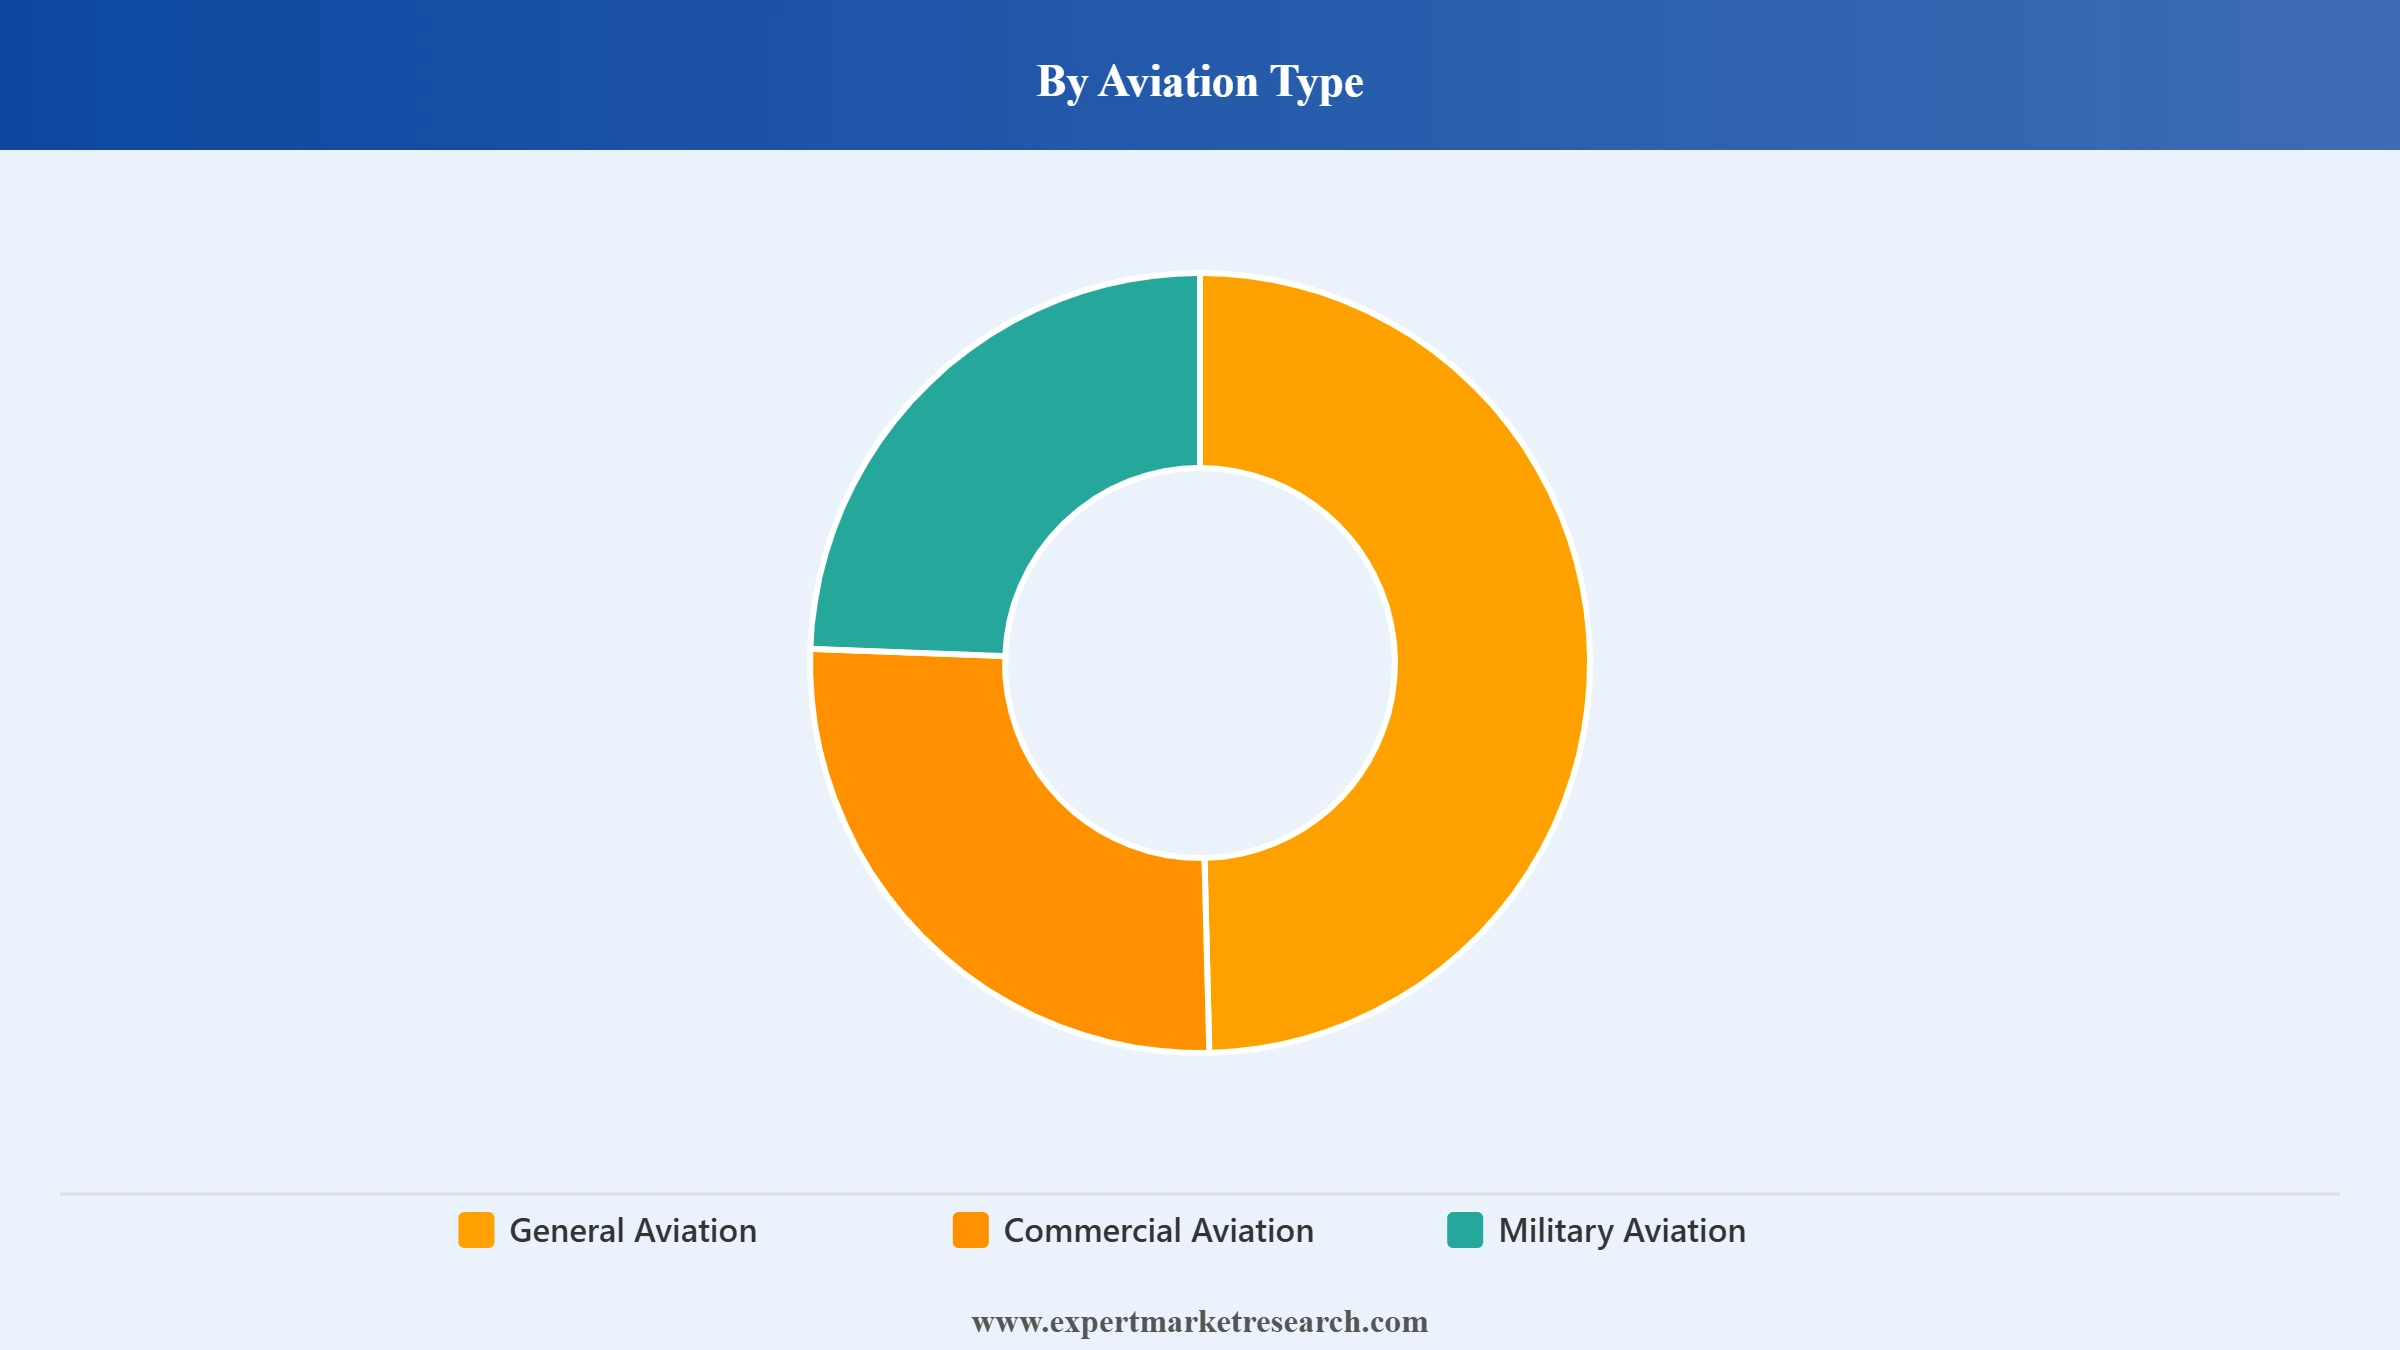
Key Insight: Commercial aviation dominates the Africa aviation MRO market as passenger and cargo carriers account for the bulk of maintenance activity across major African hub airports. Military aviation forms a substantial share, particularly in Egypt, given the country's large military aircraft fleet and modernisation priorities. General aviation, including business jets and private aircraft, remains a smaller but growing category as private aviation demand expands across South Africa, Nigeria, and Kenya.
Market Breakup by Region
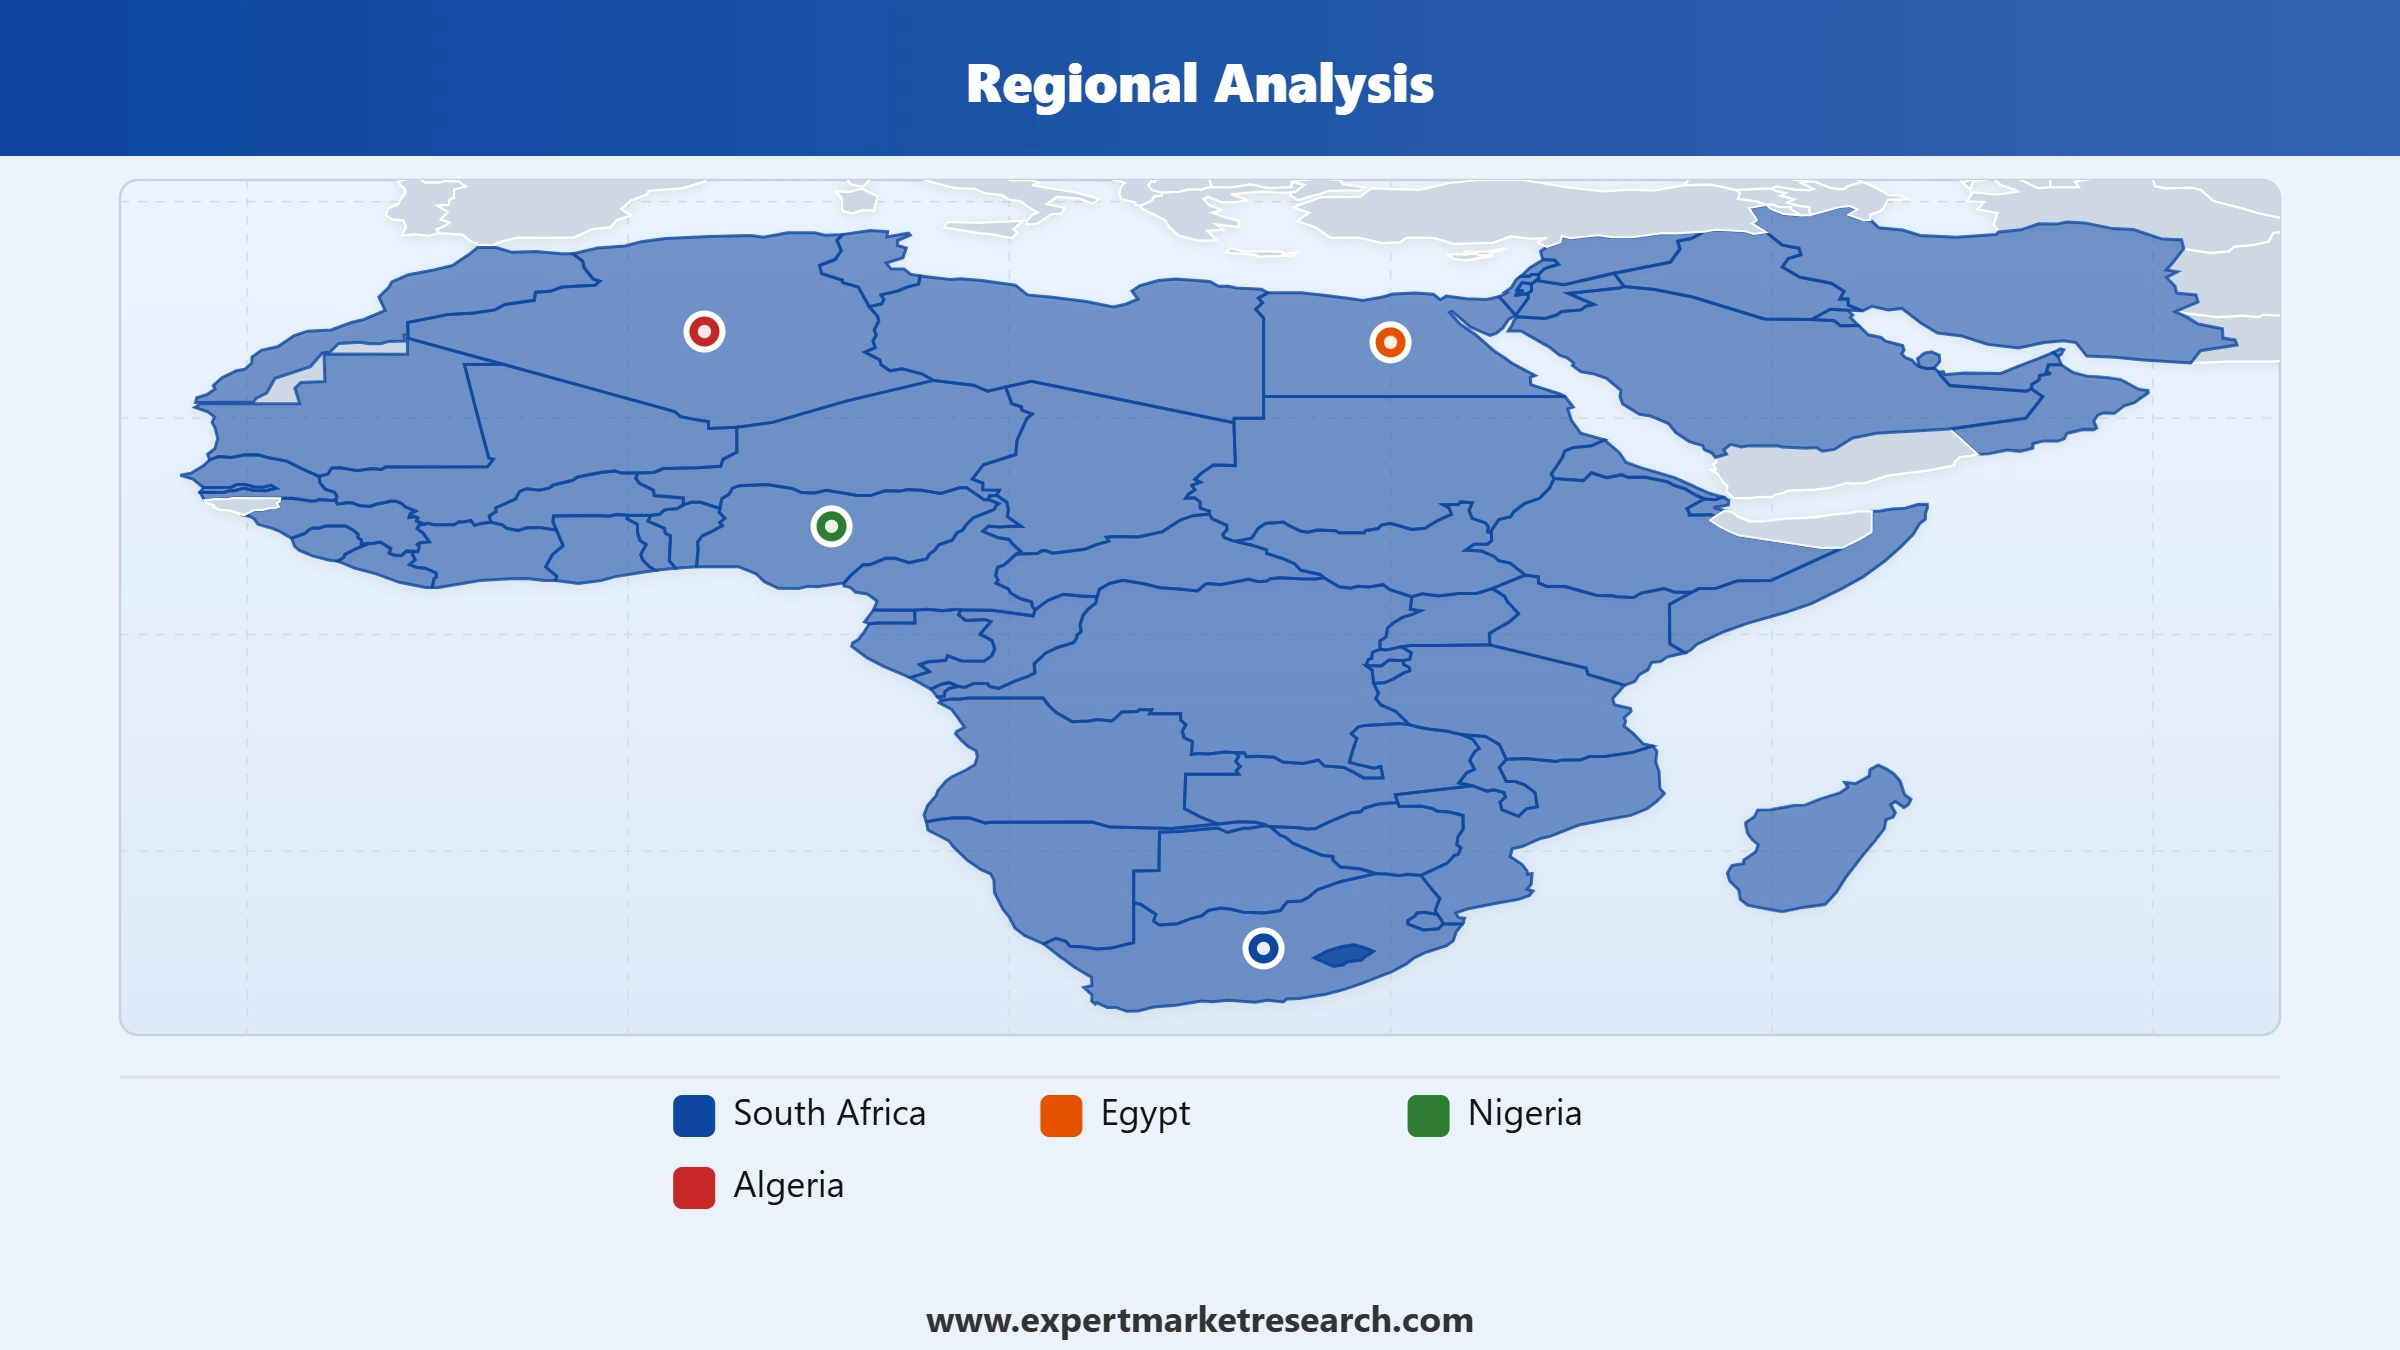
Key Insight: South Africa commands a substantial share of the Africa aviation MRO market, supported by a rising number of Part-145 certified maintenance facilities and established aerospace infrastructure built over decades. Egypt is anticipated to hold a major share during the forecast period, underpinned by its large military aircraft fleet and ongoing modernisation programmes. Nigeria is registering strong growth as private carriers and investors commit capital to new domestic MRO facilities, while Algeria continues expanding its aviation maintenance infrastructure to support both commercial and military fleet requirements. Others, including Kenya and Morocco, round out demand as smaller markets build local certification and facility capability.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By service, airframe MRO dominates the market owing to sustained structural maintenance needs across ageing African fleets
Airframe MRO accounts for the largest service share owing to sustained structural inspection and repair needs across the continent's ageing fleets in the Africa aviation MRO market. Providers serving this category continue to prioritise certified inspection capability accordingly, since airworthiness compliance depends on rigorous structural maintenance programmes. In August 2026, Nigerian carrier Binani Air announced a multimillion-dollar contract to construct a major MRO hangar at Nnamdi Azikiwe International Airport in Abuja, targeting completion within 12 months to reduce Nigeria's dependence on overseas heavy maintenance.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Engine overhaul is a fast-growing service category as African carriers seek to reduce reliance on sending engines abroad for specialised repair work. Providers serving this category continue to pursue international certification accordingly, since engine maintenance requires manufacturer-recognised accreditation that airlines evaluate closely. In September 2026, MTU Maintenance signed its first North African LEAP-1A engine contracts with Egyptian carrier Air Cairo, covering 42 engines powering 19 Airbus A320neo aircraft, delivered jointly from Germany and China.
By aircraft type, rotorcraft is the fastest-growing segment owing to expanding offshore support and medical evacuation missions
Fixed-wing aircraft represent the largest aircraft type share of the Africa aviation MRO market owing to the greater number of such aircraft operating across the continent for passenger and cargo transport. Providers serving this category continue to prioritise heavy maintenance and structural inspection capability accordingly, since fixed-wing fleets require periodic deep checks throughout their operational life. In July 2025, Somalia's Ministry of Transport signed for two Airbus A320 narrowbodies from Lima Holding Group, marking Somali Airlines' historic comeback after a 34-year hiatus and adding new fixed-wing maintenance demand to the region.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Rotorcraft is the fastest-growing aircraft type as offshore oil and gas support, medical evacuation, and law enforcement missions expand across West and East Africa. Providers serving this category continue to expand specialised technical capability accordingly, since rotorcraft maintenance demands expertise distinct from fixed-wing servicing. In March 2026, Bristow Group received the first two of five Airbus H160 medium-twin helicopters leased from Milestone Aviation Group, positioning it to operate one of the most modern offshore energy fleets in Nigeria.
By organisation type, airline and operator MRO leads the market owing to national carriers maintaining fleets in-house
Airline and operator MRO accounts for the largest organisation type share of the Africa aviation MRO market as national carriers increasingly maintain their own fleets in-house to control costs and turnaround times. Providers serving this category continue to prioritise vertical integration accordingly, since in-house maintenance reduces scheduling dependency on outside providers. In August 2025, Uganda Airlines completed its first in-house engine change on a CRJ900 at Entebbe's Eagle Air Hangar 7, a landmark coinciding with the carrier's sixth anniversary.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Independent MRO is registering steady growth as third-party maintenance demand increases across smaller operators across the Africa aviation MRO market lacking in-house capability. Providers serving this category continue to pursue OEM authorisation accordingly, since independent providers must demonstrate manufacturer-backed credibility to attract diverse customers. In February 2025, Honeywell Aerospace and ExecuJet Nigeria signed a memorandum of understanding appointing ExecuJet Nigeria as an authorised business and general aviation mechanical centre for Honeywell avionics and engine installations.
By aviation type, commercial aviation dominates the market owing to passenger and cargo carriers accounting for the bulk of maintenance activity
Commercial aviation dominates the aviation type segment as passenger and cargo carriers account for the bulk of maintenance activity across major African hub airports. Providers across the Africa aviation MRO market serving this category continue to prioritise rapid turnaround and scheduling reliability accordingly, since commercial carriers operate on tight route schedules that leave little room for extended delays. In July 2025, Air Algerie placed Africa's largest ATR order to date, ordering 16 ATR 72-600 regional aircraft powered by Pratt and Whitney PW127XT engines for a new domestic-focused subsidiary, expanding commercial fleet maintenance requirements.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Military aviation forms a substantial share of the market, particularly across West and North Africa, given large military fleets and ongoing modernisation priorities. Providers serving this category continue to prioritise security clearance and defence certification accordingly, since military contracts follow distinct procurement standards. In August 2026, the Nigerian Air Force completed factory acceptance testing for its first M-346FA jets, part of a broader acquisition that includes a 25-year maintenance, training, and fleet sustainment contract.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
South Africa leads the market through established aerospace infrastructure and rising Part-145 certified facility numbers
South Africa commands a substantial share of the market, supported by a rising number of Part-145 certified maintenance facilities and established aerospace infrastructure across the Africa aviation MRO market. In November 2025, ExecuJet MRO Services South Africa renewed its US Federal Aviation Administration certification alongside civil aviation approvals from Angola, Botswana, Malawi, Mozambique, Namibia, Nigeria, and Zambia, reinforcing Johannesburg's role as a regional business aviation maintenance hub spanning eight countries.
Egypt is anticipated to hold a major share of the Africa aviation MRO market during the forecast period, supported by its large military aircraft fleet and ongoing modernisation programmes. Algeria is registering strong momentum as national carrier Air Algerie accelerates fleet renewal, taking delivery of its first Airbus A330-900neo in November 2025 and its first Boeing 737 MAX 8 in July 2026, expanding maintenance requirements across multiple new aircraft families. Nigeria and Kenya continue building commercial MRO capability to serve growing West and East African demand.
The Africa aviation MRO companies are becoming increasingly consolidated as major Africa aviation MRO companies invest in certification, facility expansion, and technical partnerships to defend their market positions. Africa aviation MRO players are prioritising international accreditation, component repair capability, and local technician training to differentiate service offerings in a market where basic line maintenance is increasingly commoditised. Strategic emphasis on reducing overseas maintenance dependency is allowing providers to capture growing regional demand while attracting third-party customers beyond their own fleets.
Major Africa aviation MRO market players are also focusing on manufacturer partnerships, pursuing technical support agreements with global original equipment manufacturers to access training and certification pathways. Opportunities are emerging in rotorcraft maintenance and engine overhaul capability, as well as in collaborative maintenance arrangements among multiple carriers seeking shared cost efficiency. Companies that successfully combine international certification with local facility investment and manufacturer backed technical support are expected to strengthen their competitive position over the coming years.
Founded in 1929, and headquartered in Saint-Cloud, France supports the market through its Falcon business jet and military aircraft support network, offering maintenance and technical support for operators across the continent. The company's dual civil and military aircraft portfolio, spanning Falcon business jets and Rafale combat aircraft, provides a broad base of maintenance relationships across African government and private aviation customers. Dassault continues to expand its global support network following decades of aerospace manufacturing experience.
Founded in 1970, and headquartered in Leiden, Netherlands supports the market through its commercial aircraft and helicopter maintenance support network, serving operators across passenger, cargo, and rotorcraft segments. The company's broad product portfolio spanning the A320 family, wide-body aircraft, and Airbus Helicopters rotorcraft gives it an extensive installed base requiring ongoing maintenance support across African carriers. Airbus continues to pursue engagement with African governments on local MRO facility development.
Founded in 1948, and headquartered in Rome, Italy supports the market through its helicopter and defence aircraft maintenance capability, serving military and civil operators across the continent. The company's AgustaWestland helicopter portfolio and broader aerospace, defence, and security operations provide maintenance and technical support relationships across African defence and commercial aviation customers. Leonardo continues to leverage its global sites network to support regional maintenance requirements.
Founded in 1926, and headquartered in Cologne, Germany supports the market through its Lufthansa Technik maintenance division, providing technical support, component repair, and certification services to African carriers. The company's five-segment structure spanning passenger transport, logistics, MRO, catering, and IT services give it broad aviation sector expertise applicable across the African market. Lufthansa continues to serve international carriers requiring certified heavy maintenance support.
Other key players in the market include Saab AB, Pilatus Aircraft Ltd., Denel SOC Ltd., Ethiopian Airlines, Egyptair Maintenance & Engineering, Aero Contractors Company, Sabena Technics, South African Airways, and Direct Maintenance Group., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Africa aviation MRO market trends 2026 report. Discover regional growth patterns, service adoption, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 3.50% between 2026 and 2035.
Pursuing international certification, investing in domestic MRO facilities, forming collaborative maintenance committees among carriers, expanding rotorcraft and engine overhaul capability, and strengthening manufacturer backed technical partnerships across emerging African hub markets.
The increasing adoption of advanced technologies to optimise operations in the airline sector of different countries is one of the major trends in the market.
The major regional markets include South Africa, Egypt, Nigeria, and Algeria, among others.
The different services offered by aviation MRO include airframe MRO, components and modifications MRO, engine overhaul, line maintenance, and interior MRO.
The various organisation types considered in the market report are airline/operator MRO, independent MRO, and original equipment manufacturer MRO.
General aviation, commercial aviation, and military aviation are the major aviation types covered in the market report.
The key market players include Dassault Aviation SA, Saab AB, Leonardo S.p.A., Airbus SE, Pilatus Aircraft Ltd., Denel SOC Ltd., Deutsche Lufthansa AG, Ethiopian Airlines, Egyptair Maintenance & Engineering, South African Airways, Aero Contractors Company, Sabena Technics, and Direct Maintenance Group, among others.
The Africa aviation MRO market reached approximately USD 4082.00 Million in 2025, helped by fleet renewal and new hangar capacity across the continent.
The market is projected to reach USD 5758.06 Million by 2035, with Boeing forecasting around 6% annual passenger traffic growth for Africa.
Companies face ageing fleet maintenance complexity, a shortage of certified technicians, high capital costs for facility and certification investment, and continued reliance on foreign providers for specialised engine and component work across diverse national regulatory environments.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Service |
|
| Breakup by Aircraft Type |
|
| Breakup by Organisation Type |
|
| Breakup by Aviation Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




