

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The global air quality control systems market attained a value of USD 120863.86 Million in 2025 and is projected to grow at a CAGR of 5.00% through 2035. The market is further expected to reach USD 196874.48 Million by 2035. Tighter emission limits, urban pollution action plans, and rising attention to indoor air are supporting growth in the market.
Air quality control systems are equipment and services that measure, filter, and treat pollutants in indoor and outdoor air. They include monitoring stations, filters, scrubbers, catalysts, and ventilation controls used in power plants, factories, tunnels, stations, buildings, and vehicles. Demand follows emission rules, urban pollution action plans, industrial output, and health awareness. Suppliers earn revenue from equipment sales, engineering contracts, consumables such as filter media and catalysts, and long-term service agreements with plant owners, building managers, and public agencies.
Pollution control spending is supported by public health programs and growing evidence linking fine particles to illness. Governments are tightening limits for sulphur dioxide and dust, and aging filter replacement creates recurring orders. In September 2026, Fuel Tech announced air pollution control contracts valued at about USD 2.8 million, including a urea reagent delivery system for a United States utility expanding a plant with natural gas fired turbines and engines. Buyers weigh lifecycle cost, energy use, and reliability when choosing.
Competition combines large engineering groups, filtration specialists, and many regional contractors. Suppliers are widening ranges through purchases of catalyst, filtration, and cleanroom businesses, investing in digital monitoring, and offering performance guarantees. Competitive positioning rests on technical references, local project delivery, and aftermarket service. Price pressure is strongest in standard filters and monitors, while custom engineered systems for power, metals, and chemicals keep higher margins and longer contracts with plant owners. Long project cycles mean wins can shape revenue for years.
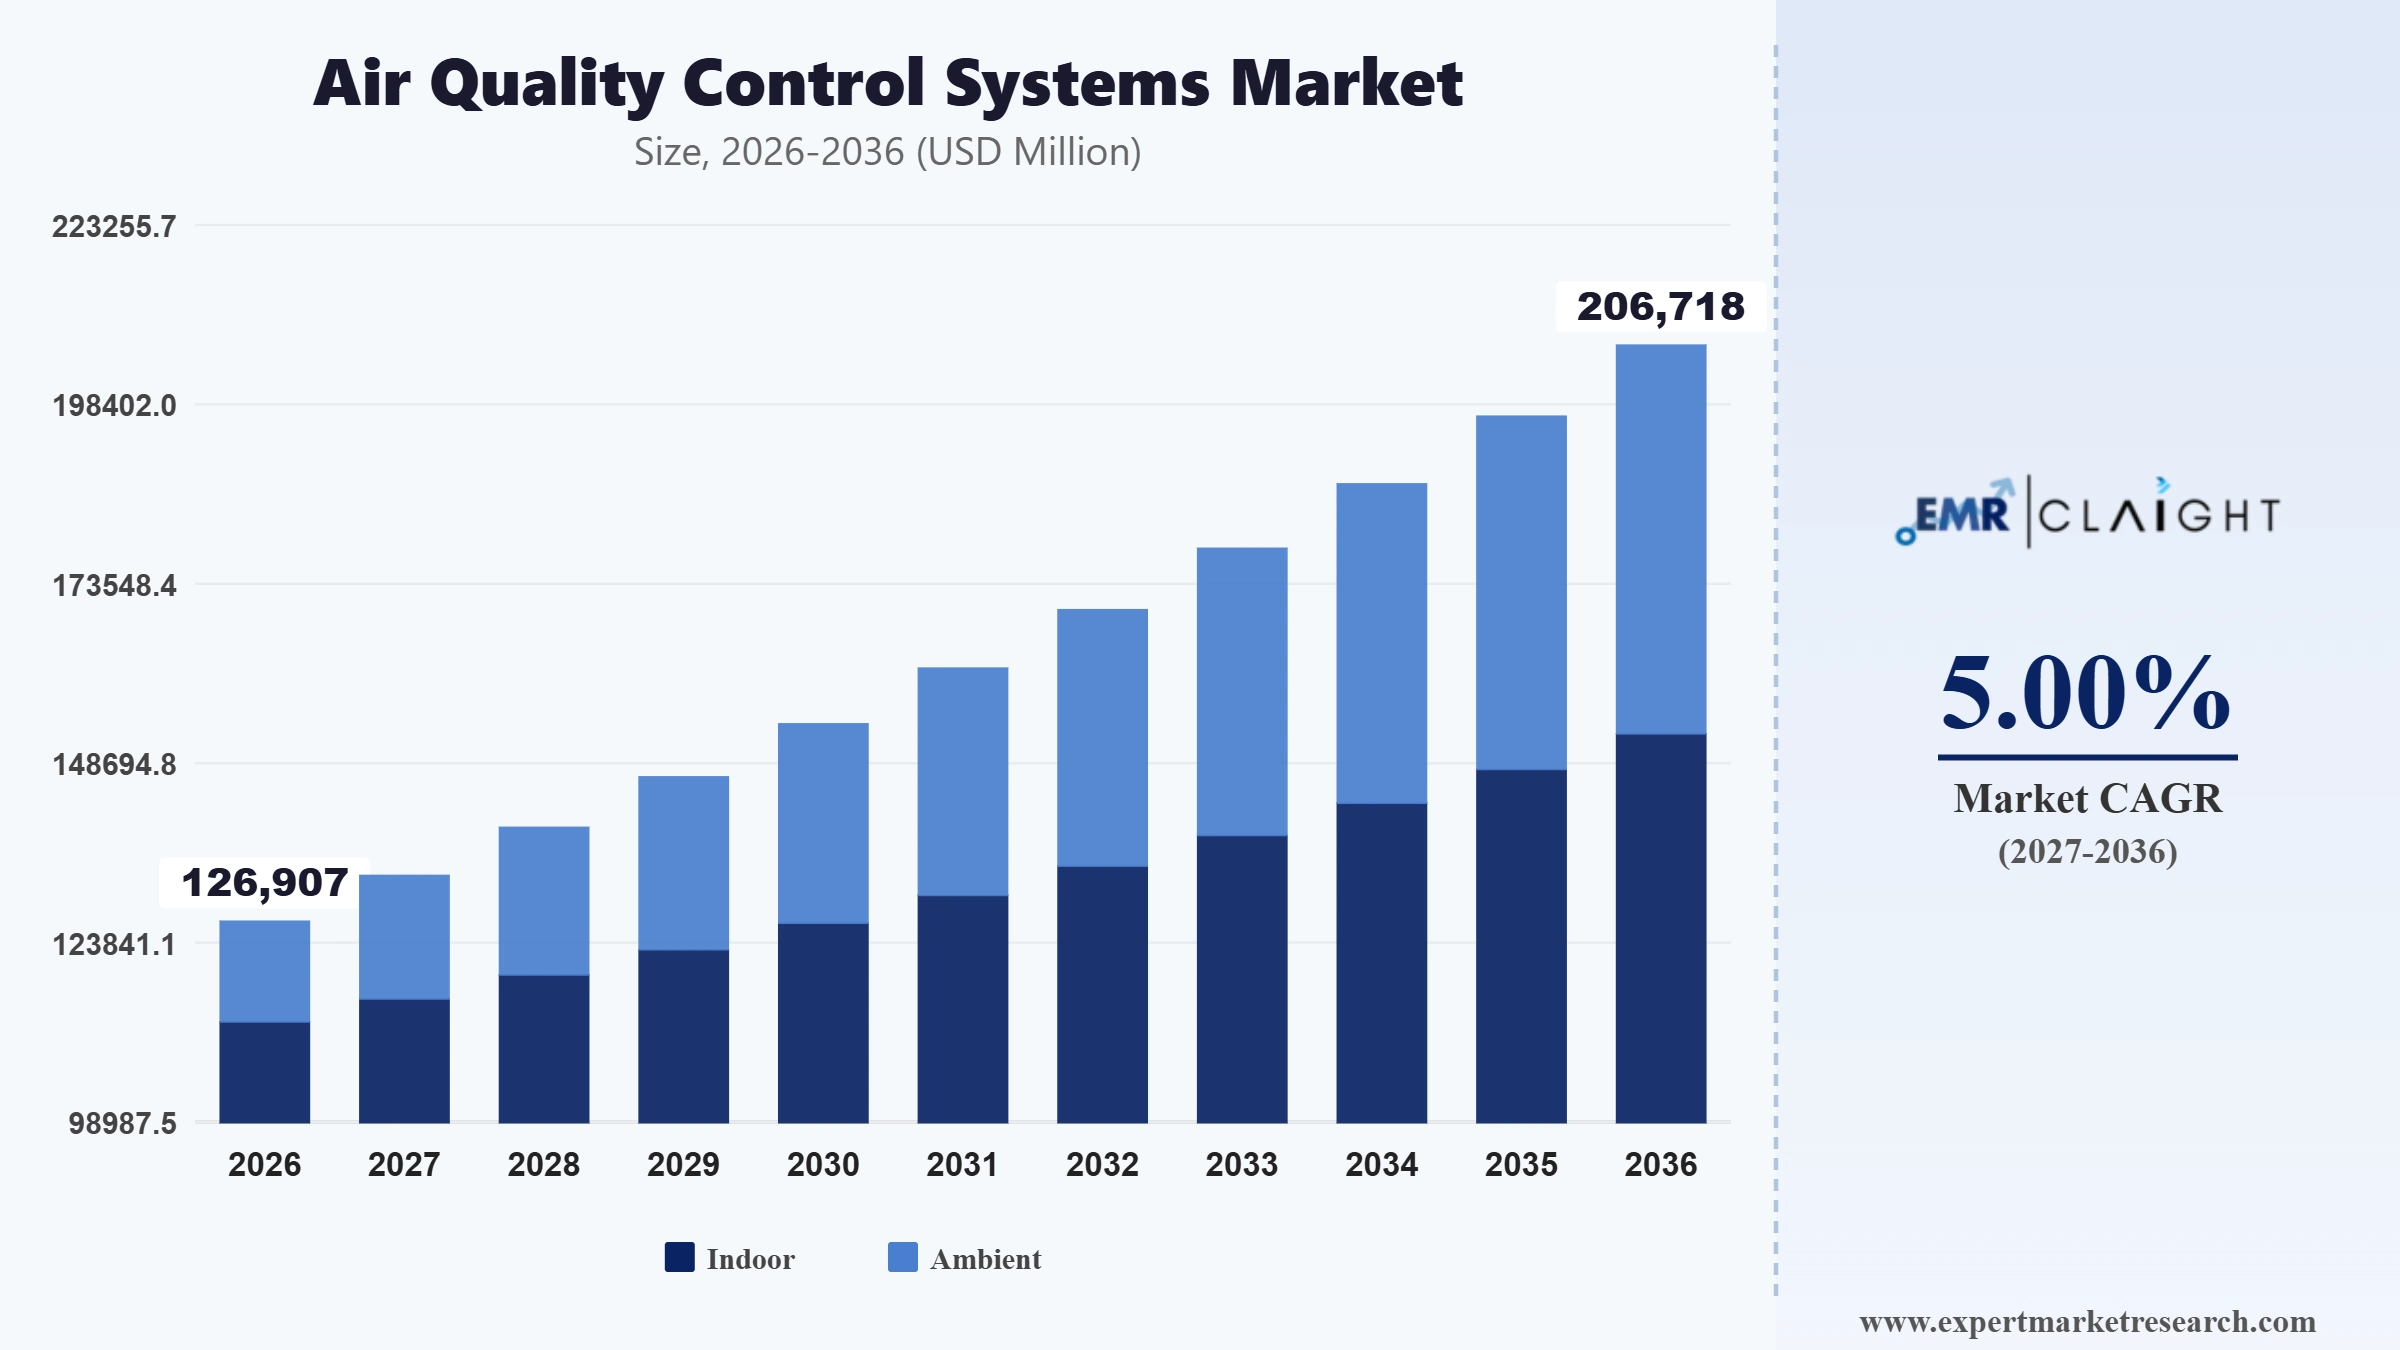
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The acquisition widened a specialized air filtration group's offering and reach across North America and Europe, with engineering teams combining to develop new filtration products for industrial and healthcare users. Terms were not disclosed. Suppliers across the air quality control systems market can leverage this trend by acquiring niche purification businesses, which broadens ranges, adds customers in laser cutting and soldering, and strengthens their market position overall.
The launch brought three purifiers to the indoor segment, including a large model that removes particles, gases, and formaldehyde and a compact version with an ionizer and ultraviolet lamp, with quiet nozzles lowering noise. Brands across the air quality control systems market can leverage this trend by pairing gas removal with low noise, which helps them win share in homes and offices across cities and urban markets.
The acquisition added DeNOx systems that cut nitrogen oxide emissions for refining, petrochemical, and waste processing customers, along with intellectual property and staff. The price was not disclosed. Technology providers across the air quality control systems market can leverage this trend by acquiring specialist units, which brings customers and service relationships quickly and widens environmental portfolios well beyond their core engineering and licensing businesses in many regions.
The agreement covers a United States maker of selective catalytic reduction catalysts for power generation and industrial uses, at an enterprise value of USD 360 million payable in cash, creating a leader in stationary emissions control. Catalyst makers can leverage this trend by building scale for retrofit demand and spreading research costs across many more customers and end use applications.
Carmakers across the air quality control systems market in polluted cities are treating cabin air as a selling feature, and filter makers are gaining volume from vehicle production. In October 2025, JSW MG Motor announced PM 2.5 air filters and air purifiers across its range, including the Comet EV, Windsor EV, Astor, Hector, ZS EV, and Gloster, with the Hector also getting a built-in air quality display. Rival brands are following with similar cabin features across popular models, and aftermarket sales may grow in dense cities.
Filtration groups across the air quality control systems market are buying specialists to widen their offers, and adsorbent expertise is helping them serve gas phase pollution in electronics and pharmaceutical facilities. In March 2026, Camfil acquired Bioconservacion (Bion), a Spain based supplier of air filtration products and adsorbents for industrial and commercial clients, to expand its Molecular Contamination Control division. The price was not disclosed, and the target joined the Spanish arm and specialist team, giving engineers one group for filters, adsorbents, and technical advice for clients.
Private equity backed groups across the air quality control systems market are consolidating cleanroom specialists and buy and build strategies are speeding consolidation while smaller suppliers gain scale. In January 2026, Cleanova, a filtration manufacturer owned by PX3 Partners, announced the acquisitions of Airflotek and TES-Clean Air Systems, two United States companies that supply cleanroom air filtration and controlled environment systems, giving it a foothold in semiconductor, biotech, and pharmaceutical markets, where clean air standards are strict and replacement cycles are regular for filters and control systems.
Industrial air filtration is attracting large strategic buyers, and data center growth is creating a new source of filtration demand. In January 2026, Atmus Filtration reported completion of its acquisition of Koch Filter Corporation for about USD 450 million in cash and launched an Industrial Solutions segment, with end markets including commercial and industrial HVAC, data centers, and power generation. Engine filter specialists are using acquisitions to diversify, and large buyers are paying for service networks and recurring replacement sales.
Engineering groups across the air quality control systems market are reporting larger order books, and large orders are converting to revenue over several quarters, which smooths earnings for project suppliers. In July 2026, Thermax reported first quarter fiscal 2027 consolidated revenue of INR 2,303 crore, up 7%, and an order book of INR 14,045 crore, up 23% from a year earlier, while order inflow rose 2% to INR 2,809 crore. Suppliers are now seeing steady demand, which supports capacity planning, hiring, and investment in digital monitoring tools.
The Expert Market Research's report titled "Global Air Quality Control Systems Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
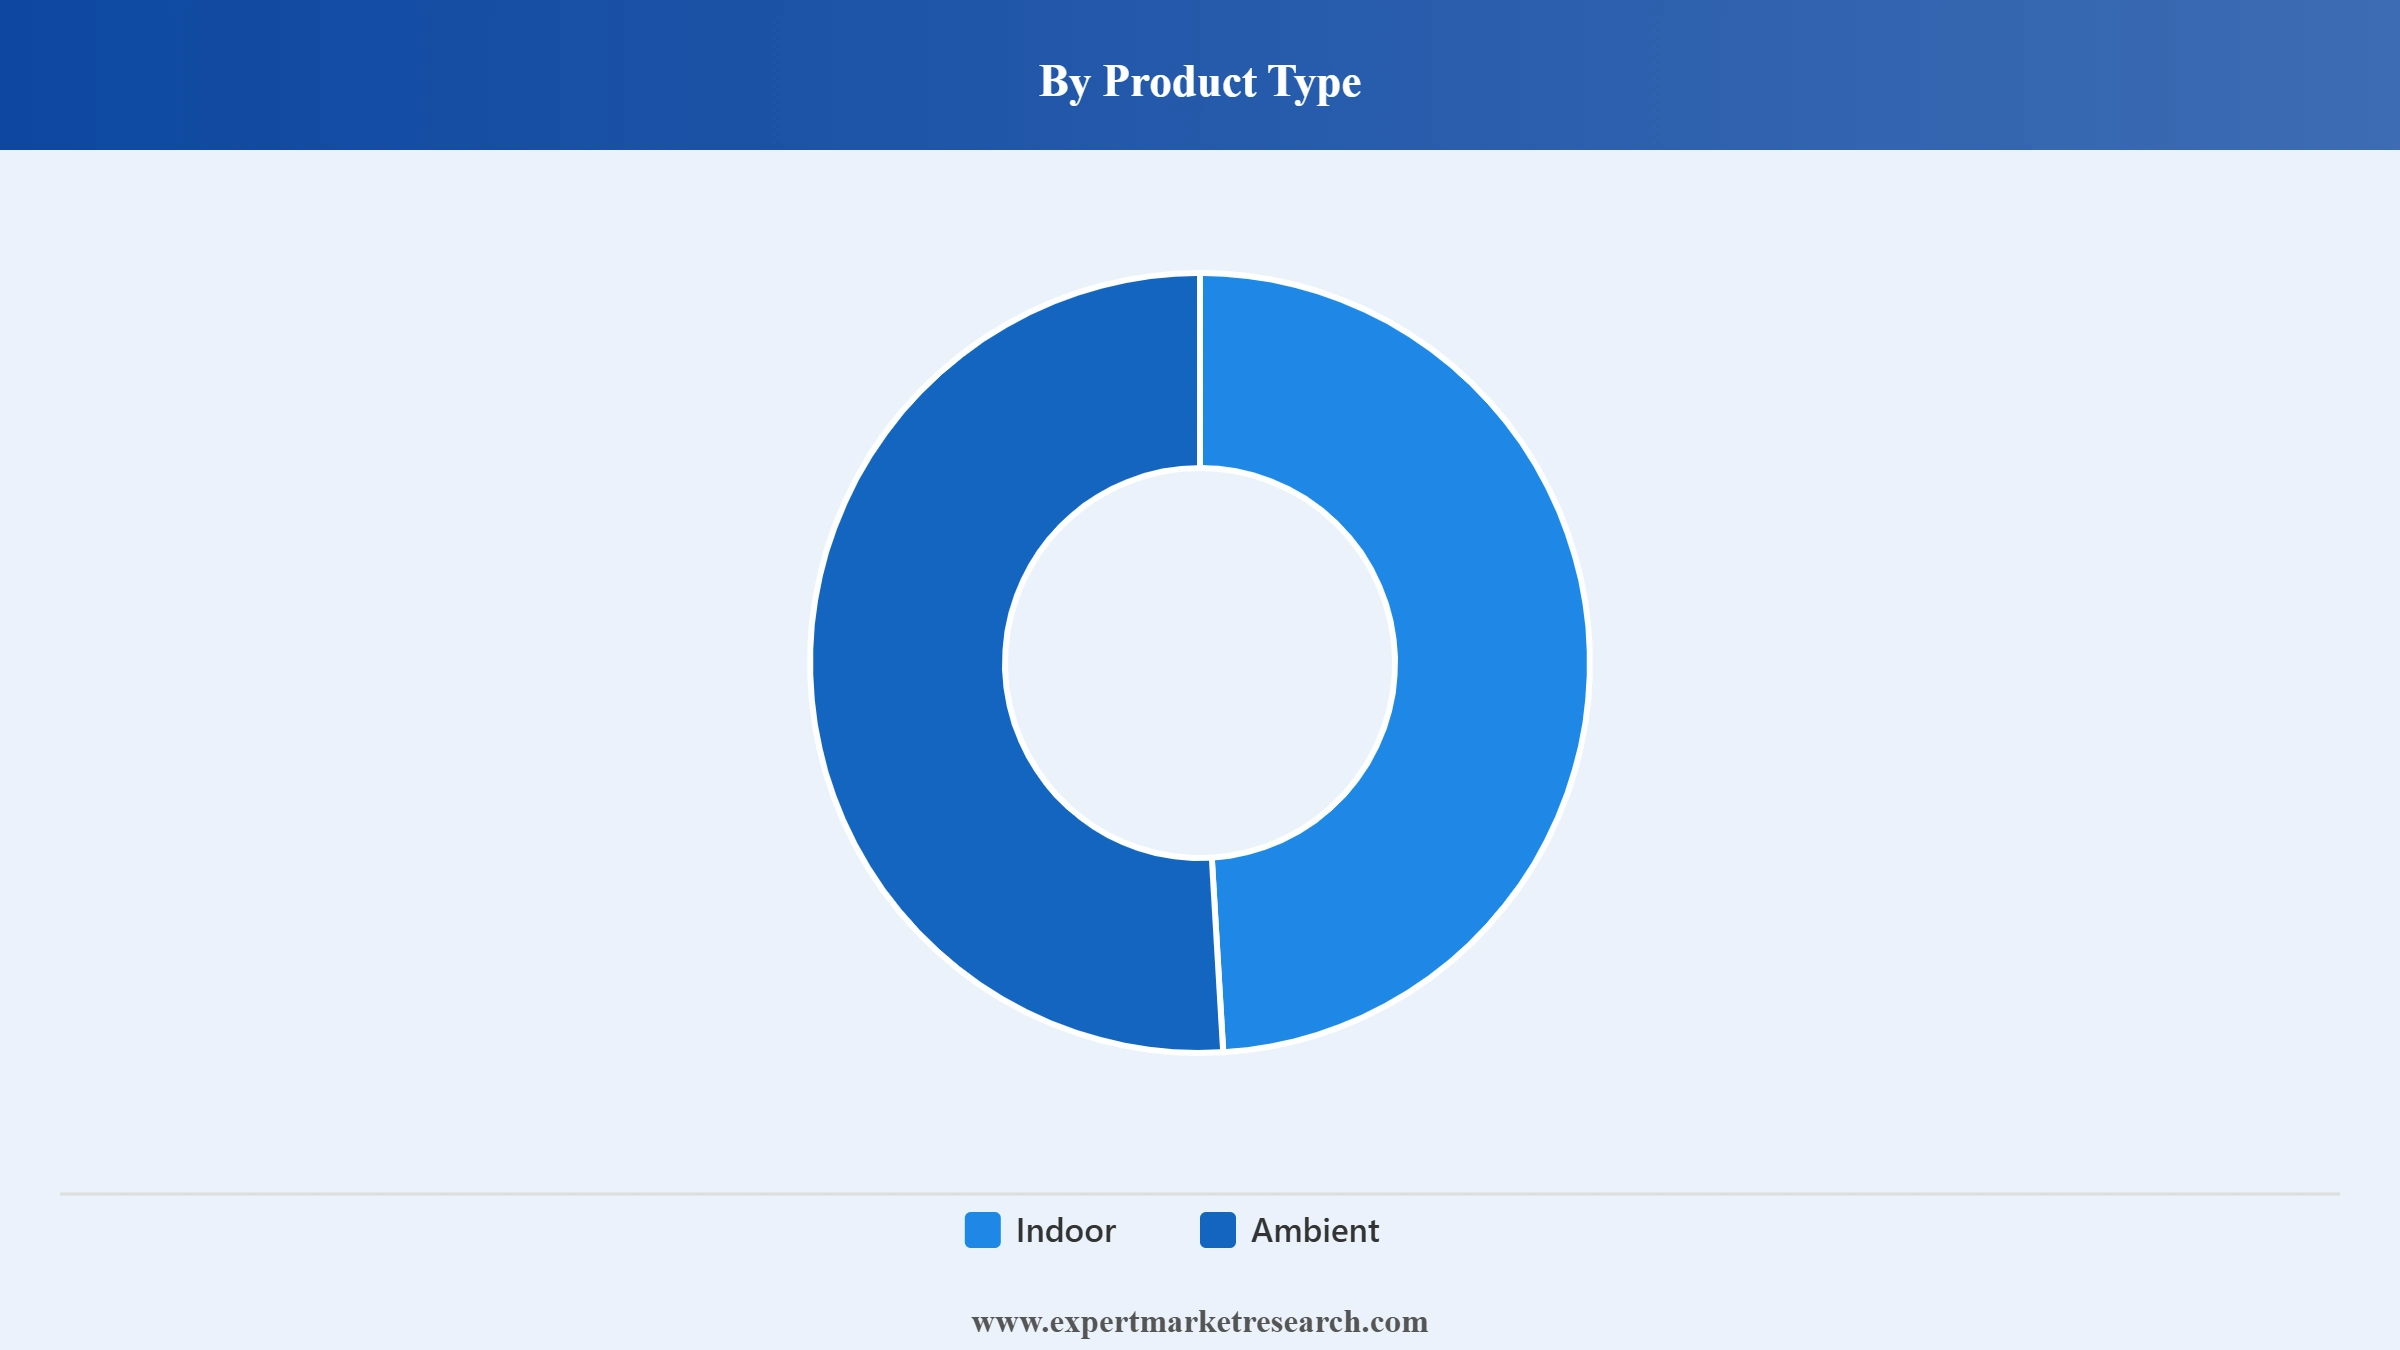
Key Insight: Indoor leads the product type segment of the air quality control systems market, since buildings, vehicles, and factories all need filtration and ventilation controls. Ambient is expected to grow fastest, as cities and plants expand outdoor monitoring, scrubbing, and emission control. Indoor products include purifiers, filters, and ventilation controls, while ambient systems include monitoring stations, scrubbers, collectors, and catalysts. Purchase decisions depend on pollutant mix, energy use, filter life, and rules set by building owners and environmental agencies in each region. Large buyers also request service contracts covering filter changes.
Market Breakup by Pollutant Type
Key Insight: Gas leads the pollutant type segment of the air quality control systems market, as sulphur dioxide and nitrogen oxide limits drive scrubber and catalyst demand. Dust is expected to grow fastest, as stricter particulate limits push upgrades of filters and collectors. Volatile organic compounds are controlled in coating, printing, chemical, and wood processing plants through oxidizers and adsorbents, while others include mercury, odor, and acid gases. Selection depends on emission limits, gas volume, temperature, and the cost of reagents and disposal. Reagent supply and waste handling add to lifetime cost.
Market Breakup by Application
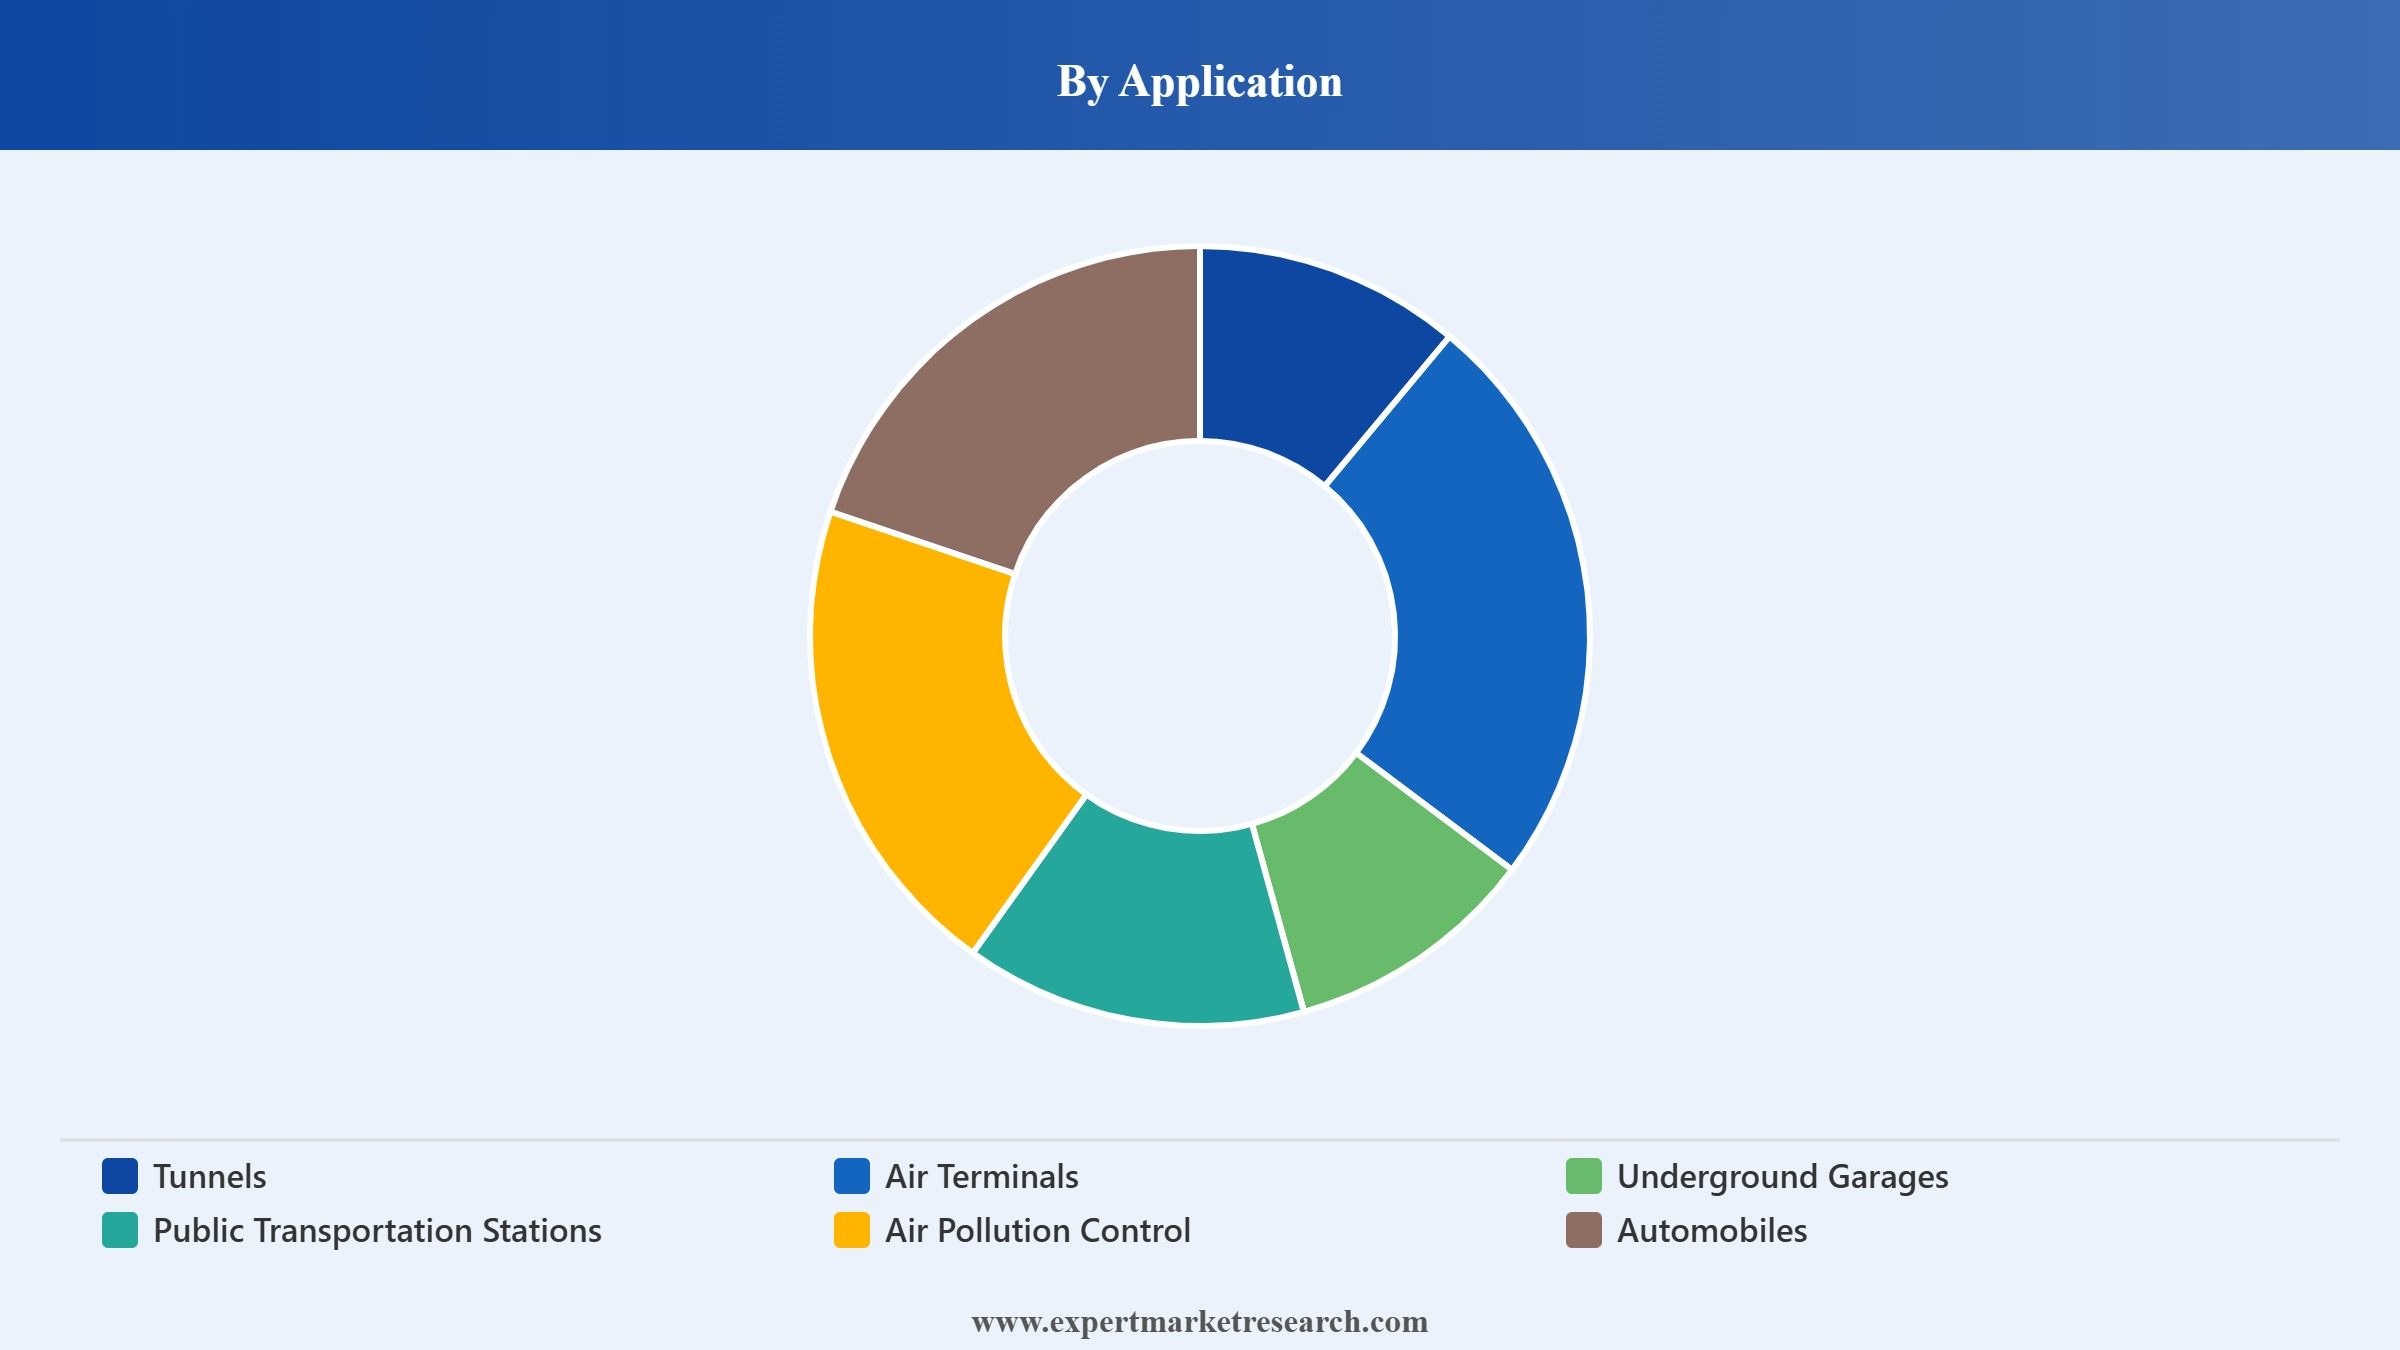
Key Insight: Air pollution control leads the application segment of the air quality control systems market, as industrial plants invest heavily to meet permits. Public transportation stations are expected to grow fastest, as metro and rail operators modernize ventilation and filters. Tunnels, air terminals, and underground garages need fans, sensors, and filters to manage vehicle exhaust and enclosed air, while automobiles use cabin filters and sensors. Safety codes, passenger comfort, and energy cost guide system design in each type of facility. Operators also weigh maintenance access and downtime during peak hours.
Market Breakup by Region
Key Insight: Asia Pacific leads the regional landscape of the air quality control systems market, backed by heavy industry and large urban pollution programs in China, India, and ASEAN. Middle East and Africa is expected to grow fastest, as new power, petrochemical, and metro projects specify emission control. North America focuses on retrofits and rule compliance, Europe follows strict industrial emission limits and indoor air standards, and Latin America grows with mining, cement, and urban transport investment across the region. Local rules and funding shape the pace of adoption in each country.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By product type, indoor dominates the air quality control systems market owing to widespread filtration needs in buildings and vehicles
Indoor holds the largest share of the product type segment, because homes, offices, hospitals, schools, factories, and vehicles all need filtration, ventilation controls, and purification equipment. Buyers replace filters on regular schedules, which creates steady consumables sales beside equipment orders. Building codes, health awareness, and energy efficiency programs encourage upgrades to higher grade filters and controls. Suppliers sell through HVAC contractors, distributors, and online channels, and large facilities sign service contracts that cover monitoring and filter changes at each site.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Ambient is registering the fastest growth within the product type segment in the air quality control systems market, as cities and agencies expand outdoor monitoring and control programs. Sensor networks give residents and regulators near real time data on fine particles and gases, and public dashboards raise pressure for action. In February 2026, the Chicago Department of Public Health and the University of Illinois Chicago opened public access to 277 solar powered sensors measuring PM2.5 and nitrogen dioxide on city light poles across roughly 60 ZIP codes.
By pollutant type, gas dominates the air quality control systems market owing to strict limits on sulphur dioxide and nitrogen oxides
Gas holds the largest share of the pollutant type segment, because power plants, refineries, cement kilns, and chemical sites must control sulphur dioxide, nitrogen oxides, and other gaseous emissions under permit limits. Scrubbers, catalysts, and monitoring analyzers are sold for new plants and retrofits, and owners also buy replacement catalysts and reagents. Rules are tightening in Asia and the Middle East, while mature regions keep investing to meet updated limits and keep older plants compliant during continued operation and upgrades.
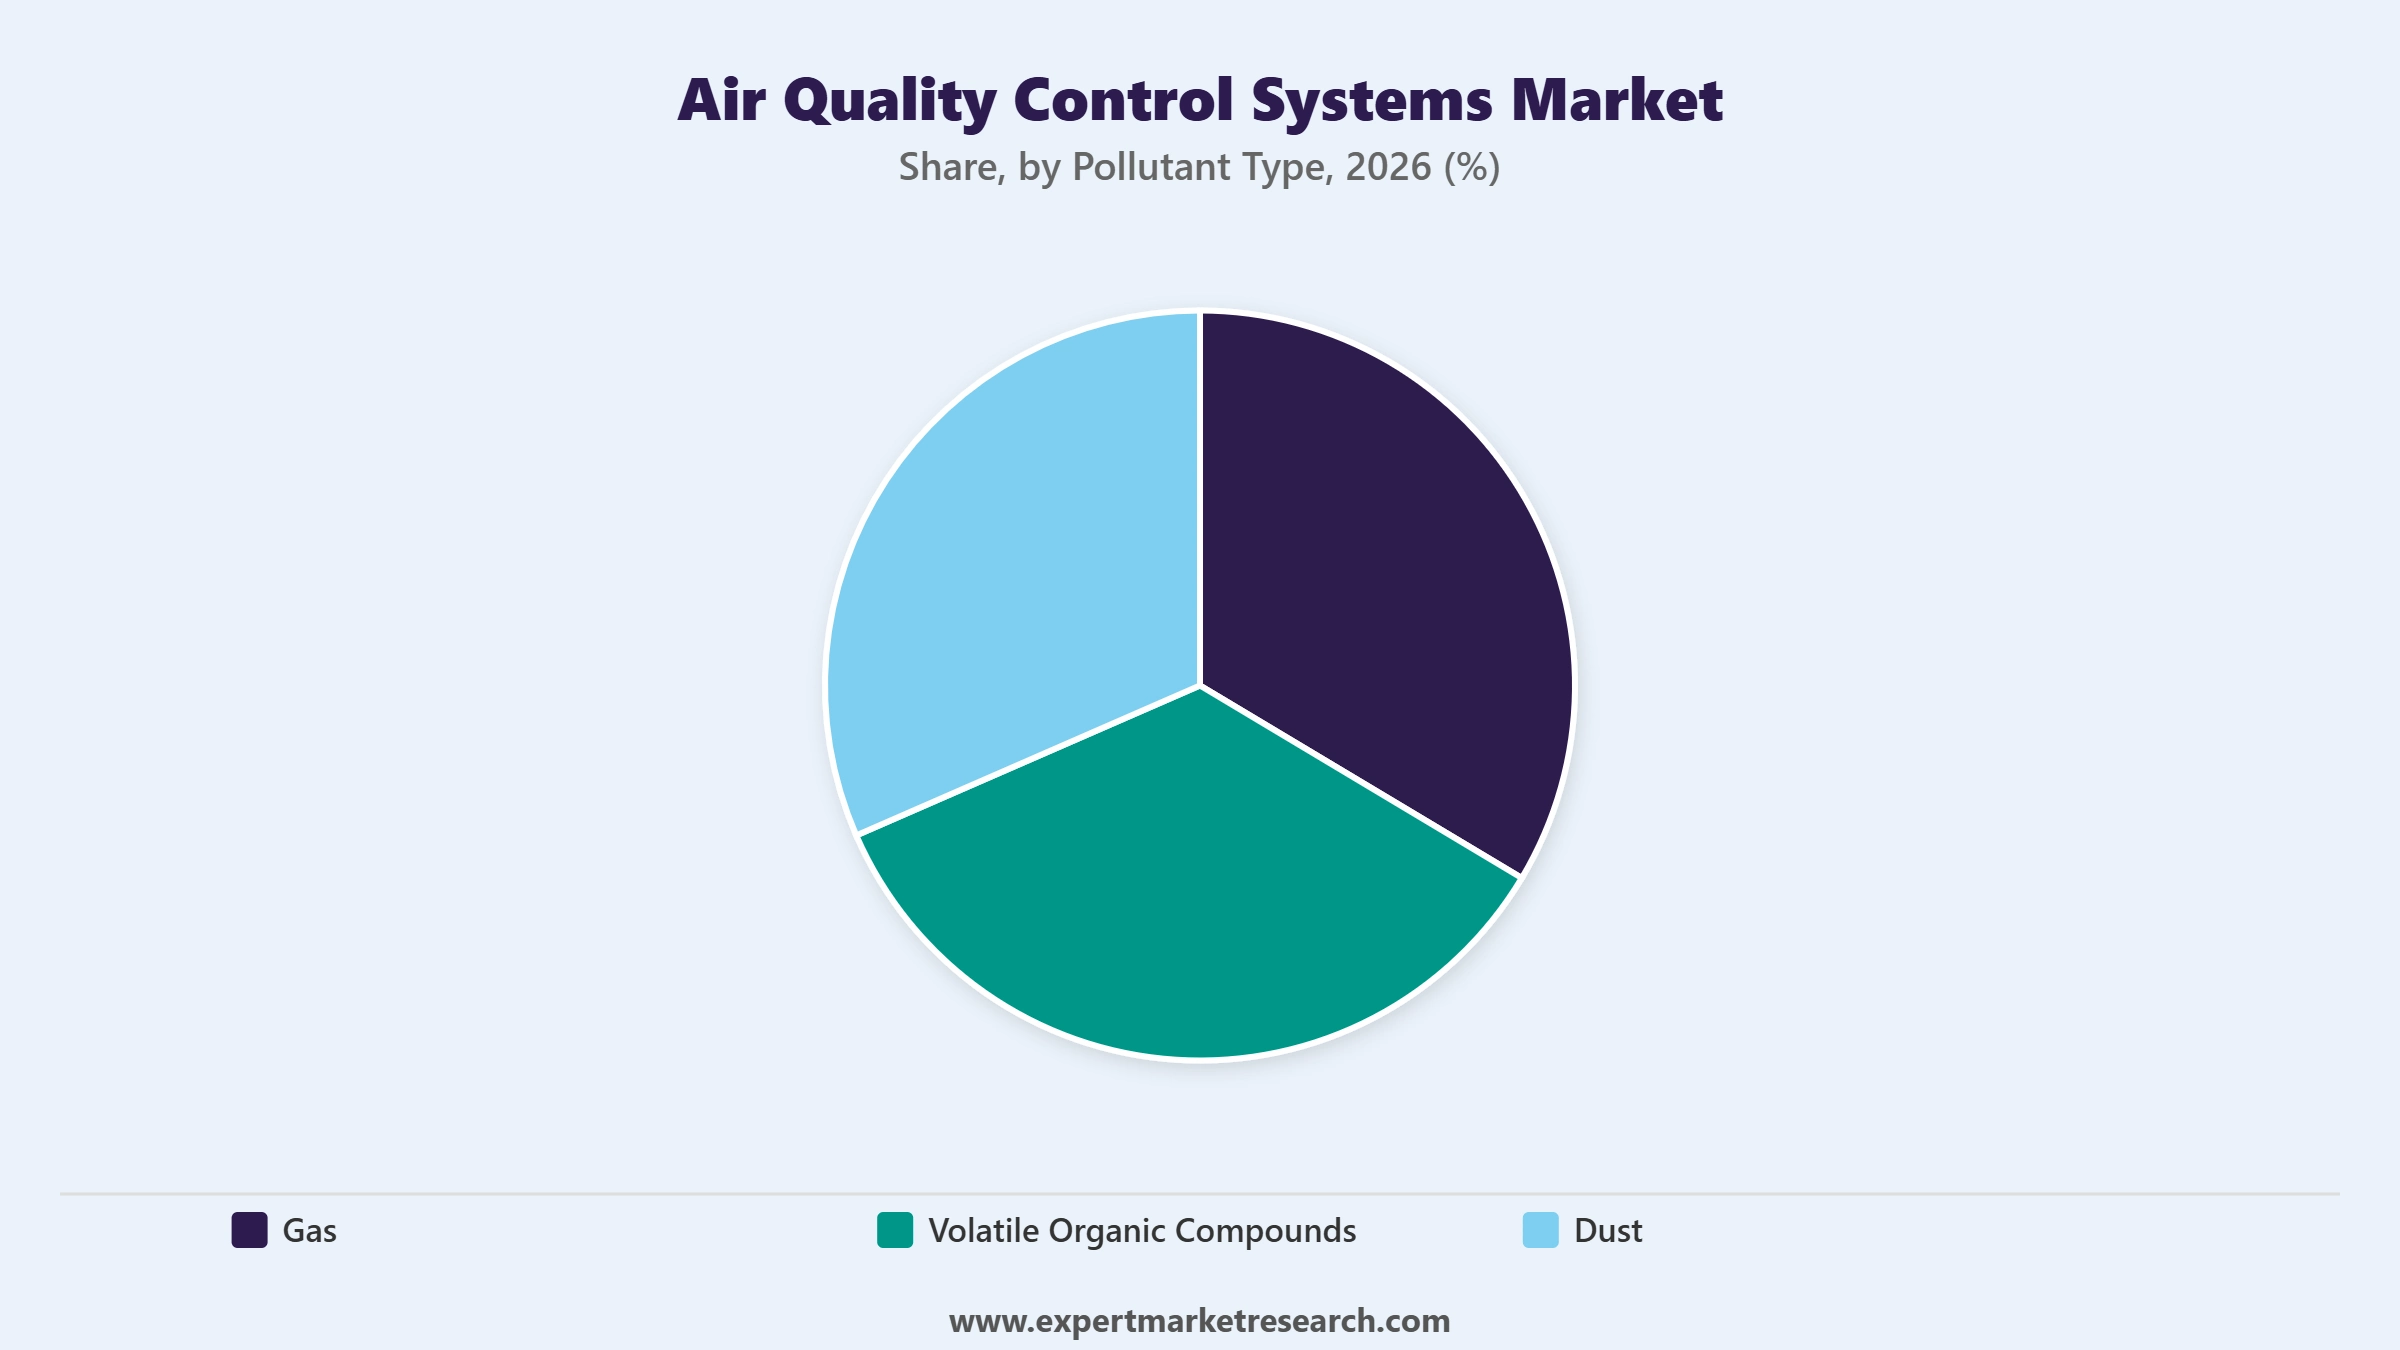
Dust is registering the fastest growth within the pollutant type segment in the air quality control systems market, as stricter particulate limits and attention to fine particles drive investment in bag filters, precipitators, and collectors. Cement, steel, mining, and power plants are upgrading older collectors to cut emissions. In September 2026, Babcock & Wilcox received a limited notice to proceed on an air quality control project at a United States coal fired power plant valued at about USD 130 million, covering engineering work and long lead procurement.
By application, air pollution control dominates the air quality control systems market owing to compliance spending at industrial plants
Air pollution control holds the largest share of the application segment, because power plants, metal producers, cement makers, and chemical sites spend heavily to meet emission permits. Orders cover scrubbers, filters, catalysts, monitoring systems, and long-term service. Projects are large and often awarded to engineering groups that can design, build, and maintain full systems. Public pressure and carbon plans also push owners to modernize older units, which keeps retrofit pipelines active in major industrial economies and rapidly industrializing countries.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Public transportation stations are registering the fastest growth within the application segment, as metro operators upgrade ventilation and filtration for crowded underground spaces. Sensors, fans, and filters are being tied together to manage pollutants from trains and passengers. In July 2026, the Roads and Transport Authority of Dubai and Keolis MHI were upgrading tunnel ventilation on the Metro Red and Green Lines to improve air quality, showing how transit agencies treat air quality as a core service standard for riders.
Asia Pacific commands the largest regional share of the air quality control systems market, supported by heavy industrial output and expanding monitoring networks
Asia Pacific commands the largest regional share of the air quality control systems market, supported by coal power, cement, steel, and chemical output in China, India, and ASEAN, and by large urban pollution programs. Authorities are tightening limits and adding monitoring stations. In October 2026, Delhi added 13 continuous ambient air quality monitoring stations, lifting its network from 47 to 60 stations, placed on a grid approach and linked to national data servers and a public mobile app for residents.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Middle East and Africa are registering the fastest growth among the regional markets, driven by new power, desalination, petrochemical, and metro projects, together with rising attention to urban air in Gulf cities and large African metros. Governments are setting stricter emission rules, and developers specify ventilation and filtration for tunnels, stations, and airports. Imports of engineered systems are common, so global suppliers form partnerships with local contractors across the region. Smaller economies often depend on development funding for monitoring programs.
The competitive landscape is fragmented, with global engineering groups, specialist filtration firms, and regional contractors serving different parts of the value chain. Established air quality control systems companies compete on project references, technology, financing support, local delivery, and aftermarket service. Large groups offer complete packages for power and industrial plants, while smaller firms focus on filters, monitors, or niche scrubbers. Tender based buying and performance guarantees make track record a key advantage for new project awards.
Leading air quality control systems market players are pursuing acquisitions of catalyst and filtration businesses, product launches in indoor purification, and digital monitoring services to defend share. Several air quality control systems players are also bundling engineering, installation, and service contracts to secure recurring revenue. Investment in sensors, data platforms, and low noise products is rising as customers seek proof of results. Partnerships with local contractors help suppliers reach Asia Pacific and Middle East projects, where demand is expanding fastest.
Founded in 2014 and headquartered in Yokohama, Japan, the company supplies the market through flue gas desulfurization and denitration equipment for power and industrial plants. It also provides gas turbines, steam power systems, and related services.
Founded in 1966 and headquartered in Pune, India, the company supplies the market through air pollution control equipment, including flue gas desulphurisation, alongside boilers and heating systems. It serves power, cement, steel, and chemical customers.
Founded in 1867 and headquartered in Akron, Ohio, United States, the company supplies the market through environmental systems for power and industrial plants. It also offers volatile organic compound control equipment through its MEGTEC business.
Founded in 1938 and headquartered in Melville, New York, United States, the company supplies the market through air pollution control equipment for steel, power, and chemical industries. It serves industrial customers in many countries.
Other key players in the market include John Wood Group PLC and General Electric Company, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global air quality control systems market trends 2026 report. Discover regional growth patterns, product types, pollutants, applications, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market. Request a customised quote to align the findings with your own business planning.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of USD 120863.86 Million in 2025.
The market is projected to grow at a CAGR of 5.00% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach about USD 196874.48 Million by 2035.
The major drivers expected to aid the market growth are growing health awareness, increasing product demand in medical and pharmaceutical industries, rapid urbanisation and industrialisation, rising demand from the developing regions, and favourable initiatives by various governments.
The key trends guiding the growth of the market include the launch of enhanced products with rapid technological advancements and increased investment by the major players in research and development activities.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
Indoor and ambient are the major product types of air quality control systems in the market.
Gas, volatile organic compounds, and dust, among others, are the leading pollutant types on which air quality control systems work in the market.
Tunnels, air terminals, underground garages, public transportation stations, air pollution control, and automobiles are the significant applications of the product in the market.
The major players in the global air quality control systems market are Mitsubishi Power, Ltd., Thermax Ltd, Babcock & Wilcox Enterprises, Inc, Ducon Technologies Inc, John Wood Group PLC, and General Electric Company, among others.
Indoor leads the market by product type, while ambient is expected to grow fastest.
The key players in the market include Mitsubishi Power, Ltd., Thermax Ltd, Babcock & Wilcox Enterprises, Inc, Ducon Technologies Inc, John Wood Group PLC, and General Electric Company, among others.
Asia Pacific leads the market by region, while Middle East and Africa is registering the fastest growth.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product Type |
|
| Breakup by Pollutant Type |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




