

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
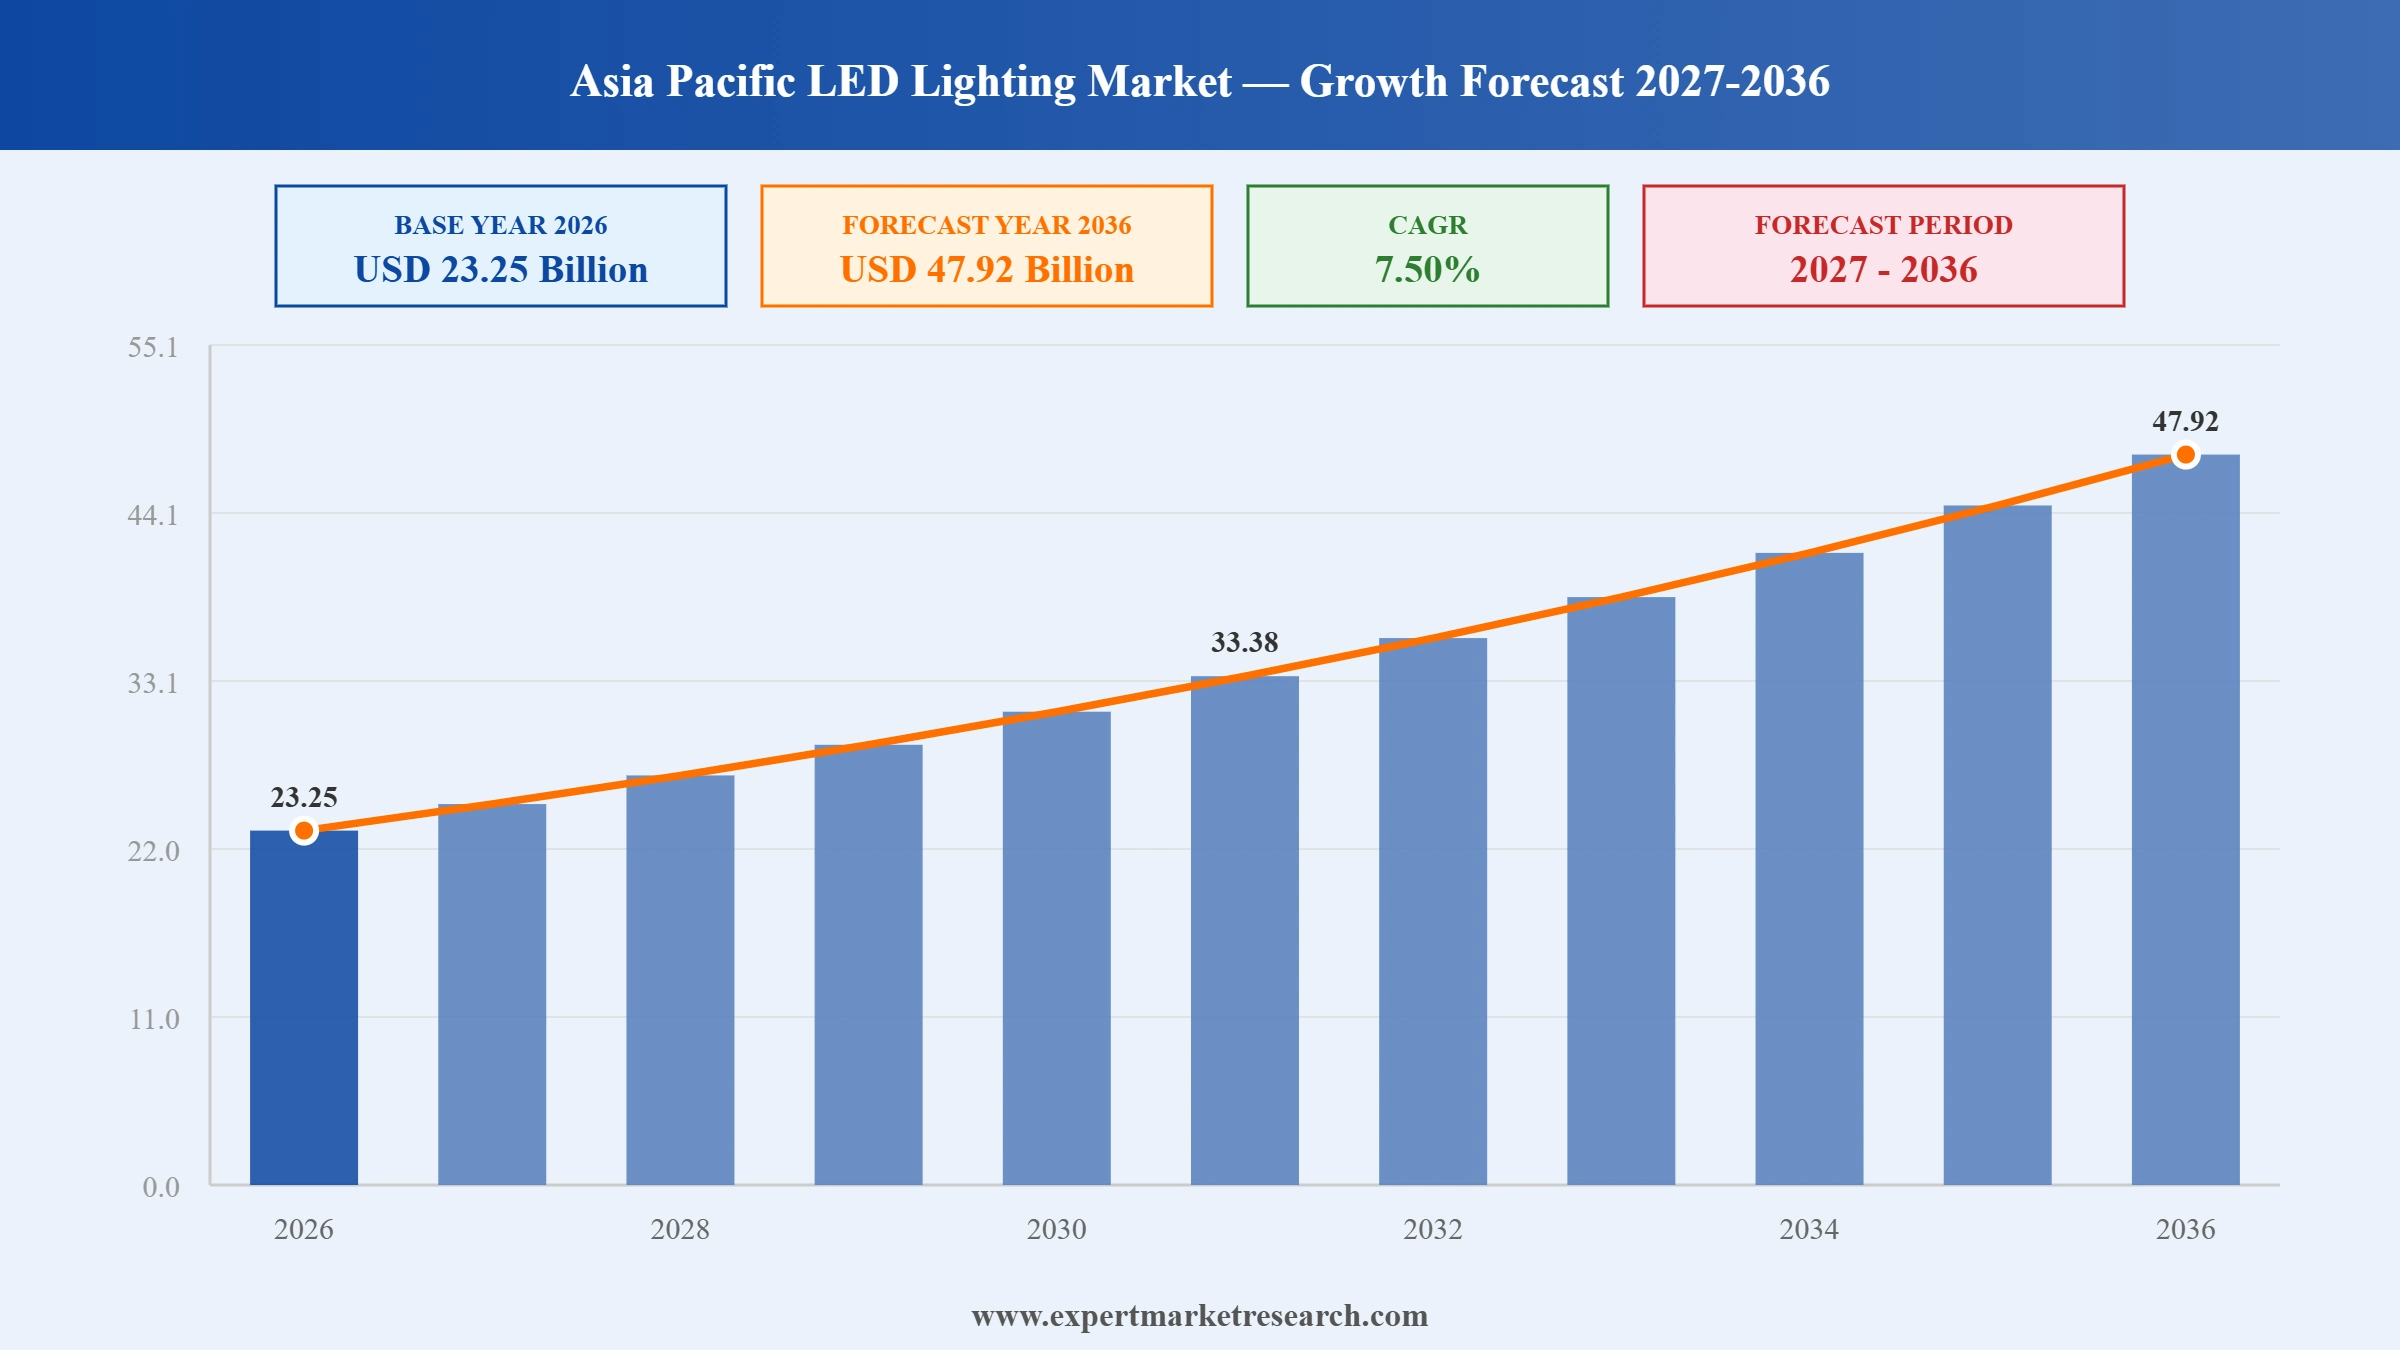
The Asia Pacific LED lighting market attained a value of USD 21.63 Billion in 2025 and is projected to expand at a CAGR of 7.50% through 2035. The market is further expected to achieve USD 44.58 Billion by 2035, driven by rapid urbanisation, expanding smart city infrastructure programmes, and increasingly stringent energy-efficiency regulations phasing out conventional lighting technologies across the region. Growth spans lamps and luminaires deployed across indoor and outdoor applications, with manufacturers increasingly competing on connected lighting technology, energy-efficiency certification, and local manufacturing depth across China, Japan, India, ASEAN, and Australia.
Strong government mandates and accelerating urbanisation continue to anchor steady demand across the Asia Pacific LED lighting market, as fluorescent lamp phase-outs and building code revisions across the region turbo-charge conversion to LED technology. China holds an estimated 35 percent share of regional revenue as of 2026, reflecting its manufacturing depth and large installed replacement base across commercial and municipal infrastructure.
The Asia Pacific LED lighting market is witnessing further developments as manufacturers extend sustainability commitments deeper into regional supply chains. Signify launched Europe's first LED lighting tube made with recycled plastic in May 2025, using post-consumer materials reclaimed from fishing nets, water jugs, and car headlights, with the initiative supporting planned expansion across ASEAN, Indonesia, and Greater China markets through 2026.
In addition, leading lighting component suppliers are increasingly defending intellectual property positions as competition intensifies across the region's LED chip manufacturing segment. A German court confirmed, in June 2026, damages of EUR1.63 million against Everlight Electronics in a patent dispute brought by Nichia Corporation, underscoring the growing commercial stakes attached to core LED semiconductor patents among competing Asia Pacific manufacturers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Large diversified electronics conglomerates continue committing capital to concentrated regional manufacturing hubs to secure long-term production capacity for advanced components. Samsung Display announced, in July 2026, plans to resume investment in its Asan Campus 2 project in South Korea's Chungcheongnam-do province, allocating KRW67 trillion to upgrade production facilities and build new manufacturing lines for advanced components and displays as part of Samsung Group's broader regional investment plan. Companies can commit large-scale capital to concentrated regional manufacturing hubs to secure long-term component supply capacity ahead of anticipated demand growth.
Lighting component suppliers continue extending established brand equity into adjacent categories through licensing partnerships rather than direct manufacturing investment across new geographies. ams OSRAM entered a new brand licensing partnership in March 2026, granting Chinese company Eaglerise a license under the OSRAM brand for general lighting LED drivers across the Asia Pacific and EMEA regions, effective from March 1, 2026 onward as part of a broader strategy to expand brand presence without direct capital investment. Companies can extend established brand equity into adjacent categories through licensing partnerships to generate revenue without direct manufacturing investment.
Industry analysis continues confirming Asia Pacific's position as the leading region for connected lighting hardware adoption as governments and enterprises accelerate smart infrastructure investment. Industry analysis confirmed, in January 2026, that Asia Pacific smart lighting hardware is expected to account for the largest regional market share as governments and enterprises accelerate adoption of connected LED systems across major regional economies and expanding urban centres throughout the region. Companies can prioritise Asia Pacific expansion for connected lighting products to capture the region's outsized share of global smart infrastructure investment.
Global electronics manufacturers continue expanding India-based production to serve both domestic demand and shift operations away from Japan-centric supply chains. Panasonic Life Solutions India announced, in September 2025, plans for a new manufacturing unit in the country as it prepares to apply under the reopened production-linked incentive scheme, with its chief executive outlining ambitions to make more Indian teams provide services globally rather than depending on Japan-led operations. Companies can pursue government incentive schemes to justify expanded local manufacturing capacity while accelerating the shift toward India-led operations.
Lighting component suppliers are increasingly extending established brand equity into adjacent categories through licensing partnerships rather than direct manufacturing investment across new geographies. ams OSRAM confirmed, in a June 2025 announcement of its EURES GmbH consumer battery partnership, that it had established a dedicated IP Offerings business to extend the OSRAM brand into additional product categories, building on that collaboration and a separate Ziwooo Biotechnology tie-up for health and beauty products, alongside its more recent Eaglerise partnership for general lighting LED drivers. Companies can leverage established brand licensing programmes to generate additional revenue streams without the capital intensity of direct manufacturing expansion.
Global lighting and electronics manufacturers are increasingly deepening state-level partnerships across India to capture next-phase infrastructure and distribution growth. Panasonic Life Solutions India's CEO reaffirmed, at the UP-Japan Investment Meet in August 2026, the company's long-term commitment to India, highlighting its Make in India manufacturing base of seven facilities and outlining plans to expand its contribution to Uttar Pradesh across distribution, services, and smart infrastructure. Companies can deepen state-level government engagement to secure early positioning within emerging regional infrastructure and distribution opportunities.
Regional LED chip manufacturers are increasingly closing the competitive gap with established European and Japanese component suppliers through sustained technology investment. Seoul Semiconductor reported, in May 2025, that it had narrowed the global LED market share gap with second-ranked ams OSRAM to just one percentage point based on recent industry rankings, sustaining both revenue and market share while larger rivals experienced declines amid an industry-wide slowdown. Companies can sustain focused technology investment through industry downturns to close competitive gaps with larger, established rivals.
LED and photonics component manufacturers are increasingly diversifying beyond traditional lighting applications into adjacent high-growth technology segments to reduce reliance on cyclical demand patterns. ams OSRAM unveiled, in March 2026, its microLED-based optical interconnect technology combining micro-emitter and micro-photodiode expertise to address rising bandwidth density and reach challenges in AI data centre infrastructure, positioning the company's photonics expertise for adjacent high-growth applications beyond conventional lighting. Companies can leverage core LED and photonics manufacturing expertise to diversify into adjacent high-growth technology segments beyond traditional lighting applications.
This Expert Market Research's Report titled "Asia Pacific LED Lighting Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
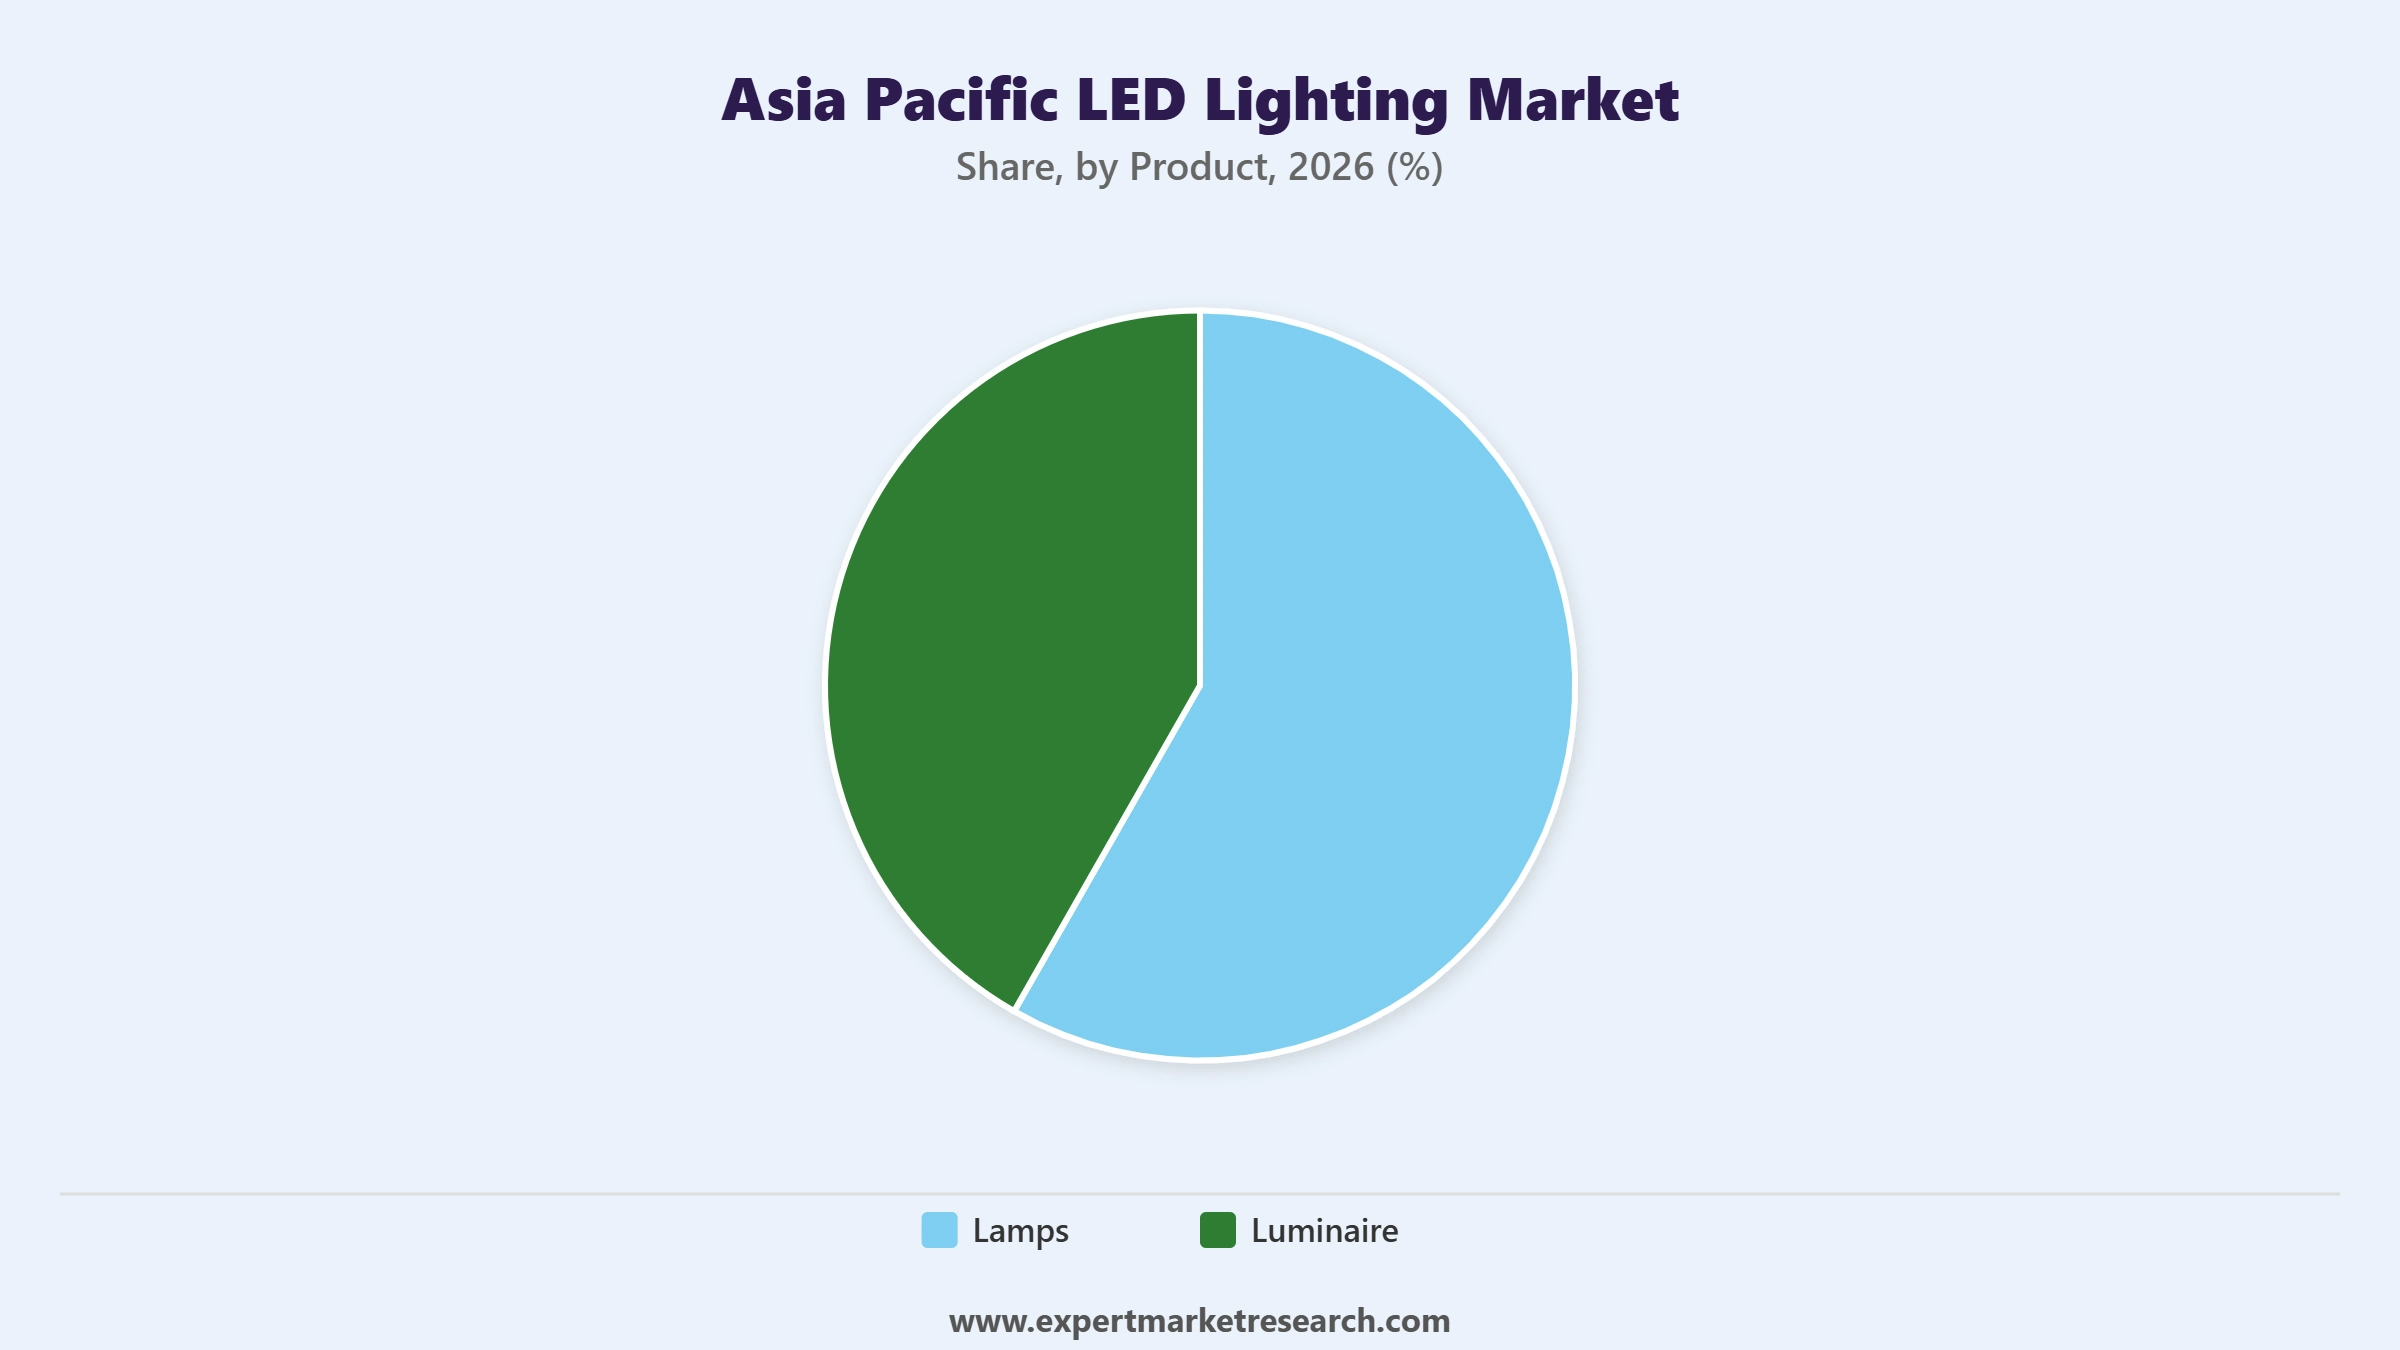
Market Breakup by Product
Key Insight: Luminaire accounts for the largest share of the market, led by Street Light and Downlight fixtures deployed across commercial and municipal infrastructure nationwide throughout the region's expanding cities. Lamps continues to represent substantial retrofit demand across residential and commercial settings undergoing conversion from conventional lighting technologies, with A-Type and T-Type formats serving conventional replacement demand within the segment. Troffers, High Bay, Track Lights, and Suspended Pendants serve varied commercial and industrial applications within Luminaire, while Others rounds out both product categories with niche and specialty formats. ams OSRAM's March 2026 brand licensing partnership with Eaglerise, covering general lighting LED drivers across the Asia Pacific region, reinforces continued manufacturer investment supporting both luminaire and lamp component supply chains region-wide.
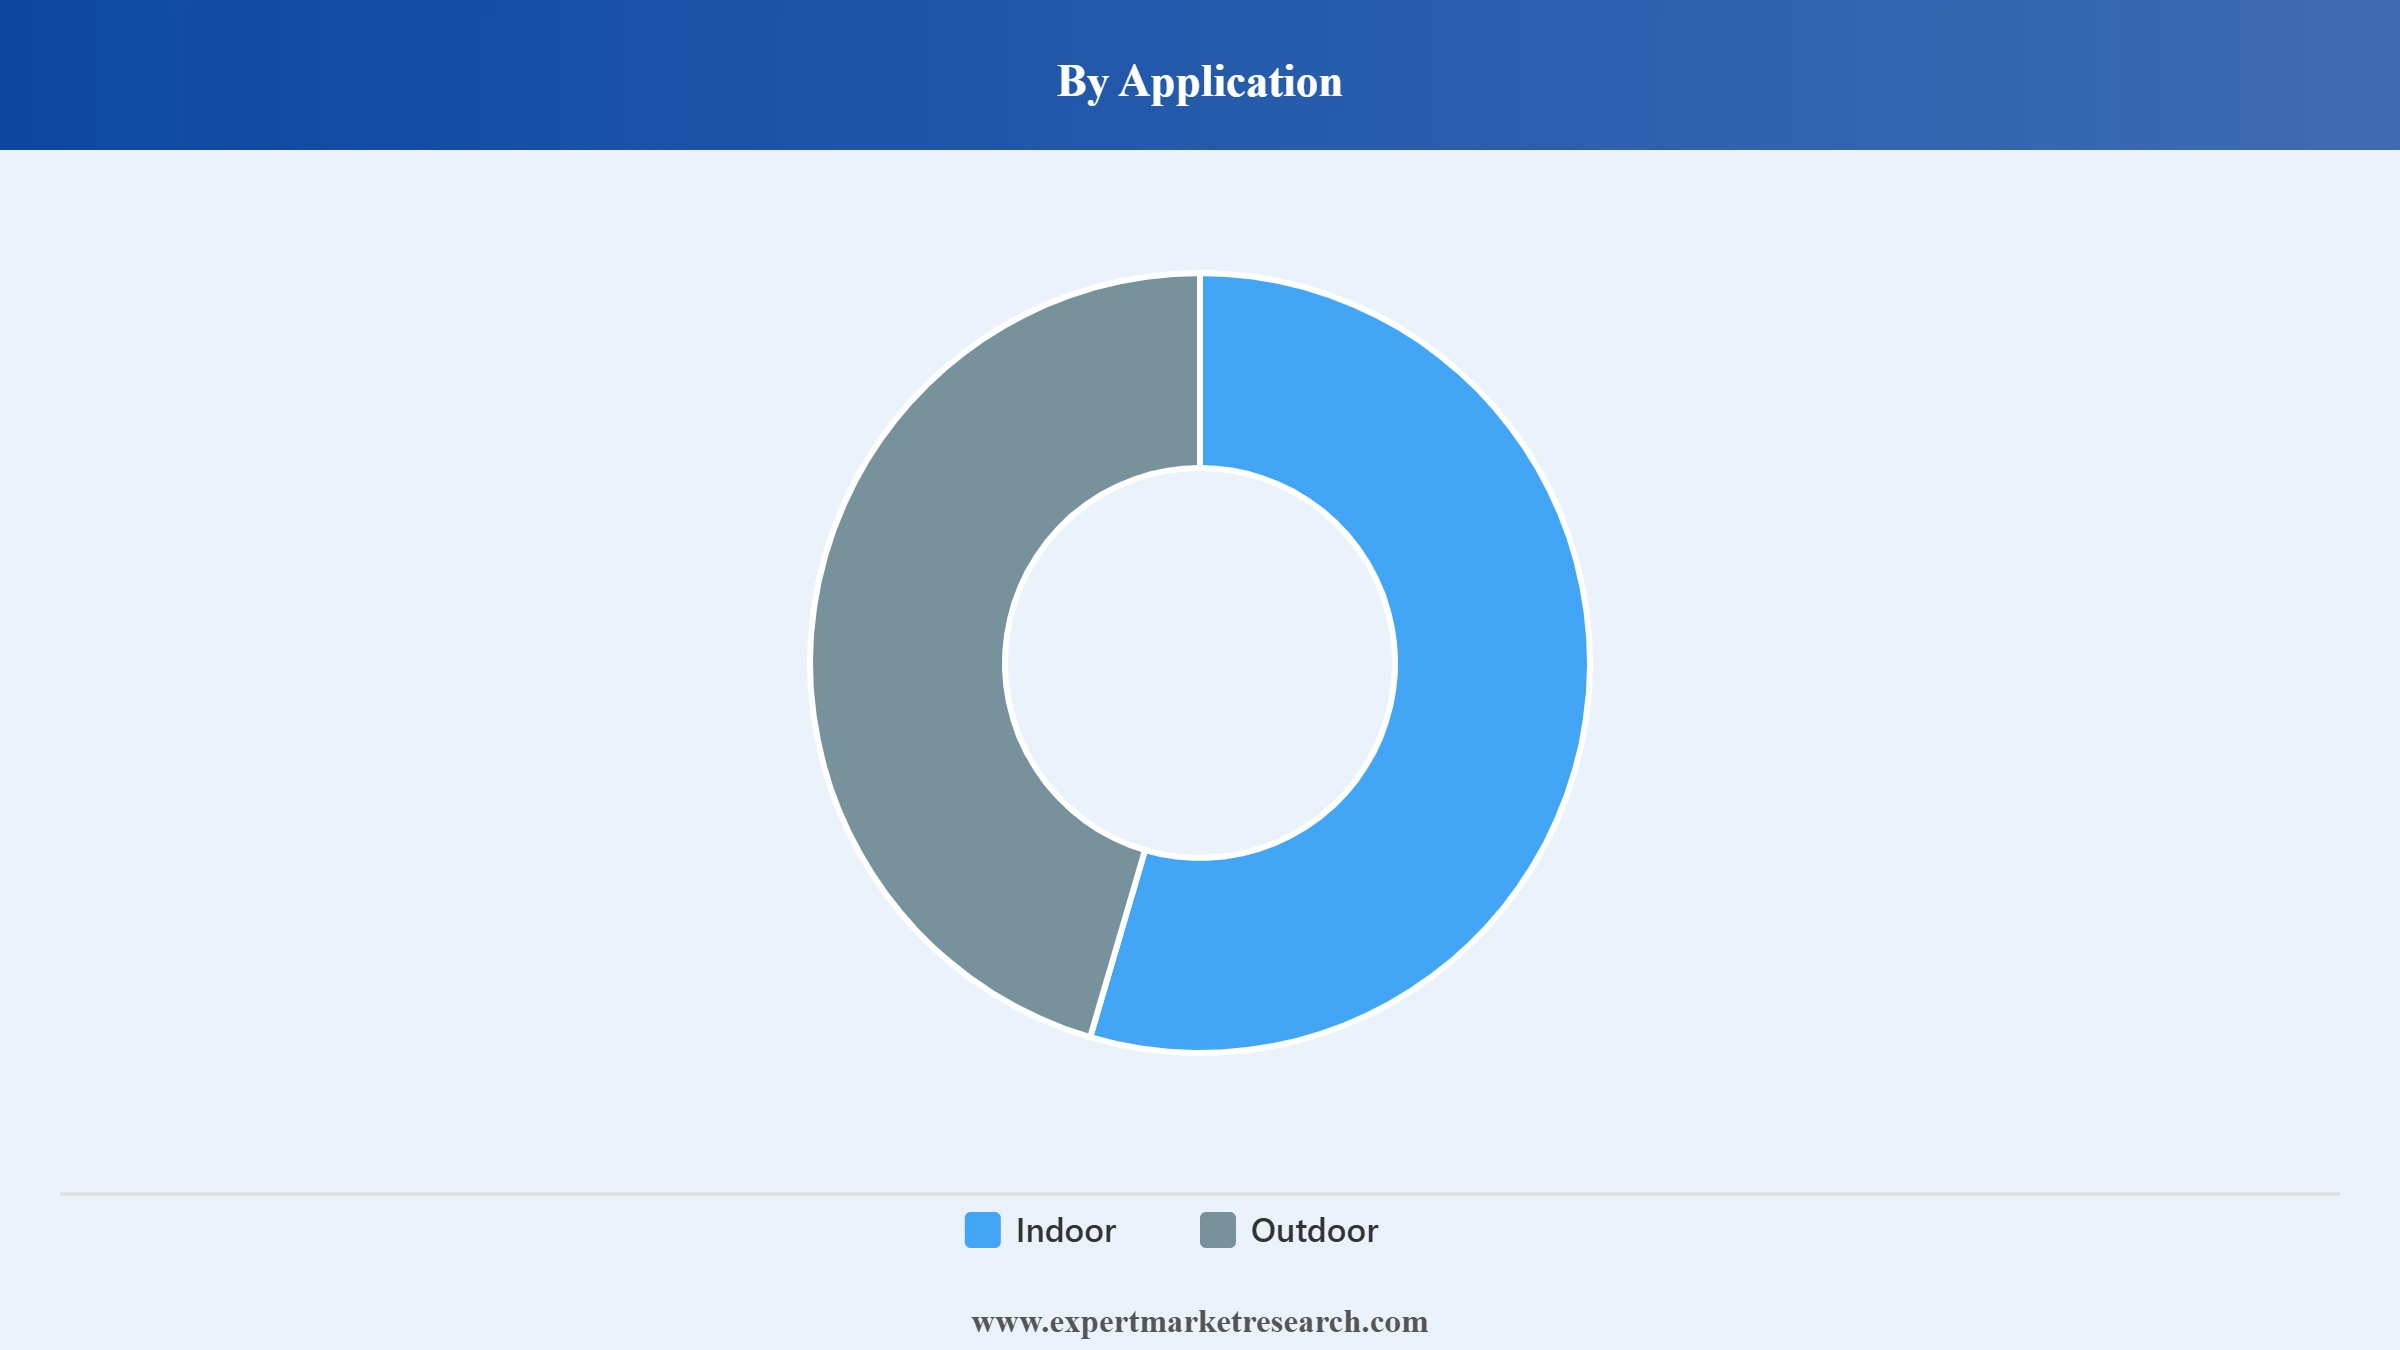
Market Breakup by Application
Key Insight: Indoor accounts for the largest share of the market, reflecting sustained residential, commercial, and industrial demand across the region's expanding urban centres and infrastructure development projects. Outdoor is growing fastest as municipal conversion programmes accelerate across major economies. Samsung Group's July 2026 commitment of KRW140 trillion to its Chungcheong region manufacturing hub supports broader regional component capacity underpinning both indoor and outdoor lighting demand across the wider Asia Pacific market.
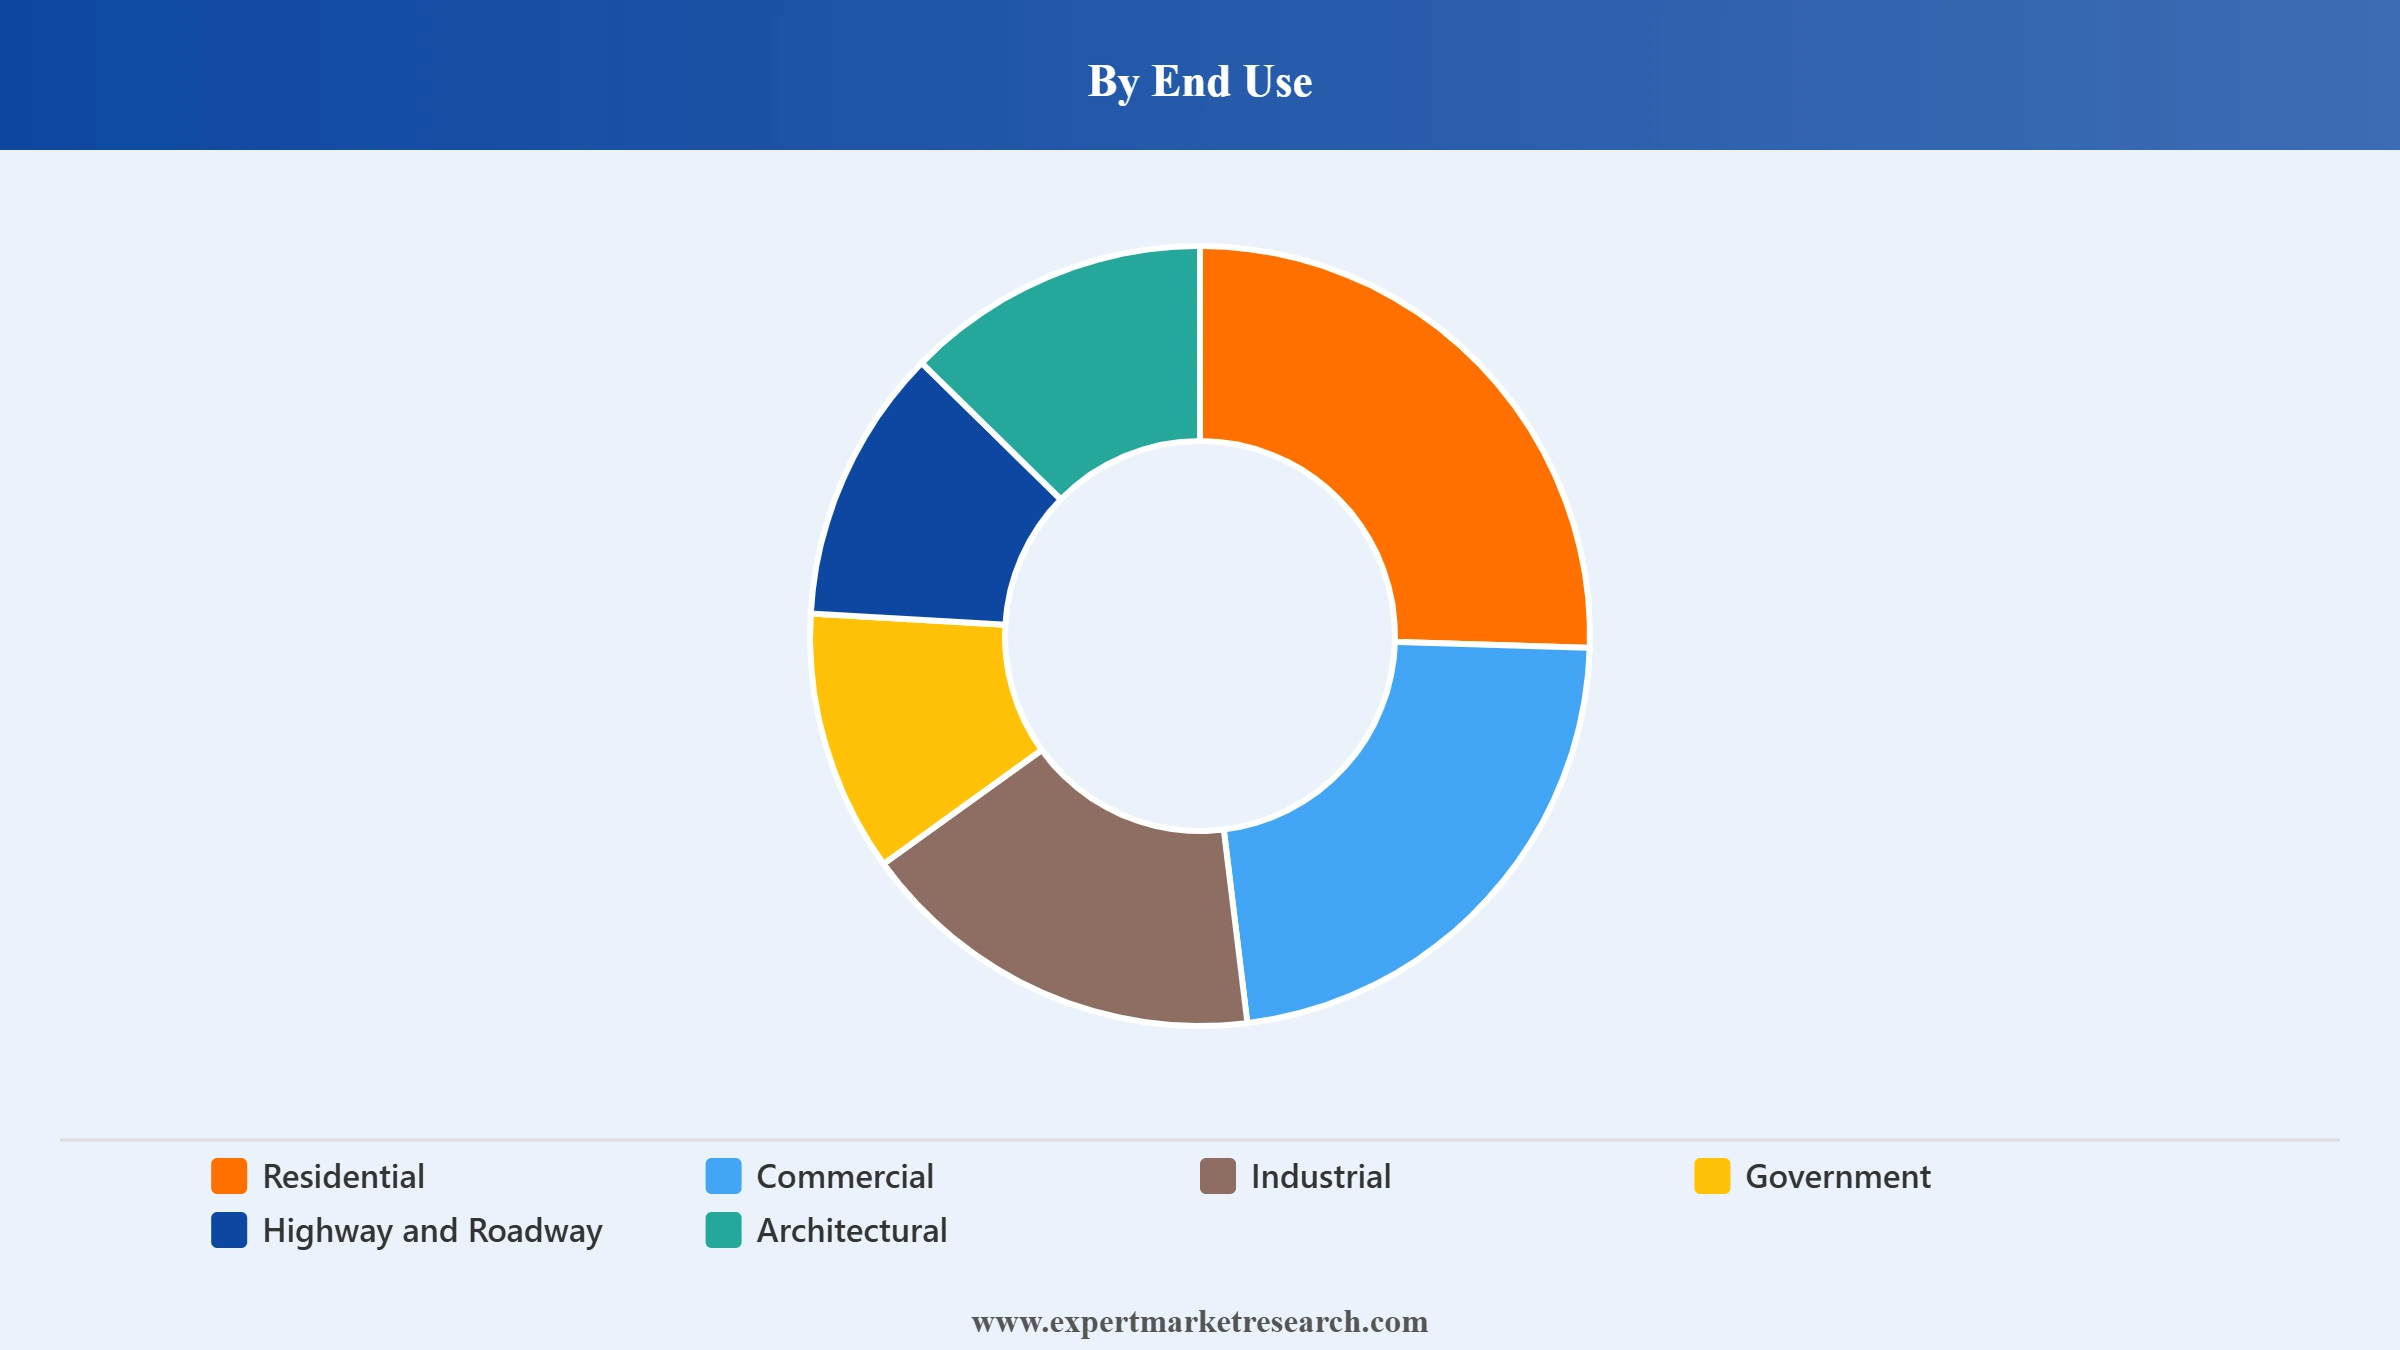
Market Breakup by End Use
Key Insight: Commercial accounts for the largest share of the market, supported by office and retail lighting upgrades across the region's expanding urban centres and business districts nationwide. Residential and Industrial applications each continue to sustain steady baseline demand tied to housing construction and factory lighting upgrades, while Government and Architectural segments serve public infrastructure and design-led commercial projects respectively. Highway and Roadway is growing fastest as municipal streetlight conversion programmes accelerate across major economies. Industry analysis confirmed in January 2026 that Asia Pacific is expected to account for the largest regional share of connected lighting hardware adoption worldwide, reinforcing demand across all end-use categories in the market.
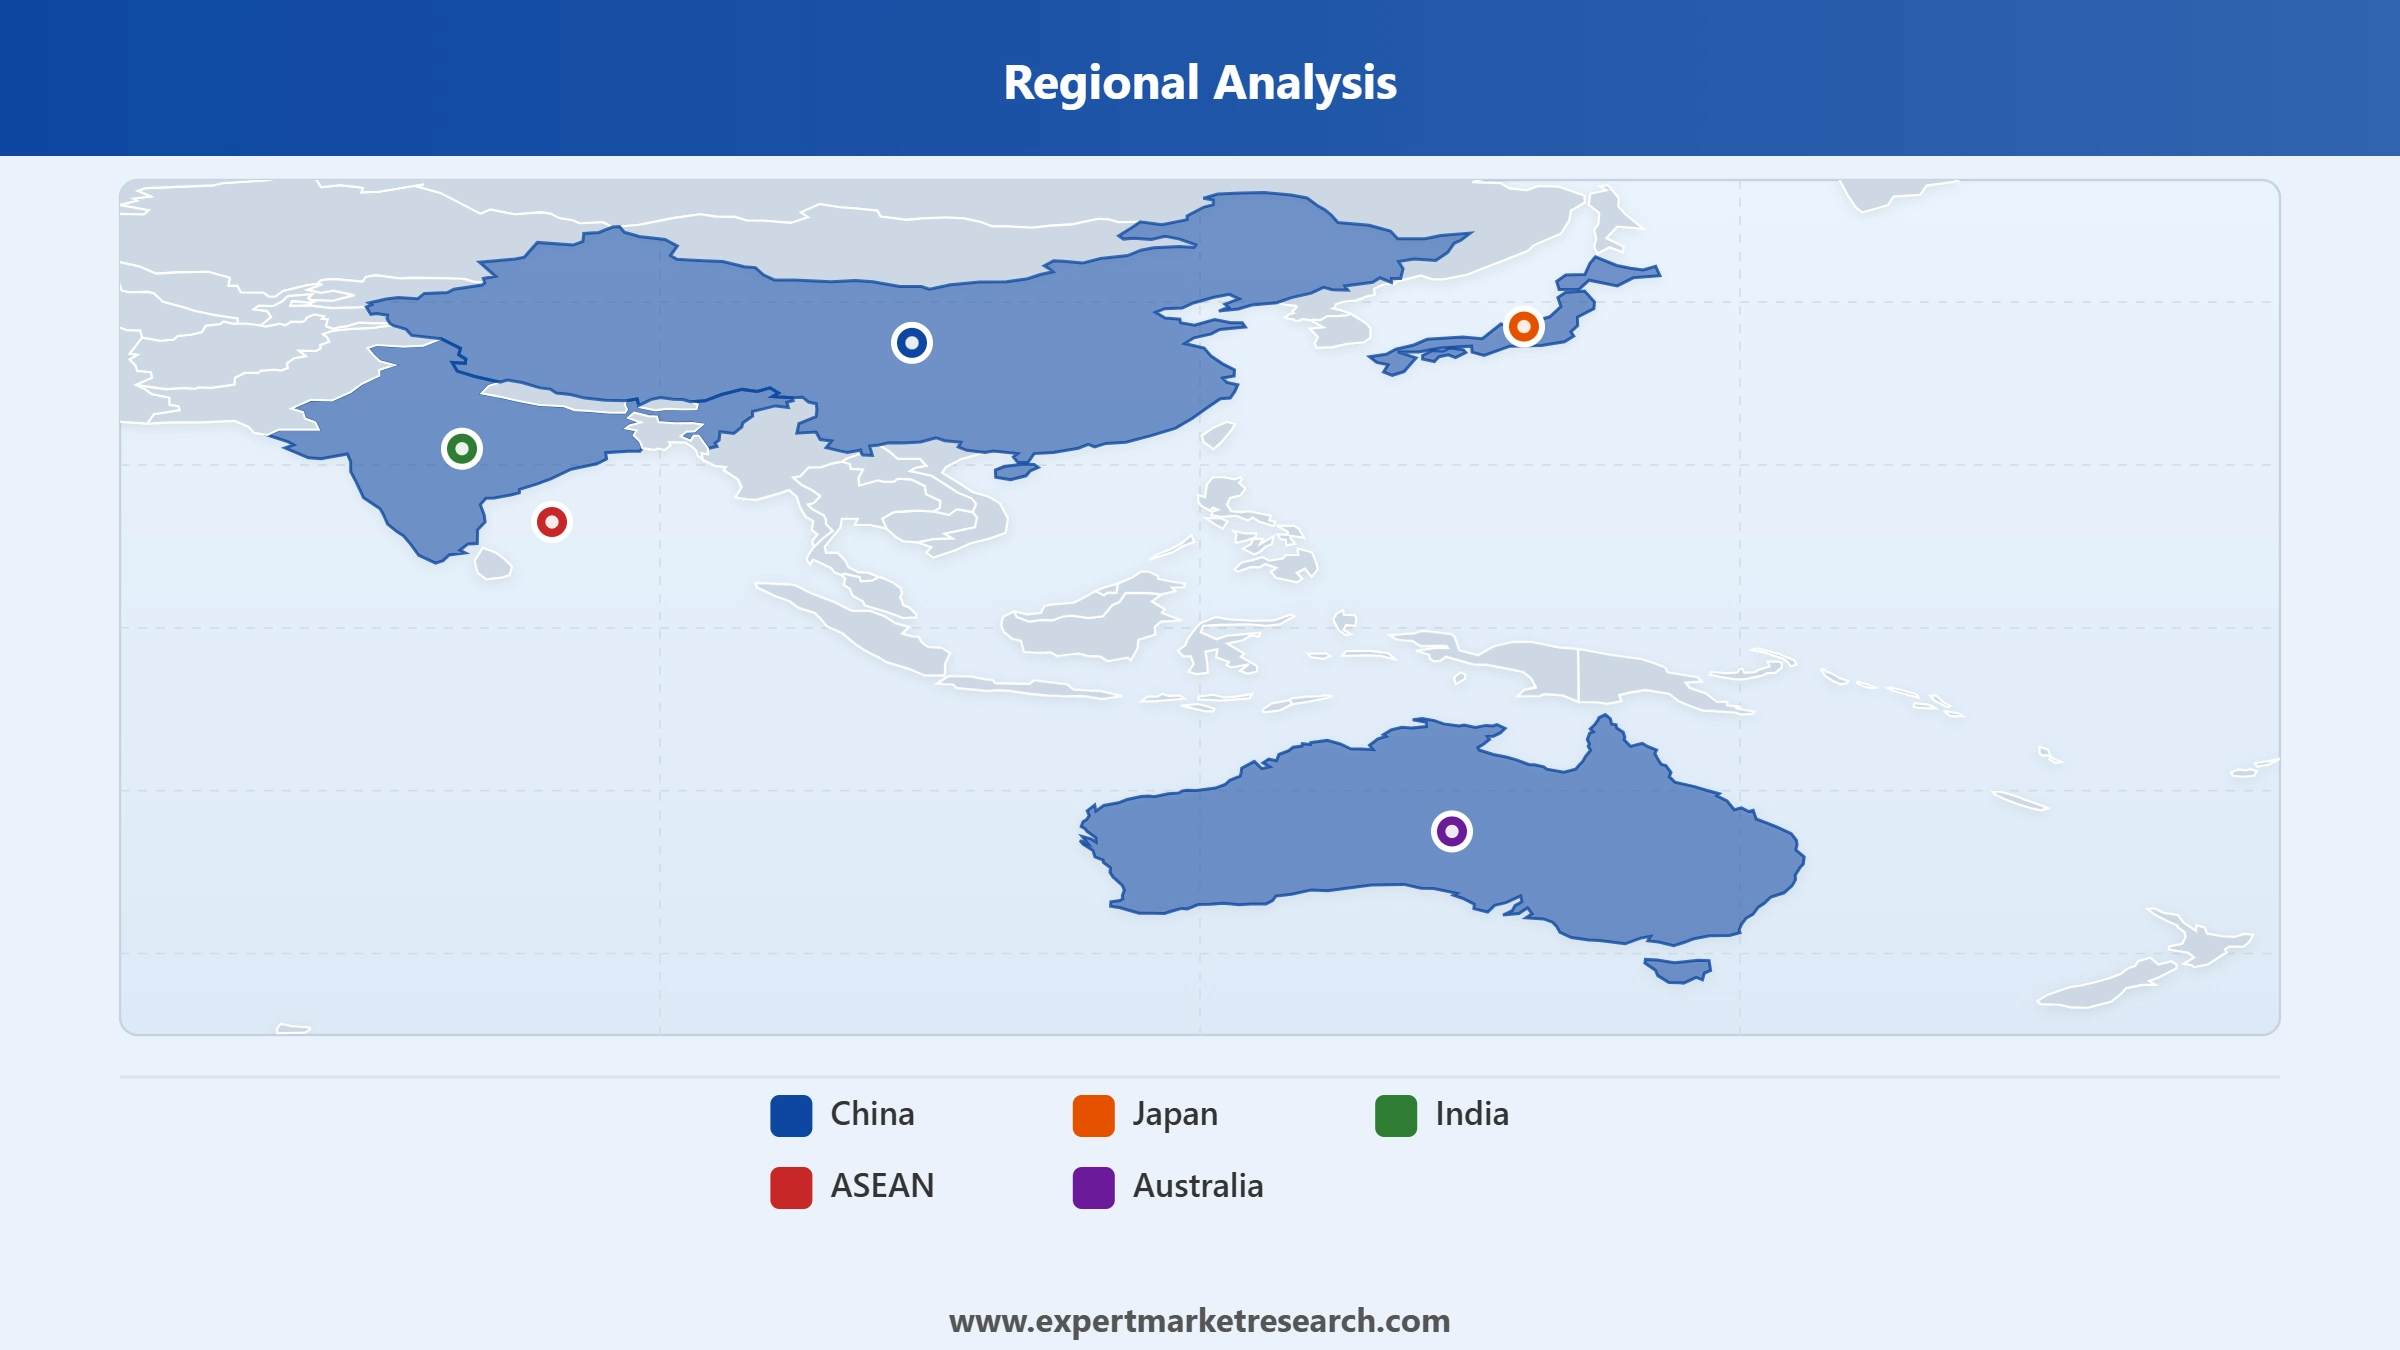
Market Breakup by Country
Key Insight: China accounts for the largest share of the market, anchored by its extensive manufacturing base and status as the region's largest consumer market for LED lighting products. India is growing fastest, driven by Smart Cities Mission retrofit targets. Japan continues to represent a mature, technology-advanced market driven by ongoing fluorescent-to-LED conversion, while ASEAN and Australia each sustain steady demand tied to urbanisation and infrastructure upgrades. Others captures smaller Pacific island and emerging Asia Pacific markets with nascent LED adoption. Panasonic's September 2025 plans for a new India manufacturing unit under the country's production-linked incentive scheme reinforce sustained manufacturer commitment across the region's fastest-growing country market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By product, luminaire leads the market while lamps grows fastest given accelerating retrofit programmes
Luminaire continues to account for the largest share of the market, encompassing street light and downlight fixtures deployed across commercial and municipal infrastructure nationwide. The global LED lighting market was valued at approximately USD110.76 billion in 2026, growing at a 5.55 percent CAGR through 2031 across luminaire and lamp categories combined.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Lamps is growing fastest as retrofit programmes accelerate across the region's ageing conventional lighting installations. The global high-power LED market, a core lamp-driving component category, was valued at approximately USD4.23 billion in 2025 and is projected to reach USD6.08 billion by 2036.
By application, indoor leads the market while outdoor grows fastest given municipal streetlight conversion
Indoor continues to account for the largest share of the market, sustained by residential, commercial, and industrial interior lighting demand across the region's expanding cities. The global smart lighting market, concentrated in indoor commercial and residential retrofit applications, is projected to grow from approximately USD33.49 billion in 2026 to USD165.89 billion by 2034.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Outdoor is the fastest-growing application as governments accelerate smart city and street lighting infrastructure spending. Outdoor and street lighting programmes tied to municipal smart city initiatives were identified in 2026 industry analysis as a primary growth driver across the region's government infrastructure projects.
By end use, commercial leads the market while highway and roadway grows fastest given municipal conversion programmes
Commercial continues to account for the largest share of the market, supported by office and retail lighting upgrades across the region's expanding urban centres. Construction and infrastructure activity was identified in 2026 industry analysis as the primary demand driver for commercial LED lighting, tied to new building projects and retrofitting initiatives.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Highway and Roadway is the fastest-growing end use as municipal governments prioritise energy-efficient street lighting conversion. Healthcare and education facilities were separately identified in 2026 industry analysis as adopting high-quality, energy-efficient lighting environments, reflecting broader institutional demand alongside roadway conversion programmes nationwide.
The industry is fragmented, with Asia Pacific LED lighting market companies ranging from global connected-lighting conglomerates to specialist semiconductor and LED chip manufacturers competing across product, application, end-use, and country segments nationwide.
Competitive dynamics among Asia Pacific LED lighting players are increasingly shaped by the depth of local manufacturing investment, the breadth of brand licensing partnerships, and early positioning within adjacent photonics applications. Manufacturers are investing in dedicated regional facilities, expanded component licensing programmes, and diversification into AI data centre optics to secure long-term relationships with government, commercial, and industrial customers.
Founded in 1891 as Philips and rebranded as Signify in 2018, and headquartered in Eindhoven, Netherlands, Signify is the world leader in connected LED lighting systems, software, and services, operating global brands including Philips, Interact, and Color Kinetics across the Asia Pacific smart lighting market. Signify's global connected-lighting software platform differentiates its offering from hardware-only regional competitors.
Founded in 1918 and headquartered in Kadoma, Japan, Panasonic is a diversified global electronics manufacturer with an established lighting business spanning residential, commercial, and industrial applications worldwide. Panasonic announced plans in September 2025 for a new India manufacturing unit under the country's production-linked incentive scheme. Panasonic's sustained India manufacturing investment differentiates its offering from competitors relying on imported product.
Founded in 1911 and headquartered in Dublin, Ireland, Eaton is a diversified power management company with an established lighting business serving commercial, industrial, and infrastructure customers across the region's expanding construction sectors. Eaton's broader power management portfolio differentiates its offering from pure-play lighting manufacturers by enabling integrated electrical infrastructure solutions for large commercial and industrial customers across Asia Pacific.
Founded in 1919 and headquartered in Munich, Germany, OSRAM, now operating as part of ams OSRAM following its merger with Austrian sensor specialist ams AG, is a global leader in light and sensor solutions. ams OSRAM signed a brand licensing agreement with Eaglerise in March 2026 covering general lighting LED drivers across Asia Pacific. ams OSRAM's combined lighting and photonics sensor expertise differentiates its offering from single-category competitors.
Other key players in the Asia Pacific LED lighting market include Nichia Corporation, SMART Global Holdings, Inc., Samsung Electronics Co Ltd., Acuity Brands, Inc., Seoul Semiconductor Co., Ltd., EVERLIGHT Electronics Co., Ltd., and EPISTAR Corporation, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
China commands the largest share of the market through its dual position as manufacturing anchor and largest consumer base
China's concentrated LED component manufacturing capacity and vast domestic construction sector continue to anchor its position as the region's single-largest LED lighting market, further reinforced by government-backed infrastructure programmes and brand licensing partnerships such as ams OSRAM's March 2026 Eaglerise agreement.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
India is the fastest-growing country at an estimated CAGR of 9.12%, supported by Smart Cities Mission streetlight retrofit targets and expanding domestic manufacturing incentives, reinforced by Panasonic's September 2025 plans for a new India manufacturing unit under the country's production-linked incentive scheme. Japan continues to represent substantial demand tied to upcoming fluorescent lamp phase-out regulations, with local rebate schemes supporting the transition to LED alternatives ahead of the regulatory deadline. ASEAN continues to expand alongside regional infrastructure development, positioning LED adoption as a pathway toward national carbon-neutrality goals. Australia rounds out demand as a smaller but steady mature replacement market, while Others captures remaining Asia Pacific economies including South Korea and New Zealand.
Unlock the latest insights with our Asia Pacific LED lighting market trends 2026 report. Discover regional growth patterns, product and end use adoption trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 21.63 Billion.
The market is projected to grow at a CAGR of 7.50% between 2026 and 2035.
The LED lighting market is expected to witness significant growth to reach USD 44.58 Billion in 2035.
The market is categorised according to its application, which includes indoor and outdoor.
The key players in the market include Signify N.V., Panasonic Corp., Eaton Corporation Plc, OSRAM Licht AG, Nichia Corporation, SMART Global Holdings, Inc., Samsung Electronics Co Ltd., Acuity Brands, Inc., Seoul Semiconductor Co., Ltd., EVERLIGHT Electronics Co., Ltd., and EPISTAR Corporation.
Establishing dedicated local manufacturing facilities, pursuing brand licensing partnerships with regional component suppliers, and diversifying core LED and photonics expertise into adjacent technology applications are among the leading strategies shaping the market.
The market is categorised according to its end use, which includes residential, commercial, industrial, government, highway and roadway, and architectural.
Koninklijke Philips N.V.: Koninklijke Philips N.V. (Netherlands), commonly known as Philips Lighting is a prominent player in the global LED lighting landscape.
Manufacturers face intensifying price competition from regional component suppliers, the technical complexity of integrating connected lighting systems across diverse regulatory environments, and the need for sustained local manufacturing investment to meet domestic content requirements across key country markets.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product |
|
| Breakup by Application |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




