

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
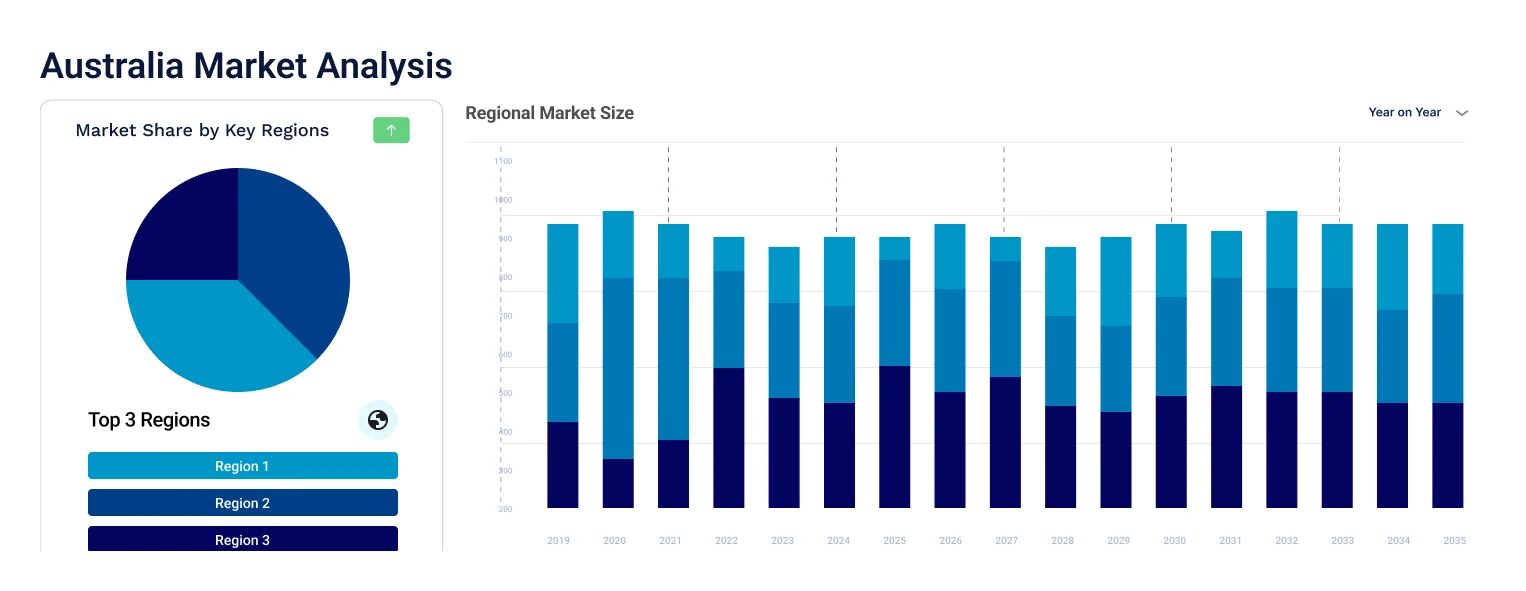
The Australia adhesives market attained a value of USD 961.27 Million in 2025 and is projected to expand at a CAGR of 4.32% through 2035. The market is further expected to achieve USD 1467.31 Million by 2035. Australia’s expansion of utility-scale solar and battery projects is creating a specialized application area for adhesives used in cable management, sealing, insulation, protective components and lightweight assemblies. The Australian Energy Market Operator’s 2024 Integrated System Plan identifies 6–7 GW of new utility-scale renewable generation and storage capacity needed each year through 2030 to support the energy transition. This expanding infrastructure base creates opportunities for adhesives engineered for outdoor exposure, thermal cycling, moisture resistance and long service life, an application distinct from mining equipment maintenance.
A major factor supporting the Australia adhesives market is the government-backed expansion of infrastructure and housing-enabling projects. The 2026–27 Federal Budget includes a $2 billion Local Infrastructure Fund intended to support infrastructure connected with housing development, while more than $8.6 billion is allocated to nationally significant road and rail projects. Such activity expands requirements for flooring, façade, waterproofing, structural bonding, insulation and general construction applications, thereby boosting the Australia adhesives market value.
An important innovation in the Australian adhesives industry is the development of low-VOC and solvent-free formulations that maintain strong bonding performance while reducing impacts on indoor air quality and worker exposure. For example, Bostik Australia offers Ultraset SF, a solvent- and VOC-free polyurethane adhesive that retains flexibility and high final strength, while Australian manufacturer Envirosystems has developed solvent-free and low-VOC construction adhesives for demanding building applications. This shift is also supported by Australia's Green Star building framework, under which at least 95% of internally applied paints, adhesives and sealants by volume must meet specified VOC limits in applicable rating pathways.
Many manufacturers are coming up with more water-based, reactive, and hybrid chemical compositions for use in the construction, flooring, packaging, and industrial sectors. An example of a manufacturer is Mapei, which produces solvent-free products with very low VOC emissions and increased sustainable products with environmental product declarations. The trend reflects increasing demand for sustainable building products and environmental certifications. This helps push manufacturers to improve curing capabilities, durability, and application efficiency with reduced emissions.
A major challenge for the Australia adhesives market is rising regulatory and formulation pressure surrounding chemical composition and environmental emissions. Adhesive manufacturers must increasingly manage VOC emissions and restrictions affecting certain chemical substances while maintaining required bonding strength, durability, curing speed and application performance. Australia’s Industrial Chemicals Environmental Management framework includes chemical classes relevant to adhesives and sealants, with additional management requirements taking effect from 2027. At the same time, shifting from conventional solvent-based formulations to lower-emission alternatives can increase development and production costs. Manufacturers must therefore invest in reformulation, testing, compliance and technical support while keeping products competitively priced. These pressures are particularly challenging for smaller suppliers with limited R&D and regulatory resources, potentially slowing the introduction of new adhesive technologies, thus aiming more towards the Australia adhesives market developments.
Compound Annual Growth Rate
4.32%
Value in USD Million
2026-2035
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Sika completed its acquisition of Turkish adhesives and sealants producer Akkim in September 2026, expanding production capacity, distribution access and the company’s international adhesives platform. Greater global scale can strengthen Sika’s ability to supply specialised bonding technologies and compete for industrial and construction customers in Australia.
Henkel commenced Australian production of LOCTITE PC 9313 at its Kilsyth facility in Victoria. The rubber-modified epoxy targets severe abrasion and impact environments in industries including mining, quarrying and power generation. Local production improves supply resilience and delivery responsiveness for Australian industrial adhesive users.
Mapei commenced construction of a new manufacturing facility at Truganina, Melbourne, to expand its Australian production footprint and serve infrastructure and construction requirements. Additional domestic manufacturing capacity should improve product availability and support faster servicing of Victorian and regional construction projects.
Bostik announced ADCOTE as the main global brand for its flexible-materials portfolio, bringing multiple technologies under a unified identity. Portfolio consolidation can simplify product selection and strengthen supplier visibility among packaging and flexible-material customers.
Australia’s 2026–27 Budget maintains a rolling infrastructure pipeline exceeding $120 billion over ten years, while funding continues for nationally significant transport projects. This environment benefits suppliers capable of providing adhesives with defined curing profiles, weather resistance, substrate compatibility and long-term durability rather than commodity bonding products. For manufacturers, specification engagement with engineering contractors, infrastructure designers and building-material distributors can improve project visibility before procurement decisions are finalized. The opportunity is particularly relevant to suppliers able to combine adhesives with waterproofing, flooring, façade and concrete-repair systems, allowing them to participate in broader construction-material packages rather than compete solely on adhesive price.
The move towards sustainable energy in Australia has increased the need for adhesives used in energy-related components, including solar panels, batteries, electric-vehicle chargers and other consumer energy-resource equipment. Australia had more than 4.3 million households with rooftop solar by the end of 2025, with 28.3 GW of installed rooftop PV capacity, while 268,000 home batteries were installed during 2025 alone, representing a 260% year-on-year increase. Battery adoption is continuing to broaden the installed base of energy-storage equipment requiring reliable protection against vibration, moisture, thermal cycling and electrical stresses. The Australian Government’s 18 minimum consumer energy-resource device requirements introduced in March 2026 further strengthen the focus on interoperability and communications capabilities. Together, these developments provide adhesive manufacturers with opportunities to develop application-specific solutions for electronics protection, sealing, thermal management and electrical isolation rather than relying primarily on construction-oriented products.
Adhesive buyers operating in mining, infrastructure and industrial maintenance increasingly value predictable availability alongside technical performance. Henkel’s 2026 decision to manufacture LOCTITE PC 9313 locally demonstrates how suppliers can reduce dependence on imported finished products while improving regional supply responsiveness. The strategic implication for Australia adhesives market participants is significant. Local production, regional warehousing and technical-service capability can become purchasing criteria where downtime carries substantial costs. Producers can strengthen competitiveness by localising high-volume or critical formulations and maintaining technical teams close to industrial customers rather than relying exclusively on international distribution networks.
The adhesive industry is moving to develop adhesives that consume lower energy, lower exposure to VOC, use less materials and are simpler to install. According to the 2026 INDEX launch by H.B. Fuller, there are low application temperature, high mileage and bio-based adhesive technologies used in hygiene applications. For the Australian industry, the business opportunity is to convert sustainable features to tangible purchasing advantages, such as less adhesive usage, faster cycles, low application temperatures and better recyclable substrates compatibility.
Adhesive selection increasingly involves simulation, substrate modelling and digital technical support, particularly for demanding industrial assemblies. 3M’s Ask 3M, launched for engineers in December 2025, uses generative AI, advanced modelling and simulation-ready data to help users evaluate adhesives against substrates, environmental conditions, assembly methods and performance requirements. Its Digital Materials Hub provides verified material data cards compatible with major FEA platforms, including Abaqus, ANSYS MAPDL, ANSYS Workbench and LS-Dyna. 3M also states that its structural adhesives can deliver more than 1,000 psi of overlap shear strength, demonstrating why accurate material modelling is important for engineering applications. For Australian industrial customers, these tools can support faster material screening and specification, helping suppliers move upstream from product vendors towards engineering and design partners.
The Expert Market Research’s report titled "Australia Adhesives Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Resin
Key Insight: Resins are now evolving more towards application-specific solutions, with epoxies, acrylics, silicones, cyanoacrylates, and VAE/EVA resins each suitable for a certain type of application. Epoxy resins have great potential in applications that require strength and resistance to tough environmental conditions. Acrylics are suitable due to their versatility in assembly and construction applications, whereas silicones cater to sealing, electronics and temperature sensitive applications. Cyanoacrylates still have a role in rapid assembly and repair applications. VAE/EVA resins are relevant in woodworking, packaging, and general bonding applications. Suppliers stand to gain significantly by creating resin systems based on substrate and processing requirements rather than marketing formulations simply according to their chemical category. This would allow differentiation in high value applications and help avoid direct competition based on price.
Market Breakup by Technology
Key Insight: Technology selection in Australia is increasingly determined by curing speed, emissions, energy consumption, automation compatibility and application environment. Water-borne adhesives benefit from reduced solvent requirements and are suited to several construction, flooring, woodworking and general assembly applications. Hot melts provide fast processing and are attractive for automated production lines, packaging and component assembly. UV-cured technologies offer rapid curing and process control where compatible substrates and light exposure can be maintained. Reactive adhesives address applications demanding durable, high-performance bonds, while solvent-borne systems remain relevant where specific wetting and bonding characteristics are required. The strongest growth opportunities are likely to emerge where manufacturers can demonstrate measurable productivity improvements alongside environmental benefits. Automated dispensing, lower-temperature processing and reduced curing time are becoming increasingly important for Australian industrial users managing labour, energy and production-efficiency pressures.
Market Breakup by End Use
Key Insight: Building and construction represents a substantial application base due to the usage of adhesives in floors, tiles, insulation, water-proofs, façades, woodworking and repairs. The trend for automotive applications is shifting towards using adhesives because of the need for lightweight, vibration reduction and improved assembly processes. Aerospace continues to be a high-end field where special materials and great reliability is required. The fields of woodworking and joinery will be helped by the growing demands for tough and clean bonding, whereas healthcare will require precise adhesive solutions for its particular products and devices. Footwear and leather fields continue to be more specialized but may benefit from the advanced flexible bonding technology solutions. Opportunities for future growth in the market will be more related to the areas where the adhesive bonding will replace mechanical fastening or will perform several functions, like bonding and sealing.
Market Breakup by Region
Key Insight: Regional demand reflects differences in population, construction activity, industrial concentration, mining exposure and infrastructure investment. New South Wales benefits from a large construction and infrastructure base and extensive commercial activity, supporting consistent adhesive consumption. Victoria has a strong manufacturing, construction and advanced-industry ecosystem and is attracting additional adhesive production capacity. Queensland offers opportunities through transport infrastructure, housing development, mining and energy projects. Western Australia provides specialised industrial demand linked to resources and engineering activities. The Australian Capital Territory represents a smaller but specification-intensive market associated with government, commercial and institutional construction. Other territories and states contribute through mining, regional construction, infrastructure and maintenance requirements. Regional suppliers can improve market penetration by aligning distribution networks with project clusters and industrial users rather than applying a uniform national sales strategy.
By resin, epoxy is anticipated to dominate due to structural strength and industrial versatility
Epoxy is anticipated to dominate the resin segment because of its structural strength and industrial versatility. Its suitability for demanding bonding, repair, equipment protection and composite applications provides a broad addressable customer base. Industrial users value epoxy systems where mechanical fastening is difficult or where resistance to impact, abrasion, chemicals and environmental exposure is important. The technology also benefits from applications in energy equipment and advanced manufacturing. Its ability to bond dissimilar substrates further increases its relevance to Australian manufacturers seeking lightweight or simplified assemblies. Such developments will thus boost the Australia adhesives market dynamics and trends in the long run.
Silicone is expected to record rapid growth as electronics and energy applications expand. Silicone adhesives and sealants combine flexibility with temperature resistance, electrical insulation and environmental durability, making them suitable for electronic assemblies, power equipment and specialised industrial applications. Australia’s expanding renewable-energy base is supporting this opportunity, with 6.8 GW of renewable energy capacity added in 2025, including around 2.8 GW of rooftop solar installations. Their relevance increases as Australian businesses adopt batteries, distributed energy equipment and connected electrical systems. Suppliers with thermally stable and electrically insulating silicone formulations can target higher-value applications where conventional construction adhesives provide inadequate performance.
By technology, water-borne adhesives are anticipated to dominate due to broad application suitability
Water-borne adhesives are expected to remain dominant because of their broad industrial applicability and lower solvent dependence. continue dominating on account of their wide range of applications across various industries and reduced dependence on solvents. These adhesives apply especially well to flooring, wood processing, building construction, and a variety of other assembling processes where manufacturers are looking for easy-to-apply products with low emissions. Suppliers can strengthen this segment by improving moisture resistance, open time, bond strength and substrate compatibility without compromising environmental performance.
Reactive adhesives are positioned for rapid growth as high-performance assembly requirements increase. These systems provide durable bonds across demanding applications where conventional adhesives may not meet structural, thermal or chemical requirements. Their relevance is increasing in transportation, advanced manufacturing, electronics and specialised construction. Australian suppliers can capture growth by offering two-component and moisture-cure systems with controlled processing, rapid handling strength and compatibility with automated dispensing equipment.
By end use, building and construction is anticipated to dominate due to extensive application diversity
Building and construction is expected to dominate end-use demand due to extensive application diversity. Adhesives are used throughout flooring, tiling, insulation, waterproofing, joinery and finishing activities, creating recurring demand across residential, commercial and infrastructure projects. In Australia, the value of building work done reached A$45.8 billion in the June quarter of 2026, up 10.0% year-on-year, highlighting the scale of construction activity supporting adhesive consumption. The segment also provides suppliers with opportunities to bundle adhesive products with complementary construction chemicals. Local manufacturing and technical distribution can further strengthen competitiveness by improving delivery reliability for contractors and project-based procurement.
Automotive is expected to be among the fastest-growing end-use segments as bonding supports lightweight vehicle construction. Adhesives can join metals, plastics, composites and glass while reducing the need for conventional fasteners. They also support vibration damping and improved component integration. Future opportunities extend beyond conventional vehicles into battery systems, EV components and advanced electronic assemblies. Suppliers able to provide thermal, structural and electrically functional bonding technologies can access higher-value vehicle applications.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
New South Wales leads, supported by diverse construction, commercial, industrial, and infrastructure demand
New South Wales is expected to remain the leading regional market because of its diversified construction, commercial, industrial and infrastructure ecosystem. The state offers adhesive manufacturers a broad customer base spanning building contractors, flooring specialists, joinery businesses, industrial users and engineering companies. Victoria represents a particularly important growth centre because its manufacturing capabilities and infrastructure programme are attracting additional investment from materials suppliers. Mapei’s decision to develop a new Truganina facility illustrates how manufacturers are increasing local production capacity close to major construction demand. The project is intended to support infrastructure requirements across metropolitan and regional Victoria, thereby directly boosting the Australia adhesives market regional growth.
Queensland offers a different growth profile, with transport infrastructure, housing, mining and energy projects supporting demand for industrial and construction bonding systems. The Federal Budget specifically includes funding for the Bruce Highway, reinforcing the state’s infrastructure opportunity. Western Australia remains strategically relevant for high-performance industrial adhesives because of its resources and engineering base, while the Australian Capital Territory provides a smaller but specification-oriented market associated with government and institutional construction. Other regions can generate niche opportunities through mining, regional infrastructure, maintenance and renewable-energy projects. Overall, suppliers seeking national expansion should prioritise NSW and Victoria for market scale and manufacturing connectivity while developing specialist sales channels in Queensland and Western Australia for project-driven industrial applications.
Competition in the Australia adhesives market is increasingly centred on technical differentiation, application engineering, supply reliability and product localisation. Global suppliers are expanding specialist formulations for automotive, electronics, construction and energy applications, while regional operations are strengthening manufacturing and distribution capabilities. Companies are also using acquisitions, local production and portfolio consolidation to improve scale and shorten supply chains.
Another important strategy is movement toward solutions rather than individual adhesive products. Australia adhesives companies are combining bonding, sealing, waterproofing, thermal management and surface-treatment capabilities to increase customer retention. Digital technical support is also becoming more important as engineers increasingly evaluate bonding solutions during the design stage. Sustainability is being integrated into formulation development through lower-temperature processing, reduced emissions and improved material efficiency. These approaches allow suppliers to defend margins by selling application performance and lifecycle benefits instead of competing primarily on adhesive unit price.
3M traces its operations to 1902 and has its principal executive offices in St. Paul, Minnesota. Its Australian business participates across industrial, transportation, electronics, healthcare and consumer applications. Its adhesive offering includes pressure-sensitive tapes, bonding systems, industrial tapes and specialised attachment technologies. The company’s strength lies in combining adhesive technologies with material science, converting and application engineering, enabling it to address customers seeking bonding, protection and assembly solutions across multiple industrial environments.
Dow was founded in 1897 by Herbert H. Dow and is headquartered in Midland, Michigan. The company supplies materials across adhesives, sealants, silicones, polyurethanes and specialty polymers. Its portfolio addresses mobility, electronics, infrastructure and industrial applications. In Australia, Dow can leverage its broader materials-science capabilities to supply customers seeking integrated bonding, sealing and thermal-management solutions, particularly where adhesive performance must be combined with heat resistance, electrical protection or lightweighting requirements.
DuluxGroup’s origins date to 1918 and its headquarters are located in Clayton, Victoria. Its adhesives presence is centred on Selleys, which manufactures and markets sealants, adhesives and fillers for Australian and New Zealand trade and DIY customers. The portfolio includes Selleys, Liquid Nails, No More Gaps and Poly. Its Australian manufacturing and distribution infrastructure provides an important advantage in serving construction, maintenance, repair, home improvement and trade applications requiring accessible, application-specific bonding solutions.
Mapei was founded in Milan in 1937 and remains headquartered there. The company specialises in construction chemicals and offers extensive adhesive technologies for ceramics, stone, flooring, timber, waterproofing and structural applications. Its Australian strategy is increasingly supported by local production. The planned Melbourne manufacturing facility is intended to strengthen supply to Victorian and regional infrastructure and construction projects. This combination of specialised formulations, technical support and local manufacturing provides Mapei with a strong position in specification-led construction applications.
Other key players in the market include Huntsman International LLC, H.B. Fuller Australia Pty Ltd., and Sika Australia Pty Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the Australia adhesives market trends 2026 and gain a clearer view of competitive opportunities, financing channels, regional demand and evolving borrower requirements. Download the sample report to examine the Australia adhesives market forecast 2026-2035, market segmentation, competitive landscape and strategic insights supporting lenders, automotive businesses, dealerships and financial-service providers planning their next growth initiatives.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market was valued at USD 961.27 Million in 2025.
The market is projected to grow at a CAGR of 4.32% between 2026 and 2035.
The revenue generated from the market is expected to reach USD 1467.31 Million in 2035.
The adhesive market is categorised according to technology, which includes UV cured adhesives, water-borne, solvent-borne, hot melt and reactive.
The key players are 3M Australia Pty Limited, Dow Performance Materials (Australia) Pty Ltd., DuluxGroup Limited, H.B. Fuller Australia Pty Ltd., Huntsman International LLC, Mapei Australia Pty Ltd., and Sika Australia Pty Ltd. among others.
Based on the end use, the market is divided into automotive, building and construction, aerospace, footwear and leather, woodworking and joinery, healthcare, and others.
The market is broken down into New South Wales, Victoria, Queensland, Australian Capital Territory, Western Australia, and others.
Key challenges include volatile raw-material costs, stringent VOC and environmental regulations, supply-chain disruptions, skilled-labour shortages, intense competition, and costly development of high-performance sustainable adhesive formulations.
Key strategies include developing low-VOC and sustainable adhesives, investing in advanced bonding technologies, expanding local supply capabilities, targeting construction and packaging demand, and strengthening specialised automotive and industrial applications.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Resin |
|
| Breakup by Technology |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




