

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
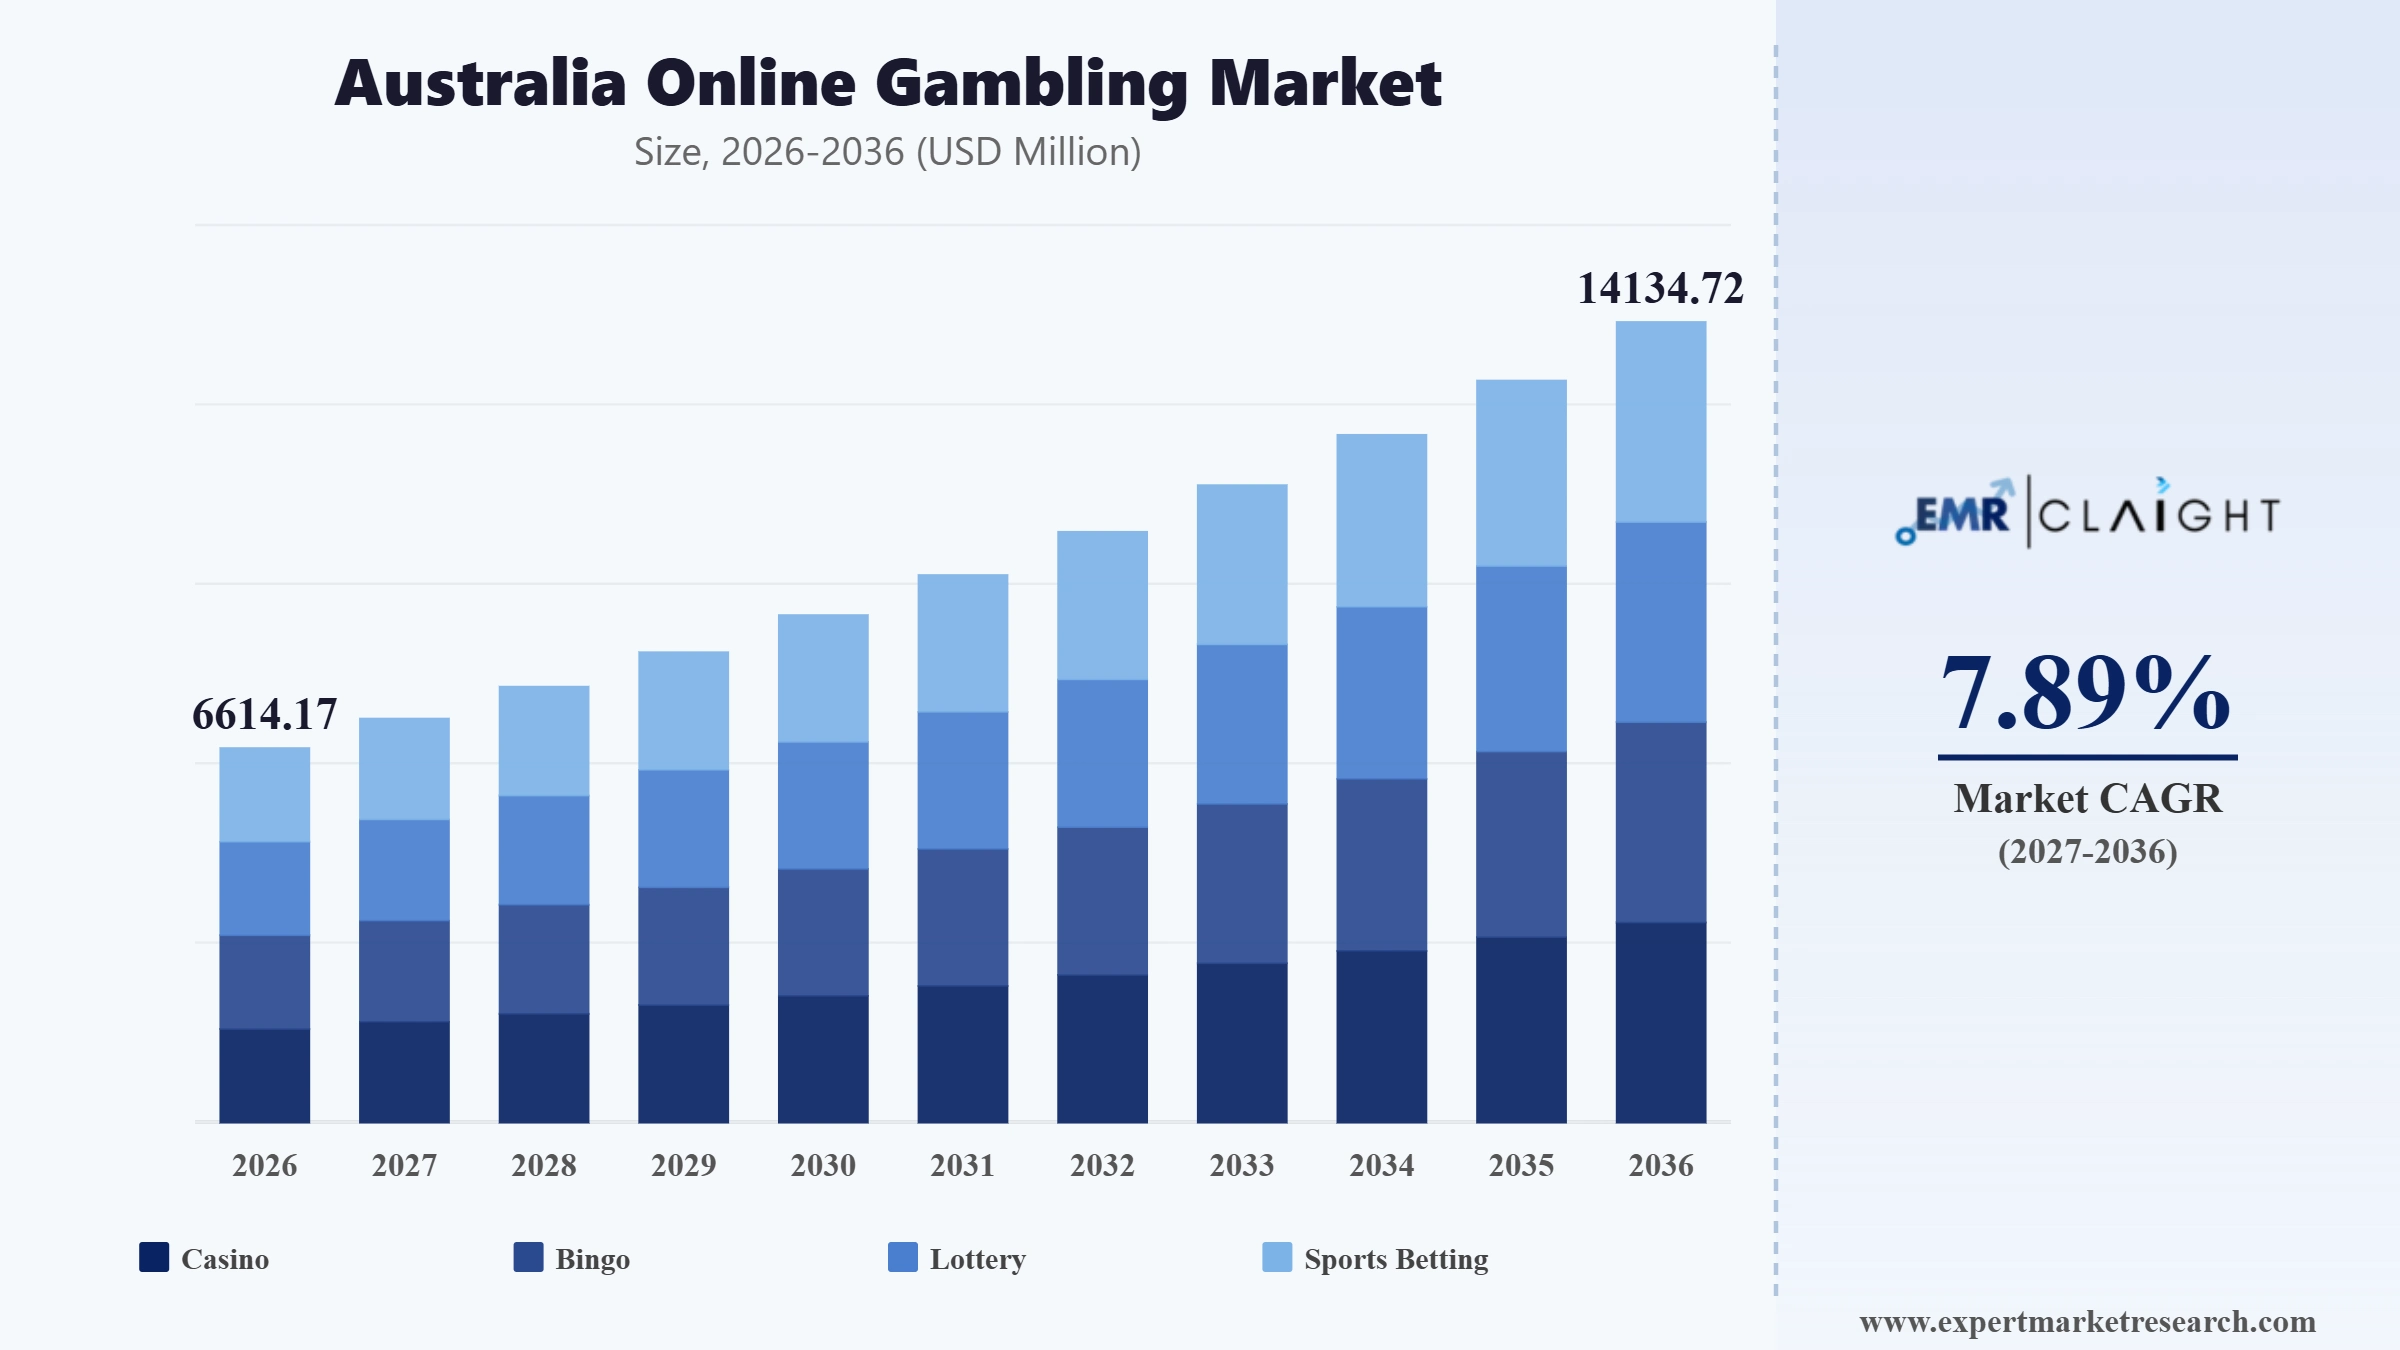
The Australia online gambling market attained a value of USD 6130.48 Million in 2025 and is projected to expand at a CAGR of 7.89% through 2035. The market is further expected to achieve USD 13101.06 Million by 2035, driven by rising mobile betting adoption, expanding digital payment options, and growing consumer preference for sports betting and live casino formats. Growth spans casino, bingo, lottery, and sports betting game types across mobile and desktop devices, with operators across New South Wales, Victoria, Queensland, and Western Australia competing on licensing compliance, responsible gambling technology, and personalised user experience.
Rising smartphone penetration and digital payment adoption continue to anchor steady demand across the Australia online gambling market, as consumers increasingly favour convenient, on-the-go betting over traditional retail wagering channels. Operators are also investing in platform consolidation and rebranding, reflecting the industry's ongoing merger and acquisition activity as smaller brands combine under larger, better-capitalised parent companies.
The Australia online gambling market is witnessing further developments as established operators consolidate brands following acquisition activity. PlayUp Interactive, following its acquisition by NextBet, is set to complete its rebrand with the new NextBet-branded platform launching in March 2026. This shift toward brand consolidation following acquisition is concentrated among operators seeking scale efficiencies, while smaller independent bookmakers instead compete on niche product features and community-driven engagement.
In addition, regulators are increasingly enforcing compliance with responsible gambling frameworks, reflecting the industry's recognition that self-exclusion register adherence increasingly shapes licensing risk for operators. The Australian Communications and Media Authority fined Unibet approximately AUD 1 million in May 2025 for failing to close the accounts of customers registered on the BetStop national self-exclusion register. Such regulatory enforcement activity is reshaping competitive positioning across the wider australia online gambling market as operators with robust self-exclusion compliance systems increasingly differentiate themselves from competitors facing enforcement risk.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Australian operators are increasingly reassessing their licensing jurisdiction as state-based regulatory frameworks evolve. Betr became the first major operator to switch from a Northern Territory licence to a Tasmanian Gaming Licence, with existing customer accounts and open bets carrying over unchanged during the transition. Companies can leverage jurisdictional flexibility to align licensing arrangements with evolving regulatory expectations without disrupting existing customer relationships.
Consolidation activity in the Australian betting sector continues translating into full brand transitions rather than parallel operation of acquired platforms. PlayUp, following its acquisition by NextBet, is completing its transition with the new NextBet-branded platform launching in March 2026, with former PlayUp accounts migrating to the new brand. Companies can leverage full brand consolidation following acquisition to simplify technology stacks and marketing spend rather than maintaining multiple parallel platforms.
International gaming technology companies are increasingly viewing Australian betting brands as attractive acquisition targets amid a wave of consolidation. Japan's Mixi completed its takeover of PointsBet, acquiring approximately 66 percent of the operator and ending a prolonged bidding war with rival bidder Betr. Companies can leverage international parent company backing to access deeper capital reserves for technology investment and marketing than standalone domestic operators typically command.
Regulatory scrutiny of self-exclusion register compliance is intensifying as authorities enforce national responsible gambling frameworks more rigorously. The Australian Communications and Media Authority fined Unibet approximately AUD 1 million for failing to close accounts of customers registered on the BetStop national self-exclusion register. Companies can leverage robust automated self-exclusion checking systems to reduce enforcement risk as regulators increase scrutiny of compliance gaps.
State and territory gaming regulators are competing more actively for operator licensing business as the jurisdictional landscape continues to evolve. Betr's move to a Tasmanian Gaming Licence in July 2026 is prompting rival operators to formally review their own licensing arrangements, weighing potential compliance and cost advantages against the administrative burden of a jurisdiction switch. Companies can leverage close monitoring of competitor licensing decisions to inform their own jurisdiction strategy ahead of regulatory changes, positioning themselves to react quickly should a shift in licensing conditions materially alter the relative attractiveness of any given state or territory framework.
Operators completing brand consolidation following acquisition are prioritising minimal-disruption account migration over abrupt platform switchovers. The PlayUp-to-NextBet transition, completed in March 2026, included staged customer account migration to preserve betting history and balances, a template other Australian operators are studying ahead of their own anticipated consolidation activity. Companies can leverage staged account migration processes to retain customer loyalty through brand transition periods, reducing the churn risk that abrupt platform switchovers typically introduce when long-standing customers are forced to re-register on unfamiliar systems.
Smaller independent bookmakers are increasingly exiting the Australian wagering market as competitive and cost pressures intensify against better-capitalised operators. boombet.com.au, a Northern Territory-licensed operator tracing its roots to 1998, announced it would close its wagering platform entirely, ceasing new bets on 21 January 2026 and directing customers to withdraw remaining balances ahead of account closure. Companies can leverage the exit of smaller independent operators to absorb displaced customer accounts through targeted retention marketing, directing promotional offers specifically toward customers whose previous betting provider has ceased operating in the Australian market.
Overseas gaming and technology companies continue identifying Australian betting operators as attractive acquisition targets, drawn by the sector's established regulatory framework and sustained wagering growth. The Mixi-PointsBet transaction, concluded in September 2025 after a prolonged bidding war against rival suitor Betr, reflects broader international investor interest in accessing the Australian market through acquisition rather than the compliance complexity of securing new operator licences from scratch. Companies can leverage acquisition of an established, already-licensed local operator to enter the Australian market considerably faster than pursuing a new licence application independently.
This Expert Market Research Report titled "Australia Online Gambling Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market by Game Type
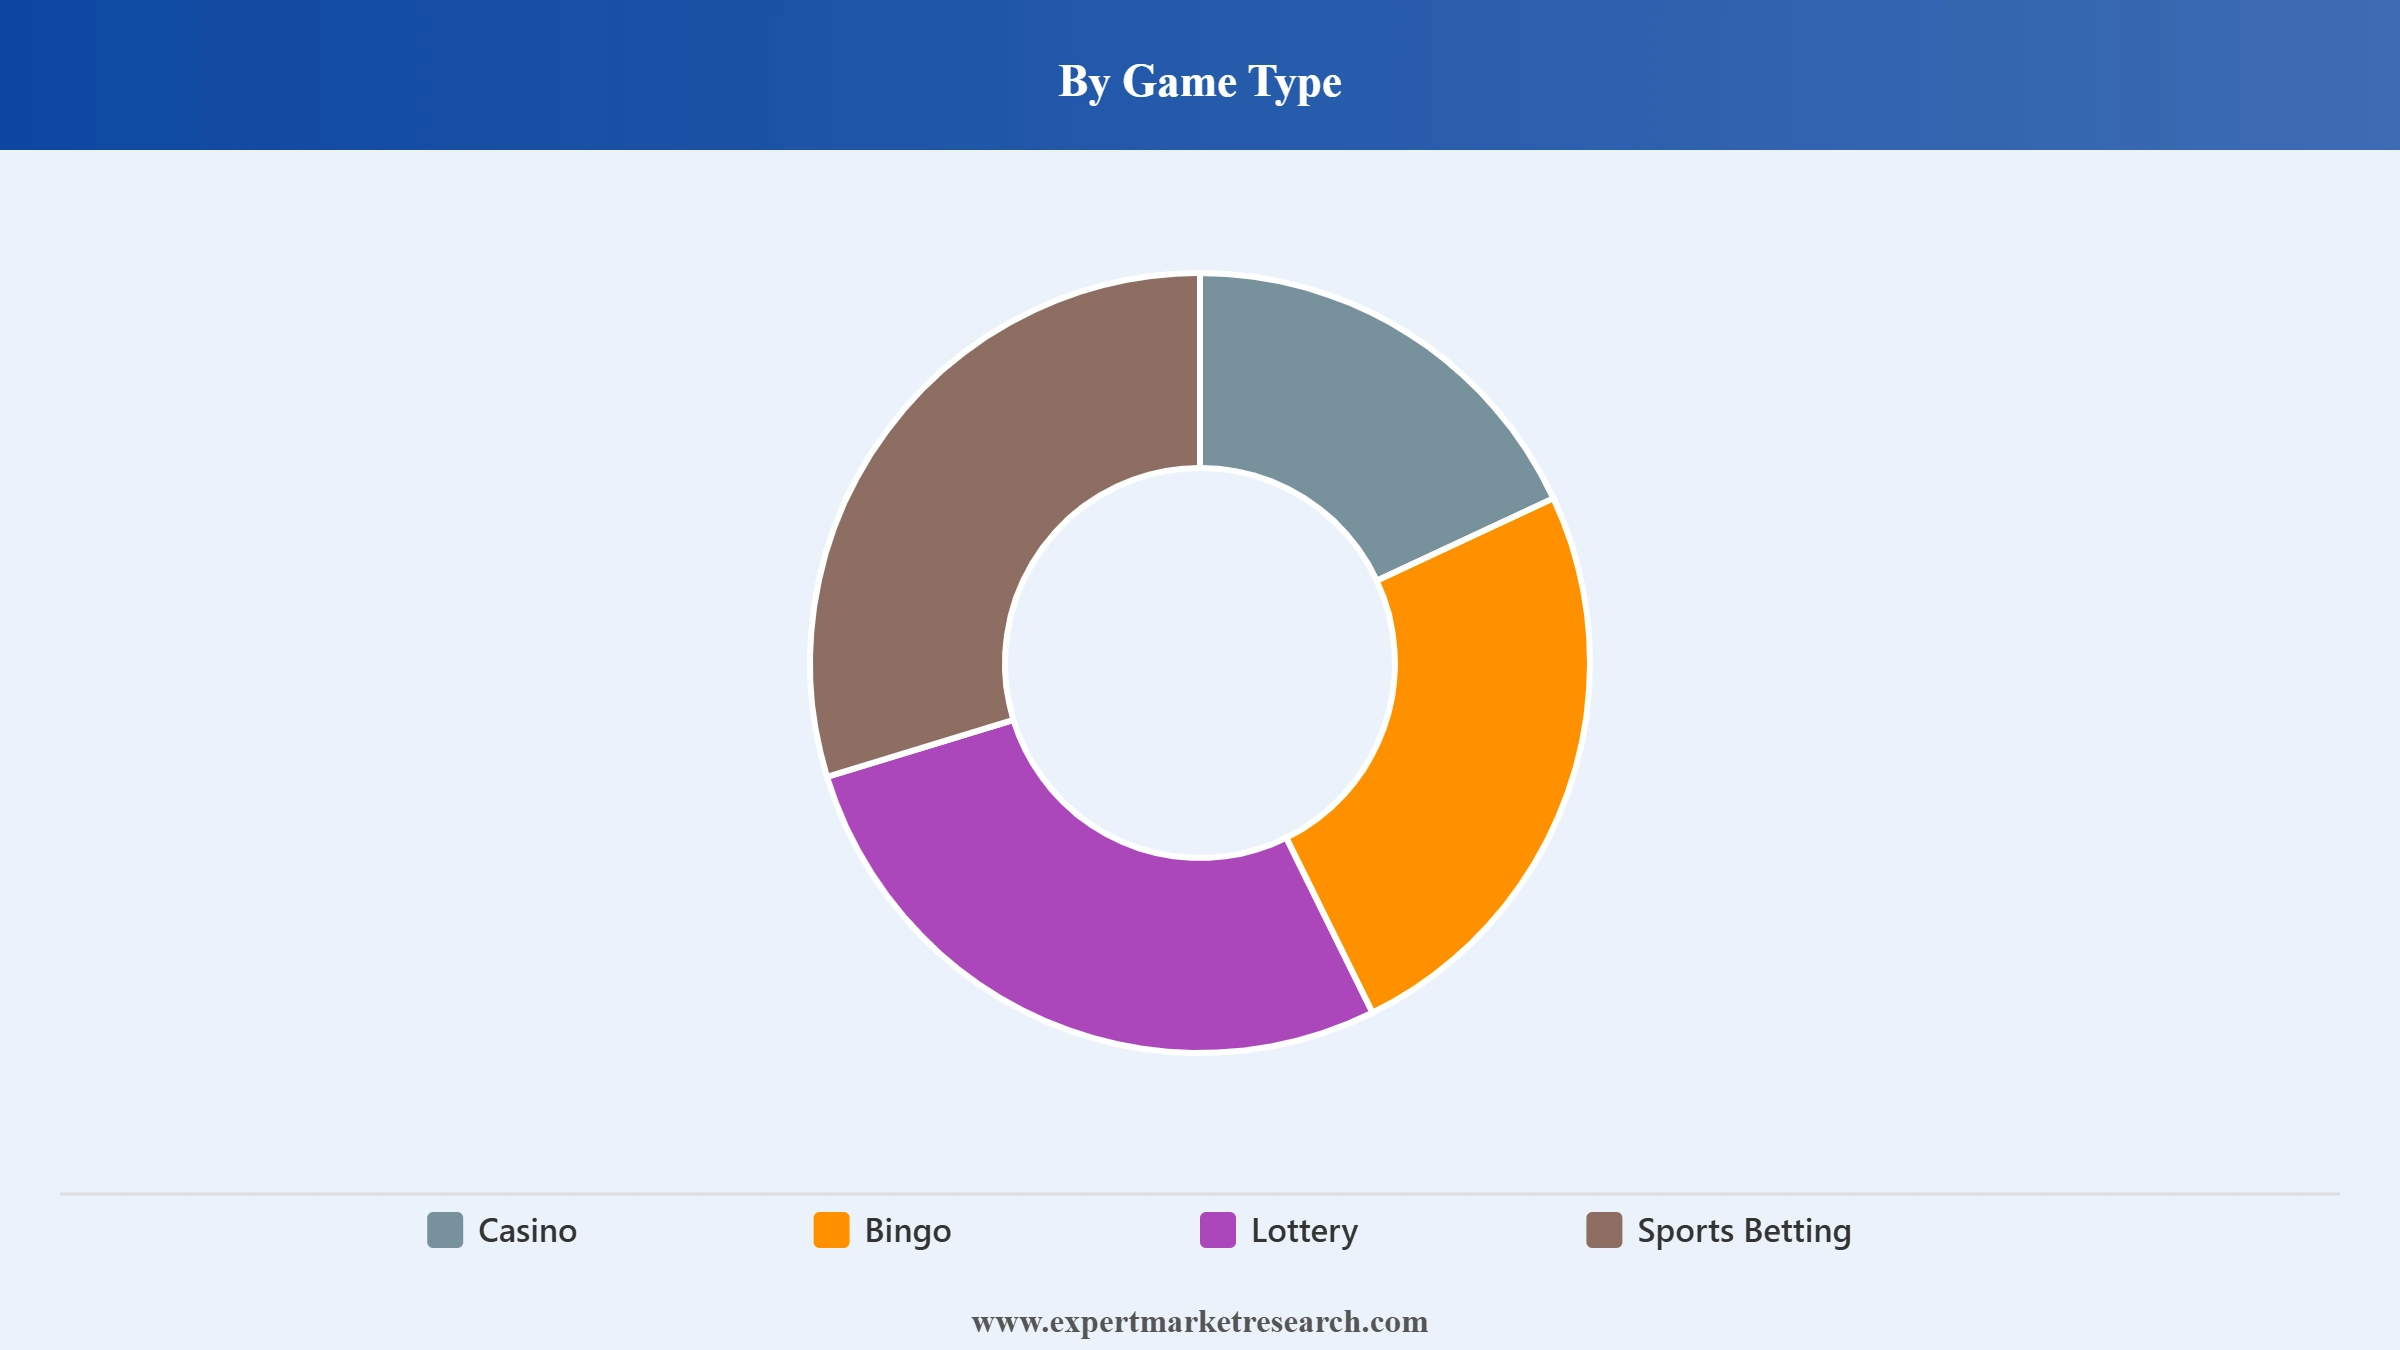
Key Insight: Sports Betting accounts for the largest share of the market, growing at a projected CAGR of 8.60%, with Horse Racing and Tennis representing established codes while Formula 1 and eSports drive growing specialist interest, reflecting the industry consolidation illustrated by PlayUp's March 2026 rebrand to NextBet. Casino follows closely, with Slots gaining popularity for accessibility and ease of play, Live Casino attracting players seeking authentic real-time dealer interaction, Poker retaining appeal through online tournaments and social features, and Blackjack and Baccarat serving traditional table game preferences. Bingo is regaining appeal among younger players through online social networks. Lottery continues attracting casual participants seeking simple, low-engagement wagering. Others within both Casino and Sports Betting categories captures smaller-volume niche game and betting code variants, formats that continue to attract dedicated enthusiast communities despite representing a modest share of overall wagering turnover.
Market Breakup by Device Type
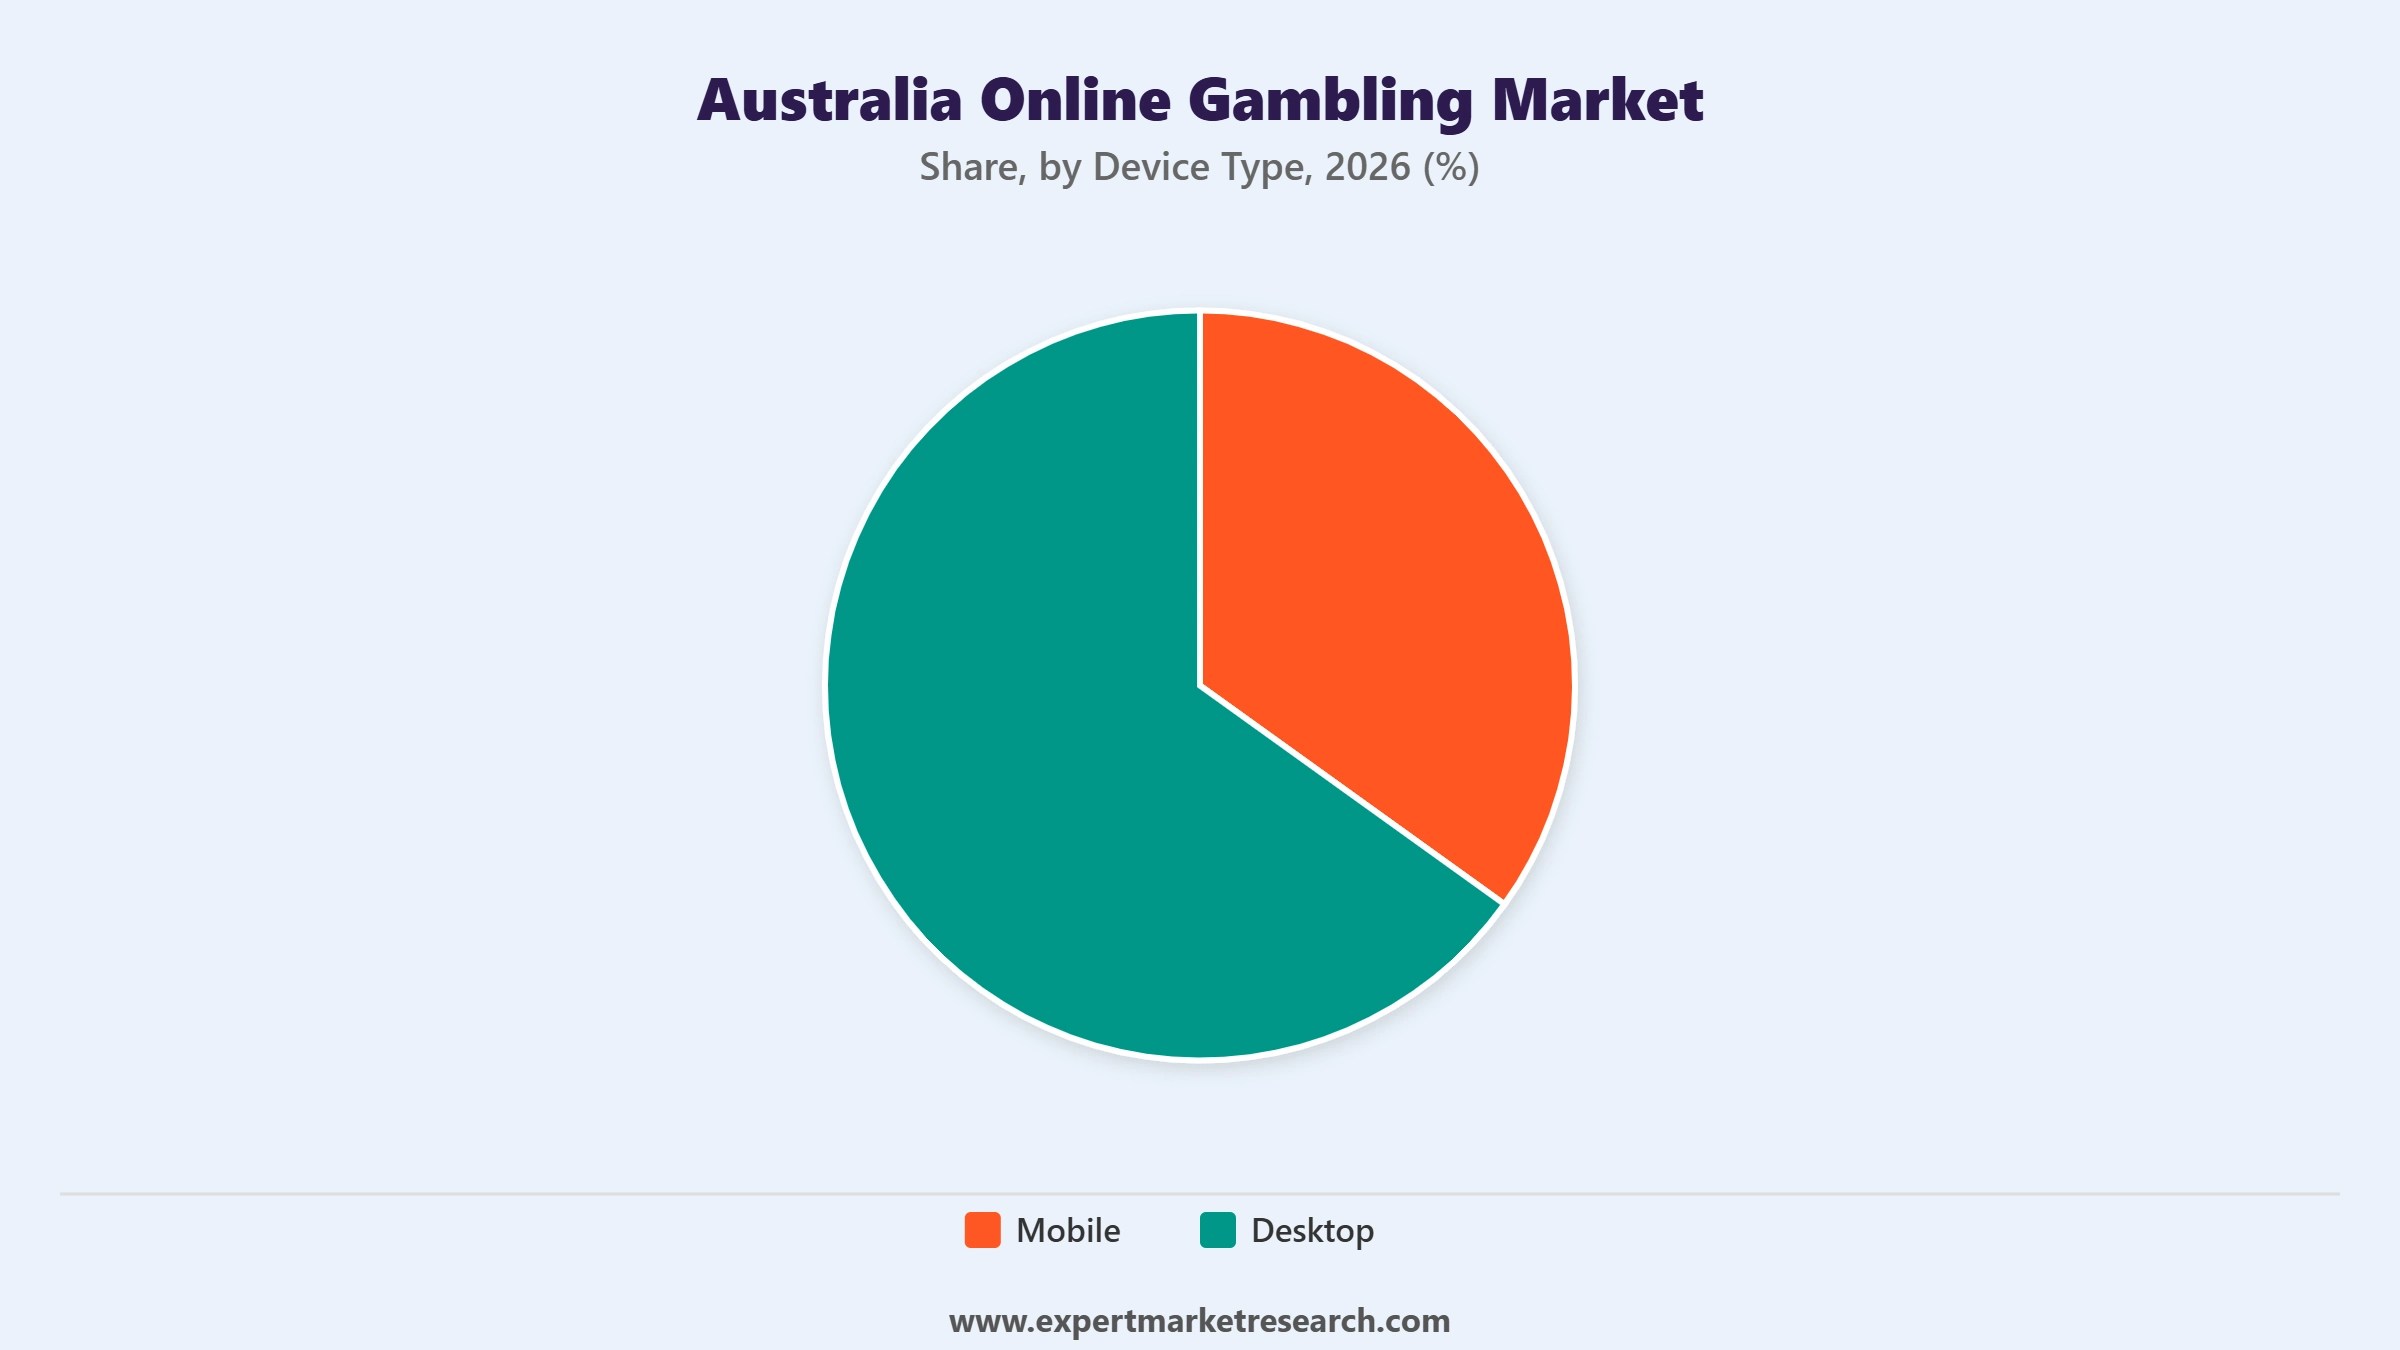
Key Insight: Mobile accounts for the largest share of the market at approximately 80% of total wagers, growing at a projected CAGR of 9.10%, as smartphone-first betting via dedicated apps becomes the dominant channel for placing bets on the go. Desktop continues to serve experienced players who prefer larger screens for intricate, detail-heavy games such as live casino tables. Others, including tablets, plays a smaller supporting role as consumers seek diverse device options for their online gaming experience, with tablet usage particularly concentrated among players who value larger screens for live casino streaming without the full desktop setup.
Market Breakup by Region
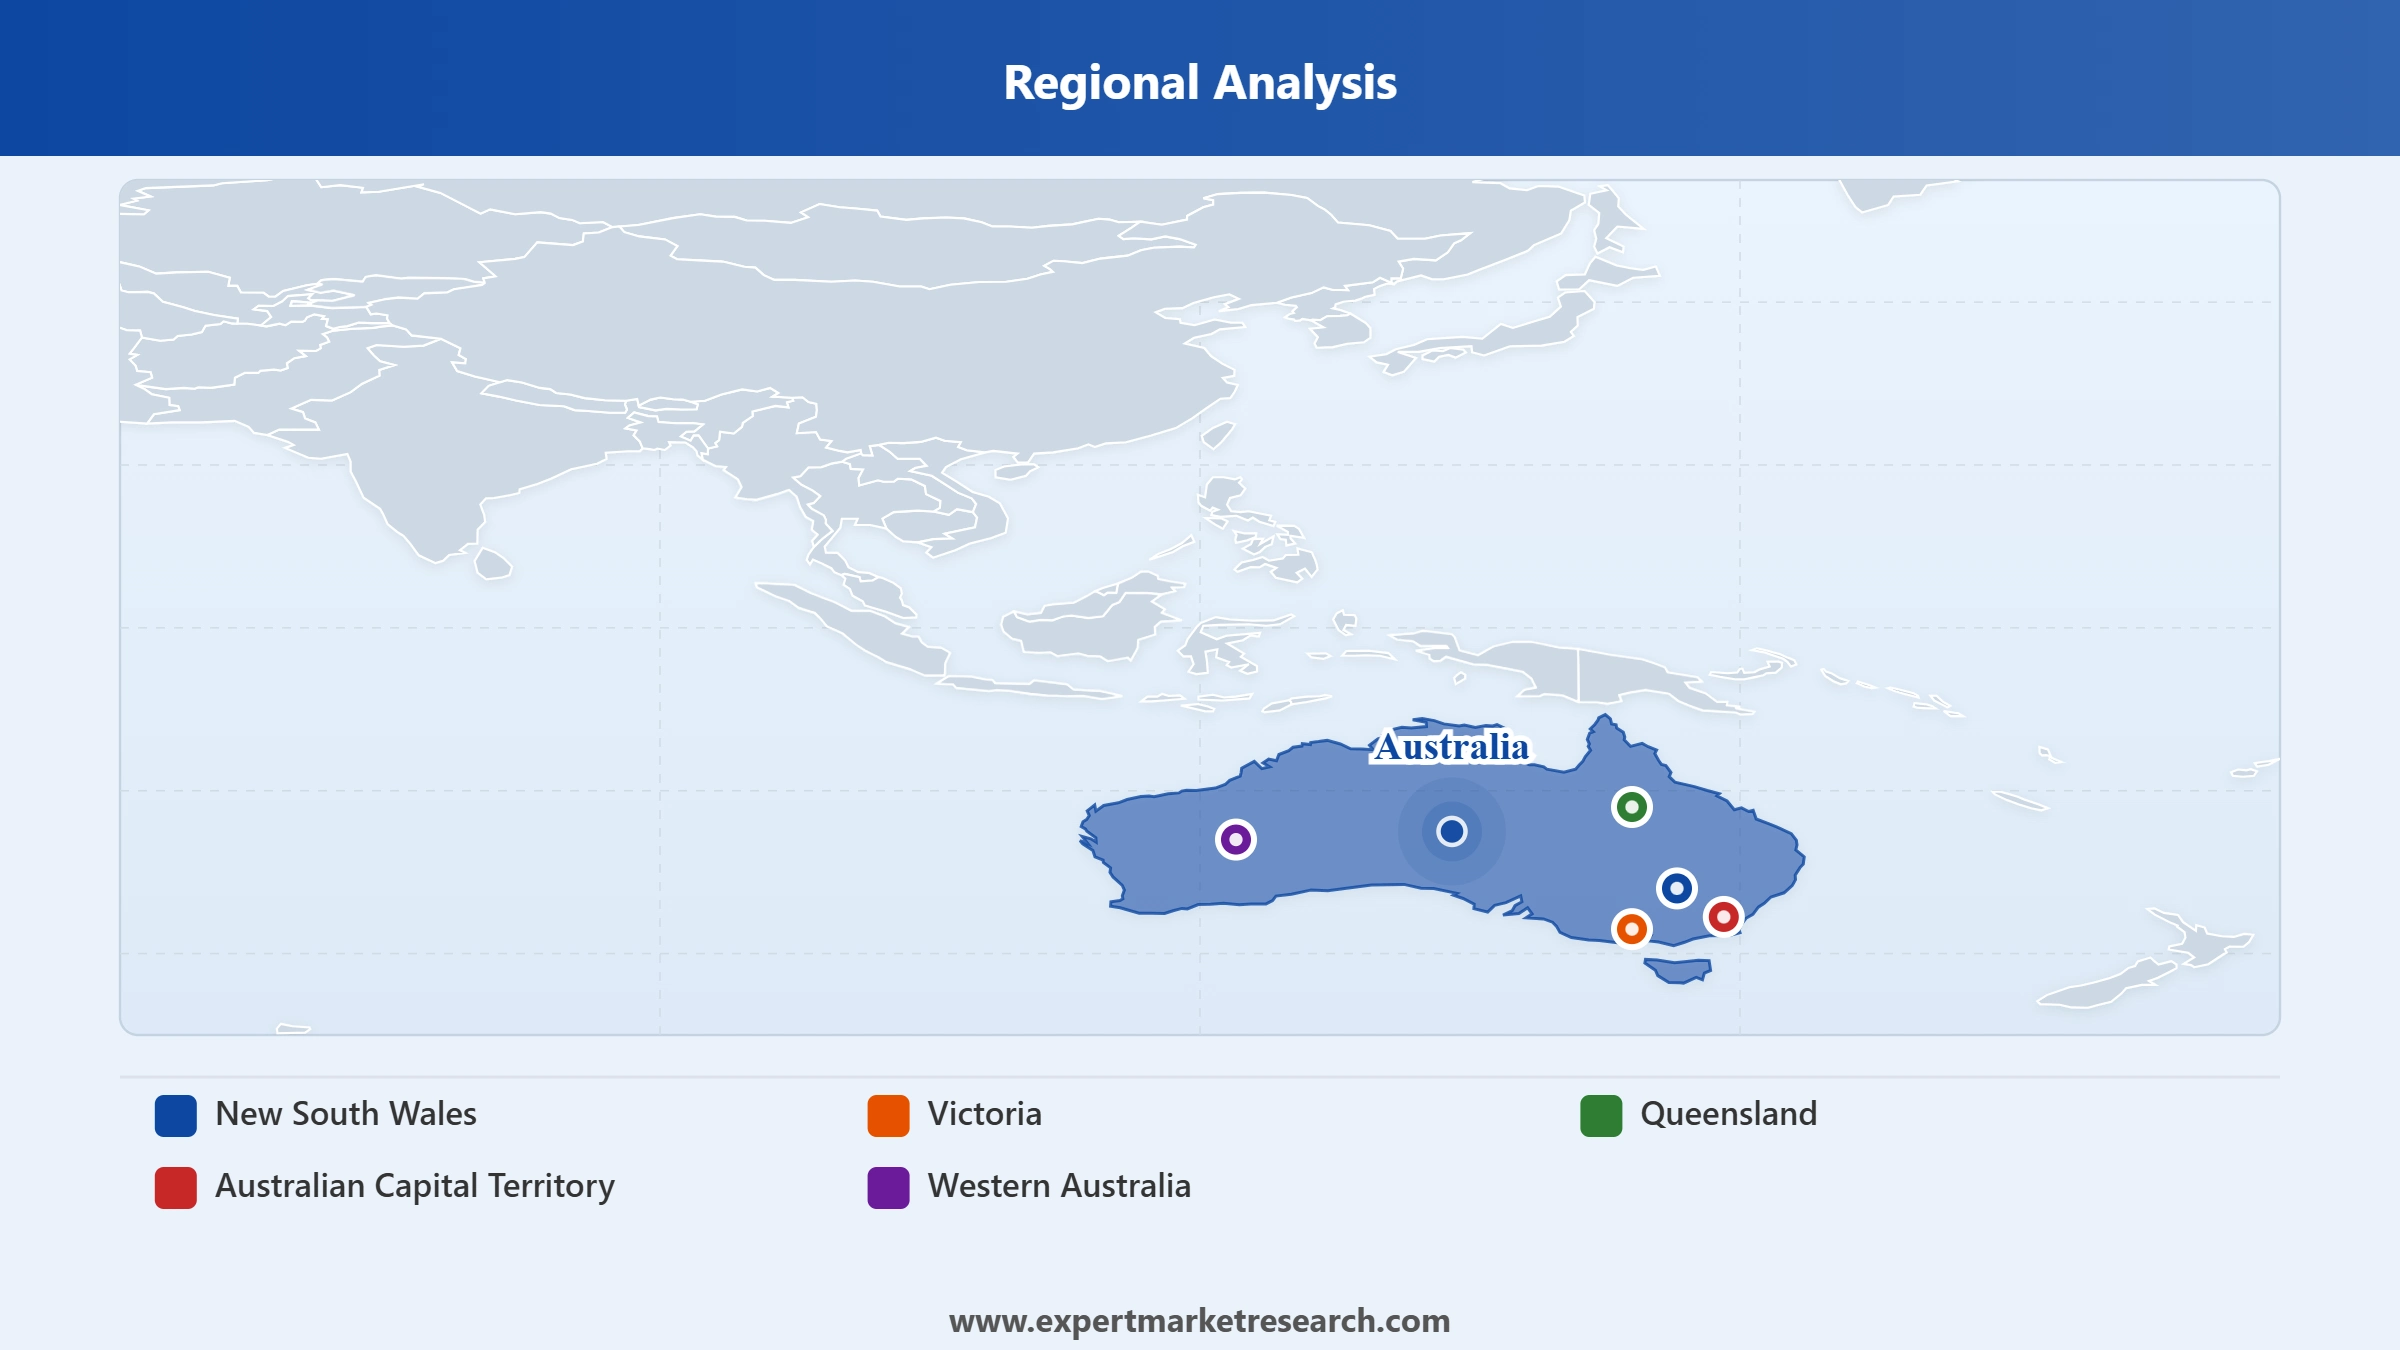
Key Insight: New South Wales accounts for the largest share of the market at over 40% of Australia's total online wagering earnings, with strong preference for sports betting on major events such as the NRL and AFL reflecting the state's sports culture. Victoria demonstrates robust competition and innovation underpinned by a solid regulatory framework supporting mobile betting and live sports wagering. Queensland shows significant mobile betting and live wagering trends as operators refine platforms for smartphone-first users. Australian Capital Territory continues growing as tech-savvy, increasingly populated residents adopt mobile betting and live wagering options. Western Australia faces more restrictive local regulatory limitations shaping how operators offer sports betting and digitised services. Others captures smaller state and territory markets including South Australia and Tasmania, where wagering activity tends to track closely with population size and major sporting event participation rather than any distinct regional pattern.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By game type, sports betting leads the market while further growth is reinforced by brand consolidation activity
Sports Betting continues to dominate the market, with growing interest in specialist areas such as Formula 1 and eSports alongside classic favourites including tennis and horse racing reflecting a wide range of consumer interests, a breadth Betr's July 2026 shift to a Tasmanian Gaming Licence has done nothing to disrupt for existing customers, with account balances and open bets carrying over unchanged throughout the licensing transition.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
This dominance is being reinforced by ongoing brand consolidation across the australia online gambling market, illustrated by PlayUp's completion of its rebrand to NextBet in March 2026 following its acquisition, concentrating sports betting market share under fewer, larger platforms with deeper marketing budgets and consolidated technology stacks, a pattern rival operators are watching closely as a possible template for their own future consolidation activity.
By device type, mobile leads the market while desktop remains popular among traditional gamblers
Mobile devices dominate the market, accounting for approximately 80% of total bets placed, with access via dedicated betting applications proving convenient for users wagering on the go, a dominance reinforced by Mixi's September 2025 takeover of PointsBet, which brought deeper international capital investment into mobile-first platform development, funding that competing platforms increasingly need to match given how central seamless mobile experience has become to customer retention.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Desktop remains popular among more experienced players who prefer larger screens with greater detail, particularly when engaging with intricate games such as live casino tables requiring closer visual attention. Others, including tablets, play a smaller supporting role as consumers seek diverse device options for their online gaming experience, with tablet usage skewing toward players who prefer a larger screen for live casino streaming over a full desktop setup.
New South Wales commands the largest regional share through its concentrated sports betting culture
New South Wales holds the largest share of the Australia online gambling market at over 40% of total online wagering earnings, with strong preference for sports betting on major events such as the NRL and AFL reflecting the state's deep sports culture.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Victoria demonstrates robust competition underpinned by a solid regulatory framework supporting continued mobile betting and live sports wagering innovation. Queensland shows significant momentum in mobile betting as operators refine platforms specifically for smartphone-first users across the state. Australian Capital Territory continues growing steadily as its tech-savvy, increasingly populated resident base adopts mobile betting and live wagering options. Western Australia contends with more restrictive local regulatory limitations that shape how operators structure their sports betting and digitised service offerings. Others, including South Australia and Tasmania, continues to serve distinct regional demand patterns tied to smaller population bases.
The industry is fragmented, with australia online gambling market companies ranging from international gaming conglomerates to Australian-owned specialist operators competing across game type, device type, and regional segments. Established players focus on better user experience and improved mobile access, with attention on personalised marketing promotions and responsible gambling initiatives.
Competitive dynamics among australia online gambling players are increasingly shaped by the pace of brand consolidation following acquisition, the depth of regulatory compliance systems, and the strength of mobile-first product development. Operators are investing in self-exclusion monitoring technology, licensing jurisdiction flexibility, and international capital partnerships to secure long-term relationships with customers and regulators alike.
Founded in 2020 and headquartered in Curacao, Dama N.V. is an online gambling operator offering casino games, sports betting, and live games. The company emphasises a user-friendly interface and a wide range of gaming content offerings designed to appeal to diverse player preferences. Dama's broad, internationally licensed casino and sports betting portfolio differentiates its offering from Australian-only domestic operators.
Founded in 2021 and headquartered in Sydney, Australia, WinnersBet focuses on sports betting and online wagering with competitive odds and wide sports coverage. The company emphasises user experience through features including live betting and targeted offers for both general and dedicated customers. WinnersBet's Australian-owned, sports-focused positioning differentiates its offering from broader international casino-led operators.
Founded in 2019 and headquartered in Melbourne, Australia, Puntaa is an innovative online betting platform specialising in sports betting and in-play betting opportunities. The company has developed itself as a social betting platform, enabling seamless sharing of tips among users and communication between fellow bettors. Puntaa's social, community-driven betting model differentiates its offering from conventional single-user wagering platforms.
Founded in 1997 and headquartered in Sydney, Australia, Unibet offers online gambling services spanning sports betting, casino games, and poker. The company emphasises user experience by combining advanced technology with a wide variety of gaming options. In May 2025, the company was fined approximately AUD 1 million by the Australian Communications and Media Authority for self-exclusion register compliance failures. Unibet's long-established, technology-led multi-product offering differentiates it from newer, narrower-focused entrants.
Other key players in the Australia online gambling market include PuntNow Pty Ltd., Merlehan Bookmaking Pty Ltd., boombet.com.au pty ltd, and PlayUp Interactive Pty Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Australia online gambling market trends 2026 report. Discover regional growth patterns, game type and device type trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 7.89% between 2026 and 2035.
The revenue generated from the market is expected to reach USD 13101.06 Million in 2035.
In 2025, the market reached an approximate value of USD 6130.48 Million.
The online gambling market is categorised according to the type, which includes casino, bingo, lottery, sports betting.
The key players in the market include Dama N.V., WinnersBet Pty Ltd., Puntaa Pty Ltd., Unibet/Betchoice Corporation Pty Ltd., PuntNow Pty Ltd., Merlehan Bookmaking Pty Ltd., boombet.com.au pty ltd, and PlayUp Interactive Pty Ltd., among others.
Based on the price range, the online gambling market is divided into mobile, desktops and others.
The market is broken down into New South Wales, Victoria, Queensland, Australian Capital Territory, Western Australia, and others.
Operators face strict and varying regulatory requirements across states, mounting compliance obligations tied to self-exclusion registers and responsible gambling frameworks, and the ongoing costs of maintaining licensing across multiple jurisdictions.
Consolidating acquired brands under unified platforms to achieve scale efficiencies, investing in automated self-exclusion compliance systems to reduce regulatory risk, and pursuing international capital partnerships to fund technology and marketing investment.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Game Type |
|
| Breakup by Device Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




