

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
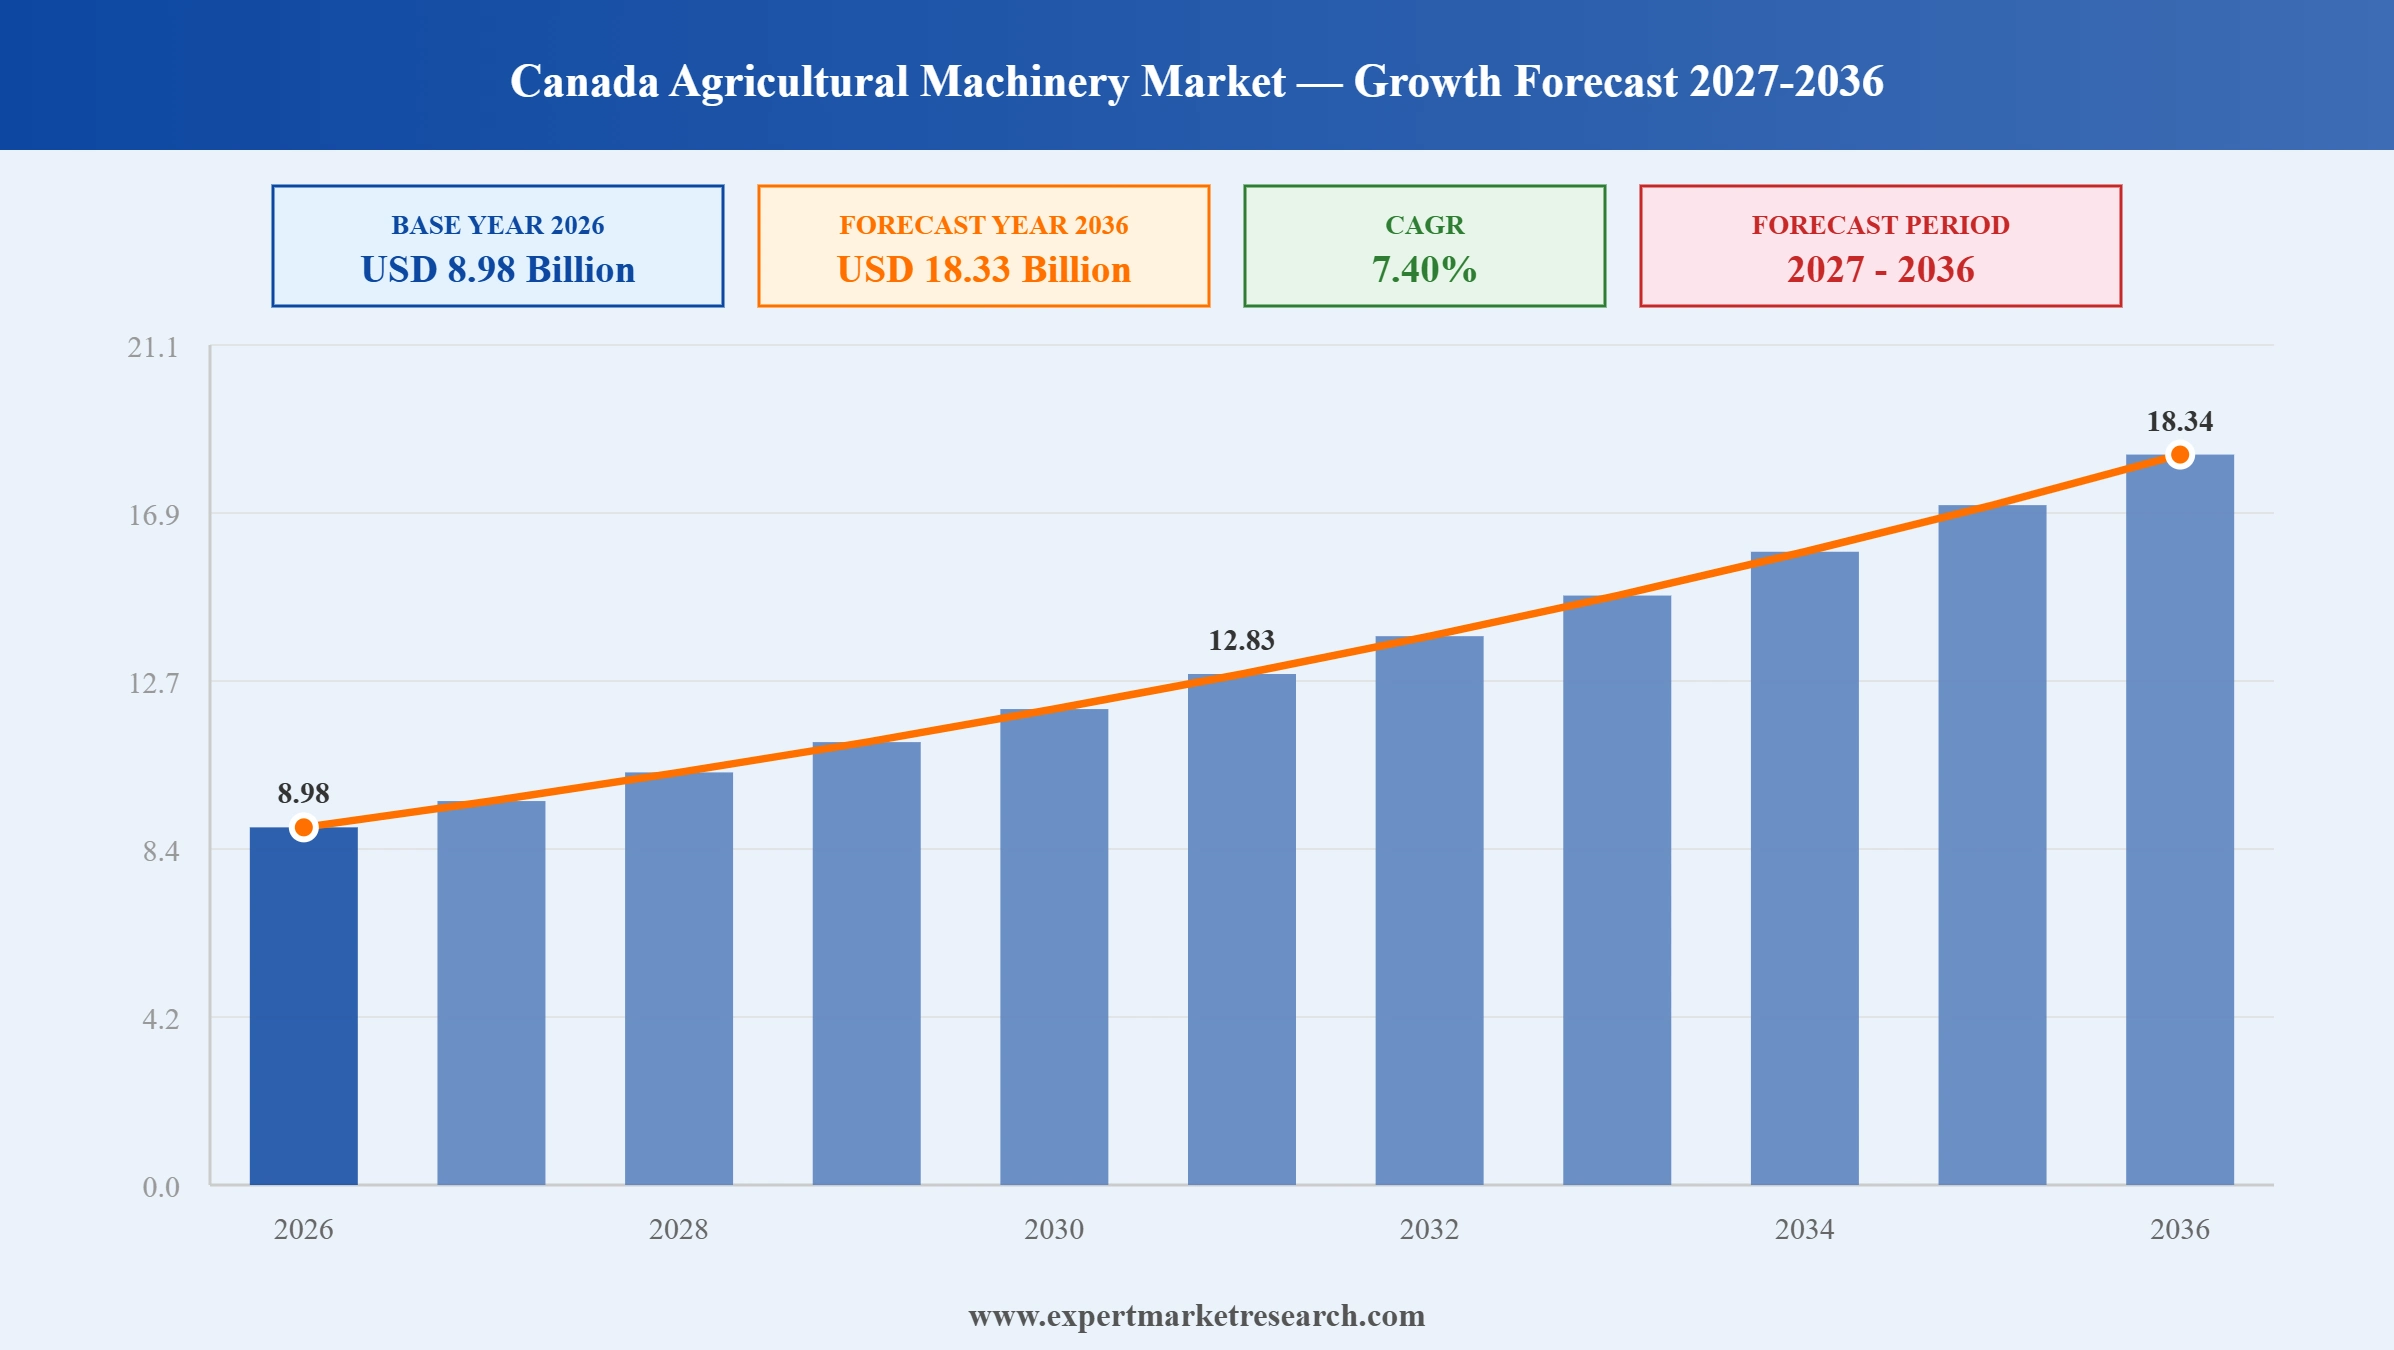
The Canada agricultural machinery market attained a value of USD 8.36 Billion in 2025 and is projected to expand at a CAGR of 7.40% through 2035. The market is further expected to achieve USD 17.07 Billion by 2035. Growing mechanisation of agriculture, rising demand for higher horsepower machines, and persistent shortages of specialised farm labour continue to support demand for tractors, tillage, planting, harvesting, and irrigation equipment across Canada's provinces.
Growing mechanisation of agriculture continues to anchor steady demand across the Canada agricultural machinery market, as farms grow larger and labour availability tightens across rural provinces, making equipment investment less a productivity choice than an operational necessity for many farmers. Manufacturers are also pursuing technology-focused acquisitions and regional partnerships, reflecting the industry's ongoing shift toward connected, data-driven equipment platforms and locally manufactured implements suited to large-scale Canadian operations.
The Canada agricultural machinery market is witnessing further developments as established manufacturers pursue technology acquisitions to expand equipment management capabilities. Deere & Company completed its acquisition of Tenna, a construction technology company offering mixed-fleet equipment and asset tracking solutions, with the platform designed to provide near-real-time visibility into equipment operations and maintenance needs. This shift toward connected equipment management technology is concentrated among manufacturers with sufficient technology investment capacity, while smaller regional dealers continue to compete on established local service relationships and equipment availability.
In addition, established manufacturers are increasingly forming strategic alliances with Canadian implement specialists to strengthen regional product coverage, reflecting the industry's recognition that partnerships with domestic seeding and ploughing and cultivating machinery manufacturers increasingly complement broader international product lines for large-scale Canadian grain operations. Such alliance activity is reshaping competitive positioning across the wider canada agricultural machinery market as manufacturers with strong Canadian-specific partnerships increasingly differentiate themselves from competitors relying solely on imported, non-localised equipment lines.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
CNH Industrial entered into a strategic alliance with Bourgault Industries, a Canadian manufacturer of seeding equipment for large-scale operations, with the agreement providing for the supply of Bourgault's seeding equipment through CNH Industrial's distribution network. Companies can form strategic alliances with established domestic implement manufacturers to strengthen product coverage for large-scale Canadian seeding and tillage operations without developing comparable equipment internally.
AGCO unveiled new Fendt and Massey Ferguson products at the Farm Progress Show, including updates to existing Vario tractor series and a preview of the IDEAL combine ahead of the Fendt Harvest Tour, alongside new planters and hay equipment from Massey Ferguson. Companies can use major industry trade shows to showcase updated tractor and implement lineups ahead of subsequent regional harvest tours and dealer demonstrations.
Deere & Company completed its acquisition of Tenna, a construction technology company offering mixed-fleet equipment and asset tracking solutions, with Tenna continuing to operate as an independent business under its existing trade name and business model. Companies can acquire established equipment tracking and asset management technology platforms to expand mixed-fleet visibility capabilities beyond core agricultural equipment lines.
Kubota advanced its autonomy project targeting specialty crop markets, focusing on autonomous solutions for spraying and mowing applications across categories identified by agricultural authorities as specialty crops. Companies can focus autonomous equipment development on specific specialty crop categories to demonstrate safety and cost-saving benefits before broader autonomous platform commercialisation.
Building out a full equipment lineup from scratch takes years, so at least one manufacturer chose instead to team up with an established domestic seeding specialist already trusted by Prairie farmers. In September 2026, CNH Industrial entered into an alliance with Bourgault Industries, a Canadian seeding equipment manufacturer, to supply equipment through its distribution network across the canada agricultural machinery market. Such alliances reflect manufacturers' recognition that partnering with established domestic implement specialists increasingly strengthens product coverage more efficiently than developing comparable equipment internally.
Knowing exactly where every machine is and what condition it's in has become its own competitive edge, prompting at least one manufacturer to buy rather than build that tracking capability. In February 2026, Deere & Company completed its acquisition of Tenna, an equipment tracking and asset management technology company, with the acquired platform continuing to operate independently under its existing business model. Such acquisitions reflect manufacturers' recognition that mixed-fleet tracking technology increasingly extends equipment management value beyond core agricultural machinery sales alone.
Rather than chasing full-farm autonomy right away, one manufacturer is starting narrow, proving out self-driving spraying and mowing on specialty crops first. Starting in January 2026, Kubota continued developing autonomous solutions specifically for specialty crop spraying and mowing applications. Such focused autonomous development reflects manufacturers' recognition that demonstrating safety and cost-saving benefits within narrower specialty crop categories increasingly builds the operational track record needed before broader autonomous platform commercialisation.
A single well-attended trade show can reach more farmers and dealers in a weekend than months of individual outreach, which is presumably why one manufacturer used its latest one to unveil an entire updated lineup at once. In September 2026, AGCO unveiled new tractor and implement products across multiple brand lines at the Farm Progress Show. Such trade show product launches reflect manufacturers' recognition that major industry events increasingly provide efficient platforms for demonstrating updated equipment lineups to farmers and dealers simultaneously.
This Expert Market Research Report titled "Canada Agricultural Machinery Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Tractors
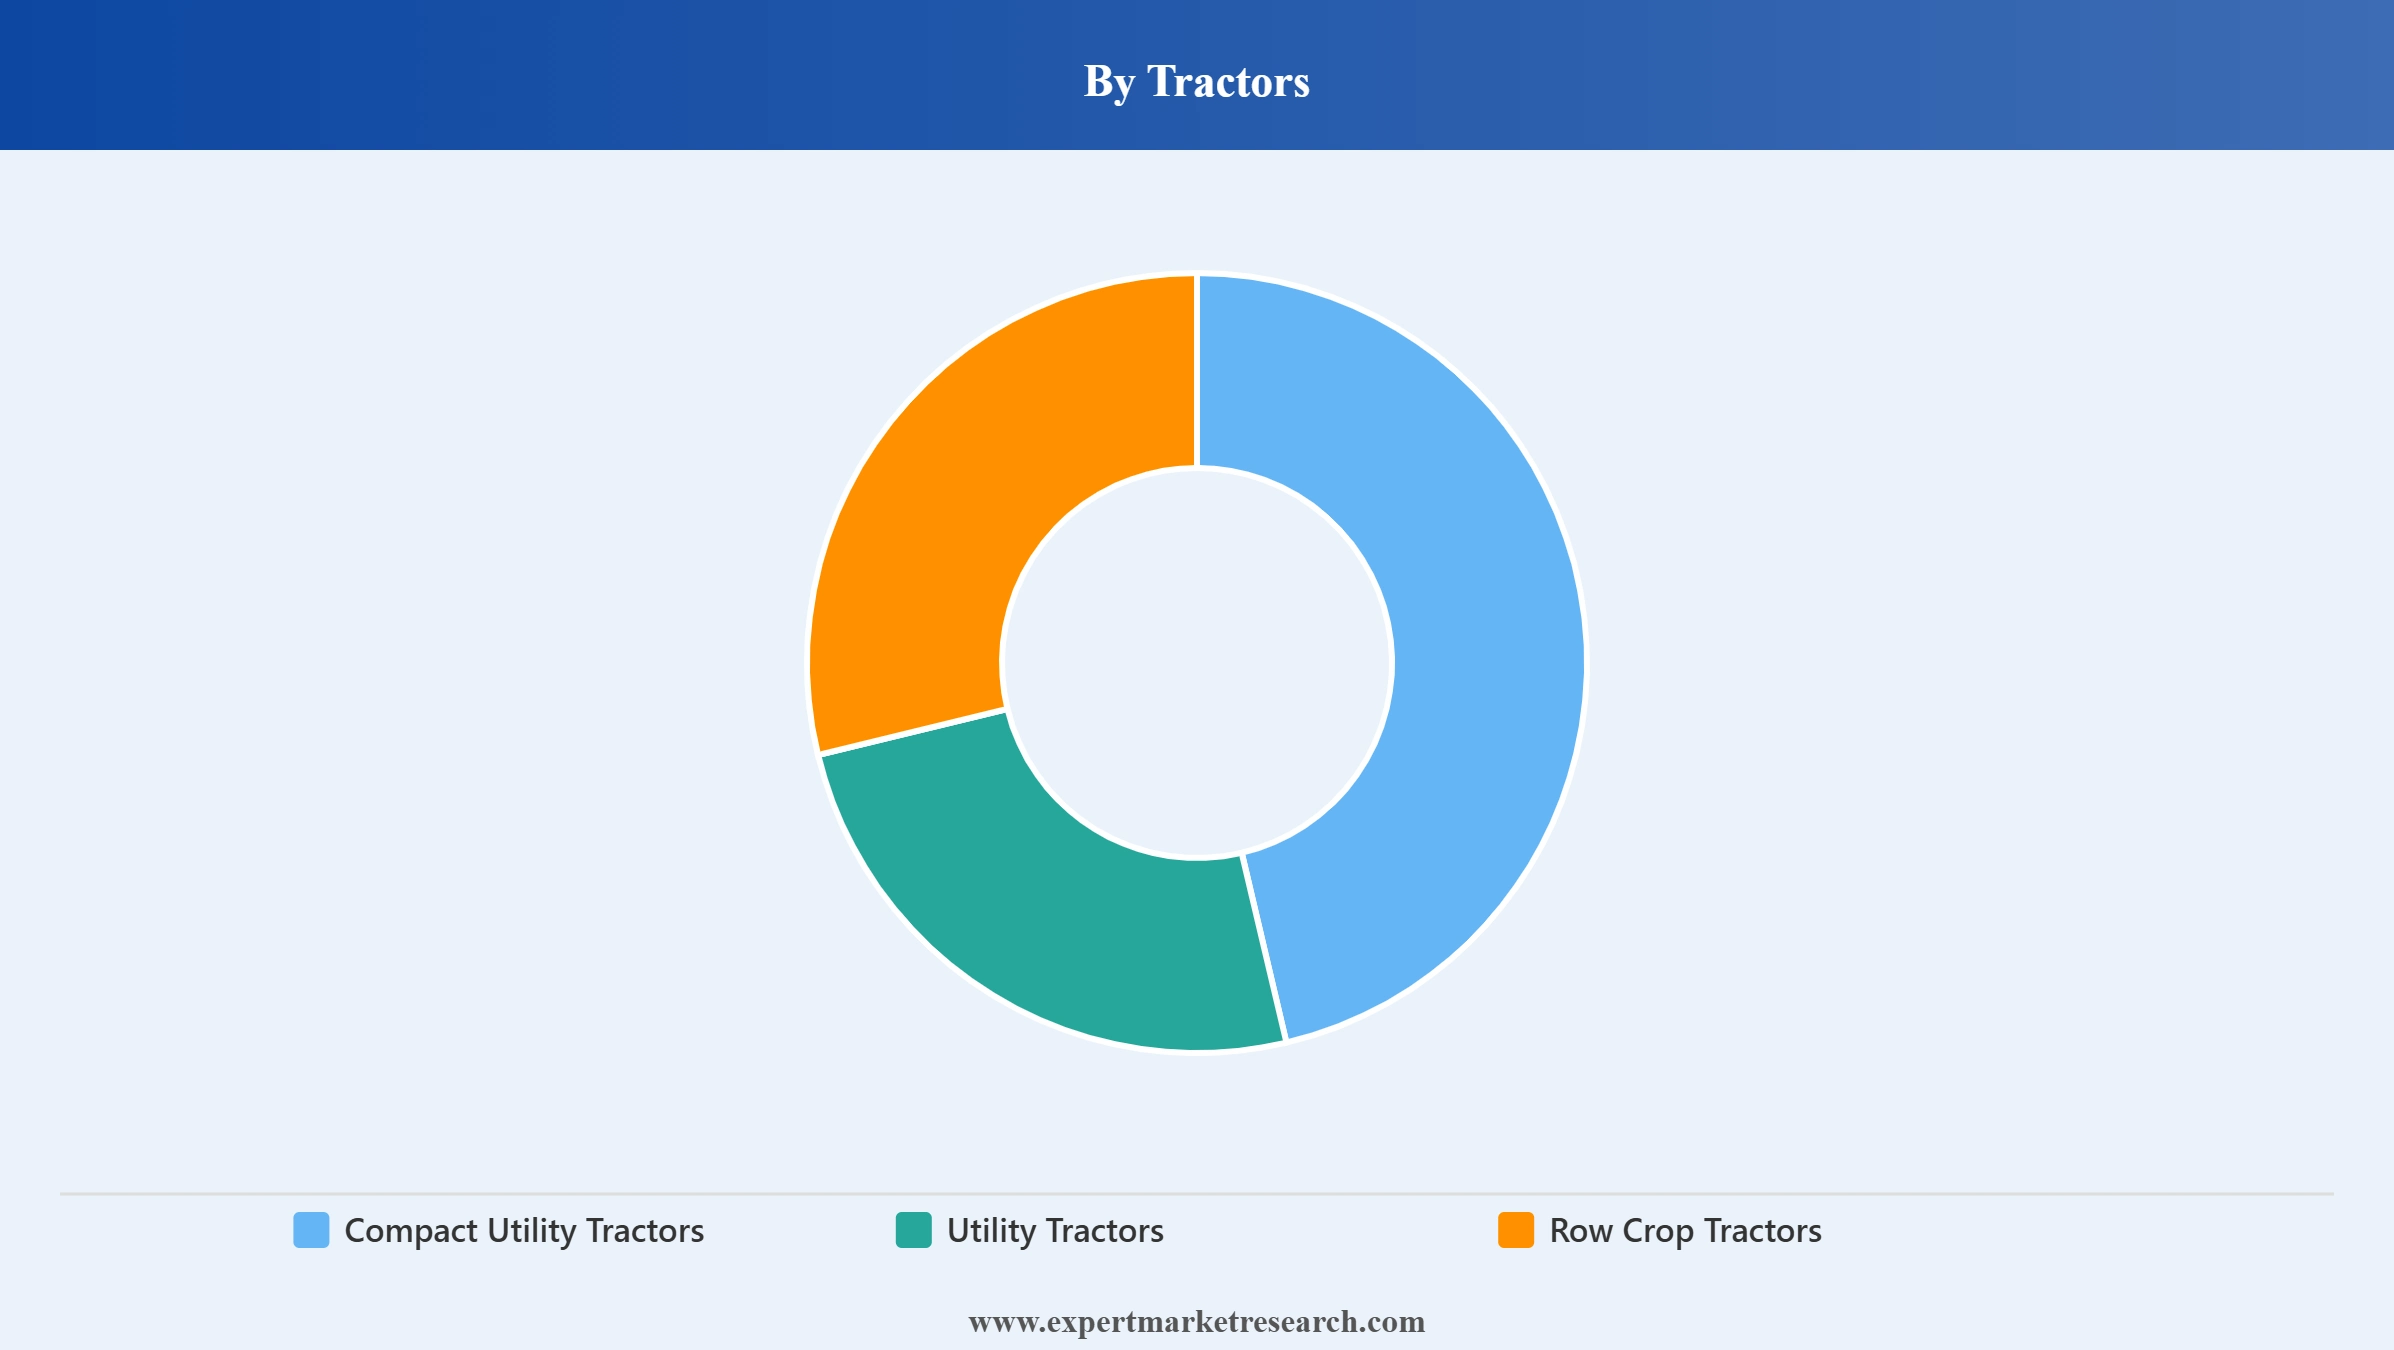
Key Insight: Utility Tractors accounts for the largest share of the canada agricultural machinery market, reflecting its versatility across mid-sized farm operations and diverse task applications. Row Crop Tractors continues to represent substantial demand tied to large-scale grain and oilseed operations, illustrated by AGCO's September 2026 Vario tractor series updates unveiled at the Farm Progress Show, while Compact Utility Tractors serves smaller acreage and specialty farm applications.
Market Breakup by Ploughing and Cultivating Machinery
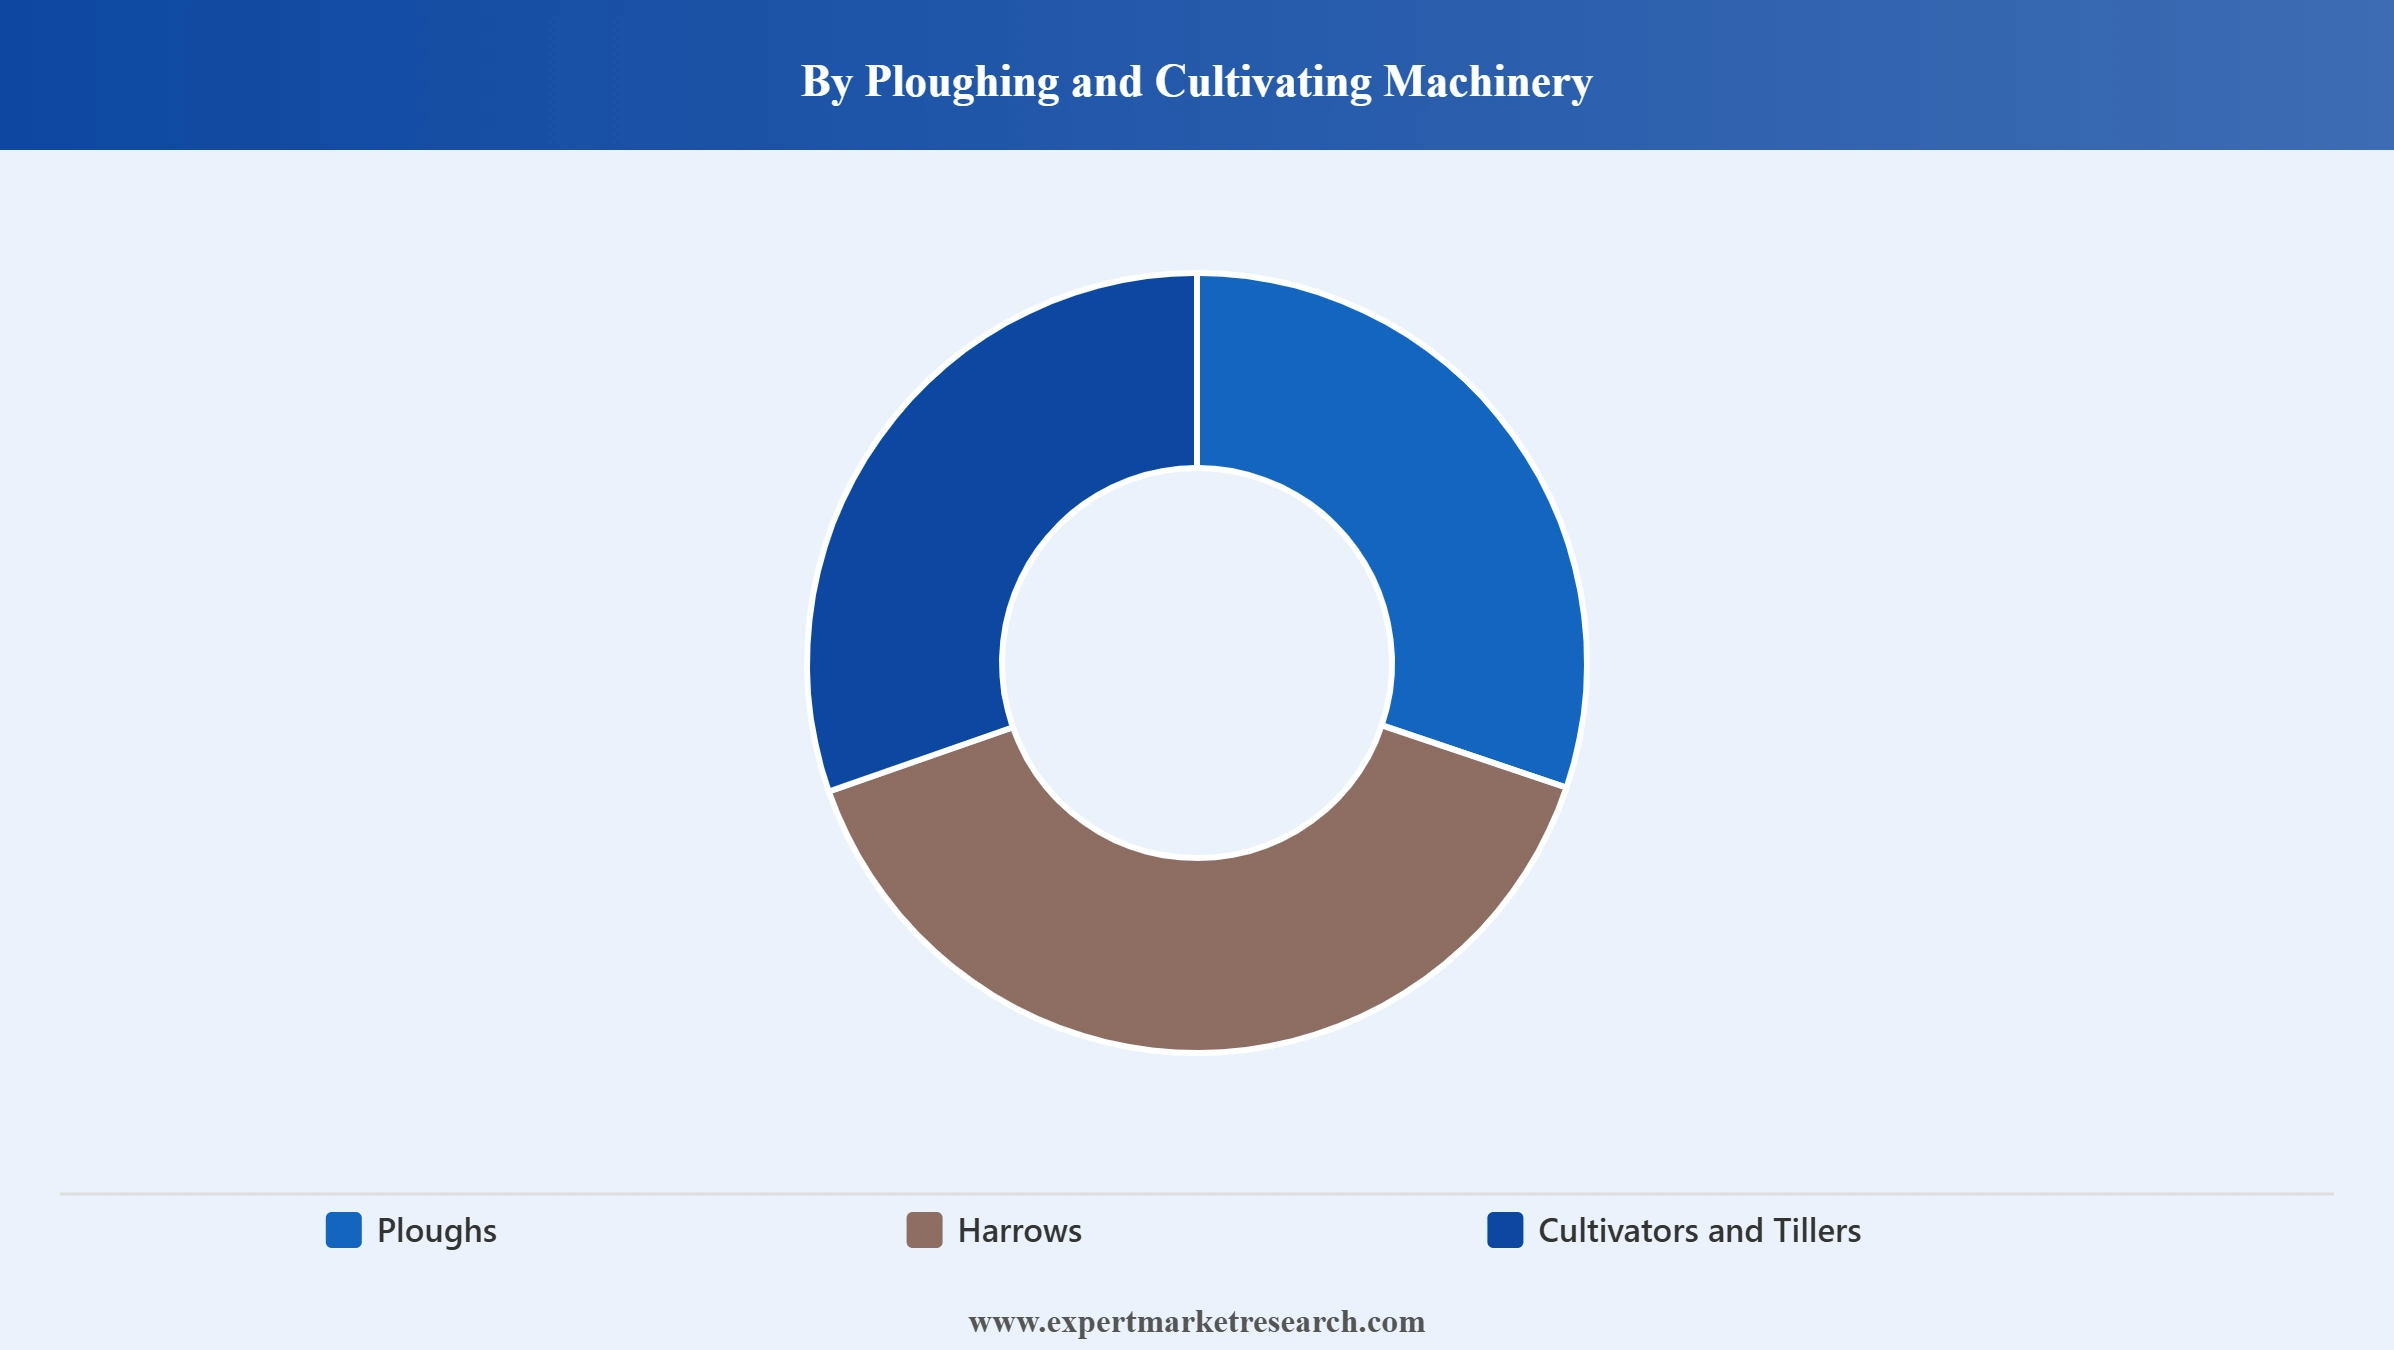
Key Insight: Cultivators and Tillers accounts for the largest share of the canada agricultural machinery market, reflecting sustained demand for soil preparation equipment across large-scale grain operations. Harrows continue to serve secondary tillage and residue management requirements. Ploughs handle primary tillage and deep soil inversion across varying field conditions, with CNH Industrial's September 2026 Bourgault Industries alliance covering seeding and ploughing and cultivating machinery alike. Others covers specialised soil preparation implements including rollers and packers.
Market Breakup by Planting Machinery
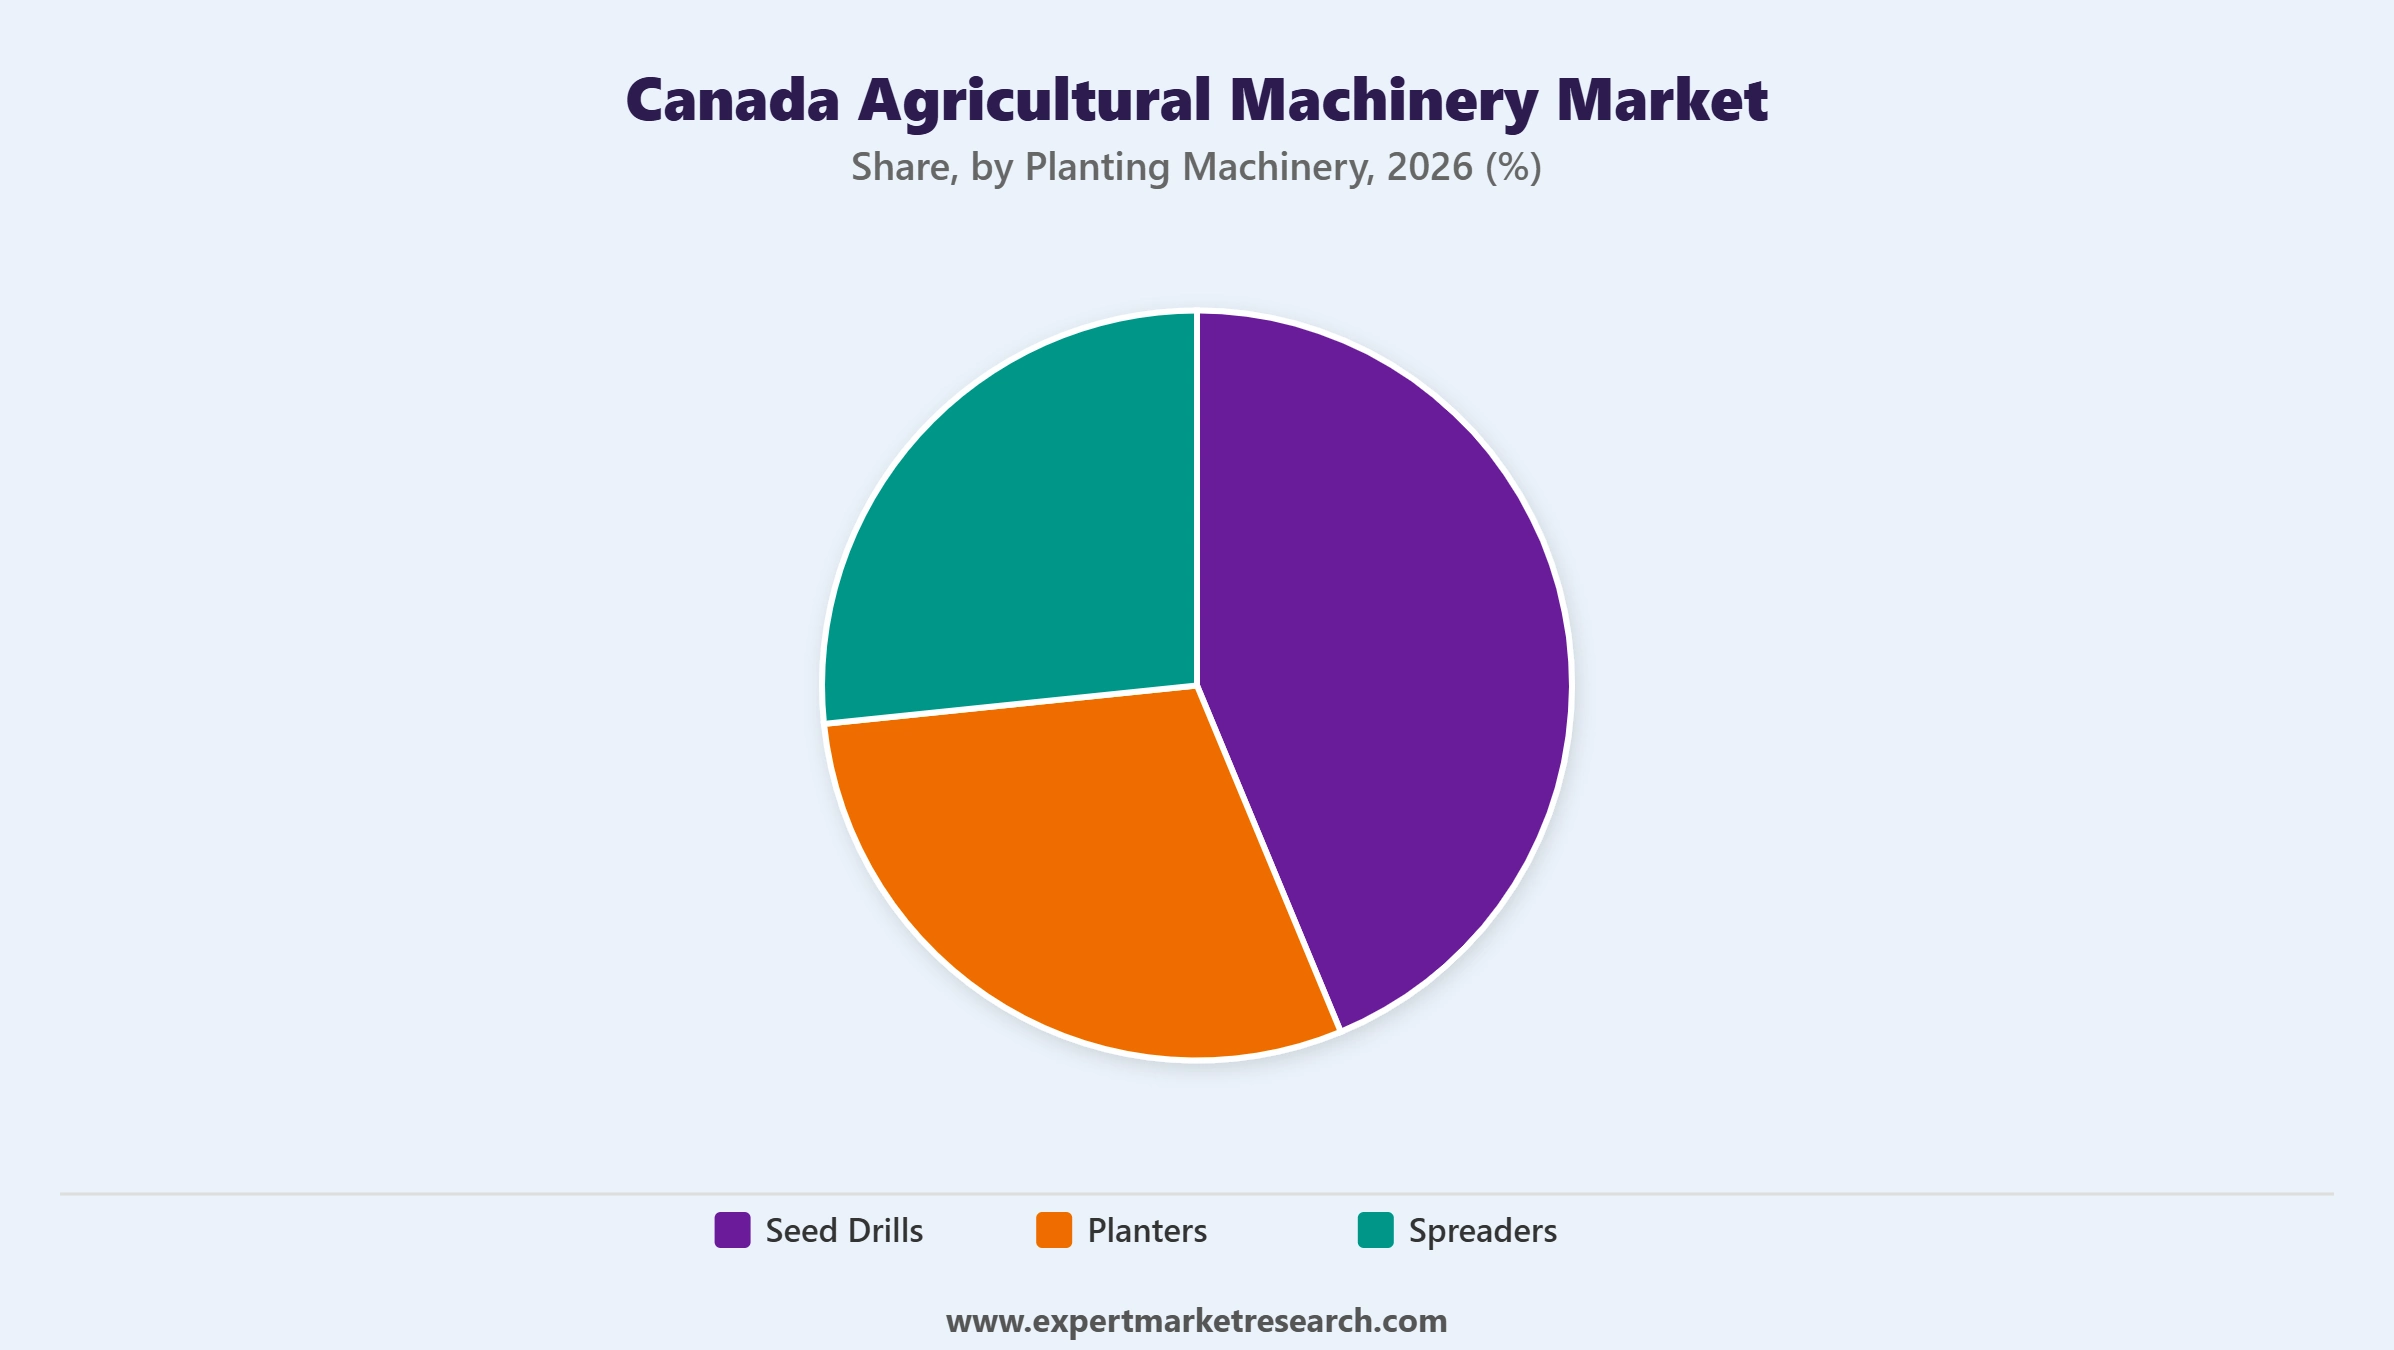
Key Insight: Seed Drills accounts for the largest share of the canada agricultural machinery market, reflecting their widespread use in Prairie grain and oilseed seeding operations. Planters continues to represent substantial demand tied to row crop applications, illustrated by CNH Industrial's September 2026 alliance with a Canadian seeding equipment manufacturer, while Spreaders serves fertiliser and input application requirements, and Others covers specialised planting attachments including precision air-seeders.
Market Breakup by Harvesting Machinery
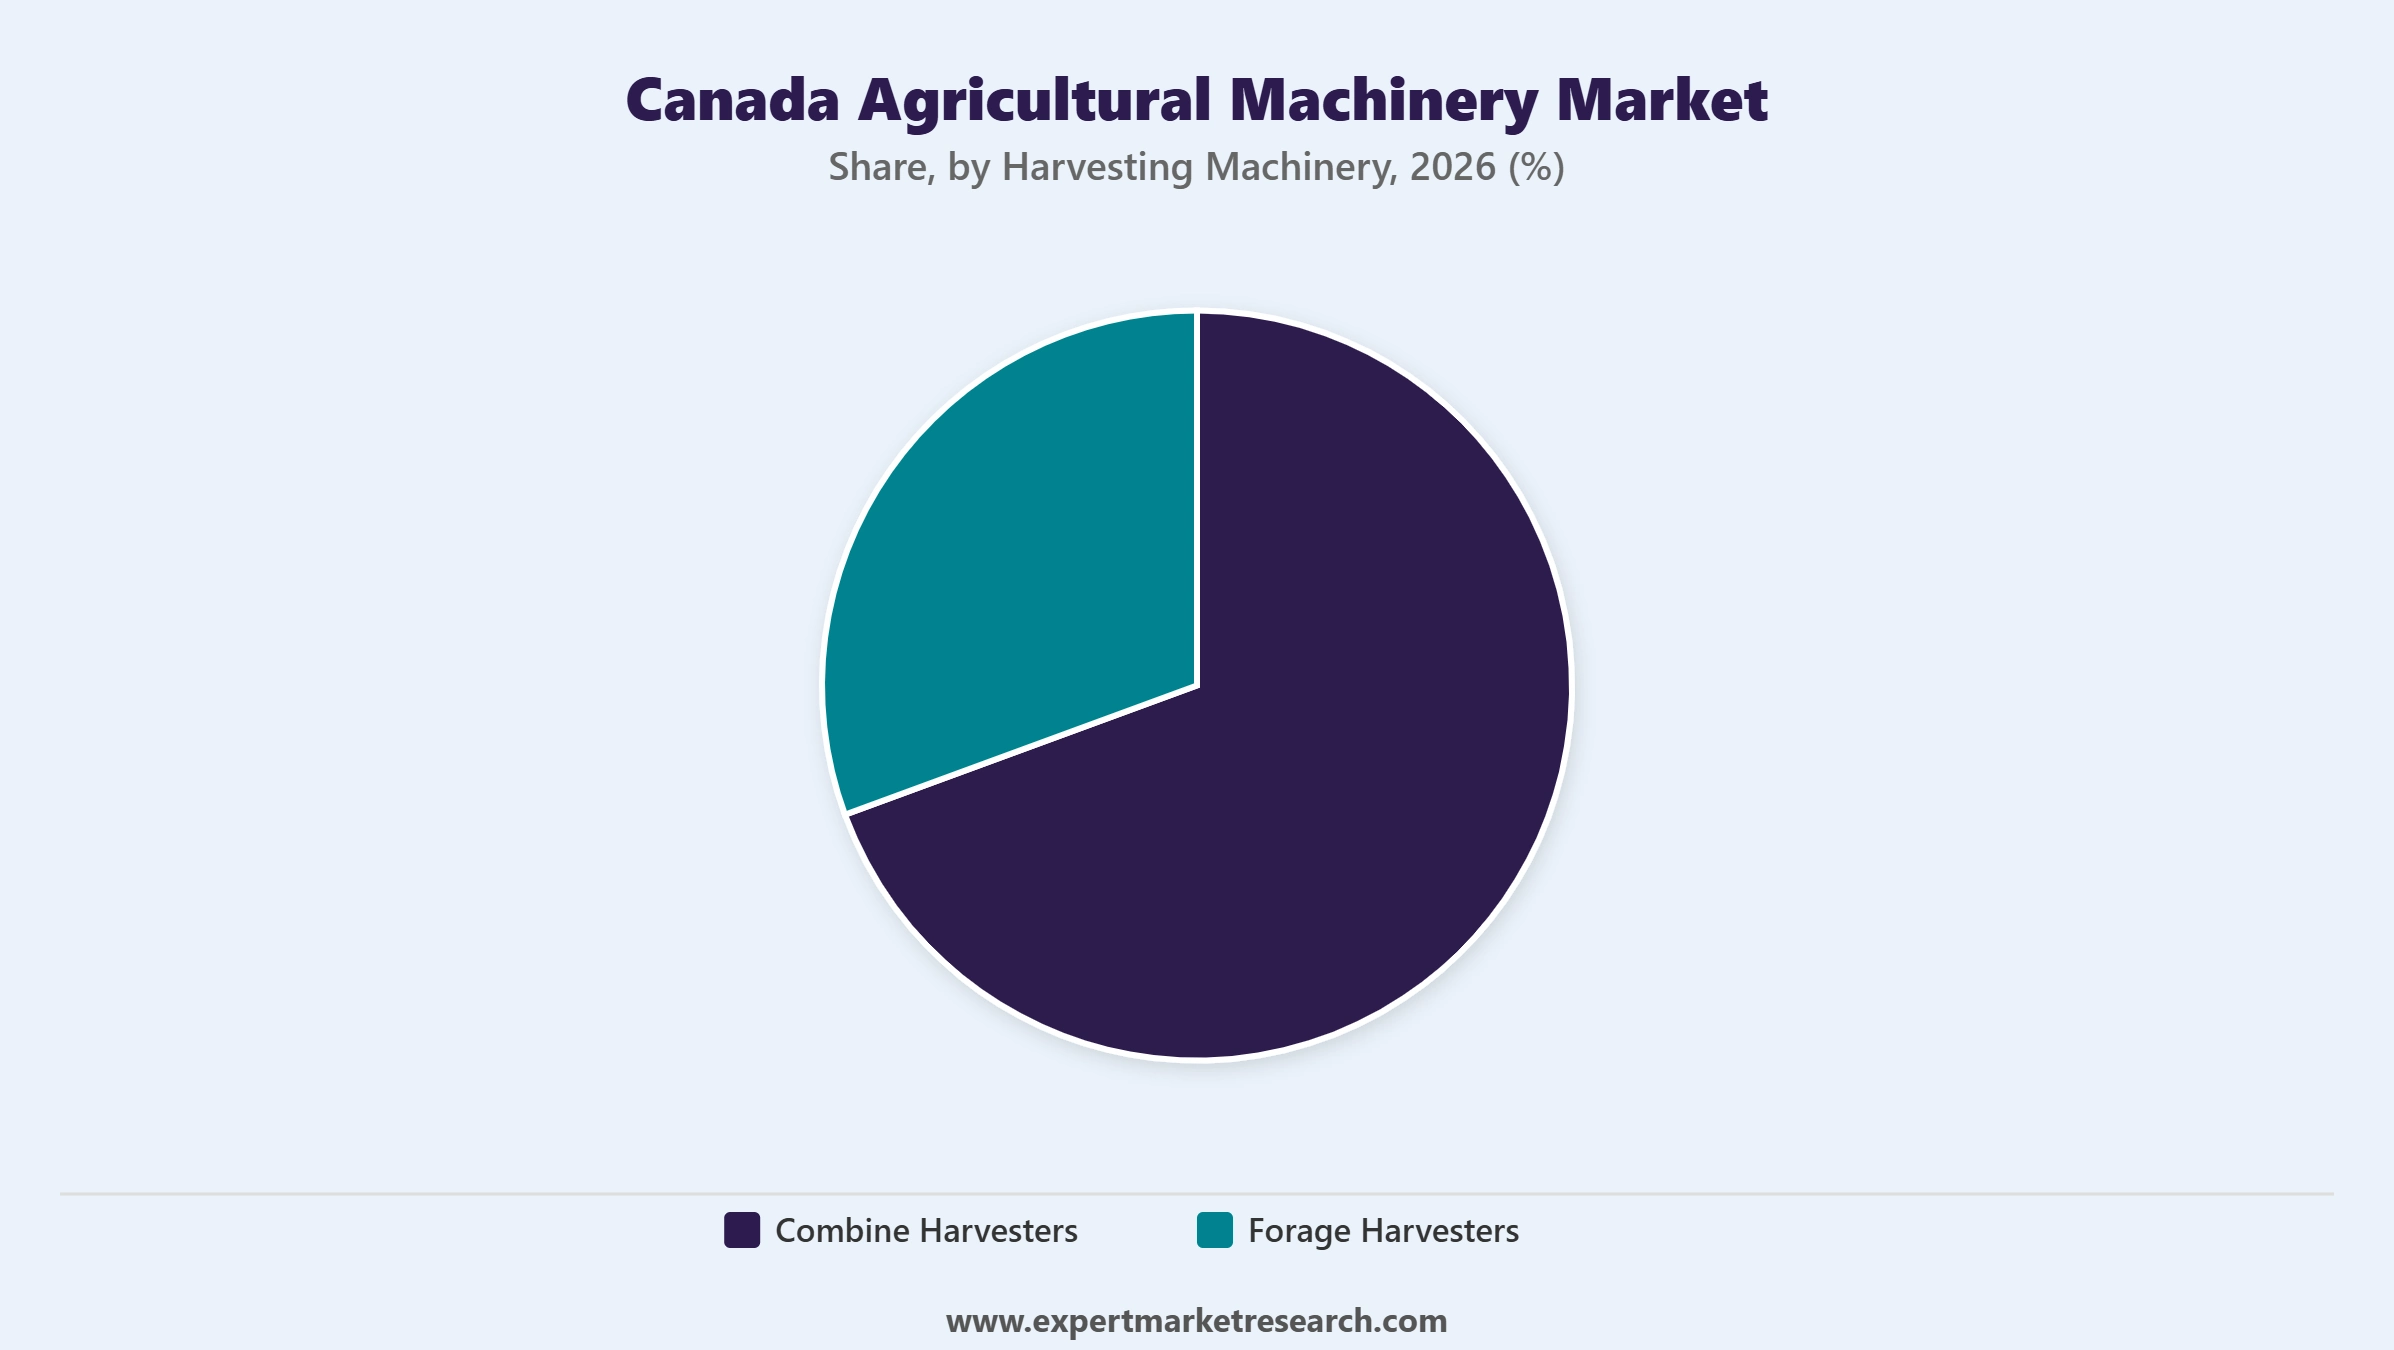
Key Insight: Combine Harvesters accounts for the largest share of the canada agricultural machinery market, reflecting sustained demand for grain and oilseed harvesting across large-scale Prairie operations. Forage Harvesters continues to represent demand tied to livestock feed production and hay operations, while AGCO's September 2026 preview of its IDEAL combine ahead of the Fendt Harvest Tour illustrated continued product investment in this category. Others encompasses specialised harvesting attachments including root and tuber harvesters.
Market Breakup by Haying and Forage Machinery
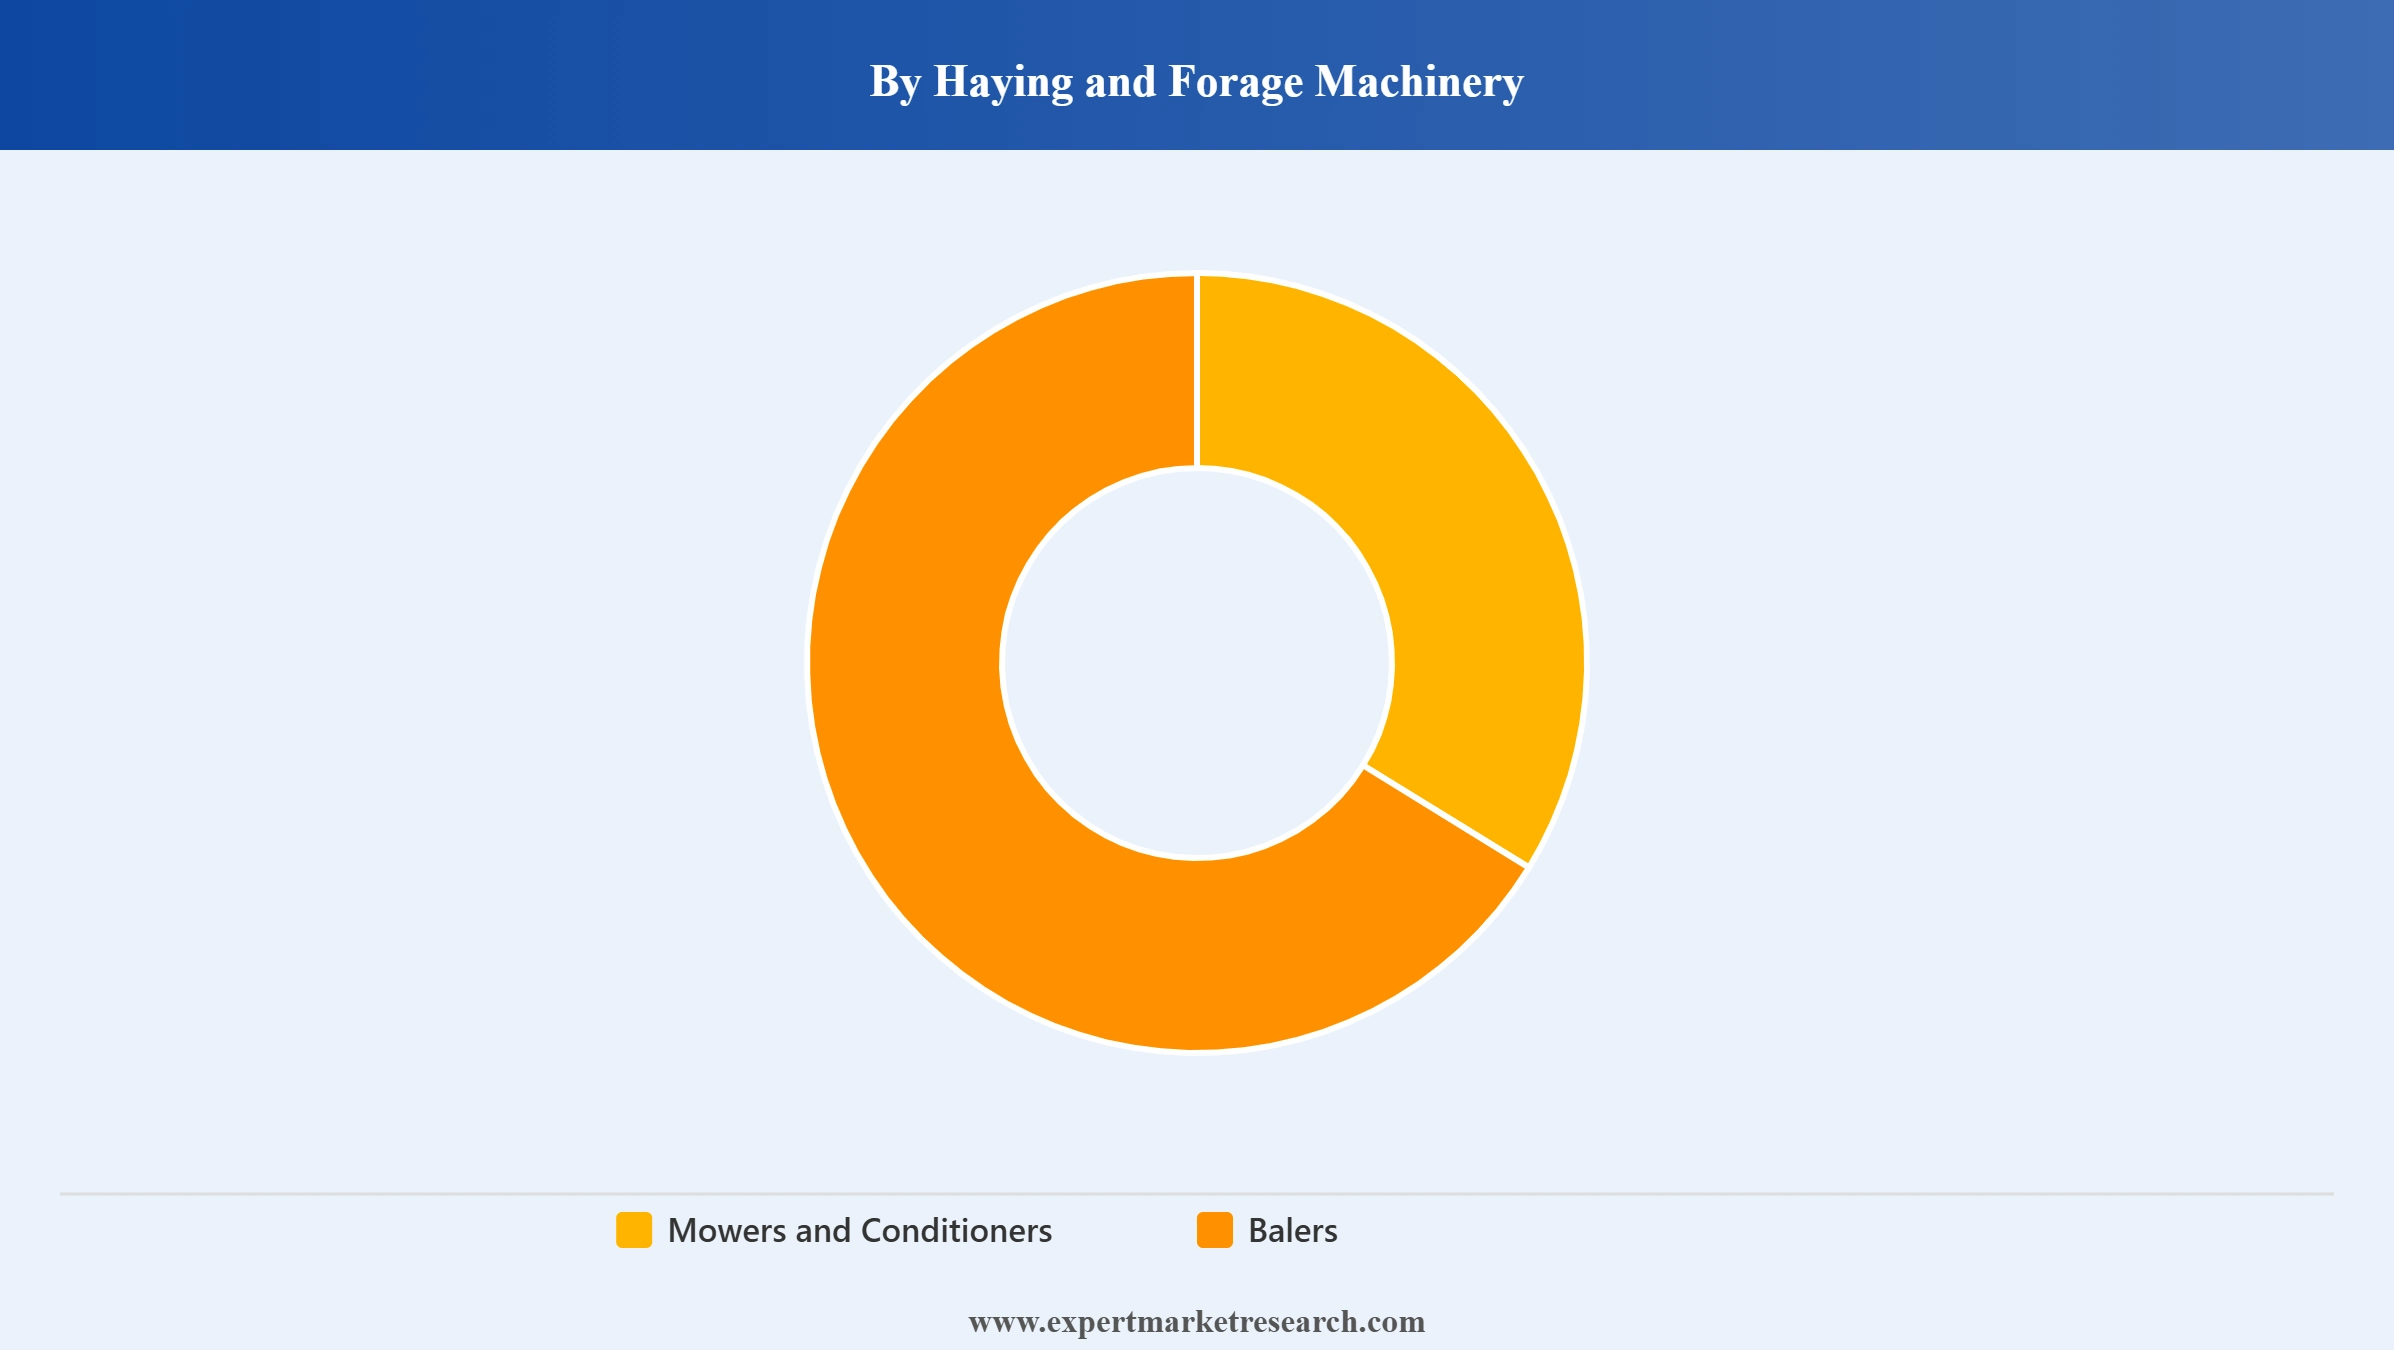
Key Insight: Balers accounts for the largest share of the canada agricultural machinery market, reflecting sustained demand for hay and forage packaging across livestock operations. Mowers and Conditioners continues to represent complementary demand tied to forage cutting and conditioning ahead of baling, illustrated by AGCO's September 2026 unveiling of new Massey Ferguson hay equipment at the Farm Progress Show. Others covers specialised forage handling equipment including rakes and tedders.
Market Breakup by Irrigation Machinery
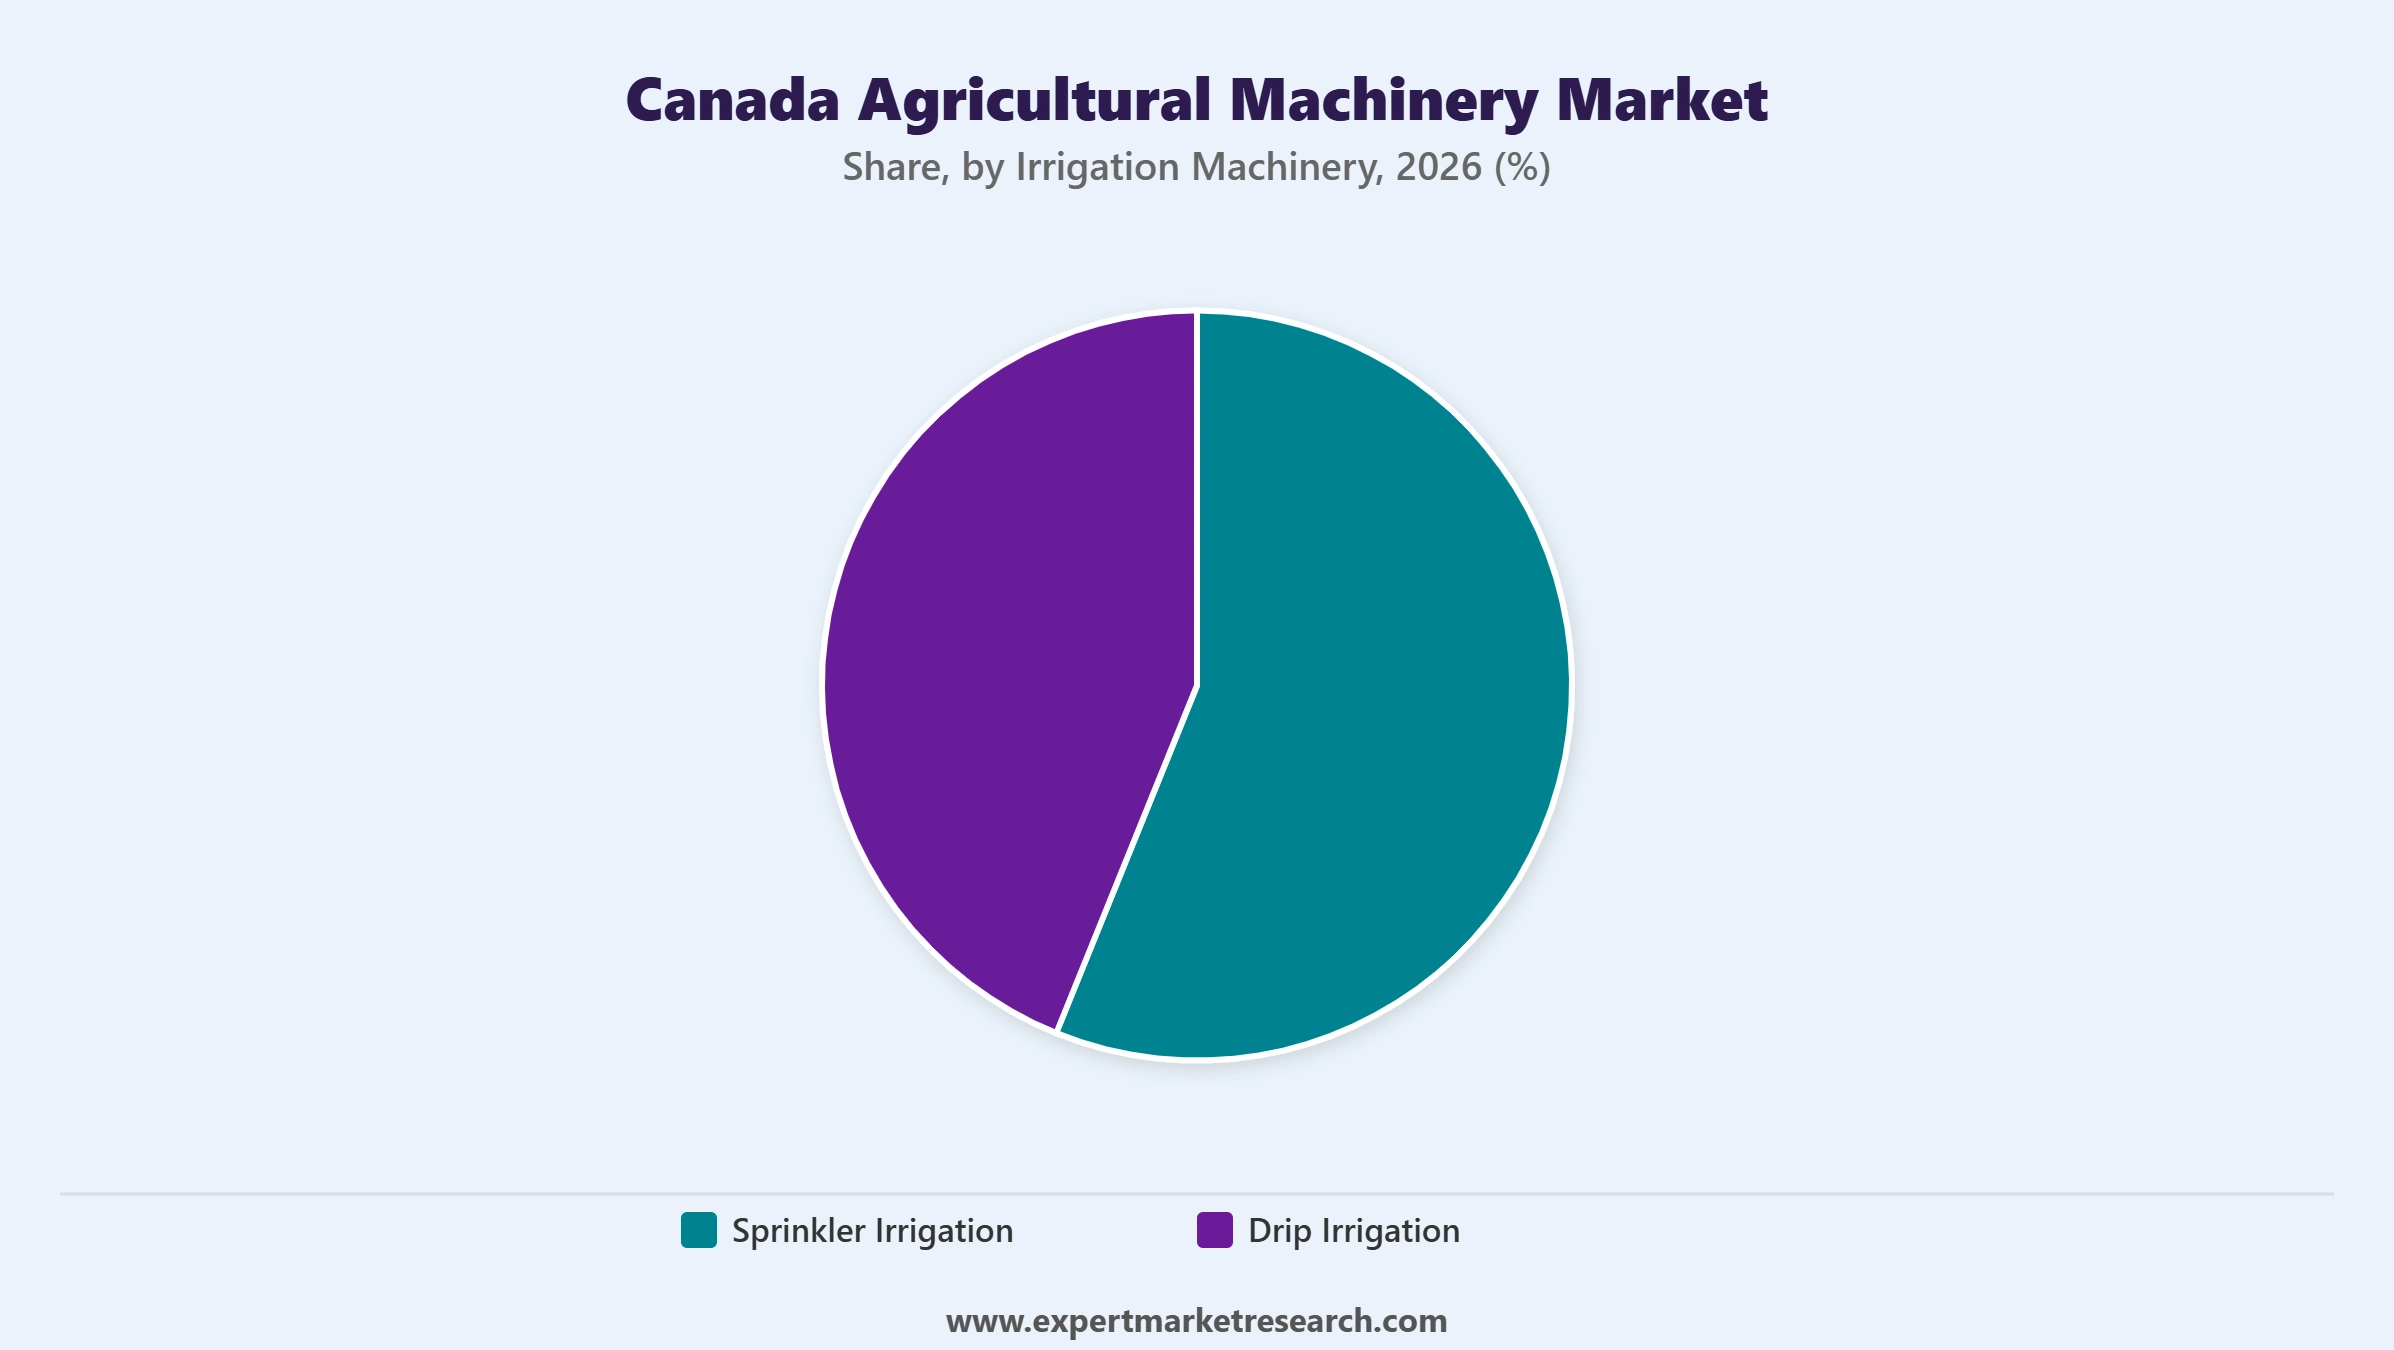
Key Insight: Sprinkler Irrigation accounts for the largest share of the canada agricultural machinery market, reflecting its established suitability for large-scale field crop irrigation across Prairie operations. Drip Irrigation continues to represent growing demand tied to water-efficient irrigation for higher-value horticultural applications, supported by July 2026 federal digital agriculture investment through Manitoba's EMILI initiative. Others includes emerging precision irrigation technologies such as variable-rate centre-pivot systems.
Market Breakup by Application
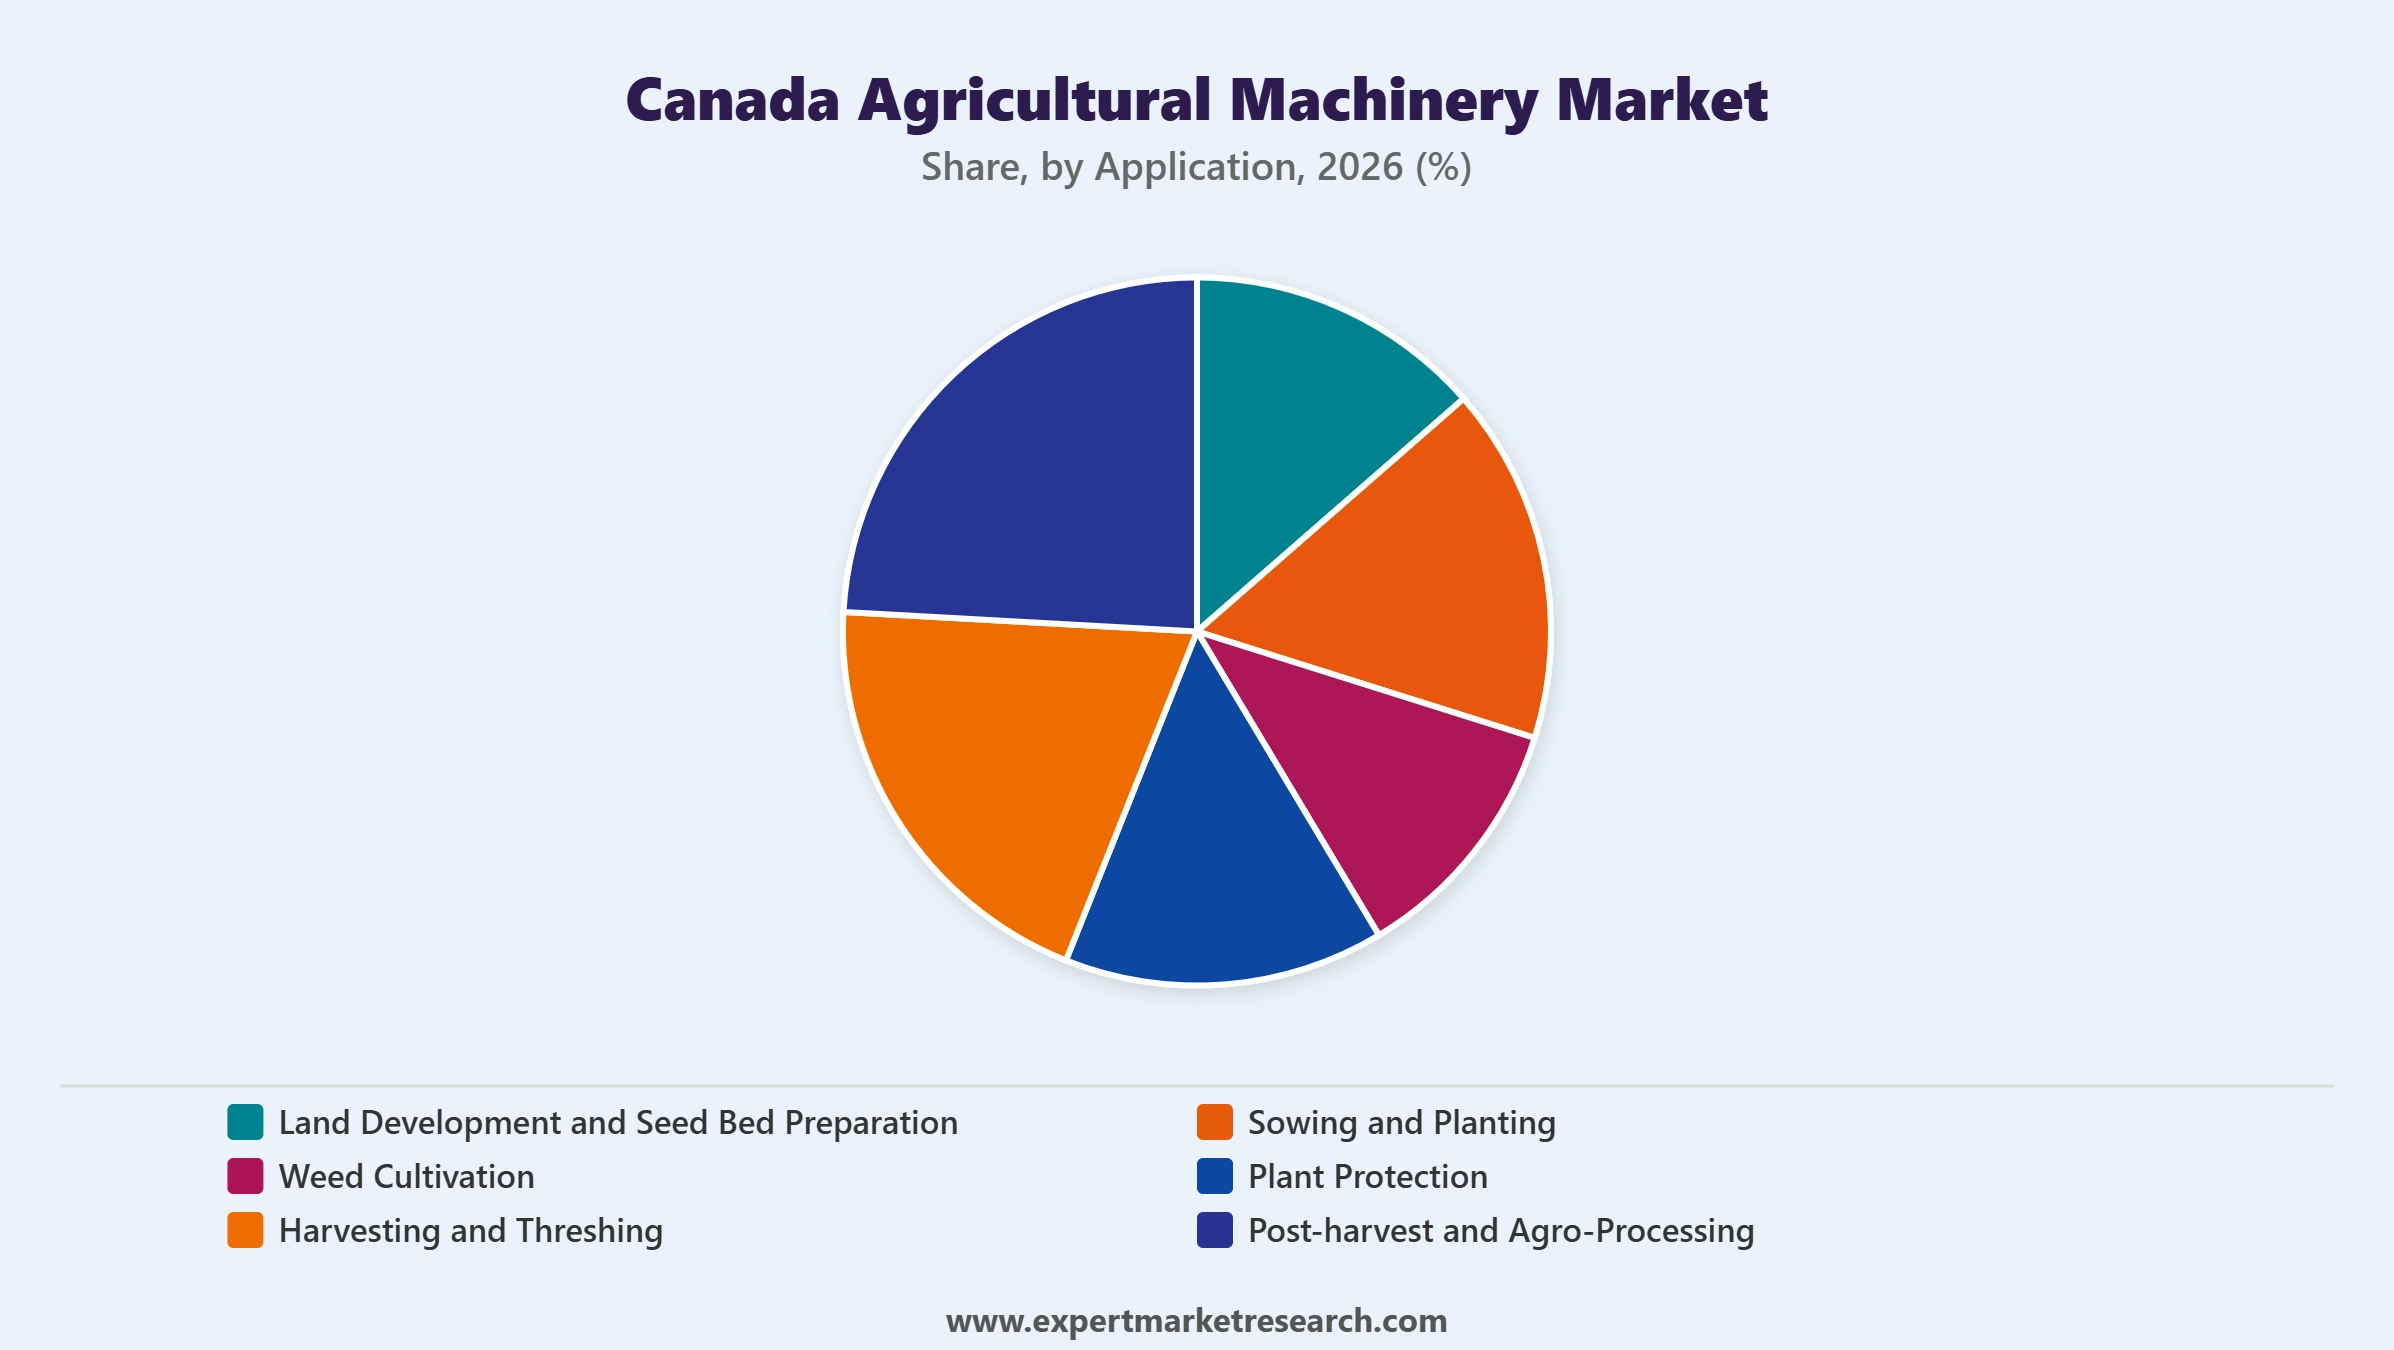
Key Insight: Harvesting and Threshing accounts for the largest share of the canada agricultural machinery market, reflecting sustained demand for combine and forage harvesting equipment across large-scale grain operations. Plant Protection continues to represent growing demand, illustrated by Kubota's January 2026 autonomous spraying project targeting specialty crop applications, Land Development and Seed Bed Preparation supports initial field preparation ahead of planting. Sowing and Planting covers seed placement operations across the growing season. Weed Cultivation addresses in-season crop protection through mechanical and chemical weed management. Post-harvest and Agro-Processing serves grain drying, storage, and initial processing stages following harvest.
Market Breakup by Region
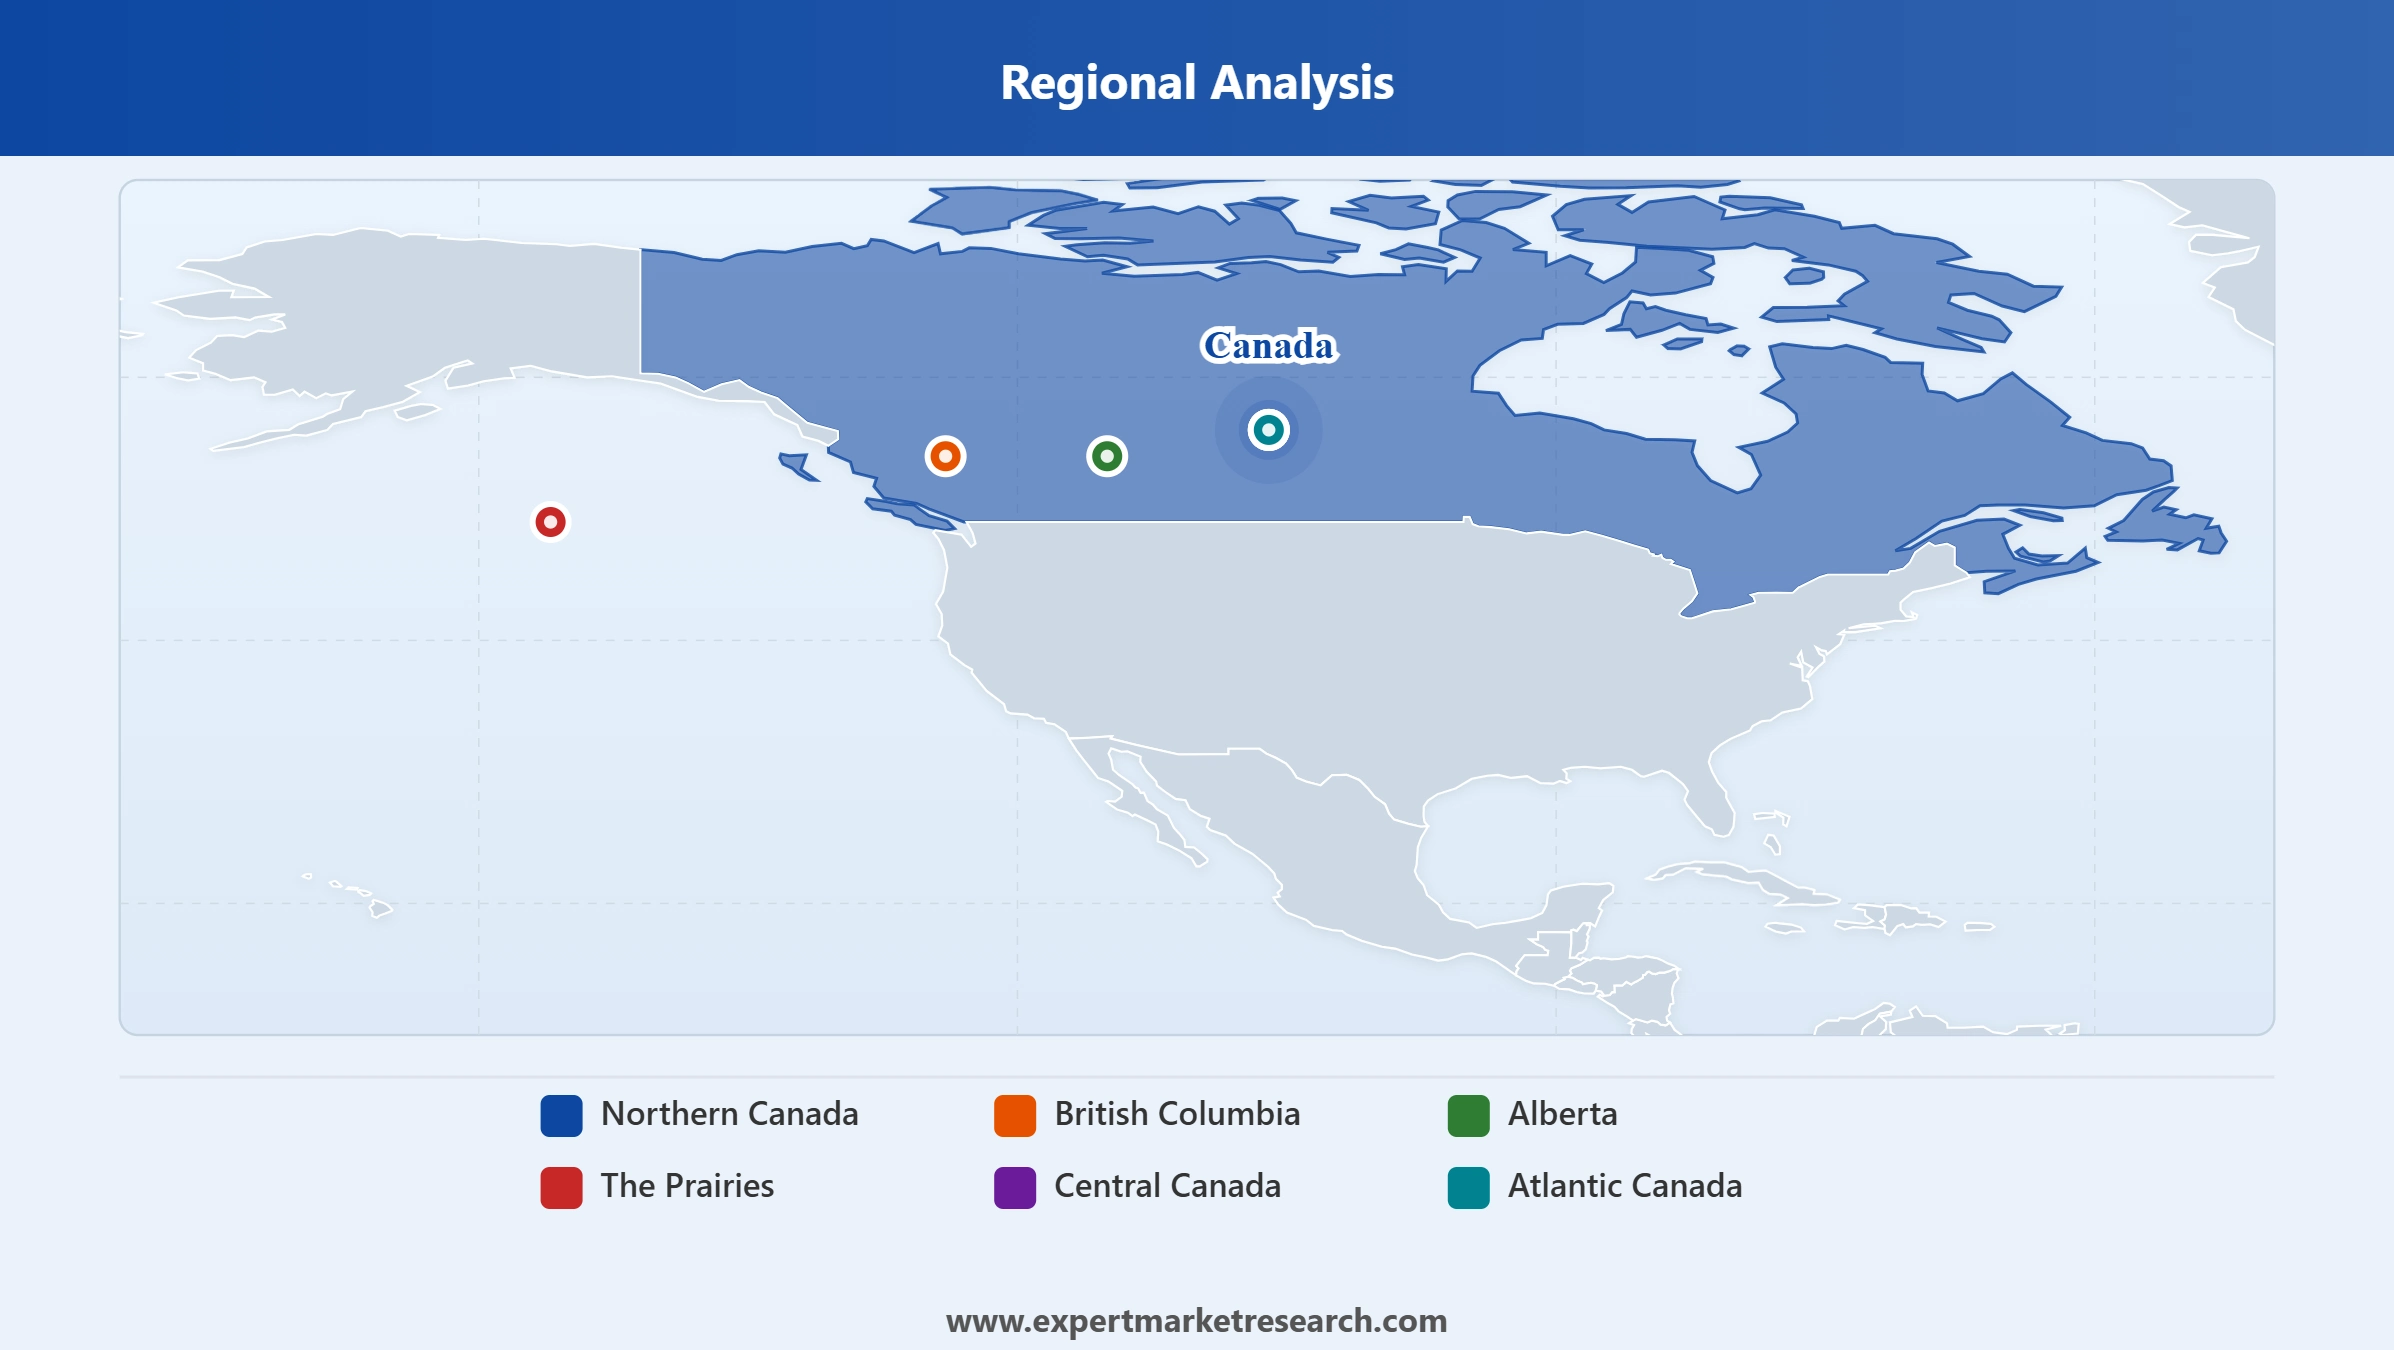
Key Insight: The Prairies accounts for the largest share of the canada agricultural machinery market, supported by concentrated grain, oilseed, and pulse production across Saskatchewan, Alberta, and Manitoba. Alberta is emerging as a key growth region as large-scale grain operations continue to expand equipment fleets. British Columbia serves diversified horticultural and specialty crop operations across its varied terrain. Central Canada supports mixed grain and dairy farming operations across Ontario and Quebec. Atlantic Canada maintains a smaller equipment base tied to potato and mixed farming operations. Northern Canada represents a niche market constrained by short growing seasons and limited arable land, with Deere & Company's February 2026 Tenna acquisition supporting fleet visibility across dealer networks nationwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By tractors, utility tractors lead the market while row crop tractors grow fastest given large-scale grain operations
Utility Tractors continue to account for the largest share of the market, reflecting their versatility across mid-sized farm operations and diverse task applications. Utility tractors retain their lead as dealers keep returning to proven model lineups refined across successive equipment replacement cycles, a lineup AGCO refreshed with September 2026 Vario series updates at the Farm Progress Show.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Row Crop Tractors is growing at a fast pace across the canada agricultural machinery market as large-scale grain and oilseed operations continue to expand equipment fleets. In February 2026, Deere & Company's acquisition of Tenna expanded equipment tracking capabilities relevant to large, multi-tractor fleet operations.
By harvesting machinery, combine harvesters lead the market while combine harvesters continue strengthening its position given sustained grain production
Combine Harvesters continue to account for the largest share of the market, reflecting sustained demand for grain and oilseed harvesting across large-scale Prairie operations. Farmers rarely deviate from established combine harvester sourcing, whose track record has held up across successive harvest seasons, reinforced by AGCO's September 2026 preview of its IDEAL combine ahead of the Fendt Harvest Tour.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Forage Harvesters continues to represent demand across the canada agricultural machinery market tied to livestock feed production and hay operations across mixed farming regions, an area AGCO's September 2026 Massey Ferguson hay equipment lineup targeted directly.
By application, harvesting and threshing leads the market while plant protection grows fastest given rising autonomous spraying adoption
Harvesting and Threshing continues to account for the largest share of the market, reflecting sustained demand for combine and forage harvesting equipment across large-scale grain operations, underscored by AGCO's September 2026 IDEAL combine preview. Switching costs keep farmers anchored to harvesting and threshing equipment sourcing built up over successive harvest cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Plant Protection is growing at a fast pace across the canada agricultural machinery market as autonomous spraying adoption continues to expand. In January 2026, Kubota advanced its autonomous tractor project specifically targeting specialty crop spraying applications.
By ploughing and cultivating machinery, cultivators and tillers lead the market while cultivators and tillers continue strengthening its position given sustained soil preparation demand
Cultivators and Tillers continue to account for the largest share of the market, reflecting sustained demand for soil preparation equipment across large-scale grain operations, an area CNH Industrial's September 2026 Bourgault alliance also touches through its combined seeding and tillage coverage. Few farmers see reason to move away from cultivator and tiller sourcing, given how dependable it has proven across successive planting seasons.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Harrows and Ploughs continue to represent complementary demand across the canada agricultural machinery market tied to distinct soil conditioning and land preparation requirements across varying field conditions.
By planting machinery, seed drills lead the market while planters grow fastest given rising row crop demand
Seed Drills continue to account for the largest share of the market, reflecting their widespread use in Prairie grain and oilseed seeding operations, a category CNH Industrial's September 2026 Bourgault alliance directly serves. Seed drills' dominance persists as farmers favour the predictability of proven equipment sourcing over successive seeding seasons.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Planters is growing at a fast pace across the canada agricultural machinery market as row crop applications continue to expand. In September 2026, CNH Industrial's alliance with Bourgault Industries strengthened distribution of Canadian-manufactured seeding equipment relevant to this segment.
By haying and forage machinery, balers lead the market while balers continue strengthening its position given sustained livestock feed demand
Balers continue to account for the largest share of the market, reflecting sustained demand for hay and forage packaging across livestock operations, a category AGCO's September 2026 Massey Ferguson hay equipment lineup expanded into. Long-standing equipment sourcing arrangements keep farmers tied to established balers across successive haying seasons, sustaining the segment's lead.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Mowers and Conditioners continue to represent complementary demand across the canada agricultural machinery market tied to forage cutting and conditioning ahead of baling.
By irrigation machinery, sprinkler irrigation leads the market while drip irrigation grows fastest given rising water-efficiency demand
Sprinkler Irrigation continues to account for the largest share of the market, reflecting its established suitability for large-scale field crop irrigation across Prairie operations, supported by July 2026 federal digital agriculture investment through Manitoba's EMILI initiative. Farmers show little appetite to shift away from sprinkler irrigation, whose equipment sourcing advantages have compounded across successive growing seasons.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Drip Irrigation is growing at a fast pace across the canada agricultural machinery market as water-efficient irrigation demand increases for higher-value horticultural applications, an area supported by July 2026 federal EMILI digital agriculture funding in Manitoba.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The Prairies commands the largest share of the market through its concentrated grain and oilseed production
The Prairies holds the largest share of the Canada agricultural machinery market, supported by concentrated grain, oilseed, and pulse production across Saskatchewan, Alberta, and Manitoba, which together account for the bulk of the country's crop output. Equipment and parts inventory keeps growing region-wide as dealers respond to large-scale farm operations' steady appetite for machinery.
Alberta is emerging as a key growth region as large-scale grain operations continue to expand equipment fleets. CNH Industrial's September 2026 Bourgault alliance and Deere's February 2026 Tenna acquisition underscored sustained industry investment in Canadian-specific equipment coverage extending well beyond The Prairies' traditional market concentration across the wider canada agricultural machinery market.
The industry is moderately consolidated, with canada agricultural machinery market companies ranging from diversified global equipment manufacturers spanning multiple machinery categories to specialist implement producers competing across tractors, application, and regional segments. Established players operate across the full agricultural machinery value chain, from tractor and implement engineering through complete equipment production, dealer distribution, and aftermarket parts and service support.
Competitive dynamics among canada agricultural machinery players are increasingly shaped by the pace of technology acquisitions expanding equipment management capabilities, the scale of alliances with domestic Canadian implement specialists, and autonomous equipment development for specialty applications. Manufacturers are investing in connected fleet tracking technology, regional distribution partnerships, and focused autonomous platform development to differentiate their offering and secure long-term dealer and farmer customer relationships.
Founded in 1837 and headquartered in Moline, Illinois, United States, Deere & Company manufactures tractors, combines, and agricultural implements under its John Deere brand, serving farm operations across Canada and internationally. In February 2026, the company completed its acquisition of Tenna, an equipment tracking and asset management technology company. Deere's transition toward upgradeable, software-defined equipment platforms differentiates its offering from competitors relying primarily on traditional hardware-focused product lines.
Founded in 1990 and headquartered in Duluth, Georgia, United States, AGCO manufactures tractors and implements under its Fendt, Massey Ferguson, and PTx brands, serving global agricultural markets including Canada. In September 2026, the company unveiled new products across its Fendt and Massey Ferguson lines at a major North American farm equipment show. AGCO's disciplined production alignment with retail demand and expanding North American high-horsepower market share differentiate its offering from competitors managing less coordinated dealer inventory strategies.
Founded in 2013 and headquartered in Basildon, United Kingdom, CNH Industrial manufactures tractors and implements under its Case IH, New Holland, and STEYR brands, with a strong strategic focus on precision agriculture and autonomy-led equipment platforms. In September 2026, the company formed a strategic alliance with Bourgault Industries, a Canadian seeding equipment manufacturer. CNH Industrial's focus on AI-enabled machinery and Canadian-specific implement partnerships differentiate its offering from competitors with less-developed autonomous and regional distribution capabilities.
Founded in 1913 and headquartered in Harsewinkel, Germany, CLAAS manufactures combine harvesters, forage harvesters, and tractors serving European and North American agricultural markets including Canada. The company maintains a strong European engineering heritage with growing North American market ambitions. CLAAS's specialised harvesting equipment engineering expertise differentiates its offering from more diversified, full-line competitors.
Other key players in the Canada agricultural machinery market include Kubota Corporation, Caterpillar, Inc., SDF S.p.A (Deutz-Fahr), Yanmar Holdings Co., Ltd., KUHN Group, Inc., and Mahindra & Mahindra Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Canada agricultural machinery market trends 2026 report. Discover regional growth patterns, tractors and application trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 8.36 Billion.
The market is projected to grow at a CAGR of 7.40% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach a value of around USD 17.07 Billion by 2035.
Forming strategic alliances with domestic Canadian implement specialists to strengthen regional product coverage, acquiring equipment management technology platforms to expand mixed-fleet visibility, and advancing autonomous equipment projects focused on specialty crop applications.
The key trends aiding the market expansion include increase in demand for higher horsepower machines, threat of import disruptions, and shortage of specialised farm labour.
The major regions in the market are Northern Canada, British Columbia, Alberta, the Prairies, Central Canada, and Atlantic Canada.
The major applications of agricultural machinery include land development and seed bed preparation, sowing and planting, weed cultivation, plant protection, harvesting and threshing, and post-harvest and agro-processing.
The key players in the market include Deere & Company, AGCO Corporation, CNH Industrial NV, CLAAS KGaA mbH, Kubota Corporation, Caterpillar, Inc., SDF S.p.A (Deutz-Fahr), Yanmar Holdings Co., Ltd., KUHN Group, Inc., and Mahindra & Mahindra Ltd., among others.
Manufacturers face persistent shortages of specialised farm labour and service technicians, threat of import disruptions affecting equipment and parts supply chains, and the challenge of scaling autonomous equipment solutions across diverse farm sizes and crop types.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Tractors |
|
| Breakup by Ploughing and Cultivating Machinery |
|
| Breakup by Planting Machinery |
|
| Breakup by Harvesting Machinery |
|
| Breakup by Haying and Forage Machinery |
|
| Breakup by Irrigation Machinery |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




