

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
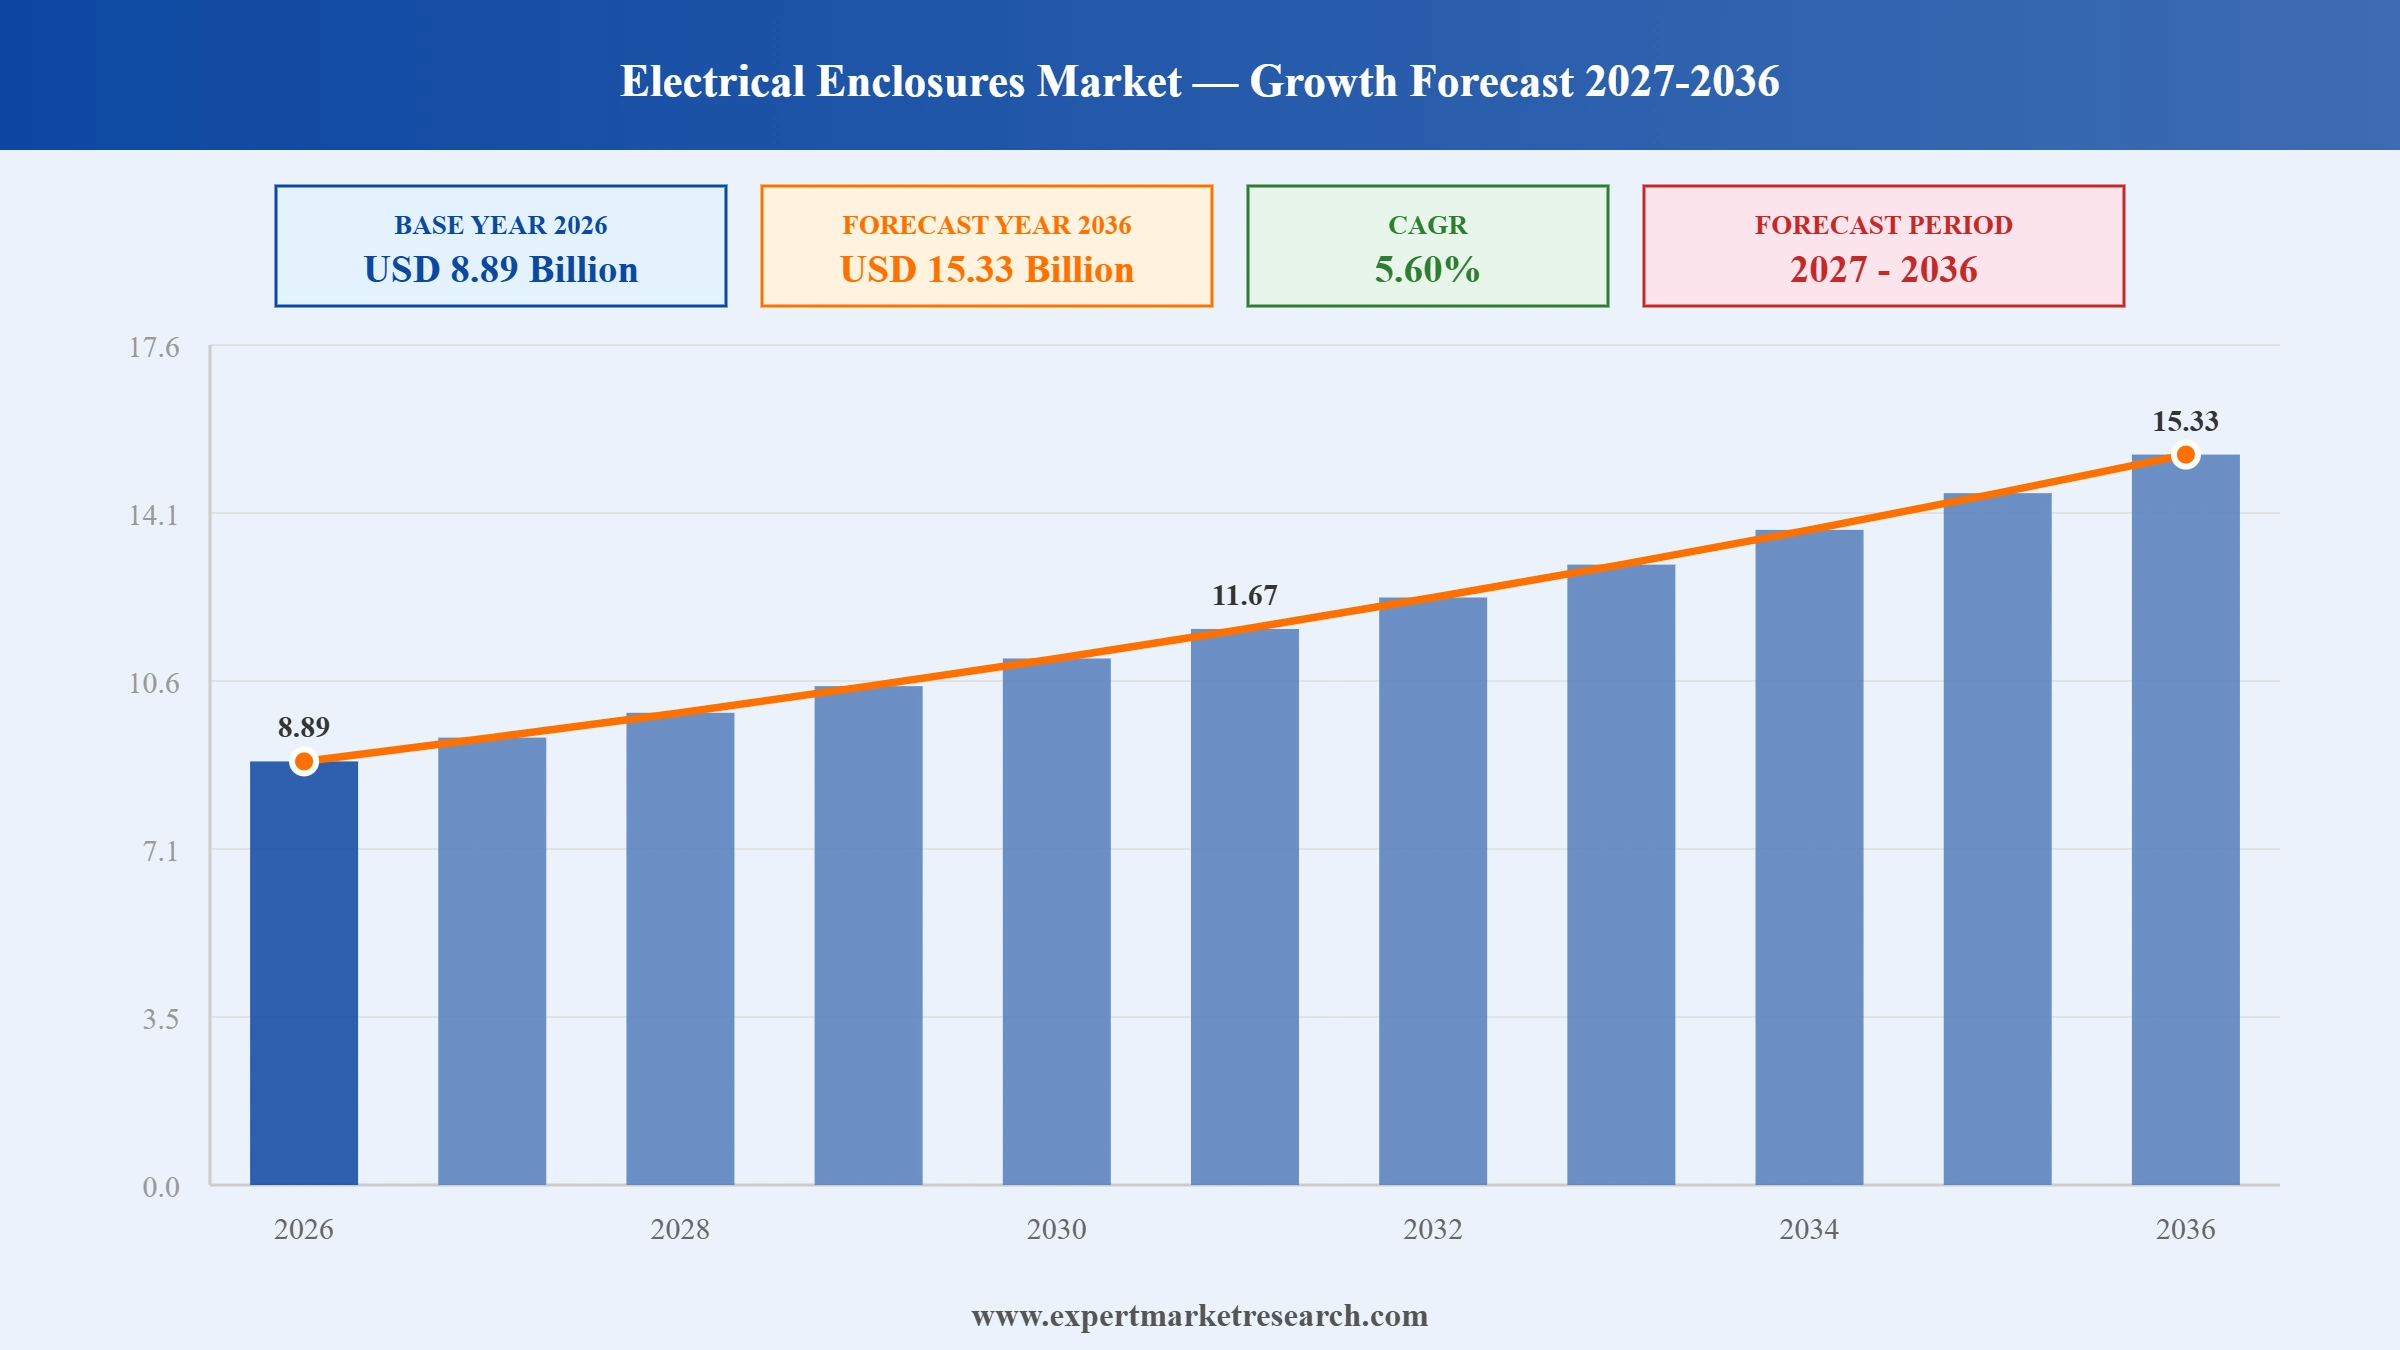
The global electrical enclosures market attained a value of USD 8.42 Billion in 2025 and is projected to expand at a CAGR of 5.60% through 2035. The market is further expected to achieve USD 14.52 Billion by 2035. Growing concern for equipment safety and operational reliability, rising demand for enclosures in solar and renewable energy applications, and expanding commercial and industrial sectors continue to support demand across metallic and non-metallic enclosures for power generation, oil and gas, and transportation applications.
Growing concern for equipment safety continues to anchor steady demand across the electrical enclosures market, as manufacturing, oil and gas, and utility sectors increasingly house critical systems in protective enclosures to safeguard against dust, moisture, and extreme temperatures. Manufacturers are also investing in sustainable material innovation, reflecting the industry's ongoing pursuit of enclosures that combine environmental responsibility with proven protection performance.
The electrical enclosures market is witnessing further developments as established manufacturers expand sustainable material offerings across their enclosure portfolios. In July 2026, Schneider Electric published its Universal Enclosures 2026 catalogue, extending its low-carbon emission steel portfolio and continuing the integration of recycled materials across its PanelSeT enclosure ranges. This shift toward sustainable material innovation is concentrated among manufacturers with sufficient research and development scale, while smaller specialists continue to compete on application-specific customisation and regional distribution relationships.
In addition, established manufacturers are increasingly expanding manufacturing capacity to serve data centre and AI infrastructure demand, reflecting the industry's recognition that specification-driven, high-reliability enclosure requirements from hyperscale computing customers increasingly determine competitive positioning beyond traditional industrial applications alone. Such capacity expansion activity is reshaping competitive positioning across the wider electrical enclosures market as manufacturers with proven data centre-grade manufacturing scale increasingly differentiate themselves from competitors serving only traditional industrial and utility applications.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Schneider Electric published its Universal Enclosures 2026 catalogue, extending its low-carbon emission steel portfolio to additional PanelSeT ranges and continuing the integration of recycled materials, alongside new certifications for PrismaSeT switchboard systems up to 1000 V AC. Companies can extend sustainable material portfolios across enclosure product ranges to meet growing customer demand for lower-carbon industrial infrastructure.
Eaton completed its 9.5 billion dollar acquisition of Boyd Thermal, a leader in thermal components and systems for data centres, aerospace, and other end markets, positioning the combined business as one of the world's largest grid-to-chip solutions providers. Companies can acquire complementary thermal management capabilities to extend electrical enclosure portfolios into integrated cooling solutions for high-growth data centre applications.
ABB launched its 2026 residual current circuit breaker with overcurrent protection range, supplying System pro M compact residual-current devices designed for space-efficient distribution boards and panel enclosures. Companies can develop space-efficient protection devices optimised for compact enclosure integration to meet rising demand for higher-density electrical distribution panels.
nVent Electric reported first-quarter 2026 sales surging 51 percent year-over-year to a record high, driven by strong demand for electrical enclosures, cabinets, and thermal management solutions used in data centre infrastructure, with the company projecting full-year 2026 revenue growth of 26 to 28 percent. Companies can track data centre-driven enclosure demand as a leading indicator of accelerating growth beyond traditional industrial and utility end markets.
Environmental credentials are becoming a bigger part of the enclosure buying decision, pushing manufacturers to broaden their lower-carbon and recycled-material offerings. In July 2026, Schneider Electric published an updated enclosures catalogue extending its low-carbon steel portfolio and continuing recycled material integration across multiple product ranges within the electrical enclosures market. Such sustainable material investment reflects manufacturers' recognition that lower-carbon industrial infrastructure increasingly influences procurement decisions among environmentally conscious enterprise customers.
Rather than partnering externally, several manufacturers have moved to acquire thermal management specialists outright, folding cooling capability directly into their enclosure portfolios. In March 2026, Eaton completed a multi-billion dollar acquisition of a thermal components specialist, positioning the combined business among the largest grid-to-chip solutions providers globally. Such acquisitions reflect manufacturers' recognition that data centre customers increasingly demand integrated enclosure and thermal management solutions rather than separately sourced components.
As distribution panels get denser, hardware makers are engineering protection devices specifically to fit tighter enclosure footprints. In March 2026, ABB launched a new residual current protection device range at Light + Building 2026, designed for space-efficient distribution boards and panel enclosures. Such compact device development reflects manufacturers' recognition that higher-density electrical distribution requirements increasingly demand protection hardware engineered specifically for smaller enclosure footprints.
Earnings from several manufacturers point to the same trend: AI and data centre buildouts are now a distinct, fast-growing demand pool for enclosures and thermal management hardware. In January 2026, nVent Electric reported sales surging more than 50 percent year-over-year to a record high, projecting continued strong growth for the full year. Such accelerating growth reflects manufacturers' recognition that hyperscale computing customers increasingly represent a distinct, high-growth demand segment beyond traditional industrial and utility applications.
This Expert Market Research Report titled "Electrical Enclosures Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Material Type
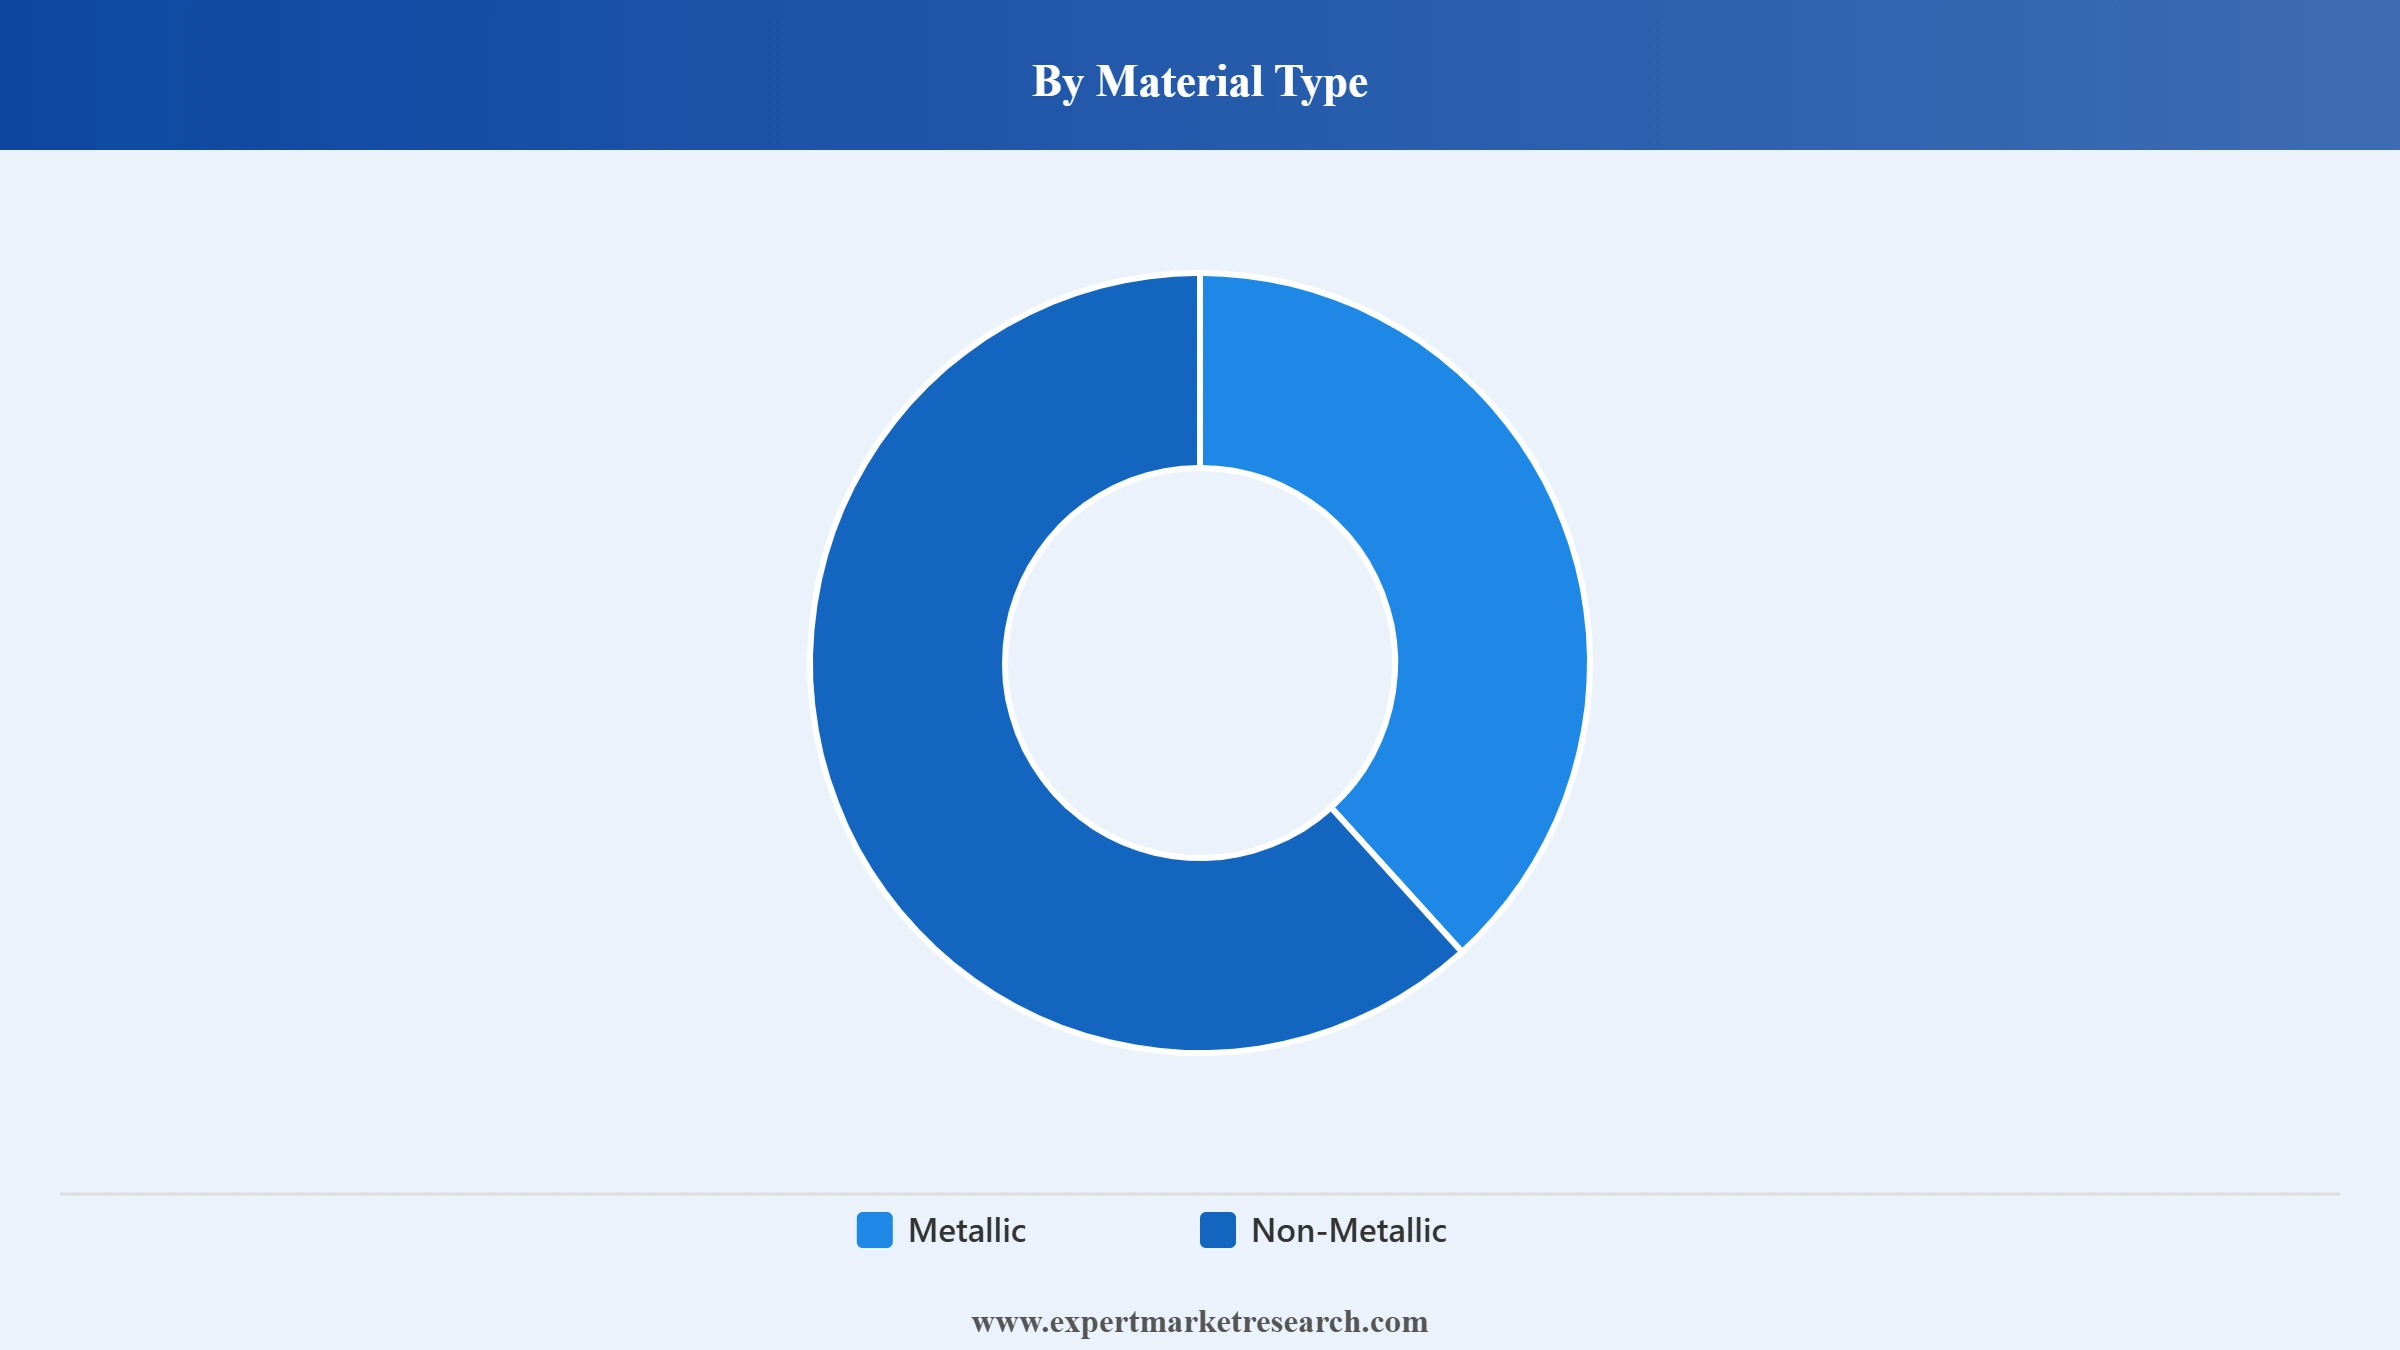
Key Insight: Metallic accounts for the largest share of the electrical enclosures market, reflecting its established durability and mechanical protection performance across industrial and utility applications. Non-Metallic is growing at the fastest pace as corrosion resistance and lightweight properties drive adoption in outdoor and harsh environments, illustrated by Schneider Electric's July 2026 catalogue expanding its non-metallic Thalassa enclosure ranges alongside sustainable steel options.
Market Breakup by Mounting Type
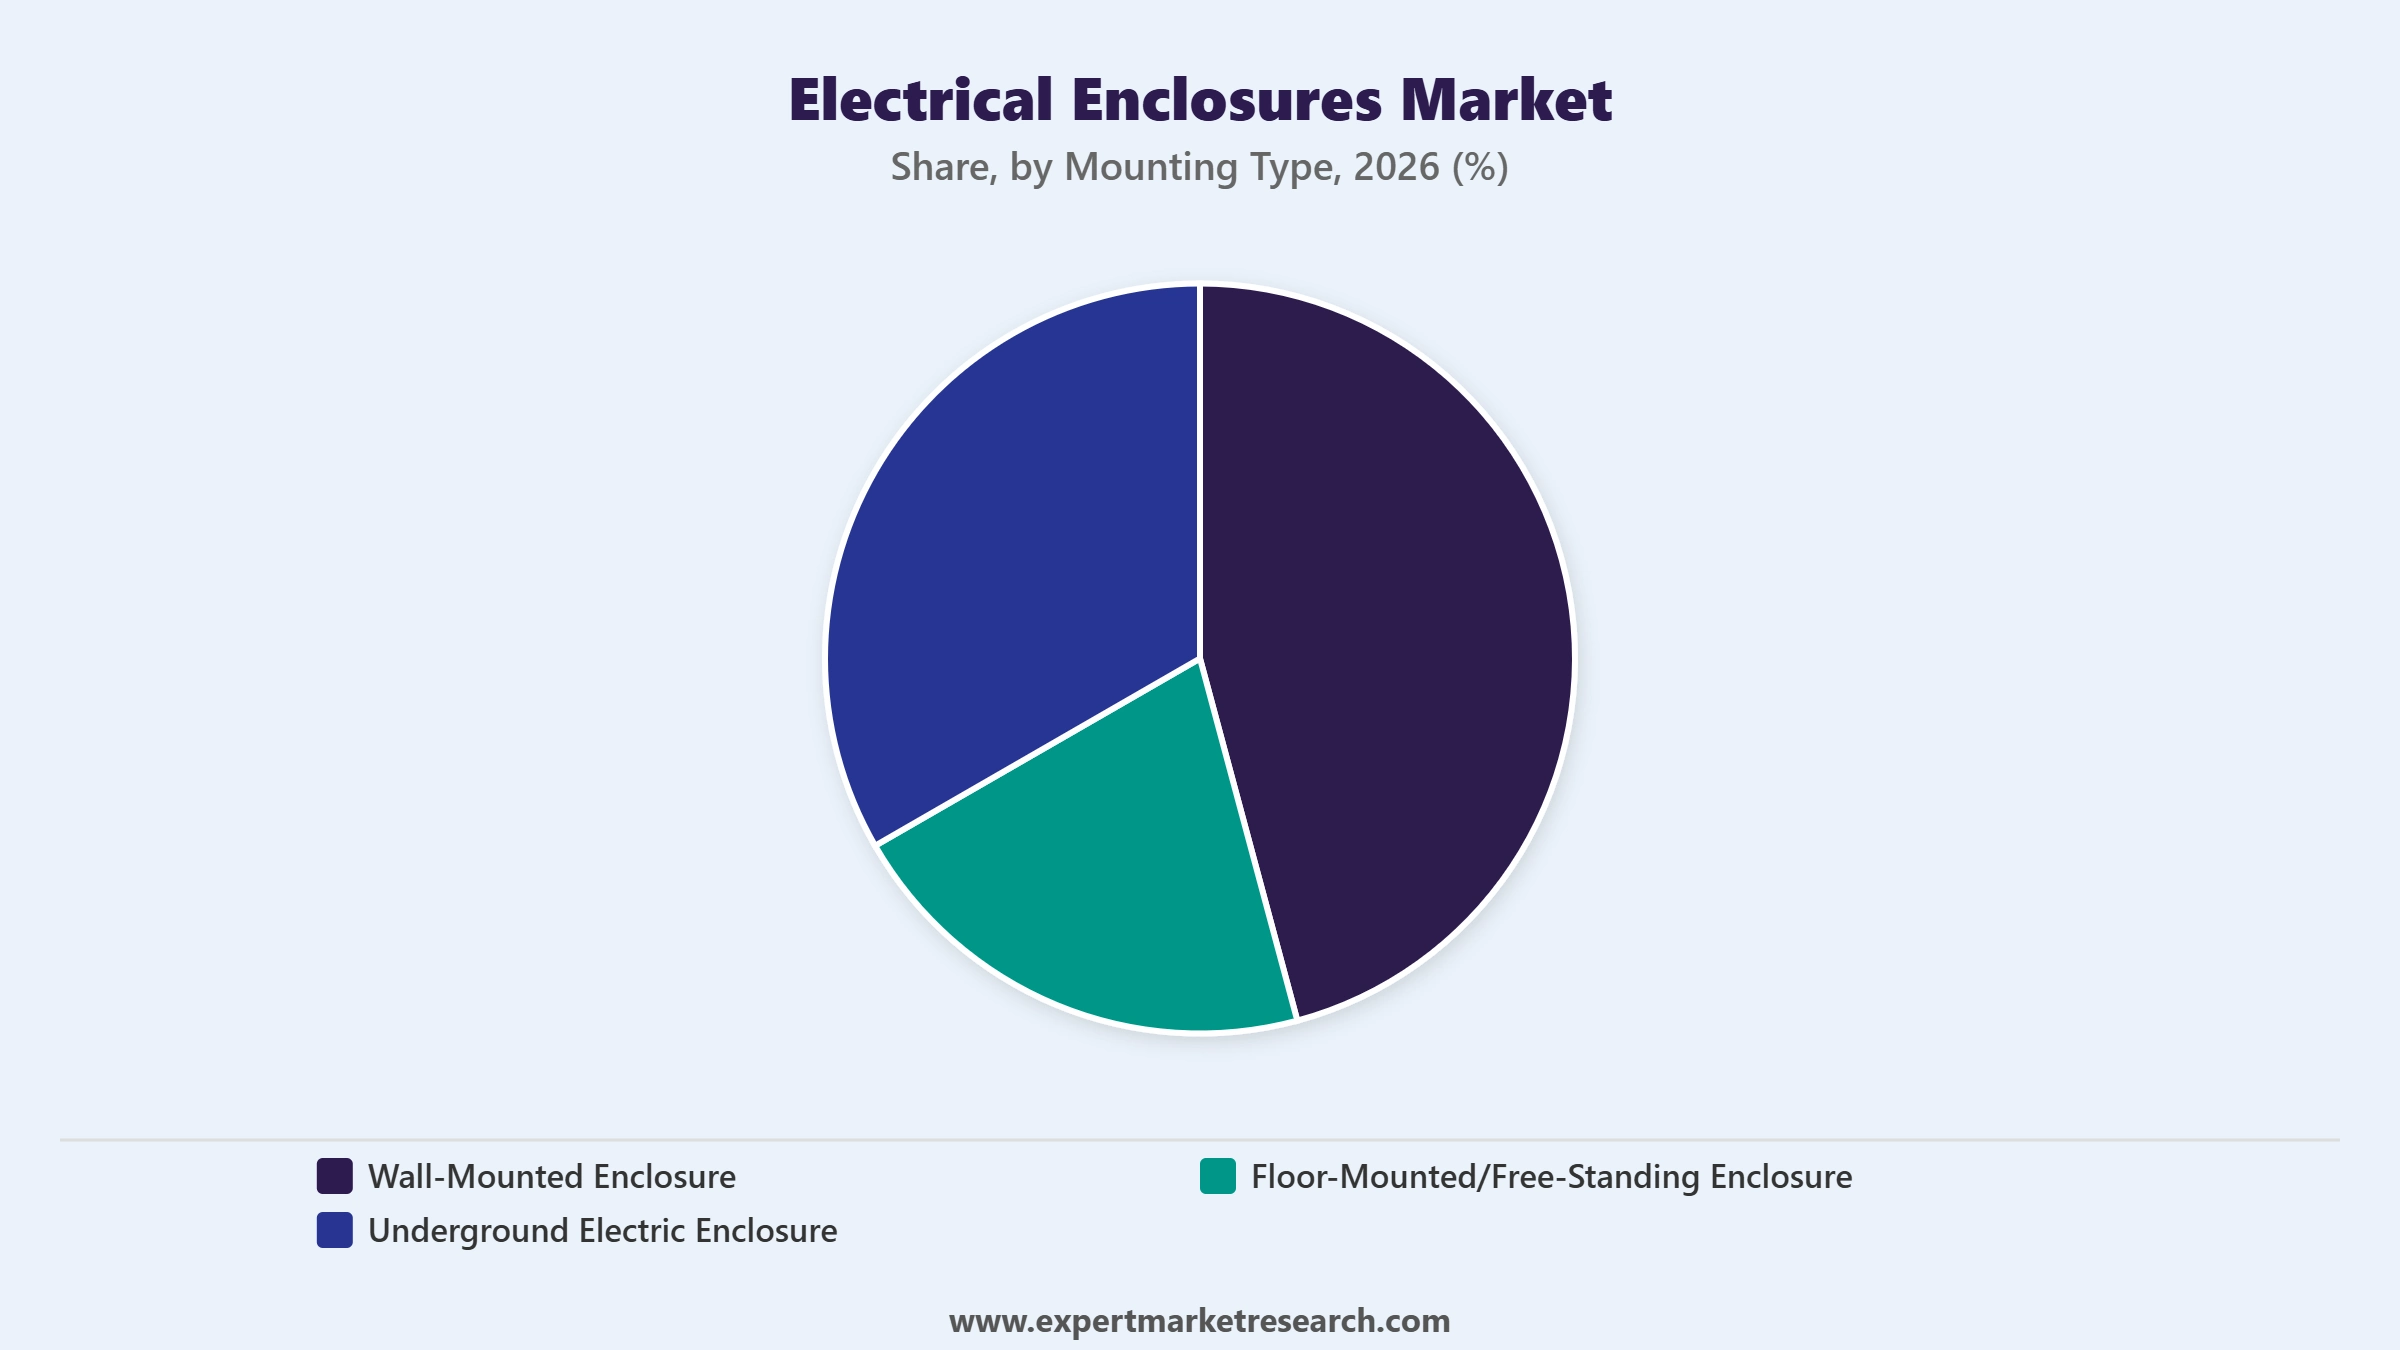
Key Insight: Wall-Mounted Enclosure accounts for the largest share of the electrical enclosures market, reflecting its space-efficient installation across commercial and light industrial applications. Floor-Mounted/Free-Standing Enclosure continues to serve heavy industrial and utility applications requiring larger equipment housing, while Underground Electric Enclosure serves a smaller, more specialised category for below-grade utility infrastructure. In March 2026, Eaton's 550 million dollar Warren County, Tennessee plant expansion targeted increased free-standing enclosure production capacity for commercial fleet and utility customers.
Market Breakup by Form Factor
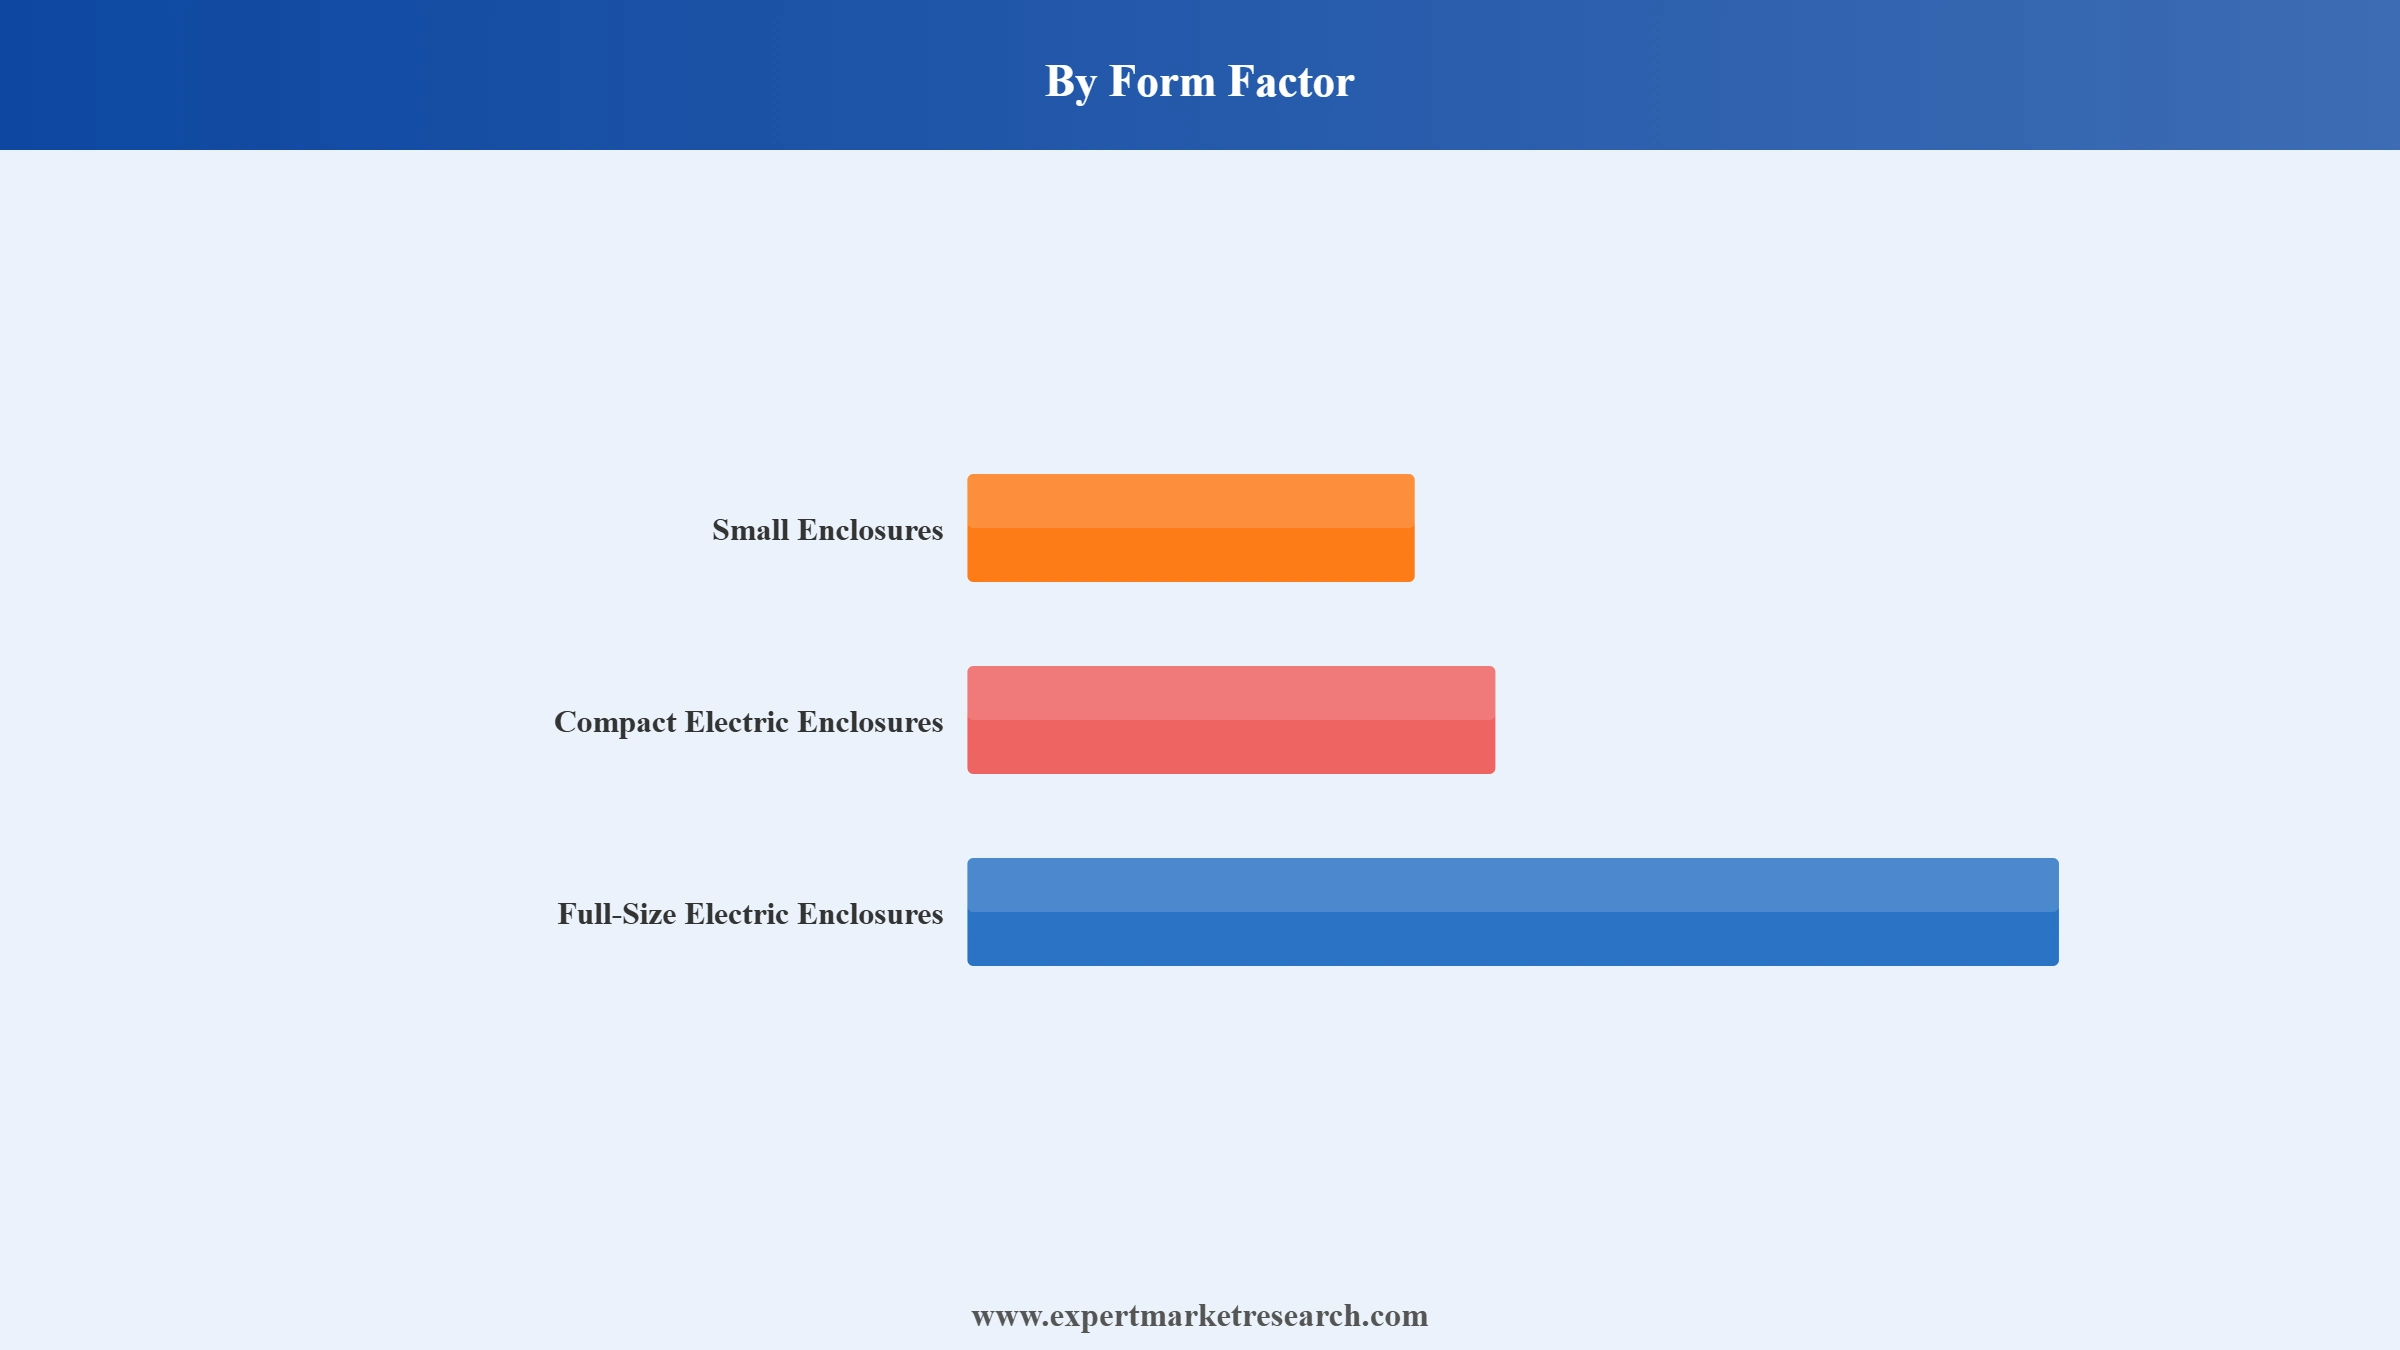
Key Insight: Full-Size Electric Enclosures accounts for the largest share of the electrical enclosures market, reflecting sustained demand from heavy industrial and utility applications requiring substantial equipment housing capacity. Compact Electric Enclosures is growing at a fast pace as space-constrained installations increasingly favour higher-density solutions, illustrated by ABB's 2026 RCBO range designed for space-efficient distribution boards. Small Enclosures continues to serve light commercial and residential applications.
Market Breakup by Product Type
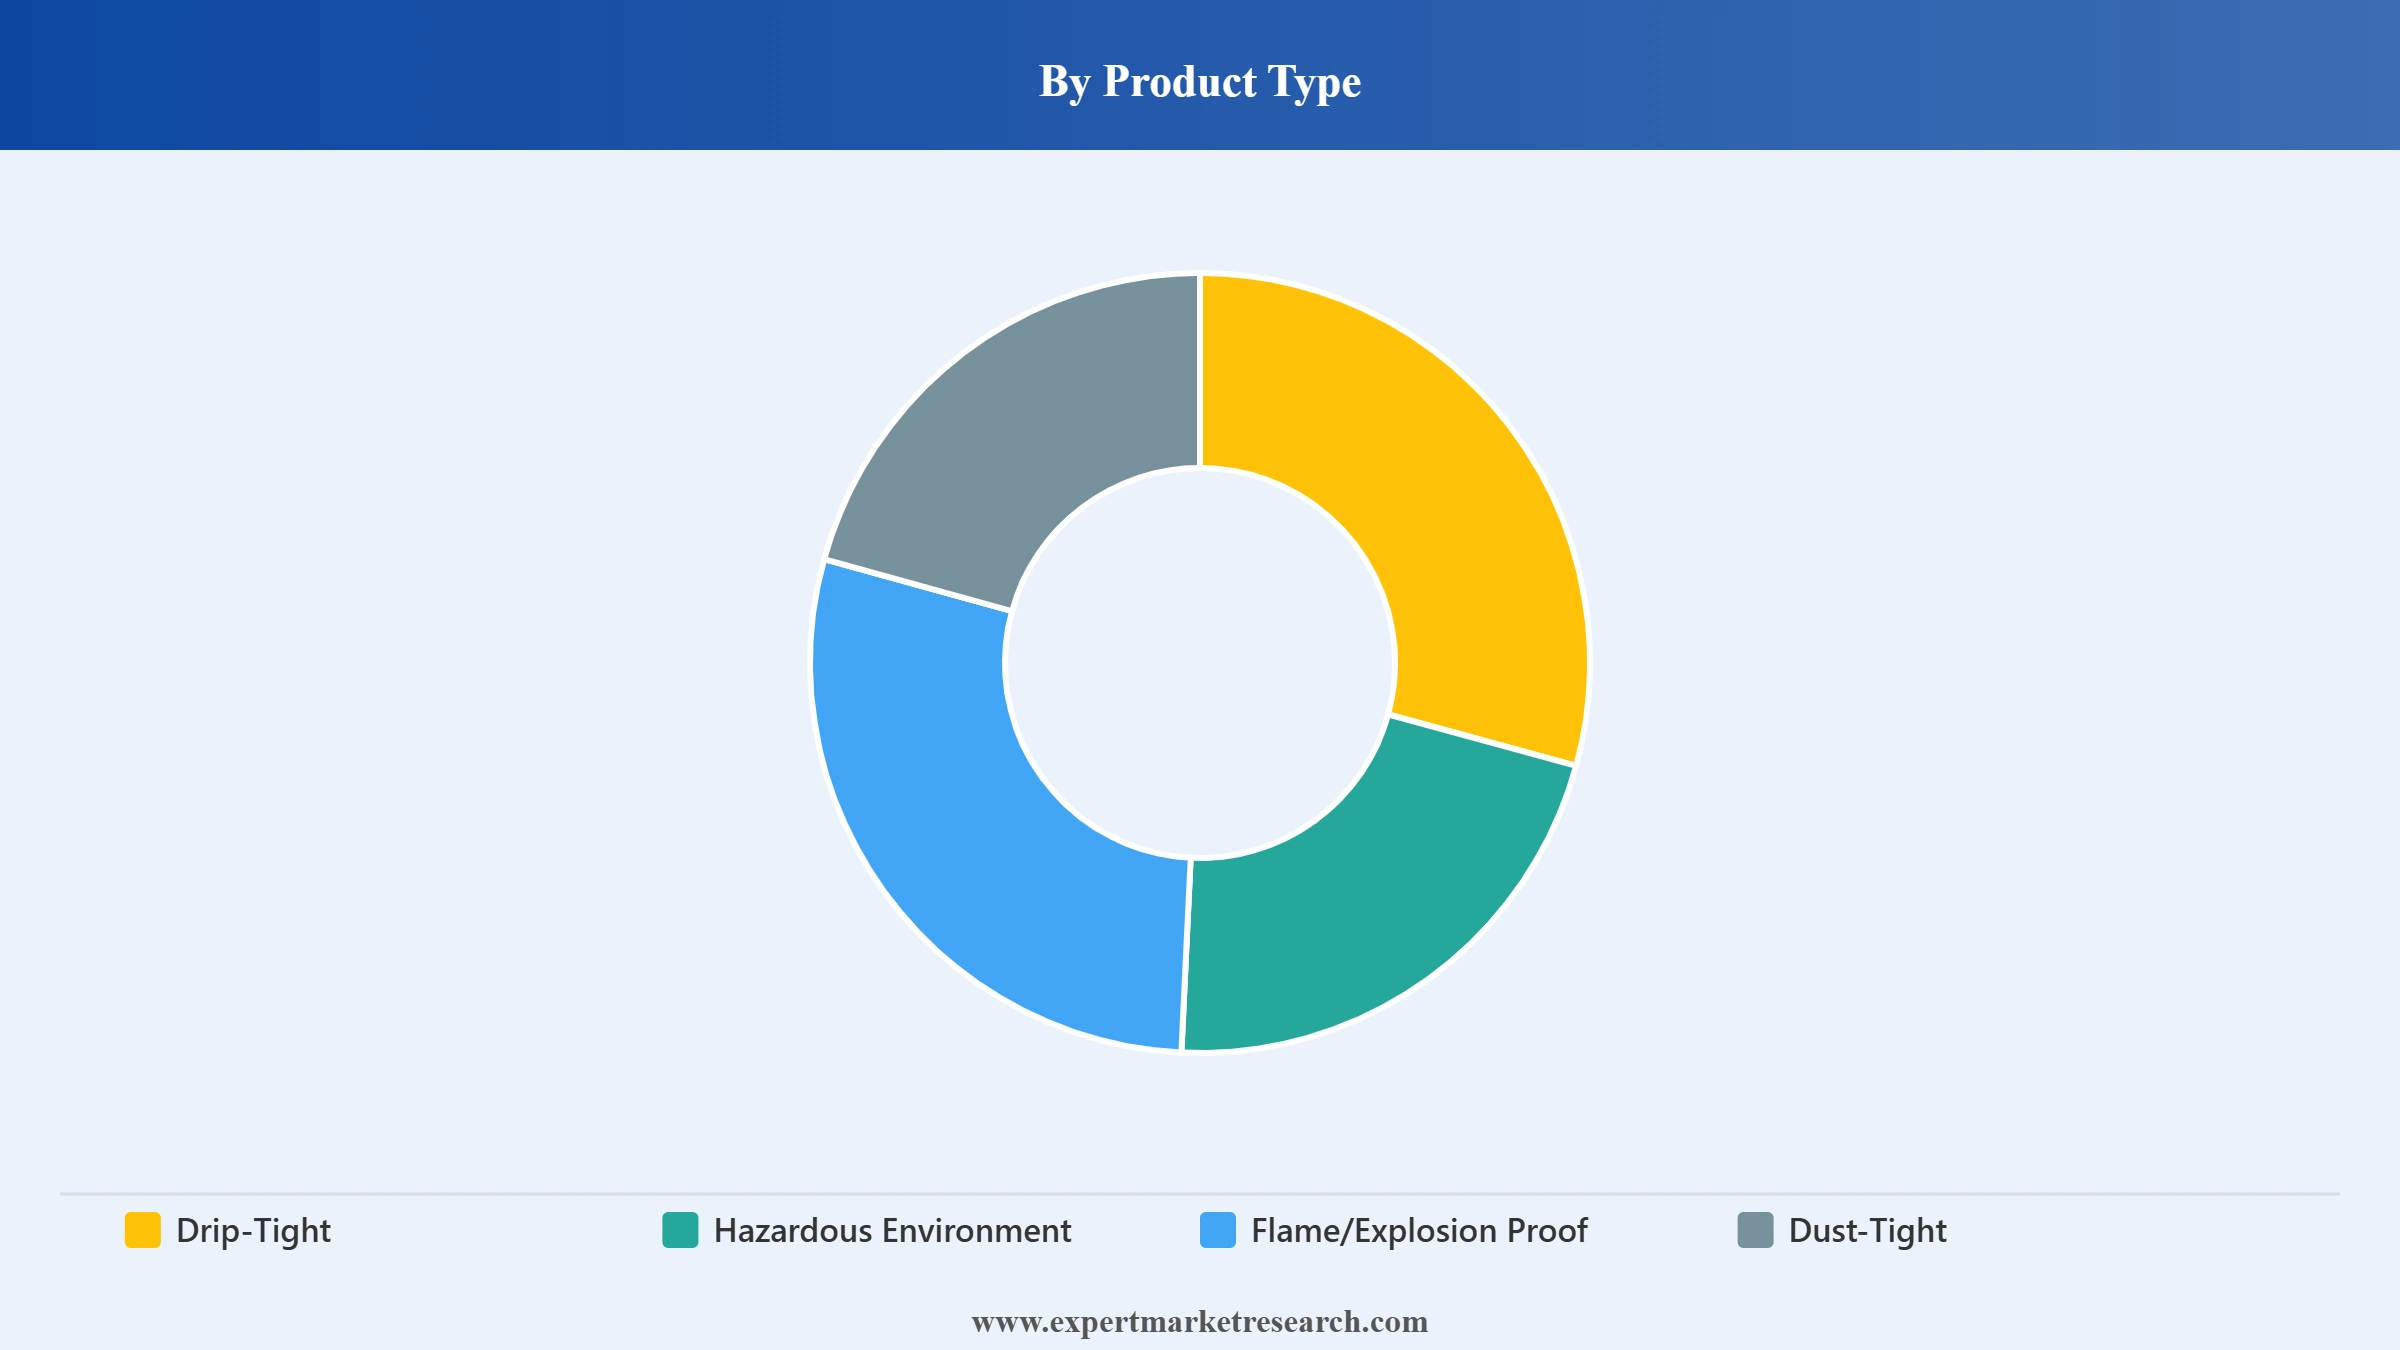
Key Insight: Hazardous Environment accounts for the largest share of the electrical enclosures market, reflecting sustained demand from oil and gas, chemical, and mining applications requiring explosion-resistant equipment housing. Dust-Tight and Drip-Tight continue to serve applications requiring protection from particulate and moisture ingress, while Flame/Explosion Proof serves the most demanding hazardous location requirements, with other product types rounding out the remaining category. In January 2026, nVent Electric reported sales surging 51 percent year-over-year, driven substantially by hazardous environment and dust-tight enclosure demand from data centre infrastructure customers.
Market Breakup by Industry Vertical
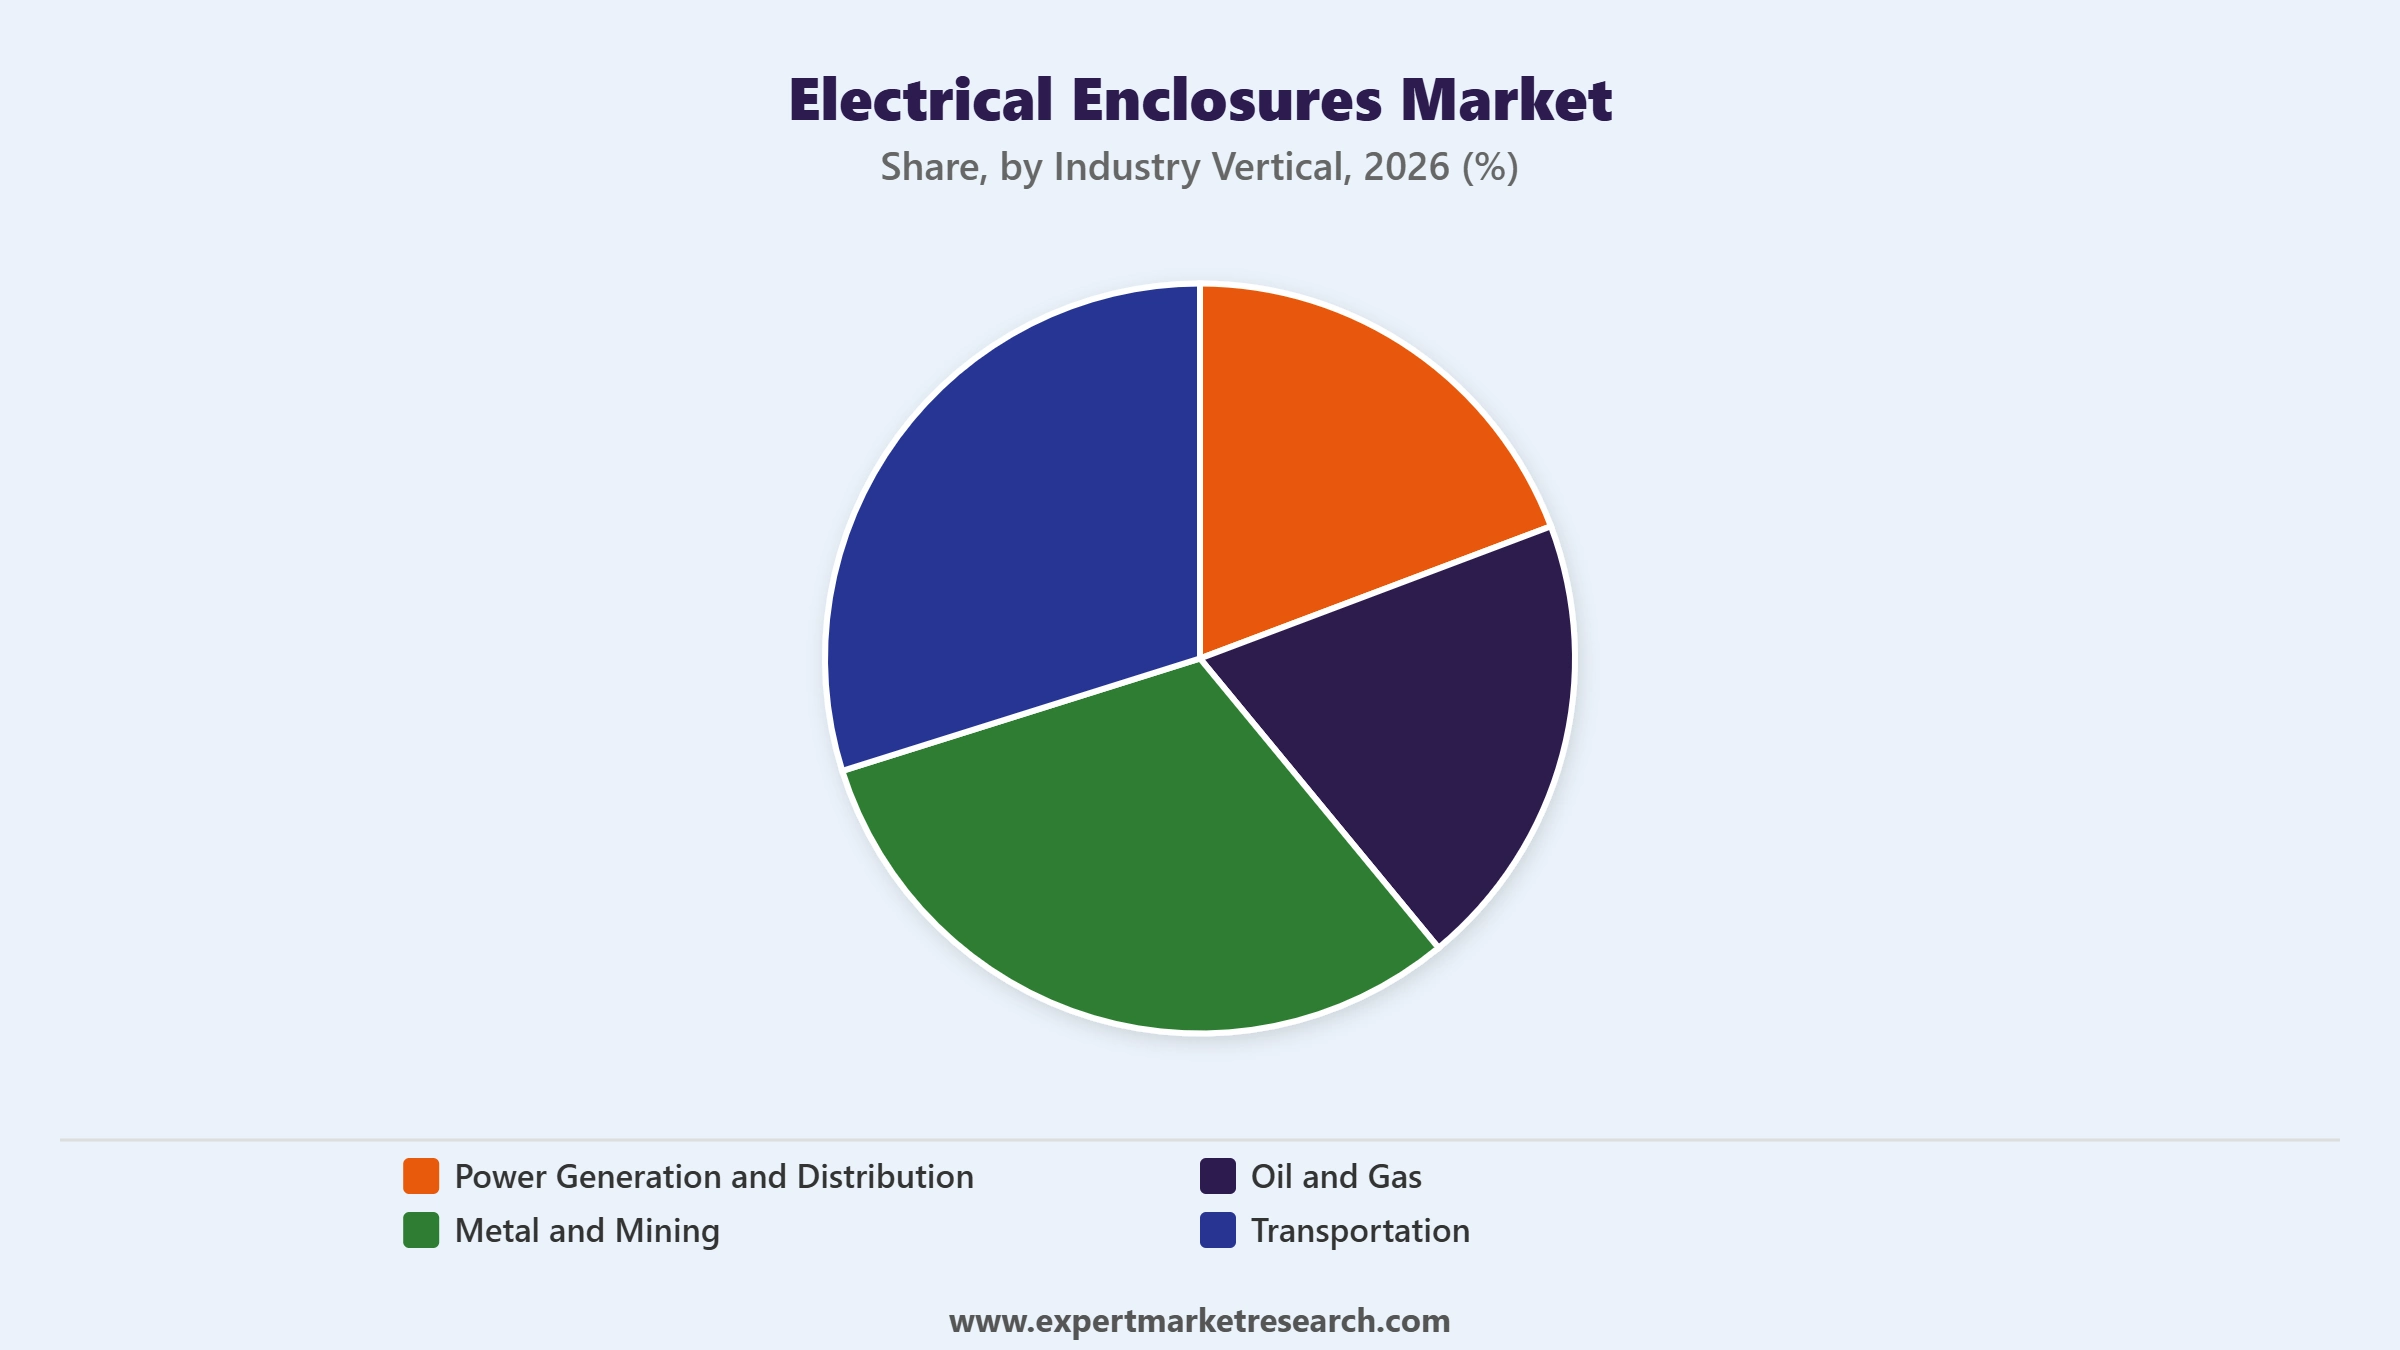
Key Insight: Power Generation and Distribution accounts for the largest share of the electrical enclosures market, reflecting sustained utility and renewable energy infrastructure investment requiring protective equipment housing. Oil and Gas continues to represent substantial demand given harsh operating environments, while Metal and Mining and Transportation each maintain steady adoption tied to sector-specific equipment protection needs, with other verticals rounding out the remaining category. In July 2026, Schneider Electric's Universal Enclosures catalogue highlighted new PrismaSeT certifications supporting power generation and distribution applications up to 1000 V AC.
Market Breakup by Region
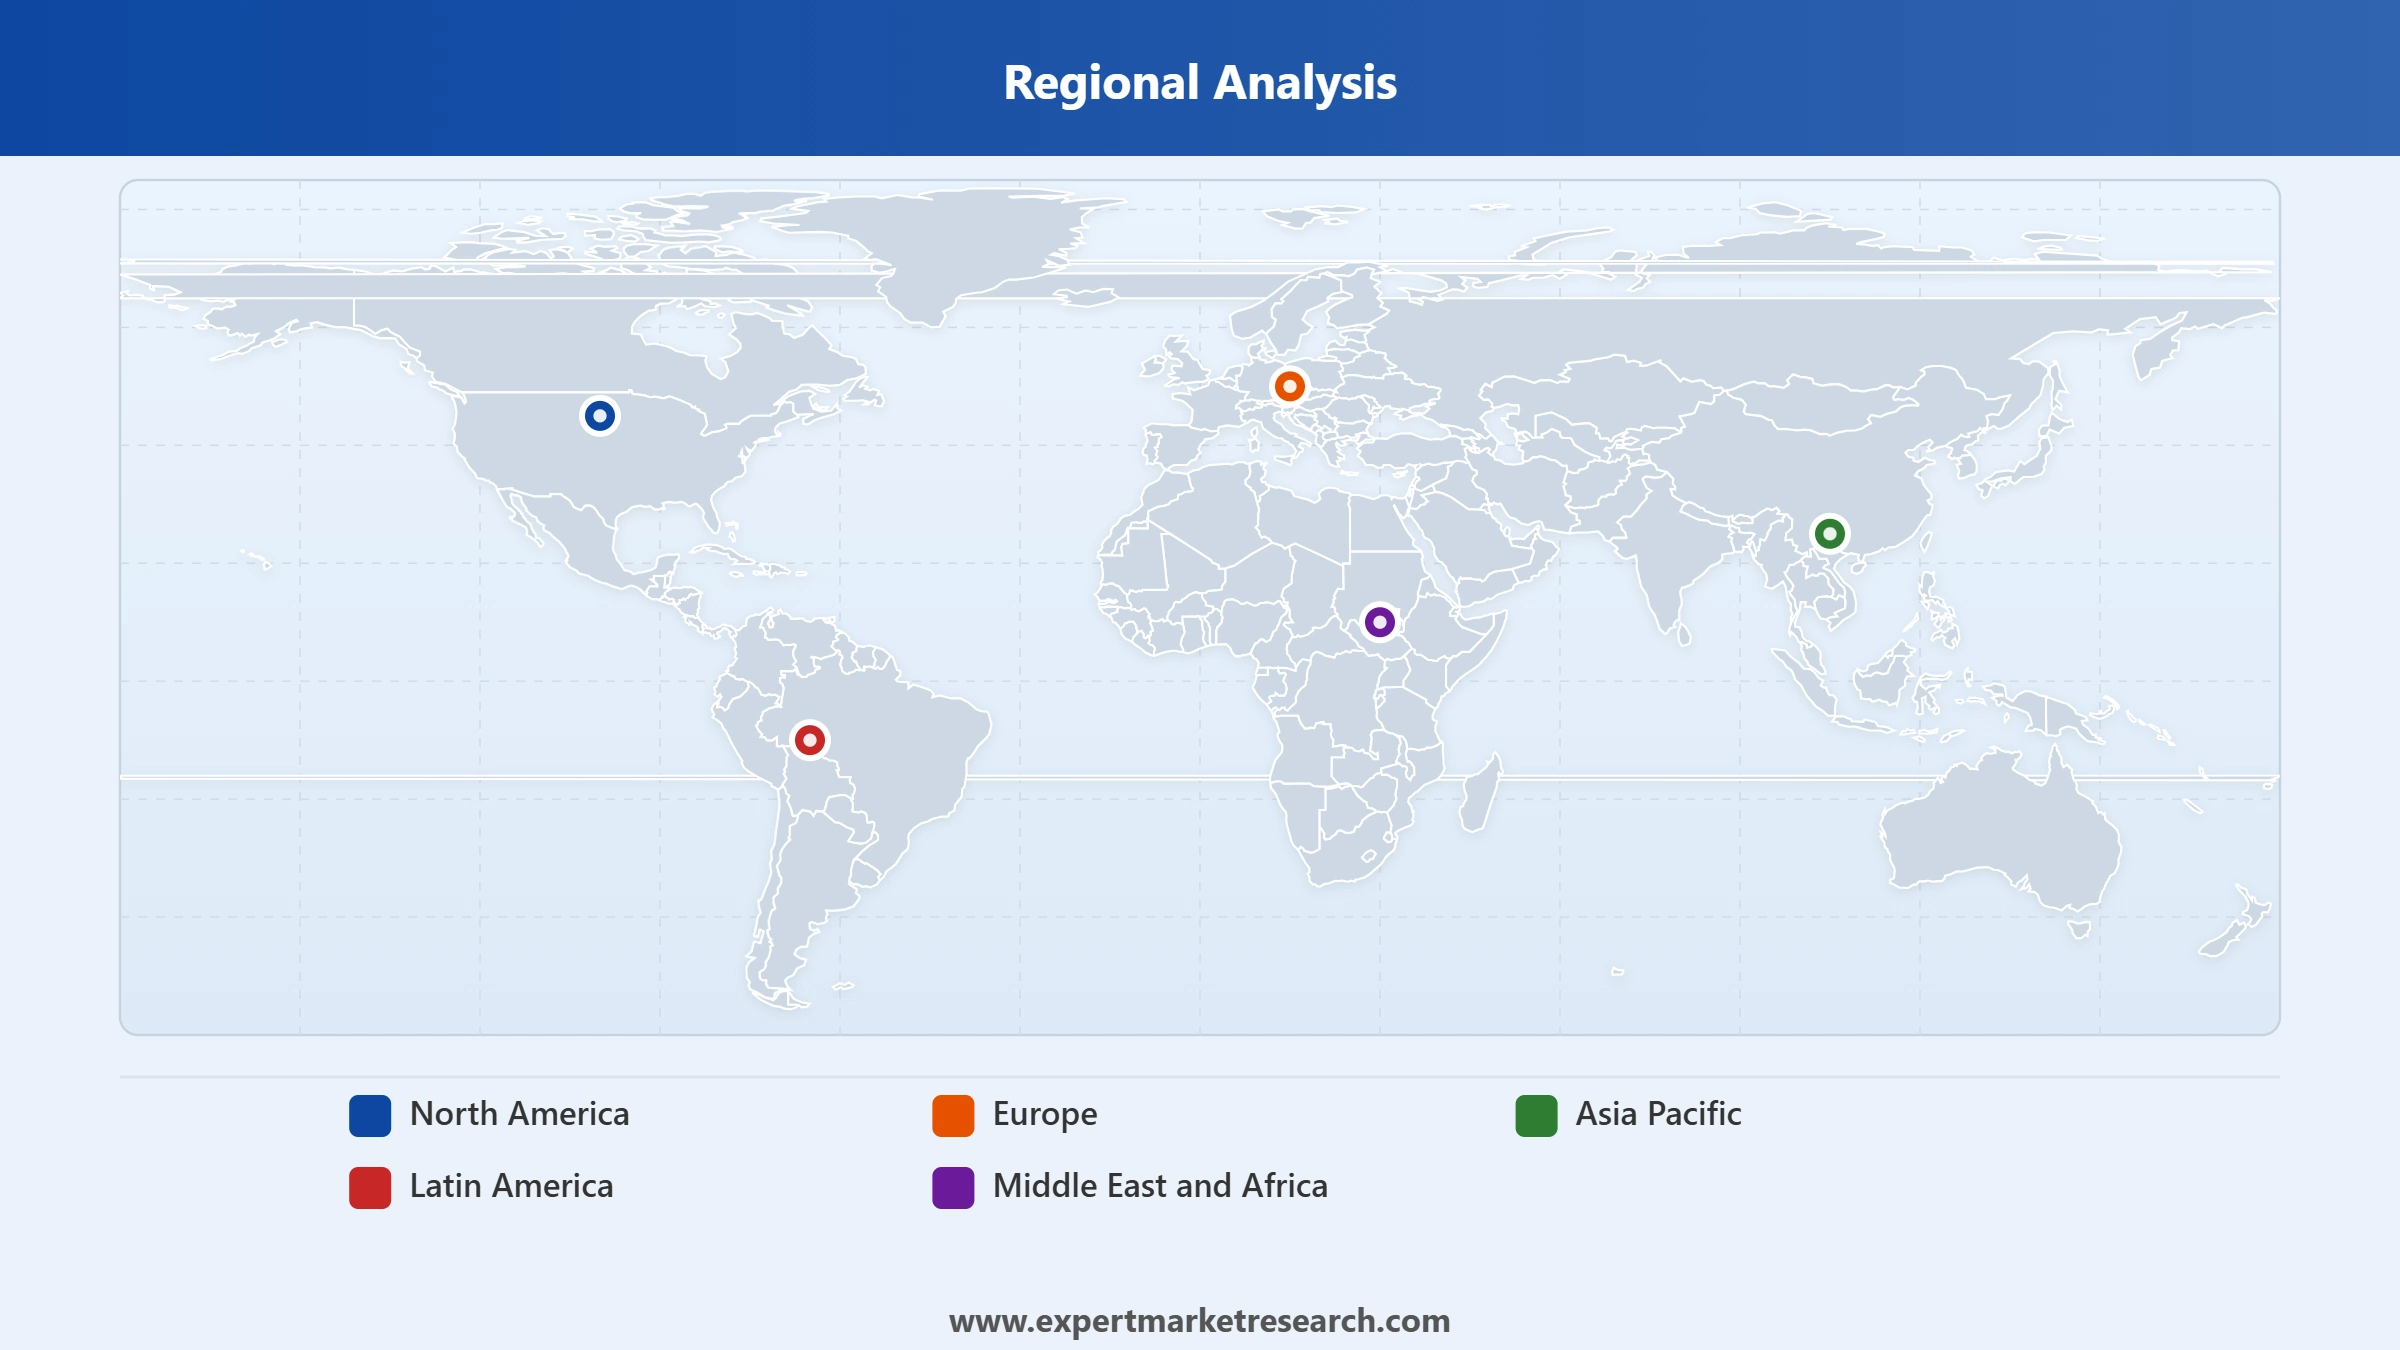
Key Insight: Asia Pacific accounts for the largest share of the electrical enclosures market, supported by the region's rapid industrialisation and expanding infrastructure development. North America is emerging as a key growth market as data centre and AI infrastructure investment continue to drive demand. Europe, Latin America, and the Middle East and Africa each continue to serve distinct regional industrial and utility infrastructure patterns.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By material type, metallic leads the market while non-metallic grows fastest given rising corrosion resistance demand
Metallic continues to account for the largest share of the market, reflecting its established durability and mechanical protection performance across industrial and utility applications. Established metallic enclosure relationships continue to anchor steady demand as manufacturers maintain proven material sourcing across successive production cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Non-Metallic is growing at the fastest pace across the electrical enclosures market as corrosion resistance and lightweight properties drive adoption in outdoor and harsh environments, supported by manufacturer investment in sustainable, recycled non-metallic material options. In July 2026, Schneider Electric's Universal Enclosures catalogue continued the integration of recycled materials across its non-metallic Thalassa enclosure ranges.
By product type, hazardous environment leads the market while dust-tight grows fastest given expanding industrial applications
Hazardous Environment continues to account for the largest share of the market, reflecting sustained demand from oil and gas, chemical, and mining applications requiring explosion-resistant equipment housing. Established hazardous environment enclosure relationships continue to anchor steady demand as operators maintain proven suppliers across successive safety certification cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Dust-Tight is growing at a fast pace across the electrical enclosures market as expanding industrial and data centre applications increasingly require protection from particulate ingress in high-density equipment environments. In January 2026, nVent Electric reported sales surging 51 percent year-over-year, driven substantially by demand for hazardous environment and dust-tight enclosures serving data centre customers.
By industry vertical, power generation and distribution leads the market while power generation and distribution continues strengthening its position given renewable expansion
Power Generation and Distribution continues to account for the largest share of the market, reflecting sustained utility and renewable energy infrastructure investment requiring protective equipment housing. Established power generation relationships continue to anchor steady demand as utilities maintain proven enclosure suppliers across successive infrastructure investment cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Oil and Gas continues to represent substantial demand across the electrical enclosures market given harsh operating environments requiring hazardous-location-rated equipment housing across drilling, refining, and pipeline applications. In July 2026, Schneider Electric's Universal Enclosures catalogue highlighted new PrismaSeT certifications up to 1000 V AC supporting power generation and distribution infrastructure.
By mounting type, wall-mounted enclosure leads the market while wall-mounted enclosure grows fastest given space-efficient installation demand
Wall-Mounted Enclosure continues to account for the largest share of the market, reflecting its space-efficient installation across commercial and light industrial applications. Established wall-mounted enclosure relationships continue to anchor steady demand as installers maintain proven suppliers across successive project cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Floor-Mounted/Free-Standing Enclosure continues to represent substantial demand across the electrical enclosures market as heavy industrial and utility applications maintain steady demand for larger equipment housing. In March 2026, Eaton's 9.5 billion dollar acquisition of Boyd Thermal underscored continued investment in large-scale, free-standing enclosure and cooling infrastructure for data centre applications.
By form factor, full-size electric enclosures leads the market while compact electric enclosures grows fastest given rising space-constrained installation demand
Full-Size Electric Enclosures continues to account for the largest share of the market, reflecting sustained demand from heavy industrial and utility applications requiring substantial equipment housing capacity. Established full-size enclosure relationships continue to anchor steady demand as operators maintain proven suppliers across successive infrastructure cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Compact Electric Enclosures is growing at the fastest pace across the electrical enclosures market as space-constrained installations increasingly favour higher-density solutions. In 2026, ABB launched its System pro M compact residual current protection range designed specifically for space-efficient distribution boards.
Asia Pacific commands the largest share of the market through its rapid industrialisation
Asia Pacific holds the largest share of the electrical enclosures market, supported by the region's rapid industrialisation and expanding infrastructure development. Regional manufacturers continue to expand production capacity to meet both domestic industrial demand and rising export volumes to international markets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America is emerging as a key growth market as data centre and AI infrastructure investment continue to drive demand across the region. In March 2026, continued manufacturer acquisition activity in thermal management capabilities reinforced the region's growing importance for integrated enclosure and cooling solutions across the wider electrical enclosures market.
The global industry is moderately consolidated, with electrical enclosures market companies ranging from diversified global electrical equipment groups spanning multiple product categories to specialist enclosure manufacturers competing across material type, mounting type, and industry vertical segments. Established players operate across the full electrical enclosures value chain, from material sourcing and precision fabrication through complete enclosure assembly and distribution for industrial, utility, and data centre customers.
Competitive dynamics among electrical enclosures players are increasingly shaped by the pace of sustainable material innovation, the scale of data centre-focused capacity expansion, and the race to integrate thermal management capabilities into enclosure portfolios. Manufacturers are investing in low-carbon materials, space-efficient protection devices, and integrated cooling solutions to differentiate their offering and secure long-term industrial and data centre customer relationships.
Founded in 1988 and headquartered in Zurich, Switzerland, ABB manufactures electrical enclosures and protection devices as part of its broader electrification and automation technology portfolio. In 2026, the company launched its System pro M compact residual current protection range designed for space-efficient distribution boards. ABB's combined electrification and automation technology portfolio differentiates its offering from specialist enclosure manufacturers with narrower product scope.
Founded in 1836 and headquartered in Rueil-Malmaison, France, Schneider Electric manufactures electrical enclosures under its PanelSeT, Thalassa, and Actassi brand families for industrial, IT, and electrical distribution applications. In July 2026, the company published its Universal Enclosures 2026 catalogue extending its low-carbon steel portfolio and recycled material integration. Schneider Electric's extensive sustainable material investment differentiates its offering from competitors with less developed environmental product credentials.
Founded in 1911 and headquartered in Dublin, Ireland, Eaton manufactures electrical enclosures and power management solutions serving industrial, utility, and data centre customers. In March 2026, the company completed its 9.5 billion dollar acquisition of Boyd Thermal, strengthening its integrated grid-to-chip solutions capability. Eaton's combined power management and thermal management portfolio differentiates its offering from competitors providing enclosures alone without integrated cooling capability.
Founded in 1890 and headquartered in St. Louis, Missouri, United States, Emerson Electric manufactures electrical enclosures as part of its broader automation and industrial technology portfolio. The company serves process industries requiring integrated automation and protective housing solutions. Emerson's extensive process automation technology portfolio differentiates its offering from specialist enclosure manufacturers focused solely on protective housing.
Other key players in the electrical enclosures market include RITTAL GmbH & Co. KG, Hubbell Incorporated, Scott Fetzer Company (Adalet), nVent Electric Plc, Hammond Manufacturing Company Limited, and SOCOMEC, Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our electrical enclosures market trends 2026 report. Discover regional growth patterns, material type and product type trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 8.42 Billion.
The electrical enclosures market is assessed to grow at a CAGR of 5.60% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 14.52 Billion by 2035.
Expanding sustainable material portfolios across enclosure product ranges, acquiring complementary thermal management capabilities to serve data centre customers, and developing space-efficient protection devices optimised for compact, high-density enclosure integration.
The key market trends include growing research and development activities to offer various enclosure material options to meet industry specific requirements, providing ideal solution for virtually any application.
Metallic and non-metallic electrical enclosures are the different material types available in the market.
Wall-mounted enclosure, floor-mounted/free-standing enclosure, and underground electric enclosure, are the major segments of the market based on mounting type.
ABB Ltd., Schneider Electric SE, Eaton Corporation Plc, Emerson Electric Co., RITTAL GmbH & Co. KG, Hubbell Incorporated, Scott Fetzer Company (Adalet), nVent Electric Plc, Hammond Manufacturing Company Limited, and SOCOMEC, Inc., among others, are the key players operating in the market.
Manufacturers face raw material price volatility affecting both metallic and non-metallic input costs, complex regional certification requirements varying across hazardous location standards, and intensifying competition to differentiate products beyond basic protection toward integrated thermal and monitoring capability.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Material Type |
|
| Breakup by Mounting Type |
|
| Breakup by Form Factor |
|
| Breakup by Product Type |
|
| Breakup by Industry Vertical |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




