

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
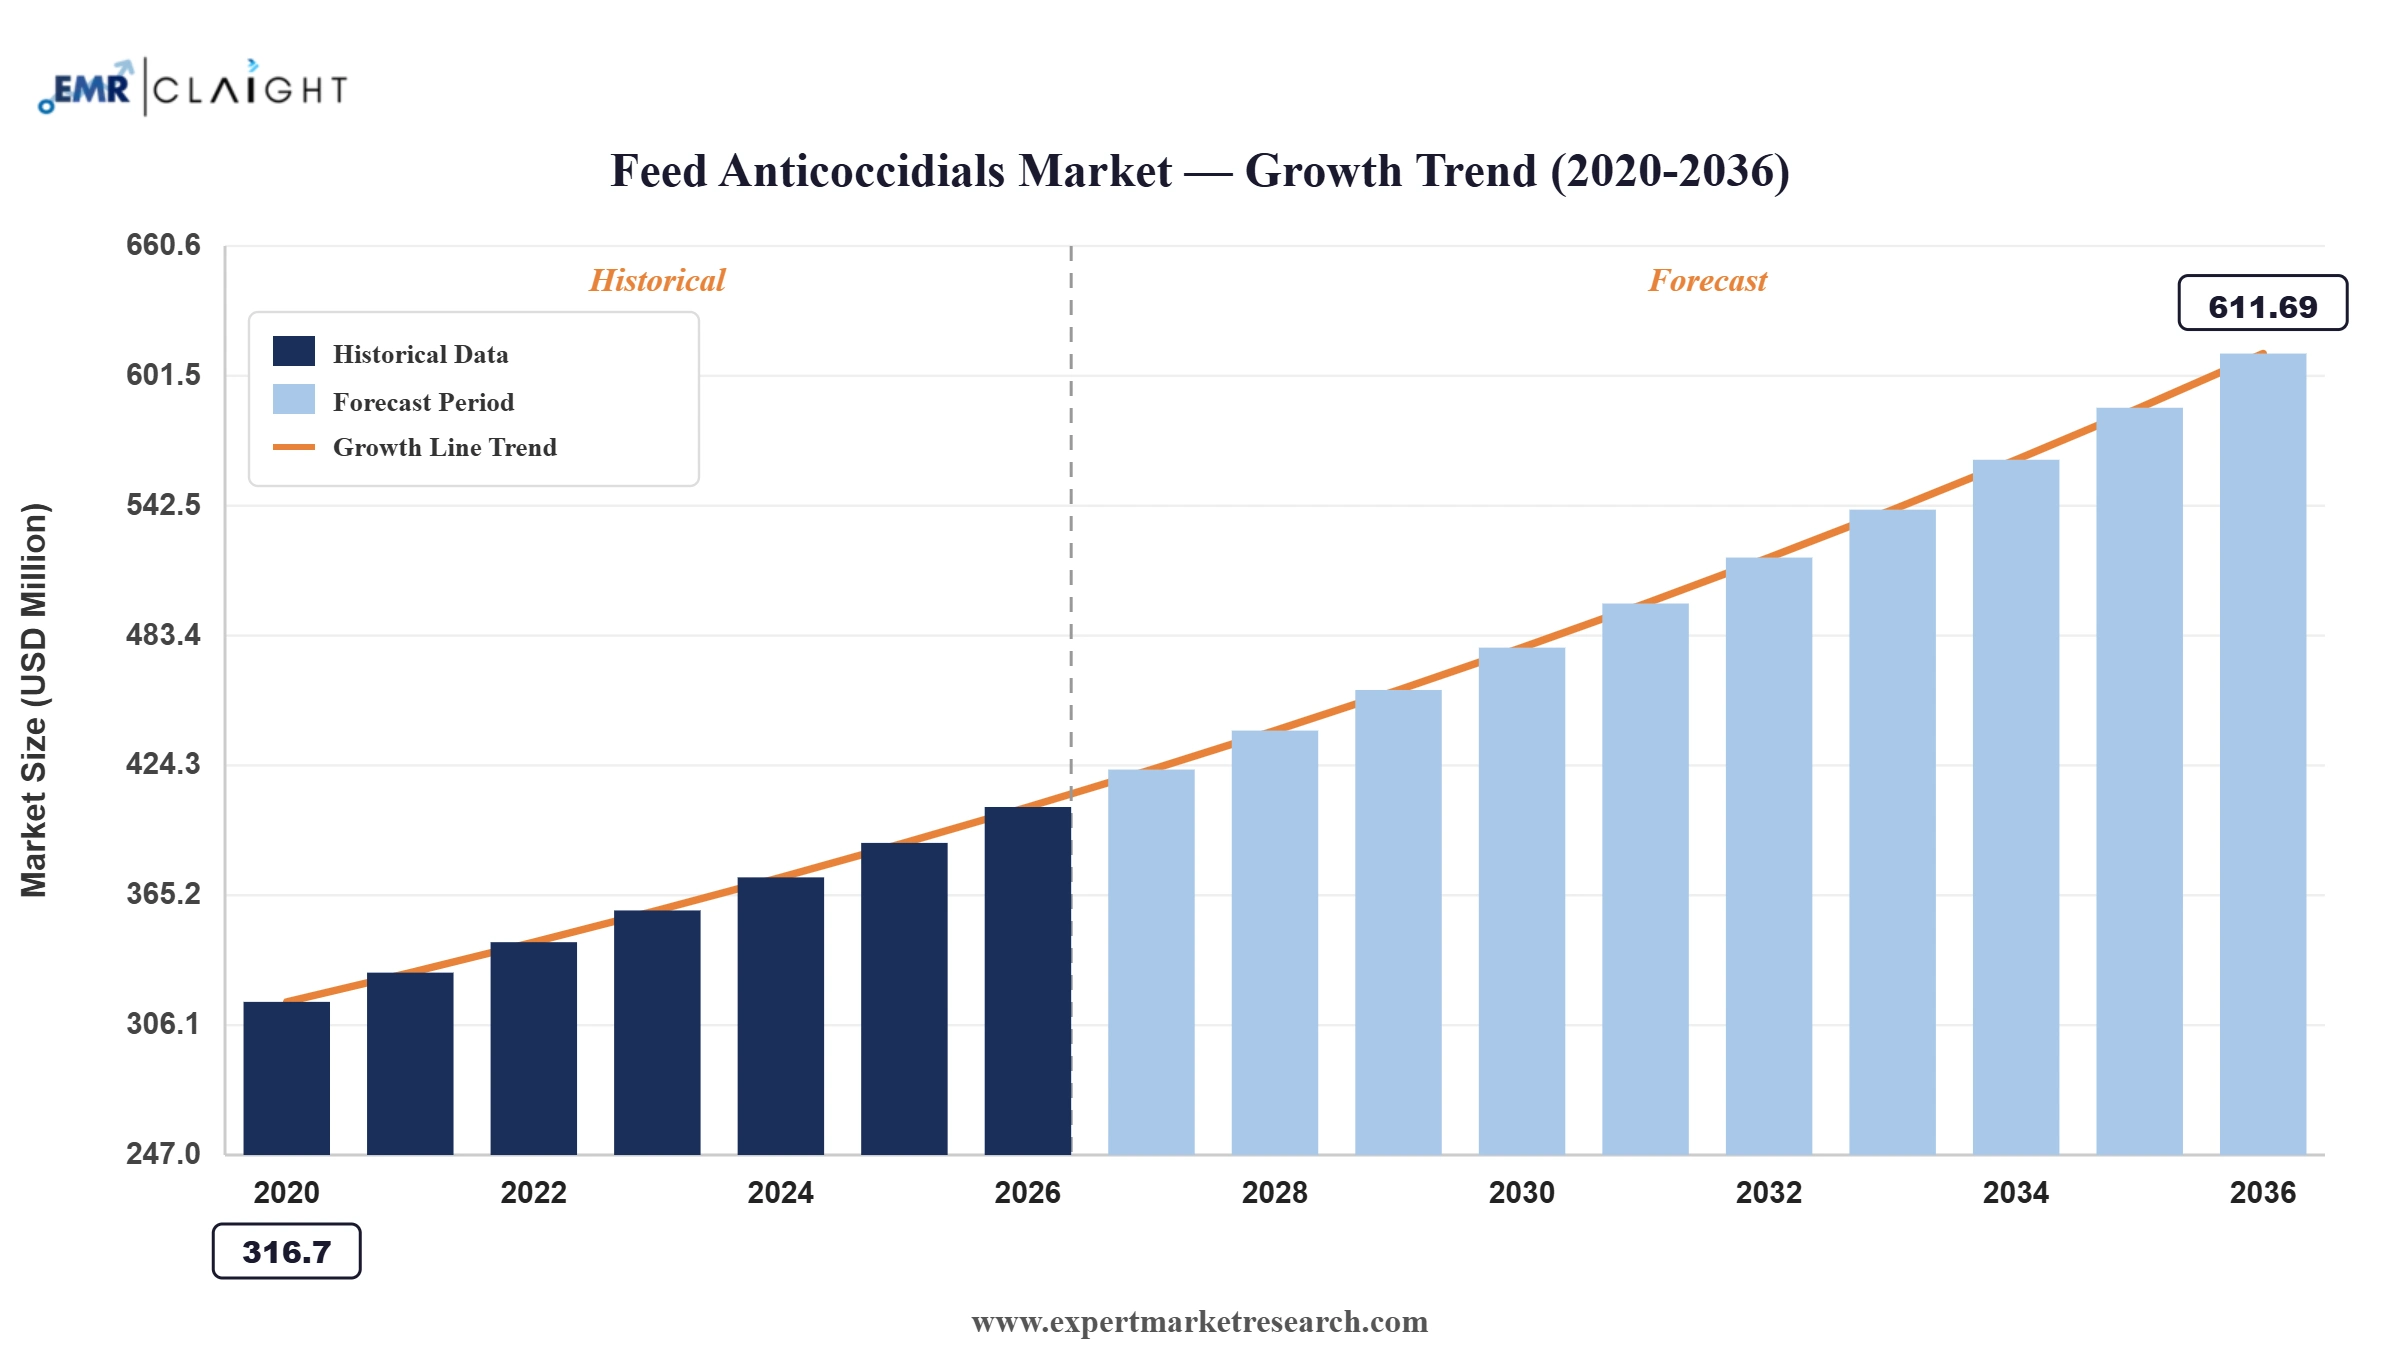
The global feed anticoccidials market attained a value of USD 389.03 Million in 2025 and is projected to grow at a CAGR of 4.20% through 2035. The market is further expected to reach USD 587.03 Million by 2035. Rising poultry production, resistance management through rotation programs, and tighter feed antibiotic rules are supporting growth in the market.
Feed anticoccidials are additives mixed into poultry, swine, and ruminant feed to prevent coccidiosis, a gut disease caused by Eimeria parasites that cuts growth and feed efficiency. Producers choose between ionophores, chemical agents, and natural products, often rotating them across flocks. Demand follows poultry production, farming intensity, and rules on antibiotic use. Suppliers sell premixes through feed mills and integrators, and revenue is supported by regulatory approvals, field trials, technical service, and long-standing relationships with large global poultry integrators.
Animal health groups continue to report steady livestock demand. In September 2026, Virbac reported first half revenue growth of 7.4% at constant scope and exchange rates, with its Mobility and Ruminants ranges supporting growth, and said it now targets the top of its 2026 guidance range. Farm animal health spending supports regular purchases of preventive products, and demand for feed anticoccidials benefits as producers protect flock and herd performance. Vaccination, treatment, and feed additive purchases follow herd and flock cycles.
Leading suppliers across the feed anticoccidials market are building scale through portfolio purchases and regional manufacturing, while spending on resistance management and non-antibiotic alternatives rises. In August 2026, Phibro reported fiscal 2026 net sales of USD 1,518.1 million, up 17%, as its medicated feed additive and other products group grew 25%. Competitive positioning increasingly rests on range breadth, regulatory approvals, technical service, and reliable supply to large integrators. Suppliers also invest in vaccines, natural products, and technical service to support producers through changing rules.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The company gained European Union authorisation for Interban, a coccidiostat containing narasin and diclazuril for chickens reared for fattening and for laying, valid until 2036. The approval gives poultry producers a combination product for rotation programs. Firms across the feed anticoccidials market filing combination dossiers early can secure approved options ahead of rivals and spread resistance risk across several major producing regions.
The company announced completion of the purchase of a Dutch farm animal health innovator whose plant derived technologies aim to cut disease pressure and antibiotic use in dairy herds. The purchase strengthens its ruminant position in global markets. Buyers across the feed anticoccidials market of specialist natural product developers can add non antibiotic options to existing herd health ranges quickly and cheaply.
The company announced an agreement to sell the unit at an enterprise value of about EUR 2.2 billion, including an earnout of up to EUR 0.5 billion, with closing expected by the end of 2026. The unit will split into two standalone companies. Carve outs like this free specialist additive businesses for new owners and sharper strategies.
Hysolv launched Alquernat Zycox, a pronutrient feed additive developed by Biovet and offered as an alternative to chemical coccidiostats for broilers, supplied as a premix with a companion drinking water product and no withdrawal period. Pairing feed and water products lets suppliers cover late cycle disease control, so antibiotic free broiler programs gain a practical new option across the feed anticoccidials market.
Fermentation is the base process for ionophore anticoccidials, so capacity matters. Suppliers are buying sites to raise output and develop new formulations. In July 2026, Huvepharma signed an agreement to acquire 100% of Euroapi Italy, including the Brindisi fermentation site, which lifts its fermentation capacity by 25% to more than 12,000 cubic meters, subject to closing conditions. Feed mills gain steadier supply of actives, while smaller rivals may face tighter access to contract capacity for new formulations over coming years.
Feed additive suppliers across the feed anticoccidials market are buying early-stage science to widen gut health offers beyond chemical agents. In August 2025, Kemin acquired Bactana, a Cornell licensed biotechnology company developing postbiotic products for gut and metabolic health in livestock and companion animals. The deal adds microbiome expertise to its research pipeline. Targets gain manufacturing, regulatory, and distribution support, while integrators may see more non antibiotic options entering rotation programs over coming years. Small firms lack plants or approvals, so buyers supply both.
Governments across the feed anticoccidials market continue to restrict antimicrobials used as growth promoters, and producers respond by tightening gut health programs. In April 2026, the agriculture ministry of Brazil published Portaria 1.617/2026, which banned avoparcin, bacitracin, and virginiamycin as growth promoters, while avilamycin, enramycin, flavomycin, and halquinol remain allowed. Exporters supplying global poultry buyers face closer scrutiny, and feed formulators gain reasons to review coccidiosis control programs. A phased transition covers existing stocks of the affected products, giving feed makers time to adjust formulations.
Quarterly results show how strongly poultry health products are selling across the feed anticoccidials market. In May 2026, an animal health leader reported first quarter farm animal revenue of USD 642 million, up 18%, with poultry rising 22% to USD 230 million, and cited strong demand led by poultry and ruminants. Strong volumes suggest producers keep investing in flock health, and suppliers may add capacity to meet demand. Swine revenue also rose 13% to USD 96 million, while cattle rose 16% to USD 316 million.
Second quarter results show animal health spending is holding up across the feed anticoccidials market. In August 2026, Zoetis reported livestock revenue up 12% to USD 731 million, with poultry up 11% on higher vaccine sales linked to disease outbreak activity, while cattle revenue rose 21%. Producers facing outbreaks may widen preventive budgets, which supports sales of feed additives, and suppliers may expand technical support programs for integrators. Total company revenue was USD 2,468 million, flat year over year, with livestock the faster growing area.
The Expert Market Research's report titled "Global Feed Anticoccidials Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
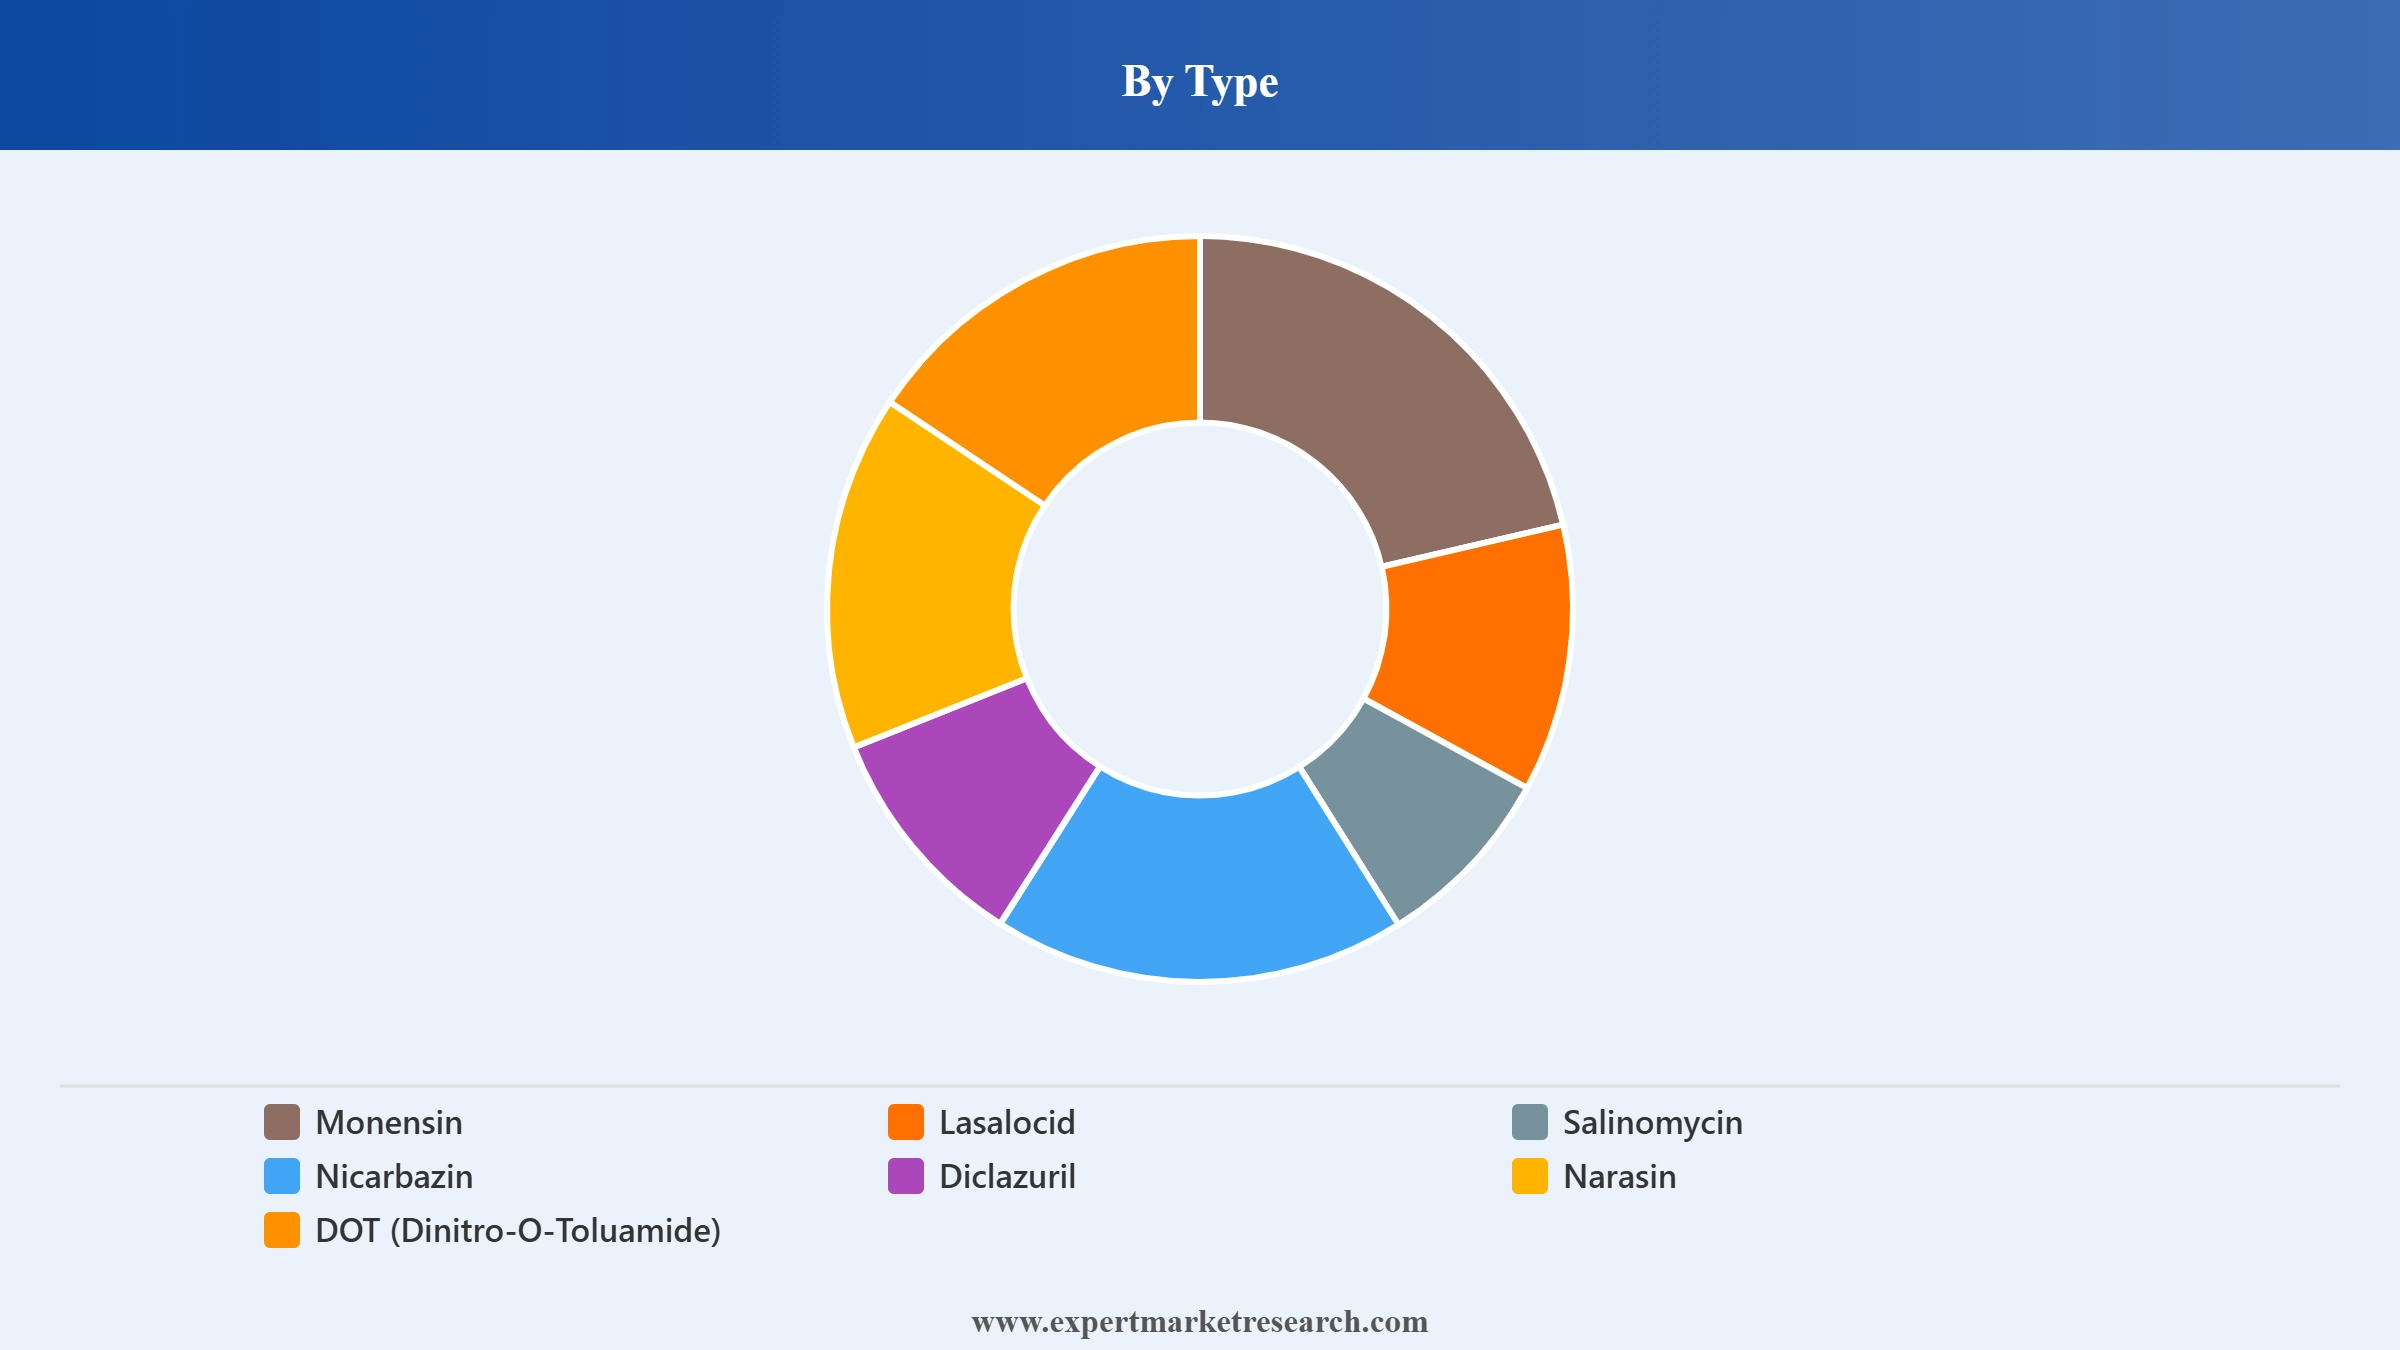
Key Insight: Monensin leads the type segment of the feed anticoccidials market, since this ionophore has long served poultry, cattle, and goat producers with a low resistance risk. Diclazuril is expected to grow fastest, as shuttle programs bring in a chemical agent late in each production cycle. Lasalocid suits poultry and cattle rations, salinomycin and narasin serve broilers, and nicarbazin is often paired with narasin for stronger control. DOT fills rotation gaps, while others include amprolium and robenidine. Producers pick agents by cost, withdrawal period, and local approvals.
Market Breakup by Livestock
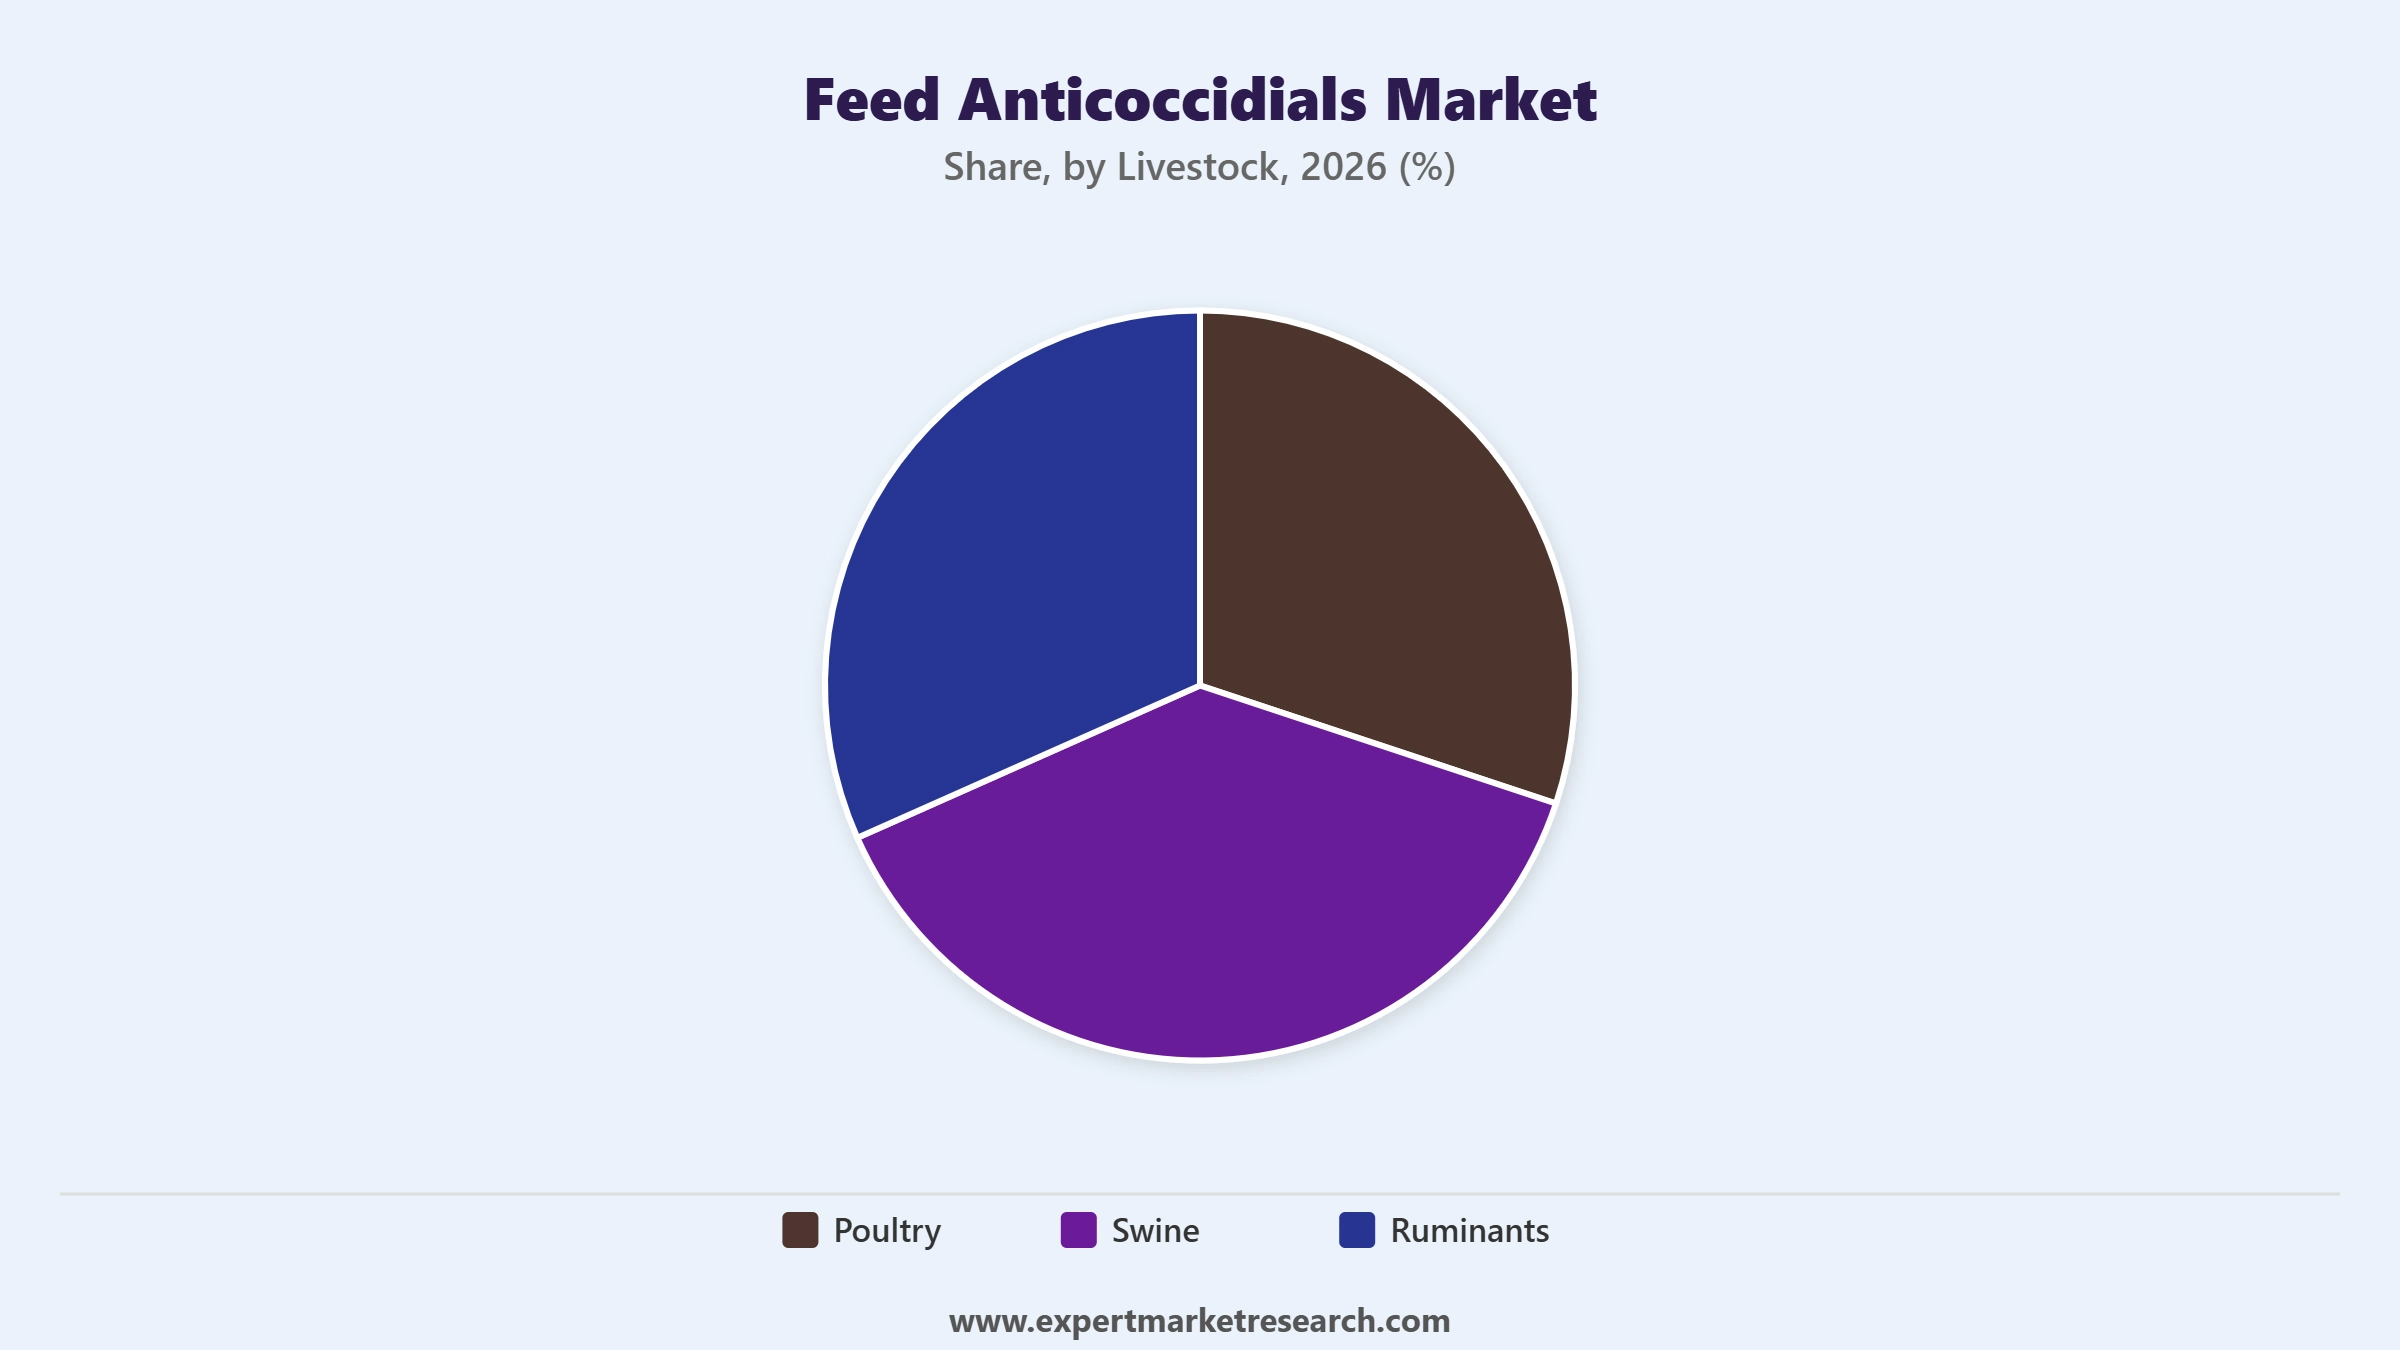
Key Insight: Poultry leads the livestock segment of the feed anticoccidials market, as broilers, layers, and turkeys raised on litter face constant exposure to Eimeria and rely on feed borne control. Ruminants are expected to grow fastest, as cattle, sheep, and goat keepers start early protection for young stock. Swine producers use anticoccidials mainly for piglets, and others include rabbits and farmed game that need species specific doses. Label restrictions differ by species, and some ionophores are unsafe for horses, so approvals shape product choice in each country.
Market Breakup by Form
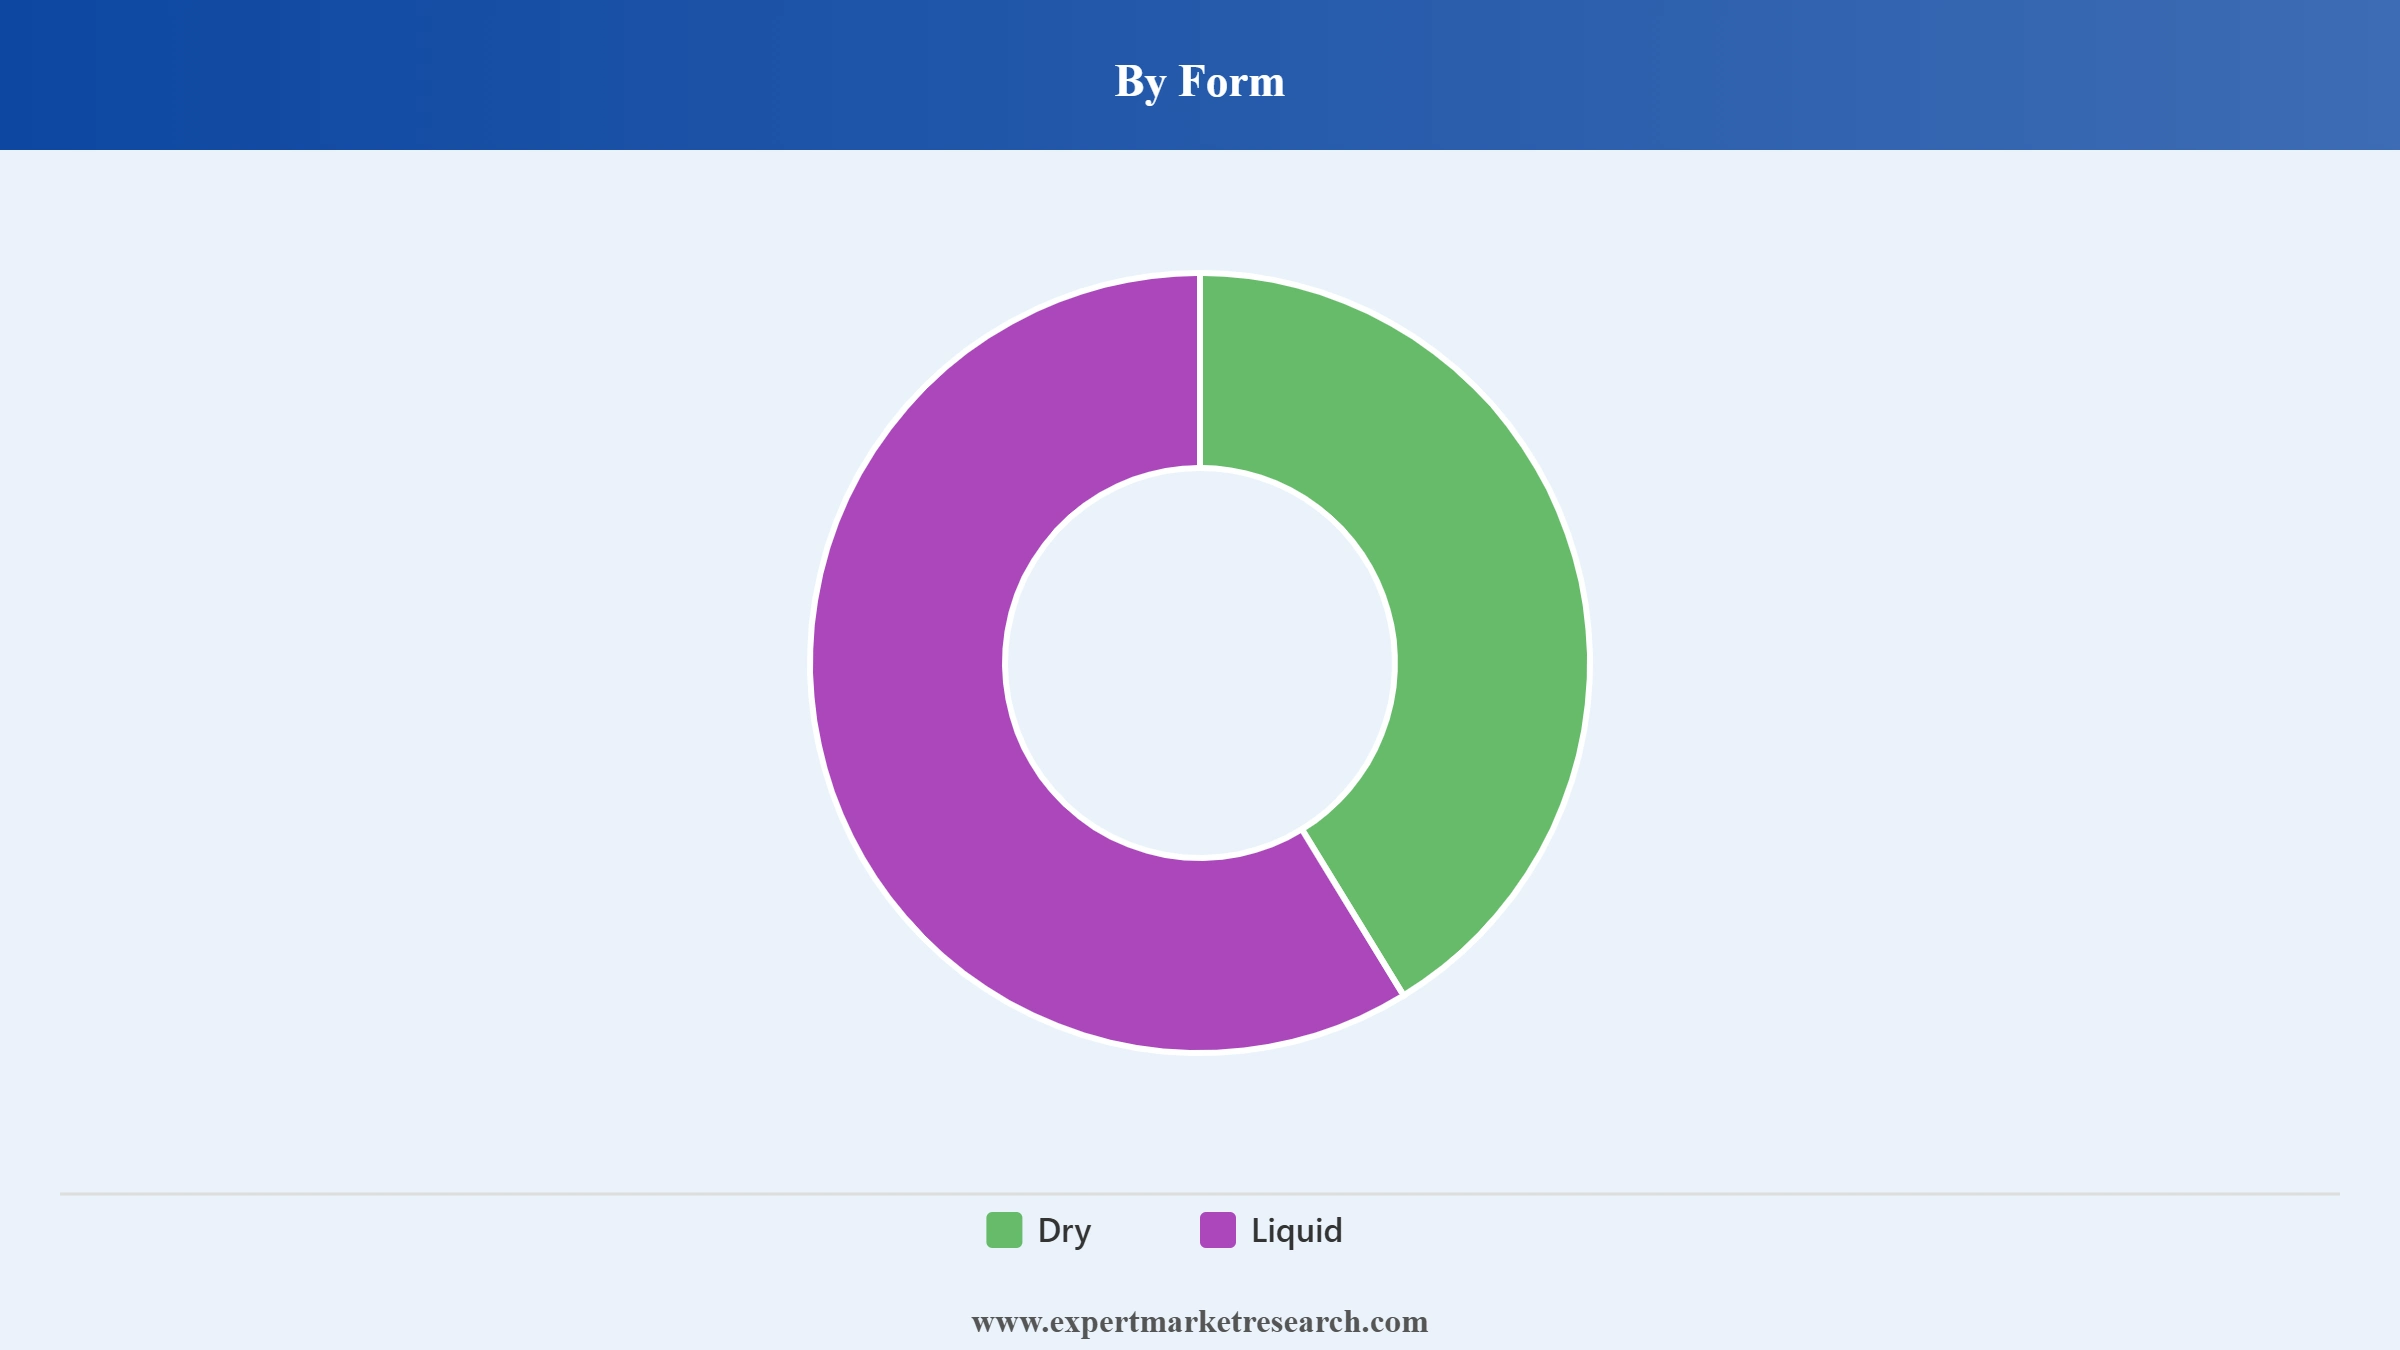
Key Insight: Dry leads the form segment of the feed anticoccidials market, because premixes and medicated articles are blended into mash and pellets at feed mills with accurate dosing and long shelf life. Liquid is expected to grow fastest, as drinking water systems let farms treat flocks quickly when disease appears and adjust doses without changing feed. Dry products suit large integrators operating their mills, while liquids suit small farms and young breeding flocks. Stability, mixing quality, and ease of handling decide which form buyers choose for each site.
Market Breakup by Source
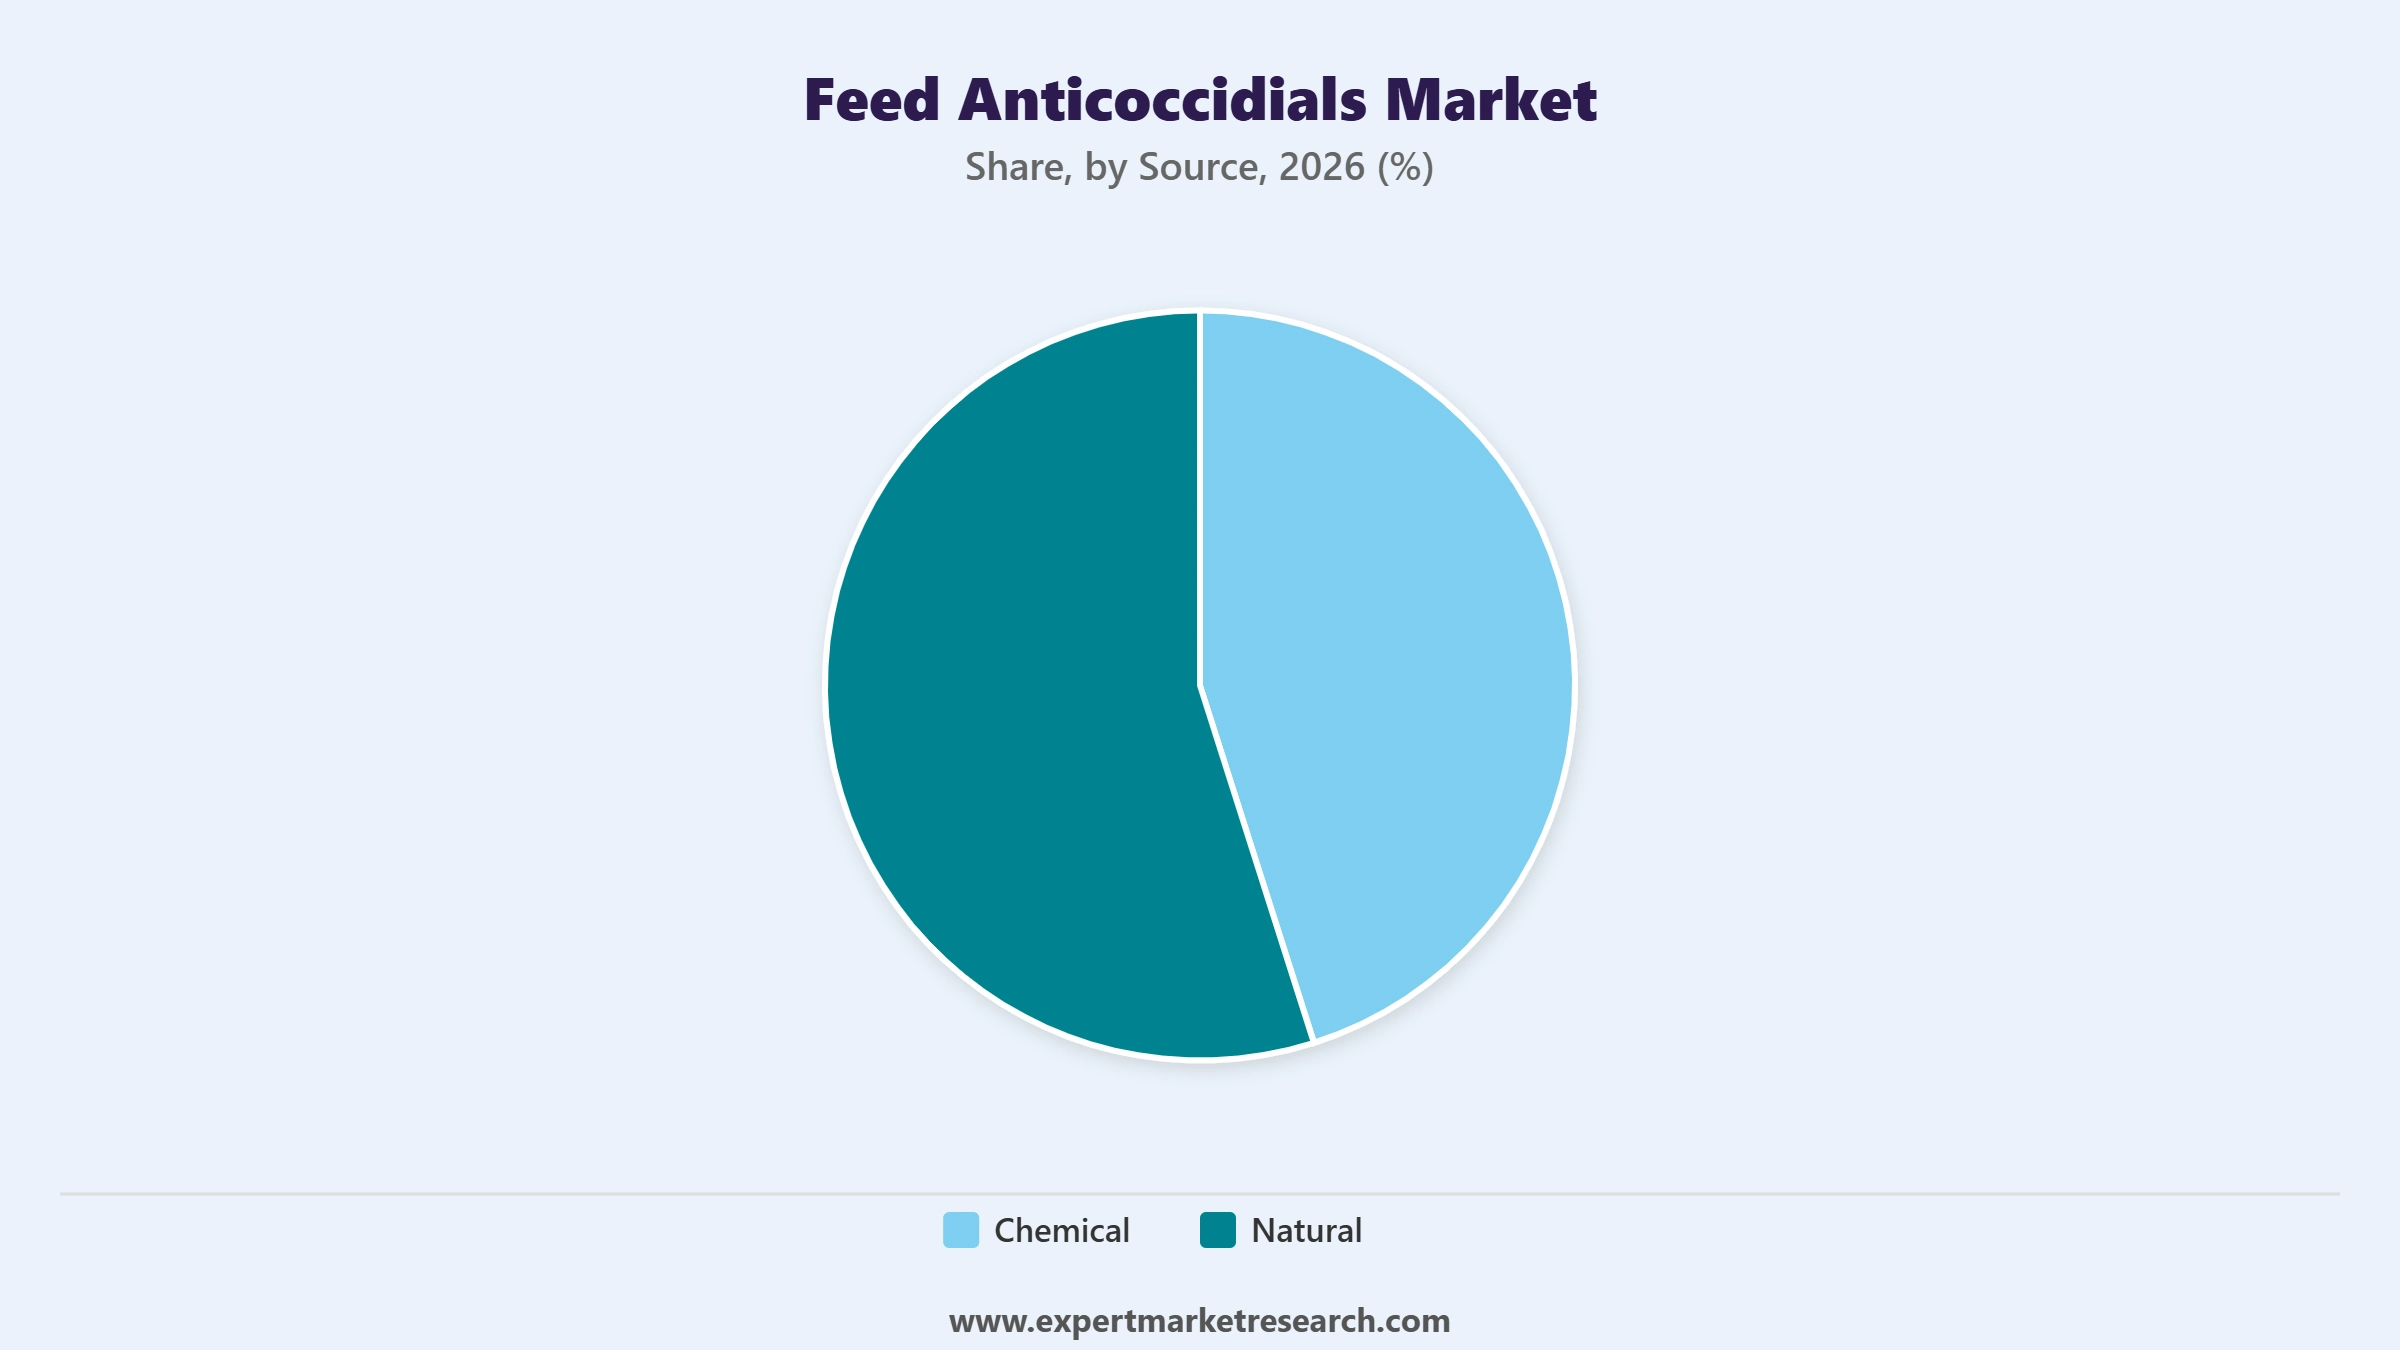
Key Insight: Chemical leads the source segment of the feed anticoccidials market, as these drug classes combine reliable efficacy, predictable cost, and decades of regulatory history in poultry and ruminant feed. Natural is expected to grow fastest, as retailers and brands selling antibiotic free meat ask for botanical blends and pronutrients that fit label claims. Chemical products dominate large commercial flocks and are rotated to manage resistance, while natural products are used alongside vaccines or in organic systems. Cost, field trial proof, and withdrawal need guide the choice.
Market Breakup by Mode of Consumption
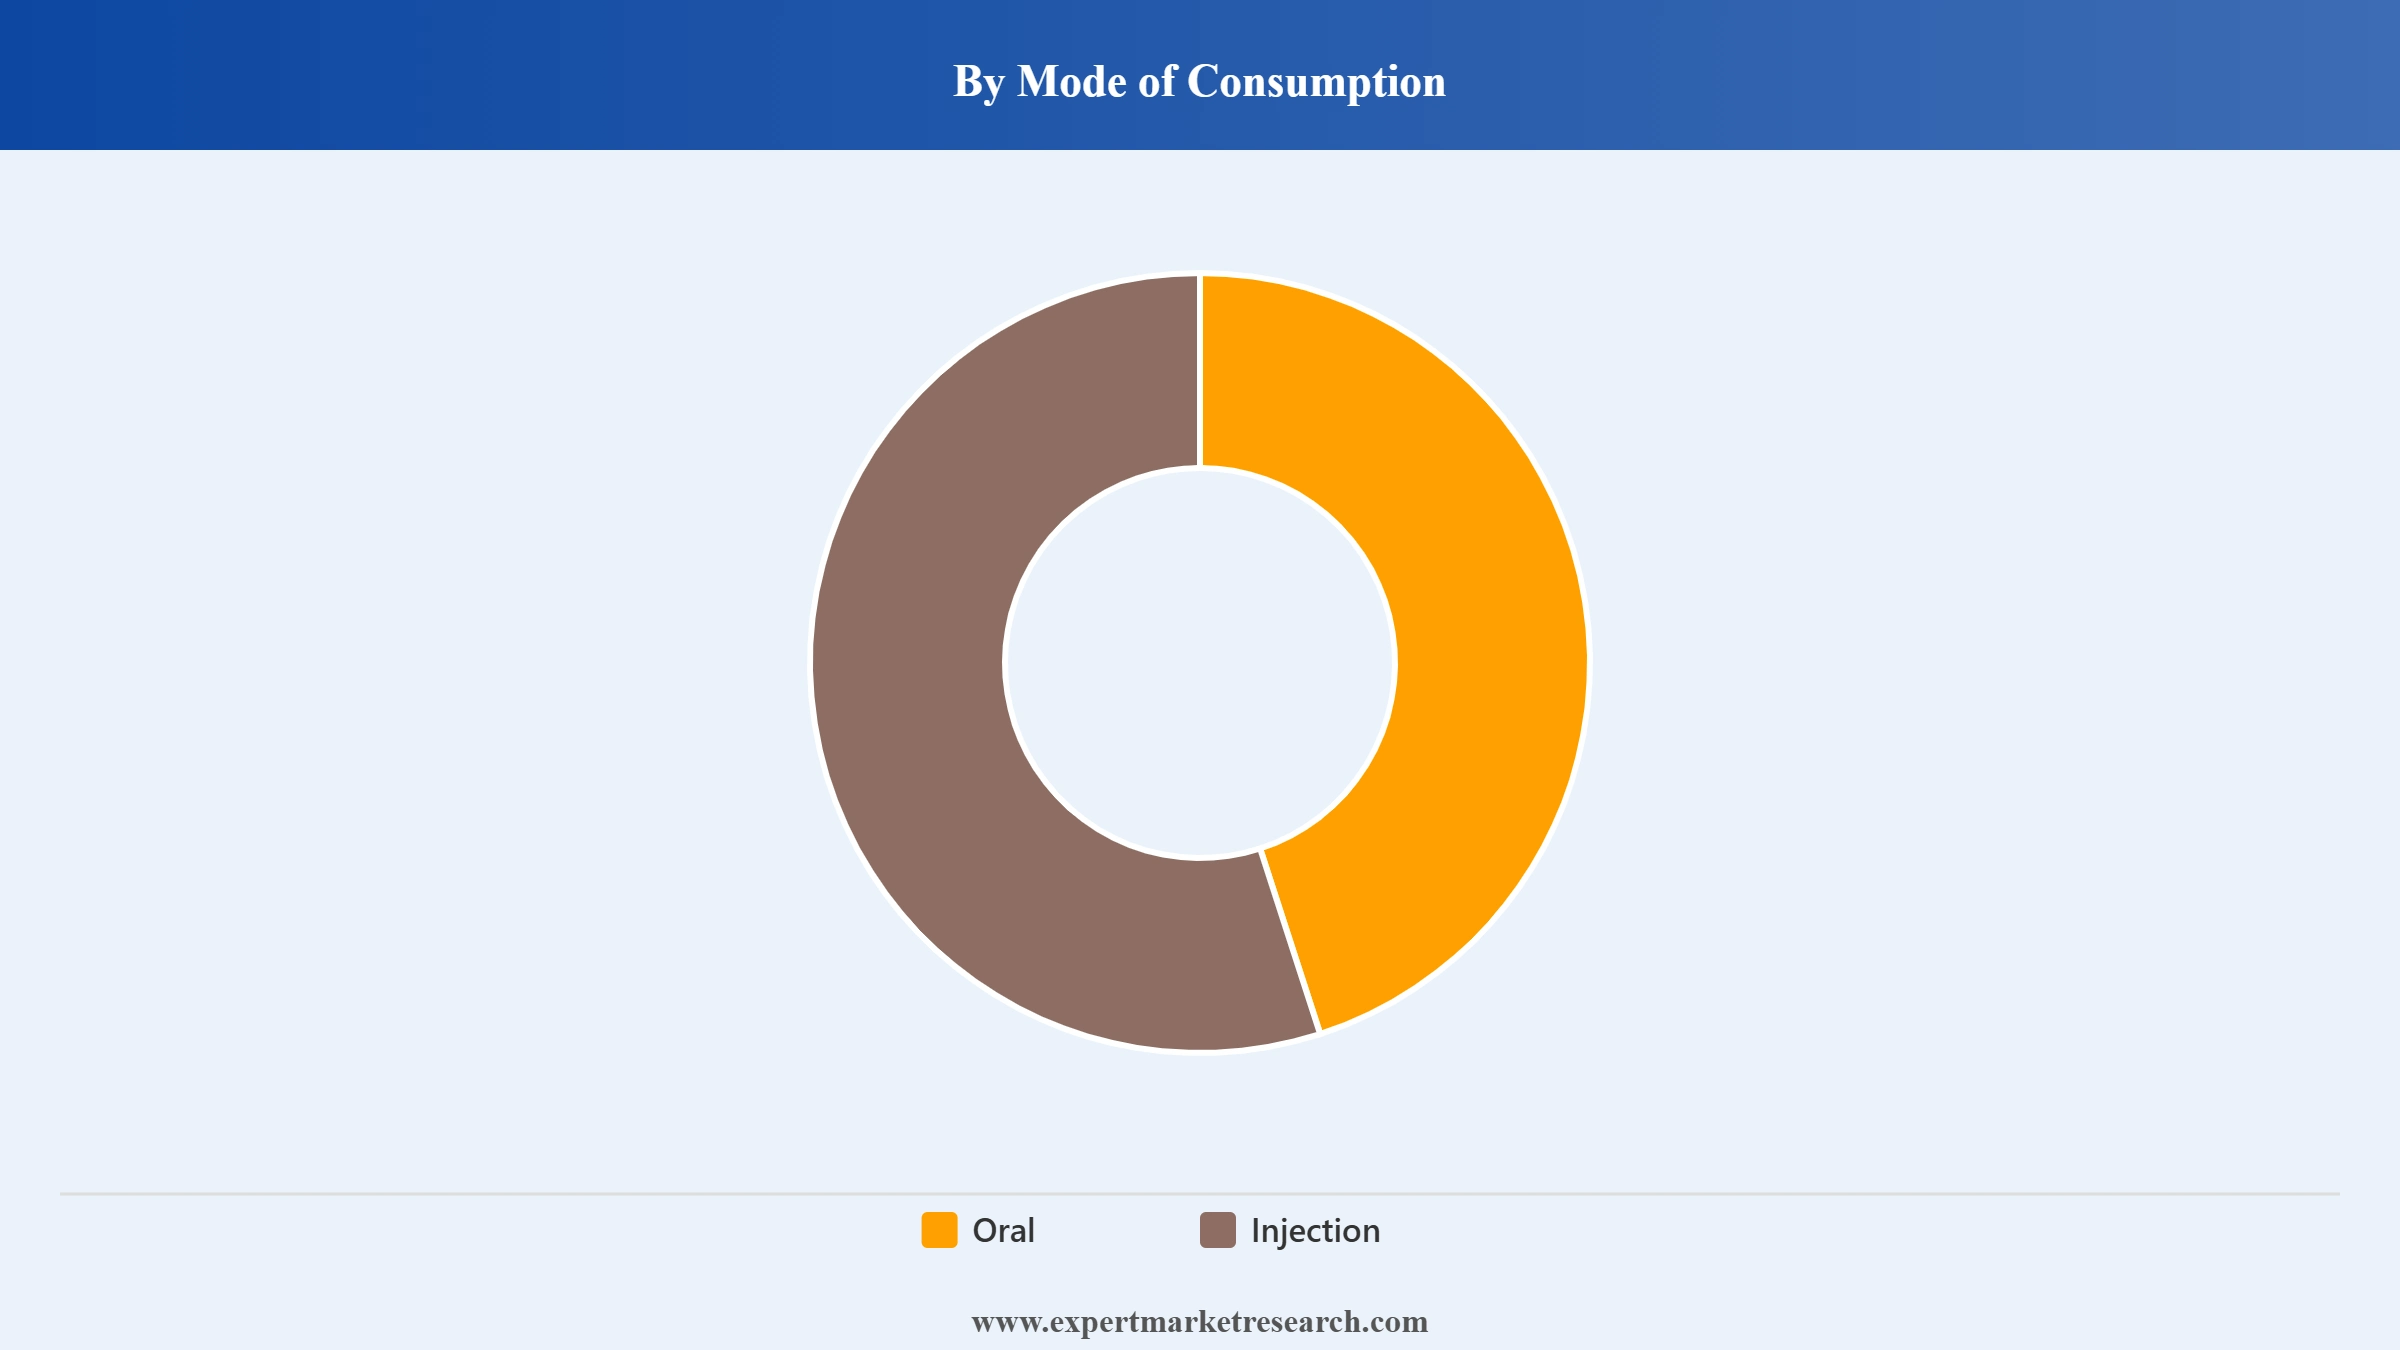
Key Insight: Oral leads the mode of consumption segment of the feed anticoccidials market, because feed and water delivery reach whole flocks and herds with little labor and fit existing mills. Injection is expected to grow fastest from a small base, as care for single calves and piglets gains attention where outbreaks occur. Oral options include medicated premixes, soluble powders, and boluses, while injections suit valuable breeding stock and animals unable to eat. Labor needs, skilled staff, and veterinary oversight limit the use of injections in large commercial flocks.
Market Breakup by Region
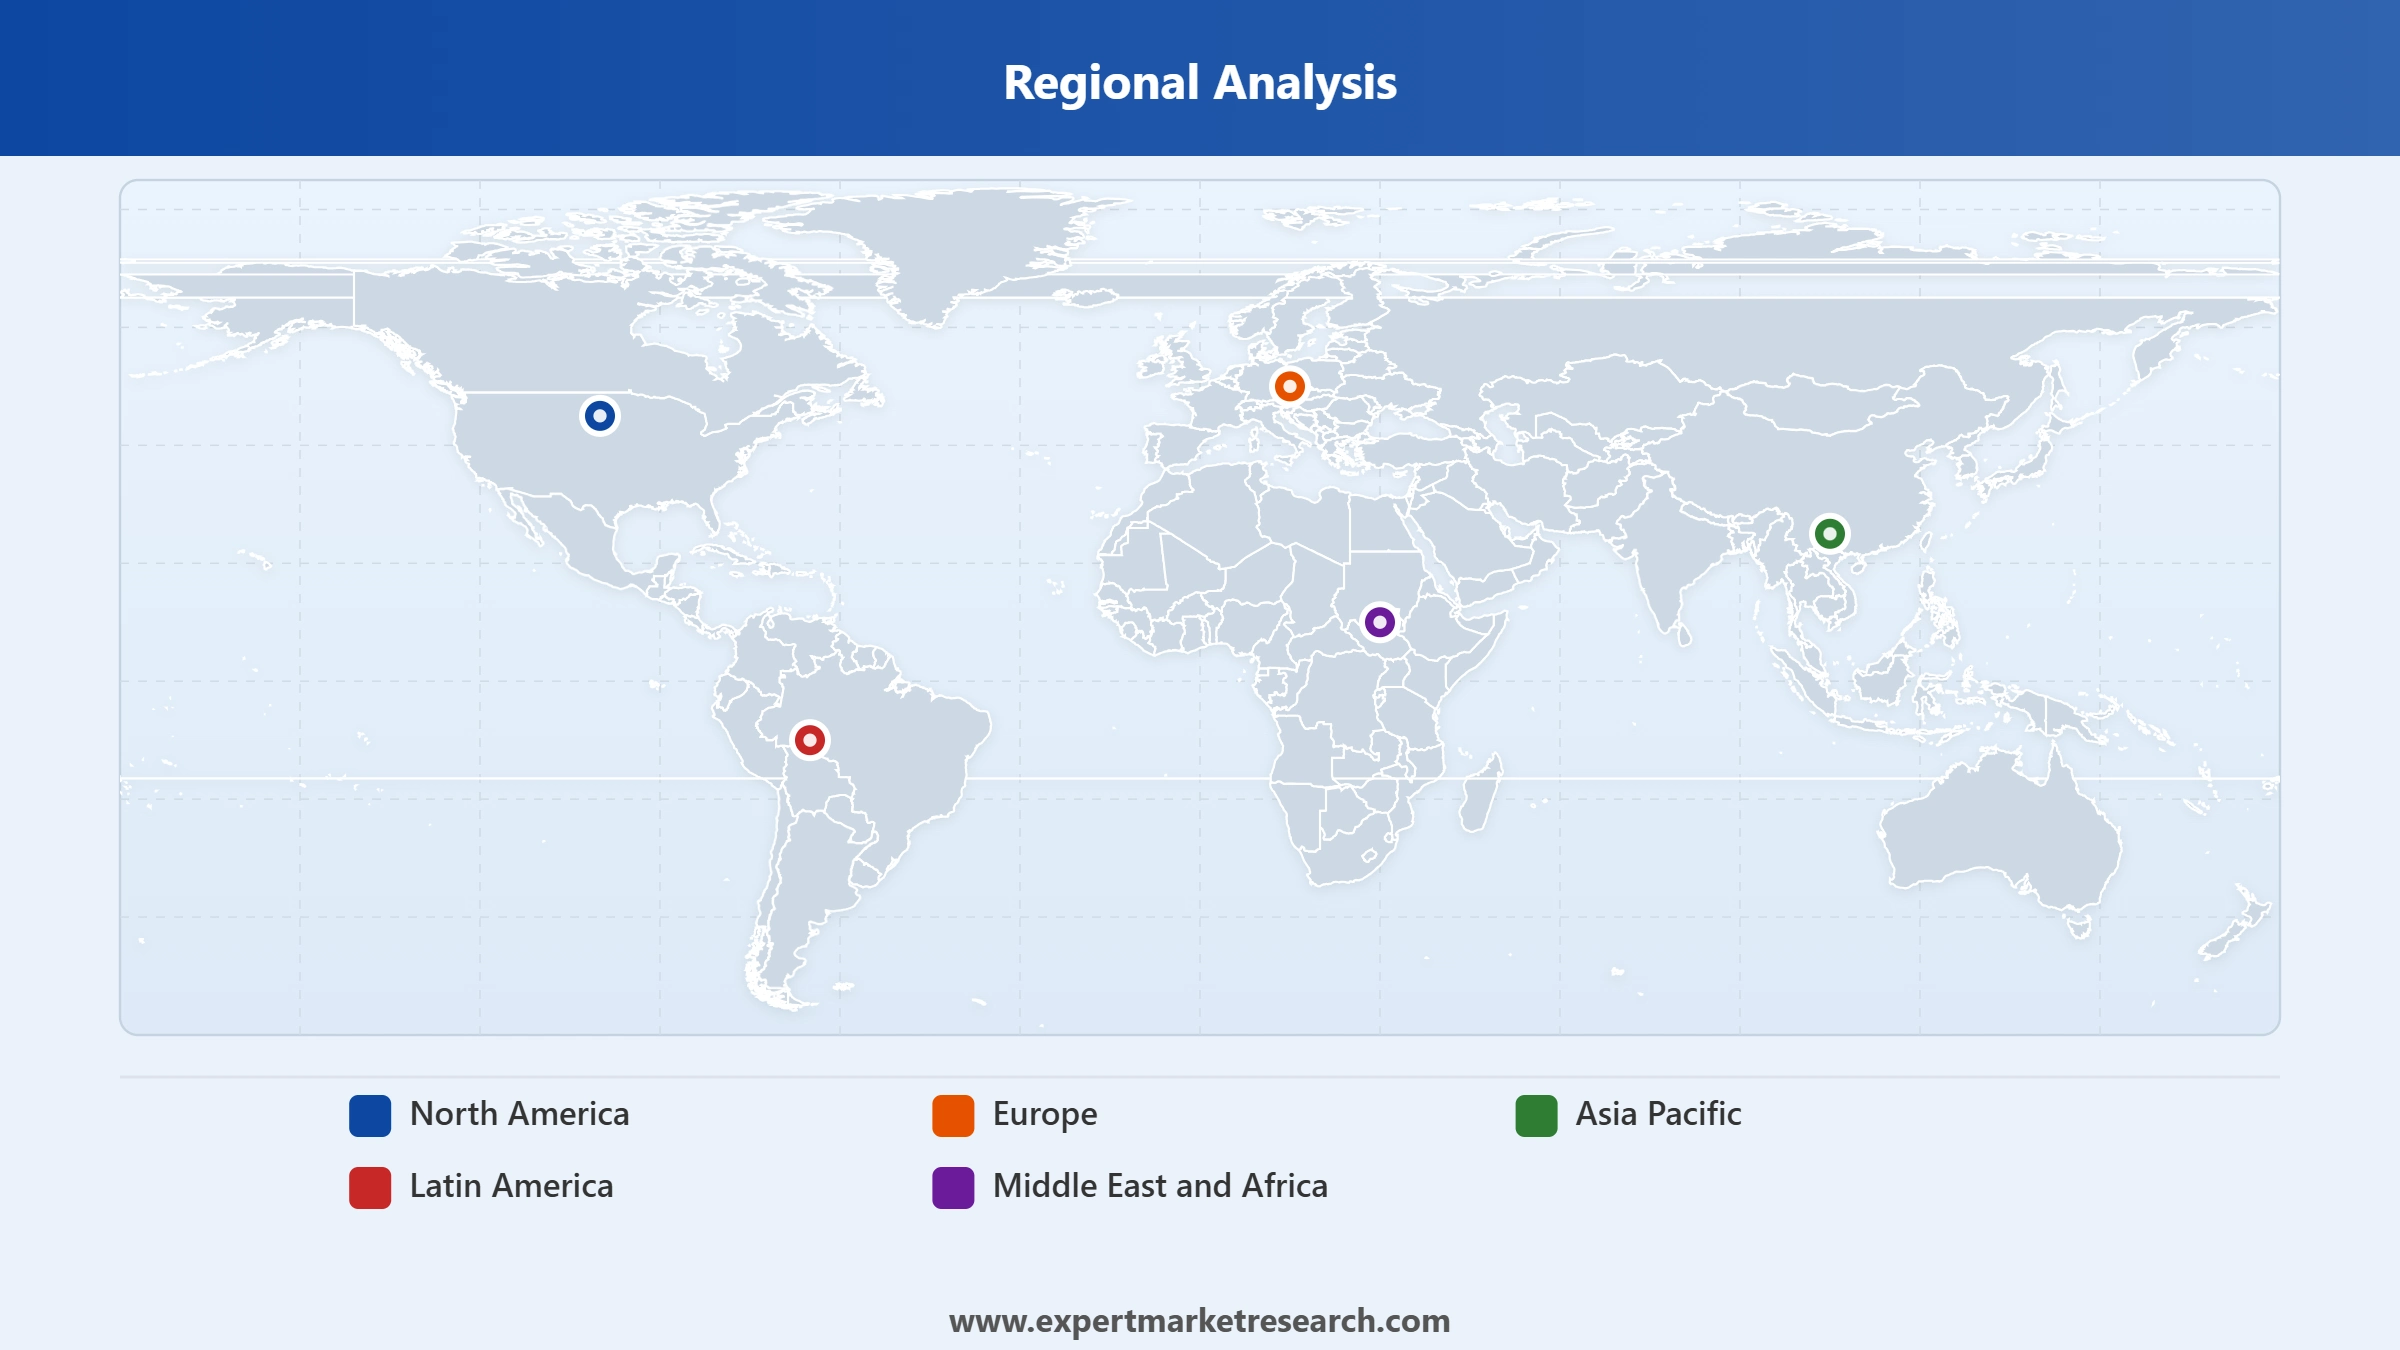
Key Insight: Asia Pacific leads the regional landscape of the feed anticoccidials market, backed by large poultry and swine output in China, India, and ASEAN. Latin America is expected to grow fastest, as Brazil and Mexico expand broiler exports and tighten antimicrobial rules. North America relies on ionophore and chemical rotation programs in a mature broiler sector, Europe follows strict approval and residue rules for coccidiostats, and Middle East and Africa grow with new poultry integrations and rising local meat demand and import needs across the region.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By type, monensin dominates the feed anticoccidials market owing to its long-proven efficacy across poultry and ruminants
Monensin holds the largest share of the type segment in the feed anticoccidials market, because it has controlled coccidiosis in chickens, turkeys, and cattle for decades and fits low-cost programs at feed mills. Resistance builds slowly against ionophores, so many integrators keep monensin in rotation and in shuttle plans. Its broad label across species, strong safety record at approved doses, and wide supplier base keep prices stable, while formulators trust its record when planning programs for broiler and turkey cycles in major producing regions.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Diclazuril is registering the fastest growth within the type segment, as chemical agents are added to the final weeks of a production cycle in shuttle programs. It works at very low inclusion rates, which suits modern premix systems and combinations with ionophores. In October 2026, dsm-firmenich launched AccuGut C.1, a eubiotic intestinal health solution meant to complement anticoccidial programs, targeting clinical and subclinical coccidiosis in flocks where Eimeria shows reduced sensitivity to older agents. It is positioned beside existing rotations.
By livestock, poultry dominates the feed anticoccidials market owing to dense housing and constant Eimeria exposure
Poultry holds the largest share of the livestock segment, because broilers, turkeys, and breeders are raised in dense houses where Eimeria spreads quickly through litter. Feed borne control is the standard defense in most countries, and integrators plan programs flock by flock to safeguard growth rates and feed conversion. Large global poultry output, short production cycles, and frequent restocking create regular purchases of premixes. Rules on withdrawal periods and residues shape product selection, and large integrators negotiate supply contracts directly.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Ruminants are registering the fastest growth within the livestock segment, as cattle, sheep, and goat producers adopt preventive programs for calves, lambs, and kids. Coccidiosis in young ruminants causes diarrhea, weight loss, and deaths, and growing dairy and beef herds raise awareness of early protection. In January 2026, a cattle health supplier described early United States uptake of Pradalex, an injectable fluoroquinolone labeled for calf pneumonia in dairy and beef herds, which signals strong herd health spending across major markets.
By form, dry dominates the feed anticoccidials market owing to easy blending into mash and pellet feed at commercial mills
Dry holds the largest share of the form segment, because premixes, granules, and medicated articles blend easily into mash and pellet feed at commercial mills. These products offer long shelf life, stable potency, and accurate dosing across large batches. Integrators with their own feed mills prefer dry forms, which move easily through existing storage and mixing equipment. Suppliers also sell carriers that limit dust and static, and mill operators value standard handling, record keeping, and compliance with medicated feed rules.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Liquid is registering the fastest growth within the form segment, as water-based delivery lets farms respond quickly when disease signs appear. Liquids can be added through medicators and dosing pumps without changing feed orders, which suits small farms, breeders, and replacement stock. Dosage can be adjusted daily. In September 2026, the American Feed Industry Association held its Liquid Feed Symposium in Kansas City, Missouri, where 149 attendees reviewed vitamin stability in liquid feed and cattle health and feeding programs.
By source, chemical dominates the feed anticoccidials market owing to proven efficacy and low cost per ton of feed
Chemical holds the largest share of the source segment, because ionophores and synthetic agents offer proven efficacy, low cost per ton of feed, and long regulatory records. Large commercial flocks depend on these products, which are approved in many countries and backed by decades of field data. Rotation between chemical agents manages resistance, and technical teams at suppliers help integrators design programs. Competitive pricing among established manufacturers keeps chemical products the default choice for most commercial poultry and cattle producers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Natural is registering the fastest growth within the source segment, as antibiotic free brands, retailers, and consumers ask for botanical extracts, oil blends, and pronutrients in place of drugs. Such products carry no withdrawal period and fit organic and vaccinated flocks. Evidence from field trials remains uneven. In November 2025, CJ BIO presented Coxield, a plant-based anticoccidial screened from more than 600 compounds, reporting lower lesion scores than salinomycin in broiler challenge trials against Eimeria tenella and no residues.
By mode of consumption, oral dominates the feed anticoccidials market owing to easy delivery through feed and drinking water
Oral holds the largest share of the mode of consumption segment, because feed and drinking water reach every bird or animal with little labor. Premixes, water soluble powders, and boluses fit existing mills and farm equipment, and dosing can be matched to feed intake. Veterinary oversight is lighter than for injected drugs, which suits large flocks and herds. Oral delivery also costs less per animal, and it supports preventive programs that run for the whole duration of a flock cycle.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Injection is registering the fastest growth within the mode of consumption segment, from a much smaller base, as treatment of individual animals gains attention in calves and piglets. Injectable products give a precise dose to sick animals and can act faster than feed-based control. Use stays limited by handling effort and veterinary supervision. In February 2025, a New Jersey animal health company will market Loncor 300, an injectable florfenicol for cattle, after acquiring the marketing rights from a rival.
Asia Pacific commands the largest regional share of the feed anticoccidials market, supported by large poultry and swine output
Asia Pacific commands the largest regional share of the feed anticoccidials market, supported by heavy poultry and pig production in China, India, and other economies, alongside rapid growth of integrated broiler farming. Domestic producers manufacture bulk ionophore and chemical actives locally, while multinational firms distribute premixes via local feed mills. In May 2026, a Bulgarian animal health group and Qilu Tsingta partnered through a Shandong joint venture to commercialize coccidiosis vaccines in China, adding a biological option beside feed additives.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Latin America is registering the fastest growth among the regional markets, driven by broiler exports from Brazil, rising poultry output in Mexico and Argentina, and tighter rules on antimicrobial use in feed. Large integrators in the region run rotation and shuttle programs to protect weight gain and meet export standards. Local feed mills are widening use of ionophores and chemical agents, while importers look for natural alternatives that meet buyer requirements. New broiler complexes support steady demand across the region.
The competitive landscape is concentrated at the top, with a few global feed anticoccidials companies holding approvals, plants, and customer ties alongside many regional producers. Established feed anticoccidials companies compete on efficacy data, regulatory dossiers, price, technical service, and supply reliability. Large groups offer broad ranges of ionophore and synthetic drugs, while smaller firms focus on single actives, generics, or natural products. Stringent registration rules and the cost of residue studies act as barriers for new entrants.
Leading feed anticoccidials market players are pursuing portfolio purchases, manufacturing investments, and combination product approvals to defend share. Several feed anticoccidials players are also adding natural alternatives, vaccines, and flock monitoring services to support rotation programs. Investment in fermentation capacity and regional plants is rising as customers seek secure supply. Partnerships with vaccine developers, integrators, and distributors help suppliers reach Asia Pacific and Latin America, where poultry output is expanding fastest.
Founded in 1954 and headquartered in Indianapolis, Indiana, United States, the company supplies the market through ionophore and combination products such as Coban and Maxiban for poultry. It also sells other farm animal and pet health products across global markets.
Founded in 1946 and headquartered in Teaneck, New Jersey, United States, the company supplies the market through products including Nicarb, Aviax, Coxistac, and Avatec for poultry, cattle, and other livestock. It also sells medicated feed additives and nutritional specialties.
Founded in 1952 and headquartered in Parsippany, New Jersey, United States, the company supplies the market through livestock vaccines and animal health products. It serves poultry, cattle, and swine producers worldwide.
Founded in 1961 and headquartered in Des Moines, Iowa, United States, the company supplies the market through animal nutrition and health ingredients for poultry and livestock producers. It serves feed and food customers in many countries.
Other key players in the market include Huvepharma EOOD, Qilu Animal Health Products Co., Ltd., Virbac S.A., and Merck Animal Health, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global feed anticoccidials market trends 2026 report. Discover regional growth patterns, types, livestock, forms, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market. Request a customised quote to align the findings with your own business planning.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of USD 389.03 Million in 2025.
The market is projected to grow at a CAGR of 4.20% between 2026 and 2035, reaching USD 587.03 Million by 2035.
Monensin leads the market by type, while diclazuril is expected to grow fastest.
The key players in the market include Elanco, Huvepharma EOOD, Phibro Animal Health Corporation, Zoetis Services LLC, Kemin Industries, Inc., Qilu Animal Health Products Co., Ltd., Virbac S.A., and Merck Animal Health, among others.
Asia Pacific leads the market by region, while Latin America is registering the fastest growth.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Livestock |
|
| Breakup by Form |
|
| Breakup by Source |
|
| Breakup by Mode of Consumption |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




