

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
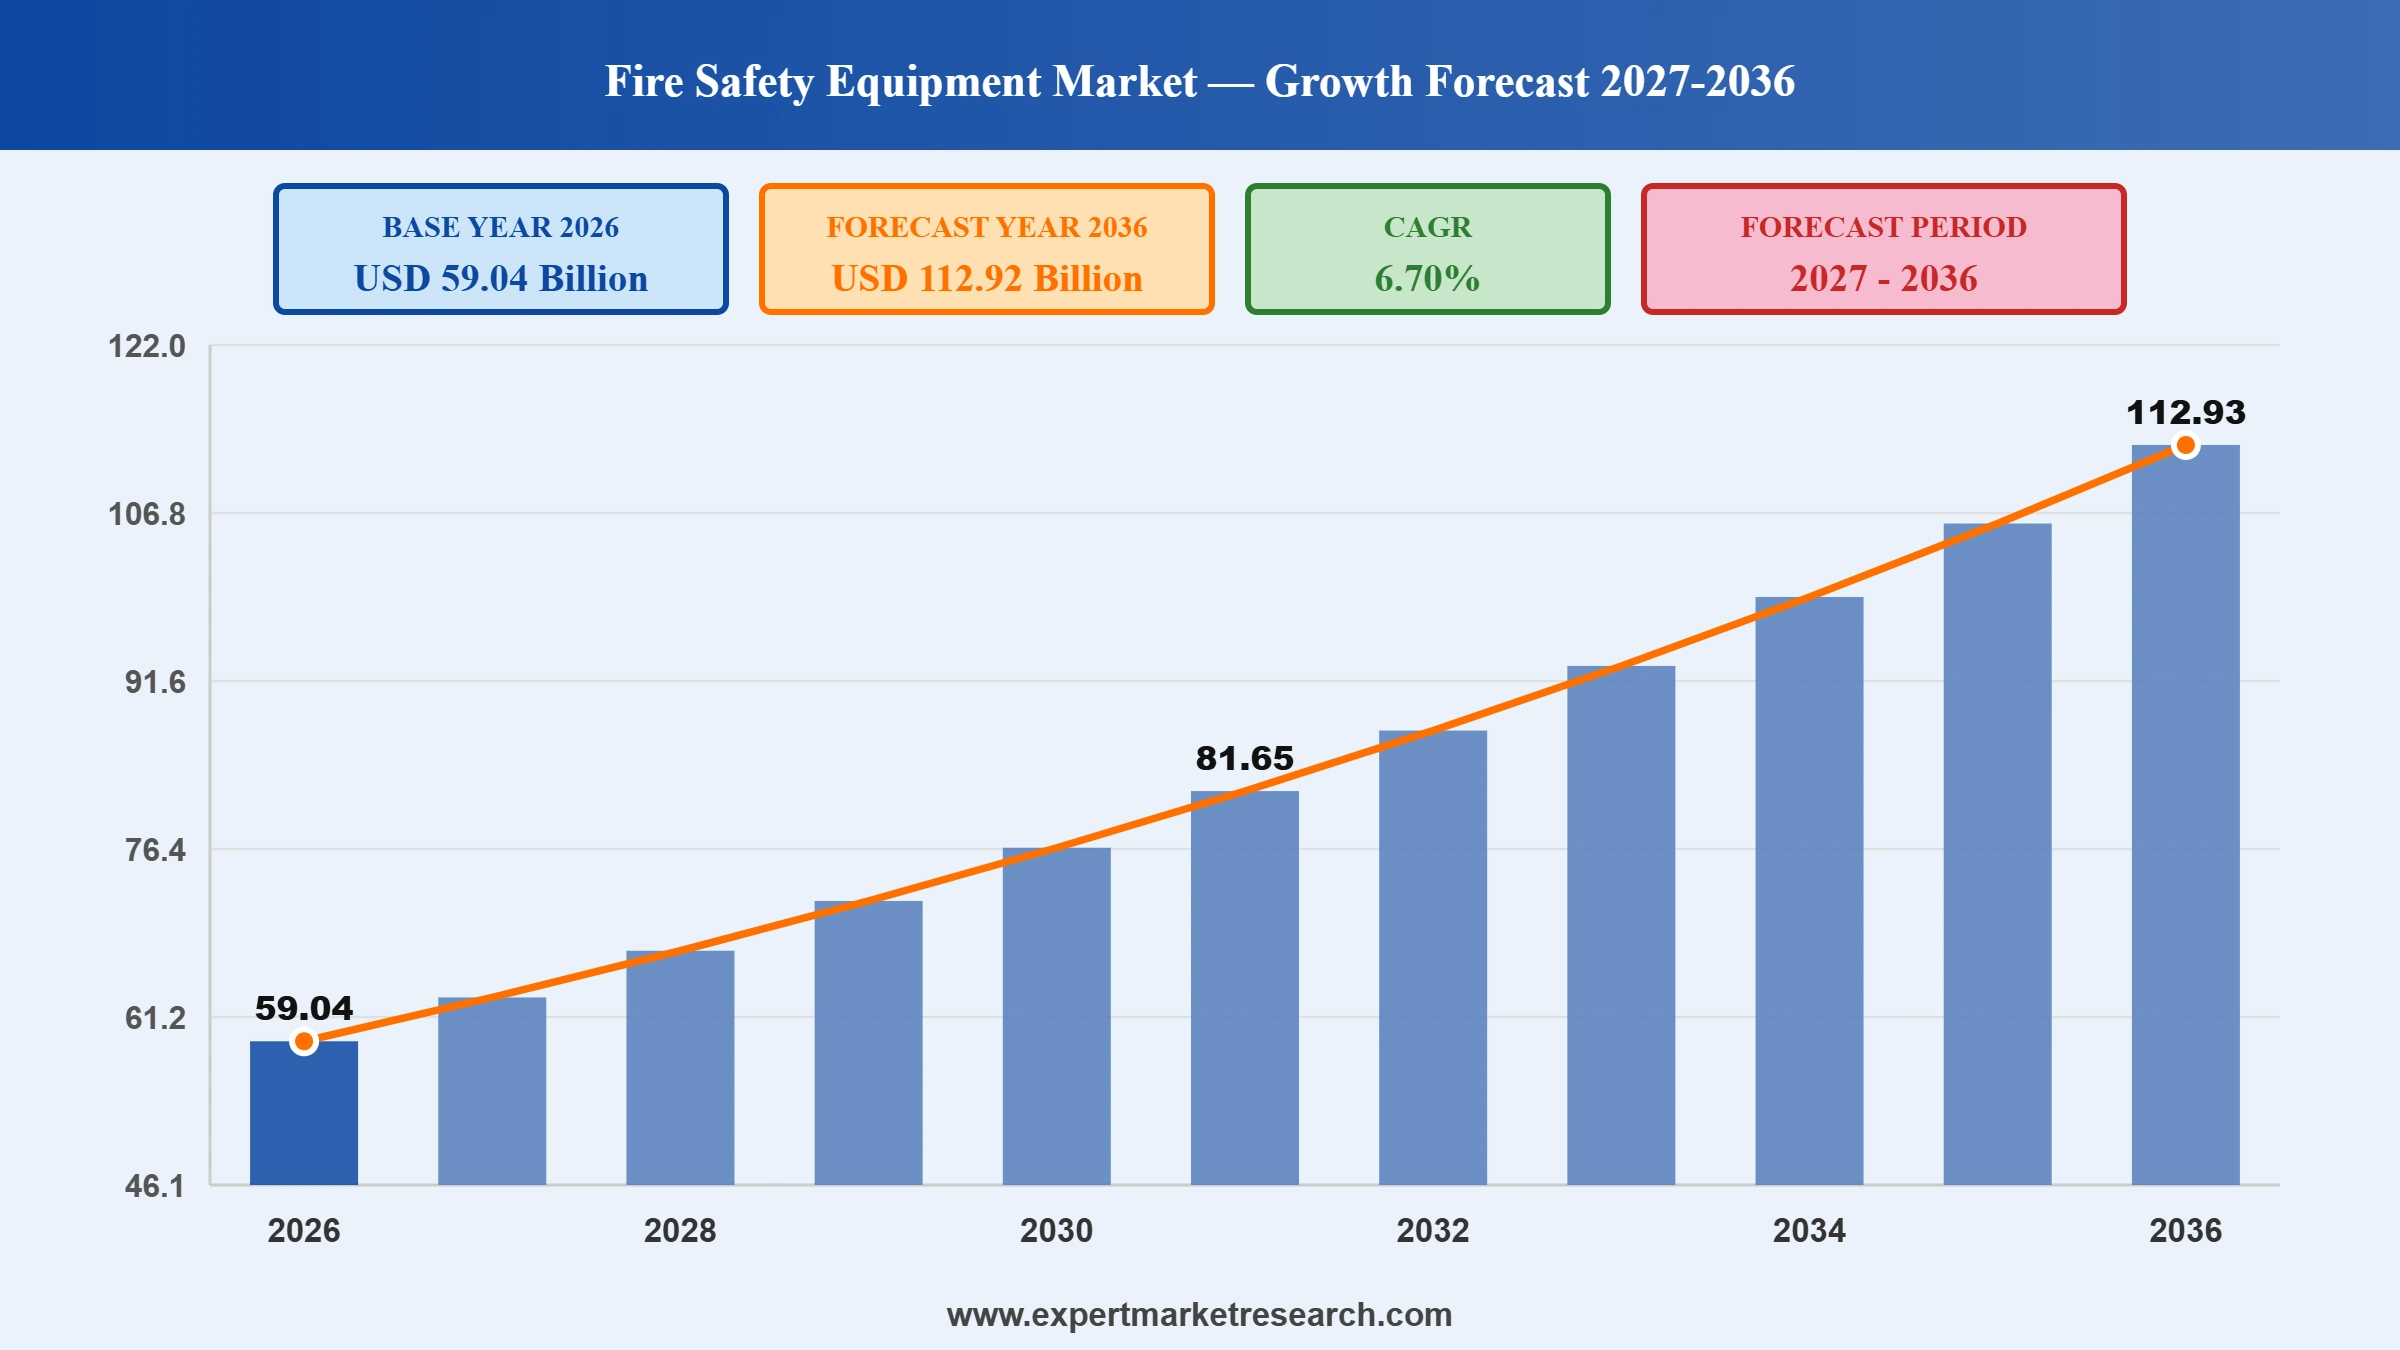
The global fire safety equipment market attained a value of USD 55.33 Billion in 2025 and is projected to grow at a CAGR of 6.70% through 2035. The market is further expected to reach USD 105.83 Billion by 2035. Stricter building codes, rising construction activity, and wider adoption of connected detection are supporting growth in the market.
Demand for fire safety equipment spans detection, alarm, extinguishing, and passive protection products installed in offices, factories, apartments, and hospitals. Construction activity, stricter fire codes, insurance requirements, and awareness after major fires keep orders steady. Manufacturers sell through installers, distributors, and large contractors, and many customers sign inspection and maintenance contracts that create repeat revenue. Rapid urbanisation across Asia Pacific and Gulf states adds new buildings each year, while retrofit work in North America and Europe keeps older sites compliant.
Connected detection is widening the customer base beyond professional installers. In January 2026, Ring introduced Fire Watch at CES, a feature in its Neighbors section where cameras scan footage for smoke or flames and share alerts with the fire monitoring app Watch Duty. Homeowners gain earlier warning without extra hardware, and the approach may push alarm makers to add app links and camera analytics to products that were once sold as standalone devices in the fire safety equipment market.
Leading suppliers are directing capital toward wireless detection, connected panels, and broader passive protection ranges, while acquisitions of regional installers give them direct access to local service revenue. In April 2026, FIREFLY planned to unveil four new passive products at the Fire Safety Event in Birmingham, including a construction joint product and a raised access floor system. Competitive positioning increasingly depends on testing, certification, and the ability to bundle detection, suppression, and protection under one contract across large projects worldwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Stöbich Fire Protection Systems expanded its North Charleston site, investing USD 2.53 million and adding 33 new jobs to assemble the GX Smoke Curtain in the United States instead of Germany. Other manufacturers across the fire safety equipment market can follow this lead by assembling products near their buyers, which shortens delivery times for smoke containment systems and cuts import and currency exposure.
Emerson launched the Rosemount 965 Flame Detector, a flameproof model with four infrared sensors that separate hydrocarbon fires from background radiation, a detection range of up to 45 meters, and IP66 and IP68 protection. Vendors across the fire safety equipment market serving major oil, gas, and chemical plants stand to gain by shipping factory calibrated detectors, which lowers maintenance visits and nuisance alarms.
Honeywell launched a next generation NOTIFIER INSPIRE release with built in smoke control, a carbon monoxide purge function, and automated testing, alongside Zone Sync and Rescue Assist services. Panel makers across the fire safety equipment market that bundle smoke control software with alarm hardware can cut custom programming, simplify retrofits in older buildings, and strengthen long term service contracts with their building owners.
Century Fire Protection, a FirstService subsidiary, acquired GSC Fire and Security in Texas and Titan Fire Protection in Florida, adding alarm and sprinkler services in the growing Sun Belt. Terms were not disclosed. Buying established regional contractors is a quick way for service groups to add trained technicians, recurring inspection and testing revenue, and local customer relationships.
Passive protection suppliers across the fire safety equipment market are shifting toward low odor, water-based coatings that suit occupied and fast-moving building sites. These products let trades work in sequence and lower emissions while keeping steel stable during a fire. In February 2026, PPG introduced PPG STEELGUARD 652 for interior structural steel in North America, offering up to two hours of protection, UL 263 certification, and up to 20 years of performance. Contractors gain faster project schedules, and rivals may respond with similar formulations.
Certification demand is rising as new codes require tested products, yet many countries lack local laboratories. International testing groups are building facilities and buying local partners to shorten approval times. Local testing lowers sample shipping costs. In September 2026, Efectis Group launched Efectis India in Chennai, taking a majority stake in AADIT and opening what it describes as the first international fire testing laboratory in the country. Manufacturers may qualify new products faster, and more global testers may follow soon.
Large safety and service groups across the fire safety equipment market are buying regional contractors to gain trained technicians and steady inspection revenue. Sprinkler design, installation, and maintenance work is spread across many small firms, which makes it attractive for roll ups. In June 2026, APi Group acquired Mid-Atlantic Fire Protection of Virginia Beach, Virginia, adding sprinkler design and maintenance capacity. Buyers gain local density and trained staff, while independent contractors gain access to capital, and further deals are likely as compliance work keeps growing steadily.
Retrofit and heritage projects across the fire safety equipment market favor wireless detection because it avoids drilling and cabling. Hybrid designs that mix wired loops with a wireless mesh give installers flexibility on large networks. In January 2026, Hochiki Middle East showed its Ekho hybrid wireless system and Latitude panels at Intersec Dubai, alongside EN and UL approved detection for regional conditions. Specifiers gain faster installation. Battery backed nodes also keep monitoring active during outages. Competing suppliers may expand their wireless portfolios for Gulf region customers.
Strong order books across the fire safety equipment market show that life safety spending is resilient across economic cycles. Safety technology groups report broad growth across their portfolios and are using cash to buy more companies. In June 2026, Halma reported full year revenue of GBP 2,582.3 million, up 15%, and adjusted operating profit of GBP 594.5 million for the year to 31 March 2026. Investors gain confidence, and further acquisitions in safety niches are expected. Management had guided to cash conversion near its 90% target.
The Expert Market Research's report titled "Global Fire Safety Equipment Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
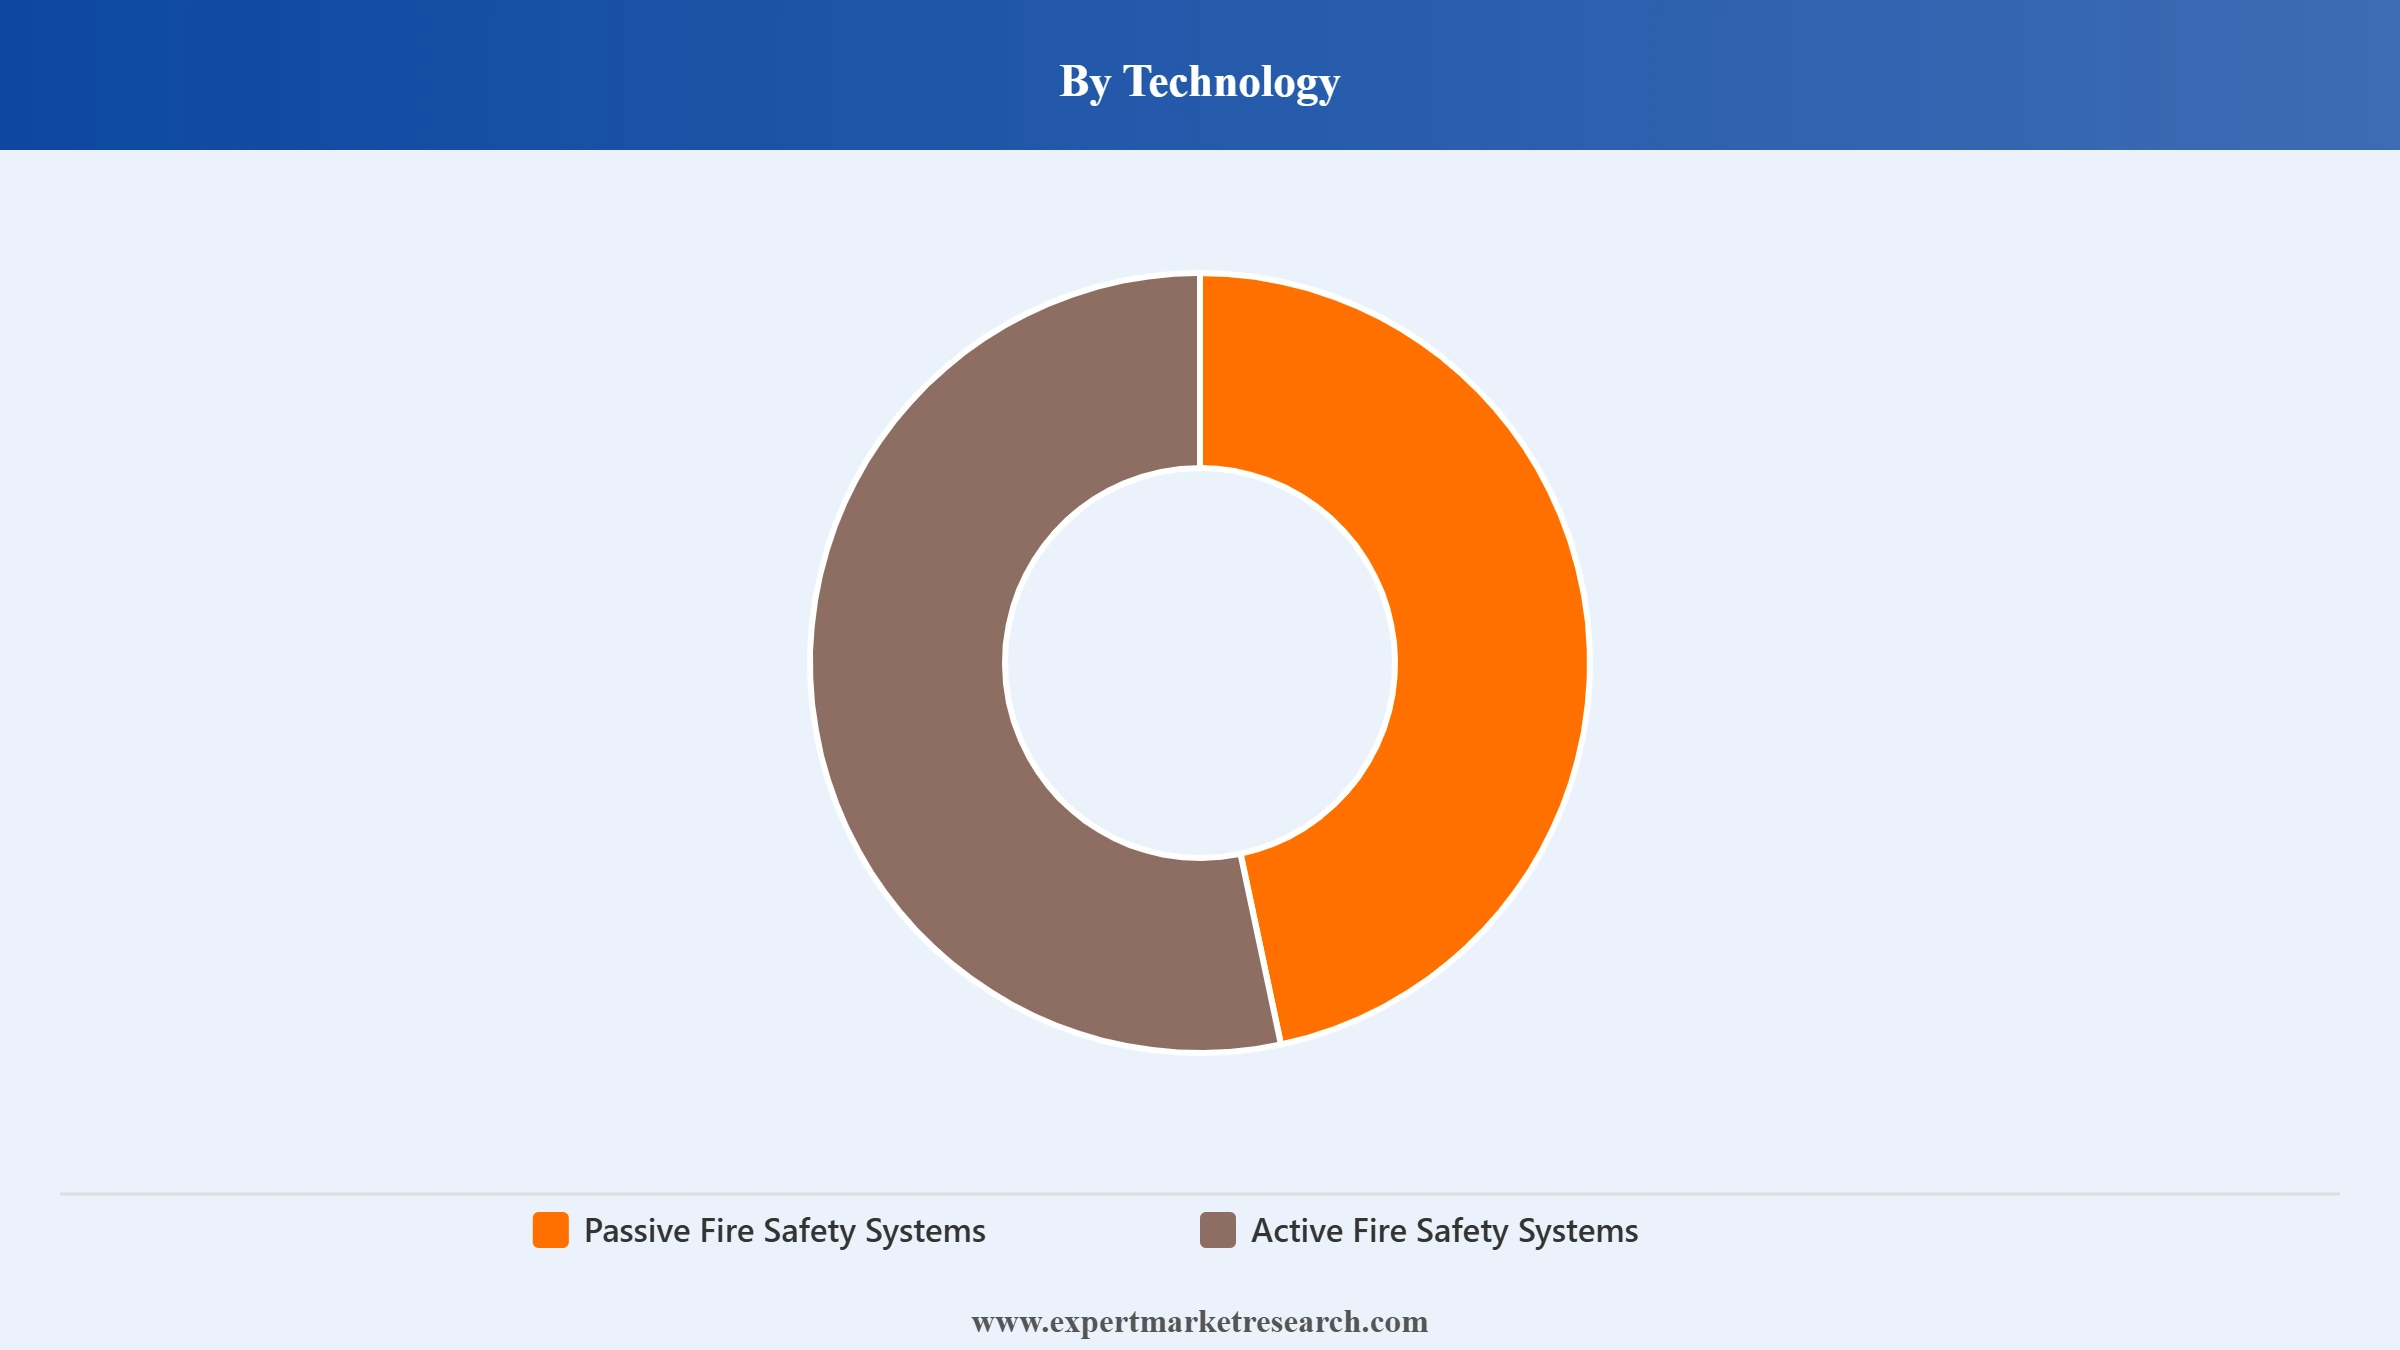
Market Breakup by Technology
Key Insight: Active fire safety systems lead the technology segment by revenue, as sprinklers, extinguishers, alarms, and detectors are fitted in nearly all office, factory, and home settings and need regular servicing, testing, and eventual replacement. Both technologies are often specified together on large projects, so suppliers that sell certified products in each category win larger contracts and repeat service business. Passive fire safety systems, which include fire resistant coatings, doors, glazing, and fire stopping materials, are expected to grow fastest, as stricter codes ask buildings to contain fire and protect structure for longer evacuation times.
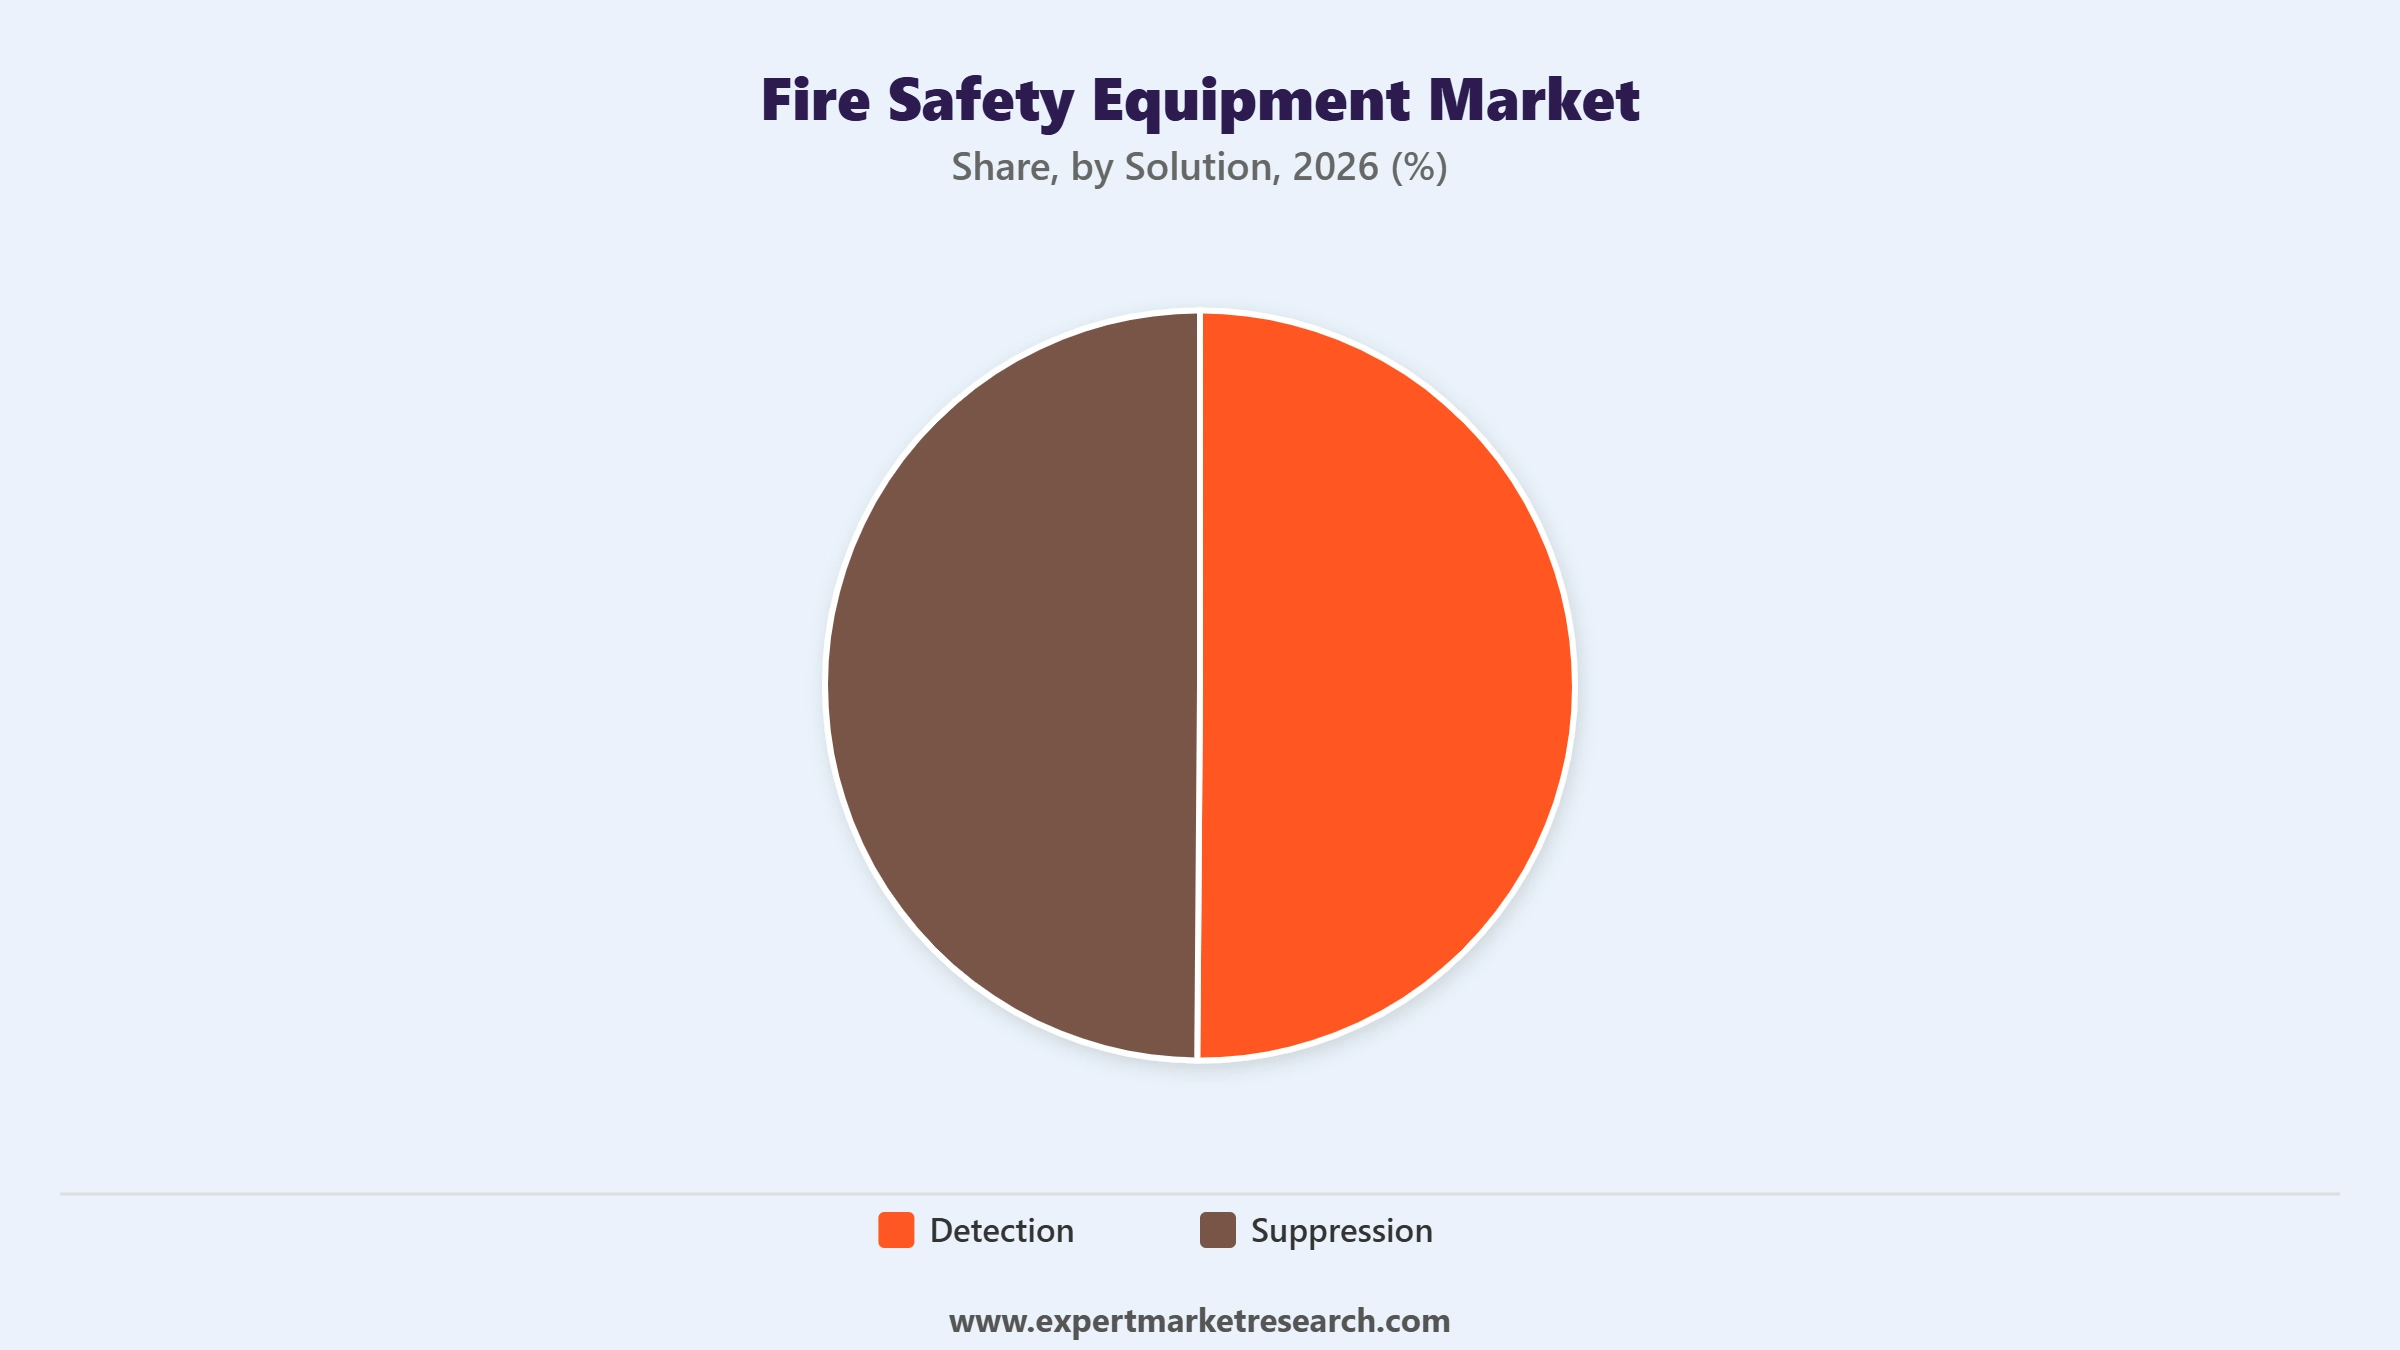
Market Breakup by Solution
Key Insight: Suppression leads the solution segment, as extinguishers and sprinklers are compulsory across buildings and need refills, testing, and replacement. Extinguishers cover gas, water, and dry chemical powder types, and sprinklers protect larger spaces automatically by reacting to heat. Detection is expected to grow fastest, as detectors, which include flame, smoke, and heat types, and alarms move toward wireless and connected designs. In January 2026, Full Circle Lithium launched six lithium battery fire extinguisher sizes for retail and industrial users, from 20 ounces to 50 liters.
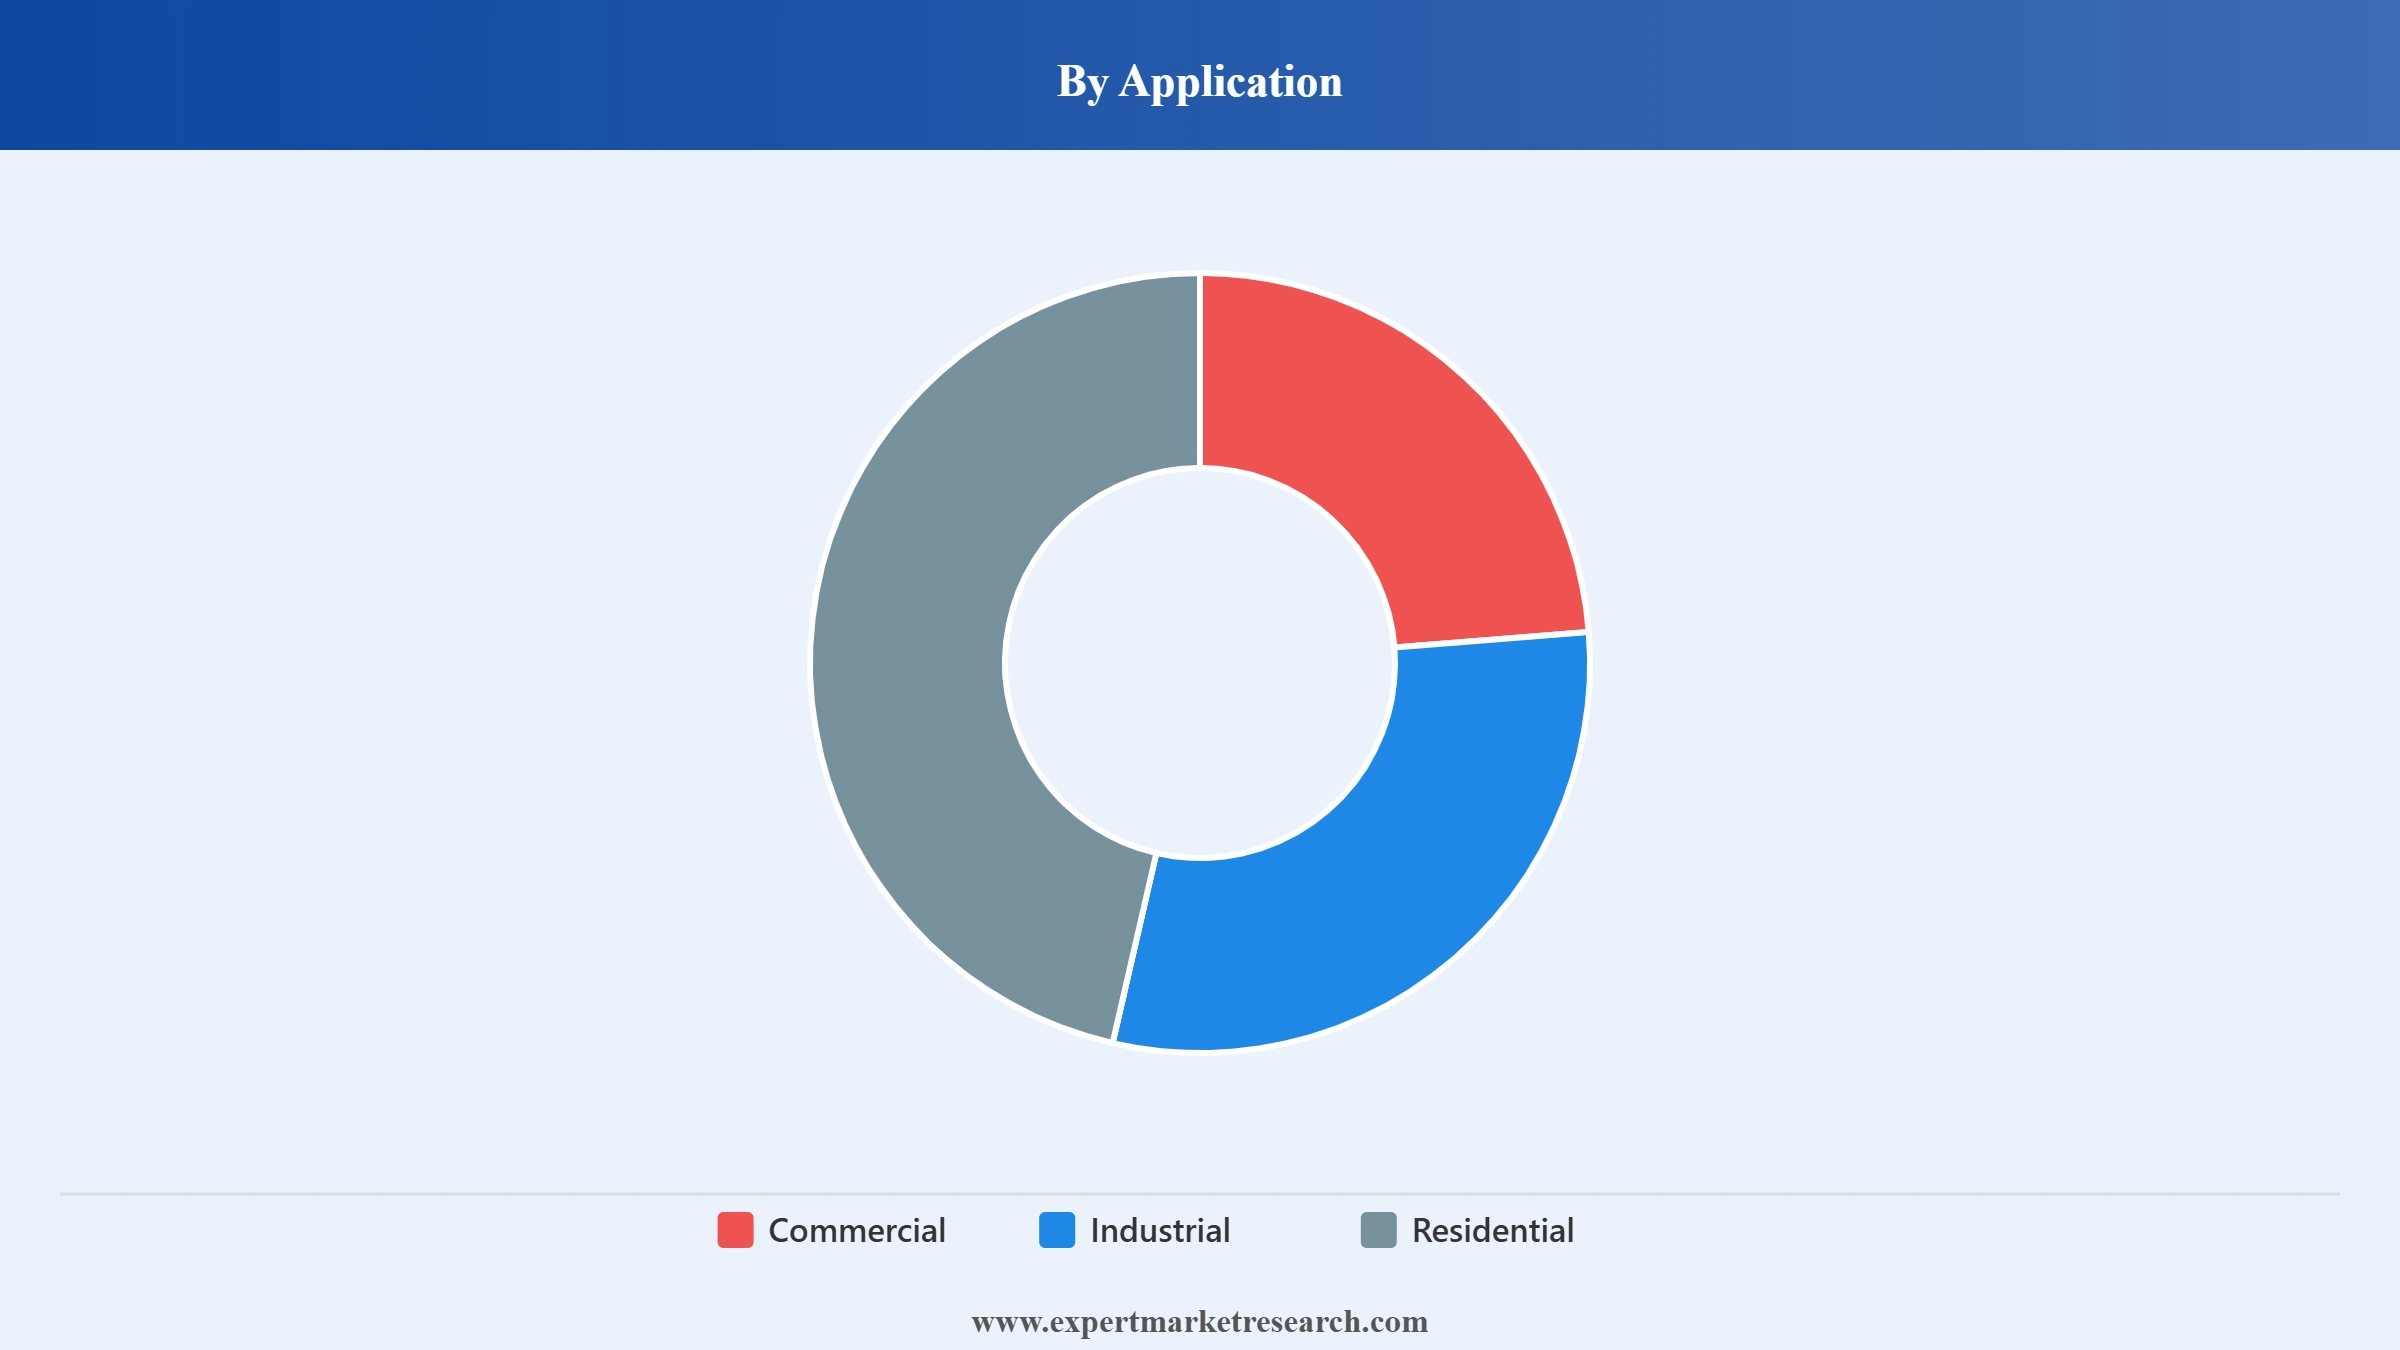
Market Breakup by Application
Key Insight: Commercial buildings hold the largest share of the application segment of the fire safety equipment market, as offices, hotels, hospitals, malls, and public venues face strict codes and regular inspection. Industrial sites such as refineries, factories, warehouses, and energy facilities need flame detectors, suppression systems, and passive protection for hazardous processes, and they renew equipment on fixed cycles. Commercial demand is also supported by renovation cycles and retrofit rules in older city centers. Residential use is expected to grow fastest, as smoke alarm rules, connected devices, and rising apartment construction bring protection to more homes.
Market Breakup by Region
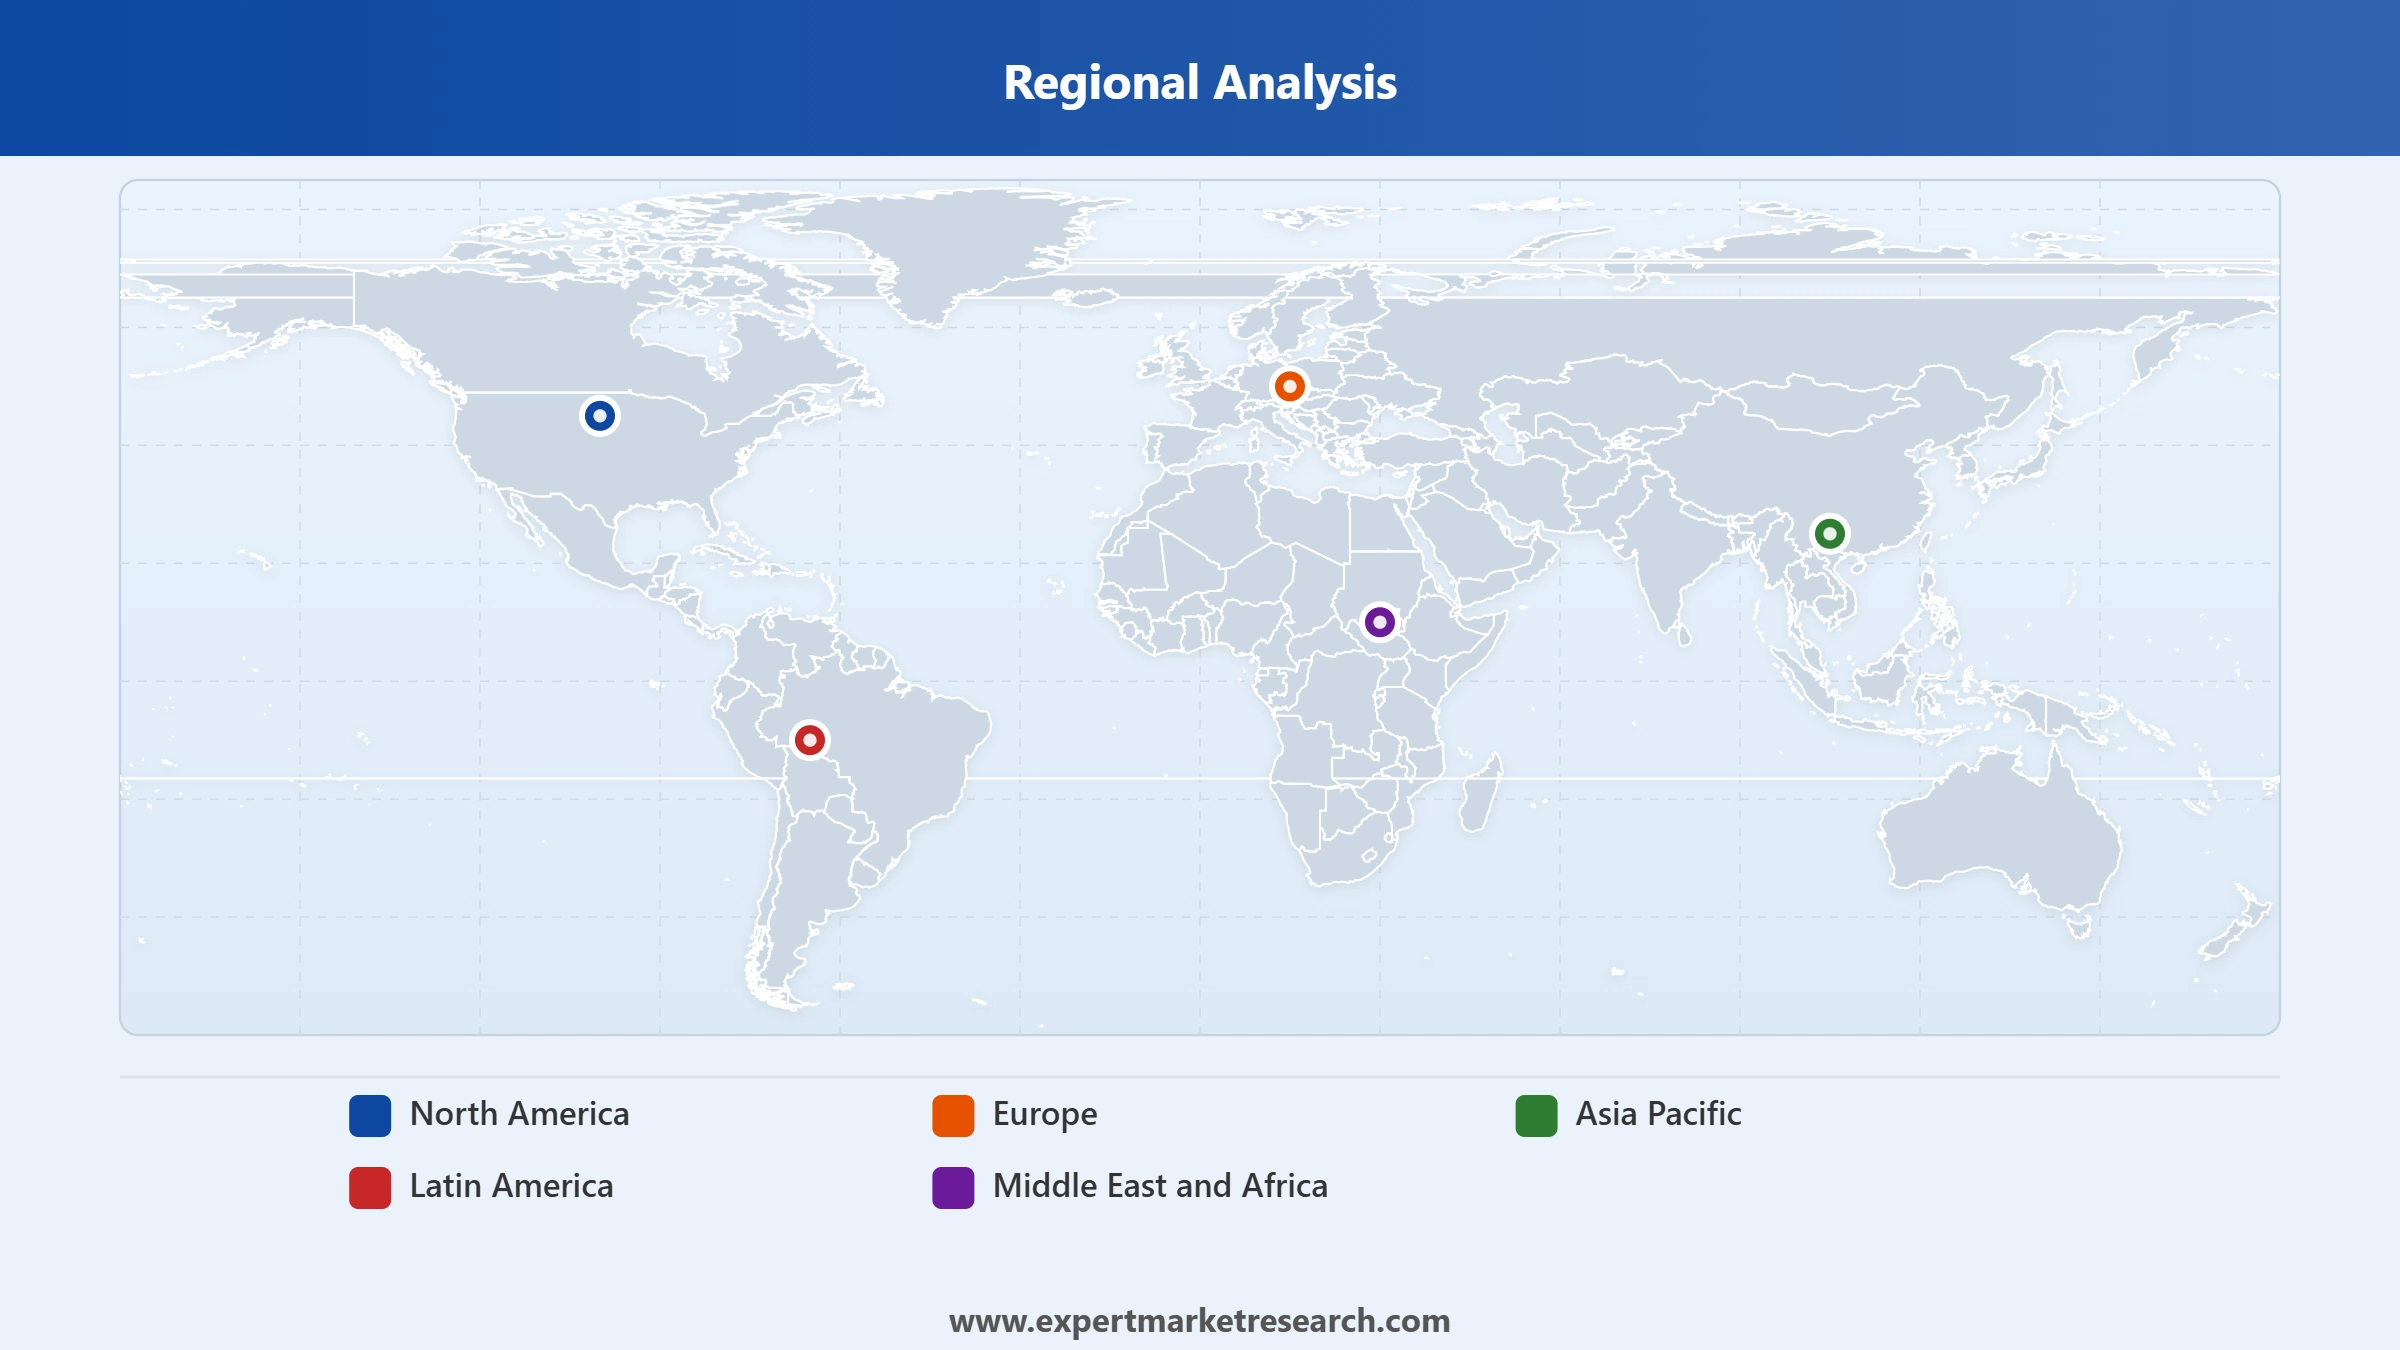
Key Insight: North America holds the largest regional share of the fire safety equipment market, backed by rigorous codes, a vast building base, and well-developed installer networks. Europe follows with demanding standards and strong retrofit activity. Asia Pacific is expected to grow fastest, as building activity, factory output, and new fire rules lift demand in large economies such as China and India. Latin America adds demand as commercial building and industrial investment widen in Brazil and Mexico. Middle East and Africa benefits from large infrastructure, hospitality, and energy projects in Saudi Arabia and the United Arab Emirates.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By technology, active fire safety systems dominate the fire safety equipment market owing to mandatory installation in every building type
Active fire safety systems hold the largest share of the technology segment, because detectors, alarms, extinguishers, and sprinklers are legally required in nearly every commercial, industrial, and residential building. These products also wear out, so owners must test, refill, and replace them on fixed schedules. Insurers and fire authorities check compliance, which keeps spending steady even when new construction slows. Installers and distributors earn recurring service income, and manufacturers benefit from a large installed base that needs parts and upgrades.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Passive fire safety systems are registering the fastest growth within the technology segment in the fire safety equipment market, as stricter fire codes ask buildings to resist fire without needing power or human action. In October 2025, Mann McGowan launched Pyroglaze Compression, a graphite intumescent seal for glazed apertures rated for 30 and 60 minutes and tested to EN1634-1 with fire rated glass. Door, glazing, and coating makers gain from these requirements, and architects now specify certified assemblies earlier in the design stage of large projects.
By solution, suppression dominates the fire safety equipment market owing to mandatory extinguishers and sprinklers
Suppression holds the largest share of the solution segment, because fire extinguishers and sprinklers are mandatory in most buildings worldwide and need regular inspection, refilling, and replacement. Sprinkler networks protect large floor areas automatically, while portable extinguishers give occupants a first response, and both categories are tested at fixed intervals by licensed contractors under local rules and inspection schedules. Insurers favor sites with automatic fire protection, and data centers, battery storage sites, and warehouses add demand for specialised extinguishing agents.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Detection is registering the fastest growth within the solution segment in the fire safety equipment market, as owners replace older detectors and alarms with wireless, addressable, and camera-based designs. Early warning reduces fire damage, injuries, and downtime, and connected panels let building teams find the source of an alarm. Panels also log events for audits. In March 2026, Siemens unveiled Sinteso Nova and Cerberus Nova detectors with cloud connectivity, continuous self-checks, and multi wavelength sensing that reduces false alarms. Owners gain remote diagnostics too.
By application, commercial buildings dominate the fire safety equipment market owing to strict occupancy codes and regular inspections
Commercial buildings hold the largest share of the application segment, because offices, hotels, hospitals, shopping centers, and public venues must meet strict occupancy codes and pass regular inspections. Large floor areas call for many smoke detectors, sprinklers, alarms, and emergency lighting points, and owners sign long term maintenance contracts. Tenant fit outs and renovations trigger fresh safety installations, so demand continues even in mature cities. Insurers and local authorities reinforce compliance, which supports consistent orders for installers, contractors, and distributors.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Residential use is registering the fastest growth within the application segment, as alarm mandates, smart devices, and growing apartment stock extend protection to many more households. In March 2025, First Alert and Google Home announced a smart smoke and carbon monoxide alarm that works with Nest Protect, with a projected U.S. price of USD 129.99. Interconnected alarms warn every room at once, and homeowners value instant alerts on phones when they are away. Landlords also fit alarms in rental units.
North America commands the largest regional share of the fire safety equipment market, supported by strict codes and a large building base
North America commands the largest regional share of the fire safety equipment market, supported by strict codes, a large stock of commercial buildings, and dense installer networks. Local authorities adopt updated fire codes regularly, which triggers replacement of older alarms, sprinklers, and extinguishers. Insurers reward protected sites, and large service groups sell inspection contracts across states. Large server rooms, grid storage plants, and distribution centers need suppression systems, while homeowners buy connected smoke and carbon monoxide alarms in growing numbers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is registering the fastest growth among the regional markets, driven by construction, industrial output, and tighter fire rules in China, India, and ASEAN. In August 2026, Delhi notified the Delhi Fire Service (Amendment) Rules 2026, which require six-meter access routes for fire engines, continuous monitoring, sprinkler systems, and emergency power backups across buildings. Rising urban populations, new factories, and growing local manufacturing of detectors and extinguishers support steady long-term expansion of the fire safety equipment market.
The competitive landscape is moderately consolidated, with global fire safety equipment companies competing alongside many regional specialists. Established fire safety equipment companies differentiate through detection accuracy, product certification, panel software, installer training, and long service contracts. Large groups sell complete systems across detection, suppression, and passive protection, while smaller firms focus on single categories such as extinguishers, sprinklers, or fire doors. Approvals under UL, FM, and EN standards act as a barrier for new entrants in most countries.
Leading fire safety equipment market players are pursuing acquisitions, regional assembly lines, and connected product launches to widen their reach. Several fire safety equipment players are also buying sprinkler and alarm contractors to capture service revenue and local relationships. Investment in wireless detection, smoke control software, and certified passive products is increasing as customers ask for single source suppliers. Partnerships with testing laboratories and trade bodies help suppliers meet new codes in Asia Pacific and the Middle East.
Founded in 1886 and headquartered in Gerlingen, Germany, the company supplies the market through its Building Technologies business, including AVENAR detectors, aspirating, linear heat, and flame detectors, and fire alarm control panels. It sells through installers and system integrators, and it assembles AVENAR detectors in India.
Founded in 1911 and headquartered in Dublin, Ireland, the company supplies the market through fire alarm notification appliances, including Wheelock horns and strobes and Eluxa LED devices, together with mass notification systems. It sells through electrical distributors and contractors to commercial and institutional buildings.
Founded in 1918 and headquartered in Tokyo, Japan, the company supplies the market through conventional and intelligent smoke and heat detectors, fire alarm panels, and extinguishing systems. It operates through American and European subsidiaries, with a production facility in Gillingham, United Kingdom.
Founded in 1894 and headquartered in Amersham, United Kingdom, the company supplies the market through its Safety sector, whose brands include Apollo, Ampac, Advanced, E2S, and Firetrace. It operates as a group of niche technology businesses selling to customers worldwide.
Other key players in the market include Honeywell International Inc., Gentex Corporation, and Napco Security Technologies, Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global fire safety equipment market trends 2026 report. Discover regional growth patterns, technology formats, solution types, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market. Request a customised quote to align the findings with your own business planning.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of USD 55.33 Billion in 2025.
The market is projected to grow at a CAGR of 6.70% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach about USD 105.83 Billion by 2035.
The market is being driven by rapid industrialisation and urbanisation, favourable government policies, and rising awareness regarding fire safety.
Surge in manufacturing practices to include smart technology driven by software like Internet of Things (IoT) in fire safety equipment is expected to be a key trend guiding the market.
The major regional markets for fire safety equipment are North America, Latin America, the Asia Pacific, Europe, and the Middle East and Africa.
The different types of technology are passive and active fire safety systems.
The various solutions of fire safety equipment considered in the market report are detection and suppression.
The significant applications of fire safety equipment include commercial, residential, and industrial.
The key players in the market include Robert Bosch GmbH, Eaton Corporation, Hochiki Corporation, Halma PLC, Honeywell International Inc., Gentex Corporation, and Napco Security Technologies, Inc., among others.
Active fire safety systems lead the market by technology, while passive fire safety systems are expected to grow fastest.
North America leads the market by region, while Asia Pacific is registering the fastest growth.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Technology |
|
| Breakup by Solution |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




