

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
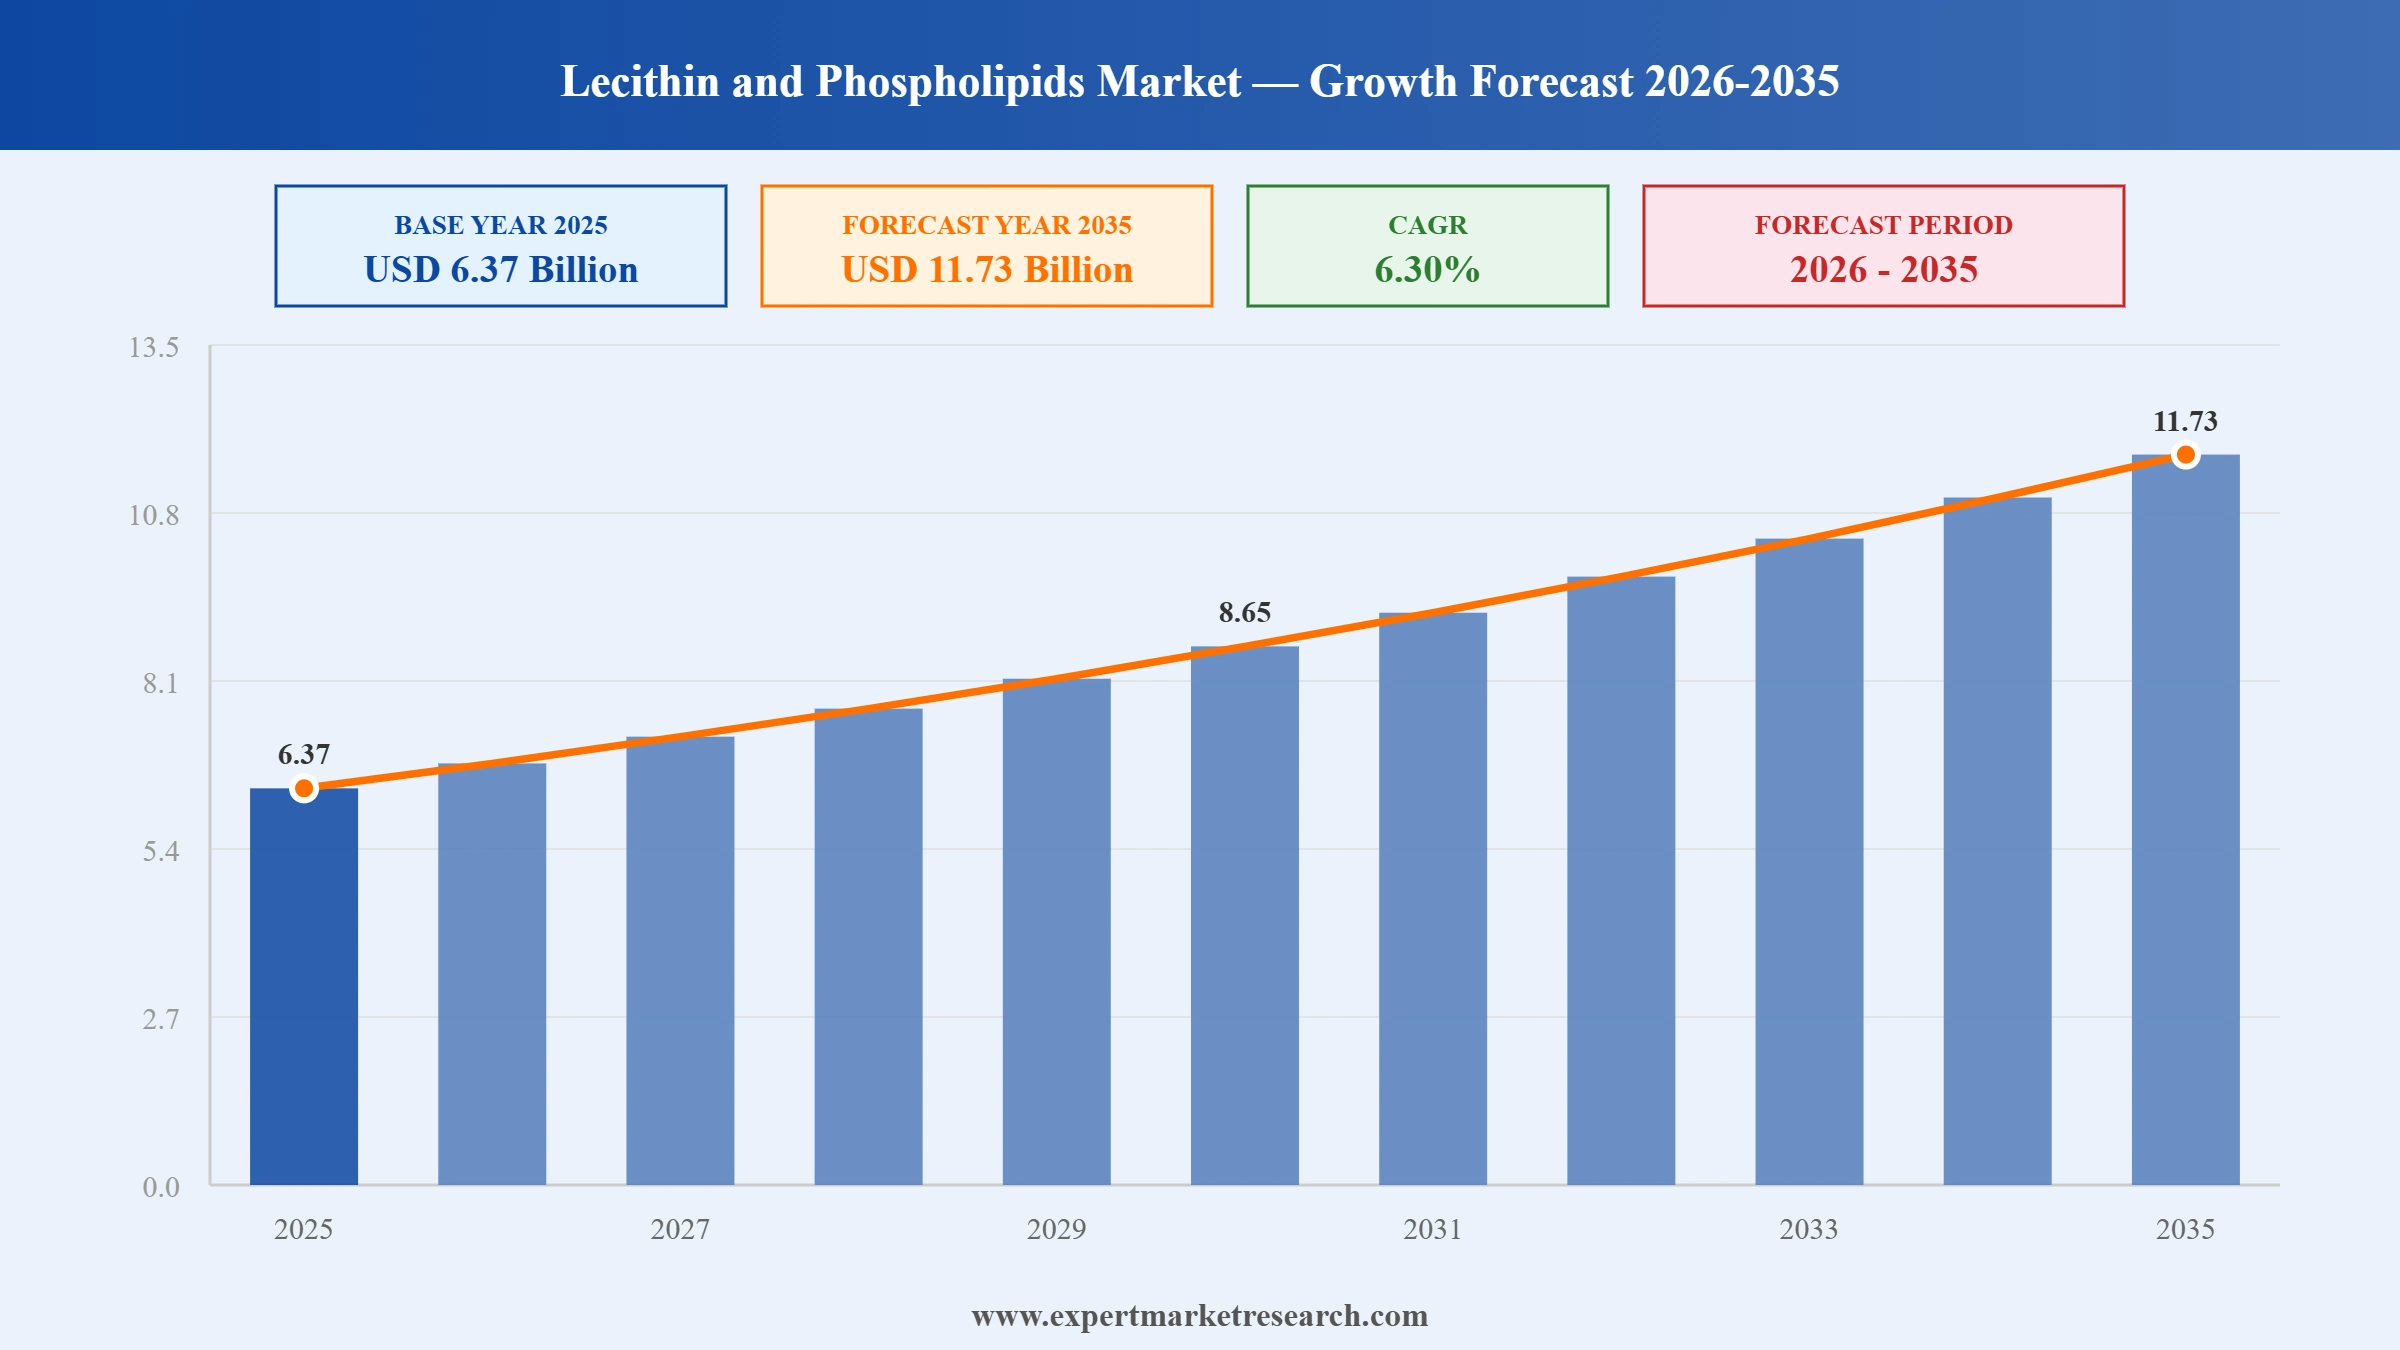
The global lecithin and phospholipids market attained a value of USD 6.37 Billion in 2025 and is projected to expand at a CAGR of 6.30% through 2035. The market is further expected to reach USD 11.73 Billion by 2035. Rising demand for natural emulsifiers, expanding pharmaceutical drug delivery applications, and growing consumer preference for clean label food ingredients are encouraging established suppliers to pursue new product launches, expand regional operations, and diversify sourcing across plant-based lecithin categories worldwide.
The lecithin and phospholipids market encompasses natural emulsifiers and bioactive lipids extracted from soy, sunflower, rapeseed and canola, and egg sources, serving food and beverage, feed, pharmaceutical, and cosmetic applications worldwide. Demand continues to be shaped by rising clean label preferences, growing drug delivery applications, and expanding functional food consumption, with soy accounting for the largest source share given its established extraction infrastructure and cost effectiveness across mass market applications.
Established ingredient suppliers are increasingly launching specialised sunflower lecithin variants tailored to specific end use applications, reflecting the sector's shift toward differentiated, application specific product development beyond commodity grade lecithin. In January 2026, Cargill launched Topcithin Ultra, a new de-oiled sunflower lecithin powder developed for bakery and confectionery applications, offering improved flowability and reliable emulsification for allergen free product formulations.
Leading suppliers are also expanding their pharmaceutical grade phospholipid capabilities to support the growing liposomal drug delivery market, reflecting increased cross industry investment in high purity, functionally differentiated lipid ingredients. In March 2026, Archer-Daniels-Midland Company introduced a high purity sunflower lecithin solution designed for pharmaceutical liposomal delivery systems, using an enzymatic extraction process to improve phospholipid quality for clean label pharmaceutical formulations.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| Global Lecithin and Phospholipids Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 6.37 |
| Market Size 2035 | USD Billion | 11.73 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 6.30% |
| CAGR 2026-2035 - Market by Region | Asia Pacific | 7.3% |
| CAGR 2026-2035 - Market by Country | India | 8.3% |
| CAGR 2026-2035 - Market by Country | China | 7.0% |
| CAGR 2026-2035 - Market by Source | Soy | 7.1% |
| CAGR 2026-2035 - Market by End Use | Food and Beverages | 7.2% |
| Market Share by Country 2025 | UK | 3.7% |
Croda International opened a new hub in Guangzhou, China, bringing together fragrance and beauty active development to strengthen its regional research and manufacturing presence across Asian personal care and specialty ingredient markets nationwide. Companies across the lecithin and phospholipids market can leverage regional innovation hubs to accelerate product development cycles and better serve local formulation requirements across cosmetic and personal care applications worldwide.
Croda International successfully launched its new BioXPro amino acid range, expanding its biopharma ingredient portfolio following recent launches of Virodex for viral inactivation and Super Refined Poloxamer 188 as a shear protectant in cell culture media worldwide. Companies across the lecithin and phospholipids market can leverage expanded amino acid and phospholipid portfolios to strengthen positioning across biologic drug formulation and biomanufacturing applications nationwide.
Stern-Wywiol Gruppe rebranded its United States teams as SternMaid America, consolidating its contract manufacturing and ingredients divisions under one unified brand to better serve North American food and beverage partners with lecithin and functional lipid solutions nationwide and beyond. Companies across the lecithin and phospholipids market can leverage unified regional branding to strengthen customer relationships and streamline ingredient portfolio communication across established manufacturing facilities and networks internationally.
Lipoid GmbH introduced a new sunflower lecithin-based phospholipid complex specifically formulated for cosmetic emulsions, expanding its portfolio of plant sourced functional ingredients for skin care and personal care manufacturers seeking natural, allergen free alternatives worldwide and beyond. Companies can leverage sunflower based phospholipid complexes to meet growing cosmetic industry demand for clean label, non-GMO emulsifier systems across international markets nationwide.
Established agribusiness companies across the lecithin and phospholipids market are increasingly acquiring dedicated lecithin and soy protein businesses from flavor and fragrance companies exiting non-core categories, rather than building emulsifier capacity through internal investment alone. This is helping acquiring companies rapidly expand their ingredient portfolios while giving divesting companies capital to focus on core operations. In March 2026, Bunge completed its acquisition of International Flavors and Fragrances' soy protein concentrate, lecithin, and soy crush businesses, expanding its lecithin offerings across soy, sunflower, and rapeseed sources.
Established European lecithin manufacturers across the lecithin and phospholipids market are increasingly launching dedicated United States based entities to serve the North American bulk lecithin market directly, rather than relying on export relationships through third party distributors. This is helping European manufacturers offer faster sample turnaround and localised inventory while maintaining production quality standards. In October 2025, Fismer Lecithin launched FISMER Farms, a United States initiative co-founded by Peter Fismer and Robert Bardsley to expand its non-GMO sunflower and rapeseed lecithin presence across the American market.
Established cosmetic ingredient specialists across the lecithin and phospholipids market are increasingly setting long term sustainability commitments for their lecithin derived phospholipid platforms, rather than addressing sourcing transparency on an ad hoc basis. This is helping ingredient specialists meet growing brand owner demand for verified non-GMO and deforestation free supply chains within premium personal care formulations. In September 2025, Lucas Meyer Cosmetics unveiled 2030 sustainability goals for its lecithin platform, committing to 100 percent non-GMO soy derivatives and majority verified non deforestation sourcing.
Established soy processing companies across the lecithin and phospholipids market are increasingly forming strategic partnerships with specialty lecithin manufacturers to expand global supply capacity, rather than pursuing standalone capacity expansion independently. This is helping soy processors leverage specialised lecithin manufacturing expertise while giving partner companies access to broader raw material sourcing networks. In March 2025, Sodrugestvo announced a strategic partnership with Lecico to expand the global supply of soy-based lecithin and phospholipid ingredients, combining integrated soybean processing with specialised lecithin grade development.
Established agricultural processing companies are increasingly opening automated specialty feed lecithin lines powered by renewable electricity, rather than expanding conventional lecithin capacity alone, to meet rising demand from the animal nutrition sector. This is helping processors offer enzymatically treated, low viscosity lecithin variants that improve nutrient absorption for livestock producers. In May 2025, Louis Dreyfus Company unveiled a new automated production line for specialty feed lecithin at its oilseed crushing plant in Tianjin, China, operating on 100 percent renewable electricity.
The Expert Market Research's report titled “Global Lecithin and Phospholipids Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Source
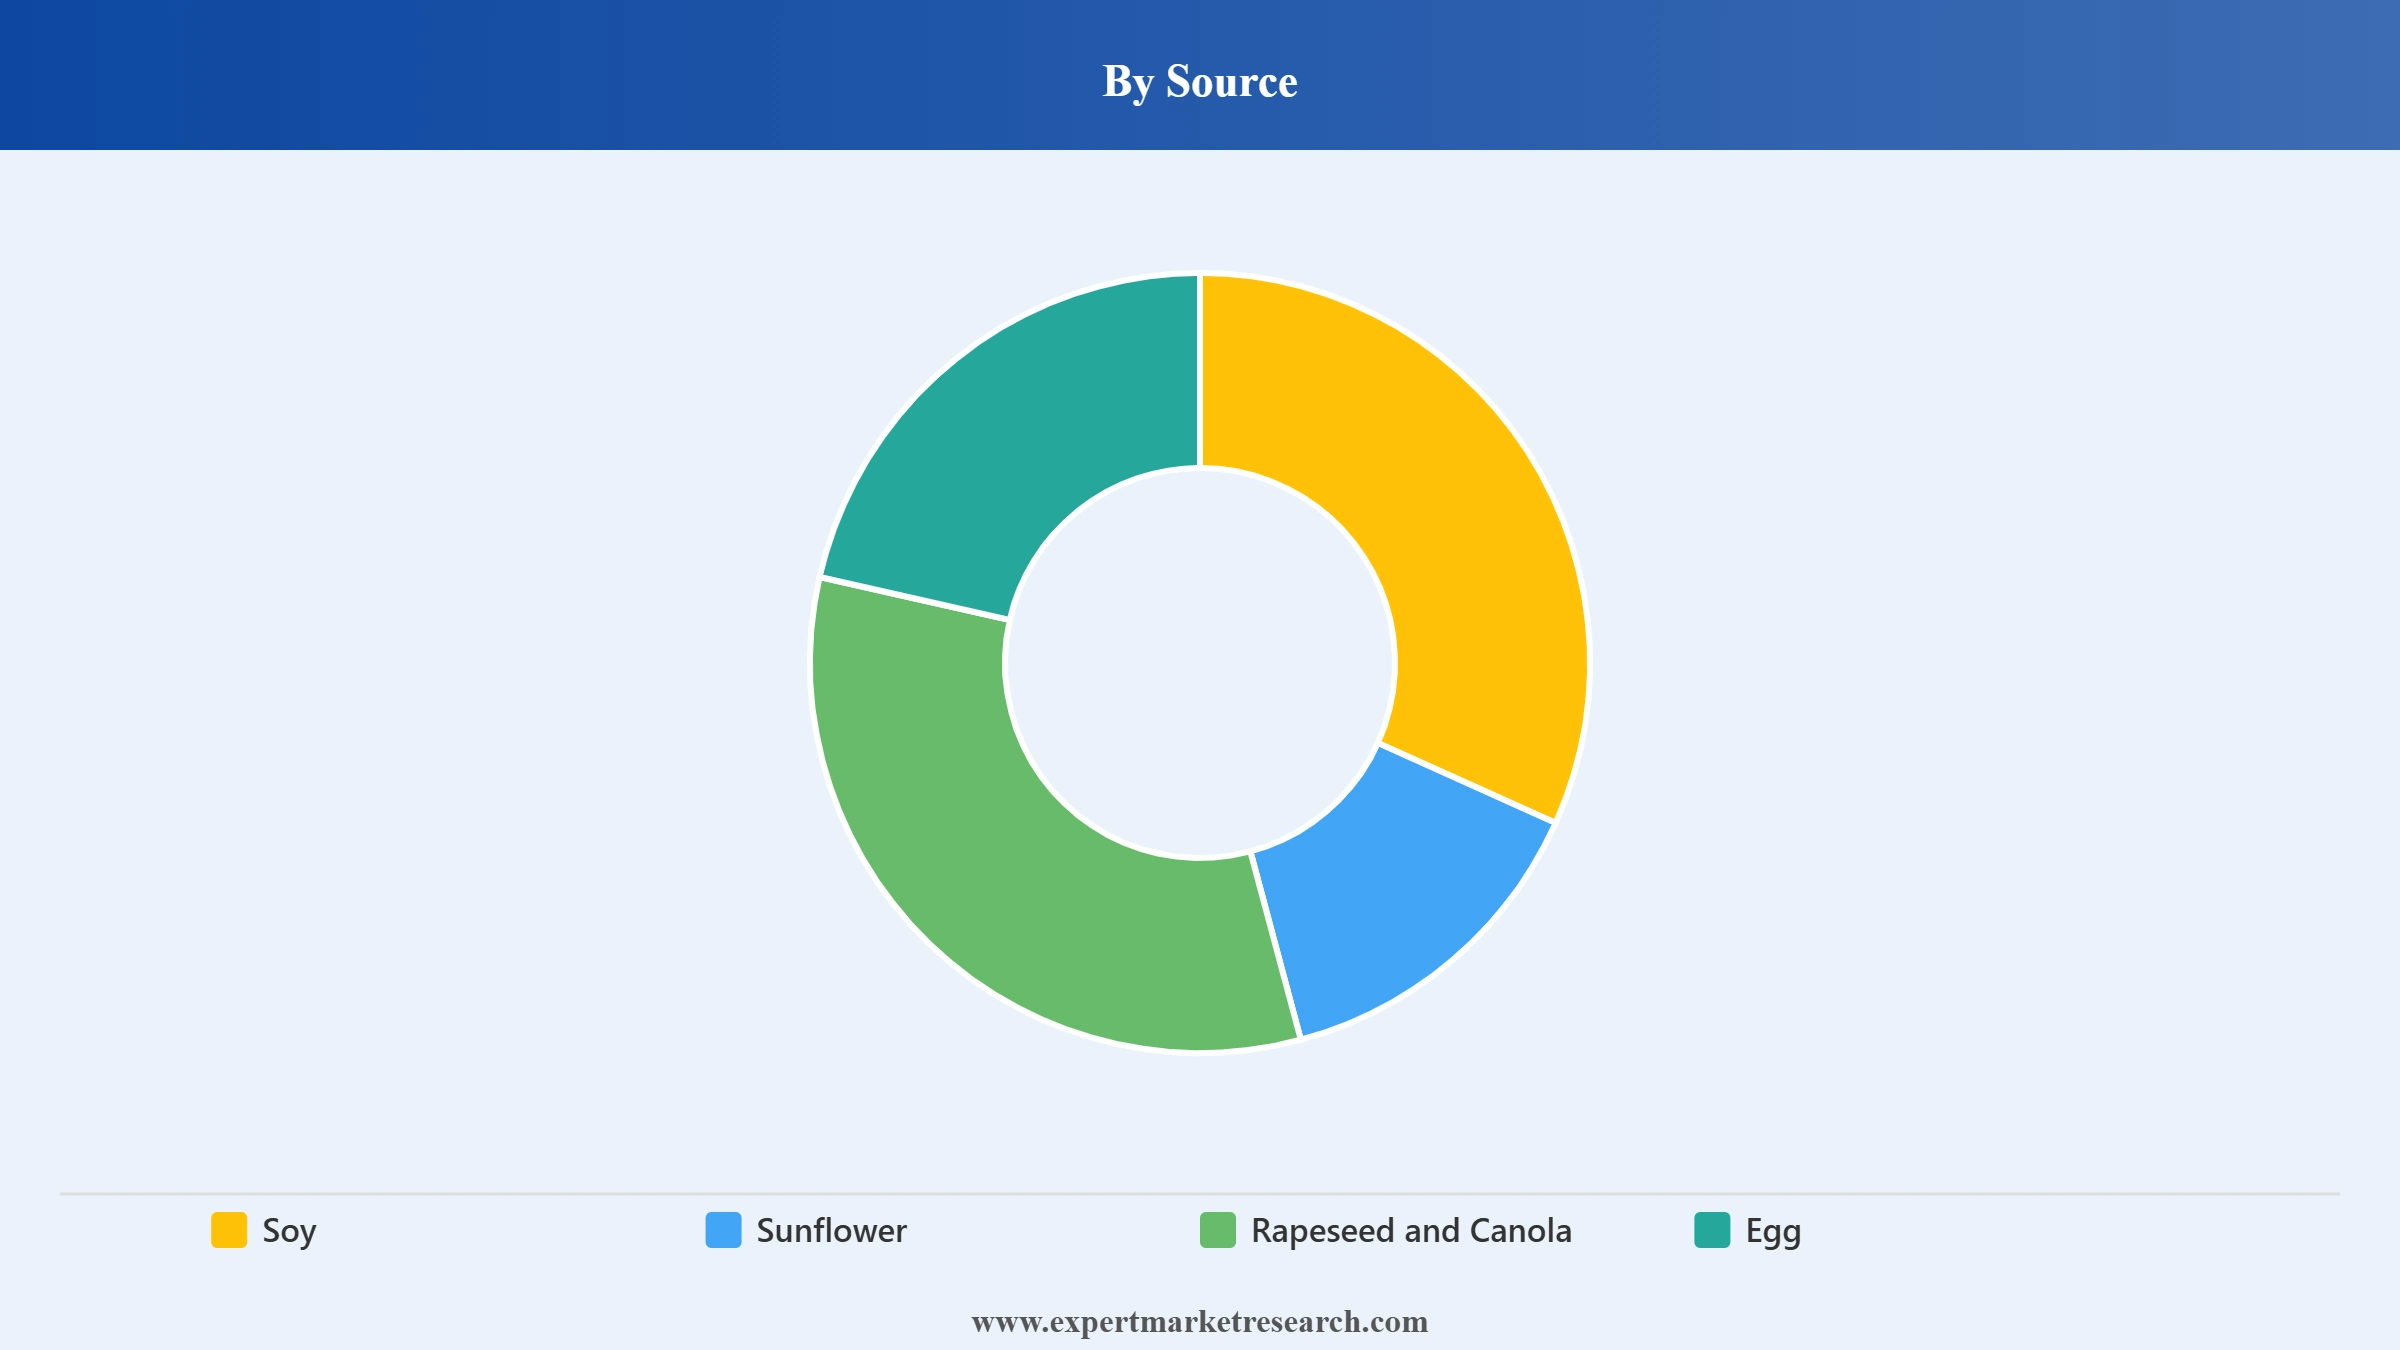
Key Insight: Soy accounts for the largest source share of the lecithin and phospholipids market, supported by established extraction infrastructure and cost-effective processing across global oilseed crushing facilities, illustrated by IFF entering a definitive agreement in August 2025 to sell its soy protein concentrate and lecithin business to Bunge. Sunflower is growing quickly as manufacturers increasingly seek non-GMO and allergen free labelling options, while rapeseed and canola serve similar clean label positioning and egg-based phospholipids continue to serve specialised pharmaceutical and nutraceutical applications requiring animal sourced lipids.
Market Breakup by Type
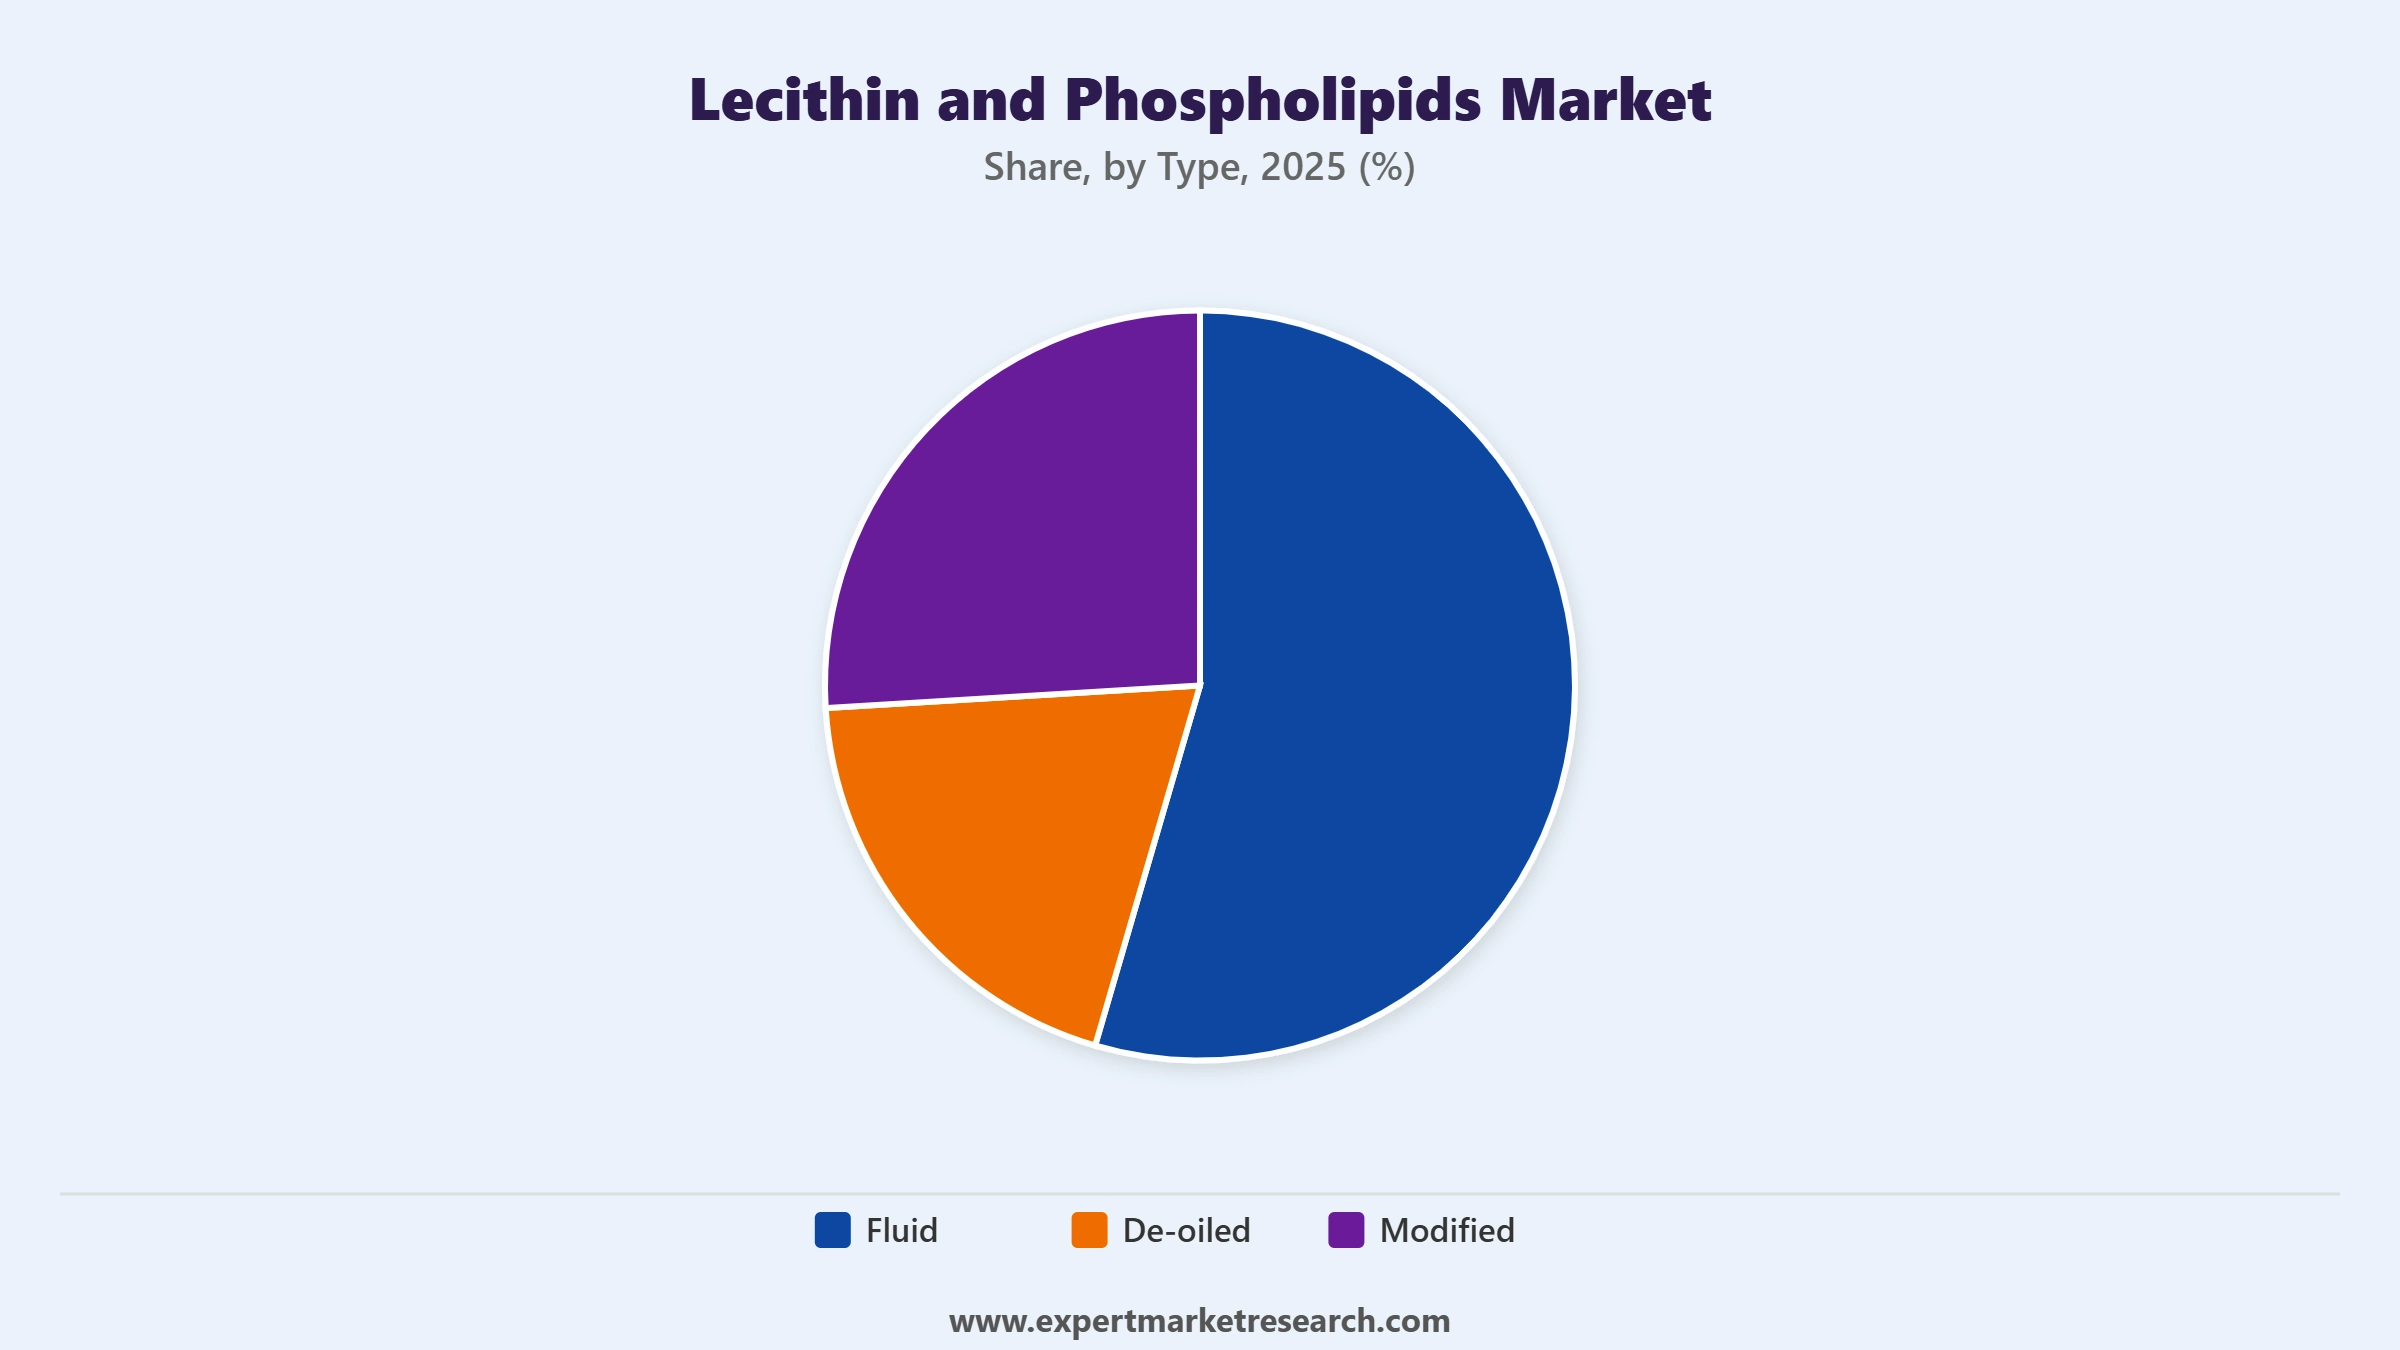
Key Insight: Fluid lecithin accounts for the largest type of share of the lecithin and phospholipids market, valued for its versatility and cost effectiveness across bulk food and feed applications requiring liquid emulsifier systems. De-oiled lecithin is growing quickly as manufacturers seek concentrated, powder form ingredients for confectionery and bakery applications, while modified lecithin continues to serve specialised applications requiring enhanced functional properties through enzymatic processing.
Market Breakup by End Use
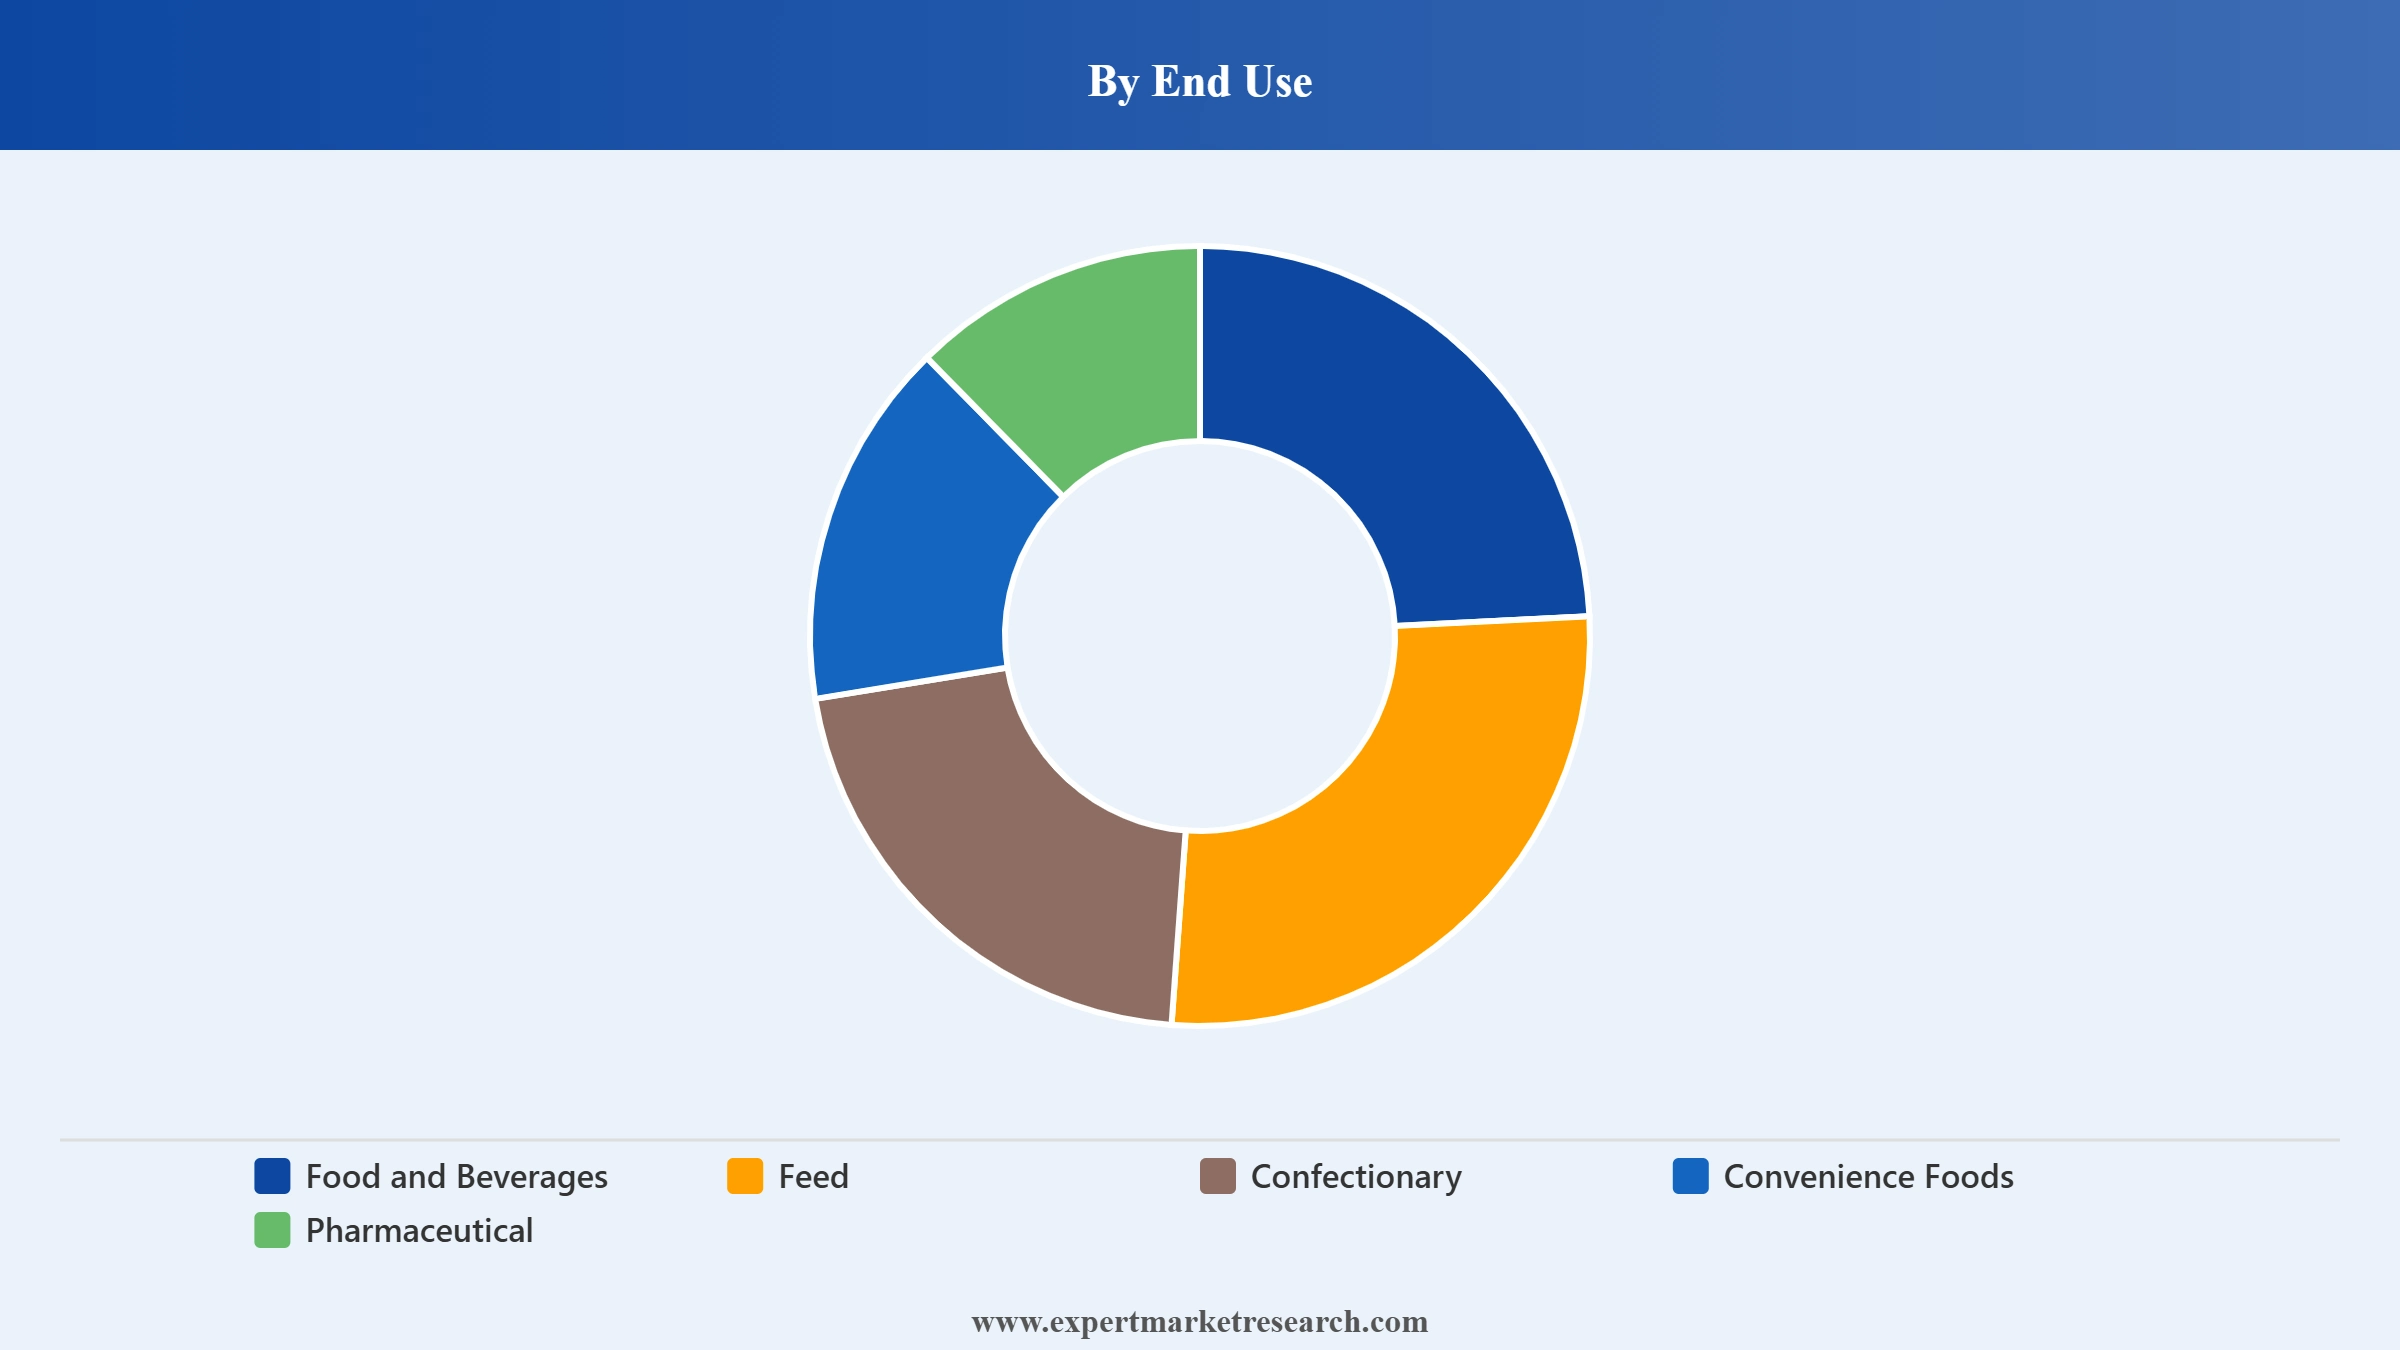
Key Insight: Food and beverages accounts for the largest end use share of the lecithin and phospholipids market, driven by sustained demand for emulsification across bakery, dairy, and processed food categories worldwide. Pharmaceutical is growing quickly as liposomal drug delivery systems increasingly rely on high purity phospholipids, while feed continues to represent a stable demand category, illustrated by ADM and Alltech's September 2025 North American animal feed joint venture combining premix and additive operations, alongside established confectionary and convenience food categories.
Market Breakup by Region
Key Insight: North America leads the lecithin and phospholipids market, supported by strong processed food demand and a concentration of major ingredient suppliers with established manufacturing infrastructure. Asia Pacific is registering the fastest growth as expanding food processing industries and rising oilseed crushing capacity across China and India drive demand for lecithin-based emulsifiers. Europe, Latin America, and the Middle East and Africa remain significant markets supported by established food manufacturing and clean label ingredient adoption.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By source, soy dominates the market through established extraction infrastructure and cost-effective processing
Soy accounts for the largest source share of the lecithin and phospholipids market, supported by established extraction infrastructure and cost-effective processing across global oilseed crushing facilities that have served the emulsifier industry for decades and generations worldwide. Established suppliers maintain extensive soy lecithin product ranges spanning multiple grades and price points to serve this consistent, high volume demand base across food and feed applications worldwide and beyond internationally.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Sunflower is growing quickly as manufacturers increasingly seek non-GMO and allergen free labelling options that avoid major food allergen declarations required for soy-based ingredients across sensitive consumer categories worldwide and beyond. In July 2025, Sternchemie introduced new primary production lecithin granules, SternPur G S from sunflower and SternPur G R from rapeseed, delivering improved quality and sourcing reliability beyond traditional soy-based granulation methods.
By type, fluid dominates the market through versatile, cost-effective bulk applications
Fluid lecithin accounts for the largest type of share of the lecithin and phospholipids market, valued for its versatility and cost effectiveness across bulk food and feed applications requiring liquid emulsifier systems that integrate easily into existing processing lines nationwide and beyond. In April 2025, Cargill inaugurated a transformed innovation center in Singapore to expand food innovation advancements across the Asia Pacific region, strengthening its fluid lecithin application development capabilities and regional technical support.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
De-oiled lecithin is growing quickly as manufacturers seek concentrated, powder form ingredients for confectionery and bakery applications requiring precise dosing and extended shelf stability compared to fluid alternatives across categories and formats. Established suppliers continue to expand de-oiled product portfolios spanning multiple plant sources to serve this fast growing, application specific demand category worldwide and across international markets and regions.
By end use, food and beverages dominates the market through sustained emulsification demand
Food and beverages accounts for the largest end use share of the lecithin and phospholipids market, driven by sustained demand for emulsification across bakery, dairy, and processed food categories requiring reliable texture and shelf-life performance nationwide and beyond. Established suppliers maintain extensive food grade lecithin portfolios spanning multiple sources to serve this consistent, high volume demand base across global food manufacturing worldwide and internationally.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Pharmaceutical is growing quickly as liposomal and lipid nanoparticle drug delivery systems increasingly rely on high purity phospholipids for targeted therapeutic formulations requiring consistent, well characterised lipid compositions across formulations worldwide. In December 2025, Croda International announced a strategic supply partnership with Amino GmbH to strengthen global availability of high purity amino acids for pharmaceutical formulation and biomanufacturing applications internationally.
North America dominates the market through strong processed food demand and established supplier infrastructure
North America leads the lecithin and phospholipids market, supported by strong processed food demand and a concentration of major ingredient suppliers with established manufacturing and distribution infrastructure serving food, feed, and pharmaceutical customers nationwide and beyond. In September 2025, Gattefossé opened a new dedicated facility in Lufkin, Texas for lipid based pharmaceutical excipients, strengthening North American supply of high purity phospholipid ingredients and formulations across markets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is registering the fastest growth as expanding food processing industries and rising oilseed crushing capacity across China and India drive demand for lecithin-based emulsifiers across bakery, confectionery, and convenience food categories nationwide and beyond. In October 2025, Kewpie Corporation completed its acquisition of Aohata, expanding its fine chemicals business encompassing egg yolk lecithin and related ingredients across Japan's food and pharmaceutical sectors and supply chains internationally.
The global lecithin and phospholipids companies are becoming increasingly competitive as major lecithin and phospholipids companies invest in application specific product development, pharmaceutical grade purification technology, and clean label sourcing to differentiate their portfolios. Companies are prioritising non-GMO certification, allergen free labelling, and functional performance improvements to appeal to food, pharmaceutical, and cosmetic manufacturers seeking reliable, traceable emulsifier supply.
Major lecithin and phospholipids market players are also focusing on regional brand consolidation and strategic joint ventures to strengthen distribution networks across established and emerging markets. Strategic emphasis on liposomal drug delivery applications and plant-based sourcing diversification is allowing established companies to capture growing demand across pharmaceutical, cosmetic, and clean label food categories.
Founded in 1902 and headquartered in Chicago, Illinois, United States, ADM is one of the world's largest agricultural processing companies, offering lecithin and phospholipid ingredients across food, feed, and pharmaceutical applications. In August 2026, ADM announced plans to expand oilseed crush capacity at four United States plants with an estimated investment of approximately 100 million dollars, with six additional sites identified for potential future growth.
Founded in 1865 and headquartered in Wayzata, Minnesota, United States, Cargill is a global agricultural and food ingredient company offering a broad portfolio of soy, sunflower, and canola-based lecithin products. The company continues to invest in application specific emulsifier development to serve bakery, confectionery, and convenience food manufacturers.
Founded in 1925 and headquartered in Snaith, United Kingdom, Croda International is a global specialty chemicals company offering phospholipid and lecithin derived ingredients across pharmaceutical, cosmetic, and industrial applications. The company continues to expand its biotechnology research capabilities across Asian manufacturing operations.
Founded in 1978 and headquartered in Ludwigshafen, Germany, Lipoid is a specialised manufacturer of high purity phospholipids and lecithin ingredients serving pharmaceutical, cosmetic, and nutraceutical customers worldwide. In August 2025, Lipoid reached a construction milestone at its Cologne production site, with logistics, administration, and production areas ready for planned commissioning in 2026.
Other key players in the market include Stern-Wywiol Group, Sternchemie GmbH & Co. KG, VAV Life Sciences Pvt. Ltd., Fismer Lecithin GmbH, American Lecithin Company, and Kewpie Corporation., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our lecithin and phospholipids market trends 2026 report. Discover regional growth patterns, source and type economics, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 6.37 Billion.
The market is projected to grow at a CAGR of 6.30% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 11.73 Billion by 2035.
The major market drivers include expansion of the pharmaceutical sector and increasing consumption of baked goods.
The key trends fuelling the growth of the market include increased consumption of mayonnaise, hollandaise, and aioli and incorporation of lecithin and phospholipids in animal diet.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The end uses of lecithin and phospholipids include food and beverages, feed, confectionary, convenience food, and pharmaceutical, among others.
The key players in the market include Archer-Daniels-Midland Company, Cargill Incorporated, Croda International Plc, Lipoid GmbH, Stern-Wywiol Group, Sternchemie GmbH & Co. KG, VAV Life Sciences Pvt. Ltd., Fismer Lecithin GmbH, American Lecithin Company, and Kewpie Corporation., among others.
North America dominates the market, supported by strong processed food demand and a concentration of major ingredient suppliers.
Soy holds the largest source share, supported by established extraction infrastructure and cost-effective processing across global oilseed crushing facilities.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Source |
|
| Breakup by Type |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




