

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
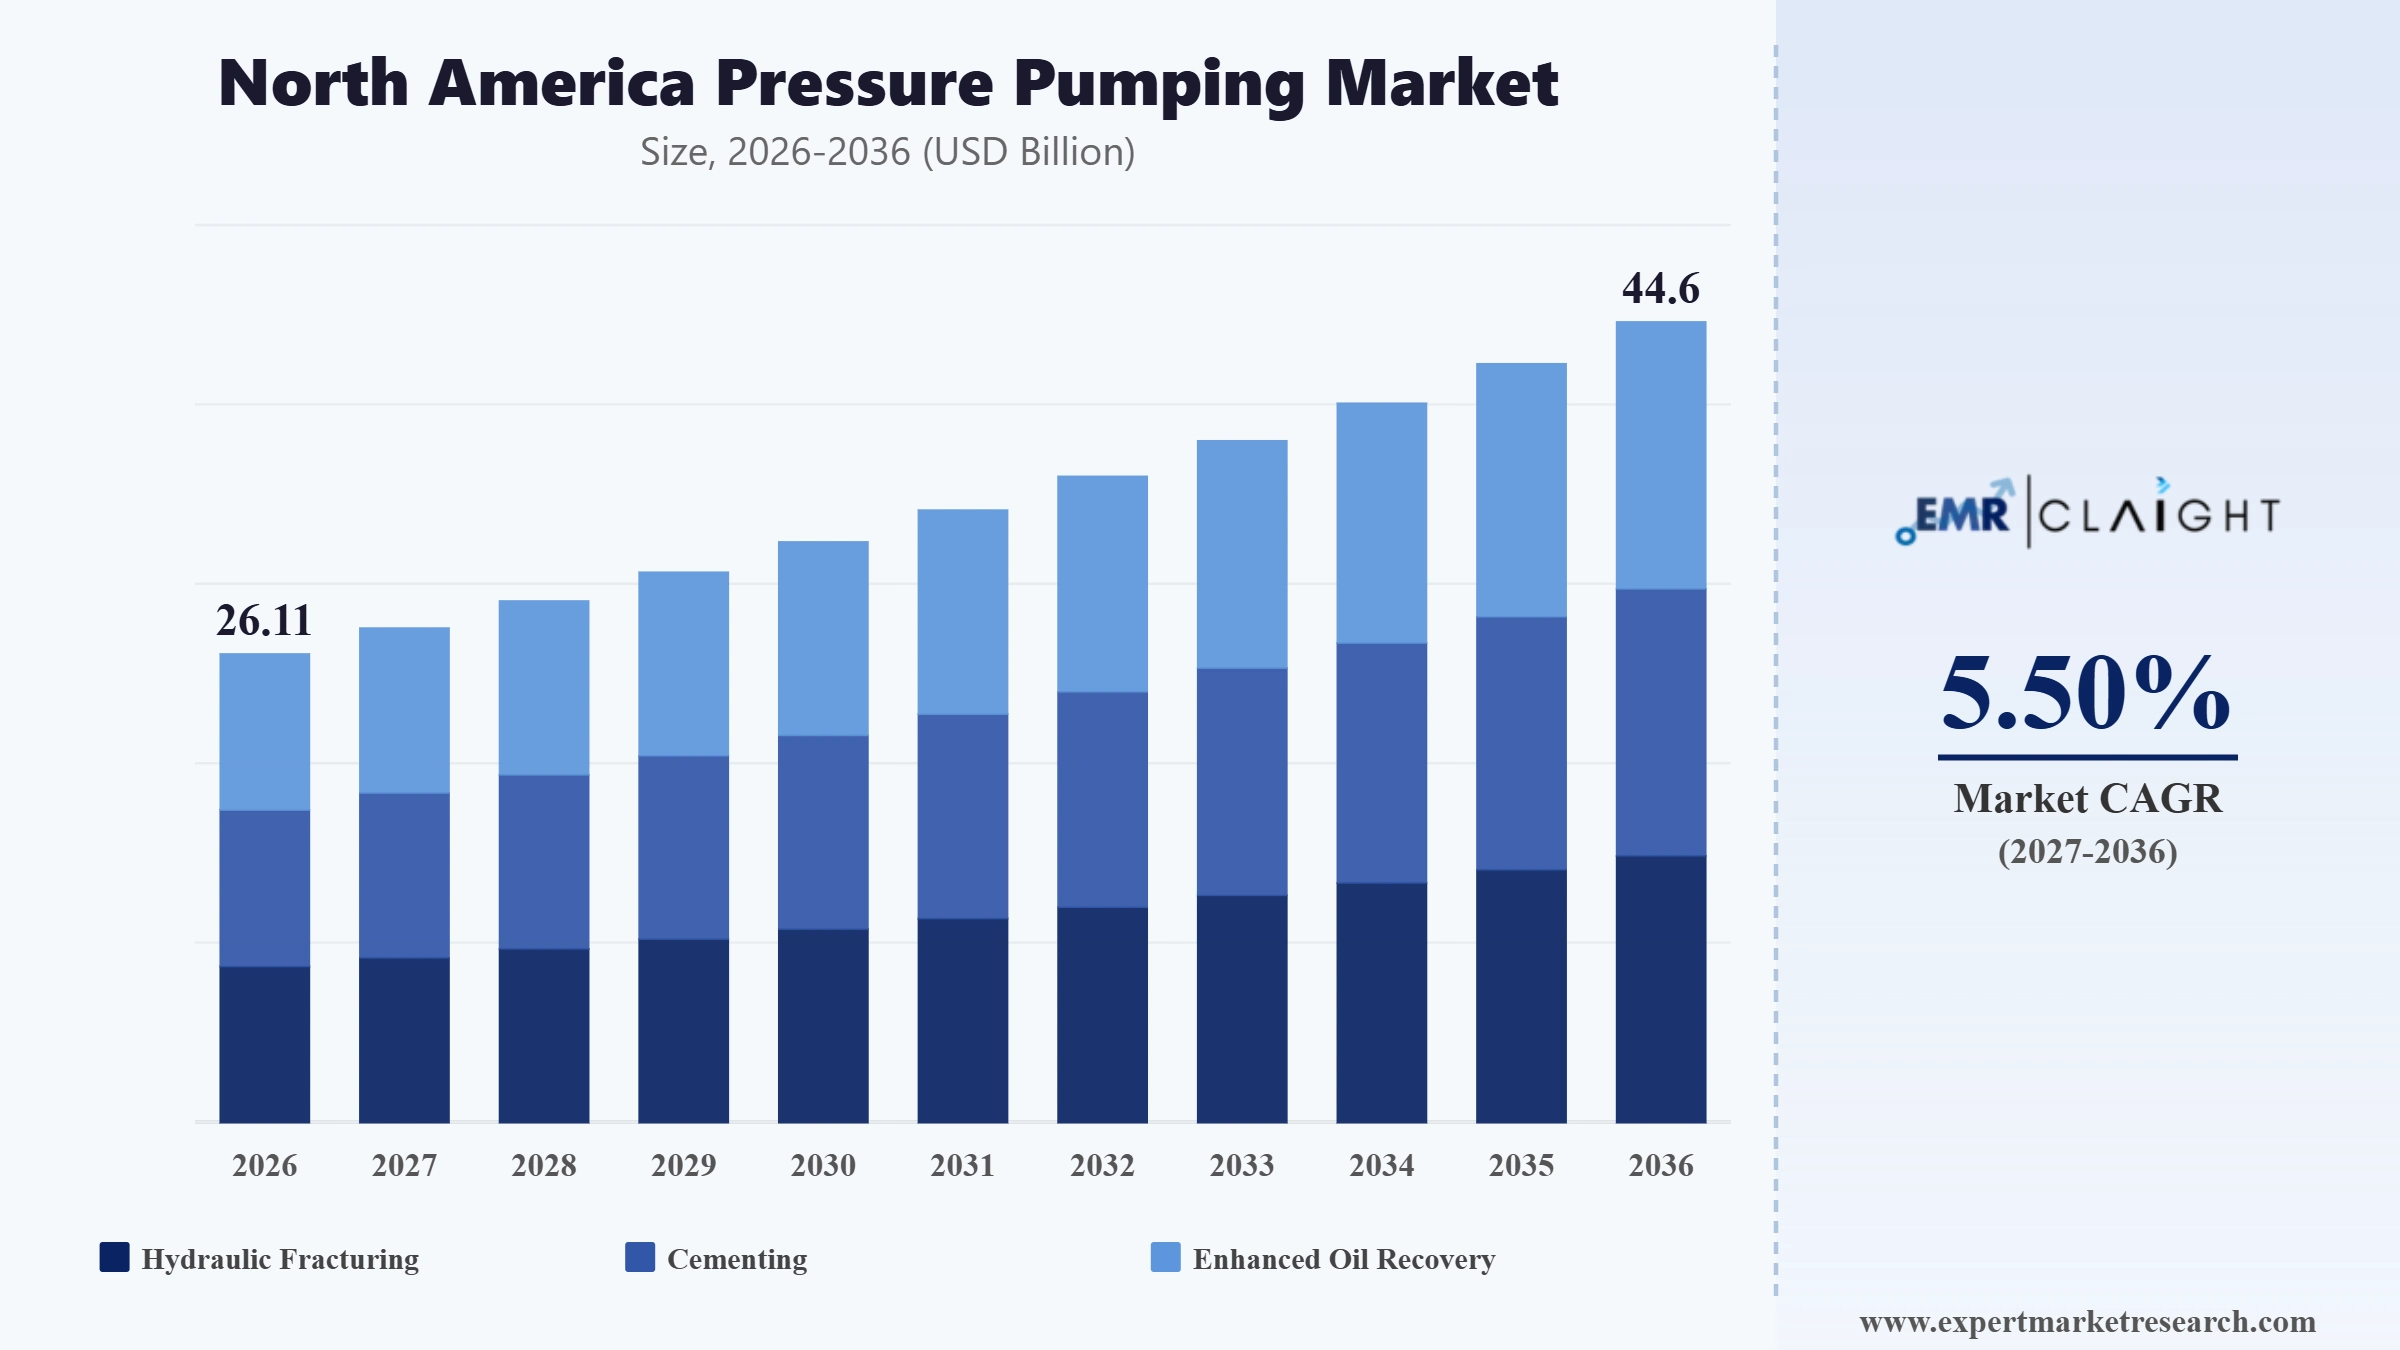
The North America pressure pumping market attained a value of USD 24.75 Billion in 2025 and is projected to expand at a CAGR of 5.50% through 2035. The market is further expected to reach USD 42.28 Billion by 2035. Rising unconventional oil and gas exploration, expanding shale development, and growing adoption of electric powered fracturing fleets are strengthening pressure pumping demand across the region. Expanding enhanced oil recovery operations, alongside continued horizontal drilling activity, are further encouraging service providers to widen their pressure pumping fleet capacity across every basin.
Pressure pumping refers to the process of using high pressure fluid to fracture rock formations, primarily to enhance the extraction of oil and gas from unconventional reservoirs. Hydraulic fracturing holds a substantial share of the market owing to its critical role in stimulating shale and tight oil formations across major North American basins. Rising unconventional resource development continues to widen the customer base for pressure pumping services among independent and major oil and gas operators.
Demand is concentrating around service providers able to combine electric fleet capability with diversified revenue streams beyond core pumping services. In October 2025, ProPetro confirmed in its third quarter results that its PROPWR power generation unit had secured a long-term contract to commit 60 megawatts of capacity to a hyperscale data centre customer, marking its entry into the data centre power market. This diversification driven positioning is converting rising demand for flexible power and pumping capability directly into expanded adoption across the North America pressure pumping market.
Service providers across the North America pressure pumping market are converging on a common development direction, widening from standalone fracturing services toward integrated power generation and automation capability. Companies are increasingly pursuing long term contracts with data centre operators and large independent producers to secure predictable utilization. This shift is reshaping competitive dynamics among providers, favouring companies who can demonstrate electric fleet capability and diversified power revenue over those offering standalone diesel fracturing alone.
Read more about this report - Request a Free Sample
Evolution Well Services signed a two-year contract extension for continued high efficiency electric hydraulic fracturing services with an existing customer, extending a relationship built on its fully electric frac fleet platform nationwide. The extension reflects sustained operator preference for electrified completions equipment. Companies across the North America pressure pumping market can use long term contract extensions to secure predictable utilization for their electric fleet investments and planning.
Atlas Energy Solutions completed full operational commissioning of Phase 1 of its Dune Express conveyor system, reaching throughput of 1.5 million tons per year ahead of the Permian Basin drilling season nationwide. The system supports direct mine to wellsite proppant delivery for Midland Basin operators. Companies across the North America pressure pumping market can use dedicated conveyor infrastructure to reduce trucking costs and improve proppant delivery reliability.
U.S. Silica completed a 1.2 million ton per year expansion of its in basin Permian Basin production capacity, reinforcing its regional supply position in response to sustained operator demand nationwide. The expansion supports locally sourced proppant with reduced logistics cost for regional operators. Companies across the North America pressure pumping market can use in basin capacity expansions to strengthen supply reliability against transportation bottlenecks and delays.
Solaris Energy Infrastructure reported deployment of its 600th Solaris Wellsite System unit, marking a milestone in automated proppant handling adoption across North American shale plays nationwide. The milestone reflects accelerating operator adoption of automated last mile logistics equipment. Companies can use automated proppant handling systems to reduce wellsite labour requirements and improve delivery consistency and reliability.
Wireline and completion service providers are increasingly pursuing targeted acquisitions to strengthen their presence in specific high activity basins rather than expanding broadly across every region, since basin specific expertise increasingly determines contract wins. This is reshaping competitive positioning across the North America pressure pumping market, favouring acquirers who can integrate specialised basin expertise quickly. In April 2025, RPC completed the acquisition of Pintail Completions, a leading Permian wireline perforation service provider, in a transaction valued at approximately 245 million dollars.
Operators are increasingly piloting fully automated fracturing execution platforms that remove manual stage decisions from the completions process entirely, since automation increasingly reduces variability across repeated stage sequences. This is reshaping service delivery models across the North America pressure pumping market, favouring providers who can support automated control integration. In January 2025, Coterra Energy and Halliburton launched North America's first fully automated hydraulic fracturing programme using the Octiv Auto Frac service.
Proppant suppliers are increasingly consolidating Northern White sand mining assets to secure premium reserves supporting performance sensitive hydraulic fracturing programmes, since reserve quality increasingly determines long term supply reliability for operators. This is reshaping supply chain structure across the North America pressure pumping market, favouring consolidators who can integrate mining and logistics operations. In August 2025, Iron Oak Energy acquired HC Minerals' Northern White sand assets, expanding its integrated proppant supply position.
Independent operators are increasingly advancing enhanced oil recovery programmes in mature basins to extend production life from existing wells rather than pursuing new drilling exclusively, since drilling costs increasingly exceed the economics of incremental recovery. This is reshaping service demand across the North America pressure pumping market, favouring providers who can support water injection and wellhead modification work. In September 2025, Empire Petroleum completed modified wellhead installations for its enhanced oil recovery programme in the Starbuck drilling project in North Dakota.
Diversified oilfield services companies are increasingly securing federal infrastructure contracts that redeploy existing power generation and gas conditioning assets beyond traditional completions work, since idle equipment increasingly represents an untapped revenue opportunity. This is reshaping revenue diversification strategy across the market, favouring companies who can service critical infrastructure customers. In March 2026, Flotek Industries won its first contract to deliver power services supporting federal disaster recovery infrastructure, coordinating installation of up to 50 megawatts of power generation equipment.
The Expert Market Research's report titled "North America Pressure Pumping Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Service Type
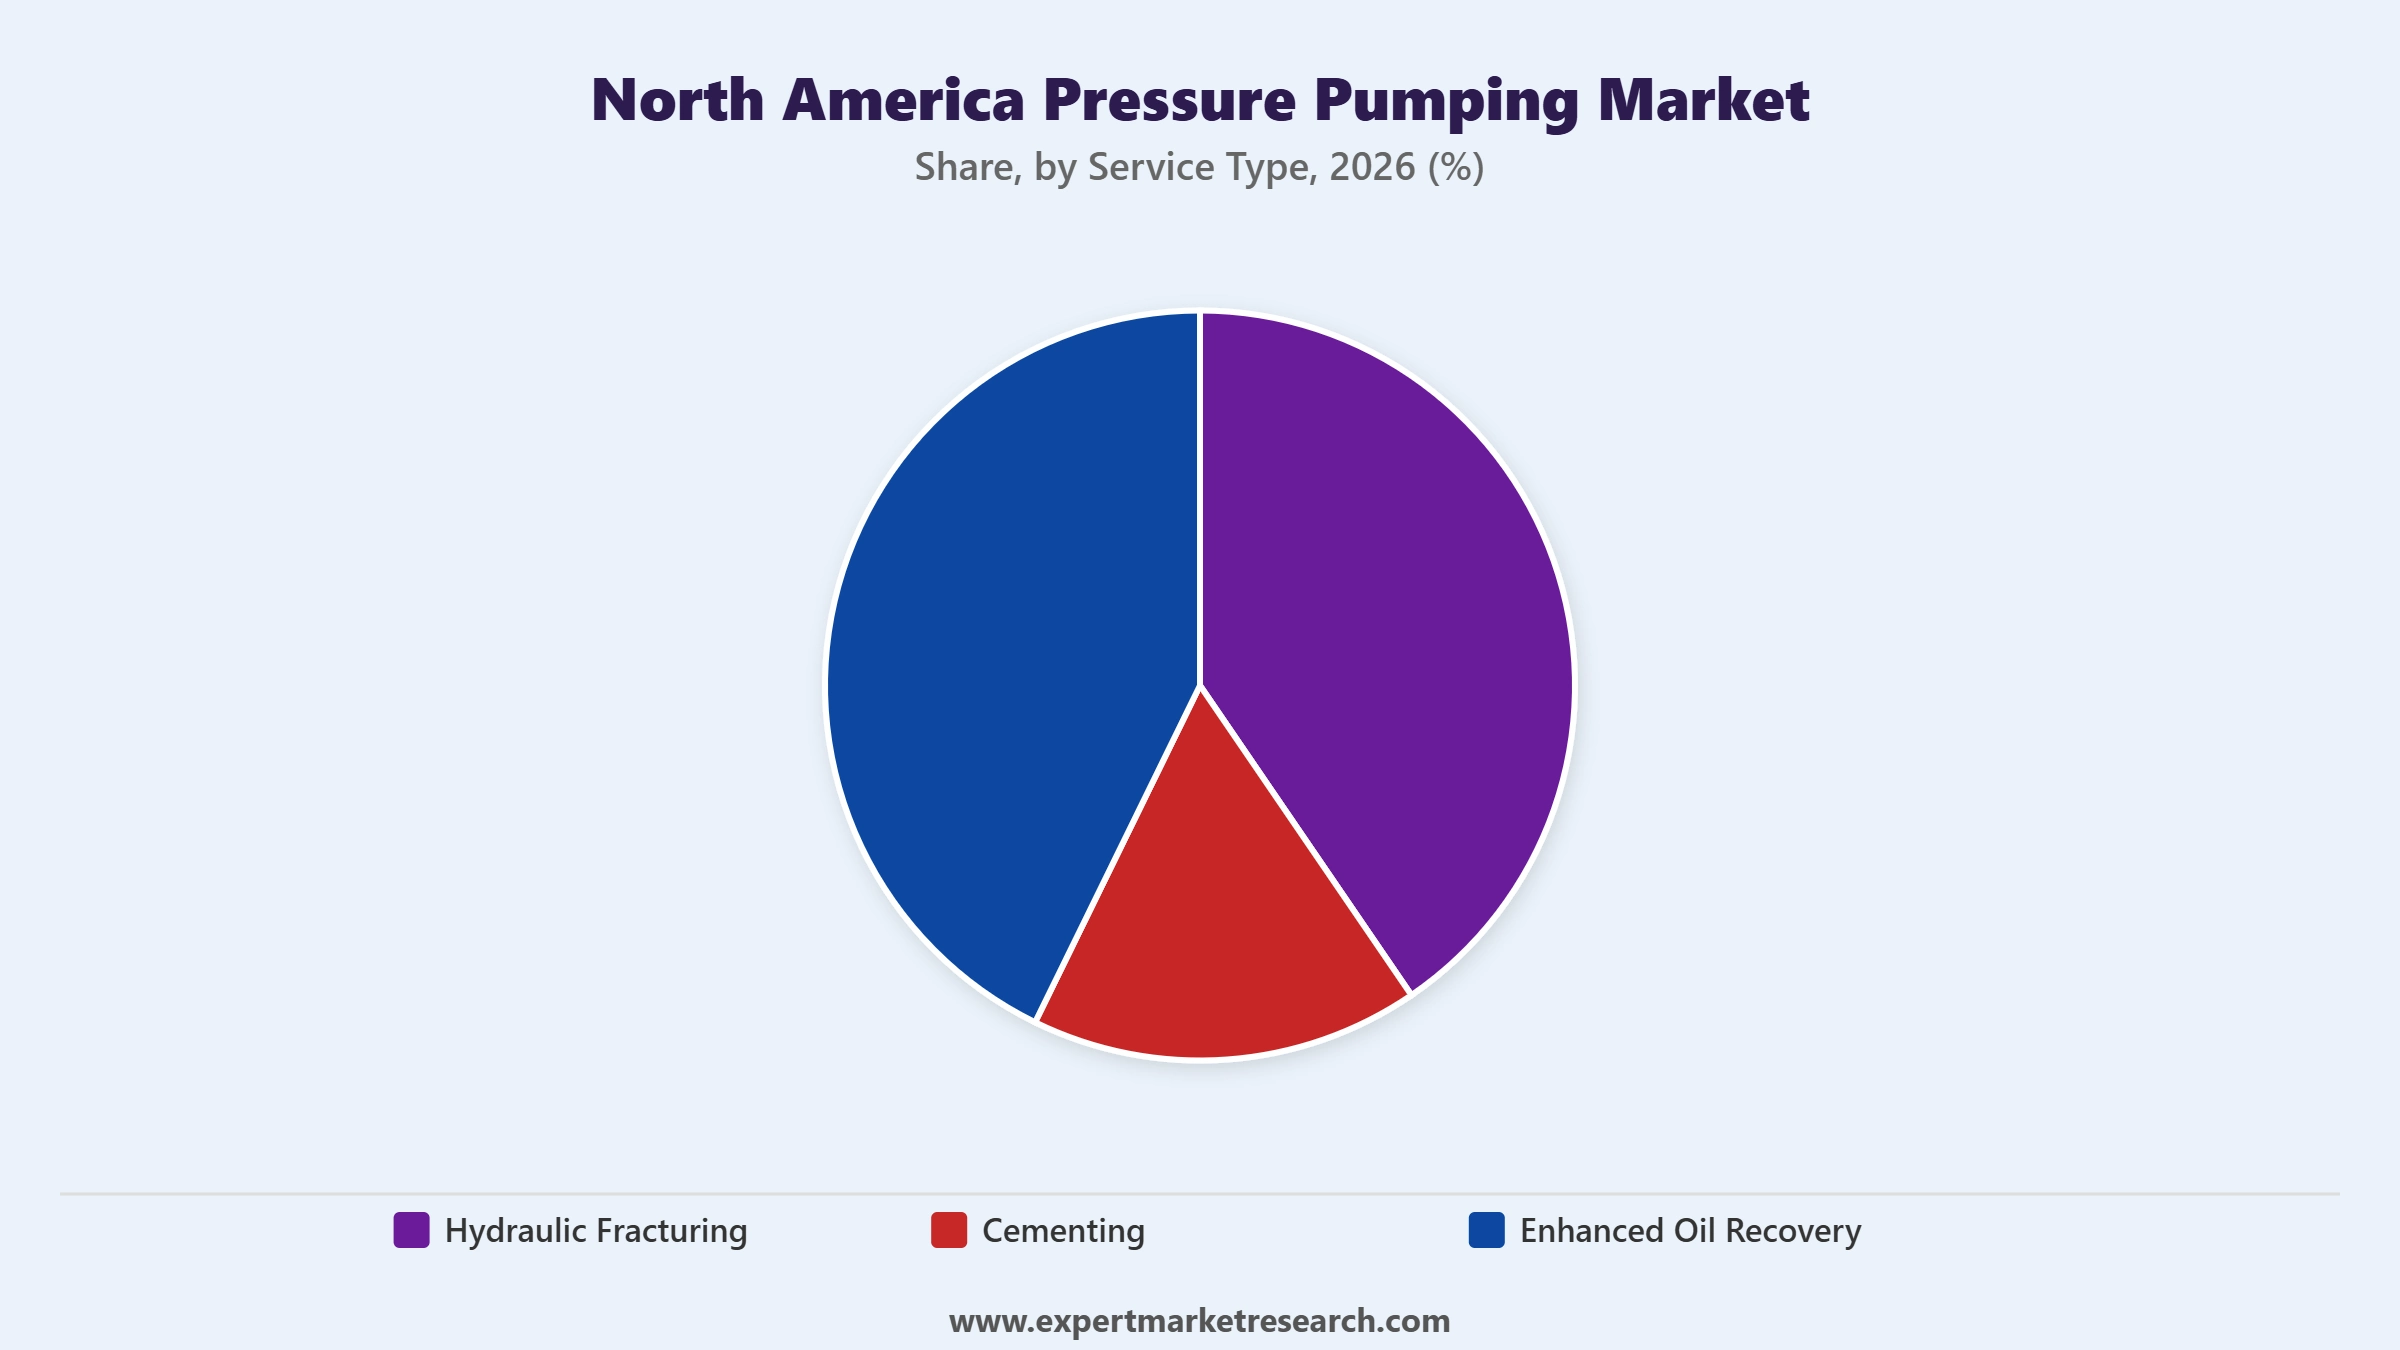
Key Insight: Hydraulic fracturing dominates the service type segment in the North America pressure pumping market given its critical role in stimulating shale and tight oil formations across major unconventional basins. Enhanced oil recovery is registering the fastest growth as operators increasingly turn to water injection and other recovery techniques to extend output from mature wells. In December 2025, Trican Well Service amended its bank agreement, extending facility maturity and increasing borrowing capacity to support continued investment across its pressure pumping service lines. Cementing sustains steady demand across well construction and completion activity, while other services, including acidizing and coiled tubing, round out remaining demand across specialised applications.
Market Breakup by Well Type
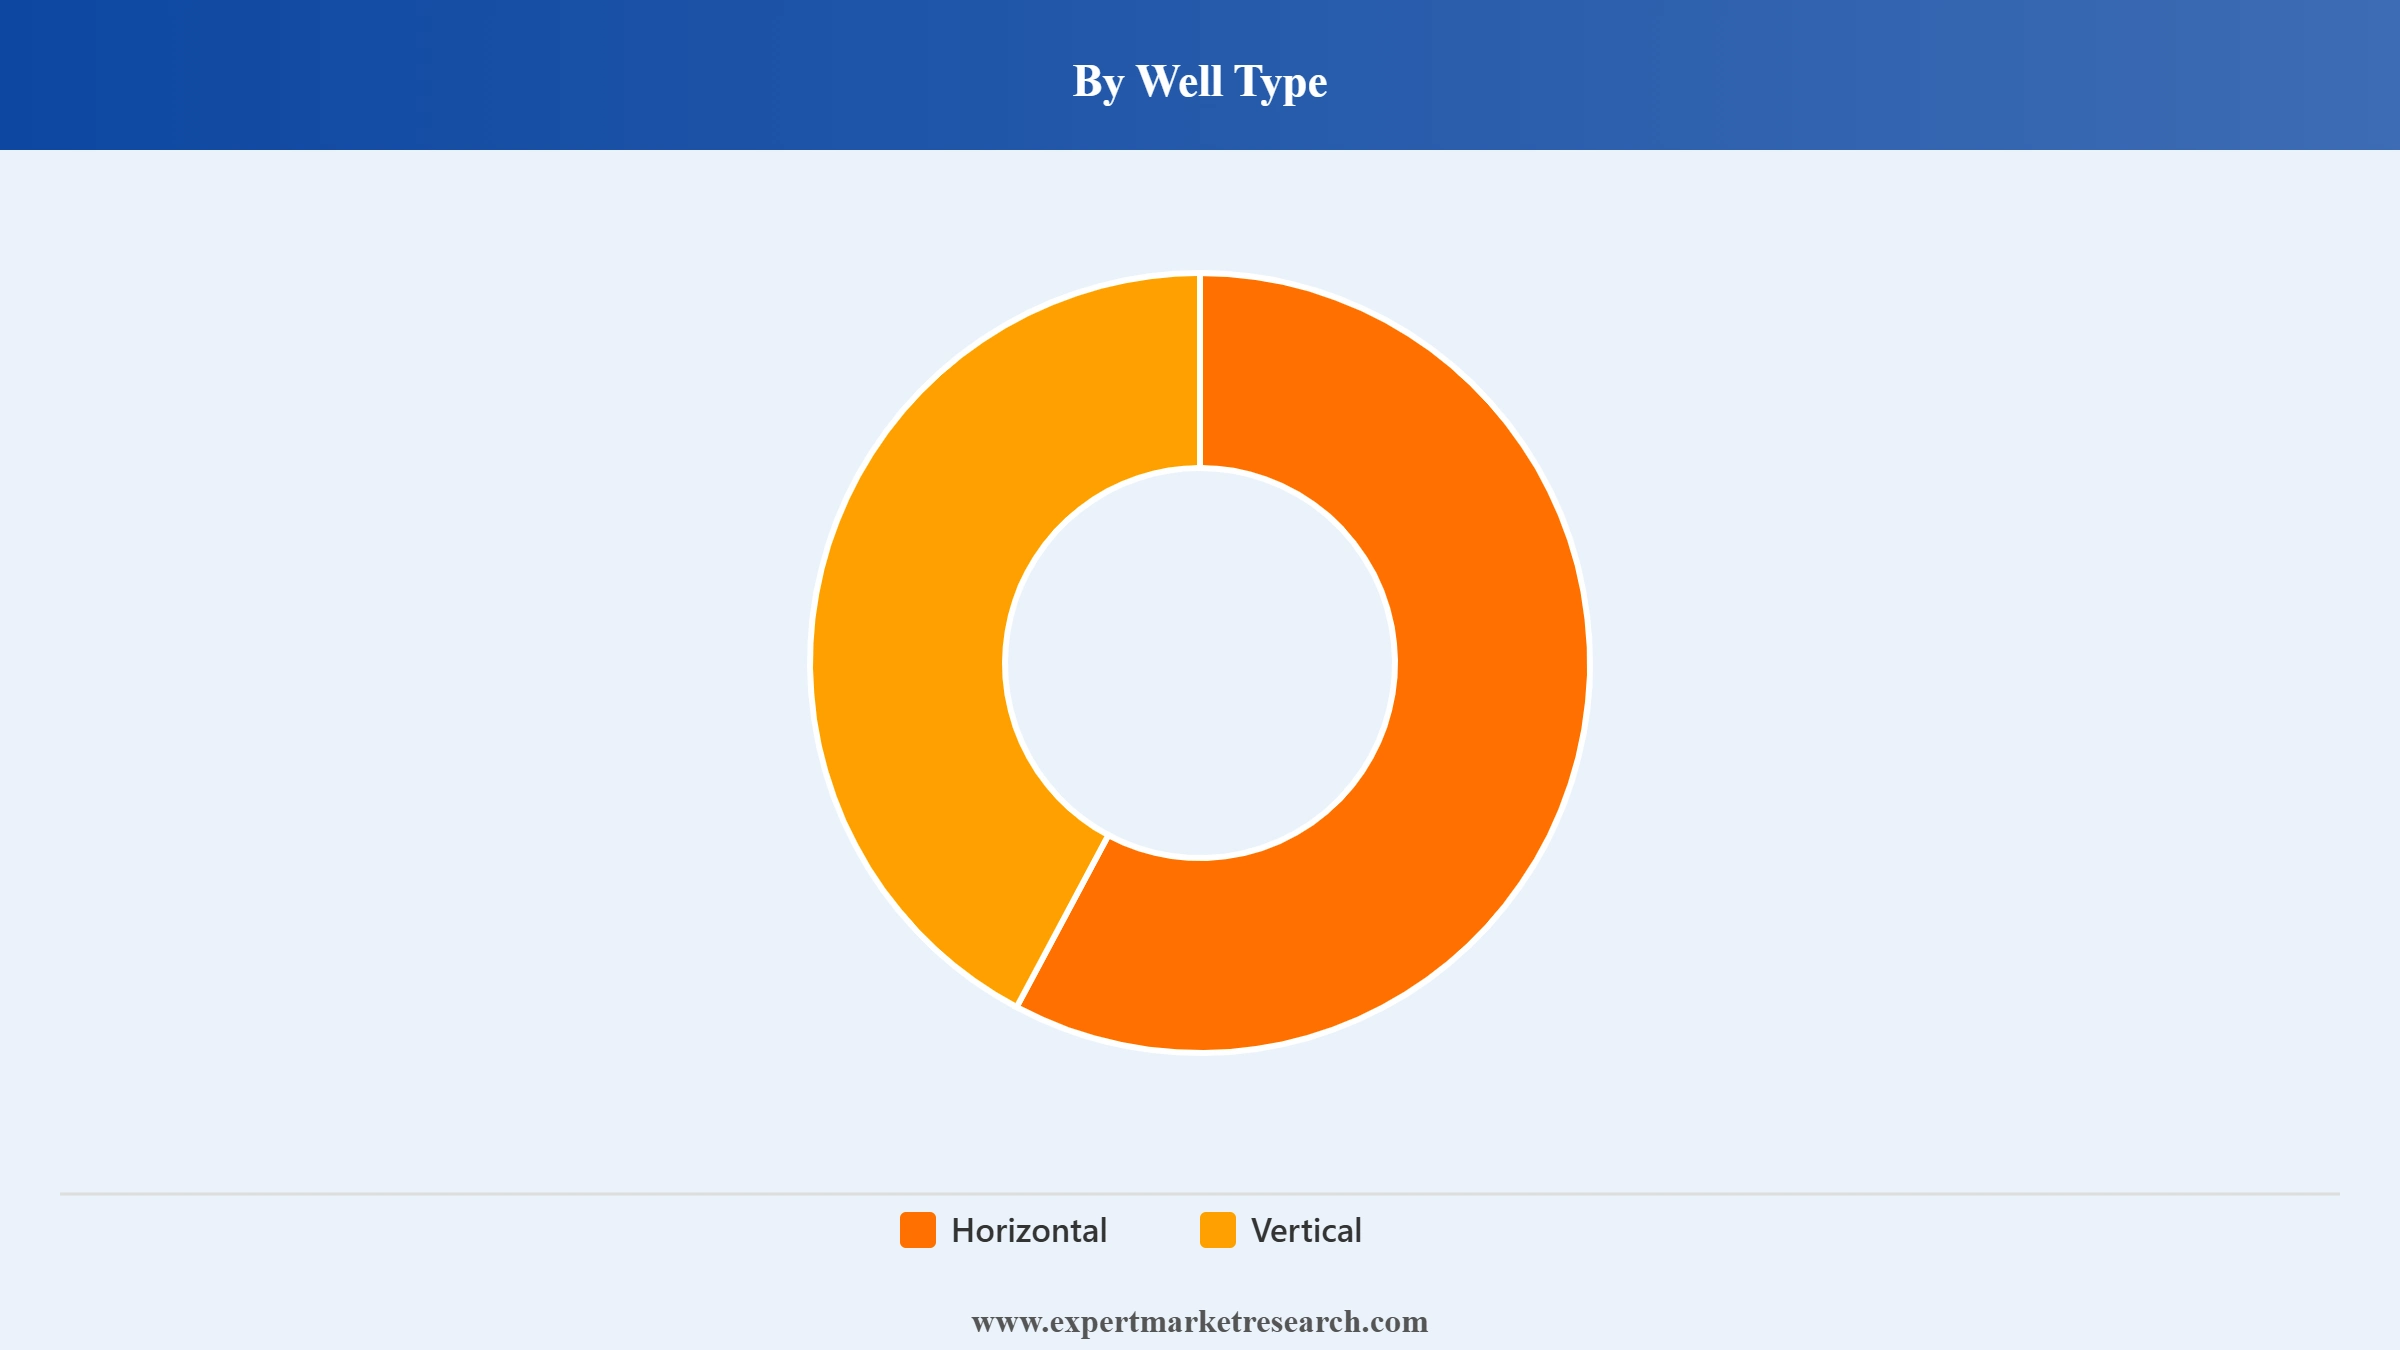
Key Insight: Horizontal wells dominate the well type of segment in the North America pressure pumping market given their ability to expose greater reservoir contact area and deliver higher production rates from unconventional formations. Vertical wells sustain steady demand across conventional and enhanced oil recovery applications where reservoir geometry favours simpler well architecture.
Market Breakup by Region
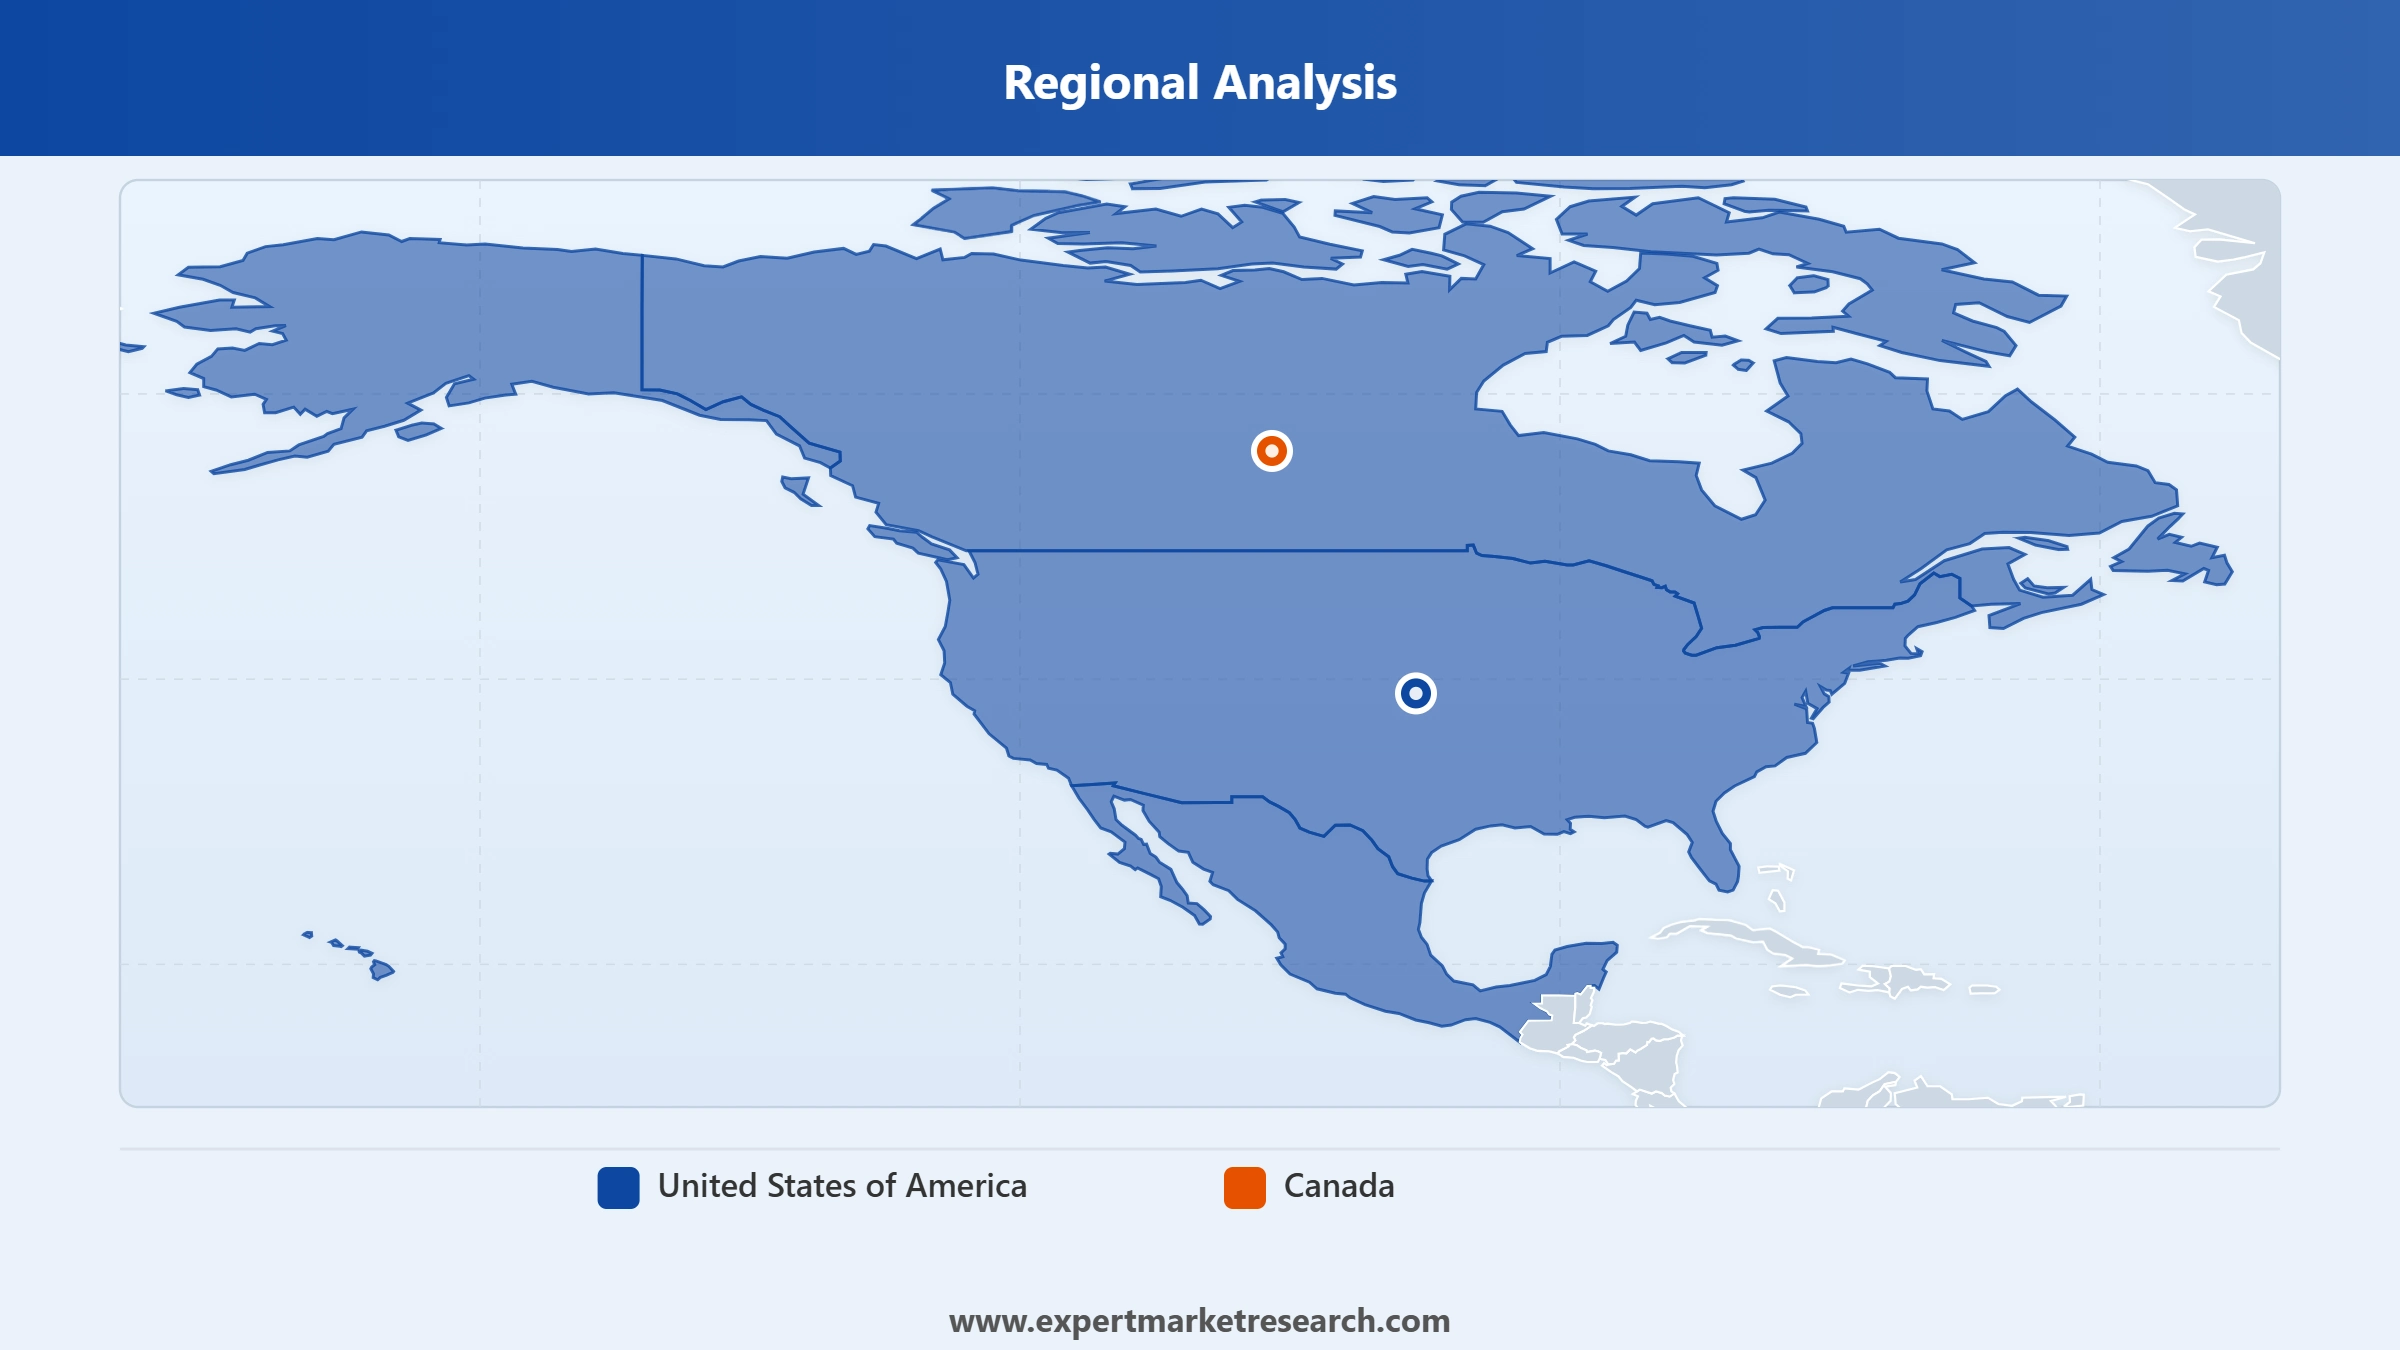
Key Insight: The United States dominates the region breakup in the North America pressure pumping market given its extensive shale resource base across the Permian, Bakken, and Haynesville basins and its concentration of pressure pumping fleet capacity. Canada sustains demand through its oil sands and Western Canadian Sedimentary Basin operations, with providers increasingly securing long term contracts to support recurring maintenance and completion activity.
Read more about this report - Request a Free Sample
By service type, hydraulic fracturing dominates the market owing to its critical role in stimulating shale and tight oil formations
Hydraulic fracturing dominates the service type segment of the North America pressure pumping market given its critical role in stimulating shale and tight oil formations across major unconventional basins nationwide, since alternative stimulation methods rarely match its cost efficiency and proven reliability at scale across every major operating basin. In February 2026, NexTier Oilfield Solutions launched eos, a digital completions platform designed to improve real time monitoring and operational control during hydraulic fracturing and well completion activities.
Read more about this report - Request a Free Sample
Enhanced oil recovery is registering the fastest service type growth as operators across the North America pressure pumping market increasingly turn to water injection and wellhead modification techniques to extend output from mature wells, since drilling new wells increasingly costs more than recovering bypassed reserves from existing field infrastructure. In February 2026, Occidental Petroleum confirmed during its fourth quarter earnings call that it would raise capital allocated to enhanced oil recovery in the Permian Basin by approximately 200 million dollars in 2026.
By well type, horizontal wells account for the largest share owing to greater reservoir contact area and higher production rates
Horizontal wells dominate the well type of segment across the North America pressure pumping market given their ability to expose greater reservoir contact area and deliver higher production rates from unconventional formations nationwide, since longer laterals increasingly reduce the total well count and surface footprint needed to develop acreage efficiently. In August 2026, the United States Energy Information Administration reported that super lateral wells exceeding 15,000 feet accounted for 15 percent of new Permian Basin well completions in 2025.
Read more about this report - Request a Free Sample
Vertical wells sustain steady well type demand across conventional and enhanced oil recovery applications where reservoir geometry favours simpler well architecture over complex lateral configurations, since thermal recovery processes typically depend on carefully paired injector and producer well arrangements nationwide. In December 2025, Canadian Natural Resources received regulatory approval for its Pike 2 steam assisted gravity drainage project, a thermal in situ development relying on vertical well pairs.
Read more about this report - Request a Free Sample
The United States leads the market through its extensive shale resource base and pressure pumping fleet capacity
The United States dominates the country breakup of the North America pressure pumping market given its extensive shale resource base across the Permian, Bakken, and Haynesville basins and its concentration of pressure pumping fleet capacity nationwide, since no other country matches this combined resource base and established service infrastructure. In December 2025, Chevron confirmed plans to spend nearly 6 billion dollars in 2026 across United States shale and tight assets, having drilled 210 wells in the Permian Basin during 2025.
Canada sustains demand through its oil sands and Western Canadian Sedimentary Basin operations, with providers increasingly securing long term contracts to support recurring maintenance and completion activity, since equipment providers value predictable multiyear revenue visibility over shorter term arrangements common across other markets. In July 2026, North American Construction Group was awarded a five-year heavy equipment services contract with a major Canadian oil sands customer, adding approximately 135 million dollars to its backlog.
The North American pressure pumping companies are becoming increasingly consolidated as major pressure pumping companies invest in electric fleet capability, automation, and diversified power revenue to defend their market positions. Pressure pumping players are prioritising emissions reduction, contract diversification, and expanded service scope to differentiate their offerings in a capital intensive and increasingly competitive landscape.
Major North American pressure pumping market players are also focusing on data centre power partnerships, pursuing long term contracts to redeploy mobile power assets beyond core fracturing operations. Opportunities are emerging in enhanced oil recovery services and Canadian oil sands maintenance contracts. Companies that successfully combine electric fleet capability with diversified revenue streams are expected to strengthen their competitive position over the coming years.
Founded in 1907 and headquartered in Houston, Texas, United States, Baker Hughes Company supports the pressure pumping market through its integrated well construction and completion services portfolio, serving operators across major North American basins. The company continues to expand its digital fracturing monitoring capabilities. Baker Hughes draws on its position as one of the world's largest oilfield technology companies to serve a broad customer base across upstream operations.
Founded in 1919 and headquartered in Houston, Texas, United States, Halliburton Energy Services, Inc. contributes to the pressure pumping market through its Zeus intelligent fracturing platform and electric pumping units. The company continues to expand automated fracturing capability across its customer base. Halliburton draws on more than a century of well cementing and completion expertise distinguishing it as a founding company in the pressure pumping sector.
Founded in 1926 and headquartered in Houston, Texas, United States, Schlumberger Limited supports the pressure pumping market through its integrated hydraulic fracturing and well stimulation services portfolio. The company continues to expand its digital reservoir characterisation capabilities alongside completion services. Schlumberger draws on its position as the world's largest oilfield services company to serve operators across every major North American basin.
Founded in 1941 and headquartered in Houston, Texas, United States, Weatherford International plc contributes to the pressure pumping market through its well construction, completions, and production intervention service lines. The company continues to expand its pressure pumping and artificial lift offerings across North American operations. Weatherford draws on decades of consolidated oilfield service expertise built through more than 300 acquisitions since its establishment.
Other key players in the market include Calfrac Well Services Ltd., Clariant International Ltd, RPC, Inc., Chevron Corporation, NexTier Completion Solutions, Inc., and Trican Well Service Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our North america pressure pumping market trends 2026 report. Discover country level growth patterns, service type economics, and key industry players. Stay ahead of the competition and identify emerging opportunities in the evolving North America pressure pumping market landscape.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 5.50% between 2026 and 2035.
Expanding electric fleet capacity, diversifying into data centre power generation, pursuing automated fracturing platforms, strengthening enhanced oil recovery service lines, and securing long term Canadian oil sands contracts are key strategies driving the market.
Key trends aiding market expansion include the emergence of waterless fracking, potential increase in recoverable resources and production, and government incentives and initiatives.
Major regions in the market are the United States and Canada.
Pressure pumping is utilised for the extraction of unconventional resources like shale gas.
The key players in the market include Baker Hughes Company, Halliburton Energy Services, Inc., Schlumberger Limited, Weatherford International plc, Calfrac Well Services Ltd., Clariant International Ltd, RPC, Inc., Chevron Corporation, NexTier Completion Solutions, Inc., and Trican Well Service Ltd., among others.
Unconventional oil and gas resources include shale, tight gas, coal bed methane, among others.
In 2025, the market reached an approximate value of USD 24.75 Billion.
Providers face capital intensity of electric fleet conversion, volatile commodity prices, tightening emissions regulations, and the need to secure long term contracts amid cyclical drilling activity.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Service Type |
|
| Breakup by Well Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




