

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The soft drink concentrates market was valued at USD 40.04 Billion in 2025. The market is expected to grow at a CAGR of 5.70% during the forecast period of 2026-2035 to reach a value of USD 69.70 Billion by 2035. Rising demand for ready-to-dilute beverage formats, expanding foodservice and quick-service restaurant channels, and manufacturer investment in dedicated fruit and flavour processing infrastructure are collectively driving the market growth.
The current soft drink concentrates market dynamics reflect continued consumer preference for familiar, value-oriented beverage formats alongside steady bottler reinvestment in packaging capacity. In September 2026, Arca Continental Coca-Cola Southwest Beverages completed a 42-million-dollar expansion of its bottling plant on the eastside of San Antonio, Texas, adding a second production line across 170,000 square feet of new space and roughly 80 new employees. This expansion, enabling faster canning throughput, illustrates how bottling partners are scaling capacity to keep pace with growing regional concentrate-based beverage demand.
The overall soft drink concentrates industry dynamics through 2025 and 2026 are being shaped by continued modernisation of legacy concentrate production lines among established manufacturers. In February 2026, Suntory revealed a GBP 25 million expansion of its Coleford factory in the United Kingdom, part of a wider GBP 57 million investment programme installing a new production line to consolidate Ribena concentrate and ready to drink output. Such upgrades underscore the sustained capital commitment flowing into modernising concentrate-dependent manufacturing infrastructure across mature Western markets.
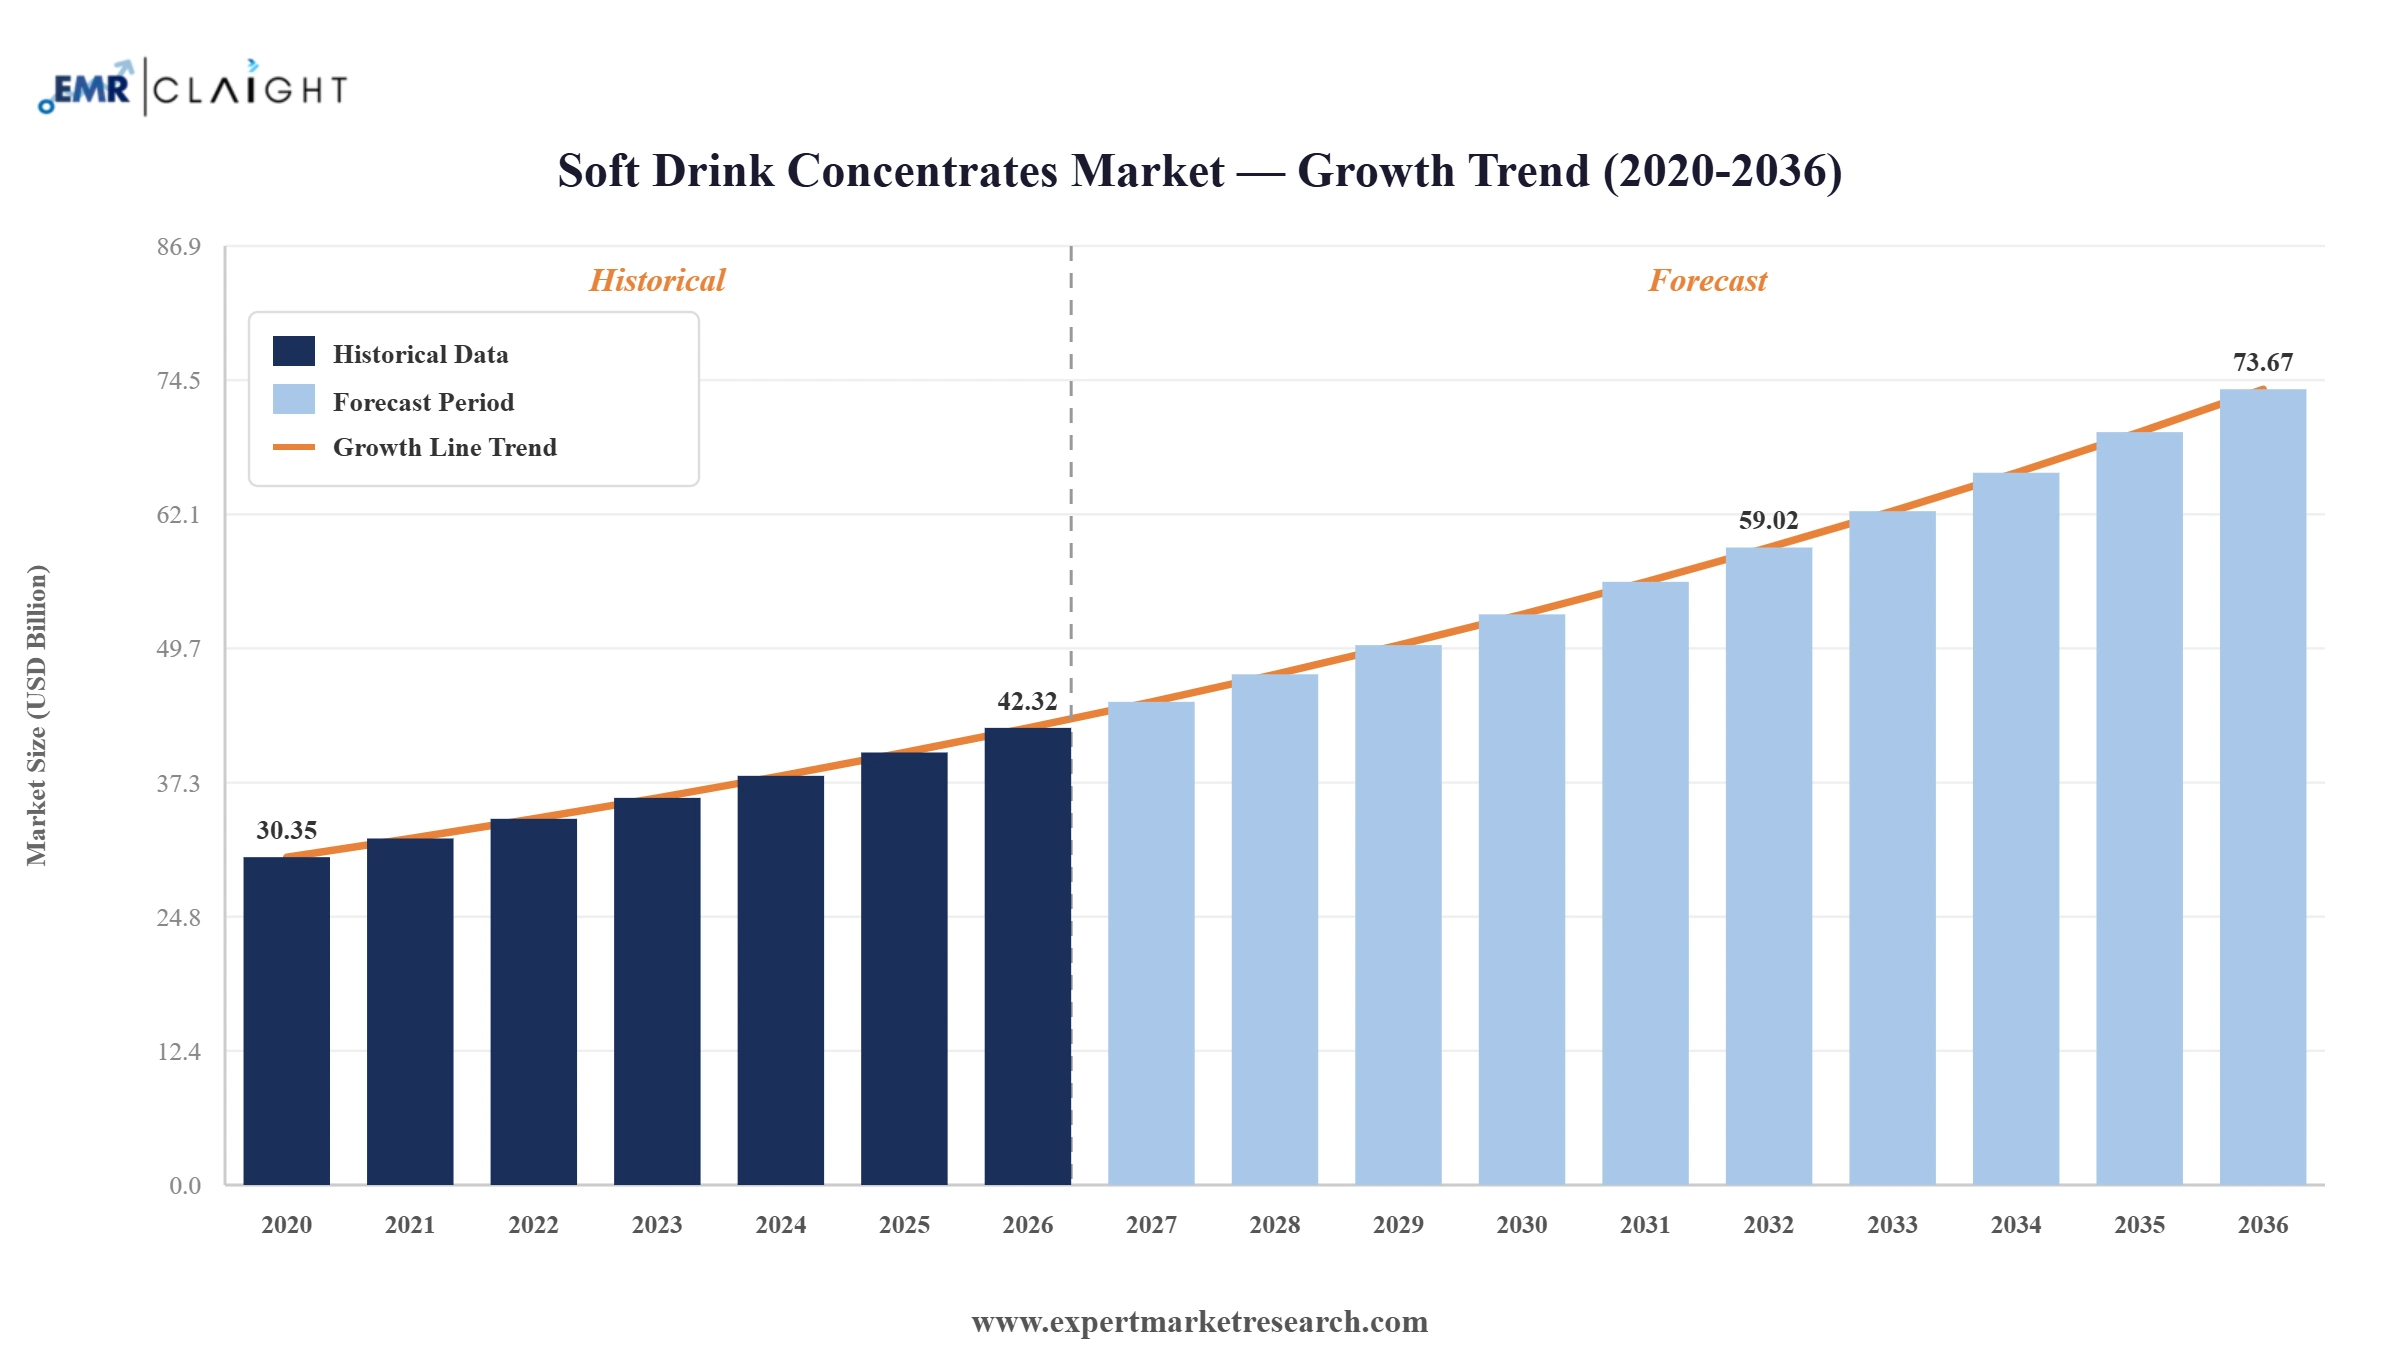
Read more about this report - Request a Free Sample
|
Soft Drink Concentrates Market Report Summary |
Description |
Value |
|
Base Year |
USD Billion |
2025 |
|
Historical Period |
USD Billion |
2019-2025 |
|
Forecast Period |
USD Billion |
2026-2035 |
|
Market Size 2025 |
USD Billion |
40.04 |
|
Market Size 2035 |
USD Billion |
69.70 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
5.70% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
7.6% |
|
CAGR 2026-2035 - Market by Product Type |
Non-Carbonated Concentrates |
6.8% |
|
CAGR 2026-2035 - Market by Flavor |
Fruit Punch |
7.8% |
|
2025 Market Share by Region |
North America |
34.2% |
The soft drink concentrates market is being reshaped by continued premium brand consolidation, manufacturer investment in dedicated fruit and flavour processing infrastructure, and growing non-carbonated and reduced-sugar product innovation. Expanding foodservice demand across Asia Pacific and sustained squash and cordial brand loyalty in Europe are further reshaping the competitive landscape.
Suntory invested GBP 14.5 million in a new blackcurrant processing facility in Ledbury, Herefordshire, developed with Dohler Group's Bevisol operation to future proof Ribena concentrate production for years ahead. The facility uses advanced evaporators to modernise fruit preparation for roughly 10,500 tonnes of UK blackcurrants annually. Manufacturers across the soft drink concentrates market can leverage this by co-investing in dedicated fruit processing infrastructure to secure supply.
Keurig Dr Pepper rolled out Canada Dry Fruit Splash Strawberry nationally as part of a portfolio of more than 35 new beverage varieties introduced that month, made with real juice and positioned within its wider zero sugar carbonated soft drink push across North America. Manufacturers across the soft drink concentrates market can diversify flavoured carbonated concentrate portfolios to capture younger consumers seeking lower sugar options nationwide.
AG Barr acquired premium soft drinks and mixer brands Fentimans and Frobishers, strengthening its portfolio of botanical and fruit juice concentrate offerings sold across United Kingdom retail and foodservice channels, alongside its core carbonated and squash ranges built over decades. Manufacturers across the soft drink concentrates market can therefore broaden premium concentrate brand portfolios through targeted acquisitions rather than solely relying on organic product development efforts.
Monin invested roughly INR 350 crore in a new syrup and concentrate manufacturing plant spread across 40 acres in Sangareddy, near Hyderabad, India, targeting INR 500 crore in annual revenue within three years of commissioning the new operations across domestic markets. Companies can therefore establish dedicated regional manufacturing capacity to serve growing foodservice and retail demand for flavoured syrup concentrates.
Bottling partners across the soft drink concentrates market are expanding glass and canning capacity to keep pace with concentrate producers' growing retail demand, particularly for premium and returnable formats favoured by consumers. Such investments help the wider market by strengthening downstream capacity without requiring concentrate manufacturers themselves to expand. For example, in May 2026, Coca-Cola Consolidated announced a USD 35 million investment in a new glass bottle production line at its Indianapolis, Indiana facility, creating 15 to 20 new positions.
Concentrate-based beverage manufacturers are investing in canning line automation to raise throughput and meet rising demand for recyclable, multipack formats across UK and European retail channels. This trend reduces per-unit production costs while supporting continued private-label and branded concentrate soft drink volume growth across the region. For example, in October 2025, Carlsberg Britvic invested GBP 20 million in a new canning line at its Rugby factory, lifting production capacity from 560,000 to 610,000 cans per hour and creating 34 jobs.
Flavour and beverage ingredient suppliers across the soft drink concentrates market are expanding manufacturing footprints into new geographies to shorten supply chains for concentrate and extract-based ingredients used across the soft drink concentrates industry. This diversification helps ingredient suppliers reduce reliance on single-region production while serving multiple beverage categories simultaneously. For example, in September 2025, Kerry Group opened its first Pennsylvania manufacturing facility in the Lehigh Valley for coffee roasting and extraction, creating 61 new jobs and supporting its broader beverage ingredients platform across North America.
Concentrate-dependent bottling partners across the soft drink concentrates market are increasingly designing new production facilities to meet recognised sustainability certification standards rather than retrofitting older plants after construction has already been completed. This shift is embedding environmental considerations directly into capacity expansion decisions across the soft drink concentrates value chain more broadly. For example, in December 2025, Swire Coca-Cola announced a USD 475 million, 620,000 square foot bottling facility in Colorado Springs that will pursue LEED Gold certification while replacing a 90-year-old production plant.
Established squash and cordial brands across the soft drink concentrates market are introducing new double strength concentrate variants to refresh their core ranges and attract younger shoppers seeking reduced sugar options with added vitamins. Such expansions reinforce legacy brand relevance within mature concentrate categories while supporting continued overall market growth across retail channels. For example, in May 2025, Capri-Sun launched three new double strength squash variants exclusively through Asda stores across the United Kingdom, each enriched with vitamins C and D and containing no added sugar.
The Expert Market Research's report titled "Soft Drink Concentrates Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
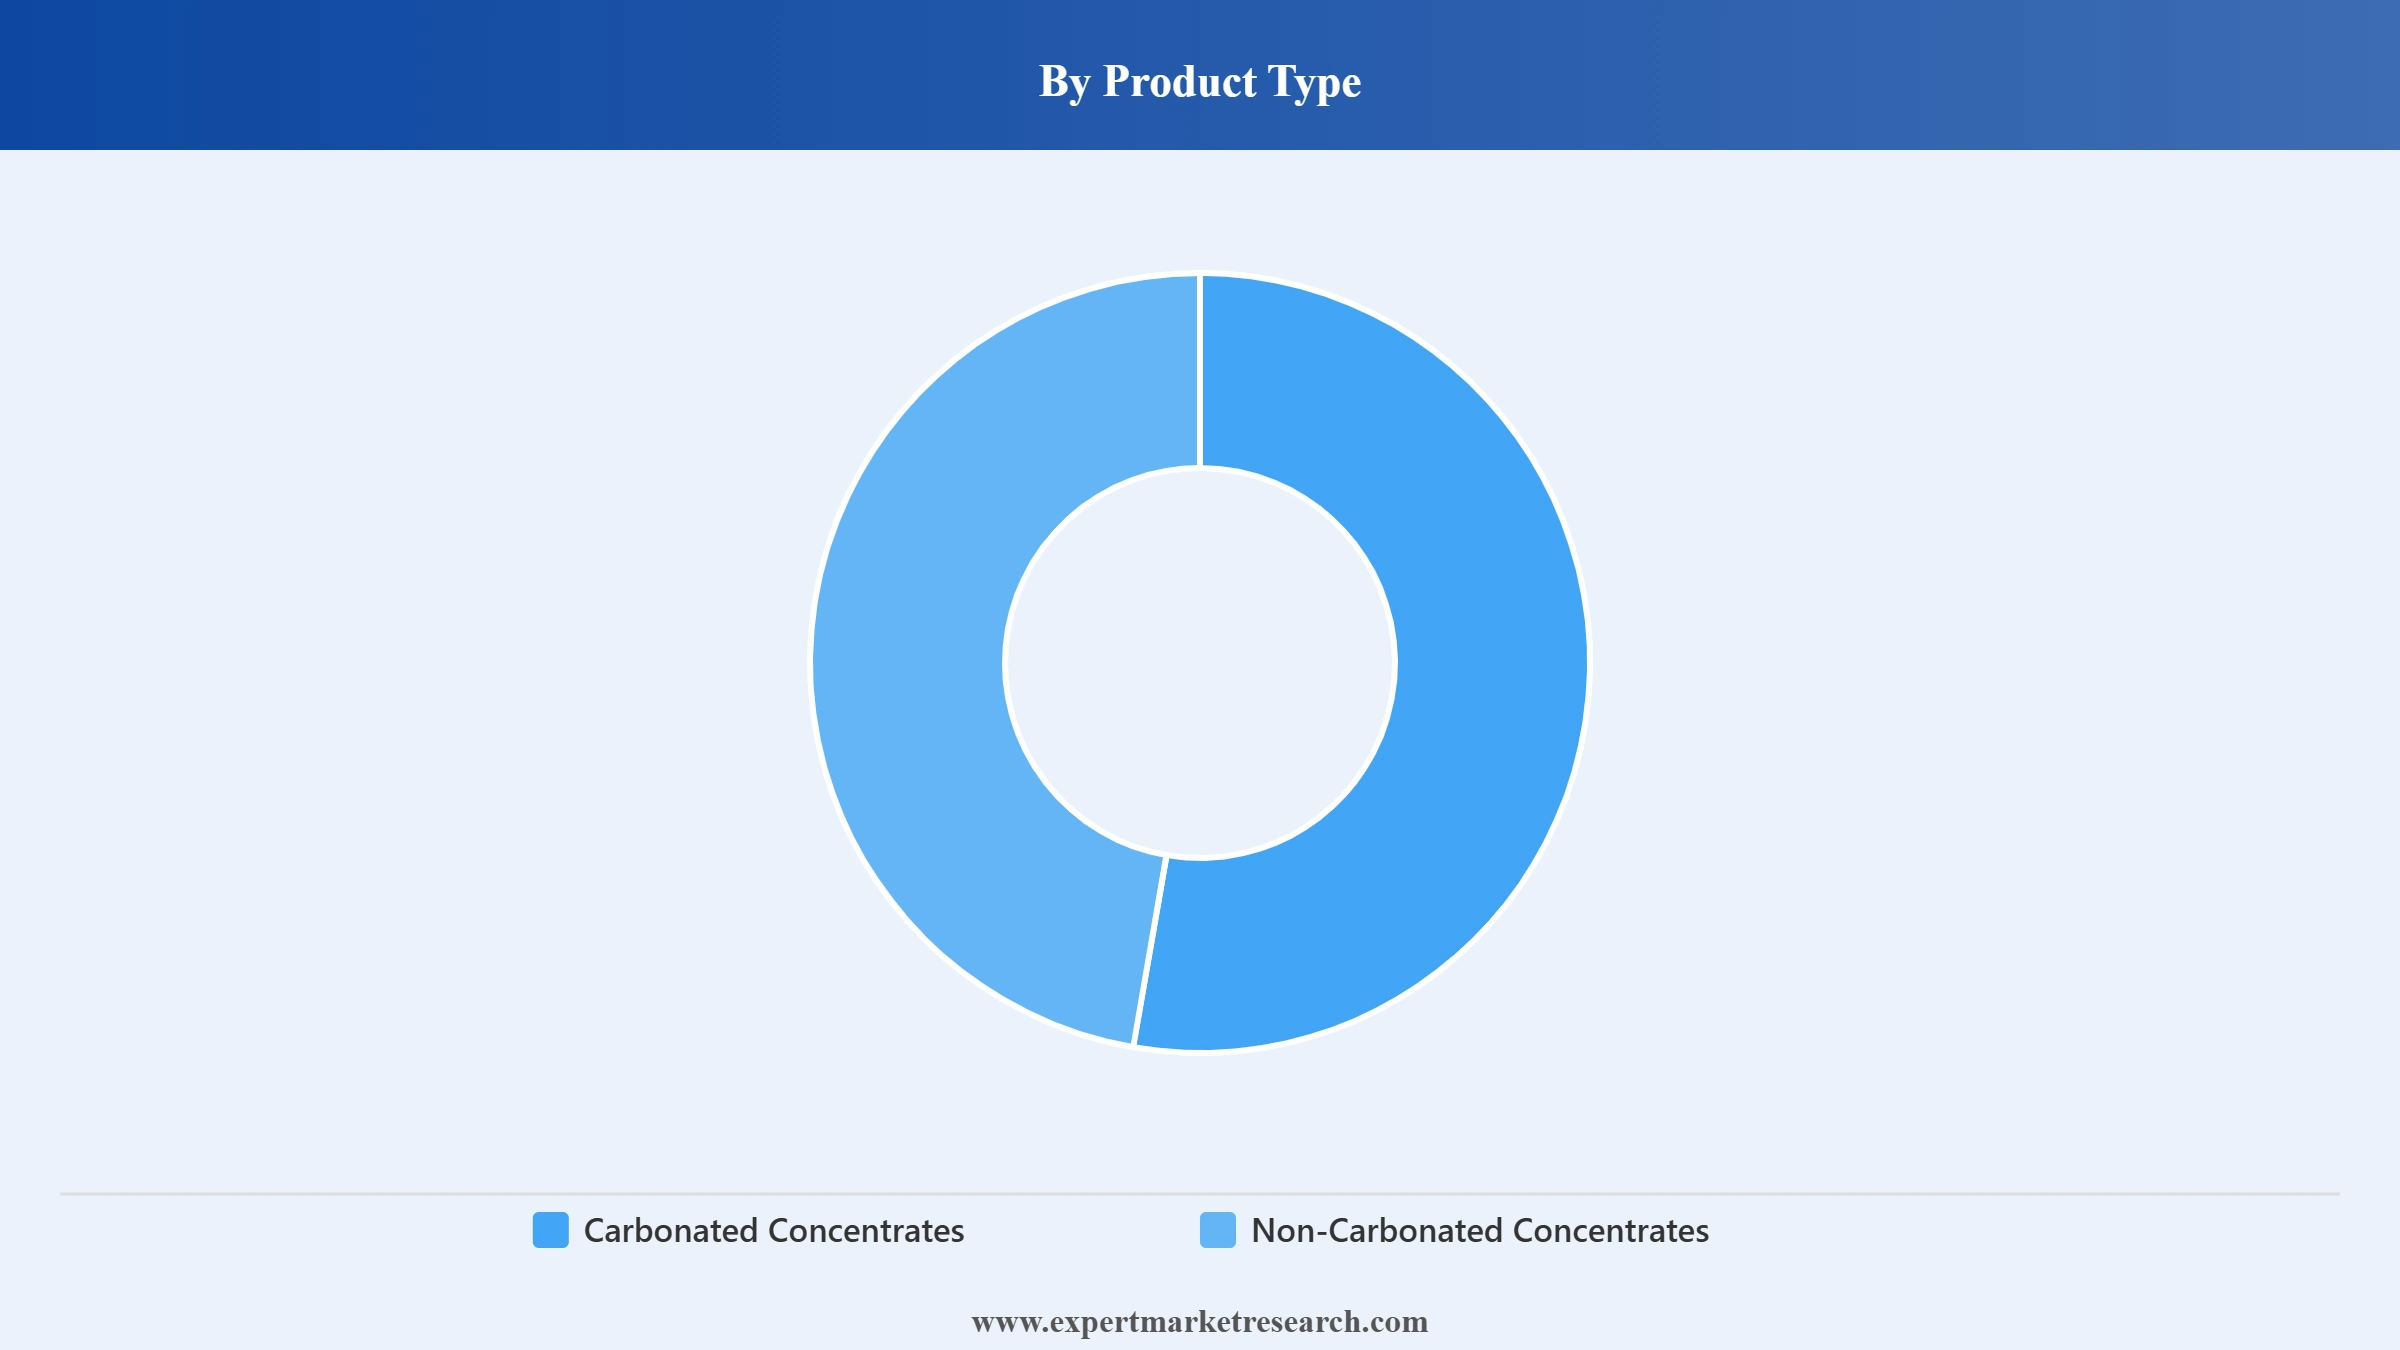
Key Insight: Carbonated concentrates account for the largest share of the soft drink concentrates market by product type, reflecting enduring consumer demand for traditional cola and citrus formats across established retail and foodservice channels worldwide. Non-carbonated concentrates are the fastest-growing product type as manufacturers reformulate toward reduced-sugar and functional positioning to attract health-conscious consumers. Demonstrating such shifts in the industry, in January 2026, The Coca-Cola Company began rolling out single-serve 7.5-ounce mini cans across Original Taste, Zero Sugar, Cherry, Sprite, and Fanta Orange variants into convenience stores nationwide, extending accessible, portion-controlled carbonated formats.
Market Breakup by Flavor
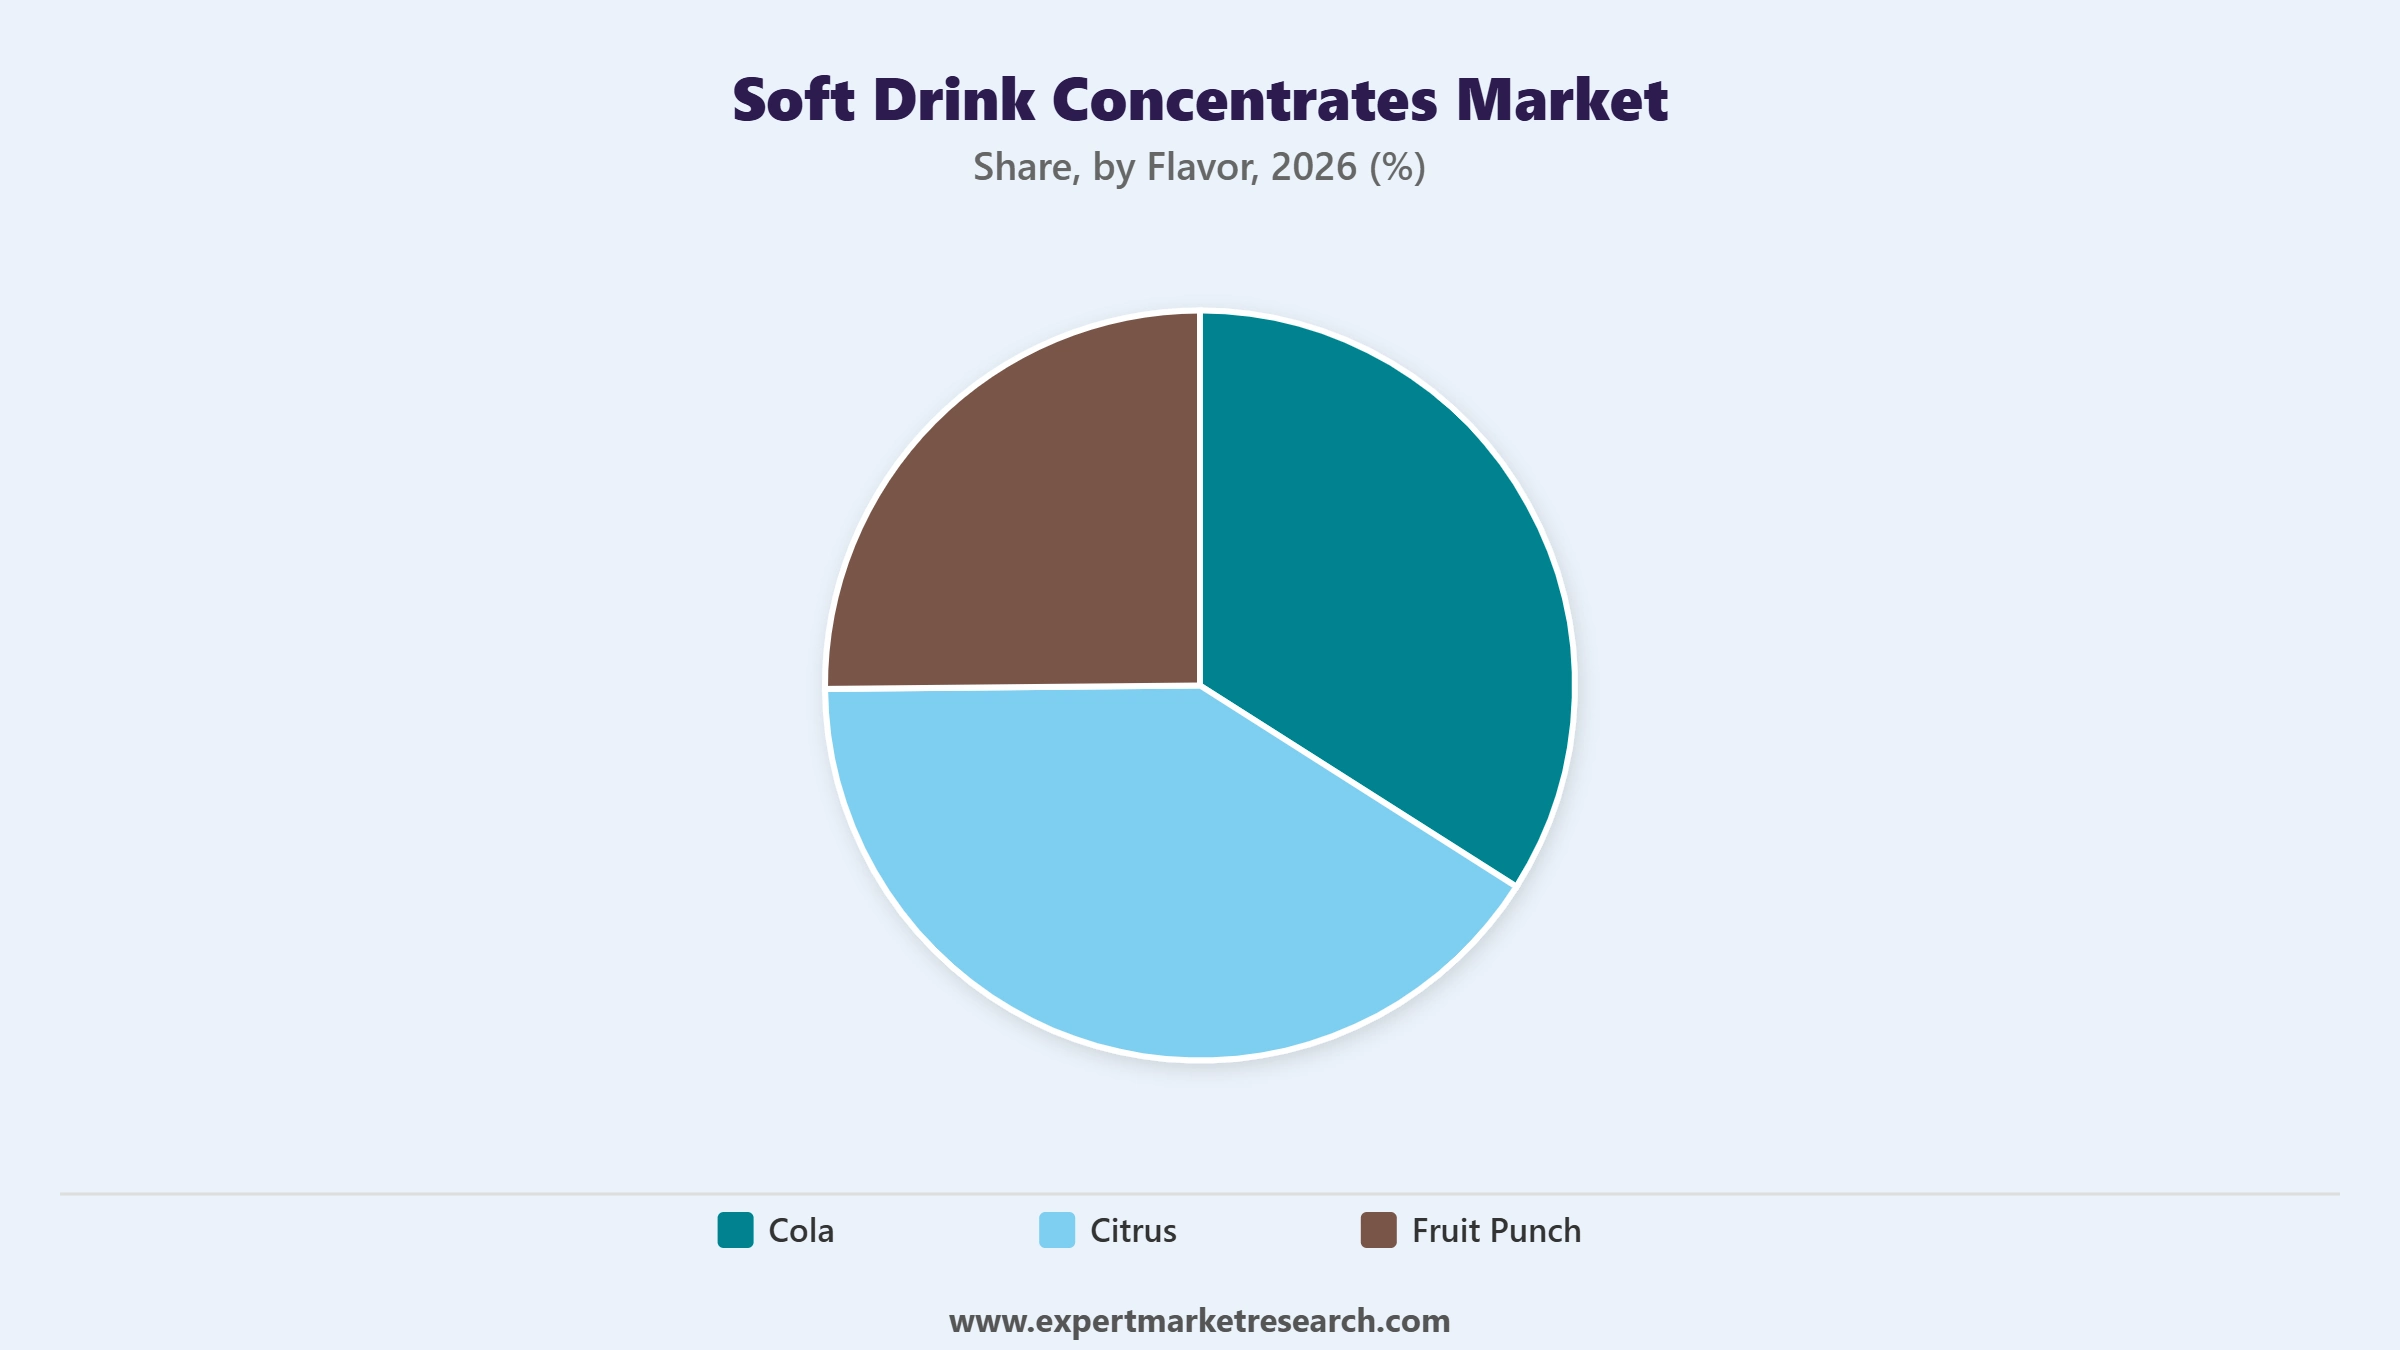
Key Insight: Cola remains the dominant flavor within the soft drink concentrates market, anchored by decades of brand loyalty and extensive distribution built by the leading multinational manufacturers across nearly every retail channel. Fruit punch is the fastest-growing flavor as manufacturers broaden non-carbonated and sports hydration portfolios beyond classic citrus and cola profiles. For example, in spring 2026, PepsiCo launched a reformulated lower-sugar Gatorade featuring Fruit Punch, Lemonade, Glacier Cherry, and Rain Berry variants, containing no artificial flavors, sweeteners, or colors from artificial sources.
Market Breakup by Distribution Channel
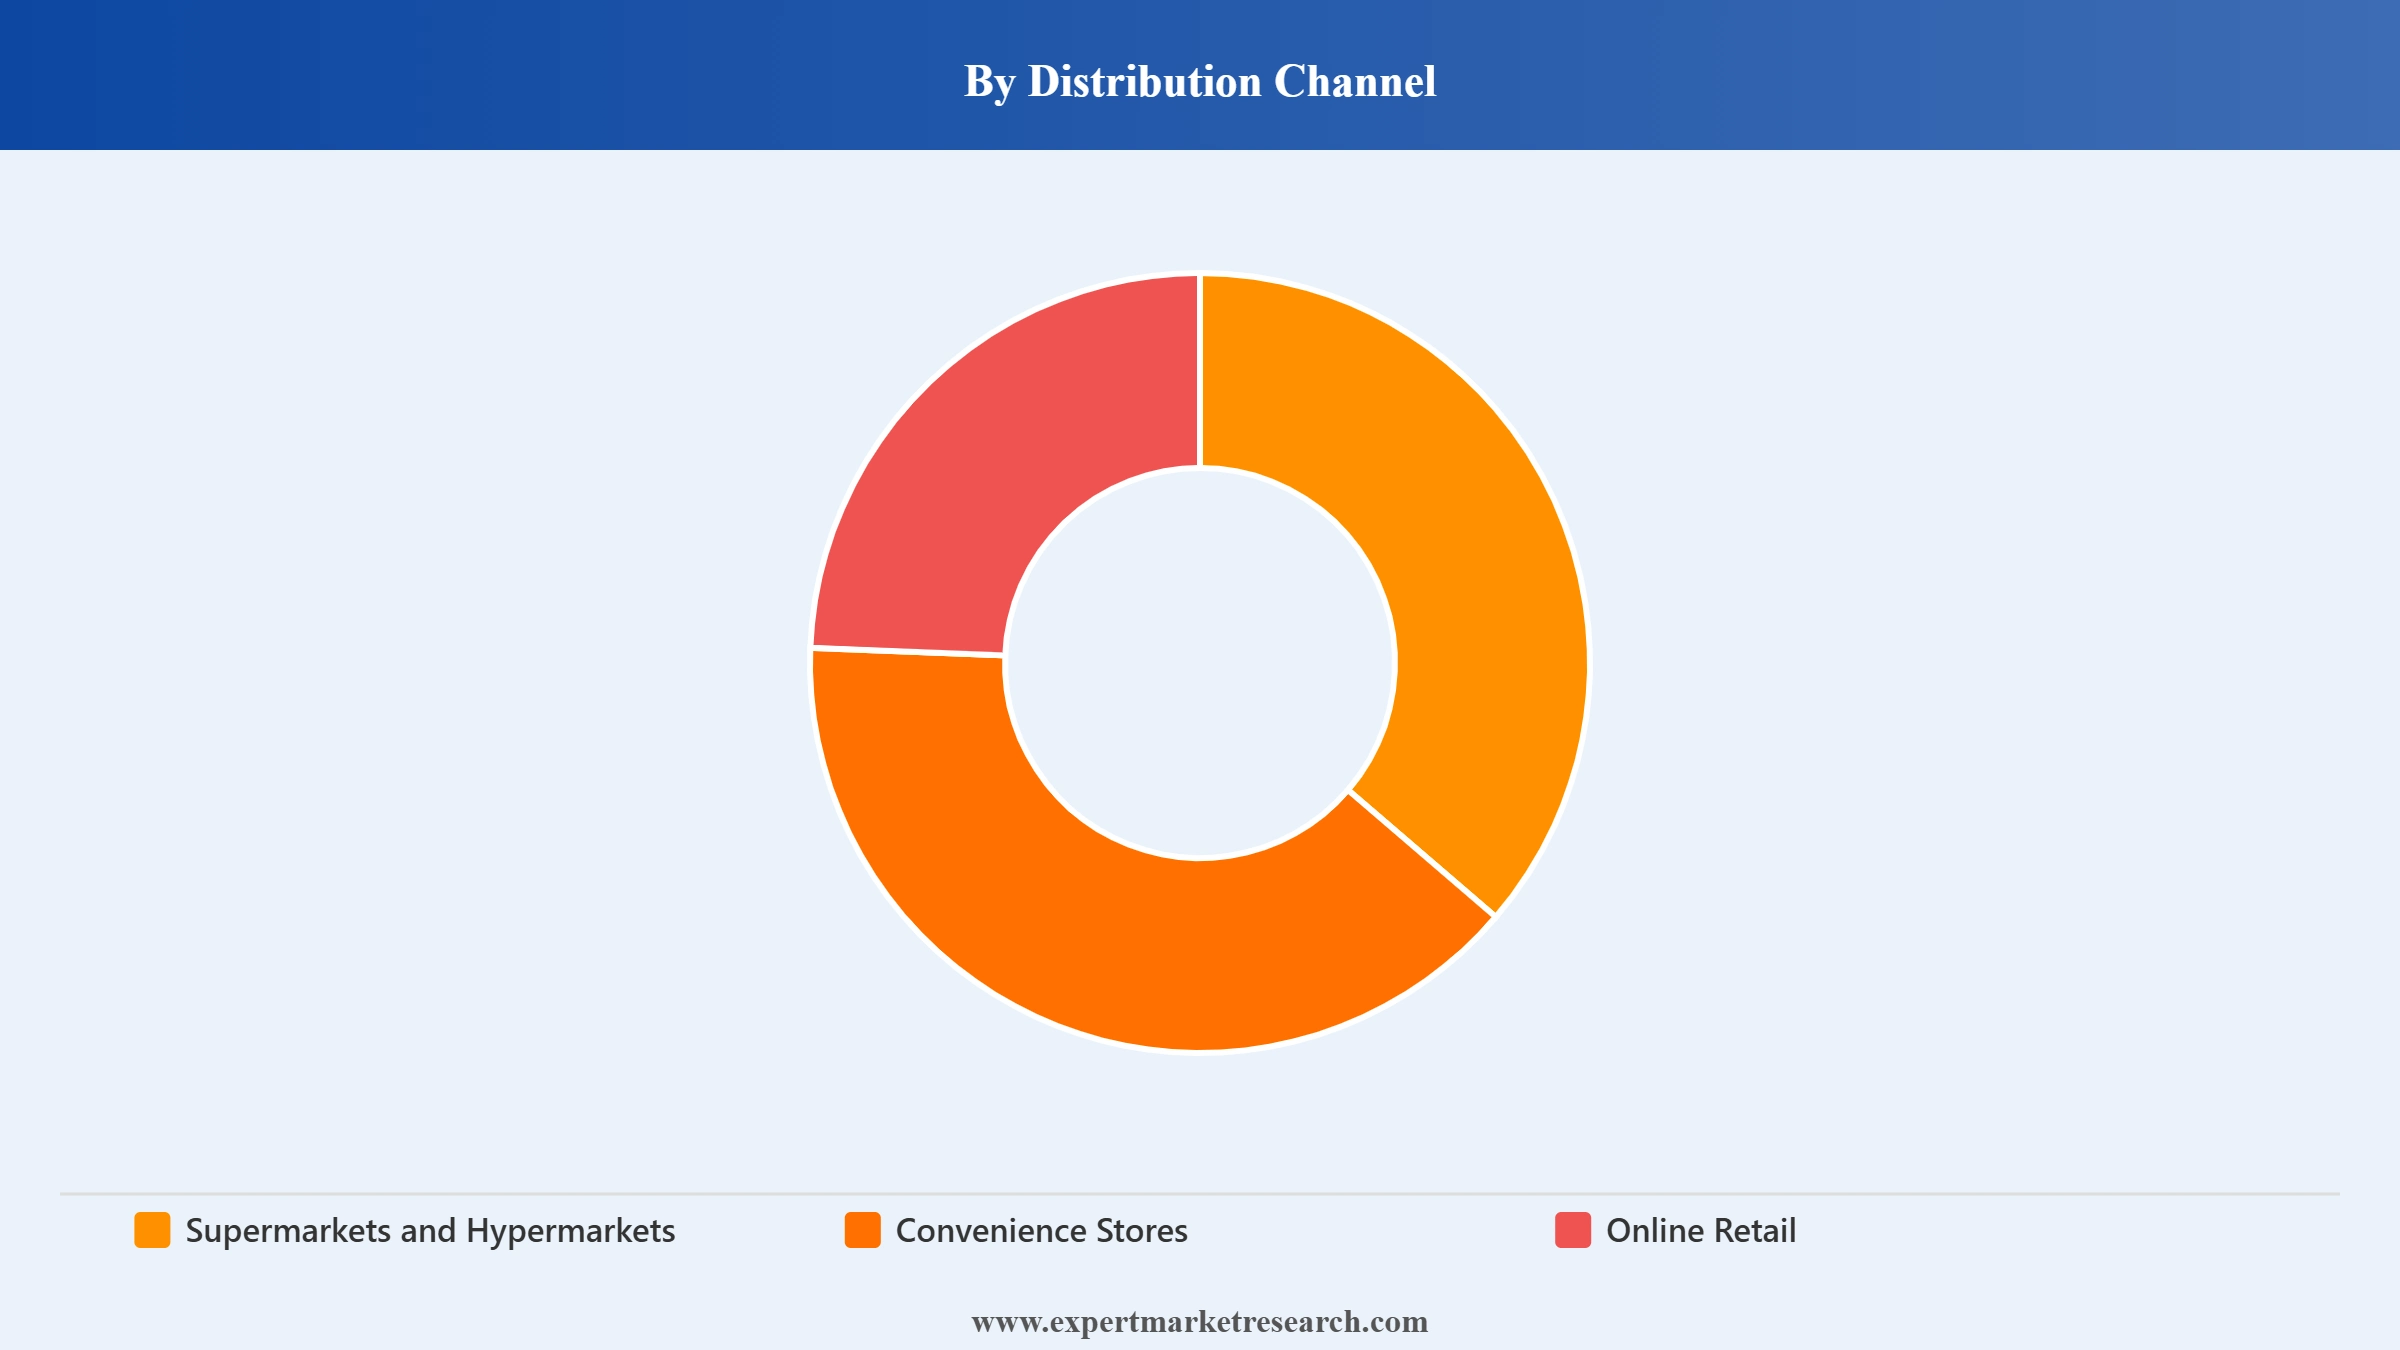
Key Insight: Supermarkets and hypermarkets remain the dominant distribution channel for soft drink concentrates, offering consumers broad product assortments, promotional pricing, and the physical shelf space needed to display multiple flavor and format variants side by side. Online retail is the fastest-growing distribution channel as direct-to-consumer subscription and pre-order models expand consumer access to niche and limited-edition concentrate formats. For example, in January 2025, SodaStream launched Pepsi Wild Cherry drink mix concentrate exclusively online through staggered pre-registration and pre-order phases ahead of general retail availability.
Market Breakup by Region
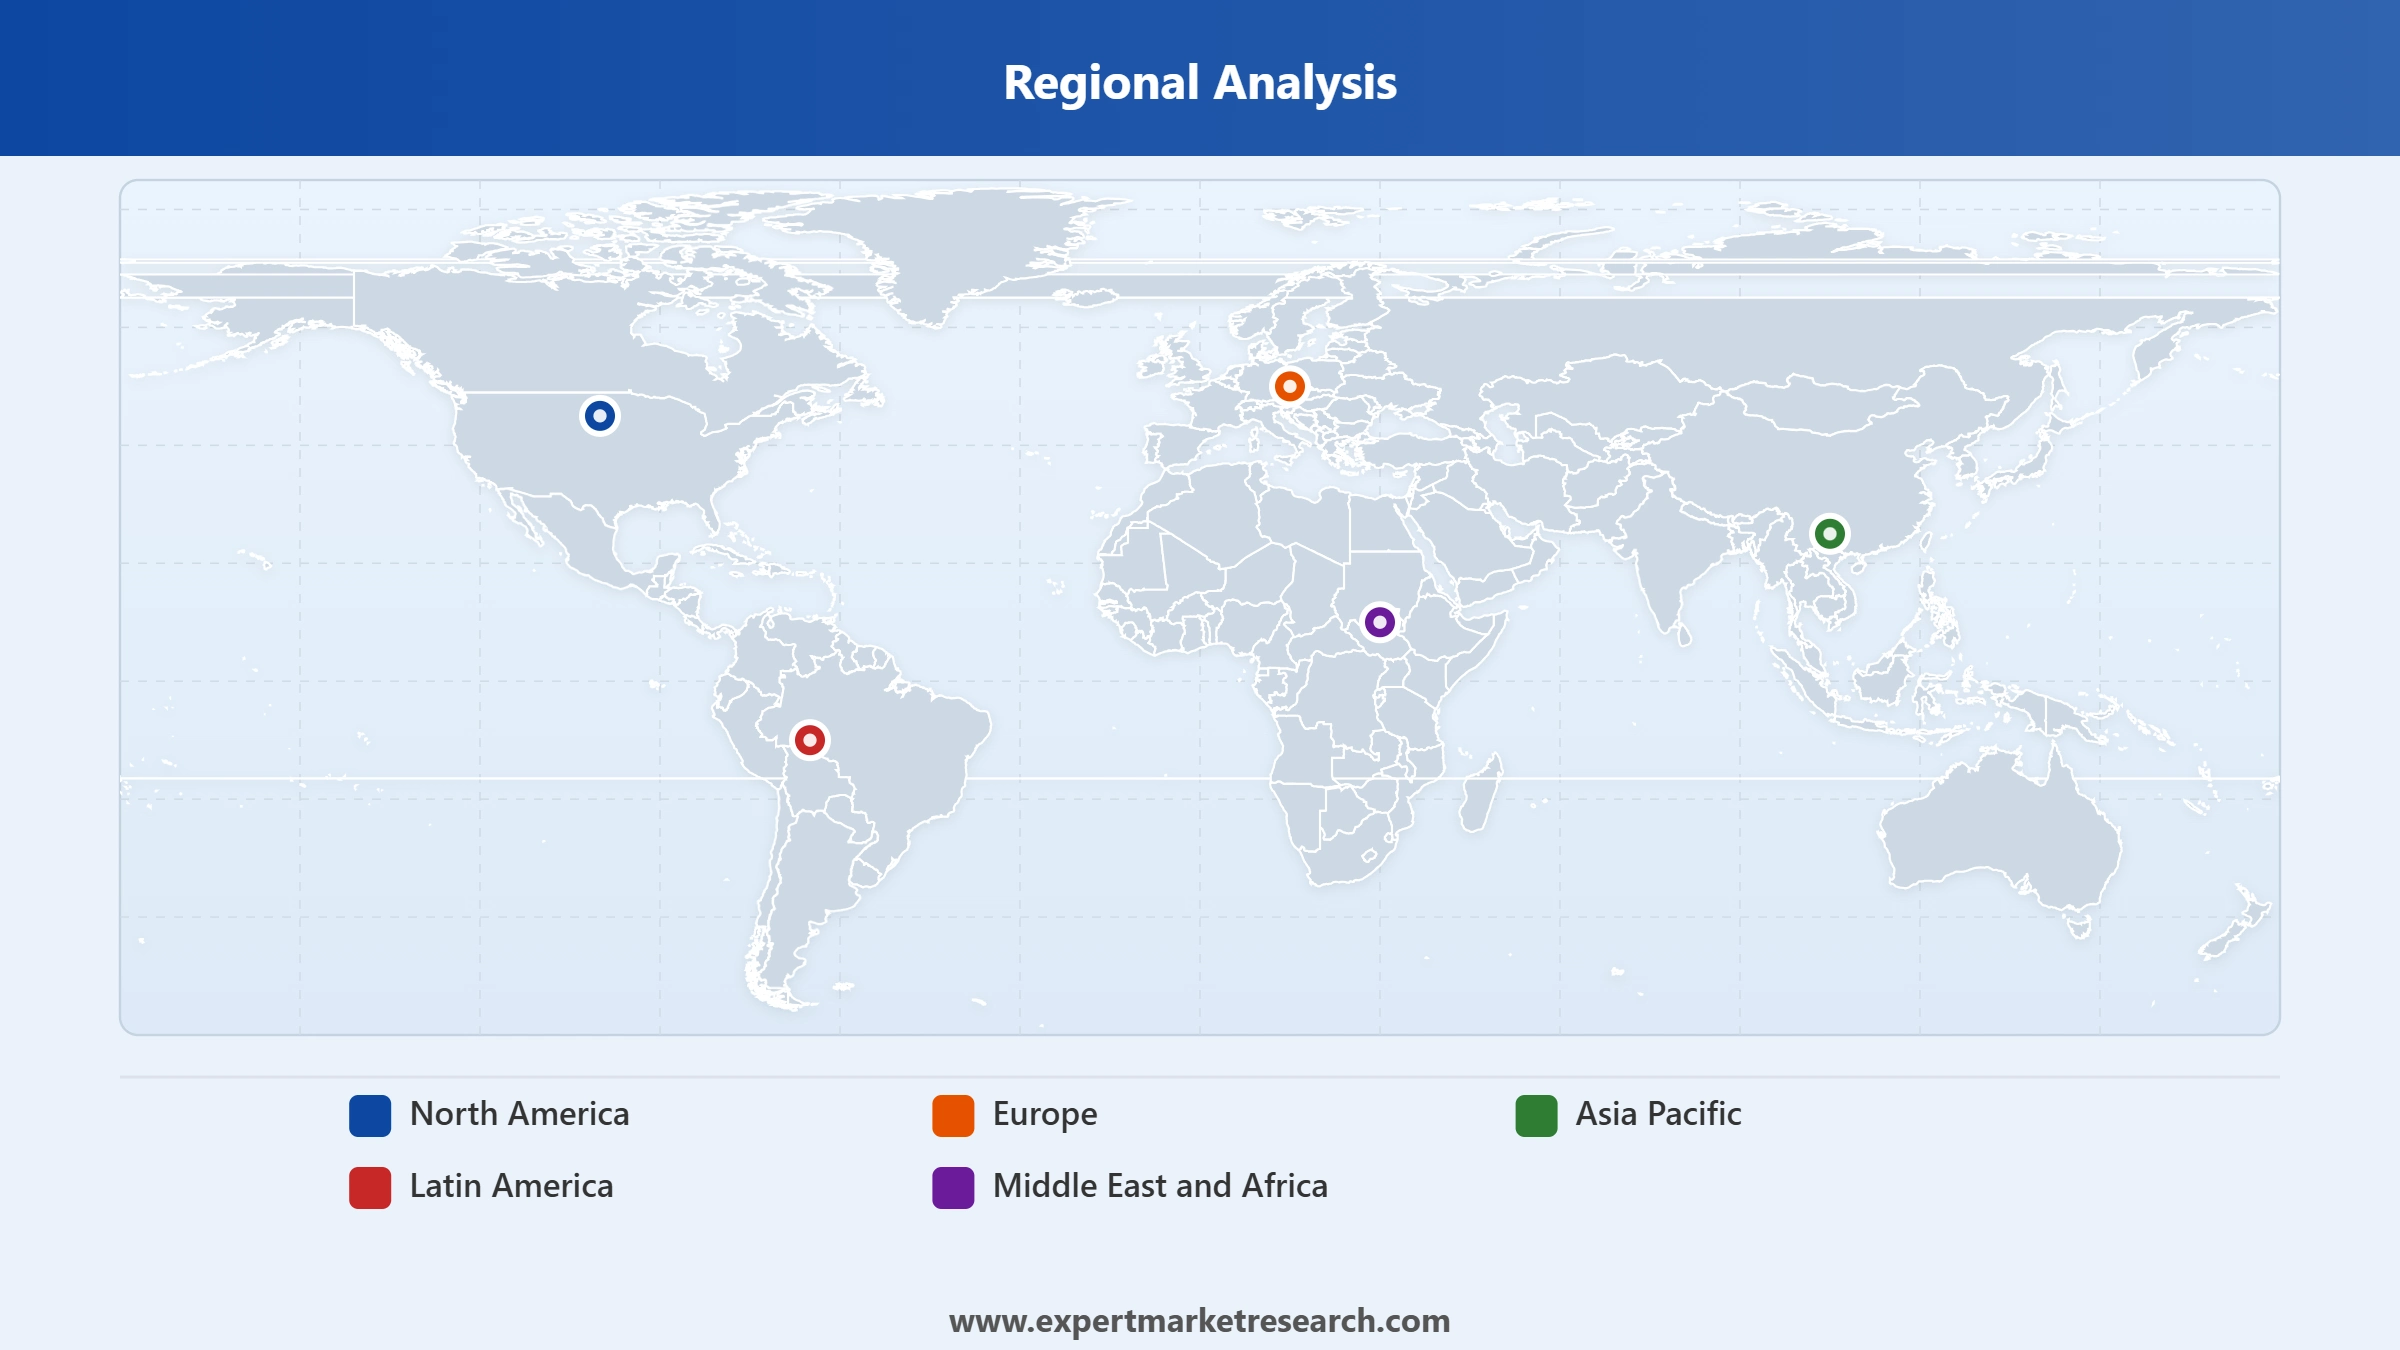
Key Insight: North America dominates the soft drink concentrates market, supported by the presence of leading manufacturers including The Coca-Cola Company, PepsiCo, and Keurig Dr Pepper, alongside extensive bottling and retail distribution infrastructure built up over more than a century. Asia Pacific emerges as the fastest-growing region, propelled by rising foodservice penetration and expanding manufacturing investment across India, Vietnam, and other developing markets. Reinforcing this momentum, in July 2026, Suntory PepsiCo opened a USD 300 million beverage plant in Tay Ninh province, Vietnam, its largest-ever investment in the country and sixth manufacturing facility there.




Read more about this report - Request a Free Sample
By product type, carbonated concentrates dominate the market due to established consumer demand and extensive manufacturer distribution
Carbonated concentrates account for the largest share of the soft drink concentrates market, supported by the extensive bottling networks and strong brand recognition that multinational manufacturers have built around cola and citrus formulations over more than a century of investment. For example, in February 2026, PepsiCo launched Pepsi Prebiotic Cola nationwide in stores and online, becoming the first legacy cola brand to introduce prebiotic fiber within the traditional carbonated cola category. Such innovation reinforces continued manufacturer investment in the segment.
Read more about this report - Request a Free Sample
Non-carbonated concentrates represent the fastest-growing product type as manufacturers steadily reformulate squash, cordial, and powdered drink mix offerings to meet rising consumer demand for reduced sugar and functional beverage alternatives across global markets. Expanding retail distribution of ready to mix formats, coupled with growing consumer interest in portion controlled and customisable beverage preparation at home, is accelerating adoption of non-carbonated concentrates across both household and foodservice settings worldwide, particularly among younger, health conscious, and increasingly budget conscious household consumer segments.
By flavor, cola leads the market due to decades of brand loyalty and extensive retail distribution
Cola remains the dominant flavor within the soft drink concentrates market, underpinned by decades of strong brand loyalty and the extensive marketing and distribution infrastructure that leading manufacturers have steadily established across virtually every retail and foodservice channel worldwide. Demonstrating continued investment in the category, in February 2026, The Coca-Cola Company launched Coca-Cola Cherry Float nationwide, combining its classic cola taste with cherry and cream flavouring across regular and zero sugar formats. Consistent demand continues to anchor cola's leading position.
Read more about this report - Request a Free Sample
Fruit punch is the fastest-growing flavor category as manufacturers steadily broaden their non-carbonated and sports hydration portfolios beyond traditional citrus and cola profiles to capture younger and health focused consumer segments worldwide. Growing demand for naturally flavoured, lower sugar beverage options, together with expanding retail shelf space for fruit forward concentrate formats, continues to support above average growth in this flavor category across multiple regional markets, particularly among younger households and increasingly active, fitness-oriented lifestyle consumers across many regions.
By distribution channel, supermarkets and hypermarkets lead the market due to broad product assortments and competitive promotional pricing
Supermarkets and hypermarkets remain the dominant distribution channel for soft drink concentrates, offering consumers broad product assortments, competitive promotional pricing, and the physical shelf space required to prominently display multiple flavor and format variants side by side together. Illustrating this channel strength, in 2026, Walmart introduced its own Great Value branded soda line, including a new cola variant sweetened with cane sugar, directly onto supermarket shelves alongside established national brands nationwide. Established supplier relationships further reinforce this channel's leading position.
Read more about this report - Request a Free Sample
Online retail is the fastest-growing distribution channel as direct to consumer subscription services and e-commerce platforms steadily expand consumer access to niche, limited edition, and fully customisable concentrate formats across multiple geographies worldwide. Rising smartphone penetration, growing comfort with online grocery ordering, and manufacturers' increasing investment in digital storefronts and targeted social media advertising campaigns are steadily accelerating the overall shift of concentrate purchases toward online retail channels across several regions, particularly among younger and digitally native shoppers everywhere today.
Read more about this report - Request a Free Sample
North America dominates the market due to established manufacturer presence and extensive bottling infrastructure
North America dominates the soft drink concentrates market on the strength of its deeply established manufacturer base, well developed cold chain logistics, and long-standing consumer habits around both carbonated and non-carbonated concentrate formats built up over several decades. Reinforcing this leadership, in February 2026, Coca-Cola Canada Bottling announced a USD 141 million investment to expand its Brampton, Ontario facility, increasing annual production capacity by at least 20 million cases yearly. Continued investment in canning capacity reinforces the region's leading position.
Asia Pacific emerges as the fastest-growing region, propelled by rising disposable incomes, expanding foodservice penetration, and growing manufacturing investment across India, Vietnam, and other developing economies throughout the wider region. Increasing urbanisation and the steady expansion of modern retail and online grocery infrastructure are further supporting the accelerated adoption of concentrate-based beverages across the region's developing markets, particularly in urban centres where rising disposable incomes and growing western style retail penetration continue to steadily rise with each passing year.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
4.8% |
|
Europe |
4.5% |
|
Asia Pacific |
7.6% |
|
Latin America |
6.2% |
|
Middle East and Africa |
5.8% |
The global soft drink concentrates market features a moderately consolidated competitive structure led by large multinational beverage manufacturers with extensive brand portfolios spanning carbonated and non-carbonated concentrate formats, alongside specialised flavour and syrup houses serving foodservice and retail channels across mature and emerging regions. Soft Drink Concentrates companies like The Coca-Cola Company, PepsiCo, and Keurig Dr Pepper compete primarily through brand portfolio scale and bottling network reach, while Nestle and other manufacturers focus on flavour innovation and regional distribution partnerships.
Leading soft drink concentrates market players are focusing on product reformulation, reduced sugar innovation, sustainable packaging development, and expansion into emerging foodservice and retail destinations to strengthen their competitive position. Increasing emphasis on functional ingredients, premium flavour profiles, and flexible pack sizing is also enabling manufacturers to broaden their consumer base while supporting long term market growth.
The Coca-Cola Company, headquartered in Atlanta, Georgia, United States, and founded in 1892, is one of the world's largest beverage manufacturers, with its concentrate formulas licensed to an extensive global network of independent bottling partners. The company trades on the New York Stock Exchange under the ticker KO and maintains a broad portfolio spanning carbonated colas, citrus beverages, and flavoured concentrate-based drink mixes sold across more than 200 countries and territories worldwide.
PepsiCo, headquartered in Purchase, New York, United States, and formed through the 1965 merger of Pepsi-Cola and Frito-Lay, manufactures and markets a wide portfolio of carbonated and non-carbonated concentrate-based beverages alongside its snack food operations. Listed on the Nasdaq under the ticker PEP, the company operates an extensive bottling and distribution network and continues to expand its lower sugar and functional beverage offerings across developed and emerging markets.
Keurig Dr Pepper, formed through the 2018 merger of Dr Pepper Snapple Group and Keurig Green Mountain, maintains dual headquarters in Burlington, Massachusetts, and Frisco, Texas, United States. Trading on the Nasdaq under the ticker KDP, the company manufactures a diverse portfolio of carbonated soft drink concentrates, flavoured waters, and mixers, supported by an integrated direct store delivery and third-party bottling network across North America.
Nestle, headquartered in Vevey, Switzerland, traces its beverage heritage to the 1866 founding of the Anglo-Swiss Condensed Milk Company and its 1905 merger with Henri Nestle's company. Listed on the SIX Swiss Exchange under the ticker NESN, Nestle manufactures powdered and liquid concentrate-based beverage brands distributed through retail and foodservice channels across both developed and emerging economies worldwide.
Other key players in the market report include Suntory Beverage and Food Limited, Britvic plc, AG Barr plc, Kerry Group plc, and Monin Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the soft drink concentrates market 2026-2035 with our in-depth report. Gain strategic insights to support your business decisions. Get in touch with our analysts today.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the soft drink concentrates market reached an approximate value of USD 40.04 Billion.
The market is projected to grow at a CAGR of 5.70% between 2026 and 2035.
The key players in the market include The Coca-Cola Company, PepsiCo, Keurig Dr Pepper, Nestle, Suntory Beverage and Food Limited, Britvic plc, AG Barr plc, Kerry Group plc, and Monin Inc., among others.
Leading manufacturers are pursuing capacity investment, reduced sugar product reformulation, flavour portfolio diversification, and distribution channel expansion into online retail.
Key challenges include volatile raw material and sweetener input costs, shifting consumer preference away from sugar sweetened beverages, and regulatory scrutiny over sugar content and labelling requirements.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Product Type |
|
|
Breakup by Flavor |
|
|
Breakup by Distribution Channel |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




