

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
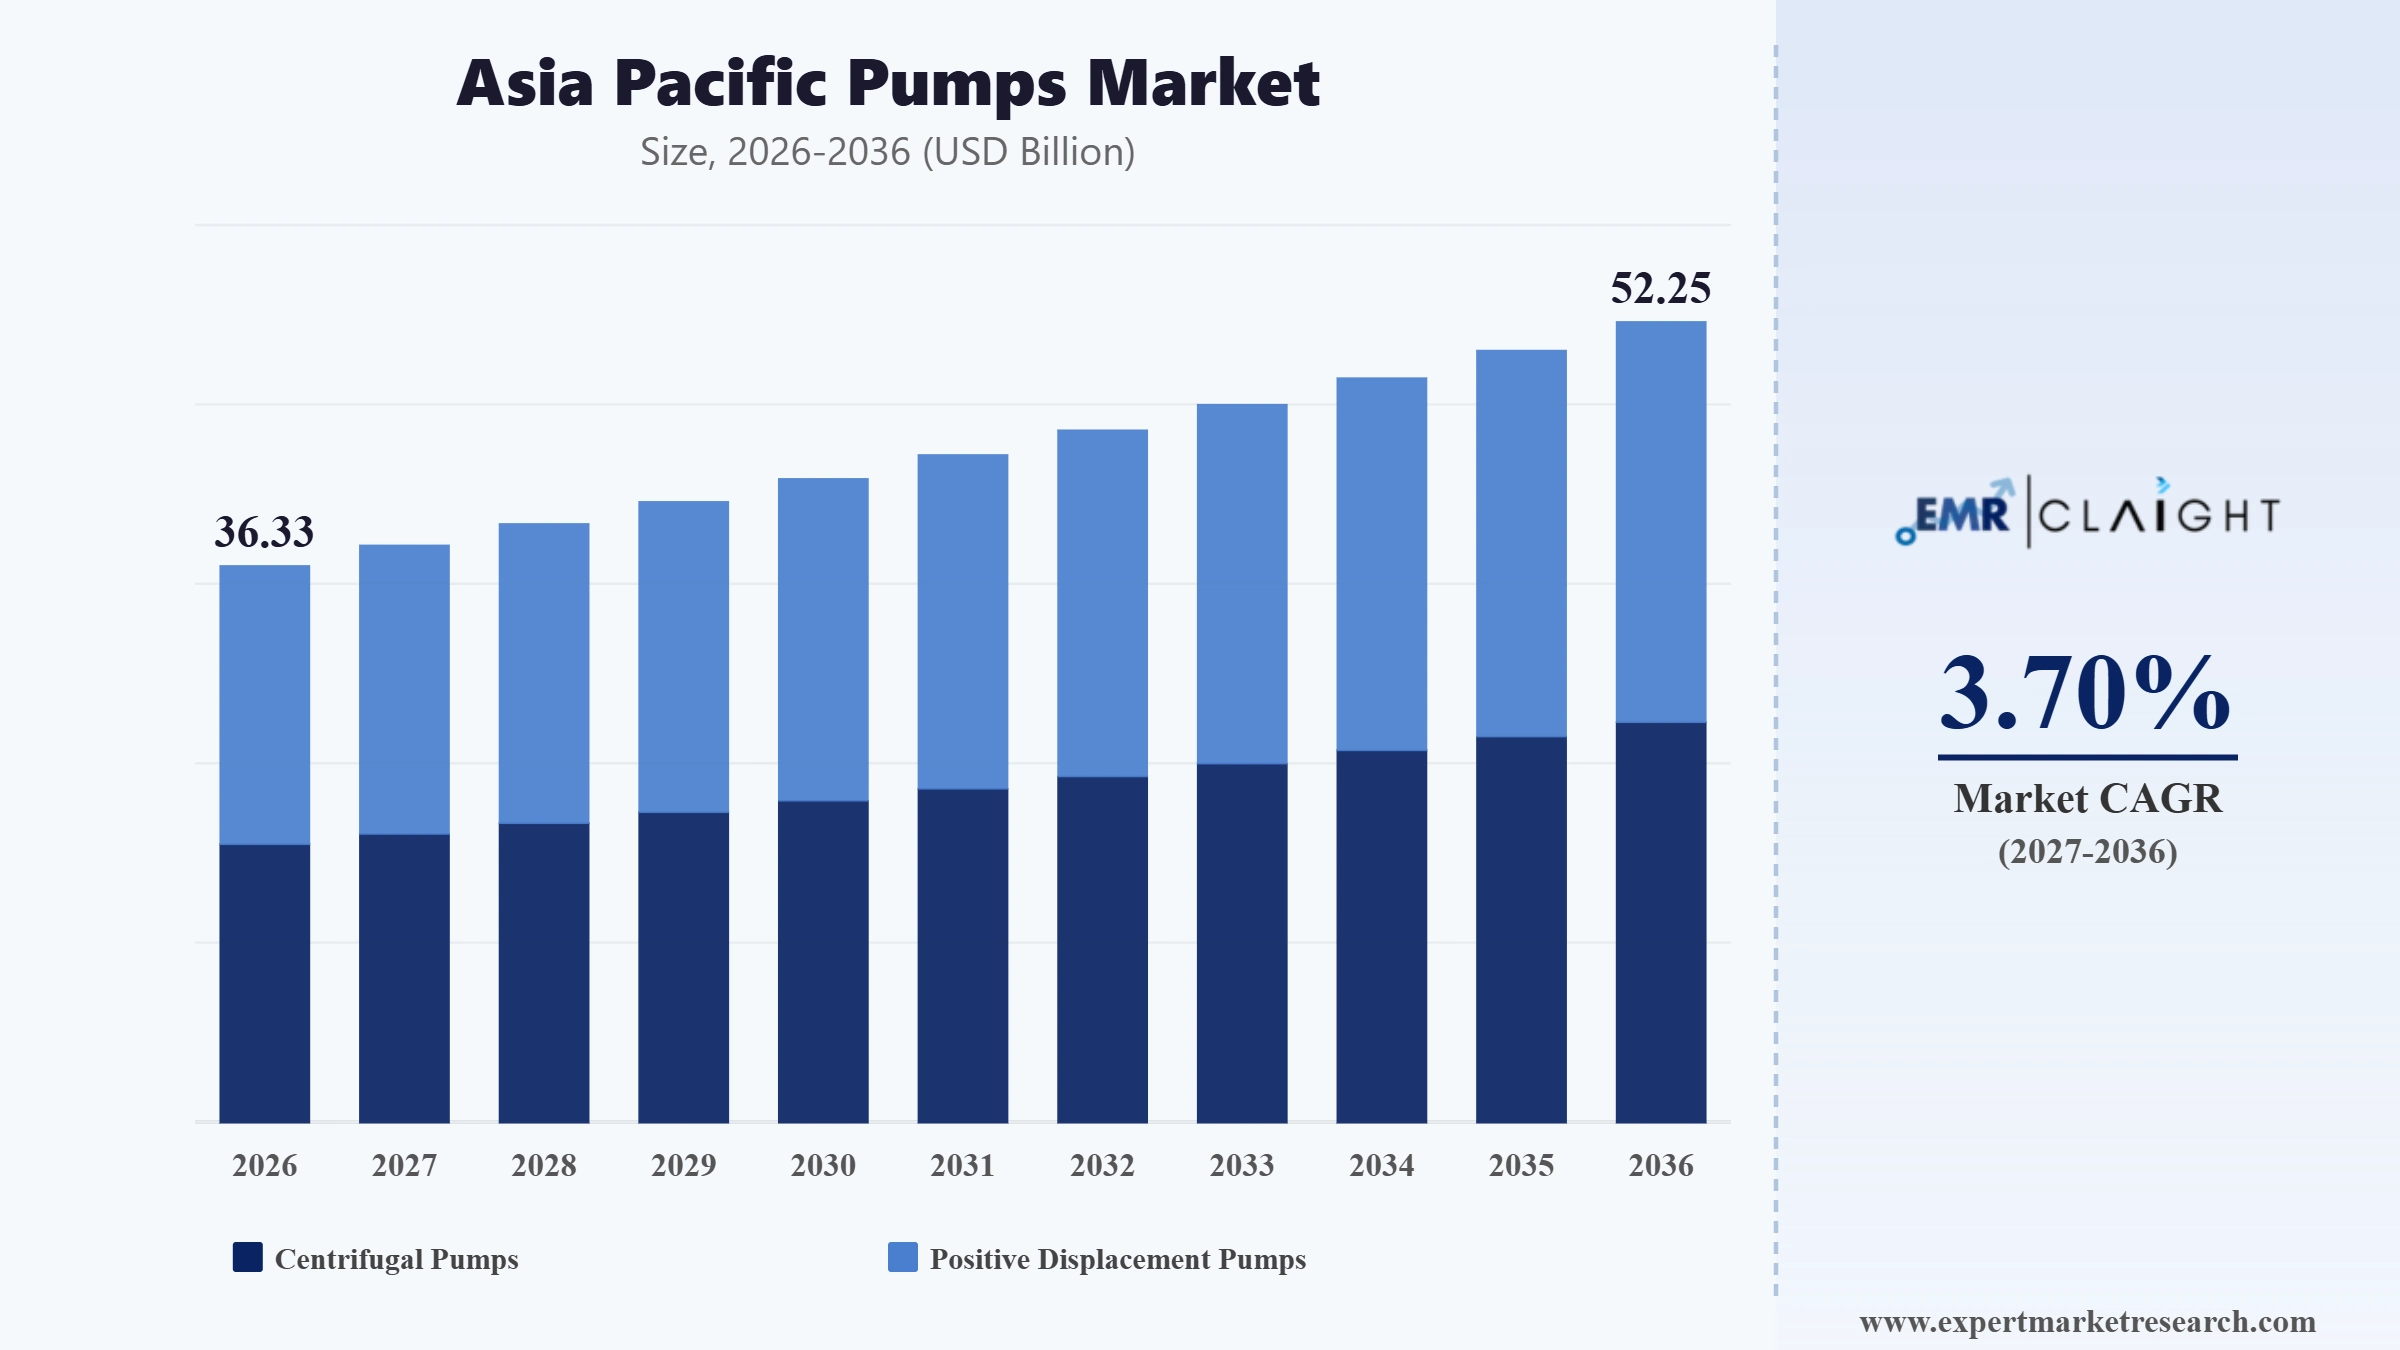
The Asia Pacific pumps market attained a value of USD 35.03 Billion in 2025 and is projected to expand at a CAGR of 3.70% through 2035. The market is further expected to achieve USD 50.38 Billion by 2035, supported by rapid industrialisation, expanding water and wastewater infrastructure, and sustained power generation and mining sector investment across the region. Growth spans oil and gas, chemicals and petrochemicals, mining, and power generation end uses, with manufacturers across China, Japan, India, ASEAN, and Australia competing on manufacturing scale, local production presence, and large-project execution capability.
Sustained infrastructure investment and industrial expansion continue to anchor steady demand across the Asia Pacific pumps market, as utilities and industrial operators across the region commission new power generation and processing capacity. Manufacturers are also investing in large-project execution capability, reflecting the industry's pursuit of high-value domestic and international contracts rather than smaller aftermarket business alone.
The Asia Pacific pumps market is witnessing further developments as established domestic manufacturers secure sizeable contracts for critical power infrastructure projects. Kirloskar Brothers disclosed in February 2026 that it had secured a contract worth approximately 214 crore rupees from Adani Power and its subsidiaries for circulating and auxiliary cooling water pump packages across thermal power projects in Madhya Pradesh, Assam, Chhattisgarh, and Bihar. This shift toward large domestic power-sector contracts is concentrated among manufacturers with sufficient thermal-project engineering scale, while smaller specialists instead compete on regional service depth.
In addition, established regional manufacturers are increasingly winning international orders through their overseas subsidiaries, reflecting the industry's recognition that global distribution reach increasingly determines competitiveness beyond domestic markets alone. Kirloskar Brothers' UK subsidiary SPP Pumps secured a contract worth approximately 11.7 million pounds from Saipem Offshore Construction in July 2026 for the supply of vertical pumps and spares. Such international order activity is reshaping competitive positioning across the wider asia pacific pumps market as manufacturers with established overseas subsidiary networks increasingly differentiate themselves from competitors focused solely on domestic contracts.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Regional manufacturers with established overseas subsidiaries are increasingly capturing international offshore energy contracts rather than relying solely on domestic demand. SPP Pumps, the UK subsidiary of Kirloskar Brothers, secured an order worth approximately 11.7 million pounds from Saipem Offshore Construction for vertical pumps and spares, with execution scheduled within 52 to 60 weeks of order receipt. Companies can leverage established overseas manufacturing subsidiaries to access offshore energy contracts beyond their home market reach.
International industrial groups are deepening their Chinese manufacturing presence to align with the country's next industrial development cycle. Atlas Copco inaugurated its new Power Technique campus in Wuxi, Jiangsu province, with company executives citing alignment with China's 15th Five-Year Plan priorities around energy efficiency and cleaner industrial technology. Companies can leverage expanded local manufacturing presence to strengthen relationships with Chinese industrial customers ahead of new regulatory cycles.
Domestic power sector expansion continues generating substantial contract opportunities for manufacturers with thermal-project engineering scale. Kirloskar Brothers disclosed a contract worth approximately 214 crore rupees from Adani Power and its subsidiaries for circulating water and auxiliary cooling water pump packages across four Indian states, with execution scheduled over 18 to 24 months. Companies can leverage thermal power project engineering credentials to secure multi-state contract visibility extending well beyond a single project.
Established pump manufacturers continue investing in local Chinese production capacity to serve the region's expanding refinery and petrochemical sector. Sulzer's Suzhou facility, its second major Chinese production site alongside an existing Dalian plant, has continued fulfilling complex multi-design pump orders for domestic refinery customers requiring rapid, locally manufactured delivery. Companies can leverage dual-site Chinese manufacturing presence to reduce delivery timelines for time-sensitive refinery upgrade projects.
Offshore energy developers across Southeast Asia are increasingly awarding integrated subsea production packages to suppliers with proven deepwater engineering scale. Baker Hughes secured an award in August 2026 from Searah North Ganal Limited, a joint venture between Eni and PETRONAS, to supply 17 deepwater horizontal tree systems along with associated manifolds, connections, and pumping and control systems for the Kutei Northern Hub development offshore Indonesia. Companies can leverage integrated subsea systems capability to capture large offshore contracts spanning multiple equipment categories rather than competing on individual components alone.
Global pump manufacturers are increasingly citing power generation and nuclear-sector demand as a significant driver of order growth alongside traditional oil and gas activity. Flowserve reported, in July 2026, second-quarter bookings growth of 26 percent year over year to 1.35 billion dollars, supported by record aftermarket orders, large engineered projects, and strengthening demand across power and nuclear markets. Companies can leverage diversified end-market exposure spanning power, nuclear, and traditional energy sectors to sustain order growth even as any single end market experiences softer periods.
Global pump manufacturers are increasingly citing emerging Asian markets alongside established Western territories as parallel growth engines in annual results. Grundfos reported, in February 2026, full-year 2025 sales growth of 5.7 percent despite geopolitical uncertainty, with the company specifically highlighting substantial sales growth in India alongside double-digit growth in the United States, even as China and parts of Europe faced softer demand. Companies can leverage diversified regional growth, spanning both mature and emerging Asian markets, to offset softness concentrated in any single geography.
Indian electrical engineering conglomerates with diversified industrial equipment portfolios are increasingly winning large international orders beyond their traditional domestic base. CG Power and Industrial Solutions received an order in January 2026 worth approximately 900 crore rupees for power transformers from Tallgrass, reinforcing the company's broader industrial systems and power systems portfolio that includes motors, drives, and pumps for industrial and consumer applications. Companies can leverage diversified electrical engineering portfolios to win large contracts extending beyond their core product categories, a strategy that continues to open doors with international customers seeking a single supplier capable of servicing multiple equipment needs at once.
This Expert Market Research's Report titled "Asia Pacific Pumps Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
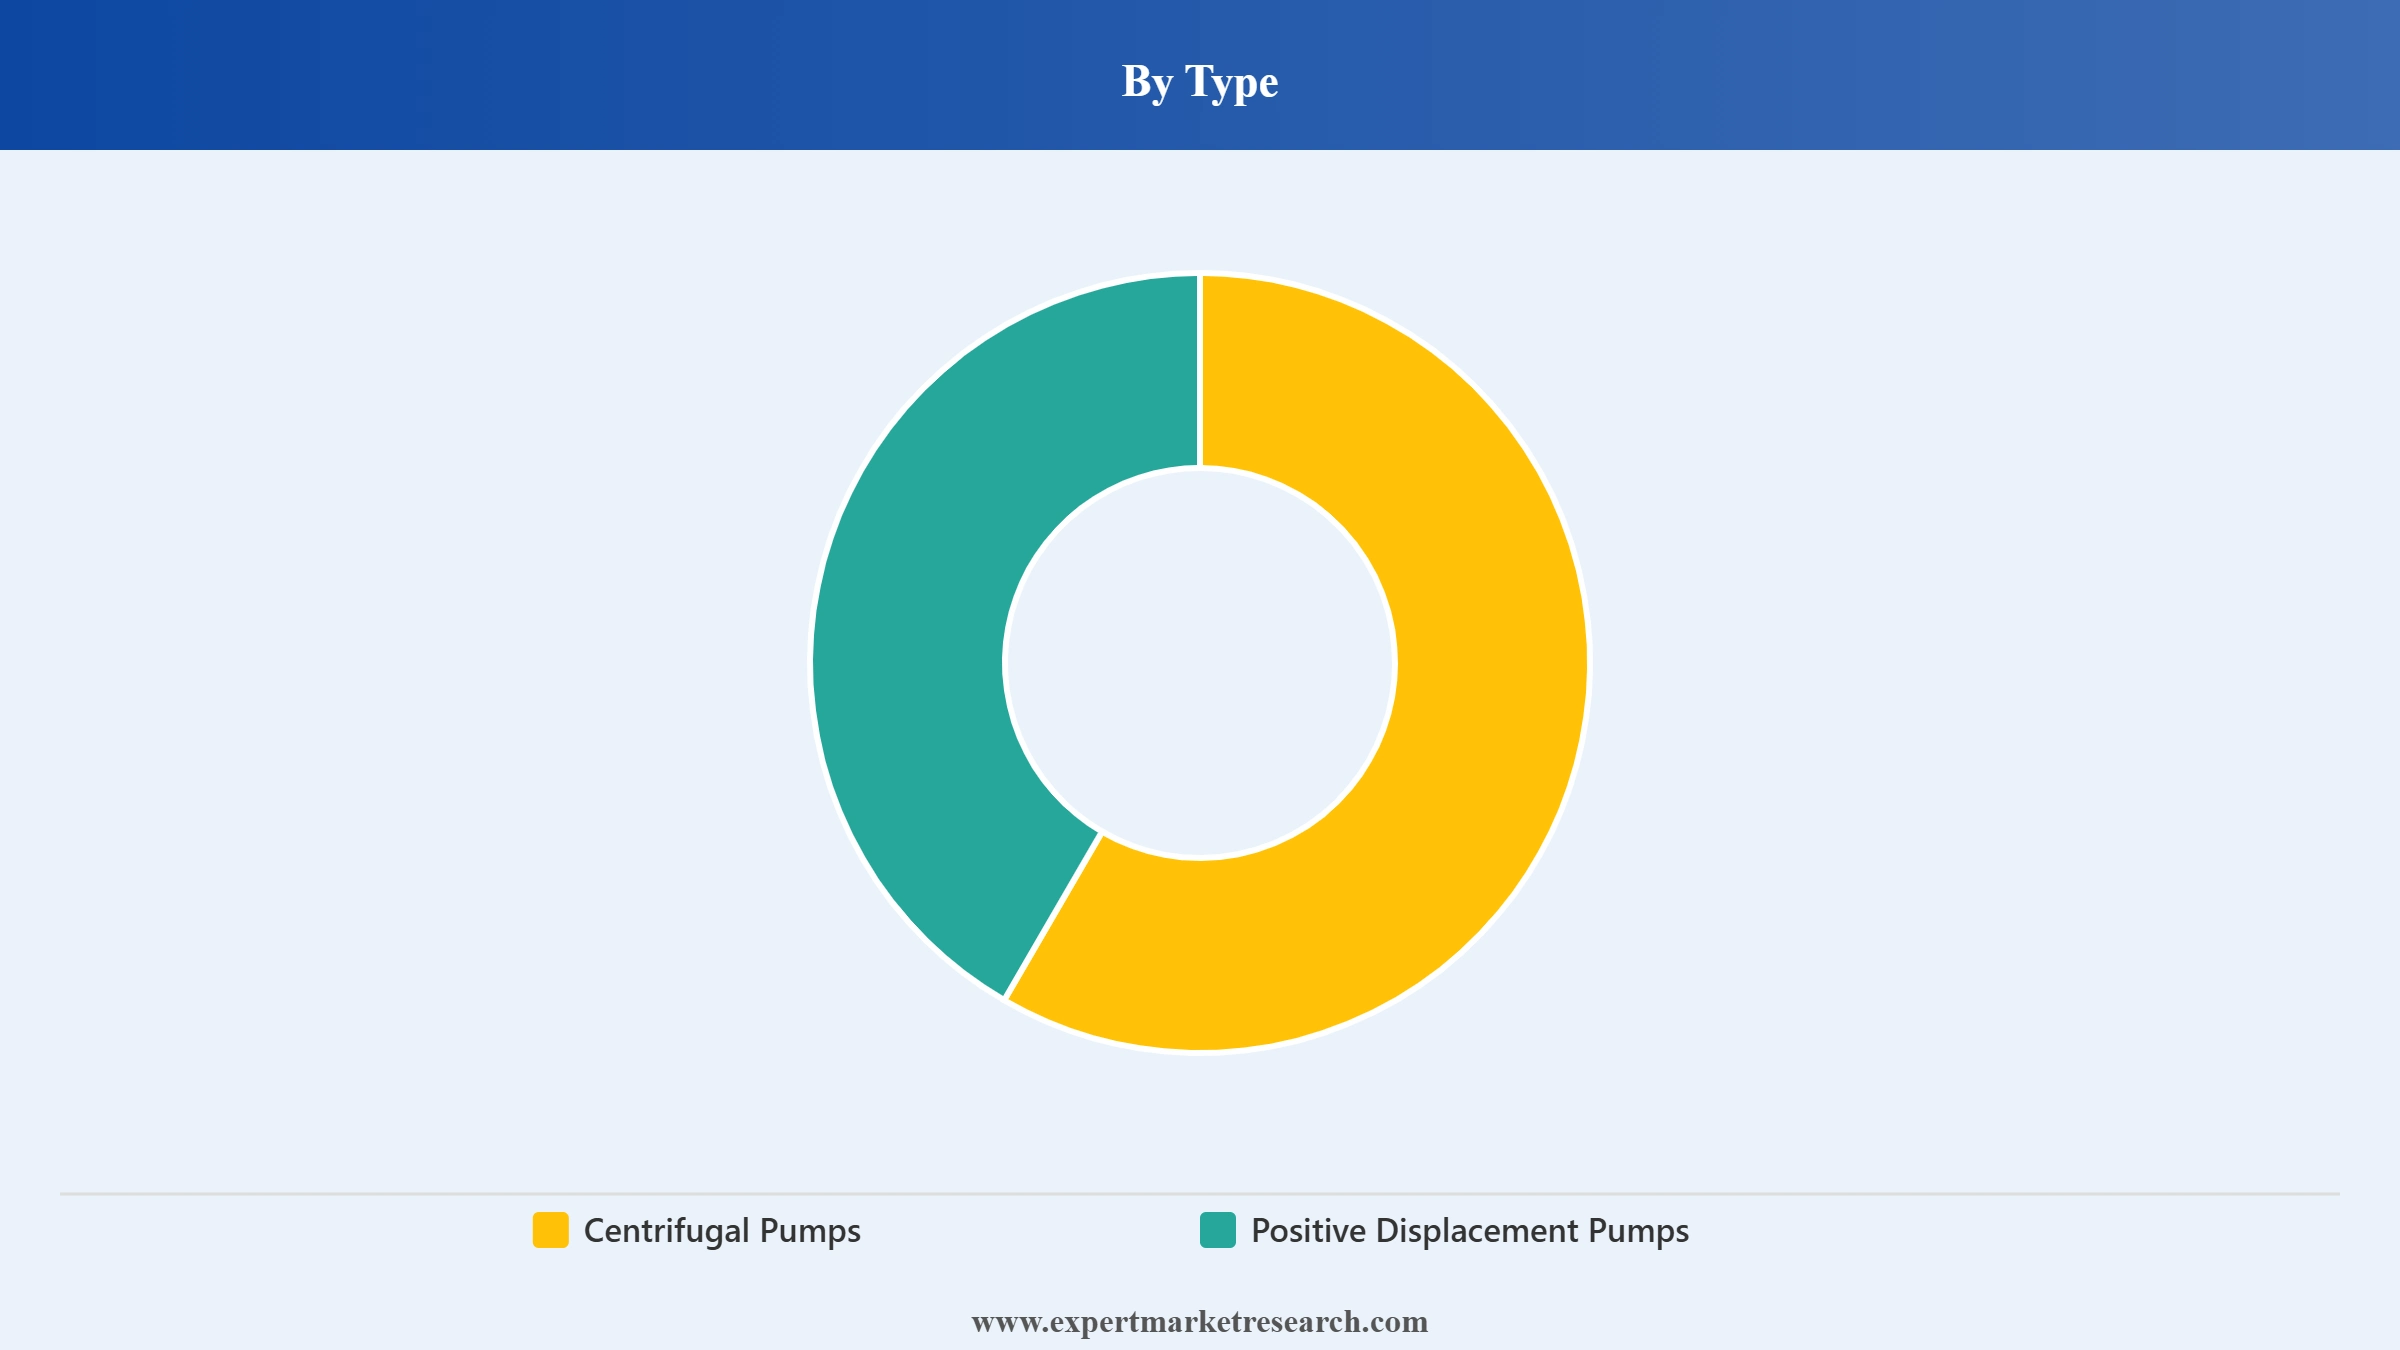
Key Insight: Centrifugal Pumps accounts for the largest share of the asia pacific pumps market, reflecting widespread use across water supply, wastewater, and general industrial applications given lower maintenance requirements and higher flow-rate capacity. Positive Displacement Pumps is growing at a fast pace at a projected CAGR of 4.10%, illustrated by SPP Pumps' July 2026 vertical pump order from Saipem Offshore Construction for high-pressure offshore energy applications, a category where regional manufacturers with established overseas subsidiary networks continue capturing disproportionate share of new contract awards.
Market Breakup by End Use
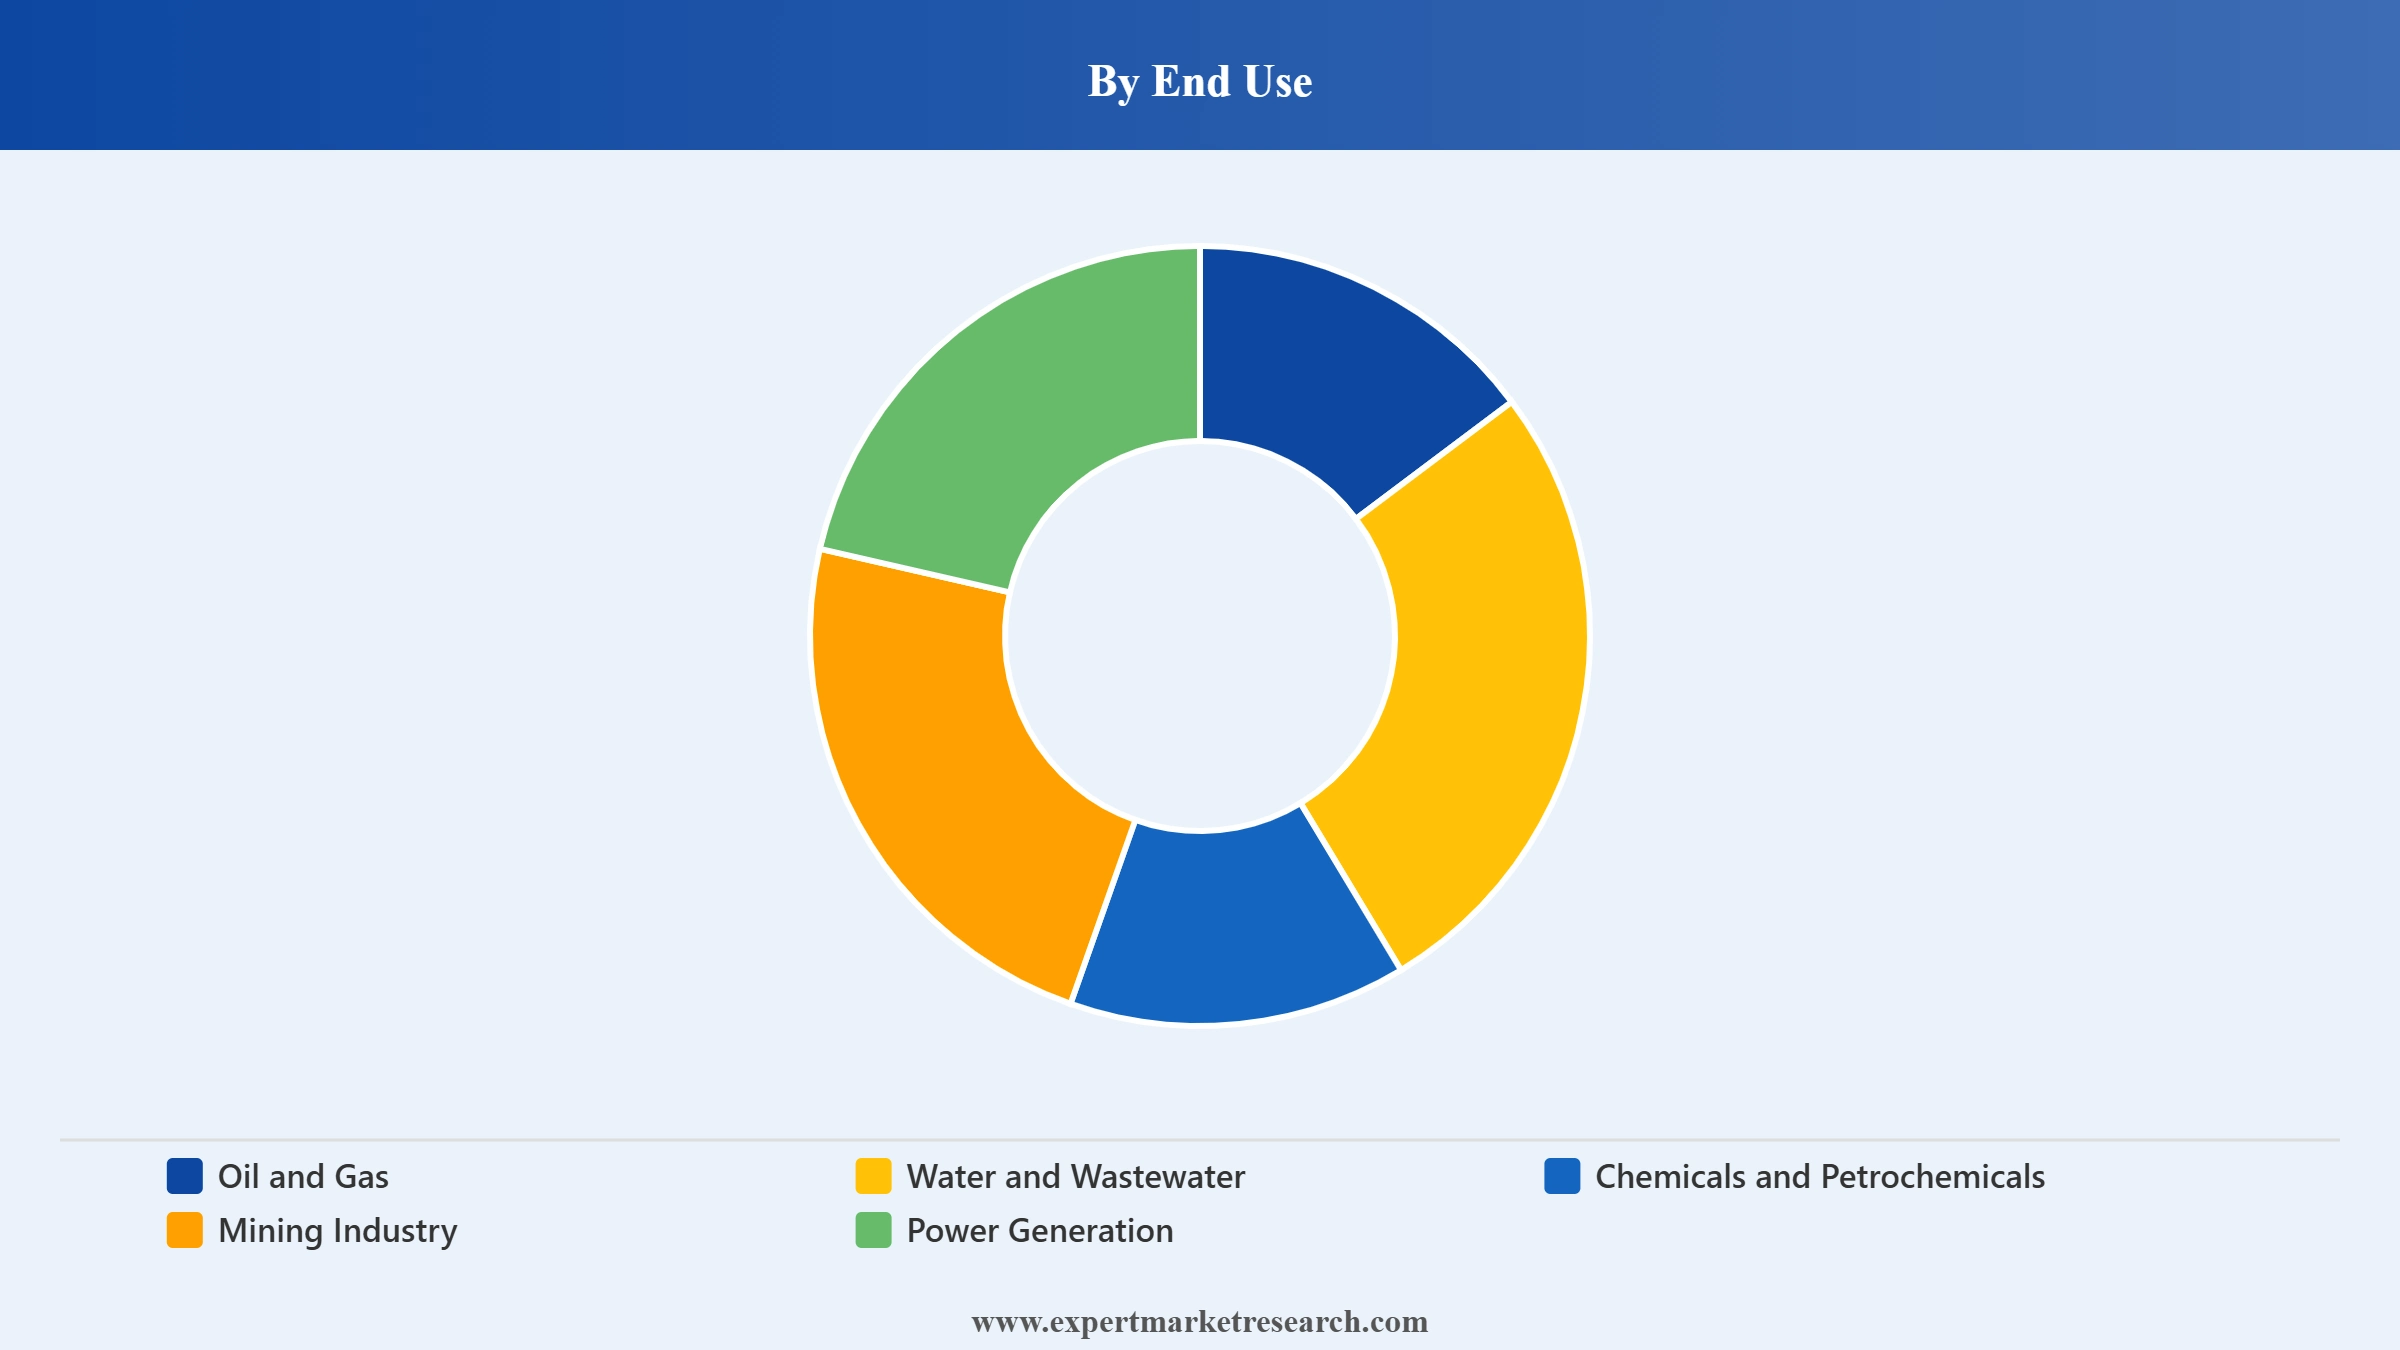
Key Insight: Power Generation accounts for the largest share of the market, reinforced by Kirloskar Brothers' February 2026 contract with Adani Power for circulating and auxiliary cooling water pump packages across four Indian states. Oil and Gas is growing steadily, illustrated by SPP Pumps' July 2026 vertical pump order from Saipem Offshore Construction. Chemicals and Petrochemicals demand is reinforced by Sulzer's continued dual-site Chinese manufacturing supporting domestic refinery upgrade projects. Water and Wastewater continues to represent substantial demand tied to municipal infrastructure expansion across the region. Mining Industry serves resource-processing applications across Australia and Southeast Asia. Others encompasses smaller-volume end-use categories including agriculture and food processing applications, segments that generally specify smaller, standardised pump models rather than the customised engineering solutions common across power generation and mining contracts.
Market Breakup by Country
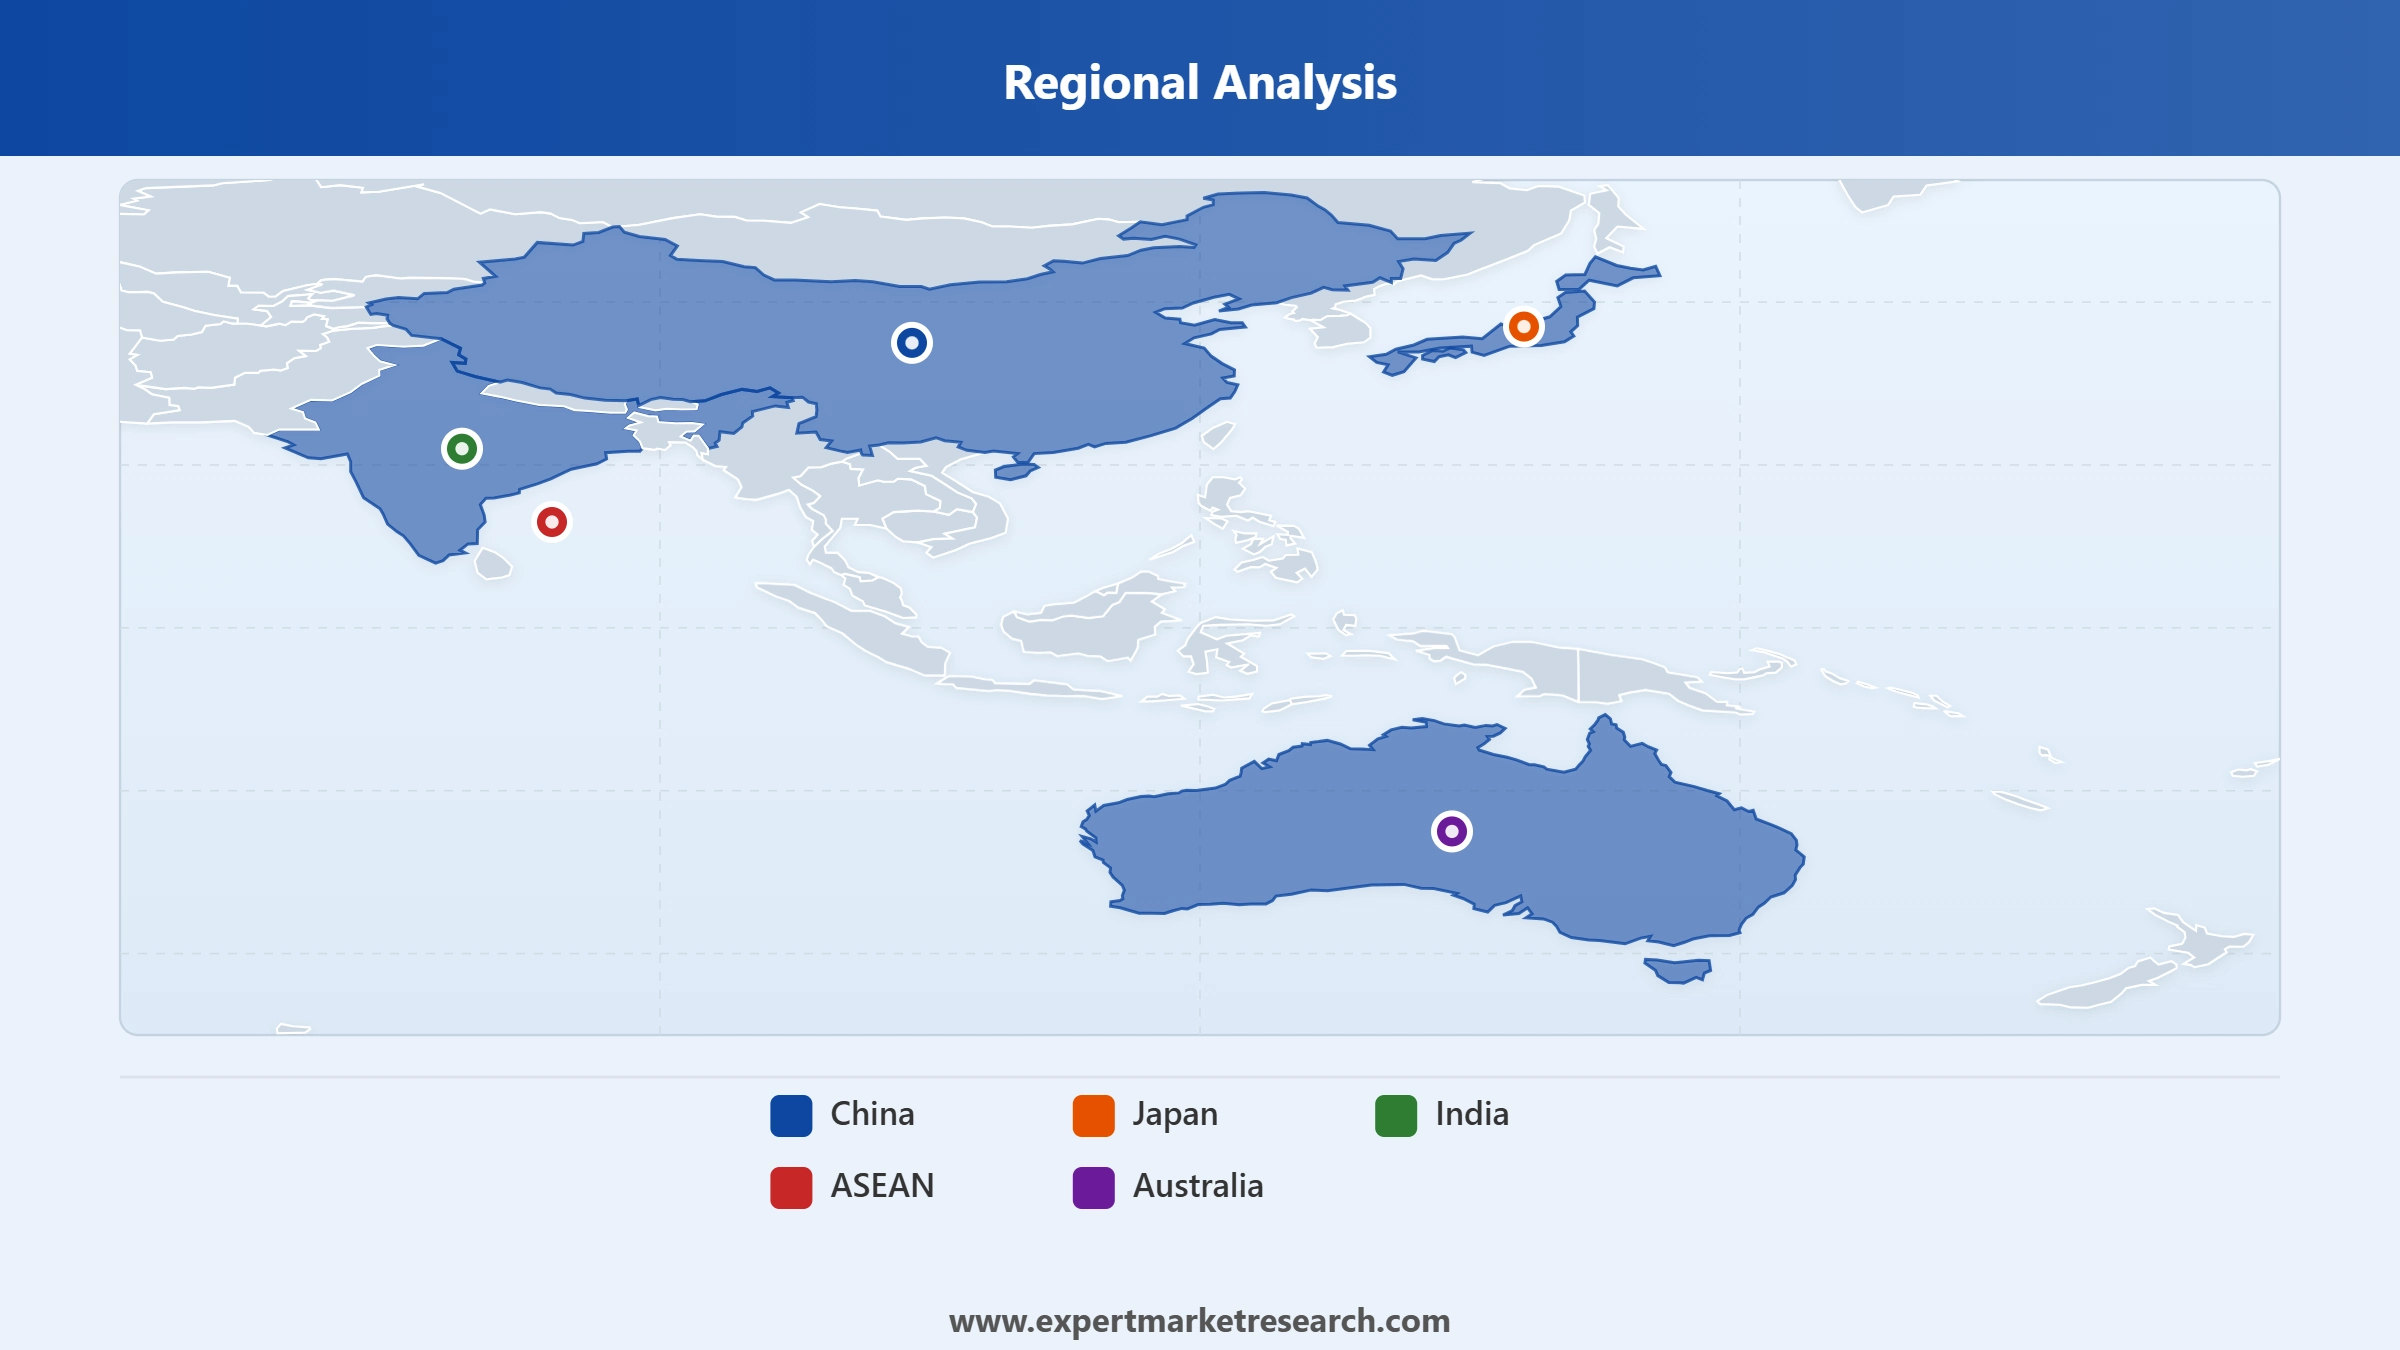
Key Insight: China accounts for the largest share of the market, anchored by its extensive industrial and refinery infrastructure and reinforced by Atlas Copco's April 2026 inauguration of its new Power Technique campus in Wuxi, Jiangsu province, alongside Sulzer's established dual-site Chinese manufacturing base. India is emerging as the fastest-growing market at an estimated CAGR of 5.20%, illustrated by Kirloskar Brothers' February 2026 thermal power contract with Adani Power. Japan continues to represent substantial demand tied to its established industrial manufacturing base. ASEAN serves growing infrastructure and industrial demand across Southeast Asian economies. Australia supports resource-processing applications tied to its mining sector. Others captures smaller regional markets including South Korea and Taiwan, where demand remains tied primarily to established electronics and semiconductor manufacturing infrastructure rather than the large-scale power and mining projects driving growth elsewhere.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By type, centrifugal pumps leads the market while positive displacement pumps grows fastest given offshore energy demand
Centrifugal Pumps continues to account for the largest share of the market, reflecting sustained deployment across water supply, wastewater, and general industrial fluid transfer applications throughout the region. Grundfos reinforced this position with its February 2026 full-year results, reporting 5.7 percent global sales growth alongside particularly strong momentum in India, one of the region's largest centrifugal pump markets, a performance the company attributed partly to expanding demand from industrial water treatment and commercial building services customers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Positive Displacement Pumps is growing at a fast pace across the asia pacific pumps market at a projected CAGR of 4.10%, illustrated by SPP Pumps' July 2026 vertical pump order from Saipem Offshore Construction requiring high-pressure, precision-engineered pump technology suited to demanding offshore energy applications across the region's expanding subsea project pipeline, which continues to attract fresh investment as regional energy majors sanction new offshore developments requiring specialised, high-pressure pumping equipment.
By end use, power generation leads the market while oil and gas grows steadily given offshore contract activity
Power Generation continues to account for the largest share of the market, reinforced by Kirloskar Brothers' February 2026 contract with Adani Power for circulating and auxiliary cooling water pump packages across four Indian states, underscoring the segment's reliance on domestic thermal-project engineering scale rather than imported equipment alone, a preference that continues to favour manufacturers with established local production and servicing infrastructure across the subcontinent.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Oil and Gas demand continues to expand, illustrated by SPP Pumps' July 2026 vertical pump order from Saipem Offshore Construction requiring compliance bonding and rigorous performance standards, reflecting the increasingly stringent qualification bar offshore energy contractors now apply to regional pump suppliers bidding for platform support work, a trend that is gradually consolidating offshore contract volume among a smaller pool of proven, compliance-ready manufacturers.
Water and Wastewater remains substantial, tied to municipal infrastructure expansion across the region. Chemicals and Petrochemicals is reinforced by Sulzer's continued dual-site Chinese manufacturing supporting domestic refinery projects. Mining Industry serves resource-processing applications across Australia and Southeast Asia, a segment CG Power's January 2026 transformer order from Tallgrass indirectly reflects through the wider industrial equipment investment cycle, while Others covers smaller-volume agricultural and food-processing demand, categories where hygiene-grade materials and simpler installation requirements typically favour smaller, regionally focused pump manufacturers over larger multinational suppliers.
China commands the largest share of the market through its extensive industrial and refinery manufacturing base
China holds the largest share of the Asia Pacific pumps market, anchored by its extensive refinery and industrial infrastructure and reinforced by Atlas Copco's April 2026 inauguration of its new Power Technique campus in Wuxi alongside Sulzer's established dual-site Chinese manufacturing base.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
India is emerging as the fastest-growing market at an estimated CAGR of 5.20%, illustrated by Kirloskar Brothers' February 2026 thermal power contract win with Adani Power and its subsidiaries. Japan continues to represent substantial demand tied to its established industrial manufacturing base and equipment replacement cycles. ASEAN serves growing infrastructure and industrial demand across Southeast Asian economies, supported by expanding manufacturing investment. Australia supports steady demand tied to its mining and resource-processing sector. Others, including South Korea and Taiwan, continues to serve distinct national industrial demand patterns.
The industry is fragmented, with asia pacific pumps market companies ranging from diversified industrial conglomerates spanning multiple engineering sectors to specialist pump manufacturers competing across type, end use, and country segments. Established players operate across the full pump value chain, from design and manufacturing through installation and aftermarket service for industrial, municipal, and utility customers.
Competitive dynamics among asia pacific pumps players are increasingly shaped by the scale of domestic power-sector contract wins, the depth of local manufacturing presence, and the strength of international subsidiary networks. Manufacturers are investing in thermal-project engineering credentials, expanded regional production capacity, and overseas distribution reach to secure long-term relationships with utility and industrial customers.
Founded in 1888 and headquartered in Pune, India, Kirloskar Brothers manufactures pumps and fluid management systems for power generation, water supply, and industrial applications. In February 2026, the company secured a contract worth approximately 214 crore rupees from Adani Power for thermal power project pump packages, while its UK subsidiary SPP Pumps won a July 2026 offshore order from Saipem worth approximately 11.7 million pounds. Kirloskar's combination of domestic thermal-project scale and international subsidiary reach differentiates its offering from purely domestic competitors.
Founded in 1912 and headquartered in Tokyo, Japan, Ebara manufactures pumps, compressors, turbines, and other fluid and thermal machinery alongside waste treatment facility services. The company operates across precision and electronics, energy, construction industry, and infrastructure and environment business segments. Ebara's diversified fluid and thermal machinery portfolio differentiates its offering from pump-only specialists.
Founded in 1873 and headquartered in Nacka, Sweden, Atlas Copco supplies compressed air and vacuum solutions, energy solutions, dewatering and industrial pumps, and industrial power tools. In April 2026, the company inaugurated its new Power Technique campus in Wuxi, China, citing alignment with the country's 15th Five-Year Plan energy efficiency priorities. Atlas Copco's diversified industrial technology portfolio differentiates its offering from pump-only manufacturers.
Founded in 1834 and headquartered in Winterthur, Switzerland, Sulzer specialises in pumping, agitation, mixing, separation, and application technologies for fluids across industrial sectors. The company operates dual manufacturing sites in China, at Dalian and Suzhou, supporting close collaboration between Asia, Europe, and US engineering teams for complex refinery pump orders. Sulzer's established Chinese dual-site manufacturing presence differentiates its offering from suppliers reliant on imported equipment.
Other key players in the Asia Pacific pumps market include Iwaki Co., Ltd, Flowserve Corporation, Grundfos Holding A/S, KSB Limited, The Weir Group PLC, Schlumberger Limited, Baker Hughes Company, and CG Power & Industrial Solutions Ltd, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Asia Pacific pumps market trends 2026 report. Discover regional growth patterns, type and end use trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 35.03 Billion.
The market is projected to grow at a CAGR of 3.70% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 50.38 Billion by 2035.
Pumps are used to move fluids or gases from one location to another. This includes moving water for irrigation, pumping oil or gas for industrial processes, and moving air in vacuum cleaners.
Pumps increase the efficiency of a system by lowering the amount of energy needed to move fluids. Pumps can be used to transport dangerous and toxic fluids, reducing health risks to workers.
Securing large-scale domestic power sector contracts, expanding international subsidiary networks to access offshore energy orders, and investing in local manufacturing capacity to align with national industrial policy cycles.
Key trends aiding market expansion include an expanding agricultural sector, rising demand for clean water, and growing demand for energy-efficient pumps.
Major countries in the market are China, Japan, India, ASEAN, Australia, and others.
The common types of pumps are centrifugal pumps, positive displacement pumps, and others.
The key players in the market include Kirloskar Brothers Limited, Iwaki Co., Ltd, Ebara Corporation, Atlas Copco AB, Flowserve Corporation, Grundfos Holding A/S, KSB Limited, Sulzer AG, The Weir Group PLC, Schlumberger Limited, Baker Hughes Company, and CG Power & Industrial Solutions Ltd, among others.
Manufacturers face intense price competition from a fragmented supplier base, the technical complexity of securing large-scale thermal and offshore project certification, and long execution timelines for multi-state contract delivery.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




