

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
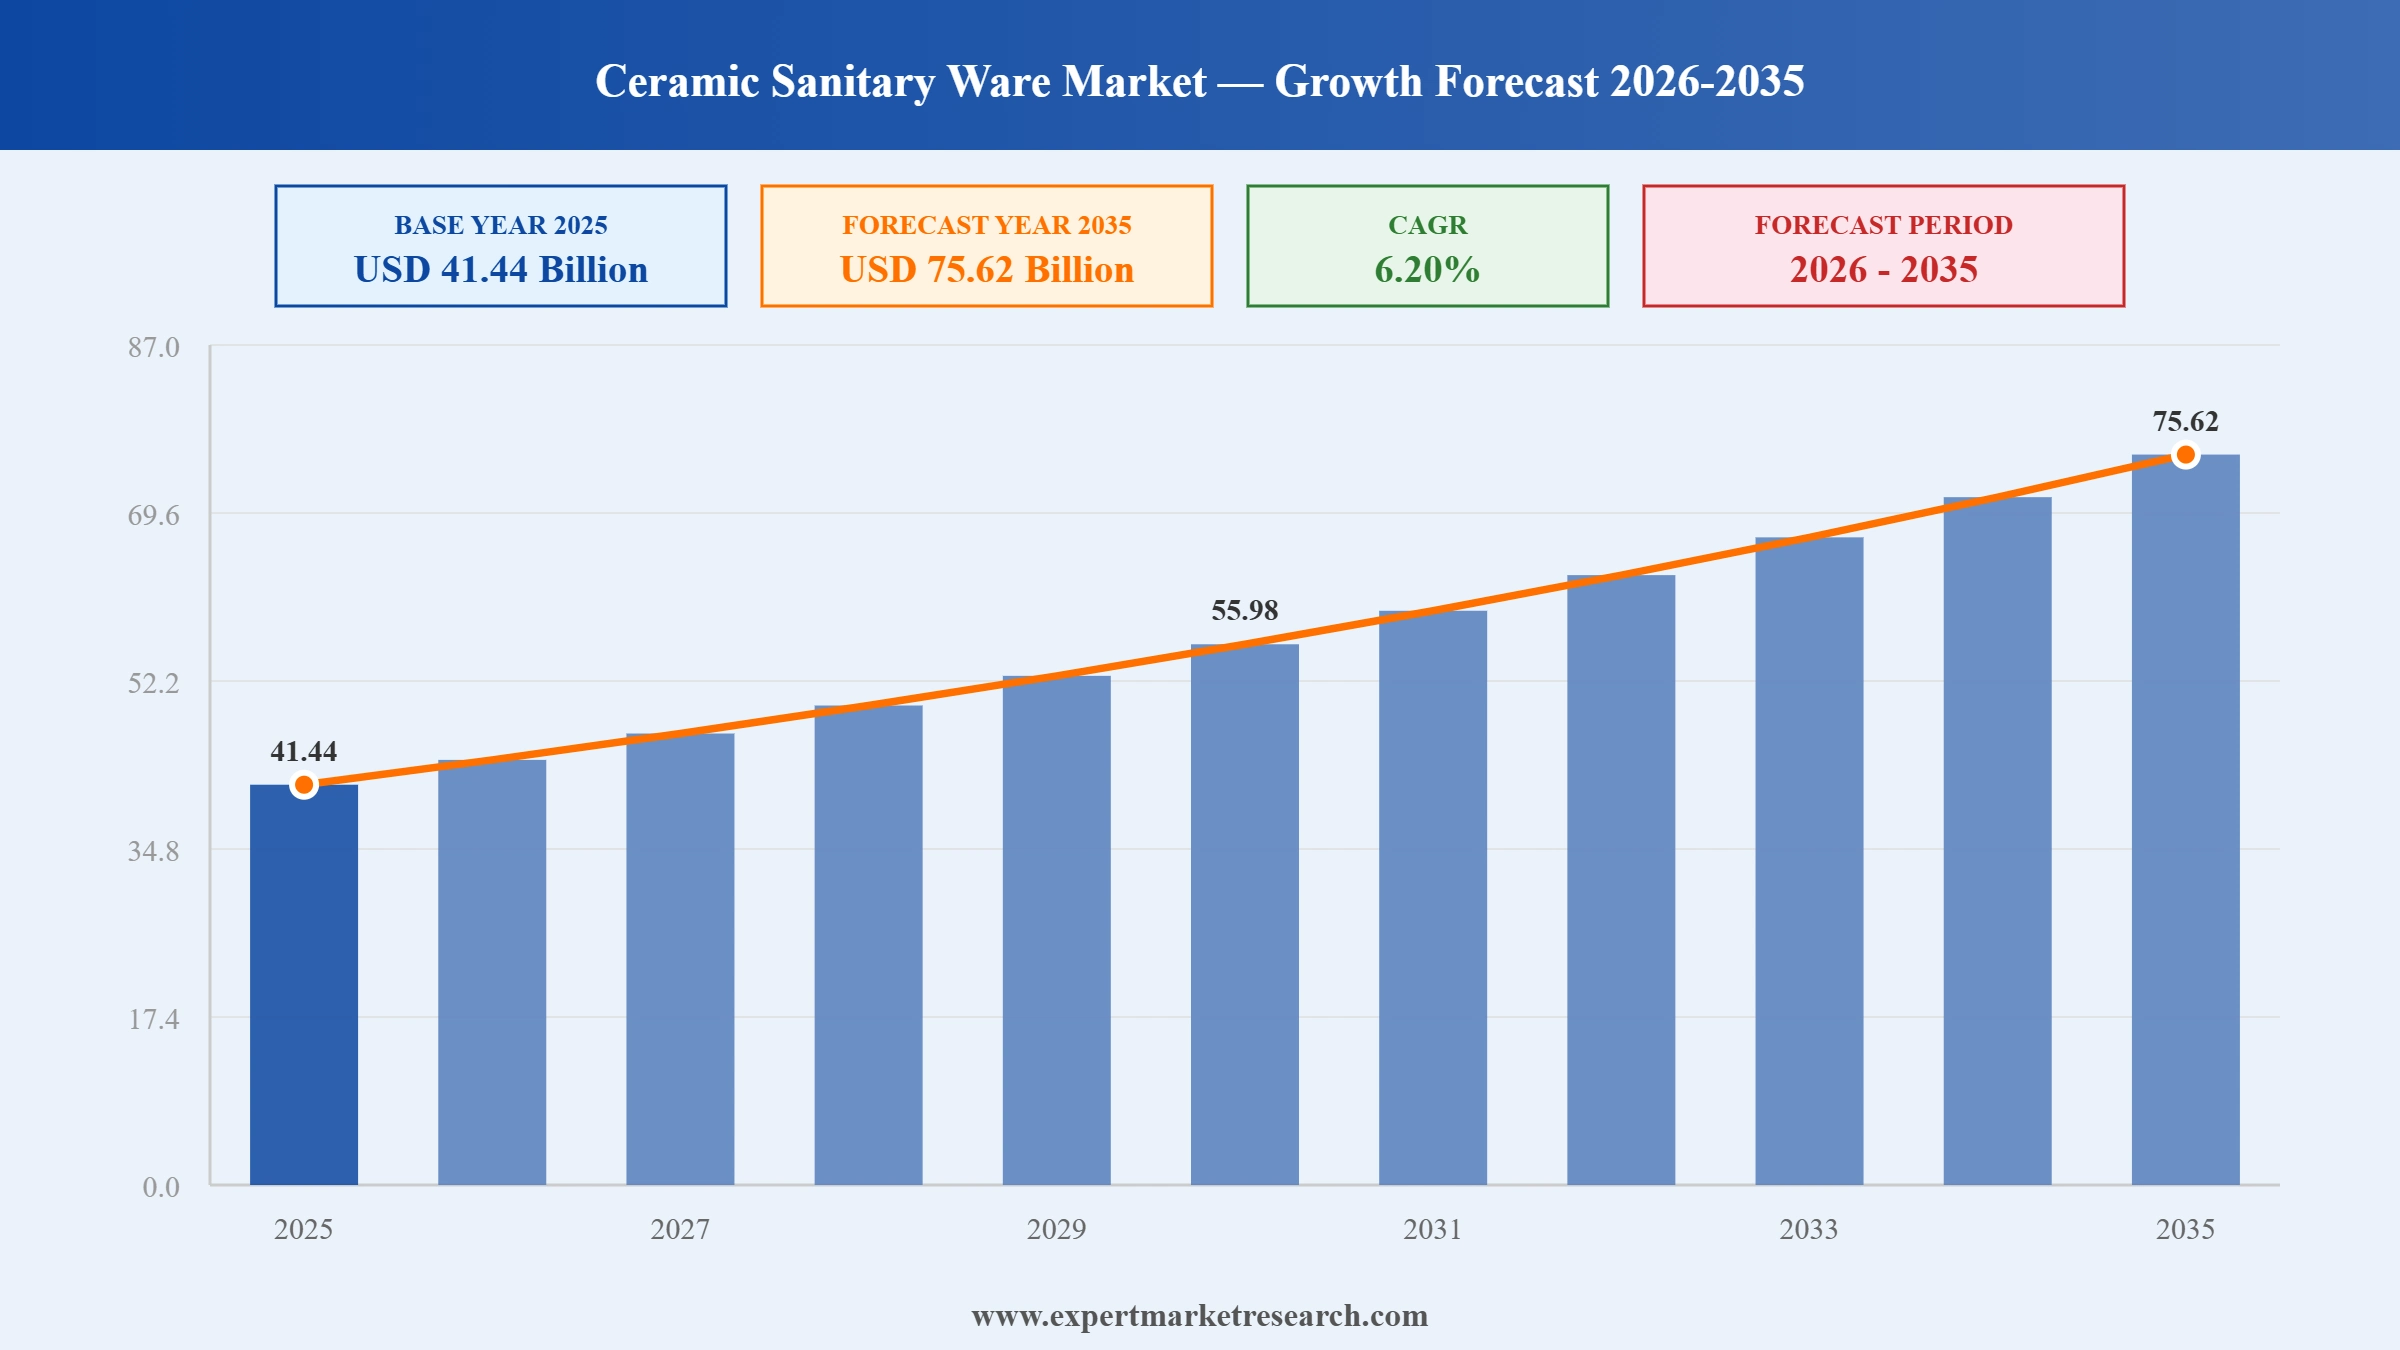
The global ceramic sanitary ware market attained a value of USD 41.44 Billion in 2025 and is projected to expand at a CAGR of 6.20% through 2035. The market is further expected to achieve USD 75.62 Billion by 2035. Rising residential and commercial construction activity, growing hygiene and sanitation awareness, and increasing adoption of smart, water-efficient bathroom fixtures continue to support demand for washbasins, urinals, and toilet sinks across both offline and online distribution channels.
Rising residential and commercial construction activity continues to anchor steady demand across the ceramic sanitary ware market, as urbanisation and infrastructure development projects in emerging economies drive new plumbing installations. Manufacturers are also investing in smart technology and water-efficient designs, reflecting the industry's ongoing pursuit of sustainable, hygiene-focused bathroom solutions. In May 2026, a United Kingdom WC suite performance specification took effect, setting a 6-litre maximum flush volume requirement starting May 2027, creating a regulatory anchor that favours manufacturers with compliant hydraulic platforms.
The ceramic sanitary ware market is witnessing further developments as established manufacturers pursue product mix upgrades toward higher-value, sustainable offerings. LIXIL reported its fiscal year 2026 results highlighting a mix shift toward high-value-added products, including the standardisation of its recycled low-carbon aluminium PremiAL material across product lines. This shift toward sustainable, premium product positioning is concentrated among manufacturers with sufficient research and development scale, while smaller specialists continue to compete on price and regional distribution reach.
In addition, established manufacturers are increasingly scaling direct-to-consumer digital sales channels, reflecting the industry's recognition that augmented-reality visualisation tools and proprietary web stores increasingly influence purchasing decisions beyond traditional showroom visits. Such digital channel expansion is reshaping competitive positioning across the wider ceramic sanitary ware market as manufacturers with proven direct-to-consumer platforms increasingly differentiate themselves from competitors reliant solely on traditional distributor networks.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
RAK Ceramics reported a resilient second quarter 2026 performance despite regional disruptions, supply chain challenges, and elevated logistics costs, supported by strong demand across the UAE, Saudi Arabia, and Bangladesh. Companies can diversify demand across multiple high-growth regional markets to offset localised disruptions and maintain resilient overall performance.
The United Kingdom published a new WC suite performance specification setting a 6-litre maximum flush volume requirement effective from May 2027, creating a procurement anchor favouring manufacturers with compliant hydraulic platforms. Companies can validate hydraulic performance ahead of tightening regulatory deadlines to secure specification advantages over slower-moving competitors.
LIXIL reported its fiscal year 2026 results, highlighting a mix shift toward high-value-added products including the standardisation of its recycled low-carbon aluminium PremiAL material across product lines. Companies can standardise sustainable materials across broad product ranges to capture premium pricing while meeting tightening environmental procurement standards.
RAK Ceramics upgraded its production line with new machinery to efficiently produce large-format ceramic tiles, responding to growing market demand for bigger tile sizes. Companies can invest in production line upgrades ahead of confirmed demand shifts to secure early positioning in emerging size and format preferences.
Established manufacturers continue to pursue product mix shifts toward higher-value, sustainable offerings. In April 2026, LIXIL reported fiscal year results highlighting a shift toward high-value-added products, including standardisation of a recycled low-carbon material across its product range within the ceramic sanitary ware market. Such sustainable product standardisation reflects manufacturers' recognition that recycled and low-carbon materials increasingly command premium pricing amid tightening environmental procurement standards across major markets.
Regulatory bodies continue tightening water efficiency performance standards for sanitary ware products. In May 2026, the United Kingdom introduced a new WC suite performance specification setting a stricter maximum flush volume requirement effective from the following year. Such regulatory tightening reflects governments' recognition that mandating hydraulic performance standards increasingly drives broader industry adoption of water-efficient product designs ahead of voluntary market transition.
Manufacturers continue reporting resilient financial performance despite ongoing regional disruptions and elevated logistics costs. In August 2026, RAK Ceramics reported a resilient second quarter performance, supported by strong demand across multiple Middle Eastern and South Asian markets. Such resilient performance reflects manufacturers' recognition that geographic demand diversification increasingly buffers against localised supply chain and logistics volatility.
Manufacturers continue upgrading production lines to meet growing demand for larger-format ceramic products. In September 2025, RAK Ceramics upgraded its production line with new machinery to efficiently produce larger-format tiles and sanitary ware components. Such production upgrades reflect manufacturers' recognition that evolving design preferences toward larger, seamless surfaces increasingly require dedicated capital investment rather than incremental equipment adjustments.
Diversified building materials groups continue to apply manufacturing and materials research developed across their broader product portfolios to increasingly sophisticated sanitary ware development. Established multi-category manufacturers continue to develop ceramic sanitary ware drawing on broader tile, faucet, and porcelain tableware research spanning multiple product categories beyond sanitary ware alone. Such cross-portfolio research investment gives diversified manufacturers a technical foundation that narrower sanitary-ware-only specialists must build through more limited, product-specific development.
This Expert Market Research Report titled "Ceramic Sanitary Ware Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
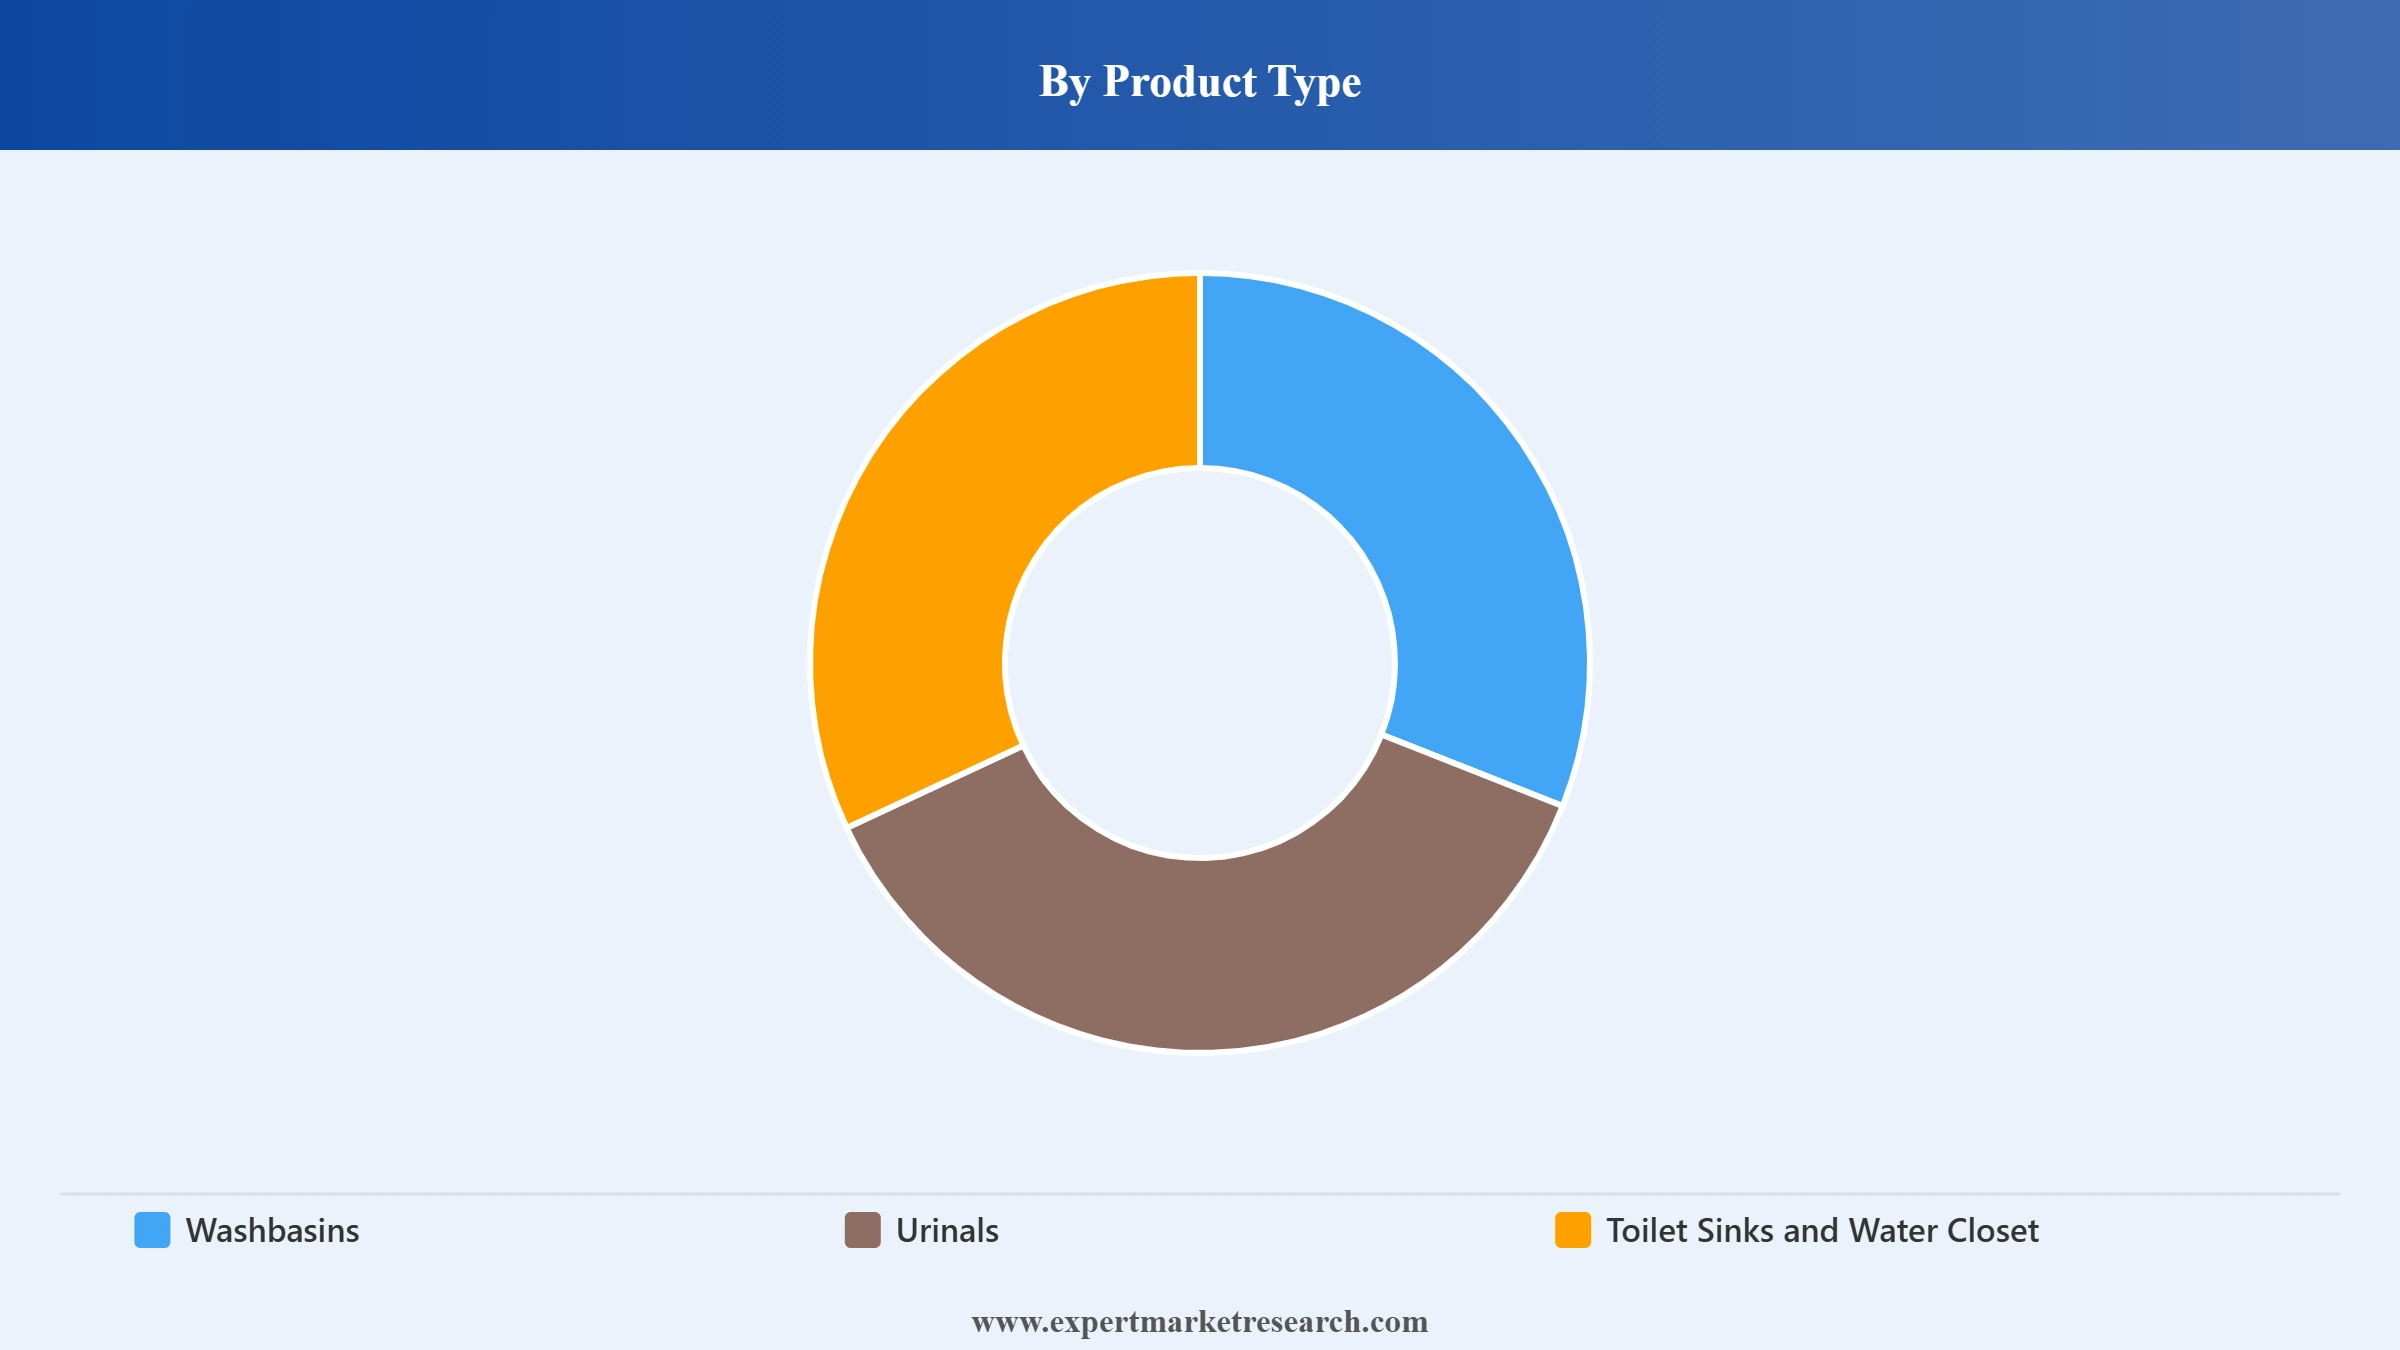
Key Insight: Toilet Sinks and Water Closet accounts for the largest share of the ceramic sanitary ware market, reflecting its essential, non-discretionary role in every residential and commercial plumbing installation. In May 2026, a new UK WC suite performance specification underscored the segment's exposure to tightening regulatory standards. Washbasins is growing at the fastest pace as renovation activity and design-led bathroom upgrades increasingly favour statement basin designs over standard fixtures. Urinals continue to serve dedicated commercial and institutional installations, with other product types rounding out the remaining category.
Market Breakup by Distribution Channel
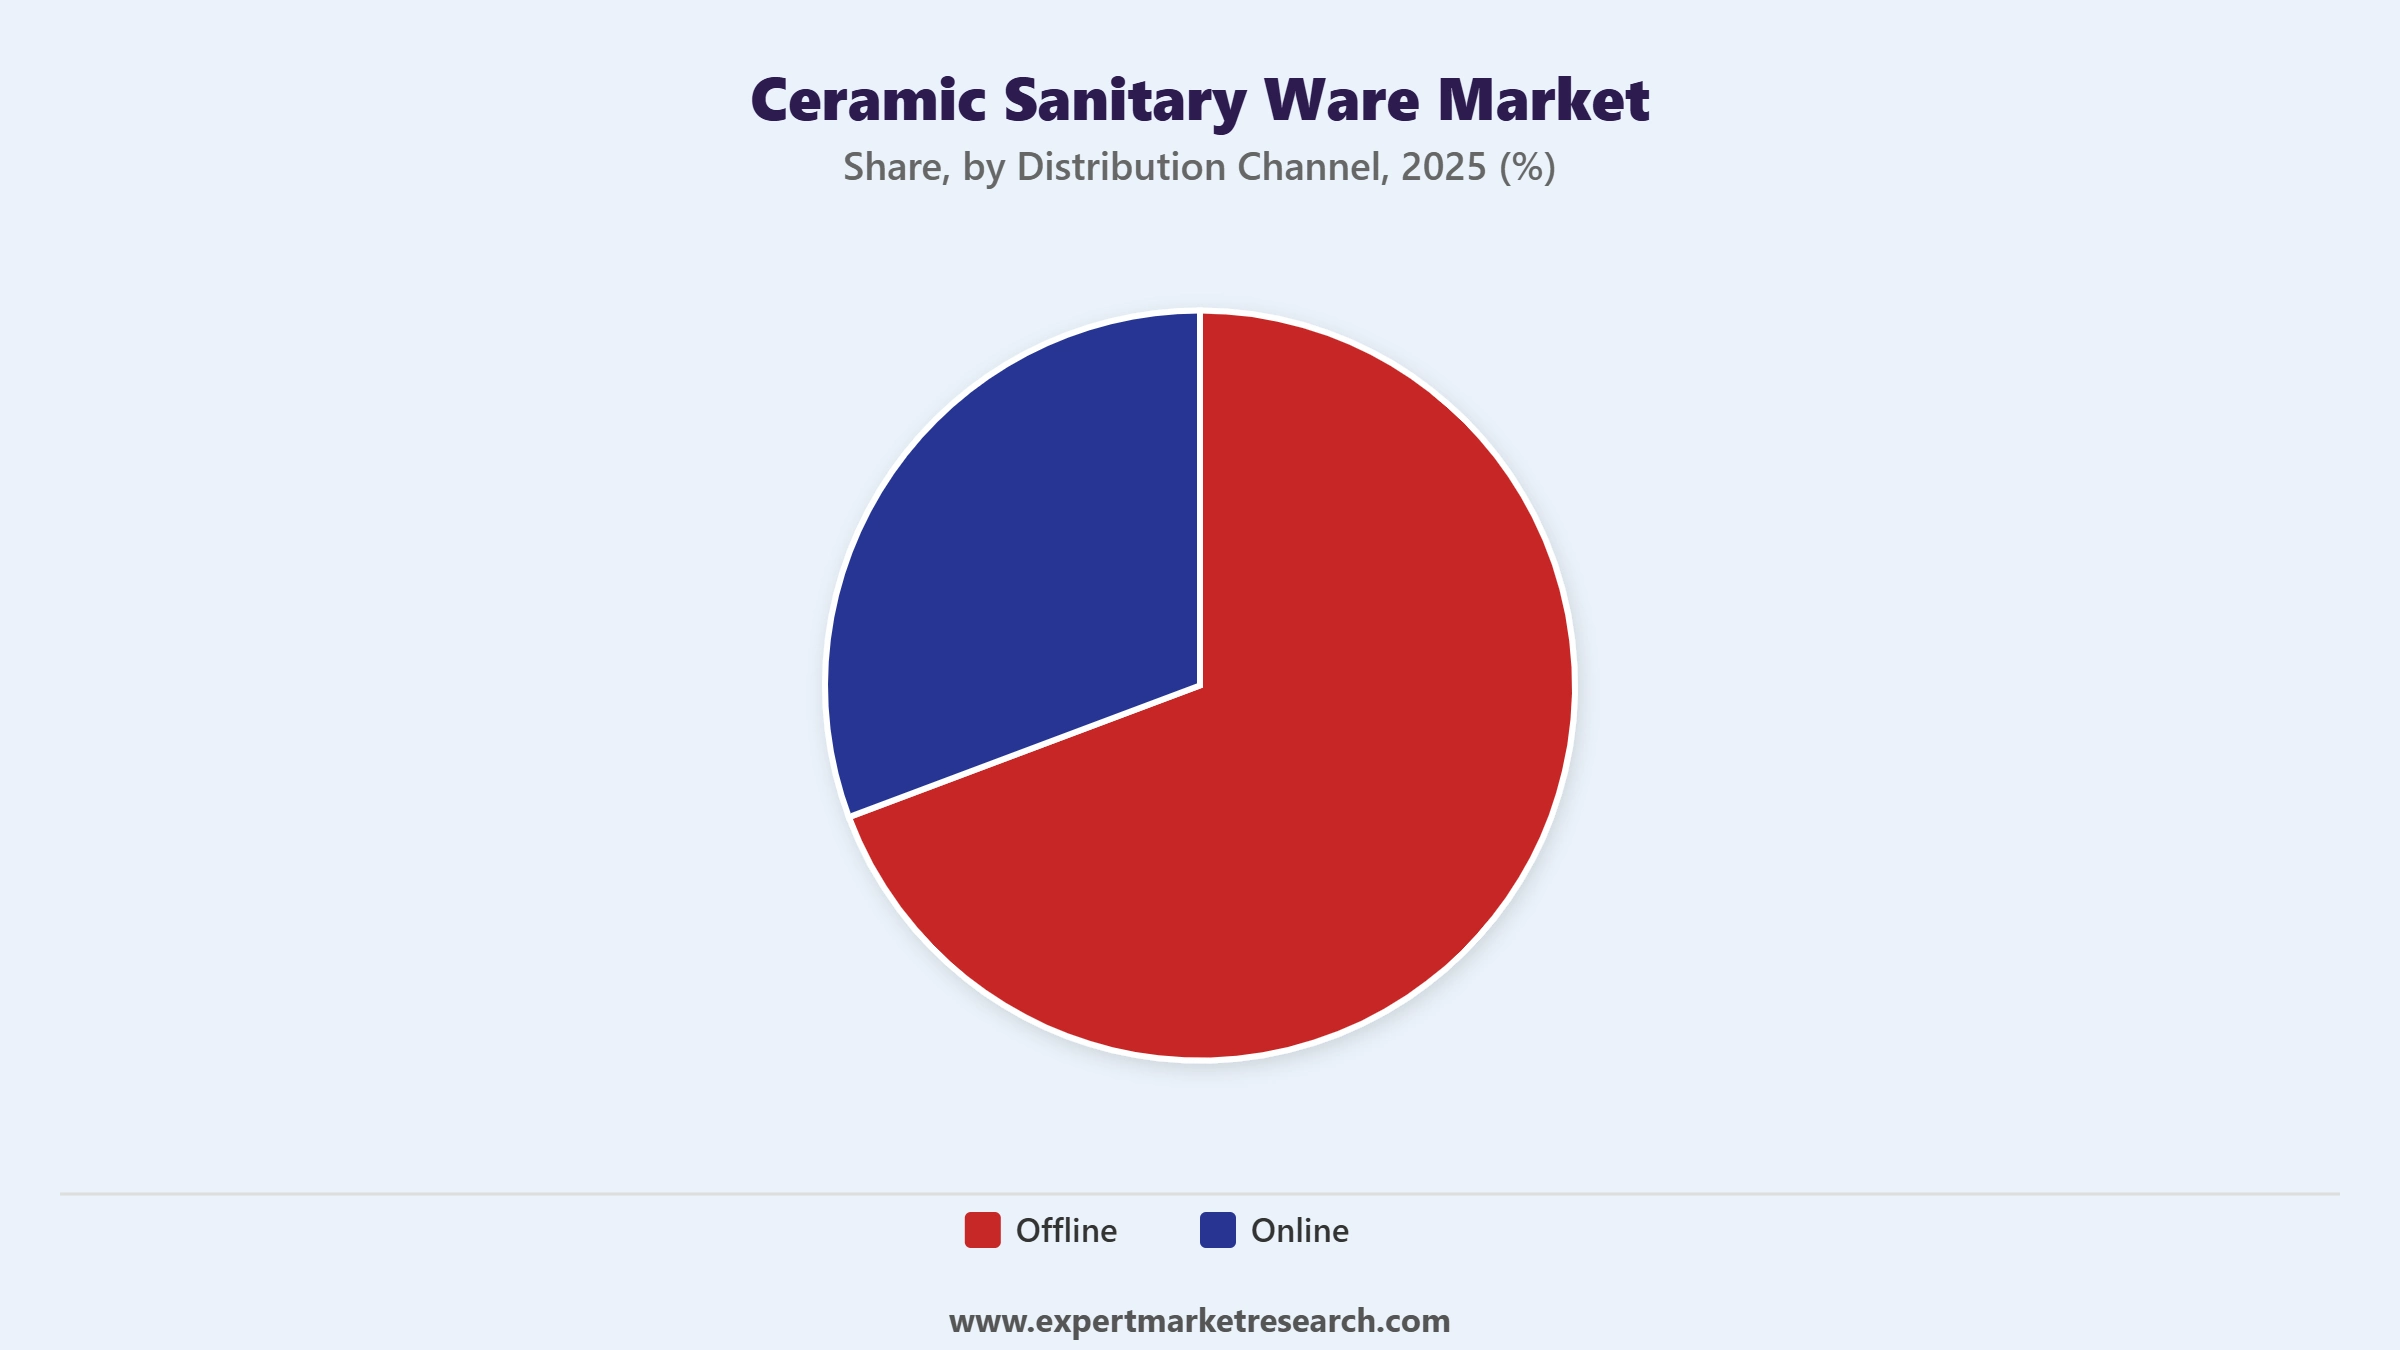
Key Insight: Offline distribution accounts for the largest share of the ceramic sanitary ware market, reflecting continued reliance on showroom visits and professional installation guidance for plumbing fixture purchases. Online distribution is growing at a fast pace as augmented-reality visualisation tools and proprietary manufacturer web stores increasingly let consumers evaluate fixtures remotely, illustrated by LIXIL and Roca scaling direct-to-consumer digital platforms. Industry survey data published in January 2026 found that 25 percent of bathroom fixture purchases were now made online, up from 21 percent the prior year.
Market Breakup by End Use
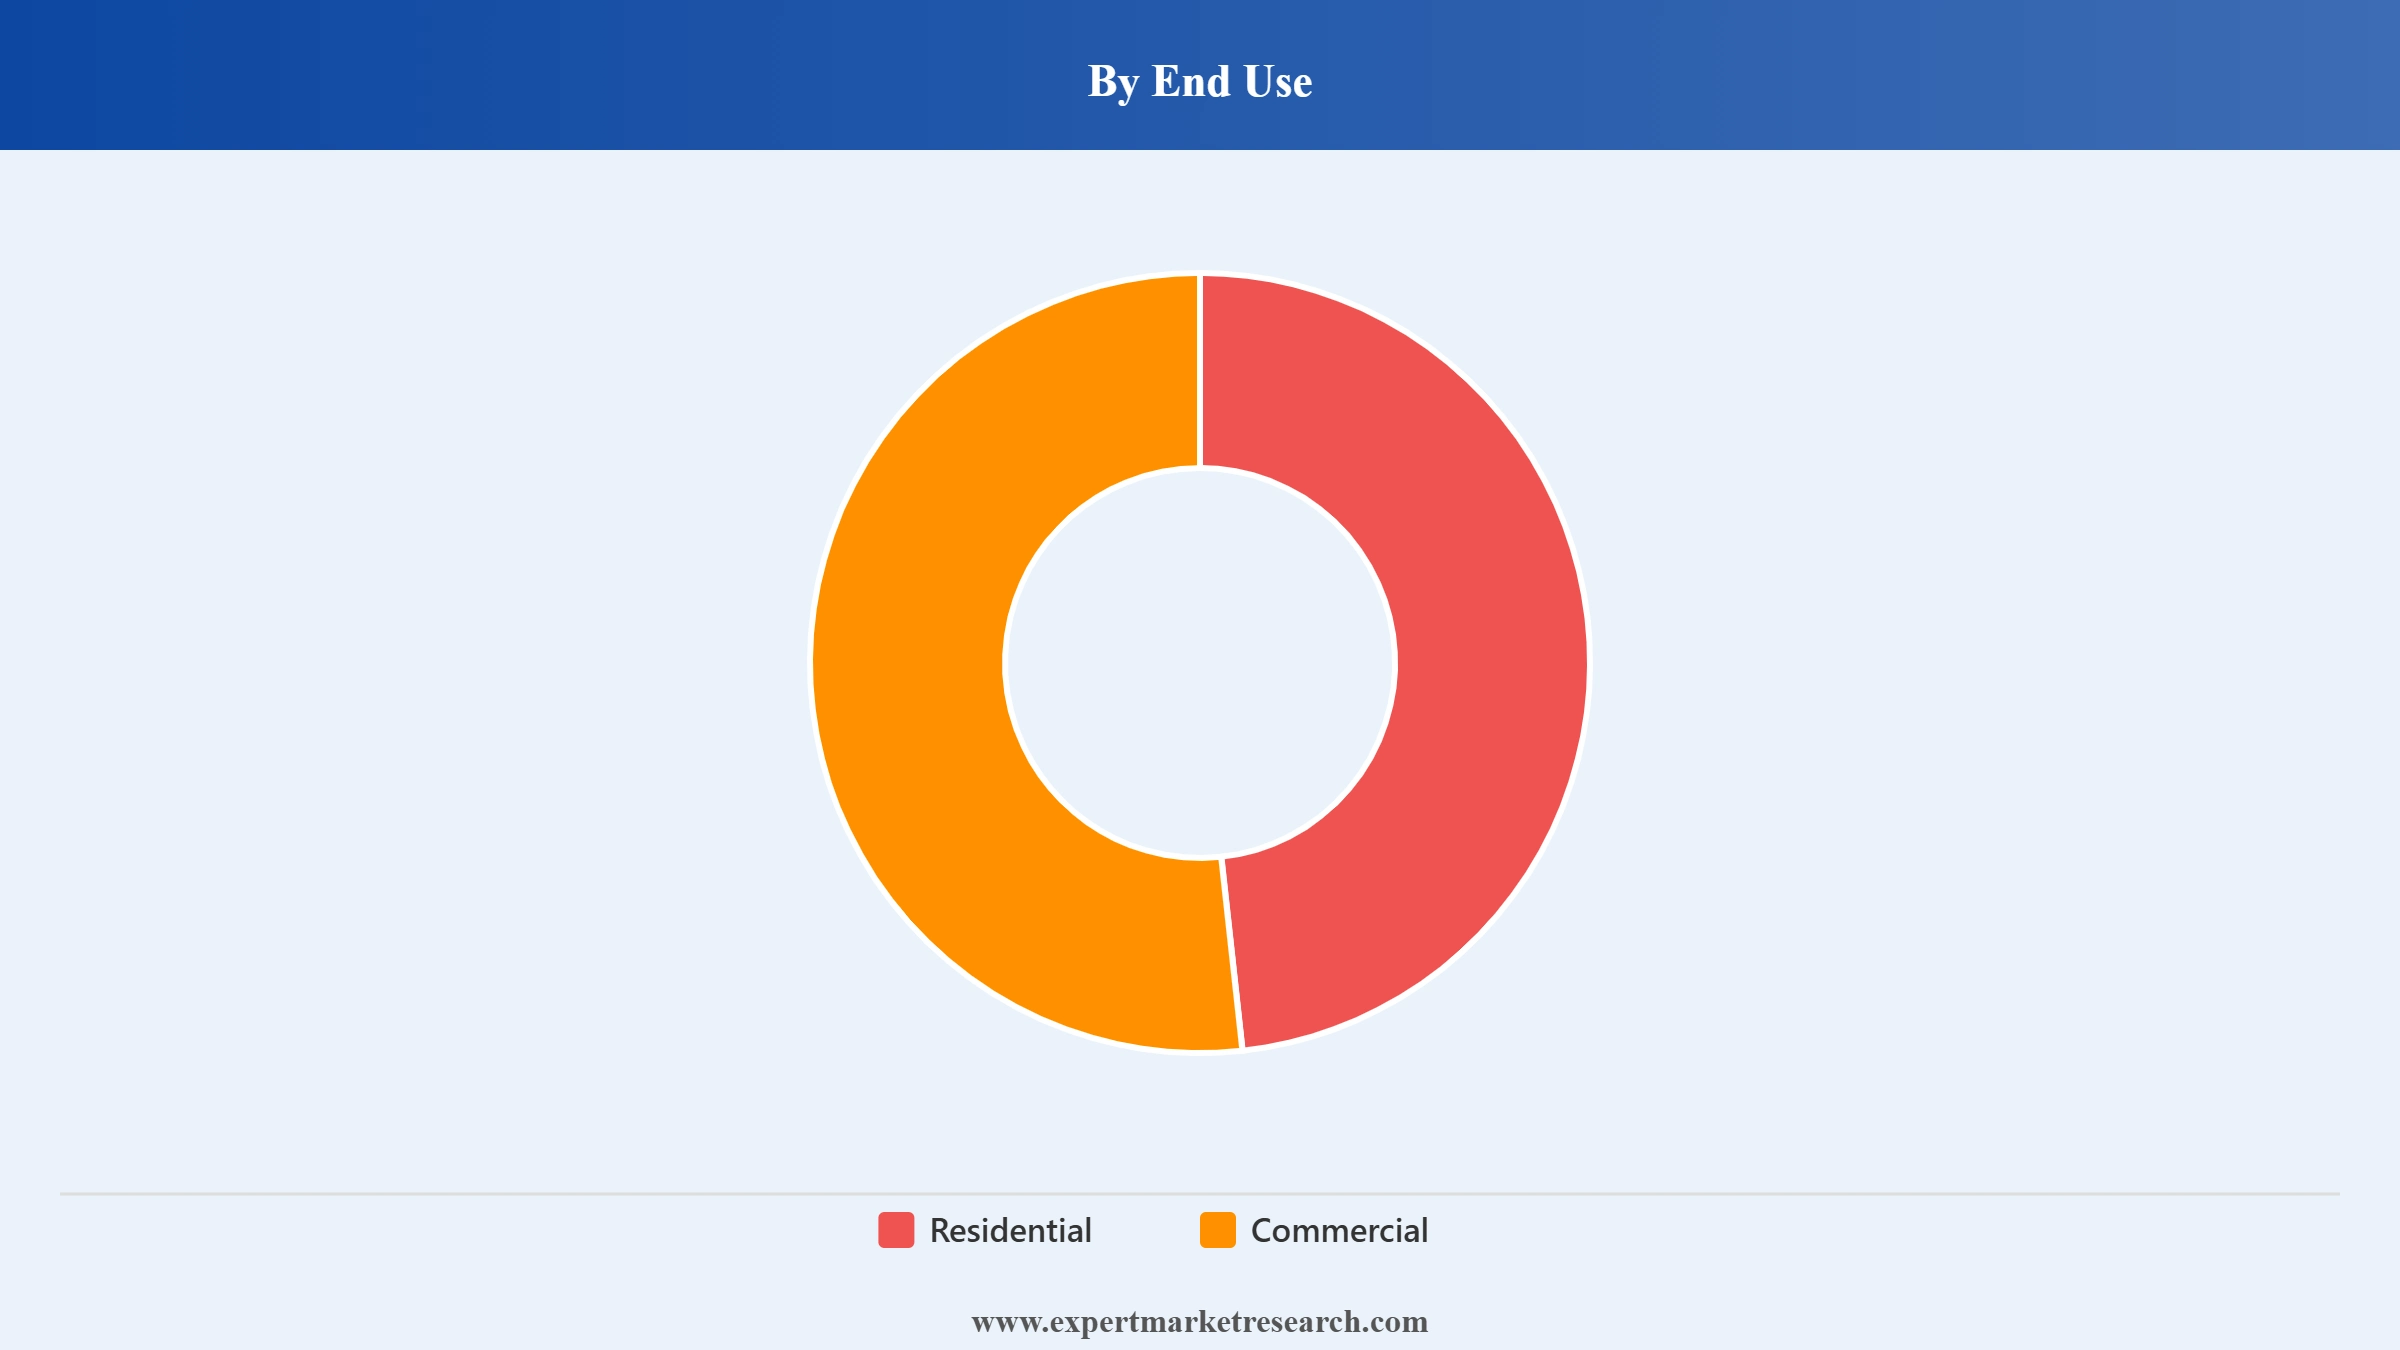
Key Insight: Residential accounts for the largest share of the ceramic sanitary ware market, reflecting sustained new-build housing construction and renovation activity across major economies. In February 2026, Kohler launched Reveal by KOHLER, a new premium bath and shower remodeling service combining design consultation with professional start-to-finish installation. Commercial end use is growing at a fast pace as hospitality, healthcare, and retail construction projects increasingly specify durable, design-consistent sanitary ware across multiple installed units. Industry analysis published in April 2026 found that hospitality and commercial developments across the Middle East are increasingly treating bathrooms as a driver of brand perception and guest experience rather than purely functional infrastructure.
Market Breakup by Region
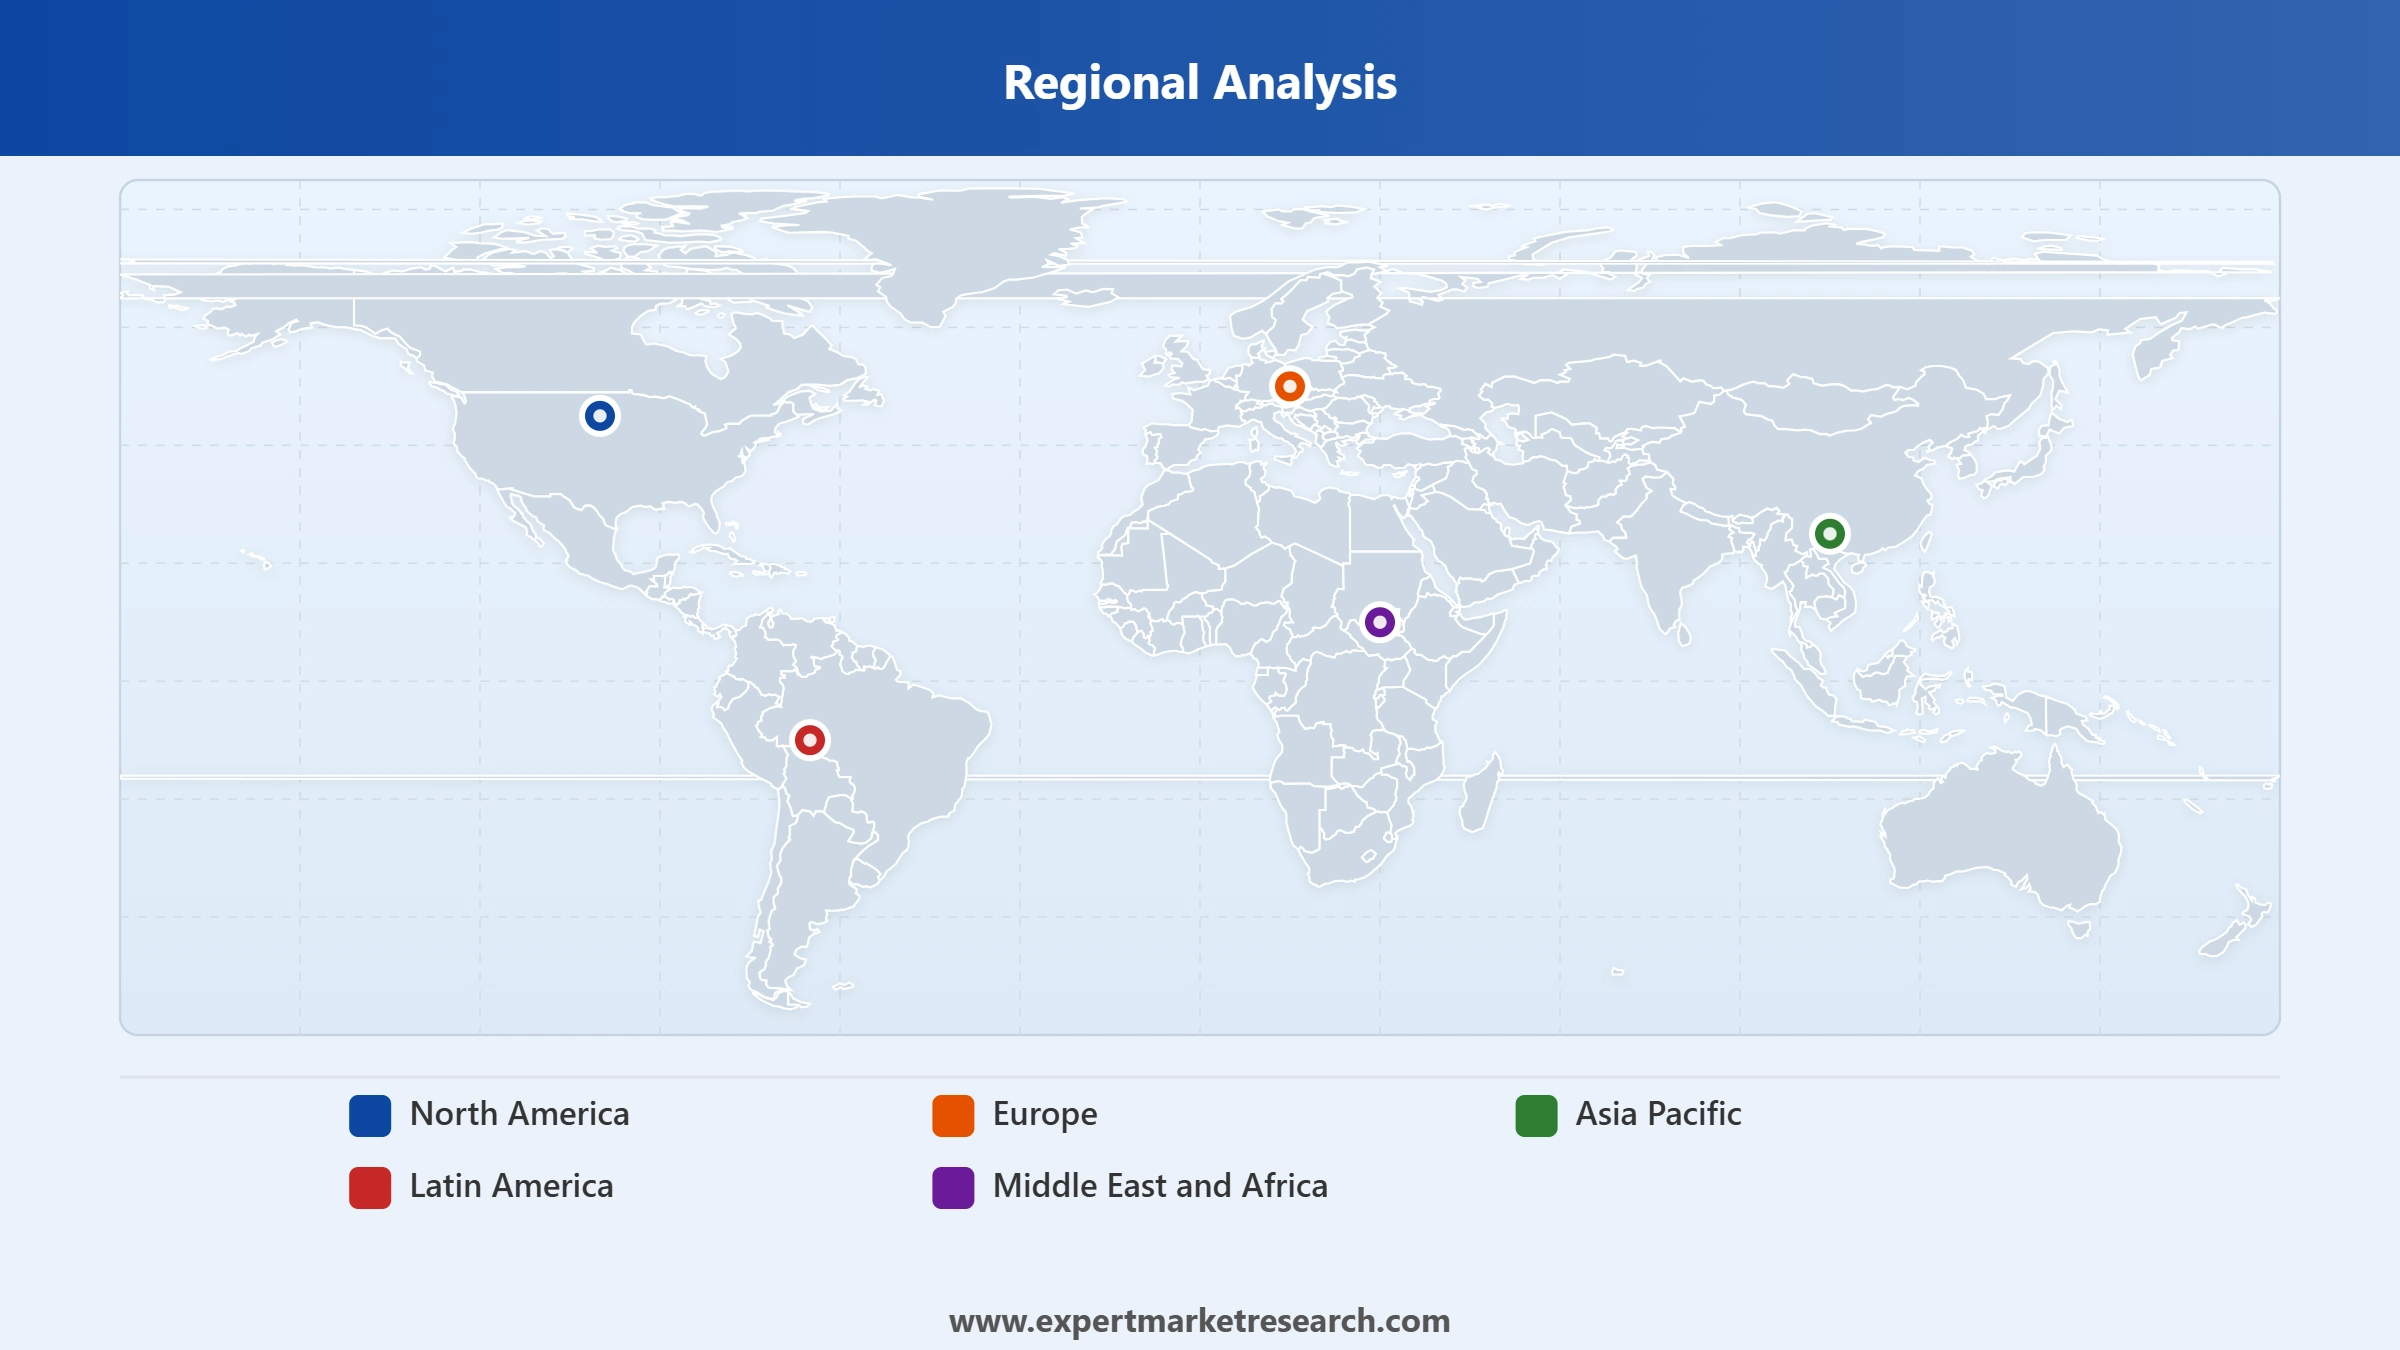
Key Insight: Asia Pacific accounts for the largest share of the ceramic sanitary ware market, supported by the region's expansive residential and commercial construction base spanning China, India, and Southeast Asia. Latin America is emerging as a key growth market as urbanisation and rising disposable incomes continue to drive bathroom fixture upgrades. North America, Europe, and the Middle East and Africa each continue to serve distinct regional construction and renovation patterns.
By product type, toilet sinks and water closet leads the market while washbasins grows fastest given renovation-driven design upgrades
Toilet Sinks and Water Closet continues to account for the largest share of the market, reflecting its essential, non-discretionary role in every residential and commercial plumbing installation. Established toilet and water closet supply relationships continue to anchor steady demand as contractors maintain proven fixture vendors across successive construction projects. In May 2026, the United Kingdom's new WC suite performance specification underscored the segment's central exposure to tightening flush-volume regulatory standards.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Washbasins is growing at the fastest pace across the ceramic sanitary ware market as renovation activity and design-led bathroom upgrades increasingly favour statement basin designs, with manufacturers expanding colour and texture options to meet aesthetic demand. At KBIS 2026 in February, Roca presented its Ona basin and bathtub collection, designed for cohesive residential, multi-family, and commercial spaces.
By distribution channel, offline leads the market while online grows fastest given expanding digital visualisation tools
Offline distribution continues to account for the largest share of the market, reflecting continued reliance on showroom visits and professional installation guidance for plumbing fixture purchases. In April 2026, Al-Futtaim Contracting highlighted its continued reliance on established sanitaryware manufacturer partnerships, including TOTO, to deliver showroom-specified fixtures across Middle East hospitality and commercial projects.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Online distribution is growing at the fastest pace across the ceramic sanitary ware market as manufacturers scale proprietary web stores and augmented-reality visualisation tools that let consumers evaluate fixtures remotely, reducing reliance on in-store showroom visits. LIXIL's fiscal year 2026 results, reported in April 2026, highlighted continued investment in digital sales tools alongside its broader product mix shift toward high-value offerings.
By end use, residential leads the market while commercial grows fastest given expanding hospitality and healthcare specification
Residential continues to account for the largest share of the market, reflecting sustained new-build housing construction and renovation activity across major economies. At KBIS 2026 in February, Roca presented a portfolio focused on performance and contemporary design for residential and multi-family projects.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Commercial is growing at the fastest pace across the ceramic sanitary ware market as hospitality, healthcare, and retail construction projects increasingly specify durable, sensor-driven fixtures. In April 2026, Al-Futtaim Contracting highlighted its use of TOTO's intelligent, sensor-driven sanitaryware to meet modern hospitality and commercial performance standards across Middle East projects.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific commands the largest share of the market through its expansive construction base
Asia Pacific holds the largest share of the ceramic sanitary ware market, supported by the region's expansive residential and commercial construction base spanning China, India, and Southeast Asia. Regional manufacturers continue to expand production capacity to meet both domestic consumption growth and rising export demand to international markets.
Latin America is emerging as a key growth market as urbanisation and rising disposable incomes continue to drive bathroom fixture upgrades across the region. In August 2026, continued strong regional demand performance across the Middle East and South Asia reinforced the broader importance of geographic diversification for manufacturers operating across the wider ceramic sanitary ware market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The global industry is moderately consolidated, with ceramic sanitary ware market companies ranging from diversified global building materials groups spanning multiple product categories to specialist ceramic sanitary ware manufacturers competing across product type, distribution channel, and end use segments. Established players operate across the full sanitary ware value chain, from raw material sourcing and ceramic forming through complete fixture manufacturing and distribution for residential and commercial customers.
Competitive dynamics among ceramic sanitary ware players are increasingly shaped by the pace of sustainable material adoption, the scale of direct-to-consumer digital channel investment, and the race to comply with tightening water efficiency regulatory standards. Manufacturers are investing in smart fixture technology, recycled material standardisation, and augmented-reality sales tools to differentiate their offering and secure long-term customer relationships.
Founded in 1917 and headquartered in Barcelona, Spain, Roca Sanitario manufactures ceramic sanitary ware, bathroom fixtures, and tiles under its Roca and Roca Tiles brands. The company serves both residential and commercial customers across more than 170 countries. Roca's combined sanitary ware and tile manufacturing portfolio differentiates its offering from competitors focused solely on plumbing fixtures.
Founded in 1873 and headquartered in Kohler, Wisconsin, United States, Kohler manufactures kitchen and bathroom fixtures including smart toilets, sinks, and bathing products. The company serves premium residential and hospitality customers seeking advanced comfort and hygiene technology. Kohler's diversified portfolio spanning engines, furniture, and hospitality alongside plumbing fixtures differentiates its offering from narrower sanitary-ware-only competitors.
Founded in 1874 and headquartered in Rapperswil-Jona, Switzerland, Geberit manufactures sanitary products and plumbing systems, with particular strength in concealed cistern and installation technology. The company serves contractors and specifiers requiring integrated plumbing system solutions beyond visible fixtures alone. Geberit's technical specialisation in installation systems differentiates its offering from competitors focused primarily on visible ceramic ware.
Founded in 1917 and headquartered in Kitakyushu, Japan, TOTO manufactures ceramic sanitary ware and smart toilets, holding a leading global position in washlet and bidet-integrated toilet technology. The company serves residential and commercial customers across Asia, North America, and Europe. TOTO's advanced washlet and self-cleaning technology differentiates its offering from competitors with less developed smart toilet capabilities.
Other key players in the ceramic sanitary ware market include Corona Industrial S.A.S., LIXIL Corporation, Huida Sanitary Ware Co., Ltd., Cersanit S.A., RAK Ceramics PJSC, and Cera Sanitaryware Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our ceramic sanitary ware market trends 2026 report. Discover regional growth patterns, product type and distribution channel trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 41.44 Billion.
The market is projected to grow at a CAGR of 6.20% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035, reaching a value of around USD 75.62 Billion by 2035.
Standardising sustainable and recycled materials across product ranges, scaling direct-to-consumer digital sales channels with augmented-reality visualisation tools, and investing in smart, water-efficient fixture technology ahead of tightening regulatory deadlines.
The key trends of the market include growing demand for sustainable sanitary ware products, increased incorporation of smart technology into ceramic toilet sinks, and a surge in investment by several market players in developing economies.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
Various product types are washbasins, urinals, and toilet sinks and water closet, among others.
The key players in the market include Roca Sanitario, S.A, Kohler Co., Geberit AG, TOTO Ltd., Corona Industrial S.A.S., LIXIL Corporation, Huida Sanitary Ware Co., Ltd., Cersanit S.A., RAK Ceramics PJSC, and Cera Sanitaryware Limited, among others.
Manufacturers face tightening water efficiency regulatory standards requiring ongoing product redesign, price sensitivity in emerging markets limiting premium product adoption, and rising raw material and energy costs affecting ceramic firing processes.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product Type |
|
| Breakup by Distribution Channel |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




