

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
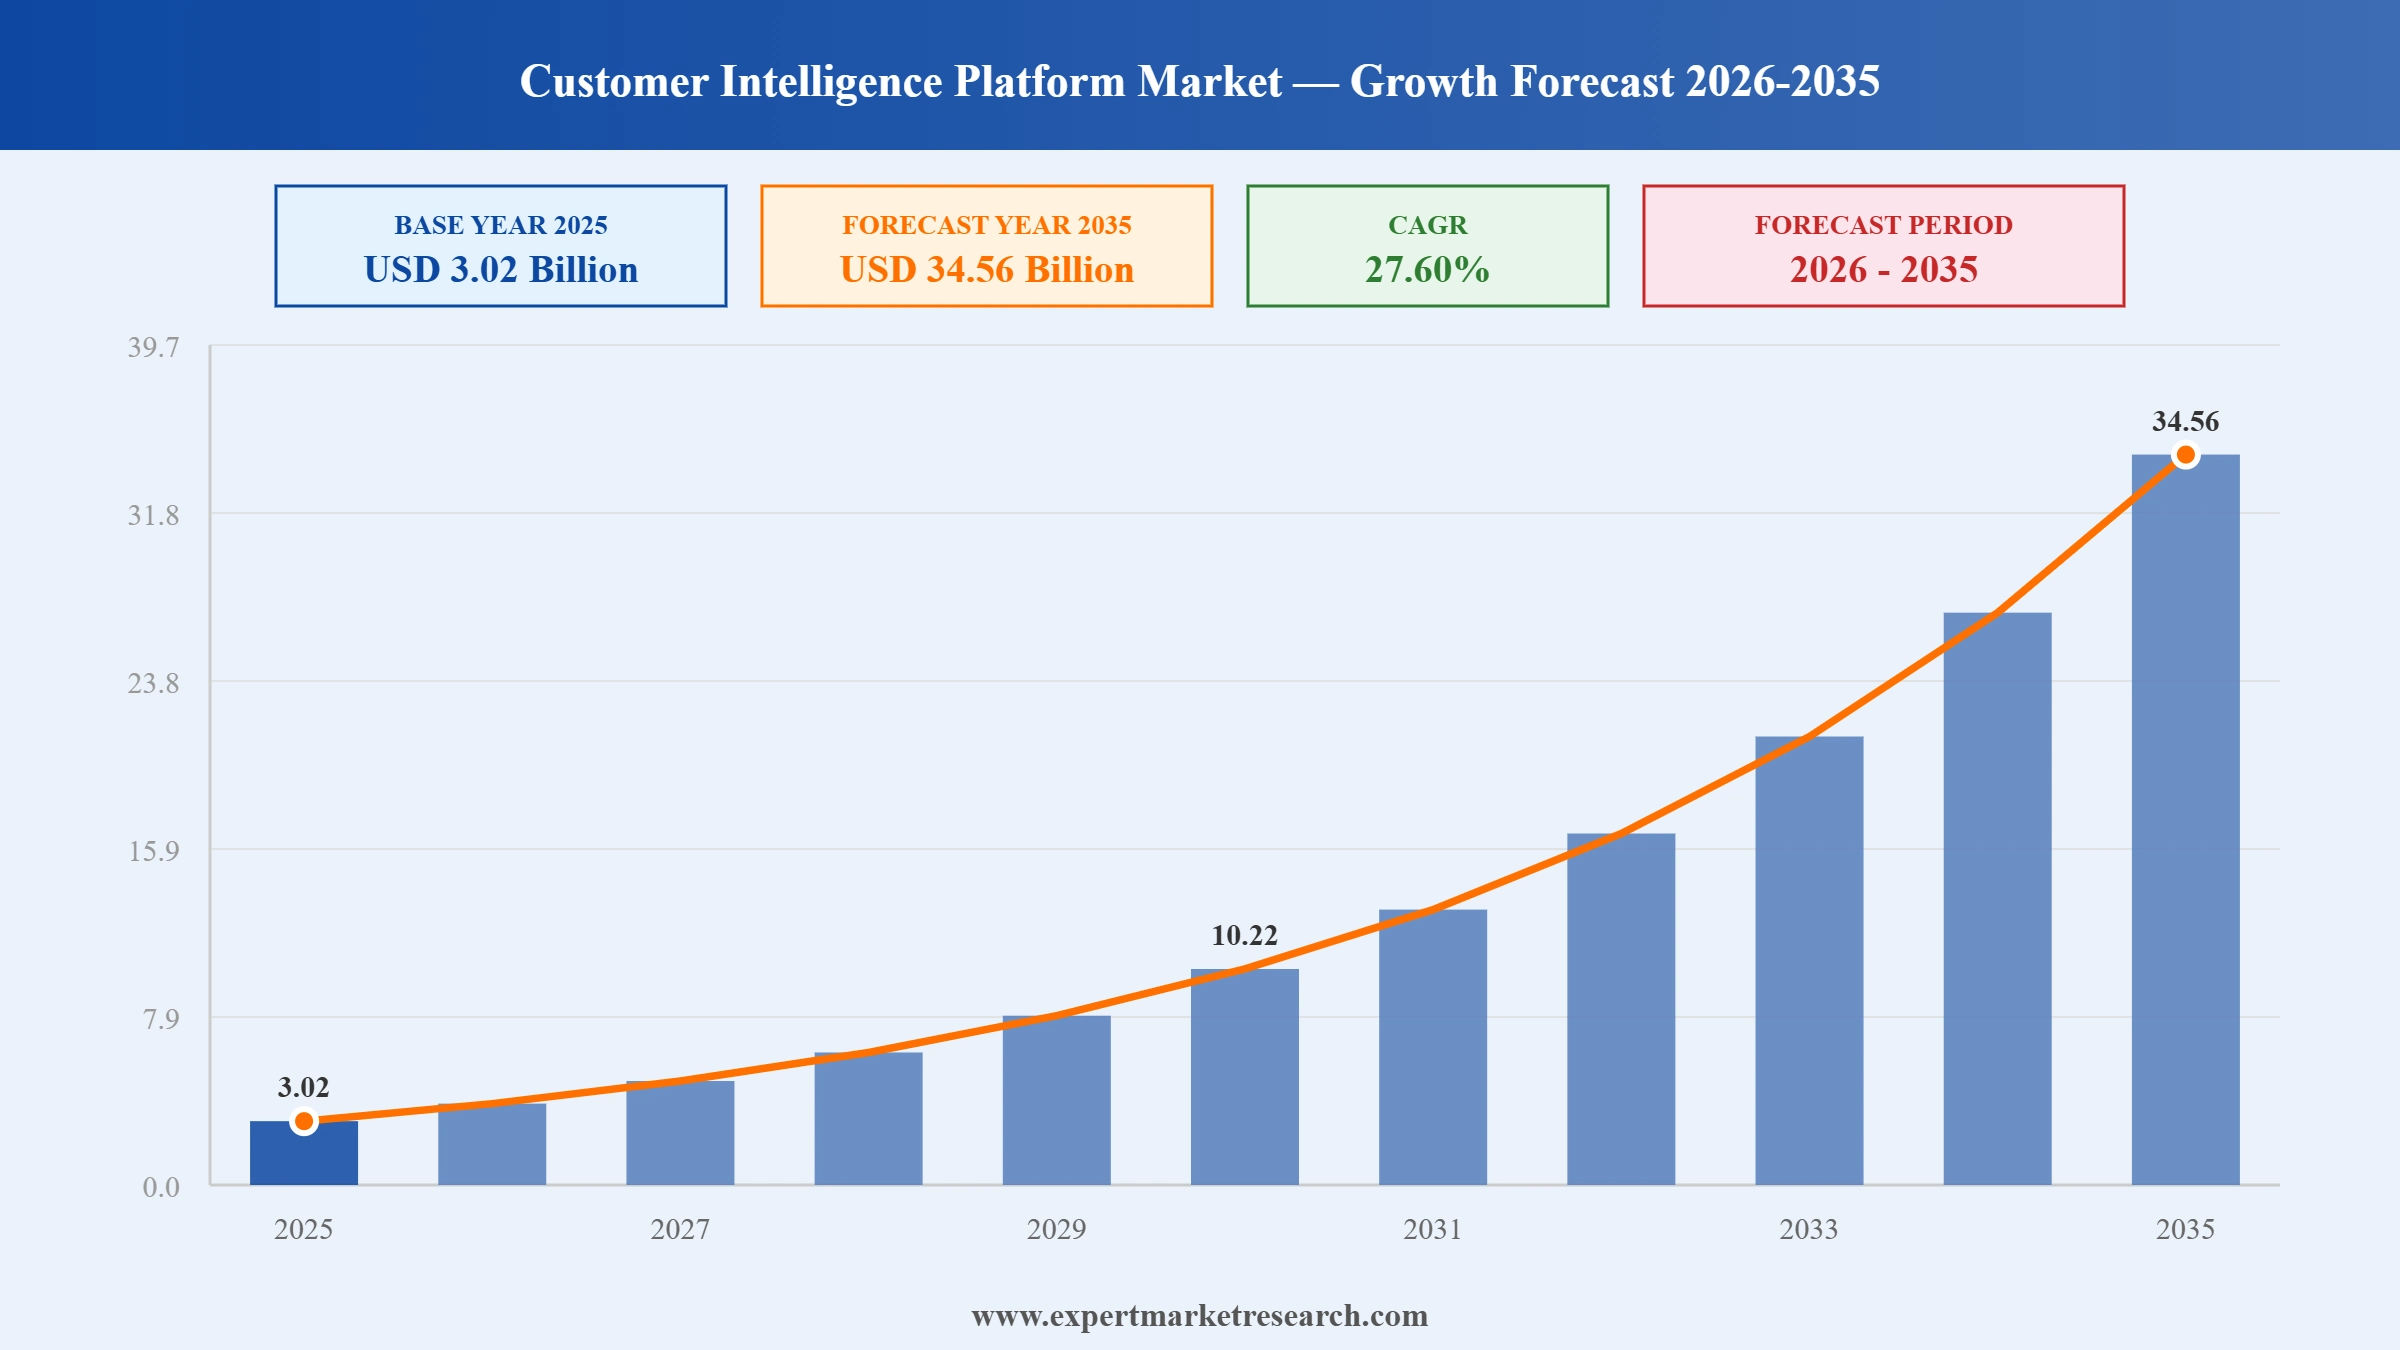
The global customer intelligence platform market attained a value of USD 3.02 Billion in 2025 and is projected to expand at a CAGR of 27.60% through 2035. The market is further expected to achieve USD 34.56 Billion by 2035. Rising demand for personalised customer experiences, growing adoption of AI-powered analytics, and the increasing shift toward data-driven marketing continue to support platform adoption across BFSI, retail, telecom, and travel and hospitality sectors.
Rising demand for personalised customer experiences continues to anchor steady demand across the customer intelligence platform market, as enterprises increasingly seek unified, real-time visibility into customer behaviour spanning web, mobile, social, and in-store touchpoints. Providers are also investing in agentic AI capabilities, reflecting the industry's ongoing pursuit of autonomous insight generation that reduces reliance on manual data analysis. In January 2026, Amperity launched its Customer Data Agent, an enterprise AI solution designed to help marketers turn raw customer insights into actionable outcomes.
The customer intelligence platform market is witnessing further developments as established providers embed agentic AI capabilities directly into core platform offerings. Adobe unveiled a new agentic AI coworker capability designed to synthesise data across its own and third-party applications while coordinating multiple specialised AI agents on behalf of enterprise customers. This shift toward agentic AI integration is concentrated among providers with sufficient platform scale to coordinate multiple AI agents simultaneously, while smaller specialists continue to compete on niche analytical capabilities.
In addition, established providers are increasingly forming strategic partnerships with frontier AI companies to extend platform capabilities beyond native development, reflecting the sector's recognition that keeping pace with rapidly advancing AI models increasingly requires external collaboration rather than solely in-house research. Such partnership activity is reshaping competitive positioning across the wider customer intelligence platform market as providers with proven AI ecosystem partnerships increasingly differentiate themselves from competitors relying solely on proprietary model development.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Salesforce and Anthropic announced Claudeforce, integrating Claude directly into Salesforce's Agentforce platform through MCP servers, APIs, and CLI tools, with additional prebuilt skills planned for later in the year. Companies can pursue partnerships with frontier AI developers to extend platform intelligence capabilities faster than proprietary model development alone would allow.
Salesforce released its Summer '26 platform update centred on the Agentic Enterprise, introducing multi-agent orchestration, Slack-first workflows, and real-time data activation designed to help human employees and AI agents work together across the enterprise. Companies can bundle multiple AI orchestration and workflow features into scheduled seasonal releases to maintain predictable upgrade cycles for enterprise customers.
Adobe announced general availability of CX Enterprise Coworker, an agentic AI offering that synthesises information from Adobe and third-party applications while coordinating AI agents across analytics, content, and customer journey orchestration. Companies can consolidate previously separate AI agent functions into a single coordinating offering to reduce workflow fragmentation for enterprise customers.
Adobe unveiled the rebrand of Experience Cloud as CX Enterprise at Adobe Summit 2026, organising the platform around three pillars spanning brand visibility, customer engagement, and content supply chain, underpinned by a new Adobe AI Platform. Companies can use major annual summit events to reposition established platforms around emerging AI-first strategic narratives rather than incremental feature updates.
Established providers continue to embed agentic AI capabilities directly into core platform offerings rather than positioning them as separate add-ons. In June 2026, Adobe launched an agentic AI offering synthesising information from its own and third-party applications while coordinating AI agents across analytics, content, and journey orchestration across the customer intelligence platform market. Such native AI integration reflects providers' recognition that customers increasingly expect autonomous insight generation built into core workflows rather than requiring separate analytical tools.
Providers continue to form strategic partnerships with frontier AI developers to extend platform intelligence capabilities beyond native development. In August 2026, Salesforce announced a partnership integrating Anthropic's Claude directly into its platform through APIs and developer tools, with additional capabilities planned for later release. Such partnerships reflect providers' recognition that matching the pace of frontier AI model development increasingly requires external collaboration rather than solely proprietary research investment.
Providers continue to reposition established customer experience platforms around AI-first strategic narratives at major annual industry events. In April 2026, Adobe unveiled a platform rebrand organised around three strategic pillars, underpinned by a new AI platform layer coordinating brand, engagement, and content functions. Such repositioning reflects providers' recognition that signalling a fundamental AI-first shift, rather than incremental feature additions, increasingly shapes enterprise customer renewal and expansion decisions.
Providers continue to release coordinated seasonal platform updates centred on multi-agent orchestration and workflow automation. In July 2026, Salesforce released a major platform update introducing multi-agent orchestration and real-time data activation designed to help human employees and AI agents work together across the enterprise. Such seasonal release cadences reflect providers' recognition that predictable, bundled upgrade cycles simplify enterprise IT planning compared with continuous incremental feature rollouts.
Diversified technology groups continue to apply cloud and AI research developed across their broader enterprise software portfolios to increasingly sophisticated customer intelligence platform development. Established multi-segment technology providers continue to develop customer intelligence capabilities drawing on broader enterprise resource planning, cloud infrastructure, and AI research spanning multiple business categories beyond customer intelligence alone. Such cross-portfolio research investment gives diversified technology groups a technical foundation that narrower customer-intelligence-only specialists must build through more limited, application-specific development. In April 2026, SAP embedded AI directly into its core customer-facing workflows across its Q1 2026 Customer Experience release, integrating intelligence into sales, service, and marketing processes rather than layering AI copilots on top.
This Expert Market Research Report titled "Customer Intelligence Platform Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Data Channel
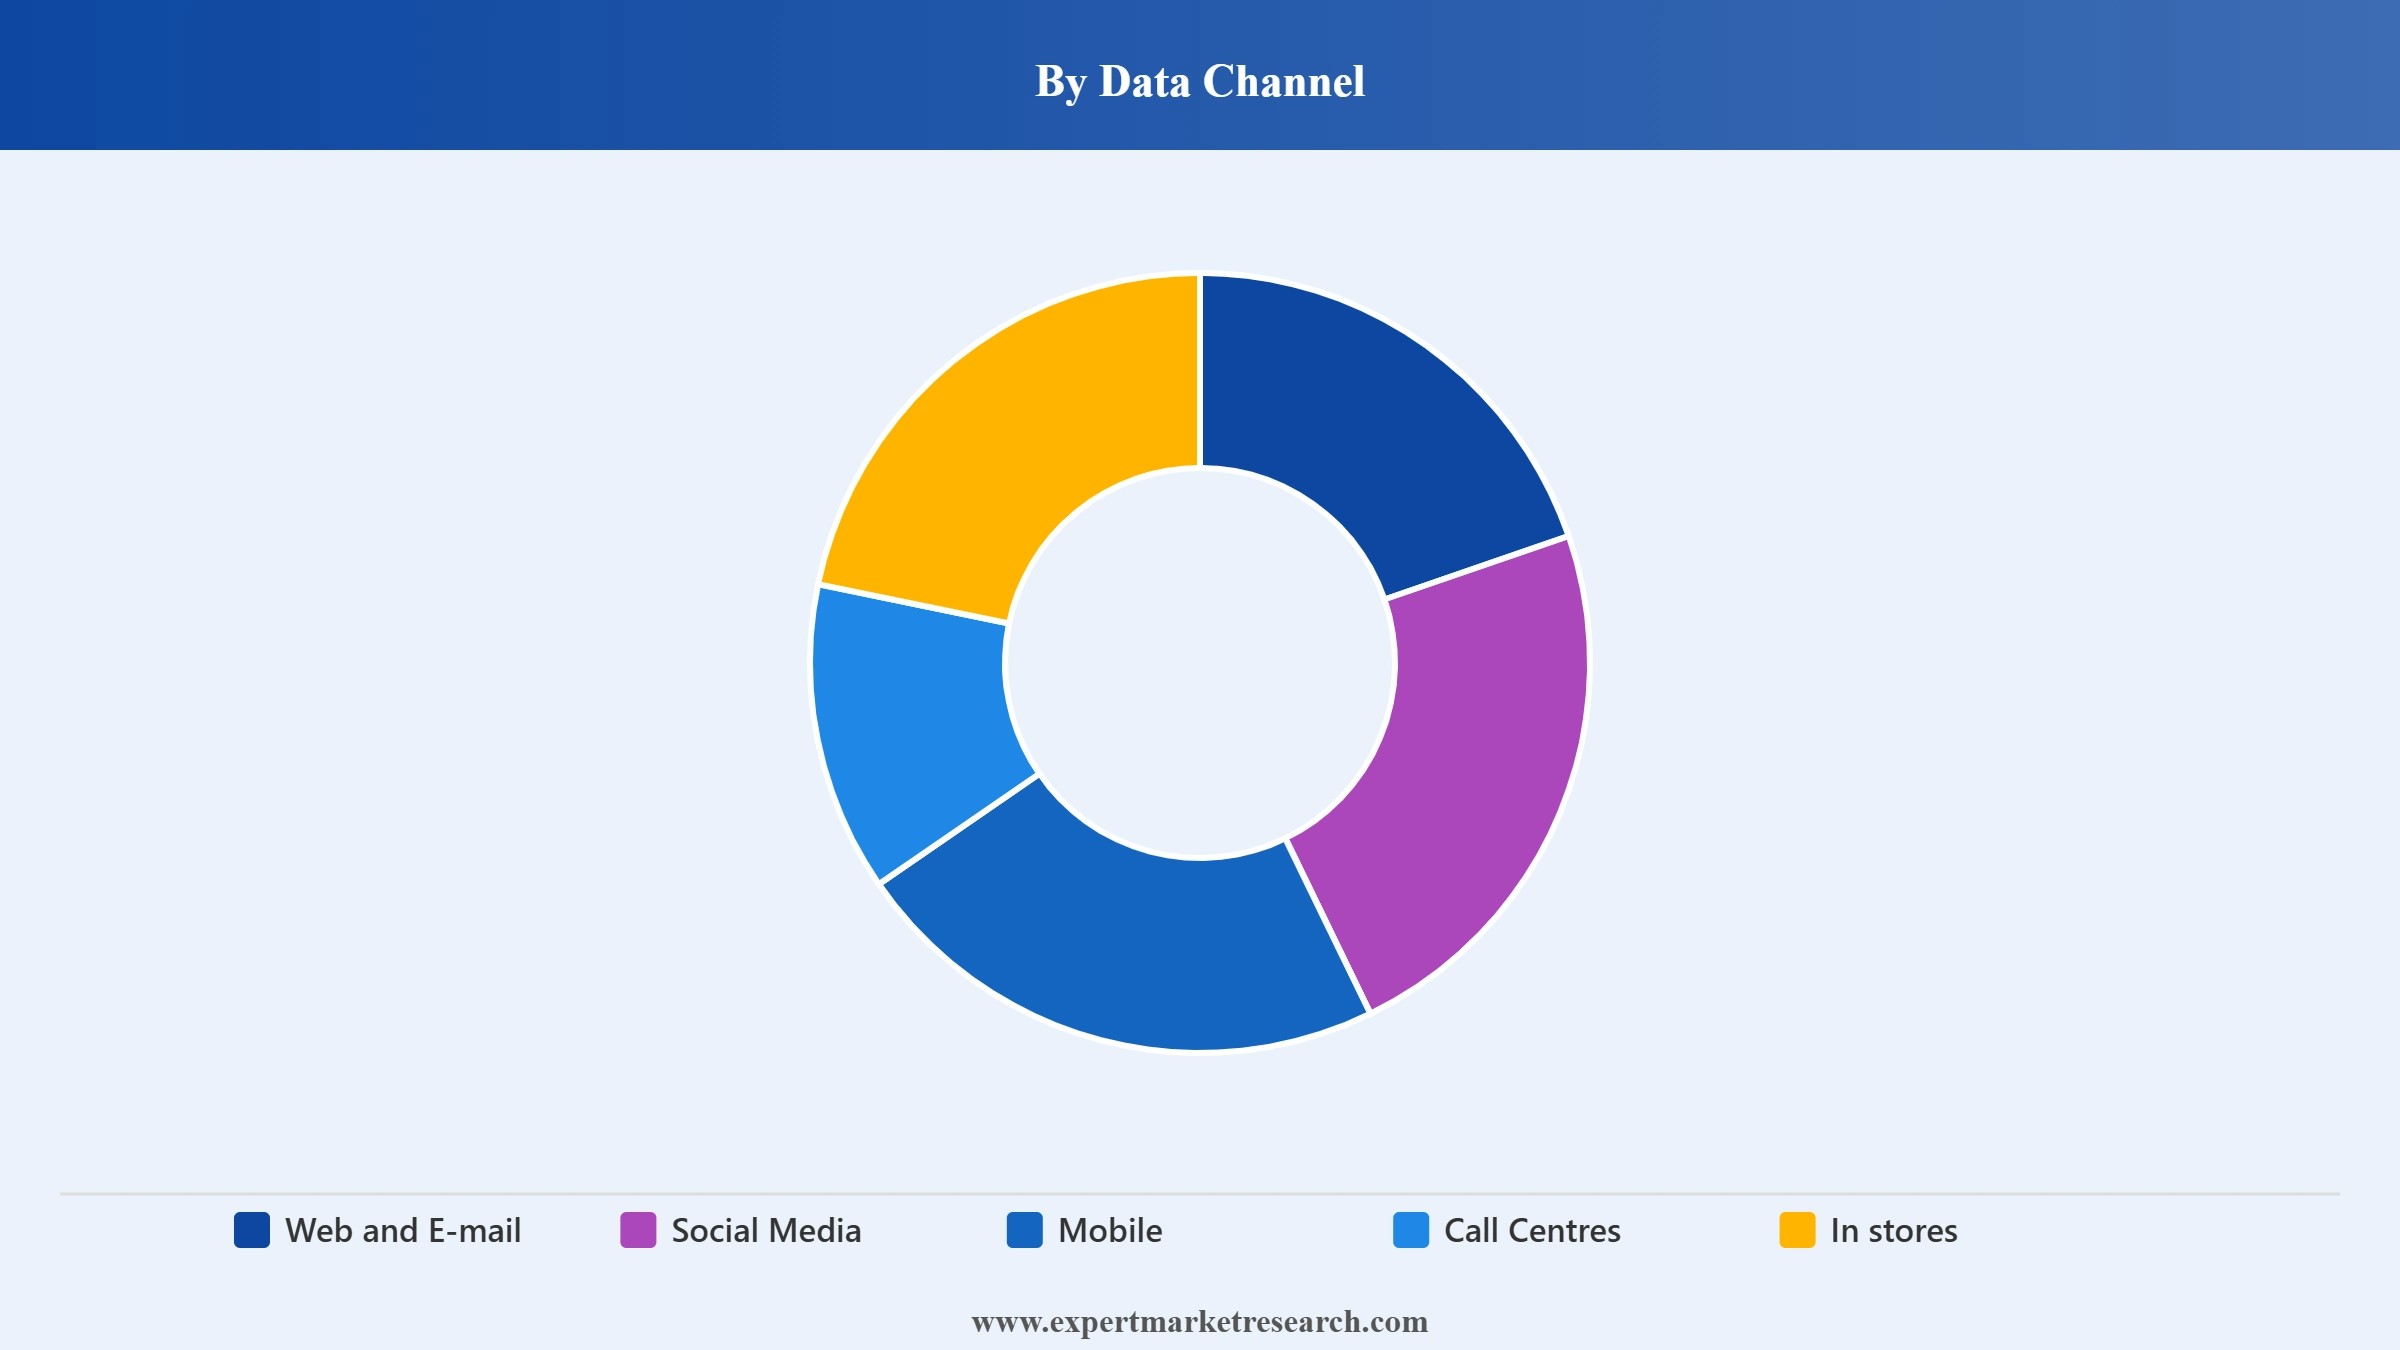
Key Insight: Web and E-mail accounts for the largest share of the customer intelligence platform market, reflecting its established role as the primary customer communication and behavioural tracking channel across enterprise marketing operations. Mobile is growing at the fastest pace as smartphone-first customer engagement continues to expand, illustrated by Adobe's June 2026 CX Enterprise Coworker launch spanning multi-channel AI coordination. Social Media serves as a critical channel for sentiment analysis and brand engagement tracking, capturing unstructured customer feedback that structured channels typically miss. Call Centres continue to generate substantial volumes of voice and transcript data, increasingly processed through speech analytics to surface customer intent and satisfaction signals in real time. In-stores data collection is gaining renewed attention as retailers integrate point-of-sale and foot-traffic signals with digital customer profiles to build a unified view across physical and online touchpoints, with other channels rounding out the remaining category.
Market Breakup by Vertical
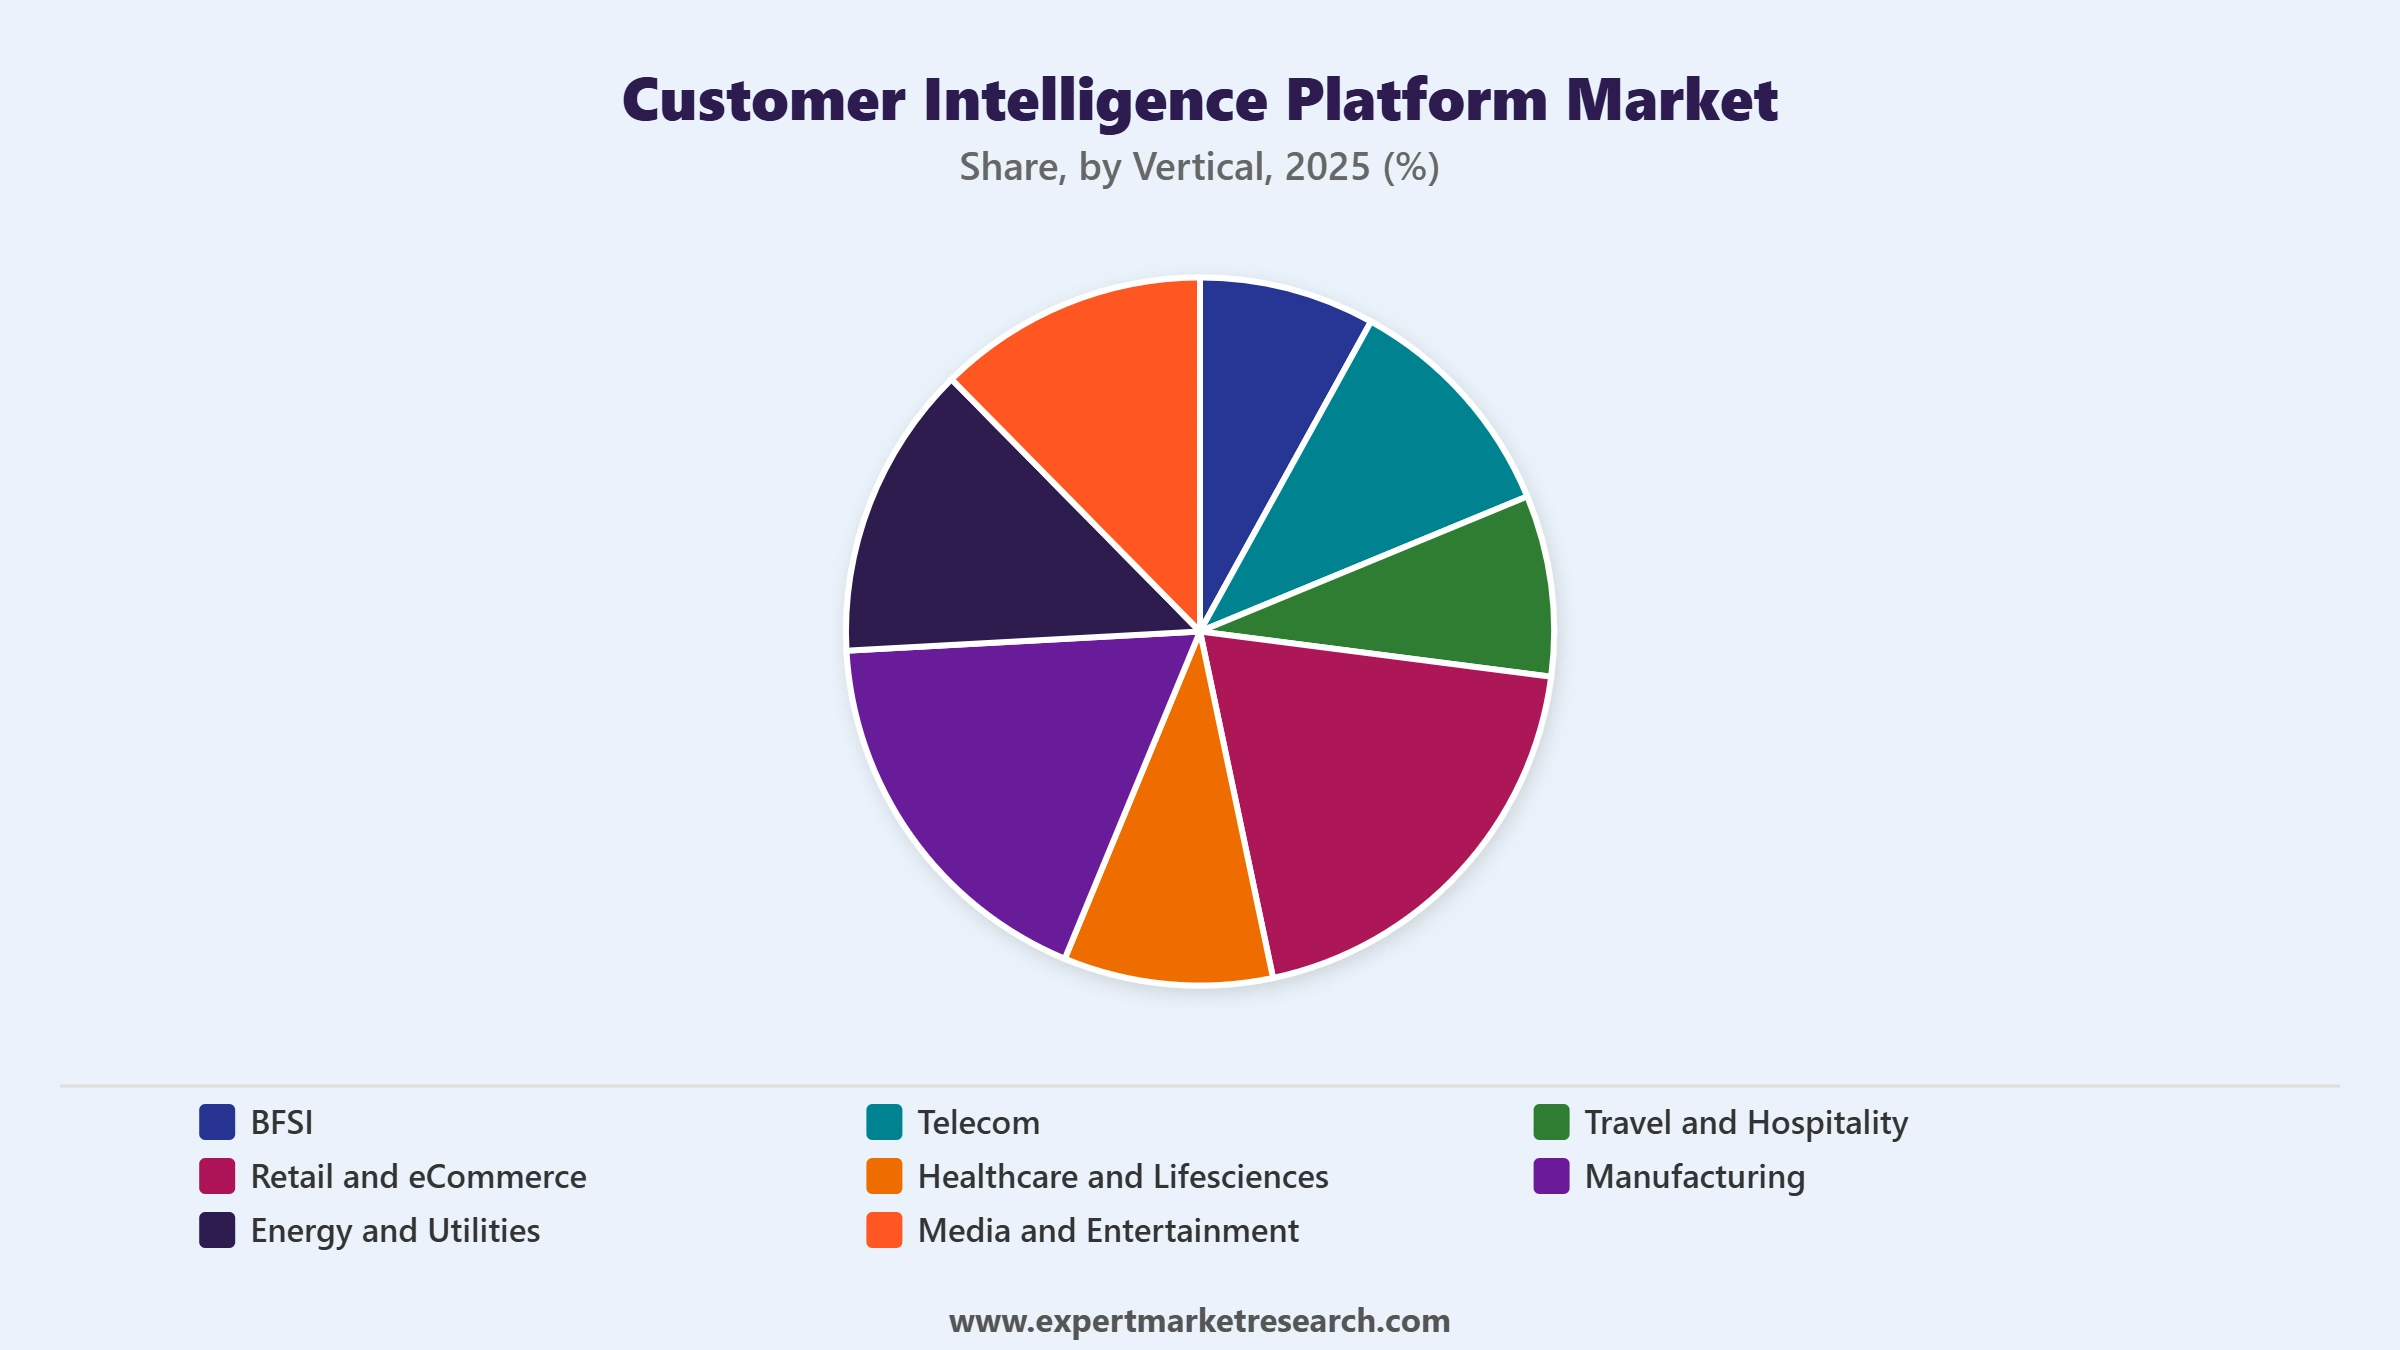
Key Insight: Retail and eCommerce accounts for the largest share of the customer intelligence platform market, reflecting the sector's intensive reliance on customer behavioural data to drive personalisation and conversion. In 2026, Accenture partnered with Databricks to help Albertsons, one of the largest US food and drug retailers, deploy an agentic pricing intelligence solution combining lookback analysis and forward-looking demand forecasting. BFSI continues to represent substantial demand given stringent customer risk profiling and fraud detection requirements across banking and insurance operations. Telecom providers rely on customer intelligence platforms to reduce churn and personalise service bundles across large subscriber bases. Travel and Hospitality operators use behavioural data to tailor itinerary and loyalty offers around shifting booking patterns. Healthcare and Lifesciences organisations increasingly apply customer intelligence to patient engagement and adherence programmes within strict data privacy constraints. Manufacturing companies are extending customer intelligence from traditional B2B account management into more granular, data-driven demand forecasting. Energy and Utilities providers use the technology to support usage-based billing and personalised conservation messaging. Media and Entertainment companies rely on it to power content recommendation engines and targeted advertising, with other verticals rounding out the remaining category.
Market Breakup by Deployment Type
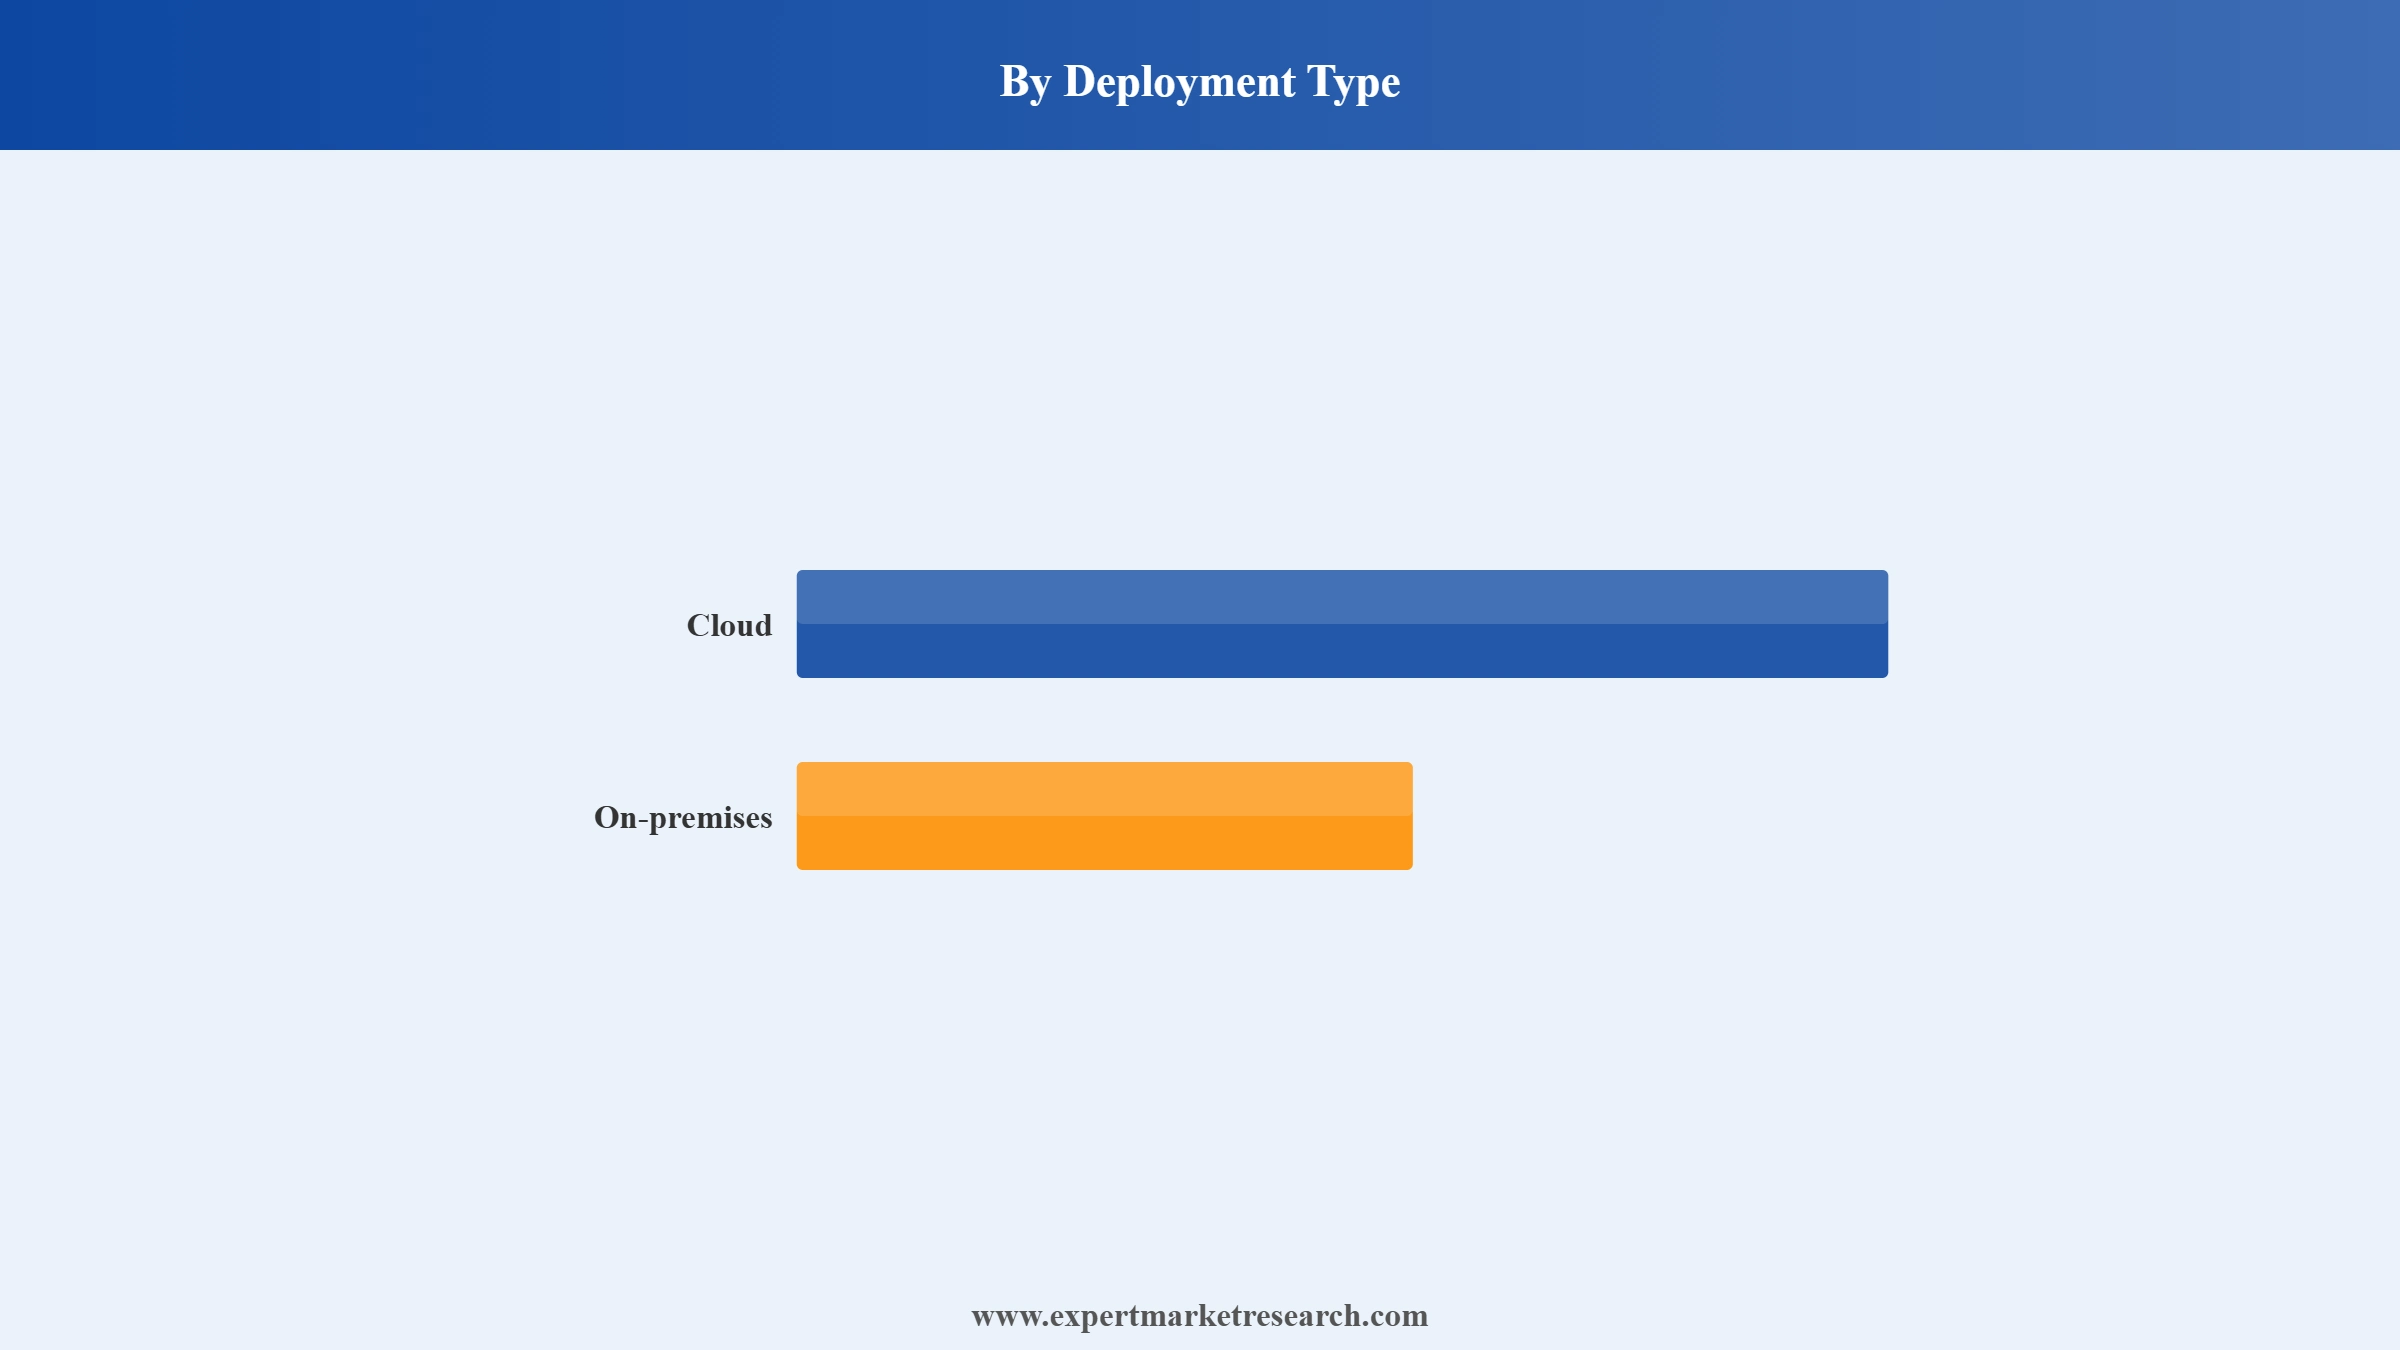
Key Insight: Cloud deployment accounts for the largest share of the customer intelligence platform market, reflecting enterprises' preference for scalable, subscription-based infrastructure that avoids substantial upfront capital investment. On-premises deployment continues to serve organisations with stringent data residency or regulatory requirements that necessitate direct infrastructure control. In June 2026, Oracle expanded its OCI Enterprise AI platform into the UAE Central region, giving customers additional regional flexibility for deploying generative AI workloads closer to their operations.
Market Breakup by Component
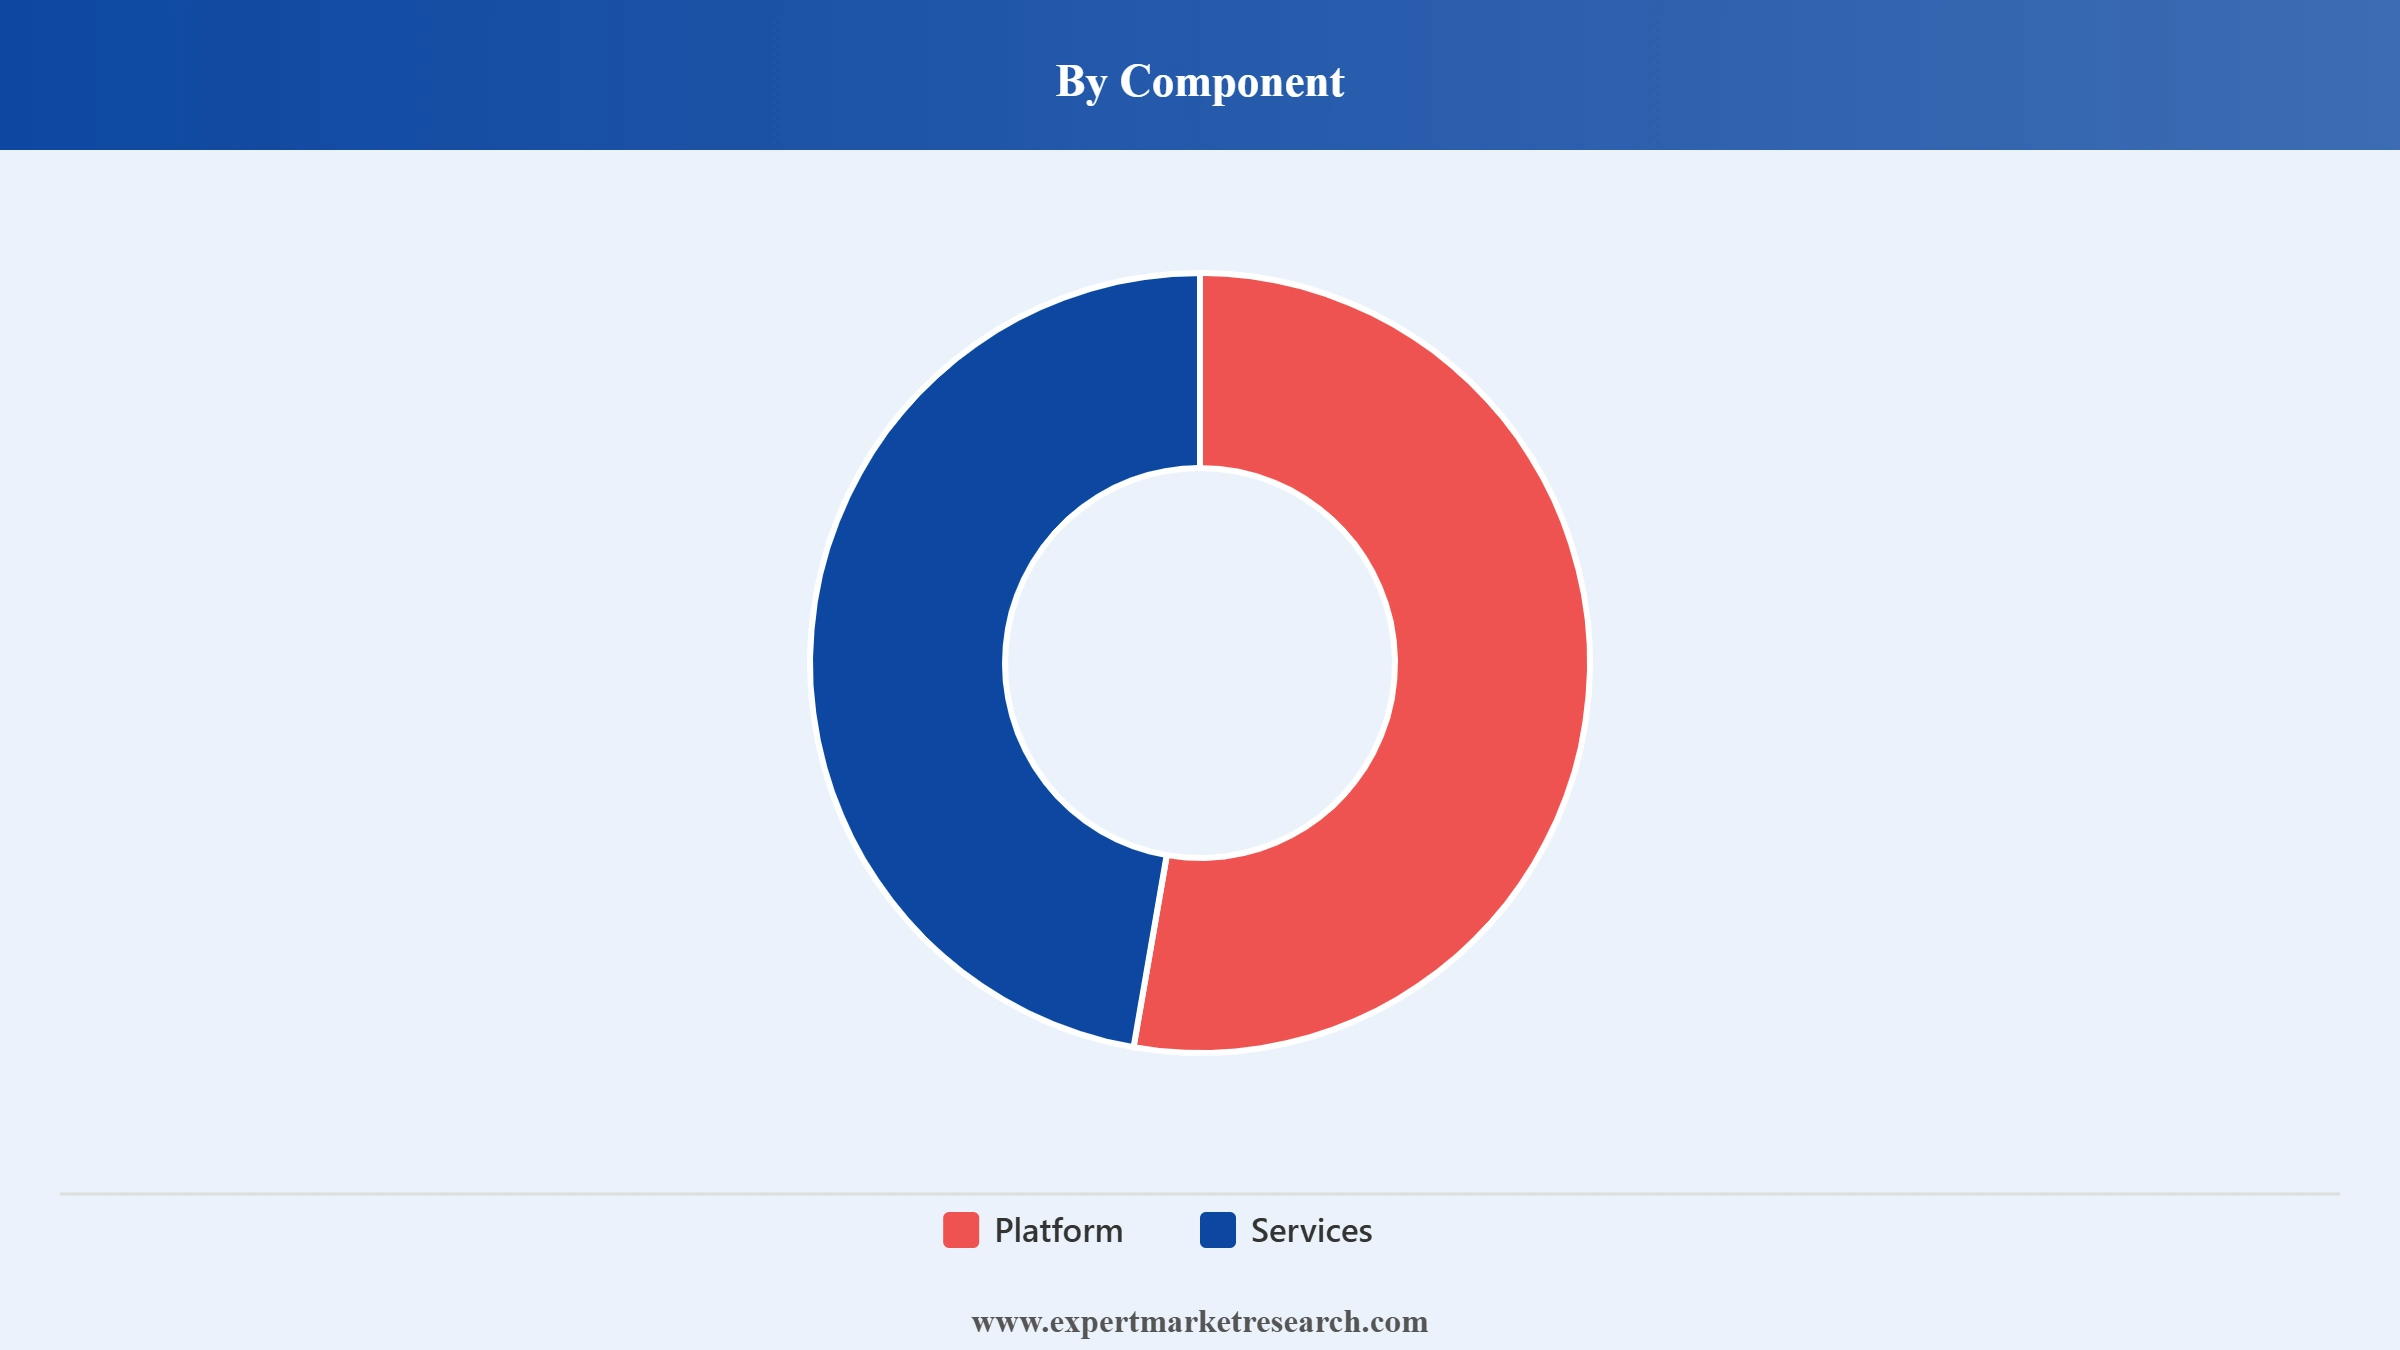
Key Insight: Platform accounts for the largest share of the customer intelligence platform market, reflecting sustained enterprise investment in core software licensing and functionality. Services are growing at a fast pace as providers increasingly bundle implementation, consulting, and ongoing optimisation support alongside core platform licensing. Oracle expanded the intelligence layer of its Analytics Cloud platform in its March 2026 update, introducing AI Data Agents that let organisations configure purpose-built assistants against specific datasets.
Market Breakup by Application
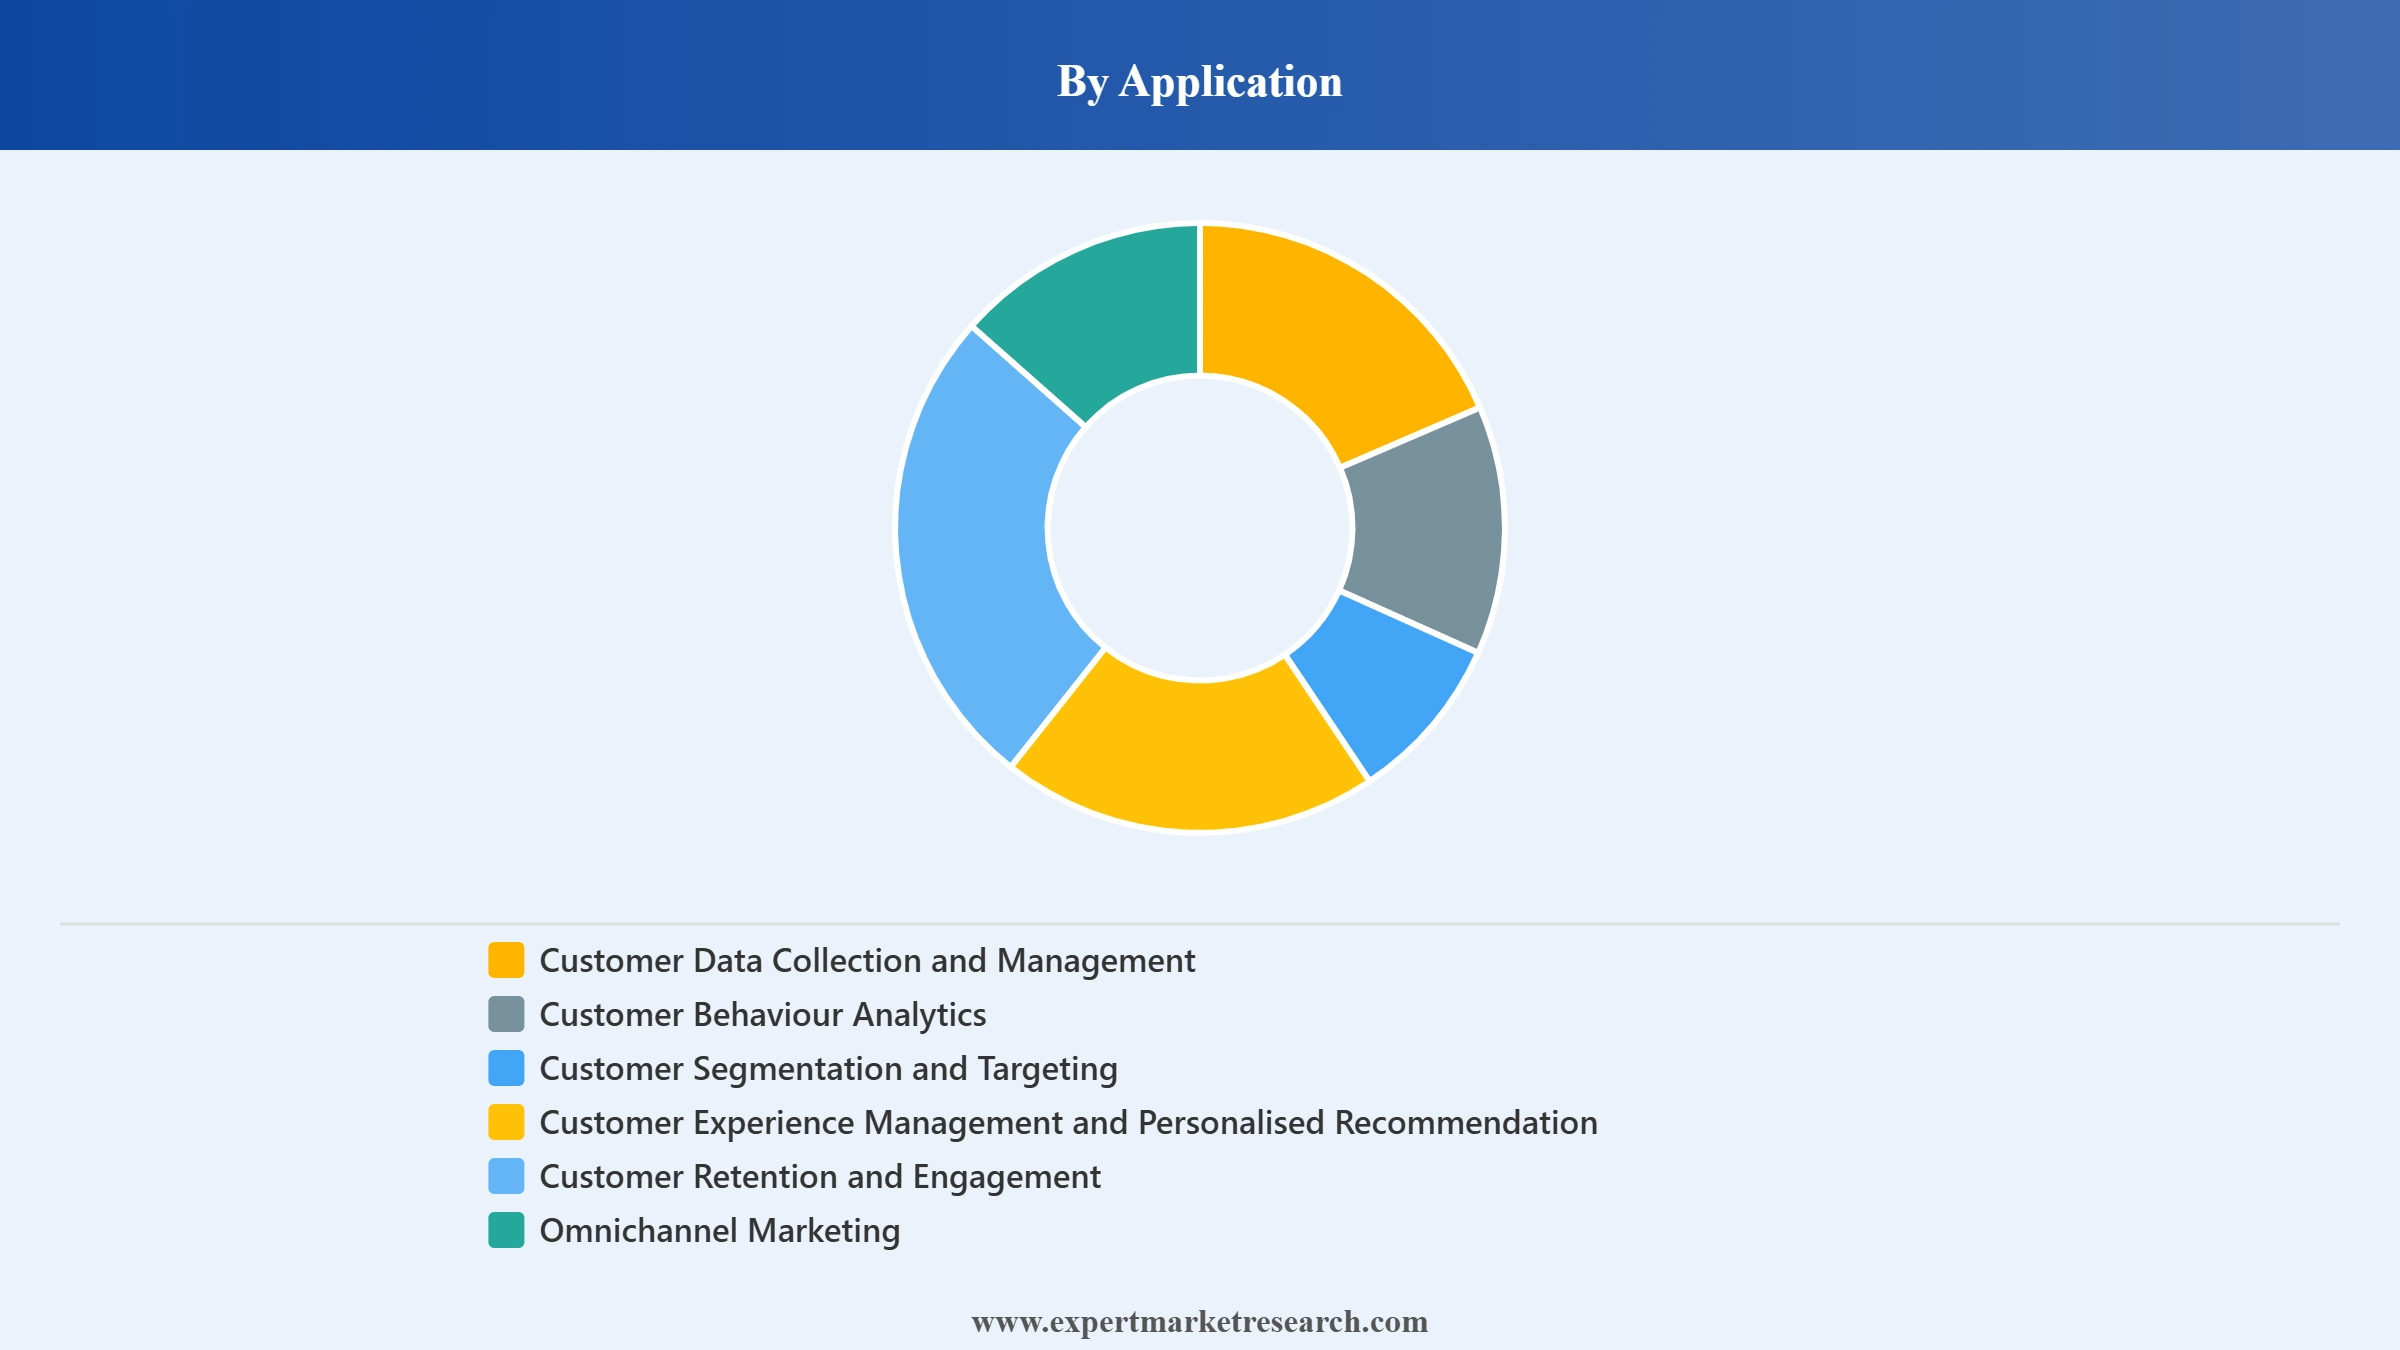
Key Insight: Customer Data Collection and Management accounts for the largest share of the customer intelligence platform market, reflecting its foundational role in aggregating data before downstream analytical applications can function. In December 2025, State Bank of India unified data across 76 business units and 491 million customers using IBM watsonx.data integration to power YONO 2.0, India's largest digital banking super-app. Customer Behaviour Analytics continues to represent substantial demand as enterprises analyse purchase history and browsing patterns to predict future customer actions. Customer Experience Management and Personalised Recommendation applications drive real-time content and product suggestions tailored to individual customer profiles. Customer Segmentation and Targeting tools group customers by shared characteristics to sharpen campaign relevance and reduce marketing waste. Customer Retention and Engagement applications identify at-risk customers early, triggering proactive outreach before churn occurs. Omnichannel Marketing applications coordinate messaging consistently across email, social, and in-store touchpoints, with other applications rounding out the remaining category.
Market Breakup by Region
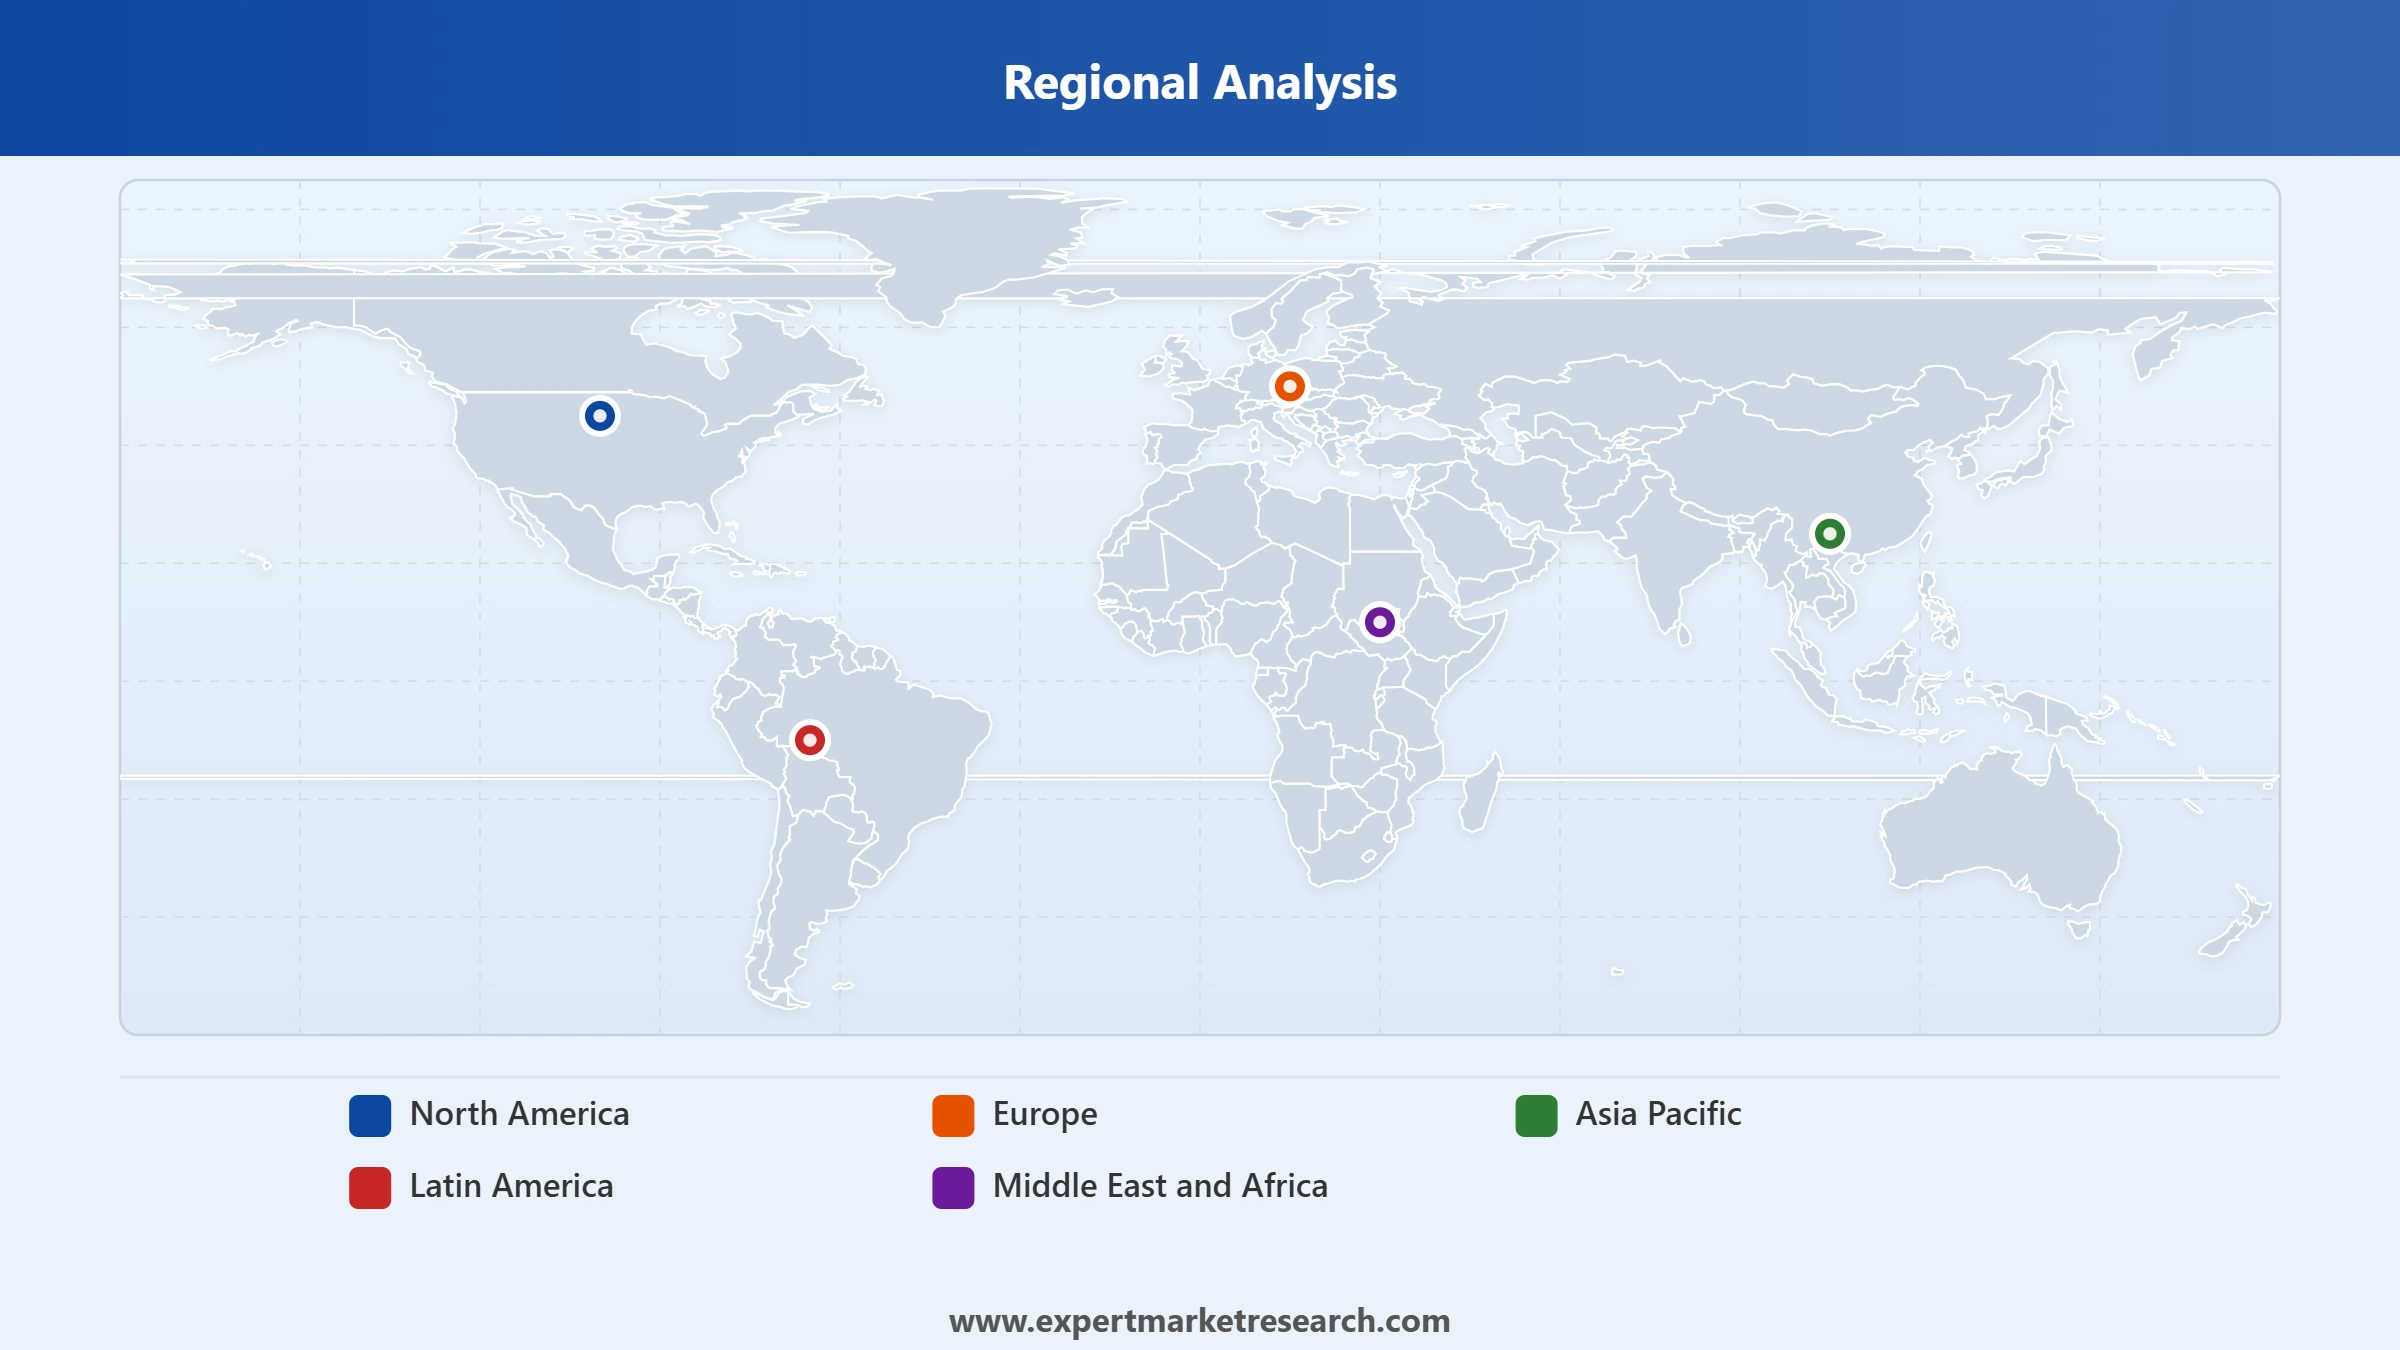
Key Insight: North America accounts for the largest share of the customer intelligence platform market, supported by its concentration of enterprise technology adopters and established customer experience management practices. Asia Pacific is emerging as a key growth market as expanding digital commerce and rising enterprise technology investment continue to drive platform adoption. Europe, Latin America, and the Middle East and Africa each continue to serve distinct regional customer engagement patterns.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By data channel, web and e-mail leads the market while mobile grows fastest given smartphone-first engagement
Web and E-mail continues to account for the largest share of the market, reflecting its established role as the primary customer communication and behavioural tracking channel across enterprise marketing operations. Established web and e-mail integrations continue to anchor steady demand as enterprises maintain proven tracking infrastructure across successive platform upgrade cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Mobile is growing at the fastest pace across the customer intelligence platform market as smartphone-first customer engagement continues to expand across consumer-facing industries, requiring platforms to capture and analyse in-app behavioural signals alongside traditional web data. Industry analysis published in May 2026 found that 71 percent of consumers now expect personalised experiences, with the majority abandoning generic mobile interactions in frustration.
By deployment type, cloud leads the market while cloud continues consolidating share given scalability advantages
Cloud deployment continues to account for the largest share of the market, reflecting enterprises' preference for scalable, subscription-based infrastructure that avoids substantial upfront capital investment. Established cloud deployment relationships continue to anchor steady demand as enterprises maintain proven vendor infrastructure across successive contract renewal cycles. Microsoft's Dynamics 365 Customer Insights 2026 release wave, running from April to September 2026, introduced expanded agentic AI capabilities for unifying customer profiles across the Dynamics 365 and Power Platform ecosystem.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
On-premises deployment continues to serve a narrowing share of the customer intelligence platform market as remaining demand concentrates among organisations with the most stringent data residency or regulatory requirements necessitating direct infrastructure control.
By vertical, retail and eCommerce leads the market while BFSI grows fastest given rising fraud and risk analytics demand
Retail and eCommerce continues to account for the largest share of the market, reflecting the sector’s intensive reliance on customer behavioural data to drive personalisation and conversion. Established retail data integrations continue to anchor steady demand as merchants maintain proven vendor relationships across successive campaign cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
BFSI is growing at the fastest pace across the customer intelligence platform market as financial institutions increasingly adopt customer intelligence tools for fraud detection, credit risk scoring, and personalised wealth management outreach at scale.
By component, platform leads the market while services grows fastest given rising demand for implementation support
Platform continues to account for the largest share of the market, reflecting sustained enterprise investment in core software licensing and functionality. Established platform licensing relationships continue to anchor steady demand as enterprises maintain proven vendor contracts across successive renewal cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Services is growing at the fastest pace across the customer intelligence platform market as enterprises increasingly rely on specialised implementation and optimisation consulting to configure increasingly sophisticated AI-driven platform capabilities.
By application, customer data collection and management leads the market while customer experience management grows fastest given rising personalisation demand
Customer Data Collection and Management continues to account for the largest share of the market, reflecting its foundational role in aggregating data before downstream analytical applications can function. Established data collection infrastructure continues to anchor steady demand across successive platform generations.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Customer Experience Management and Personalised Recommendation is growing at the fastest pace across the customer intelligence platform market as enterprises increasingly prioritise real-time, individualised customer engagement over batch-oriented segmentation and reporting alone.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America commands the largest share of the market through its concentration of enterprise technology adopters
North America holds the largest share of the customer intelligence platform market, supported by its concentration of enterprise technology adopters and established customer experience management practices. Regional providers continue to expand agentic AI capabilities to meet enterprise customers' rising expectations for autonomous, real-time customer insight generation.
Asia Pacific is emerging as a key growth market as expanding digital commerce and rising enterprise technology investment continue to drive platform adoption across the region. Continued major provider platform announcements throughout 2026 underscored sustained global investment in customer intelligence capabilities extending well beyond North America's traditional market concentration.
The global industry is moderately consolidated, with customer intelligence platform market companies ranging from diversified enterprise technology groups spanning multiple software categories to specialist customer intelligence providers competing across data channel, vertical, and deployment segments. Established players operate across the full customer intelligence value chain, from data collection and management through advanced behavioural analytics and complete customer experience orchestration for enterprise customers.
Competitive dynamics among customer intelligence platform players are increasingly shaped by the pace of agentic AI integration, the scale of frontier AI partnership activity, and the race to reposition established platforms around AI-first strategic narratives. Providers are investing in multi-agent orchestration, real-time data activation, and cross-platform AI partnerships to differentiate their offering and secure long-term enterprise customer relationships.
Founded in 1911 and headquartered in Armonk, New York, United States, IBM supplies customer intelligence and analytics capabilities as part of its broader portfolio spanning cloud computing, artificial intelligence, and enterprise consulting services. The company serves enterprise customers requiring integrated data management and AI-powered analytical capabilities. IBM's extensive enterprise consulting and hybrid cloud infrastructure differentiate its offering from narrower customer-intelligence-only specialists.
Founded in 1975 and headquartered in Redmond, Washington, United States, Microsoft supplies customer intelligence capabilities through its Dynamics 365 and broader cloud platform spanning enterprise software, productivity, and artificial intelligence services. The company serves enterprise customers requiring integrated customer relationship management and analytical capabilities. Microsoft's combined productivity suite and cloud infrastructure ecosystem differentiate its offering from narrower customer-intelligence-only competitors.
Founded in 1982 and headquartered in San Jose, California, United States, Adobe supplies customer intelligence and experience management capabilities through its CX Enterprise platform, formerly branded Experience Cloud. In June 2026, the company launched CX Enterprise Coworker, an agentic AI offering coordinating AI agents across analytics, content, and customer journey orchestration. Adobe's combined creative and customer experience software portfolio differentiates its offering from competitors focused solely on data analytics.
Founded in 1972 and headquartered in Walldorf, Germany, SAP supplies customer intelligence capabilities as part of its broader enterprise resource planning and business technology platform portfolio. The company serves large enterprise customers requiring integrated customer data alongside broader operational and financial systems. SAP's deep enterprise resource planning integration differentiates its offering from competitors providing customer intelligence as a standalone application.
Other key players in the customer intelligence platform market include Oracle Corporation, Accenture PLC, and SAS Institute Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our customer intelligence platform market trends 2026 report. Discover regional growth patterns, data channel and vertical trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of approximately USD 3.02 Billion in 2025.
The market is projected to grow at a CAGR of 27.60% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 34.56 Billion by 2035.
Embedding agentic AI capabilities directly into core platform offerings, forming strategic partnerships with frontier AI developers to extend platform intelligence, and repositioning established platforms around AI-first strategic narratives at major industry events.
The key trends fuelling the growth of the market include technological advancements in customer intelligence technologies and increasing requirement for effective data insights to optimise market growth.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The various deployment types include cloud and on-premises.
The key players in the market are IBM Corporation, Microsoft Corporation, Oracle Corporation, Accenture PLC, SAP SE, Adobe Inc., and SAS Institute Inc., among others.
Providers face rising data privacy and regulatory compliance requirements, integration complexity across fragmented enterprise data sources, and intensifying competition to embed increasingly sophisticated AI capabilities at pace with rapidly advancing frontier models.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Data Channel |
|
| Breakup by Vertical |
|
| Breakup by Deployment Type |
|
| Breakup by Component |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




