

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The Europe heart valve devices market was valued at USD 4.04 Billion in 2025, driven by the rising prevalence of cardiovascular diseases and increased funding for minimally invasive valve therapies across the region. The market is anticipated to grow at a CAGR of 9.50% during the forecast period of 2026-2035, with the values likely to reach USD 10.01 Billion by 2035. Technological advancements in transcatheter valve replacement and repair systems, are improving outcomes and expanding the eligible patient pool. Moreover, increased clinical adoption of TAVI (transcatheter aortic valve implantation), particularly for high-risk and inoperable patients are aiding growth in the market value.
Compound Annual Growth Rate
9.5%
Value in USD Billion
2026-2035
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Heart valve devices are medical implants designed to repair or replace damaged heart valves, ensuring proper blood flow direction and preventing complications such as valve stenosis or regurgitation. The market for heart valve devices in Europe is expanding due to the rising prevalence of cardiovascular diseases, an increasing aging population, advancements in transcatheter technologies, and growing preference for minimally invasive surgical procedures. It is anticipated to grow at a CAGR of 9.50% during the forecast period of 2026-2035.
Rising Cardiovascular Disease Burden to Drive the Market Expansion
The increasing prevalence of cardiovascular disease (CVD) remains a key growth driver in the heart valve devices market in Europe. As reported by the World Heart Federation, CVD is the leading cause of death in the European Union, impacting over 60 million people and resulting in more than 1.7 million deaths annually. This rising prevalence continues to propel demand for advanced heart valve interventions, supporting sustained market growth across the region.
HighLife announced that its Clarity Valve received CE Mark approval as the next-generation valve for the HighLife transcatheter mitral valve replacement system. The approval builds on the initial CE Mark received by the HighLife TMVR system in January 2026 and expands the company's European transcatheter mitral replacement platform. The development provides another device option for patients with symptomatic moderate-to-severe or severe mitral regurgitation who are unsuitable for surgery or transcatheter for edge-to-edge repair. Greater availability of dedicated TMVR technologies can expand minimally invasive treatment options and support growth of Europe's mitral valve device segment.
Boston Scientific announced a $1.5 billion investment in MiRus, acquiring a 34% equity stake and securing an option to purchase MiRus's heart-valve business. The transaction marks Boston Scientific's renewed strategic interest in the transcatheter aortic valve replacement segment after exiting the balloon-expandable TAVR market in 2025. Strategic investment by a major cardiovascular-device company can accelerate development and commercialization of innovative heart-valve technologies while increasing competitive intensity. For Europe, such investment can support the introduction and wider availability of advanced structural-heart devices as manufacturers seek to address the expanding TAVR and broader valve-treatment opportunity, thus bolstering the Europe heart valve devices demand.
P&F announced that its TricValve Bicaval Valve System received CE Mark certification under the EU Medical Device Regulation 2017/745. TricValve is designed as a minimally invasive treatment for patients with severe tricuspid regurgitation and right-heart failure who may have limited conventional treatment options. Obtaining MDR certification enables continued commercial access under the current European regulatory framework and reinforces the transition of structural-heart technologies toward more stringent regulatory requirements. Continued certification of transcatheter valve systems can preserve product availability while expanding minimally invasive options for patients with complex tricuspid disease.
HighLife announced that its Transcatheter Mitral Valve Replacement System received CE Mark approval for adults with symptomatic moderate-to-severe or severe mitral regurgitation who are unsuitable for surgical repair or replacement and transcatheter edge-to-edge repair. The system provides a transfemoral mitral valve replacement option and can accommodate native mitral annulus sizes ranging from 30 to 53 mm. HighLife stated that initial commercial availability would begin across Europe. The approval expands Europe's commercially available TMVR options and can stimulate adoption of minimally invasive mitral valve replacement among patients with limited treatment alternatives.
The market of heart valve devices in Europe is moving towards minimally invasive transcatheter technologies, especially TAVI/TAVR procedure for treating aortic stenosis as well as transcatheter technologies in case of mitral and tricuspid diseases. As a result of expanding indications, improved device designs, and increasing number of clinical data, the doctors can treat patients that cannot benefit from standard surgical operation. The guidelines released by ESC/EACTS in 2025 also encourage using transcatheter techniques taking into account the patient’s characteristics and anatomy. This shift is encouraging manufacturers to expand transcatheter portfolios and develop next-generation replacement and repair systems, creating opportunities across aortic, mitral and tricuspid valve device segments.
TAVI continues to play an important role in structural heart intervention, however, there is a huge market opportunity that exists in relation to treating mitral and tricuspid valve defects. There are new transcatheter valve replacement therapies for the mitral and tricuspid valves which can be used to treat patients not fit for surgery or traditional repair methods. The SAPIEN M3 from Edwards was granted CE mark approval in April 2025 for the transfemoral transcatheter mitral valve replacement procedure, whereas HighLife got European CE Mark approval for their TMVR in January 2026. These developments are broadening the addressable patient population and supporting diversification of Europe's heart valve device market beyond aortic interventions.
The increasing number of patients living with previously implanted bioprosthetic and transcatheter valves is creating demand for repeat and valve-in-valve interventions. Rather than undergoing another open-heart operation, selected patients can potentially receive a new transcatheter valve within a failing prosthesis. Medtronic received CE Mark in May 2025 for an expanded redo-TAVI indication covering its Evolut PRO+ and FX systems, allowing a new Evolut valve to be implanted inside a failed previously implanted TAV. Such innovations can extend treatment options for patients with structural valve deterioration while creating recurring demand for transcatheter heart valve devices as the installed patient base grows, thereby pushing the growth of the Europe heart valve devices marke+t.
European regulation is increasingly influencing the development and commercialization of Class III heart valve devices. Companies will have to show clinical data as well as adherence to the European Medical Device Regulation, making the company invest in research, post-market surveillance, and product improvement. For example, P&F’s February 2026 certification by the EU MDR of its TricValve Bicaval Valve System is indicative of how older products are now being incorporated into the new system of regulation. Meanwhile, new products are gaining CE Mark certification in terms of their mitral and aortic valve products. Regulatory compliance is therefore becoming both a market-entry requirement and an important competitive differentiator.
Competition among major cardiovascular device companies and emerging structural-heart specialists is accelerating investment in next-generation valve technologies. Companies are working on designing smaller delivery systems, better sealing mechanisms, wider anatomical coverage, and transcatheter treatment options for underrepresented patient populations. In September 2026, Medtronic made an investment of up to $80 million in Pi-Cardia, which included an option to buy the company out, while Boston Scientific invested $1.5 billion in MiRus in May 2026 and got an option to purchase the heart valve business of the latter. Such investments can accelerate innovation and increase competitive activity across the European structural-heart market.
The market report offers a detailed analysis of the market based on the following segments:
Market Breakup by Valve Type
Market Breakup by Product Type
Market Breakup by Procedure
Market Breakup by End User
Market Breakup by Region
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Biological Valves are Expected to Lead the Valve Type Segment
Based on valve types, the market is divided into biological (tissue) valves and mechanical valves. Biological valves will likely to dominate the segment due to their enhanced safety profile, reduced need for lifelong anticoagulation, and growing adoption among elderly patients. Together, these factors are driving the increasing preference for tissue-based valves across surgical and transcatheter procedures.
Segmentation by Product Type to Witness Growth in the Market
Based on the product type, the market is segmented into replacement devices (mechanical valve, bioprosthetic valve, transcatheter aortic valve replacement) and repair devices (surgical valve, transcatheter mitral valve replacement, balloon valvuloplasty devices). Replacement devices are expected to witness substantial growth, primarily due to the rapid adoption of TAVR and rising prevalence of aortic valve disorders.
Minimally Invasive Surgeries to Dominate Procedure Segment
The market share by procedure includes open surgeries and minimally invasive surgeries (MIS). Minimally invasive surgery is projected to lead the segment, supported by technological advancements, faster recovery times, reduced complications, and increasing patient demand. Together, these advantages contribute to its expanding adoption in both replacement and repair interventions.
Hospitals to Lead the End User Segmentation in the Europe Heart Valve Devices Market
Hospitals, ambulatory surgical centers (ASCs), and others together make up the end-user segmentation. Hospitals are expected to hold the largest share due to their comprehensive care capabilities, access to advanced technologies, and availability of specialized cardiac teams. Together, these factors ensure hospitals remain the primary centers for heart valve procedures.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
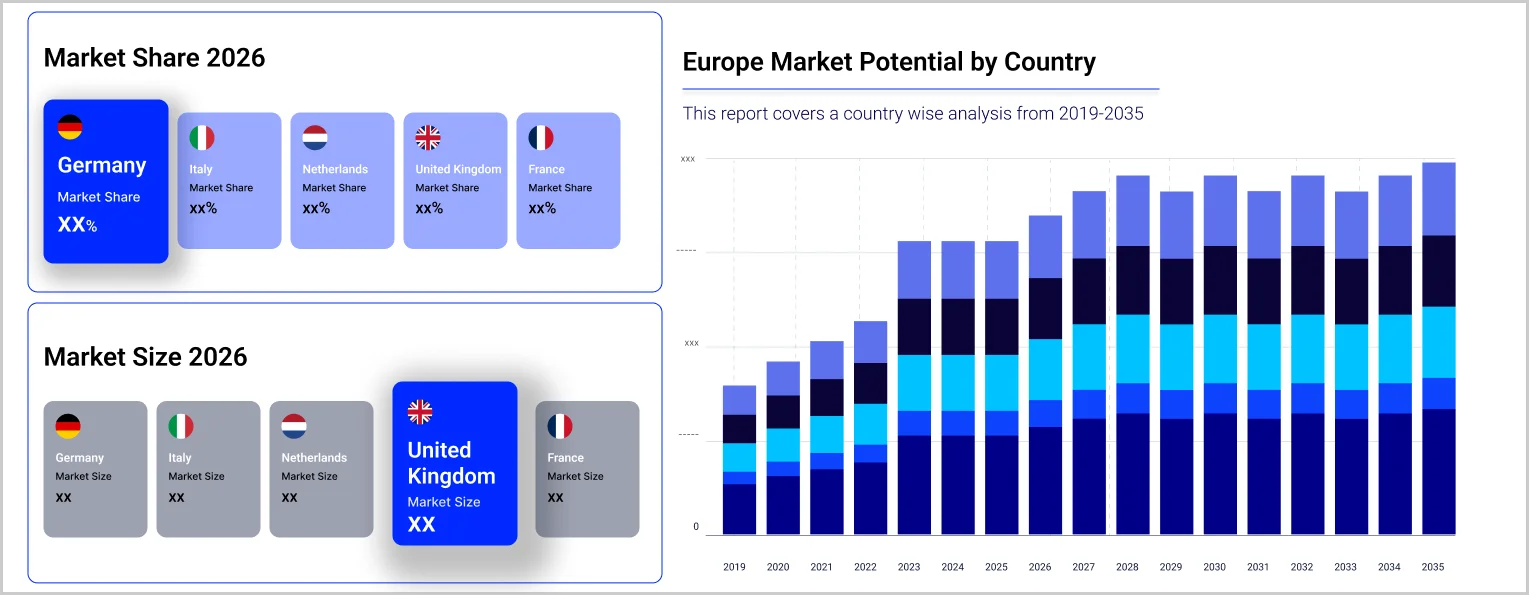
The market is divided into regions such as the United Kingdom, Germany, France, Italy, and others. The United Kingdom is likely to dominate the market, driven by advanced healthcare infrastructure, rising cardiovascular disease incidence, and increasing adoption of transcatheter procedures. Germany holds a significant share due to its strong medical technology sector, while the France benefit from government support and growing demand for minimally invasive treatments.
The key features of the market report comprise patent analysis, grants analysis, funding and investment analysis, and strategic initiatives by the leading players. The major companies in the market are as follows:
Medtronic plc, established in 1949 and headquartered in the United States, is a global leader in healthcare technology with a strong presence in the European heart valve devices market. In October 2024, the company launched the Avalus Ultra Bioprosthesis valve in Western Europe. This next-generation surgical aortic valve, designed for enhanced durability and ease of implantation, builds on a decade of clinical success with the Avalus valve. Medtronic’s expanding cardiac surgery portfolio highlights its commitment to advancing cardiovascular care across the region.
Headquartered in Irvine, California, and established in 1958, Edwards Lifesciences Corporation is a leading innovator in structural heart therapies. In May 2024, the company expanded its presence in the Europe heart valve devices market by launching the Sapien 3 Ultra Resilia valve, a transcatheter aortic valve featuring Resilia tissue technology that enhances durability and reduces calcification. With CE Mark approval, this advanced device addresses native aortic stenosis and failed bioprosthetic valves across all surgical risk levels. Edwards' strategic focus on innovation and patient-centric care reinforces its strong market position and supports growing demand for minimally invasive valve replacement options in Europe.
Abbott is a leader in innovative healthcare solutions, including cardiovascular devices. It is headquartered in Illinois, United States and was established in 1888. Abbott's TriClip transcatheter edge-to-edge repair (TEER) system, approved by the FDA in April 2024, is designed for treating tricuspid regurgitation. This minimally invasive device has shown positive results in improving patients' quality of life and reducing symptoms. Abbott's commitment to advancing structural heart therapies, including the MitraClip and Navitor systems, reinforces its strong position in the European heart valve devices market.
Founded in 1979 and headquartered in Marlborough, Massachusetts, Boston Scientific Corporation is a leading global medical technology company. In August 2024, it received CE mark approval for its Acurate Prime aortic valve system, an advanced transcatheter aortic valve replacement (TAVR) device designed for patients with severe aortic stenosis. This next-generation valve expands treatment options for larger anatomies and enhances procedural accuracy through a redesigned deployment system.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Other key players in the market include Corcym Group, B. Braun SE, Getinge AB, Shockwave Medical Inc. (Johnson & Johnson, Services Inc.), JenaValve Technology, Inc., and Xeltis.


Upto 15% Off
USD
$4299 $3869
$2699 $2429
$5799 $4949
$6999 $5949


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Valve Type |
|
| Breakup by Product Type |
|
| Breakup by Procedure |
|
| Breakup by End User |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Supplier Landscape |
|
| Companies Covered |
|
Single User License
One User
USD 4,299
USD 3,869
tax inclusive*
Datasheet
One User
USD 2,699
USD 2,429
tax inclusive*
Five User License
Five User
USD 5,799
USD 4,949
tax inclusive*
Corporate License
Unlimited Users
USD 6,999
USD 5,949
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




