

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
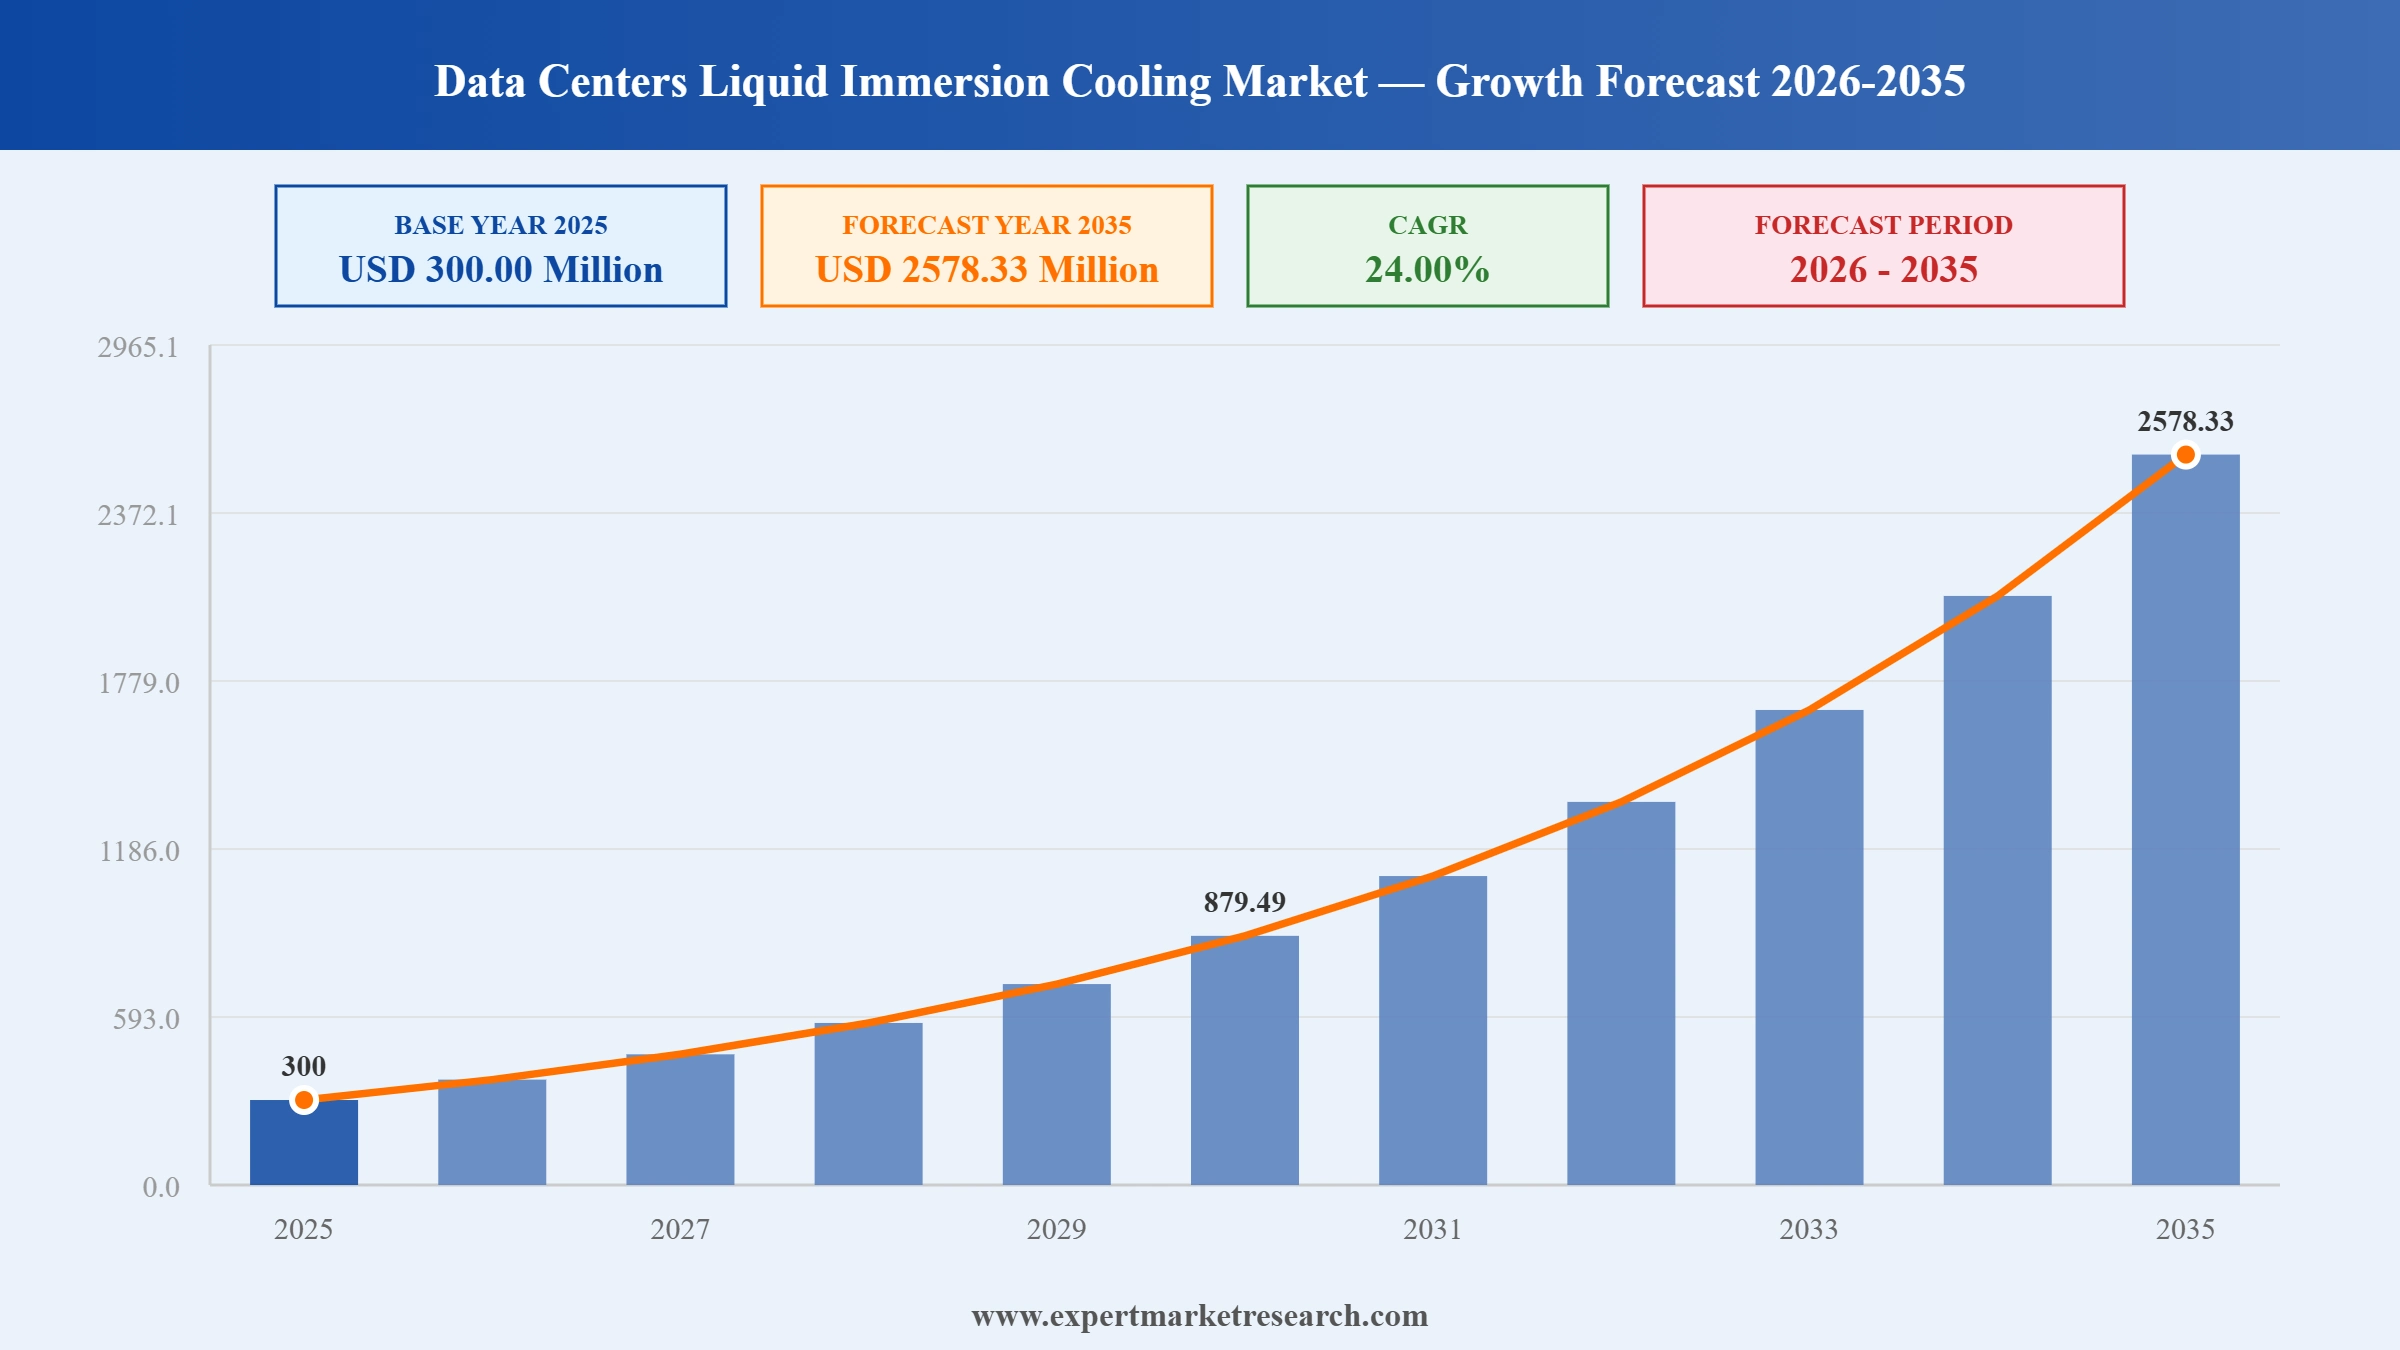
The data centers liquid immersion cooling market was valued at USD 300.00 Million in 2025. The market is expected to grow at a CAGR of 24.00% during the forecast period of 2026-2035 to reach a value of USD 2578.33 Million by 2035. Surging AI training and inference workloads, rising GPU rack power densities, and growing sustainability mandates are collectively driving data center operators toward immersion cooling as air based systems reach their thermal limits.
The current data centers liquid immersion cooling market dynamics reflect an accelerating shift from pilot deployments toward mainstream adoption, as established thermal management companies acquire specialist immersion cooling technology to build complete end to end portfolios spanning chillers, coolant distribution, and immersion tanks. This consolidation trend reflects growing recognition that AI driven power densities are outpacing what standalone immersion vendors can support without the manufacturing scale and global distribution networks that larger industrial partners provide. In February 2026, Trane Technologies announced a definitive agreement to acquire LiquidStack, a Texas based liquid cooling technology provider, building on its 2023 minority investment and completing the transaction in March 2026 to add high density liquid, direct-to-chip, and immersion cooling capability to its broader thermal management portfolio.
The overall data centers liquid immersion cooling industry through 2025 continues to be shaped by surging electricity and water consumption concerns tied to AI infrastructure, with data centers projected to account for a rapidly rising share of global electricity demand as GPU cluster power densities exceed 100 kilowatts per rack. Immersion cooling vendors are increasingly securing strategic investment from established industrial and electronics conglomerates seeking exposure to AI infrastructure growth without building thermal management capability from scratch. Continued fundraising activity, product line expansion into edge and modular formats, and deepening partnerships with server original equipment manufacturers continue to reshape the competitive landscape as the technology moves from niche deployment toward default infrastructure for the highest density AI training clusters.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
|
Data Centers Liquid Immersion Cooling Market Report Summary |
Description |
Value |
|
Base Year |
USD Million |
2025 |
|
Historical Period |
USD Million |
2019-2025 |
|
Forecast Period |
USD Million |
2026-2035 |
|
Market Size 2025 |
USD Million |
300.00 |
|
Market Size 2035 |
USD Million |
2578.33 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
24.00% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
27.4% |
|
CAGR 2026-2035 - Market by Cooling Type |
Two-Phase Immersion Cooling |
26.2% |
|
CAGR 2026-2035 - Market by Cooling Fluid |
Fluorocarbon-Based Fluid |
26.8% |
|
2025 Market Share by Region |
North America |
37.8% |
The data centers liquid immersion cooling market is being reshaped by major consolidation as established thermal management companies acquire specialist immersion vendors, new product launches expanding cooling capacity per rack, and surging revenue growth among specialist manufacturers scaling to meet AI infrastructure demand.
Asperitas launched its Direct Forced Convection immersion cooling offering, delivering cooling capacity beyond 3.6 kilowatts per U and 2,000 watts per socket, extending the Dutch specialist's tank portfolio for higher density compute environments and data center customers. Competing manufacturers across the data centers liquid immersion cooling market can look to this approach as a template for increasing per socket capacity without redesigning entire tank architecture from scratch.
DCX Liquid Cooling Systems, a Warsaw based manufacturer of facility distribution units and coolant systems for AI data centers, reported a 600 percent surge in revenue and hired more than 100 new employees to meet demand. Smaller manufacturers across the data centers liquid immersion cooling market can treat this growth as a benchmark for the revenue trajectory achievable by suppliers positioned early in the AI build out cycle.
Vertiv introduced its CoolCenter Immersion cooling system in London, expanding its global liquid cooling portfolio to support AI and high-performance computing environments with heat removal ranging from 25 to 240 kilowatts per system, now available across Europe, the Middle East, and Africa. Other companies across the data centers liquid immersion cooling market can pursue similarly scaled immersion platforms to capture demand pushing past conventional air-cooling limits.
Green Revolution Cooling secured additional investment from Samsung Ventures alongside a new strategic partnership with Samsung C&T, joining existing shareholders including HTS, SK Enmove, and ENEOS, following a year of new production customers and product releases. Specialist vendors elsewhere in the market can pursue similar strategic investor partnerships to access manufacturing scale beyond their existing shareholder base.
Established thermal management companies are increasingly acquiring controlling stakes in specialist coolant distribution unit manufacturers rather than relying solely on organic product development, reflecting the technical complexity of scaling facility level cooling infrastructure quickly enough to match AI power density growth across hyperscale campuses today. In February 2025, Schneider Electric acquired a controlling interest in Motivair, unveiling a combined liquid cooling portfolio spanning coolant distribution units from 105 kilowatts to 2.5 megawatts alongside cold plates, rear-door heat exchangers, and chillers for data center customers.
Coolant distribution unit providers across the data centers liquid immersion cooling market are increasingly scaling their platforms from rack level to facility level capacity, reflecting the growing power density of AI training clusters that require centralised, multi megawatt cooling infrastructure rather than distributed rack mounted units across data halls. In April 2025, CoolIT Systems introduced the CHx2000, its highest performance row-based coolant distribution unit, offering 2 megawatts of liquid cooling capacity within a compact footprint sufficient to support up to twelve 120-kilowatt NVIDIA GB200 NVL72 racks.
Immersion cooling vendors across the data centers liquid immersion cooling market are increasingly launching compact, edge-oriented systems alongside their core hyperscale offerings, reflecting recognition that high density compute requirements are extending beyond centralised data centers into smaller data rooms, communications closets, and industrial environments worldwide across multiple sectors. In March 2026, Submer partnered with ZEDEDA to launch modular edge AI infrastructure combining liquid cooling with edge orchestration software, extending immersion cooling capability to distributed edge computing deployments beyond traditional data center facilities and campuses.
Dielectric fluid suppliers and immersion vendors across the data centers liquid immersion cooling market are increasingly investing in dedicated in-house manufacturing capacity rather than relying solely on partnership-based production, reflecting confidence in sustained long-term demand for immersion cooling hardware across the broader European and global markets. In July 2025, STULZ opened a new liquid cooling production facility in Hamburg, Germany, marking its shift from partnership-based exploration toward in-house mass production of liquid and immersion cooling equipment for regional customers today.
Colocation providers and specialist cooling vendors are increasingly attracting large scale venture capital and strategic investment as investors recognise immersion cooling as core infrastructure for the AI era rather than a niche technology reserved for experimental pilot deployments across the industry. In September 2025, Iceotope raised 80 million dollars in Series C funding led by Emerson Electric, supporting continued development of its chassis level precision liquid cooling technology for hyperscale and edge deployments worldwide today.
The Expert Market Research's report titled “Data Centers Liquid Immersion Cooling Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Cooling Type
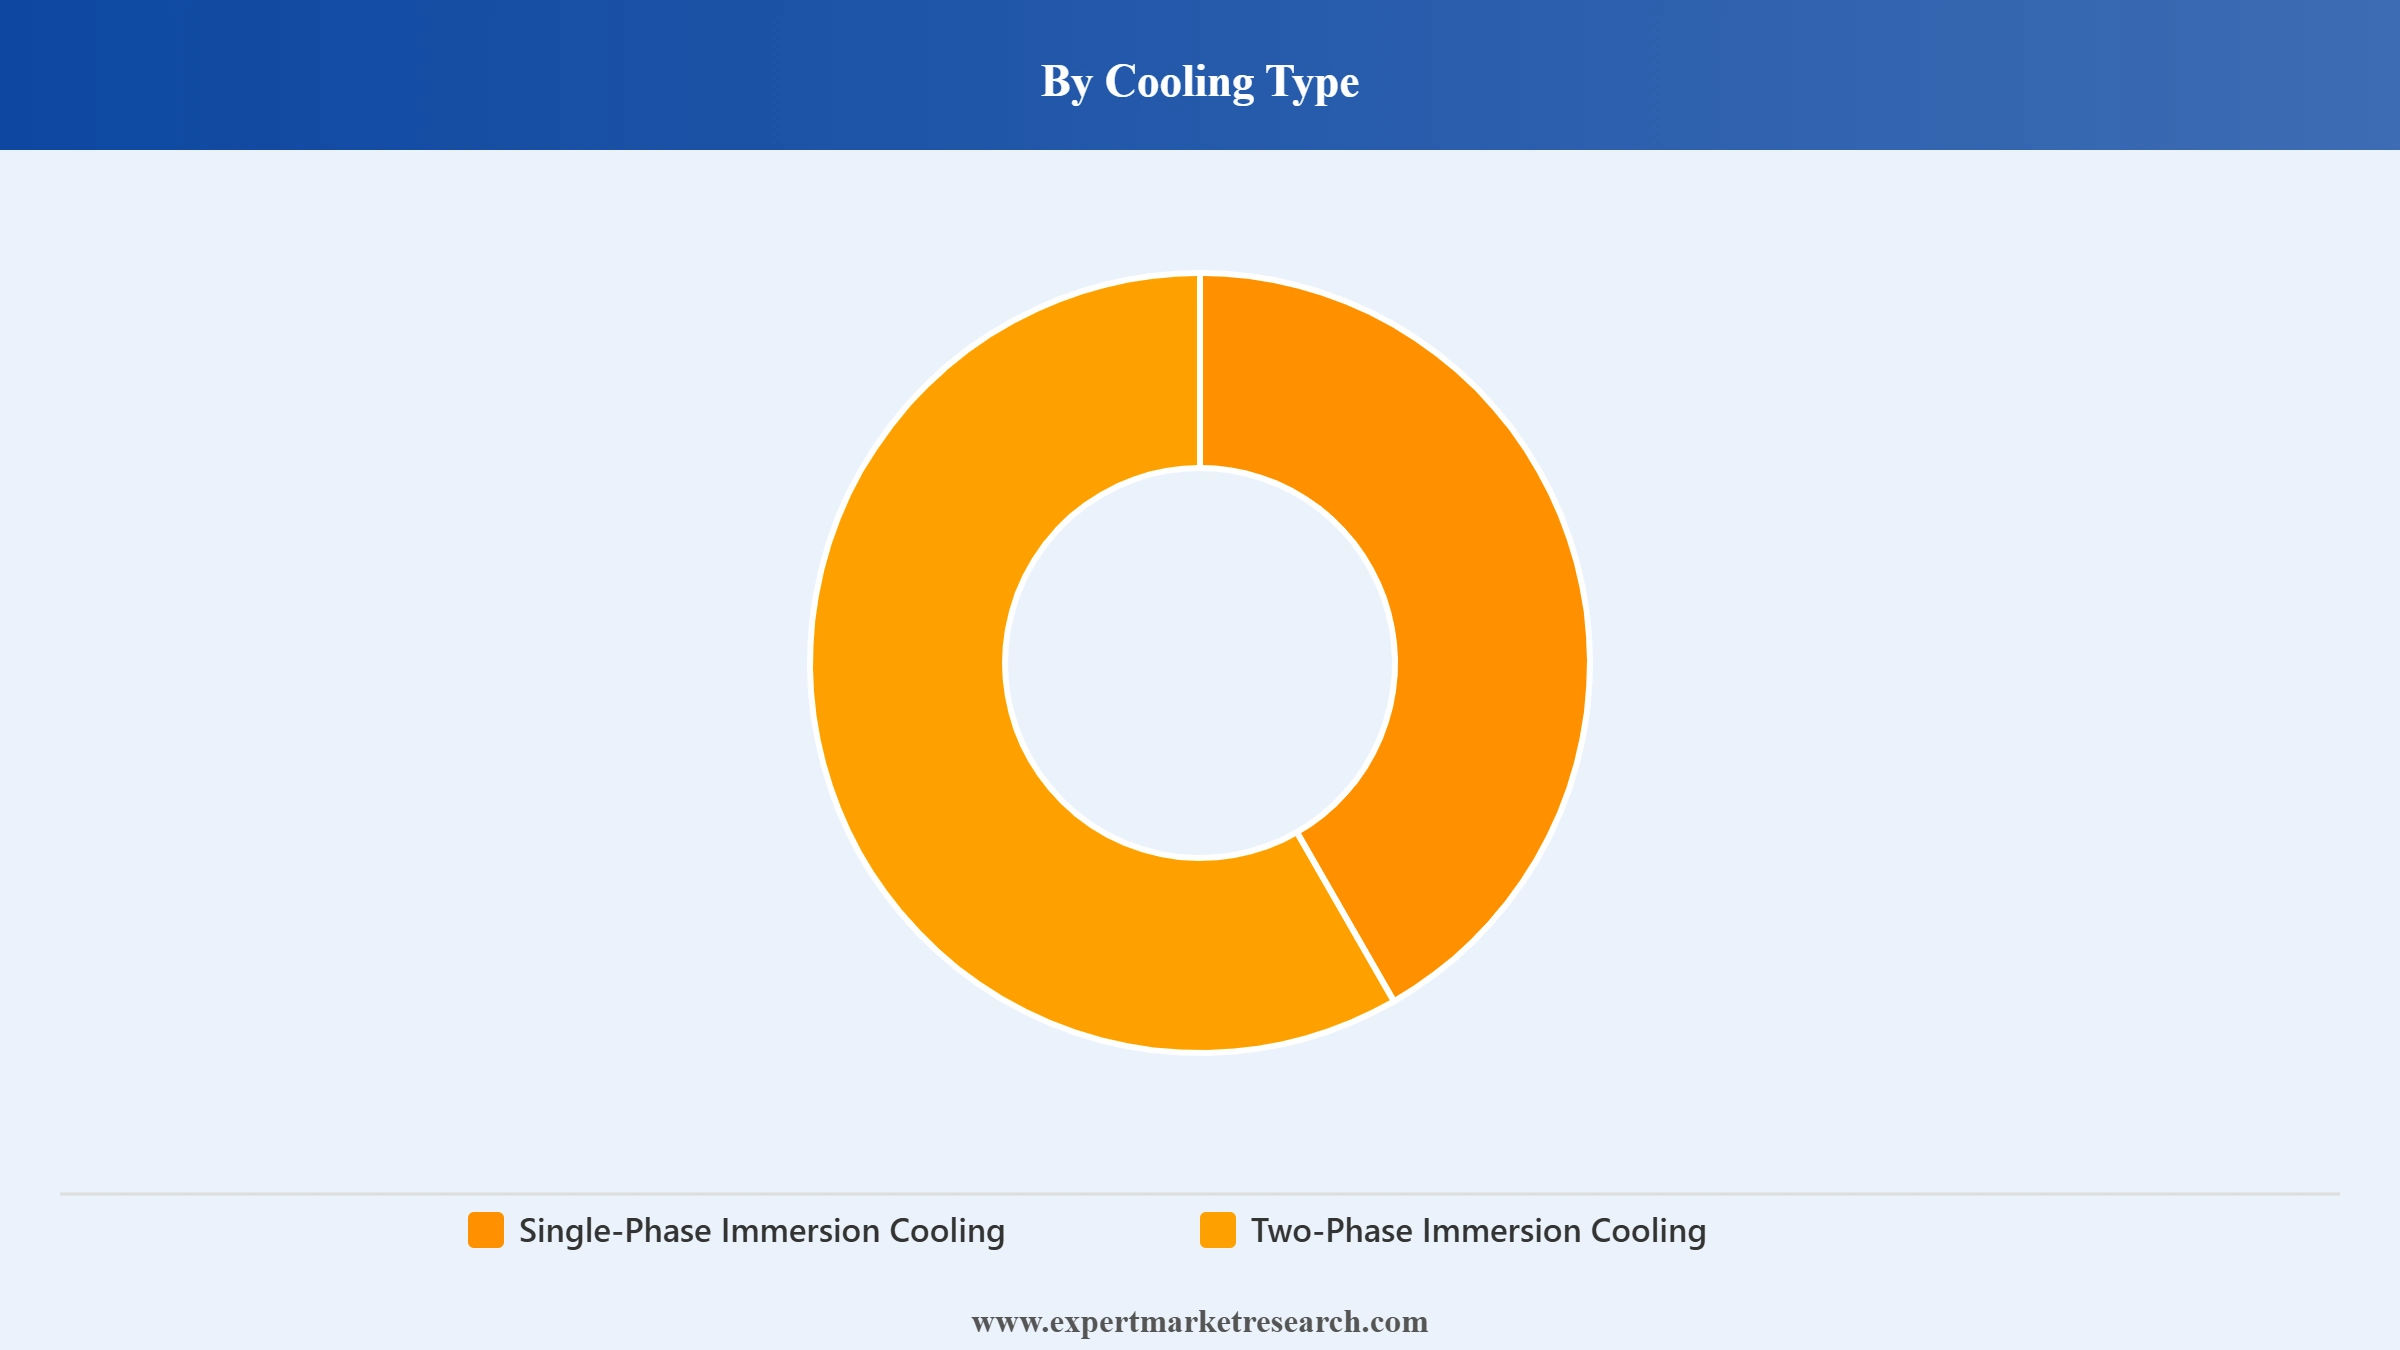
Key Insight: Single-Phase Immersion Cooling accounts for the largest share of the data centers liquid immersion cooling market by cooling type, supported by lower capital cost, simpler system design, and easier integration into existing data center infrastructure compared to two-phase alternatives. Two-Phase Immersion Cooling is the fastest-growing cooling type as operators running the highest density AI and HPC workloads increasingly require the superior thermal efficiency that phase change cooling provides. The Others category includes hybrid and emerging cooling configurations.
Market Breakup by Cooling Fluid
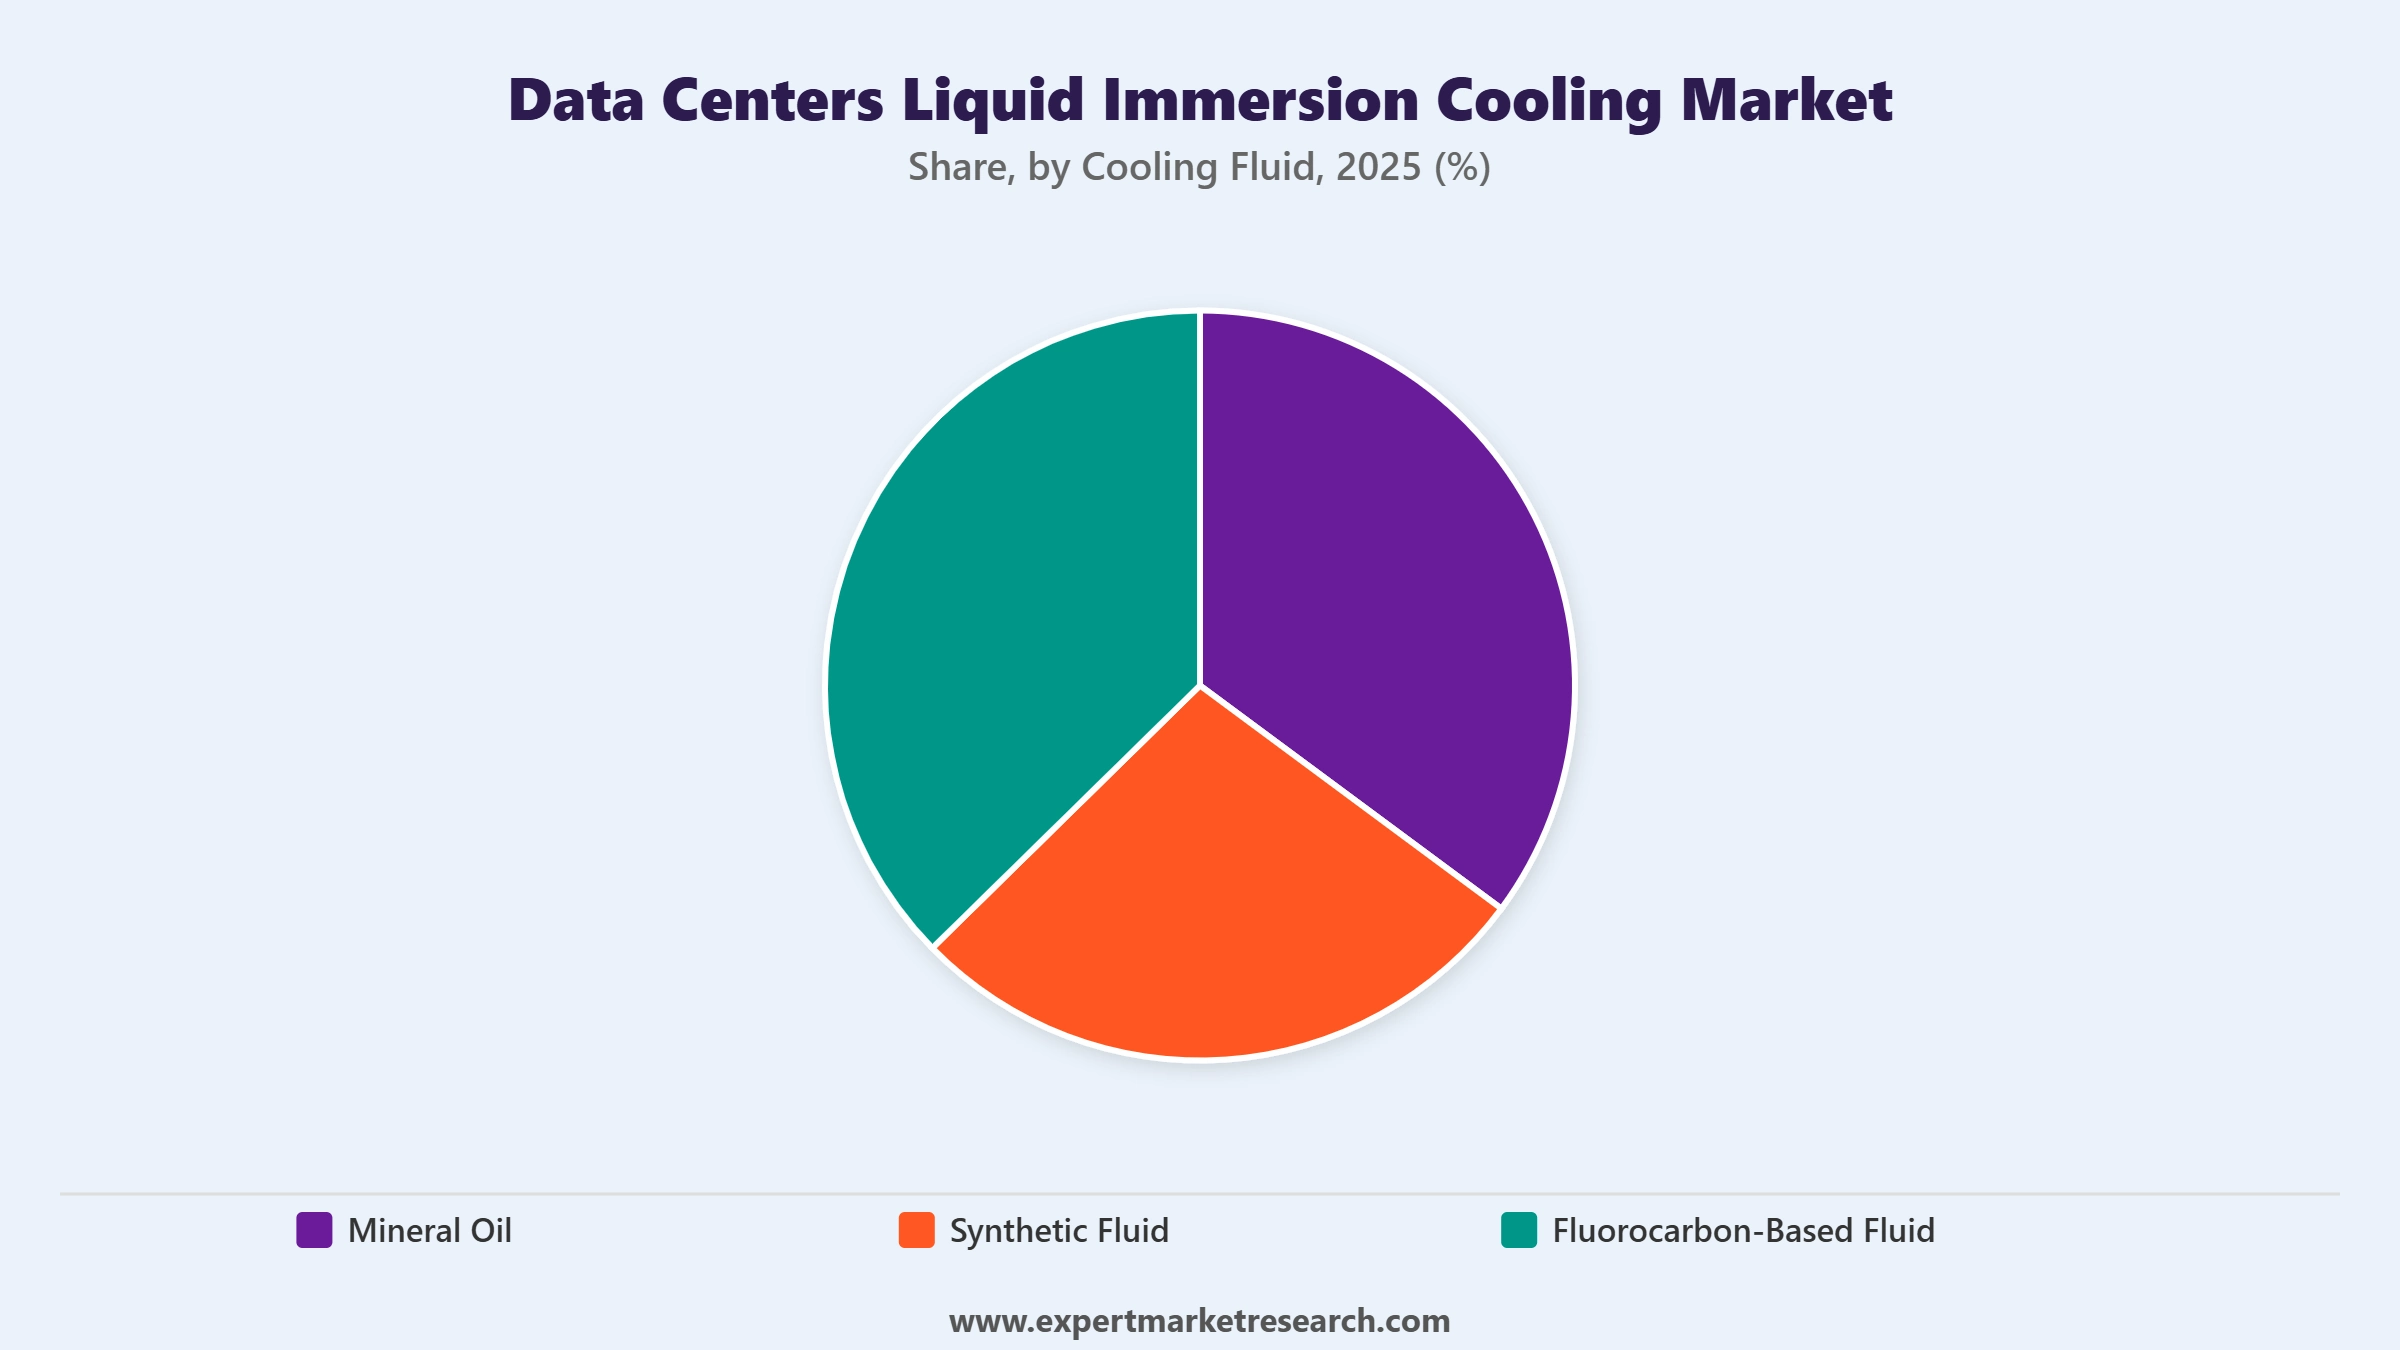
Key Insight: Mineral Oil accounts for the largest share of the data centers liquid immersion cooling market by cooling fluid, reflecting its lower cost and widespread availability for single-phase immersion deployments. In May 2025, Shell became the first immersion fluid provider to receive official chip manufacturer certification, with Intel endorsing Shell's fluids for its fourth and fifth generation Xeon processors and providing a warranty rider for immersion-cooled chips. Fluorocarbon-Based Fluid is the fastest-growing cooling fluid as two-phase systems increasingly target the highest density AI and HPC compute clusters. Synthetic Fluid continues to serve deployments prioritising extended fluid life. The Others category includes deionized water and emerging bio-based fluid chemistries.
Market Breakup by End Use
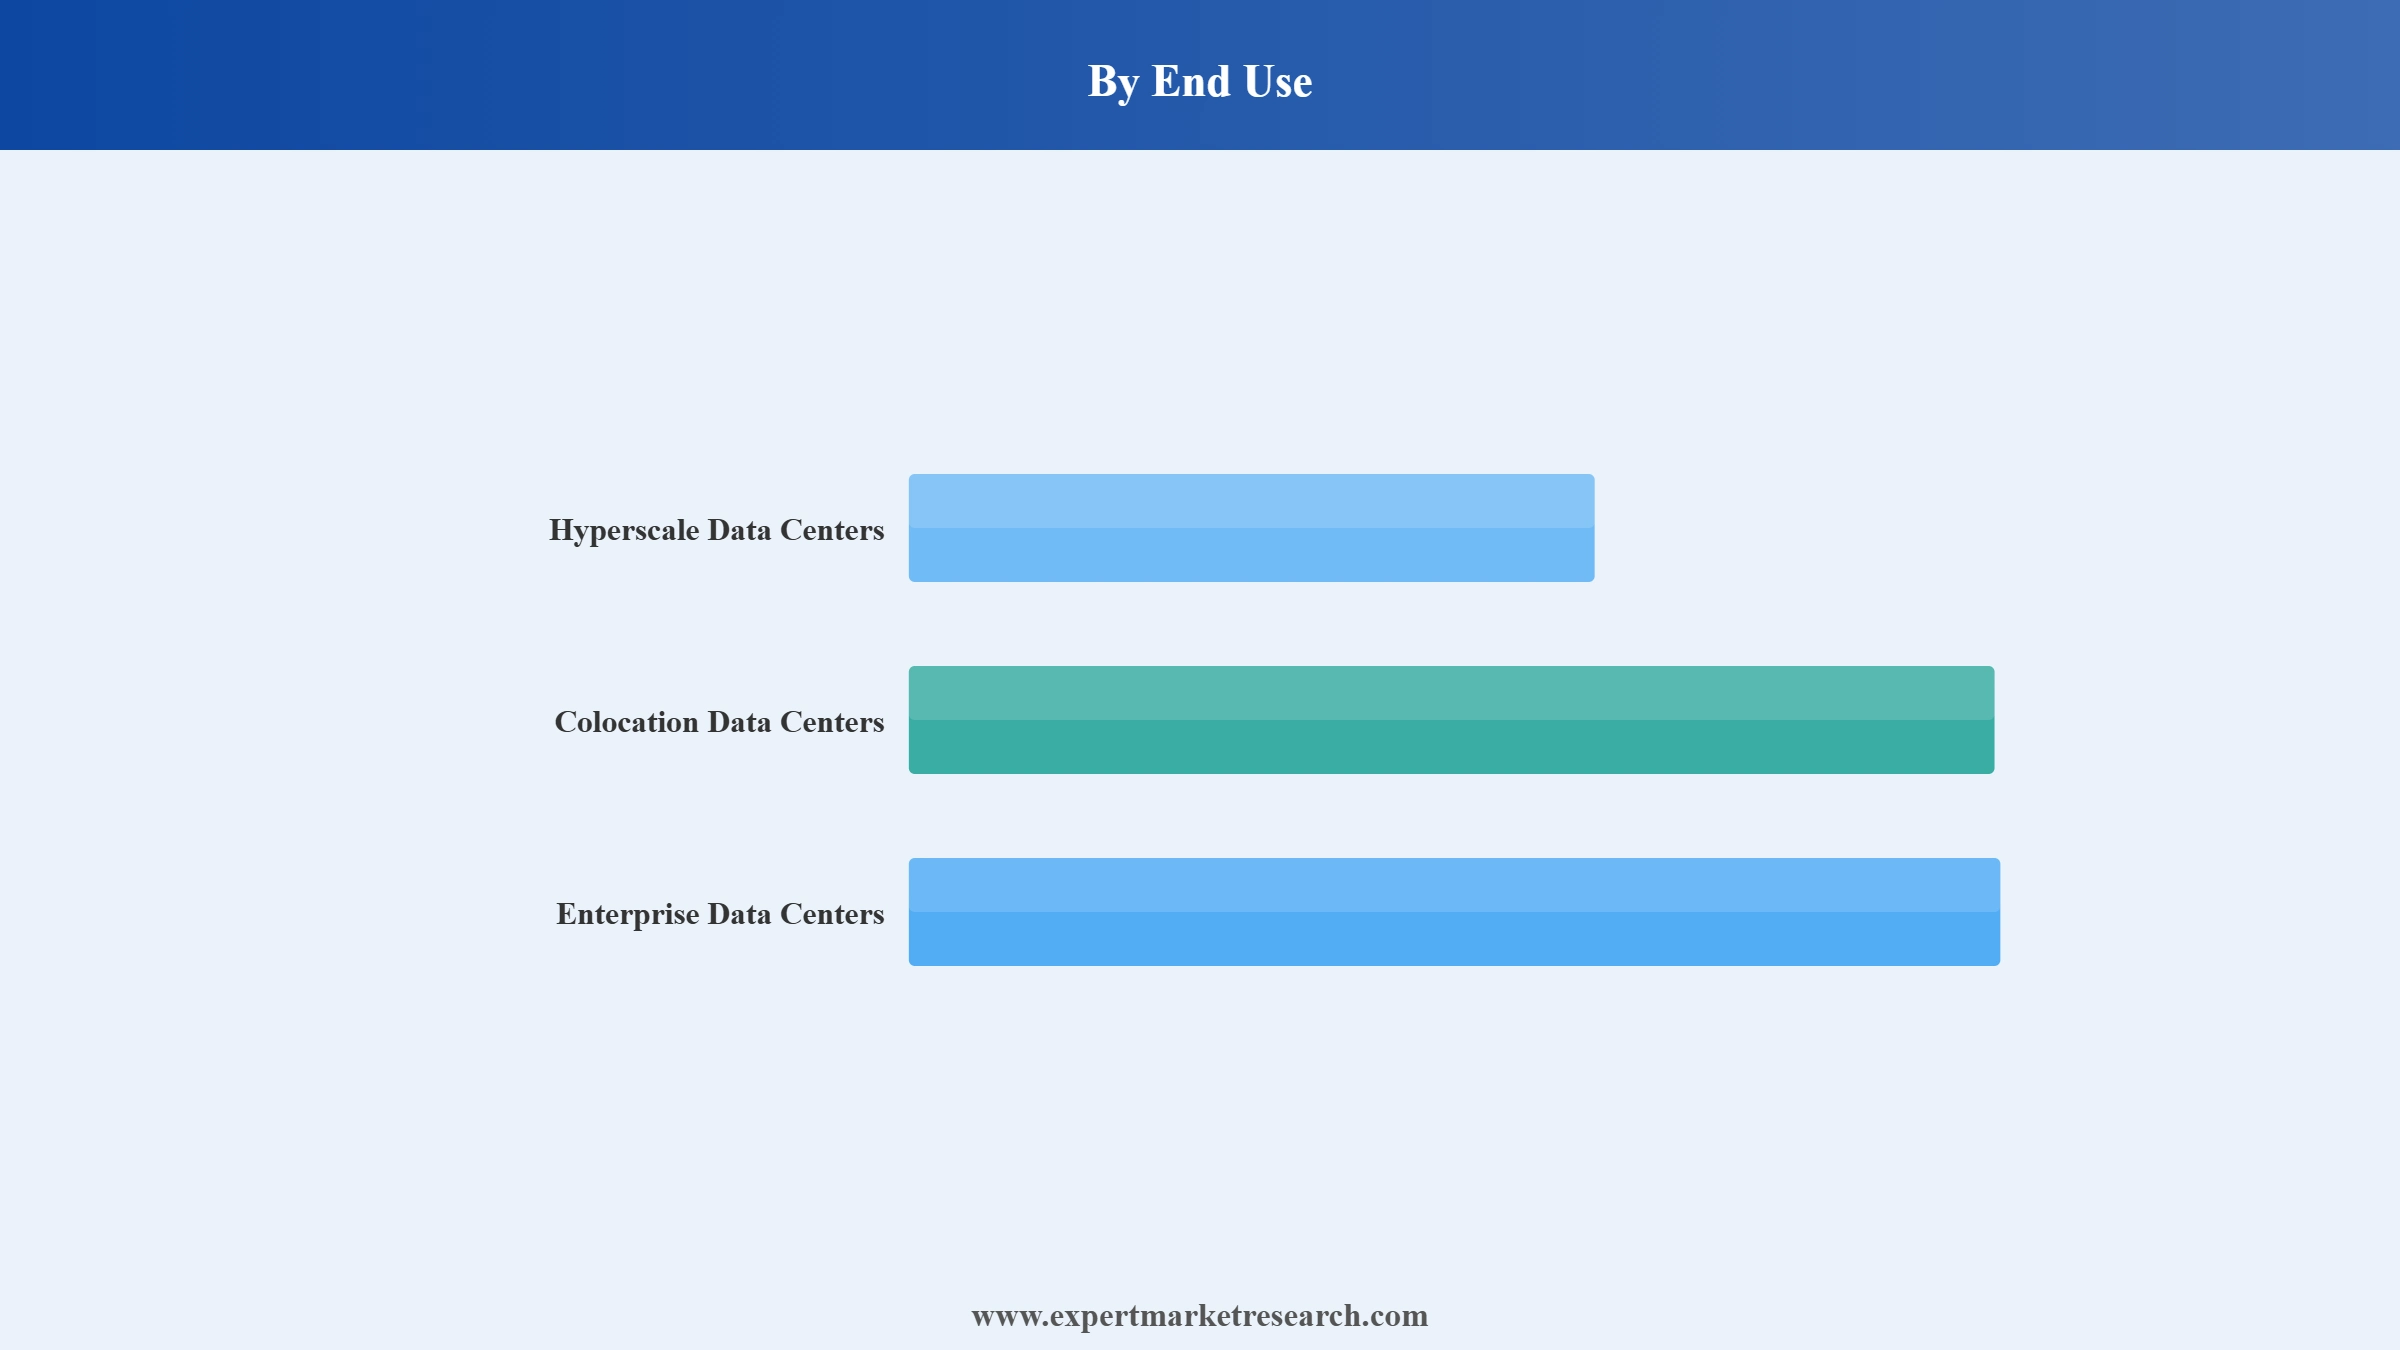
Key Insight: Hyperscale Data Centers account for the largest share of the data centers liquid immersion cooling market by end use, driven by the scale of AI training infrastructure investment among major cloud and technology companies. In July 2025, Amazon Web Services unveiled its in-house engineered IRHX rack-level liquid cooling platform, built around a coolant distribution unit flanked by liquid-to-air sidecars, to support its highest density AI training and inference instances built on NVIDIA Blackwell GPUs. Colocation Data Centers are the fastest-growing end use segment. Enterprise Data Centers continue to adopt immersion cooling more selectively. The Others category includes edge and industrial deployments.
Market Breakup by Region
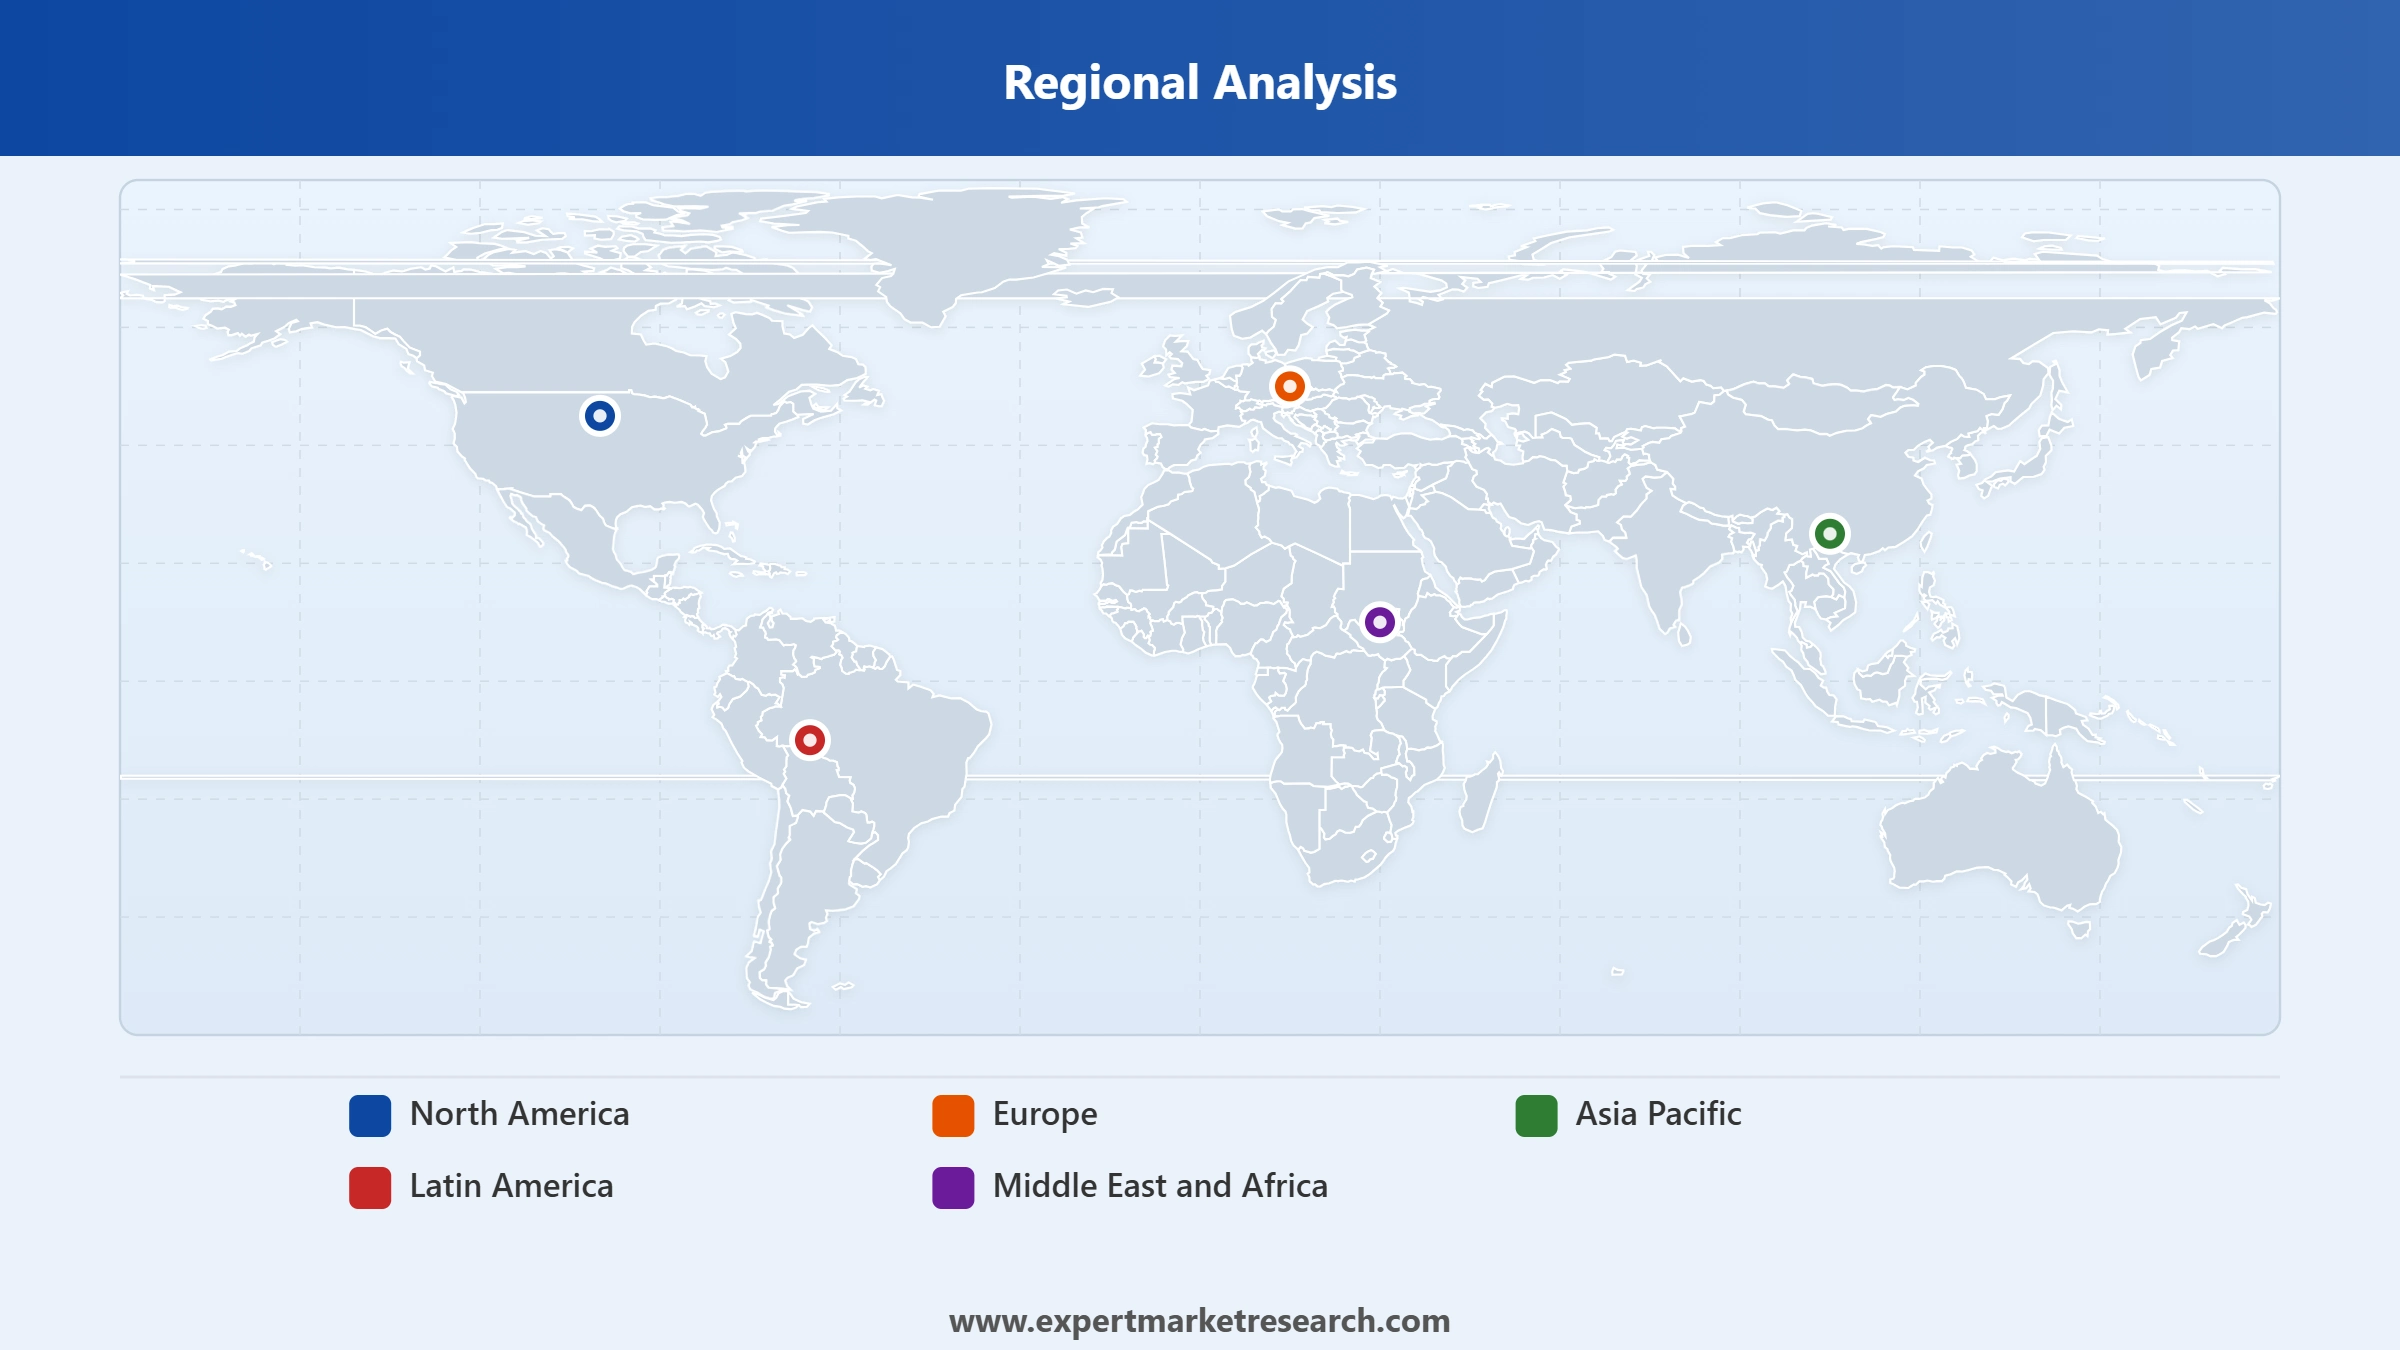
Key Insight: North America dominates the data centers liquid immersion cooling market, supported by the concentration of hyperscale AI infrastructure investment and leading immersion cooling technology providers headquartered across the region. Asia Pacific is the fastest-growing region as rapid hyperscale and AI data center capacity buildout accelerates across several key national markets. Europe remains a significant market supported by established thermal management suppliers and growing sustainability driven adoption. Latin America and the Middle East and Africa remain smaller markets tied to broader data center infrastructure investment.
By cooling type, single-phase immersion cooling leads the market while two-phase systems grow fastest
Single-Phase Immersion Cooling accounts for the largest share of the data centers liquid immersion cooling market by cooling type, supported by lower capital cost, simpler system design, and easier integration into existing data center infrastructure compared to two-phase alternatives requiring dedicated engineering expertise and specialised maintenance protocols. This simplicity continues to make single-phase systems the preferred entry point for operators pursuing their first immersion cooling deployment today across most fielded programmes worldwide and pilot projects.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Two-Phase Immersion Cooling is the fastest-growing cooling type as operators running the highest density AI and HPC workloads increasingly require the superior thermal efficiency that phase change cooling provides for next generation GPU clusters and accelerator racks. In September 2025, Microsoft announced it had become the first cloud provider running two-phase immersion cooling in a production environment, deploying sealed cooling tanks where boiling dielectric fluid condenses against a cooled lid to remove heat efficiently.
By cooling fluid, mineral oil leads the market while fluorocarbon-based fluid grows fastest
Mineral Oil accounts for the largest share of the data centers liquid immersion cooling market by cooling fluid, reflecting its lower cost and widespread availability for single-phase immersion deployments across most fielded programmes today and established facility engineer familiarity with handling procedures. In May 2025, Engineered Fluids partnered with a precision liquid cooling specialist and a leading AI-native networking provider to combine dielectric coolants, sealed-chassis cooling technology, and high-performance switching hardware into one integrated solution.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Fluorocarbon-Based Fluid is the fastest-growing cooling fluid as two-phase systems increasingly target the highest density AI and HPC compute clusters requiring superior thermal efficiency compared to mineral oil-based alternatives used in most current single-phase deployments across the industry today. Continued advances in dielectric fluid chemistry and tightening PFAS regulation continue to reshape fluid selection criteria across the market, pushing manufacturers toward lower global warming potential formulations for future regulatory compliance requirements.
By end use, hyperscale data centers lead the market while colocation providers grow fastest
Hyperscale Data Centers account for the largest share of the data centers liquid immersion cooling market by end use, driven by the scale of AI training infrastructure investment among major cloud and technology companies deploying immersion cooling at scale across their global campuses and regional facilities. Continued hyperscale capital expenditure on AI infrastructure continues to reinforce this segment's leading position today relative to colocation and enterprise deployments still scaling their own adoption curves gradually.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Colocation Data Centers are the fastest-growing end use segment as providers increasingly offer immersion cooling as a standard deployment option to attract AI and HPC focused tenants without requiring those customers to build dedicated infrastructure themselves from scratch. In June 2025, Global Switch unveiled a comprehensive suite of liquid cooling technologies developed with six leading digital infrastructure partners, showcasing direct-to-chip, single-phase immersion, and two-phase immersion systems across its colocation facilities worldwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America dominates the market due to hyperscale AI infrastructure investment concentration
North America dominates the data centers liquid immersion cooling market, supported by the concentration of hyperscale AI infrastructure investment and leading immersion cooling technology providers headquartered across the region and its broader supplier ecosystem today. In 2025, Colovore secured a 925-million-dollar debt raise and announced expansion of its liquid-cooled data center platform beyond Silicon Valley into Reno and Chicago, targeting Q4 2025 and Q4 2026 delivery respectively to serve growing NVIDIA-accelerated AI inference demand nationwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is the fastest-growing region as rapid hyperscale and AI data center capacity buildout accelerates across several key national markets pursuing digital infrastructure expansion and government backed technology investment programmes. In December 2025, Huawei Digital Power secured a 200-million-dollar order to supply FusionModule 2000 immersion cooling systems for China Mobile's 50-megawatt AI computing hub in Guangdong, reflecting the scale of regional investment in immersion cooled AI infrastructure across the region.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
23.1% |
|
Europe |
22.6% |
|
Asia Pacific |
27.4% |
|
Latin America |
24.8% |
|
Middle East and Africa |
23.9% |
The global data centers liquid immersion cooling companies feature a moderately consolidated competitive structure led by established thermal management companies with broad end to end portfolios and specialist immersion cooling vendors competing on tank design, fluid chemistry, and system density. Manufacturers, including Vertiv are competing primarily through portfolio breadth spanning direct-to-chip and immersion cooling, while specialist vendors including Green Revolution Cooling are differentiating through deep immersion specific engineering expertise and strategic investor partnerships.
Leading data centers liquid immersion cooling market players are focusing on expanding cooling capacity per rack to meet rising AI power densities, pursuing strategic acquisitions and investment partnerships to broaden manufacturing scale, and extending product lines into edge and modular deployment formats. Increasing collaboration with server original equipment manufacturers and dielectric fluid suppliers is also enabling vendors to offer more fully validated, turnkey immersion cooling solutions.
Vertiv Holdings Co., founded in 1946 and headquartered in Westerville, Ohio, United States, is a global provider of critical digital infrastructure and continuity solutions, offering an end-to-end thermal chain spanning direct-to-chip cooling, immersion cooling, rear-door heat exchangers, and coolant distribution. The company continues to expand its liquid cooling portfolio globally, including dedicated immersion systems supporting AI and high-performance computing deployments across multiple regions.
Green Revolution Cooling, Inc., founded in 2009 and headquartered in Austin, Texas, United States, is a specialist provider of single-phase immersion cooling technology for data centers, with solutions deployed across more than twenty countries serving artificial intelligence, blockchain, high-performance computing, and edge computing applications. The company holds ISO 9001 certification and has secured strategic investment from major electronics and industrial conglomerates supporting its continued product development.
LiquidStack Holding B.V., founded in 2012 and headquartered in Carrollton, Texas, United States, is a global provider of high-density liquid, direct-to-chip, and immersion cooling solutions engineered for generative AI and hyperscale computing demands. The company operates manufacturing, engineering, and research and development operations across the United States and Hong Kong, serving data center and high-performance compute customers worldwide.
Asperitas B.V., founded in 2014 and headquartered in Amsterdam, Netherlands, is a specialist immersion cooling technology provider known for its tank-based systems supporting high density compute environments without reliance on chilled water infrastructure. The company continues to expand its product portfolio with new convection-based cooling configurations supporting higher per socket cooling capacity for demanding AI and HPC workloads.
Other key players in the market report include Submer Technologies, SL, Fujitsu Limited, STULZ GmbH, DCX Liquid Cooling Company, and Iceotope Technologies Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the data centers liquid immersion cooling market 2026-2035 with our in-depth report. Gain strategic insights, future forecasts, and key market developments that can help you stay competitive. Download a free sample report or contact our team for customised consultation on the market trends 2026.


Upto 15% Off
USD
$3999 $3599
$2499 $2249
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the data centers liquid immersion cooling market reached an approximate value of USD 300.00 Million.
The market is projected to grow at a CAGR of 24.00% between 2026 and 2035.
The key players in the market include Vertiv Holdings Co., Submer Technologies, SL, Green Revolution Cooling, Inc., LiquidStack Holding B.V., Asperitas B.V., Fujitsu Limited, STULZ GmbH, DCX Liquid Cooling Company, and Iceotope Technologies Limited, among others.
Leading manufacturers are focusing on expanding cooling capacity per rack, pursuing strategic acquisitions and investment partnerships to broaden manufacturing scale, and extending product lines into edge and modular deployment formats.
Key challenges include dielectric fluid supply and cost constraints, limited server OEM warranty support for immersion deployment, and the operational complexity of retrofitting existing air cooled data center facilities.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Cooling Type |
|
|
Breakup by Cooling Fluid |
|
|
Breakup by End Use |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




