

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
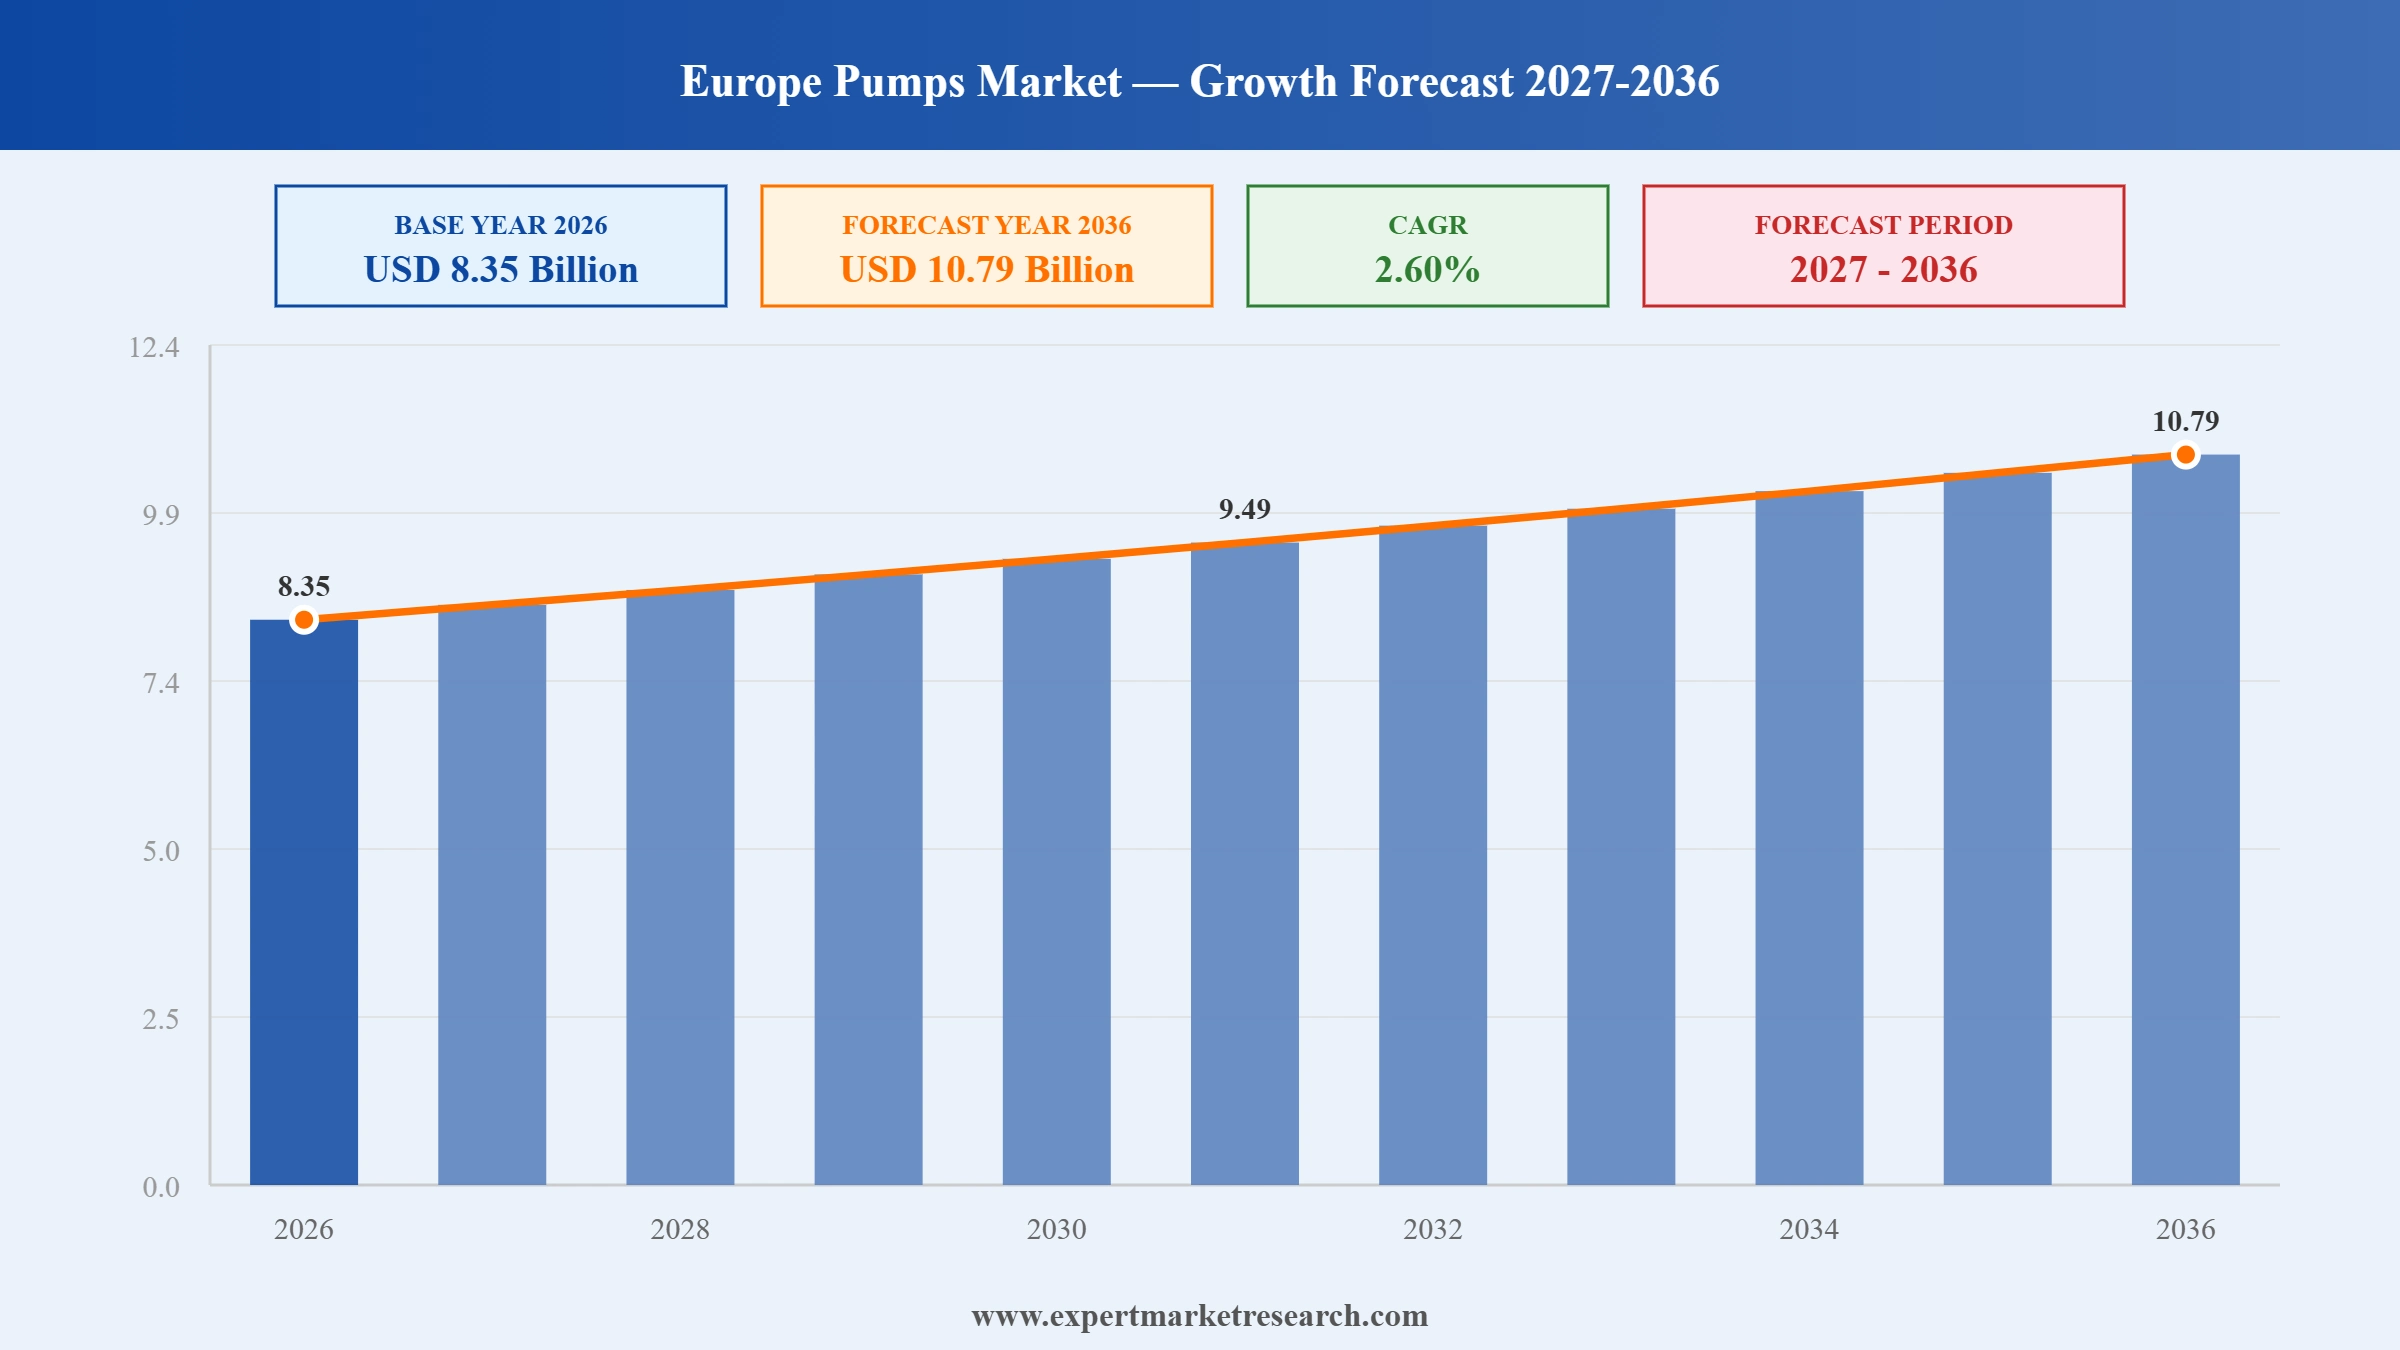
The Europe pumps market attained a value of USD 8.14 Billion in 2025 and is projected to expand at a CAGR of 2.60% through 2035. The market is further expected to achieve USD 10.52 Billion by 2035, supported by ageing water infrastructure replacement, sustained industrial and power-generation investment, and stringent EU energy-efficiency regulations driving demand for centrifugal and positive displacement pumps. Growth spans oil and gas, water and wastewater, chemicals and petrochemicals, mining, and power generation end uses, with manufacturers across Germany, the United Kingdom, France, and Italy competing on engineering scale, aftermarket service depth, and large-project execution capability.
Sustained infrastructure renewal and decarbonisation commitments continue to anchor steady demand across the Europe pumps market, as utilities and industrial operators increasingly replace ageing equipment with energy-efficient alternatives. Manufacturers are also investing in large-project execution capability, reflecting the industry's pursuit of high-value power generation and mining contracts rather than smaller aftermarket business alone.
The Europe pumps market is witnessing further developments as established manufacturers secure record-scale contracts for critical infrastructure projects. KSB secured the largest order in its history in March 2026, valued at more than 150 million euros, for eight main reactor coolant pumps destined for a nuclear power plant project in Eastern Europe, with production based at its Frankenthal facility in Germany. This shift toward record-scale power generation contracts is concentrated among manufacturers with sufficient nuclear-grade engineering certification, while smaller specialists instead compete on regional service depth.
In addition, established manufacturers are increasingly winning pumped-storage hydropower contracts as European utilities expand grid-balancing capacity, reflecting the industry's recognition that renewable energy integration increasingly determines large-project win rates. ANDRITZ secured a contract from Electricite de France in the second quarter of 2026 to supply a pump turbine for the Vouglans-Saut-Mortier pumped storage project in the French Jura region. Such hydropower contract activity is reshaping competitive positioning across the wider europe pumps market as manufacturers with proven pumped-storage engineering credentials increasingly differentiate themselves from competitors focused solely on conventional industrial pumping.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Mining operators are increasingly seeking pump solutions engineered specifically for abrasive slurry handling rather than adapting general-purpose equipment. Weir Group secured a substantial pumps order from Lloyds Metals and Energy for an iron ore project, while separately launching new grinding circuit pump technology designed to reduce energy and water use in mineral processing. Companies can leverage purpose-built mining pump ranges to capture premium pricing over generalist competitors.
European utilities are expanding grid-balancing infrastructure as renewable generation capacity grows, creating fresh demand for large-scale pump turbine equipment. Electricite de France awarded ANDRITZ a contract to supply a variable-speed pump turbine for the Vouglans-Saut-Mortier pumped storage project in the French Jura region, with the order included in the company's second-quarter order intake. Companies can leverage pumped-storage engineering credentials to secure multi-year utility contracts ahead of competitors lacking this specialism.
Nuclear capacity expansion across Eastern Europe is generating record-scale contract opportunities for manufacturers with reactor-grade engineering certification. KSB secured the largest order in its history, valued at more than 150 million euros, for eight main reactor coolant pumps manufactured at its Frankenthal facility in Germany. Companies can leverage nuclear-grade certification to access contract values well above typical industrial pump orders.
Pump manufacturers are increasingly acquiring adjacent water treatment technology providers to broaden their addressable project scope beyond pumping equipment alone. Grundfos finalised its acquisition of Newterra, a manufacturer of modular water treatment solutions, first announced in June 2025. Companies can leverage adjacent water treatment capability to bid for integrated system contracts rather than pump-only supply packages.
Diversified industrial manufacturers continue expanding their pump and process technology portfolios through targeted acquisitions rather than organic product development alone. Dover Corporation completed its acquisition of Cloeren Incorporated in August 2026, integrating the business into the MAAG unit within its Pumps and Process Solutions segment, building on a series of similar bolt-on acquisitions across the segment during 2025 and 2026. Companies can leverage bolt-on acquisitions to add specialised process technology capability faster than internal development timelines would allow, a strategy that continues to reshape the competitive landscape as larger conglomerates absorb specialist technology providers one deal at a time.
Manufacturers with European production bases are recalibrating list prices as raw material and energy input costs continue shifting through 2026. EBARA's European pump distribution arm, headquartered in Italy, confirmed a 4.5 percent price increase effective from July 2026 across its stainless steel and cast iron pump ranges. Distributors and installers are adjusting quotation practices ahead of the effective date to manage customer expectations across the wider europe pumps market, with several channel partners already flagging the increase in advance to preserve existing project bids negotiated under prior pricing terms.
Established manufacturers are refreshing core water-handling product lines with efficiency-focused redesigns even as headline attention centres on large project wins. KSB introduced the Omega 2 in January 2026, a next-generation axially split volute casing pump series for waterworks, district heating and cooling, and desalination applications, featuring an optimised hydraulic system and self-centring rotor design that improves efficiency and serviceability. Companies can leverage incremental product-line refreshes to sustain replacement demand from existing utility customers between major contract cycles, keeping core product families commercially competitive without committing the engineering resources a full platform redesign would otherwise require.
Diversified pump manufacturers are targeting niche hygienic and sanitary applications through acquisition rather than in-house development. Dover Corporation acquired ipp Pump Products GmbH in June 2025, a Bersenbrück-based manufacturer of hygienic lobe and progressive pumps for food and beverage, cosmetics, and pharmaceutical applications, integrating the business into its Pump Solutions Group. Companies can leverage acquisitions of specialised hygienic pump manufacturers to access strictly regulated end markets without the multi-year certification burden of building such capability internally, a route several diversified industrial groups are increasingly favouring over organic entry into food-grade and pharmaceutical-grade equipment segments.
This Expert Market Research Report titled "Europe Pumps Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
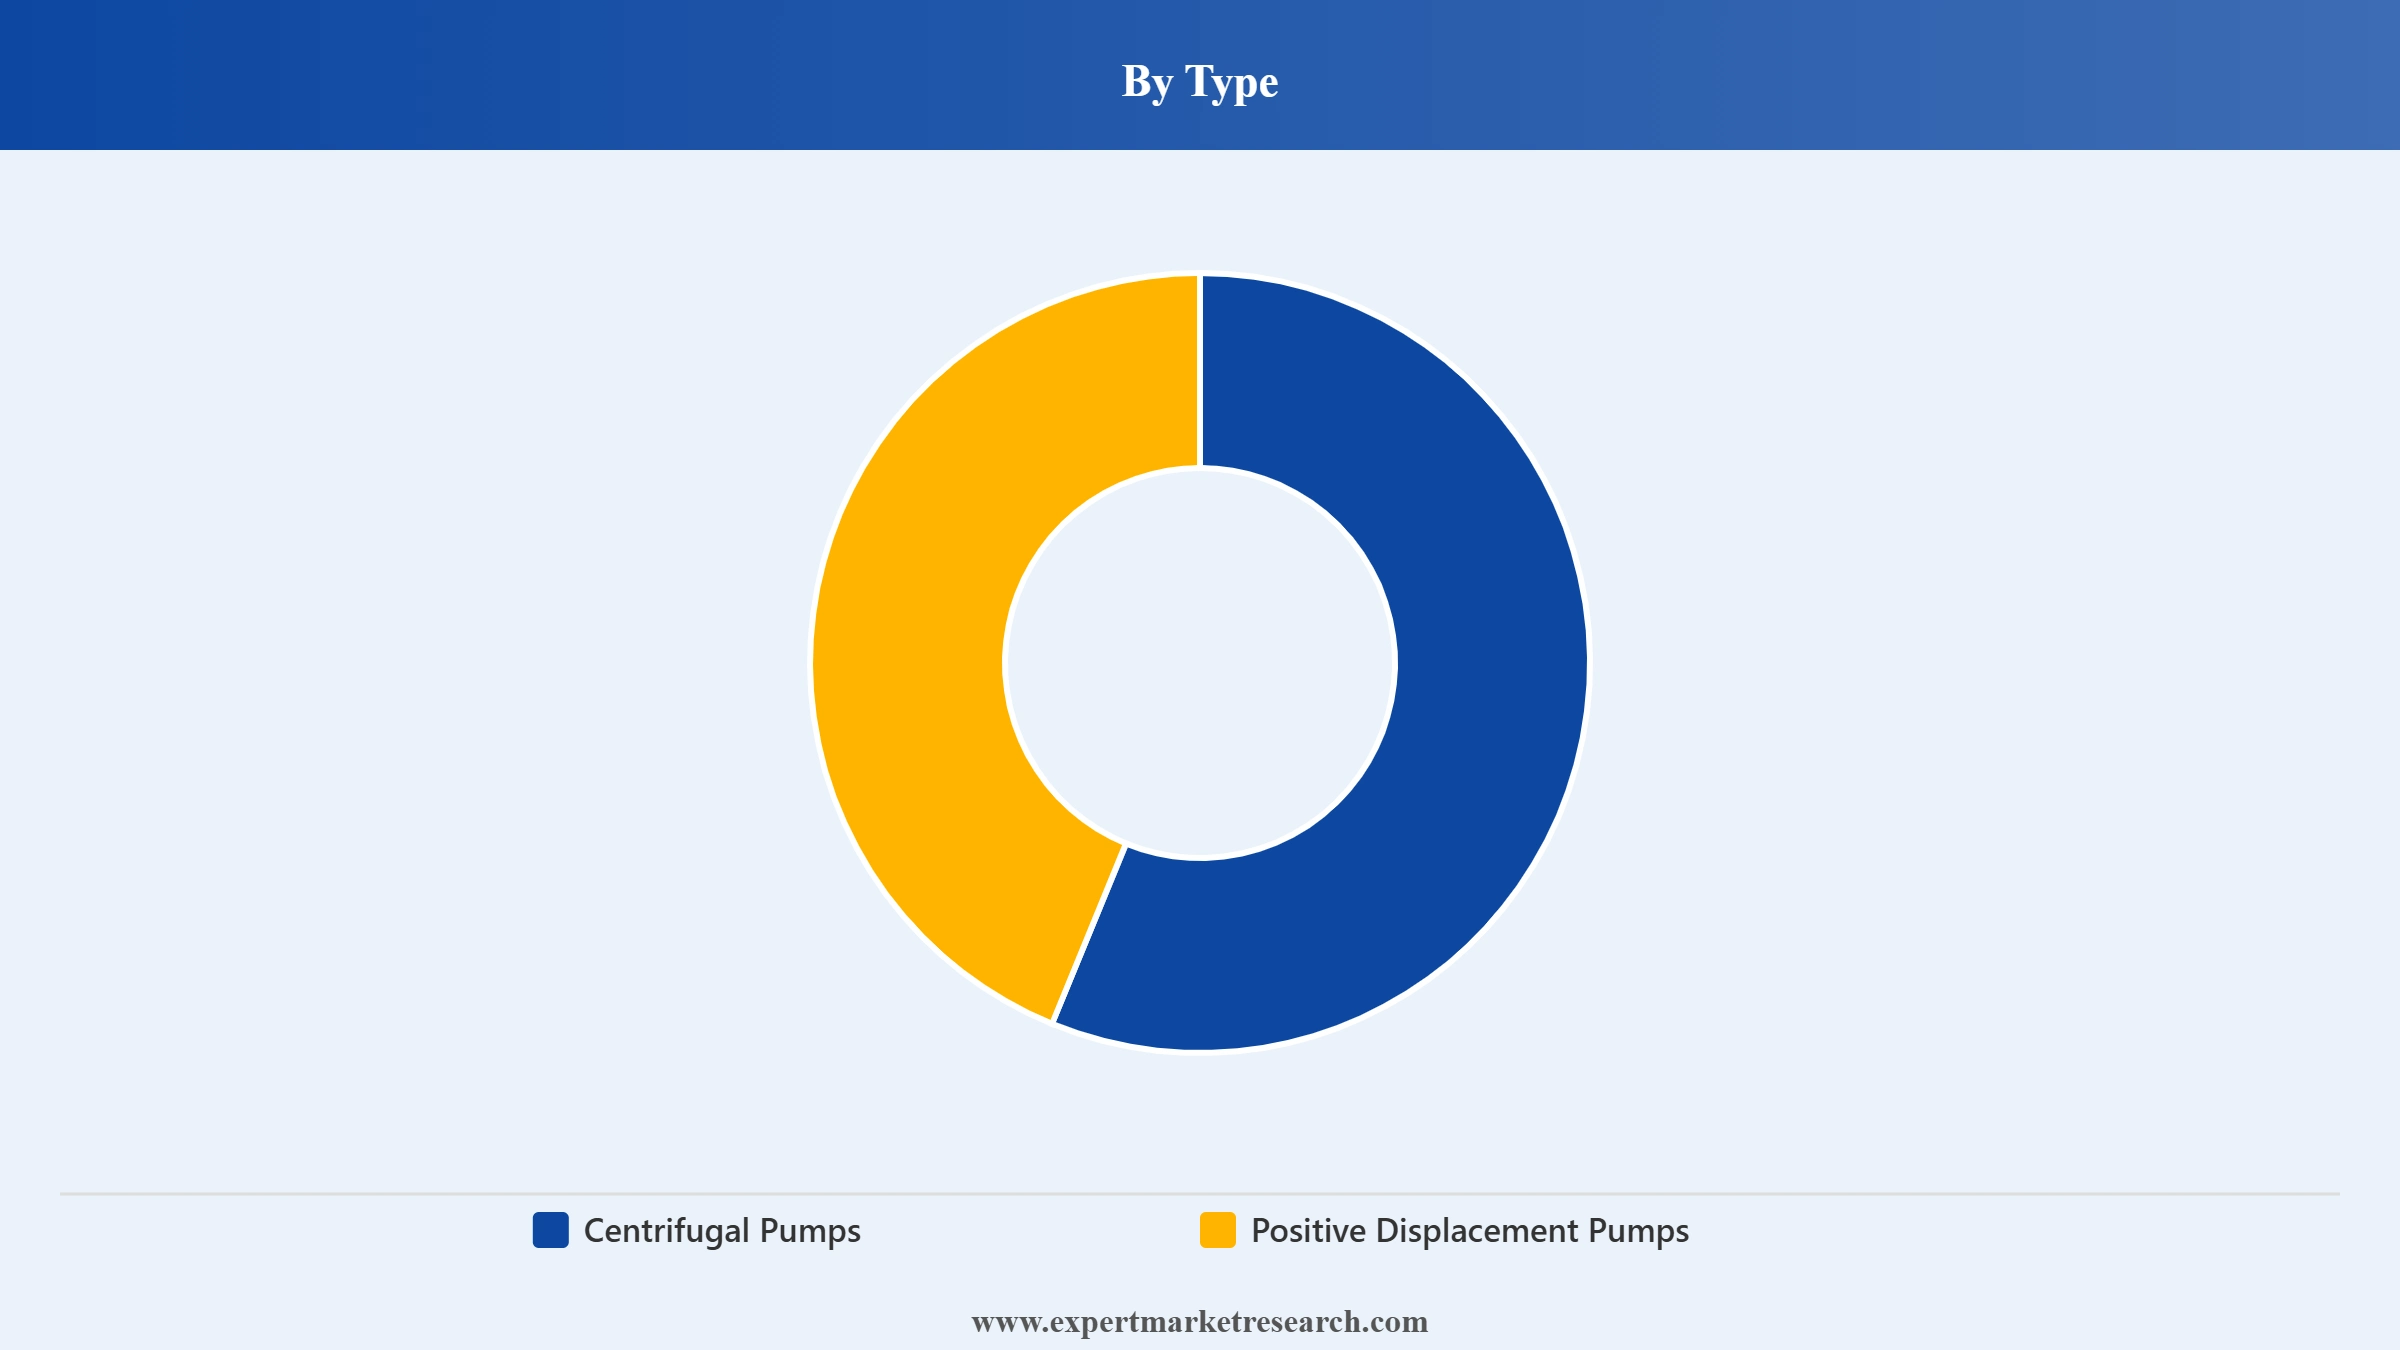
Key Insight: Centrifugal Pumps accounts for the largest share of the europe pumps market, reflecting their widespread use across water supply, wastewater, and general industrial applications given lower maintenance requirements and higher flow-rate capacity. Positive Displacement Pumps is growing at a fast pace at a projected CAGR of 3.10%, illustrated by Weir Group's June 2026 launch of new grinding circuit pump technology engineered for high-viscosity, abrasive slurry handling in mineral processing applications, an area where manufacturers continue prioritising abrasion-resistant materials and wear-part longevity to reduce total cost of ownership for high-throughput mining customers.
Market Breakup by End Use
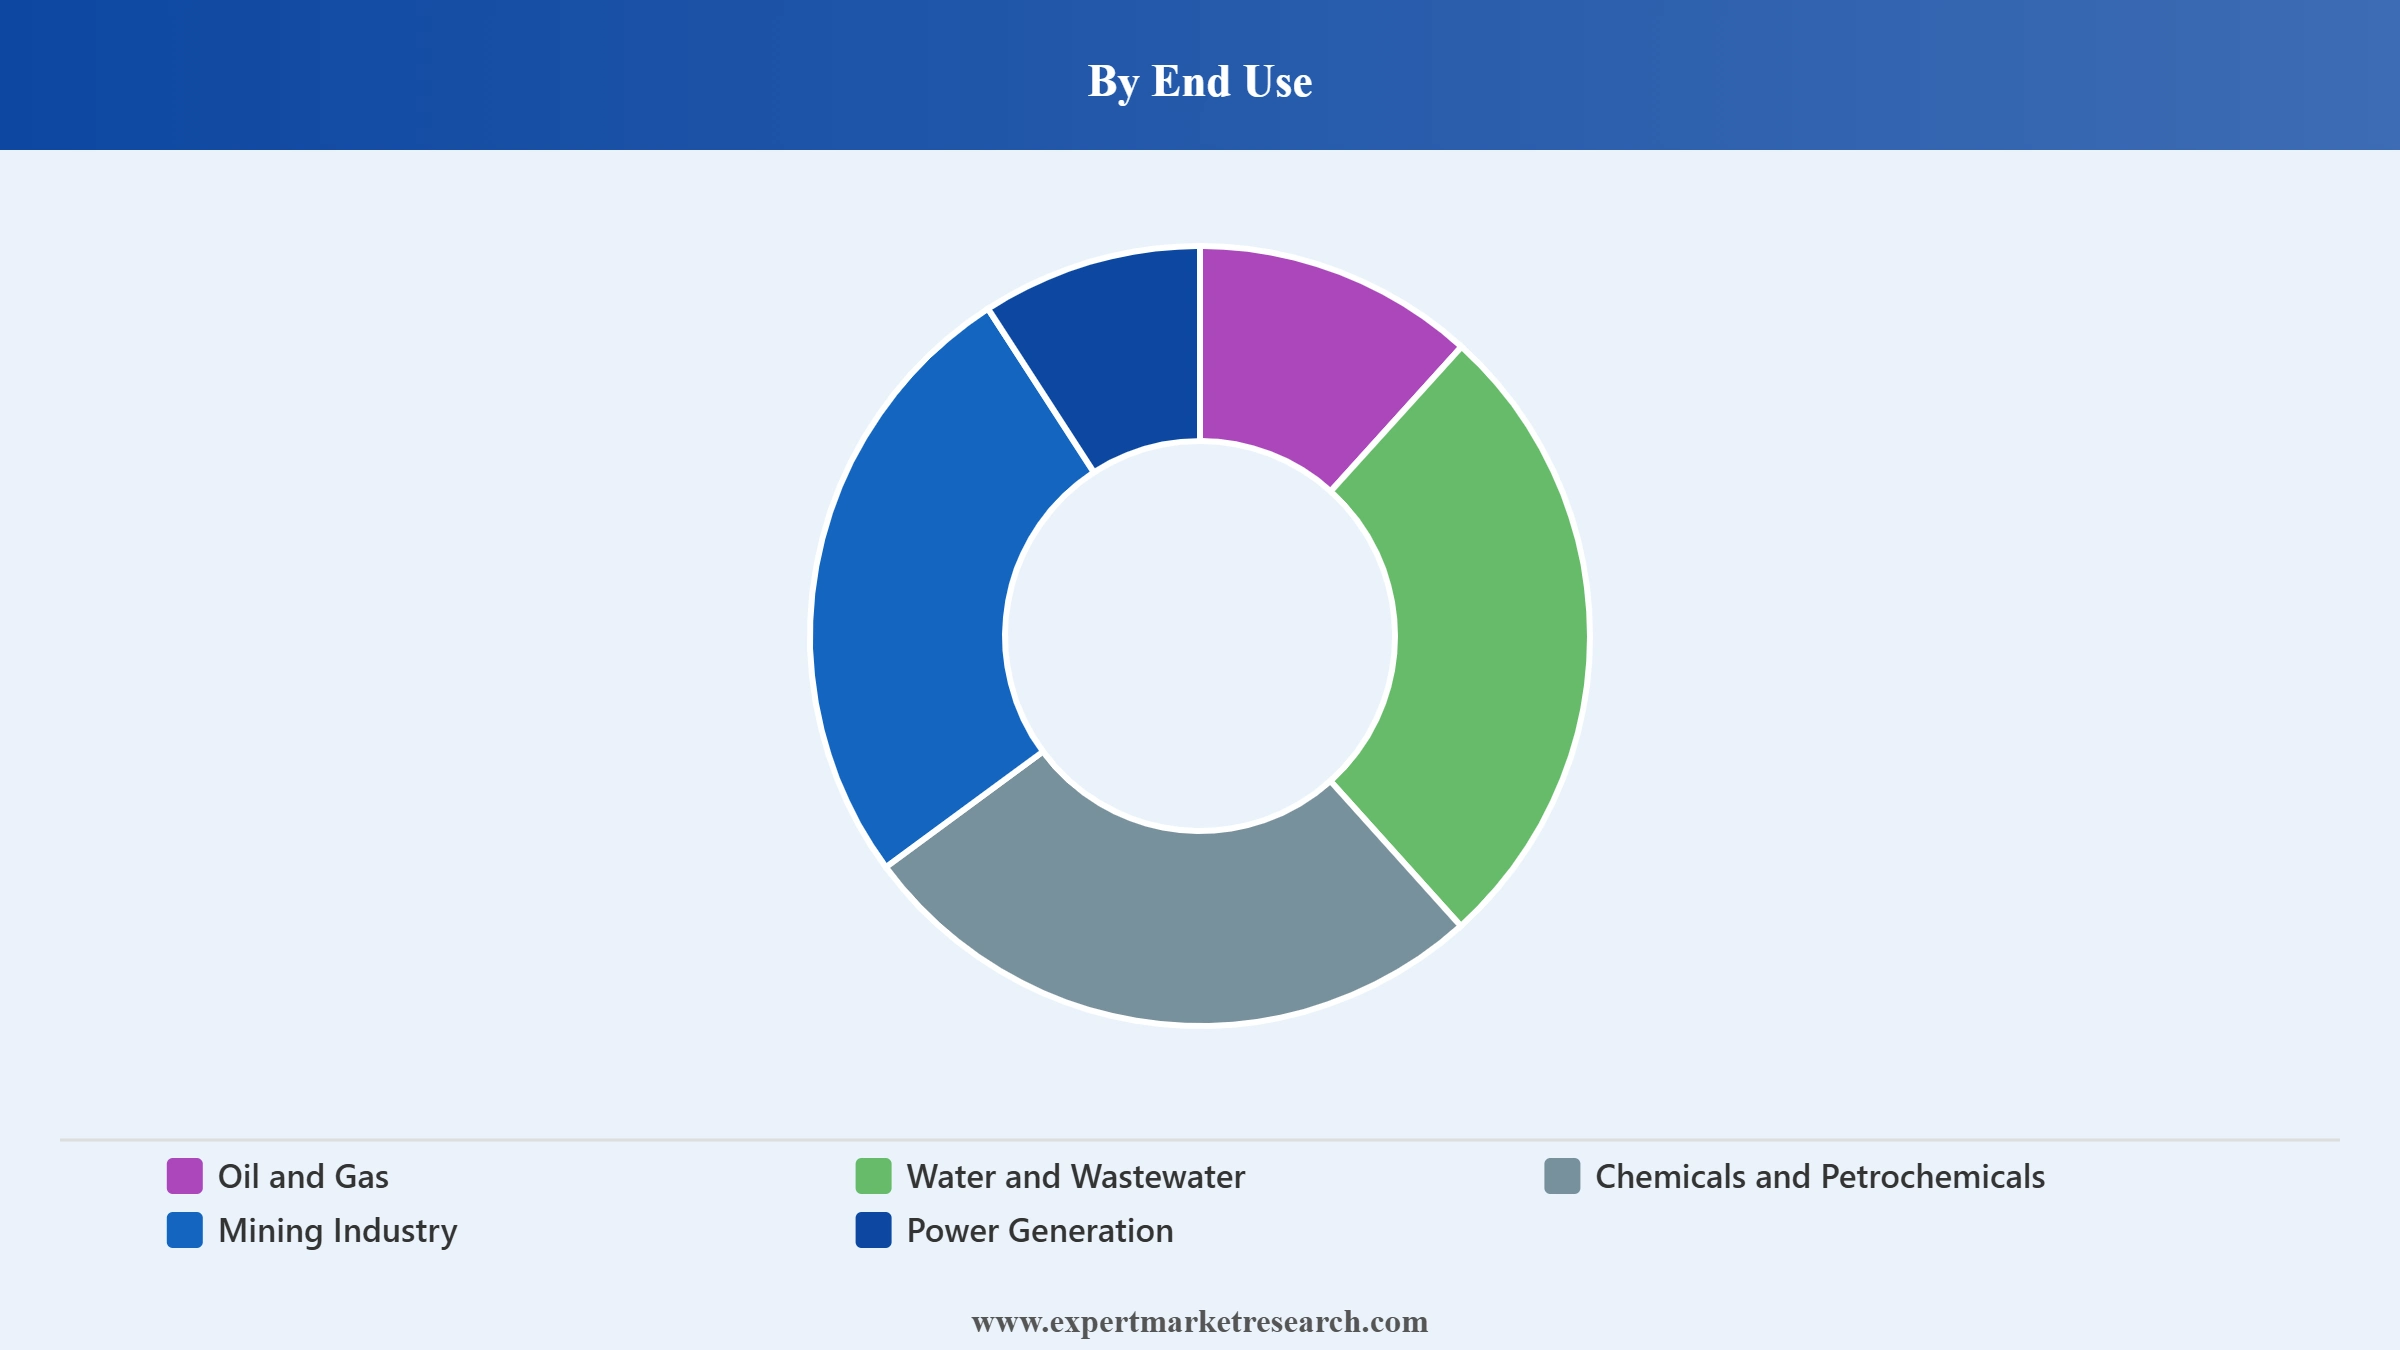
Key Insight: Water and Wastewater accounts for the largest share of the market, reinforced by Grundfos' August 2025 completion of its acquisition of Newterra, a modular water treatment technology manufacturer, broadening the addressable scope of water-sector pump contracts. Power Generation is growing steadily, illustrated by KSB's March 2026 record order for nuclear reactor coolant pumps in Germany and ANDRITZ's April 2026 pumped-storage contract with Electricite de France. Mining Industry demand is reinforced by Weir Group's June 2026 order from Lloyds Metals and Energy alongside its new grinding circuit pump technology. Oil and Gas continues to represent substantial demand tied to upstream and midstream fluid transfer applications. Chemicals and Petrochemicals serves corrosive and high-pressure fluid handling requirements across processing plants. Others encompasses smaller-volume end-use categories including agriculture and food processing applications, sectors that typically require hygienic, corrosion-resistant pump designs distinct from the heavier-duty equipment specified across industrial and mining applications.
Market Breakup by Country
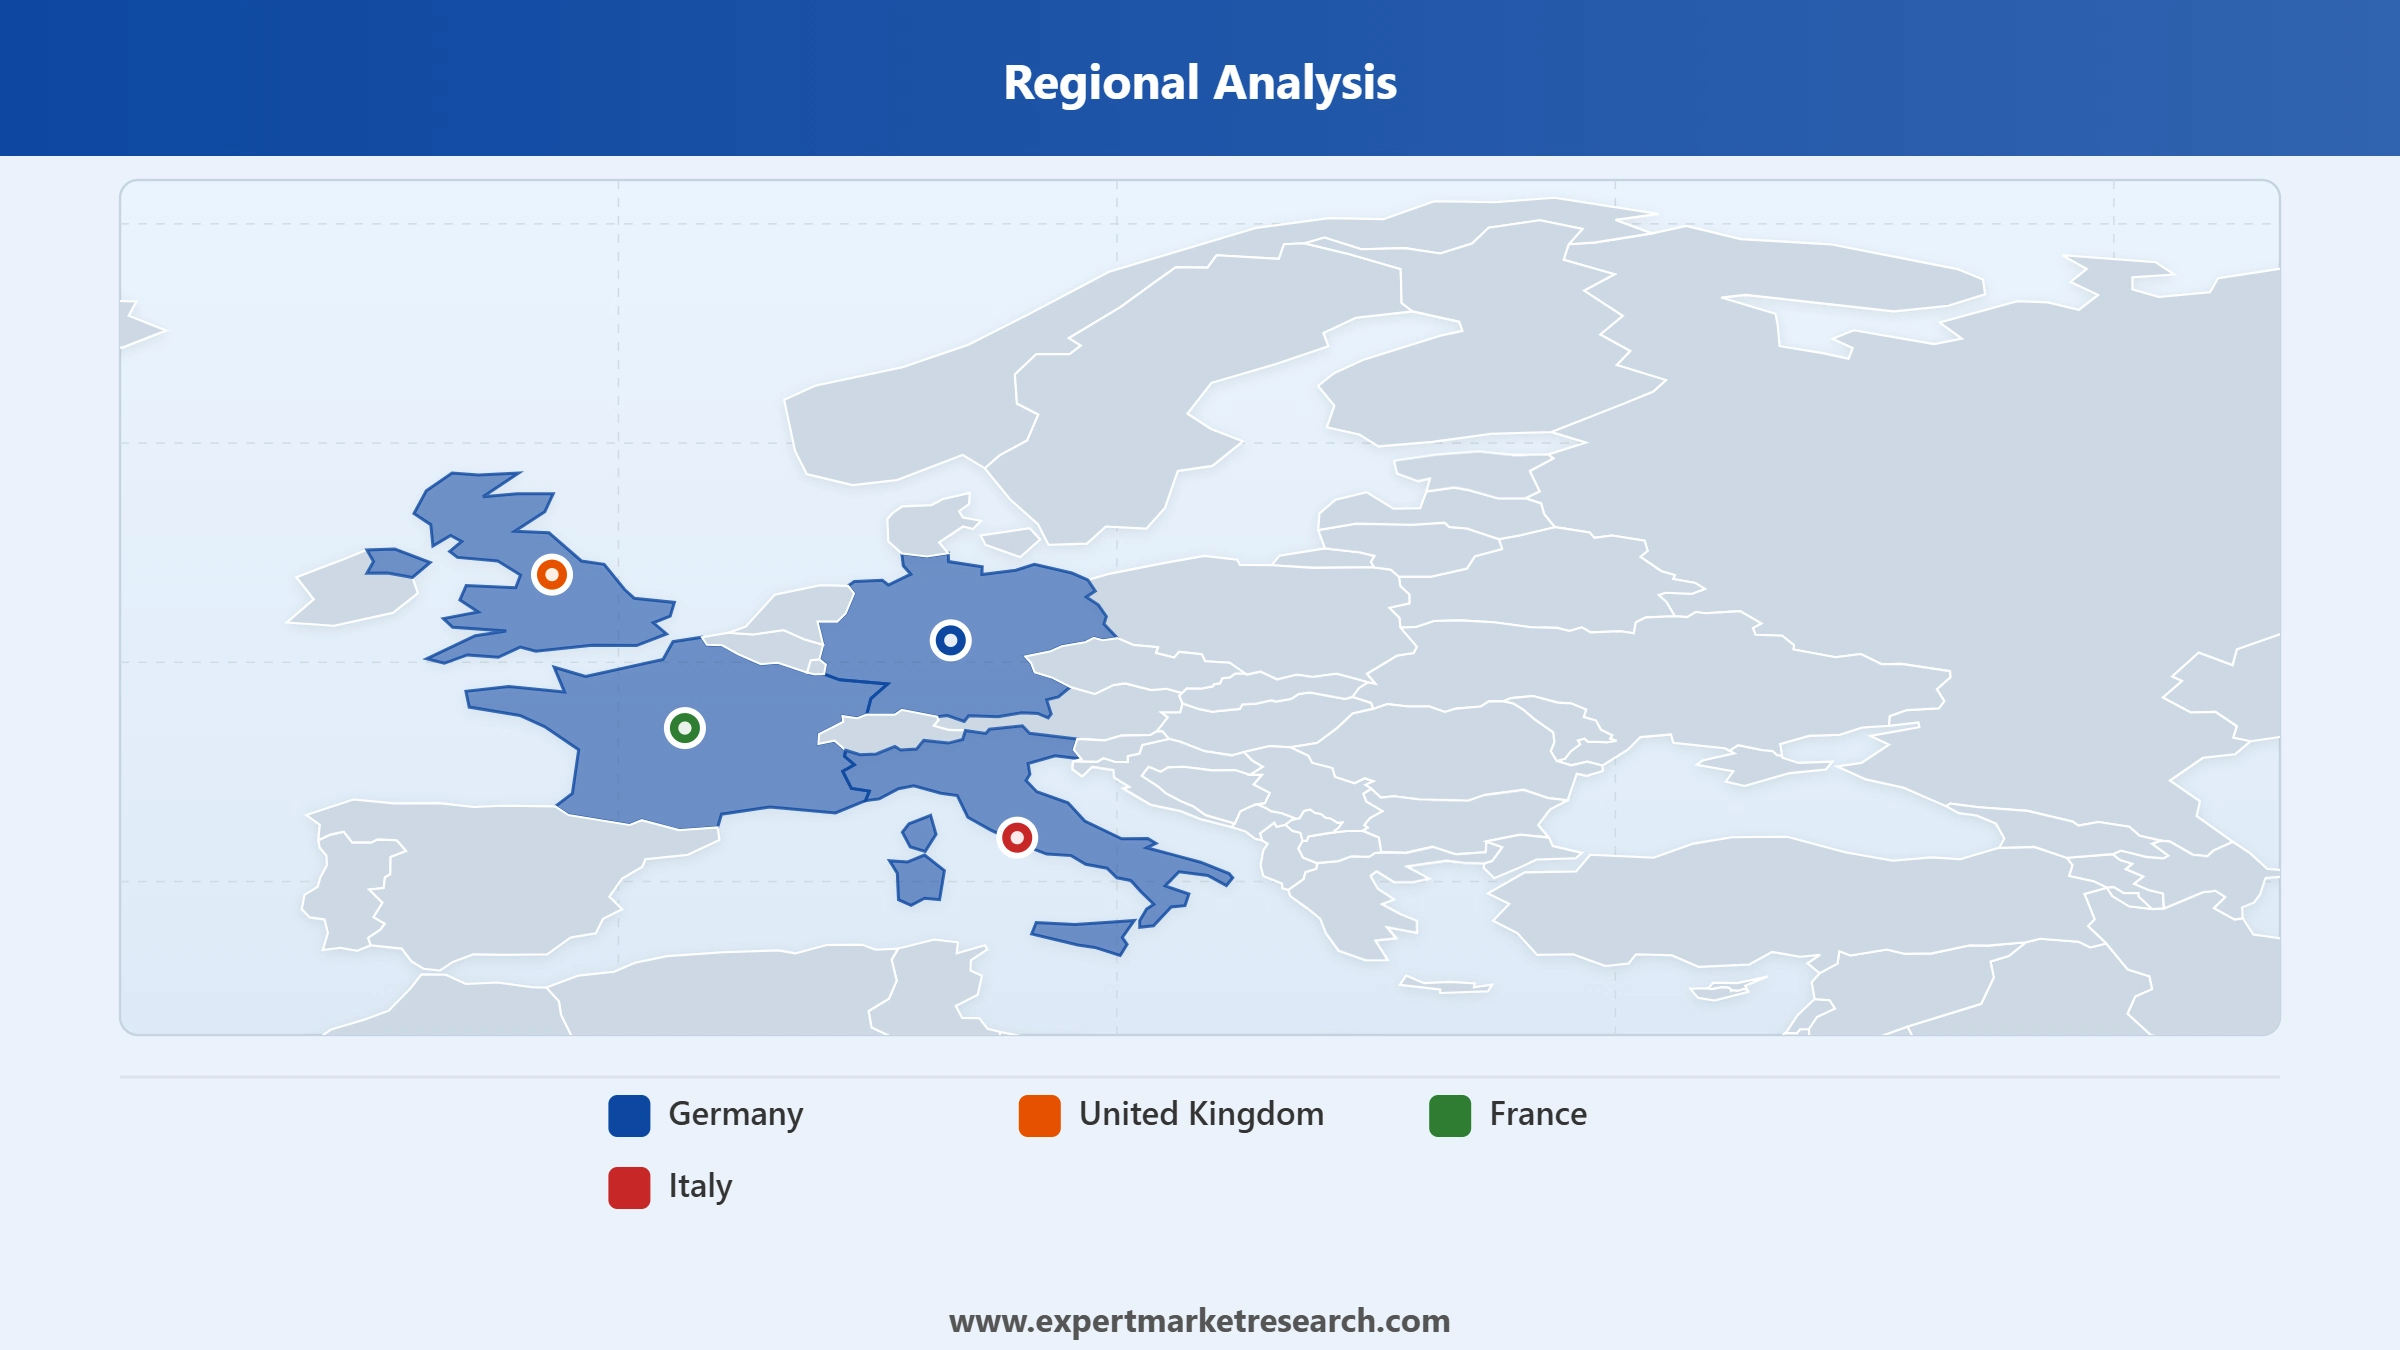
Key Insight: Germany accounts for the largest share of the market, anchored by its extensive industrial and chemical processing infrastructure and reinforced by KSB's March 2026 record nuclear pump order manufactured at its Frankenthal facility. United Kingdom is emerging as a key growth market at an estimated CAGR of 3.40%, supported by rising water infrastructure renewal and offshore energy project investment. France continues to represent substantial demand, illustrated by ANDRITZ's April 2026 pumped-storage pump turbine contract with Electricite de France in the Jura region. Italy serves a well-established manufacturing base, illustrated by EBARA Pumps Europe's July 2026 price adjustment across its Italian-produced stainless steel and cast iron pump ranges. Others captures smaller national markets including Spain, the Netherlands, and Nordic countries, where demand remains concentrated around municipal water infrastructure renewal and smaller-scale industrial process applications rather than large export-oriented manufacturing capacity.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By type, centrifugal pumps leads the market while positive displacement pumps grows fastest given mining-sector demand
Centrifugal Pumps continues to account for the largest share of the market, reflecting sustained deployment across water supply, wastewater, and general industrial fluid transfer applications, illustrated by KSB's January 2026 launch of its next-generation Omega 2 axially split volute casing pump series for waterworks and district heating applications. Established centrifugal pump suppliers keep winning repeat specification business, since utilities and industrial operators rarely deviate from proven pump ranges once maintenance and spares relationships are established, a loyalty that continues to favour incumbent suppliers over new market entrants regardless of headline pricing differences between competing ranges.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Positive Displacement Pumps is growing at a fast pace across the europe pumps market at a projected CAGR of 3.10%, illustrated by Weir Group's June 2026 launch of new grinding circuit pump technology engineered for abrasive, high-viscosity slurry handling in mineral processing applications, technology designed specifically to reduce both energy and water consumption per tonne of ore processed across European mining operations.
By end use, water and wastewater leads the market while power generation grows at a fast pace given nuclear and hydropower expansion
Water and Wastewater continues to account for the largest share of the market, reinforced by Grundfos' August 2025 completion of its acquisition of Newterra, broadening the addressable scope of integrated water treatment and pumping contracts. Sulzer added further momentum to the segment in early 2026, launching a dedicated Water Treatment Center of Excellence that consolidates several of its water treatment brands and underpinned a new five-year framework agreement with Veolia covering pumps, mixers, and turbocompressors, positioning Sulzer as a preferred equipment partner across Veolia's European water and wastewater treatment portfolio for the duration of the agreement.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Power Generation is growing at a fast pace, illustrated by KSB's March 2026 record order for nuclear reactor coolant pumps in Germany and ANDRITZ's April 2026 pumped-storage pump turbine contract with Electricite de France, as utilities expand both nuclear and hydropower grid-balancing capacity to accommodate rising shares of intermittent renewable generation on national electricity grids across the region.
Mining Industry demand remains substantial, reinforced by Weir Group's June 2026 order from Lloyds Metals and Energy alongside its new grinding circuit pump technology launch. Oil and Gas continues to serve upstream and midstream fluid transfer requirements across the sector. Chemicals and Petrochemicals supports corrosive and high-pressure fluid handling across processing plants. Others covers smaller-volume applications including agriculture and food processing, categories that typically specify smaller, lower-pressure pump variants sourced from the same manufacturers serving the market's larger industrial segments.
Germany commands the largest share of the market through its extensive industrial and nuclear-grade manufacturing base
Germany holds the largest share of the Europe pumps market, anchored by its extensive chemical processing and industrial infrastructure and reinforced by KSB's March 2026 record nuclear reactor coolant pump order manufactured at its Frankenthal facility.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
United Kingdom is emerging as the fastest-growing market at an estimated CAGR of 3.40%, supported by rising water infrastructure renewal and offshore energy project investment. France maintains a substantial market position, with ANDRITZ's April 2026 pumped-storage pump turbine contract for Electricite de France underscoring the country's continued hydropower infrastructure investment. Italy serves a well-established manufacturing base, illustrated by EBARA Pumps Europe's July 2026 price adjustment across its Italian-produced pump ranges. Others, including Spain, the Netherlands, and Nordic countries, continues to serve distinct national infrastructure and industrial demand patterns.
The industry is fragmented, with europe pumps market companies ranging from diversified industrial conglomerates spanning multiple engineering sectors to specialist pump manufacturers competing across type, end use, and country segments. Established players operate across the full pump value chain, from design and manufacturing through installation and aftermarket service for industrial, municipal, and utility customers.
Competitive dynamics among europe pumps players are increasingly shaped by the scale of record-value contract wins, the breadth of nuclear and hydropower engineering certification, and the depth of aftermarket service networks. Manufacturers are investing in application-specific pump engineering, adjacent water treatment capability, and large-project execution capacity to secure long-term relationships with utility and industrial customers.
Founded in 1953 and headquartered in Tulsa, United States, with significant European manufacturing and engineering presence, Ruhrpumpen designs and manufactures centrifugal pumps for oil and gas, power generation, and industrial applications. The company maintains manufacturing facilities and service centres across multiple European countries serving refinery, petrochemical, and utility customers. Ruhrpumpen's API-certified engineering heritage differentiates its offering from suppliers focused primarily on general industrial applications.
Founded in 1852 and headquartered in Graz, Austria, ANDRITZ is a diversified technology group supplying pump turbines and equipment for hydropower, pulp and paper, and industrial separation applications. In April 2026, the company secured a contract from Electricite de France to supply a pump turbine for the Vouglans-Saut-Mortier pumped storage project in the French Jura region. ANDRITZ's diversified engineering scale across hydropower, metals, and separation technology differentiates its offering from pump-only specialists.
Founded in 1871 and headquartered in Glasgow, United Kingdom, Weir Group is a global mining technology leader supplying slurry pumps and mineral processing equipment. In June 2026, the company secured a significant pumps order from Lloyds Metals and Energy for an iron ore project while separately launching new grinding circuit pump technology designed to reduce energy and water use. Weir's mining-sector specialisation differentiates its offering from generalist industrial pump manufacturers.
Founded in 1945 and headquartered in Bjerringbro, Denmark, Grundfos manufactures circulator, submersible, and centrifugal pumps for residential, commercial, and industrial applications. In August 2025, the company completed its acquisition of Newterra, a manufacturer of modular water treatment solutions, broadening its addressable project scope. Grundfos' expanding water treatment capability differentiates its offering from pump-only competitors.
Other key players in the Europe pumps market include EDUR-Pumpenfabrik Eduard Redlien GmbH & Co. KG, Dover Corporation, KSB Limited, ZUWA-Zumpe GmbH, Flowserve Corporation, and Ebara Corporation, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Europe pumps market trends 2026 report. Discover regional growth patterns, type and end use trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 8.14 Billion.
The market is projected to grow at a CAGR of 2.60% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach USD 10.52 Billion by 2035.
Pumps contain a moving component that displaces air, reducing the pressure and producing a partial vacuum. This facilitates the movement of air or fluid into the area of low pressure.
Centrifugal pumps are designed for high-flow applications and are more efficient compared to pneumatically driven pumps.
Securing record-scale nuclear and hydropower contracts, acquiring adjacent water treatment capability to broaden project scope, and developing application-specific mining pump technology to capture premium pricing.
Key trends aiding market expansion include an expanding demand for water treatment facilities, a demand for critical minerals, and the transition toward renewable power generation.
Major countries in the market are Germany, the United Kingdom, France, Italy, and others.
The common types of pumps are centrifugal pumps and positive displacement pumps.
The key players in the market include Ruhrpumpen, Inc., EDUR-Pumpenfabrik Eduard Redlien GmbH & Co. KG, ANDRITZ AG, The Weir Group PLC, Dover Corporation, Grundfos Holding A/S, KSB Limited, ZUWA-Zumpe GmbH, Flowserve Corporation, and Ebara Corporation, among others.
Manufacturers face intense price competition amid raw material and energy input cost pressure, the technical complexity of securing nuclear and hydropower certification, and long project lead times for record-scale utility contracts.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




