

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
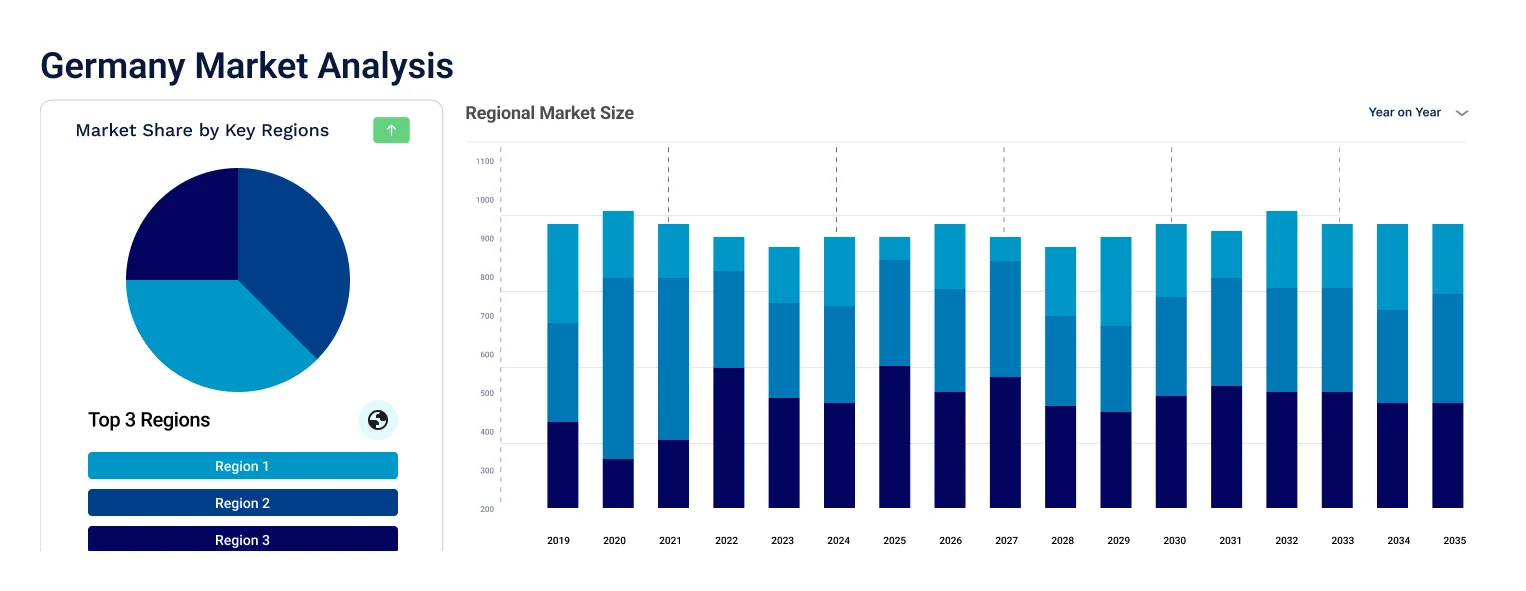
The Germany automotive parts die casting market attained a value of USD 4.96 Billion in 2025 and is projected to expand at a CAGR of 4.20% through 2035. The market is further expected to achieve USD 7.48 Billion by 2035. The United Kingdom's 29.0 million-household base creates a substantial replacement and upgrade pool, while energy labelling, repairability requirements and connected-appliance innovation are shifting competition from basic product availability towards lifetime efficiency, functionality, service and integrated kitchen solutions.
The market is being reshaped by tighter energy-efficiency and product-information requirements. UK standards include key kitchen equipment such as dishwashers, domestic ovens, hobs and range hoods, refrigerating appliances and household electrical equipment. The updated guidance issued by the government in April 2026 even included repairability information in some labeling systems, thereby increasing the significance of durability and after-sales service. In the high-end market, manufacturers are focusing more on built-in technology, artificial intelligence, smart controls and energy management systems. Samsung's April 2026 kitchen portfolio, for example, included an AI-enabled dishwasher, integrated extractor induction hob and new refrigerator technologies. Meanwhile, retailers such as Currys are expanding omnichannel, installation, repair and business-financing services, broadening the commercial ecosystem around appliance purchases, thereby boosting the Germany automotive parts die casting market value.
Connected kitchen appliances are evolving beyond basic remote control through the integration of AI, food recognition, predictive functions, and connected-home ecosystems. Samsung’s 2026 Bespoke AI Refrigerator Family Hub, for example, uses AI Vision to recognise fresh and packaged foods, monitor ingredients, recommend recipes, and help users manage food inventories. This technology also offers compatibility with Samsung’s SmartThings network, thus providing integrated control over all compatible devices in the household. This type of technology is especially relevant to the market of kitchen appliances in the United Kingdom as more companies are integrating connectivity into their product through useful functions in the home instead of offering connectivity as an independent element. It is also facilitating the use of appliances in meal planning, inventory management, energy efficiency, and reducing food wastage.
Pressure on household budgets can delay replacement purchases of higher-priced kitchen appliances. UK households spent £676.60 per week in FYE 2025, while housing, fuel and power accounted for £118.40, or 18% of total expenditure. Energy spending also increased 7% in real terms. Players can address this restraint by offering mid-range models, flexible financing, trade-in schemes, promotional bundles, and longer warranties. Highlighting energy-efficient appliances and their lower running costs can further improve value perception. Manufacturers can also introduce modular and upgradeable products, allowing consumers to access smart features without replacing entire appliances, while retailers can use seasonal promotions to reduce upfront purchasing barriers, thereby restricting the Germany automotive parts die casting market developments.
Compound Annual Growth Rate
4.2%
Value in USD Billion
2026-2035
Read more about this report - Request a Free Sample
Bosch Home Appliances introduced two Series 4 air-fryer models: a Double Drawer model with two 4.5-litre compartments and a Double Flex model with a 10-litre drawer that can operate as two cooking zones. Bosch states that the appliances can prepare complete meals up to 60% faster than an oven using a single appliance. The launch broadens the small-appliance opportunity around multi-function cooking and household time efficiency. It also intensifies competition between established appliance manufacturers in the expanding countertop cooking category.
Electrolux announced that premium brand AEG was introducing its first pasta hob as part of its IFA 2026 presentation. The launch forms part of AEG's broader focus on premium cooking experiences and differentiated kitchen design. The development illustrates how premium appliance suppliers are using specialised cooking functions to differentiate beyond conventional heating performance. Such products can support higher-value built-in appliance propositions.
Samsung unveiled new Bespoke AI kitchen appliances for European markets, including a single-door refrigerator/freezer, dishwasher and extractor induction hob. The products combine integrated design with adaptive functions, including AI Energy mode and automated dishwasher-cycle adjustment. Samsung's portfolio reinforces the shift towards connected and intelligent kitchen systems. It may increase competitive pressure on premium appliance suppliers to combine design, energy performance and software-enabled functionality, thus shaping new trends in the Germany automotive parts die casting, thus shaping new trends in the Germany automotive parts die casting market.
LG Electronics unveiled a new full built-in kitchen suite at EuroCucina 2026. The portfolio included a hood-integrated induction cooktop and ovens within a coordinated kitchen concept, reflecting LG's expansion of its built-in appliance proposition. The move strengthens competition in integrated kitchen solutions and increases the strategic importance of collaboration with kitchen designers and installation channels. It also creates opportunities for bundled appliance sales during kitchen renovation projects.
Connected and AI-enabled kitchen appliances are increasingly evolving into intelligent household assistants in the United Kingdom. In September 2026, Samsung announced a software update for selected Bespoke AI Family Hub refrigerators, expanding AI Vision through Google Gemini to recognise a wider range of fresh and packaged foods. The refrigerator can help users track ingredients and provide personalised meal suggestions through features such as “What’s for Today?”. This demonstrates how connected appliances are moving beyond remote monitoring towards AI-driven food management and personalised kitchen assistance. For UK manufacturers and retailers, such capabilities create opportunities to differentiate premium appliances through software, subscription-linked services, and connected ecosystems while encouraging longer-term customer engagement.
The distinction between individual appliances and complete kitchen systems is becoming less pronounced. In April 2026, LG Electronics presented a full built-in kitchen suite at EuroCucina, including a hood-integrated induction cooktop and ovens, positioning appliances around coordinated kitchen architecture rather than standalone functionality. Samsung also introduced an extractor induction hob in April 2026, combining cooking and ventilation within one product. This trend can increase opportunities for appliance manufacturers, kitchen designers and specialist retailers to sell bundled solutions and capture higher-value renovation projects, thus shaping the Germany automotive parts die casting market trends.
Regulation is increasing the commercial importance of lifecycle performance. UK ecodesign rules cover dishwashers, domestic ovens, hobs, range hoods and refrigerating appliances, while energy-information rules require appropriate labelling and product information. In April 2026, government guidance was updated to include repairability information within certain labelling arrangements. For manufacturers, this increases the importance of efficient components, serviceability and documentation; for retailers, it creates opportunities to differentiate through repair services, installation, recycling and extended customer relationships.
Appliance sales are becoming increasingly service-intensive, particularly for larger products requiring delivery, installation, recycling and repair. Currys reported in its 2025-26 interim results that 33.3% of UK&I big-box deliveries included installation, while 36.2% included recycling. The retailer also expanded its repair capabilities to kitchen appliances, coffee machines and vacuums. These services provide retailers with additional revenue opportunities while reducing friction around appliance replacement. For manufacturers, partnerships with retailers possessing established installation and repair networks can strengthen product availability and post-sale support.
Financing and leasing are emerging as additional mechanisms for appliance distribution, particularly for commercial customers. In 2026, Currys Business launched a leasing proposition allowing eligible UK businesses to spread payments for equipment including kitchen appliances. The offering is available to sectors including hospitality, offices and schools and can provide upgrade, return or keep options at the end of the term. For appliance suppliers, such arrangements can support higher-value purchases by reducing upfront expenditure, while commercial buyers gain greater flexibility in managing equipment replacement cycles.
The Expert Market Research’s report titled "Germany Automotive Parts Die Casting Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Raw Material
Key Insight: In Germany’s automotive parts die casting market, aluminium is gaining traction due to its lightweight characteristics and suitability for structural components, transmission housings, battery trays, and engine parts, supporting vehicle weight reduction. Magnesium is attracting interest for applications requiring further weight savings, particularly interior structures, seat frames, and instrument panel components. Zinc remains relevant for smaller, precision-engineered parts such as brackets, locks, connectors, and electronic housings because of its dimensional accuracy and surface finish. Other materials, including specialised aluminium alloys and hybrid compositions, are gaining attention as German automotive suppliers seek improved strength, thermal performance, recyclability, and corrosion resistance for increasingly complex components used in electric and conventional vehicles, thus boosting the Germany automotive parts die casting market growth.
Market Breakup by Production
Key Insight: In Germany’s automotive parts die casting market, pressure die-casting is gaining traction for high-volume production of engine, transmission, structural, and electric vehicle components, offering rapid cycle times and consistent dimensional accuracy. Vacuum die-casting is increasingly relevant for large structural and safety-critical components, as reduced porosity supports improved mechanical performance and weldability. Squeeze die-casting is being adopted for components requiring higher density and strength, particularly where heat treatment and demanding mechanical properties are important. Semi-solid die-casting is attracting interest for complex automotive parts requiring reduced shrinkage, improved surface quality, and near-net-shape production, supporting lightweight component development and material efficiency among German automotive suppliers.
Market Breakup by Application
Key Insight: Body assemblies are gaining traction as automakers increasingly use lightweight cast components for structural supports, cross-car beams, and other body-in-white applications. Engine parts continue to utilise die-cast components such as cylinder heads, engine blocks, and housings, particularly where dimensional consistency and thermal performance are required. Transmission parts are benefiting from demand for lightweight gearbox housings, covers, and related components that help reduce vehicle mass while maintaining structural integrity. Others, including battery housings, motor housings, brackets, and chassis components, are gaining importance with the expansion of electric vehicle production and the increasing use of large, integrated castings in German automotive manufacturing.
By material, aluminium is anticipated to dominate due to broad automotive lightweighting applications
Aluminium is expected to remain the dominant material in Germany’s automotive parts die-casting market, supported by its extensive use in lightweight structural, chassis, powertrain and e-mobility components. KSM Castings Group manufactures aluminium components across chassis, powertrain and e-mobility applications, while Nemak’s 2026 acquisition of GF Casting Solutions added complex aluminium and magnesium components, with around 80% of the acquired portfolio dedicated globally to e-mobility and structure and chassis applications. Such developments will thus boost the Germany automotive parts die casting market dynamics and trends in the long run.
Magnesium is emerging as a high-growth material in Germany’s automotive die-casting market as manufacturers pursue additional weight reduction for electrified and performance-oriented vehicles. Dynacast Germany combines magnesium die casting with aluminium and zinc capabilities, allowing components to be engineered around different weight and strength requirements. Magnesium is particularly relevant for applications where reducing component mass can improve vehicle efficiency while maintaining functional performance, making it an important material for next-generation lightweight automotive architectures.
By production, pressure die casting is expected to dominate because of scalable high-volume automotive manufacturing
Pressure die casting, particularly high-pressure die casting (HPDC), is expected to remain the leading production technology in Germany’s automotive parts die-casting market because of its suitability for complex, lightweight components and scalable automotive production. KSM Castings Group announced in January 2026 an investment in three new die-casting cells, reinforcing continued investment in modern die-casting capacity despite challenging market conditions. GF Casting Solutions’ former portfolio also brought additional HPDC capabilities to Nemak following the February 2026 acquisition, thereby bolstering the Germany automotive parts die casting demand.
Vacuum die casting is gaining momentum in Germany as automotive suppliers increasingly target structural and safety-relevant aluminium components requiring improved casting integrity. The technology removes air from the die cavity during filling, helping minimise porosity and enabling stronger castings that can undergo subsequent heat treatment. This is particularly relevant to Germany’s shift toward large, lightweight aluminium components for electric vehicles, where structural integration and weight reduction are becoming increasingly important design priorities.
By application, body assemblies are gaining prominence as lightweight structural content expands across vehicle platforms
Body assemblies, including structural and chassis components, represent the dominant application area in Germany’s automotive parts die-casting market as vehicle manufacturers increase the use of lightweight cast structures. Nemak reported that approximately 80% of the former GF Casting Solutions automotive portfolio was dedicated to e-mobility and structure/chassis applications. The acquisition therefore significantly strengthened capabilities serving the structural casting requirements of European vehicle manufacturers, including Germany’s established automotive production ecosystem, and thereby bolstering the demand of the Germany automotive parts die casting market.
Other applications are expanding rapidly as Germany’s die-casting industry moves beyond conventional engine and transmission components toward electric-mobility systems, thermal-management parts and integrated lightweight structures. KSM’s portfolio already spans chassis, powertrain and e-mobility applications, illustrating this diversification. The shift is particularly significant because EV architectures create new casting requirements around battery-related structures and vehicle integration, while reducing reliance on traditional combustion-engine components.
Read more about this report - Request a Free Sample
Baden-Württemberg dominates Germany’s automotive die-casting and vehicle manufacturing ecosystem
Germany’s automotive die-casting activity is concentrated around major automotive and engineering clusters rather than being evenly distributed nationally. Baden-Württemberg remains particularly significant because vehicle and automotive-parts manufacturing is the state’s largest industrial sector by turnover. In 2025, the sector generated EUR 125.7 billion in turnover and employed approximately 209,000 people, despite a challenging year for industrial demand. This creates a substantial customer base for aluminium, magnesium and precision die-cast components. Bavaria represents another major demand centre, with approximately 450,000 people directly or indirectly dependent on the vehicle and supplier industry, according to the Bavarian government, thereby directly boosting the Germany automotive parts die casting market regional growth.
North Rhine-Westphalia provides another important manufacturing ecosystem through its concentration of industrial suppliers, engineering companies and metal-processing capabilities. KSM operates German facilities in Hildesheim, Wuppertal, Radevormwald and Wernigerode, while Druckguss Westfalen operates in Geseke, illustrating the importance of Germany’s wider industrial belt for casting and component manufacturing. Lower Saxony remains strategically important because of Volkswagen's manufacturing footprint and associated supplier ecosystem. Overall, southern Germany represents a leading demand cluster, while western and northern industrial regions provide important production and supplier capacity. Regional opportunities will increasingly depend on proximity to EV programmes, structural-component development and OEM engineering centres.
The Germany automotive parts die casting market is becoming increasingly focused on technology depth, process integration and lightweight component development rather than simple casting capacity. Germany automotive parts die casting market players are investing in HPDC cells, automated machining, simulation and quality-control systems to reduce cycle times and improve component consistency. KSM’s investment in three new die-casting cells in 2026 demonstrates continued capital expenditure despite weak European automotive conditions.
Scale is also becoming important as Germany automotive parts die casting companies increasingly seek suppliers capable of supporting complex components across multiple markets. Nemak’s acquisition of GF Casting Solutions’ automotive business significantly expanded its technology portfolio and global production footprint, particularly in e-mobility and structural applications. Meanwhile, specialised suppliers such as Dynacast Germany compete through precision casting, multi-material capability, toolmaking and secondary operations.
Established in 2018 and headquartered in the United States, Form Technologies operates Dynacast Germany in Bräunlingen, providing zinc, magnesium, and aluminium die-casting solutions for automotive applications. Its German operations offer toolmaking, modelling, simulation, and secondary machining capabilities, supported by more than 50 multi-slide zinc die-casting machines alongside magnesium and aluminium casting equipment. These capabilities enable the production of complex, lightweight, and precision-engineered automotive components.
Established in 1802 and headquartered in Switzerland, Georg Fischer historically participated in the Germany automotive parts die casting market through its former GF Casting Solutions business, supplying lightweight aluminium and magnesium components for structural and e-mobility applications. Its automotive casting portfolio supported vehicle lightweighting and electrification requirements. However, GF transferred its automotive business to Nemak in February 2026, and therefore the company should now be considered a historical rather than current automotive casting player.
Established in 1947 and headquartered in Germany, KSM Castings Group participates in the Germany automotive parts die casting market by manufacturing aluminium cast components for chassis, powertrain, and e-mobility applications. As a subsidiary of CITIC Dicastal, the company offers high-pressure die casting capabilities supported by machines with clamping forces ranging from 400 to 3,200 tonnes. Its portfolio focuses on lightweight and complex components designed for conventional and electrified vehicle architectures.
Established in 1964 and headquartered in Germany, Druckguss Westfalen participates in the Germany automotive parts die casting market through its aluminium casting and component manufacturing capabilities for automotive and technical applications. The company complements die casting with machining, technical cleanliness, and leak-testing services. Its production facilities operate more than 28 die-casting machines with clamping forces ranging from 130 to 2,200 tonnes, supporting precision component production and integrated finishing requirements for automotive customers.
Other key players in the market include Protocast, Eisenmann Druckguss GmbH, Kopf Holding GmbH (Powercast), Kalmbach GmbH, EMKA Beschlagteile GmbH & Co. KG, Albert Handtmann Metallgusswerk GmbH & Co. KG, Laukötter GmbH, and Peter Mies GmbH (Miguss), among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Access the Germany automotive parts die casting market report to understand the latest industry developments, competitive strategies and technology opportunities shaping the sector. Explore Germany automotive parts die casting market trends 2026, emerging lightweighting applications, HPDC developments and supplier strategies. Download the sample to assess the Germany automotive parts die casting market forecast and identify opportunities across materials, production technologies and automotive applications.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 4.20% between 2026 and 2035.
Key strategies include adopting advanced die-casting technologies, investing in automation and lightweight alloys, developing components for electric vehicles, improving energy efficiency, strengthening supply-chain resilience, expanding recycling capabilities, enhancing precision and quality control, and forming strategic partnerships to support innovation and competitiveness.
The key trends fuelling the growth of the market include rising vehicle ownership and increasing demand for environment friendly automotive components due to rising efforts to increase carbon emissions.
The major materials include aluminium, zinc, and magnesium, among others.
The applications of automotive parts die castings include body assemblies, engine parts, and transmission parts, among others.
The various materials available in the market include aluminium, zinc, and magnesium, among others.
The major productions include pressure die-casting, vacuum die-casting, squeeze die-casting, and semi-solid die-casting.
The major players in the market are Form Technologies (Dynacast), Druckguss Westfalen GmbH & Co.KG, Georg Fischer Ltd, Protocast, Eisenmann Druckguss GmbH, Kopf Holding GmbH (Powercast), Kalmbach GmbH, EMKA Beschlagteile GmbH & Co. KG, KSM Castings Group GmbH, Albert Handtmann Metallgusswerk GmbH & Co. KG, Laukötter GmbH, and Peter Mies GmbH (Miguss), among others.
In 2025, the market reached an approximate value of USD 4.96 Billion.
The market is expected to witness sustained expansion and attain approximately USD 7.48 Billion by 2035.
Key challenges include high energy and raw material costs, stringent environmental regulations, skilled labour shortages, supply-chain disruptions, intense competition, rising production costs, technological investments, and the automotive industry’s transition towards electric vehicles, which is reshaping demand for conventional cast components.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Raw Material |
|
| Breakup by Production |
|
| Breakup by Application |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




