

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
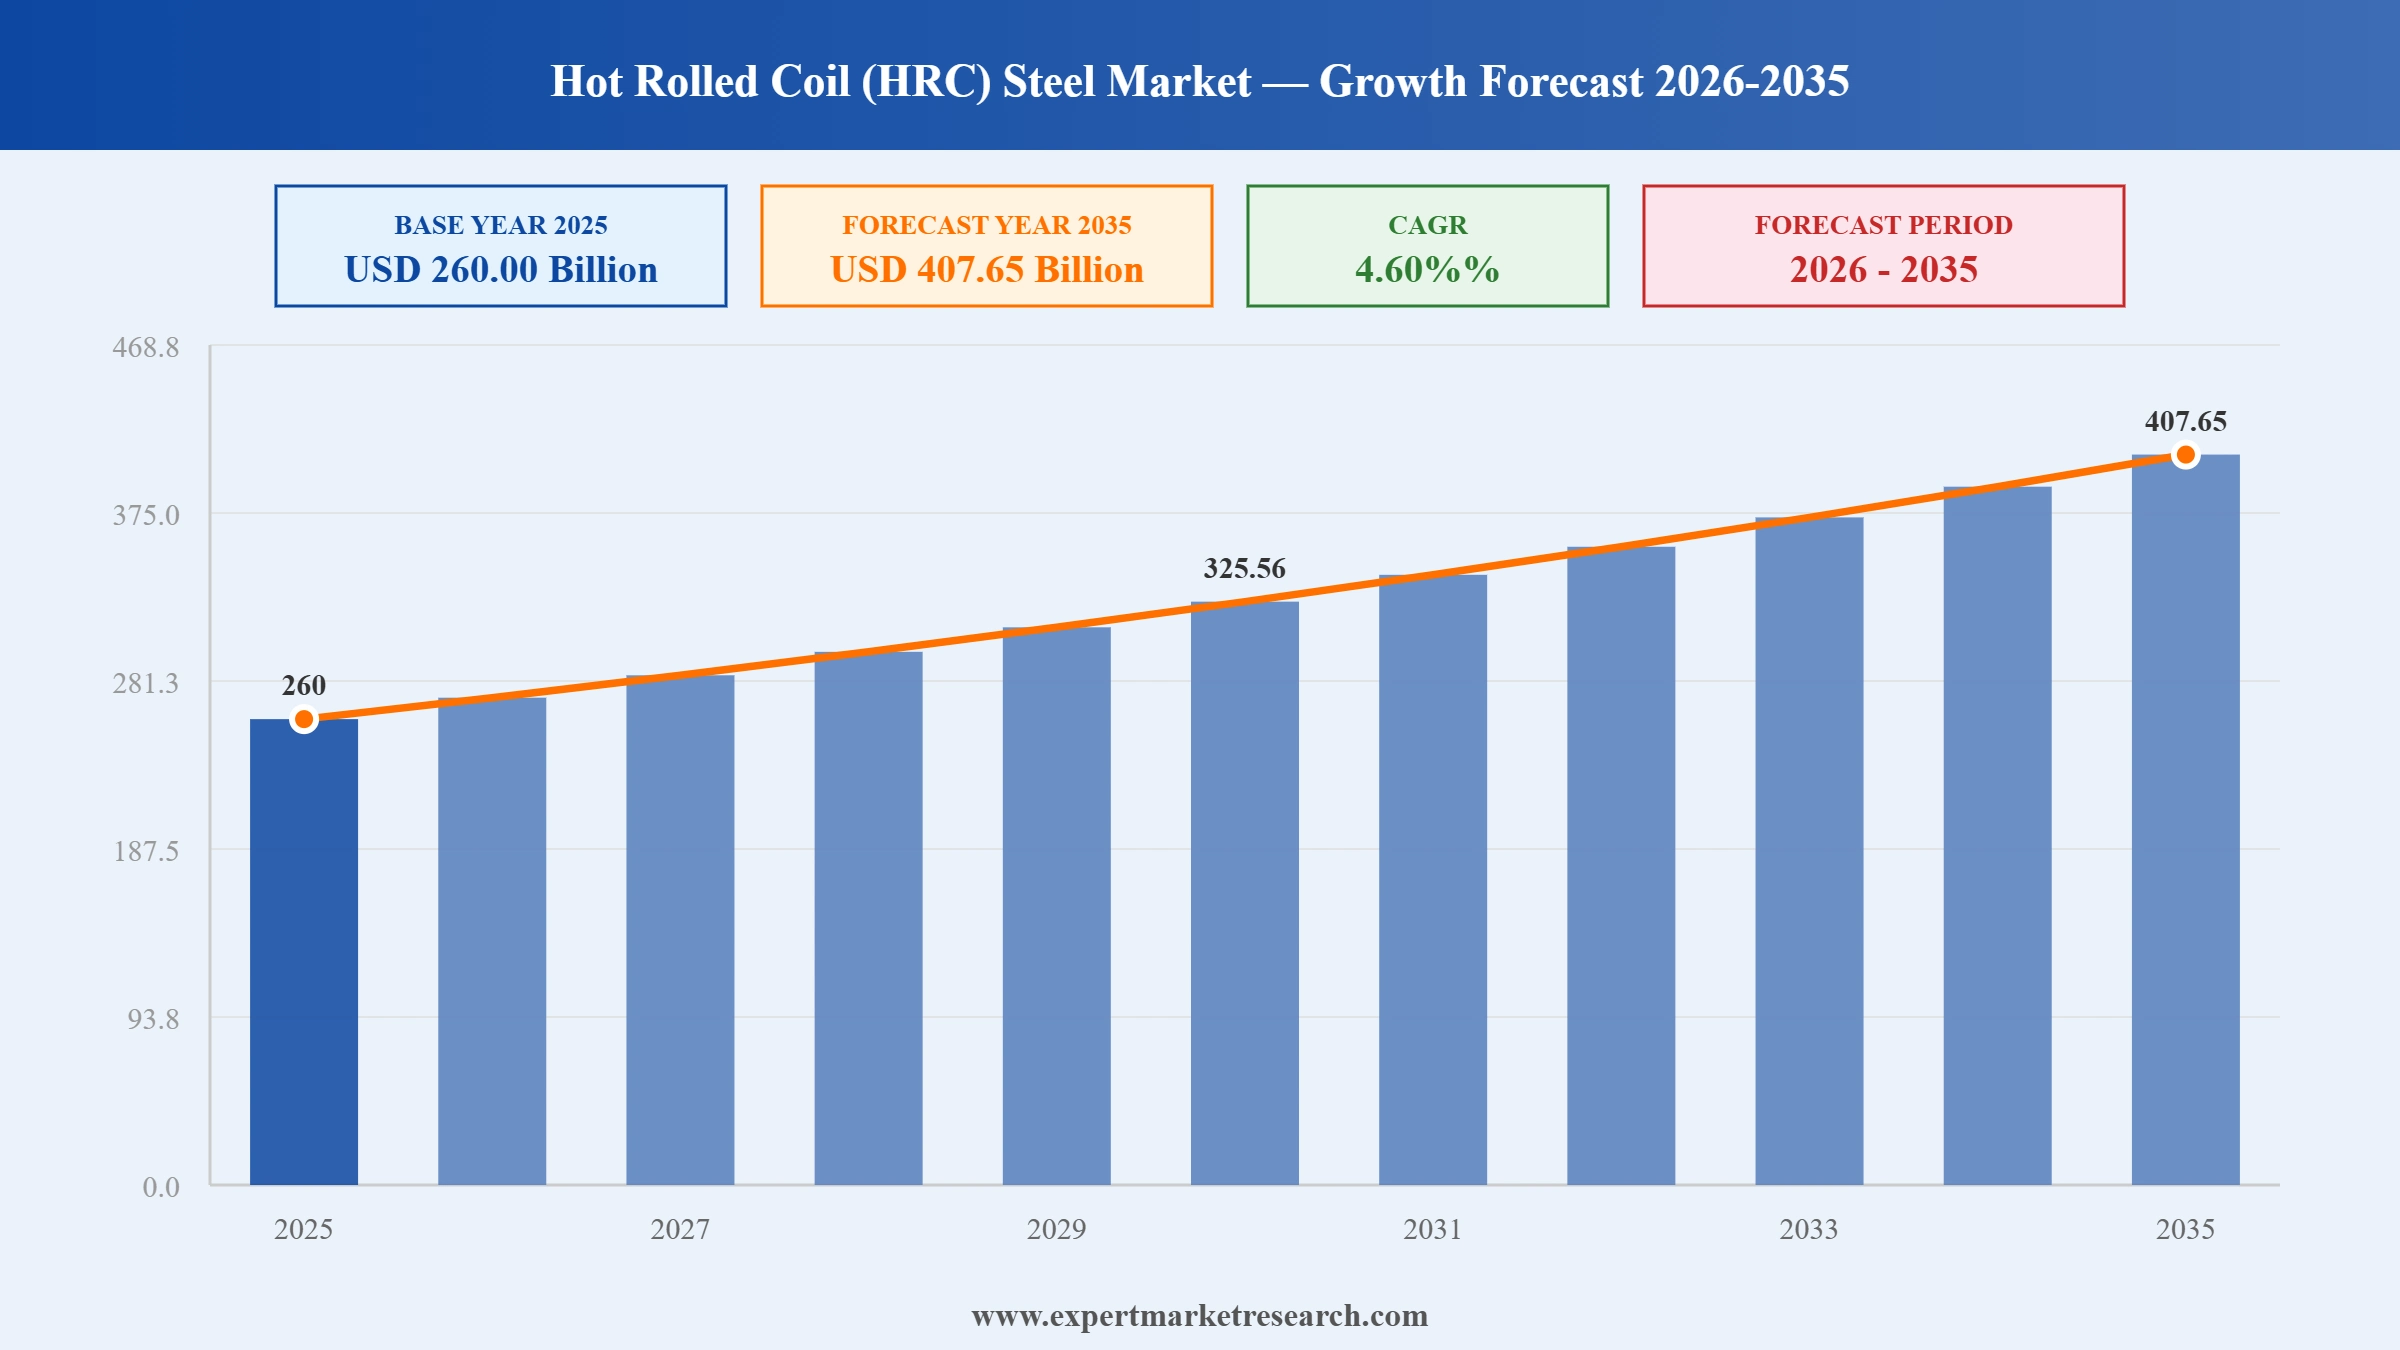
The hot rolled coil (HRC) steel market was valued at USD 260.00 Billion in 2025. The market is expected to grow at a CAGR of 4.60% during the forecast period of 2026-2035 to reach a value of USD 407.65 Billion by 2035. Sustained infrastructure and construction investment, recovering automotive production, and trade policy actions supporting domestic mill utilisation are the most significant structural drivers of this expansion.
The hot rolled coil (HRC) steel market analysis reflects a capital-intensive, cyclical industry anchored by a small group of large integrated and electric arc furnace producers supplying flat steel to construction, automotive, machinery, and energy customers worldwide. The World Steel Association reported in October 2025 that global crude steel production across its 70 reporting countries totalled 141.8 million tonnes in September 2025, with North America producing 8.8 million tonnes that month, underscoring the sheer production scale underpinning the global hot rolled coil supply chain even amid a year of generally softer output across most reporting regions.
Manufacturer strategy within the hot rolled coil steel market is increasingly shaped by decarbonisation commitments running alongside continued capacity investment. ArcelorMittal notified the German federal government in June 2025 that it could not proceed with a planned EUR 1.3 billion hydrogen-based direct reduction and electric arc furnace project, after determining construction could not begin by the contractual deadline given prevailing steel market and energy cost conditions, illustrating how regulatory and cost uncertainty is complicating capital allocation even among the market's largest integrated producers. Other manufacturers are proceeding regardless, investing in new hot rolling capacity, electric arc furnace conversions, and downstream coating lines to serve construction, automotive, and energy customers across multiple regions simultaneously.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
|
Hot Rolled Coil (HRC) Steel Market Report Summary |
Description |
Value |
|
Base Year |
USD Billion |
2025 |
|
Historical Period |
USD Billion |
2019-2025 |
|
Forecast Period |
USD Billion |
2026-2035 |
|
Market Size 2025 |
USD Billion |
260.00 |
|
Market Size 2035 |
USD Billion |
407.65 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
4.60% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
5.4% |
|
CAGR 2026-2035 - Market by Grade |
High Carbon Steel |
5.5% |
|
CAGR 2026-2035 - Market by Application |
Automotive |
5.1% |
|
2025 Market Share by Region |
Europe |
13.2% |
The hot rolled coil (HRC) steel market is being reshaped by trade policy actions supporting domestic mill pricing, capacity optimisation among integrated producers, and continued capital investment in new rolling and coating lines across North America and Asia. Decarbonisation commitments and large-scale acquisitions are further reshaping the competitive landscape.
The OECD's Steel Outlook 2026, published in June 2026, reported that global steelmaking capacity reached a record 2,445 million tonnes in 2025, with excess capacity climbing to 640 million tonnes and projected to reach 745 million tonnes by 2028, mostly from non-OECD economies. Buyers and traders across the hot rolled coil (HRC) steel market can use this capacity data to time procurement and negotiate contracts during periods of persistent oversupply.
The same OECD Steel Outlook 2026, published in June 2026, reported that Brazil, Canada, India, Mexico, and the United States had all raised tariffs on basic steel products in response to persistent global overcapacity and distorted competition from subsidised non-OECD producers. Domestic producers across the hot rolled coil (HRC) steel market can leverage this coordinated trade protection to plan capacity investments with greater confidence in near-term pricing.
China Baowu Steel Group and Rio Tinto announced in June 2026 that they had completed industrial scale pelletisation and shaft furnace trials using Rio Tinto's Pilbara Blend iron ore at Baowu's Zhanjiang Steel operations, producing direct reduced iron converted into steel in a basic oxygen furnace. Other integrated producers across the hot rolled coil (HRC) steel market can draw on these results to accelerate their own low-carbon ironmaking roadmaps.
Tata Steel Limited inaugurated its second-largest steel plant in India in March 2026, a scrap-based Electric Arc Furnace facility at Ludhiana, Punjab built at an investment of Rs 3,200 crore, India's first to combine green energy-based steelmaking with electric arc furnace technology at this scale. Regional fabricators and distributors can tap this new capacity to shorten lead times across northern India.
Cross-border acquisitions in the steel sector are increasingly being approved subject to binding domestic investment commitments rather than being blocked outright, letting foreign capital reach ageing mill networks. Nippon Steel Corporation completed its acquisition of United States Steel Corporation in June 2025 under a National Security Agreement with the U.S. Treasury including a government golden share, committing Nippon Steel to USD 11 billion in new investment by 2028, including a new hot rolling mill at Mon Valley Works, Pennsylvania.
Indian steelmakers across the hot rolled coil (HRC) steel market are completing multi-year capacity expansions that combine new blast furnace capacity with downstream cold rolling investment to serve rising domestic construction and automotive demand. Tata Steel Limited inaugurated the Phase II expansion of its Kalinganagar plant in Odisha in May 2025, raising crude steel capacity from 3 to 8 million tonnes per annum through an investment of Rs 27,000 crore that included a new cold rolling mill and the largest blast furnace built in India to date.
International steelmakers across the hot rolled coil (HRC) steel market are increasingly pursuing joint ventures with domestic Indian partners to expand flat steel capacity rather than building wholly owned greenfield plants, sharing capital costs and local market access. JSW Steel and POSCO Holdings executed their definitive joint venture agreement in April 2026 for a 6 million tonne per annum integrated steel plant in Odisha, valued at approximately Rs 35,000 crore, marking POSCO's return to the state two decades after an earlier greenfield project there was abandoned.
Producers are investing in specialised downstream coating lines to convert base hot rolled coil into higher-value products for automotive, solar, and infrastructure applications rather than selling coil as a lower-margin commodity. ArcelorMittal Nippon Steel India commissioned a new auto-focused continuous galvanising line at its Hazira plant in Gujarat in July 2025, part of a Rs 8,500 crore downstream investment programme aimed at import substitution for automotive steel and expanding coated product capacity for domestic and export customers.
Domestic mills are reporting record shipment volumes as trade actions reduce import competition and backlogs build across sheet and plate product lines. Nucor Corporation reported a 13 percent year over year increase in sheet backlogs and an all-time production record at its Berkeley, South Carolina mill in September 2025 during its third-quarter earnings call in October 2025, while its new galvanizing line at the Crawfordsville, Indiana sheet mill processed its first coil, adding further coated capacity ahead of expected 2026 demand.
The Expert Market Research's report titled "Hot Rolled Coil (HRC) Steel Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
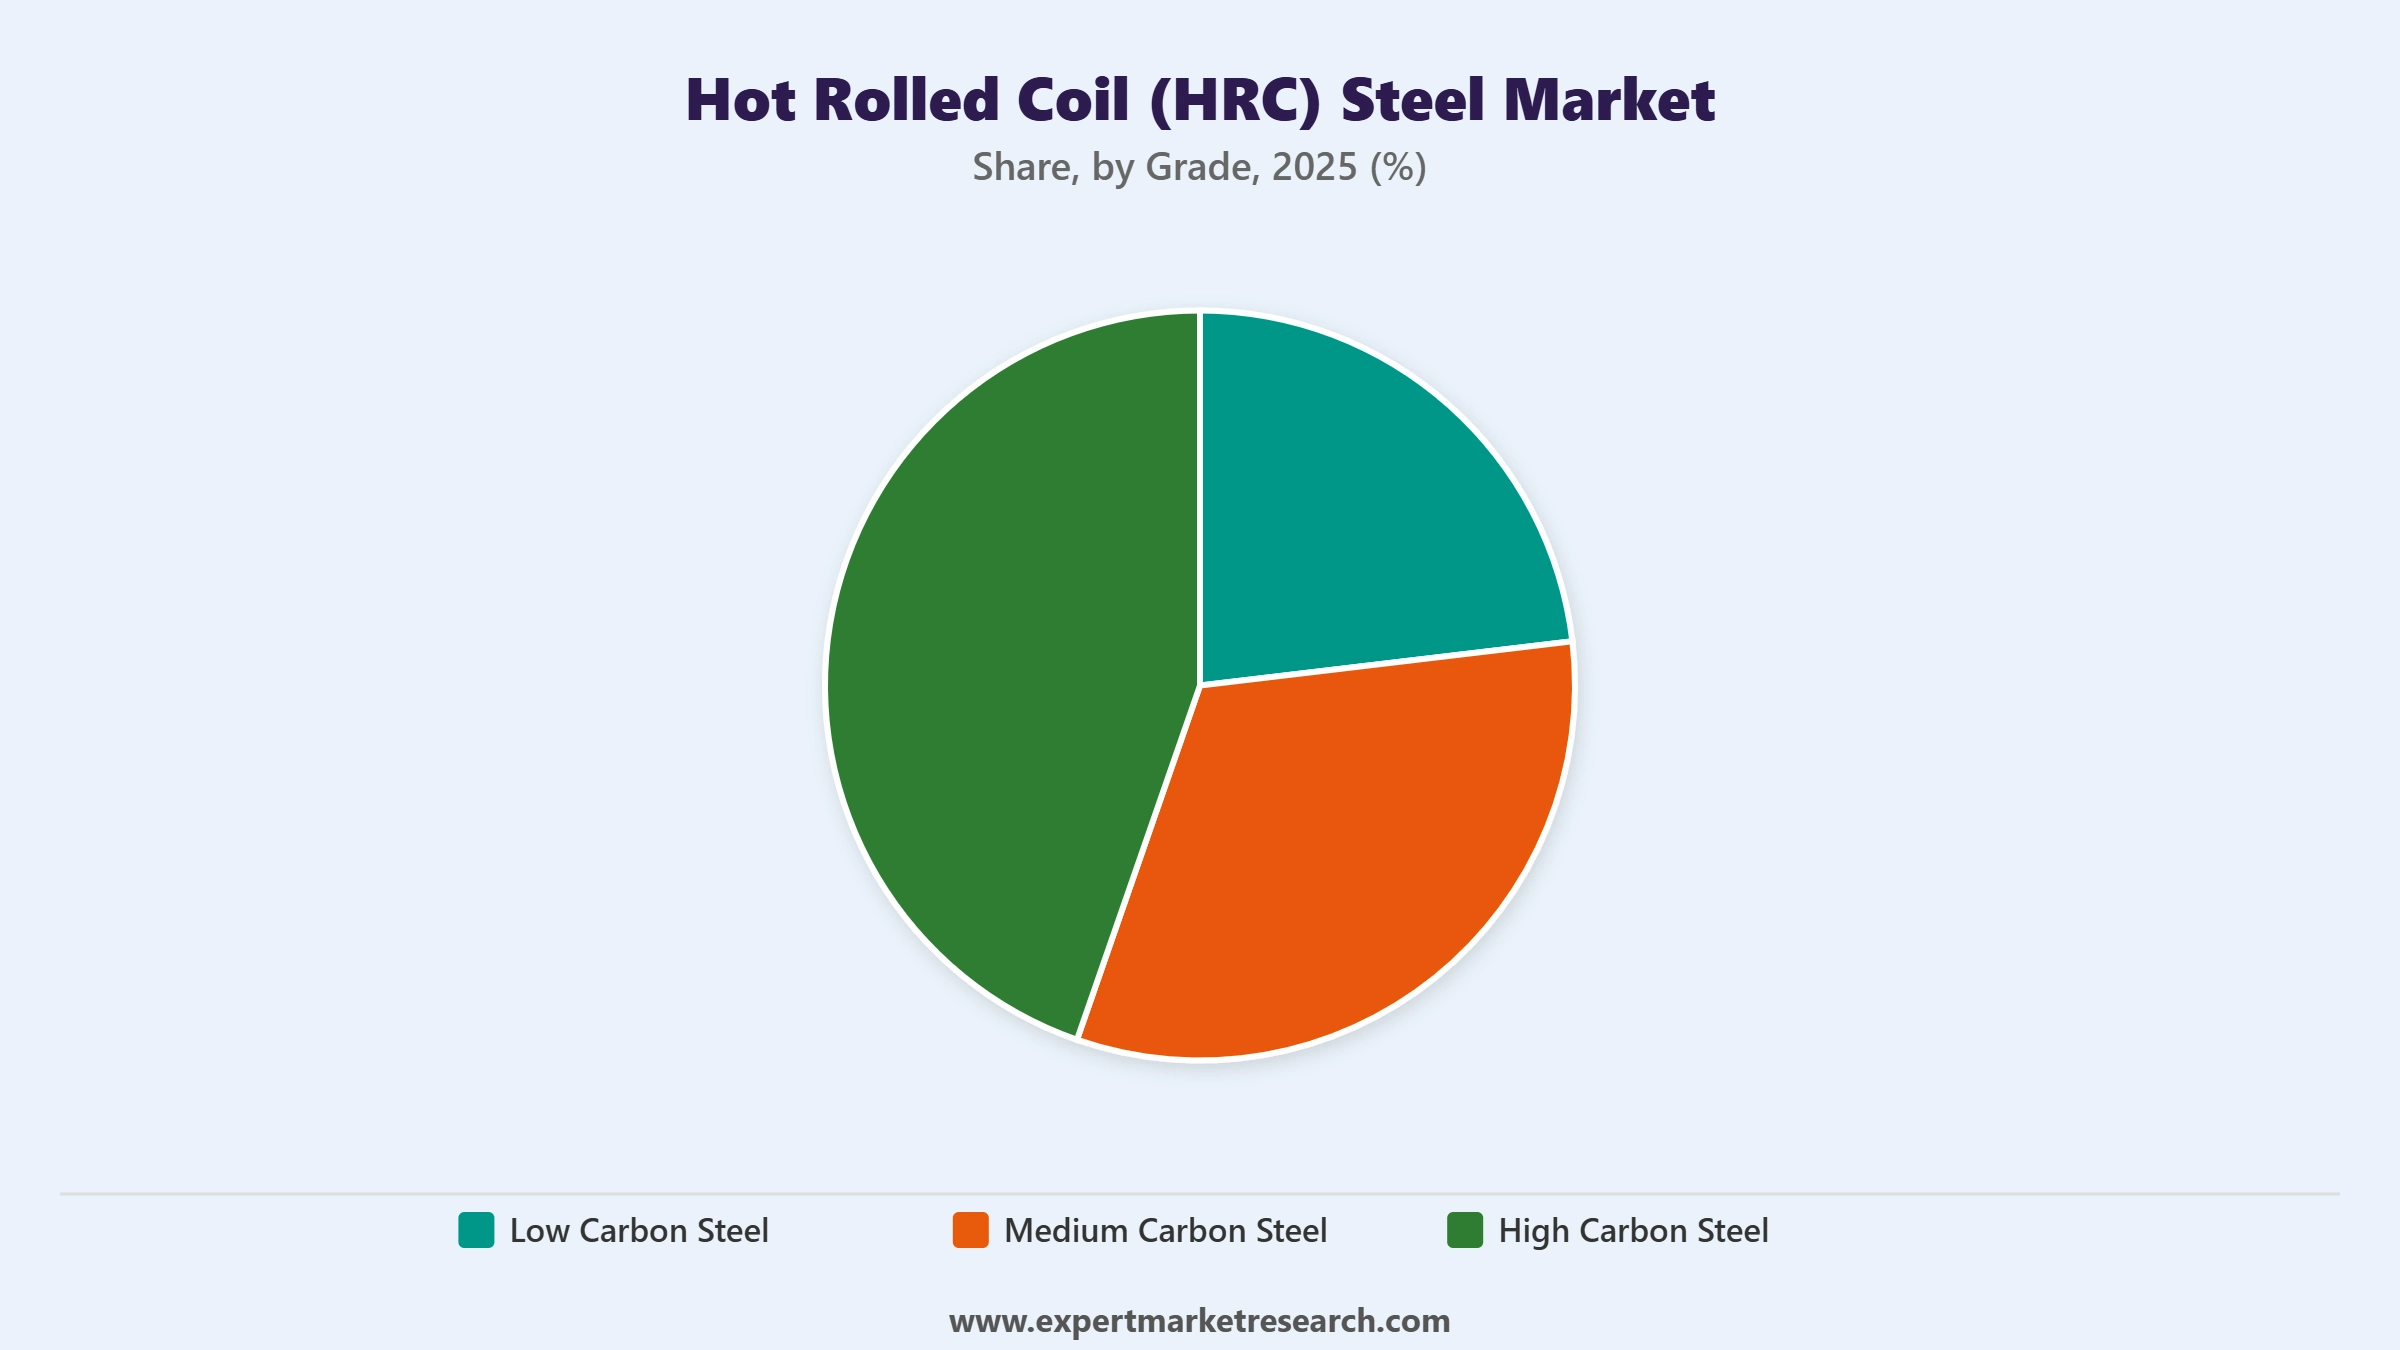
Market Breakup by Grade
Key Insight: Low carbon steel accounts for the largest share of the hot rolled coil market by grade, reflecting its widespread use in construction and general fabrication where extreme strength is not the primary specification. High carbon steel is the fastest-growing grade as automotive and machinery producers increasingly specify higher-strength coil for lightweighting and durability, supported by a steadily widening portfolio of commercially available advanced high-strength grades. Medium carbon steel continues to serve applications requiring a balance of strength and formability across general engineering uses.
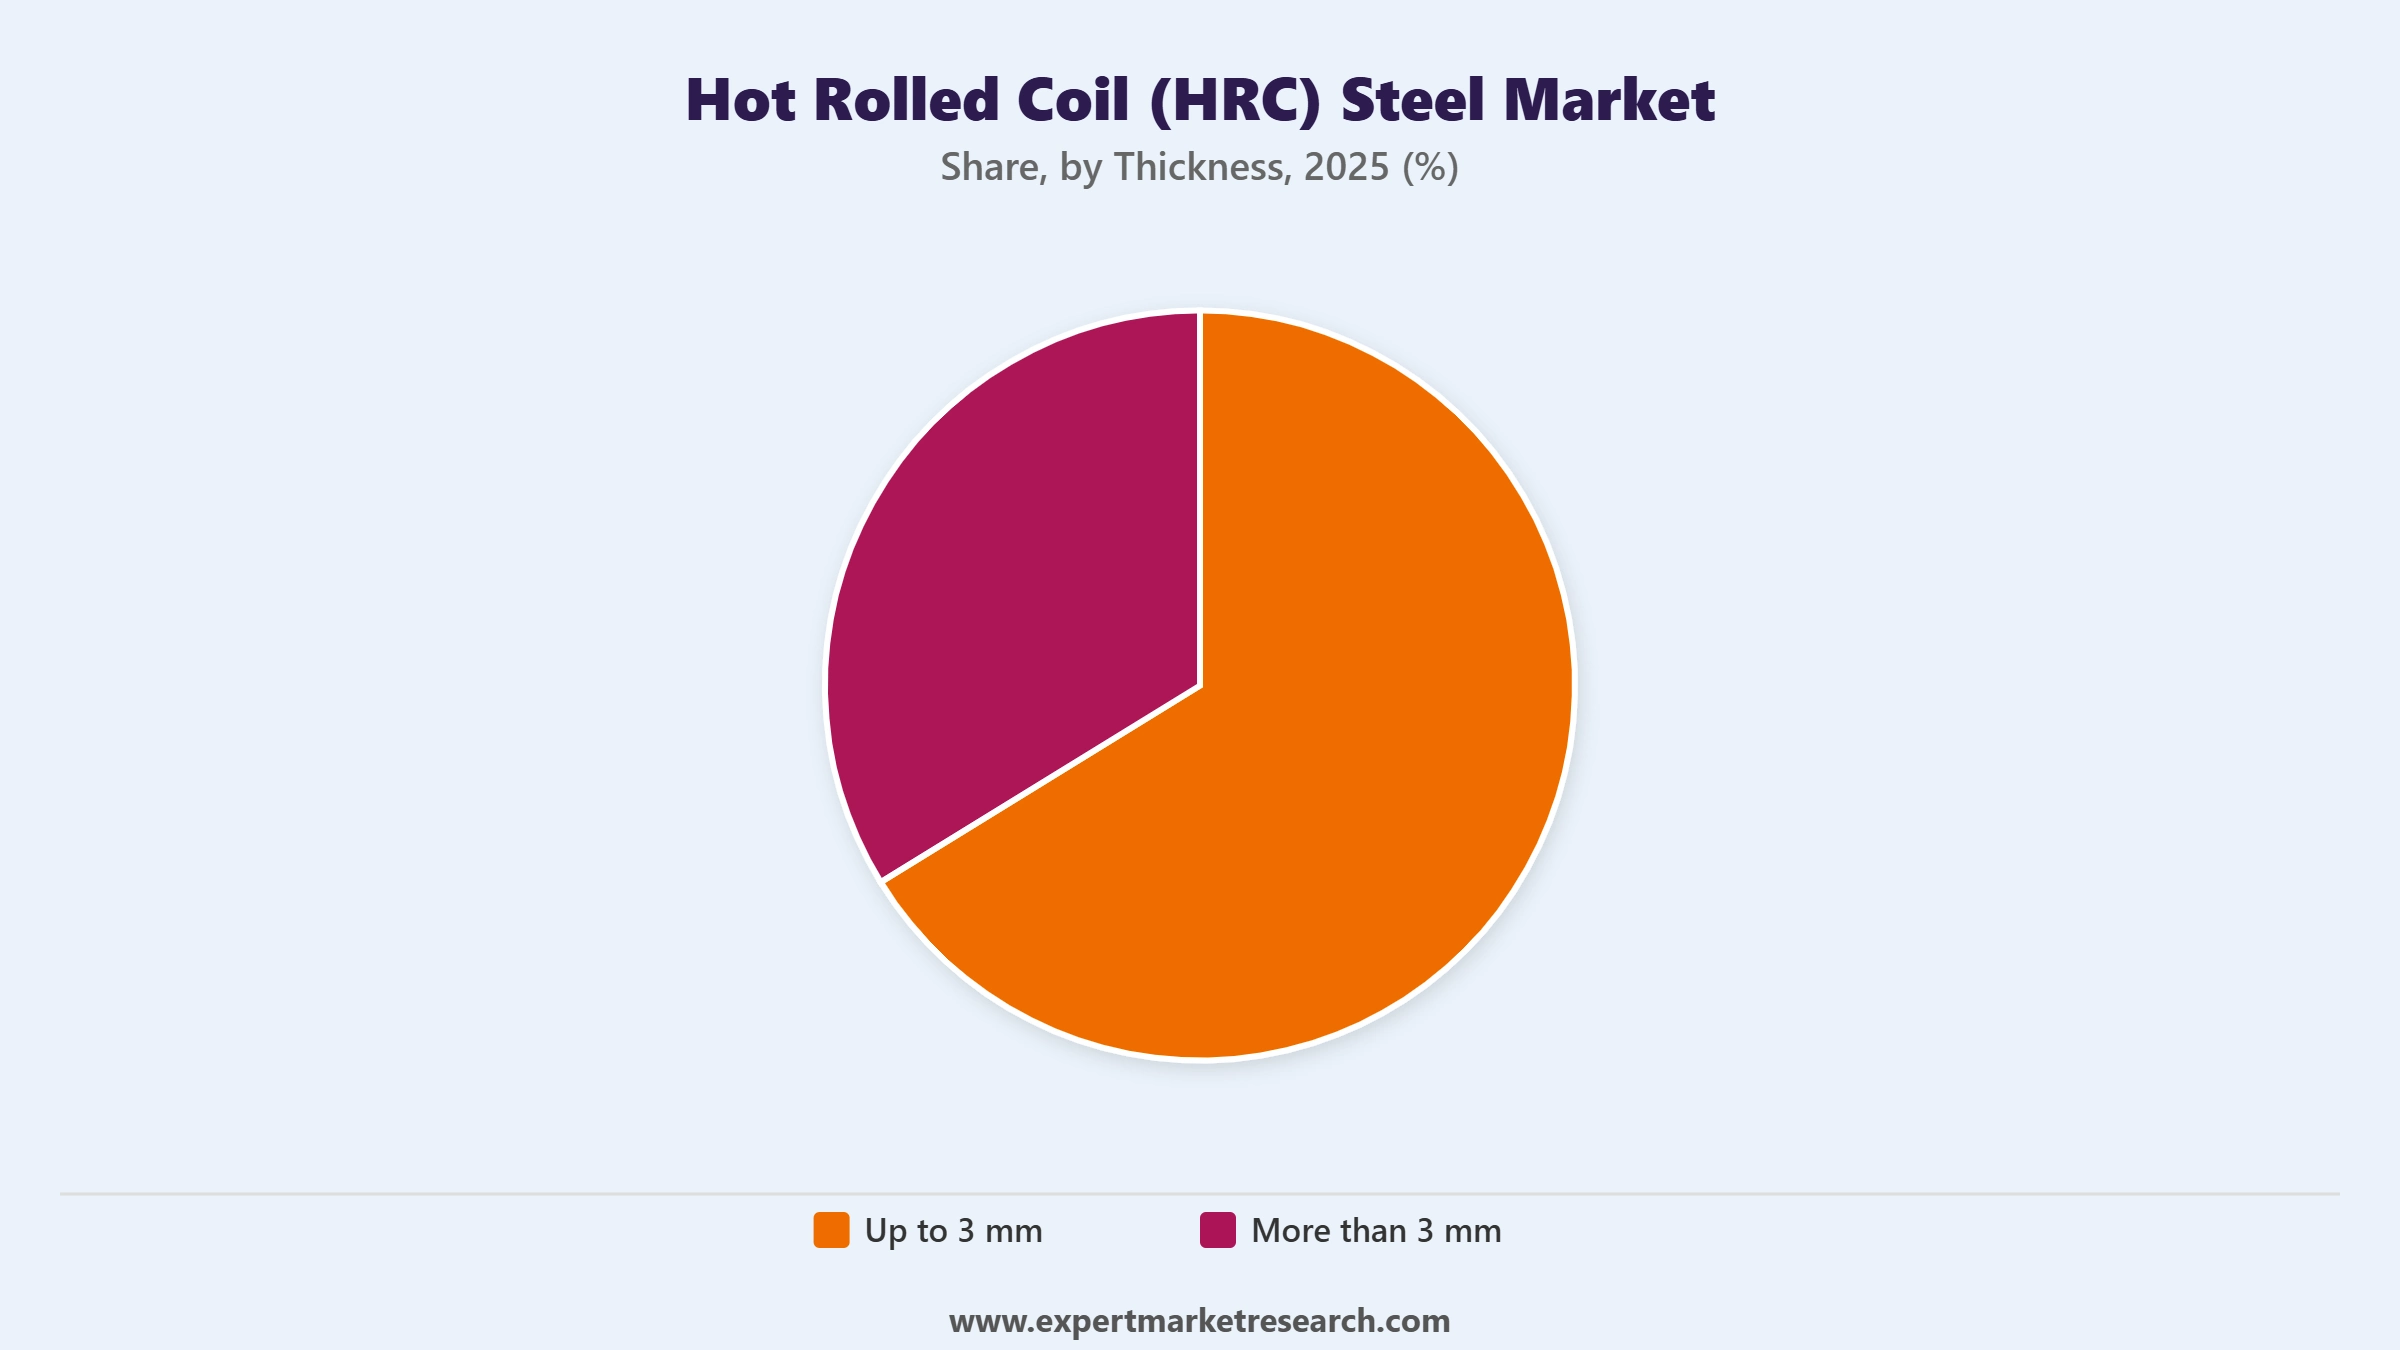
Market Breakup by Thickness
Key Insight: Coils up to 3 mm in thickness account for the largest share of the hot rolled coil market, reflecting demand from automotive body panels, appliance casings, and general fabrication where thinner gauge supports formability and weight reduction. Coils more than 3 mm thick are the fastest-growing thickness category, driven by heavy construction, machinery, and energy infrastructure applications that require greater structural strength, with producers continuing to invest in mill upgrades capable of casting thicker slabs and rolling wider, heavier gauge coil.
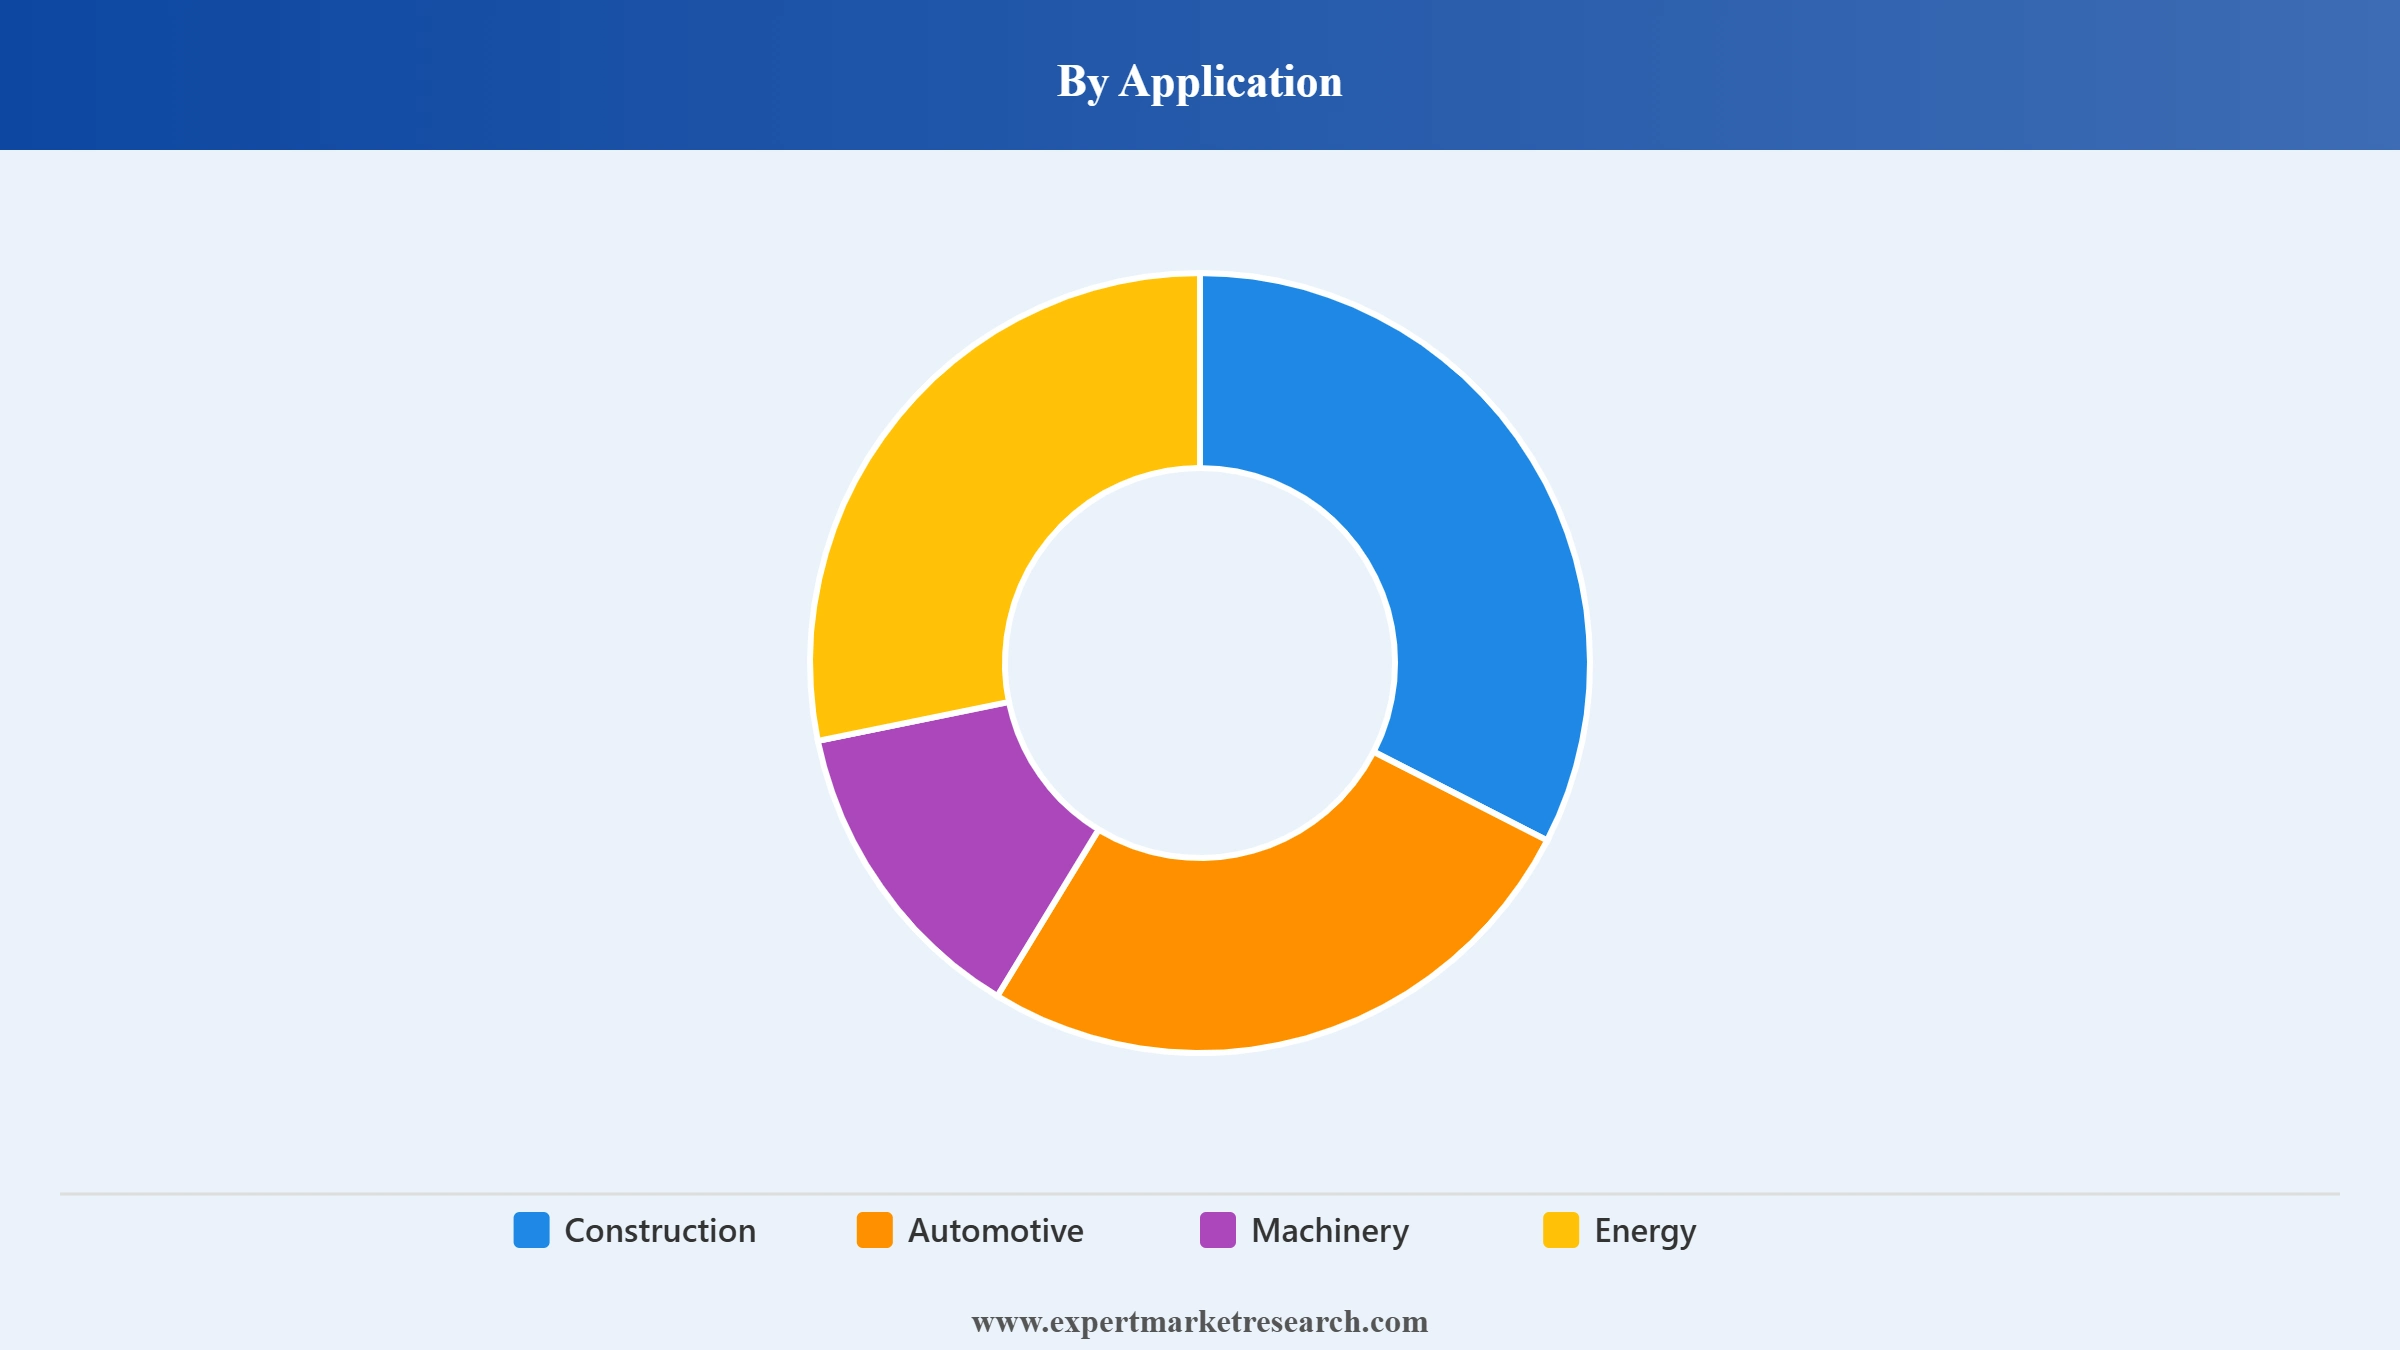
Market Breakup by Application
Key Insight: Construction accounts for the largest share of the hot rolled coil market by application, reflecting sustained demand for structural sections, reinforcement, and roofing across residential, commercial, and infrastructure projects. Automotive is the fastest-growing application as vehicle production recovers and manufacturers specify higher-strength grades for lightweighting, while Baoshan Iron and Steel, a China Baowu Steel Group subsidiary, targeted 52.61 million tonnes of steel production for 2025 in a first-quarter report published in April 2025, citing steady demand despite broader pricing pressure. Machinery and energy applications continue to draw on heavier gauge coil, while Others covers appliances, containers, and general fabrication.
Market Breakup by Region
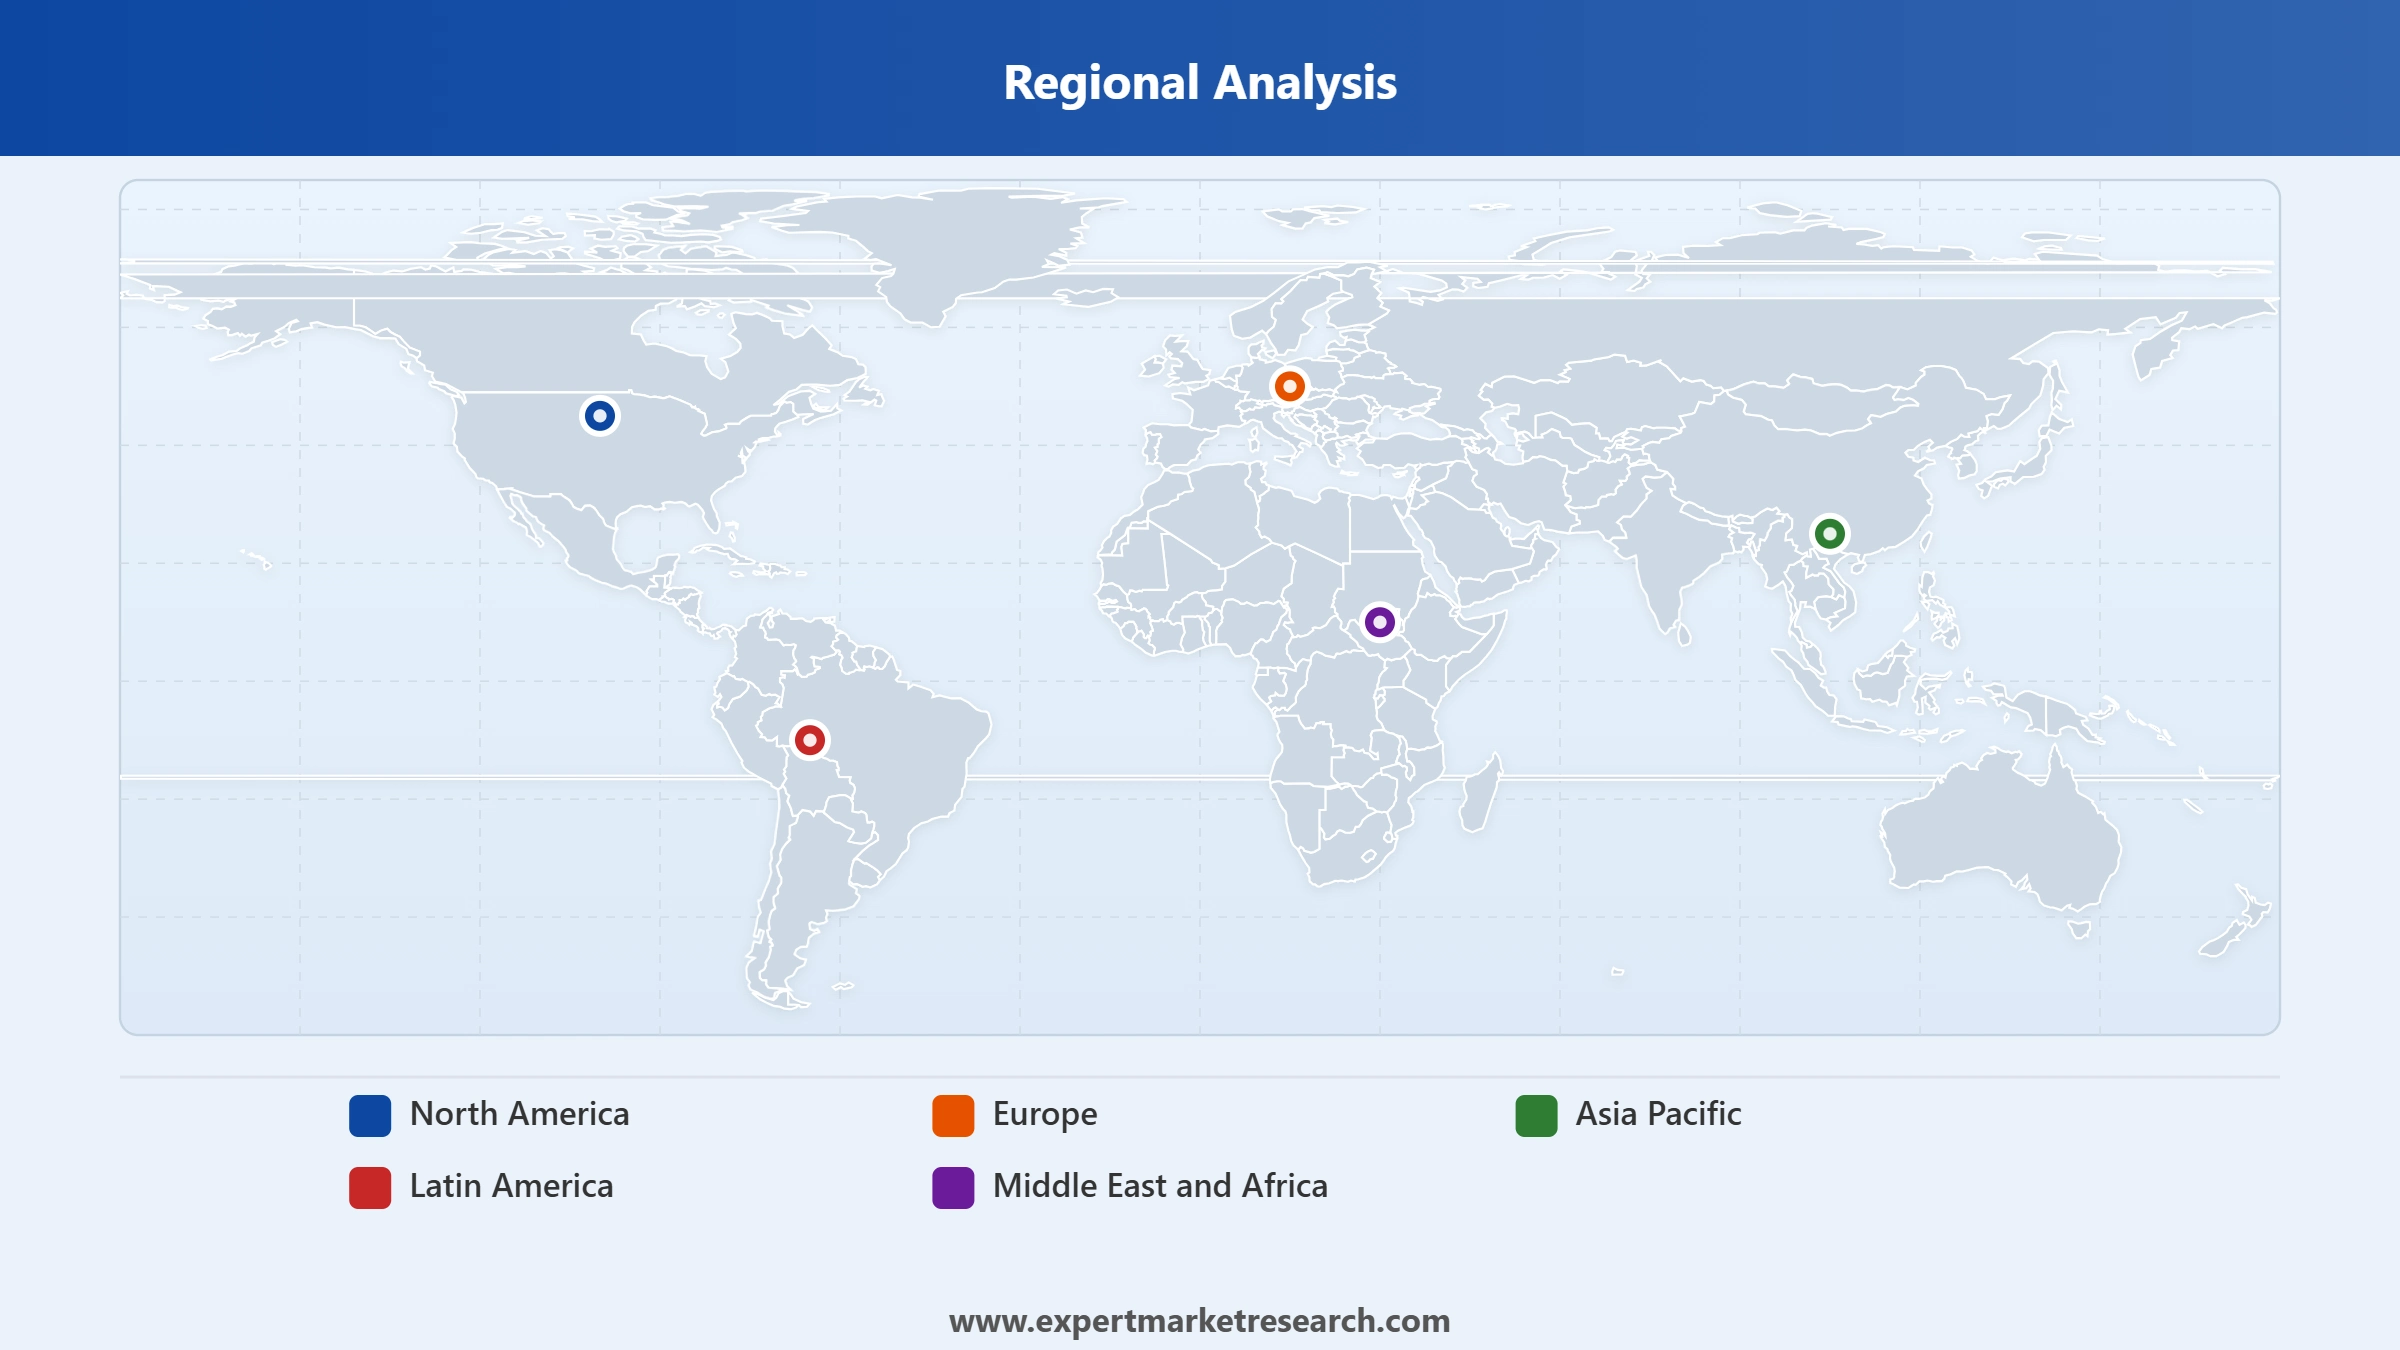
Key Insight: Asia Pacific dominates the hot rolled coil steel market, anchored by China and India's large integrated production base and sustained construction and infrastructure demand. North America and Europe follow, supported by trade policy actions and ongoing capacity modernisation. China's National Development and Reform Commission approved a National Economic and Social Development Plan for 2026 in March 2026 that calls for an orderly reduction in domestic steel production capacity to rebalance supply and demand and improve producer profitability, a policy shift that is expected to influence regional pricing and trade flows. Latin America and the Middle East and Africa remain smaller markets tied to broader industrial and construction investment.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By grade, low carbon steel dominates the market due to its broad use across construction and general fabrication
Low carbon steel holds the largest share of the hot rolled coil market, reflecting its cost efficiency and adequate strength for structural sections, reinforcement bar substitutes, and general fabrication where extreme hardness is not required. Cleveland-Cliffs reported in May 2025 that hot-rolled products made up 41 percent of its first-quarter 2025 steel shipments, the largest single product category ahead of coated, cold-rolled, and plate, illustrating how broad, lower-carbon commodity grades continue to anchor the majority of coil tonnage produced industry-wide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
High carbon steel is the fastest-growing grade as automotive and machinery producers specify higher-strength coil for lightweighting and durability. Trade bodies including WorldAutoSteel have documented a near doubling of commercially available advanced high-strength steel grades since 2017, reported in November 2025, a pace of product development steadily shifting coil demand toward higher-strength specifications across vehicle platforms. Manufacturers are expanding dedicated high-strength rolling and heat-treatment lines to meet this shift across passenger and commercial vehicle segments worldwide.
By thickness, coils up to 3 mm account for the dominant share of the market, matching automotive and appliance demand
Coils up to 3 mm thick hold the largest thickness-based share of the hot rolled coil market, aligning with automotive body panel, appliance casing, and general fabrication applications where thinner gauge supports formability and weight reduction. Nucor Corporation disclosed in an April 2026 regulatory filing that its steel mills segment shipped 3.39 million tons of sheet product in the first quarter of 2026, up 14 percent year over year and the largest single product category across its steel mills business.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Coils more than 3 mm thick are the fastest-growing thickness category as construction, machinery, and energy infrastructure projects demand heavier gauge structural steel. JFE Steel Corporation announced in December 2025 that it had developed a 130-millimetre-thick steel plate for offshore wind foundations, completing a performance evaluation by Japan's Ministry of Economy, Trade and Industry that permits steel exceeding 100 millimetres in thickness for domestic offshore wind projects, pushing gauge specifications beyond conventional structural plate.
By application, construction accounts for the dominant share of the market due to sustained structural and infrastructure demand
Construction accounts for the largest application share of the hot rolled coil market, reflecting steady demand for structural sections, roofing, and reinforcement across residential, commercial, and infrastructure projects worldwide. India's Ministry of Steel reported in May 2026 that the country's finished steel consumption reached 12.99 million tonnes in April 2026, up 8.1 percent year-on-year, attributing the growth to continued buoyancy in construction, infrastructure, and manufacturing end-use segments, which together remain the anchor demand base for hot rolled coil producers globally.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Automotive is the fastest-growing application as vehicle production recovers and manufacturers increasingly specify higher-strength coil for structural and safety components. Fives Group announced in April 2026 a contract with Hyundai Steel to design and supply advanced coil finishing lines for Hyundai-Posco Louisiana Steel's new USD 5.8 billion integrated flat steel mill, which will dedicate approximately 70 percent of its output, roughly 1.8 million tonnes annually, to automotive-grade steel supplying North American vehicle manufacturers directly, reinforcing regional supply chain resilience.
Asia Pacific dominates the market due to the scale of Chinese and Indian integrated steel production
Asia Pacific dominates the hot rolled coil steel market, anchored by China's large state-owned integrated producers and India's rapidly expanding steelmaking base, which together account for the majority of the world's crude steel output. India's Ministry of Steel reported in July 2026 that crude steel production reached 14.1 million tonnes in June 2026, up 3.9 percent year-on-year, with finished steel production rising 6 percent over the same month, underscoring the regional demand growth that keeps Asia Pacific the largest global supply source.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America is a fast-growing market as trade policy actions support domestic mill utilisation and pricing. The United States raised its Section 232 tariff on steel imports to 50 percent in June 2025, following an earlier restoration of the full 25 percent duty in March 2025, a combined shift that domestic producers have credited with reducing import competition and supporting higher domestic coil prices through 2025, strengthening capacity utilisation across integrated and electric arc furnace mills alike.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
4.9% |
|
Europe |
3.8% |
|
Asia Pacific |
5.4% |
|
Latin America |
4.3% |
|
Middle East and Africa |
4.6% |
The hot rolled coil (HRC) steel companies feature a moderately consolidated group of hot rolled coil steel companies led by large integrated and electric arc furnace producers, alongside state owned Chinese steelmakers and diversified regional players. Competition is increasingly defined by capacity scale, decarbonisation strategy, and trade policy positioning rather than product specification alone.
Leading hot rolled coil (HRC) steel market players are focusing on capacity modernisation, downstream coating and cold rolling investment, and joint ventures to strengthen competitive position. Growing emphasis on electric arc furnace conversion, trade policy compliance, and higher-strength grade development is enabling manufacturers to widen their addressable customer base while supporting long-term market share growth.
Formed in 1970 through the merger of Yawata Iron and Steel and Fuji Iron and Steel, and headquartered in Tokyo, Japan, Nippon Steel Corporation is one of the world's largest integrated steelmakers, producing flat, long, and specialty steel products for construction, automotive, and infrastructure customers. The company has stated a long-term ambition to reach 100 million tonnes of global annual crude steel capacity through continued international expansion and technology partnerships.
Founded in 1907 and headquartered in Mumbai, India, Tata Steel Limited operates Asia's first integrated steel plant and today ranks among the world's most geographically diversified steel producers, with operations spanning India, the United Kingdom, and the Netherlands. The group reported a consolidated turnover of approximately USD 26 billion for the financial year ended March 2025 and employs more than 78,000 people across five continents.
Tracing its roots to 1905 and headquartered in Charlotte, North Carolina, United States, Nucor Corporation is the largest steel producer in the United States by capacity, operating an electric arc furnace-based production model across mini mills and specialty facilities. The company continues construction of its new sheet mill in West Virginia, which management has said remains on schedule for a phased ramp-up toward full production capacity in the years ahead.
Formed in 2006 through the merger of Arcelor and Mittal Steel, and headquartered in Luxembourg, ArcelorMittal is the largest steel producer outside China, with primary steelmaking operations across more than a dozen countries and a significant presence in flat, long, and automotive-grade steel products. The company holds joint venture interests across multiple regions, including ArcelorMittal Nippon Steel India, which supplies flat steel products to South Asian construction and automotive customers.
Other key players in the Hot Rolled Coil (HRC) Steel Market report include China Baowu Steel Group, JFE Steel Corporation, POSCO Holdings, United States Steel Corporation, Ansteel Group, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the Hot Rolled Coil (HRC) Steel Market 2026-2035 with our in-depth report. Gain strategic insights, future forecasts, and key market developments that can help you stay competitive. Download a free sample report or contact our team for customised consultation on the market trends 2026.


Upto 15% Off
USD
$3999 $3599
$2499 $2249
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the Hot Rolled Coil (HRC) Steel Market reached an approximate value of USD 260.00 Billion.
The market is projected to grow at a CAGR of 4.60% between 2026 and 2035.
The key players in the market include Nippon Steel Corporation, Tata Steel Limited, Nucor Corporation, ArcelorMittal, China Baowu Steel Group, JFE Steel Corporation, POSCO Holdings, United States Steel Corporation, Ansteel Group, among others.
Leading companies are pursuing capacity modernisation, electric arc furnace conversion, joint ventures, and downstream coating investment to capture demand.
Key challenges include trade policy volatility, decarbonisation compliance costs, and overcapacity pressure in major producing regions such as China.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Grade |
|
|
Breakup by Thickness |
|
|
Breakup by Application |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




