

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
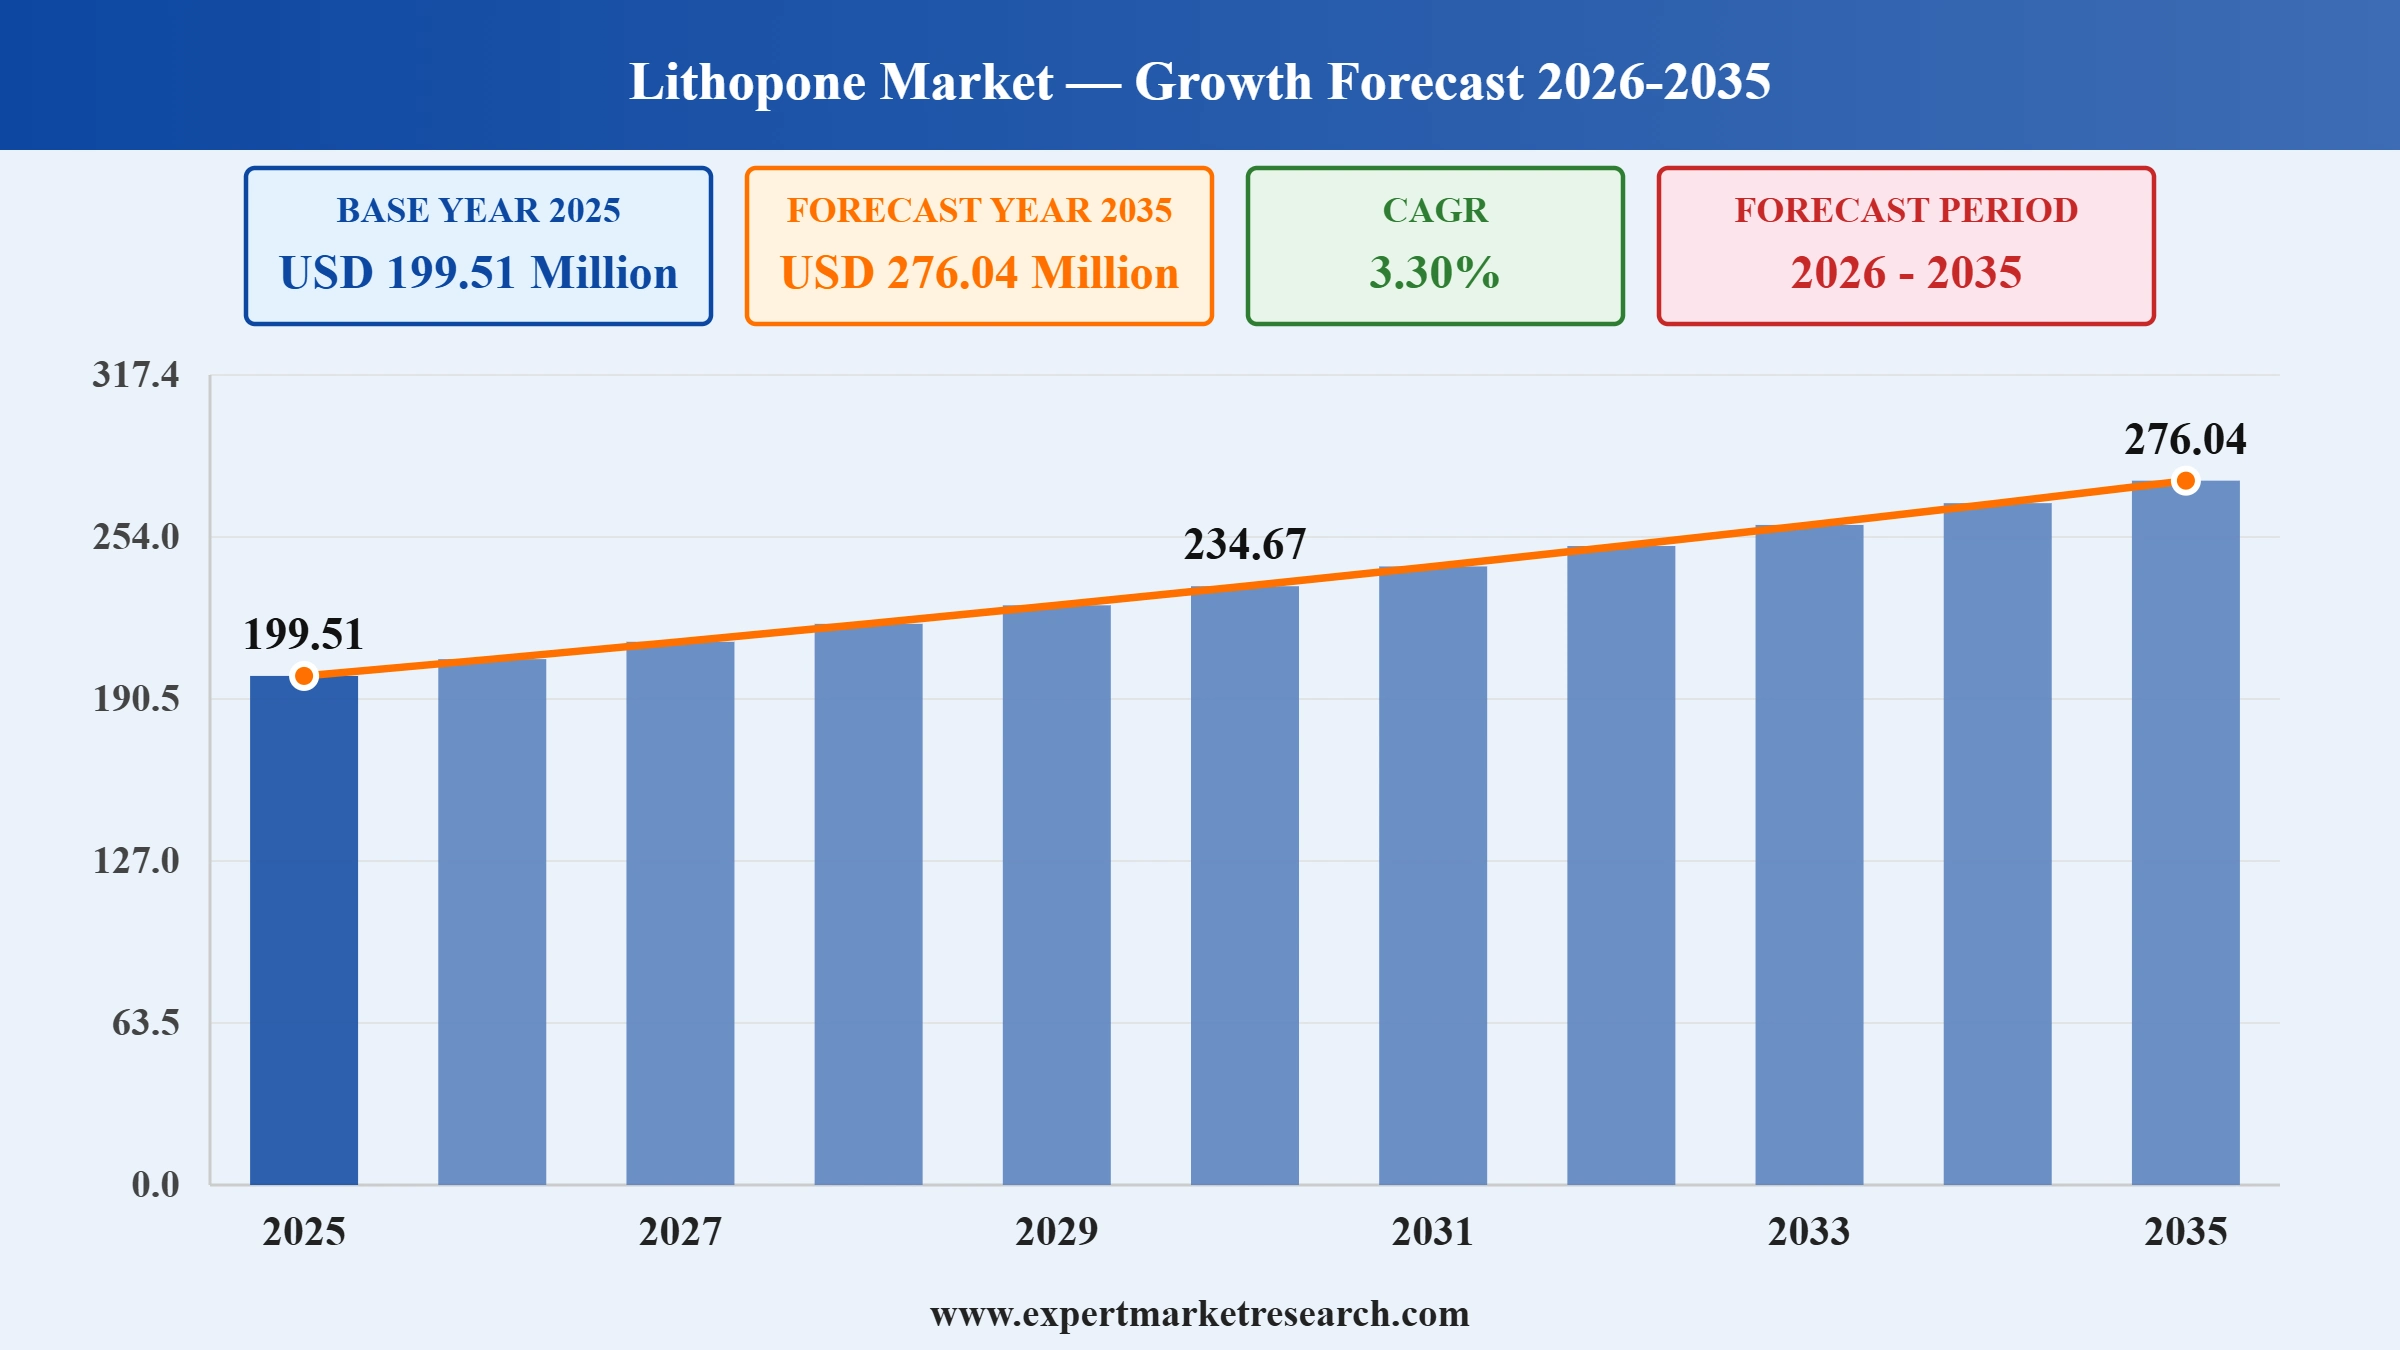
The global lithopone market attained a value of USD 199.51 Million in 2025 and is projected to grow at a CAGR of 3.30% through 2035. The market is further expected to reach USD 276.04 Million by 2035. Rising demand for cost effective, non-toxic white pigments across paints and coatings, plastics, and paper applications, along with tightening environmental regulations on heavy metal-based alternatives, are helping manufacturers expand production capacity and broaden their customer base.
The lithopone market spans three product grades, lithopone 28%, lithopone 30%, and lithopone 60%, sold into paints and coatings, plastics, printing inks, paper and pulp, rubber, and leather applications worldwide. Lithopone, a co-precipitated blend of zinc sulfide and barium sulfate, has served for over a century as a cost effective, non-toxic alternative to titanium dioxide and white lead, offering strong tinting strength and covering power at a fraction of the cost of premium white pigments. Production remains highly concentrated in China, where a cluster of specialized manufacturers supply both domestic formulators and export markets across Asia, Europe, and the Americas, while smaller producers in India and Europe serve regional and specialty grade demand.
Manufacturers are responding to shifting competitive dynamics in the broader white pigment industry by reinforcing their cost and sustainability positioning relative to titanium dioxide. Persistent overcapacity across China's titanium dioxide sector has encouraged price sensitive formulators to reassess their reliance on premium grade pigment where full titanium dioxide opacity is not strictly required. This kind of capacity discipline among major titanium dioxide producers is reinforcing the relative cost advantage of lithopone in applications such as masterbatch, budget coatings, and papermaking, where a lower cost pigment can substitute without a meaningful performance penalty.
Leading lithopone suppliers are increasingly formalizing export relationships and quality certifications to serve international paint and plastics formulators seeking REACH and EPA compliant, non-toxic pigment alternatives. Following ECHA's February 2026 additions of n-hexane and BPAF to the REACH Substances of Very High Concern candidate list, with SCIP notification required by August 2026, exporters supplying the EU are updating safety data sheets and compliance documentation to maintain market access. This kind of certification driven market access signals where the industry is heading, with suppliers competing increasingly on regulatory compliance and supply reliability rather than price alone.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
PPG installed a new testing line dedicated to radiation curable coatings at its European research centre in Marly, France, aimed at accelerating ultraviolet curing innovation for industrial coatings. The investment reflected growing interest in faster curing, lower emission platforms. Pigment suppliers can leverage this trend by qualifying products early for UV curable systems as formulators expand testing capacity.
Tronox permanently closed its 46,000-tonne titanium dioxide plant in Fuzhou, China, in January 2026, citing weak domestic demand, rising sulphur costs, and regional oversupply. The closure affected approximately 550 employees and followed a pattern of rationalization among global pigment majors. Regional pigment suppliers across the lithopone market can leverage this trend by capturing displaced volume from formulators seeking alternative pigment sources.
Chloride process titanium dioxide output rose to 752,000 tonnes in China, reaching nearly 16 percent of total production, as producers shifted toward higher quality processes amid consolidation. The shift concentrated premium capacity among fewer, more capable producers. Lithopone suppliers across the lithopone market can leverage this trend by targeting mid-tier and budget formulators priced out of premium chloride process pigment.
China's titanium dioxide industry recorded its first annual output decline in over 20 years, with production reaching 4.72 million tonnes, down 1 percent, as overcapacity pushed plant utilization to roughly 83 percent. The decline reflected a shift toward technological upgrades over pure capacity growth. Lithopone suppliers across the lithopone market can leverage this trend by positioning their pigment as a stable alternative for formulators facing tighter supply.
Ink formulators across the lithopone market are increasingly refreshing established pigment compatible product platforms to serve higher performance sheetfed and packaging printing applications, rather than developing entirely new chemistries from scratch. This is helping suppliers extend the commercial life of proven pigment dispersion technology while controlling development costs and shortening qualification timelines for new and existing customers alike across regions. In September 2026, Sun Chemical launched SunLit OptiPace, the latest evolution of its established Pace technology platform for high performance sheetfed printing applications across Europe.
Mineral filler and pigment producers across the lithopone market are increasingly building satellite production plants directly inside customer paper mills rather than shipping slurry from centralized facilities, reducing logistics costs and ensuring consistent quality for high-speed coating lines. This inside the fence model is becoming the benchmark for pigment supply in expanding packaging markets. In January 2026, Minerals Technologies announced it had started up three new satellite plants in Asia during 2025, two in China and one in India, while doubling capacity at an existing Indian facility.
Specialty ink and coatings suppliers across the lithopone market are increasingly expanding dedicated pigment dispersion product lines for niche substrates such as rubber and flexible packaging, rather than relying solely on general purpose pigment grades. This is widening the range of qualified pigment options available to formulators serving these smaller, higher margin application niches across multiple international regions. In September 2026, DIC Corporation introduced new water-based pigment dispersions engineered specifically for inkjet printing applications on non-absorbent surfaces including food packaging materials and decorative wallpaper substrates.
Specialty chemical suppliers across the lithopone market continue to strengthen production capacity within China even as broader pigment oversupply persists, reflecting confidence in longer term demand from coatings, plastics, and construction materials customers across the broader Asian region. This is reinforcing China's position as the dominant global manufacturing base for cost effective white pigments. In April 2026, Evonik officially inaugurated a double digit million-euro expansion of its specialty amine production facility in Nanjing, China, supporting sustainable solutions for the region's chemical manufacturing customers.
Regional pigment distribution networks are continuing to realign as European polymer producers adjust supply relationships following broader industry consolidation across the continent. This is creating openings for smaller, regionally focused chemical distributors to expand their customer base and territorial coverage across several adjacent national markets throughout Western Europe. Since April 2026, Snetor has been distributing Ineos Olefins and Polymers products across Germany, Italy, Spain, and Portugal, while also handling exclusive marketing responsibilities for the France market under a newly realigned distribution agreement.
The Expert Market Research's report titled “Global Lithopone Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Product
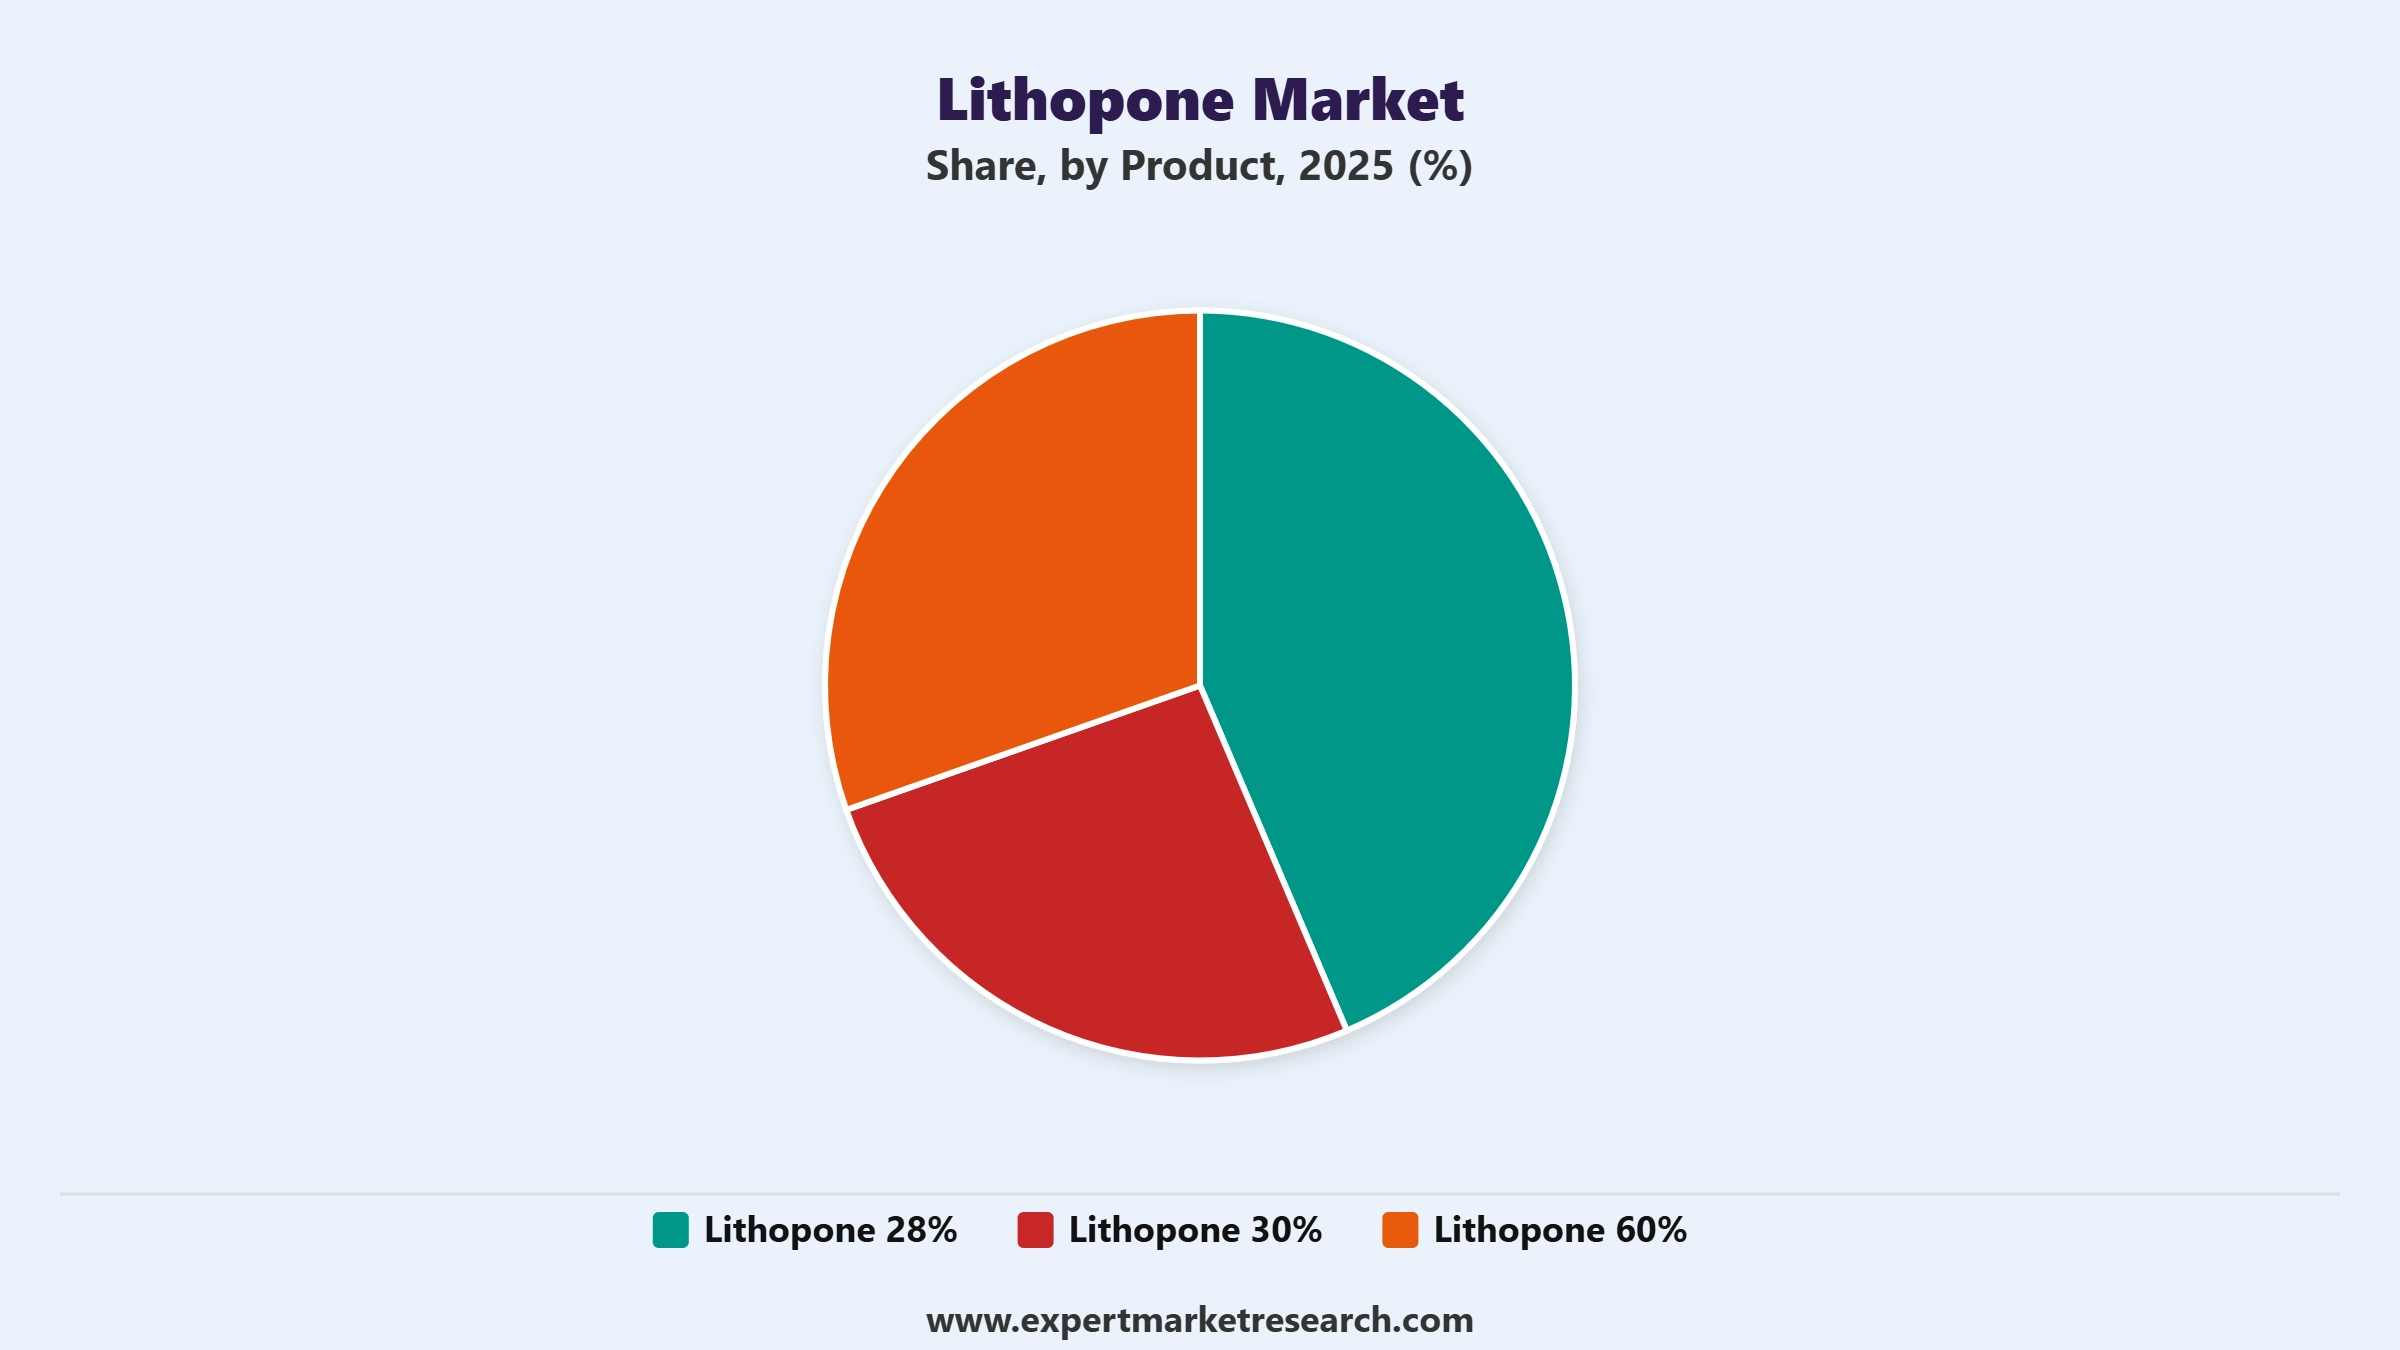
Key Insight: Lithopone 28% accounts for the largest product share of the lithopone market given its widespread use as a general purpose pigment across mainstream paints, coatings, and plastics applications where moderate opacity and cost efficiency are prioritized; lithopone 30% serves as a marginally higher performance alternative used interchangeably across similar applications depending on regional supplier availability; and lithopone 60% is growing fastest as specialty formulators in premium coatings and inks increasingly require higher zinc sulfide content for improved brightness and tinting strength, a trend reinforced by industry consolidation such as LB Group's October 2025 asset purchase agreement with Venator to acquire its European titanium dioxide operations under the newly created Tioxide brand.
Market Breakup by Application
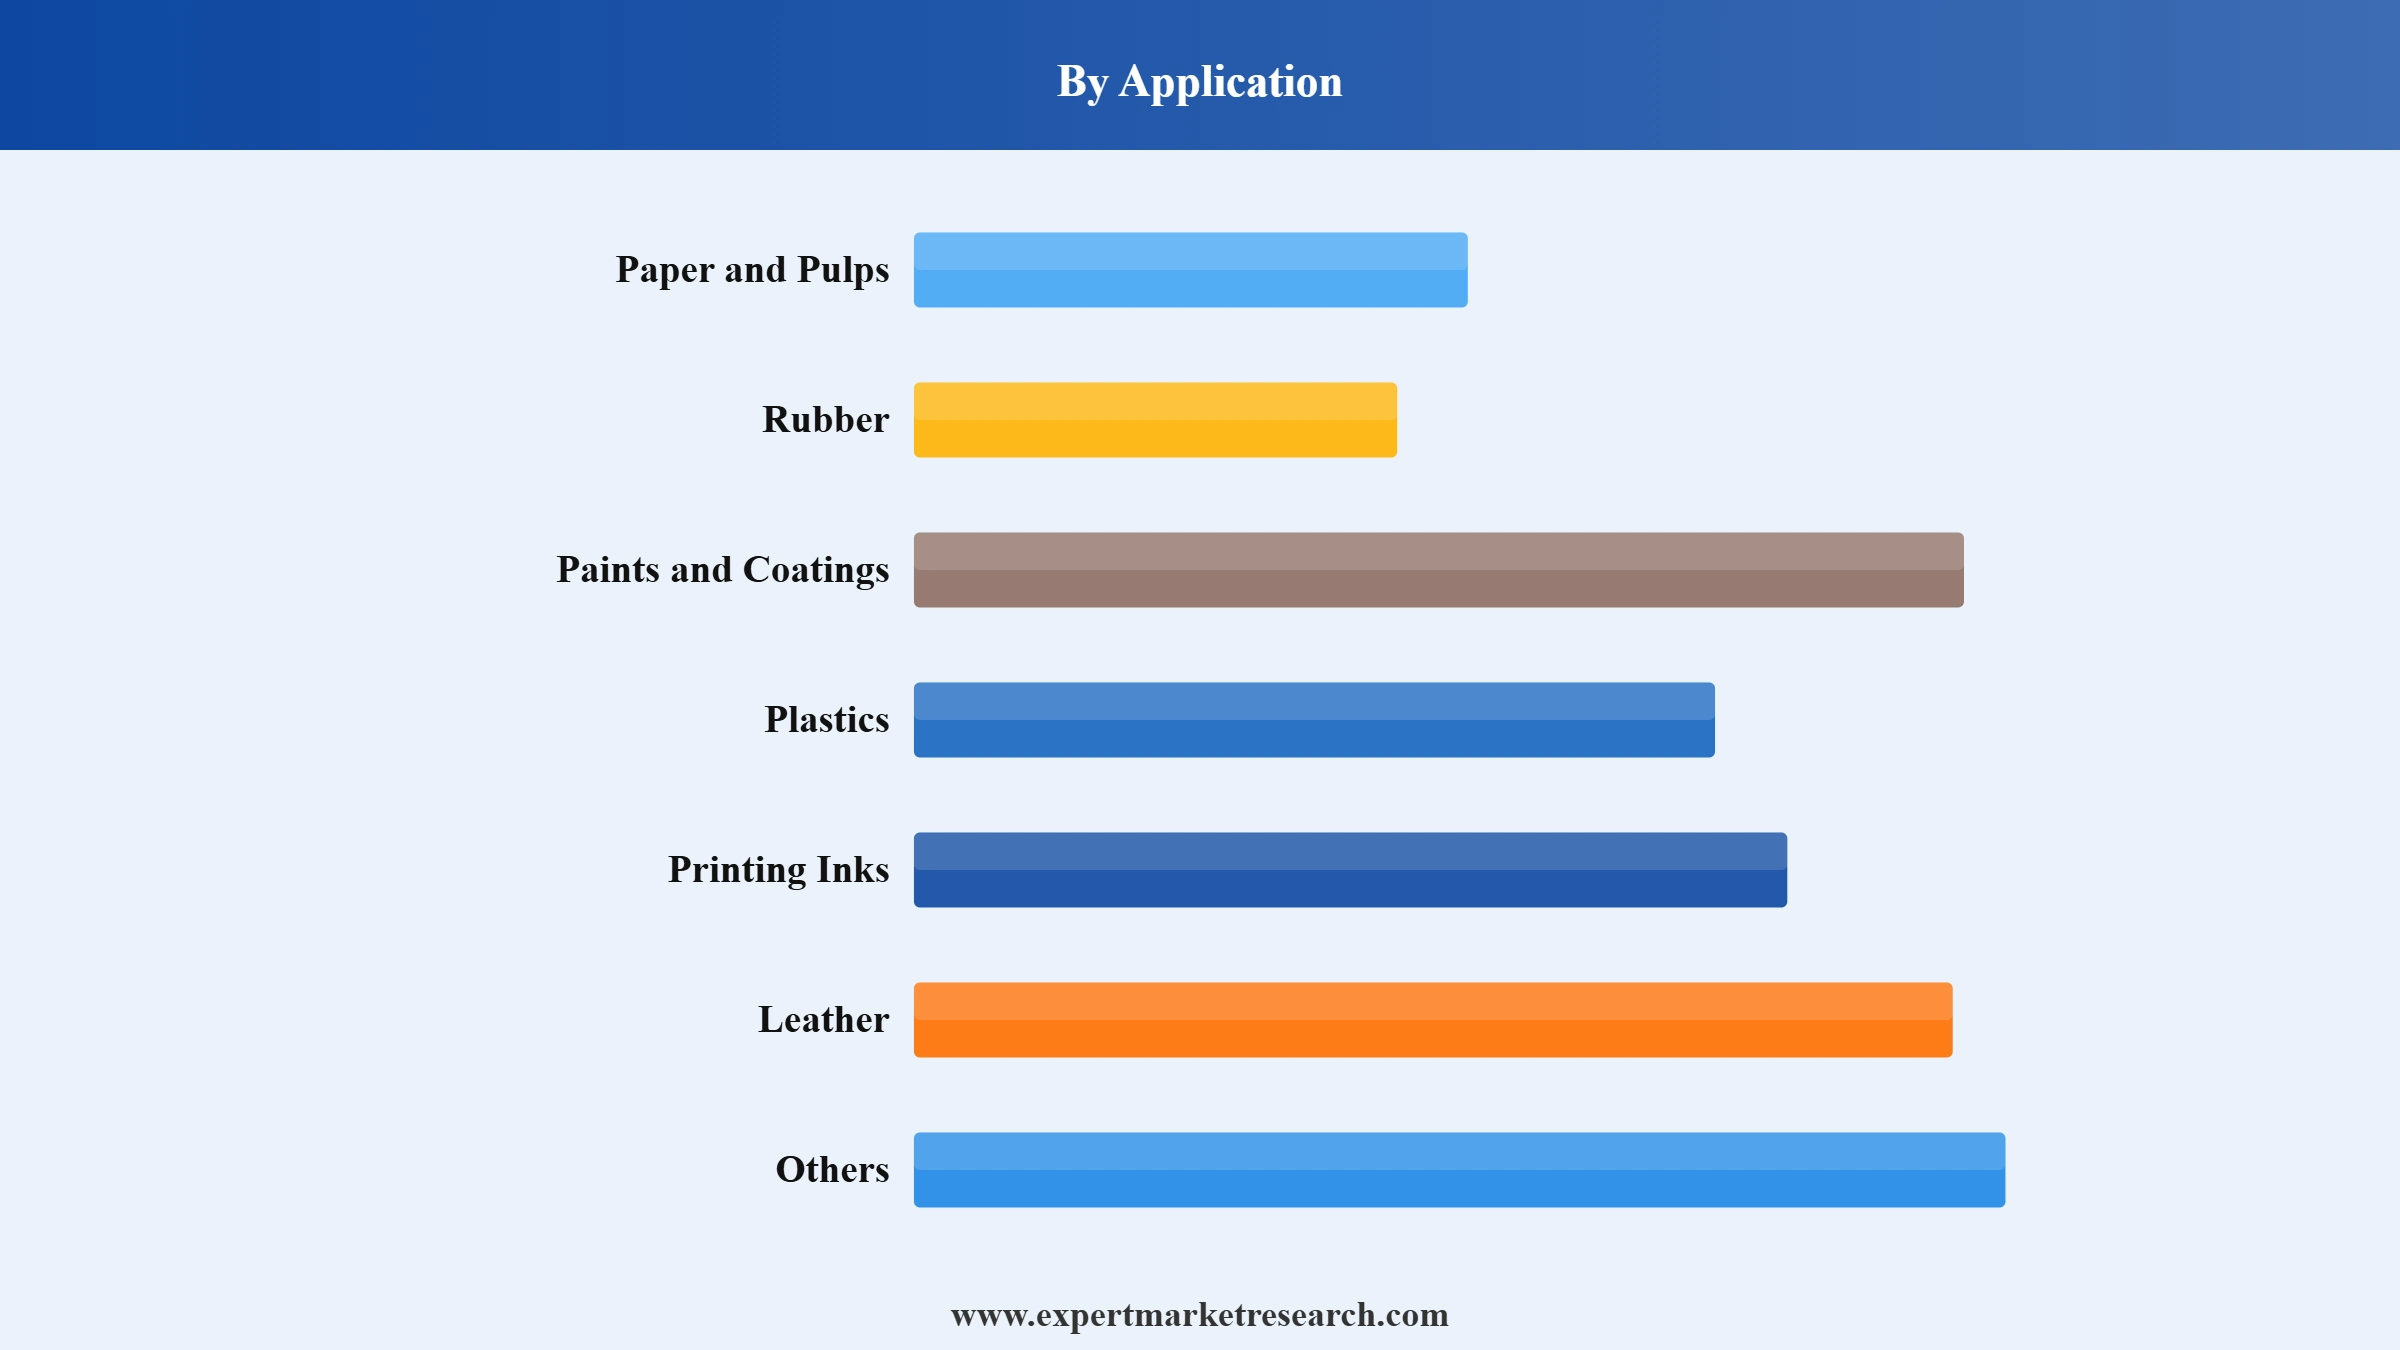
Key Insight: Paints and coatings represent the largest application segment of the lithopone market given sustained demand for cost effective opacity across architectural and industrial coatings; plastics form a significant and fast growing application as manufacturers use lithopone as a functional filler and whitening agent across polyolefin, PVC, and ABS resin systems; printing inks rely on lithopone for opacity in budget conscious formulations; paper and pulps use lithopone as a brightening agent in coated paper and specialty board production; rubber applications use lithopone as a reinforcing filler and whitening agent; leather finishing uses lithopone in pigment coatings; and the others category spans linoleum flooring, cosmetics, and general industrial fillers.
Market Breakup by Region
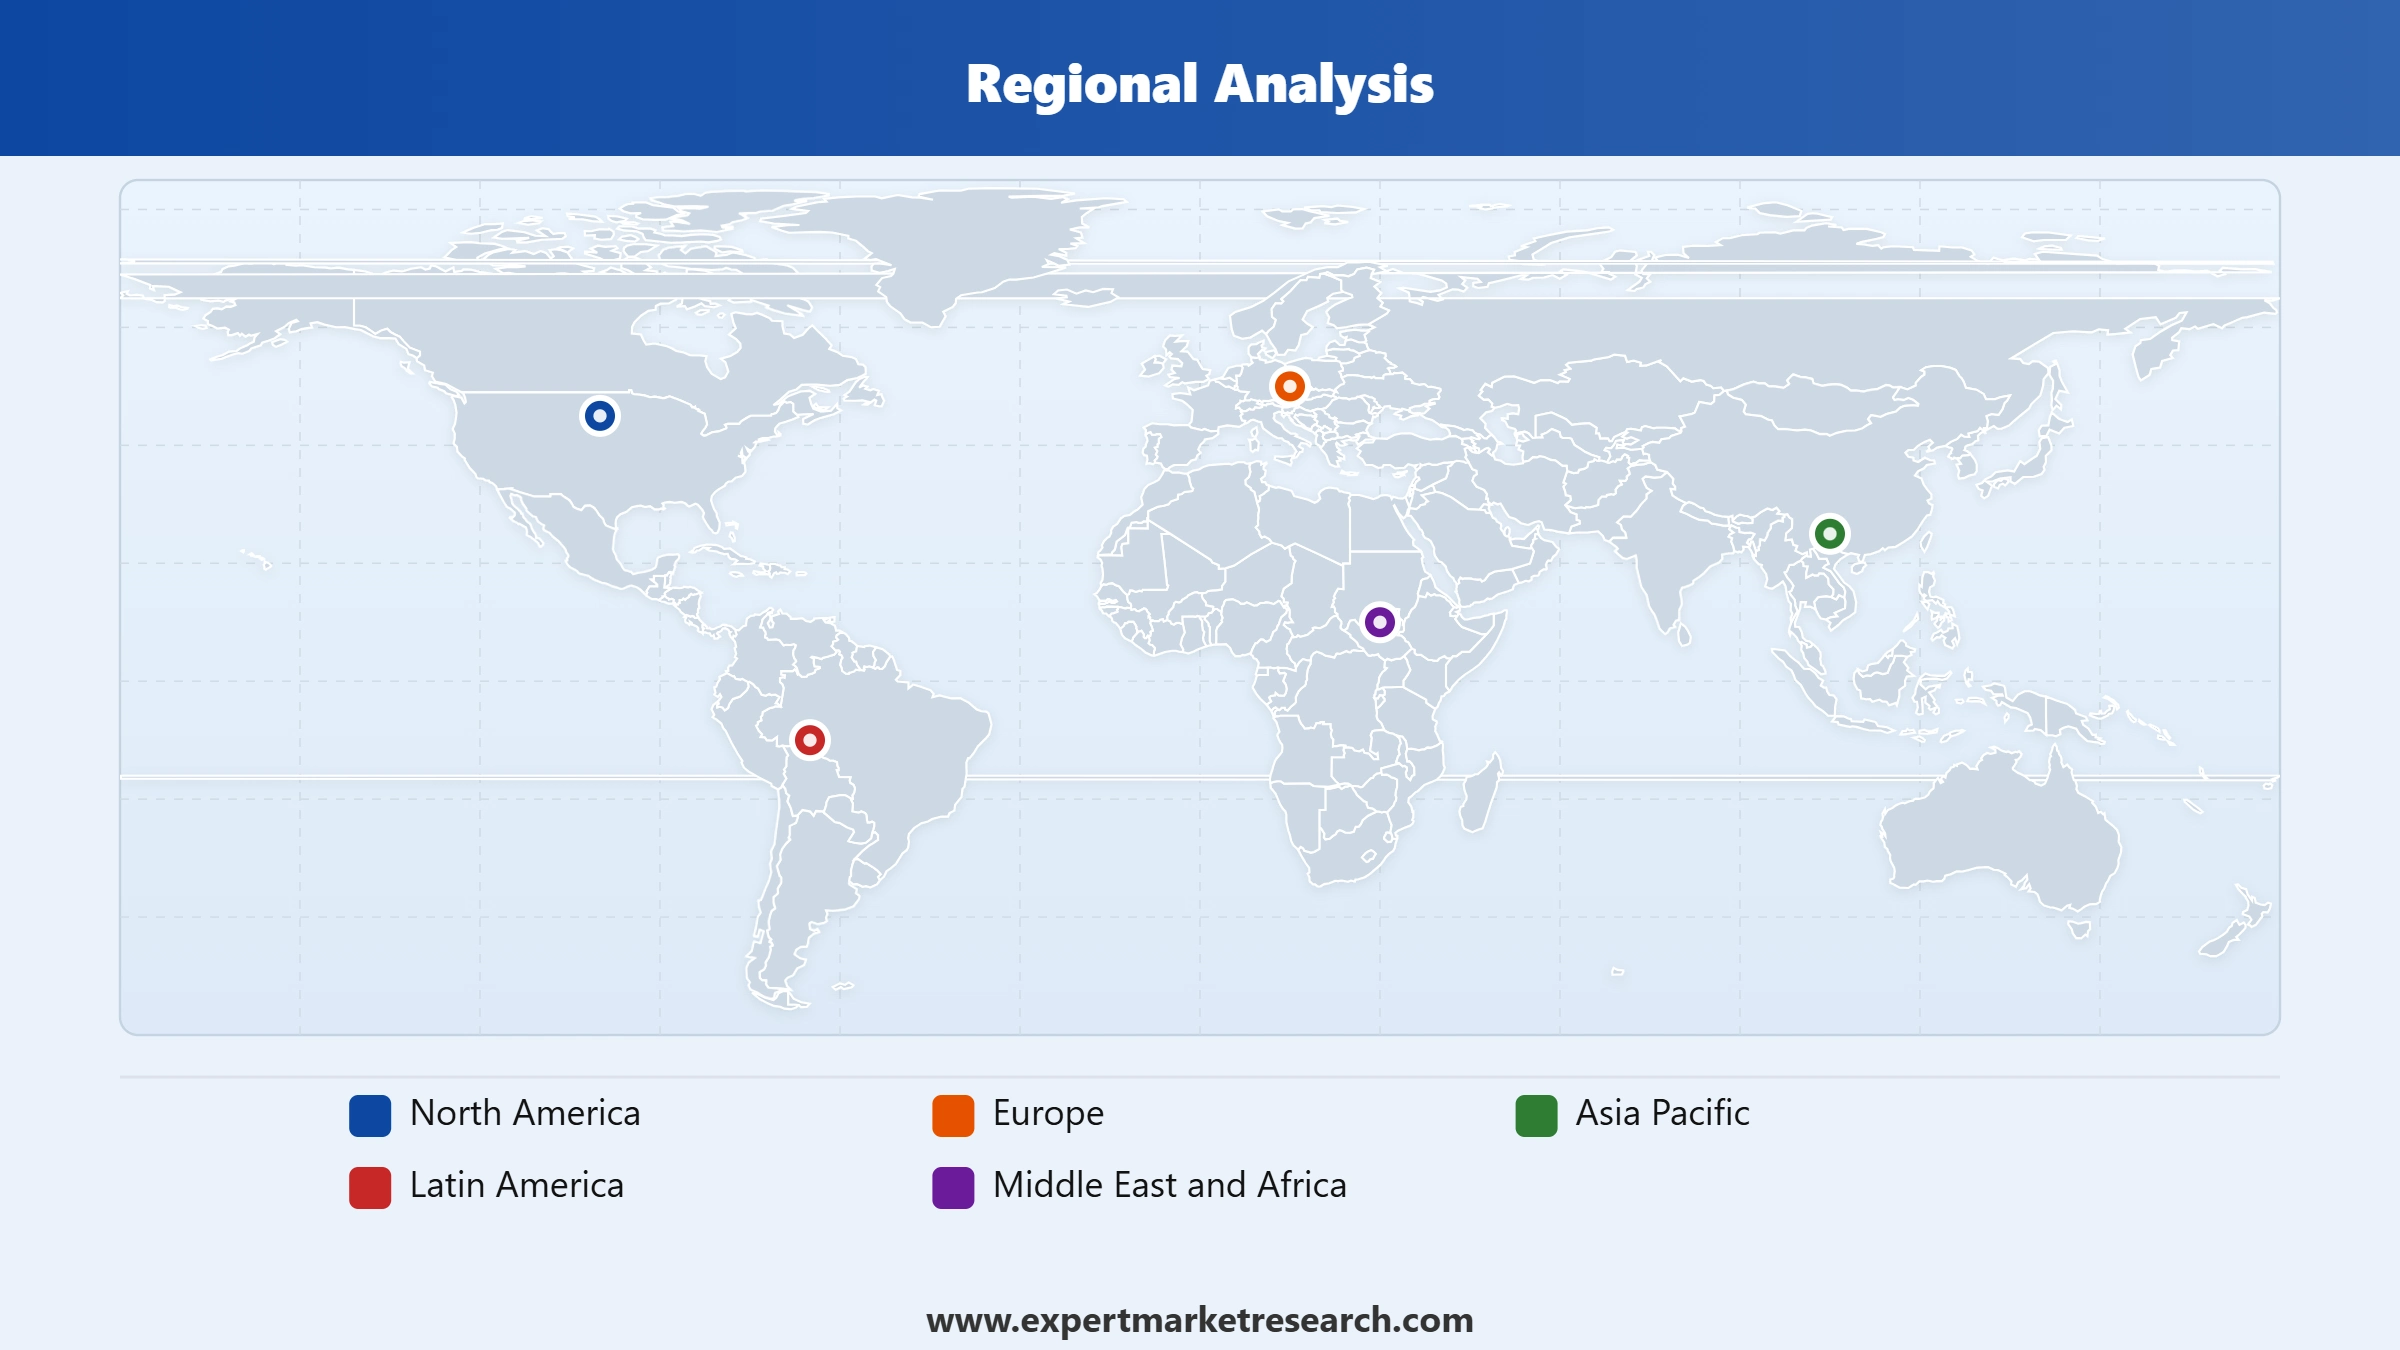
Key Insight: Asia Pacific represents the largest regional lithopone market, anchored by China's concentrated manufacturing base and rising plastics and coatings production across the region; Europe maintains a mature specialty and regulatory compliant pigment market supported by REACH driven demand for non-toxic alternatives; North America serves a smaller but stable market for cost effective, EPA compliant pigment applications; Latin America is gradually scaling alongside expanding construction and packaging activity; and the Middle East and Africa are emerging as the fastest growing region as infrastructure investment and construction activity broaden demand for cost effective coatings and building materials.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By product, the lithopone 28% segment dominates the market owing to its widespread use as a cost-effective general-purpose pigment
Lithopone 28% holds the largest product share of the lithopone market, reflecting its established position as the standard grade specified across mainstream paints, coatings, and plastics where moderate opacity at low cost is the priority. In August 2025, JG Chemicals approved a greenfield zinc chemicals project in Dahej, Gujarat, with capacity exceeding 40,000 tonnes per annum, underpinning standard grade lithopone feedstock supply. This cost advantage continues to anchor lithopone 28% as the default grade.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Lithopone 60% is registering the fastest growth in the lithopone market as specialty coatings and ink formulators increasingly require higher zinc sulfide content for improved brightness and opacity in premium applications. In March 2025, Sudarshan Chemical Industries completed its acquisition of Heubach Group's global pigment business, creating a larger premium pigment platform spanning 19 international sites. Continued consolidation among premium pigment suppliers is expected to sustain above average growth.
By application, the paints and coatings segment dominates the market owing to sustained demand for cost effective opacity across architectural and industrial coatings
Paints and coatings account for the largest application share of the lithopone market, reflecting sustained global demand for cost effective, non-toxic opacity across architectural, industrial, and protective coatings formulations. In February 2025, LANXESS launched its low-carbon Bayferrox Scopeblue iron oxide yellow pigments for architectural paints and coatings, helping formulators reduce carbon emissions while maintaining coating performance and color quality. These broad-based coatings demand continues to anchor paints and coatings as the primary application driving lithopone consumption worldwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Plastics represent the fastest growing application within the lithopone market as manufacturers increasingly use lithopone as a functional filler and whitening agent across polyolefin, PVC, and ABS resin systems. The European Union's Packaging and Packaging Waste Regulation, taking effect in August 2026, mandates minimum recycled content in plastic packaging, prompting compounders to requalify white pigment loadings within recycled content formulations. Continued growth in plastics production is expected to sustain above average growth for this application through the forecast period.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific leads the market through concentrated manufacturing capacity while the Middle East and Africa grow fastest on rising construction and infrastructure investment
Asia Pacific holds the largest share of the lithopone market, anchored by China's concentrated production base and a dense cluster of specialized manufacturers serving both domestic formulators and export markets worldwide. In August 2025, industry reporting confirmed Kingfa was expanding capacity at its Malaysia plastics compounding plant to 30,000 tonnes that year, reinforcing Southeast Asia as a growing manufacturing hub for pigment consuming plastics production alongside China's established base. These established and expanding regional supply chains continue to reinforce Asia Pacific's position as the most mature lithopone manufacturing base globally.
The Middle East and Africa region is the fastest-growing market for lithopone market, propelled by rising infrastructure investment, expanding construction activity, and growing demand for cost effective coatings and building materials across the region's largest economies. In February 2026, Jazeera Paints received a Local Content Excellence Award in Saudi Arabia, highlighting the increasing weight placed on in-Kingdom research, development, and workforce content in national tender evaluations for coatings suppliers. Continued infrastructure spending across the region is expected to sustain above average growth for lithopone demand through the forecast period.
The competitive landscape features a mix of established Chinese lithopone companies and smaller specialty producers in Europe and India competing on production scale, cost efficiency, and regulatory certification. Leading lithopone companies are investing in export quality certifications and expanded production capacity to serve international paint, plastics, and coatings formulators seeking REACH and EPA compliant, non-toxic pigment alternatives. Competition is also intensifying around grade differentiation, as manufacturers increasingly offer higher zinc sulfide content grades to serve premium coatings and ink applications alongside standard commodity grades.
Several lithopone market players are prioritizing expanded export sales networks across Southeast Asia, the Middle East, and Latin America to diversify beyond domestic Chinese demand and reduce their exposure to regional pricing pressure. Other market players are pursuing targeted capacity investments and quality certifications to strengthen their position with international formulators seeking reliable, compliant pigment supply backed by consistent particle size and whiteness performance.
Founded in 1979 and headquartered in Xiangtan, Hunan Province, China, Xiangtan Red-Swallow Chemical Co. Ltd. specializes in the research, manufacturing, and sale of lithopone and zinc carbonate. The company operates the largest domestic lithopone production base in China, with an annual lithopone output of approximately 15,000 tonnes, and maintains sales relationships with customers across Asia, the Middle East, the Americas, and Oceania. Red-Swallow continues to leverage more than four decades of production experience to serve both domestic and export focused pigment customers.
Founded in 2003 and headquartered in Shanghai, China, Shanghai Yuejiang Titanium Chemical Manufacturer Co. Ltd. is a large scale inorganic fine chemical enterprise integrating research, production, and sales of titanium dioxide, lithopone, barium sulfate, and zinc oxide pigments. The company operates with an annual titanium dioxide supply capacity of approximately 100,000 tonnes and has expanded its lithopone and barium sulfate product lines to diversify its white pigment portfolio. Yuejiang continues to invest in intelligent production lines and automated inspection systems to support its international customer base.
Founded in 2010 and headquartered in Ticino, Switzerland, VB Technochemicals SA manufactures and distributes chemical and pharmaceutical products including lithopone, blanc fixe, special barite, zinc phosphate, and barium hydroxide. The company positions itself as a link between producers and end users, drawing on decades of founder experience in the development, management, and distribution of chemicals and pharmaceuticals. VB Technochemicals serves customers across five continents through its worldwide sales network.
Founded in 1979 and headquartered in Mumbai, Maharashtra, India, Heera Chemicals produces metals and chemicals including lithopone to serve the paints, coatings, and plastics industries. The company has built its position as a regional supplier serving Indian and South Asian formulators requiring cost effective white pigment alternatives. Heera Chemicals continues to serve customers seeking reliable, regionally sourced lithopone supply across the subcontinent.
Other key players in the market include Zhengzhou Sino Chemical Products Co., Ltd., Anhui Union Titanium Enterprise Co. Ltd., Wuhu Loman Chemical Co. Ltd., Langfang Pairs Horses Chemical Co., Ltd., and Titanos Group, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our lithopone market trends 2026 report. Discover regional growth patterns, grade differentiation trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 199.51 Million.
The market is assessed to grow at a CAGR of 3.30% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 276.04 Million by 2035.
Expanding export quality certifications, differentiating through higher grade zinc sulfide content products, strengthening regional distribution networks across emerging construction markets, and positioning lithopone as a non-toxic alternative amid tightening pigment regulations.
The key trends of the market include the ability of lithopone to improve the fungicidal properties of paints, rising utilisation of plastic products, and increasing demand for leather products.
The significant products available in the market include lithopone 28%, lithopone 30%, and lithopone 60%.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The key players in the market are Xiangtan Red-Swallow Chemical Co. Ltd., Zhengzhou Sino Chemical Products Co., Ltd., Anhui Union Titanium Enterprise Co. Ltd., Wuhu Loman Chemical Co. Ltd., Shanghai Yuejiang Titanium Chemical Manufacturer Co. Ltd., VB Technochemicals SA, Langfang Pairs Horses Chemical Co., Ltd., Titanos Group, and Heera Chemicals, among others.
Manufacturers face intensifying competition from titanium dioxide price fluctuations, tightening environmental compliance requirements, regional overcapacity in China's broader pigment industry, and margin pressure from low-cost commodity grade competition.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




