

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
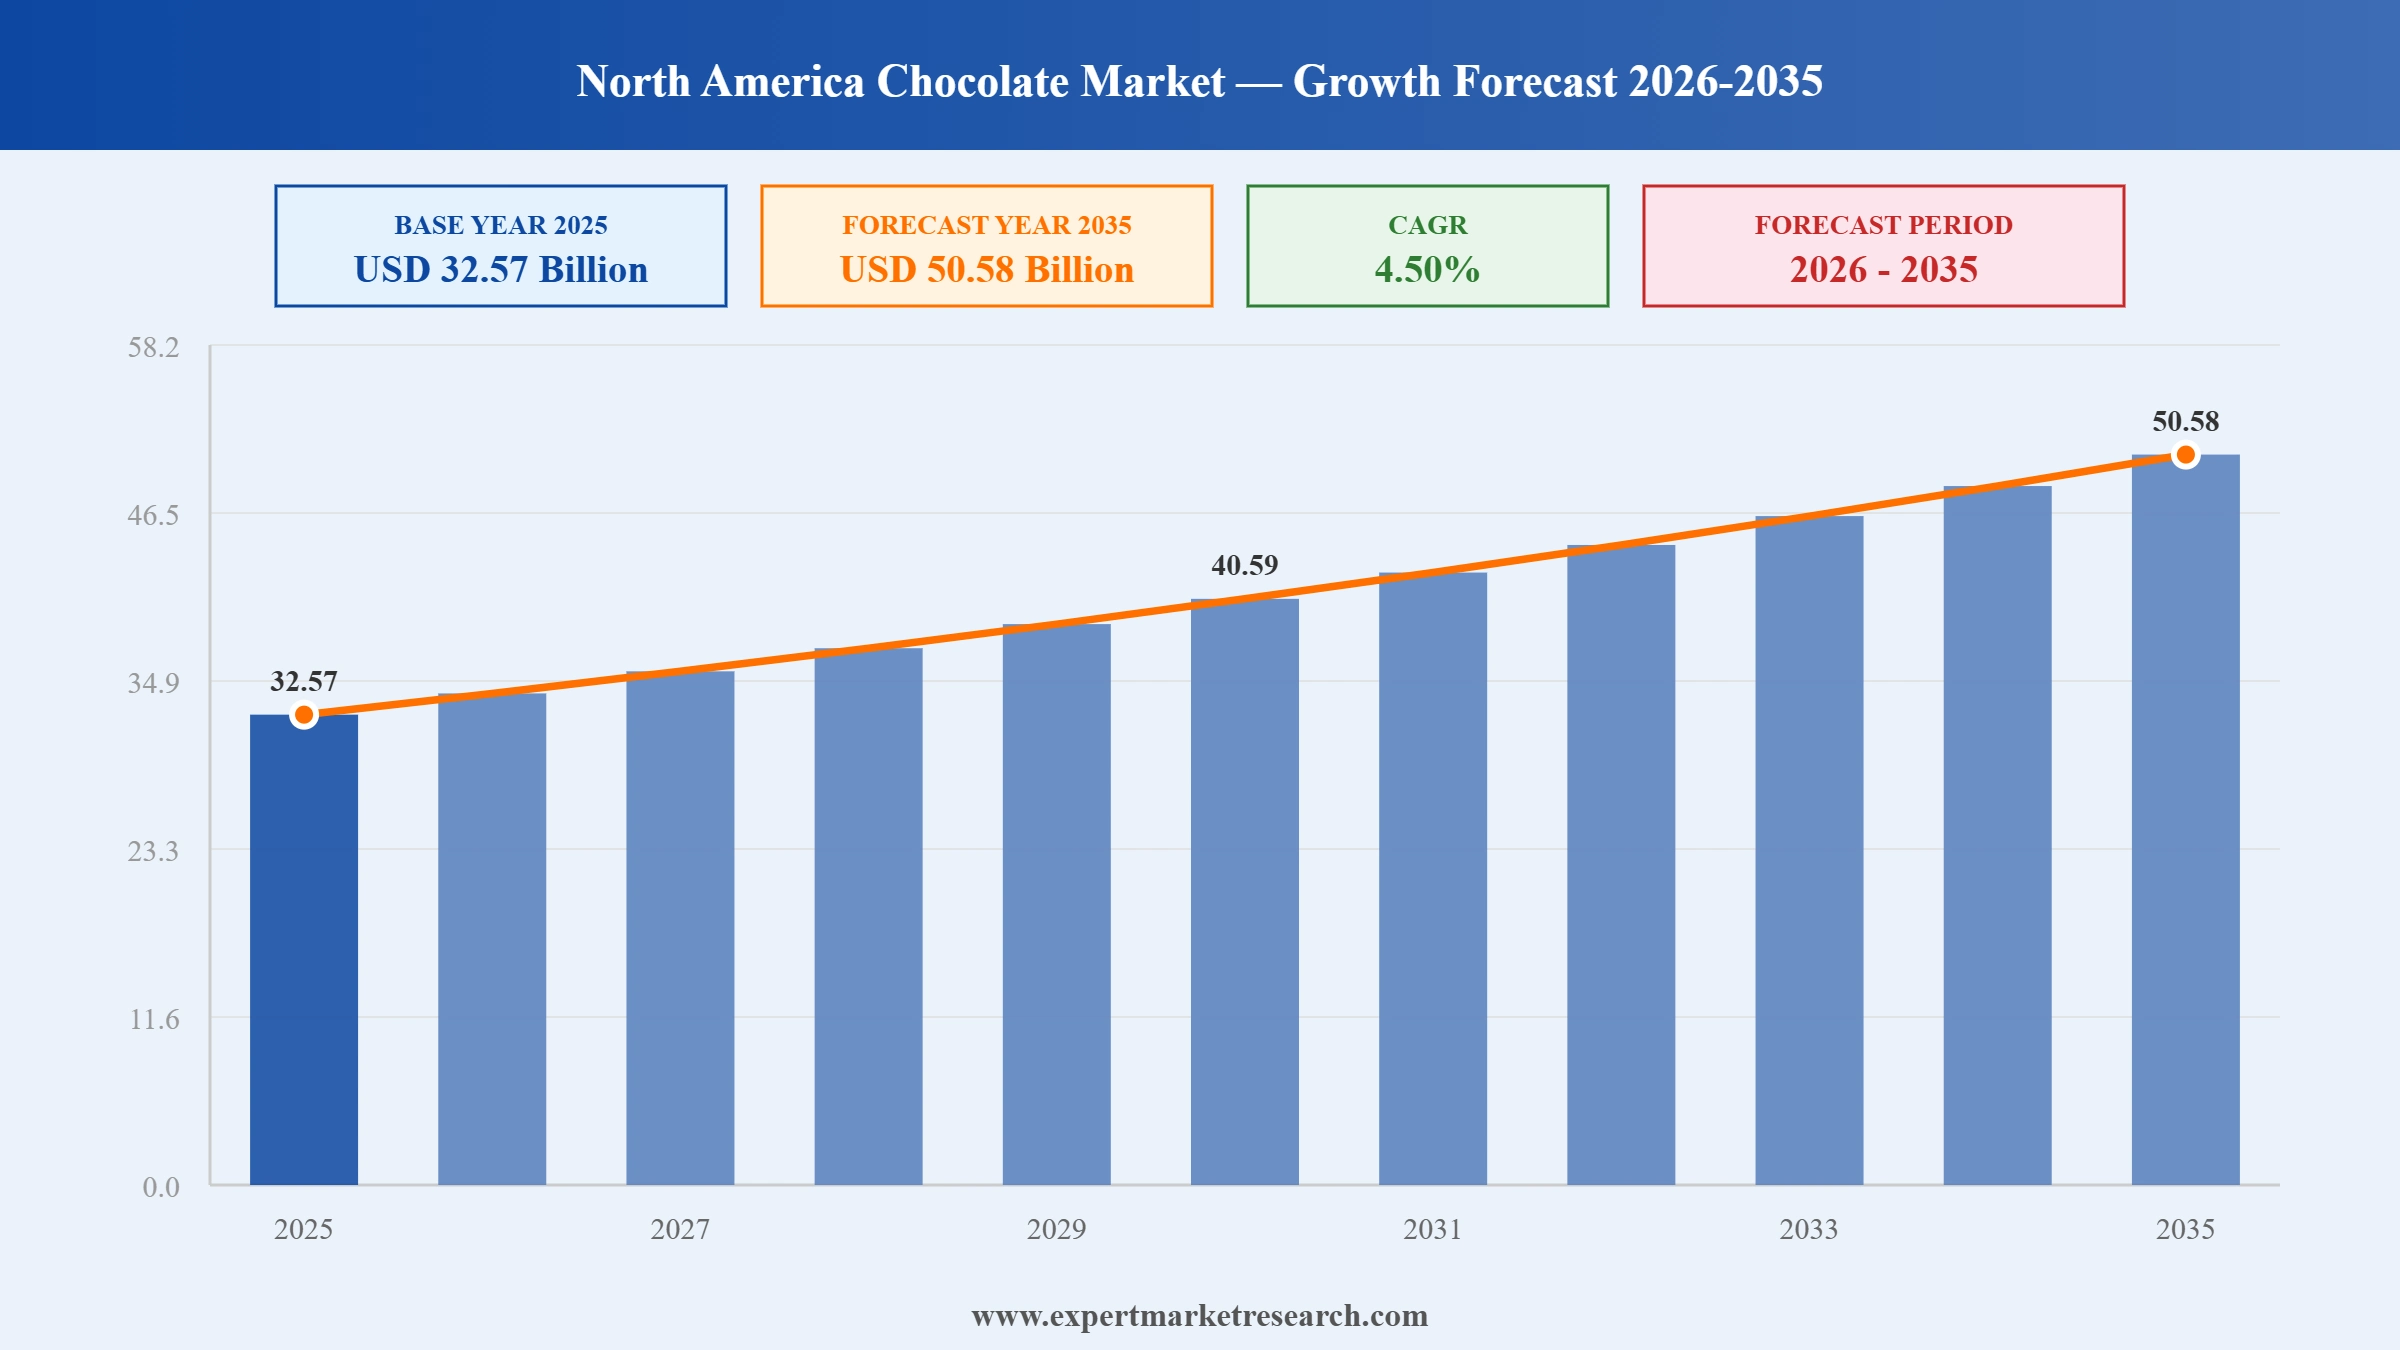
The North America chocolate market attained a value of USD 32.57 Billion in 2025 and is projected to expand at a CAGR of 4.50% through 2035. The market is further expected to reach USD 50.58 Billion by 2035. Rising demand for premium and single origin chocolates, together with growing interest in dark chocolate and functional confectionery, is helping manufacturers differentiate their product portfolios. Growing emphasis on sustainable cocoa sourcing, clean label ingredients, and expanding online retail channels is further encouraging established players to broaden their distribution footprint across the region.
Chocolate refers to a range of confectionery products made from roasted and ground cacao seeds, blended with varying proportions of cocoa solids, cocoa butter, sugar, and milk to create dark, milk, and white variants. Milk chocolate holds a substantial share of the market owing to its sweeter, softer texture and broad appeal across age groups. Rising demand for premium gifting and seasonal chocolate purchases continues to widen the customer base for chocolate products among households and specialty retailers across the region.
Demand is concentrating around manufacturers able to combine sustainable ingredient sourcing with novel product formats. In June 2026, Chocoladefabriken Lindt and Sprüngli AG achieved 100 percent Rainforest Alliance certified cocoa sourcing under its Farming Program, with certification labels set to appear progressively across its product packaging. This sustainability driven positioning is converting rising demand for alternative and sustainable chocolate formats directly into expanded adoption across the North America chocolate market.
Companies across the North America chocolate market are converging on a common development direction, widening from standalone chocolate bars toward diversified portfolios spanning functional, plant based, and premium gifting formats. Companies are increasingly pursuing new manufacturing capacity and product innovation to broaden combined offerings. This shift is reshaping competitive dynamics among companies, favouring companies who can demonstrate diversified formulation platforms over those offering standard chocolate products alone.
Read more about this report - REQUEST FREE SAMPLE
Barry Callebaut introduced ChoViva, a cocoa free chocolate alternative made from sunflower seeds, developed in partnership with Germany based Planet A Foods, at the Sweets and Snacks Expo in Las Vegas. The company also unveiled Cacao Max, a new premium cacao coating range. Companies across the North America chocolate market can use novel, non-cocoa formulations to offer customers alternatives during periods of volatile cocoa pricing and supply constraints.
Hershey opened a new chocolate processing plant after nearly three years of construction, forming part of a broader billion-dollar supply chain upgrade that will process key ingredients for brands including Reese's and Kit Kat. The facility strengthens the company's domestic manufacturing footprint. Companies across the North America chocolate market can use large scale supply chain investments to secure ingredient processing capacity for core confectionery brands.
Barry Callebaut announced a 70-million-dollar investment in its Chatham, Ontario factories in Canada, aimed at expanding liquid chocolate and moulding production lines while enhancing dairy free chocolate compound production. The investment strengthened the company's Canadian manufacturing footprint. Companies can use targeted facility investments to expand dairy free and compound chocolate capacity in response to shifting consumer preferences.
LesserEvil, a Danbury based retailer of organic popcorn and better for you snacks, was acquired by the major confectionery group for approximately 750 million dollars, expanding the acquirer's presence in the growing healthier snacking category. The deal reflected sustained investor interest in premium, clean label snack brands. Companies across the North America chocolate market can use targeted acquisitions of better for you snack brands to diversify revenue beyond core chocolate confectionery.
Chocolate manufacturers are increasingly introducing cocoa free and alternative formulations to offer customers options during periods of volatile cocoa pricing and constrained cacao supply. This is reshaping product development strategy across the North America chocolate market, favouring companies who can demonstrate credible alternative ingredient platforms. In March 2026, the National Confectioners Association reported that confectionery sales reached a record 55 billion dollars in 2025, with chocolate accounting for 51.7 percent of total category sales.
Major confectionery companies are increasingly investing in domestic processing capacity to secure ingredient supply for core chocolate brands amid ongoing cocoa price volatility. This is reshaping manufacturing footprint decisions across the North America chocolate market, favouring companies who can commit capital to multiyear facility upgrades. In November 2025, Godiva launched a new brand identity and its first Holiday Collection under the refreshed look, marking the start of centennial celebrations ahead of its 100th anniversary in 2026.
Confectionery companies are increasingly diversifying into better for you snacking categories to capture health-conscious consumers seeking alternatives to traditional chocolate products. This is reshaping portfolio strategy across the North America chocolate market, favouring companies who can integrate acquired snack brands into existing distribution networks. In July 2025, Chocxo Group announced the acquisition of Endangered Species Chocolate, a mission-based chocolate brand, extending its portfolio of premium, story driven confectionery offerings.
Chocolate producers are increasingly expanding Canadian manufacturing footprints to serve growing dairy free and compound chocolate demand across North America. This is reshaping regional production capacity across the North America chocolate market, favouring producers who can commit to multiyear facility investment programmes. In January 2026, See's Candies marked its 105th anniversary with the launch of a new Milk Scotchmallow product, continuing a tradition of handcrafted confectionery production.
Industry associations and major producers are increasingly launching collaborative sustainability initiatives to support cocoa farming communities and strengthen supply chain resilience. This is reshaping stakeholder engagement across the market, favouring companies who can demonstrate coordinated industry action. In October 2025, Meiji Holdings unveiled plans to introduce chocolate flavoured foods made with cell cultured cacao in the United States, partnering with California Cultured Inc. to address rising cacao supply pressures.
The Expert Market Research's report titled "North America Chocolate Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
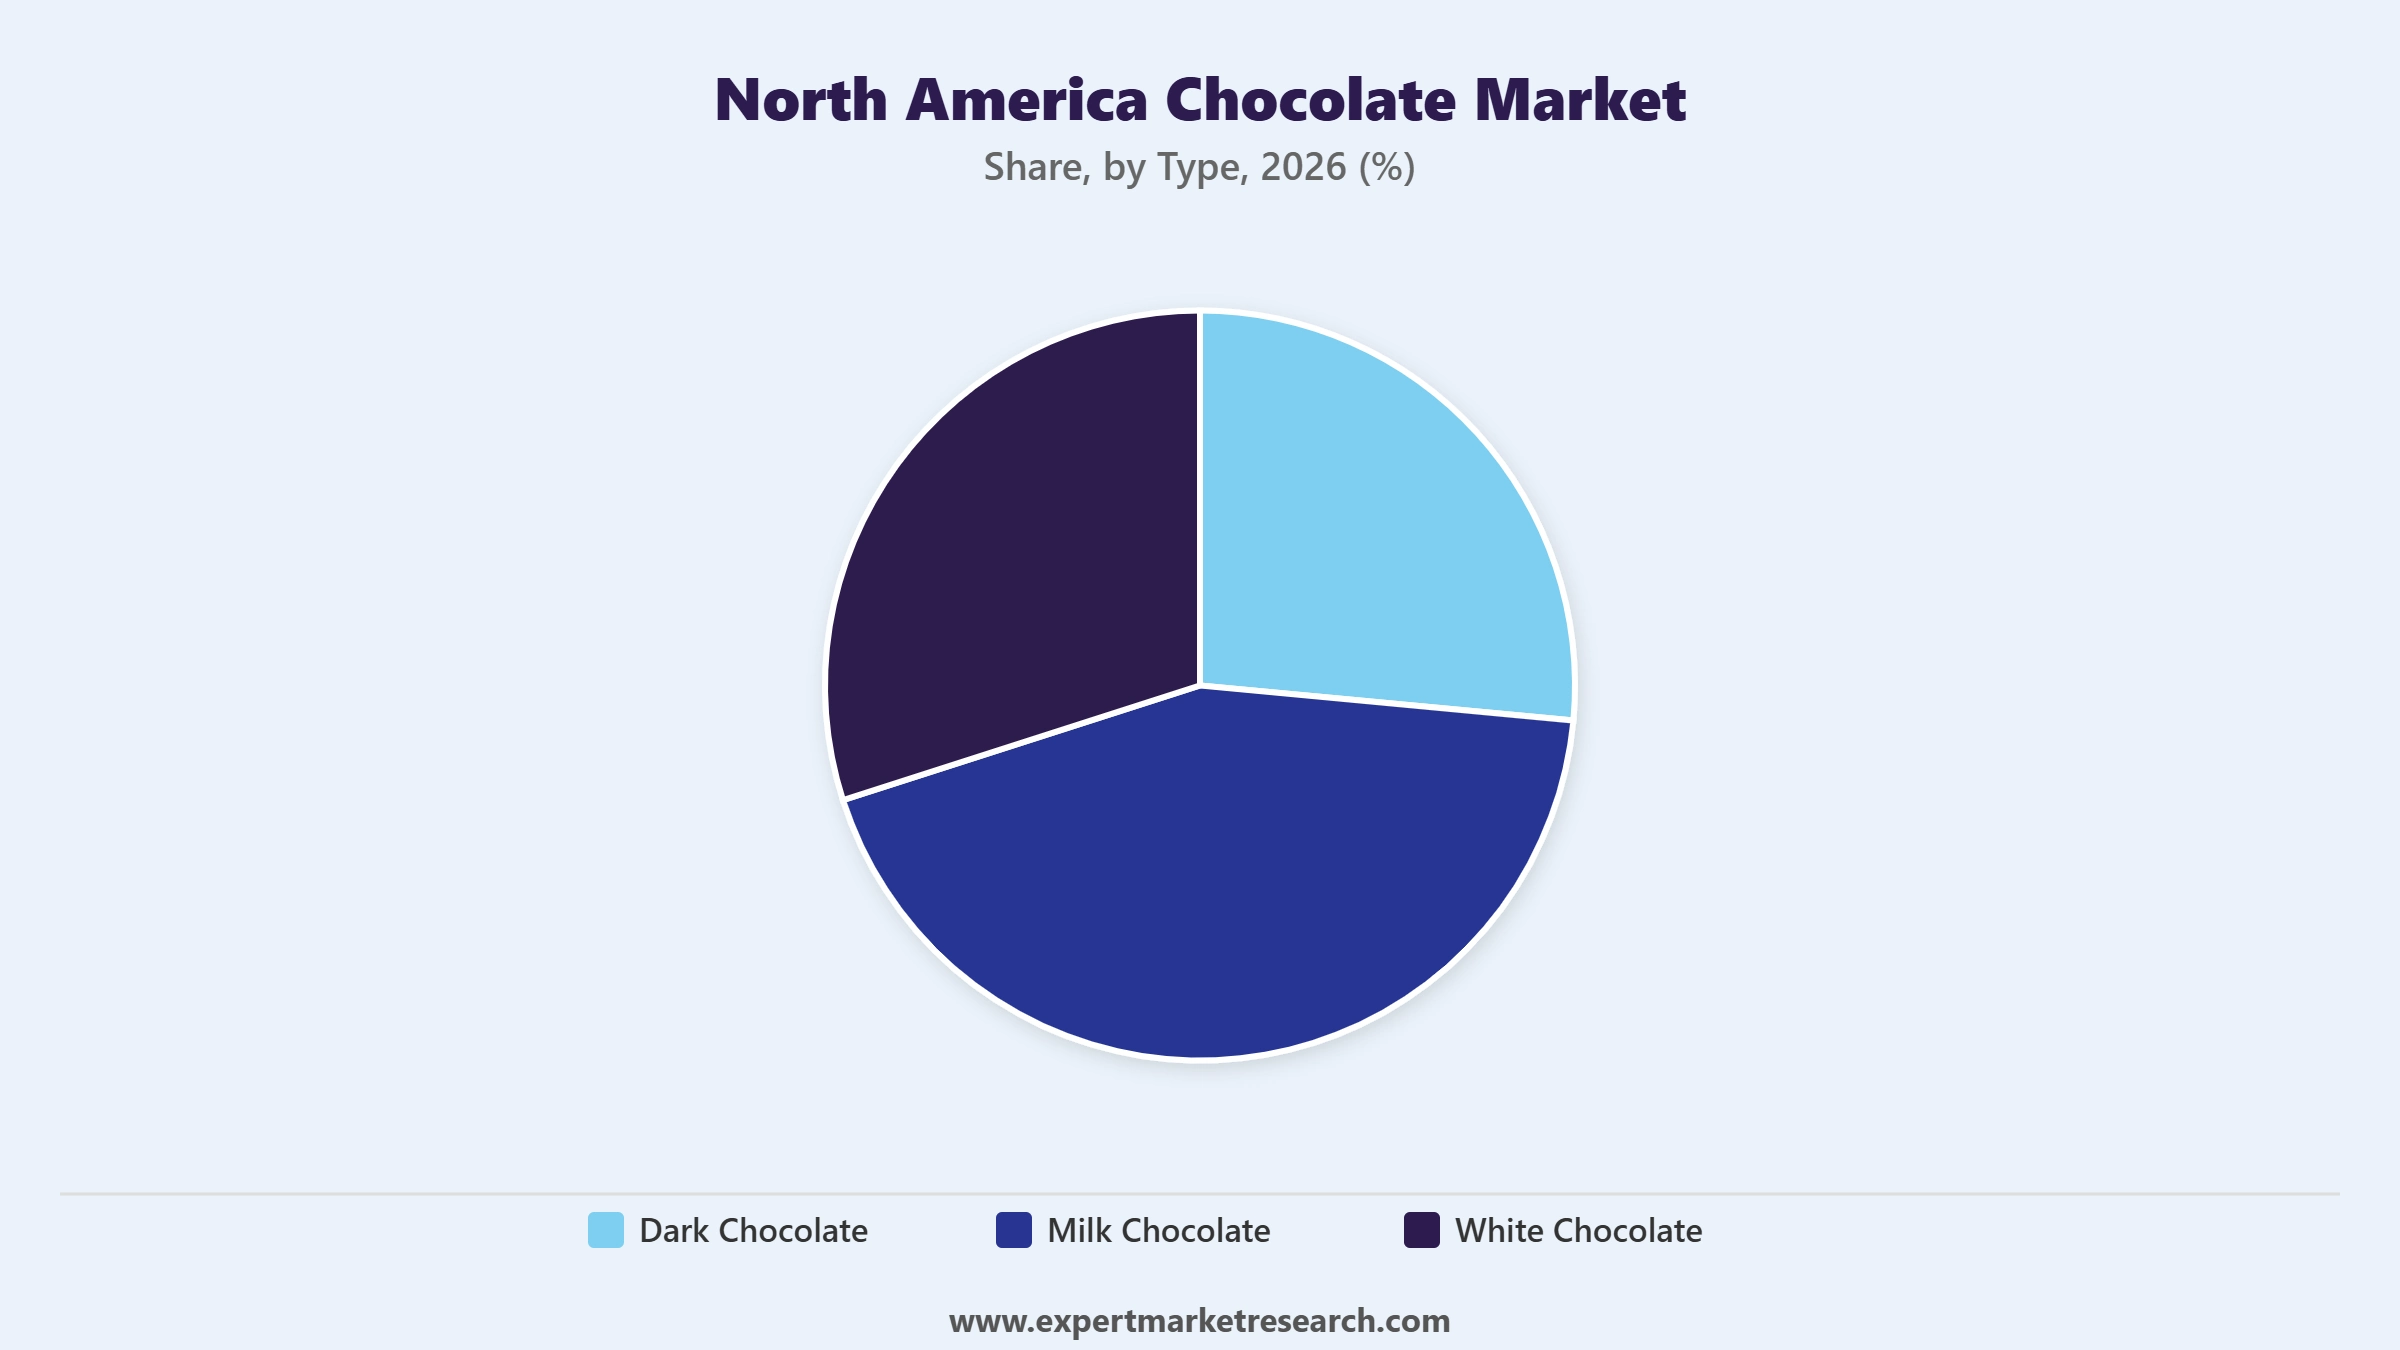
Key Insight: Milk chocolate dominates the type of segment across the North America chocolate market given its sweeter, softer texture and broad appeal across age groups and consumption occasions. In July 2026, Ghirardelli introduced a new Premium Milk Chocolate Bar line across three varieties, distributed through major national retailers including Walmart, Target, and Kroger. White chocolate is registering the fastest growth as manufacturers introduce premium and flavoured variants targeting younger consumers. Dark chocolate maintains steady demand given growing consumer interest in higher cocoa content and perceived health benefits associated with antioxidant rich formulations.
Market Breakup by Product Type
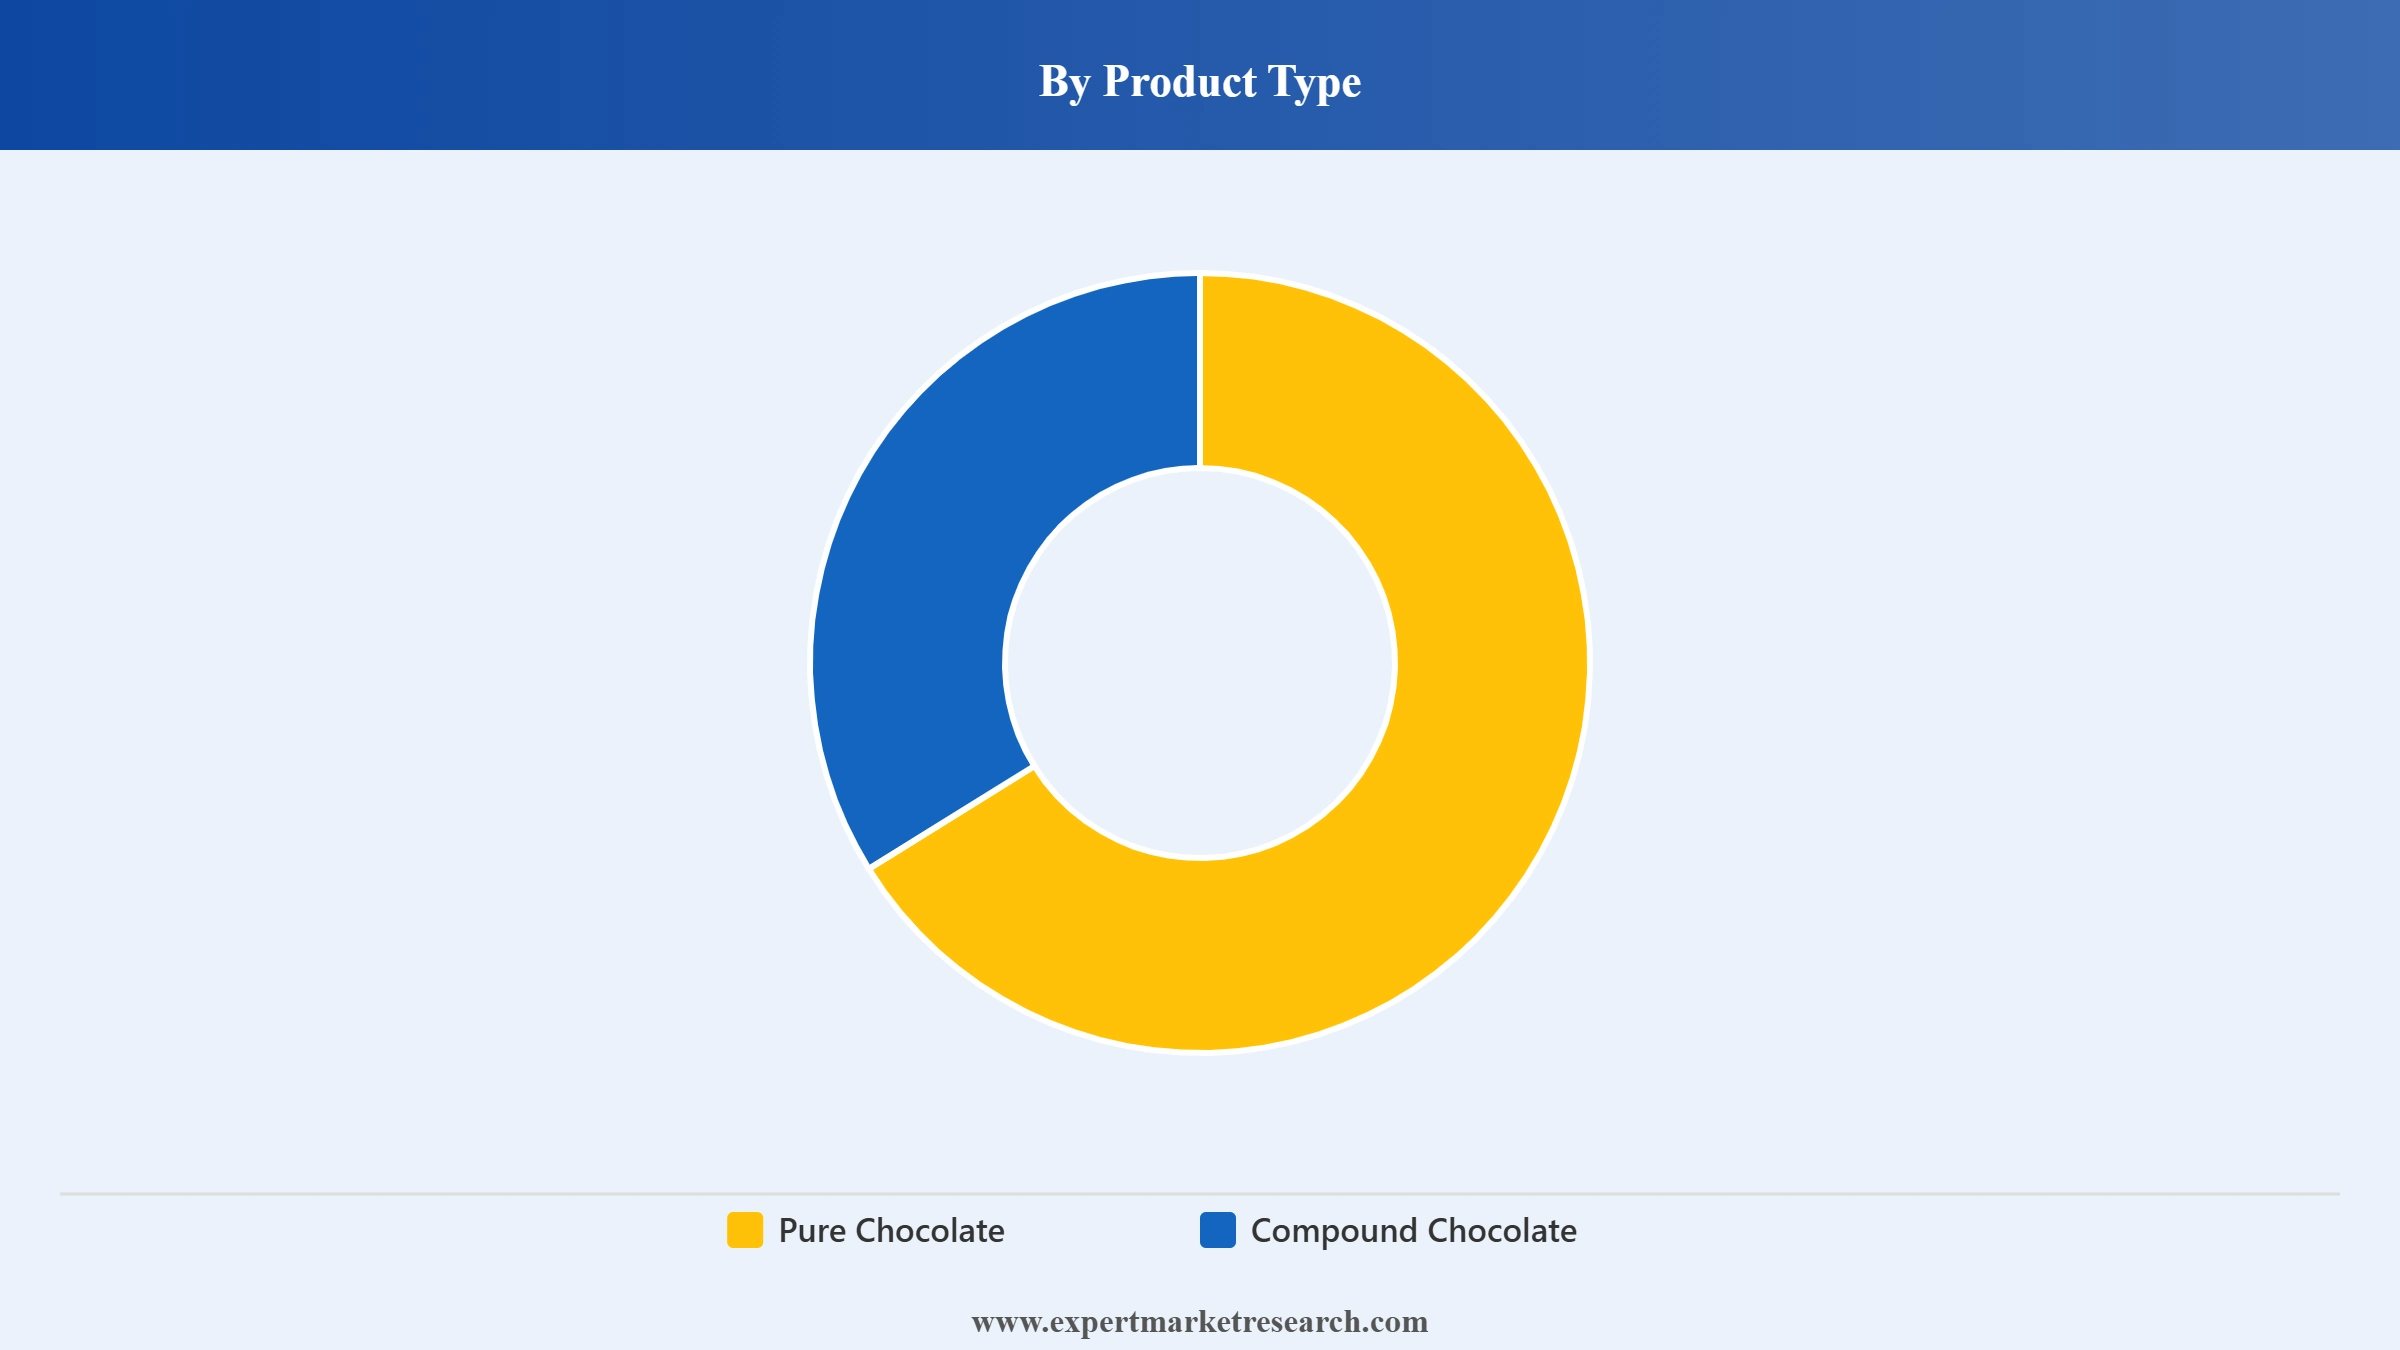
Key Insight: Pure chocolate dominates the product type segment in the North America chocolate market given consumer preference for authentic cocoa butter-based formulations in premium and gifting applications. Compound chocolate is registering the fastest growth as bakery, confectionery, and frozen dessert manufacturers seek cost efficient alternatives with greater temperature stability than couverture chocolate.
Market Breakup by Distribution Channel
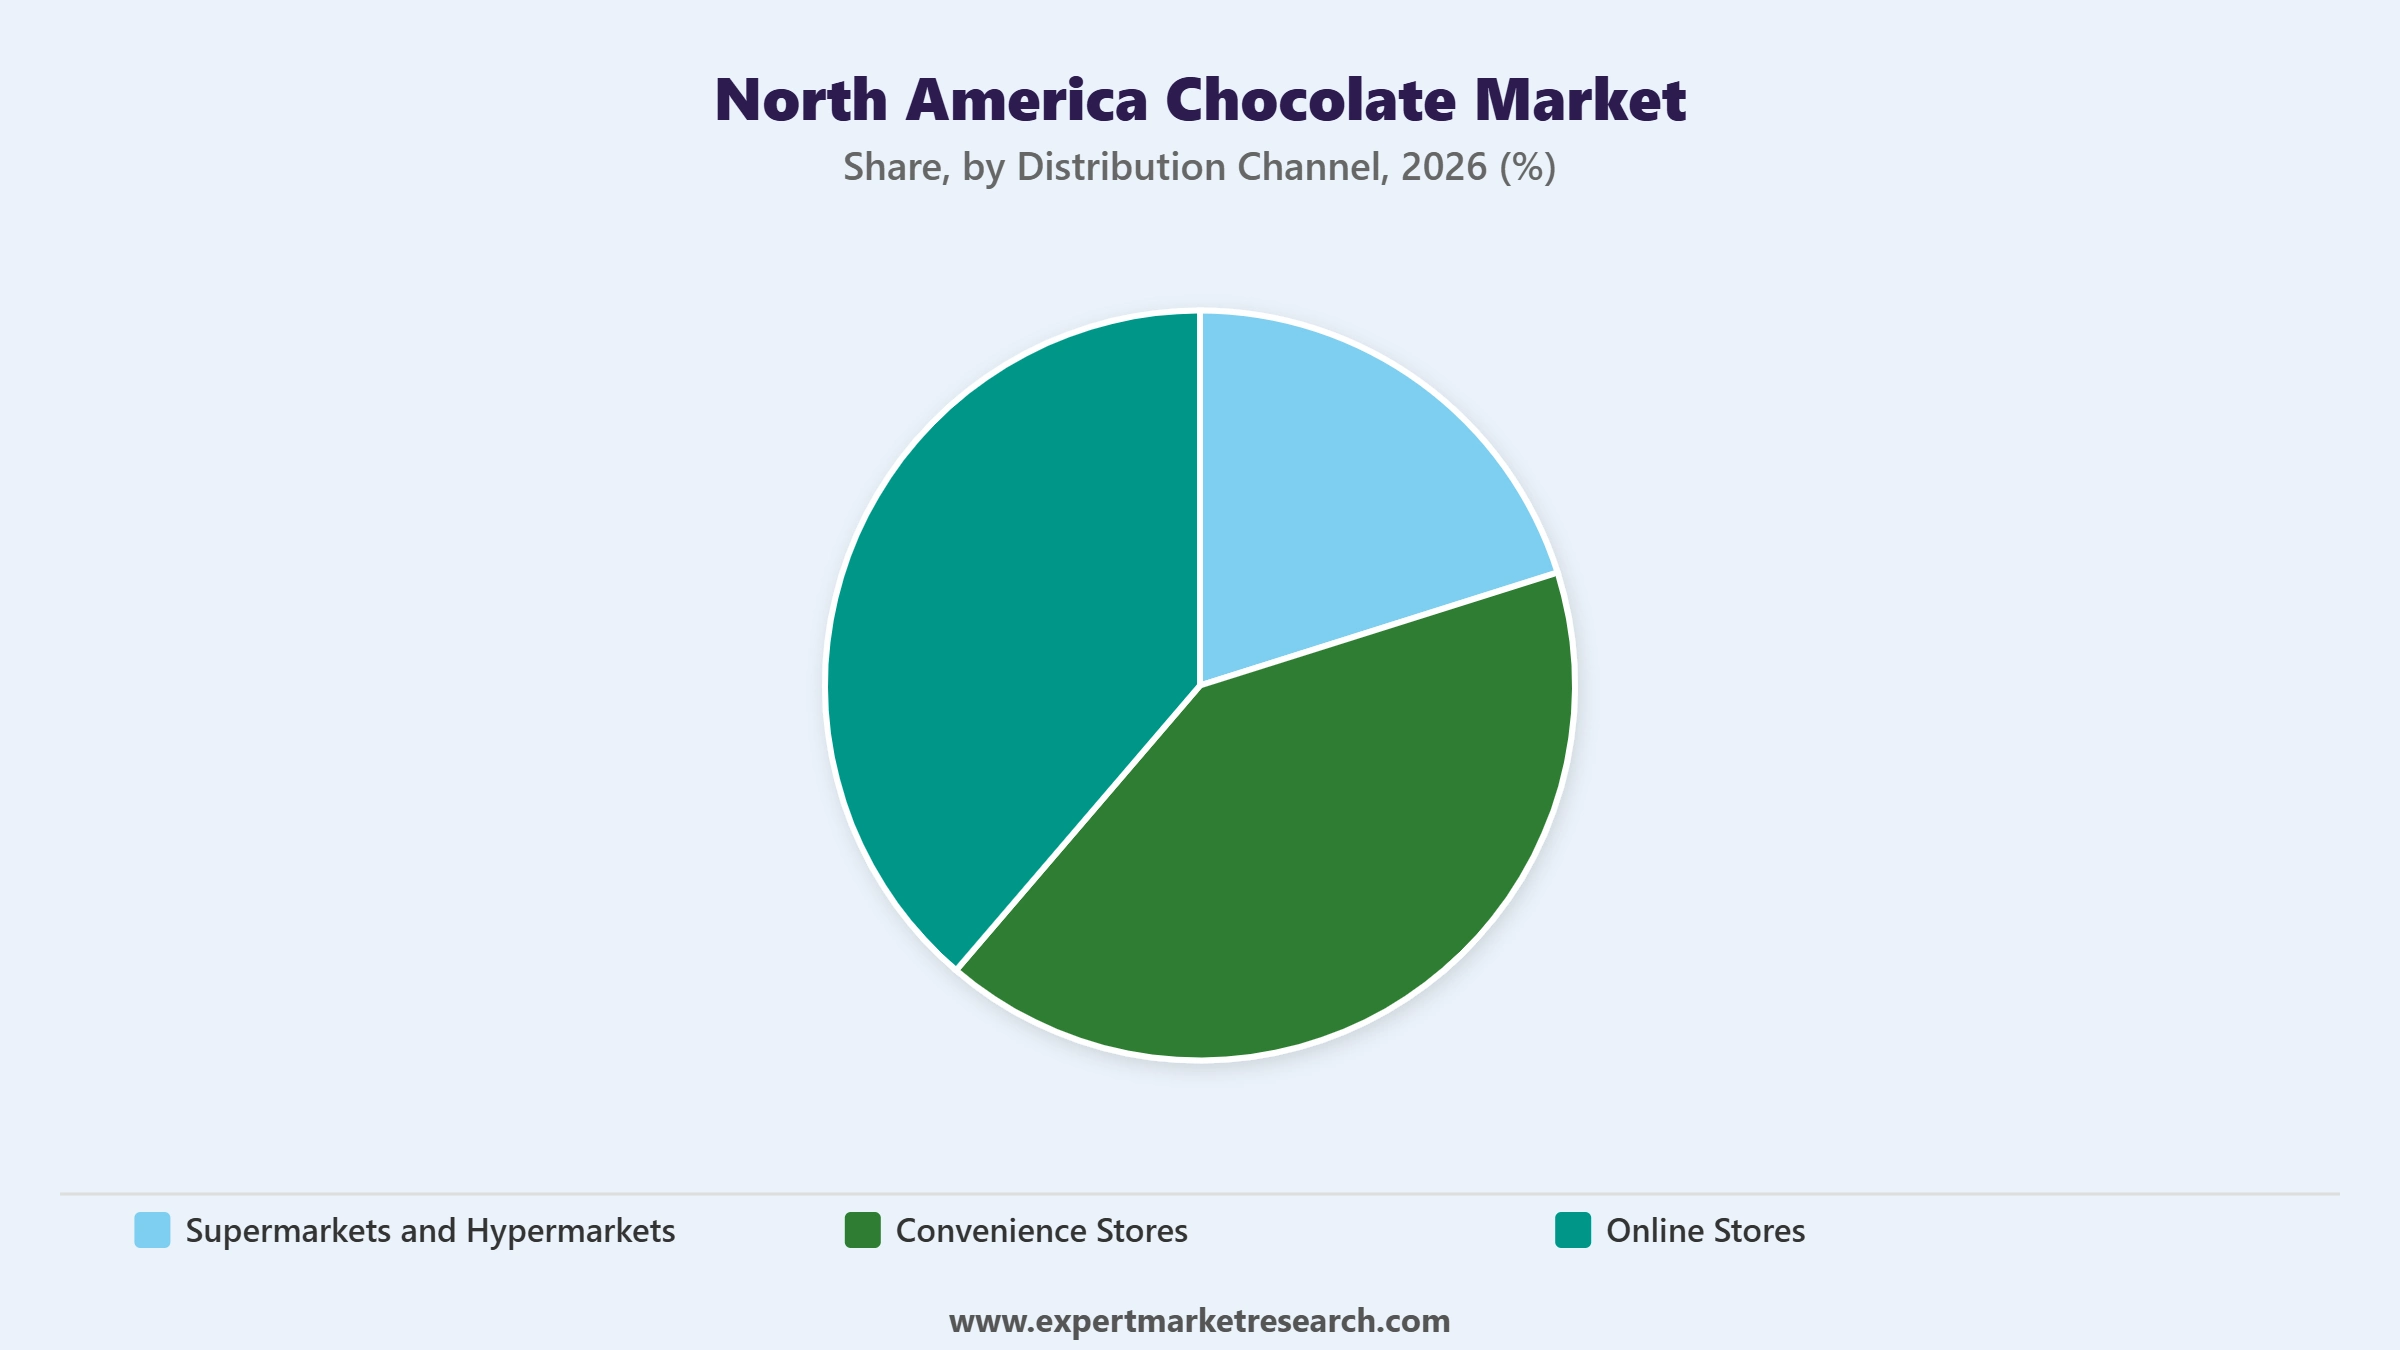
Key Insight: Supermarkets and hypermarkets dominate the distribution channel segment in the North America chocolate market given their broad product assortment and established position as primary grocery destinations across the region. Online channels are registering the fastest growth as direct to consumer subscription models and e-commerce gifting platforms expand reach beyond traditional retail. Convenience stores and other channels, including specialty and gift shops, continue to serve impulse purchase and premium gifting occasions respectively. In September 2025, August Storck unveiled new festive packaging designs across its Werther's, Toffifee, and Merci brands to strengthen seasonal retail presentation.
Market Breakup by Region
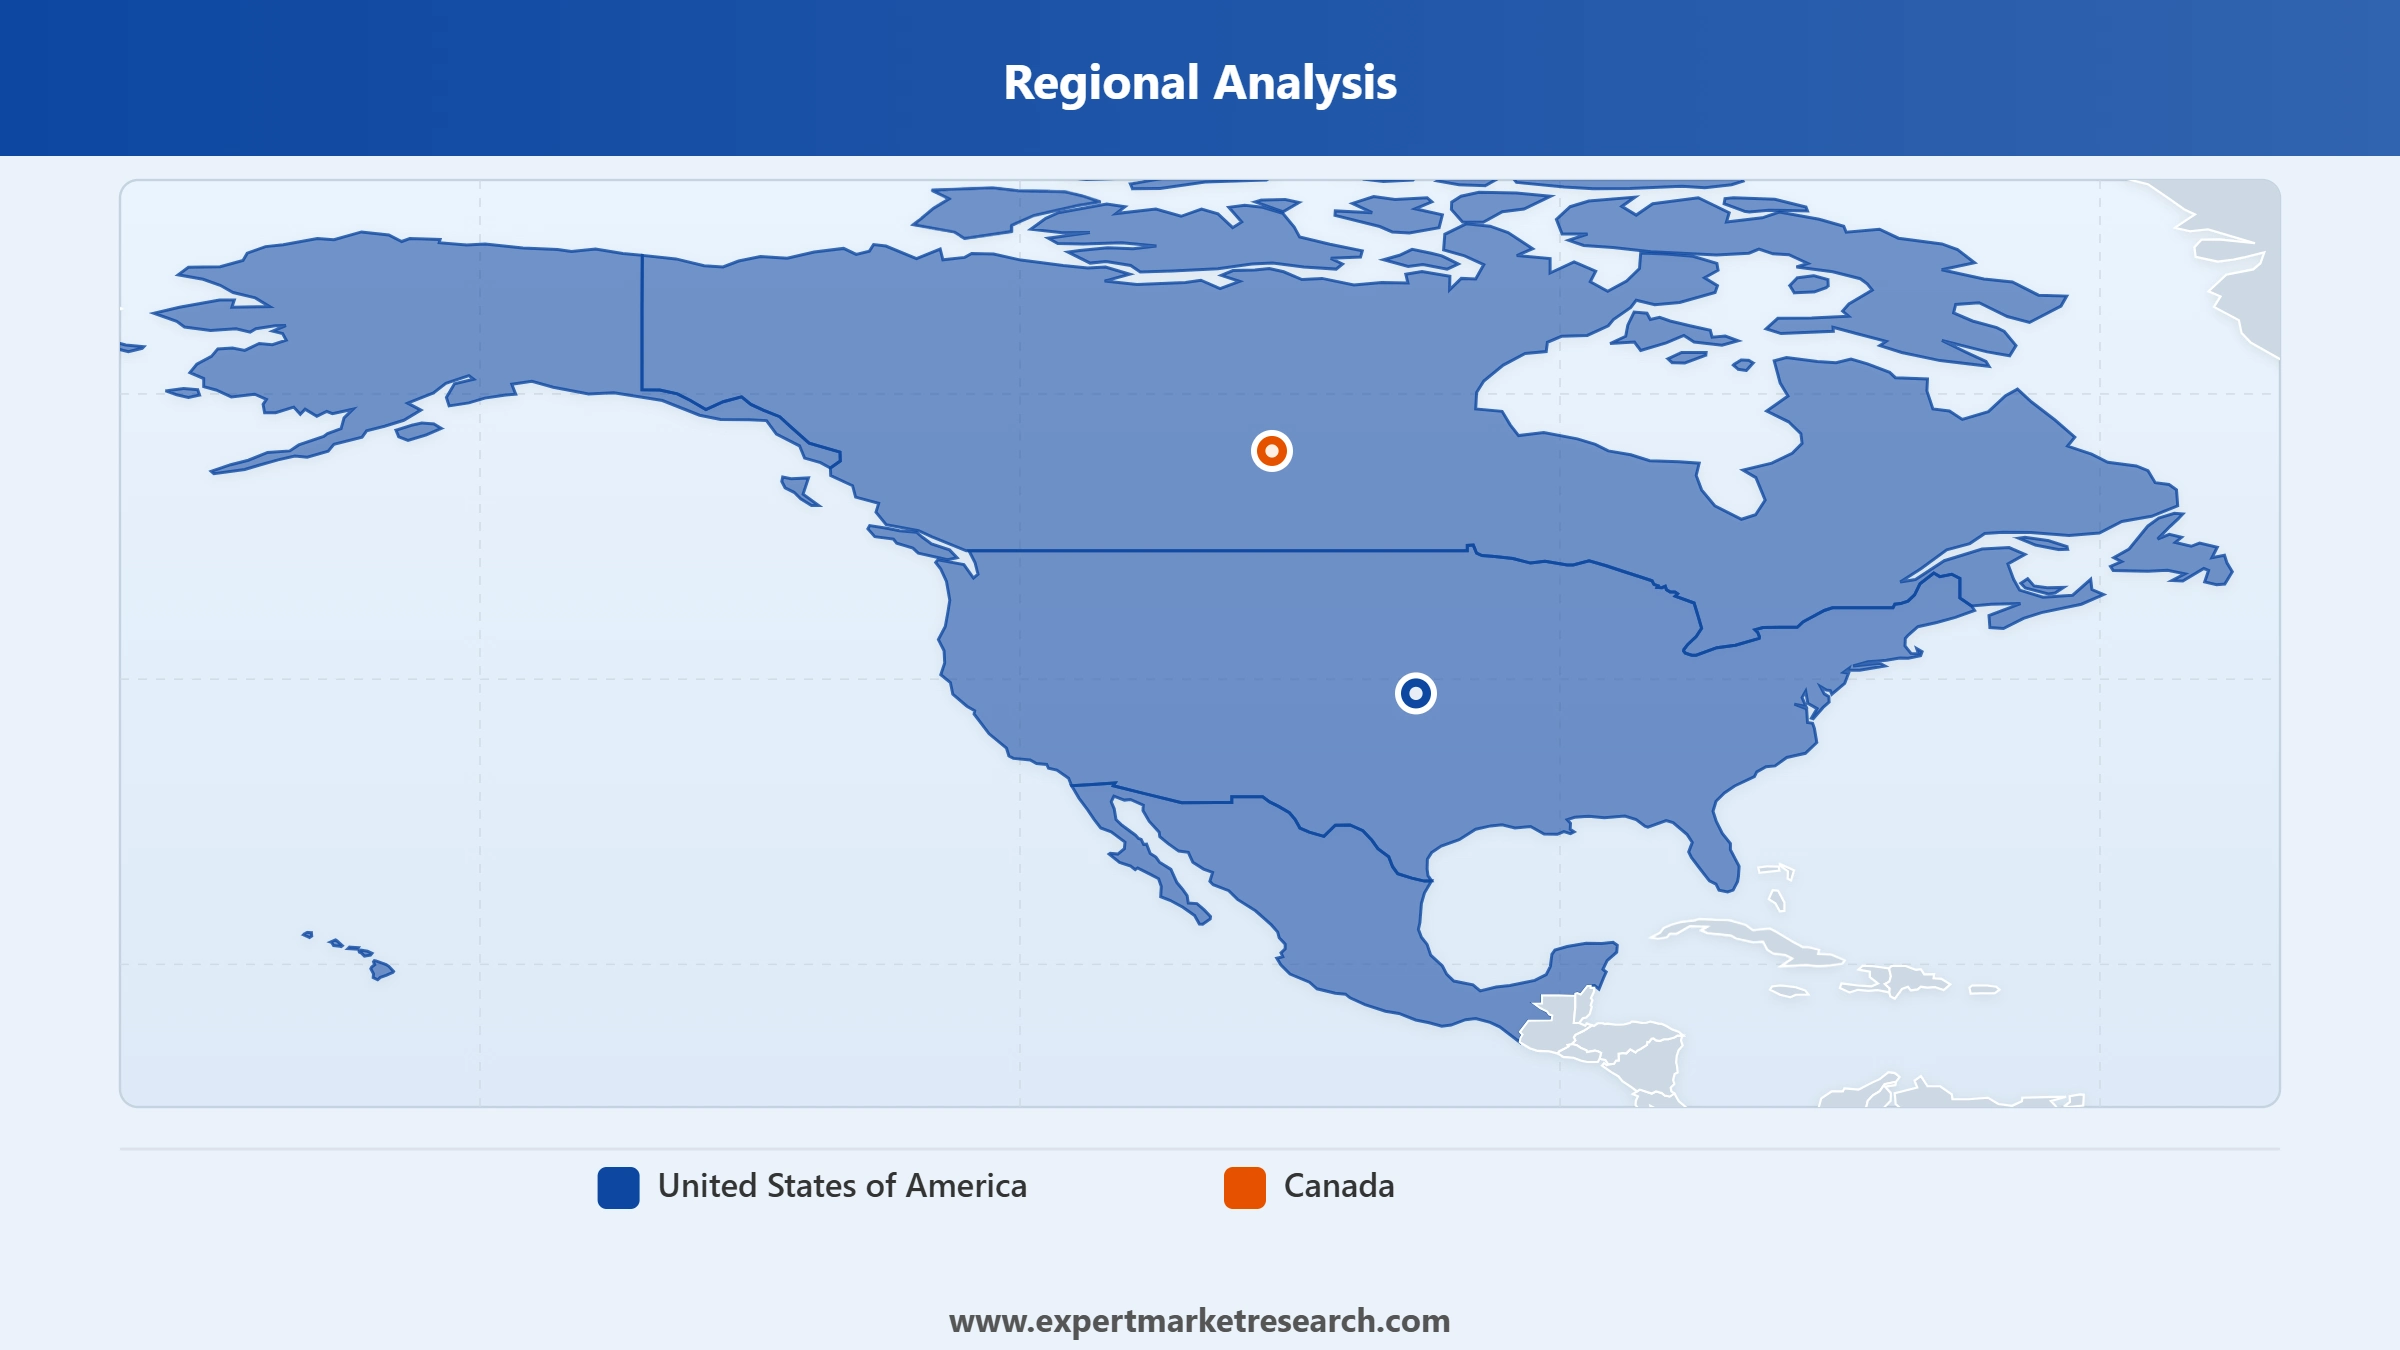
Key Insight: The United States dominates the country breakup in the North America chocolate market given its large consumer base and extensive retail and manufacturing infrastructure. Canada sustains steady demand through growing interest in ethically sourced and organic chocolate products, supported by expanding dairy free and compound chocolate manufacturing capacity.
Read more about this report - REQUEST FREE SAMPLE
Milk chocolate dominates the type of segment of the North America chocolate market given its sweeter, softer texture and broad appeal across age groups and consumption occasions nationwide, since this profile suits everyday snacking and gifting alike across every retail format and price point available today. Manufacturers serving this category continue to prioritise flavour consistency accordingly, since broad consumer familiarity increasingly rewards dependable, recognisable taste profiles across product lines and packaging formats spanning bars, bites, and seasonal assortments sold throughout the calendar year across every major retail channel nationwide.
Read more about this report - REQUEST FREE SAMPLE
White chocolate is registering the fastest type of growth as manufacturers introduce premium and flavoured variants targeting younger consumers and social media driven purchasing trends across every retail channel and packaging format available to shoppers today, from grocery aisles to specialty gifting displays. In March 2026, Grupo Arcor announced a joint venture with Danone to develop the local dairy market in Argentina, integrating dairy businesses relevant to milk-based chocolate formulations and broader confectionery ingredient supply across the region.
Pure chocolate dominates the product type segment in the North America chocolate market given consumer preference for authentic cocoa butter-based formulations in premium and gifting applications nationwide, since consumers increasingly associate authenticity with higher quality and richer sensory experience overall across every price tier and occasion. In August 2025, Russell Stover launched its Dubai Style Chocolate, a milk chocolate bar featuring pistachio filling and crispy kataifi texture, extending its offerings beyond its no sugar added segment into trend driven indulgence across every retail channel.
Read more about this report - REQUEST FREE SAMPLE
Compound chocolate is registering the fastest product type growth as bakery, confectionery, and frozen dessert manufacturers seek cost efficient alternatives with greater temperature stability than couverture chocolate across every application and climate condition nationwide, particularly in warmer distribution environments and long-haul shipping routes spanning the continent. Manufacturers serving this category continue to prioritise dairy free formulation accordingly, since plant-based compound recipes increasingly meet demand from both bakery and retail customers seeking allergen friendly ingredient options across every product category and packaging format available today.
Supermarkets and hypermarkets dominate the distribution channel segment in the North America chocolate market given their broad product assortment and established position as primary grocery destinations across the region nationwide and beyond every major metropolitan area today, anchoring most everyday purchases across every demographic. In May 2025, Trader Joe's began selling its own version of the viral Dubai style chocolate bar, becoming one of several major grocery retailers to launch a version of the trending pistachio and kataifi treat nationwide and beyond.
Read more about this report - REQUEST FREE SAMPLE
Online channels are registering the fastest distribution channel growth as direct to consumer subscription models and e-commerce gifting platforms expand reach beyond traditional retail across every demographic and geographic market segment nationwide, particularly among younger, digitally native shoppers seeking convenience and personalisation. Retailers serving this category continue to prioritise personalised packaging accordingly, since customisable online gifting options increasingly differentiate digital channels from standard retail shelves and displays available in stores across the region and beyond every major market.
Read more about this report - REQUEST FREE SAMPLE
The United States dominates the country breakup of the North America chocolate market given its large consumer base and extensive retail and manufacturing infrastructure nationwide, since scale advantages continue to reinforce its lead across every regional market and demographic segment today, from coast to coast and border to border. In April 2025, Hotel Chocolat opened two new retail stores in Chicago, marking the premium chocolatier's re-entry into the United States market after previously exiting in 2022 to focus on its home market.
Canada sustains steady demand through growing interest in ethically sourced and organic chocolate products, supported by expanding dairy free and compound chocolate manufacturing capacity across every province and territory nationwide today, reflecting a broader shift toward transparency and traceability among conscious consumers. Regional producers continue to invest in production line upgrades to serve both retail and industrial confectionery customers across the country and adjacent export markets throughout North America and beyond every major distribution channel and format available.
The North America chocolate companies are becoming increasingly consolidated as major chocolate companies invest in product innovation, sustainable sourcing, and manufacturing capacity to defend their market positions. Chocolate players are prioritising alternative formulations, premium gifting formats, and expanded better for you portfolios to differentiate themselves in an increasingly competitive landscape shaped by volatile cocoa pricing.
Major North America chocolate market players are also focusing on sustainable cocoa sourcing and supply chain traceability, pursuing industry wide initiatives that strengthen farming community resilience. Opportunities are emerging in cocoa free formulations and expanding online direct to consumer channels. Companies that successfully combine innovative formulations with resilient sourcing are expected to strengthen their competitive position over the coming years.
Founded in 1911 and headquartered in McLean, Virginia, United States, Mars, Incorporated supports the chocolate market through its Mars Wrigley confectionery division, offering brands including M&M's, Snickers, and Twix across the region. The company continues to expand its confectionery and snacking portfolio through targeted acquisitions. Mars draws on its position as one of the world's largest privately held confectionery companies to serve a broad North American customer base.
Founded in 2012 and headquartered in Chicago, Illinois, United States, Mondelez International, Inc. contributes to the chocolate market through brands including Cadbury, Milka, and Toblerone, alongside its broader biscuit and snacking portfolio. The company continues to expand its premium and functional chocolate offerings. Mondelez draws on its position as a leading global snacking company to serve customers across every major distribution channel.
Founded in 1946 and headquartered in Senningerberg, Luxembourg, Ferrero International S.A. supports the chocolate market through brands including Nutella, Ferrero Rocher, and Kinder, sold across premium gifting and everyday consumption occasions. The company continues to expand its craft quality product portfolio while emphasising responsible sourcing. Ferrero draws on its position as a leading family-owned confectionery company to serve customers across North America and international markets.
Founded in 1866 and headquartered in Vevey, Switzerland, Nestlé S.A. contributes to the chocolate market through brands including KitKat, Smarties, and Milkybar, alongside its broader food and beverage portfolio. The company continues to expand its confectionery innovation and sustainable cocoa sourcing initiatives. Nestlé draws on its position as the world's largest food and beverage company to serve customers across every major regional market.
Other key players in the market include The Hershey Company, Barry Callebaut AG, Grupo Arcor, Chocoladefabriken Lindt & Sprüngli AG, August Storck KG, and Meiji Holdings Co., Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our chocolate market trends 2026 report. Discover country level growth patterns, type and product economics, and key industry players. Stay ahead of the competition and identify emerging opportunities in the evolving North America chocolate market landscape.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 32.57 Billion.
The market is projected to grow at a CAGR of 4.50% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 50.58 Billion by 2035.
Introducing cocoa free and alternative chocolate formulations, investing in domestic processing capacity, pursuing better for you category acquisitions, expanding dairy free compound production, and strengthening sustainable cocoa sourcing initiatives are key strategies driving the market.
Key trends aiding the market expansion include growing popularity of nut-infused chocolates, a shift in consumer preferences away from traditional sweet indulgences and increasing consumer expectations of premium products.
Countries considered in the market are United States of America and Canada.
Based on distribution channel, the market segmentations include supermarkets and hypermarkets, convenience stores, and online stores, among others.
Dark chocolate, milk chocolate, and white chocolate are considered in the report.
The key players in the market include Mars, Incorporated, Mondelez International, Inc., Ferrero International S.A., Nestlé S.A., The Hershey Company, Barry Callebaut AG, Grupo Arcor, Chocoladefabriken Lindt & Sprüngli AG, August Storck KG, and Meiji Holdings Co., Ltd., among others.
Companies face volatile cocoa pricing and supply constraints, competition from diversified confectionery manufacturers, evolving consumer health preferences, and the capital intensity of expanding sustainable and alternative formulation production capacity.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Product Type |
|
| Breakup by Distribution Channel |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




