

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The Saudi Arabia automotive engine oils market attained a value of USD 682.24 Million in 2025 and is projected to expand at a CAGR of 2.40% through 2035. The market is further expected to achieve USD 864.84 Million by 2035. High-temperature engine protection is creating a premiumization opportunity as Saudi Arabia had 15.8 million registered and roadworthy vehicles in 2024, up 6.9% year-on-year. Road freight imports also increased 7.1% to 12.2 million tonnes, highlighting sustained vehicle utilization. These conditions support demand for advanced lubricants that maintain viscosity, control deposits and protect engines under intensive operating conditions.
The Saudi automotive engine oils market is benefiting from vehicle technology upgrading and fleet utilisation intensity. Newer gasoline engines increasingly require low-viscosity, high-performance formulations with tighter OEM specifications, encouraging movement towards synthetic and technically approved products rather than purely price-led lubricant selection. Castrol's Saudi product range already encompasses grades like 0W-20 and 5W-30 as well as the conventional ranges, thereby showing the increasing diversity in specifications available to the Saudi consumers. Moreover, commercial and heavy duty vehicles generate regular demand for lubricants since their maintenance is dependent on the uptime and efficiency of the vehicle. This gives suppliers opportunities to combine engine oils with technical services, lubricant monitoring, fleet programmes and workshop distribution rather than competing solely on product price, thereby boosting the Saudi Arabia automotive engine oils market value.
A particularly important structural development is the increasing technical differentiation between conventional lubricants and formulations designed around newer engine specifications. Global API performance upgrades, OEM approvals and lower-viscosity formulations are pushing suppliers towards higher-value products. At the same time, Saudi Arabia's position as a major energy and automotive market provides local supply-chain advantages for lubricant manufacturers and base-oil suppliers. Aramco's portfolio includes Group I and Group II base oils for automotive applications, strengthening the country's position within the broader lubricant value chain.
The gradual transition toward electric vehicles represents a long-term challenge for Saudi Arabia’s automotive engine-oil market. Battery-electric vehicles eliminate conventional engine-oil requirements, reducing lubricant consumption per vehicle as their penetration increases. The Saudi efforts to promote electric car production and development of infrastructure for recharging EVs will likely speed up this process, especially within large cities. Meanwhile, synthetic oils for longer use in IC engines will make oil changes less frequent, thus restraining further growth of this market. This means that engine oil producers should find ways of integrating the existing range of products for ICEs with new types of oils. This powertrain transition could gradually alter the market’s product mix and place greater pressure on companies dependent on conventional engine-oil volumes, thus aiming more towards the Saudi Arabia automotive engine oils market developments.
Compound Annual Growth Rate
2.4%
Value in USD Million
2026-2035
Read more about this report - Request a Free Sample
Shell and Hyundai Motor renewed their global cooperation agreement for another five years, with Shell retaining its position as Hyundai's recommended aftersales lubricant supplier globally. The partnership will continue product-development and aftersales collaboration while expanding service-marketing activities. Such OEM relationships strengthen lubricant credibility and help suppliers secure specification-led aftermarket demand. Stronger OEM alignment can support premium lubricant adoption and brand preference.
ExxonMobil outlined measures to maintain lubricant supply during major disruptions affecting premium base-oil availability, including integrated manufacturing assets, reformulation capabilities and diversified sourcing. The company specifically highlighted Mobil 1 synthetic motor oil within the affected lubricant value chain. Supply resilience is likely to become a more important procurement criterion for Saudi distributors, workshops and fleet customers seeking dependable lubricant availability.
FUCHS formally launched its FUCHS100 strategy in China in April 2026, targeting higher-potential growth areas amid automotive transformation, sustainability requirements and market upgrading. The company is placing greater emphasis on focused resource allocation and technically advanced specialty solutions as competition intensifies in generic lubricants. The strategy highlights the industry's shift towards higher-value, technically differentiated lubrication products rather than volume-led commodity competition.
TotalEnergies announced that six of its lubricants had secured official approval under Stellantis' new FPW9.55535/XX specification framework. The updated requirements became effective from January 2026 and consolidated numerous legacy specifications while raising performance expectations. Stricter OEM specifications encourage suppliers and distributors to prioritise approved products, strengthening premiumisation and technical qualification across automotive lubricant channels.
The transition towards newer lubricant performance standards is encouraging Saudi suppliers to update formulations and portfolios. API SQ and ILSAC GF-7 requirements place greater emphasis on engine protection, oxidation control, deposit management and fuel efficiency. Chevron's lubricant business reported that its GF-7 passenger-car motor-oil range was introduced as the market moved towards the newer specification, while its 2026 outlook identifies continued demand for full synthetics and synthetic blends. For Saudi distributors, specification-led selling provides an opportunity to move customers from commodity products towards higher-value oils supported by OEM and industry approvals.
Engine downsizing and efficiency optimization are increasing demand for technically sophisticated low-viscosity lubricants. Castrol's Saudi portfolio includes 0W-20 products, reflecting the growing relevance of formulations designed for newer engine architectures. These products can support fuel-economy objectives while maintaining protection when formulated against appropriate OEM and industry requirements. The opportunity for Saudi lubricant suppliers is therefore not simply to expand synthetic volumes, but to build application-specific portfolios around vehicle model, engine specification and recommended viscosity. This creates stronger technical differentiation between suppliers and gives workshops a more important role in lubricant selection and specification compliance, thus shaping the Saudi Arabia automotive engine oils market trends.
Saudi Arabia possesses an important upstream advantage because Aramco supplies base oils used across automotive and industrial lubricant applications. Its aramcoDURA range is an API Group I base oil aimed partly at mid-tier automotive applications, while aramcoPRIMA is a Group II base oil suitable for automotive and heavy-duty diesel lubricants. This domestic base-oil capability can support formulation consistency and regional supply resilience. For lubricant blenders, procurement strategies increasingly need to balance performance requirements, additive compatibility, formulation economics and supply continuity rather than focusing only on finished-oil purchasing costs.
Commercial customers are increasingly able to treat lubrication as part of broader maintenance management. ExxonMobil's 2026 discussion of lubricant supply resilience highlighted reformulation capability, diversified sourcing and integrated base-oil assets as mechanisms for maintaining product availability during supply disruptions. For Saudi fleet operators, this reinforces the importance of supplier reliability, approved alternatives and inventory planning. Lubricant companies that combine engine oils with technical support, oil-condition assessment, maintenance recommendations and dependable delivery can therefore create stronger B2B relationships with fleet operators than suppliers competing through product price alone.
The automotive lubricant opportunity is gradually broadening beyond conventional gasoline and diesel engines. Shell's global portfolio already includes conventional engine oils alongside fluids developed for electric-mobility applications, demonstrating how major lubricant companies are positioning around a changing vehicle technology mix. In Saudi Arabia, this does not eliminate near-term engine-oil demand; rather, it creates a need for suppliers to segment portfolios according to powertrain and application. Companies capable of serving conventional vehicles while developing adjacent thermal-management and specialised fluid offerings can protect their aftermarket relationships as the vehicle mix evolves.
The Expert Market Research’s report titled "Saudi Arabia Automotive Engine Oils Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Grade
Key Insight: Mineral oils continue to serve older vehicles and price-sensitive customers, particularly where owners prioritise lower upfront servicing costs over extended drain intervals. This is evident from the large number of motor vehicles present in Saudi Arabia and the independent workshops that are present in the country. Semi-synthetic oils have a significant middle ground market presence as they provide an effective balance between being relatively inexpensive yet providing better oxidation, deposit control and temperature resistance. Shell, for instance, has its Helix semi-synthetic range of motor oils for Saudi Arabian customers who wish to use a higher performing motor oil than the traditional mineral oil varieties. The fully synthetic variety of motor oils is making rapid inroads due to their better thermal stability and low deposit formation capability, thus boosting the Saudi Arabia automotive engine oils market growth.
Market Breakup by Engine Type
Key Insight: Gasoline engines continue to represent the core demand base, supported by Saudi Arabia’s large passenger-vehicle parc and the prevalence of Japanese, Korean and American gasoline-powered models. The demand for lubricants has started moving toward low viscosity and OEM approved oils, as new turbocharged engines need better deposit control, oxidation, and thermal stability. The significance of diesel oil still continues in heavy trucks, buses, construction equipment, and logistic fleets, as their longer operations with high loads and dust under extreme conditions require more lubrication. Fleet operators are mostly using API CK-4 and OEM approved synthetic lubricants. Alternative-fuel engines remain a smaller niche but offer longer-term potential as Saudi Arabia diversifies its mobility mix, particularly through hybrids and other lower-emission powertrains, encouraging lubricant suppliers to develop specialised formulations.
Market Breakup by Vehicle Type
Key Insight: Passenger cars continue to generate the broadest engine-oil demand, supported by Saudi Arabia’s large passenger-vehicle base, high SUV usage and recurring servicing requirements. Light commercial vehicles have been experiencing increasing popularity due to last-mile deliveries, e-commerce and logistics applications, including those in fleets operated by contractors, especially in Riyadh, Jeddah and other logistics centers. Heavy-duty vehicles have been taking advantage of the growth in construction, cargo hauling, mining and long-haul transportation, which is characterized by heavy engine loads and long working days, thus contributing to a higher demand for reliable and high-performing oils. Motorcycles represent a smaller market segment, although niche markets have been developing on the back of courier and last-mile delivery activities.
By grade, fully-synthetic oils are anticipated to dominate through advanced-engine compatibility
Fully synthetic oils are expected to retain dominance as Saudi drivers increasingly service turbocharged, high-output and newer-generation passenger vehicles that require low-viscosity lubricants meeting specific OEM standards. The country’s extreme summer temperatures also strengthen demand for formulations offering oxidation control and thermal stability during prolonged high-temperature operation. Brands such as Mobil, Castrol and Shell market advanced fully synthetic grades for modern engines, while OEM-specific approvals help workshops recommend premium products. This supports higher-value oil changes across dealership and independent-service channels. Such developments will thus boost the Saudi Arabia automotive engine oils market dynamics and trends in the long run.
Semi-synthetic oils occupy an important middle position between conventional and fully synthetic products. These companies ensure the provision of a range of products that may improve performance without necessarily placing the same high price tag on the synthetic oil product. While Shell Saudi Arabia markets semi-synthetic Helix products, Castrol also provides a part-synthetic line for uses where there is a need for more protection but at a reduced price compared to the full synthetic option. Thus, the range can still be considered relevant within mixed fleets of vehicles and customers trying to balance budget and protection needs.
By engine type, gasoline is anticipated to dominate through broad vehicle adoption
Gasoline engines are expected to remain dominant, particularly across Saudi Arabia’s large passenger-car parc, where Toyota, Hyundai, Nissan and other gasoline-powered models have extensive representation. One factor that drives demand is the growing popularity of turbocharged gasoline engines, particularly as gasoline-powered passenger vehicles remain a major part of the Saudi automotive fleet. GASTAT reported that gasoline consumption reached 188.2 million barrels in 2024, compared with 186 million barrels in 2023, indicating continued high utilization of gasoline-powered vehicles. Thus, workshops are becoming increasingly obliged to match their oils with certain API and OEM standards as opposed to traditional viscosity ratings only. It ensures the ongoing demand for high-quality lubricants for gasoline engines in the existing after-sales service facilities in Saudi Arabia.
Alternative-fuel engines are emerging from a smaller base as Saudi Arabia diversifies its mobility and transport ecosystem under broader energy-transition initiatives. The opportunity is especially pertinent to low emission fuel systems such as compressed natural gas, hybrid vehicles, and others that need certain lubricating characteristics. Lubricants manufacturers could capitalize on the opportunity by offering specific lubricants suitable for varied combustion environments and varying fleets. With increasing awareness of fleet operators concerning cost effectiveness, emissions efficiency and vehicle efficiency, demand for specialized lubricants may go beyond gasoline and diesel applications.
By vehicle type, passenger cars are anticipated to dominate recurring aftermarket demand
Passenger cars are expected to remain the largest vehicle category for engine-oil consumption because Saudi Arabia has a highly established private-vehicle culture and extensive passenger-car aftermarket. GASTAT reported 15.1 million registered and roadworthy vehicles in 2023, an increase of 6.2% from 2022, while vehicles travelled an average of 220.5 million km per day on the country’s roads. Demand is further supported by frequent driving across long distances, high summer temperatures and periodic workshop servicing, sustaining recurring demand for passenger-car engine oils. Japanese and Korean vehicles form important aftermarket populations, requiring widely available viscosity grades and manufacturer-compliant formulations. This creates a strong recurring market for brands such as Mobil, Shell and Castrol through dealerships, independent workshops, lubricant retailers and automotive-service centres serving Saudi consumers, thereby bolstering the Saudi Arabia automotive engine oils demand.
Heavy-duty vehicles offer strong growth potential as Saudi Arabia expands logistics, construction, mining and large-scale infrastructure activity. Trucks and commercial fleets working long hours focus more on lubricant life, soot formation, wear resistance and increased drain intervals since unscheduled maintenance has an impact on their operational time. The introduction of new heavy duty diesel engine oils is hence very significant. Manufacturers like Chevron stand to gain from supplying highly efficient fleet oils that cater for OEM standards and high temperatures.
Read more about this report - Request a Free Sample
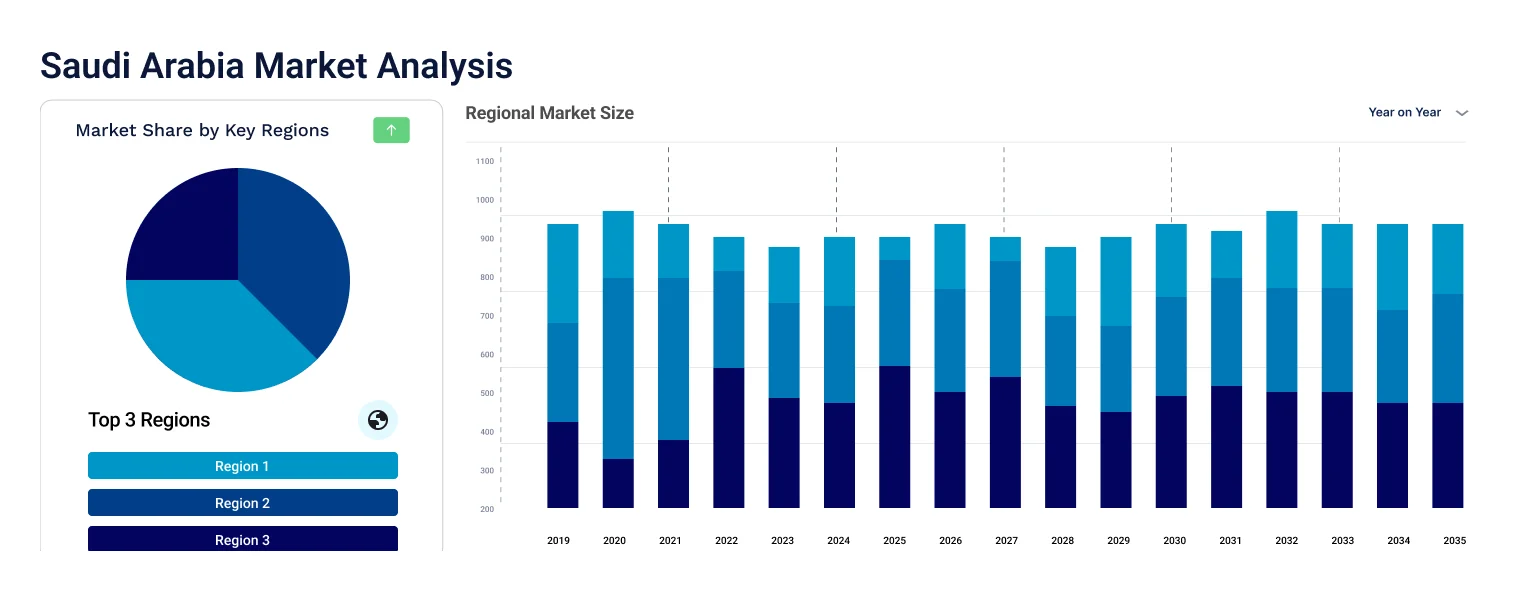
Riyadh leads Saudi automotive engine-oil demand, followed by Jeddah and Western Region
Within Saudi Arabia, Riyadh represents the leading commercial centre for automotive engine-oil demand because of its concentration of population, vehicle activity, workshops, distributors, corporate fleets and commercial operations. Jeddah and the Western Region form another important demand cluster, supported by urban mobility, logistics and commercial transportation linked to the Red Sea economic corridor. The Eastern Province, particularly the industrial belt around Dammam and Jubail, offers a distinct B2B opportunity through commercial fleets and industrial activity. Shell's Saudi lubricant infrastructure illustrates the importance of local distribution and blending capability, with JOSLOC operating a lube-oil blending plant in Riyadh and marketing Shell lubricants across the Kingdom, thereby directly boosting the Saudi Arabia automotive engine oils market regional growth.
Emerging opportunities are likely to develop around expanding logistics corridors, industrial projects and regional fleet operations rather than being limited to major retail centres. For lubricant suppliers, this makes distribution density and service capability important competitive variables. Companies can strengthen regional penetration by combining authorised distributors with workshop networks, fleet contracts and dependable inventory availability. The Eastern Province offers particular scope for technically intensive commercial applications, while Western Saudi Arabia can benefit from logistics and transportation activity. Regional strategies should therefore differentiate between passenger-car aftermarket demand and fleet-oriented B2B requirements rather than applying one national sales model across every territory.
Competition in the Saudi Arabia automotive engine oils market is increasingly centred on technical differentiation, OEM compatibility, supply reliability and portfolio breadth. Major Saudi Arabia automotive engine oils market players are expanding formulations around newer performance specifications while retaining mineral and semi-synthetic products to cover different customer budgets. Shell, for example, maintains a broad Saudi portfolio spanning fully synthetic, semi-synthetic and mineral engine oils.
Another competitive priority for the Saudi Arabia automotive engine oils companies is supply-chain resilience and customer integration. ExxonMobil's 2026 response to lubricant supply disruptions demonstrates the importance of integrated base-oil access, reformulation capabilities and diversified sourcing. Meanwhile, FUCHS is placing greater emphasis on technically advanced specialty solutions through its FUCHS100 strategy. In Saudi Arabia, these strategies translate into opportunities around fleet contracts, workshop partnerships, technical services and application-specific product portfolios.
Established in 1909, BP is headquartered in London, United Kingdom. Its Castrol business provides automotive, industrial and marine lubricants, including engine oils marketed in Saudi Arabia. Castrol's Saudi portfolio includes EDGE, MAGNATEC and GTX, covering fully synthetic, semi-synthetic and conventional applications. BP's 2026 corporate transition around Castrol is also reshaping the competitive structure of the global lubricants business.
ExxonMobil is headquartered in Spring, Texas, United States, and traces its corporate heritage to Standard Oil operations dating back to the nineteenth century. Its Mobil brand supplies passenger-car and commercial lubrication products, including Mobil 1 synthetic motor oils. The company also maintains substantial base-oil and lubricant manufacturing capabilities, giving it an integrated position across lubricant supply.
FUCHS was established in Mannheim in 1931 and remains headquartered in Mannheim, Germany. It describes itself as the world's largest independent supplier of lubrication solutions. Its portfolio covers automotive lubricants alongside industrial and specialty products. The company's customer-specific formulation approach and focus on technically advanced lubrication solutions position it to compete in applications where performance, efficiency and operating-cost optimisation are important.
Chevron was established in 1879 and is headquartered in Houston, Texas, United States. Its lubricant portfolio includes Havoline passenger-car products, Delo heavy-duty lubricants and Techron-related automotive technologies. The company is advancing formulations around newer passenger-car specifications while preparing for next-generation heavy-duty lubricant categories. This combination gives Chevron exposure to both passenger-vehicle and commercial-fleet applications within the broader automotive lubrication market.
Other key players in the market include TotalEnergies SE, Motul, Ravensberger Schmierstoffvertrieb GmbH, PETRONAS Lubricants International, and BIZOL Germany GmbH, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Access the Saudi Arabia Automotive Engine Oils Market report to evaluate market structure, competitive strategies, segmentation and emerging opportunities. The study provides decision-makers with focused insights into Saudi Arabia Automotive Engine Oils Market trends 2026, supplier positioning and evolving lubricant technologies, alongside the Saudi Arabia Automotive Engine Oils Market forecast 2026-2035 and broader industry outlook. Download the sample report to assess the findings relevant to your expansion and investment strategy.
Vietnam Automotive Engine Oils Market
Philippines Automotive Engine Oils Market
United States Automotive Engine Oils Market


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 682.24 Million.
The market is projected to grow at a CAGR of 2.40% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 864.84 Million by 2035.
Key strategies include premium synthetic-oil offerings, OEM partnerships, local blending, wider workshop and distribution networks, product diversification for hybrids and EVs, technical compliance, and investment in high-performance, fuel-efficient lubricant formulations.
The key market trends are the increasing initiatives by the Saudi Arabian government to attract foreign investors and the emergence of synthetic lubricants.
The different grades of engine oils are mineral, semi synthetic, and fully synthetic.
The different vehicle types that use engine oils are passenger cars, light commercial vehicles, heavy-duty vehicles, and motorcycles.
The major players in the market are BP PLC, Exxon Mobil Corporation, FUCHS Group, Chevron Corporation, TotalEnergies SE, Motul, Ravensberger Schmierstoffvertrieb GmbH, PETRONAS Lubricants International, and BIZOL Germany GmbH, among others.
Key challenges include crude-oil and base-oil price volatility, counterfeit lubricants, intense price competition, stringent quality requirements, longer oil-drain intervals, and the gradual shift toward electric vehicles, which reduces conventional engine-oil demand.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Grade |
|
| Breakup by Engine Type |
|
| Breakup by Vehicle Type |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




