

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
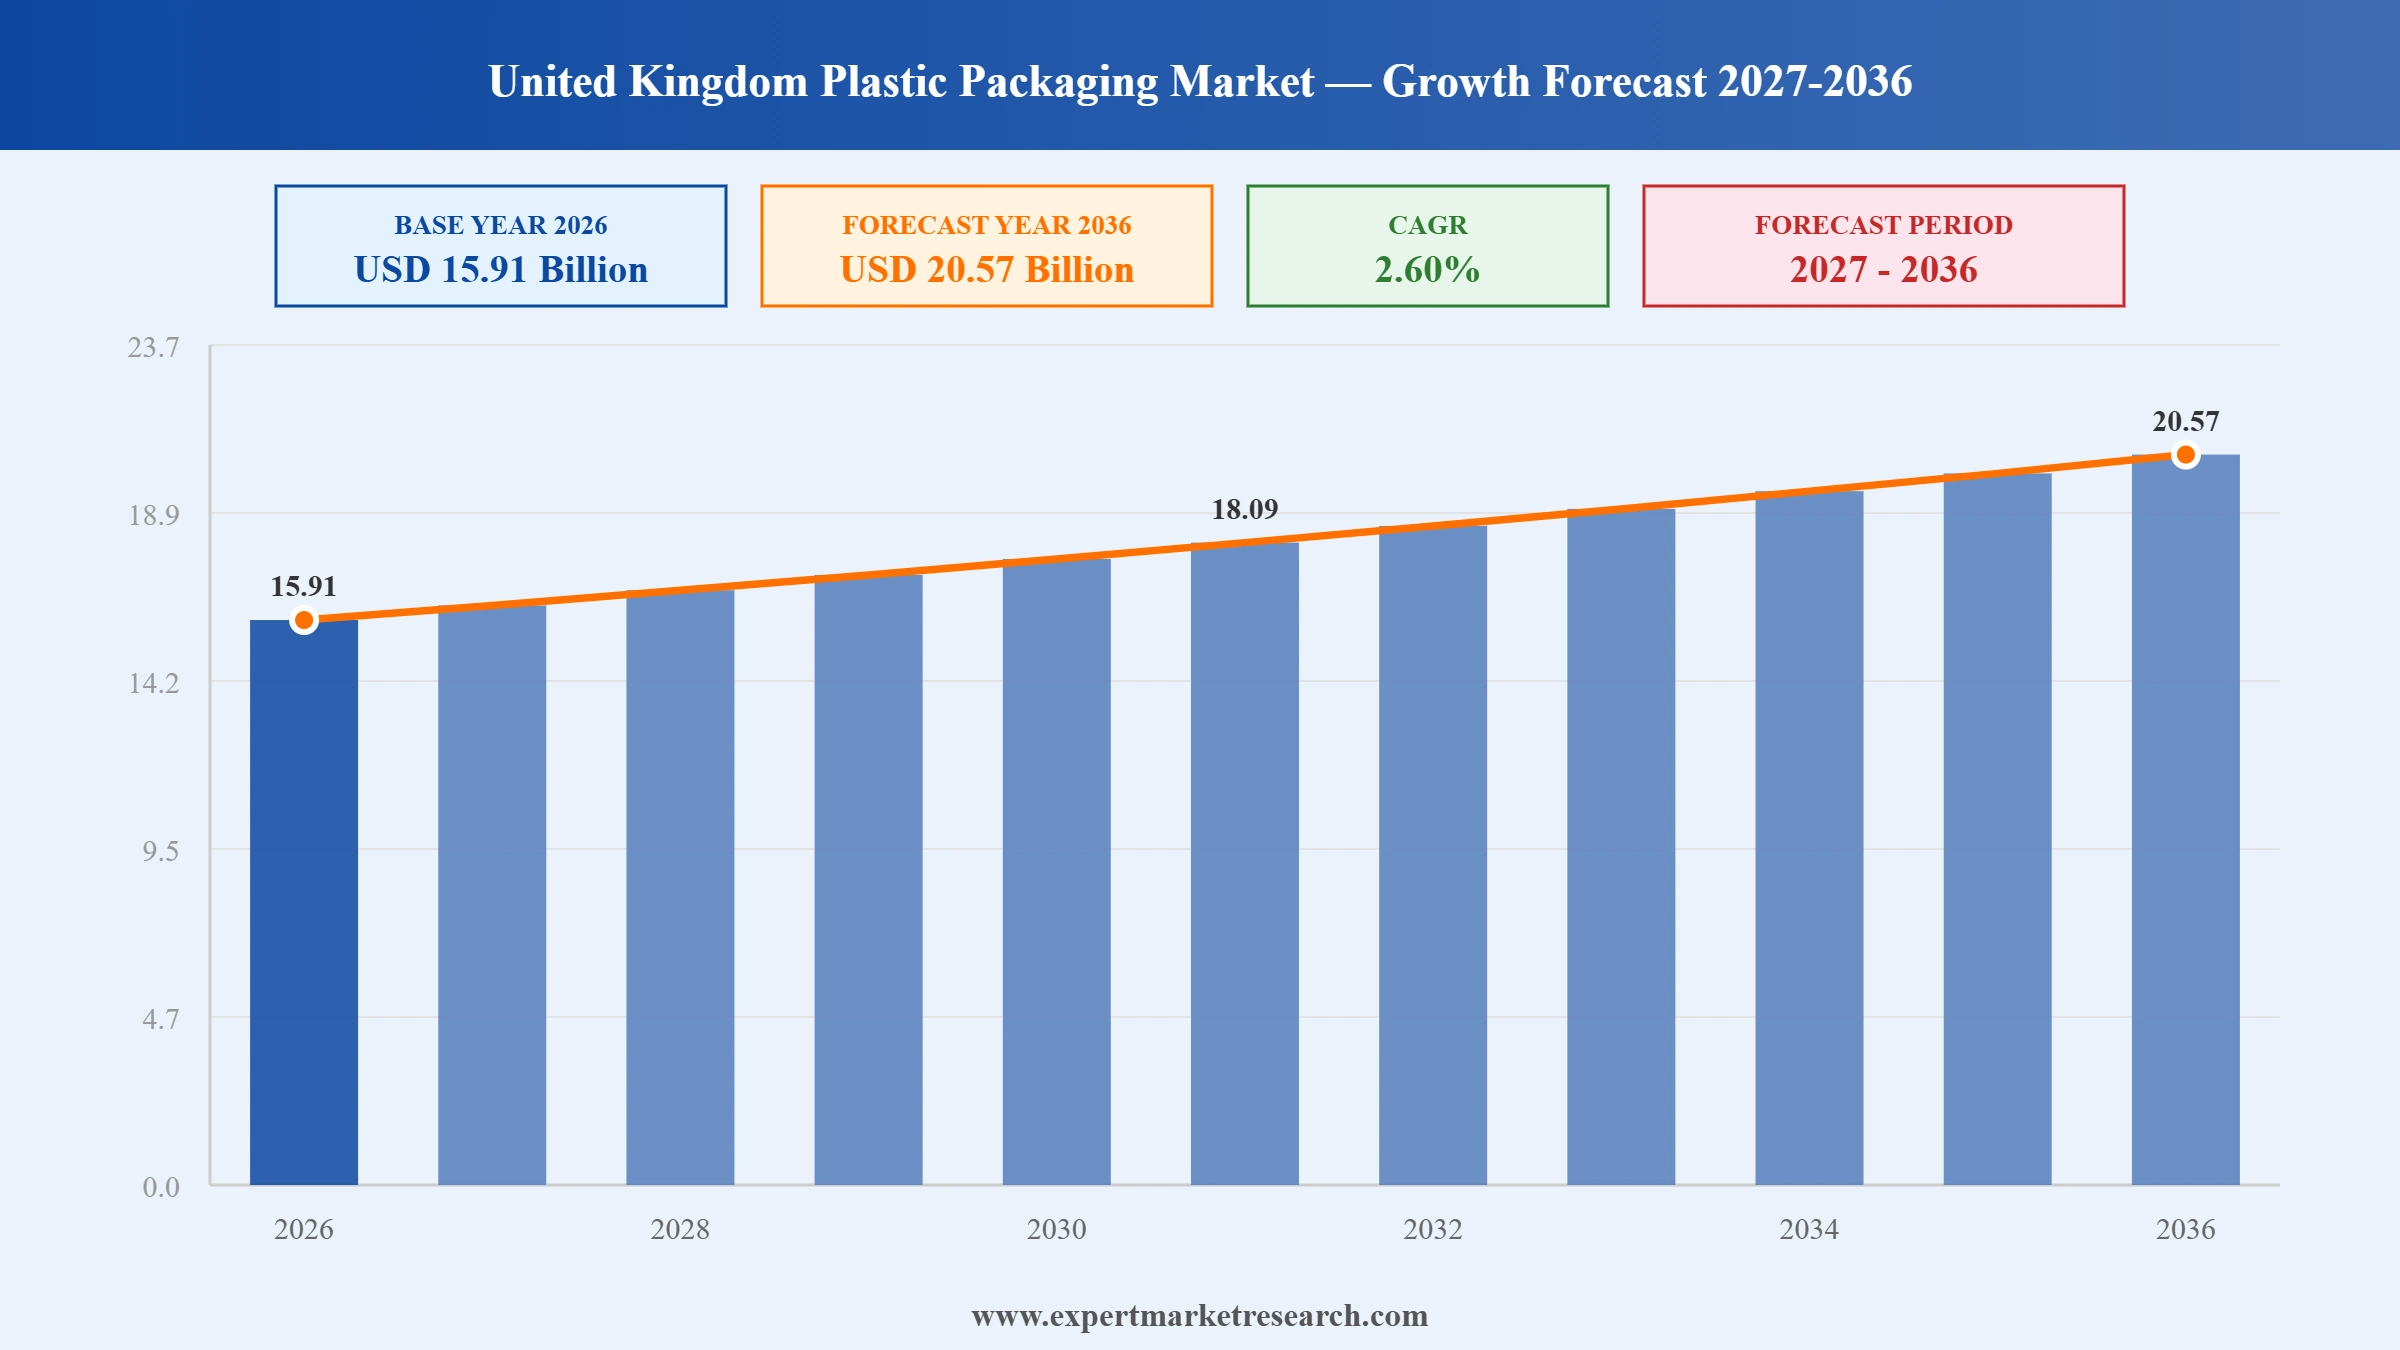
The United Kingdom plastic packaging market attained a value of USD 15.51 Billion in 2025 and is projected to expand at a CAGR of 2.60% through 2035. The market is further expected to achieve USD 20.05 Billion by 2035. Rising demand for lightweight and versatile packaging across food and beverage applications, favourable government initiatives including the UK Plastics Pact, and growing adoption of recyclable and reprocessed flexible packaging continue to support demand across rigid and flexible packaging formats.
Rising demand for lightweight and versatile packaging continues to anchor steady growth across the United Kingdom plastic packaging market, as food and beverage brands increasingly favour formats that extend shelf life while reducing transport weight and cost. Manufacturers are also investing in recyclable and mono-material designs, reflecting the industry's ongoing pursuit of packaging that satisfies both regulatory recyclability targets and brand sustainability commitments.
The United Kingdom plastic packaging market is witnessing further developments as established manufacturers pursue consolidation to build broader, more integrated packaging portfolios. Amcor completed its combination with Berry Global on 30 April 2025, creating a packaging group with combined annual sales of approximately 23 billion US dollars, around 400 facilities, and a presence spanning roughly 140 countries. This shift toward broader, integrated packaging portfolios is concentrated among manufacturers with sufficient global scale, while smaller specialists differentiate themselves through bespoke runs, rapid lead times, and localised UK service relationships.
In addition, established manufacturers are increasingly forming targeted partnerships to accelerate recyclable material development for specific product categories, reflecting the industry's recognition that category-specific barrier film innovation increasingly determines competitiveness beyond generic recyclability claims alone. Such partnership activity is reshaping competitive positioning across the wider united kingdom plastic packaging market as manufacturers with proven collaborative research capabilities increasingly differentiate themselves from competitors relying on in-house development alone.
Read more about this report - Request a Free Sample
Following the April 2026 UK tax year update, the Plastic Packaging Tax continued influencing converter behaviour, pushing manufacturers toward recycled content formulations to avoid tax liability on packaging containing less than 30 percent recycled plastic. Companies can proactively increase recycled content thresholds across product lines to minimise tax exposure while positioning ahead of anticipated regulatory tightening.
Coveris introduced its MonoFlexBP resealable tray line, merging easy-open functionality with curbside recyclability to serve brands seeking mono-material formats compatible with existing UK recycling infrastructure. Companies can develop mono-material resealable formats to satisfy both consumer convenience expectations and evolving recyclability requirements within a single product design.
Constantia Flexibles formed a partnership focused on recyclable barrier films for coffee packaging, illustrating how collaborative research and development accelerates category-specific recyclable solutions. Companies can pursue targeted partnerships focused on specific product categories to accelerate barrier film innovation beyond what generic, broad-market recyclable film development typically achieves.
Amcor completed its combination with Berry Global, forming a packaging group with combined annual sales of approximately 23 billion US dollars, around 400 facilities, and operations spanning roughly 140 countries. Companies can pursue large-scale mergers to combine complementary flexible and rigid packaging capabilities and achieve greater reach than would be possible through organic growth alone.
Scale is becoming the defining variable in this industry, and a handful of manufacturers are betting that combined revenue and facility count outweigh the integration risk of merging with a former rival across the united kingdom plastic packaging market. In April 2025, two major manufacturers completed a combination forming one of the largest packaging groups globally by combined revenue and facility count. Such large-scale consolidation reflects manufacturers' recognition that combined flexible and rigid packaging capabilities increasingly deliver competitive advantages that neither business could achieve independently.
Getting a resealable pack to also sort cleanly into a single recycling stream has proven tricky, but a growing number of product launches suggest manufacturers are closing that gap. In September 2025, one leading manufacturer launched a resealable tray line combining easy-open functionality with curbside recyclability. Such mono-material innovation reflects manufacturers' recognition that formats requiring no material separation for recycling increasingly appeal to both regulators and environmentally conscious consumers.
Generic recyclable film solutions do not always hold up against the specific demands of individual product categories, which is pushing some manufacturers toward narrower, purpose-built collaborations instead. In May 2025, one leading manufacturer formed a partnership specifically addressing recyclable packaging for coffee products. Such category-specific collaboration reflects manufacturers' recognition that niche product requirements often demand specialised barrier film properties that generic recyclable film development cannot adequately address.
Fiscal pressure rather than voluntary commitment appears to be the bigger lever here, with converters visibly adjusting resin formulations to stay under a specific tax threshold. Following the April 2026 UK tax year update, the Plastic Packaging Tax continued maintaining pressure on manufacturers to formulate products with recycled content above the 30 percent threshold required to avoid additional tax liability. Such sustained tax pressure reflects the government's recognition that fiscal incentives increasingly drive faster recycled content adoption than voluntary industry commitments alone.
This Expert Market Research Report titled "United Kingdom Plastic Packaging Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Material
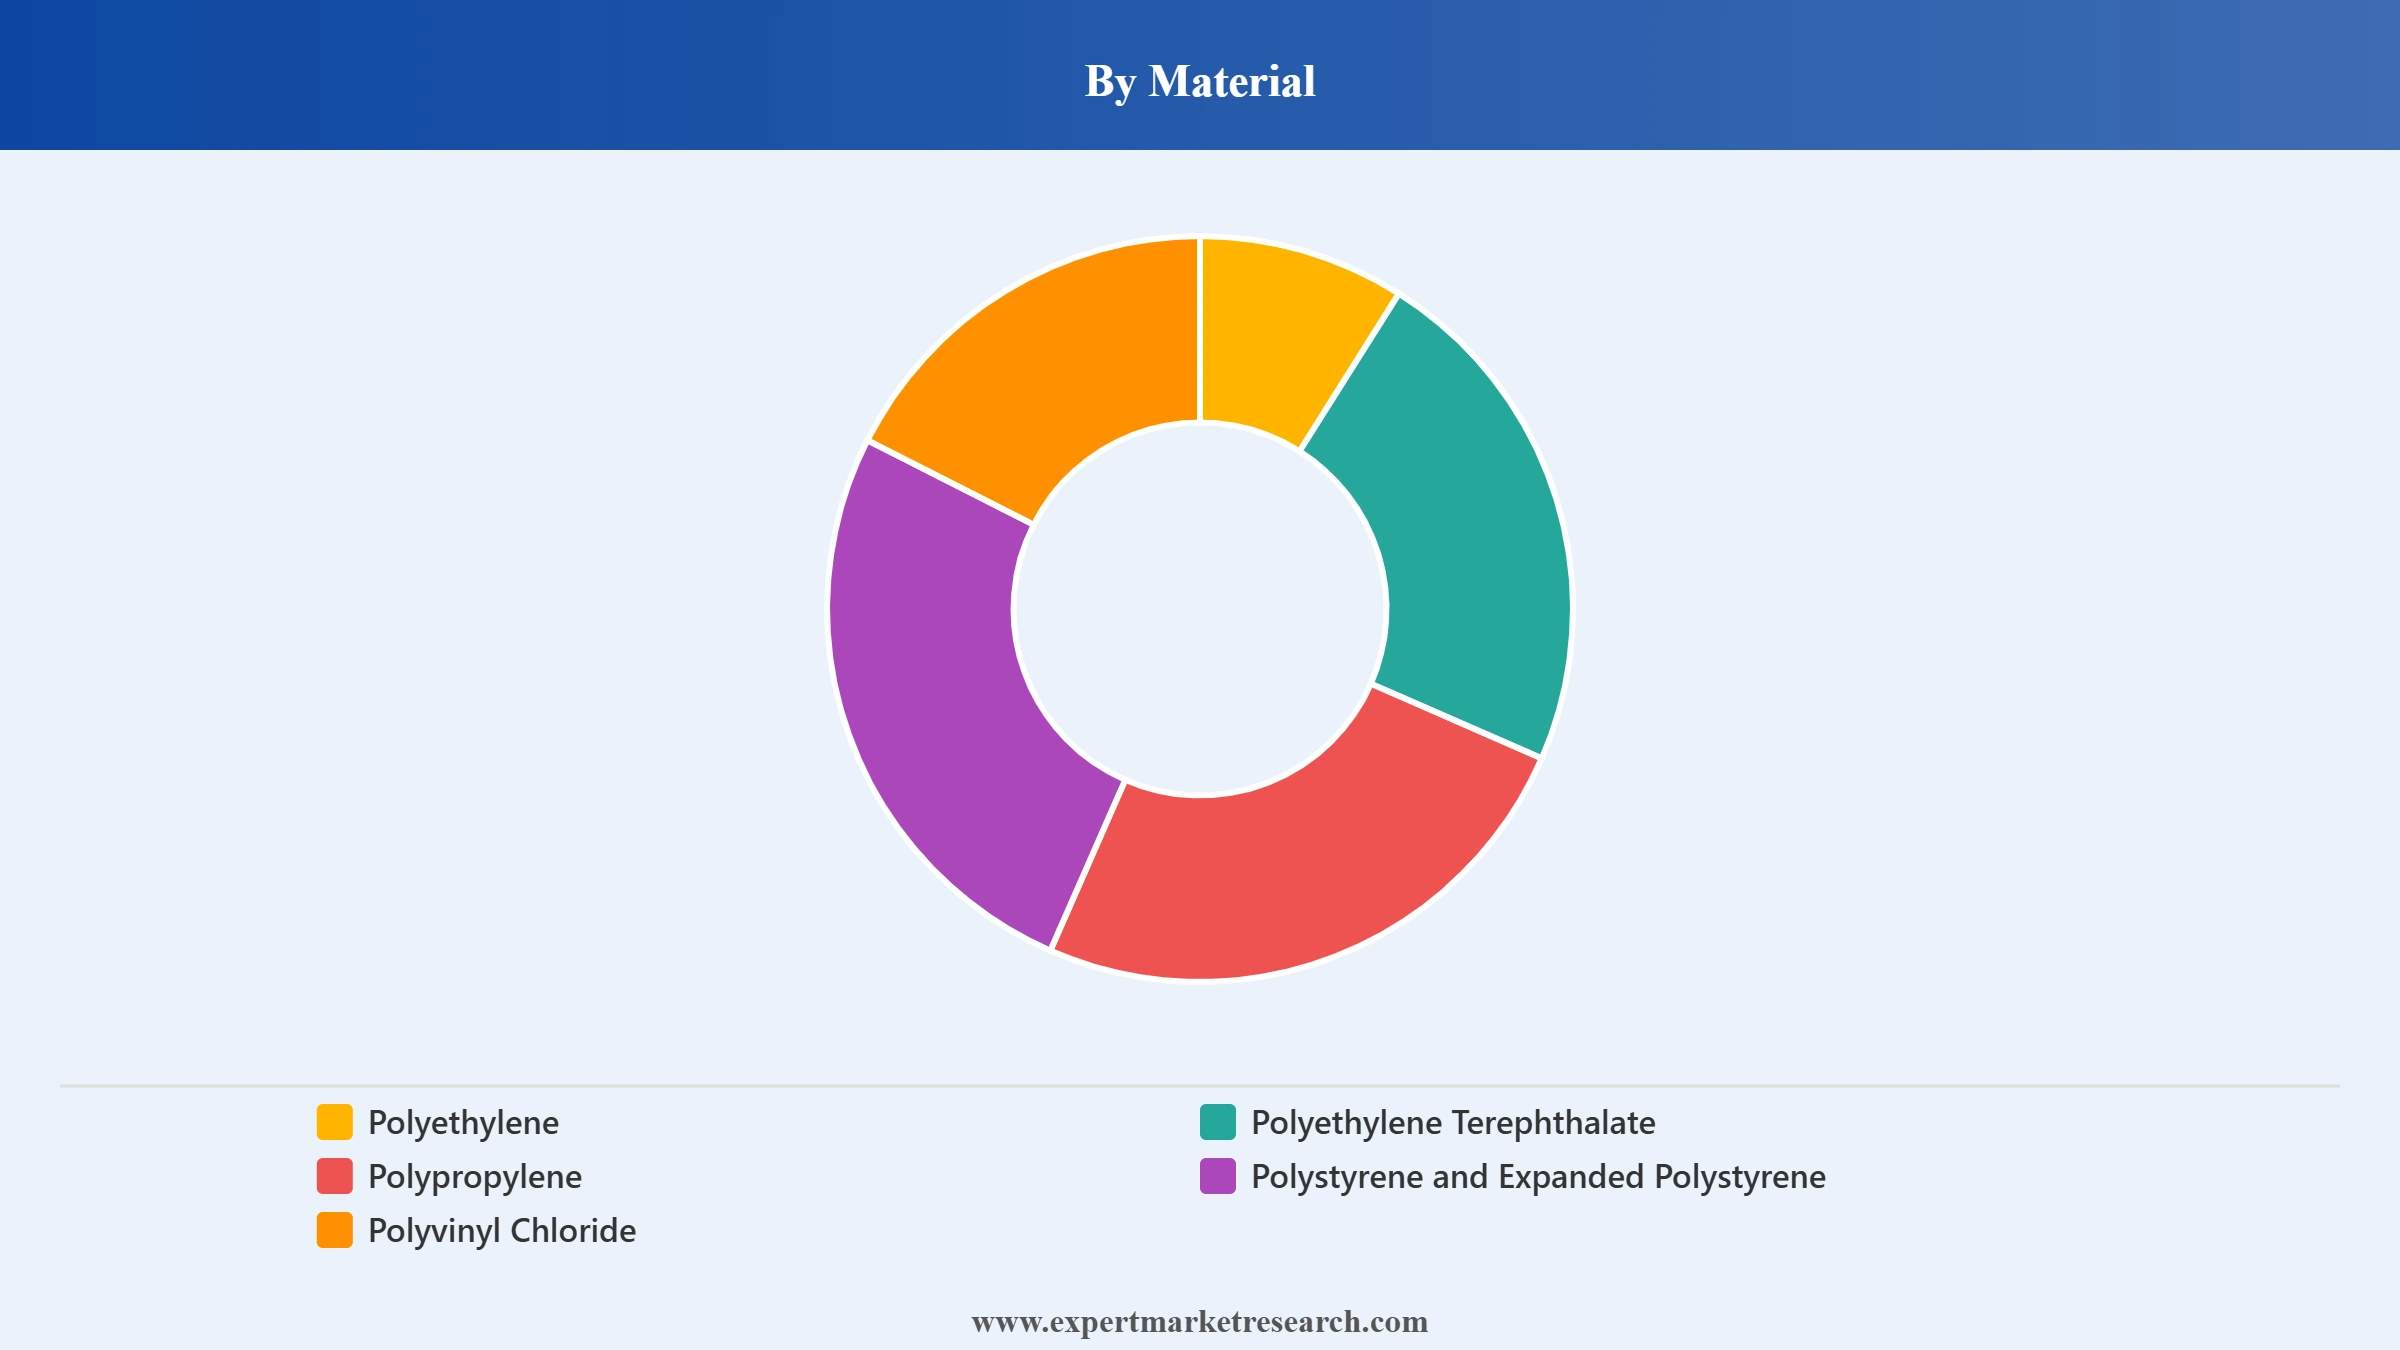
Key Insight: Polyethylene (PE) accounts for the largest share of the united kingdom plastic packaging market, reflecting its versatility across both rigid and flexible packaging formats and established recycling infrastructure. Polyethylene Terephthalate (PET) continues to represent substantial demand for beverage and food container applications, with Veolia's January 2026 announcement of a £70 million closed-loop PET tray recycling facility reflecting sustained investment in this material stream. Polypropylene (PP) continues to see mono-material innovation, illustrated by June 2026 lotion pump designs built entirely from PP to simplify recycling under the tightened tax regime. Polystyrene (PS) and Expanded Polystyrene (EPS) serve protective and food-service applications requiring lightweight cushioning. Polyvinyl Chloride (PVC) maintains a smaller, specialised presence in cling film and blister packaging applications. Others encompasses smaller-volume polymer types serving niche packaging requirements across the value chain.
Market Breakup by Product
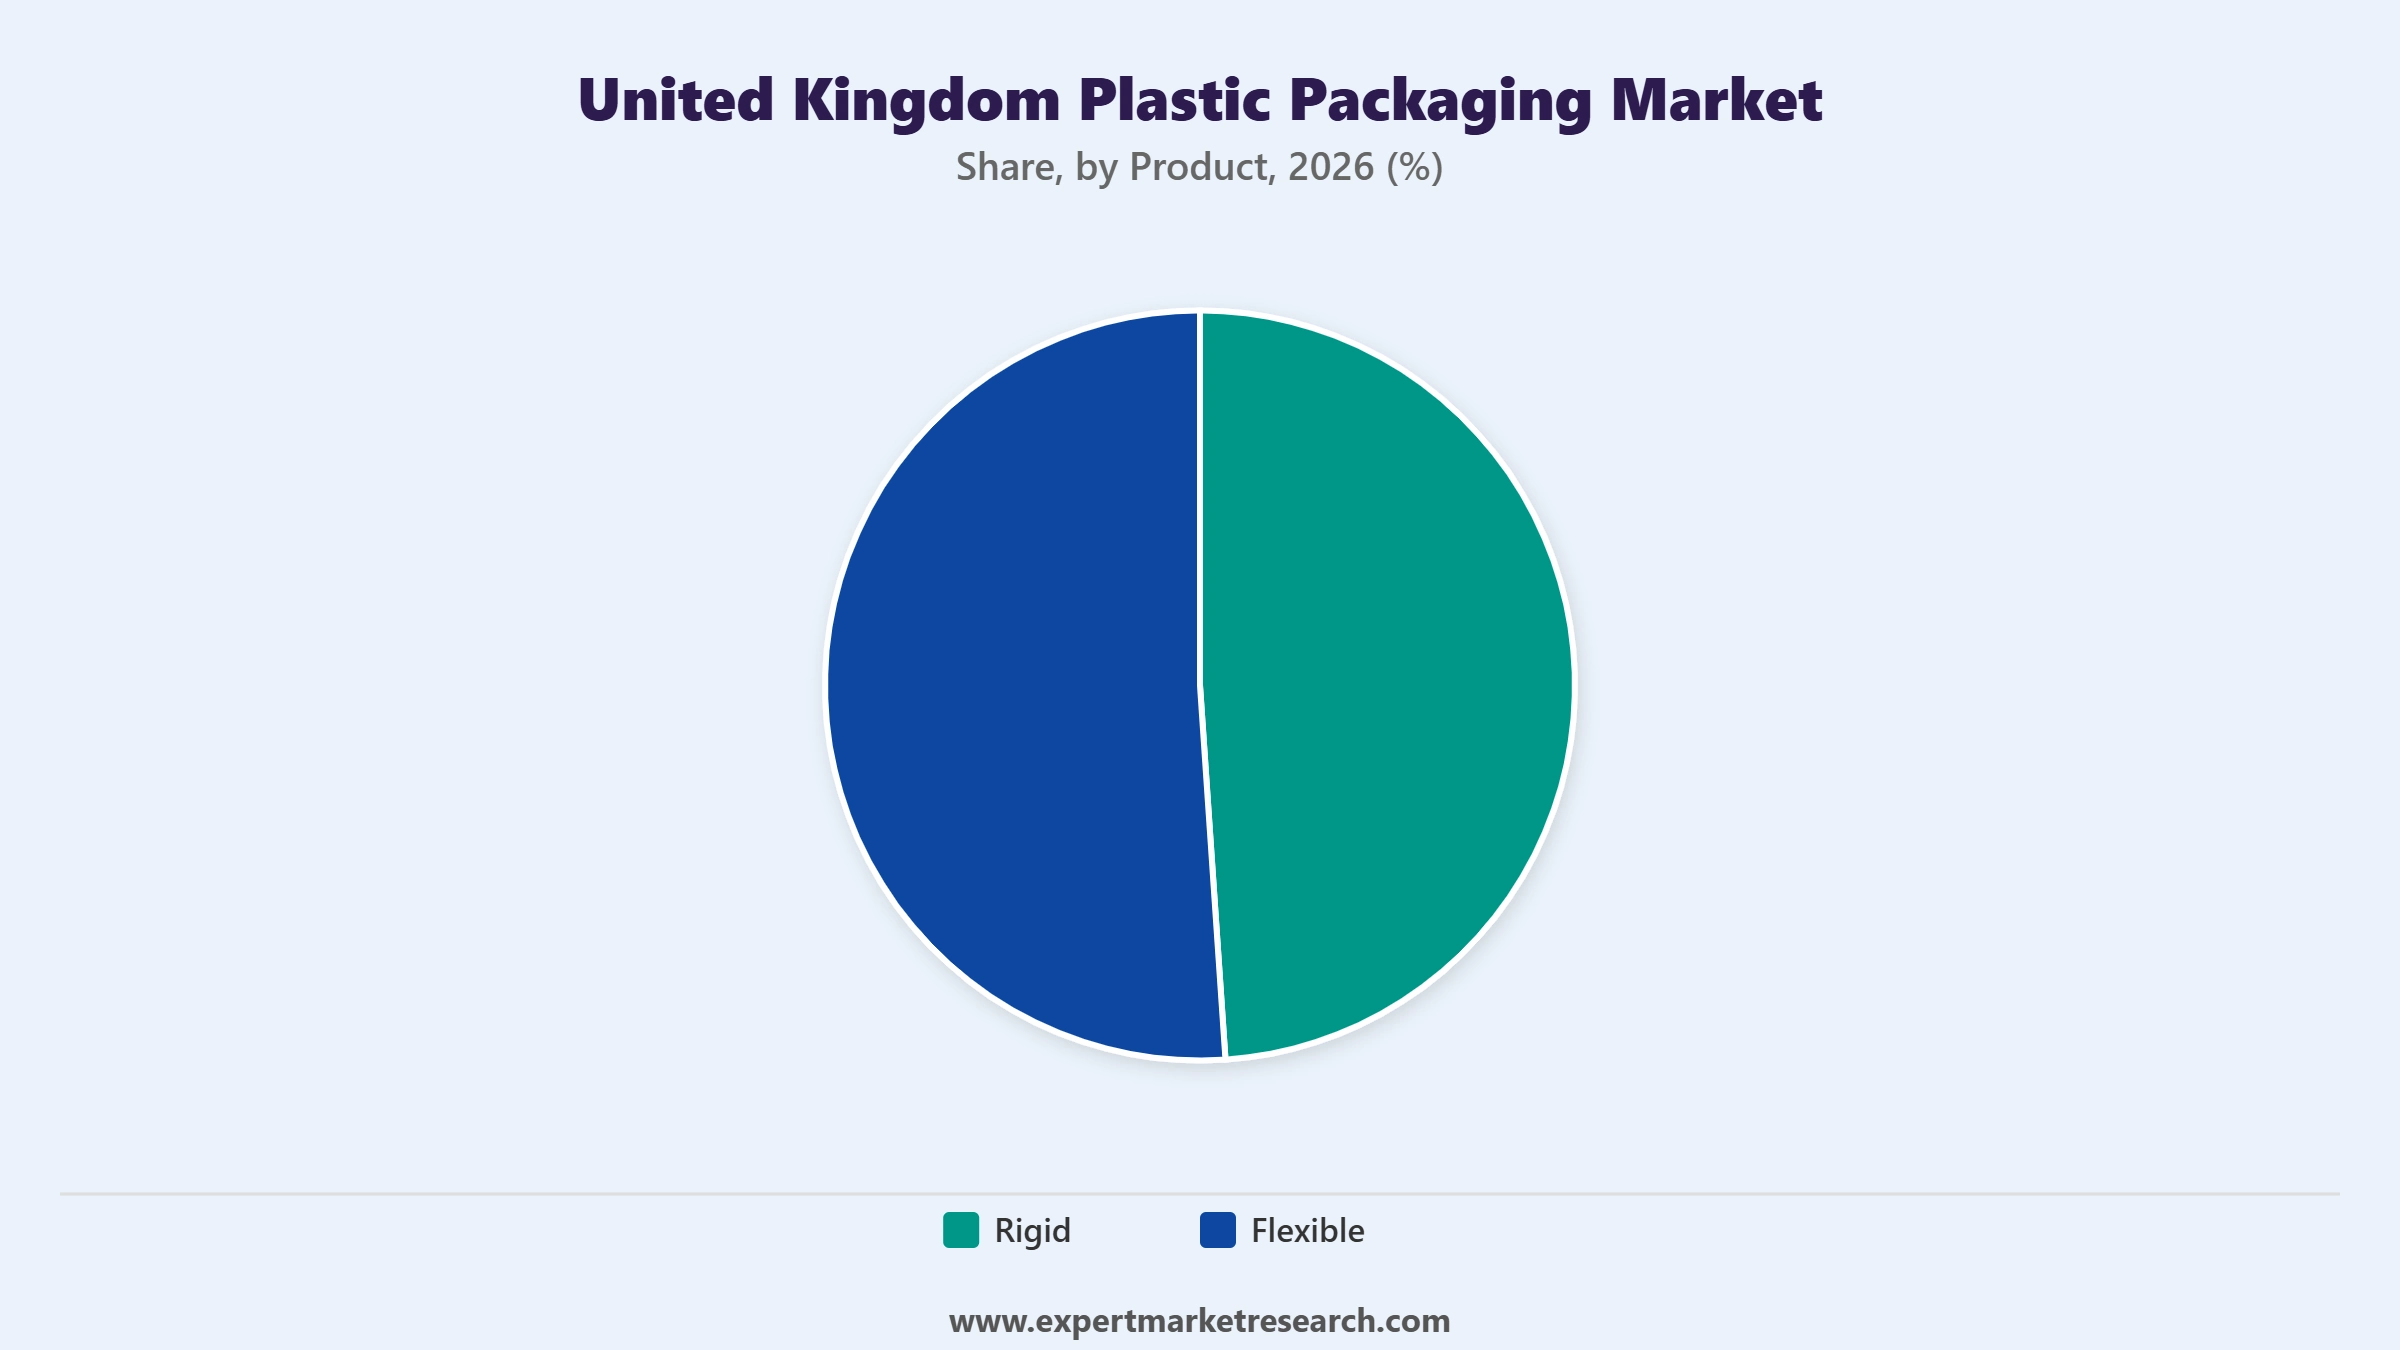
Key Insight: Rigid accounts for the largest share of the united kingdom plastic packaging market, with Bottles and Jars representing its dominant sub-category given sustained beverage and food container demand. Cans serve canned beverage and food applications requiring pressure resistance. Trays and Containers support ready-meal and fresh produce packaging, while Caps and Closures provide sealing components across the rigid range, and Others covers smaller-volume rigid formats. Flexible is growing at the fastest pace, with Wraps and Films leading its sub-category mix, illustrated by Coveris' September 2025 launch of a mono-material resealable tray line. Bags continue to serve carrier and refuse applications, Pouches gain share from rigid alternatives given their lightweight, resealable convenience, and Others captures niche flexible formats.
Market Breakup by End Use Industry
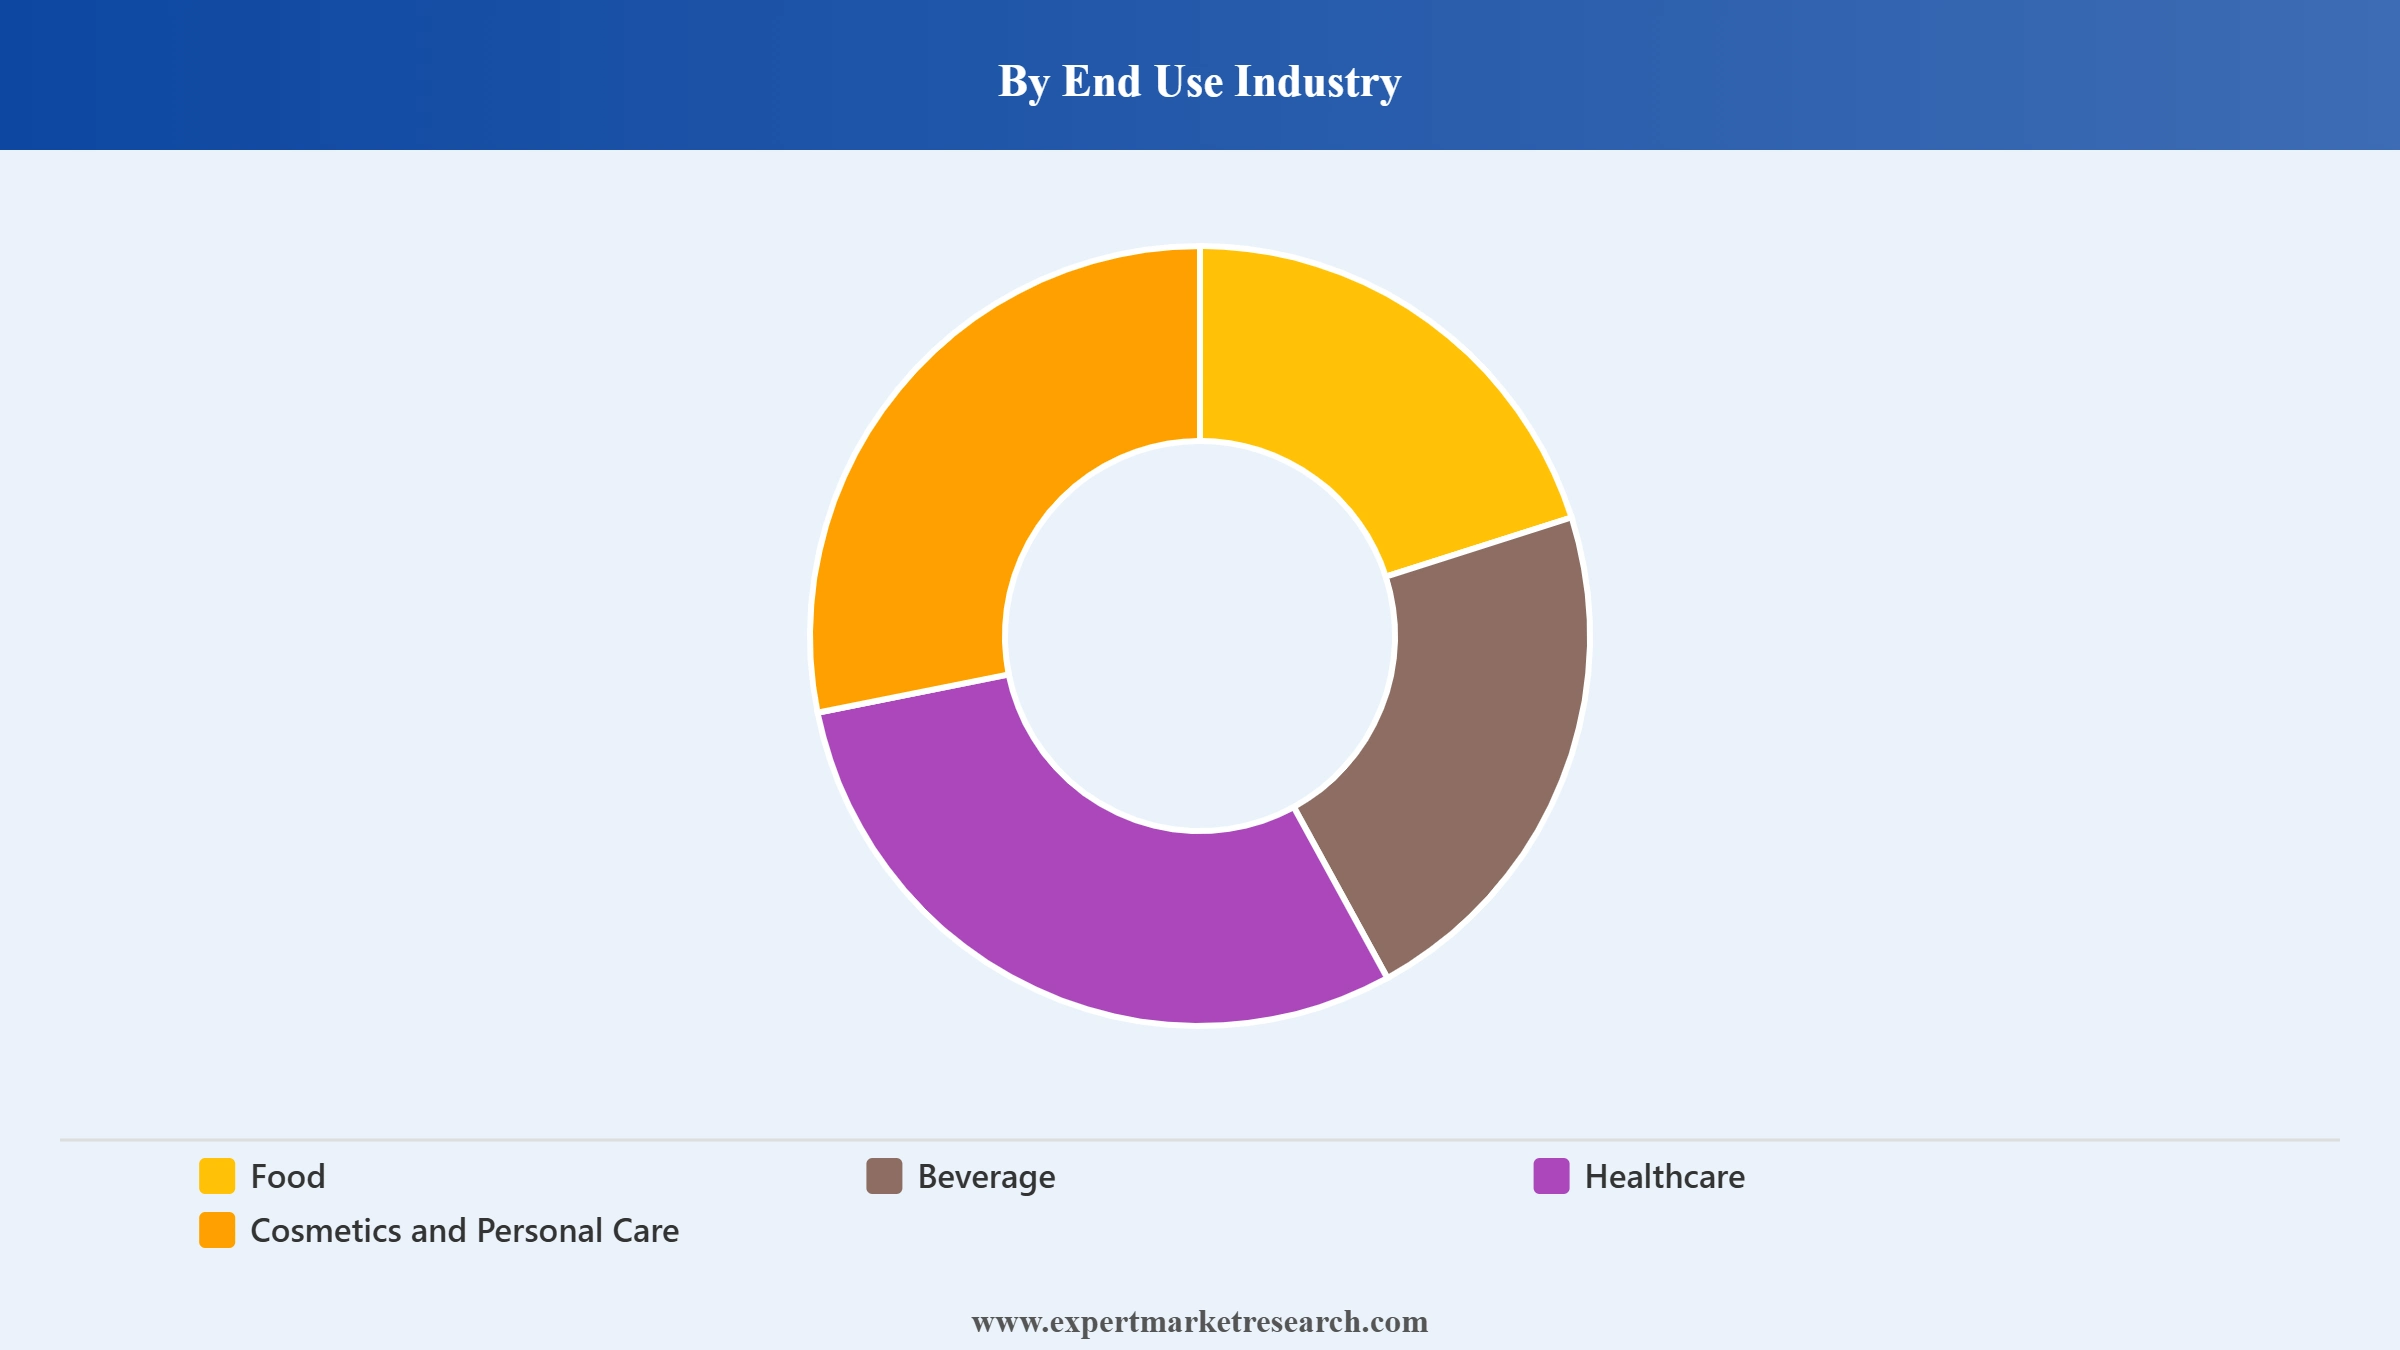
Key Insight: Food accounts for the largest share of the united kingdom plastic packaging market, reflecting sustained demand for packaging that extends shelf life and maintains product safety across processed and fresh food categories. Beverage continues to represent substantial demand tied to bottle and can packaging formats, with the April 2026 launch of the UK Packaging Pact, whose founding signatories include major food and beverage retailers alongside fellow converter Charpak, reinforcing sector-wide sustainability commitments. Healthcare demand is reinforced by pan-European investment such as Aptar Pharma's September 2025 expansion of its drug delivery and packaging innovation R&D footprint. Cosmetics and Personal Care serves brand-presentation-focused applications requiring premium finish and tamper-evidence. Others captures smaller-volume end-use categories including industrial and household packaging applications.
Read more about this report - Request a Free Sample
By material, polyethylene leads the market while polyethylene continues strengthening its position given its versatility
Polyethylene (PE) continues to account for the largest share of the market, reflecting its versatility across both rigid and flexible packaging formats and established UK recycling infrastructure. Polyethylene's hold on the category persists as converters stick with resin sourcing arrangements refined across successive production cycles, even as PET-specific recycling investment, such as Veolia's January 2026 closed-loop facility announcement, expands capacity in adjacent material streams.
Read more about this report - Request a Free Sample
Polyethylene Terephthalate (PET) continues to represent substantial demand across the united kingdom plastic packaging market for beverage and food container applications requiring clarity and barrier performance.
By product, rigid leads the market while flexible grows fastest given rising demand for lightweight, resealable formats
Rigid continues to account for the largest share of the market, reflecting sustained demand for bottles, jars, and containers across food and beverage applications requiring structural protection. A container specification that has already passed regulatory and consumer testing once tends to get reused on the next product launch rather than redesigned from scratch.
Read more about this report - Request a Free Sample
Flexible is growing at the fastest pace across the united kingdom plastic packaging market as lightweight, resealable formats continue gaining share from rigid alternatives. In September 2025, Coveris launched its MonoFlexBP resealable tray line combining easy-open functionality with curbside recyclability.
By end use industry, food leads the market while food continues strengthening its position given sustained packaged food demand
Food continues to account for the largest share of the market, reflecting sustained demand for packaging that extends shelf life and maintains product safety across processed and fresh food categories. Food packaging suppliers who have already navigated a brand's safety and shelf-life requirements once are the natural first call for the next launch too.
Read more about this report - Request a Free Sample
The April 2026 launch of the UK Packaging Pact, whose founding signatories span major food and beverage retailers, is expected to shape procurement standards across this segment. Beverage continues to represent substantial demand across the united kingdom plastic packaging market tied to bottle and can packaging formats requiring consistent barrier and clarity performance.
The industry is moderately consolidated, with united kingdom plastic packaging market companies ranging from diversified global packaging groups spanning multiple material categories to specialist UK converters competing across material, product, and end use segments. Established players operate across the full plastic packaging value chain, from resin sourcing and extrusion through complete converting, printing, and distribution for food, beverage, healthcare, and cosmetics customers.
Competitive dynamics among united kingdom plastic packaging players are increasingly shaped by the pace of large-scale consolidation, the strength of mono-material and recyclable format innovation, and the ability to navigate UK Plastic Packaging Tax requirements. Manufacturers are investing in recycled content formulations, category-specific barrier film partnerships, and curbside-recyclable packaging designs to differentiate their offering and secure long-term brand owner relationships.
Founded in 1860 and headquartered in Zurich, Switzerland, Amcor manufactures flexible and rigid packaging solutions across food, beverage, healthcare, and personal care categories. In April 2025, the company completed its combination with Berry Global, forming a packaging group with combined annual sales of approximately 23 billion US dollars and operations spanning roughly 140 countries. Amcor's expanded global scale following the Berry Global combination differentiates its offering from specialist UK converters with more limited international reach.
Coveris manufactures flexible and rigid packaging solutions serving food and beverage customers across Europe and the UK. In September 2025, the company launched its MonoFlexBP resealable tray line combining easy-open functionality with curbside recyclability. Coveris' strong UK footprint and focus on mono-material innovation differentiate its offering from competitors with less developed recyclable format portfolios.
Founded in 1967 and headquartered in Evansville, Indiana, United States, Berry Global manufactures rigid and flexible plastic packaging across consumer and industrial categories, including a UK recycling business operating a soft plastic recycling complex in Heanor, Derbyshire. In April 2025, the company's combination with Amcor was completed, with Berry's operational strength in rigid plastics and recycling now integrated within the combined group. Berry Global's specialised UK soft plastic recycling infrastructure differentiates its offering from converters lacking comparable in-house recycling capability.
Founded in 1908 and headquartered in Vienna, Austria, Constantia Flexibles manufactures flexible packaging solutions for consumer and pharmaceutical customers, including a UK consumer plant focused on recyclable laminates for flow wraps, lidding films, and pre-made pouches. In May 2025, the company formed a partnership focused on recyclable barrier films for coffee packaging. Constantia Flexibles' Design for Recycling approach and category-specific partnership capability differentiate its offering from converters pursuing generic, broad-market recyclable film development.
Other key players in the United Kingdom plastic packaging market include Polystar Plastics Ltd., Coda Plastics Limited, Charpak Ltd., Wipak Group, and Tyler Packaging Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our United Kingdom plastic packaging market trends 2026 report. Discover material and product trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 15.51 Billion.
The market is projected to grow at a CAGR of 2.60% between 2026 and 2035.
The market is estimated to witness a healthy growth during 2026-2035 to reach around USD 20.05 Billion by 2035.
The key trends of the market include the rising trend of recycling and reprocessing flexible plastic packaging, increased implementation of innovative extrusion processes in the production of plastic packaging, and growing usage of plastic bottle packaging as an alternative to glass bottle packaging in the wine sector.
The key players in the market include Amcor plc, Coveris Management GmbH, Berry Global Inc., Constantia Flexibles International GmbH, Polystar Plastics Ltd., Coda Plastics Limited, Charpak Ltd., Wipak Group, and Tyler Packaging Limited, among others.
Manufacturers face rising compliance costs associated with the Plastic Packaging Tax and Extended Producer Responsibility requirements, technical challenges in achieving curbside recyclability for multi-layer barrier formats, and intensifying competition from paper and fibre-based packaging alternatives.
Pursuing large-scale consolidation to combine complementary flexible and rigid packaging capabilities, developing mono-material formats that satisfy both convenience and recyclability requirements, and forming category-specific partnerships to accelerate barrier film innovation.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Material |
|
| Breakup by Product |
|
| Breakup by End Use |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




