

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
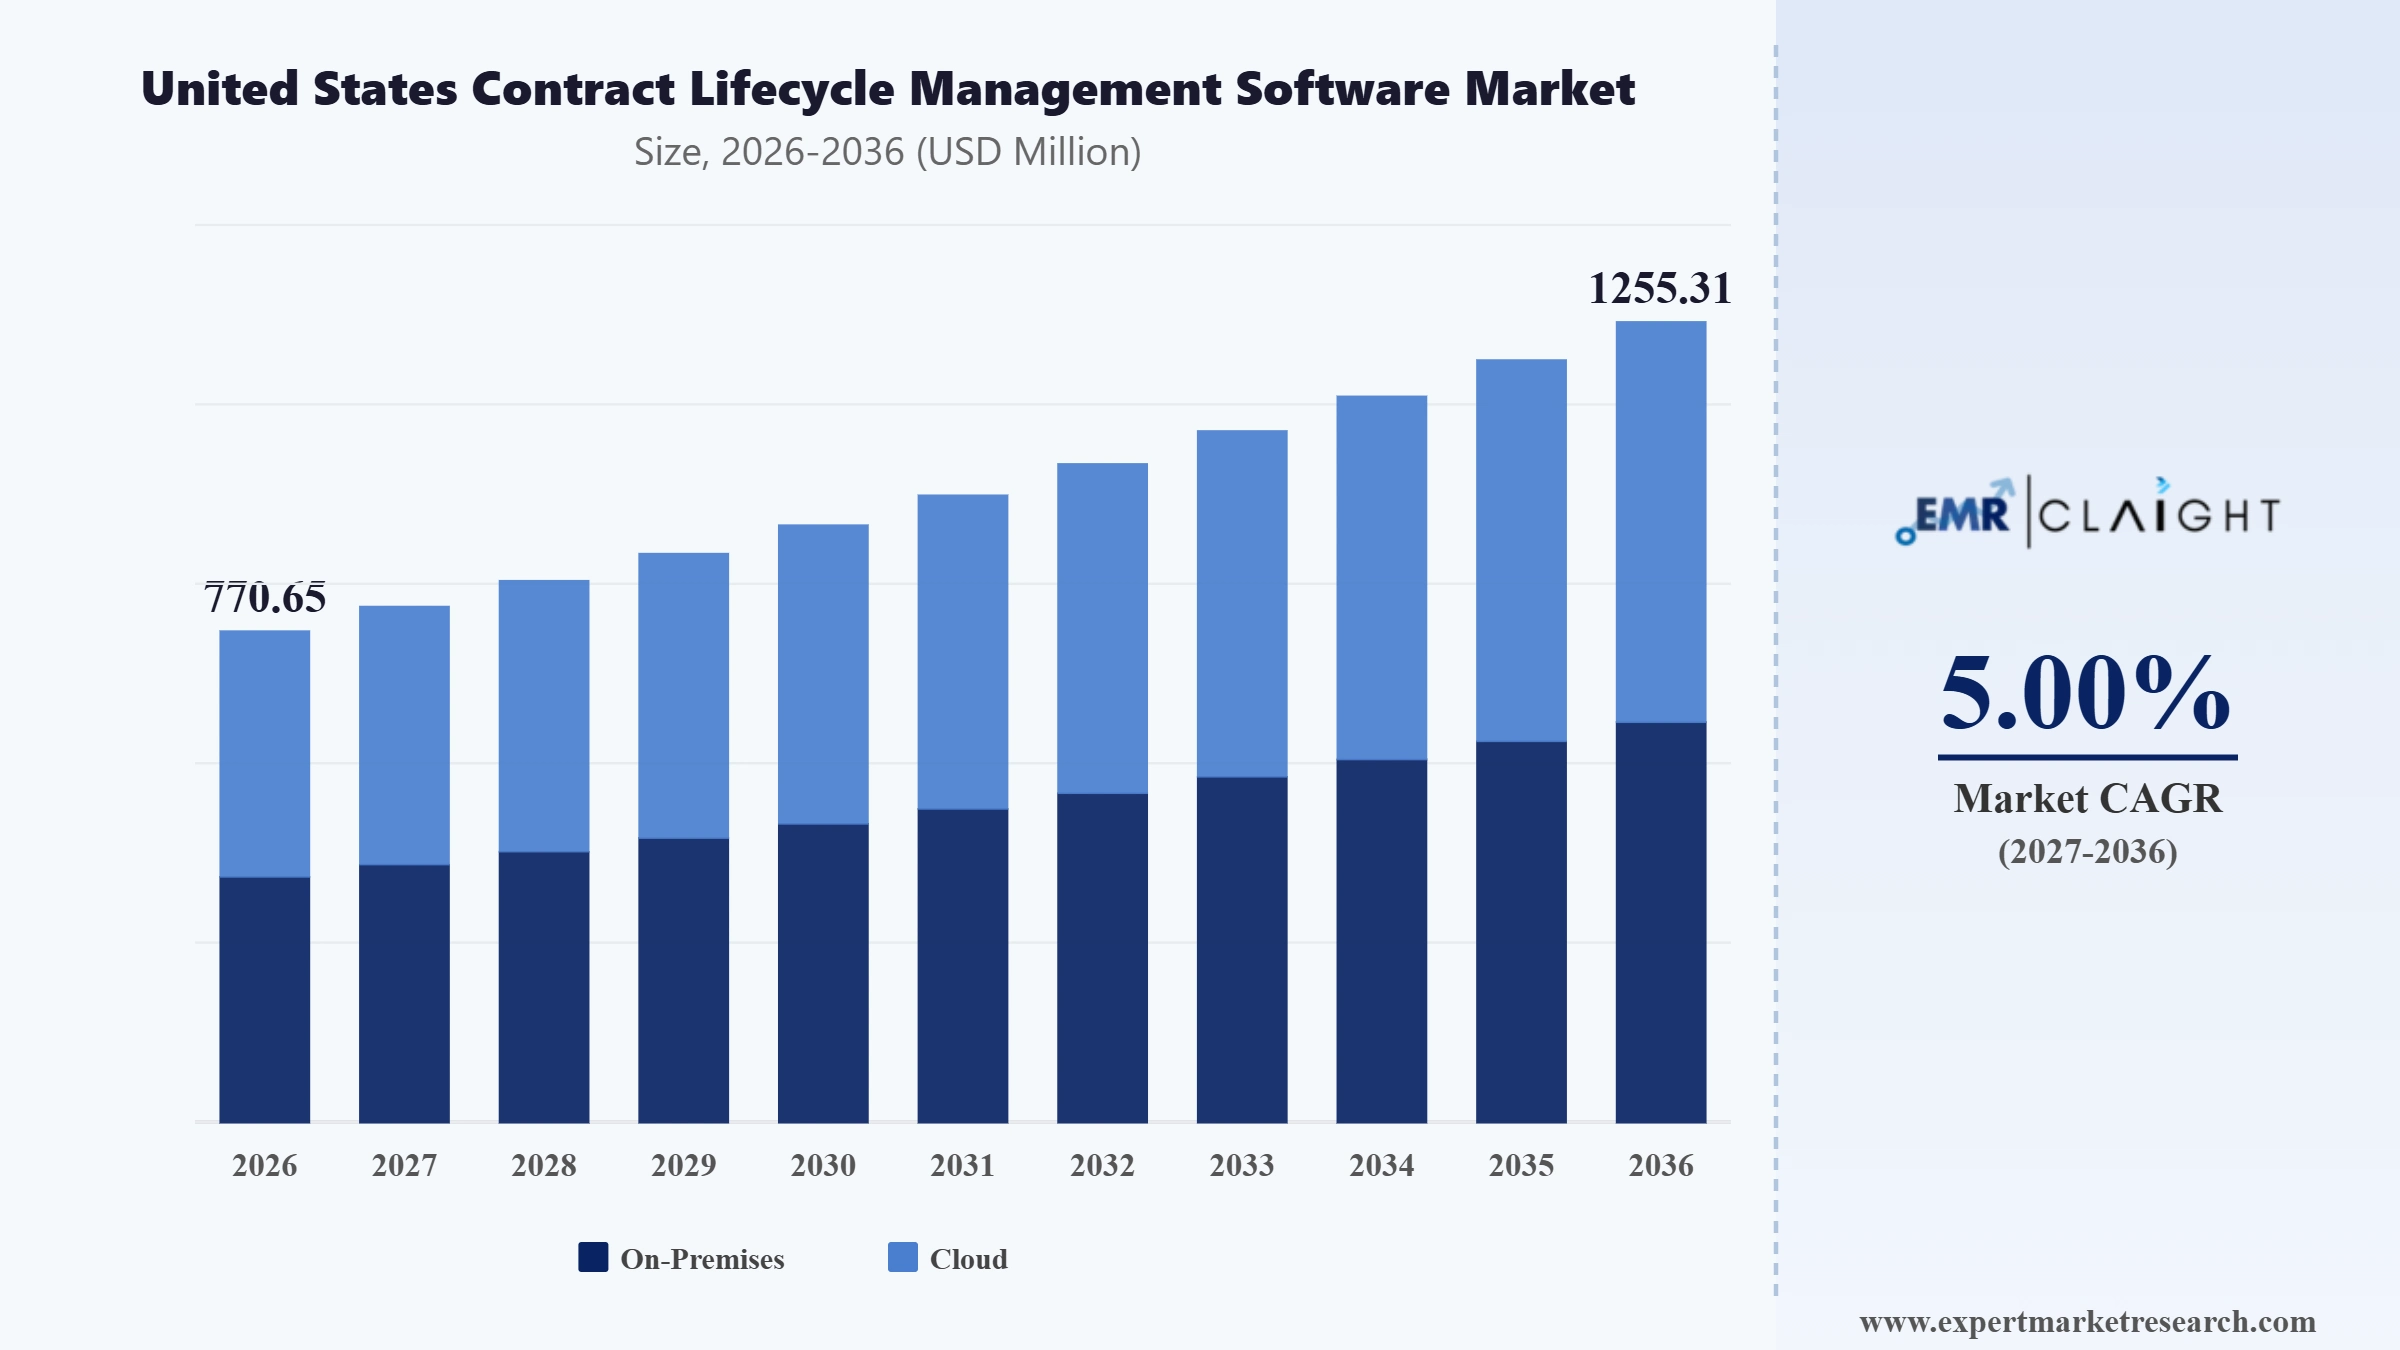
The United States contract lifecycle management software market attained a value of USD 733.95 Million in 2025 and is projected to expand at a CAGR of 5.00% through 2035. The market is further expected to achieve USD 1195.53 Million by 2035. Rising regulatory compliance requirements, increasing adoption of AI-powered contract review and risk analysis, and growing demand from large enterprises managing complex contract portfolios continue to support platform demand across cloud and on-premises deployment models.
Rising regulatory compliance requirements continue to anchor steady demand across the United States contract lifecycle management software market, as organisations increasingly seek to minimise legal and financial risk through automated contract tracking and obligation management. Providers are also investing in AI-native contract intelligence, reflecting the industry's ongoing pursuit of tools that move beyond simple document storage toward proactive risk identification and compliance monitoring.
The United States contract lifecycle management software market is witnessing further developments as established providers deepen platform investment through security certification and enterprise-grade compliance credentials. In October 2025, DocuSign achieved FedRAMP Moderate and GovRAMP authorisation for its Intelligent Agreement Management platform, while also expanding its identity verification portfolio to serve security-conscious government and enterprise customers. This shift toward government-grade security credentials is concentrated among providers with sufficient compliance infrastructure investment, while smaller specialists continue to compete on configurability and implementation speed for mid-market customers.
In addition, established providers are increasingly forming strategic partnerships with enterprise resource planning vendors to embed contract intelligence directly within existing procurement and finance workflows, reflecting the industry's recognition that native ERP integration increasingly determines platform stickiness beyond standalone contract repositories alone. Such integration partnership activity is reshaping competitive positioning across the wider united states contract lifecycle management software market as providers with proven ERP integration depth increasingly differentiate themselves from competitors offering only standalone contract management tools.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
SAP made a direct financial investment in Icertis and jointly ships the platform as the first SAP Solution Extension for contract lifecycle management, embedding contract intelligence directly within SAP's enterprise resource planning ecosystem. Companies can secure direct investment and co-branded distribution from major enterprise software vendors to embed contract intelligence within established ERP workflows used by large enterprise customers.
Conga finalised the acquisition of PROS Holdings' B2B business, expanding its revenue lifecycle and contract management capabilities to serve business-to-business pricing and configuration use cases. Companies can acquire complementary revenue optimisation businesses to extend contract lifecycle management capabilities into adjacent pricing and quoting workflows.
Agiloft launched enterprise-grade obligation management capabilities, positioning the release as pioneering the AI-native era of contract lifecycle management by automating post-signature tracking of contractual commitments and deadlines. Companies can launch dedicated obligation management modules to differentiate AI-native platforms from competitors focused primarily on pre-signature drafting and negotiation workflows.
DocuSign achieved FedRAMP Moderate and GovRAMP authorisation for its Intelligent Agreement Management platform in October 2025, while expanding its identity verification portfolio with the launch of CLEAR and Risk-Based Verification capabilities. Companies can pursue government-grade security authorisations to unlock federal and state government contract opportunities requiring stringent compliance credentials.
A notable pattern has emerged of large ERP vendors putting real capital behind niche CLM specialists rather than building competing features in-house. In August 2026, SAP made a direct investment in a specialist CLM provider, jointly shipping the platform as an official solution extension embedded within its ERP ecosystem across the united states contract lifecycle management software market. Such direct investment reflects enterprise vendors' recognition that co-branded distribution through established ERP relationships increasingly accelerates specialist platform adoption beyond independent sales channels alone.
Public sector contracts are drawing growing attention from platform vendors, many of whom now treat federal-grade compliance credentials as a prerequisite rather than a differentiator. In October 2025, DocuSign achieved FedRAMP Moderate and GovRAMP authorisation for its agreement management platform while expanding its identity verification capabilities. Such security authorisation reflects providers' recognition that stringent compliance credentials increasingly determine eligibility for high-value government contracts beyond commercial enterprise sales alone.
Vendors are looking beyond core contract drafting, folding pricing and quoting functionality into their platforms through targeted acquisitions. In February 2026, Conga finalised the acquisition of a business-to-business pricing and configuration business, expanding its revenue lifecycle capabilities. Such acquisitions reflect providers' recognition that extending beyond core contract drafting into adjacent pricing and quoting workflows increasingly captures a larger share of enterprise revenue operations spend.
Post-signature governance is emerging as its own product category, with vendors building dedicated tooling to track commitments long after a contract is executed. In December 2025, Agiloft launched enterprise-grade obligation management, automating tracking of contractual commitments and deadlines beyond initial contract execution. Such obligation management investment reflects providers' recognition that post-signature contract governance increasingly represents a distinct competitive battleground from pre-signature drafting and negotiation capability.
This Expert Market Research Report titled "United States Contract Lifecycle Management Software Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Deployment Mode
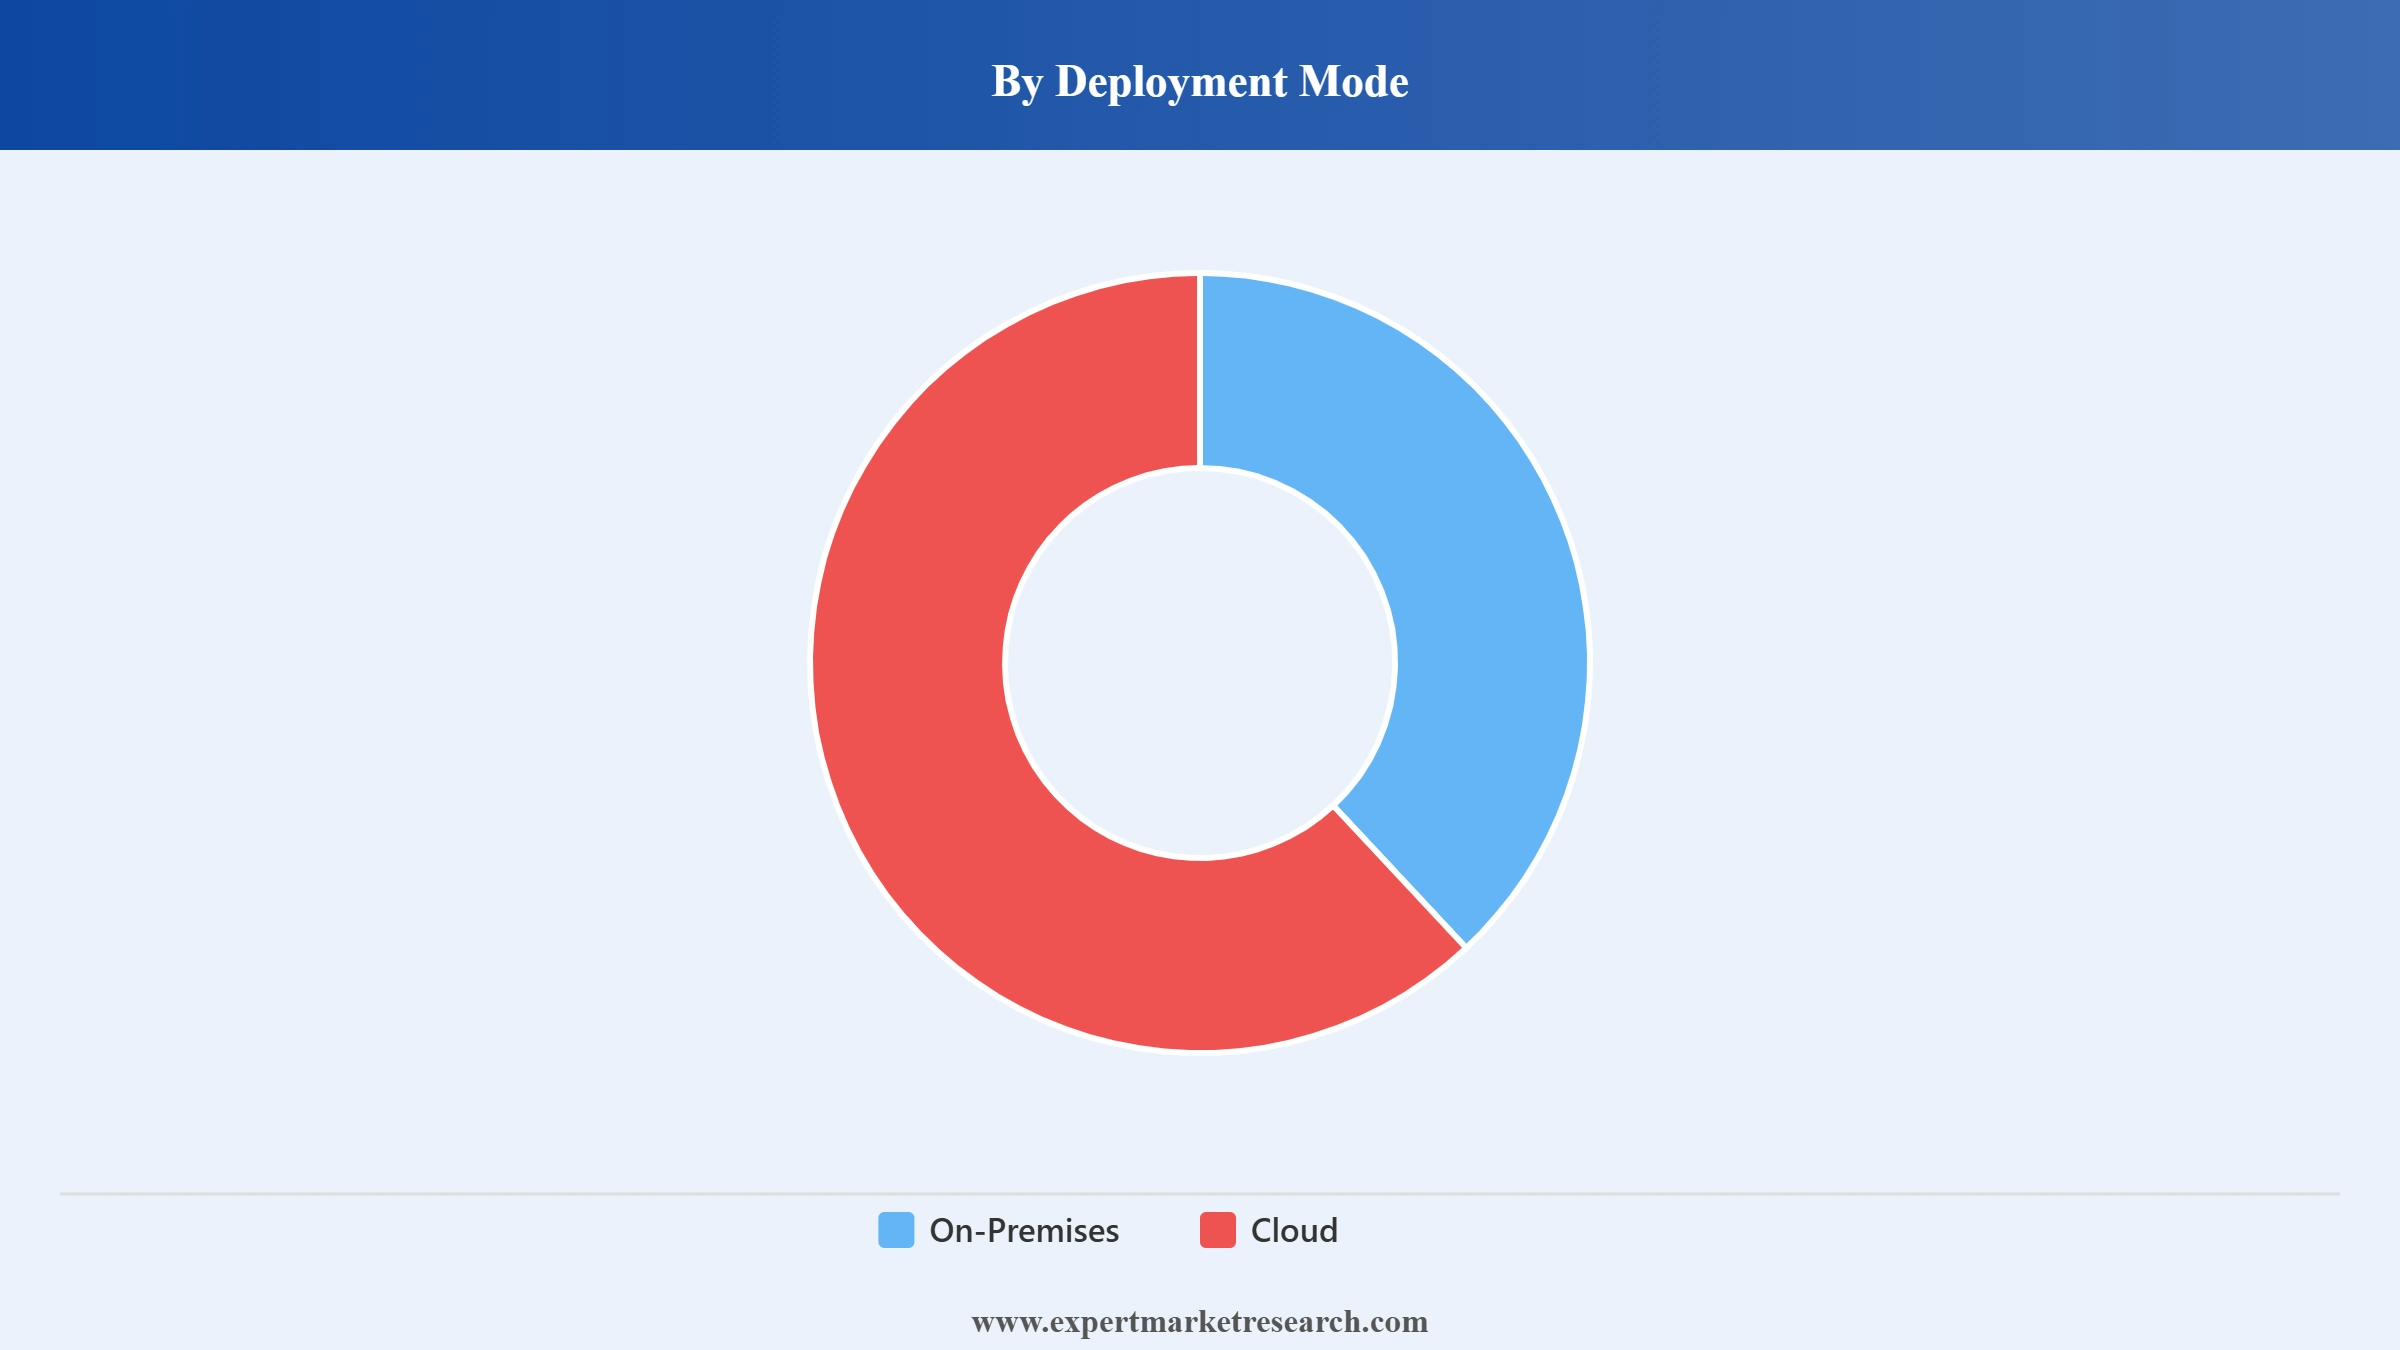
Key Insight: Cloud accounts for the largest share of the united states contract lifecycle management software market, reflecting its scalability and lower upfront infrastructure investment compared with on-premises alternatives. In August 2026, SAP's direct investment in Icertis as its first SAP Solution Extension for CLM underscored sustained enterprise investment in cloud-integrated contract intelligence. On-Premises continues to serve organisations with stringent data residency and security requirements that limit cloud adoption.
Market Breakup by Component
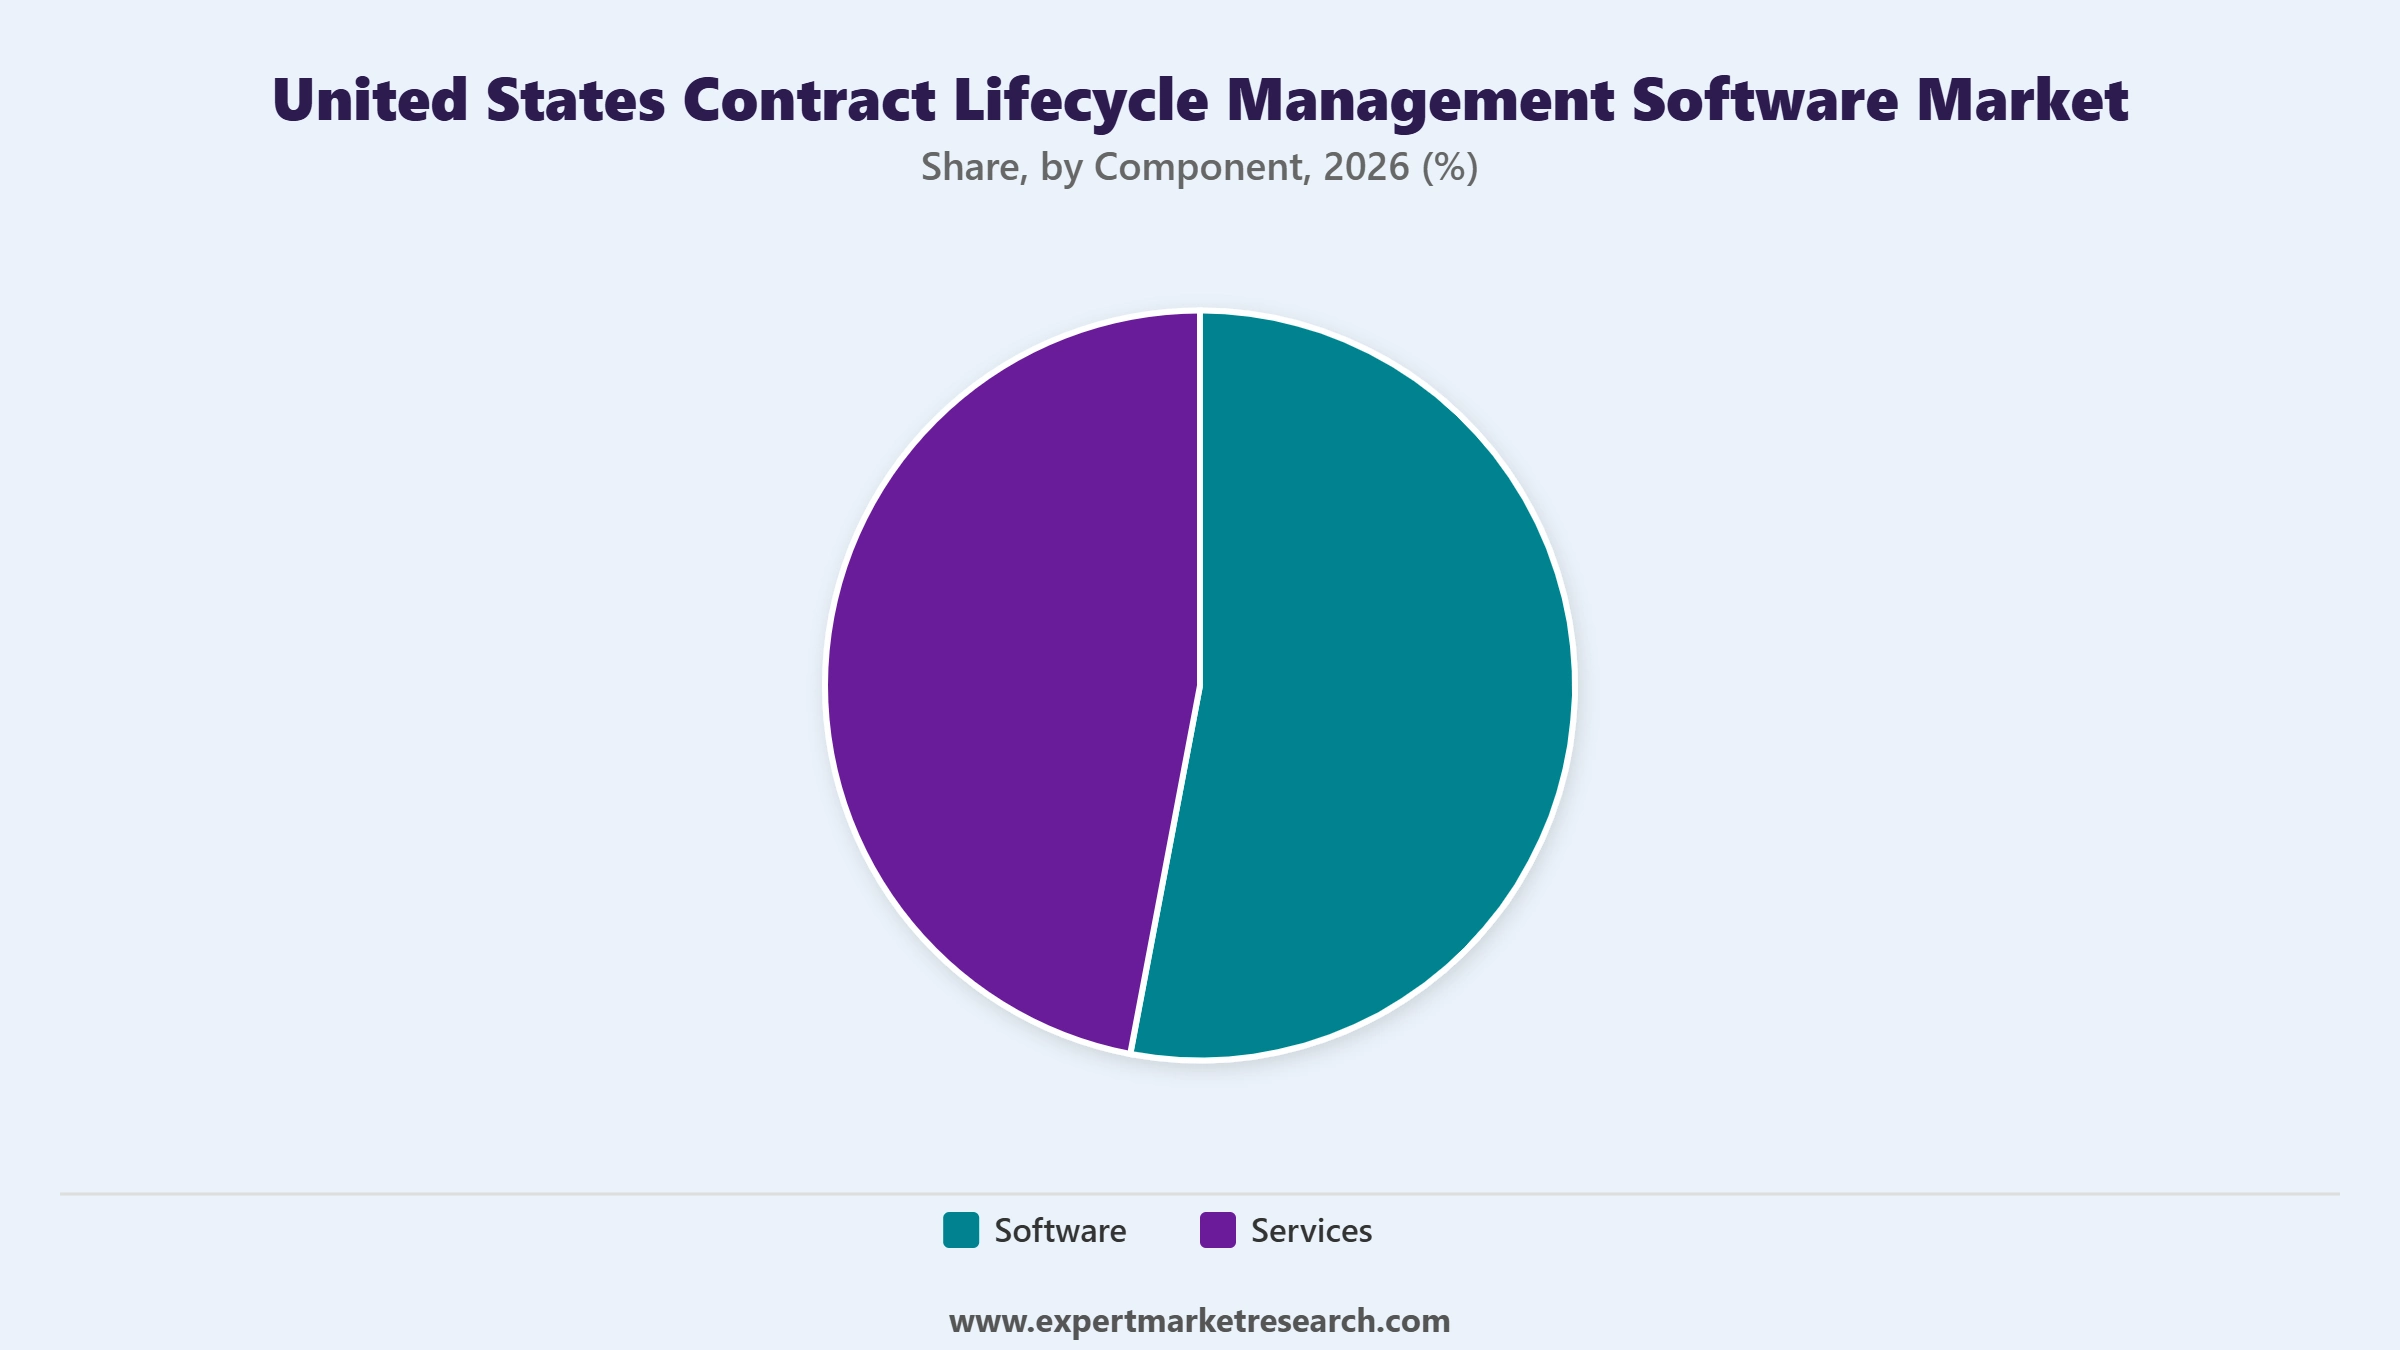
Key Insight: Software accounts for the largest share of the united states contract lifecycle management software market, reflecting sustained licensing and subscription revenue across enterprise CLM platform deployments. Services is growing at a fast pace as organisations increasingly require implementation, configuration, and change management support to fully realise platform capabilities, illustrated by DocuSign's October 2025 expansion of its identity verification and compliance service offerings.
Market Breakup by Enterprise Size
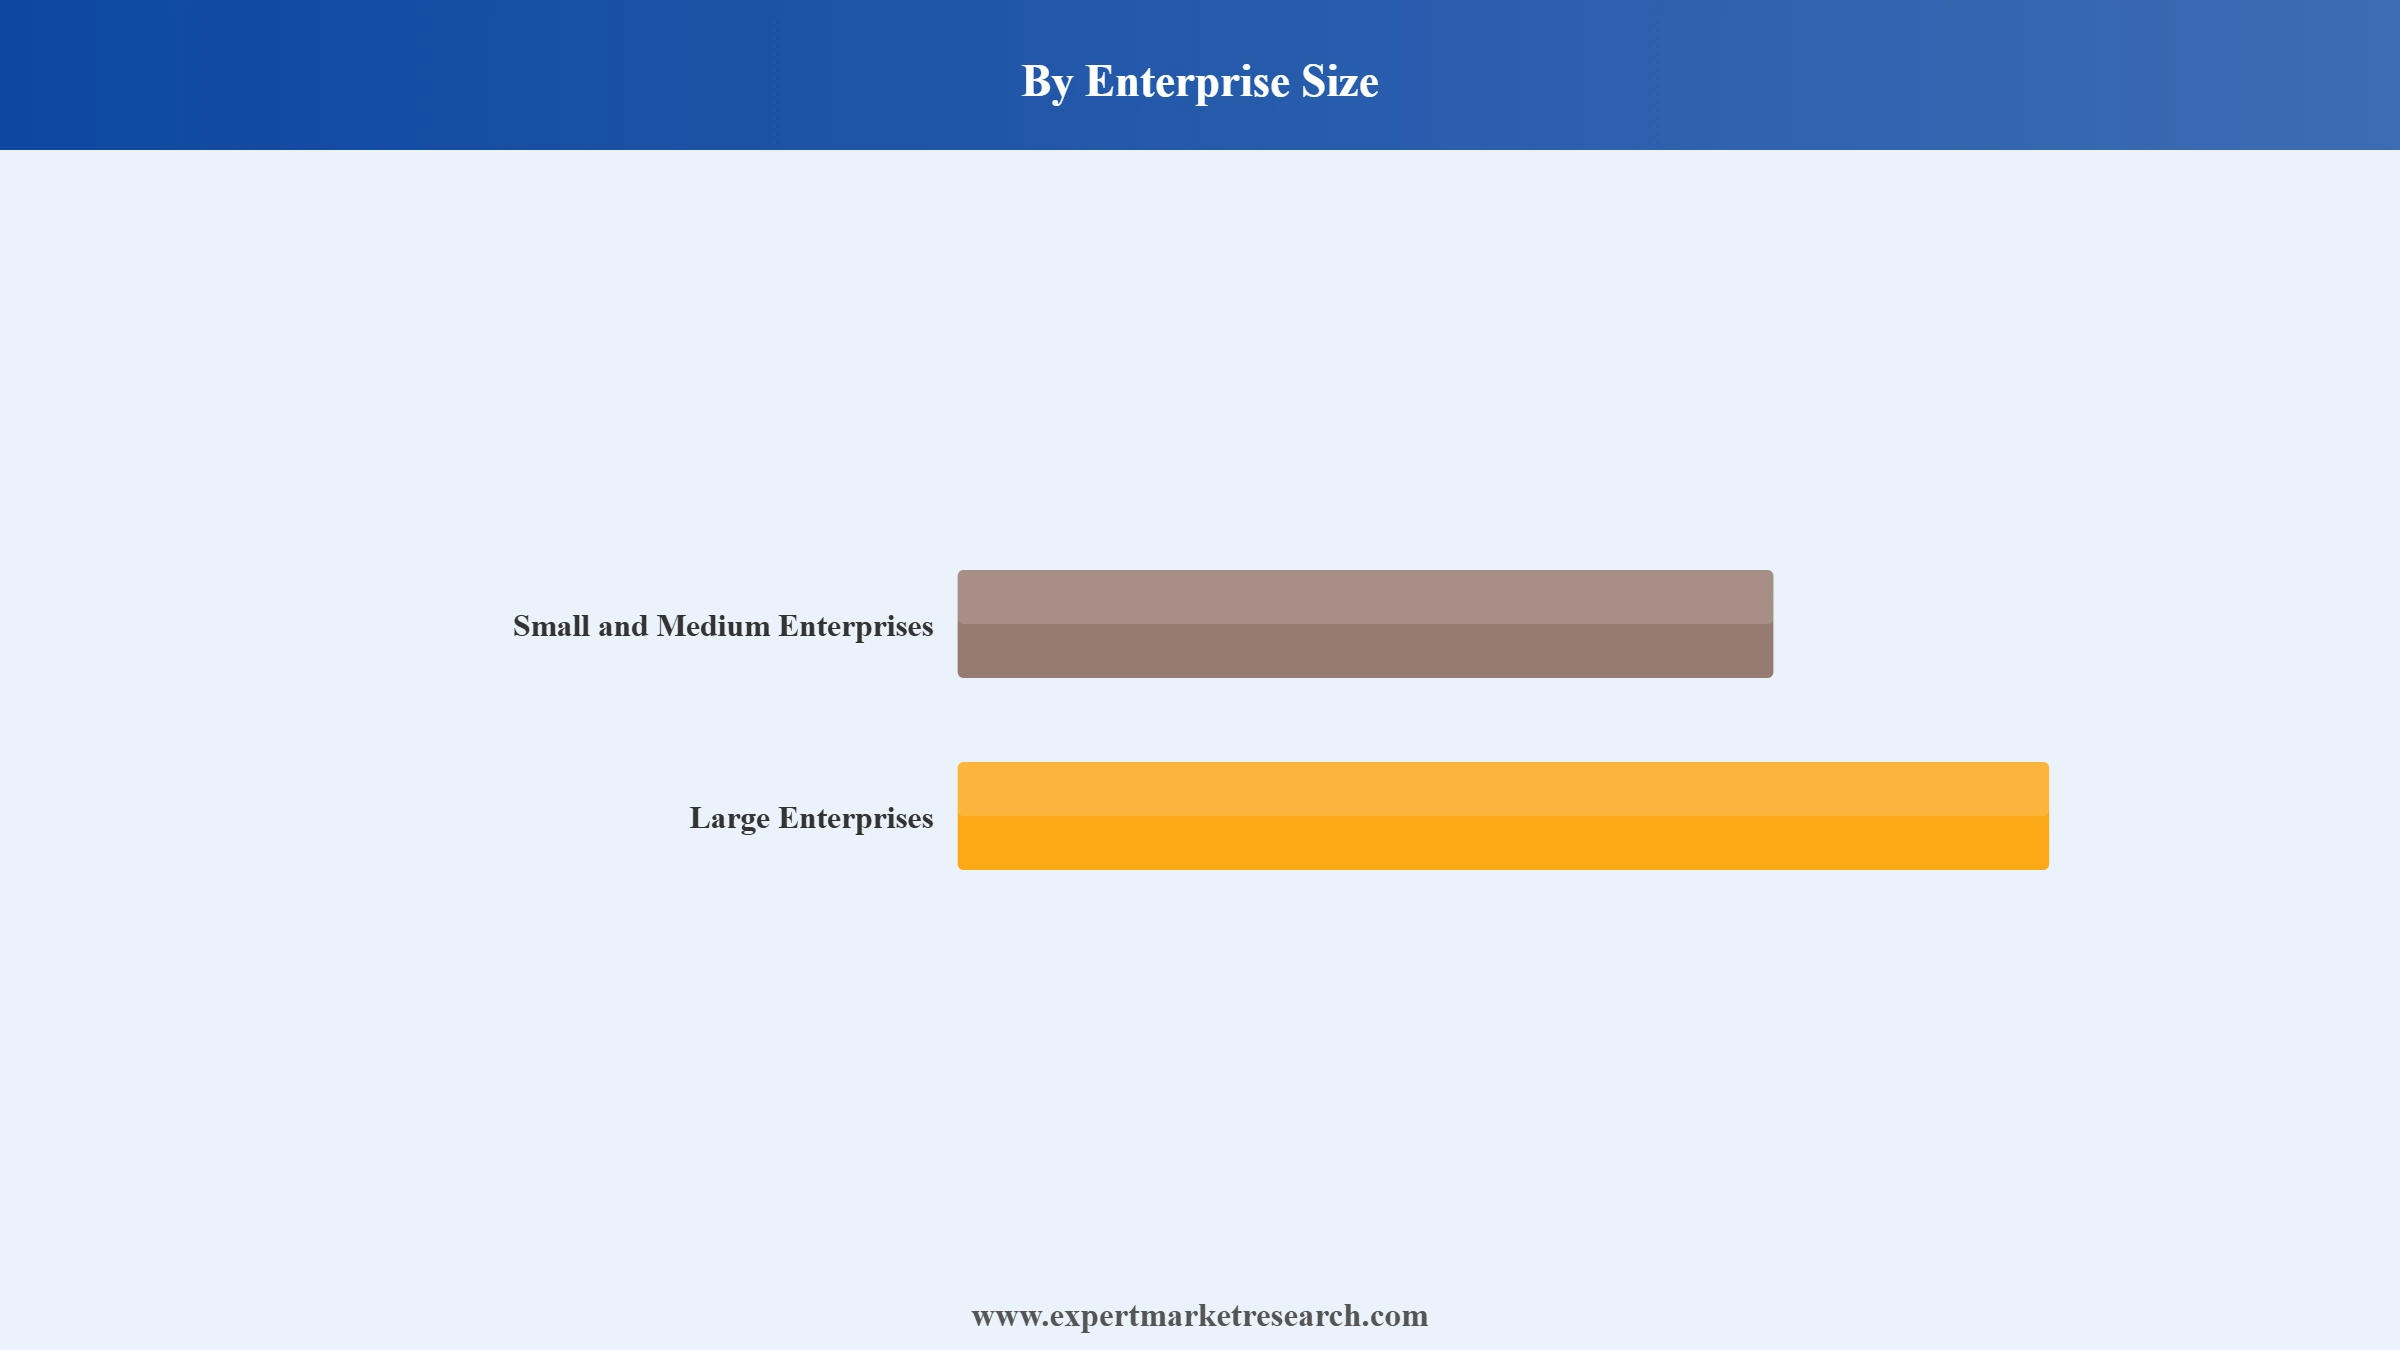
Key Insight: Large Enterprises accounts for the largest share of the united states contract lifecycle management software market, reflecting substantial contract volume and complexity requiring sophisticated obligation tracking and compliance capability. In December 2025, Agiloft launched enterprise-grade obligation management specifically targeting large enterprise post-signature governance needs. Small and Medium Enterprises is growing at a fast pace as more accessible, configurable platforms lower the barrier to structured contract management adoption.
Market Breakup by Industry Vertical
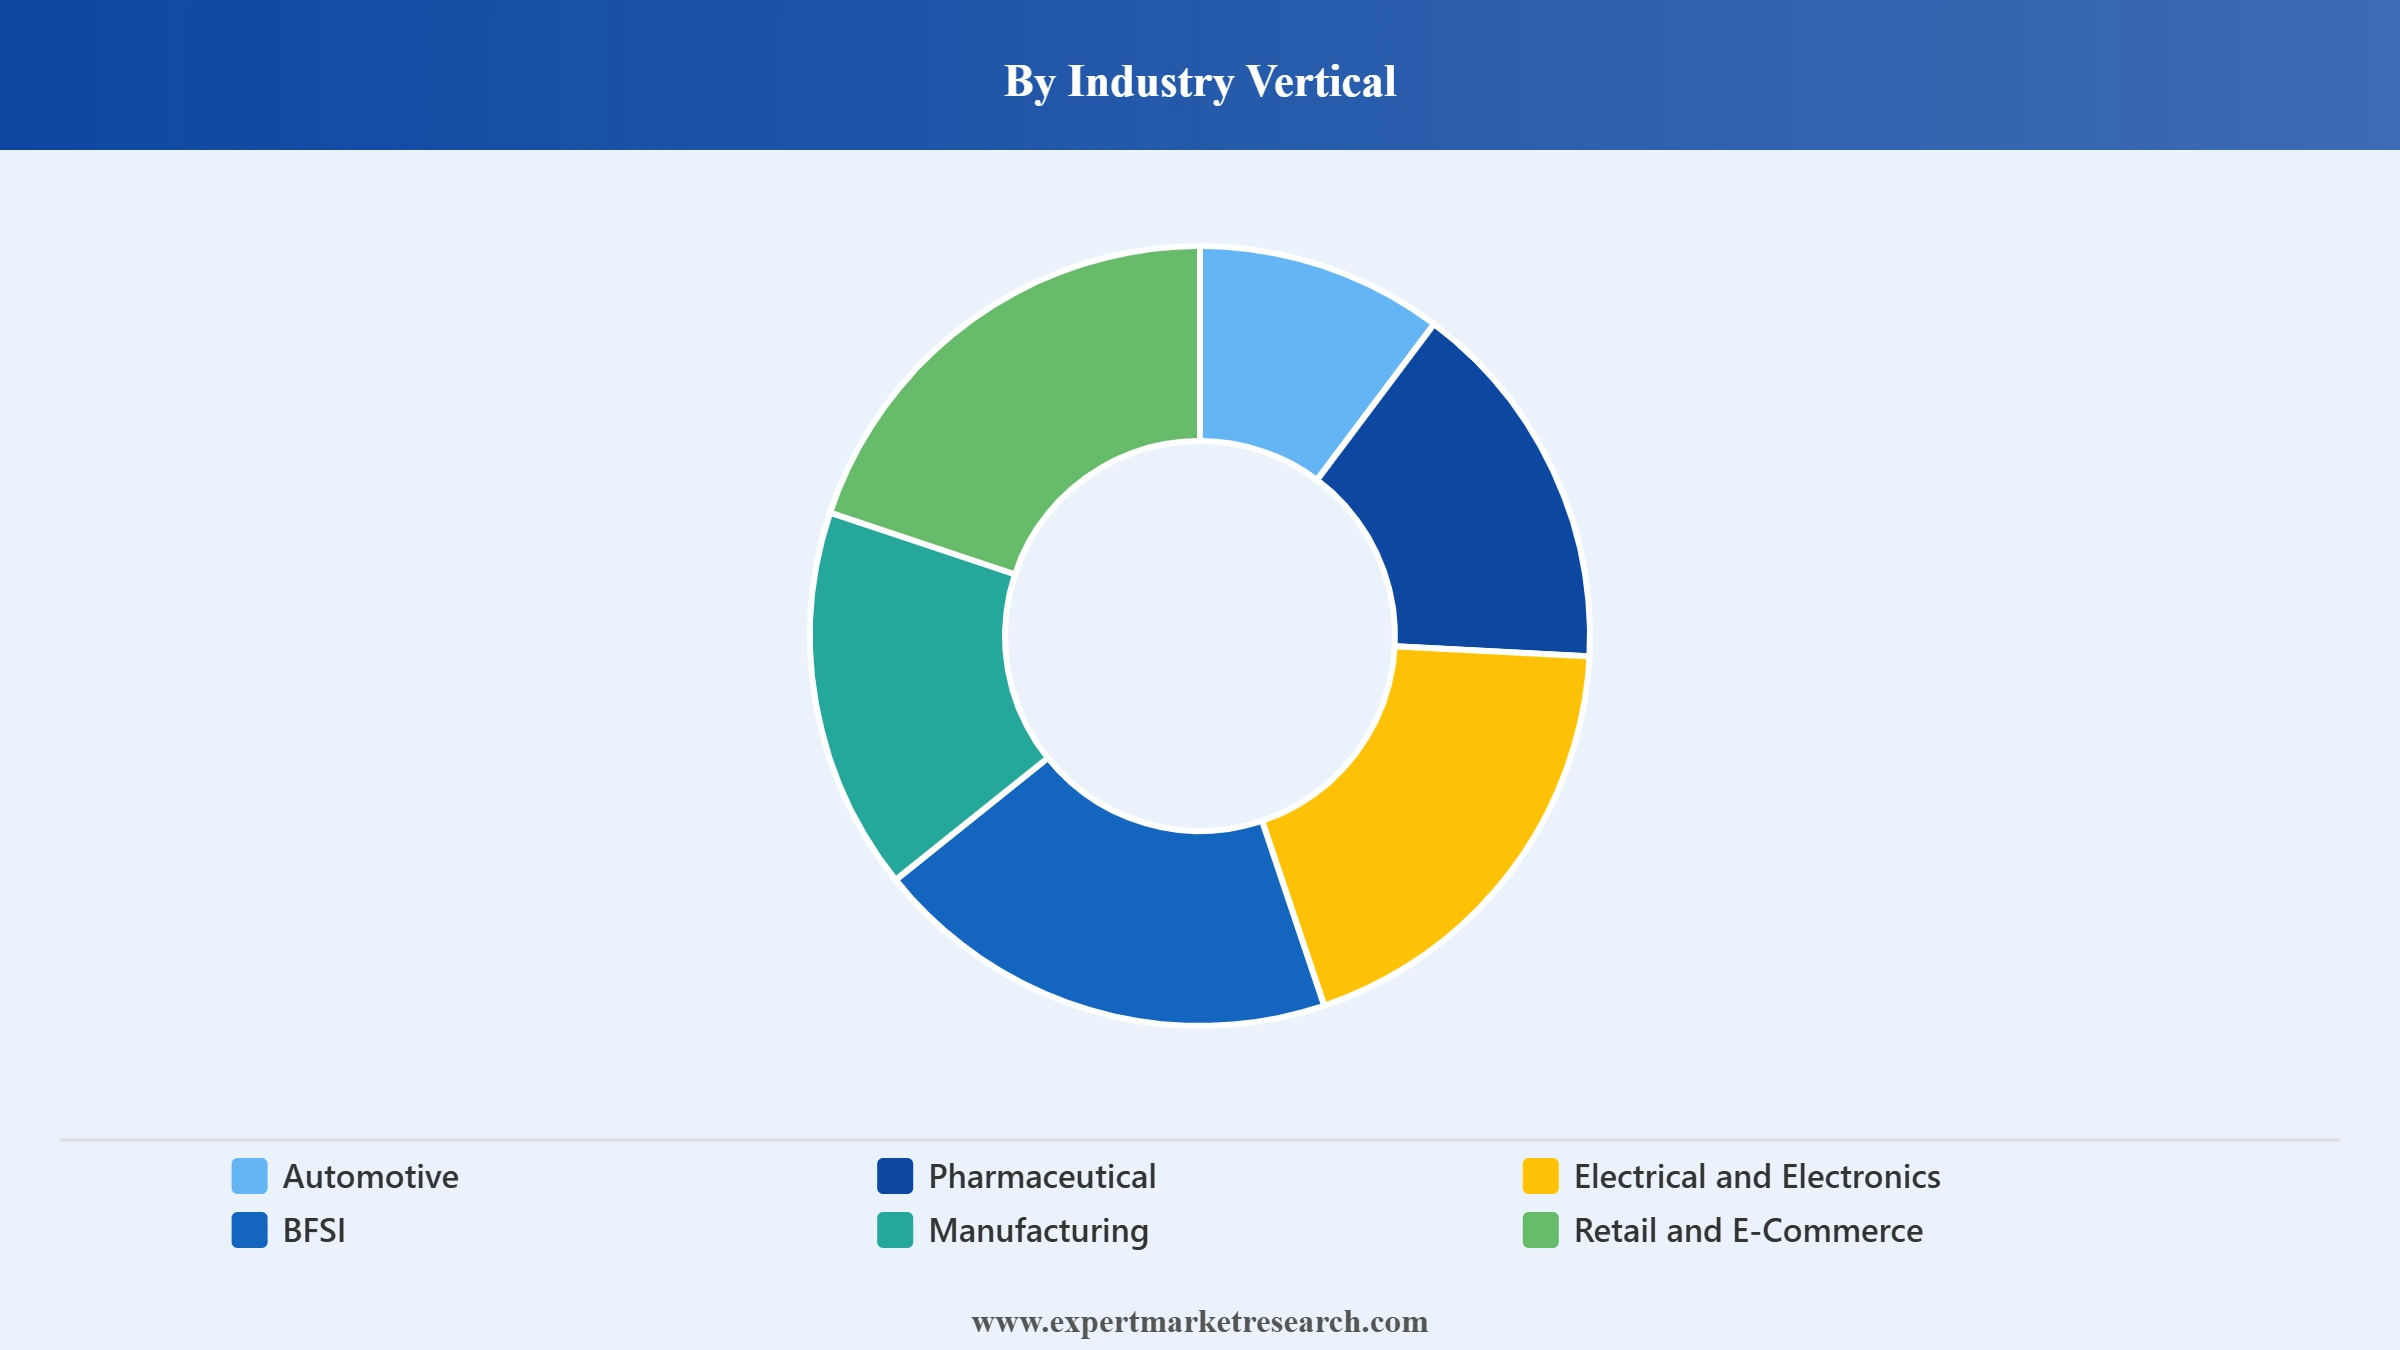
Key Insight: BFSI accounts for the largest share of the united states contract lifecycle management software market, reflecting the sector's stringent regulatory compliance requirements and high contract volume across lending, insurance, and investment services. Pharmaceutical continues to represent substantial demand given complex licensing and regulatory contract obligations, while In 2026, industry analysis highlighted growing agentic AI adoption in banking contract renewals, with Zycus reporting engagement from some of the largest financial institutions in the United States for digital procurement and contract transformation. Automotive, Electrical and Electronics, Manufacturing, and Retail and E-Commerce each maintain steady adoption tied to supplier and vendor contract complexity.
Market Breakup by Region
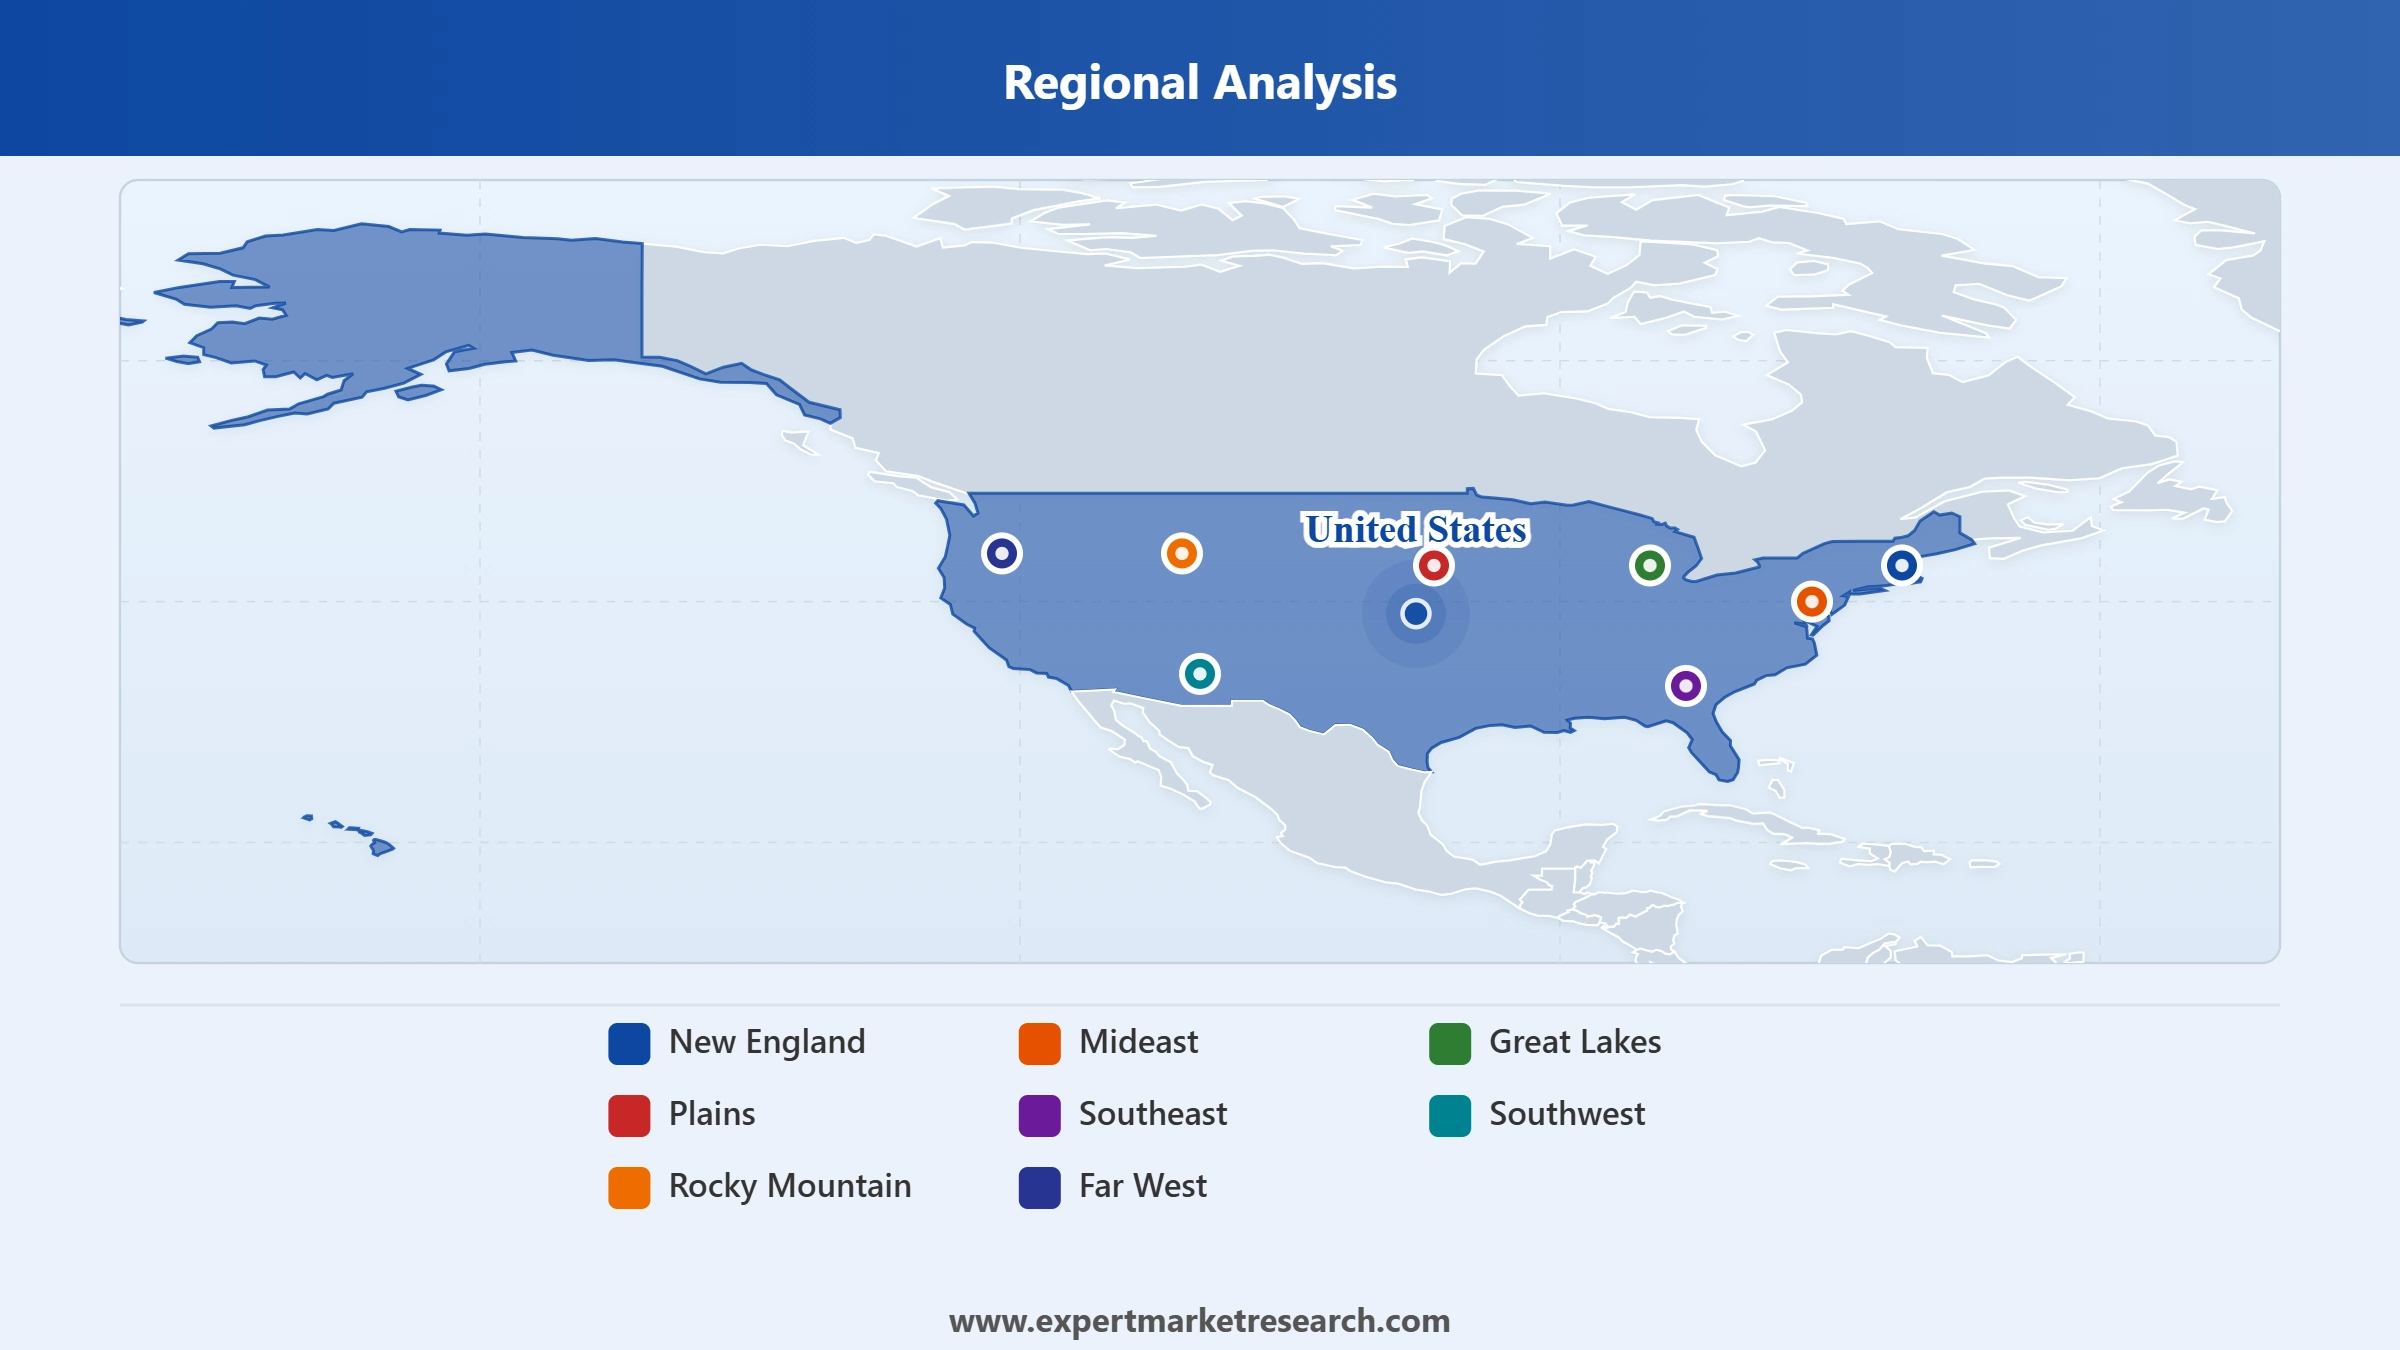
Key Insight: Southeast accounts for the largest share of the united states contract lifecycle management software market, supported by the region's concentration of corporate headquarters and growing technology infrastructure investment. Southwest is emerging as a key growth region as expanding enterprise technology hubs continue to drive adoption. Mideast, Great Lakes, Plains, Rocky Mountain, and Far West each continue to serve distinct regional industry concentration and adoption patterns.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By deployment, cloud leads the market while cloud continues strengthening its position given scalability advantages
Cloud continues to account for the largest share of the market, reflecting its scalability and lower upfront infrastructure investment compared with on-premises alternatives. Established cloud deployment relationships continue to anchor steady demand as enterprises maintain proven platform vendors across successive contract cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
On-Premises continues to serve a meaningful share of the united states contract lifecycle management software market as organisations with stringent data residency and security requirements maintain steady demand for direct infrastructure control. As of July 2026, Coupa's cloud-based contract management platform reported a mindshare of 2.8 percent within the category, up from 2.2 percent the prior year.
By enterprise size, large enterprises lead the market while large enterprises grow fastest given rising obligation management demand
Large Enterprises continues to account for the largest share of the market, reflecting substantial contract volume and complexity requiring sophisticated obligation tracking and compliance capability. Established large enterprise platform relationships continue to anchor steady demand as organisations maintain proven vendors across successive procurement cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Large Enterprises is also growing at the fastest pace across the united states contract lifecycle management software market as organisations managing high contract volumes increasingly invest in AI-native platforms. In December 2025, Agiloft launched enterprise-grade obligation management specifically targeting large enterprise post-signature governance needs.
By industry vertical, BFSI leads the market while BFSI continues strengthening its position given stringent regulatory requirements
BFSI continues to account for the largest share of the market, reflecting the sector's stringent regulatory compliance requirements and high contract volume across lending, insurance, and investment services. Established BFSI platform relationships continue to anchor steady demand as financial institutions maintain proven vendors across successive compliance cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Pharmaceutical continues to represent substantial demand across the united states contract lifecycle management software market given complex licensing and regulatory contract obligations requiring sophisticated compliance tracking capability. In April 2026, an independent review of Icertis highlighted its Vera AI engine, trained on more than 10 million contracts, as the highest-scoring platform for enterprises managing complex, regulated agreements across BFSI and pharmaceutical sectors.
By component, software leads the market while services grows fastest given rising implementation support demand
Software continues to account for the largest share of the market, reflecting sustained licensing and subscription revenue across enterprise CLM platform deployments. Established software licensing relationships continue to anchor steady demand as enterprises maintain proven platform vendors across successive renewal cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Services is growing at the fastest pace across the united states contract lifecycle management software market as organisations increasingly require implementation, configuration, and change management support. In October 2025, DocuSign expanded its identity verification and compliance service offerings alongside its FedRAMP and GovRAMP authorisation.
Southeast commands the largest share of the market through its concentration of corporate headquarters
Southeast holds the largest share of the United States contract lifecycle management software market, supported by the region's concentration of corporate headquarters and growing technology infrastructure investment. Regional enterprises continue to expand AI-native contract intelligence adoption to meet sustained demand for compliance and risk management capability.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Southwest is emerging as a key growth region as expanding enterprise technology hubs continue to drive adoption. Continued provider investment in government-grade security authorisation in October 2025 underscored sustained demand for compliant contract management capability extending well beyond Southeast's traditional market concentration across the wider united states contract lifecycle management software market.
The industry is fragmented, with united states contract lifecycle management software market companies ranging from diversified enterprise software groups spanning multiple business applications to specialist contract lifecycle management providers competing across deployment, organisation size, and industry vertical segments. Established players operate across the full CLM value chain, from contract drafting and negotiation through complete post-signature obligation management and compliance monitoring for enterprise customers.
Competitive dynamics among united states contract lifecycle management software players are increasingly shaped by the pace of ERP integration partnerships, the scale of government-grade security certification, and the race to launch AI-native obligation management capabilities. Providers are investing in artificial intelligence contract review, native ERP integration, and post-signature governance tools to differentiate their offering and secure long-term enterprise customer relationships.
Founded in 1972 and headquartered in Walldorf, Germany, SAP provides enterprise resource planning software with contract lifecycle management capabilities delivered through its investment in and integration with Icertis. In August 2026, the company deepened its investment in Icertis, jointly shipping the platform as the first SAP Solution Extension for contract lifecycle management. SAP's extensive enterprise resource planning ecosystem differentiates its offering from standalone CLM providers lacking comparable ERP integration depth.
Founded in 2003 and headquartered in San Francisco, California, United States, DocuSign provides electronic signature and contract lifecycle management software through its Intelligent Agreement Management platform. In October 2025, the company achieved FedRAMP Moderate and GovRAMP authorisation while expanding its identity verification portfolio. DocuSign's market-leading e-signature footprint differentiates its offering from competitors lacking comparable native signature integration.
Founded in 2006 and headquartered in San Mateo, California, United States, Coupa provides business spend management software with integrated contract management capabilities spanning sourcing, procurement, and invoicing. The company serves enterprise customers requiring unified spend visibility and contract compliance. Coupa's combined procurement and contract management platform differentiates its offering from standalone CLM providers lacking comparable spend management breadth.
Founded in 2009 and headquartered in Bellevue, Washington, United States, Icertis provides enterprise contract intelligence software serving large organisations with complex, high-volume contracting needs across legal, sales, procurement, and finance functions. In August 2026, the company became the first SAP Solution Extension for contract lifecycle management following SAP's direct investment. Icertis' enterprise-grade scalability and deep ERP integrations differentiate its offering from platforms designed primarily for mid-market contract volumes.
Other key players in the United States contract lifecycle management software market include Concord Worldwide, Inc., Zycus Inc., Agiloft Inc., Apttus Corp. (Conga), Onit Inc. (SecureDocs, Inc.), and Evisort Inc. (now Workday Contract Intelligence), among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our United States contract lifecycle management software market trends 2026 report. Discover regional growth patterns, deployment and organisation size trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 733.95 Million.
The market is estimated to grow at a CAGR of 5.00% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach a value of around USD 1195.53 Million by 2035.
Deepening direct investment and integration partnerships with major enterprise resource planning vendors, pursuing government-grade security authorisations to unlock public sector contracts, and launching dedicated post-signature obligation management capabilities to differentiate AI-native platforms.
The key trends aiding the market expansion include technological advancements in AI and machine learning, mergers and acquisitions in the industry, and the shift to sustainability and a paperless workspace, supported by the automation of contract creation.
The major regions in the market are New England, Mideast, Great Lakes, Plains, Southeast, Southwest, Rocky Mountain, and Far West.
The major industry verticals include automotive, pharmaceutical, electrical and electronics, BFSI, manufacturing, and retail and e-commerce, among others.
The key players in the market are SAP SE, Concord Worldwide, Inc., DocuSign, Inc., Coupa Software Inc., Zycus Inc., Icertis, Inc., Agiloft Inc., Apttus Corp. (Conga), Onit Inc. (SecureDocs, Inc.), and Evisort Inc., among others.
Providers face lengthy implementation timelines and change management complexity for large enterprise deployments, pricing pressure from AI-native point solutions targeting simpler contract workflows, and intensifying competition from broader enterprise software platforms embedding contract capabilities natively.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Deployment Mode |
|
| Breakup by Component |
|
| Breakup by Enterprise Size |
|
| Breakup by Industry Vertical |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




