

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
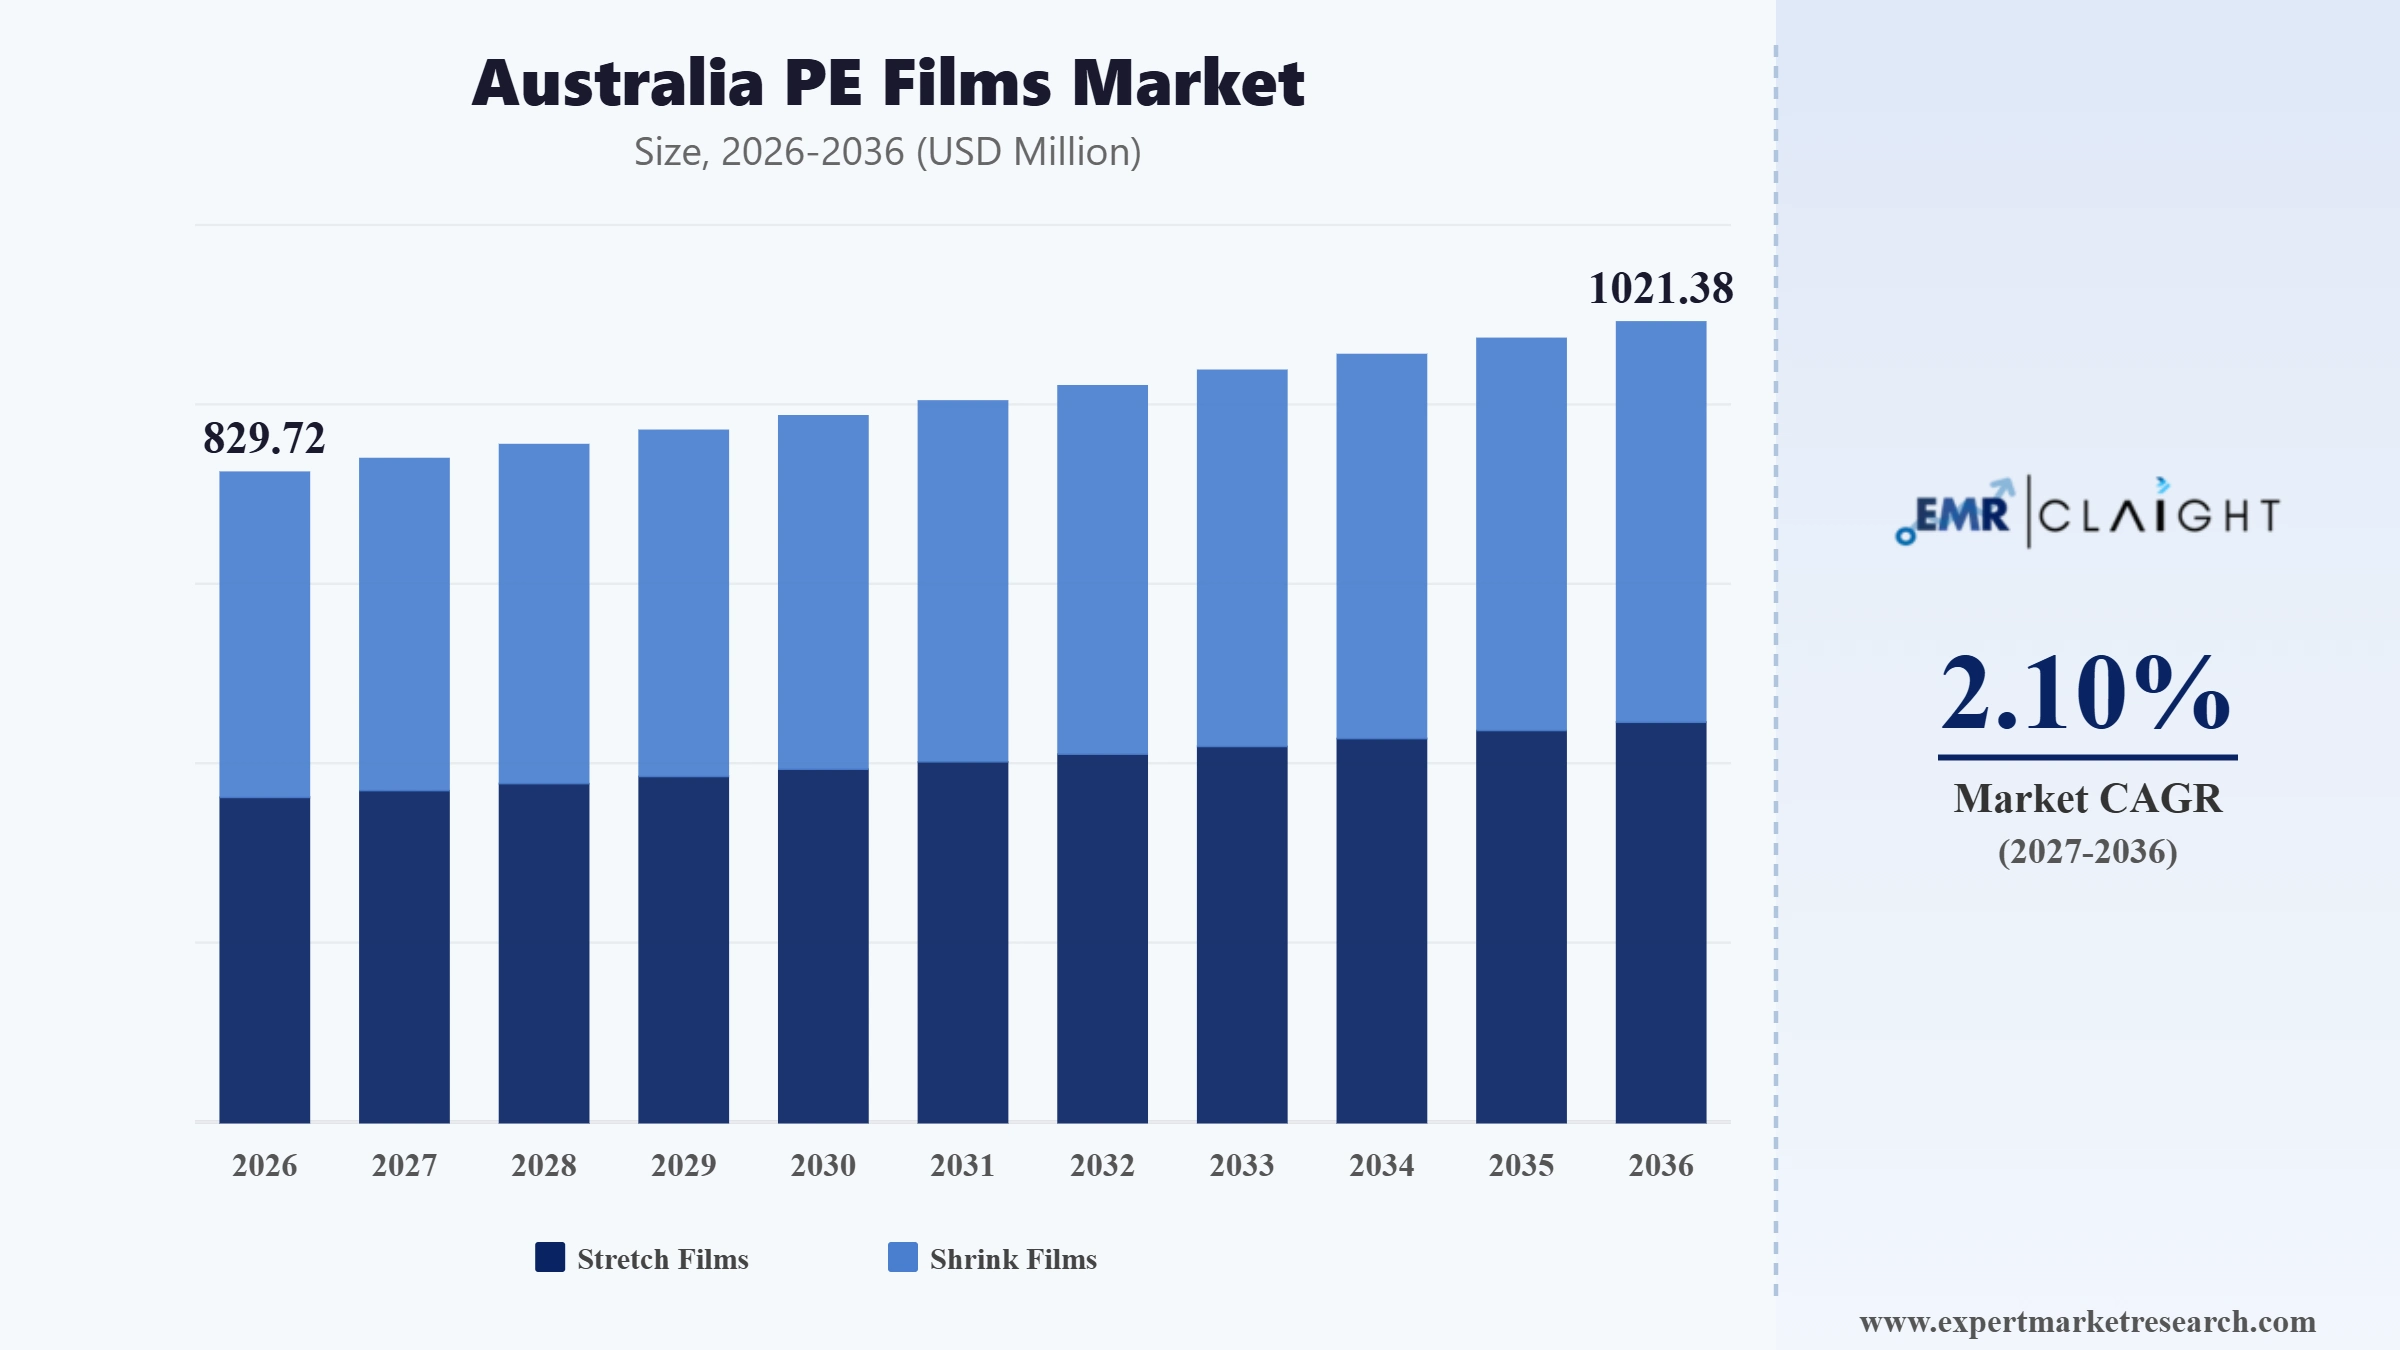
The Australia PE films market attained a value of USD 812.65 Million in 2025and is projected to expand at a CAGR of 2.10% through 2035. The market is further expected to achieve USD 1000.37 Million by 2035. Expansion of domestic recycled-plastics capacity is creating a new opportunity for Australian PE film manufacturers to develop locally sourced recycled-content films. Australia’s plastics reprocessing capacity reached 600 kilotonnes in 2023-24, up from 305 kilotonnes in 2022-23, while a further 624 kilotonnes of planned capacity is expected by 2028-29. This expanding processing base can improve recycled-resin availability for film converters, supporting material substitution, packaging redesign, and higher recycled-content integration.
The dispersed population of Australia and its long internal supply chain make it necessary to have protective packaging that will keep the products safe during handling, storage, and transport. PE films help in offering the needed flexibility in sealing, moisture protection, and light packaging of foods and fresh produce. The possibilities for film suppliers in Australia go beyond the regular packaging materials to include film that is suitable for automated filling, fast sealing, puncture resistance, and efficient packing. Film suppliers who work with food processing companies on film specification can gain contracts that are regular and at the same time help the customers cut down the amount of packaging materials used per unit. Increasing emphasis on shelf-life management and transport efficiency is also encouraging buyers to evaluate film performance alongside total packaging costs, creating opportunities for higher-value customized PE film solutions, thereby boosting the Australia PE films market value.
One area of innovation in the Australian PE films market is the application of multilayer extrusion technology that allows the combination of multiple PE grades into one film. In contrast to the traditional practice of increasing film thickness in order to enhance its mechanical properties, multilayer extrusion can allow converters to allocate materials with improved characteristics in certain layers to achieve either better puncture resistance, sealing ability, rigidity, or elasticity. By applying multilayer extrusion, converters will be able to reduce the thickness of the film, i.e., perform downgauging, while retaining the required performance characteristics demanded by industrial and packaging markets. Modern extrusion technologies will enable precise adjustment of layers and resin ratios to produce films for certain applications. For Australian converters, the commercial opportunity lies in pairing multilayer engineering with recyclable PE-based structures, enabling performance optimization without automatically increasing material consumption. This can strengthen product differentiation and improve resource efficiency for high-volume customers.
Incorporating recycled polyethylene into film production can create difficulties because recycled feedstock may vary in melt flow, contamination levels, color, and mechanical properties. SThe variation will pose challenges to the manufacturing process, such as extruder stability, film gauge, sealing ability and the strength of the films. It will be challenging for the converters to maintain the same standards among the film batches. The issue will be significant especially for customers who are using automatic packaging machinery since poor quality films may cause more production downtime and production losses. Manufacturers can establish supplier-specific resin qualification protocols covering melt flow, contamination, moisture, density, and mechanical performance before recycled material enters production. Controlled blending with virgin PE and inline process monitoring can further stabilize film properties. Maintaining approved recycled-resin specifications and batch traceability allows converters to increase recycled content while protecting consistency and customer performance requirements, thereby boosting the Australia PE films market developments.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
KM Packaging introduced K-Peel VPMe in Australia and New Zealand on August 27, 2026, adding a 55-micron multi-seal polyolefin lidding film to its Recycle Ready range. The film seals PET, PP and PE trays, as well as lacquered foil, and is commercial in frozen ready meals while being trialled for chilled meals, fresh protein and snacks. The launch may increase demand for technically engineered PE/polyolefin films, particularly where converters need reliable sealing across tray substrates while improving complete-pack recyclability. Commercially.
Pakaflex completed its transition to water-based inks across manufacturing operations in May 2026, removing VOC emissions from its printing systems and making the inks non-flammable. The company said the conversion required nearly a year of testing, ink formulation, an ink-mixing system and laser anilox cleaning systems. For Australia’s PE film market, the development increases emphasis on lower-impact printed-film conversion and production environments, while improved scratch and UV resistance could support demand for higher-value printed PE films in industrial packaging applications.
Amcor and Belgium-based De Ceuster Meststoffen NV introduced recycle-ready mono-PE fertiliser packaging in Europe on March 3, 2026. The packs contain 35% post-consumer recycled content and replace a previous multi-material structure, using machine-direction-oriented PE with a sealant layer. Available from 650 grams to 7 kilograms, the packaging targets strength, moisture protection and recycling. For Australian PE film suppliers, the development highlights opportunities in farm packaging, accelerating interest in MDO-PE structures, recycled-content qualification and films for fertiliser and agricultural inputs.
Amcor invested in a new production line at its Lugo di Vicenza facility on March 9, 2026, expanding production of high-barrier recycle-ready films for lidding and pouches. The facility supports food, beverage, pet food and healthcare applications and includes quality-control and temperature-controlled warehousing systems. The expansion could influence Australia via multinational supply chains by increasing access to recycle-ready film technologies. It also signals growing demand for PE-based structures that combine barrier performance, process consistency and recyclability in demanding applications, thus shaping the trends of the Australia PE films market.
Australian PE film manufacturers are increasingly focusing on mono-material structures that can simplify packaging recovery while preserving the performance required by demanding applications. The opportunity is particularly relevant to agricultural-input and industrial packaging, where conventional laminated structures can combine incompatible polymers. In March 2026, Amcor and Belgium-based DCM introduced a mono-PE fertiliser bag containing 35% post-consumer recycled content, demonstrating how recycled resin can be incorporated into performance-oriented flexible packaging. For Australian converters, the trend extends beyond simply replacing multilayer packs: resin compatibility, seal strength, puncture resistance, printability, and end-of-life identification must be considered together. This creates opportunities for specialised PE formulations and application-specific mono-material structures.
Australian PE film production is moving toward more sophisticated blown-film configurations as converters address increasingly specific performance requirements. Polyem, an Australian manufacturer incorporated in 1977, produces custom blown films using LDPE, LLDPE, mLLDPE, and HDPE, demonstrating the value of combining different polyethylene grades within engineered film structures. This capability is particularly relevant for industrial liners, protective films, packaging, and specialised bags where tensile strength, elongation, sealing and puncture resistance need to be balanced. The niche opportunity is shifting from commodity film output toward formulation-led manufacturing, where converters can adjust resin combinations and processing parameters for individual customers. Better extrusion control can also reduce thickness variation and off-specification production.
Supply-chain resilience is becoming a distinct competitive factor for Australian PE film buyers that require customised dimensions, frequent replenishment or application-specific specifications. Domestic manufacturing can provide shorter communication and production cycles than overseas sourcing, particularly when customers require modifications to film width, thickness, printing or packaging configuration. In May 2026, Signet highlighted its flexible-packaging manufacturing capabilities for Australian businesses alongside its international supply network. For PE film suppliers, this model points toward a hybrid procurement environment in which local conversion complements imported raw materials and selected finished products. The opportunity is particularly relevant to industrial customers requiring dependable supply, customised film specifications, technical support and responsive inventory management, thereby boosting the Australia PE films market dynamics and trends.
The expansion of Australia's plastics reprocessing infrastructure is creating a more practical pathway for PE film manufacturers to investigate recycled-content formulations. Government statistics indicate an increase in the nation's plastic reprocessing capacity from 305 kilotonnes in 2022-23 to 600 kilotonnes in 2023-24, although actual usage was only about half of the total capacity available. The difference creates a distinct market opportunity to obtain technically consistent recycled PE as opposed to simply increasing recycled content. Film manufacturers can develop resin qualification procedures covering melt-flow characteristics, contamination, colour, tensile performance and processing behaviour. The most immediate opportunities are likely to occur in applications where recycled resin can be incorporated without stringent food-contact requirements, including industrial bags, liners, agricultural products and protective films.
Australian PE film suppliers are increasingly participating in packaging redesign at the complete-pack level, particularly where films must function with different tray substrates or sealing systems. In August 2026, KM Packaging introduced K-Peel VPMe in Australia and New Zealand, a 55-micron polyolefin lidding film designed to seal with PET, PP and PE trays. This type of multi-substrate compatibility creates a specialised opportunity for film suppliers to work directly with food manufacturers, tray producers and packaging engineers rather than supplying film as an isolated component. For Australia's PE film market, the trend is therefore toward engineered sealing interfaces, controlled peel performance and pack-specific recyclability considerations, supporting higher-value technical film development.
The Expert Market Research’s report titled "Australia PE Films Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
Key Insight: Stretch and shrink films address distinct packaging requirements across Australia’s logistics, warehousing, manufacturing, food, beverage, and retail supply chains. Stretch film is primarily associated with pallet stabilisation and unit-load containment, while shrink film supports bundling, product protection, and presentation. The broader packaging environment provides a substantial demand base: Australia placed 6.84 million tonnes of packaging on the market in 2023-24, with plastic representing an important component of this stream. At the same time, only 20% of plastic packaging was recovered for recycling in the latest reported year. This recovery gap is encouraging converters to develop thinner, higher-performance films and structures that use less virgin polymer while maintaining load integrity. Packaging-line compatibility, puncture resistance, recyclability, and material consumption per packaged unit are therefore becoming increasingly important purchasing considerations.
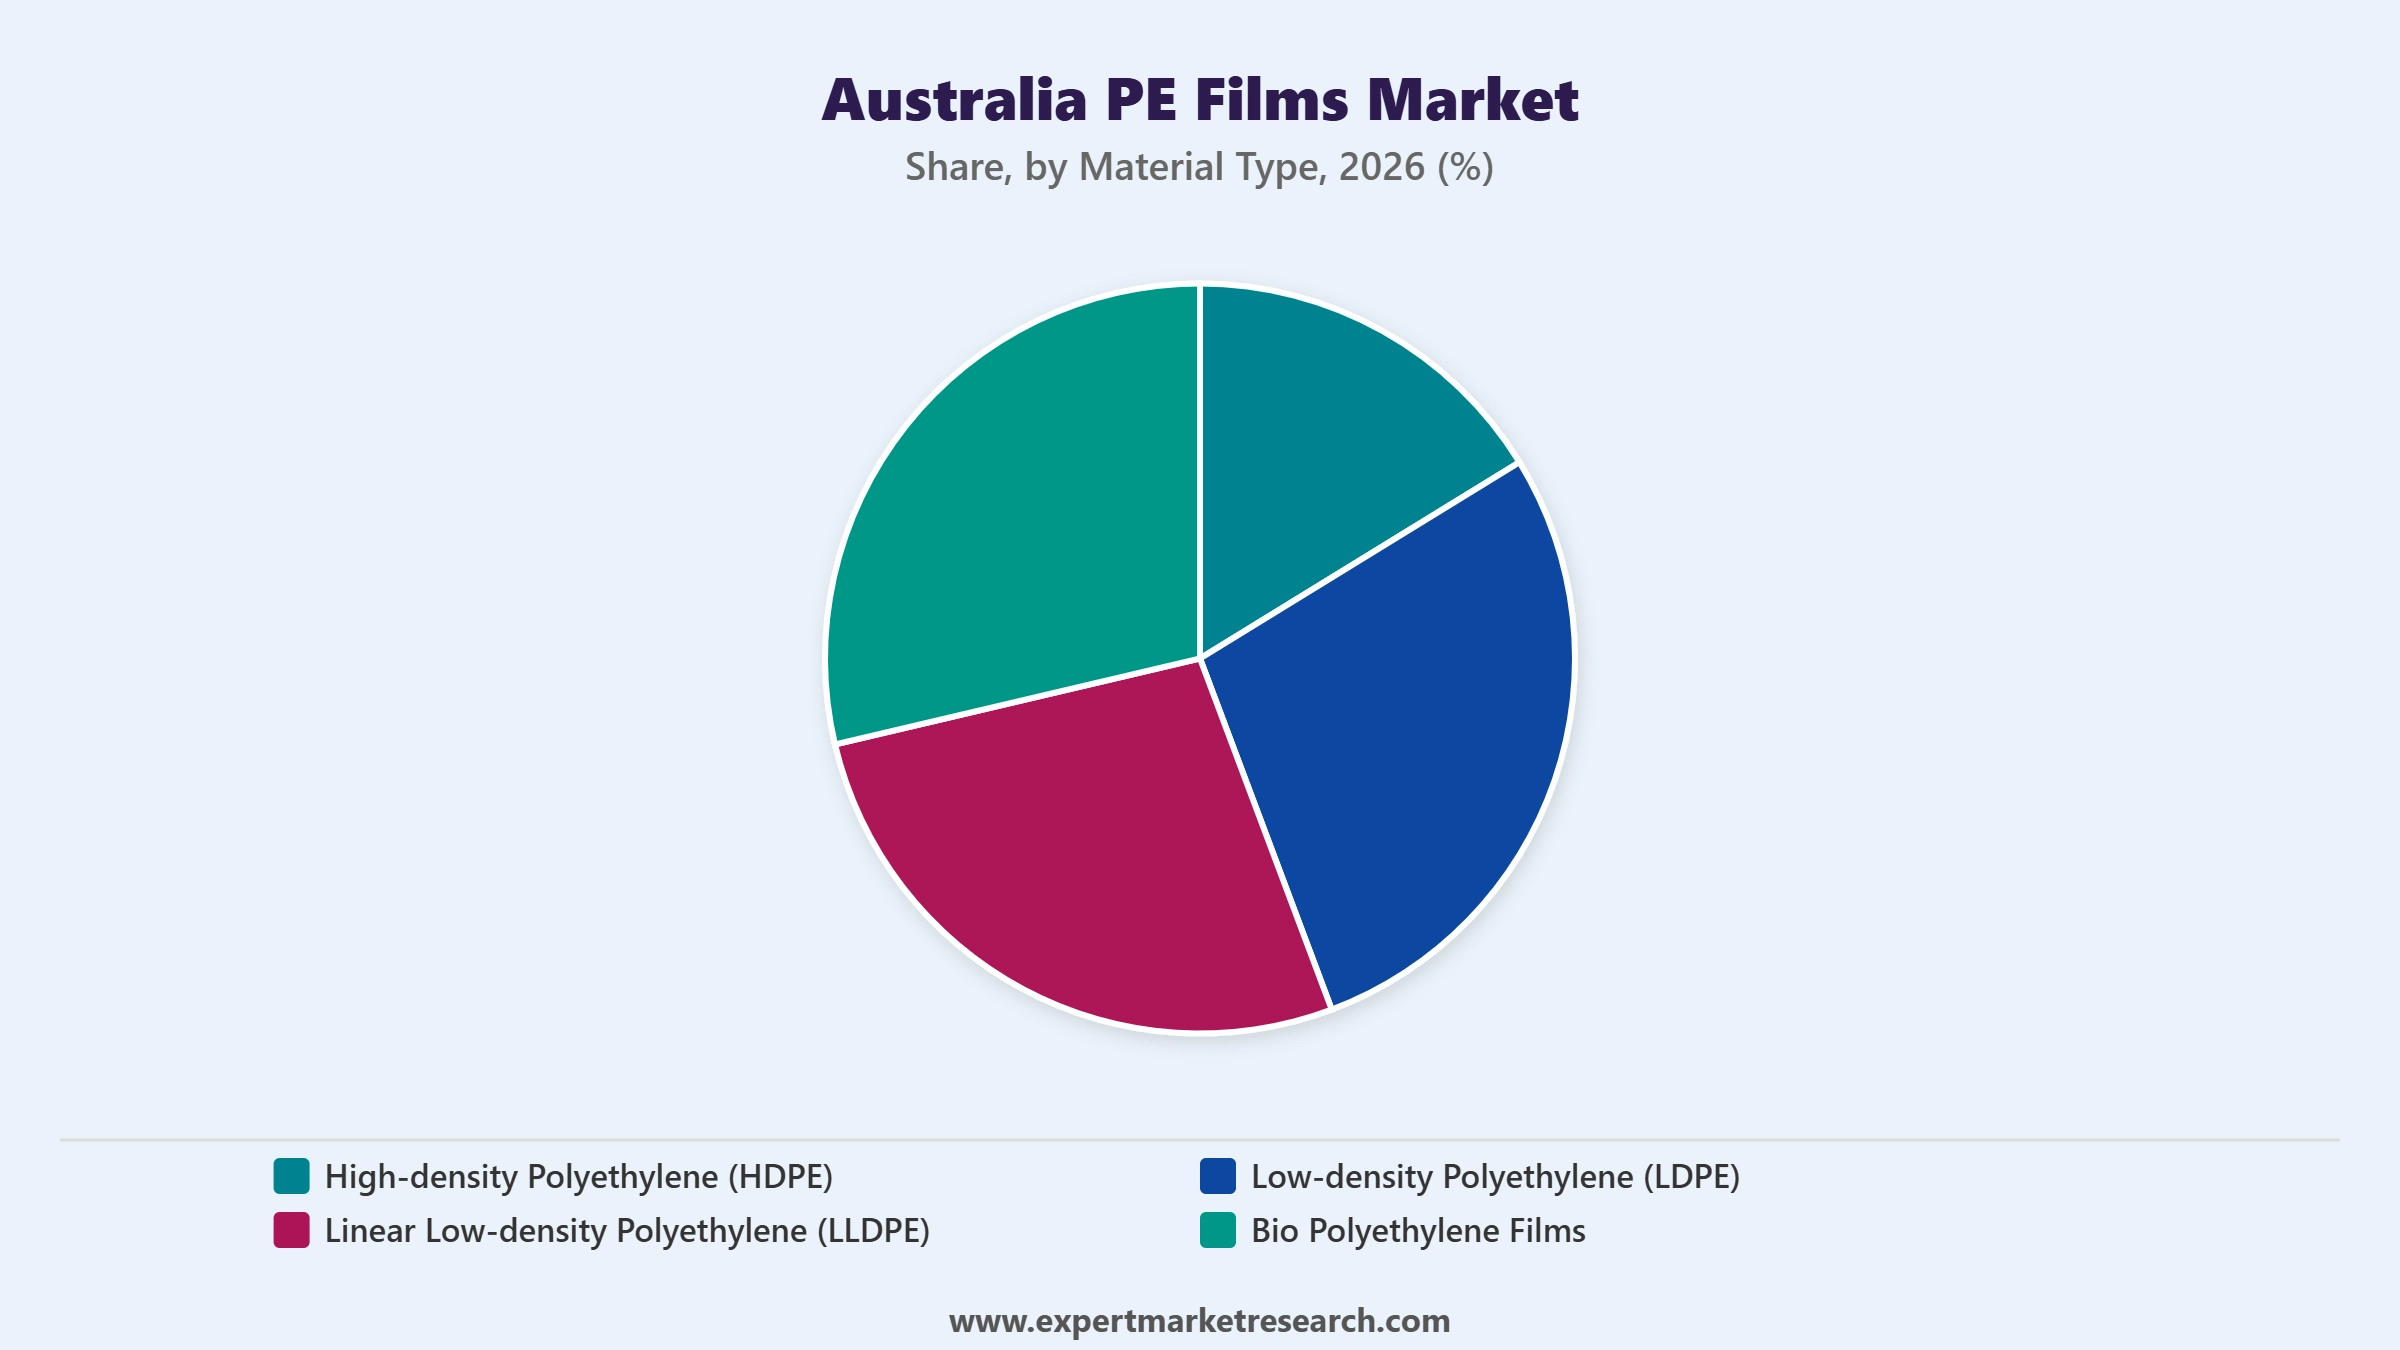
Market Breakup by Material Type
Key Insight: HDPE, LDPE, and LLDPE provide different combinations of flexibility, stiffness, tensile strength, puncture resistance, and processing performance, making resin selection highly application-specific in Australia's PE film industry. Government data shows that Australia consumed approximately 4.0 million tonnes of plastics in 2023-24, with HDPE accounting for 17% and LDPE for 9% of total plastics consumption. A significant structural change has also occurred in domestic resin supply: production of virgin HDPE and LDPE in Australia ceased from October 2024, increasing reliance on imported resin for downstream film manufacturing. This situation places greater emphasis on resin procurement, formulation optimisation, recycled-content availability, and consistent film quality. LLDPE remains particularly relevant for applications requiring toughness and stretch performance, including load-containment films. Bio-based polyethylene films are gaining traction in Australia as packaging converters adopt renewable feedstocks such as sugarcane-derived PE, offering conventional PE-like performance while supporting lower-carbon packaging objectives. Australian suppliers are already incorporating bio-based PE into flexible packaging applications, reflecting growing demand for renewable alternatives.
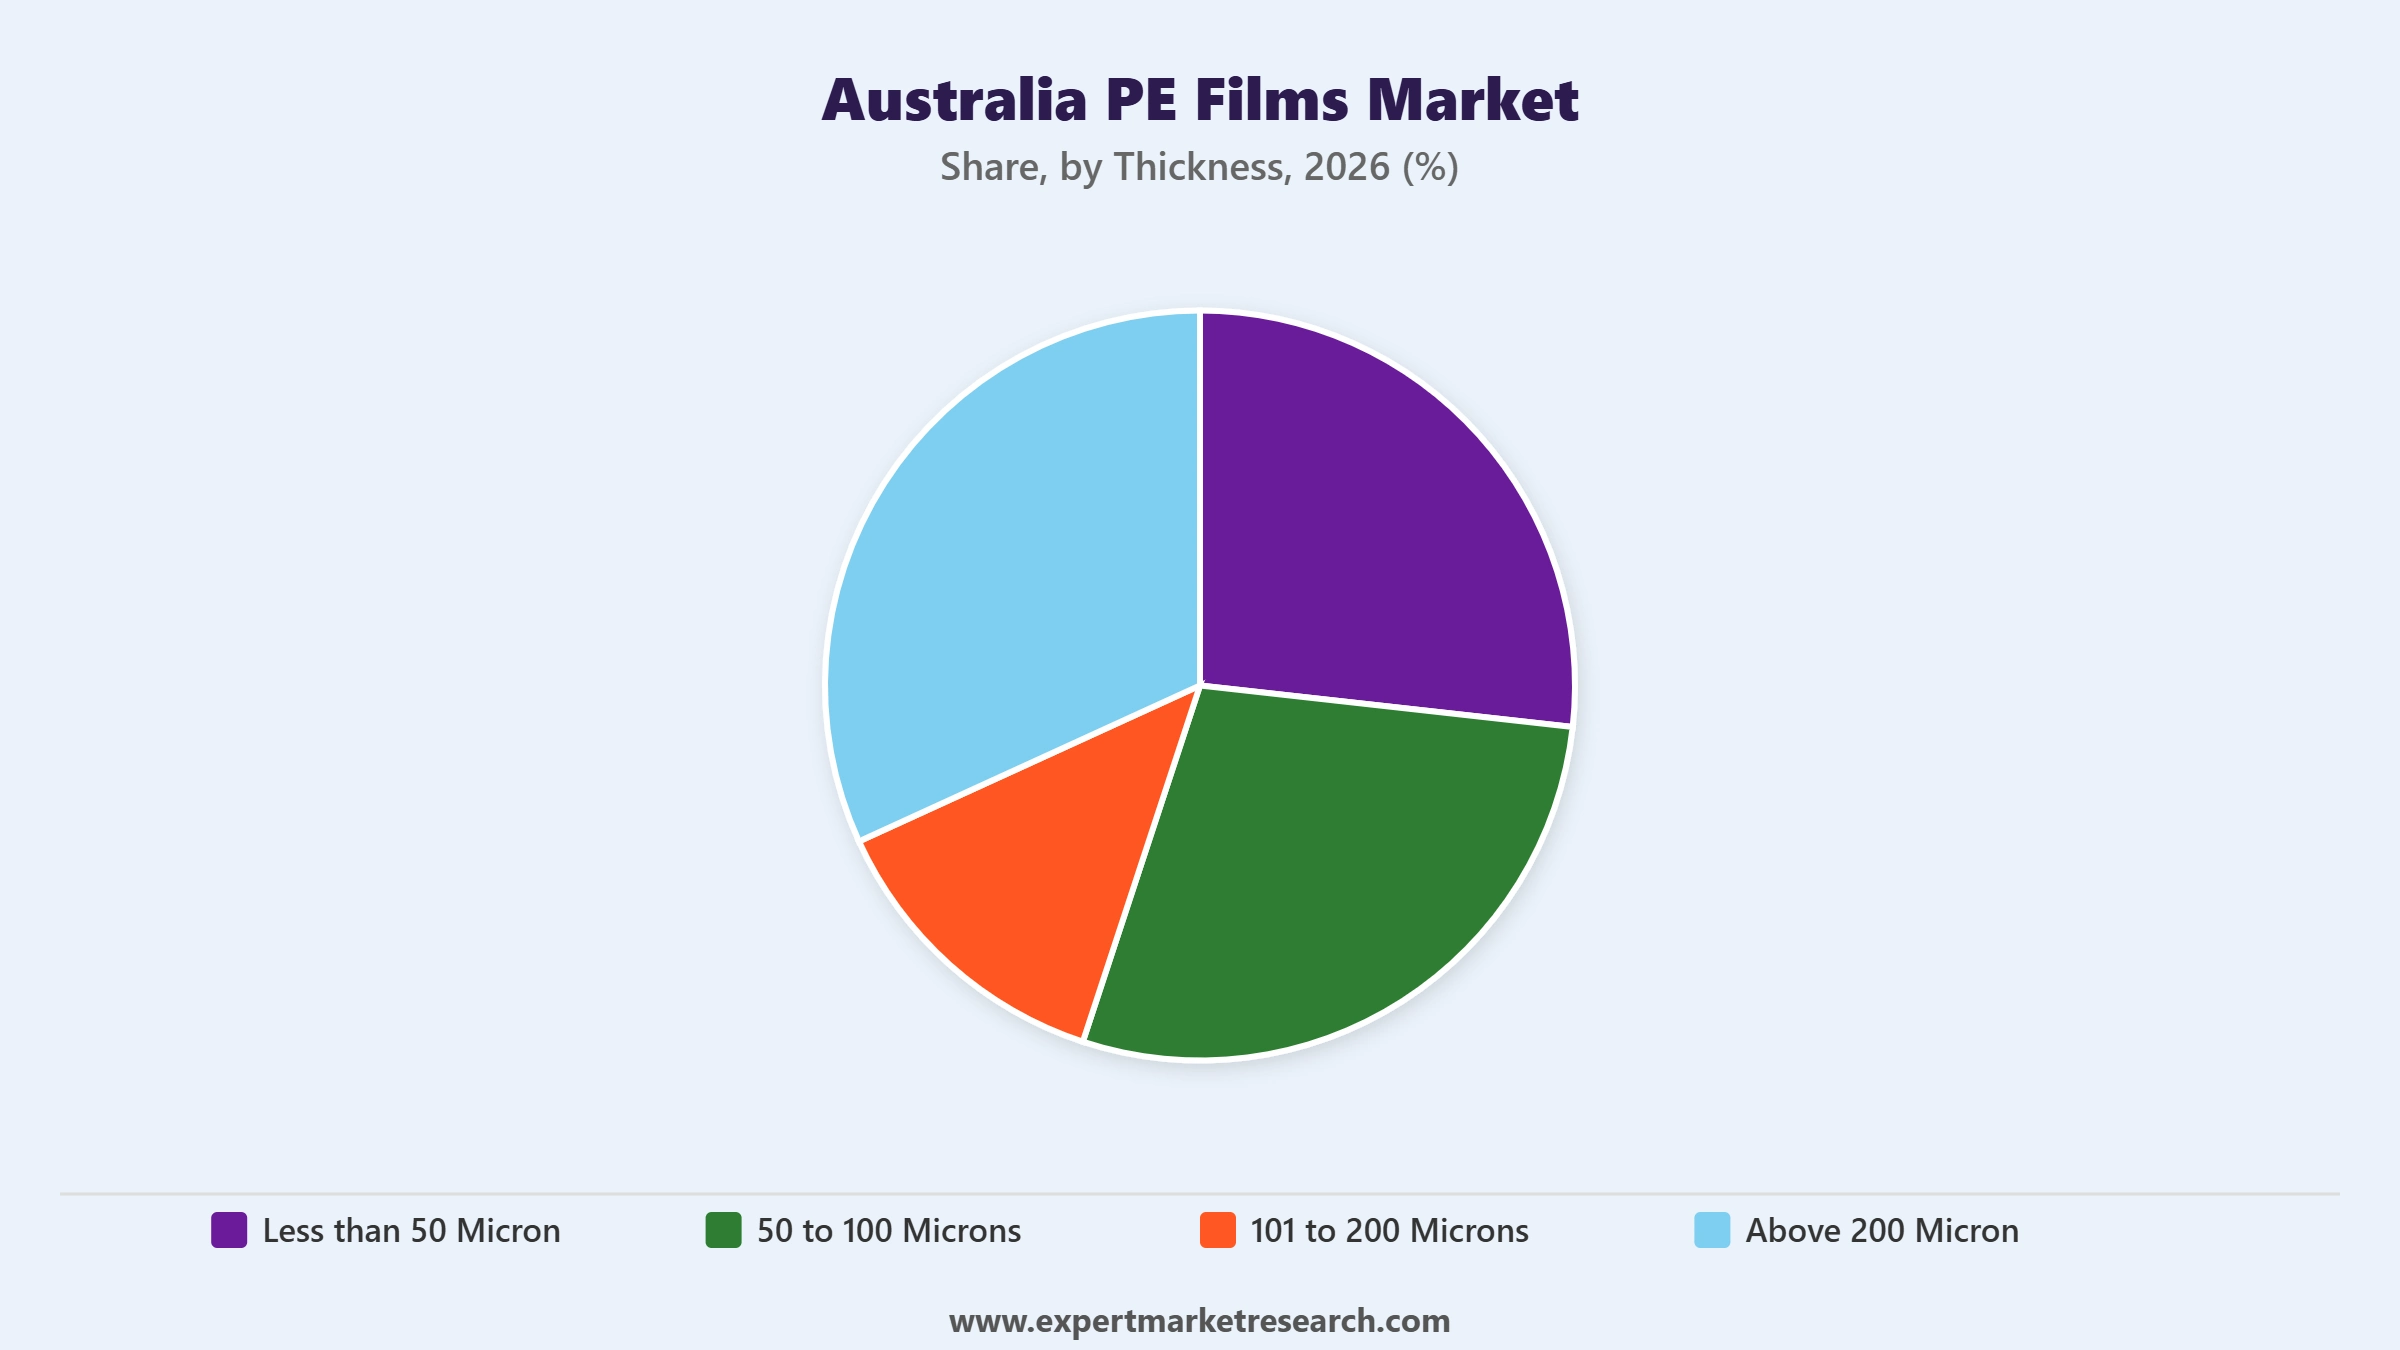
Market Breakup by Thickness
Key Insight: PE film thickness is increasingly influenced by Australia's push toward material efficiency, waste reduction, and packaging circularity. Thinner films can reduce polymer consumption per packaged unit when adequate tensile strength, puncture resistance, sealing performance, and load stability are maintained. Australia's plastics consumption reached approximately 4.0 million tonnes in 2023-24, while only 14% of plastics were recovered through recycling or energy recovery. During the same year, around 300 kilotonnes of recovered plastics were reprocessed domestically, highlighting the importance of designing products that can participate effectively in recovery systems. These conditions create opportunities for downgauged PE films, particularly in high-volume applications such as pallet wrapping, bags, liners, and flexible packaging. However, converters must balance lower thickness against equipment settings, resin quality, handling conditions, and customer performance specifications.
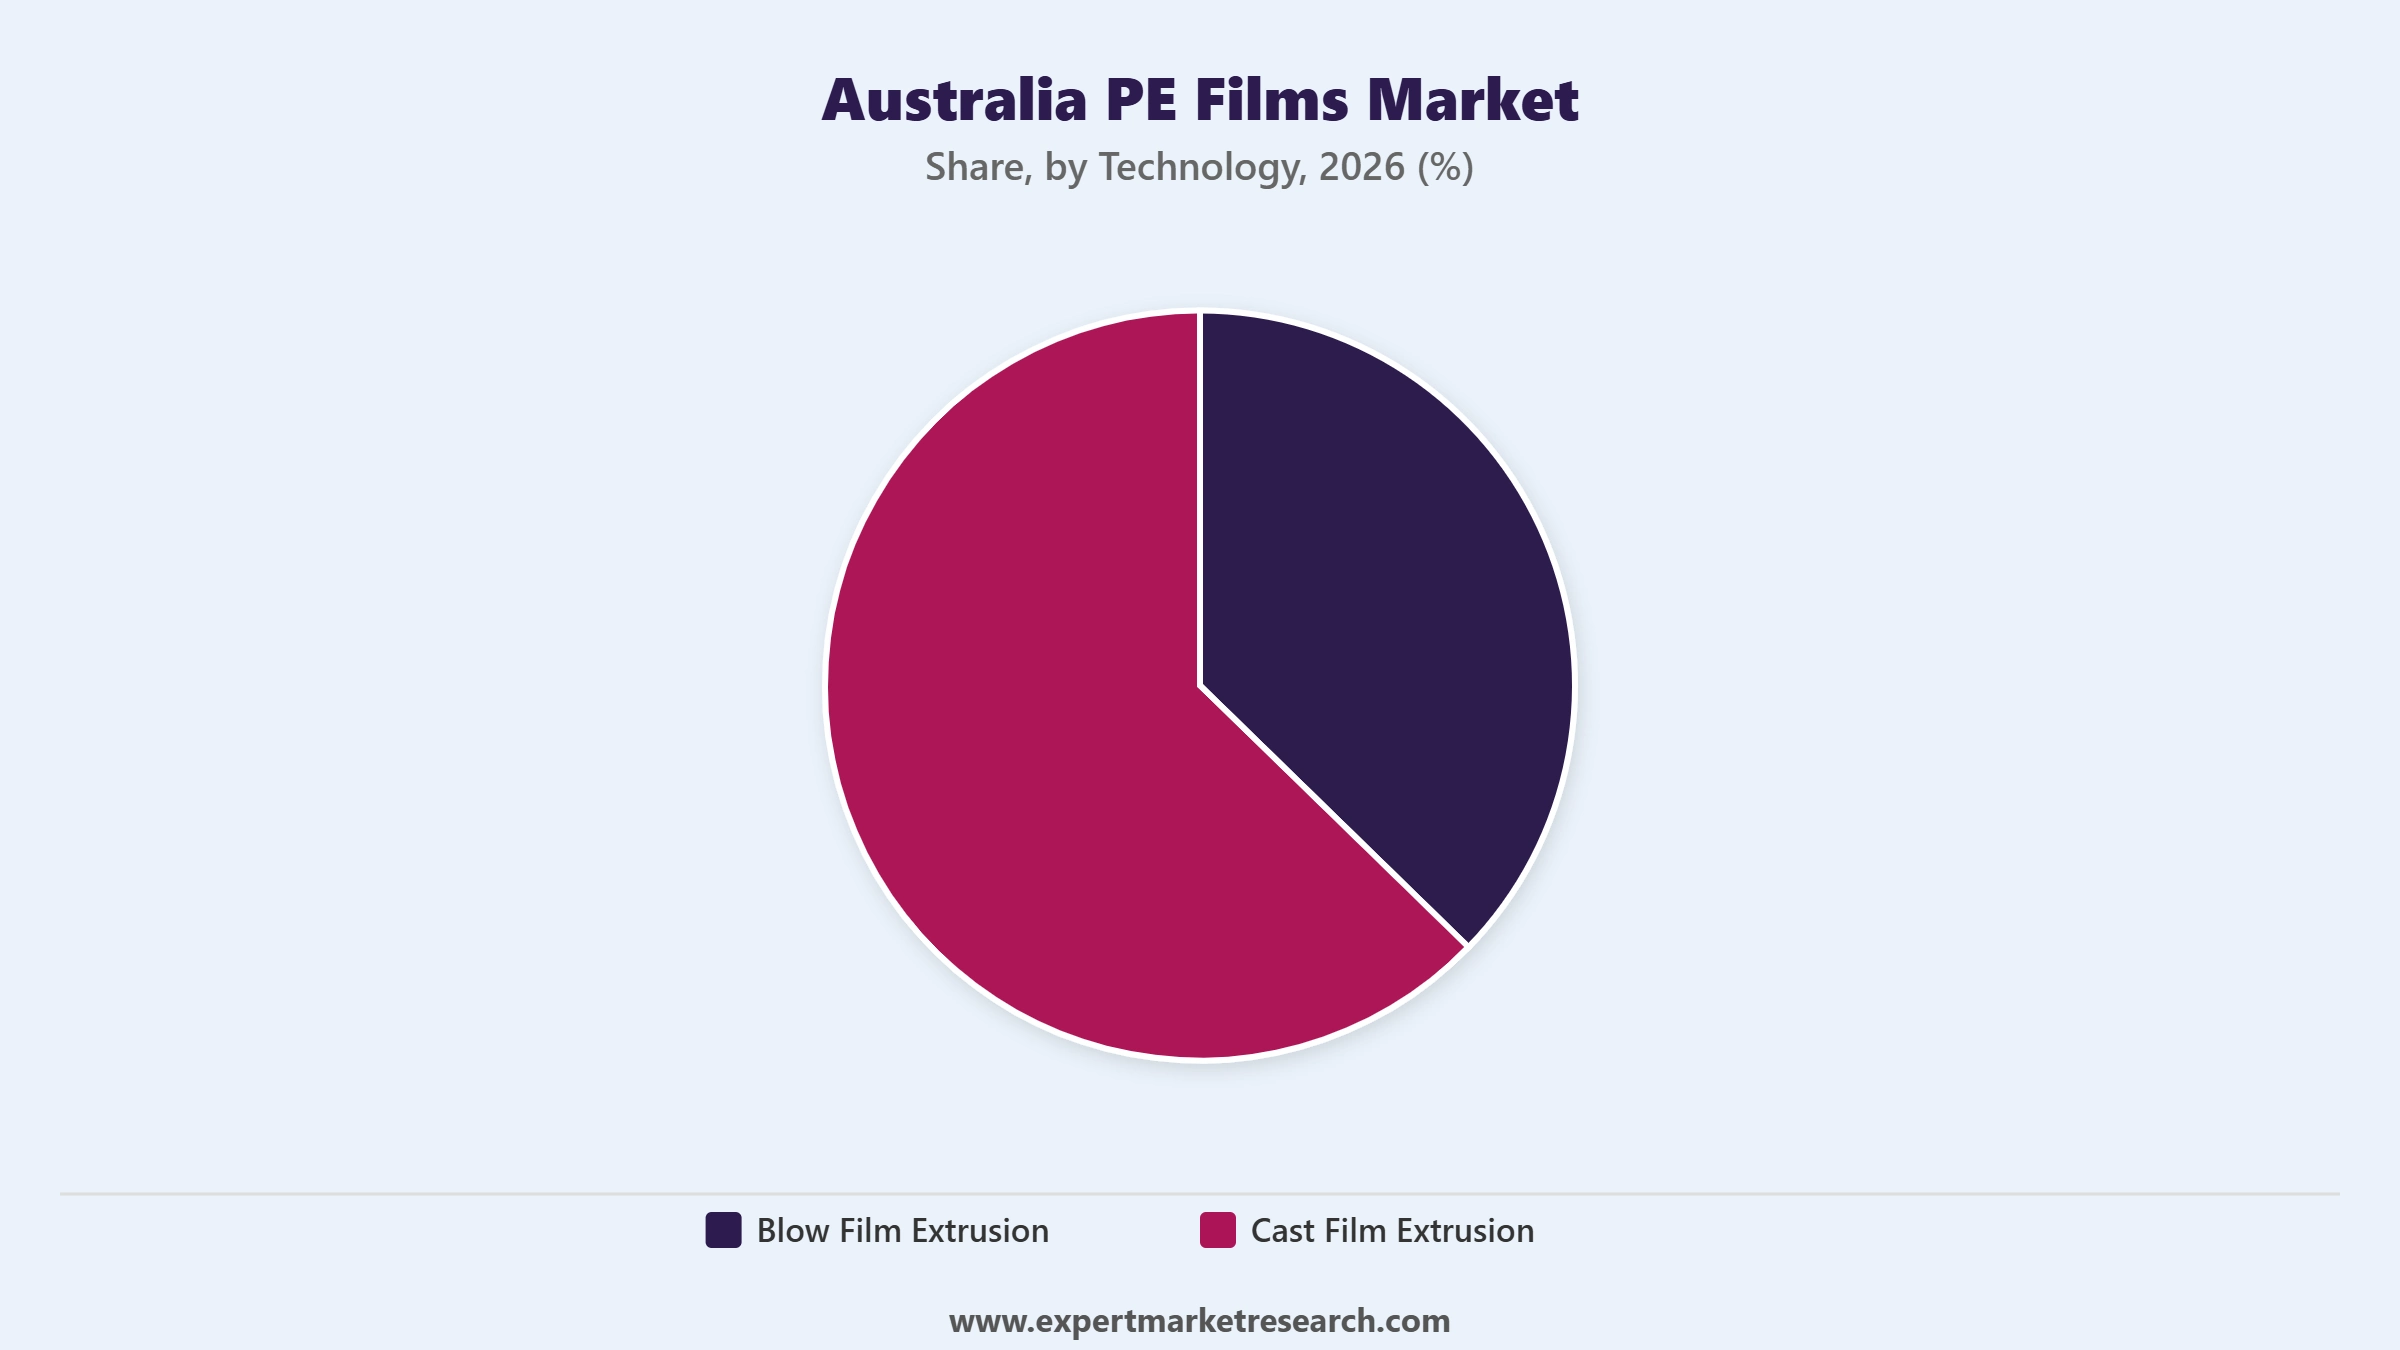
Market Breakup by Technology
Key Insight: Blown-film and cast-film extrusion address different production requirements in Australia's PE film manufacturing industry. Blown-film extrusion supports products such as bags, liners, agricultural films, industrial sheeting, and packaging structures, while cast-film processes can provide controlled gauge and surface characteristics for selected applications. Australia's dependence on imported plastics adds importance to efficient domestic conversion. In 2023-24, 62% of plastics consumed in Australia originated from imported finished or semi-finished products, while 31% came from local manufacturing using virgin resin and 7% from local manufacturing using recycled plastics. This structure creates opportunities for domestic converters to differentiate through specialised film production, efficient extrusion, multilayer structures, and customised specifications. Investment decisions increasingly depend on resin flexibility, output efficiency, gauge control, energy consumption, automation, and the ability to produce films suited to changing packaging requirements.
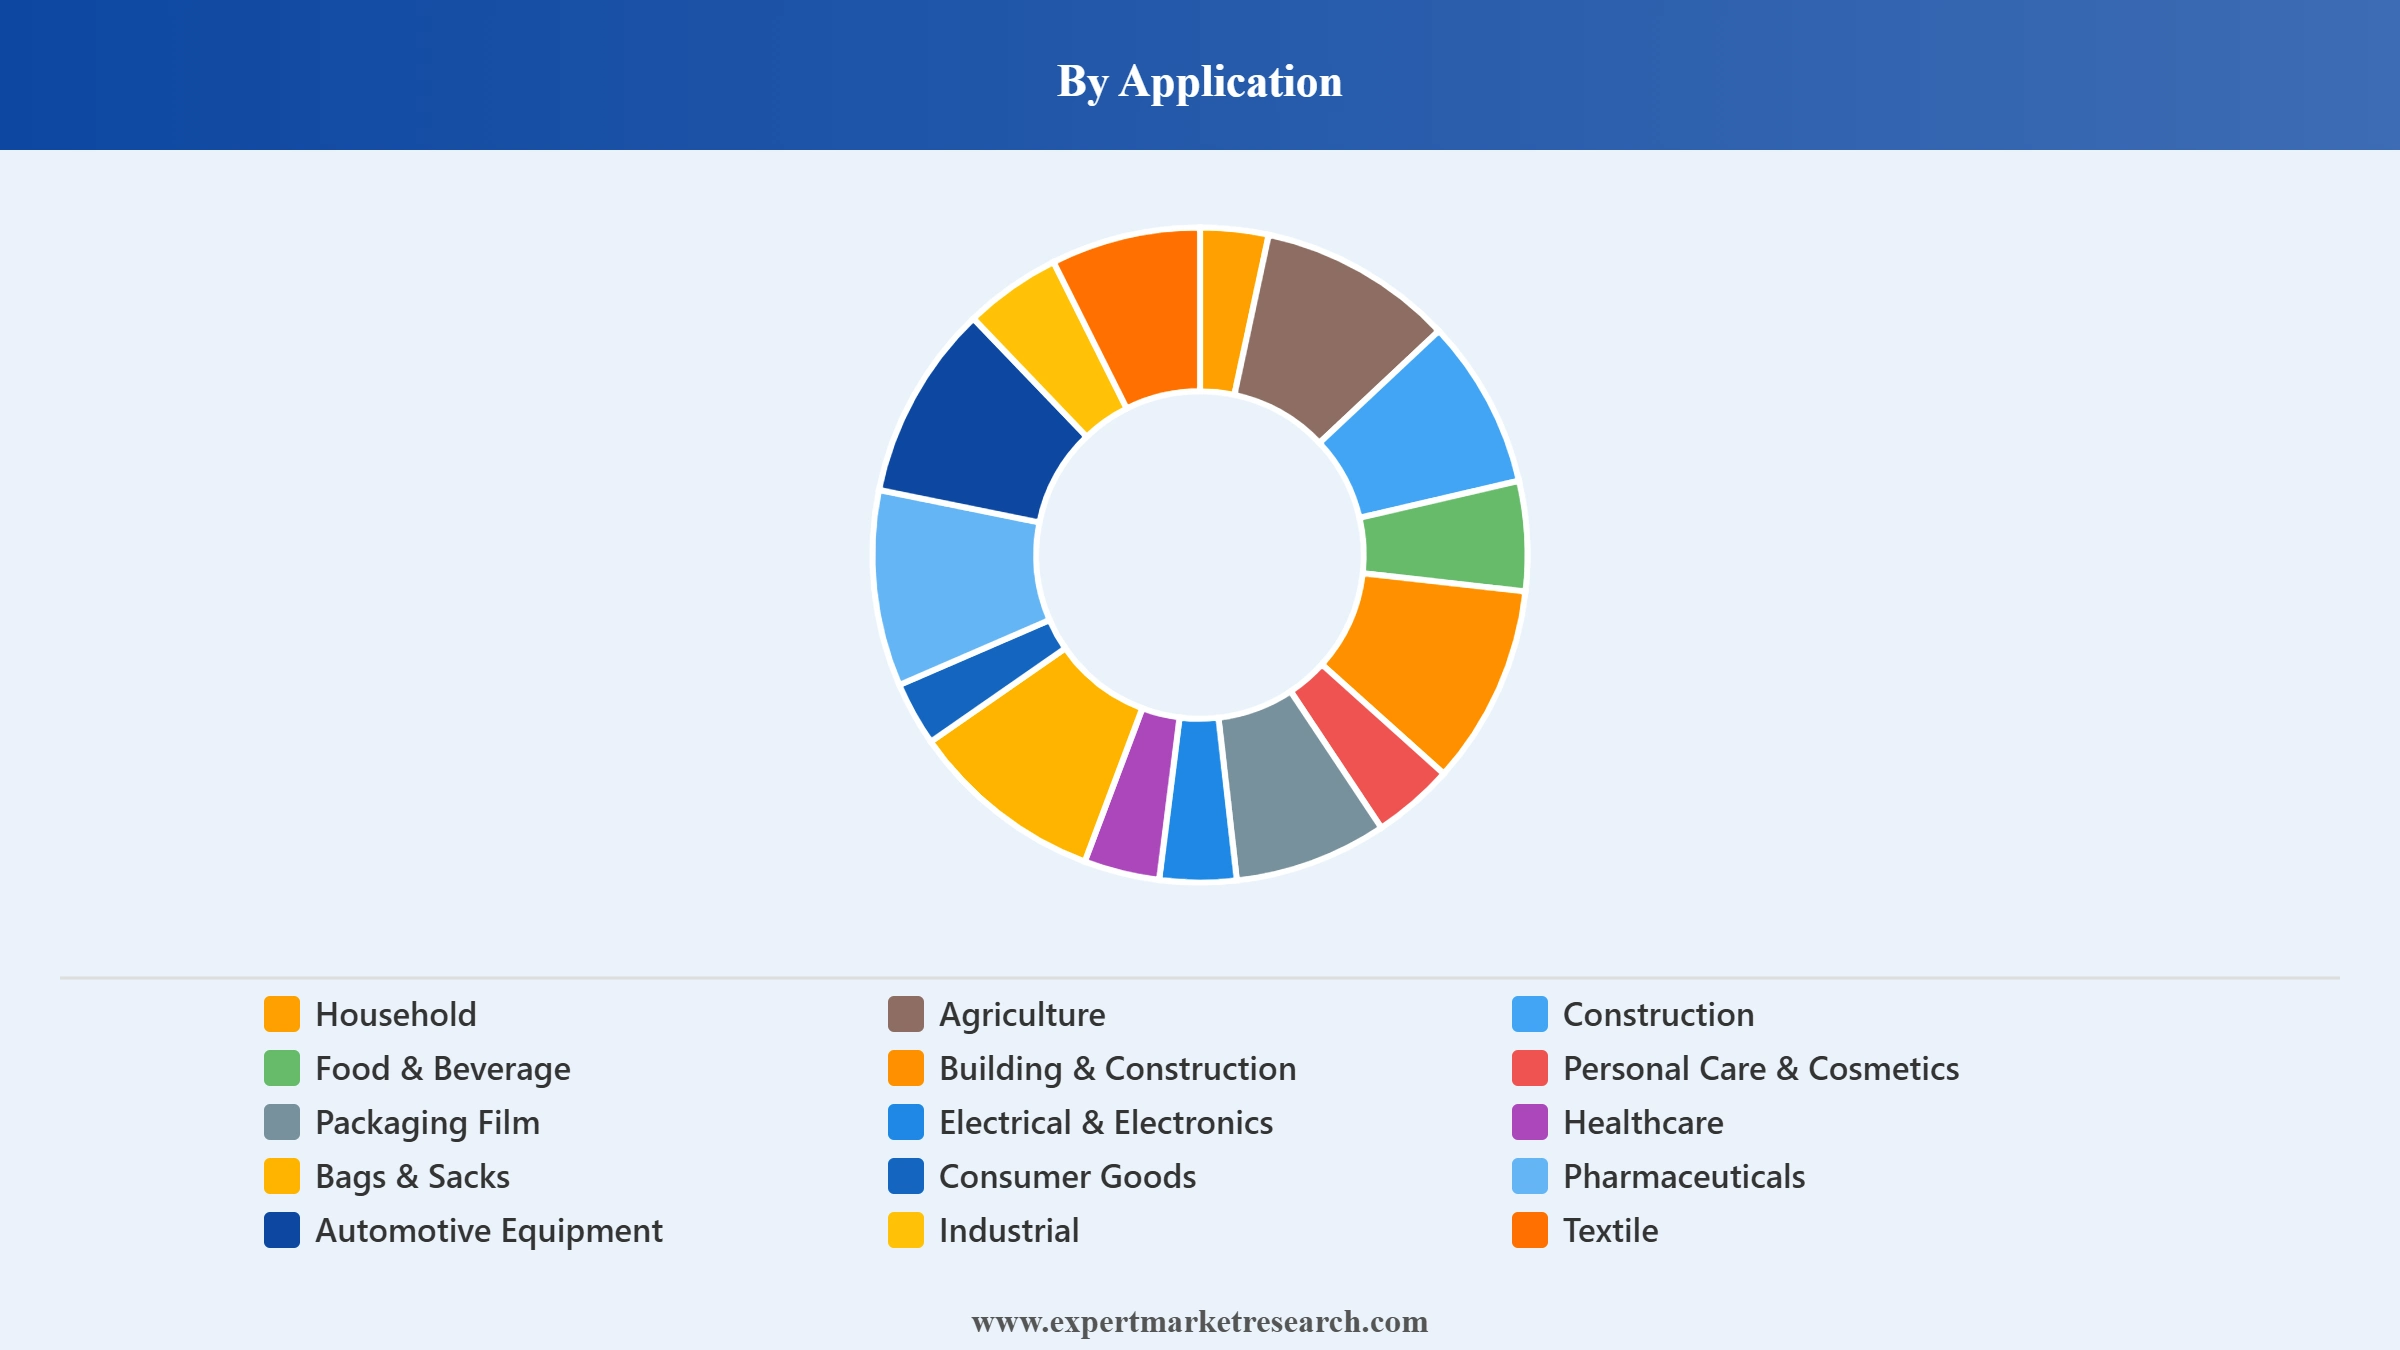
Market Breakup by Application
Key Insight: Packaging represents a particularly important application environment for PE films in Australia because of the substantial volume of packaging moving through the national economy. The Australian Government estimates that approximately 1.2 million tonnes of plastic packaging reached end-of-life in 2023-24, representing 39% of total plastic end-of-life generation. However, only 20% of plastic packaging was recovered, leaving a significant volume for disposal or other treatment routes. This is increasing attention on recyclable film structures, downgauging, recycled content, and improved end-of-life compatibility. Food and beverage packaging remains relevant because PE films provide sealing, wrapping, lining, and moisture-protection functions, while industrial and agricultural users require stronger films for covering, storage, silage, greenhouse, and handling applications. Application requirements therefore increasingly determine resin selection, film thickness, barrier properties, and conversion technology.
Market Breakup by Region
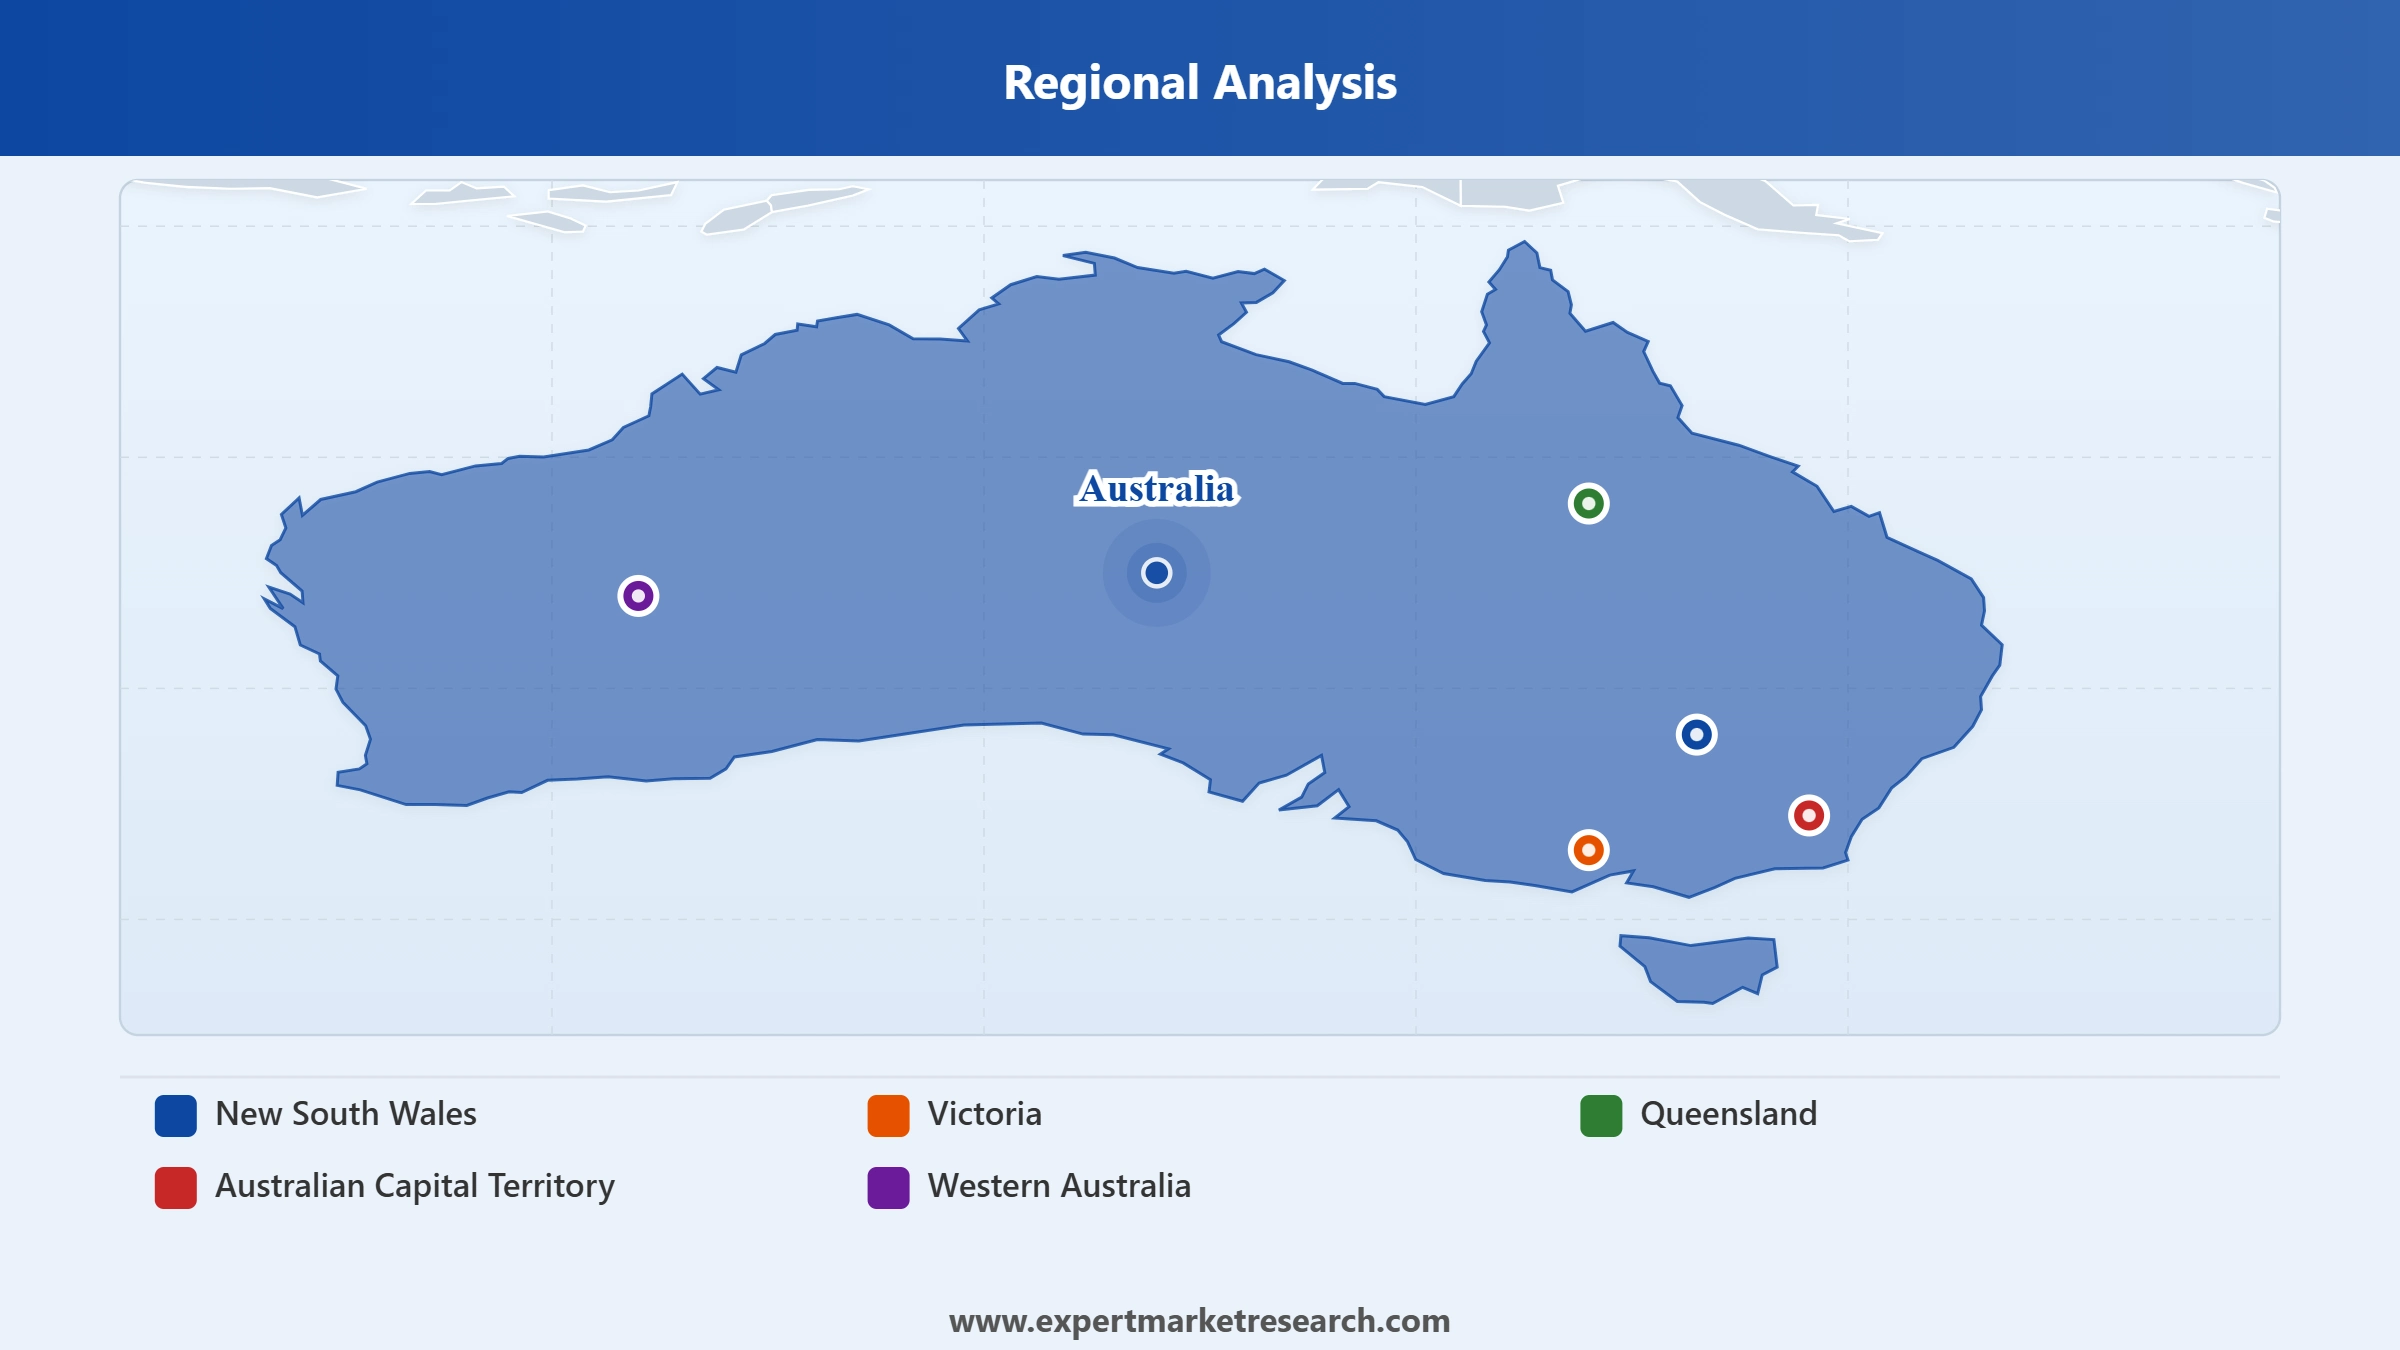
Key Insight: New South Wales and Victoria represent important regional markets for PE films because of their large manufacturing, food-processing, logistics, retail, and packaging ecosystems. Australia's official plastics-flow database provides jurisdiction-level data, although it does not publish a PE-film-specific market share by state. In 2023-24, Australia consumed 4.0 million tonnes of plastics, with 62% originating from imported finished or semi-finished goods, highlighting the importance of downstream conversion and distribution networks. Victoria's GSP increased 1.1% in 2024-25, while New South Wales recorded 0.9% growth. Queensland expanded by 2.2%, supported by continued industrial and population activity. Western Australia, meanwhile, recorded 1.3% GSP growth, providing a sizeable industrial base for packaging and materials demand, thus driving the demand in the Australia PE films market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
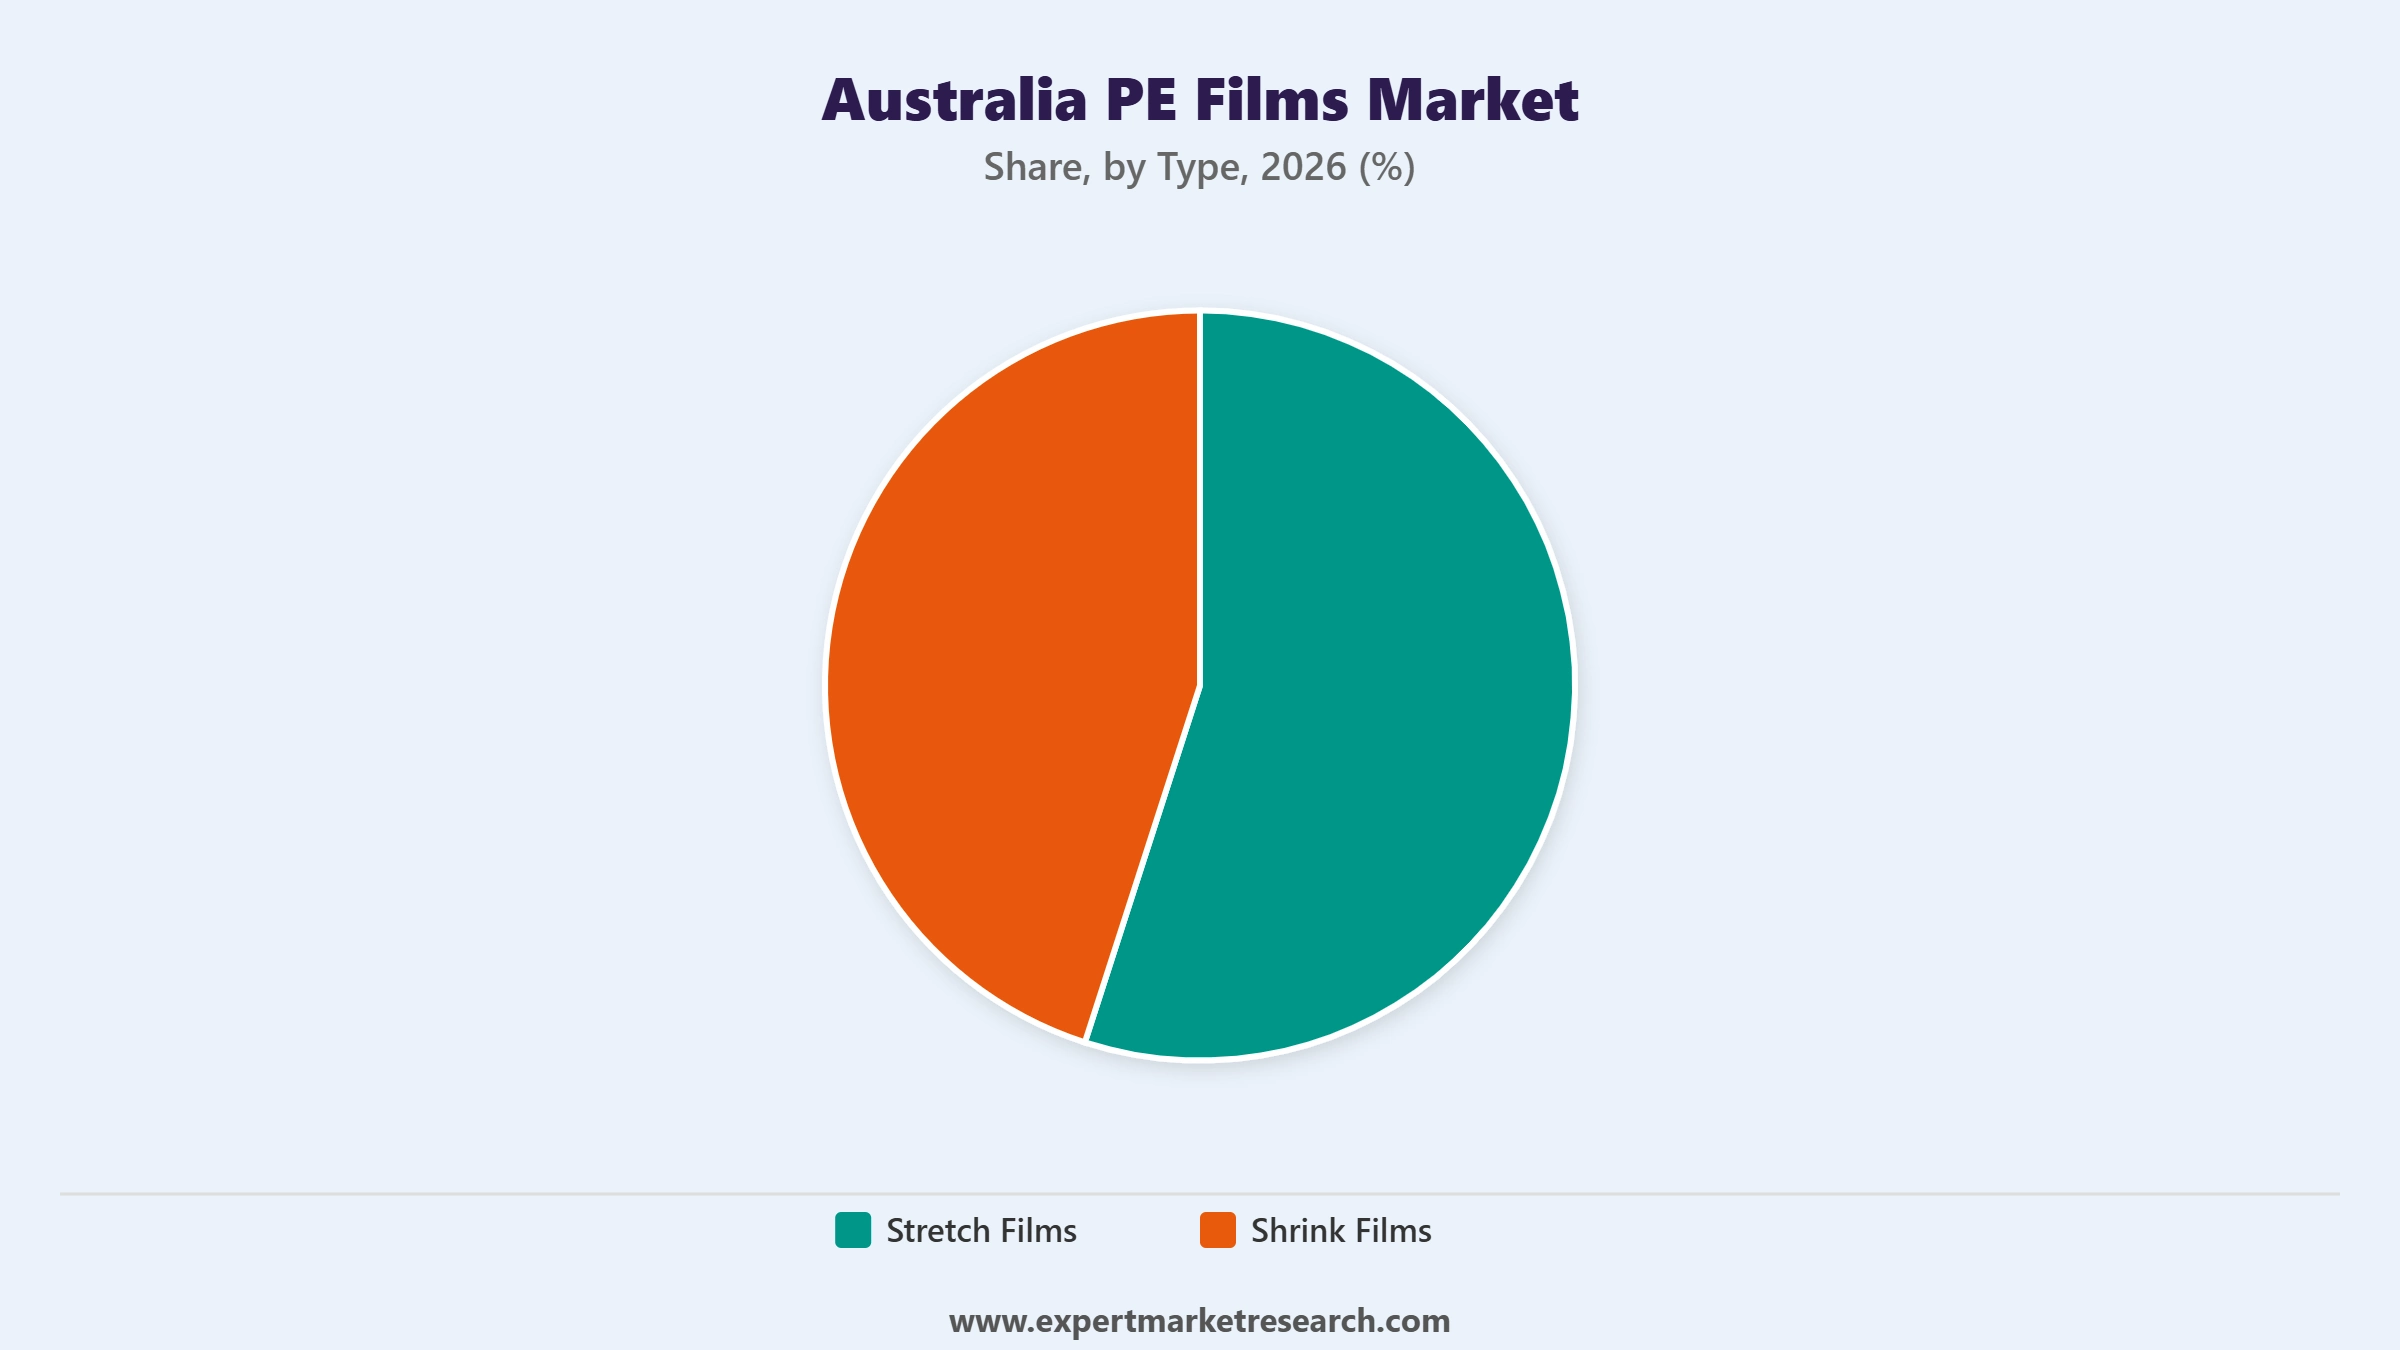
Stretch films are positioned as the dominant type, particularly in industrial load containment where machine and hand wrapping require different performance specifications. Dolphin Plastics & Packaging supplies both hand and machine stretch wrap, including industrial-scale formats, pallet covers and pallet bags, demonstrating the breadth of Australian end uses. Its machine-wrap range is specifically designed for high-volume operations, where film consistency and wrapping efficiency affect packaging costs. This creates demand for PE films engineered around pre-stretch ratios, puncture resistance and controlled cling rather than simply higher film thickness. Such developments will thus boost Australia PE films market trends in the long run.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Shrink films have stronger niche growth potential in applications where continuous tubing can replace individually sized bags. Dolphin Plastics & Packaging manufactures shrink-wrap tubing in customised widths, while its poly tubing ranges from 100 mm to 1,500 mm and 25-250 microns, allowing manufacturers to match film dimensions closely to product geometry. This is particularly relevant for irregularly sized industrial components and consumer goods requiring heat-shrinkable protection. Such customisation can reduce packaging preparation compared with pre-sized formats and supports adoption among manufacturers seeking application-specific film rather than standard stock products.
LDPE is positioned as the dominant material because Australian converters continue to use it across highly varied flexible-film structures rather than a single end use. Richdale Plastics manufactures bags, liners and rewind films using LDPE, while Polyem produces custom mono- and co-extruded films incorporating LDPE alongside LLDPE, mLLDPE and HDPE. Richdale has also developed recyclable LDPE-based barrier structures to replace combinations involving nylon, PET and other less readily recyclable materials. This creates a specialised opportunity for LDPE formulations that combine flexibility with recycling compatibility and adequate product protection.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
LLDPE has strong growth potential in performance-oriented films where toughness enables material reduction without sacrificing mechanical integrity. Polyem specifically uses LLDPE and mLLDPE in customised blown-film formulations, including engineered films incorporating multiple resin components. The opportunity is particularly relevant for load-containment and industrial applications where puncture resistance and stretch characteristics influence the amount of film required per unit. Rather than competing solely on resin price, Australian converters can use LLDPE-rich formulations to engineer films around customer-specific load weights, wrapping conditions and downgauging objectives, creating a technically driven growth niche.
The 50-100 micron range is emphasized as the main thickness range because it enables packaging with more strength than lightweight packaging and still enables efficient conversion. Dolphin Plastics & Packaging produces PE bags that range between 25 and 250 microns, highlighting the varying thicknesses dealt with by converters in Australia. The mid-gauge range is especially significant for pallet liners, industrial bags, protective films, and customized packaging that requires puncture resistance and strength during handling. Thickness is thus determined by actual conditions and not by standardized dimensions of packaging, thereby shaping the demand in the Australia PE films market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Sub-50-micron films have an opportunity to expand in applications where converters can replace thicker structures through improved resin blends and multilayer engineering. Dolphin's capability to manufacture bags beginning at 25 microns demonstrates that very thin PE formats are already technically feasible in Australia. Polyem similarly produces engineered films using combinations of LDPE, LLDPE, mLLDPE and HDPE, allowing film properties to be adjusted without relying solely on thickness. This creates a niche for high-strength lightweight films in bags, liners and wrapping applications where material savings can be achieved without compromising handling performance.
Blown-film extrusion remains the dominant technology because it supports a particularly wide range of Australian PE film formats, from tubes and bags to industrial and agricultural films. Dolphin Plastics & Packaging manufactures poly tubing through continuous blown-film extrusion, with customised widths extending to 1,800 mm. Polyem likewise operates custom blown-film production using multiple PE blends. This technology's ability to produce tubular structures directly is particularly valuable for bag and liner conversion, reducing the need for certain downstream forming operations. Its flexibility across widths, gauges and resin blends supports diverse customer specifications.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Cast-film extrusion has growth potential in specialised applications requiring highly controlled film characteristics, although Australian public sources provide limited evidence for a national cast-film growth rate. The opportunity is particularly relevant where flat-film geometry, gauge uniformity and surface characteristics are critical to downstream converting. Growth can therefore come from specialised food, industrial and technical packaging rather than commodity sheeting. This segment can benefit as converters move toward engineered structures requiring tighter process control and repeatability.
Packaging film is positioned as the dominant application because Australian converters are increasingly developing technically differentiated PE structures for specific food and consumer-product requirements. Richdale Plastics supplies flow wraps, lidding, top and bottom webs, vacuum webs and recyclable co-extruded structures, while its fresh-produce portfolio includes MAP films, macro-perforated formats and berry and grape bags. These applications require more than basic containment, films must manage shelf life, ventilation, sealing and presentation. Such specialised requirements favour suppliers capable of integrating extrusion, printing and conversion rather than competing purely on commodity film pricing.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Agricultural films offer a specialised growth avenue because Australian converters are expanding beyond conventional packaging into films designed for crop and livestock-related applications. Gelpack's portfolio includes strawberry mulch covers, silage wrap, grape covers, greenhouse film, cloche film and silver/black mulch covers, demonstrating the breadth of agricultural PE-film requirements. These products face different performance conditions from packaging films, including UV exposure, moisture management and outdoor durability. Dolphin also supplies agricultural packaging and planter bags, while Gelpack reports recent traction in agricultural films, indicating increasing diversification into application-specific farm plastics.
Victoria and New South Wales represent important markets for PE films because of their established manufacturing, packaging, food-processing, and distribution ecosystems. Victoria is an important PE films market, supported by its manufacturing, packaging, food-processing, and distribution base. In March 2025, the state recorded 261,900 manufacturing jobs, while manufacturing accounted for 109.5 million hours worked during the quarter. In 2024-25, Victoria's sales and service income increased by A$40.8 billion, or 3.4%, demonstrating continued industrial activity. Local film converters, including Polyem in Dandenong, further support PE film production and conversion capabilities. Furthermore, Victoria has a visible base of local film converters, including Polyem in Dandenong and Richdale Plastics in Mentone. These manufacturers demonstrate the presence of technical film production and conversion capabilities in the state. Victoria's position is also supported by its role in supplying packaging to industrial and consumer-facing customers, thereby directly boosting the Australia PE films market regional growth.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
New South Wales benefits from its large commercial and distribution ecosystem, while Queensland offers demand opportunities linked to agriculture, food production, and industrial packaging. Meridian Plastics' Brisbane manufacturing facility illustrates the presence of local PE film conversion capabilities in Queensland. Western Australia also provides opportunities associated with industrial, resource-sector, and agricultural packaging requirements, although freight distances and supply-chain economics influence procurement. The Australian Capital Territory and other regions contribute through smaller industrial, commercial, and distribution requirements. Across regions, growth opportunities will depend on customer proximity, reliable film supply, application-specific specifications, and the economics of local conversion.
Leading Australia PE films market players are aiming to strengthen their competitive position through product innovation, customised film development, and expansion into high-value packaging applications. Manufacturers such as Polyem Pty Ltd., Dolphin Plastics & Packaging, Meridian Plastics Pty Ltd., and Gundle Gelpack Pty Ltd. can pursue growth by developing lightweight, durable, and recyclable polyethylene films that meet evolving customer requirements. Investment in advanced extrusion, co-extrusion, printing, and conversion capabilities can help improve product consistency, reduce material wastage, and support specialised industrial, agricultural, and food packaging needs.
Australia PE films companies are also seeking to deepen relationships with packaging converters, distributors, and end users through reliable supply, shorter lead times, and application-specific solutions. Expanding service coverage across food processing, agriculture, construction, logistics, and manufacturing can diversify revenue streams and reduce dependence on individual end-use sectors. In addition, strengthening domestic manufacturing efficiency and managing resin-price volatility remain important for protecting margins and maintaining competitiveness against imported films. Collectively, these strategies enable market participants to address changing customer specifications, improve operational resilience, and capture opportunities arising from demand for flexible, cost-effective, and resource-efficient packaging solutions across Australia.
Established in 1977, Polyem Pty Ltd. is an Australian-owned manufacturer of custom polyethylene films and flexible packaging solutions. The company operates from Dandenong, Victoria, with its manufacturing facility at 6-12 Airlie Avenue. Its product portfolio includes custom-blown LDPE, LLDPE, mLLDPE, and HDPE films, mono-extruded and co-extruded films, and engineered technical films. Polyem serves industrial and retail customers, offering tailored film formulations and recyclable packaging solutions for diverse Australian applications.
Dolphin Plastics & Packaging is a Queensland-based, family-owned manufacturer of polyethylene films and flexible packaging products, with over 20 years of industry presence reported on its website. Its headquarters and manufacturing facility are located at Kunda Park, Sunshine Coast, Queensland. The company offers custom poly tubes, plastic sheeting, centrefold films, shrink films, agricultural films, pallet covers, stretch wraps, and poly bags. It serves Australian customers across food, healthcare, construction, mining, and industrial packaging applications.
Established in 2012 following the reorganisation of Hemplas, Meridian Plastics Pty Ltd. is an Australian-owned flexible packaging manufacturer. Its headquarters and production facility are located at 11 Pease Court, Bethania, Queensland, in the Greater Brisbane area. The company specialises in custom polyethylene films, poly tubes, bags, and food-grade plastic packaging. Its capabilities include in-house extrusion, printing, and bag conversion, enabling customised packaging for food, beverage, seafood, mining, landscaping, and other industrial applications.
Established in July 2014, Gundle Gelpack Pty Ltd. is a Melbourne-based Australian packaging manufacturer headquartered in Dandenong South, Victoria. The company produces mono-extruded and co-extruded PE films, lamination films, pallet shrink tubing, mattress packaging, industrial wraps, and general-purpose flexible packaging. Its portfolio also includes agricultural films, silage wrap, greenhouse films, and volatile corrosion inhibitor films. Gelpack serves bedding, materials handling, storage, transportation, construction, and agricultural industries across Australia.
Other key players in the Australia PE films market include Polywrap, Shamrock Poly Pty Ltd., and Pro-Pac Packaging Limited among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the Australia PE Films Market trends 2026 and gain insights into material demand, extrusion technologies, competitive strategies, and emerging packaging opportunities. Download a sample report from Expert Market Research to understand the Australia PE Films Market forecast 2026-2035, evaluate industry developments, and identify opportunities for business expansion, product innovation, and strategic investment across Australia's polyethylene films value chain.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 2.10% between 2026 and 2035.
The revenue generated from the market is expected to reach USD 1000.37 Million in 2035.
In 2025, the market reached an approximate value of USD 812.65 Million.
The market is categorised according to the type, which includes stretch films and shrinks films.
Key players in the market are Polyem Pty Ltd., Dolphin Plastics & Packaging, Meridian Plastics Pty Ltd., Gundle Gelpack Pty Ltd., Polywrap, Shamrock Poly Pty Ltd., and Pro-Pac Packaging Limited among others.
Based on the technology, the PE films market is divided into blow film extrusion and cast film extrusion.
The market is broken down into New South Wales, Victoria, Queensland, Australian Capital Territory, Western Australia, and others.
Key challenges in the Australia PE films market include fluctuating polyethylene resin prices, dependence on imported raw materials, stringent plastic waste regulations, recycling infrastructure limitations, environmental concerns over single-use plastics, and competition from alternative sustainable packaging materials, including paper-based and biodegradable films.
Key strategies driving the Australia PE films market include product innovation, lightweight film development, investment in recyclable and downgauged packaging, expansion of domestic production capabilities, strategic partnerships, adoption of advanced extrusion technologies, and development of high-performance films for diverse industrial and agricultural applications.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Material Type |
|
| Breakup by Thickness |
|
| Breakup by Technology |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




