

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
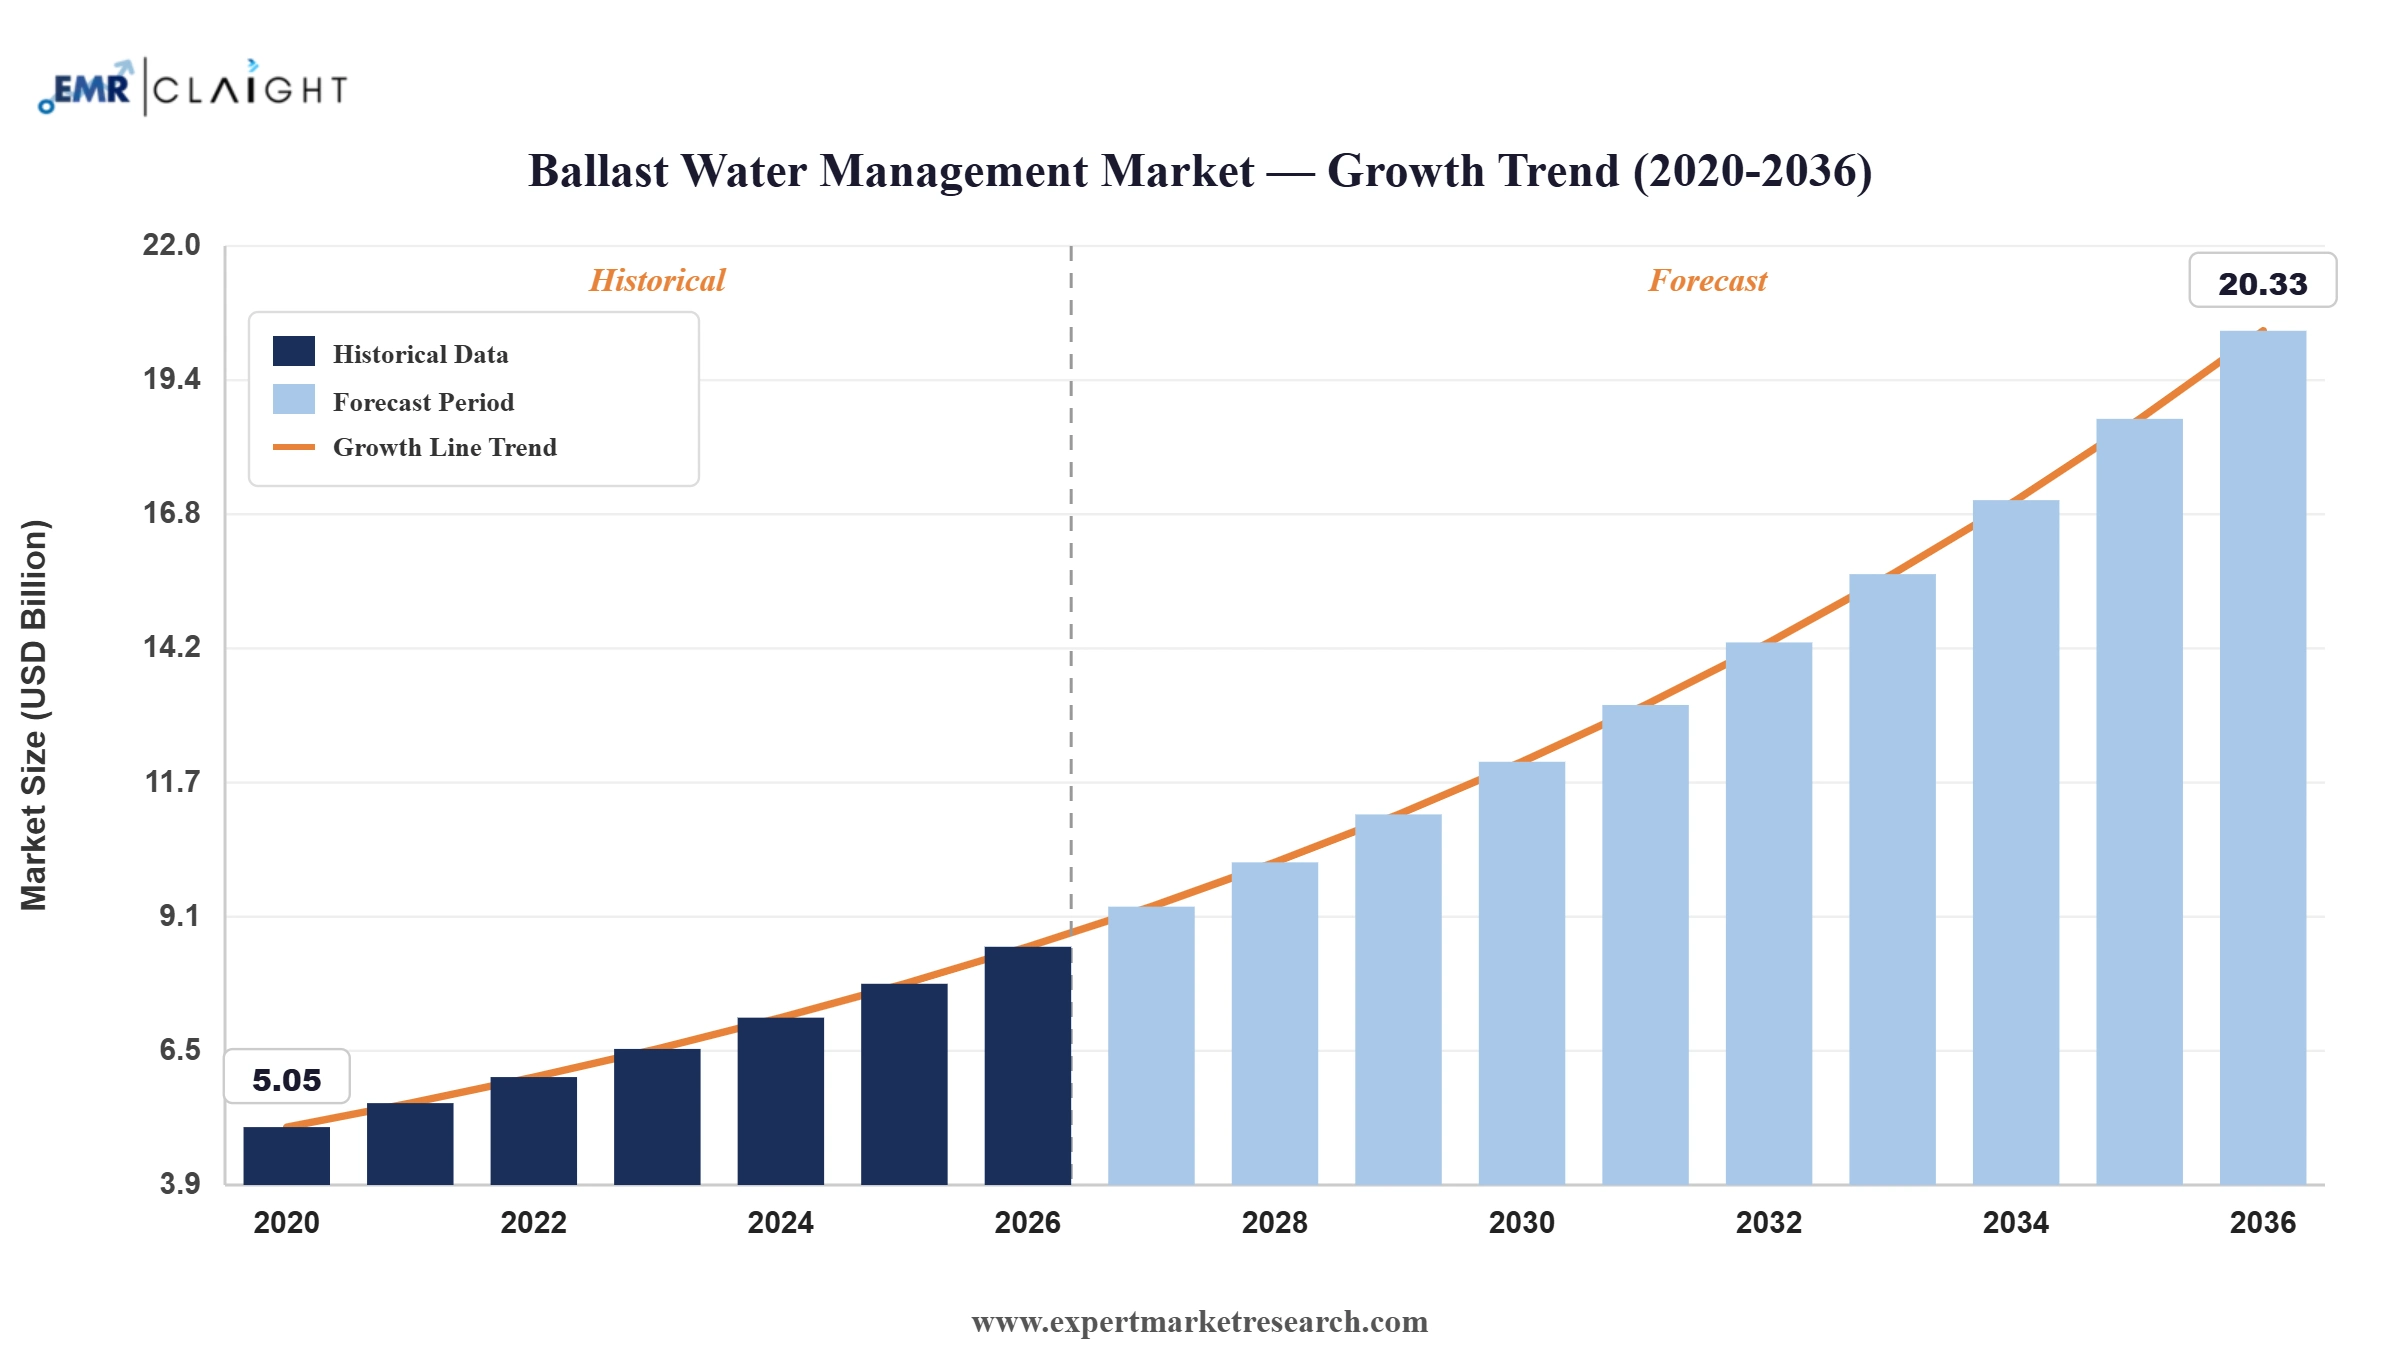
The global ballast water management market attained a value of USD 7.80 Billion in 2025 and is projected to expand at a CAGR of 9.10% through 2035. The market is further expected to achieve USD 18.64 Billion by 2035, driven by stringent international rules on ballast water discharge, rising maritime trade, and the growing number of treatment systems fitted to commercial vessels worldwide.
The approval pipeline keeps the technology base broad. The U.S. Coast Guard's review list shows an application received from Sunrui in April 2026 for its BalClor and BalClor Smart systems, alongside other pending applications for ballast water management equipment. Each added approval widens the choice open to owners, which encourages upgrades to newer and more compact designs across retrofit and newbuild programmes. Yards and owners compare approval status, capacity range, and service support when choosing among systems for a given vessel type and trading pattern.
Port-state oversight is widening as well. Brazil's Ministry of Ports and Airports proposed cooperation on ballast water monitoring in April 2026, seeking alignment and joint inspection of vessels, as reported by the Santos newspaper A Tribuna. Stronger monitoring raises the value of equipment that can demonstrate compliance, supporting demand for treatment systems, sampling services, and ongoing performance checks across busy Latin American ports. Where inspections become more frequent, owners need to document ballast handling carefully for port authorities, which makes reliable and well supported equipment more valuable.
Treatment capacity is also moving onto the quayside. Bawat Water Technologies reported in August 2026, for the six months ended June 2026, sales of SEK 12.4 million against SEK 8.3 million in the six months ended June 2025, led by its Ballast-as-a-Service units, with three units now placed between Belgium and Denmark and a first European tender for a port reception facility for ballast water open. Shore-based services give owners a compliance route when onboard equipment is out of service. For yards and ports, they add flexibility, because water can be treated before discharge without waiting for a vessel to fit new equipment, which supports demand for mobile units, sampling, and related service contracts.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The U.S. Coast Guard issued a type approval certificate in July 2026 for the LeesGreen ballast water management system from Shanghai LEE's FUDA of China, according to its approved-system status list. The certificate adds another Chinese manufacturer to the systems cleared for U.S. waters, widening choice for owners trading there. Companies can secure early approvals for American waters to win retrofit and newbuild specifications from owners with port calls there.
Euro Tech Holdings Company Limited announced in June 2026 a mobile hybrid ballast water port reception and treatment facility, due for dispatch in July 2026 to the Torvasted, Norway site of Sea Clean AS, which says it has served more than 2,300 vessels. The unit will be shown at SMM 2026 in Hamburg. Companies can expand shore-based treatment options to serve vessels with limited onboard capacity.
HAV Group's subsidiary Norwegian Greentech was awarded several contracts in February 2026 covering a total of ten ballast water treatment systems for shuttle tankers, live fish carriers, and offshore vessels, delivered as both retrofits and newbuild installations for shipyards in Norway and abroad. Contract values were not disclosed. Companies can bundle retrofit and newbuild supply to build a steady order book across niche vessel types.
DESMI Ocean Guard A/S of Denmark had the type approval for its CompactClean ballast water management system amended by the U.S. Coast Guard in December 2025. Amendments of this kind keep an approved design aligned with updated models and operating details, so owners can keep ordering current variants. Companies can maintain and extend existing approvals to protect installed bases and keep new variants available.
Alfa Laval published its interim report for April to June 2026 in July 2026, showing orders received of SEK 22,235 million, up 35%, and net sales of SEK 18,117 million, up 8%, while adjusted EBITA reached SEK 3,071 million at a 17.0% margin. The figures cover the group as a whole. Companies can leverage a broad equipment base to cushion the timing of individual marine projects.
The Norwegian Maritime Authority granted type approval to PureBallast 3.5 Ultra and PureBallast 3.5 Ultra Ex from Alfa Laval Technologies, a decision reported to the IMO ahead of MEPC 84, which met from April to May 2026. The Ex model is designed for hazardous-location installation. Approval from a second administration gives yards and owners more flexibility in where certification is sourced. Companies can leverage approvals from several administrations to broaden the fleet they can address.
Denmark's Environmental Protection Agency and Maritime Authority notified a type-approval decision for the OceanGuard Sim system from Headway Technology Group (Qingdao) Co., Ltd., listed among the documents for MEPC 84 in April 2026. Approval by a European administration gives the Qingdao maker a route to owners that favour European flag-state certification. Companies can leverage multi-administration approvals to reach European owners and yards.
Wärtsilä released its interim report for January to March 2026 in April 2026, with group order intake of EUR 2,099 million, up 10%, Marine and Energy order intake of EUR 1,997 million, up 28%, and an order book of EUR 8,900 million. The report counted 549 vessel newbuild orders in the three months. Companies can leverage rising newbuild activity to secure early equipment slots for ballast systems.
This Expert Market Research's Report titled "Ballast Water Management Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Technology
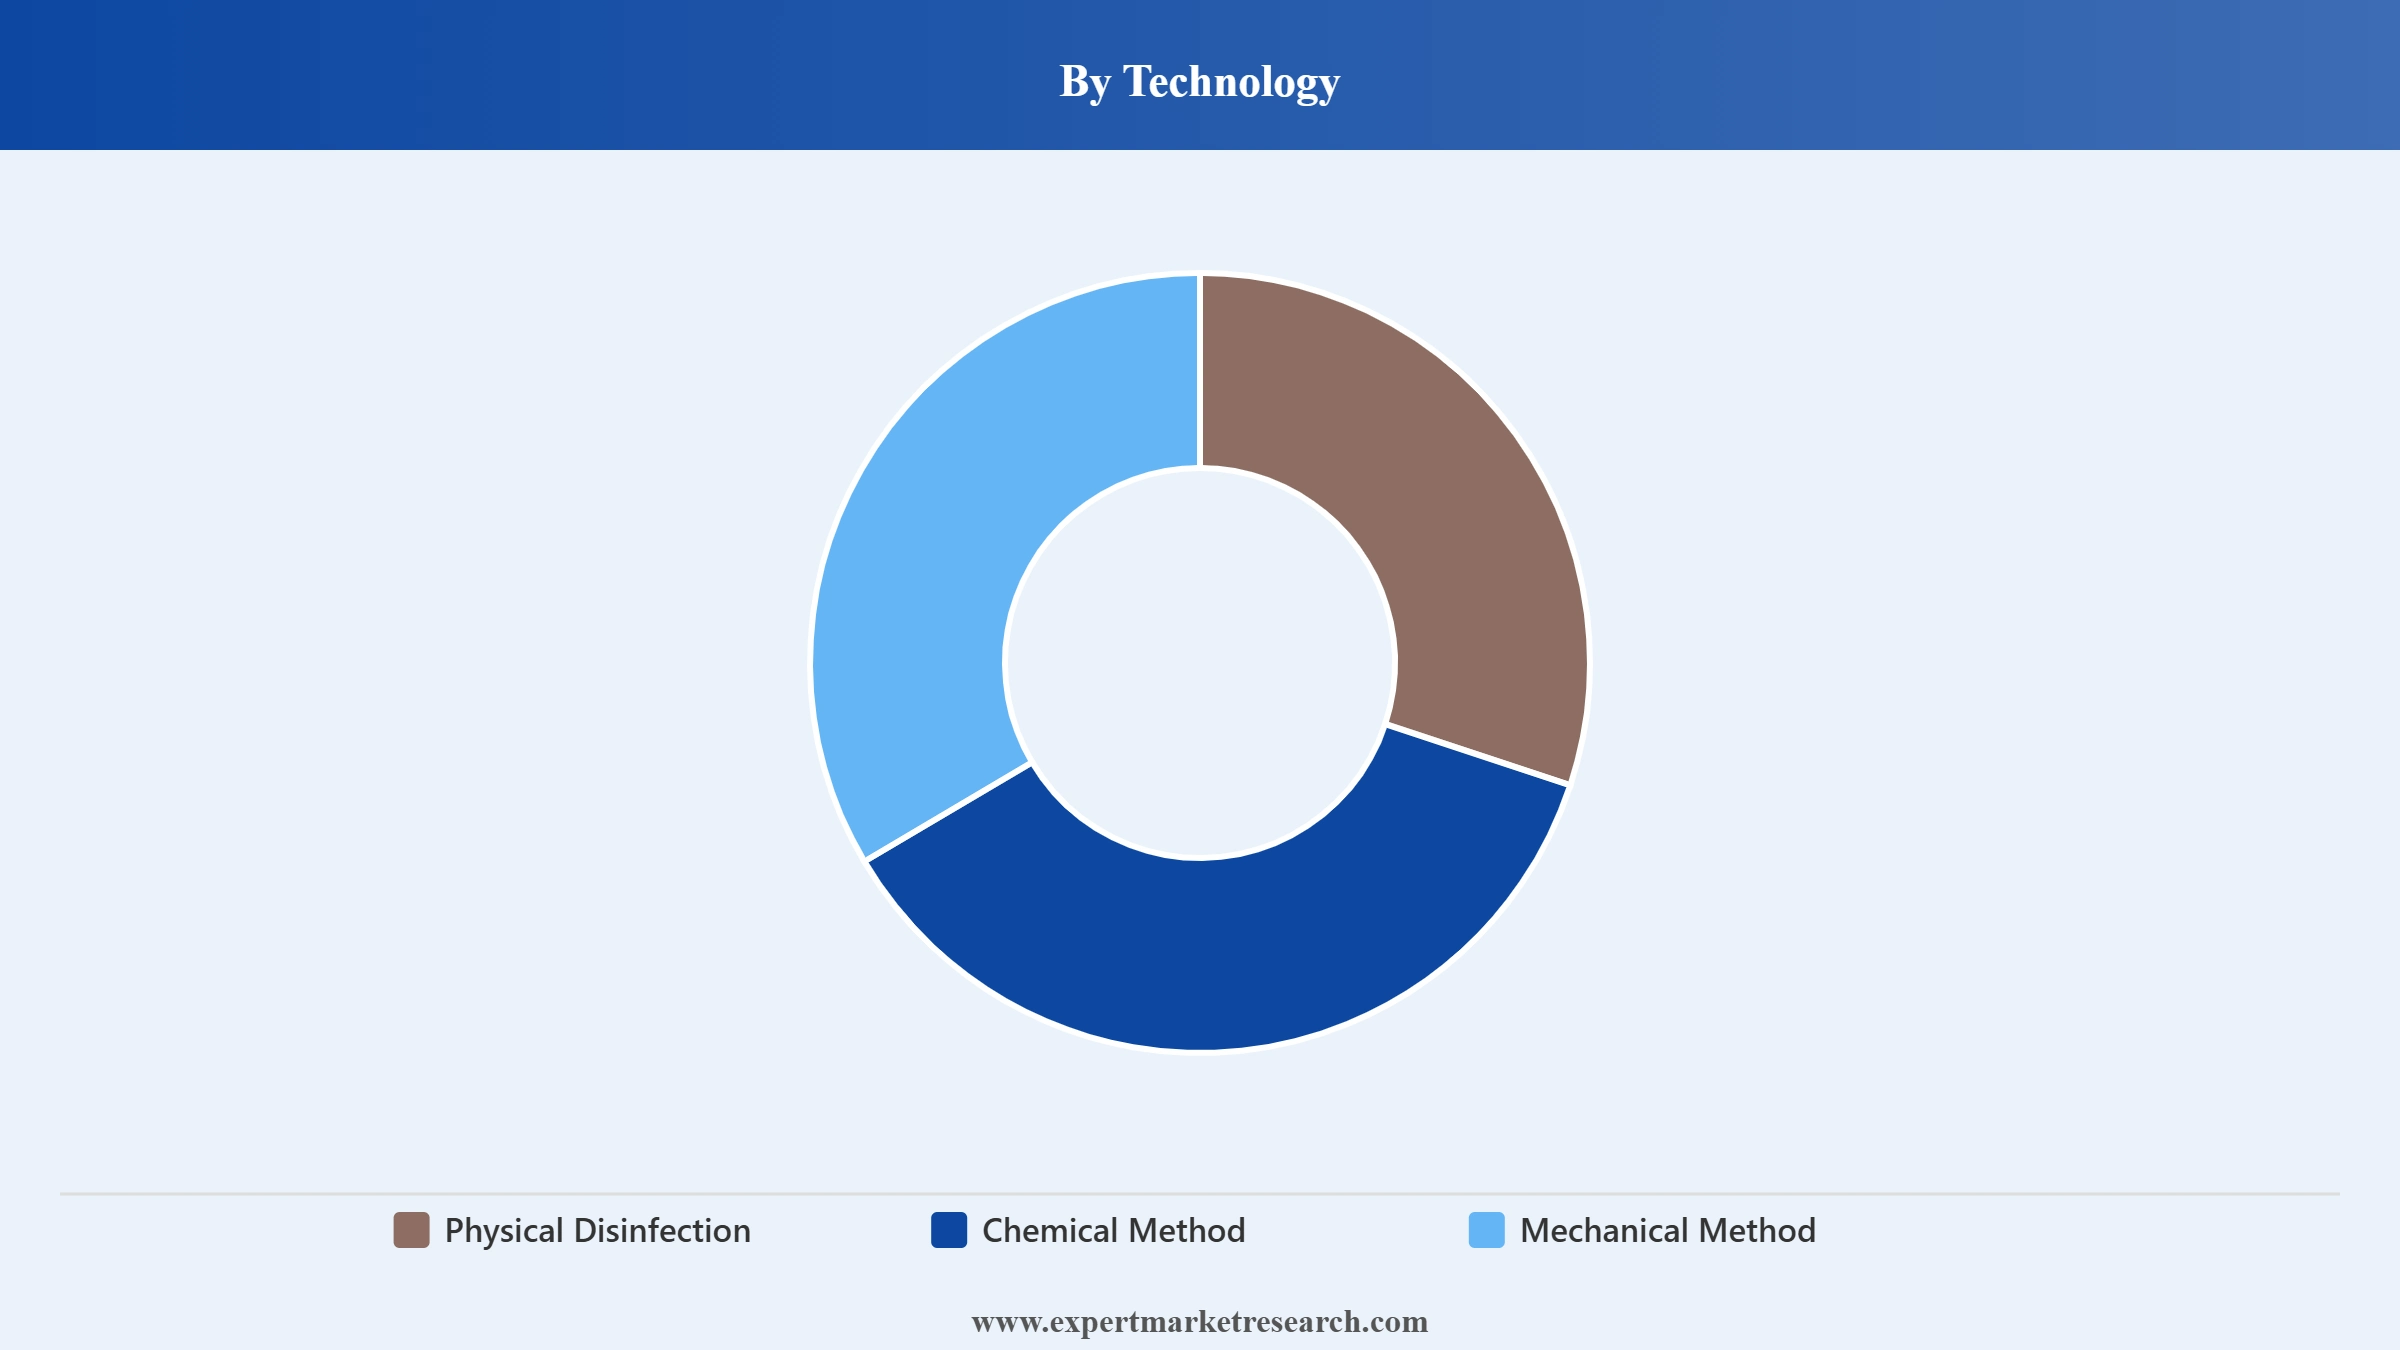
Key Insight: Physical Disinfection is the leading technology, with Alfa Laval reporting in April 2026 orders received of SEK 17,612 million for the three months ended March 2026; Chemical Method is the fastest-growing technology, supported by Techcross, which announced in August 2025 that it would equip eight Wilson ASA multi-purpose cargo vessels with its filter-less direct electrolysis system; and Mechanical Method covers the filtration and separation stages that feed treatment trains, where Shanghai Electric Cyeco Environmental Technology's Cyeco BWMS, whose amended Norwegian approval added explosion-proof Ex models, was listed among the MEPC 84 documents in April 2026.
Market Breakup by Services
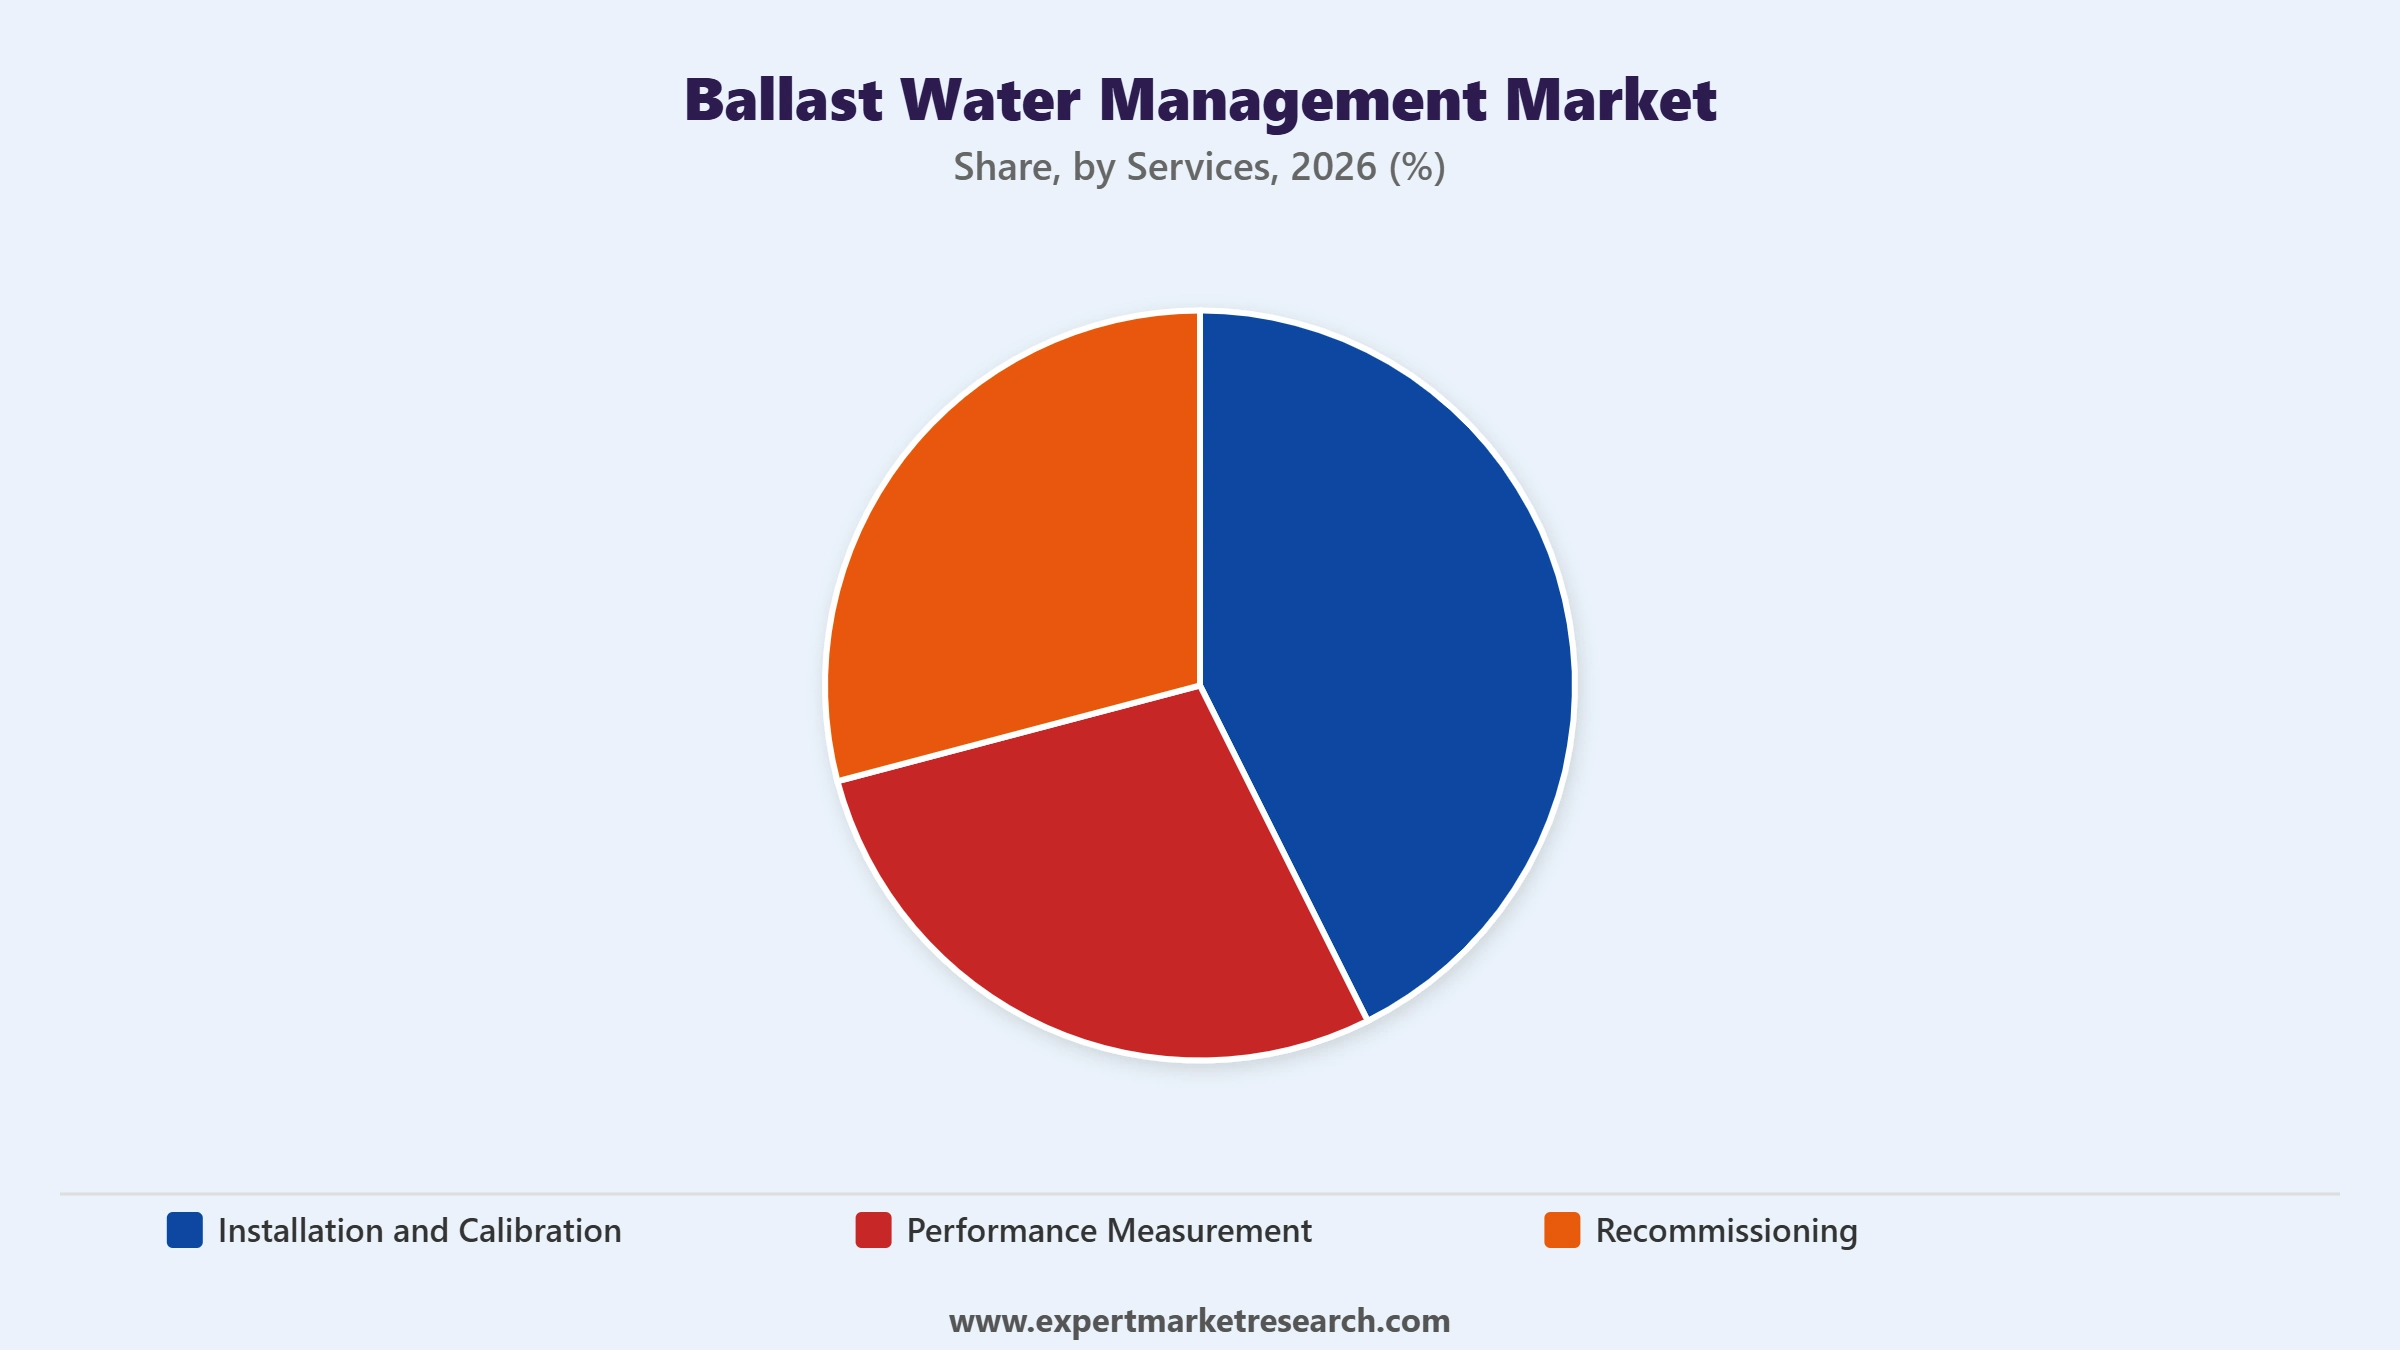
Key Insight: Installation and Calibration is the leading service, as seen in Scienco/FAST's inTank BWTS, whose amended Norwegian approval added an alternate TRO sensor and the inTank FITT and SuperFITT models and appeared on the MEPC 84 document list in April 2026; Performance Measurement is the fastest-growing service, with the board of Brazil's ANTAQ ratifying in August 2026 the suspension of a port-level notice that would have required an extra ballast water compliance certificate; and Recommissioning follows maintenance and repair, where the IMO's MEPC 84 approved draft Ballast Water Management Convention amendments in May 2026 covering system maintenance records, surveys, and certification.
Market Breakup by Region
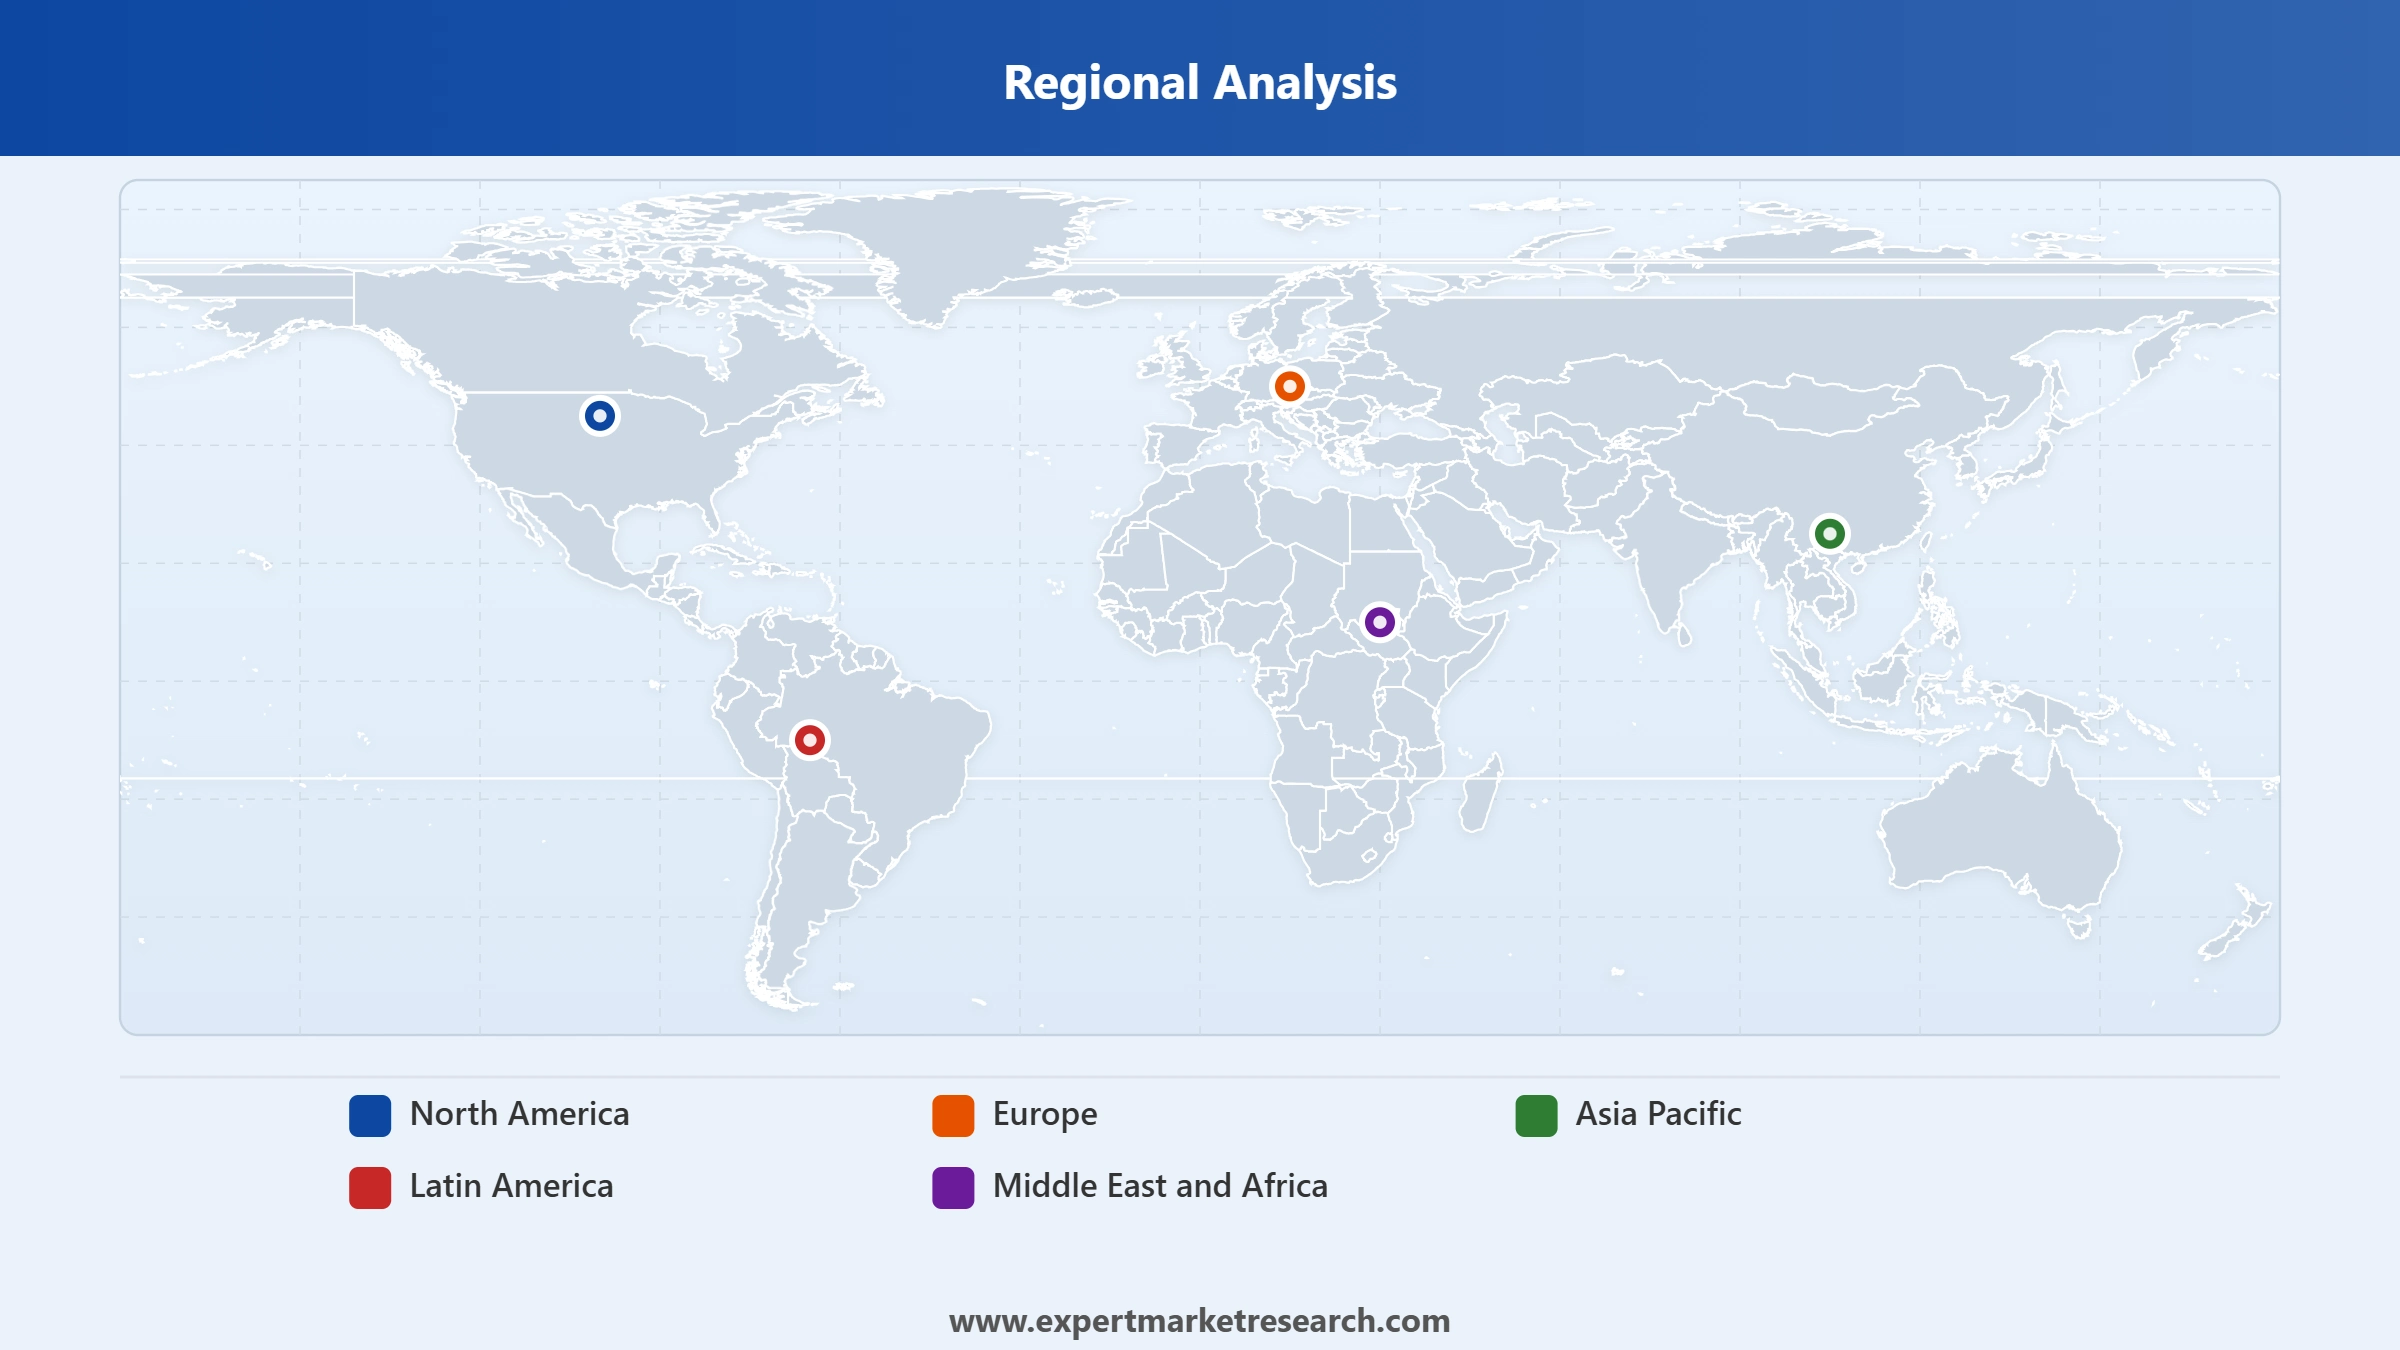
Key Insight: North America is shaped by U.S. Coast Guard certification, with oneTank, LLC recording an amended approval for its oneTank system in February 2026; Europe hosts established suppliers, among them Knutsen Ballast Water AS of Norway, which had its KBAL BWMS amended by the U.S. Coast Guard in February 2025; Asia Pacific is the largest and fastest-growing region, with S&SYS Co., Ltd of Korea recording an amended approval for its Purimar system in December 2025; Latin America is tightening port-state control, with the Brazilian Navy's Directorate of Ports and Coasts updating NORMAM-401/DPC in June 2026, as reported in July 2026; and the Middle East and Africa is led by Saudi Arabia and the United Arab Emirates, where Babard Maritime Services began offering onboard ballast water indicative sampling and testing at the Port of Fujairah from May 2026.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By Technology, Physical Disinfection leads the market while Chemical Method grows fastest because ultraviolet-based systems avoid chemical handling on board while electrolytic and ozone-based systems offer compact, high-capacity options.
Physical Disinfection leads because filtration followed by ultraviolet treatment avoids storing or dosing chemicals on board and works across fresh, brackish, and marine water. Optimarin of Norway won DNV type approval for its Guardian system in September 2026, a compact ultraviolet unit built on Hyde Marine reactor technology and offered from 60 to 3,000 m3/h, which gives owners with limited deck space or installed power a ready option and supports lasting owner confidence in physical disinfection for long-lived commercial vessels.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Chemical Method grows fastest as electrolytic and ozone-based designs scale to high flow rates on large tankers and bulk carriers. Techcross of Korea, whose systems rely on water electrolysis, received an amended U.S. Coast Guard approval for its ECS-Hychlor system in February 2025, showing how suppliers continue to refine chemical treatment designs to keep them approved and available for new orders, especially on large vessels where flow rates and available deck space shape equipment choice for each owner and project.
By Services, Installation and Calibration leads the market while Performance Measurement grows fastest because every new or retrofitted system must be fitted, commissioned, and then shown to meet the discharge standard.
Installation and Calibration leads because each newbuild and retrofit needs piping, power, sensors, and commissioning before a vessel can sail. Yards plan this work because delays can hold up delivery or idle a ship. BIO-UV Group, citing Paris Memorandum of Understanding port state control data, noted in February 2026 that the treatment system accounted for 46% of detainable ballast water deficiencies in one concentrated inspection campaign, which shows why careful fitting, calibration, and crew handover matter for every vessel owner.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Performance Measurement grows fastest as port states and owners look for proof that systems actually meet the discharge standard. Proof of this kind matters where inspections are frequent. BIO-UV Group and MicroWISE formed a partnership in January 2026 to combine the BIO-SEA treatment technology with real-time organism analysis, so that compliance can be checked before water is discharged, with validation work continuing through 2026, giving owners and port states a more direct view of whether installed systems perform as certified.
Asia Pacific is anticipated to hold the largest share of the global ballast water management market, shaped by the region's weight in shipbuilding and ship operation and a steady flow of locally developed systems.
This is supported by India's Ministry of Ports, Shipping and Waterways, which notified the Merchant Shipping (Control and Management of Vessels' Ballast Water and Sediments) Rules, 2026 in August 2026, requiring approved treatment systems, management plans, record books, and surveys once India accedes to the 2004 convention. Rules of this kind add a large national fleet to the region's compliance base, and owners and yards can specify locally supported equipment with shorter delivery chains for regional suppliers and local service.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is also the fastest-growing regional market, with Singapore's Maritime and Port Authority issuing Shipping Circular No. 7 of 2026 in July 2026, which told stakeholders to prepare for the 2026 Guidelines for Ballast Water Management and Development of BWM Plans adopted at MEPC 84. North America, Europe, Latin America, and the Middle East and Africa are expanding mainly through tighter regulation, certification, and port-state inspection, which keeps retrofit and compliance services in steady demand even where fleets are mature.
The global ballast water management market is moderately fragmented, with a handful of established treatment-system suppliers alongside many regional manufacturers and service providers competing for retrofit and newbuild orders.
Competitive dynamics are increasingly shaped by new type approvals across several administrations, compact skid-mounted designs, expansion of service networks, and tools that prove compliance after installation, as suppliers seek to defend installed bases while regulations tighten.
Alfa Laval Inc. supplies the PureBallast range of ballast water management systems, which combine filtration with enhanced ultraviolet treatment. In February 2026, the U.S. Coast Guard issued a certificate to Alfa Laval Technologies AB of Lund, Sweden, for PureBallast 3.5 Ultra and its hazardous-area Ex model, covering capacities of 85 to 3,000 m3/h, with a certificate life running to 2031.
Wärtsilä offers the Aquarius UV and Aquarius EC ballast water management systems, pairing filtration with ultraviolet treatment or side-stream electro-chlorination, and describes itself as the first supplier granted dual-technology U.S. Coast Guard type approval. For the six months ended June 2026, reported in July 2026, it posted order intake of EUR 4,934 million, up 23%, and an operating result of EUR 399 million.
Headway Technology Group (Qingdao) Co., Ltd. makes the OceanGuard family of ballast water management systems, listed by the U.S. Coast Guard under Headway Technology Co., Ltd. of China. In April 2026, the OceanGuard Sim system received U.S. Coast Guard type approval, following an application filed in October 2025, which gives the Qingdao-based group a route to owners that want U.S. certification.
Founded in 1980 and based in Busan, South Korea, NK Co., Ltd. makes the NK-O3 BlueBallast ozone-based ballast water systems, with U.S. Coast Guard listed capacities of 200 to 8,000 m3/h. Both NK-O3 BlueBallast II and NK-O3 BlueBallast II Plus were amended by the U.S. Coast Guard in March 2025, keeping the ozone-based range available for new orders.
Other key players in the ballast water management market include Hitachi, Ltd. and Ecochlor, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
For a detailed assessment of opportunities across the ballast water management market's technology, services, and regional segments through 2026 and beyond, connect with Expert Market Research for a customized consultation.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The ballast water management market is projected to grow at a CAGR of 9.10% from 2026 to 2035.
The market is expected to attain approximately USD 18.64 Billion by 2035.
Key strategies include obtaining type approvals from several administrations, launching compact and skid-mounted designs, expanding service and monitoring offerings, and bundling retrofit and newbuild supply to secure long-term customers.
The growing adoption of containerised ballast water management systems and technological advancements are the key trends propelling the growth of the market.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
The different technologies of ballast water management considered in the market report are physical disinfection, chemical method, and mechanical method.
The major services considered in the market report include installation and calibration, performance measurement, and recommissioning.
Key players in the ballast water management market include Alfa Laval Inc., Headway Technology Group (Qingdao) Co., Ltd., Hitachi, Ltd., NK Co., Ltd., Wärtsilä, and Ecochlor, among others.
The global ballast water management market attained a value of USD 7.80 Billion in 2025.
Key challenges include differing approval and port-state requirements across administrations, the cost and downtime of retrofitting older vessels, the need to prove compliance after installation, and the space and power limits of installing treatment equipment on existing ships.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Technology |
|
| Breakup by Services |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




