

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The cold rolled coil steel market was valued at USD 180000.00 Million in 2025. The market is expected to grow at a CAGR of 3.50% during the forecast period of 2026-2035 to reach a value of USD 253907.78 Million by 2035. Sustained automotive production, expanding construction and appliance manufacturing, and continued investment in advanced high strength steel capacity are collectively driving demand for cold rolled coil steel worldwide.
The current cold rolled coil steel market dynamics reflect sustained investment in advanced automotive steel capacity, as major producers expand cold rolling and galvanizing lines to meet rising demand for lightweight, high strength body panels across global vehicle manufacturing hubs. This investment reflects growing recognition that automakers increasingly require locally produced, advanced high strength steel to meet safety and lightweighting requirements without relying on imported supply chains. In November 2025, United States Steel Corporation outlined a fourteen billion dollar domestic investment plan following its recent change in ownership, with eleven billion dollars dedicated to modernising manufacturing facilities including new hot strip mill capacity by the end of 2028.
The overall cold rolled coil steel industry through 2025 continues to be shaped by capacity expansion across Asia's largest steel producing economies, as domestic manufacturers pursue new integrated steel mills to reduce reliance on imports and capture rising regional automotive and construction demand. Producers are simultaneously navigating volatile input costs and trade policy shifts, with several major economies adjusting import tariffs on flat rolled steel products to protect domestic capacity. In July 2025, thyssenkrupp Steel completed a major two year investment at its Duisburg location in Germany, commissioning a new continuous casting line and a fully modernised hot strip mill alongside automated slab logistics, creating one of the most modern plant networks in the European steel industry. Continued modernisation activity of this kind across established European and North American facilities is helping offset new capacity additions concentrated in Asia, keeping legacy production networks competitive on quality and surface finish even as overall regional output growth slows relative to expanding Asian integrated mills.
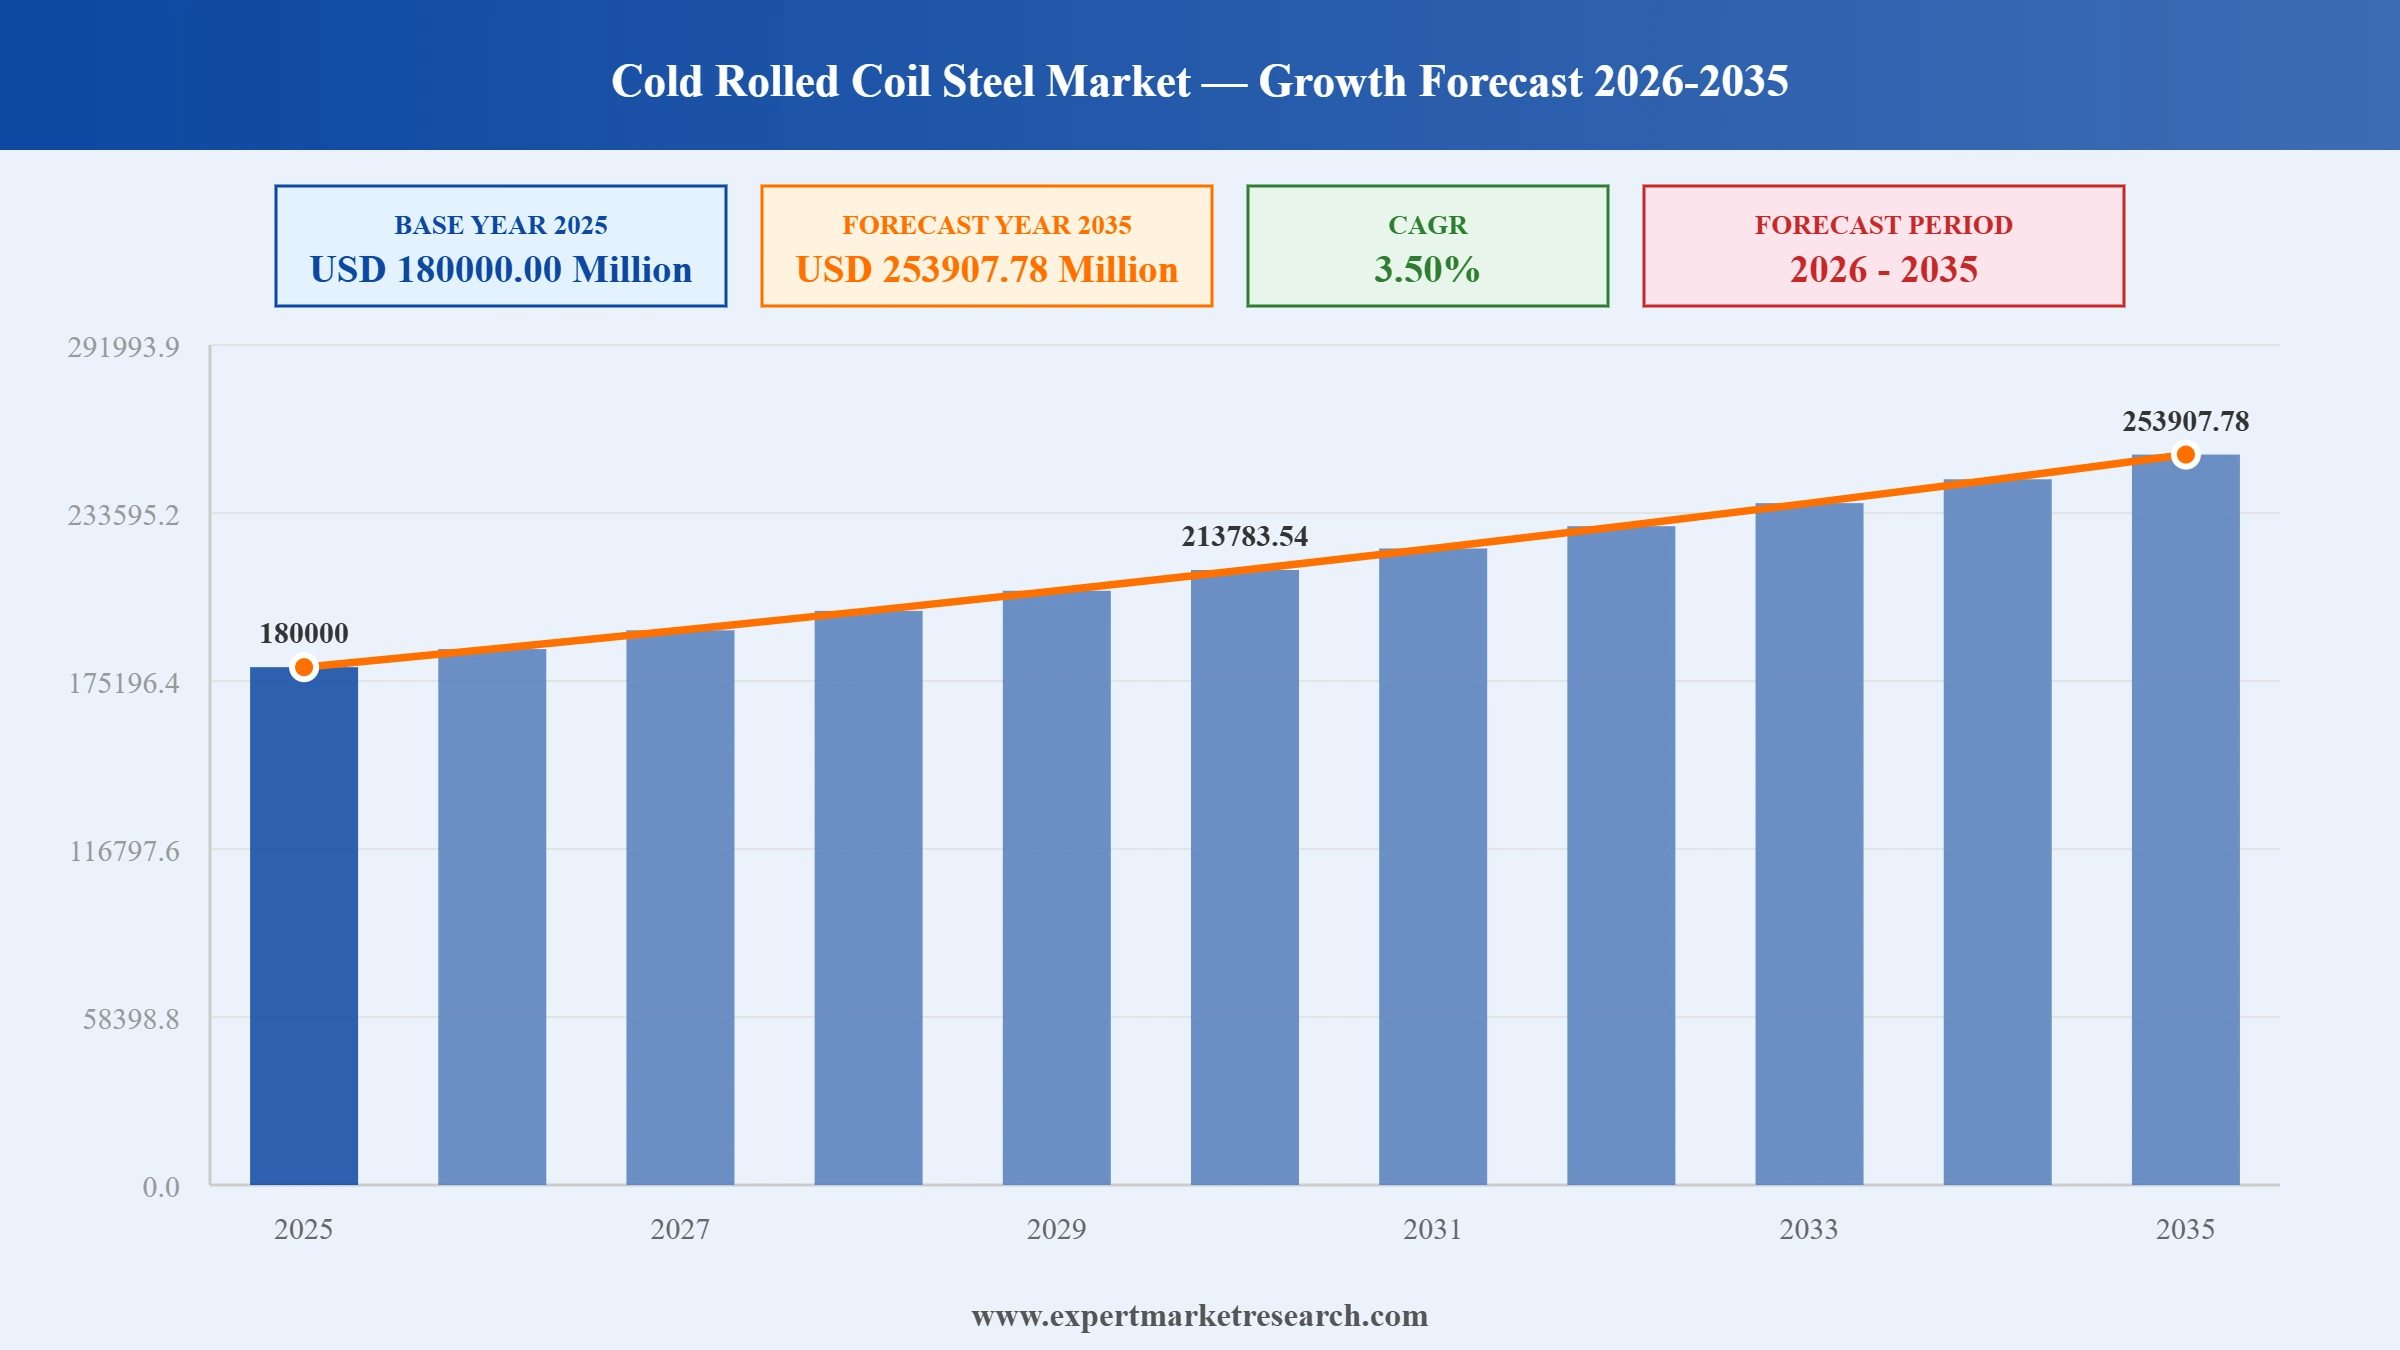
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
|
Cold Rolled Coil Steel Market Report Summary |
Description |
Value |
|
Base Year |
USD Million |
2025 |
|
Historical Period |
USD Million |
2019-2025 |
|
Forecast Period |
USD Million |
2026-2035 |
|
Market Size 2025 |
USD Million |
180000.00 |
|
Market Size 2035 |
USD Million |
253907.78 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
3.50% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
4.1% |
|
CAGR 2026-2035 - Market by Product Type |
Cold Rolled Coils |
3.7% |
|
CAGR 2026-2035 - Market by Application |
Packaging |
4.0% |
|
2025 Market Share by Region |
Asia Pacific |
48.6% |
The cold rolled coil steel market is being reshaped by major capacity expansion projects across Asia's leading steel producing economies, continued investment in advanced automotive steel grades, and new integrated mill projects targeting import substitution.
ArcelorMittal Nippon Steel India inaugurated an advanced Pickling Line and Tandem Cold Mill at its Hazira, Gujarat plant in April 2026, adding 2 million tonnes per annum of cold rolled base steel capacity capable of producing advanced high strength steel up to 1180 megapascals. Other joint ventures in the market can pursue similarly dedicated automotive steel lines to strengthen domestic supply chains rather than relying on imported advanced high strength grades.
JFE Steel agreed with JSW Steel in December 2025 to establish a 50 percent owned joint venture operating a brownfield integrated steelworks in India with expansion capacity to 10 million tonnes by 2030 and potential to scale to 15 million tonnes. Japanese producers considering a third Indian entry point can treat this brownfield joint venture structure as a faster route to scale than building an entirely new greenfield facility from the ground up.
Tata Steel approved a 0.7 million tonnes per annum hot rolled pickling and galvanizing line project at its Tarapur Cold Rolling Complex in December 2025, strengthening the company's value added steel product capabilities. Producers elsewhere in the market can pursue similar targeted line additions at existing complexes to expand value added capacity without the capital intensity of an entirely new integrated mill.
POSCO signed a heads of agreement with an Indian steelmaking partner in July 2025 to build an integrated steel mill with 6 million tonnes of annual crude steel capacity in Odisha, India, spanning ironmaking through cold rolling and galvanizing. This kind of equal partnership joint venture structure gives international producers a lower risk route into high growth steel markets while sharing capital costs and local market expertise with an established domestic player.
Cold rolled steel producers are increasingly developing dedicated advanced high strength steel grades optimised for electric vehicle battery enclosures and structural components, reflecting rising demand from automakers pursuing lighter, more crash resistant vehicle architectures. In August 2025, Hyundai Motor Group expanded its planned Louisiana investment to include a 5.8 billion dollar electric arc furnace steel mill producing 2.7 million tonnes annually of hot and cold rolled coil, with 70 percent of output directed to its own automotive factories in Georgia and Alabama.
Steel producers are increasingly investing in near zero carbon electric arc furnace capacity fed by direct reduced iron and scrap steel, reflecting mounting pressure to decarbonise production ahead of tightening environmental regulation and customer sustainability requirements. By December 2025, China Baowu Steel Group advanced construction of a 622 million dollar near zero carbon steel mill in Zhanjiang, Guangdong, featuring a 220 tonne electric arc furnace powered by green electricity.
Steel producers are increasingly constructing entirely new greenfield sheet mills incorporating dedicated cold rolling capacity rather than relying solely on brownfield expansions at existing sites, reflecting confidence in sustained long term demand for automotive and construction grade sheet steel. As of April 2026, Nucor's new 3 million ton per year sheet mill in Apple Grove, West Virginia reached approximately 85 percent completion, with commissioning of its pickle line and cold mill underway ahead of automotive galvanizing line startup later in the year.
Cold rolled steel producers are increasingly adding dedicated bright anneal processing lines rather than relying on conventional acid based annealing, reflecting rising customer demand for premium surface finish suited to high end automotive and critical appliance components. In September 2025, Cleveland-Cliffs completed a 150 million dollar Vertical Stainless Bright Anneal Line at its Coshocton Works in Ohio, eliminating conventional acid based processing to strengthen its position as a leading domestic supplier of premium stainless steel.
Steel producers in Europe and neighbouring export markets are increasingly investing in facility modernisation and renewable energy integration to protect export competitiveness against rising domestic and international carbon compliance costs. In June 2025, Turkey's Erdemir Group announced an 825 million dollar investment plan for 2025 covering green transformation of production, facility modernisation, and renewable energy development, supporting continued flat steel exports representing around 20 percent of total group sales.
The Expert Market Research's report titled “Cold Rolled Coil Steel Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
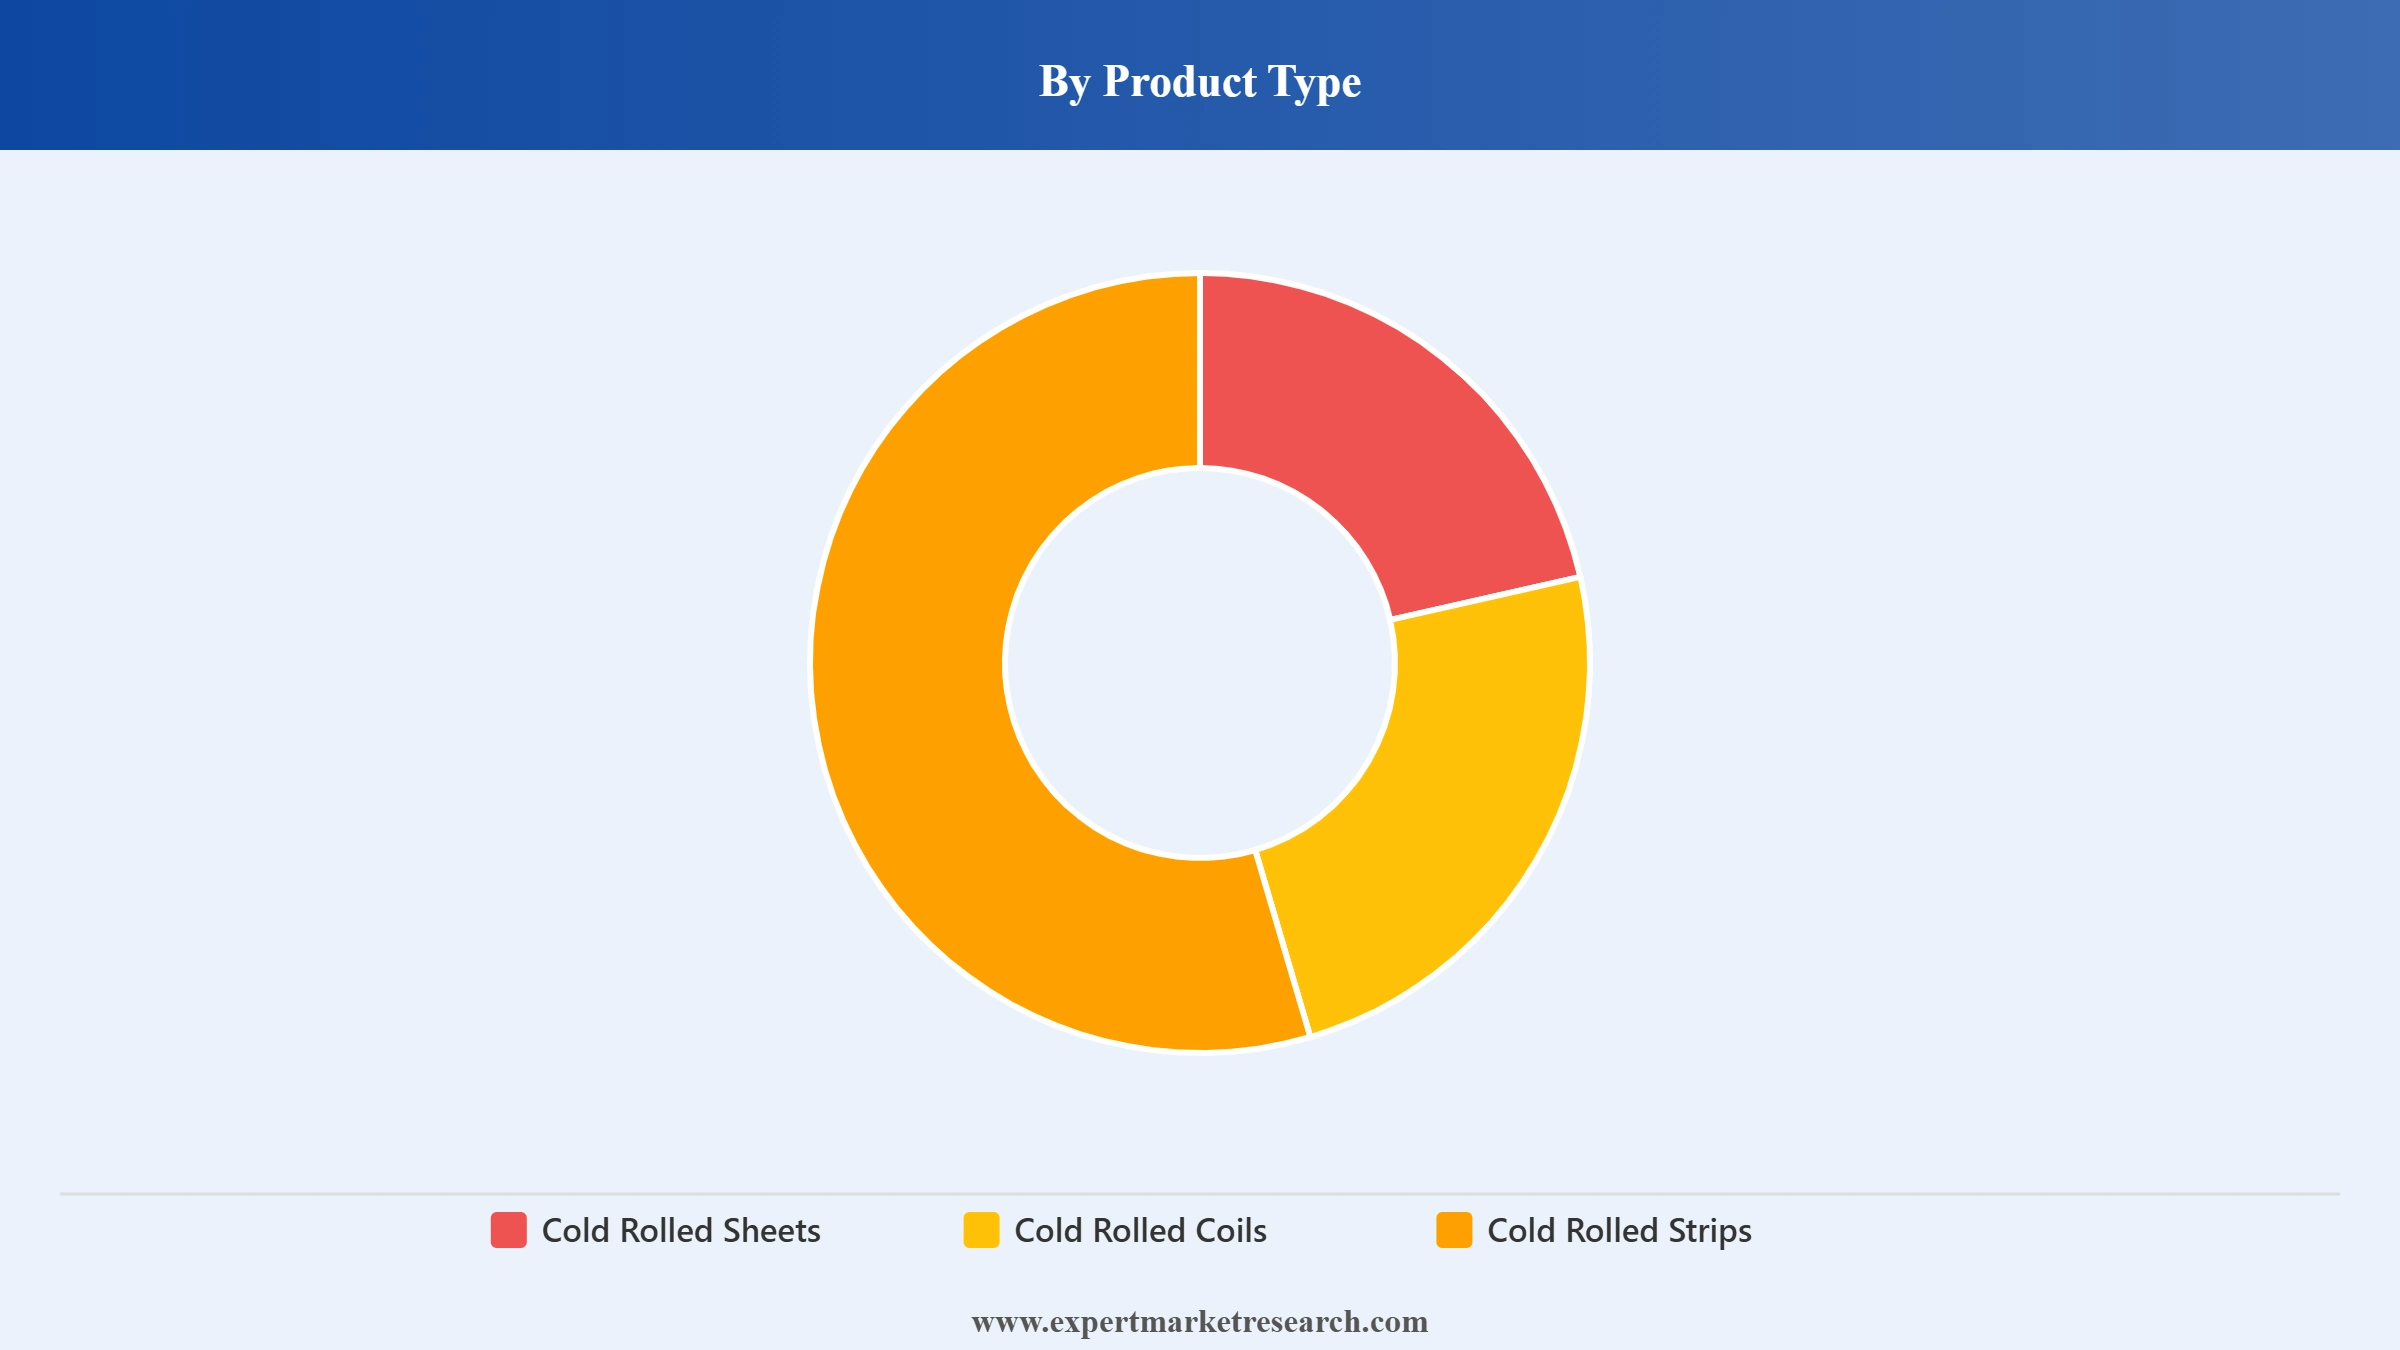
Key Insight: Cold Rolled Sheets account for the largest share of the cold rolled coil steel market by product type, supported by widespread use in automotive body panels, appliance manufacturing, and general fabrication requiring precise dimensions and smooth surface finish. In February 2026, Severstal completed hot tests on its upgraded slitting line at its Cherepovets Iron and Steel Works, enabling a wider range of cold rolled coil widths and thicknesses following a modernisation project replacing around 80 percent of the line's equipment. Cold Rolled Coils are the fastest-growing product type. Cold Rolled Strips continue to serve narrower gauge applications. The Others category includes cold rolled flat products and specialty formed shapes.
Market Breakup by Grade
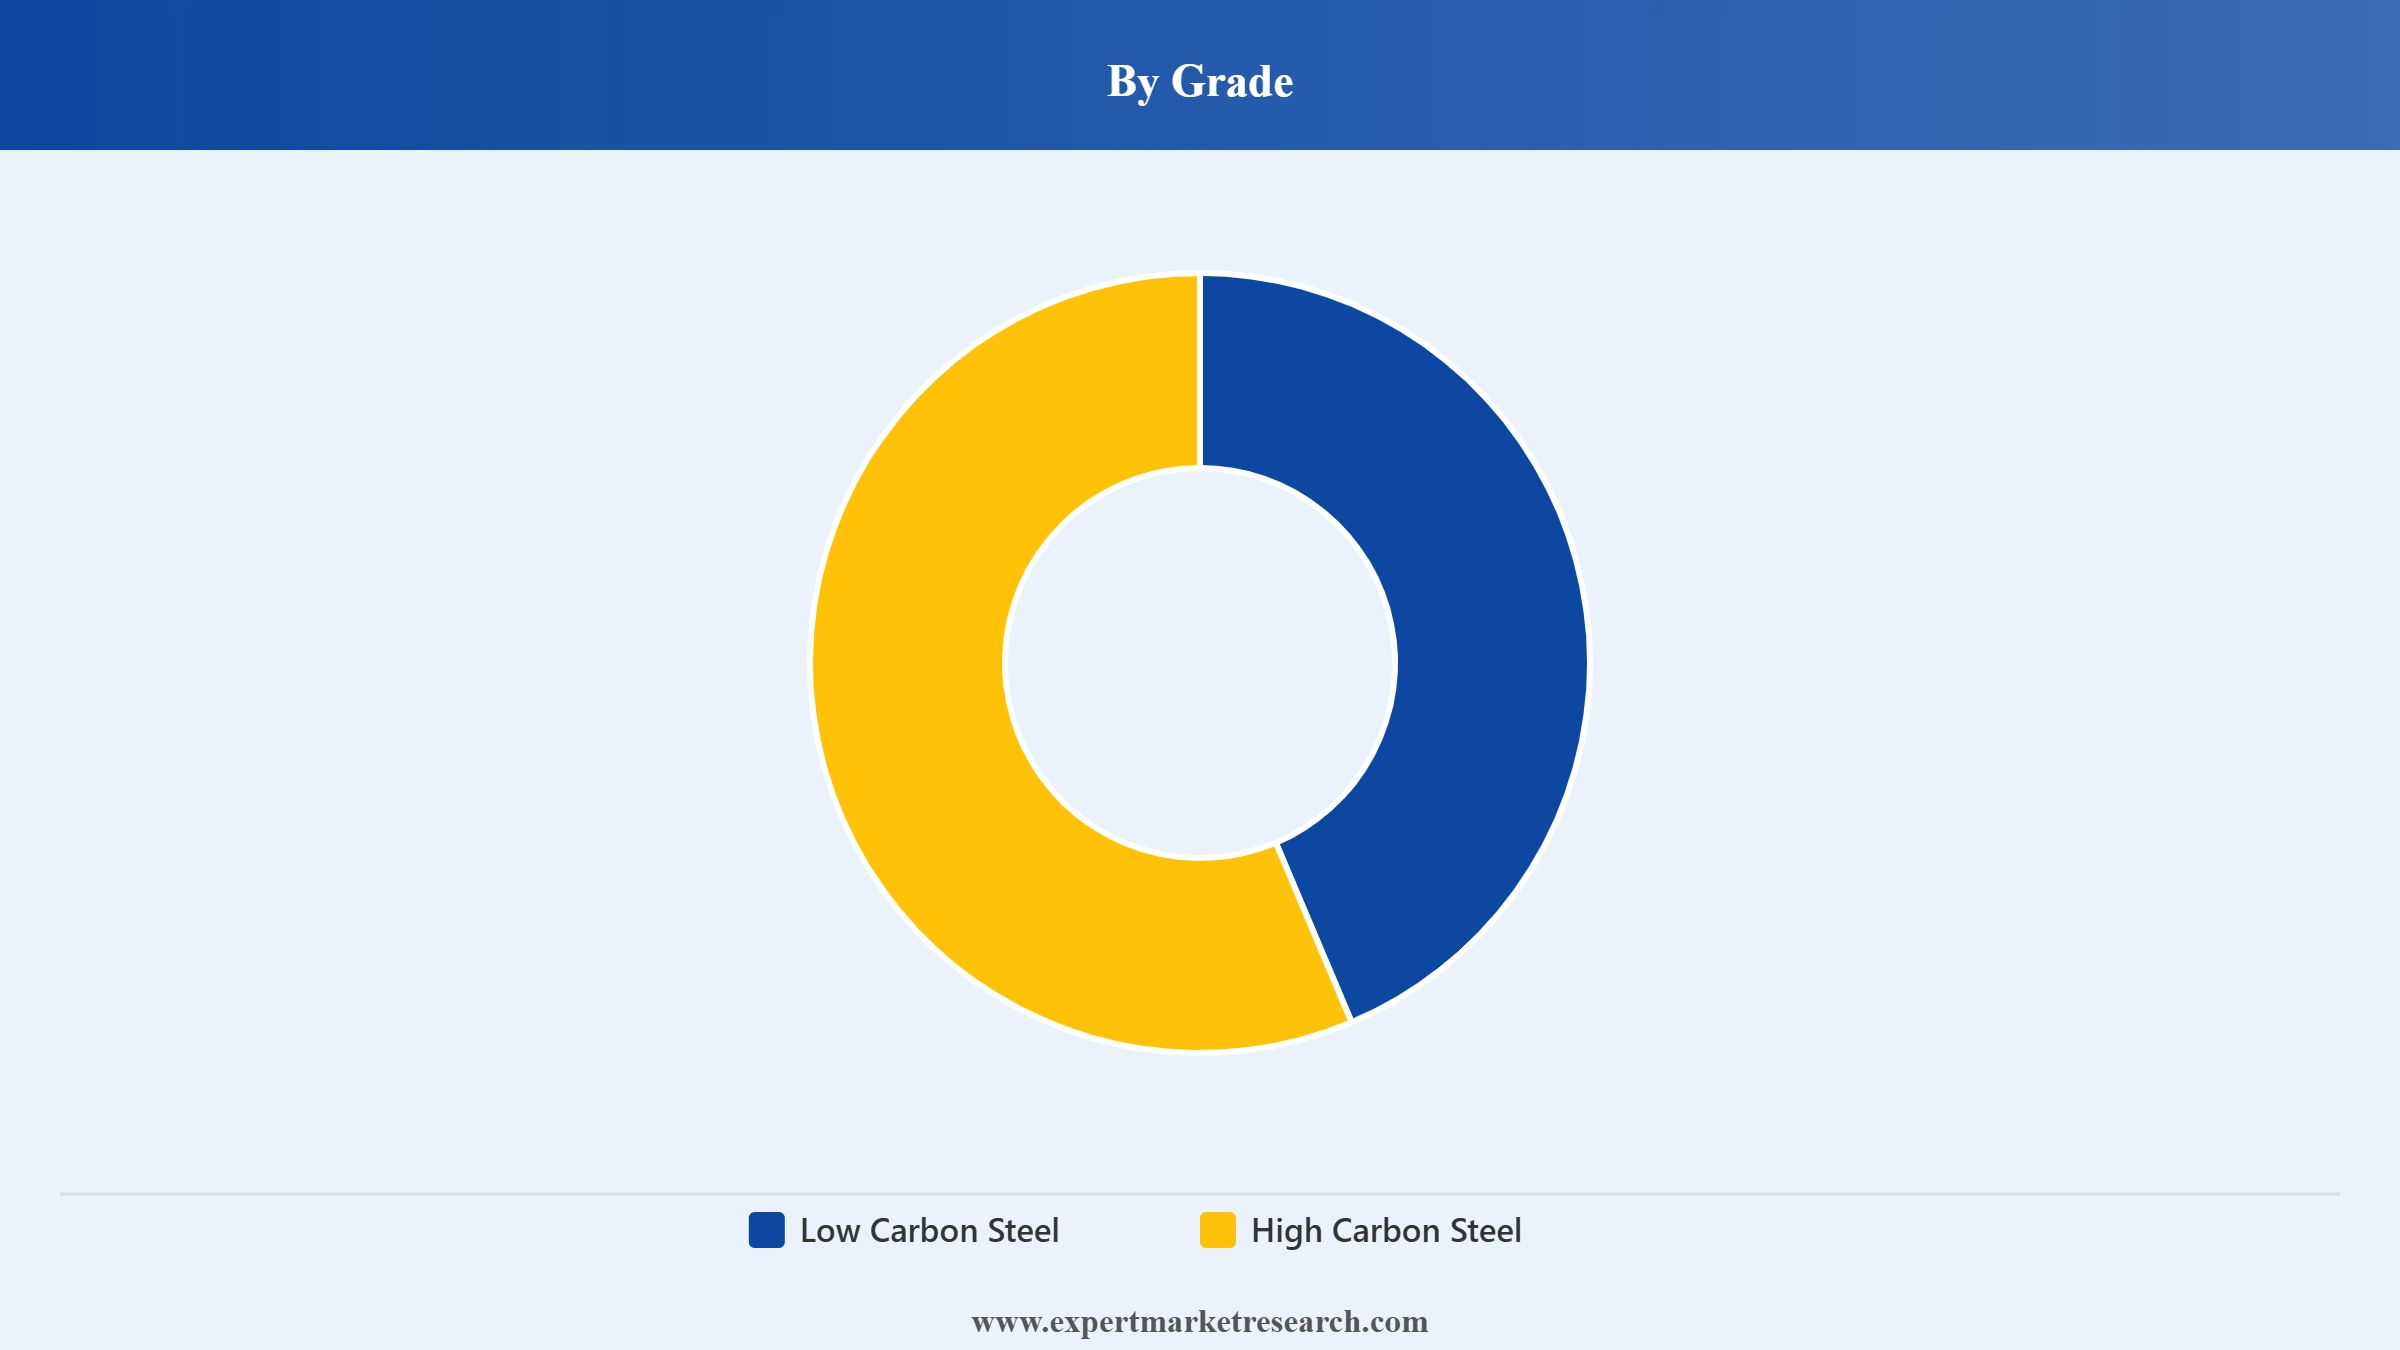
Key Insight: Low Carbon Steel accounts for the largest share of the cold rolled coil steel market by grade, reflecting its superior formability and weldability for automotive body panels, appliance housings, and general construction applications. In September 2025, voestalpine began construction of Hy4Smelt, a demonstration plant combining hydrogen direct reduction with an electric arc furnace at its Linz facility, aiming to supply lower carbon feedstock for its cold rolling and finishing operations. High Carbon Steel is the fastest-growing grade. The Others category includes advanced high strength steel and specialty alloy grades.
Market Breakup by Application
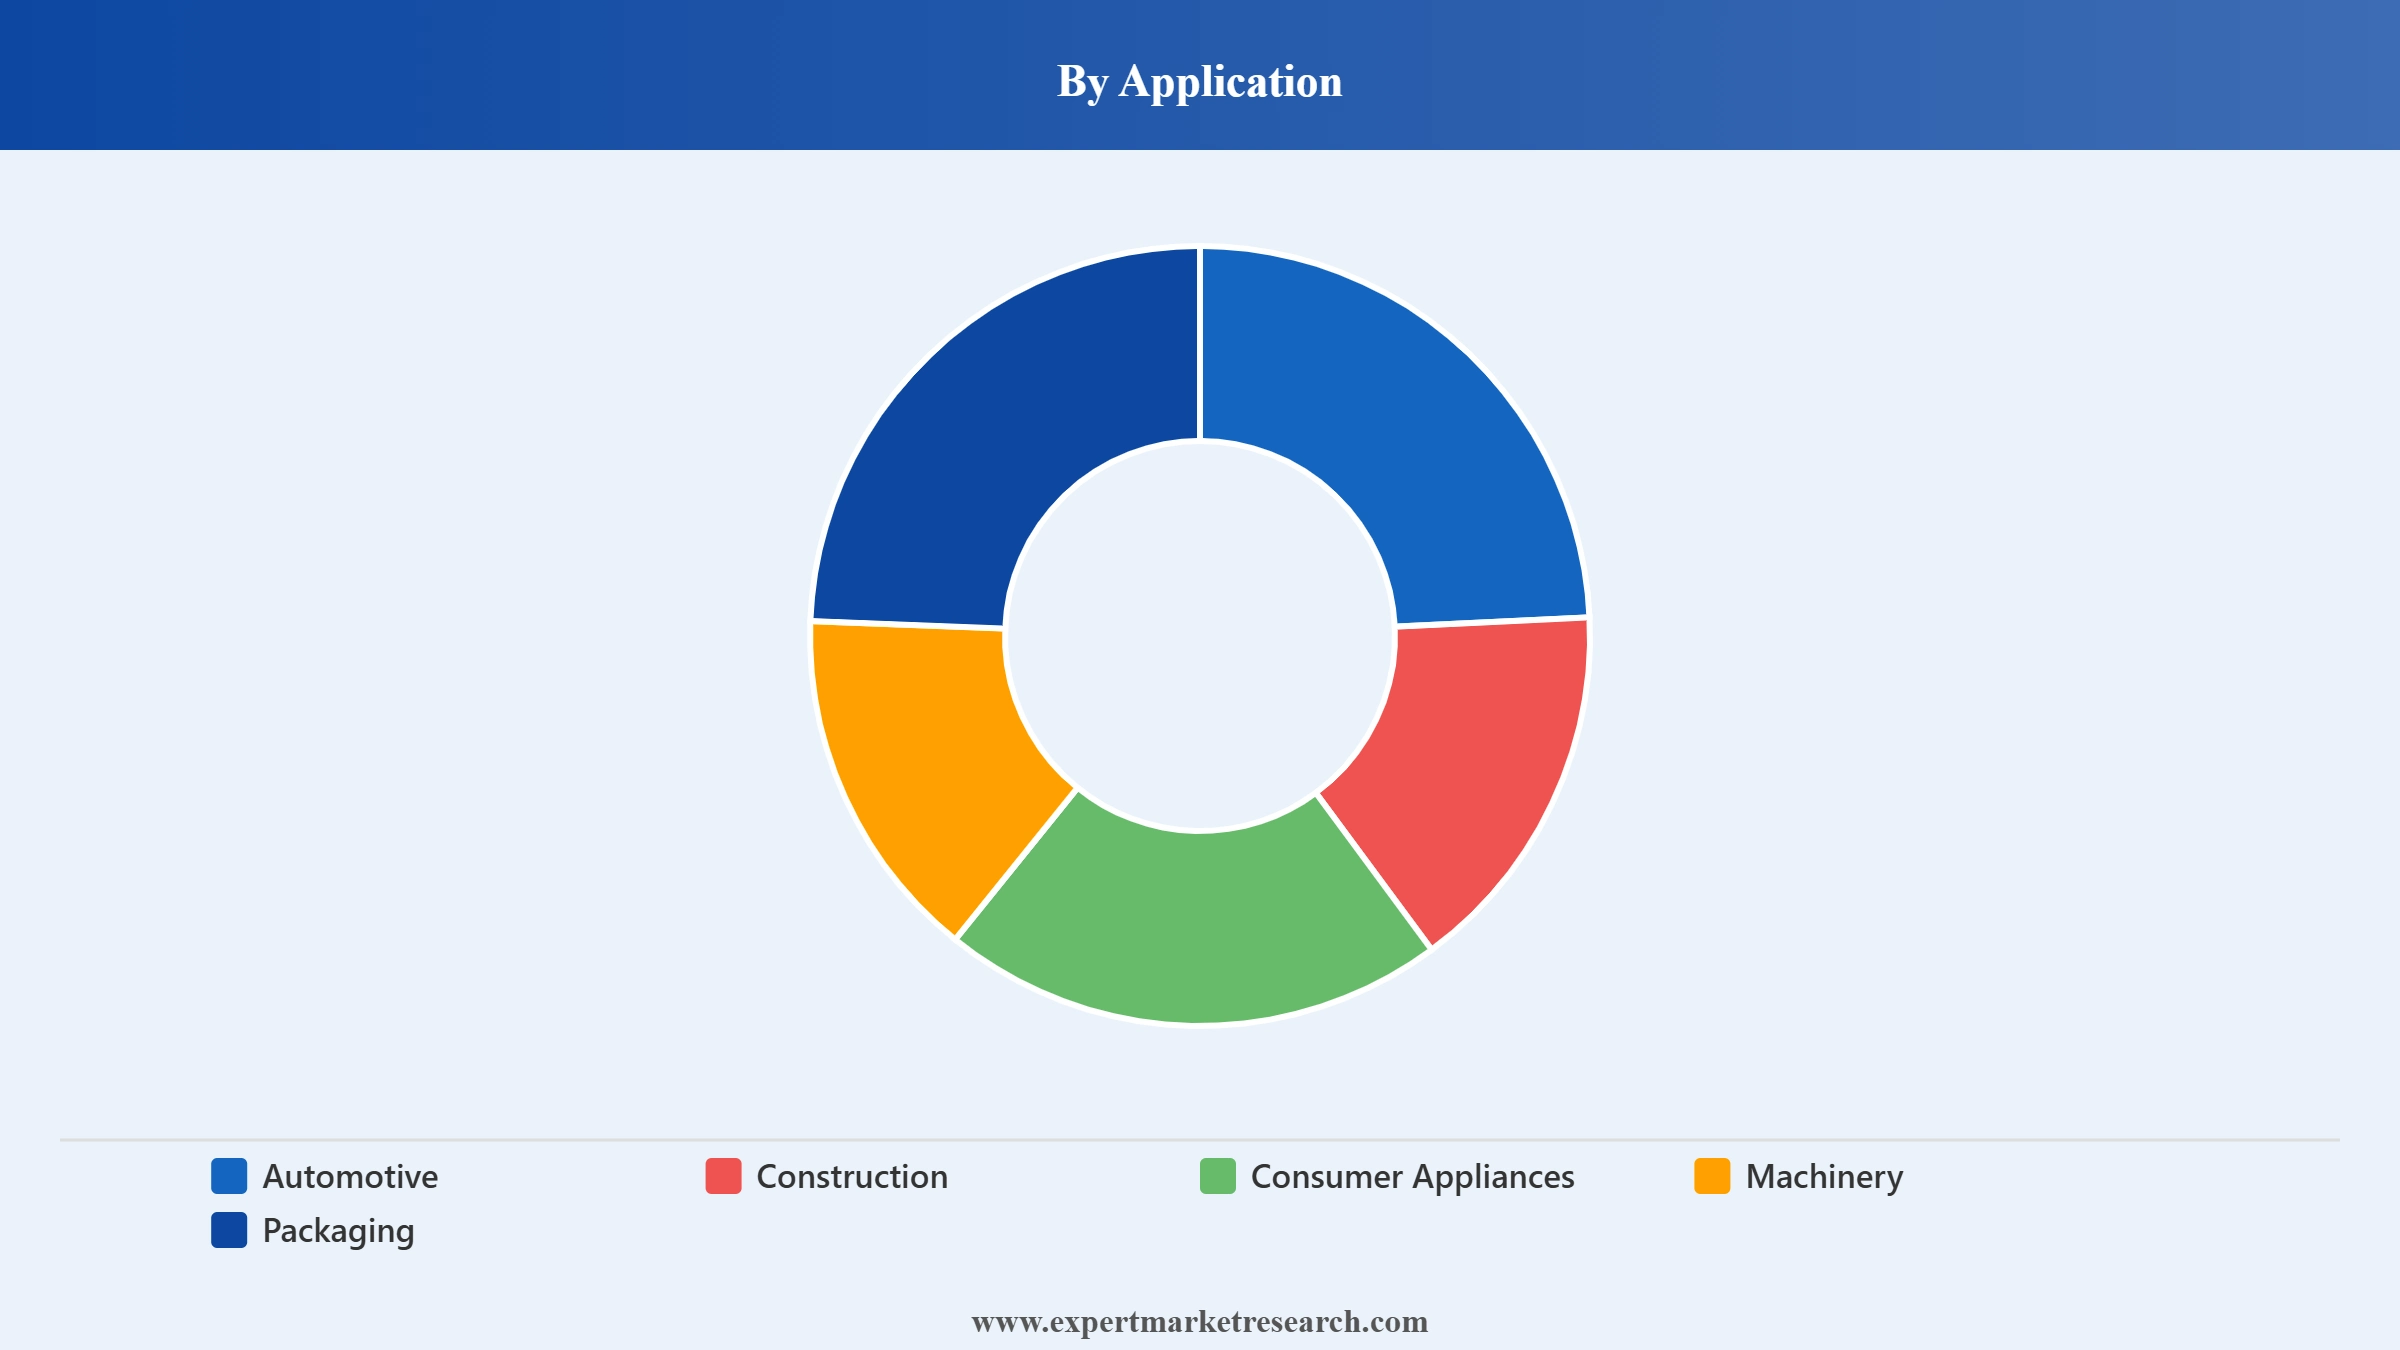
Key Insight: Automotive accounts for the largest share of the cold rolled coil steel market by application, given sustained vehicle production and reliance on cold rolled steel for body panels and structural components. Packaging is the fastest-growing application, driven by rising demand for lightweight steel containers and closures. Construction uses cold rolled steel for framing and cladding, while Consumer Appliances rely on it for durable housing and Machinery for equipment components. The Others category includes furniture and general manufacturing applications.
Market Breakup by Region
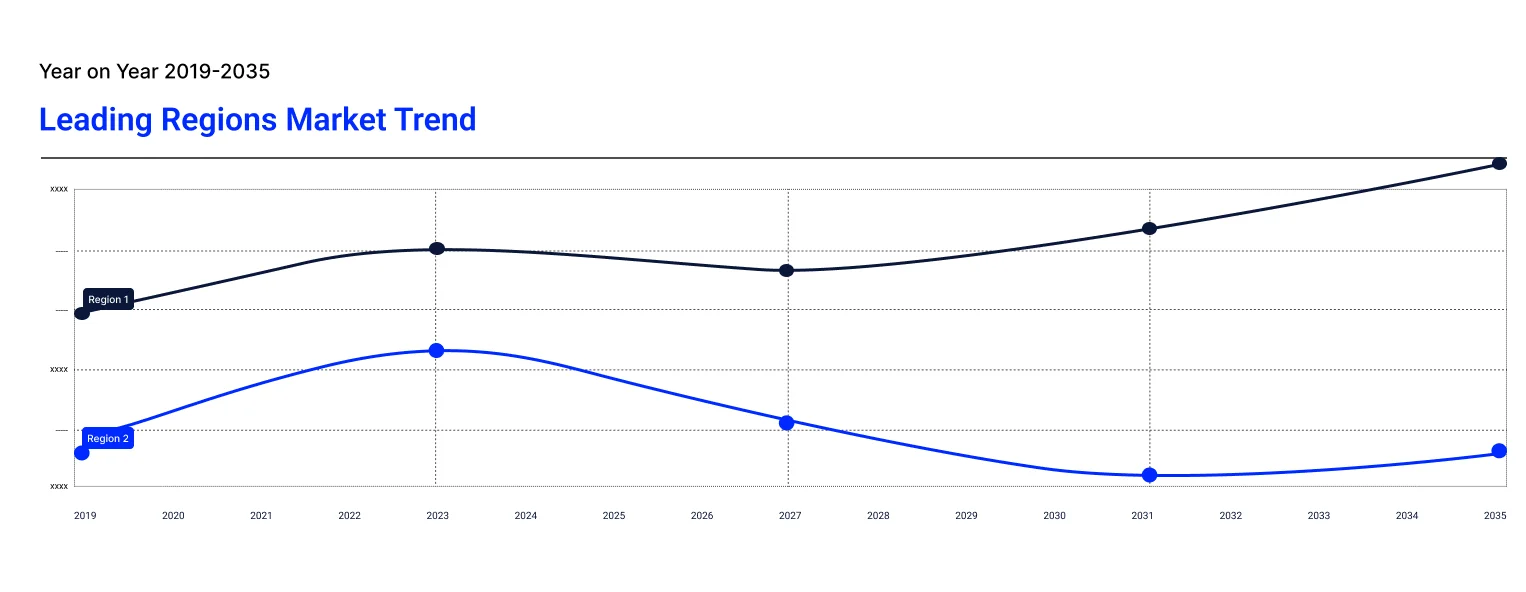
Key Insight: Asia Pacific dominates the cold rolled coil steel market, supported by massive automotive production, construction activity, and appliance manufacturing concentrated across China, Japan, India, and South Korea. Asia Pacific is also the fastest-growing region as new integrated mill capacity and joint venture investment continue expanding regional production. North America and Europe remain significant markets supported by established automotive and construction sectors. Latin America and the Middle East and Africa remain smaller markets tied to broader industrial and construction investment.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By product type, cold rolled sheets dominate the market due to their widespread use in automotive body panels and appliance manufacturing
Cold Rolled Sheets account for the largest share of the cold rolled coil steel market by product type, supported by widespread use in automotive body panels and appliance manufacturing requiring precise dimensions and smooth surface finish. This established use base continues to reinforce cold rolled sheets as the reference product form for most automotive and appliance customers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Cold Rolled Coils are the fastest-growing product type as continuous processing lines increasingly favour coil form for automated downstream cutting, stamping, and coating operations across expanding manufacturing capacity. In January 2026, Benxi Steel's cold rolling plant achieved stable production of 0.8 millimetre thin gauge CP980 ultra-high-strength steel coil, replacing previously imported material in domestic automotive component manufacturing.
By grade, low carbon steel dominates the market due to its superior formability and weldability for automotive and construction applications
Low Carbon Steel accounts for the largest share of the cold rolled coil steel market by grade, reflecting its superior formability and weldability for automotive body panels, appliance housing, and general construction applications. Continued reliance on low carbon grades across most automotive and appliance manufacturing programmes continues to reinforce this segment's leading position today.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
High Carbon Steel is the fastest-growing grade as demand rises for wear resistant and higher strength applications including machinery components and specialty tooling. As of April 2026, Beijing Shougang has targeted capturing 25 percent of China's premium electrical steel market by 2026, reallocating production away from lower margin commodity grades toward higher margin specialty steel to capture growing new energy vehicle demand.
By application, automotive dominates the market due to sustained vehicle production and reliance for body panels and structural components
Automotive accounts for the largest share of the cold rolled coil steel market by application, driven by sustained vehicle production and the sector's reliance on cold rolled steel for body panels, structural components, and battery enclosures. In April 2025, Kobe Steel's Kobenable Steel, a low carbon dioxide blast furnace steel product, was selected for use in Isuzu light-duty trucks, reflecting growing automotive demand for lower emission cold rolled steel grades.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Packaging is the fastest-growing application as demand for lightweight, precisely formed steel containers and closures continues to expand across food, beverage, and industrial packaging customers. This shift continues to broaden the addressable customer base for cold rolled steel producers beyond traditional automotive and construction demand.
Asia Pacific dominates the market due to automotive, construction, and appliance manufacturing concentration
Asia Pacific dominates the cold rolled coil steel market, supported by massive automotive production, construction activity, and appliance manufacturing concentrated across China, Japan, India, and South Korea and their broader supplier ecosystems today. New capacity is also emerging outside traditional hubs, with Algeria's Tosyali Algerie completing its first export shipment of cold rolled steel from its new Bethioua complex in September 2026, extending Mediterranean and African market reach.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is also the fastest-growing region as new integrated mill capacity and joint venture investment continue expanding regional production across several key national markets pursuing manufacturing sector growth. Rising regional automotive and appliance investment continues to create new opportunities for both established and emerging cold rolled coil steel producers across the region.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
3.2% |
|
Europe |
3.0% |
|
Asia Pacific |
4.1% |
|
Latin America |
3.6% |
|
Middle East and Africa |
3.8% |
The global cold rolled coil steel companies feature a moderately consolidated competitive structure led by established integrated steel producers with broad product portfolios spanning multiple grades and finishing lines. Manufacturers including ArcelorMittal and POSCO are competing primarily through joint venture expansion and advanced automotive steel capability, while producers including Tata Steel and Nucor differentiate through domestic market depth and specialised value-added product lines.
Leading cold rolled coil steel market players are focusing on expanding advanced high strength steel capacity to meet automotive lightweighting demand, pursuing joint ventures to enter high growth regional markets, and modernising existing rolling lines to improve surface quality and cleanliness. Increasing investment in electrical steel capacity and continued navigation of shifting trade policy are also shaping capacity and pricing decisions across the industry.
ArcelorMittal S.A., founded in 2006 and headquartered in Luxembourg City, Luxembourg, is the world's second largest steel producer, offering a broad flat and long steel product portfolio spanning automotive, construction, and industrial applications. The company continues to expand advanced high strength steel capacity through joint venture operations including ArcelorMittal Nippon Steel India, supporting growing regional demand for automotive grade cold rolled steel.
POSCO Holdings Inc., founded in 1968 and headquartered in Pohang, South Korea, is a leading global steel producer known for advanced automotive steel grades and integrated steelmaking capability spanning ironmaking through cold rolling and galvanizing. The company continues to pursue international joint ventures to expand its integrated production footprint into high growth regional markets beyond its established South Korean operations.
Tata Steel Limited, founded in 1907 and headquartered in Mumbai, India, is one of the world's leading steel producers, operating an extensive integrated value chain spanning raw materials through finished automotive, construction, and appliance grade steel products. The company continues to expand and modernise its cold rolling complexes across India, strengthening value added product capabilities for domestic and export automotive customers.
Nucor Corporation, founded in 1940 and headquartered in Charlotte, North Carolina, United States, is North America's largest steel producer and recycler, operating an extensive network of electric arc furnace mini mills across multiple states. The company continues to invest in low embodied carbon steel production and value added flat rolled coating capacity, serving automotive, construction, and appliance customers across the United States.
Other key players in the market report include Nippon Steel Corporation, China Baowu Steel Group Corporation Limited, JFE Steel Corporation, United States Steel Corporation, and ThyssenKrupp AG, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the cold rolled coil steel market 2026-2035 with our in-depth report. Gain strategic insights, future forecasts, and key market developments that can help you stay competitive. Download a free sample report or contact our team for customised consultation on the market trends 2026.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the cold rolled coil steel market reached an approximate value of USD 180000.00 Million.
The market is projected to grow at a CAGR of 3.50% between 2026 and 2035.
The key players in the market include ArcelorMittal S.A., Nippon Steel Corporation, POSCO Holdings Inc., China Baowu Steel Group Corporation Limited, JFE Steel Corporation, Tata Steel Limited, United States Steel Corporation, Nucor Corporation, and ThyssenKrupp AG, among others.
Leading manufacturers are focusing on expanding advanced high strength steel capacity, pursuing joint ventures to enter high growth regional markets, and modernising existing rolling lines to improve surface quality.
Key challenges include volatile raw material and energy costs, shifting import tariffs and trade policy, and intense price competition among a large number of established global producers.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Product Type |
|
|
Breakup by Grade |
|
|
Breakup by Application |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




