

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
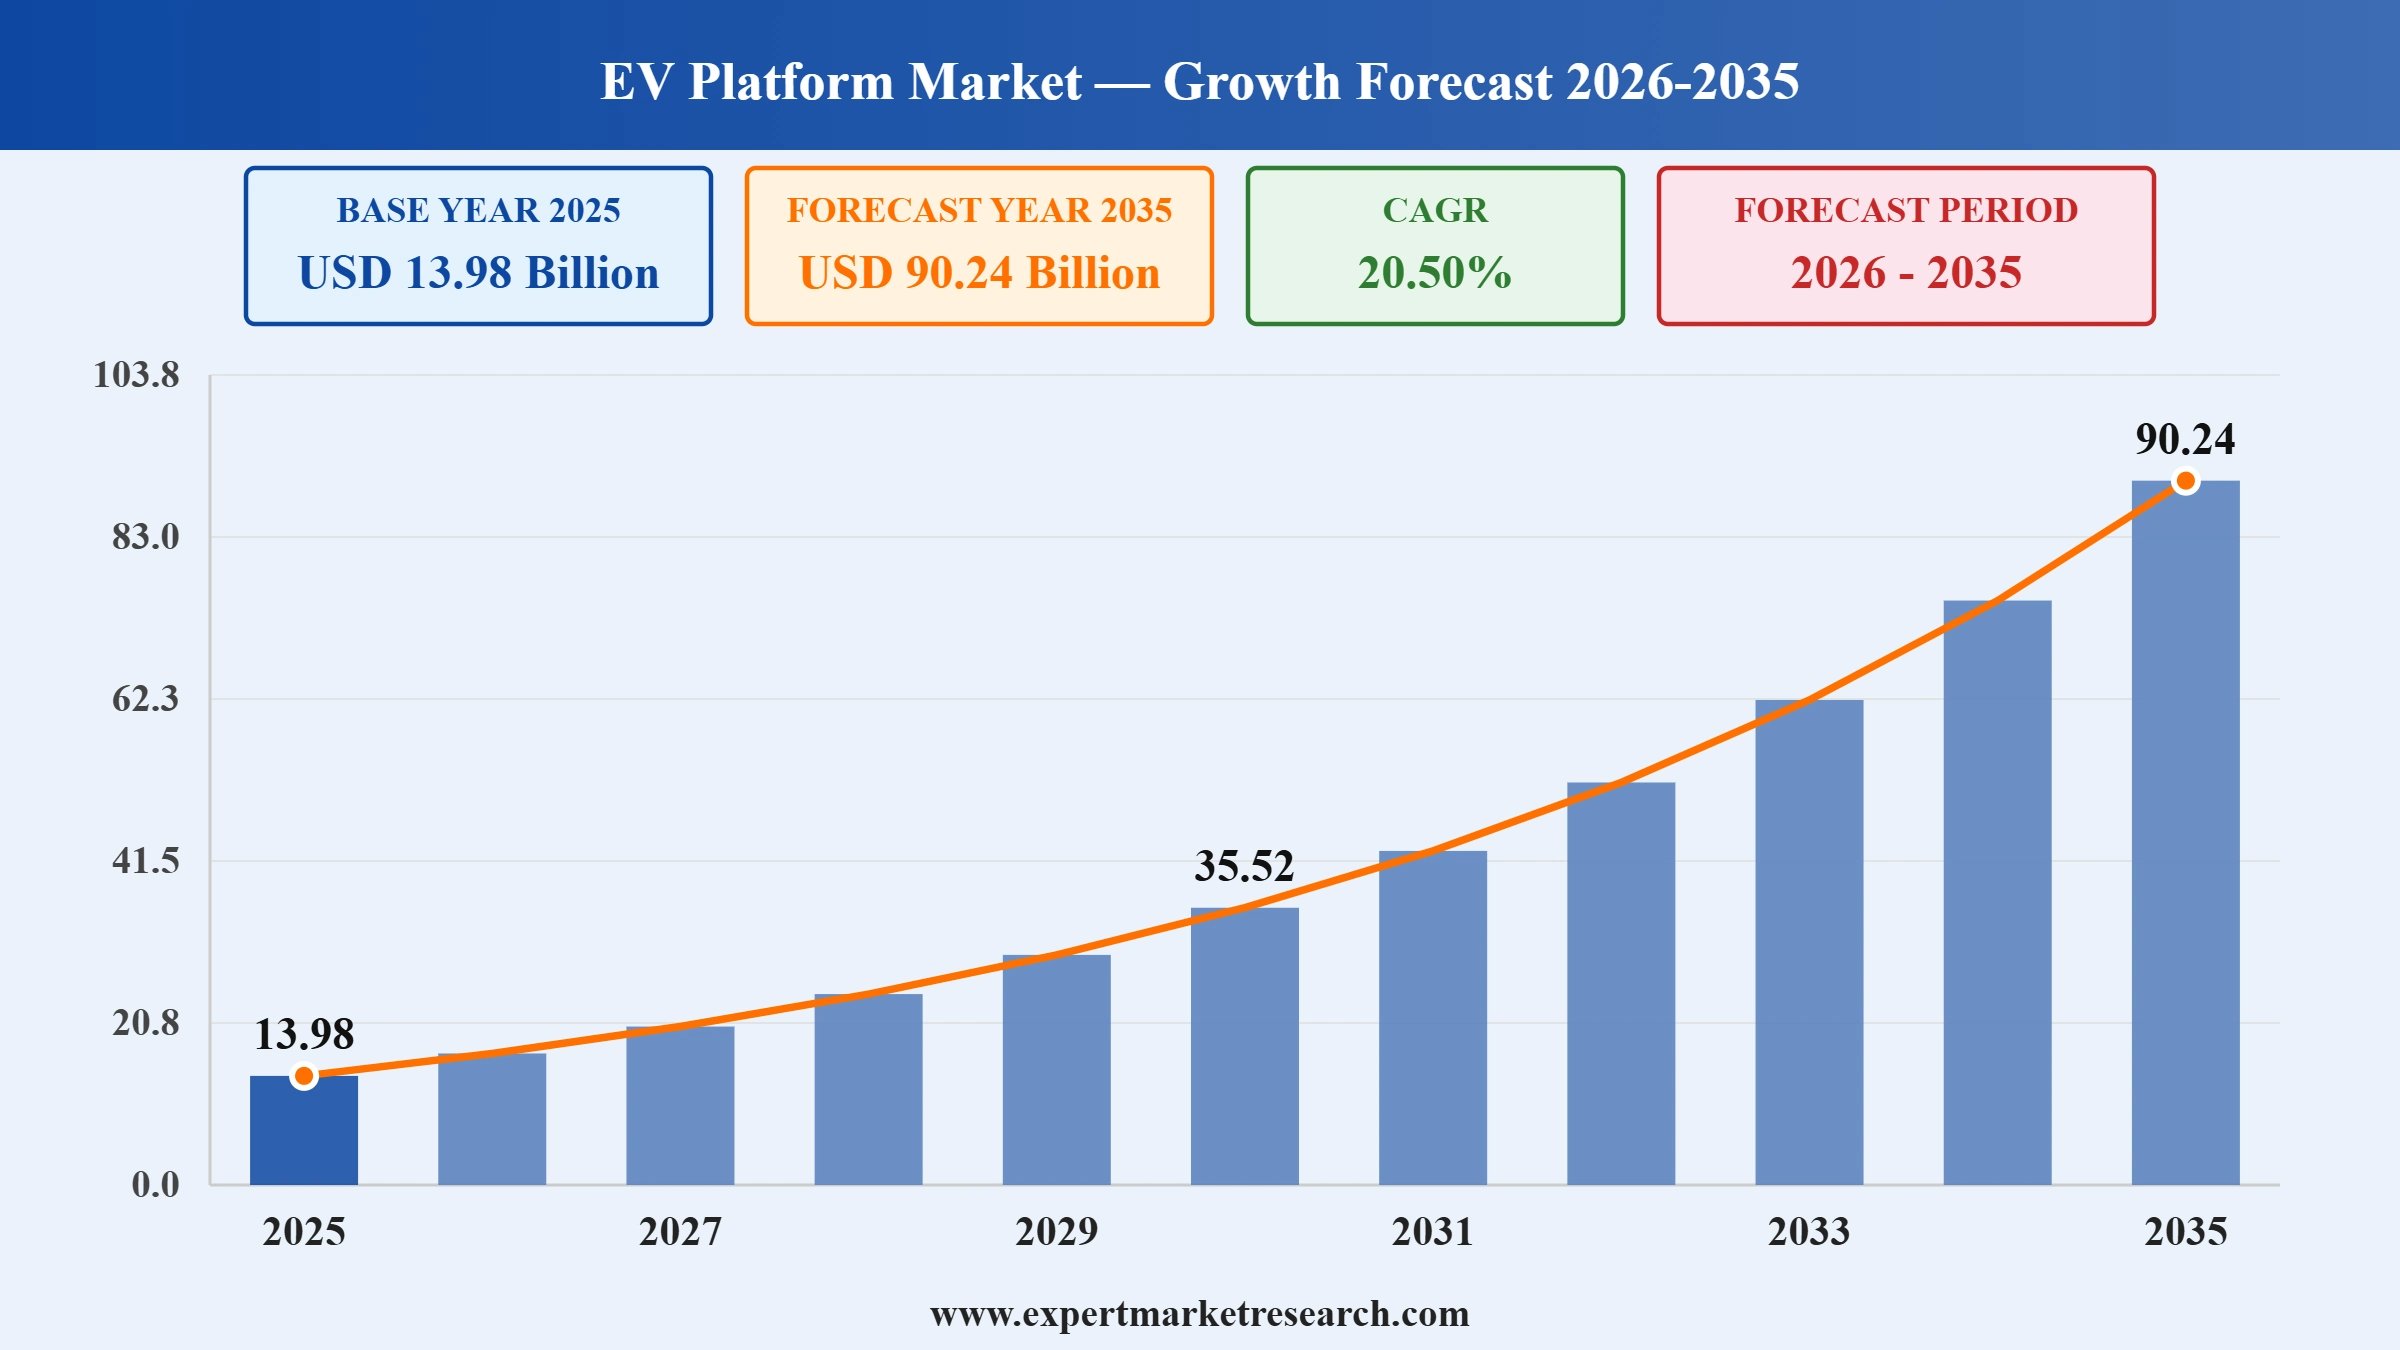
The global EV platform market attained a value of USD 13.98 Billion in 2025 and is projected to expand at a CAGR of 20.50% through 2035. The market is further expected to achieve USD 90.24 Billion by 2035. Rising global electric vehicle adoption, increasing government emission regulations, and growing automaker demand for modular, scalable vehicle architectures continue to support development of suspension, motor, battery, and chassis platforms across hybrid, plug-in hybrid, and battery electric vehicle types.
Rising global electric vehicle adoption continues to anchor steady demand across the EV platform market, as automakers accelerate the shift from conventional internal combustion architectures toward dedicated, purpose-built electric vehicle platforms. Manufacturers are also investing in modular, shared architectures, reflecting the industry's ongoing pursuit of reduced development costs and faster model launch cycles across multiple vehicle segments. In March 2026, Ford announced a 5 billion dollar investment in its Universal Electric Vehicle platform, aiming to reduce battery size and parts count to deliver a next-generation EV priced around 30,000 dollars.
The EV platform market is witnessing further developments as established automakers confirm next-generation modular architectures spanning multiple vehicle types and powertrains. Hyundai Motor Group signalled a major architectural shift, confirming plans for a next-generation platform capable of supporting electric, extended-range, and hybrid variants across its full family of brands. This shift toward multi-brand, multi-powertrain architecture is concentrated among manufacturers with sufficient engineering scale to support shared platform development, while smaller specialists continue to compete on niche vehicle segments.
In addition, established manufacturers are increasingly pursuing platform standardisation strategies that consolidate motor, controller, and chassis elements into unified frameworks, reflecting the industry's recognition that reducing component count and simplifying assembly increasingly determines manufacturing cost competitiveness. Such platform standardisation activity is reshaping competitive positioning across the wider EV platform market as manufacturers with proven modular architecture platforms increasingly differentiate themselves from competitors still reliant on model-specific engineering.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| Global EV Platform Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 13.98 |
| Market Size 2035 | USD Billion | 90.24 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 20.50% |
| CAGR 2026-2035 - Market by Region | Europe | 22.5% |
| CAGR 2026-2035 - Market by Country | India | 22.4% |
| CAGR 2026-2035 - Market by Country | Germany | 21.6% |
| CAGR 2026-2035 - Market by Vehicle Type | Battery Electric Vehicle | 23.1% |
| CAGR 2026-2035 - Market by Component | Batteries | 23.4% |
| Market Share by Country 2025 | Canada | 3.4% |
Hyundai Motor Group confirmed a successor Integrated Modular Architecture intended to underpin a wide range of future battery electric, extended-range electric, and hybrid vehicles across its Hyundai, Kia, and Genesis brands. Companies can design multi-powertrain architectures supporting battery electric, extended-range, and hybrid variants simultaneously to hedge against uncertain regional electrification timelines.
Hyundai filed a comprehensive patent for a modular body-on-frame electric vehicle architecture designed to support a new generation of rugged, long-range pickups, integrating the battery pack as a structural frame component. Companies can integrate battery packs as load-bearing structural elements to maximise energy density while preserving the durability requirements of body-on-frame vehicle segments.
Industry analysis found that BYD's platform standardisation strategy, consolidating motor, controller, and chassis elements into a unified framework, has enabled production lines to switch between different vehicle models with relative ease. Companies can consolidate core electric vehicle elements into single modular frameworks to reduce parts count and enable flexible production line switching across multiple models.
Hyundai's upcoming Elexio model was spotted testing on the same 400-volt architecture used by its existing EV5 platform, supporting DC fast charging rates of up to 140 kilowatts depending on battery configuration. Companies can extend proven shared architectures across multiple new model launches to accelerate time-to-market while maintaining consistent charging and performance specifications.
Established automakers continue confirming multi-brand modular architecture strategies spanning multiple powertrain types. In June 2026, Hyundai Motor Group confirmed a successor architecture intended to underpin battery electric, extended-range, and hybrid vehicles across multiple brand divisions within the EV platform market. Such multi-brand architecture strategies reflect automakers' recognition that shared platform development across brand divisions increasingly delivers stronger engineering economies of scale than brand-isolated development.
Manufacturers continue extending modular electric vehicle architectures into previously underserved vehicle segments. In May 2026, Hyundai revealed a patent for a dedicated body-on-frame architecture designed specifically for rugged, long-range pickup applications, departing from its existing unibody platform lineup. Such segment extension reflects manufacturers' recognition that dedicated, purpose-built architectures increasingly outperform adapted crossover platforms for demanding truck and off-road applications.
Platform standardisation continues reducing manufacturing complexity as automakers consolidate core vehicle elements into unified frameworks. Industry analysis published in May 2026 found that leading manufacturers' standardised platform strategies have enabled production lines to switch between different vehicle models with substantially reduced retooling. Such standardisation reflects the sector's recognition that consolidating motor, controller, and chassis elements into shared frameworks increasingly determines manufacturing cost competitiveness across high-volume vehicle production.
Automakers continue extending proven shared electric vehicle architectures across successive new model launches to accelerate development timelines. In April 2026, Hyundai's upcoming Elexio model was confirmed testing on the same charging architecture used by an existing platform sibling, supporting consistent fast-charging specifications. Such architecture reuse reflects automakers' recognition that extending validated platforms across new models reduces both engineering risk and time-to-market compared with developing entirely new architectures.
Diversified automotive groups continue to apply engineering and manufacturing research developed across their broader vehicle portfolios to increasingly sophisticated EV platform development. Established multi-brand automotive manufacturers continue to develop electric vehicle architectures drawing on broader internal combustion, hybrid, and commercial vehicle engineering research spanning multiple product categories beyond dedicated EV platforms alone. Such cross-portfolio research investment gives diversified automotive groups a technical foundation that narrower EV-only specialists must build through more limited, platform-specific development. In 2025, Volkswagen deployed a zonal electrical and electronic architecture jointly developed with XPENG across both its EV and internal combustion models produced locally in China, applying shared engineering research across powertrain types.
This Expert Market Research Report titled "EV Platform Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Component
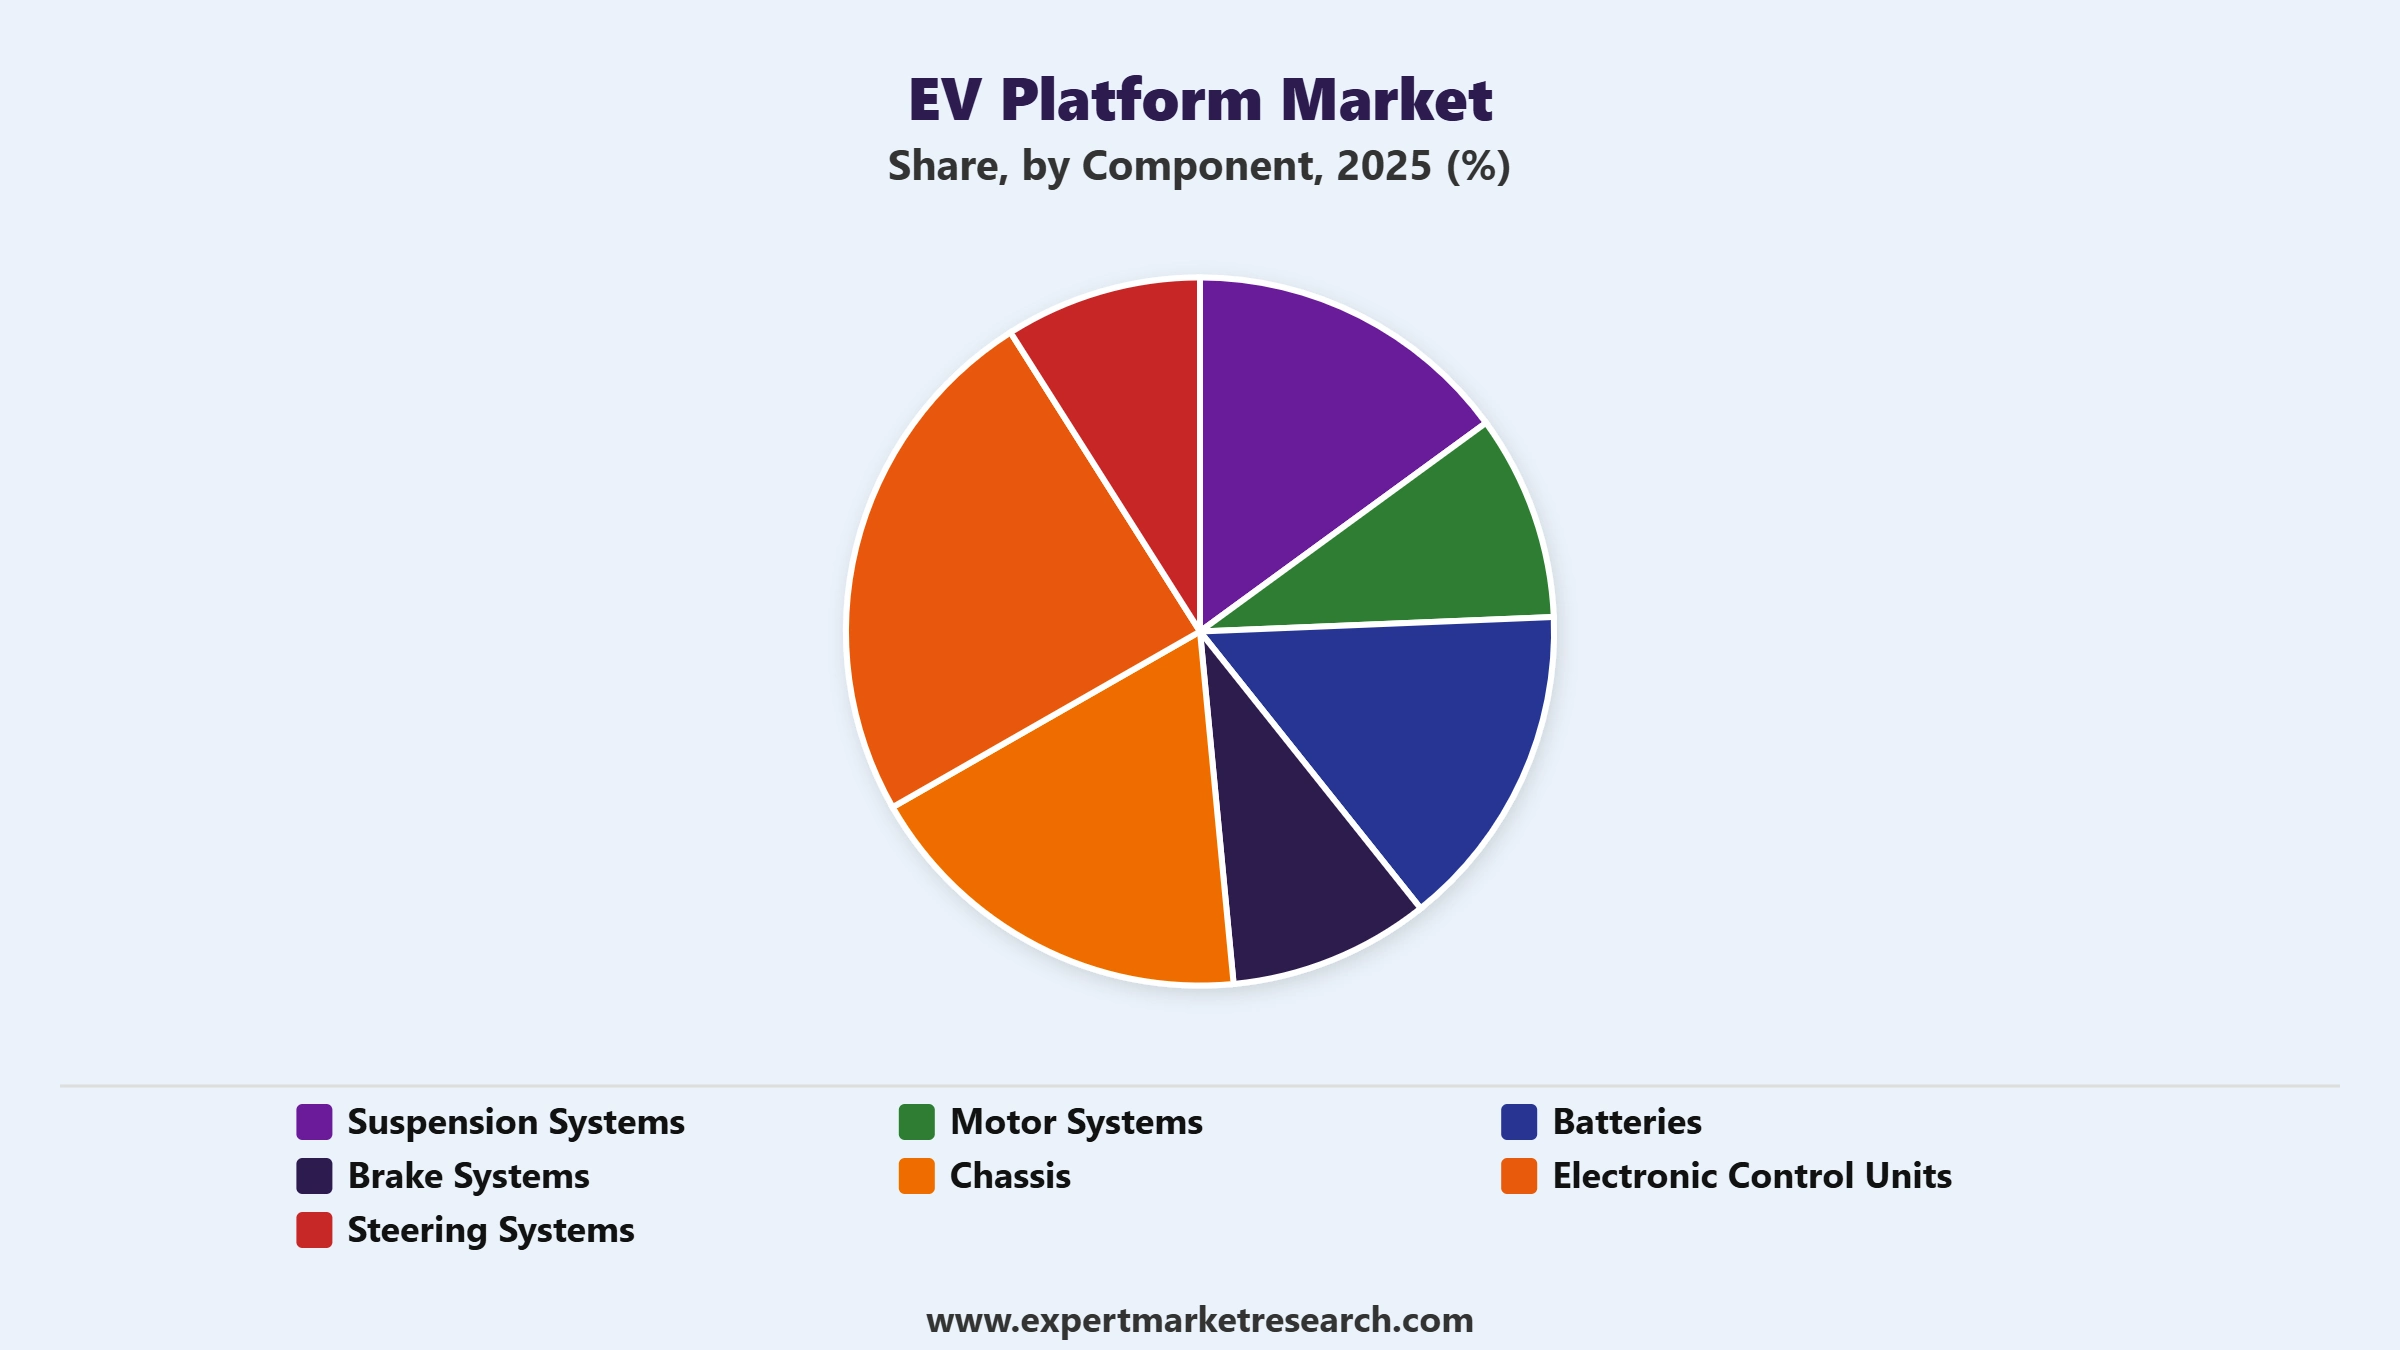
Key Insight: Batteries account for the largest share of the EV platform market, reflecting their foundational role in determining electric vehicle range, performance, and overall platform architecture. Steering Systems is growing at the fastest pace as automakers increasingly integrate advanced steer-by-wire and autonomous-ready systems, illustrated by Hyundai's June 2026 Integrated Modular Architecture spanning multiple future vehicle generations. Motor Systems convert stored battery energy into mechanical output, with output density and efficiency remaining key differentiators between platform designs. Suspension Systems are increasingly re-engineered around battery pack placement, balancing ride comfort against the added structural weight of large battery arrays. Brake Systems on electric platforms integrate regenerative braking with conventional friction braking, requiring more sophisticated control software than combustion-engine equivalents. Chassis architecture increasingly serves as the structural foundation for skateboard-style platforms shared across multiple vehicle models. Electronic Control Units coordinate the growing number of software-defined vehicle functions, from battery management to driver assistance systems.
Market Breakup by Electric Vehicle Type
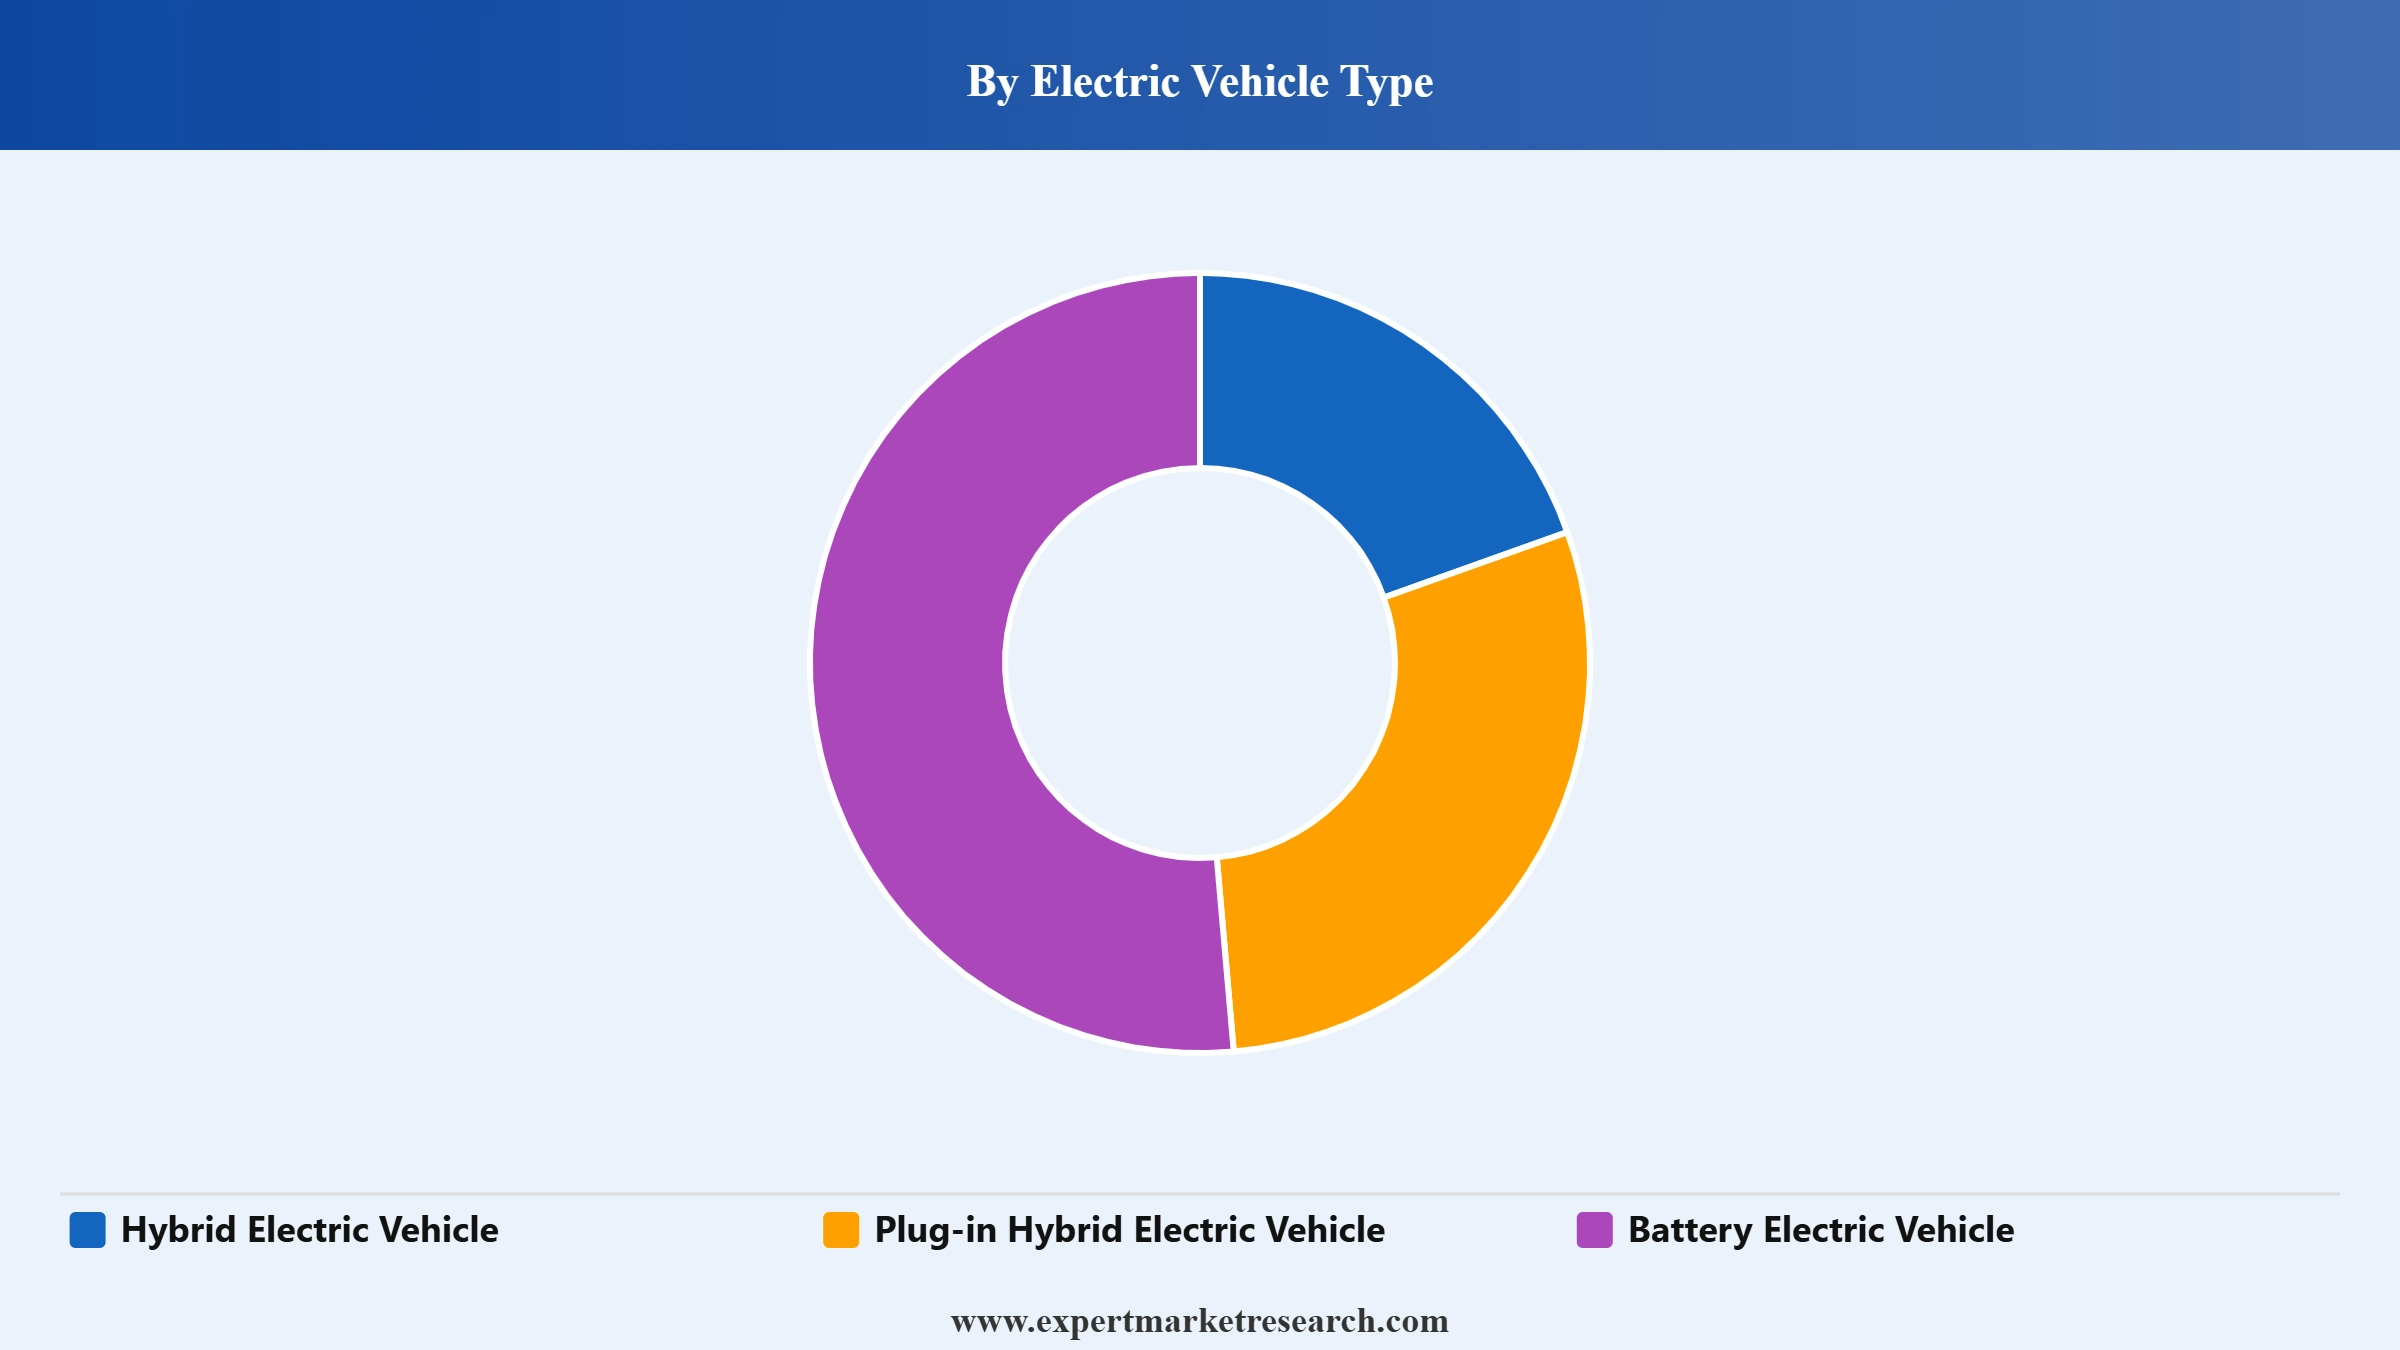
Key Insight: Battery Electric Vehicle accounts for the largest share of the EV platform market, reflecting automakers' increasing focus on fully electric powertrains supported by larger battery packs and longer driving ranges. In July 2026, BYD delivered 557,090 battery electric vehicles in the second quarter, outpacing Tesla's global deliveries by roughly 16 percent as international export volumes continued expanding. Hybrid Electric Vehicle platforms continue to serve consumers seeking fuel efficiency gains without full dependence on charging infrastructure. Plug-in Hybrid Electric Vehicle platforms bridge the gap further, offering meaningful electric-only range while retaining a combustion engine for longer journeys, supported by rising fuel efficiency standards and government incentives.
Market Breakup by Vehicle Type
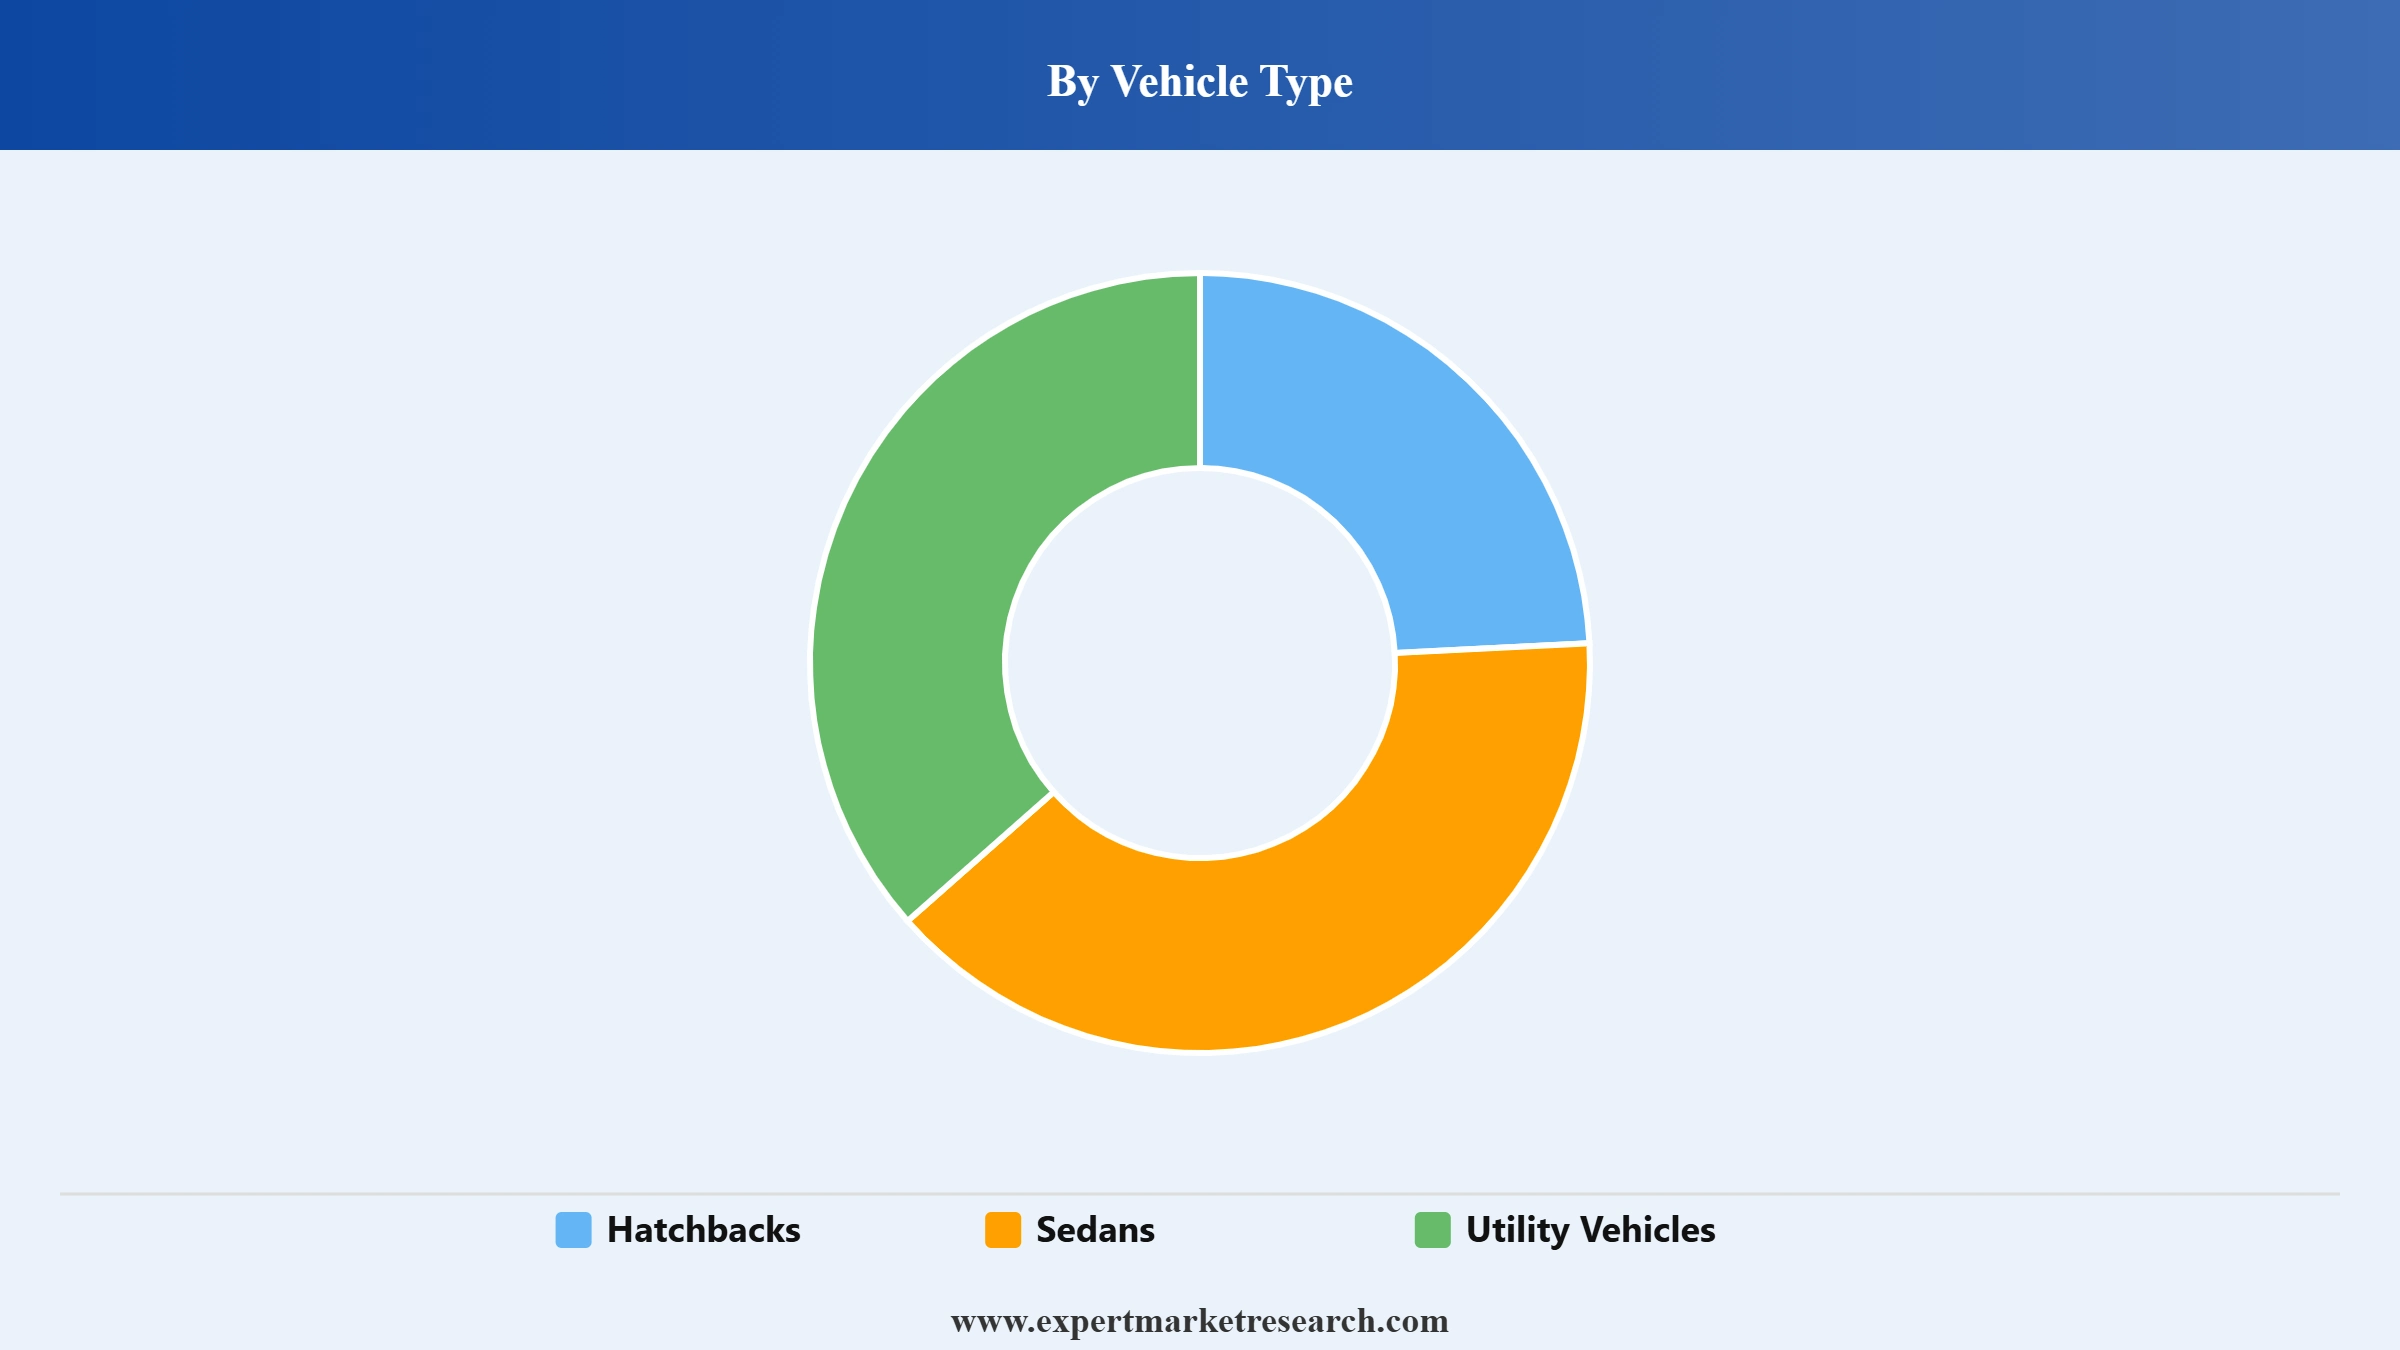
Key Insight: Utility Vehicles account for the largest share of the EV platform market, reflecting strong consumer preference for SUV and crossover body styles across major electric vehicle markets. Sedans continue to represent substantial demand given their established position across both passenger and premium electric vehicle segments, while Hatchbacks serve compact and urban mobility requirements, illustrated by Hyundai's development of dedicated entry-level electric hatchback platforms.
Market Breakup by Region
Key Insight: Asia Pacific accounts for the largest share of the EV platform market, supported by the region's concentrated electric vehicle manufacturing base spanning China, Japan, and South Korea. North America is emerging as a key growth market as domestic automakers develop dedicated body-on-frame and truck-focused electric platforms to compete in the region's high-value pickup segment. Europe, Latin America, and the Middle East and Africa each continue to serve distinct regional electrification policy and adoption patterns.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By component, batteries lead the market while steering systems grows fastest given rising steer-by-wire adoption
Batteries continue to account for the largest share of the market, reflecting their foundational role in determining electric vehicle range, performance, and overall platform architecture. Established battery supply relationships continue to anchor steady demand as automakers maintain proven cell and pack vendors across successive platform generations. Reporting in January 2026 confirmed that Tesla abandoned its structural 4680 battery pack approach for the Model Y after manufacturing challenges, though the design remains in use for the Cybertruck.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Steering Systems is growing at the fastest pace across the EV platform market as automakers increasingly integrate advanced steer-by-wire systems designed to support both current driver-operated vehicles and future autonomous-ready architectures. In April 2026, Mercedes-Benz confirmed steer-by-wire technology for its facelifted EQS sedan, becoming the first German automaker to bring the fully electronic steering system to production.
By electric vehicle type, battery electric vehicle leads the market while battery electric vehicle continues strengthening its lead given falling battery costs
Battery Electric Vehicle continues to account for the largest share of the market, reflecting automakers' increasing focus on fully electric powertrains supported by larger battery packs and longer driving ranges. Established battery electric vehicle platform relationships continue to anchor steady demand as automakers maintain proven architectures across successive model generations.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Hybrid Electric Vehicle demand continues to persist across the EV platform market as markets with developing charging infrastructure or consumer range concerns maintain steady appetite for transitional powertrain options ahead of full battery electric adoption. Toyota confirmed plans in 2026 to introduce four additional dedicated electric crossover models, targeting annual EV sales of 200,000 units as the automaker accelerates its historically cautious electrification pace.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By vehicle type, utility vehicles lead the market while hatchbacks grows fastest given rising demand for affordable compact EVs
Utility Vehicles continue to account for the largest share of the market, reflecting strong consumer preference for SUV and crossover body styles across major electric vehicle markets. As of 2026, Tesla's Model Y remains the best-selling EV in the United States, with an estimated 163,454 units sold, illustrating sustained demand for electric utility vehicle platforms.
Hatchbacks is growing at the fastest pace across the EV platform market as automakers increasingly develop dedicated, entry-level compact electric platforms to broaden affordability and capture urban mobility demand.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific commands the largest share of the market through its concentrated EV manufacturing base
Asia Pacific holds the largest share of the EV platform market, supported by the region's concentrated electric vehicle manufacturing base spanning China, Japan, and South Korea. Regional manufacturers continue to benefit from government subsidies and favourable electrification policies supporting sustained platform development investment.
North America is emerging as a key growth market as domestic and international automakers develop dedicated body-on-frame and truck-focused electric platforms to compete in the region's high-value pickup segment. In May 2026, Hyundai revealed patent filings for a dedicated North American truck platform, reinforcing the region's growing importance for specialised electric vehicle architecture development.
The global industry is moderately consolidated, with EV platform market companies ranging from diversified global automakers spanning multiple vehicle categories to specialist electric vehicle platform developers competing across component, electric vehicle type, and vehicle type segments. Established players operate across the full EV platform value chain, from battery and motor system design through complete chassis, suspension, and electronic control unit integration for passenger and commercial vehicle applications.
Competitive dynamics among EV platform players are increasingly shaped by the pace of multi-brand modular architecture development, the scale of platform standardisation strategy, and the race to extend proven architectures into new vehicle segments such as trucks and utility vehicles. Manufacturers are investing in steer-by-wire systems, structural battery integration, and shared charging architectures to differentiate their offering and secure long-term platform development efficiency.
Founded in 2003 and headquartered in Austin, Texas, United States, Tesla designs and manufactures dedicated battery electric vehicle platforms spanning its passenger vehicle lineup. The company serves consumers and commercial customers seeking purpose-built electric architectures rather than adapted internal combustion platforms. Tesla's vertically integrated battery and software development differentiates its offering from competitors reliant on external component suppliers.
Founded in 1995 and headquartered in Shenzhen, China, BYD designs and manufactures electric vehicle platforms including its e-Platform 3.0 architecture, consolidating motor, controller, and chassis elements into a unified framework. The company serves both domestic Chinese and expanding international markets including Latin America and Southeast Asia. BYD's vertically integrated battery manufacturing, including its Blade battery technology, differentiates its offering from competitors reliant on third-party cell suppliers.
Founded in 1967 and headquartered in Seoul, South Korea, Hyundai designs and manufactures electric vehicle platforms including its E-GMP architecture, shared across its Hyundai, Kia, and Genesis brands. In June 2026, the company confirmed a successor Integrated Modular Architecture spanning battery electric, extended-range, and hybrid powertrains. Hyundai's multi-brand shared platform strategy differentiates its offering from competitors developing architectures for a single brand alone.
Founded in 1908 and headquartered in Detroit, Michigan, United States, General Motors designs and manufactures electric vehicle platforms including its Ultium architecture, supporting multiple vehicle segments across its brand portfolio. The company serves passenger and commercial customers across North America and international markets. General Motors' extensive existing manufacturing footprint and dealer network differentiate its offering from newer, less established electric vehicle competitors.
Other key players in the EV platform market include Nissan Motor Co., Ltd., Mahindra & Mahindra Limited, Volkswagen AG, Open Motors, and REE Automotive Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our EV platform market trends 2026 report. Discover regional growth patterns, component and vehicle type trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 13.98 Billion.
The market is estimated to grow at a CAGR of 20.50% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach about USD 90.24 Billion by 2035.
Confirming multi-brand modular architectures spanning multiple powertrain types, extending proven platforms into new vehicle segments such as trucks, and pursuing platform standardisation strategies that consolidate core components into unified, cost-efficient frameworks.
The implementation of policies and regulations for carbon emission control and the increasing consumer interest towards EVs due to reduced environmental impact are some of the major trends in the market.
The market is broken down into North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa.
The different vehicle types considered in the market report are hatchbacks, sedans, and utility vehicles.
The market's key players are Nissan Motor Co., Ltd., Mahindra & Mahindra Limited, General Motors, Hyundai Motor Company, Volkswagen AG, Tesla Group, BYD Company Ltd., Open Motors, and REE Automotive Ltd., among others.
Based on the components, the market is divided into suspension systems, motor systems, batteries, brake systems, chassis, electronic control units, and steering systems.
Automakers face high upfront engineering investment required for dedicated platform development, underdeveloped charging infrastructure limiting adoption in certain regions, and the technical complexity of designing architectures flexible enough to support multiple powertrain types and vehicle segments.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Component |
|
| Breakup by Electric Vehicle Type |
|
| Breakup by Vehicle Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




