

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The hafnium market was valued at USD 430.00 Million in 2025. The market is expected to grow at a CAGR of 6.20% during the forecast period of 2026-2035 to reach a value of USD 784.72 Million by 2035. Sustained demand from nuclear reactor control rods, aerospace superalloys, and semiconductor high-k dielectric applications, combined with a structurally constrained byproduct supply chain, are collectively driving value growth in the hafnium market worldwide.
The current hafnium market dynamics reflect a persistently tight supply chain, as hafnium remains a byproduct of nuclear grade zirconium refining rather than a directly mined commodity, leaving output constrained by zirconium demand rather than hafnium demand itself. This structural constraint has kept spot prices elevated through 2025 and 2026, with buyers across nuclear, aerospace, and semiconductor end markets competing for a limited pool of high purity material. In May 2025, Executive Order 14301 directed the Department of Energy to overhaul federal reactor testing procedures, accelerating advanced reactor demonstrations that continue to sustain long term domestic zirconium and hafnium demand across the United States nuclear supply chain.
The overall hafnium industry through 2026 continues to be shaped by geopolitical supply risk, as the metal's status as a byproduct of nuclear grade zirconium refining leaves Western buyers structurally dependent on a small number of producing countries for high purity material. Producers and downstream customers are simultaneously navigating this constrained landscape, with governments and manufacturers increasingly prioritising supply chain diversification and strategic stockpiling to reduce exposure to any single source region. The Minor Metals Trade Association estimated in September 2025 that global effective capacity of aerospace and electronic grade hafnium stood at no more than 140 to 150 tonnes, against nonmilitary demand of roughly 130 tonnes, underscoring how little spare capacity the market carries.
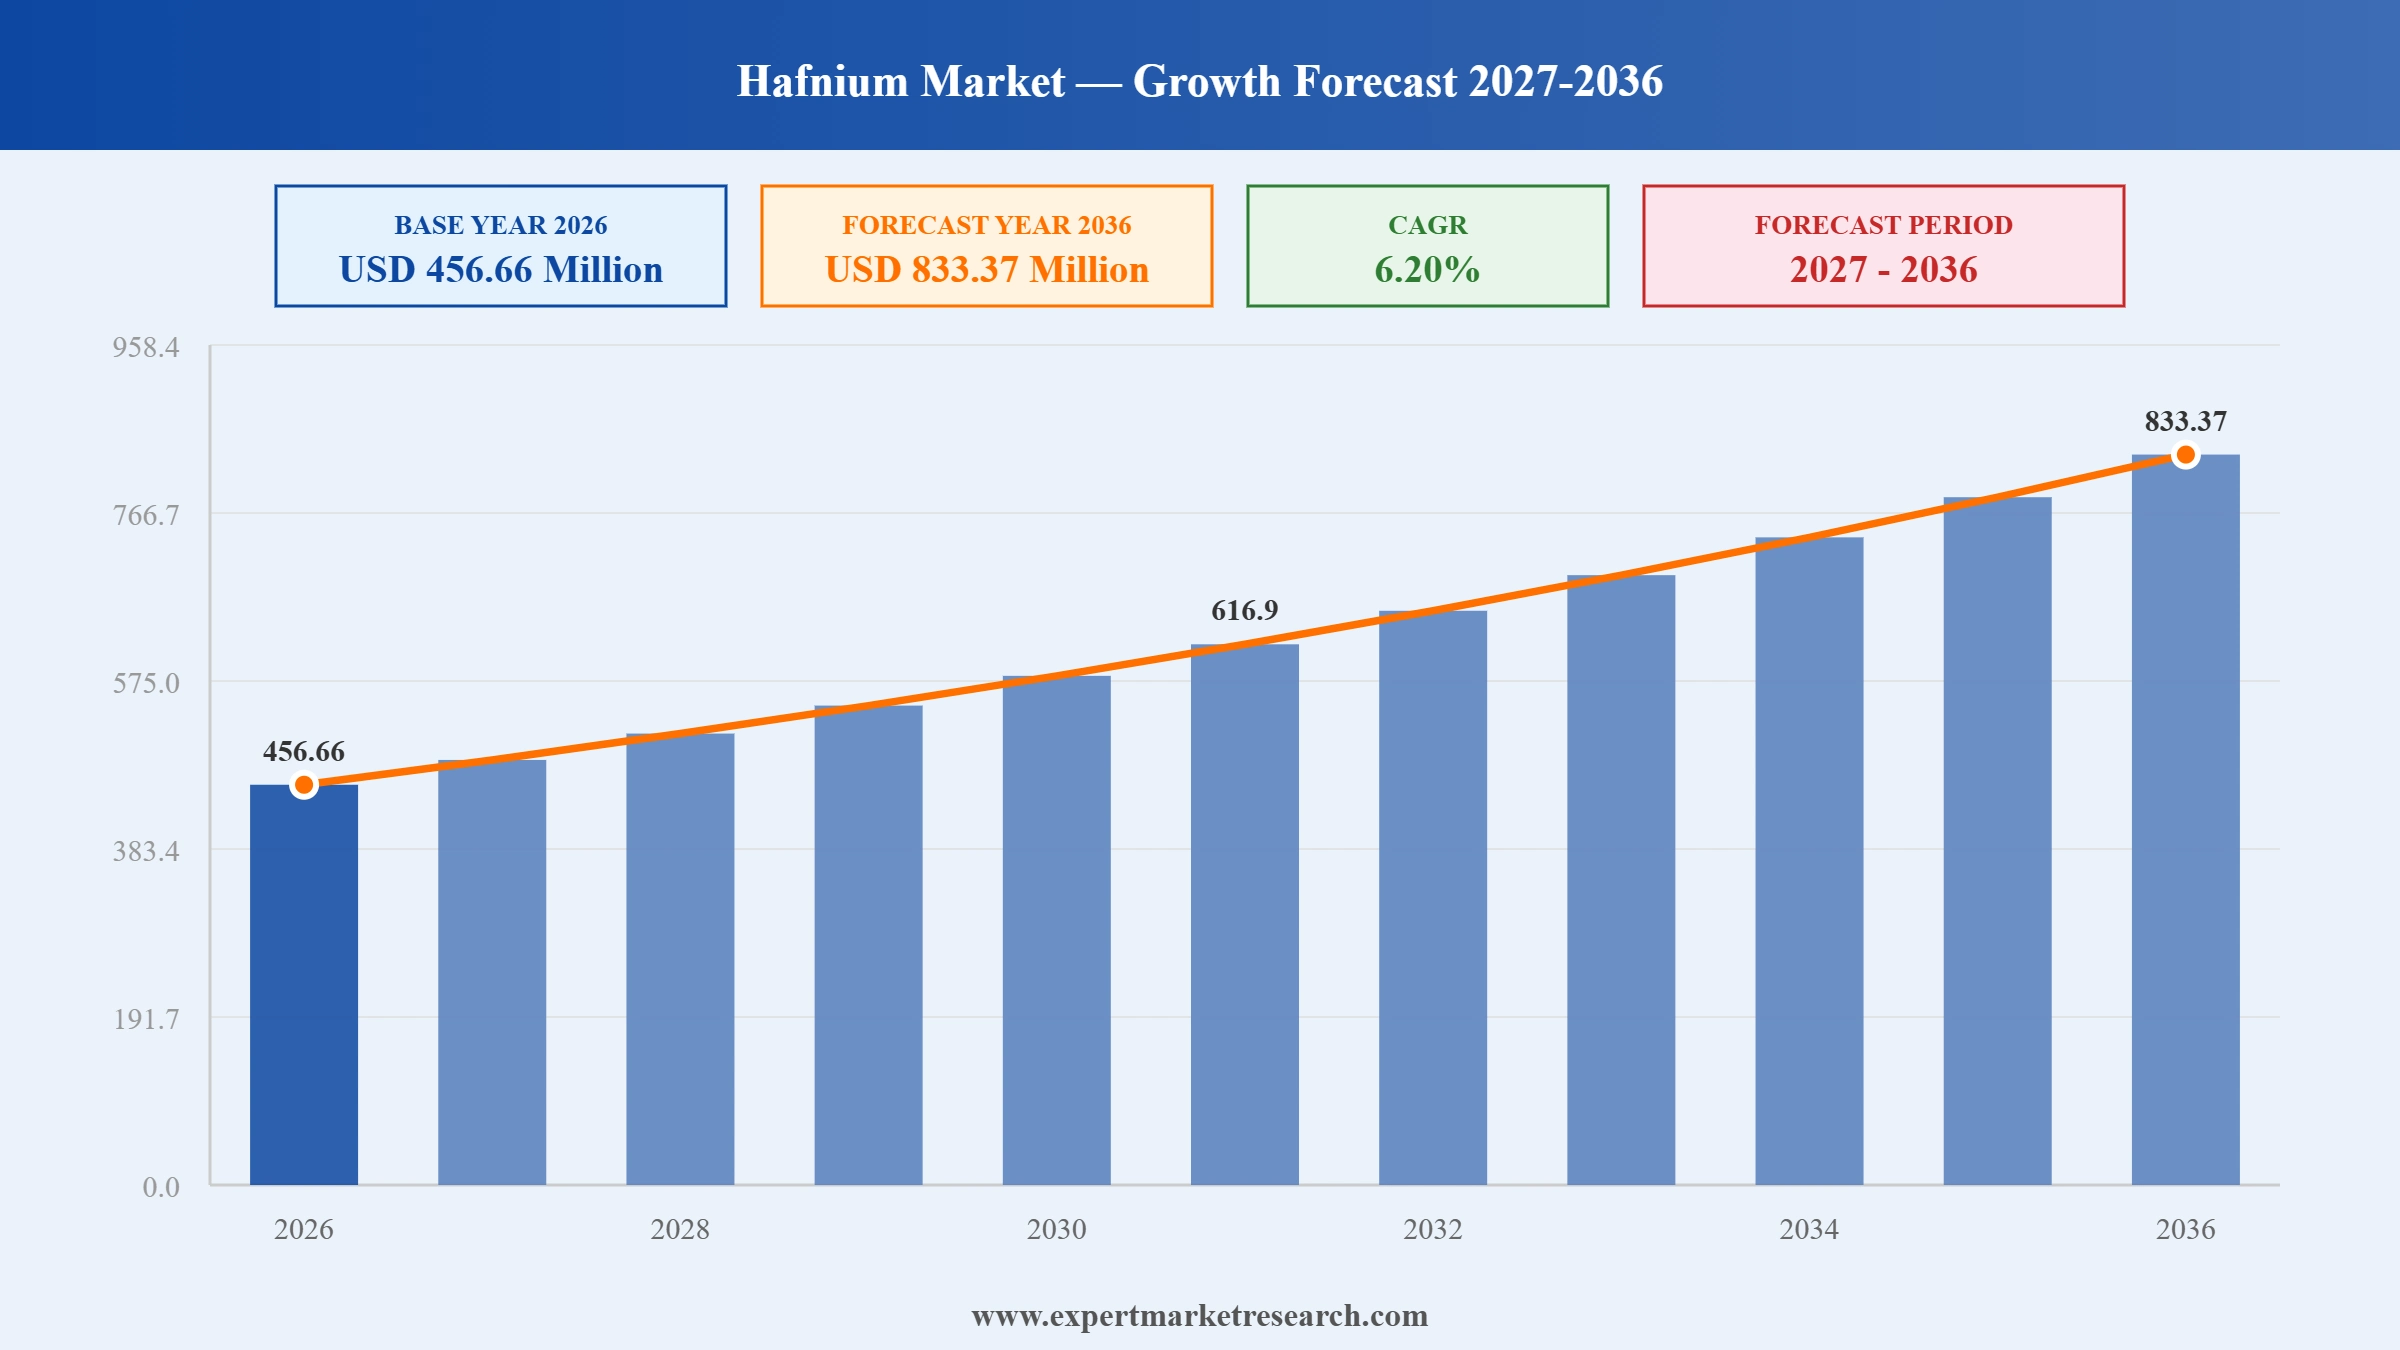
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
|
Hafnium Market Report Summary |
Description |
Value |
|
Base Year |
USD Million |
2025 |
|
Historical Period |
USD Million |
2019-2025 |
|
Forecast Period |
USD Million |
2026-2035 |
|
Market Size 2025 |
USD Million |
430.00 |
|
Market Size 2035 |
USD Million |
784.72 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
6.20% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
6.8% |
|
CAGR 2026-2035 - Market by Product Type |
Hafnium Oxide |
6.9% |
|
CAGR 2026-2035 - Market by Application |
Semiconductor and Electronics |
7.1% |
|
2025 Market Share by Region |
North America |
38.6% |
The hafnium market is being reshaped by tightening Chinese export controls, growing Western efforts to diversify byproduct supply sources, and rising defense and semiconductor sector investment amid persistently elevated spot prices. Producers and downstream customers alike are increasingly prioritising long term supply agreements and strategic stockpiling to manage the structural constraint of a market where output remains tied to zirconium refining capacity rather than direct hafnium demand.
Amaero announced a collaboration with Bechtel Plant Machinery, a Department of War prime contractor, and the United States Navy, receiving a production contract to supply zirconium and hafnium alloy components for the submarine industrial base. Alloy producers can treat this kind of partnership as a route into qualified defense supply chains difficult for newer entrants to access.
Critical Metals Corp highlighted the potential of its Tanbreez rare earth project in Greenland as a future Western hafnium source in May 2026, following project assays that identified consistent by-product hafnium alongside a 30-million-dollar acceleration programme. Developers across the hafnium market of polymetallic deposits can look to this kind of by-product characterisation as a low-cost route to diversifying hafnium supply outside China.
Materion Corporation confirmed in its fourth quarter 2025 results, reported in February 2026, that it had secured a 65-million-dollar investment from a major defense prime to expand critical materials capacity supporting United States inventory replenishment initiatives. Producers across the hafnium market serving defense customers can point to this prime backed investment as a template for securing capital in a supply constrained market.
Chinese customs data reported in November 2025 showed unwrought hafnium exports falling from 5,001 kilograms in January to just 499 kilograms in September, a decline of roughly 90 percent over nine months following tightened dual use export licensing. Downstream buyers navigating similarly concentrated supply chains can treat this as an early indicator of tightening availability before prices fully reflect it.
Hafnium producers across the hafnium market are increasingly prioritising investment in separation and refining capacity rather than new resource exploration, reflecting the reality that hafnium availability is constrained primarily by zirconium dehafniation capacity rather than by underlying mineral scarcity across most producing regions today overall too. In September 2026, GE Aerospace agreed to acquire Consolidated Precision Products for 11.75 billion dollars, targeting the superalloy investment casting bottleneck that has constrained hafnium alloyed turbine blade production across the wider jet engine supply chain and aftermarket.
Downstream customers across nuclear, aerospace, and semiconductor end markets in the hafnium market are increasingly pursuing longer term supply agreements with established hafnium producers rather than relying on spot purchases, reflecting concern over export volatility and the structural inability of hafnium supply to expand quickly against rising demand. In January 2026, Orano was selected by the United States Department of Energy to receive 900 million dollars toward a nearly 5-billion-dollar uranium enrichment facility, reinforcing the French nuclear group's broader supply chain presence.
Governments across Europe and Asia are increasingly formalising strategic stockpiling programmes for hafnium and related zirconium derivatives, reflecting growing recognition of the metal's role in nuclear reactor control rods, defense grade superalloys, and advanced semiconductor manufacturing where substitution options remain limited overall today across markets. In May 2025, India's Defence Minister inaugurated a titanium and superalloy materials plant at the Strategic Materials Technology Complex in Lucknow, supporting domestic production of the specialty alloys used across defense and aerospace applications nationwide.
Semiconductor manufacturers across the hafnium market are increasingly specifying tighter purity requirements for hafnium oxide used in high-k dielectric layers, reflecting the continued miniaturisation of logic chip architectures where even trace contamination can measurably affect transistor performance and yield across advanced fabrication processes overall today. In April 2026, SK trichem expanded its hafnium-based precursor supply to advanced DRAM manufacturing, diversifying an established supply relationship as memory makers increasingly favour hafnium over zirconium-based materials in scaled down capacitor architectures requiring higher dielectric constants.
Mining and materials companies across the hafnium market are increasingly evaluating hafnium recovery from polymetallic and rare earth deposits outside the traditional zirconium refining regions of France, the United States, Russia, and China, reflecting growing interest in diversifying the geographic concentration of global hafnium supply. In June 2026, Tosoh Corporation announced a complete halt to high-end zirconia powder shipments to China after Chinese export controls cut off its yttrium oxide supply, illustrating how tightly linked hafnium adjacent supply chains remain to broader trade policy.
The Expert Market Research's report titled “Hafnium Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
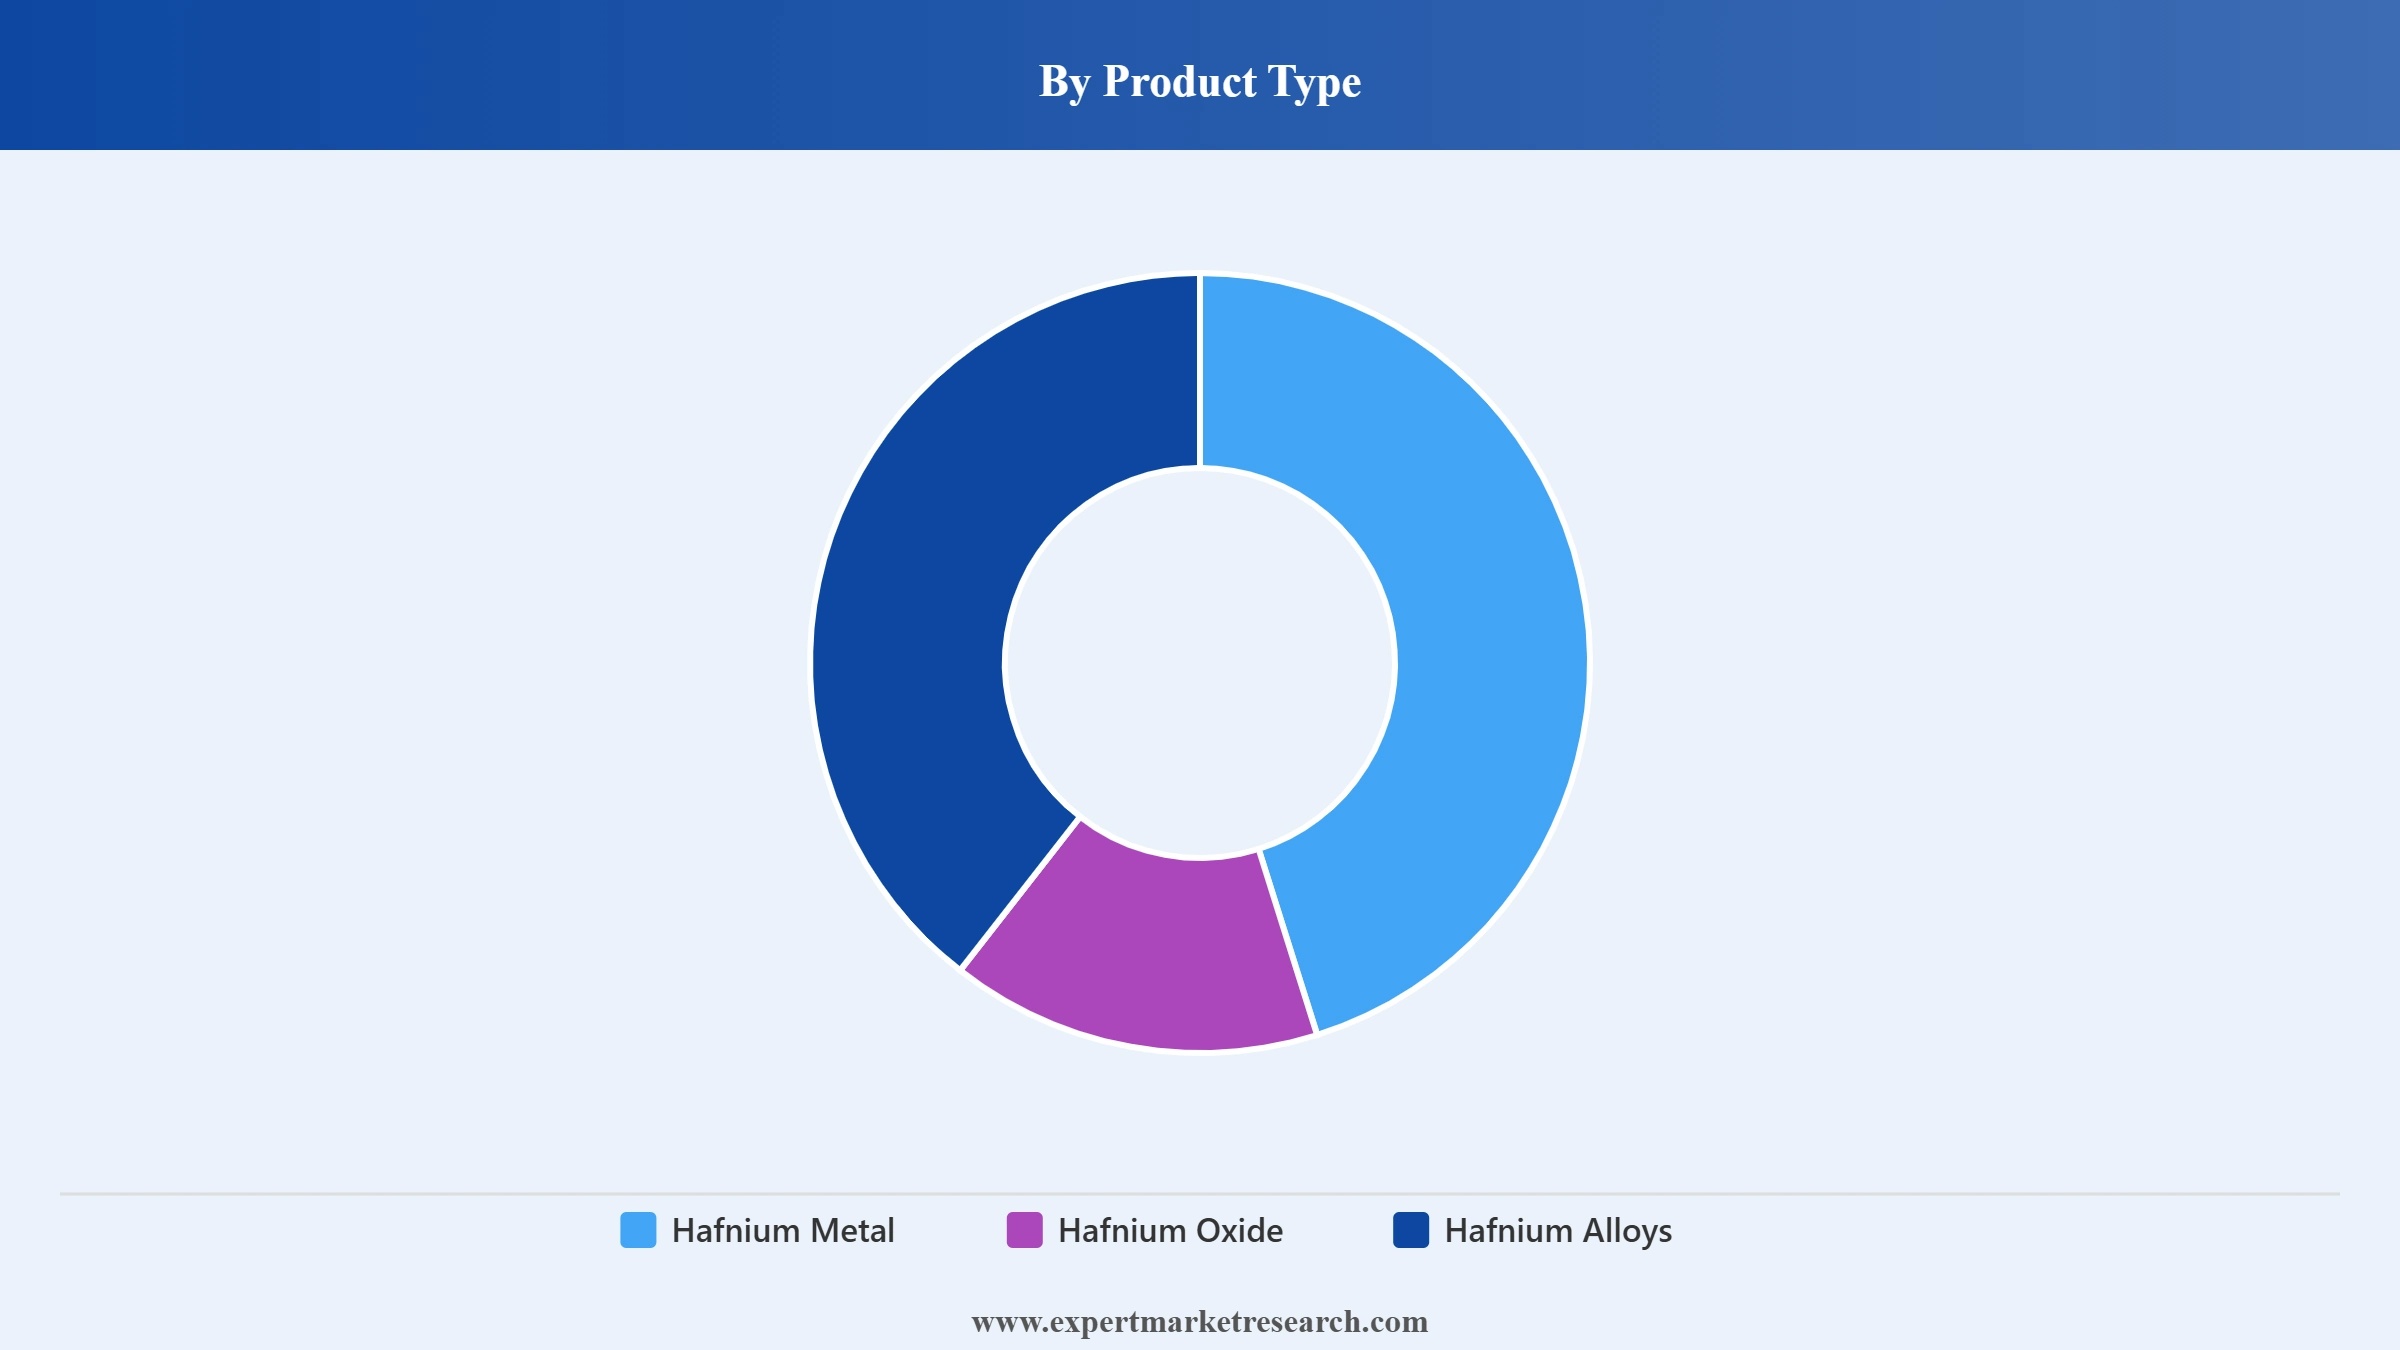
Key Insight: Hafnium Metal accounts for the largest share of the hafnium market by product type, valued for its exceptional neutron absorption, corrosion resistance, and high melting point across nuclear, aerospace, and industrial applications. USGS Mineral Commodity Summaries published in February 2026 confirmed Germany accounted for 68 percent of wrought hafnium exports in 2025, followed by China at 14 percent, underscoring the concentration of global refined hafnium metal trade. Hafnium Oxide is the fastest-growing product type as semiconductor manufacturers increasingly specify high purity grades for high-k dielectric layers in advanced logic chip architectures. Hafnium Alloys serve high temperature superalloy applications in jet engine and rocket components. The Others category includes hafnium carbide and specialty compounds for plasma cutting and coating applications.
Market Breakup by Application
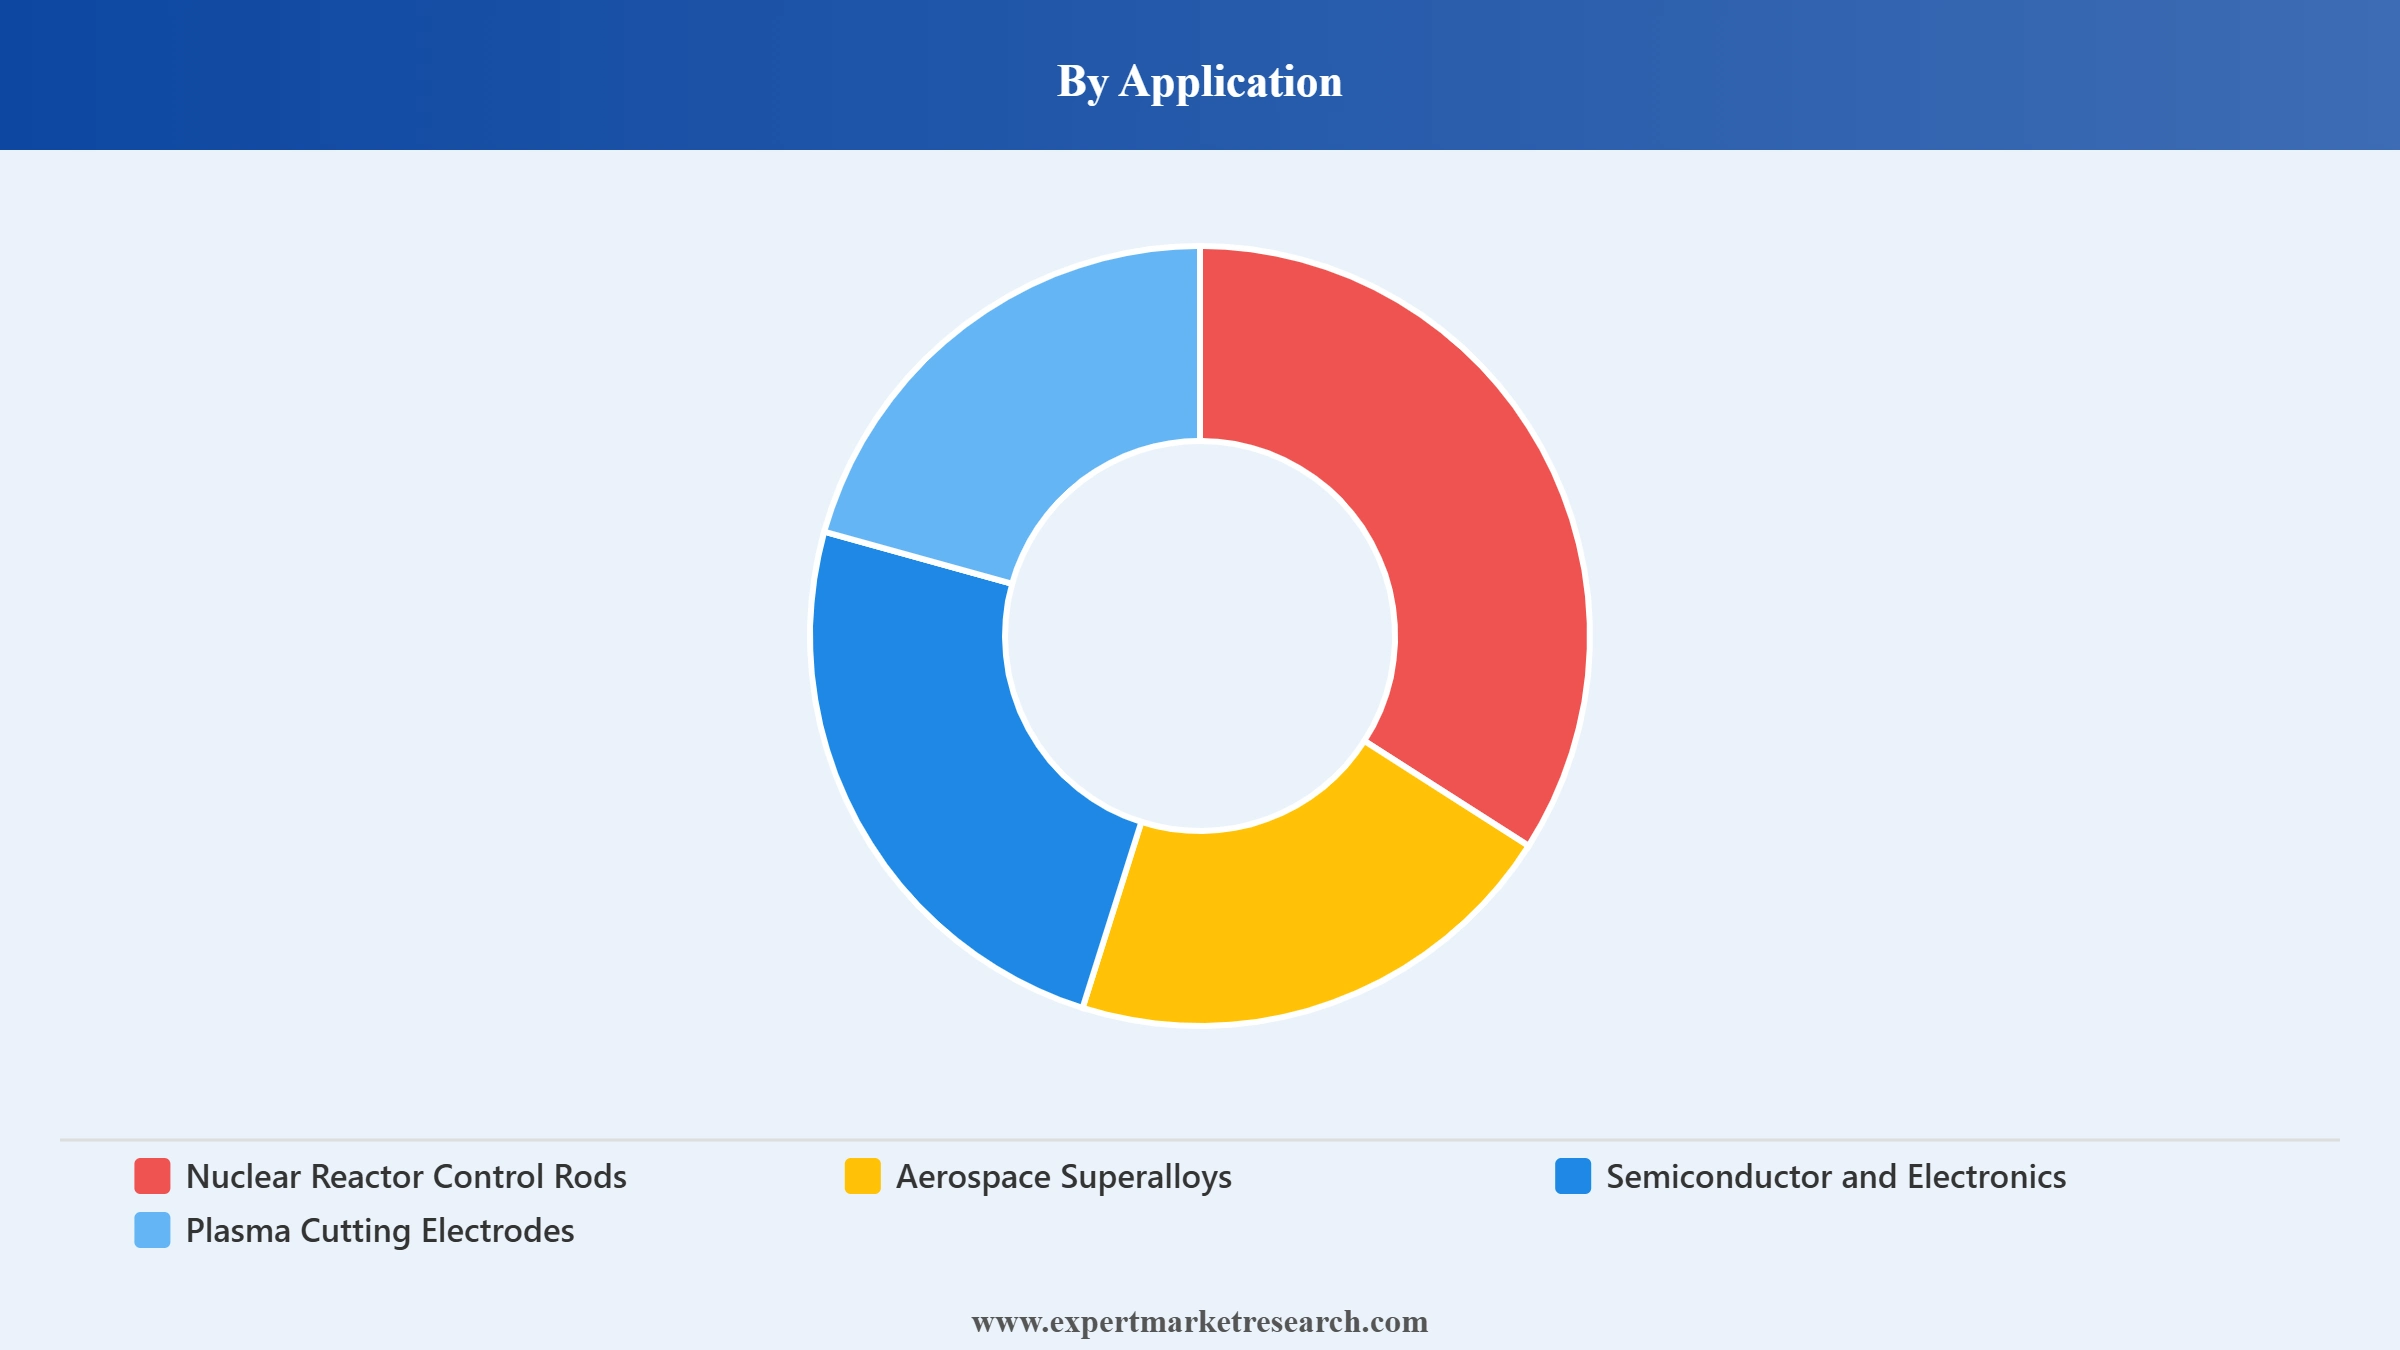
Key Insight: Nuclear Reactor Control Rods account for the largest share of the hafnium market by application, reflecting the metal's unmatched neutron absorption properties in pressurised water reactor control assemblies. In February 2026, ATI Inc reported in its 2025 annual results that aerospace and defense, particularly commercial jet engines, represented 68 percent of full year revenue, illustrating how heavily hafnium alloy demand skews toward aerospace superalloy applications among specialty metal producers. Semiconductor and Electronics is the fastest-growing application as artificial intelligence driven computing demand expands requirements for high purity hafnium oxide dielectric layers across leading edge fabrication nodes worldwide. Aerospace Superalloys rely on hafnium for high temperature turbine blade and rocket nozzle performance. Plasma Cutting Electrodes use hafnium for its high melting point and electrical conductivity. The Others category includes chemical catalysts and research applications.
Market Breakup by Region
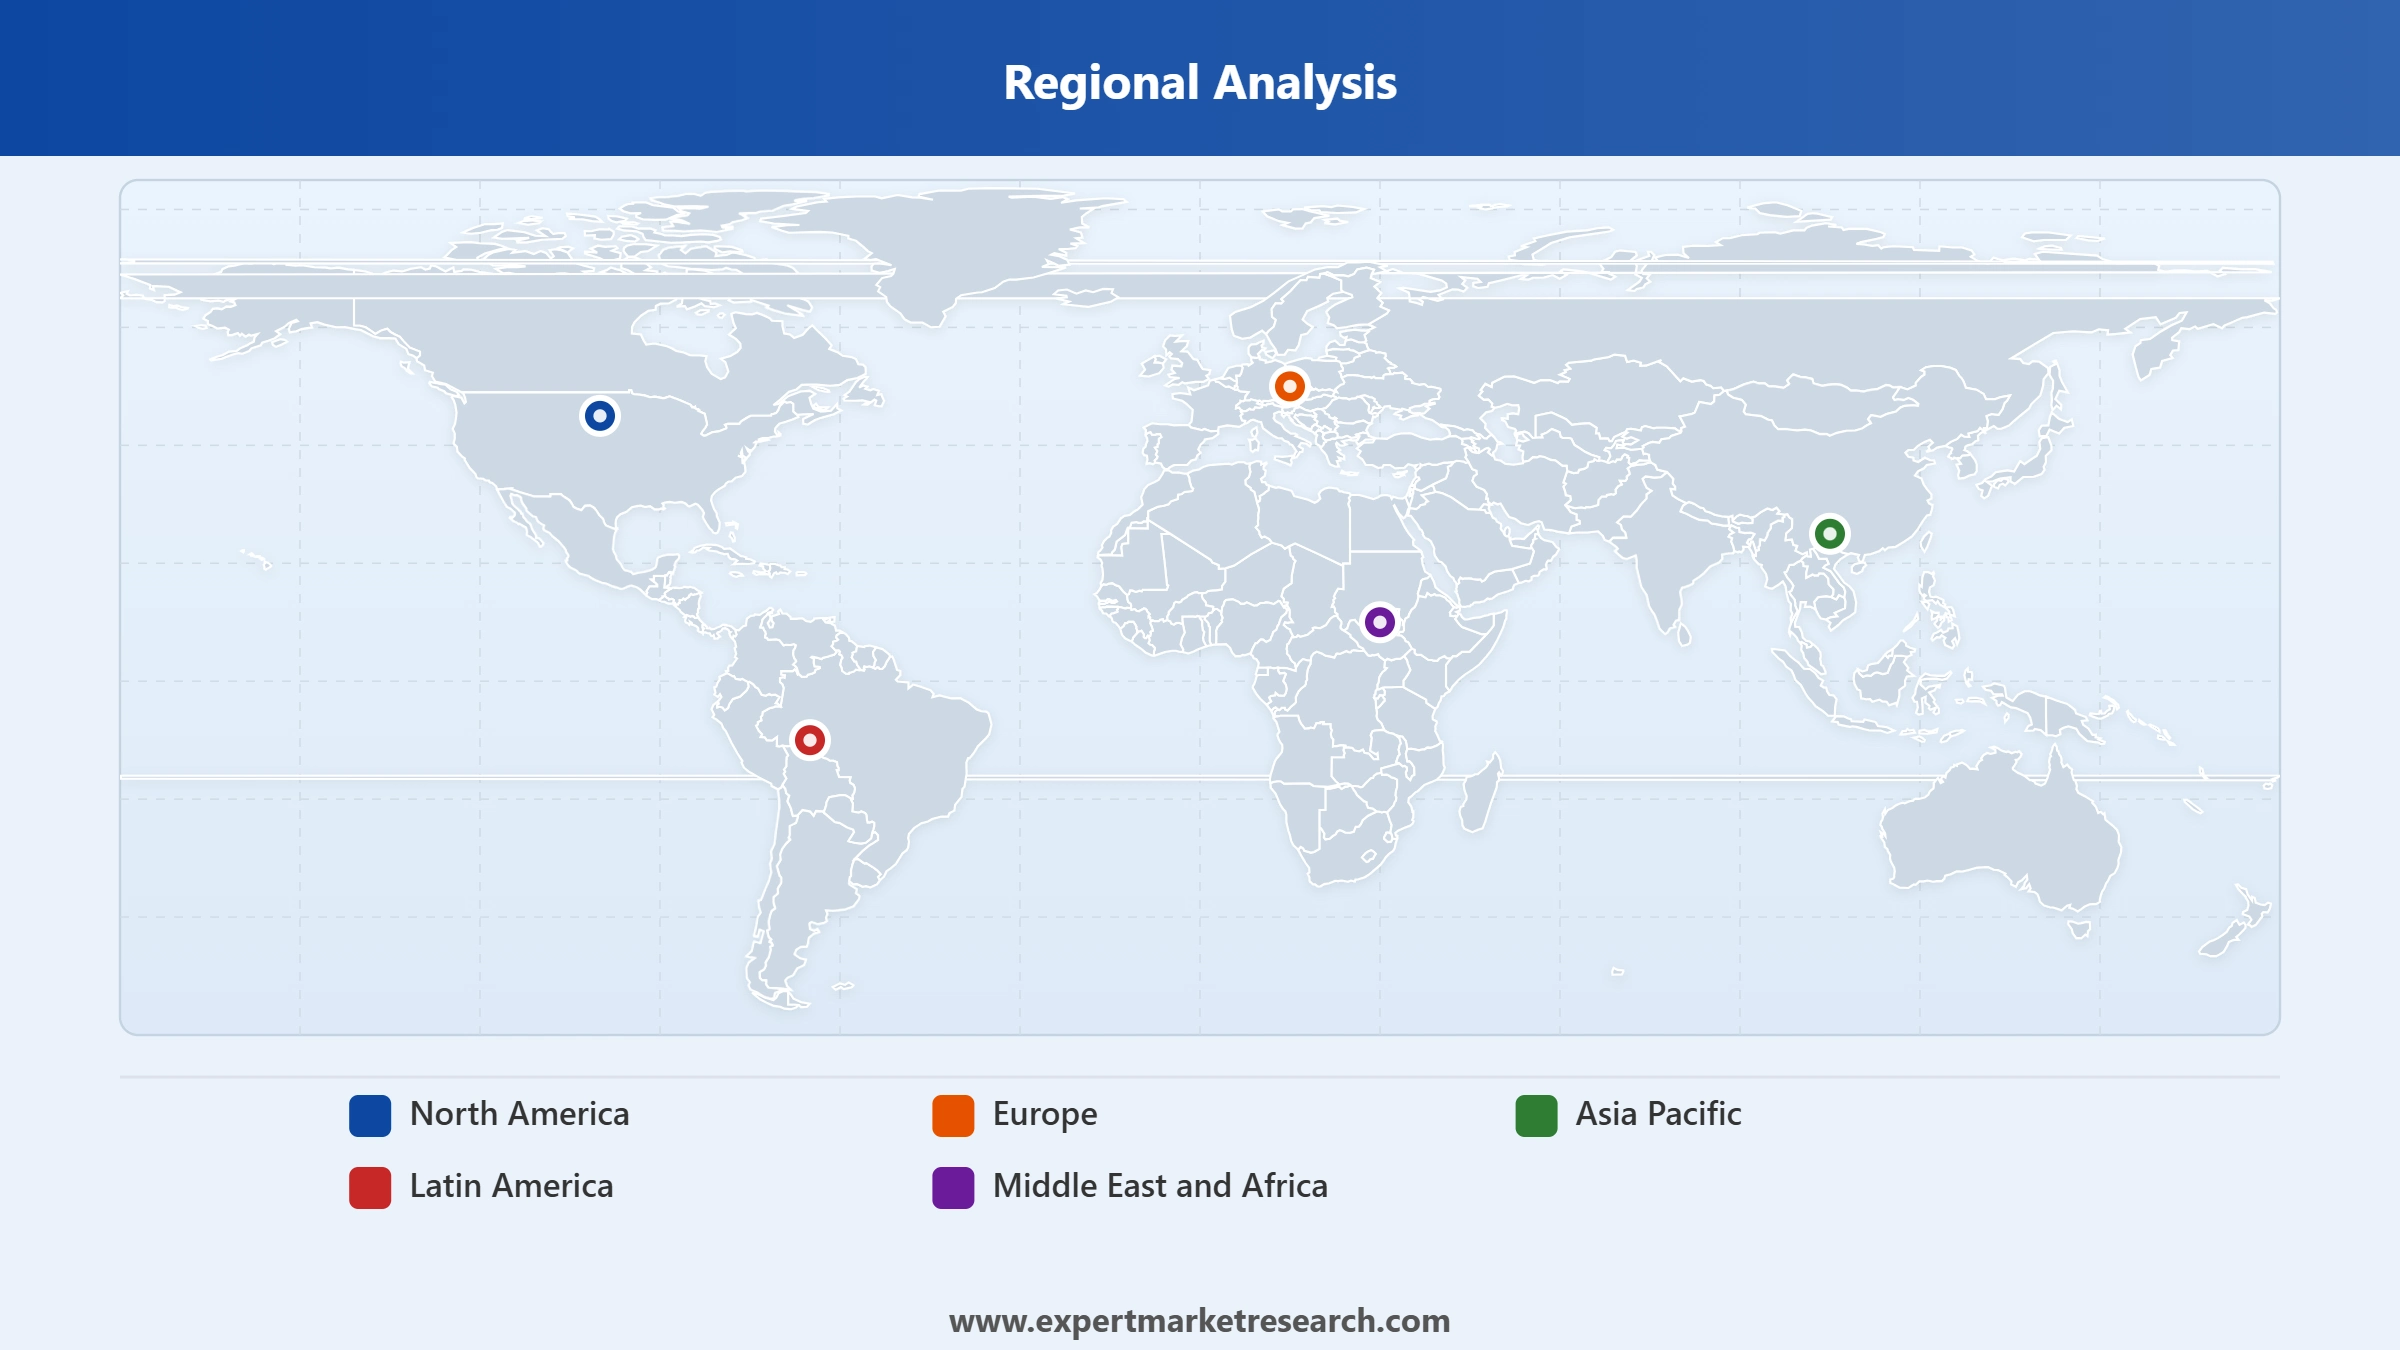
Key Insight: North America dominates the hafnium market, driven by robust nuclear and defense sector demand and established zirconium refining infrastructure in the United States. World Nuclear News reported in August 2026 that China's State Council had approved construction of eight additional reactors, underscoring how rapidly expanding Asia Pacific nuclear capacity continues to widen the gap in global hafnium demand relative to North America's more mature reactor fleet. Asia Pacific is expected to grow steadily as expanding semiconductor manufacturing and rising nuclear power investment lift regional demand. Europe maintains significant refining capacity through its established nuclear fuel supply chain. Latin America and the Middle East and Africa remain smaller markets tied to broader industrial and energy sector investment.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By product type, hafnium metal dominates the market due to its exceptional neutron absorption, corrosion resistance, and high melting point
Hafnium Metal accounts for the largest share of the hafnium market by product type, valued for its exceptional neutron absorption, corrosion resistance, and high melting point across nuclear, aerospace, and industrial applications requiring extreme performance reliability worldwide today overall. Energy Fuels' proposed acquisition of Australian Strategic Materials, targeted for completion in early July 2026, would combine ASM's polymetallic Dubbo project resource containing zirconium, niobium, and hafnium with an operating Korean metals plant, extending Western hafnium metal supply diversification efforts nationwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Hafnium Oxide is the fastest-growing product type as semiconductor manufacturers increasingly specify high purity grades for high-k dielectric layers in advanced logic chip architectures requiring ever tighter contamination tolerances across leading edge fabrication processes worldwide today overall. In July 2025, Ferroelectric Memory Company's chief executive announced plans for the German fabless chip designer's own semiconductor memory factory built around hafnium oxide based ferroelectric technology, aiming to rebuild European technological sovereignty in system critical memory chips.
By application, nuclear reactor control rods dominate the market due to hafnium's unmatched neutron absorption properties and long service life
Nuclear Reactor Control Rods account for the largest share of the hafnium market by application, reflecting the metal's unmatched neutron absorption properties and long service life in pressurised water reactor control assemblies across most operating nuclear fleets worldwide today. In January 2025, Westinghouse announced it had resolved its technology and export dispute with KEPCO and KHNP, establishing a framework for additional reactor deployments outside South Korea and reinforcing global demand for hafnium bearing control rod materials across its reactor fleet.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Semiconductor and Electronics is the fastest-growing application as artificial intelligence driven computing demand and continued logic chip miniaturisation expand requirements for high purity hafnium oxide dielectric layers across leading edge fabrication nodes worldwide today overall too. In December 2025, TSMC's 2 nanometre N2 process technology reached high volume production using an advanced nanosheet transistor structure that requires higher performance hafnium oxide dielectrics than previous generation nodes, illustrating the semiconductor industry's growing reliance on hafnium-based materials worldwide.
North America dominates the market due to robust nuclear and defense sector demand and established zirconium refining infrastructure
North America dominates the hafnium market, driven by robust nuclear and defense sector demand concentrated in the United States alongside its established zirconium refining and hafnium separation infrastructure serving nuclear, aerospace, and semiconductor customers across the wider region worldwide today. On June 4, 2026, Antares Nuclear's Mark-0 advanced microreactor became the first to achieve criticality under the Department of Energy's Reactor Pilot Program at Idaho National Laboratory, part of a broader push to accelerate advanced reactor deployment supporting long term domestic zirconium and hafnium demand.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is also expected to grow steadily as expanding semiconductor manufacturing capacity and rising nuclear power investment across the region continue to lift regional hafnium demand across several key national markets pursuing manufacturing and energy sector growth worldwide today. In June 2026, South Korean President Lee Jae Myung announced that Samsung and SK Hynix plan to invest approximately 518 billion dollars to build four new semiconductor fabs, alongside 18.4 gigawatts of additional AI data centre capacity requiring roughly 18 new nuclear reactors worth of power generation.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
6.1% |
|
Europe |
5.7% |
|
Asia Pacific |
6.8% |
|
Latin America |
5.9% |
|
Middle East and Africa |
6.0% |
The global hafnium companies feature a highly concentrated competitive structure, with a small number of producers controlling most of the zirconium refining and hafnium separation capacity worldwide. Manufacturers including ATI and Framatome compete primarily through integrated zirconium hafnium separation infrastructure, while producers including Materion and PLANSEE differentiate through specialty alloy development and precision fabrication expertise.
Leading hafnium market players are focusing on expanding refining and separation capacity, securing longer term supply agreements with defense and semiconductor customers, and investing in purity improvement technologies for advanced applications. Increasing government backed stockpiling initiatives and continued evaluation of alternative byproduct recovery projects are also shaping strategy across the industry.
ATI Inc., founded in 1996 and headquartered in Dallas, Texas, United States, is one of only a handful of companies worldwide capable of separating hafnium from zirconium at commercial volume and quality, operating a vertically integrated facility in Oregon spanning mineral feedstock through finished hafnium products. The company continues to supply nuclear, aerospace, defense, and medical customers, describing itself as the largest independent provider of these materials in the Western world.
Materion Corporation, founded in 1931 and headquartered in Mayfield Heights, Ohio, United States, is a global leader in advanced materials solutions supplying hafnium-based compounds to precision industries across semiconductor, aerospace, defense, and energy end markets. The company continues to expand its critical materials capacity through targeted capital investment, serving customers that require consistent, high purity supply across strategically important applications.
Framatome, founded in 2001 and headquartered in Paris, France, is a key player in the global nuclear technology landscape, operating its integrated zirconium component manufacturing chain at the Jarrie site through a unique extractive separation process that also yields high quality hafnium alloys. The company continues to reinforce its production capacity to meet growing needs from nuclear, aeronautics, defense, space, medical, and electronics customers.
PLANSEE SE, founded in 1921 and headquartered in Reutte, Austria, is a leading European precision metallurgy specialist focusing on high purity refractory metal products and customised solutions for electronics, coating, and industrial applications. The company continues to serve customers requiring specialty hafnium and related refractory metal components across demanding high temperature and high-performance industrial environments.
Other key players in the market report include Precision Castparts Corp., Merck KGaA, American Elements, Nanjing Youtian Metal Technology Co., Ltd., and China Nuclear JingHuan Zirconium Industry Co., Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the hafnium market 2026-2035 with our in-depth report. Gain strategic insights, future forecasts, and key market developments that can help you stay competitive. Download a free sample report or contact our team for customised consultation on the market trends 2026.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the hafnium market reached an approximate value of USD 430.00 Million.
The market is projected to grow at a CAGR of 6.20% between 2026 and 2035.
The key players in the market include ATI Inc., Materion Corporation, Precision Castparts Corp., Framatome, PLANSEE SE, Merck KGaA, American Elements, Nanjing Youtian Metal Technology Co., Ltd., and China Nuclear JingHuan Zirconium Industry Co., Ltd., among others.
Leading producers are focusing on expanding refining and separation capacity, securing longer term supply agreements with defense and semiconductor customers, and investing in purity improvement technologies for advanced applications.
Key challenges include a structurally constrained byproduct supply chain tied to zirconium refining capacity, volatile export licensing policy in major producing regions, and persistently elevated spot prices.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Product Type |
|
|
Breakup by Application |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




