

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
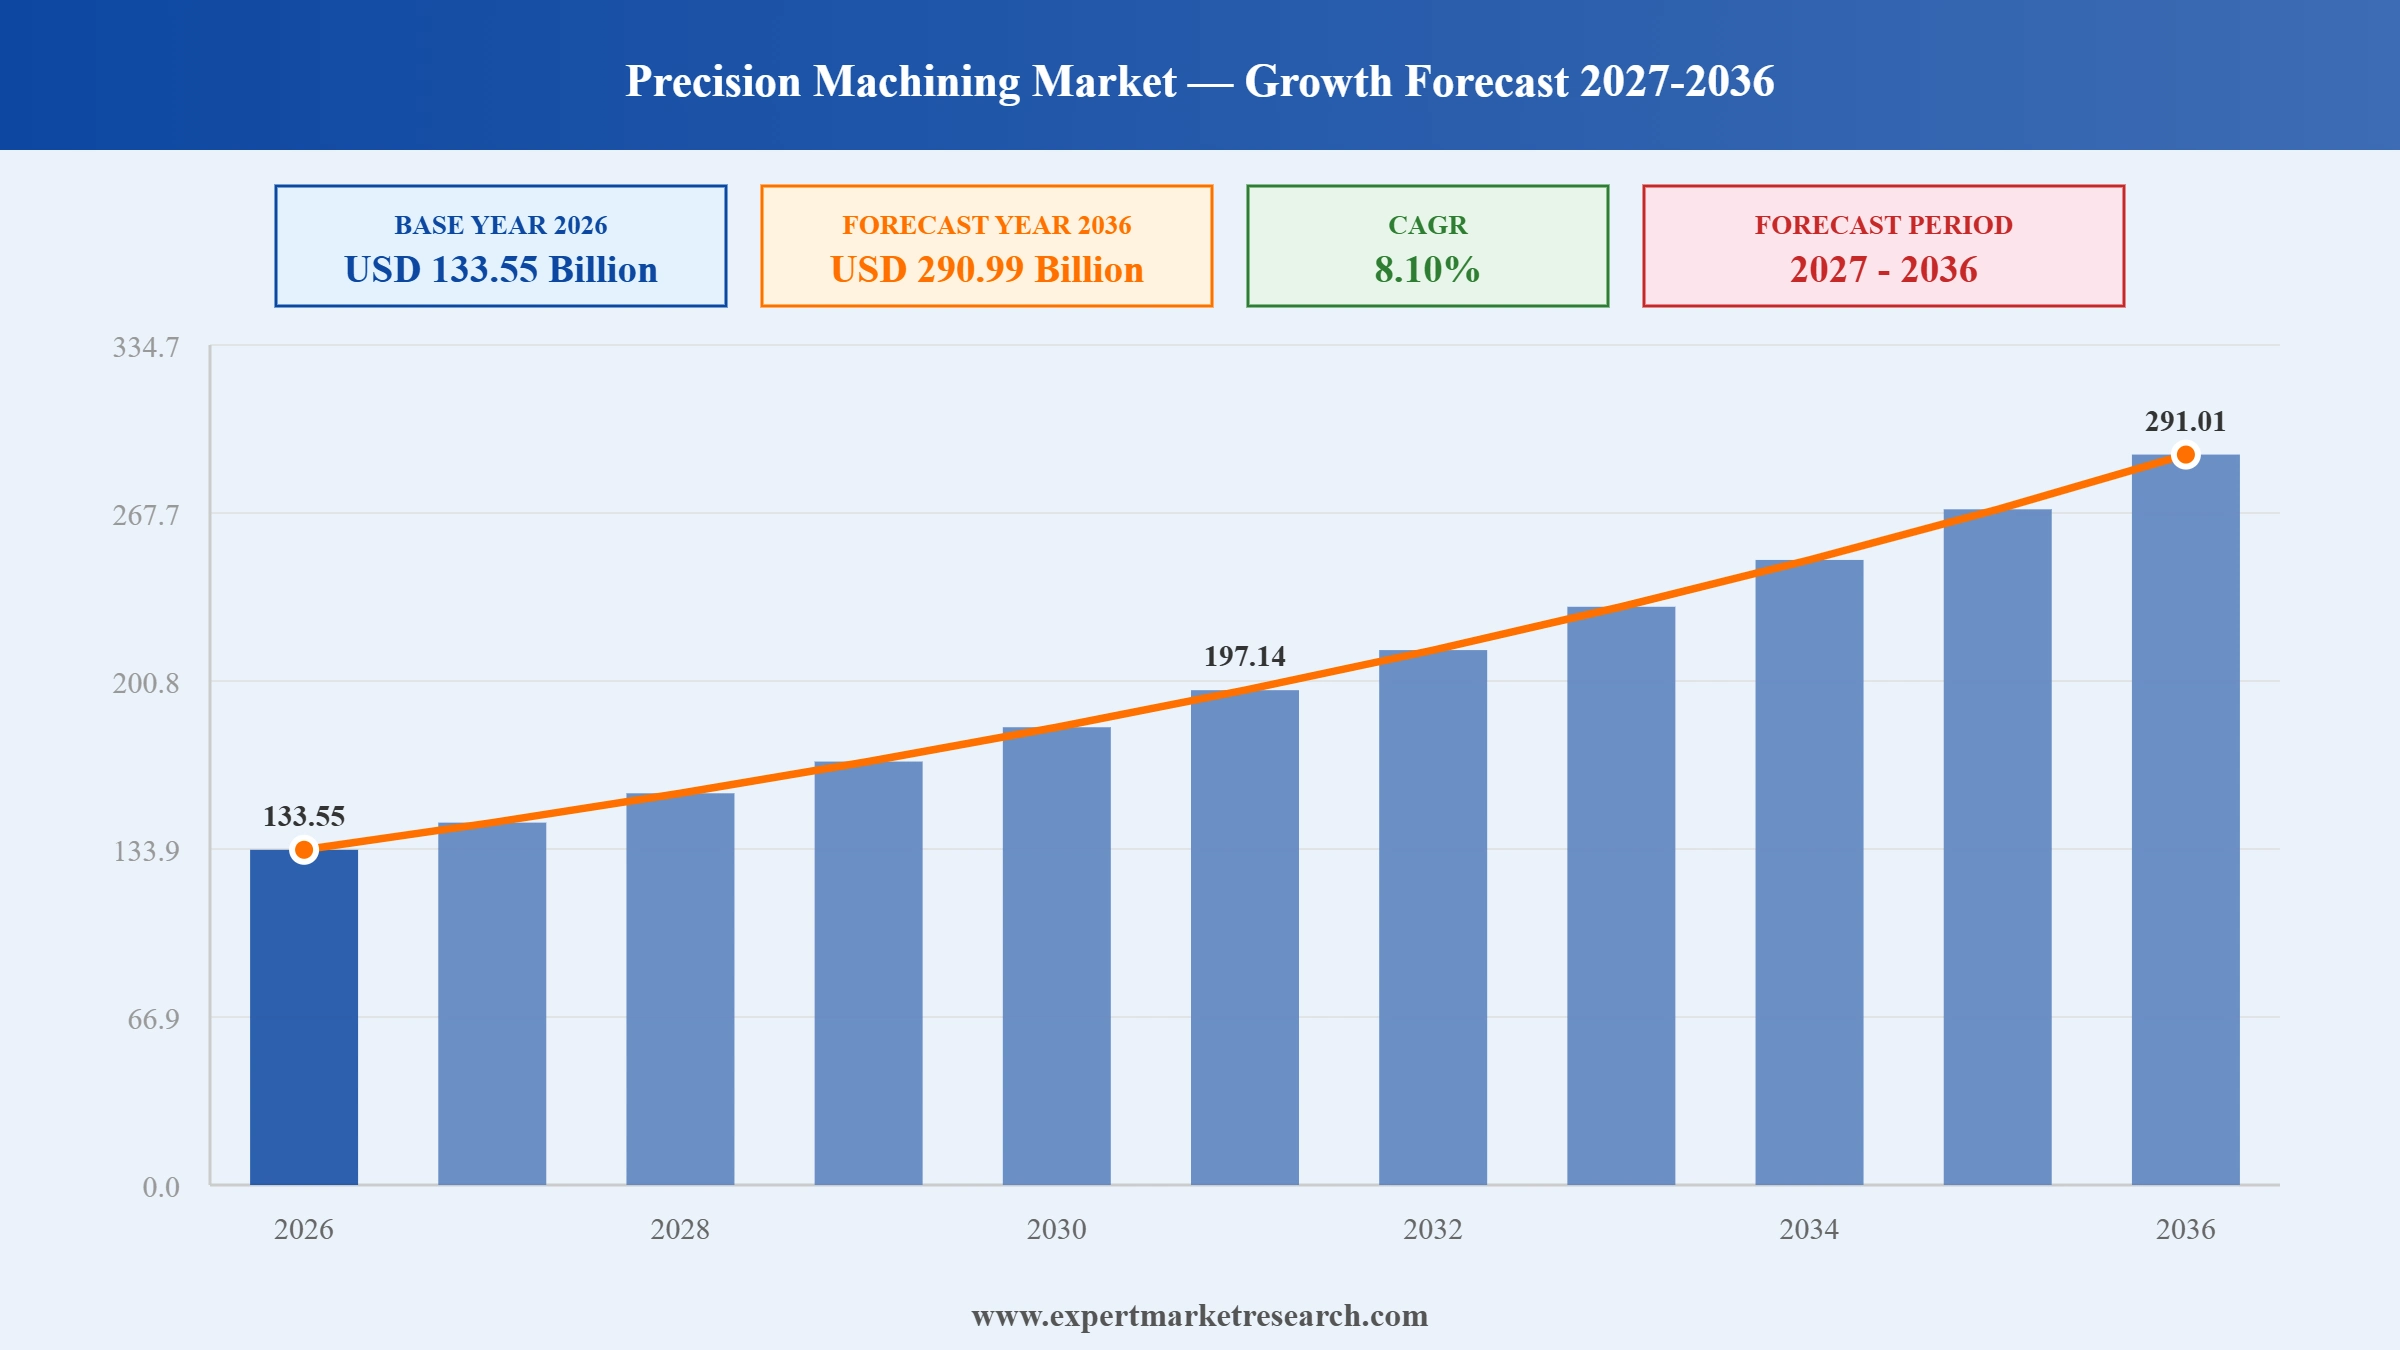
The precision machining market was valued at USD 123.54 Billion in 2025. The market is expected to grow at a CAGR of 8.10% during the forecast period of 2026-2035 to reach a value of USD 269.19 Billion by 2035. Rising demand for high-precision components across aerospace, automotive, and medical device industries, accelerated adoption of CNC automation and smart manufacturing, and increasing complexity of component tolerances are collectively driving market growth.
The precision machining market is shaped by rising demand for high-precision components across advanced manufacturing sectors and accelerating adoption of CNC automation and smart manufacturing technologies. Asia Pacific dominated the market, supported by large-scale industrial production hubs across China, Japan, and India. Metals account for the largest share by material type, reflecting the ubiquity and indispensable nature of metallic components across aerospace, automotive, and general industrial machinery.
Established precision machining and component manufacturers are reinforcing their market presence through continued corporate restructuring, capacity investment, and strategic separations rather than relying on a single growth lever. In August 2026, for example, Bodycote received competing takeover proposals worth approximately £1.6 billion each from private equity firms CVC Advisers and Veritas Capital, with the heat treatment and thermal processing specialist recommending shareholders consider either offer. This continued pace of corporate restructuring is helping precision manufacturers sharpen strategic focus even as demand accelerates across aerospace and industrial end markets worldwide, with leadership transitions increasingly accompanying these strategic realignments.
The competitive landscape remains fractionated, with high entry costs and operational complexity creating significant barriers for smaller manufacturers to compete against larger, well-capitalized firms such as Precision Castparts, Barnes Group, and Bodycote that possess the substantial capital, economies of scale, and established skilled workforce necessary to remain competitive. In March 2026, for example, Fabrinet entered a share purchase agreement to acquire a 16.0% equity interest in Raytek Semiconductor for approximately $32.4 million, illustrating the scale of capital well-established precision manufacturers can deploy to secure strategic supply relationships that smaller competitors cannot match. Participation requires sustained investment in machinery upgrades, advanced software, and specialized workforce training, creating meaningful entry barriers and driving continued industry consolidation as smaller firms struggle to keep pace with technological advancements.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
|
Precision Machining Market Report Summary |
Description |
Value |
|
Base Year |
USD Billion |
2025 |
|
Historical Period |
USD Billion |
2019-2025 |
|
Forecast Period |
USD Billion |
2026-2035 |
|
Market Size 2025 |
USD Billion |
123.54 |
|
Market Size 2035 |
USD Billion |
269.19 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
8.10% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
8.5% |
|
CAGR 2026-2035 - Market by Process Type |
Milling |
7.5% |
|
CAGR 2026-2035 - Market by Material Type |
Composites |
9.0% |
|
2025 Market Share by Region |
Asia Pacific |
42% |
The precision machining market is being reshaped by major corporate restructuring among aerospace component suppliers, continued capacity investment, and operational resilience challenges following facility disruptions. Growing leadership transitions are further reshaping the competitive landscape.
Precision Castparts completed its acquisition of Morvern Group, a UK-based turbine casting specialist, marking the company's first confirmed deal since being acquired by Berkshire Hathaway. The acquisition deepened PCC's turbine casting capabilities and strengthened its position within European aerospace and defense supply chains. Other companies can pursue similar targeted acquisitions to deepen specialized manufacturing capabilities within key regional supply chains.
Rocket Lab acquired Precision Components Limited (PCL) in Auckland, New Zealand, establishing the new Auckland Machine Complex dedicated to high-volume, high-tolerance precision machining for its Electron and Neutron launch vehicle programs. The acquisition expanded Rocket Lab's in-house precision manufacturing capacity to support its growing contract backlog and increasing launch cadence. Other companies can pursue similar targeted acquisitions to vertically integrate precision machining capacity supporting high-growth production programs.
Barnes Aerospace named Michael Mosley as Chief Executive Officer, effective January 26, 2026, with Mosley bringing prior leadership experience from Precision Castparts and Rolls-Royce. The appointment followed Barnes Aerospace's establishment as an independent company. Other companies can pursue similar experienced leadership appointments to strengthen operational execution following major corporate restructuring events.
Barnes Group completed its separation into two independent companies, Barnes Aerospace and The Industrial Solutions Group, following its acquisition by Apollo Global Management in a $3.6 billion deal. The separation allowed each business to pursue focused strategic priorities within aerospace and industrial markets respectively. Other companies can pursue similar corporate separations to sharpen strategic focus across distinct end-market segments.
High entry costs and operational complexity are creating significant barriers for smaller precision machining firms, favoring larger companies with substantial capital and economies of scale. This is driving consolidation as larger players acquire smaller firms unable to sustain continuous investment in machinery upgrades and specialized training. In March 2026, for example, Radial Equity Partners acquired Thomas Precision Machining, a Connecticut-based aerospace and defense manufacturer, marking its latest move into the fragmented precision machining consolidation landscape.
Manufacturers are increasingly adopting Industry 4.0-ready CNC platforms featuring real-time spindle load monitoring, adaptive feed rate control, and integrated probing systems. This is elevating quality output while reducing tool breakage and workpiece scrap across production lines. In April 2026, for example, DMG Mori showcased its Machining Transformation strategy at Hannover Messe, demonstrating an AI-supported, seamless CNC process chain spanning intelligent planning, simulation, and automated production.
Rapid expansion of electric vehicle production is increasing demand for precision-machined lightweight components, including EV motor housings and battery structural components. In 2026, for example, Ford confirmed its Louisville Assembly Plant is being retooled for large-scale aluminum "unicasting" on its electric pickup, replacing more than 146 stamped parts with two structural castings still requiring precision finish-machining. Global EV sales growth continues reinforcing demand for machining across drivetrain and powertrain components.
Commercial aerospace fleet renewal cycles are providing precision component manufacturers with multiyear demand visibility as major aircraft programs ramp up production rates. This is supporting sustained capacity investment decisions across the supply chain. In its 2025 Annual Report, Berkshire Hathaway disclosed that Precision Castparts generated $2.4 billion in net cash flows from operating activities during 2025, compared with an average of just $0.9 billion in 2021 and 2022 and $1.7 billion in 2015, the last full fiscal year before Berkshire's acquisition, reflecting the strength of ongoing aerospace production ramp-up.
Growing complexity of medical devices and implants is driving demand for precision machining capable of micrometer-level dimensional accuracy and specialized surface finishes. This is establishing medical devices as an increasingly important end-use category alongside traditional aerospace and automotive applications. In July 2026, for example, Viant, a leading global medical device design and manufacturing services provider, named Dan Croteau as Chief Executive Officer, bringing more than 30 years of medical device and contract manufacturing leadership to guide the company's next phase of growth.
The Expert Market Research's report titled "Precision Machining Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Process Type
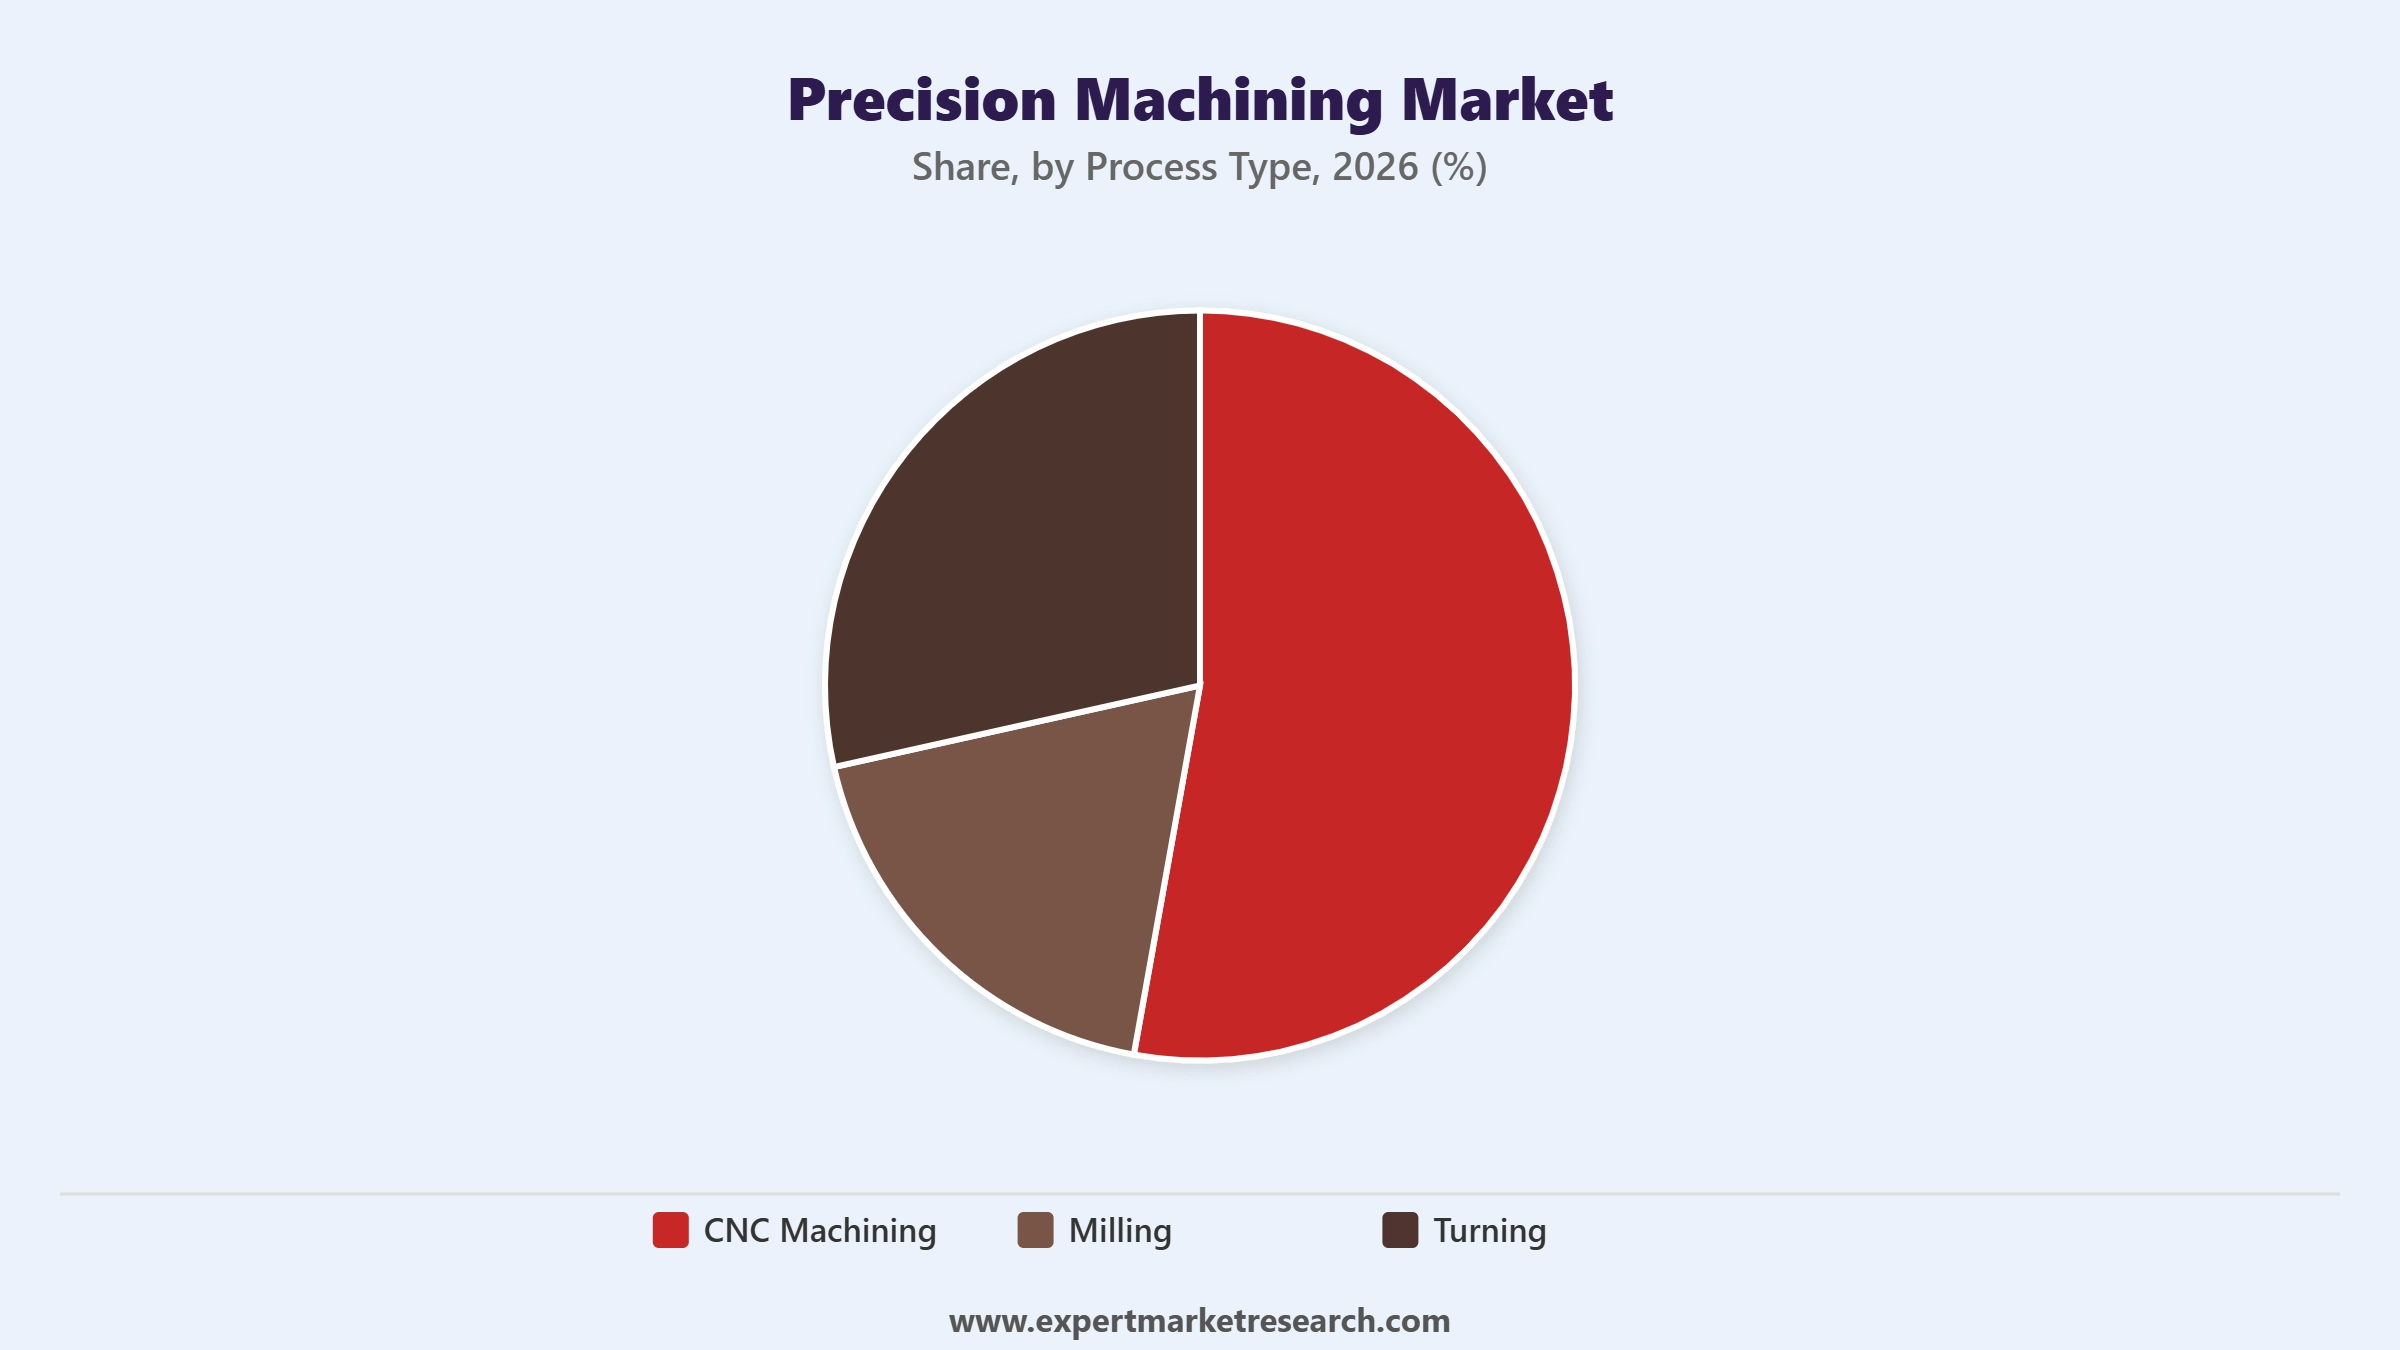
Key Insight: CNC machining accounts for the largest share of the market by process type, driven by its high precision, automation capability, and ability to produce complex components efficiently across automotive, aerospace, and industrial manufacturing sectors. In February 2026, for example, Makino announced a new partnership with Miami University and Butler Tech to establish the Makino Subtractive Lab, an advanced manufacturing workforce development initiative aimed at training the next generation of CNC machinists. Milling continues to see strong adoption given its versatility and ability to handle a wide range of materials and complex geometries in a single setup. Turning holds a meaningful share, particularly prevalent in automotive and industrial applications requiring high-volume rotational parts such as shafts, pins, and bushings. Others, including grinding, drilling, and electrical discharge machining, round out the category's broader process portfolio for specialized, high-precision applications.
Market Breakup by Material Type
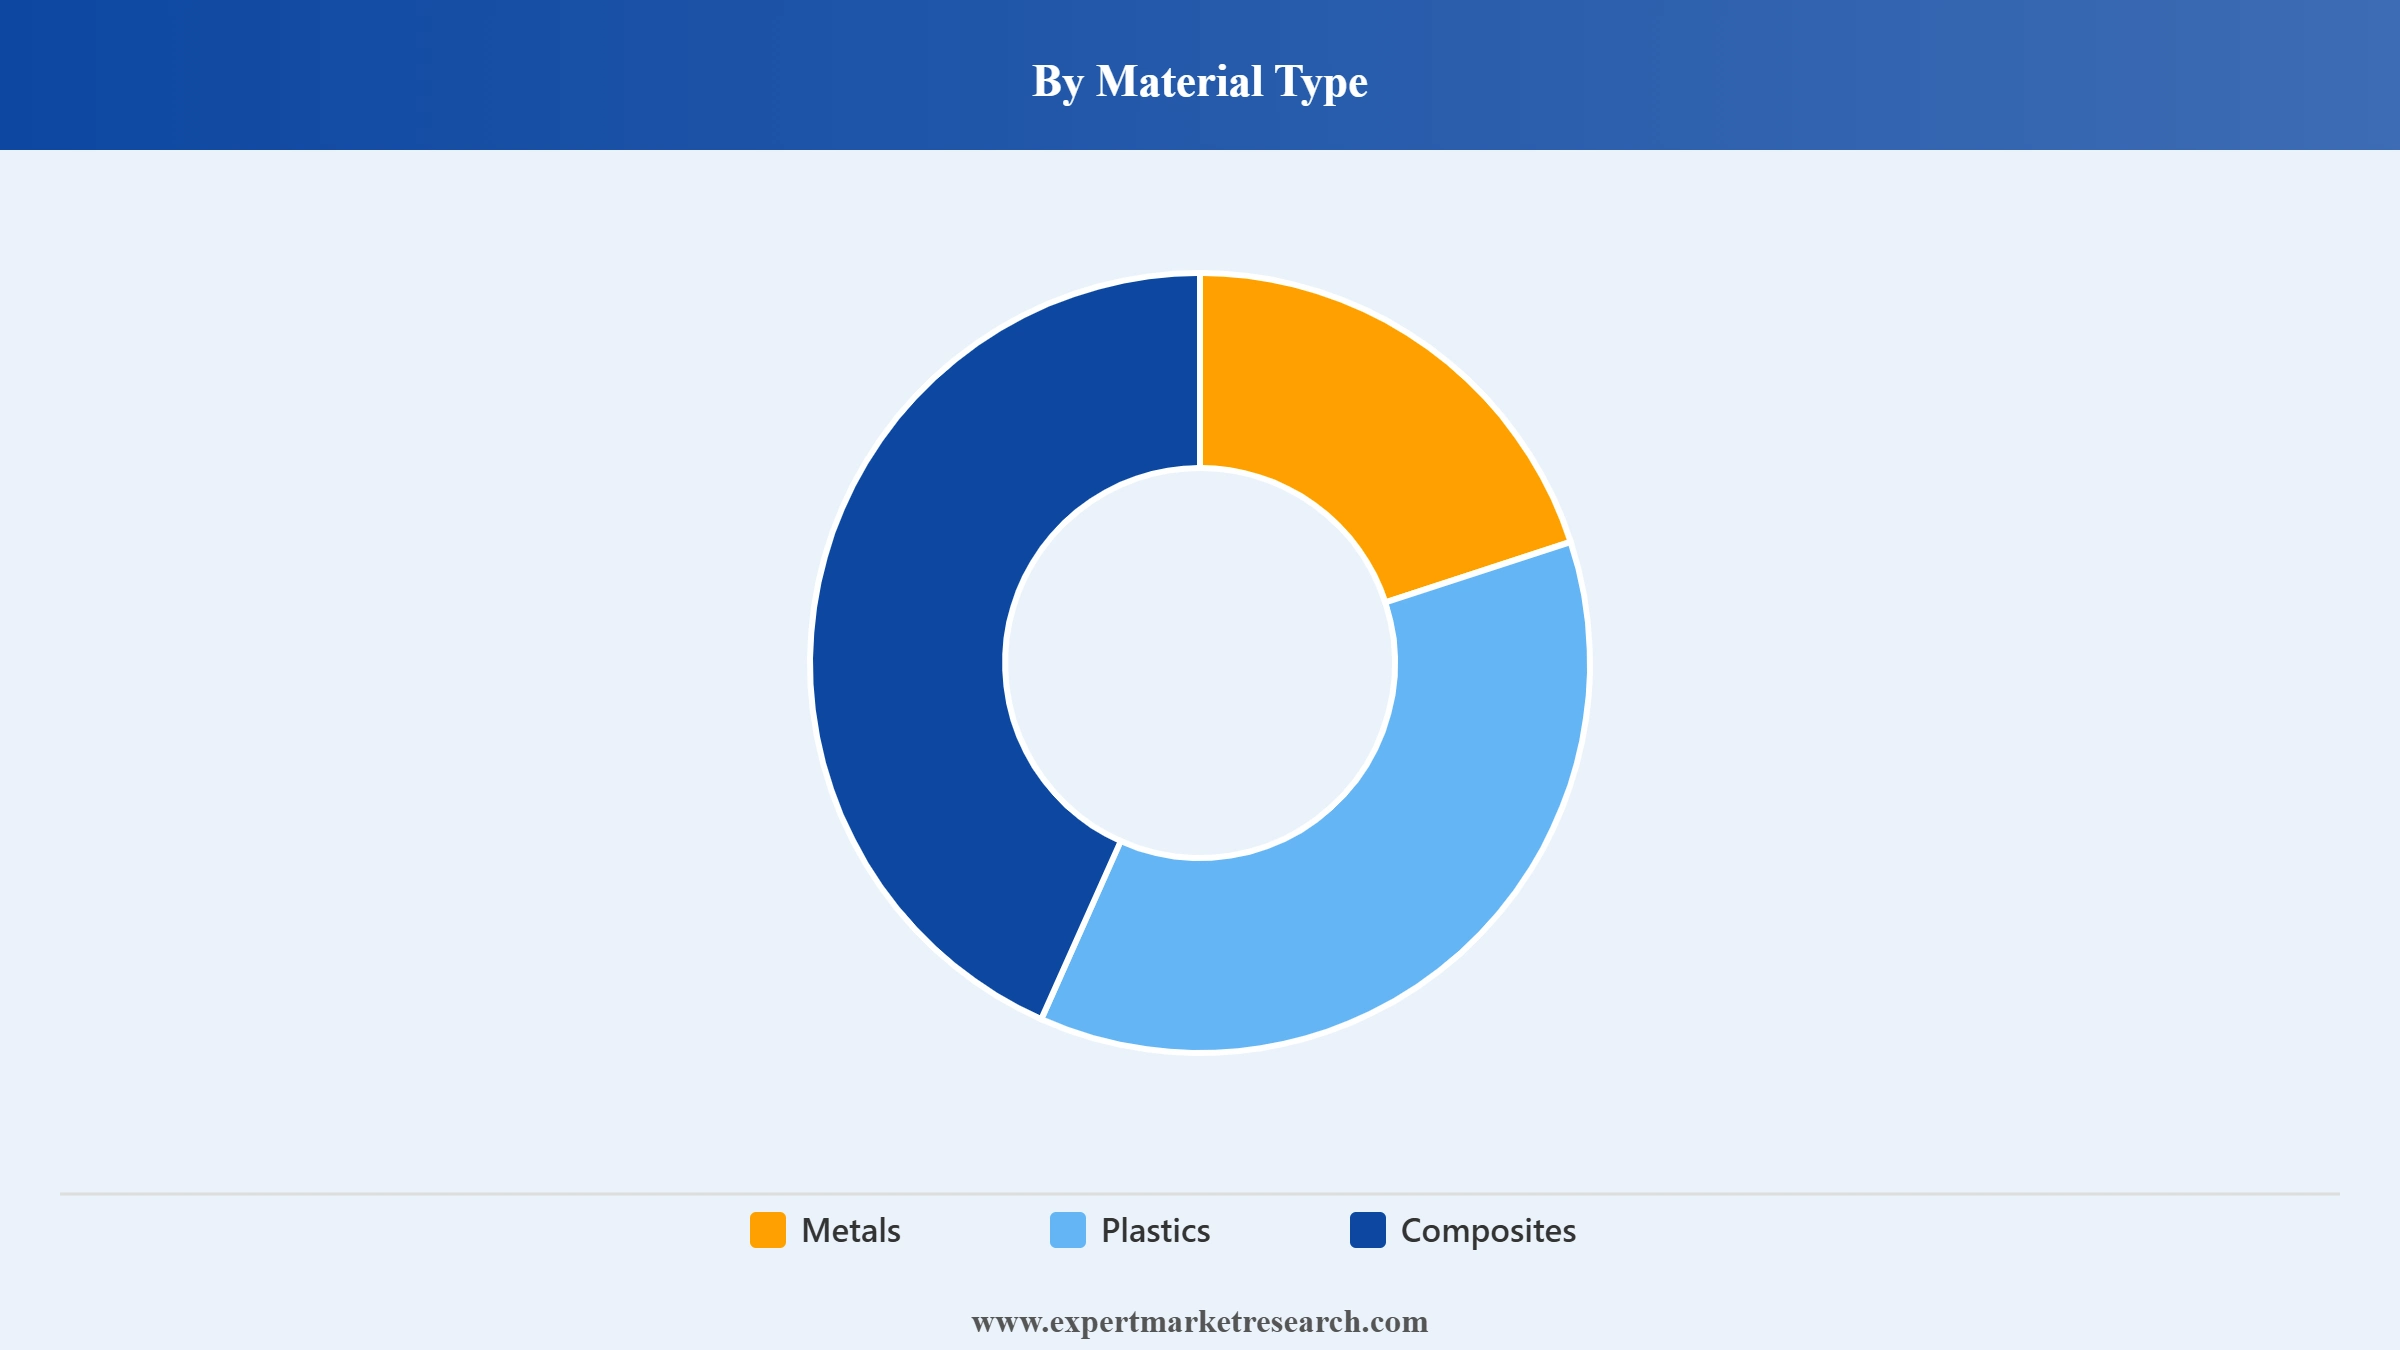
Key Insight: Metals account for the largest share of the market by material type, reflecting the ubiquity and indispensable nature of metallic components including steels, aluminum alloys, titanium, and superalloys across aerospace, automotive, and general industrial machinery. In August 2026, for example, India's Aerolloy Technologies, a subsidiary of PTC Industries, signed a landmark agreement with Airbus to develop, manufacture, and supply fully machined, ready-to-fit titanium castings for the A320neo, A330neo, and A350 aircraft programs. Plastics continue to see steady demand for lightweight, cost-sensitive applications where metal's structural properties are not required. Composites represent a smaller but strategically important category, valued for extreme environment applications requiring superior strength-to-weight characteristics. Others, including ceramics, serve specialized applications requiring exceptional heat and wear resistance.
Market Breakup by End-Use Industry
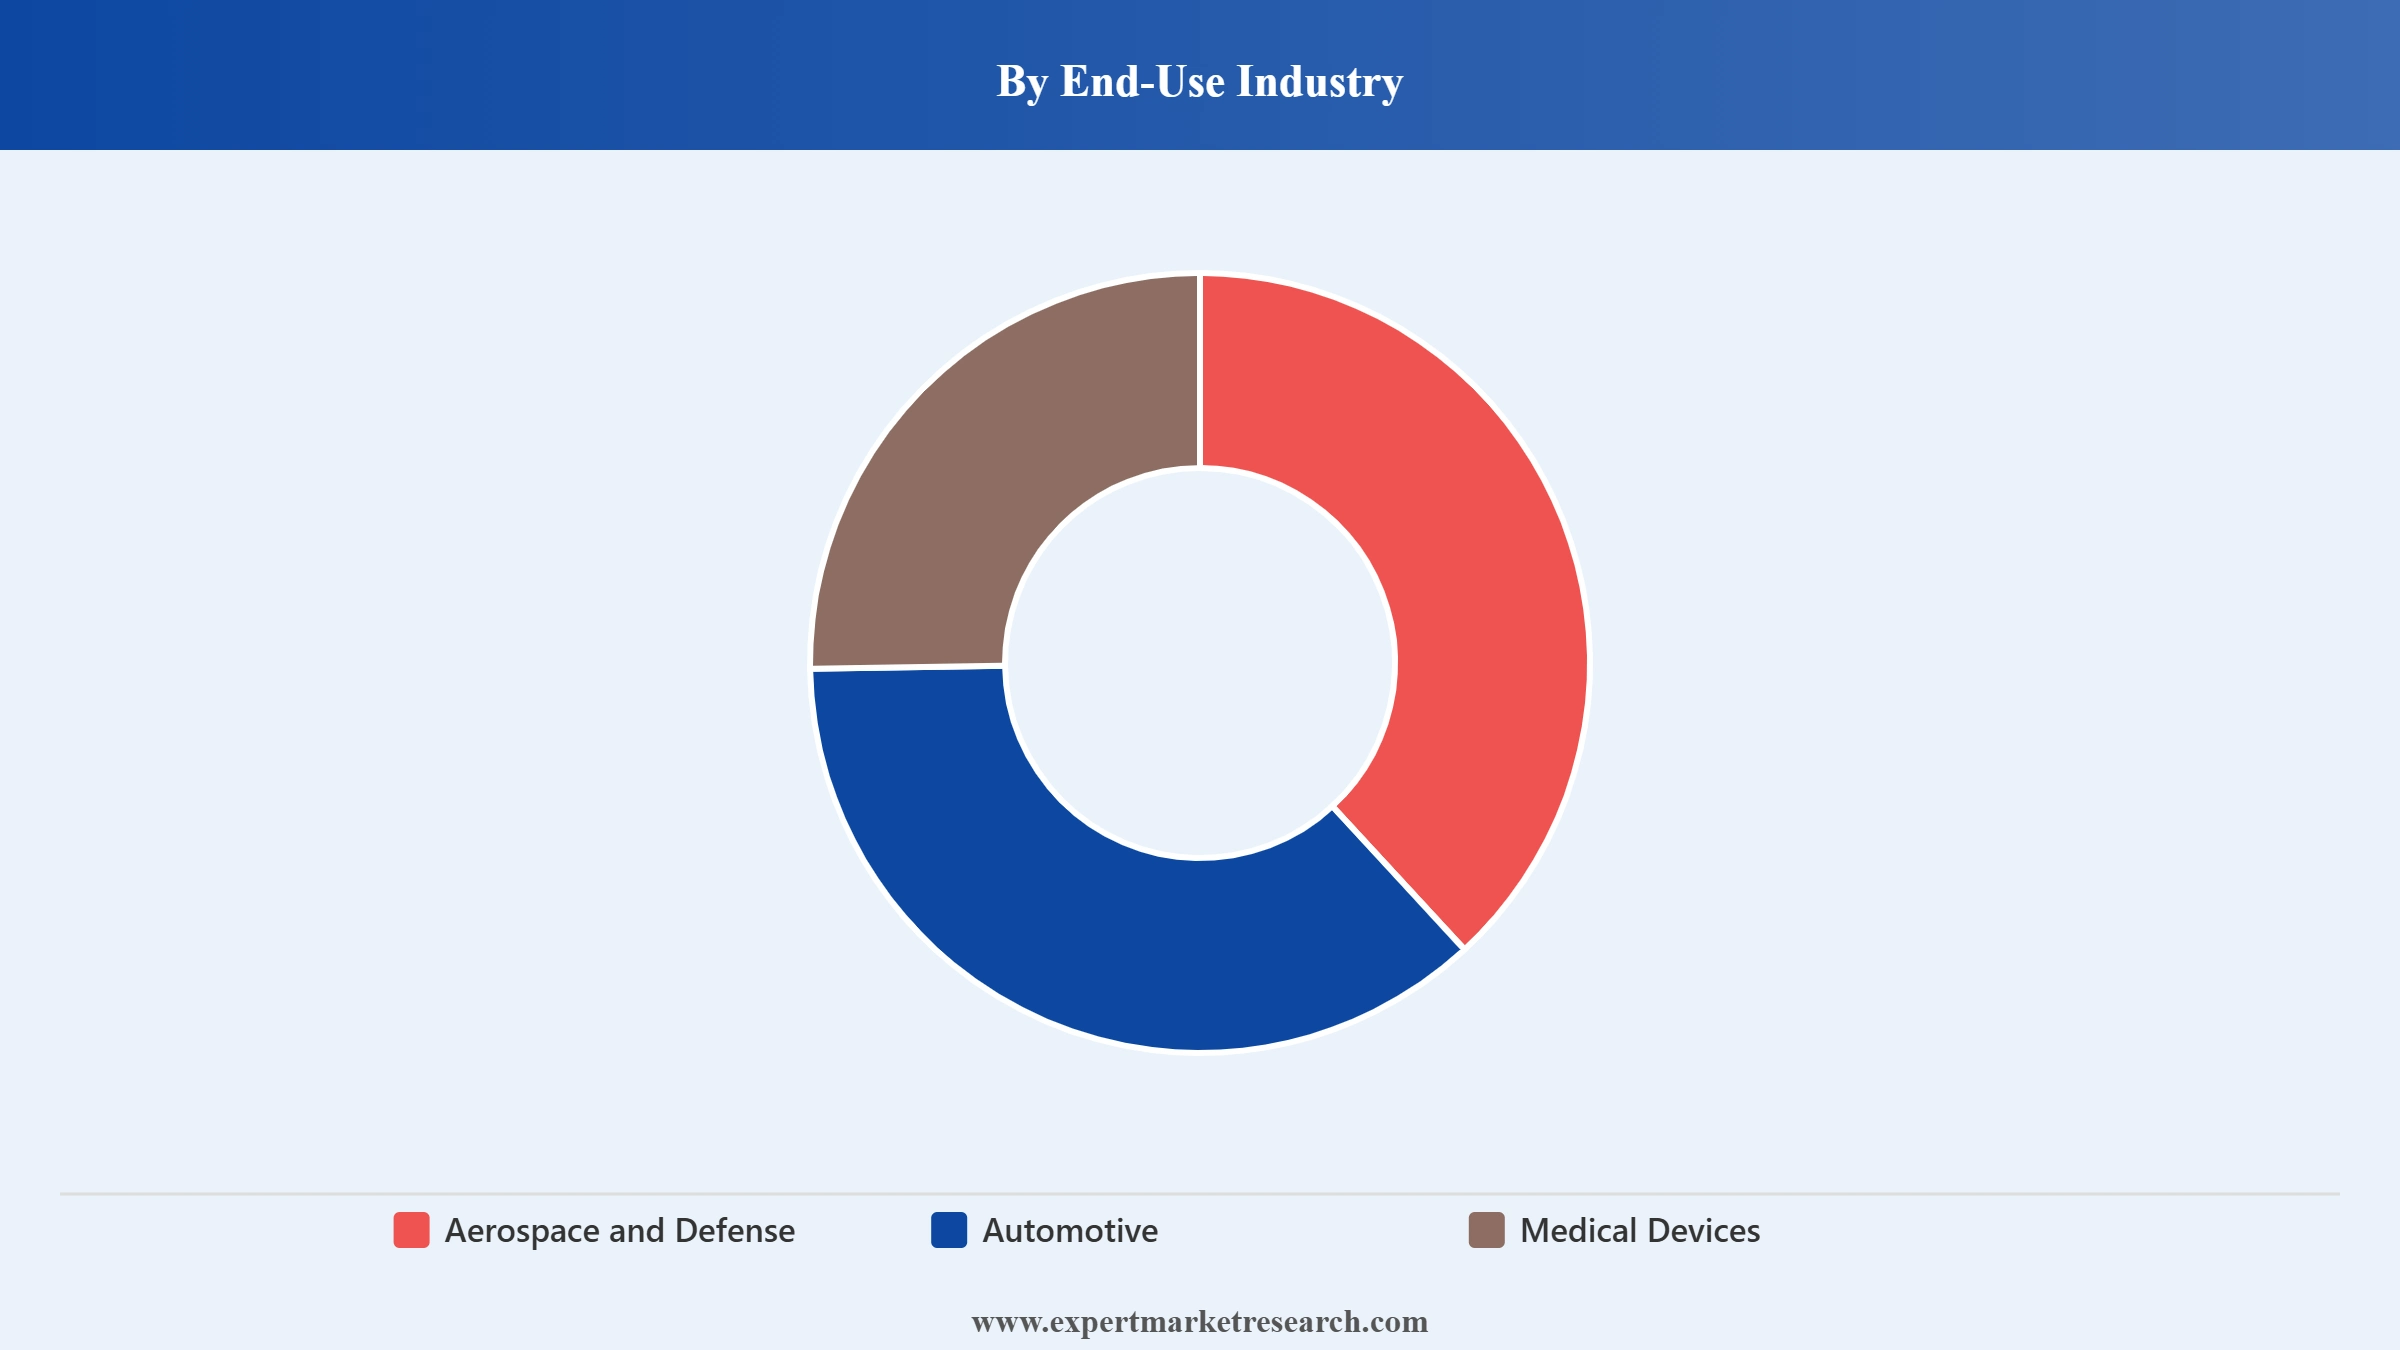
Key Insight: Automotive accounts for the largest share of the market by end-use industry, driven by strong demand for precision components used in engines, transmissions, and increasingly electric vehicle motor housings and battery structural components. Aerospace and defense is a fast-growing end-use industry as increasing complexity of aircraft components and rising fleet renewal cycles continue to drive demand for tight-tolerance, high-precision parts. Medical devices represent a growing end-use category as increasing device complexity requires micrometer-level dimensional accuracy for implants and surgical components; in May 2026, for example, Tecomet and Orchid Orthopedic Solutions completed their merger, creating a scaled precision machining platform serving medical technology and aerospace and defense customers. Others, including electronics, energy, and telecommunications, round out the category's broader industrial footprint.
Market Breakup by Region
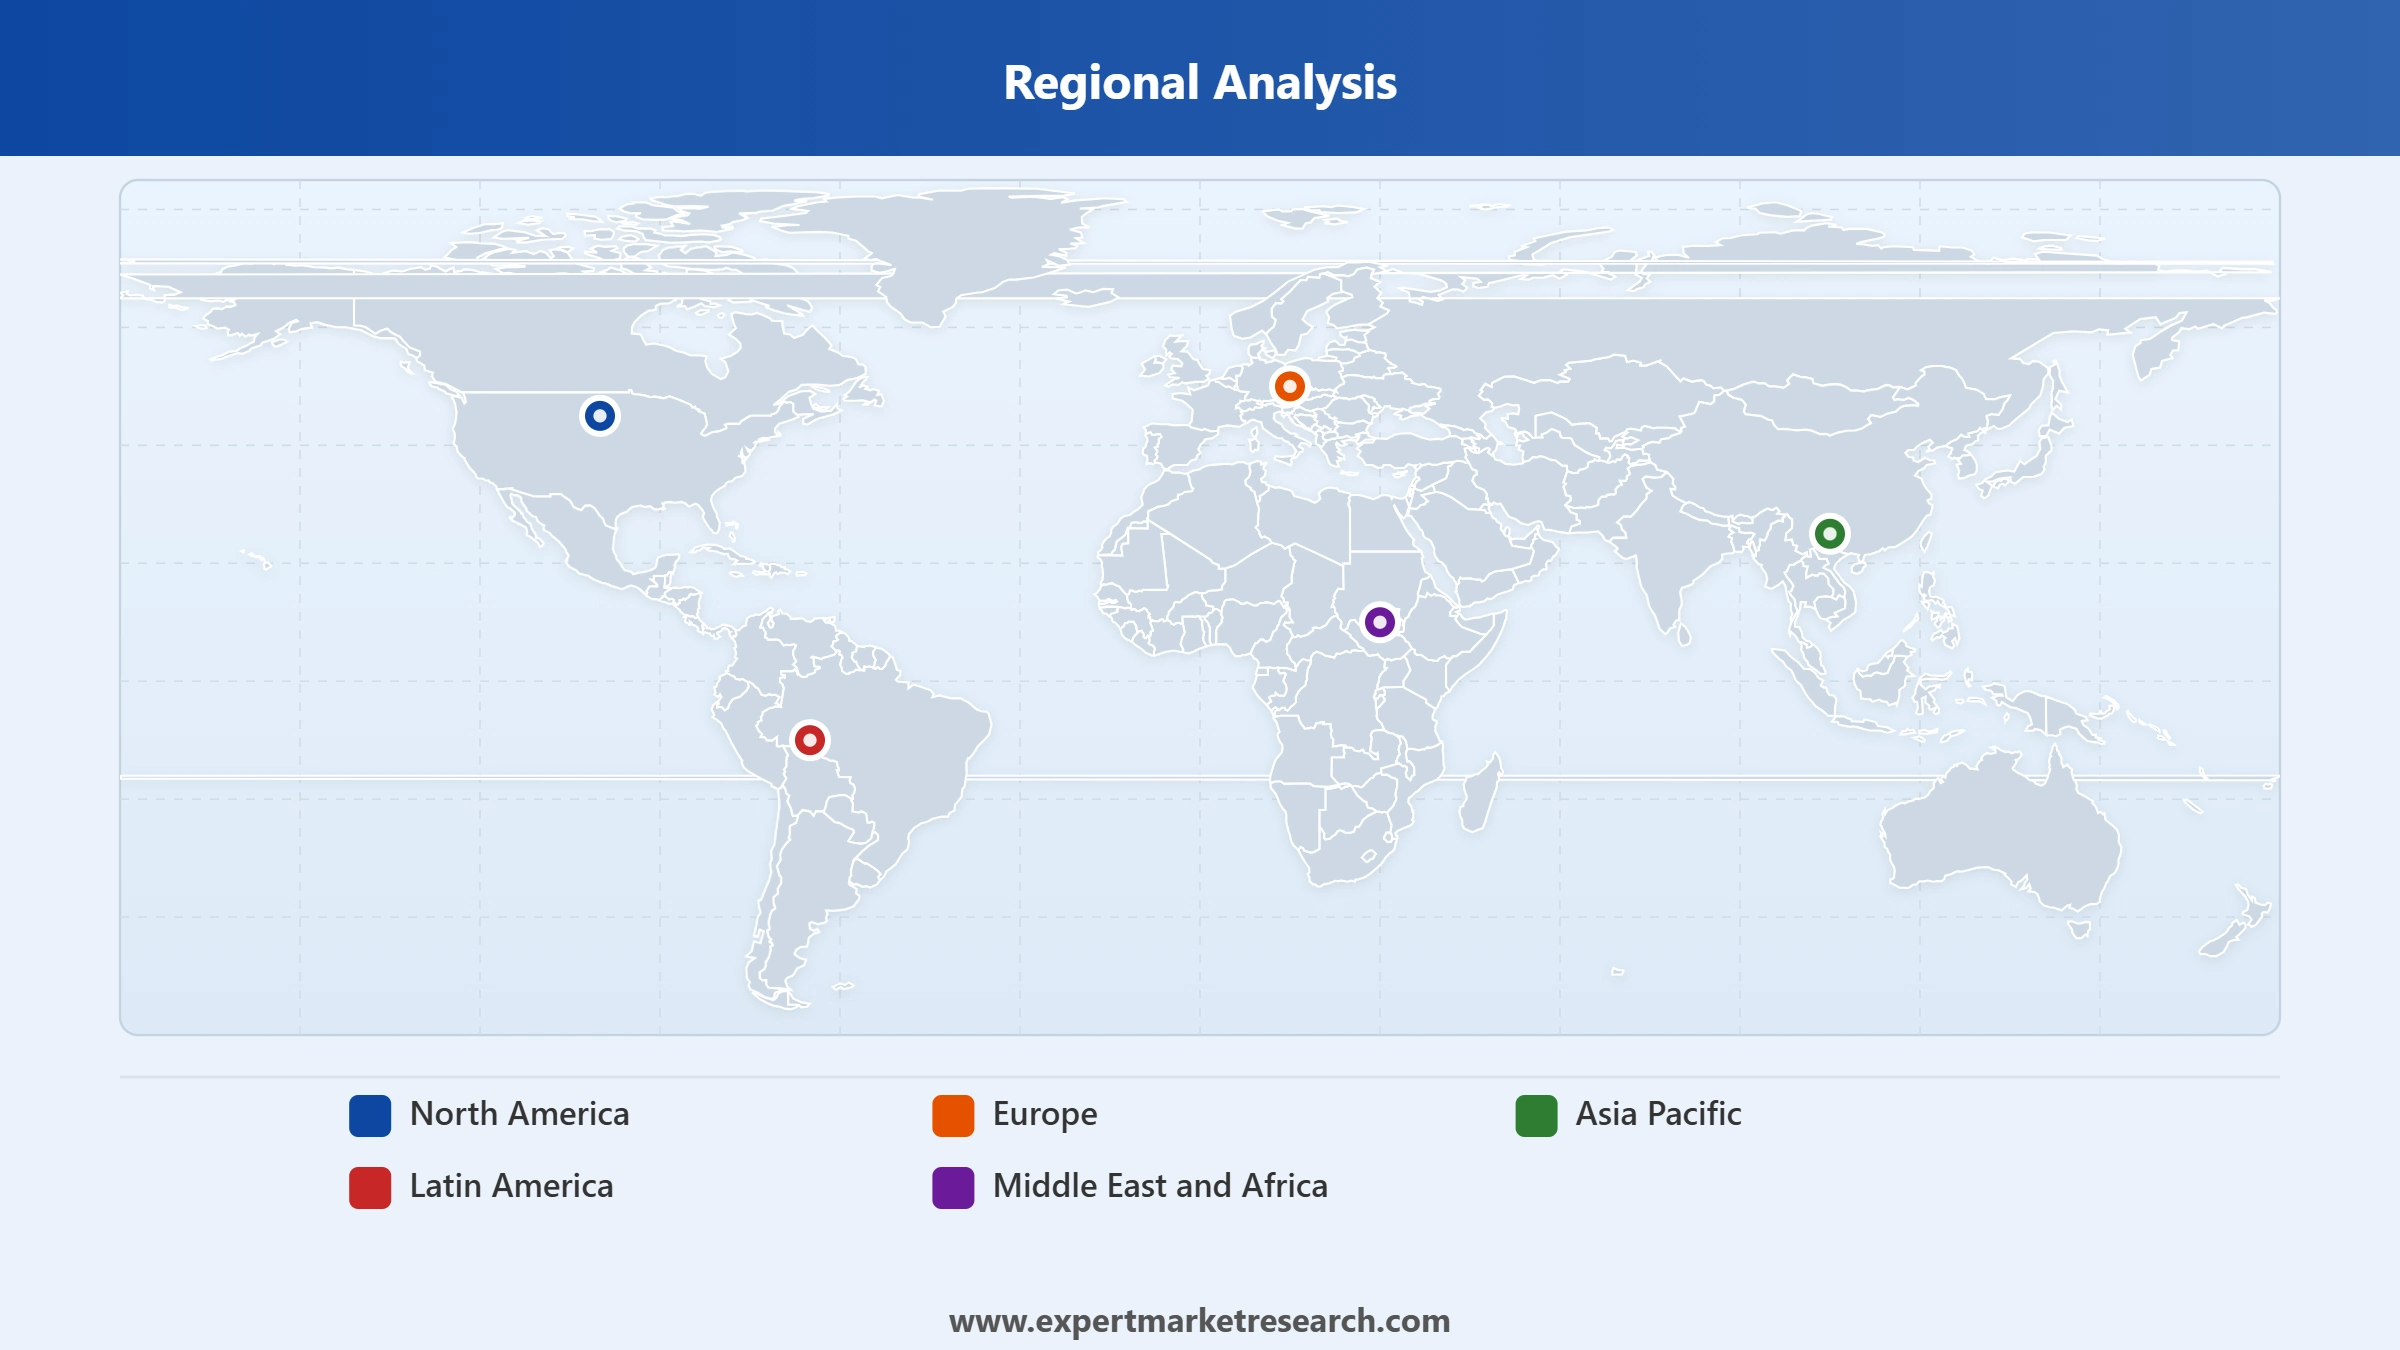
Key Insight: Asia Pacific dominates the precision machining market, supported by large-scale industrial production hubs across China, Japan, and India, alongside strong automation and digital manufacturing adoption throughout the region. In August 2026, for example, India's Commerce and Industry Minister led a delegation of more than 200 representatives across manufacturing, semiconductors, and automotive sectors to Tokyo, Nagoya, and Osaka, building on a July 2026 summit where India and Japan marked 75 years of diplomatic relations and deepened industrial and technology cooperation. North America remains a significant and mature market anchored by established aerospace and defense manufacturing infrastructure. Europe continues to see steady demand tied to strong automotive and industrial machinery manufacturing presence, while Latin America and the Middle East and Africa witness steadier growth tied to expanding industrial and infrastructure investment.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By process type, CNC machining dominates the market due to its high precision and automation capabilities
CNC machining accounts for the largest share of the market by process type, reflecting its high precision, strong automation, and ability to produce complex components efficiently across automotive, aerospace, and industrial manufacturing sectors. Continued digital manufacturing adoption and rising private equity investment in fragmented precision machining shops are reinforcing CNC machining's leading position across the industry.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Milling is a fast-growing process type as advances in multi-axis CNC milling enhance efficiency, allowing for faster production times and reduced operational costs. In 2026, for example, Haas Automation introduced its new VF-2SSYT and VF-4SS vertical machining centers, featuring a high-speed 12,000rpm inline spindle and an updated control system with a 19-inch display, targeting shops requiring greater milling capacity without sacrificing productivity. The flexibility of milling machines to perform multiple operations in one setup continues to reinforce their importance across modern manufacturing.
By material type, metals lead the market due to their ubiquity across aerospace, automotive, and industrial machinery
Metals account for the largest share of the market by material type, reflecting the ubiquity and indispensable nature of metallic components including steels, aluminum alloys, titanium, and superalloys across core end-use sectors requiring structural integrity and durability. In April 2026, for example, AGA Precision Systems, an ITAR-registered and AS9100-certified precision CNC manufacturer, executed a second long-term supply agreement with a globally recognized Tier 1 aerospace and defense company, formalizing an ongoing multi-year supplier relationship.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Composites are a fast-growing material category as extreme environment applications increasingly require superior strength-to-weight characteristics that traditional metals cannot always provide across specialized applications. In June 2026, for example, Continuous Composites was awarded a multi-year contract with the U.S. Army DEVCOM Aviation and Missile Center to advance its CF3D fiber 3D printing technology for current and future missile platform components.
By end-use industry, automotive leads the market due to sustained demand for precision engine and transmission components
Automotive accounts for the largest share of the market by end-use industry, driven by strong demand for precision components used in engines, transmissions, and increasingly electric vehicle motor housings and battery structural components as automakers pursue lightweighting strategies. In February 2026, for example, AISIN Corporation announced a ¥32 billion investment to expand its existing plant and build a new facility in Maharashtra, India, for local production of automatic and continuously variable transmissions, reflecting the country's rapidly growing automotive manufacturing base.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Aerospace and defense is a fast-growing end-use industry as increasing complexity of aircraft components and rising fleet renewal cycles drive demand for tight-tolerance, high-precision parts across commercial and military platforms. In April 2026, for example, SVM Machining executed a long-term supply agreement with Turbo-Jet Products to deliver mission-critical aerospace and defense components, marking the third such agreement signed that year.
Asia Pacific dominates the market due to large-scale industrial production hubs and strong automation adoption
Asia Pacific dominates the Precision Machining market, supported by large-scale industrial production hubs across China, Japan, and India, alongside strong automation and digital manufacturing adoption throughout the region. In May 2026, for example, TDConnex opened its sixth manufacturing facility, an 800,000-square-foot micro-precision campus in Xiamen, China, significantly expanding its metal injection molding capacity to produce high-precision micro-components. Continued expansion of automotive and electronics manufacturing capacity reinforces the region's leading position.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America is a significant and mature market anchored by established aerospace and defense manufacturing infrastructure, with major precision component suppliers continuing to invest in capacity expansion to support aerospace fleet renewal cycles and reshoring of critical manufacturing capability. As of September 2026, announced private-sector U.S. manufacturing investment commitments have crossed $2.070 trillion across 237 companies, reflecting a broad rebuild of domestic industrial capacity spanning aerospace, semiconductors, and strategic manufacturing sectors.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
7.0% |
|
Europe |
7.5% |
|
Asia Pacific |
8.5% |
|
Latin America |
9.0% |
|
Middle East and Africa |
8.5% |
The global market features a fractionated competitive structure favoring larger, well-capitalized firms with established skilled workforces. precision machining companies like Barnes Group, Precision Castparts, and Bodycote are competing primarily through manufacturing scale and long-standing aerospace OEM relationships, while Fabrinet and other manufacturers focus on specialized electro-mechanical and optical precision applications.
Leading precision machining market players are focusing on CNC automation investment, capacity expansion, and strategic corporate restructuring to strengthen their competitive position. Increasing emphasis on Industry 4.0-ready platforms and specialized workforce training is also enabling manufacturers to diversify their customer base while supporting long-term market growth.
Barnes Group, headquartered in Bristol, Connecticut, and founded in 1857, is a diversified industrial and aerospace manufacturer providing highly engineered precision components, tooling systems, and aftermarket repair services. The company's Barnes Aerospace division manufactures complex machined components and provides component repair and overhaul services primarily for aeroengine platforms.
Precision Castparts, headquartered in Lake Oswego, Oregon, and founded in 1949, is a worldwide diversified manufacturer of complex metal components serving the aerospace, power, and general industrial markets. The company, a wholly owned subsidiary of Berkshire Hathaway since 2016, is a market leader in structural investment castings, forged components, and highly engineered critical fasteners for aerospace applications.
Bodycote, headquartered in Macclesfield, United Kingdom, and founded in 1923, is a global provider of thermal processing services including heat treatment, metal joining, and hot isostatic pressing that support precision-machined component performance across aerospace, automotive, and industrial markets. The company operates a global network of specialist facilities serving precision component manufacturers worldwide.
Fabrinet, headquartered in Bangkok, Thailand, and founded in 2000, provides advanced precision optical, electro-mechanical, and electronic manufacturing services to OEM customers across optical communications, industrial lasers, and medical device markets. The company operates large-scale manufacturing campuses supporting high-precision, high-reliability component production for demanding technology applications.
Other key players in the market report include NN, Inc., Amada Co., Ltd., DMG Mori Co., Ltd., Makino Milling Machine Co., Ltd., and Haas Automation, Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the precision machining market 2026-2035 with our in-depth report. Gain strategic insights, future forecasts, and key market developments that can help you stay competitive. Download a free sample report or contact our team for customized consultation on the market trends 2026.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the precision machining market reached an approximate value of USD 123.54 Billion.
The market is projected to grow at a CAGR of 8.10% between 2026 and 2035.
The key players in the market include Barnes Group Inc., Precision Castparts Corp., Bodycote plc, NN, Inc., Fabrinet, Amada Co., Ltd., DMG Mori Co., Ltd., Makino Milling Machine Co., Ltd., and Haas Automation, Inc., among others.
Leading manufacturers are pursuing CNC automation investment, capacity expansion, and strategic corporate restructuring to strengthen market position.
Key challenges include high entry costs, operational complexity, and increasing consolidation pressure that create difficulty for smaller firms to compete.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Process Type |
|
|
Breakup by Material Type |
|
|
Breakup by End-Use Industry |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




