

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
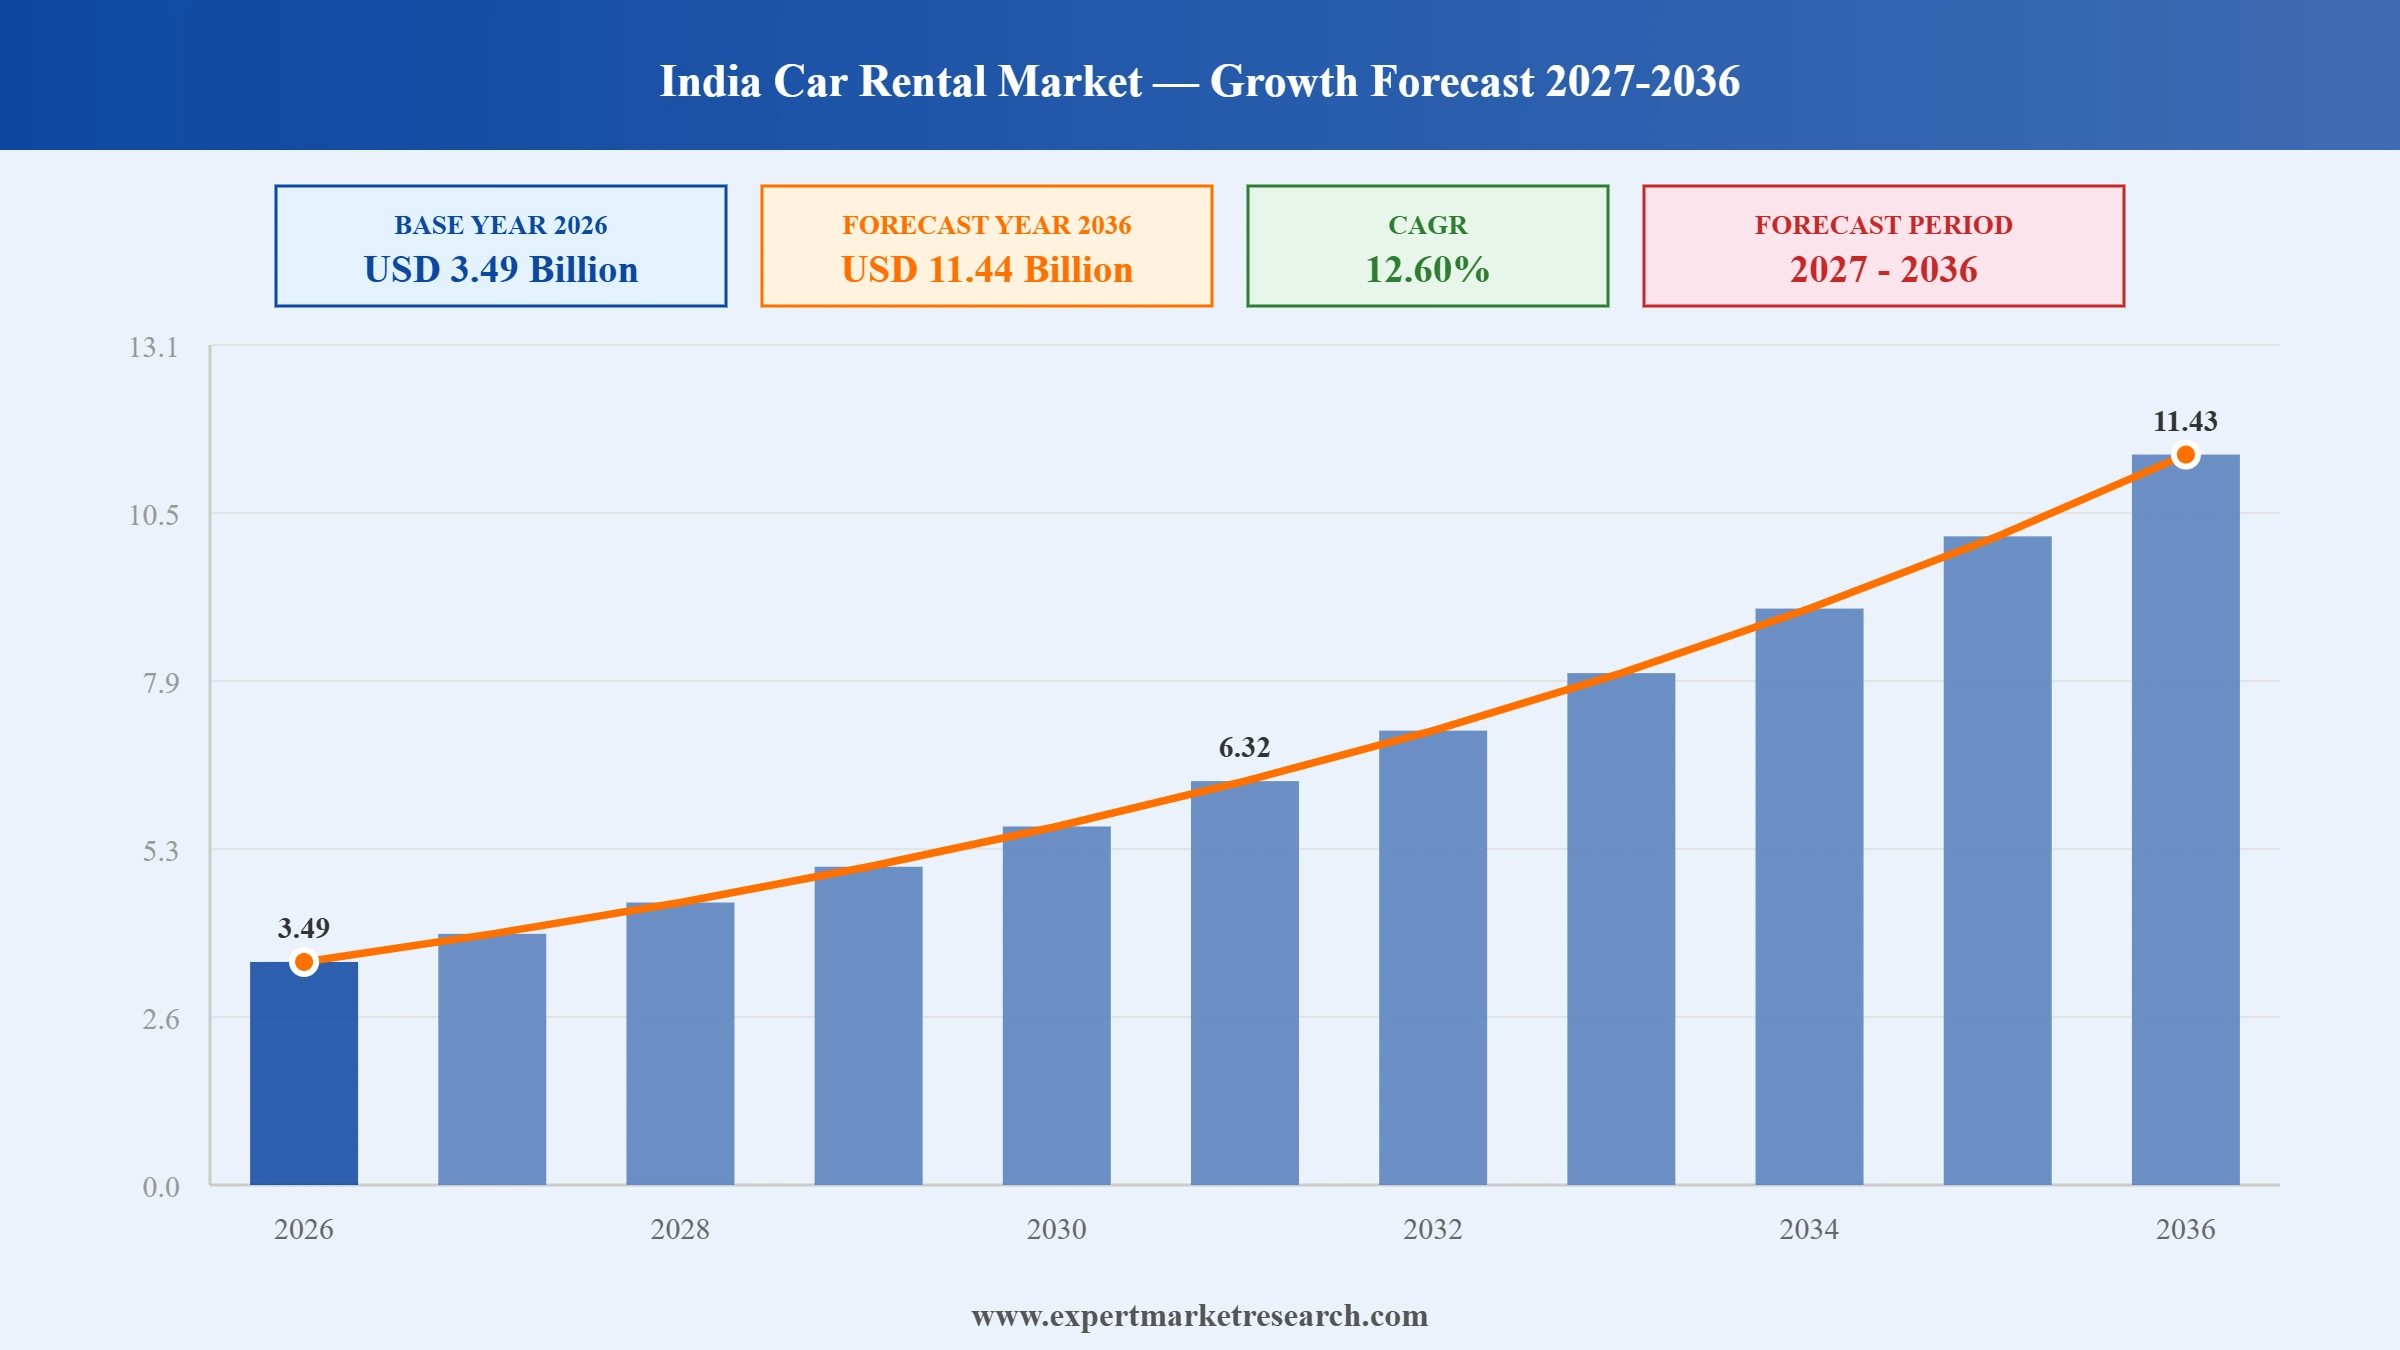
The India car rental market attained a value of USD 3.10 Billion in 2025 and is projected to grow at a CAGR of 12.60% through 2035, reaching USD 10.16 Billion by 2035, driven by rising urban mobility demand, expanding online booking platforms, and growing corporate and tourism-linked travel across the country.
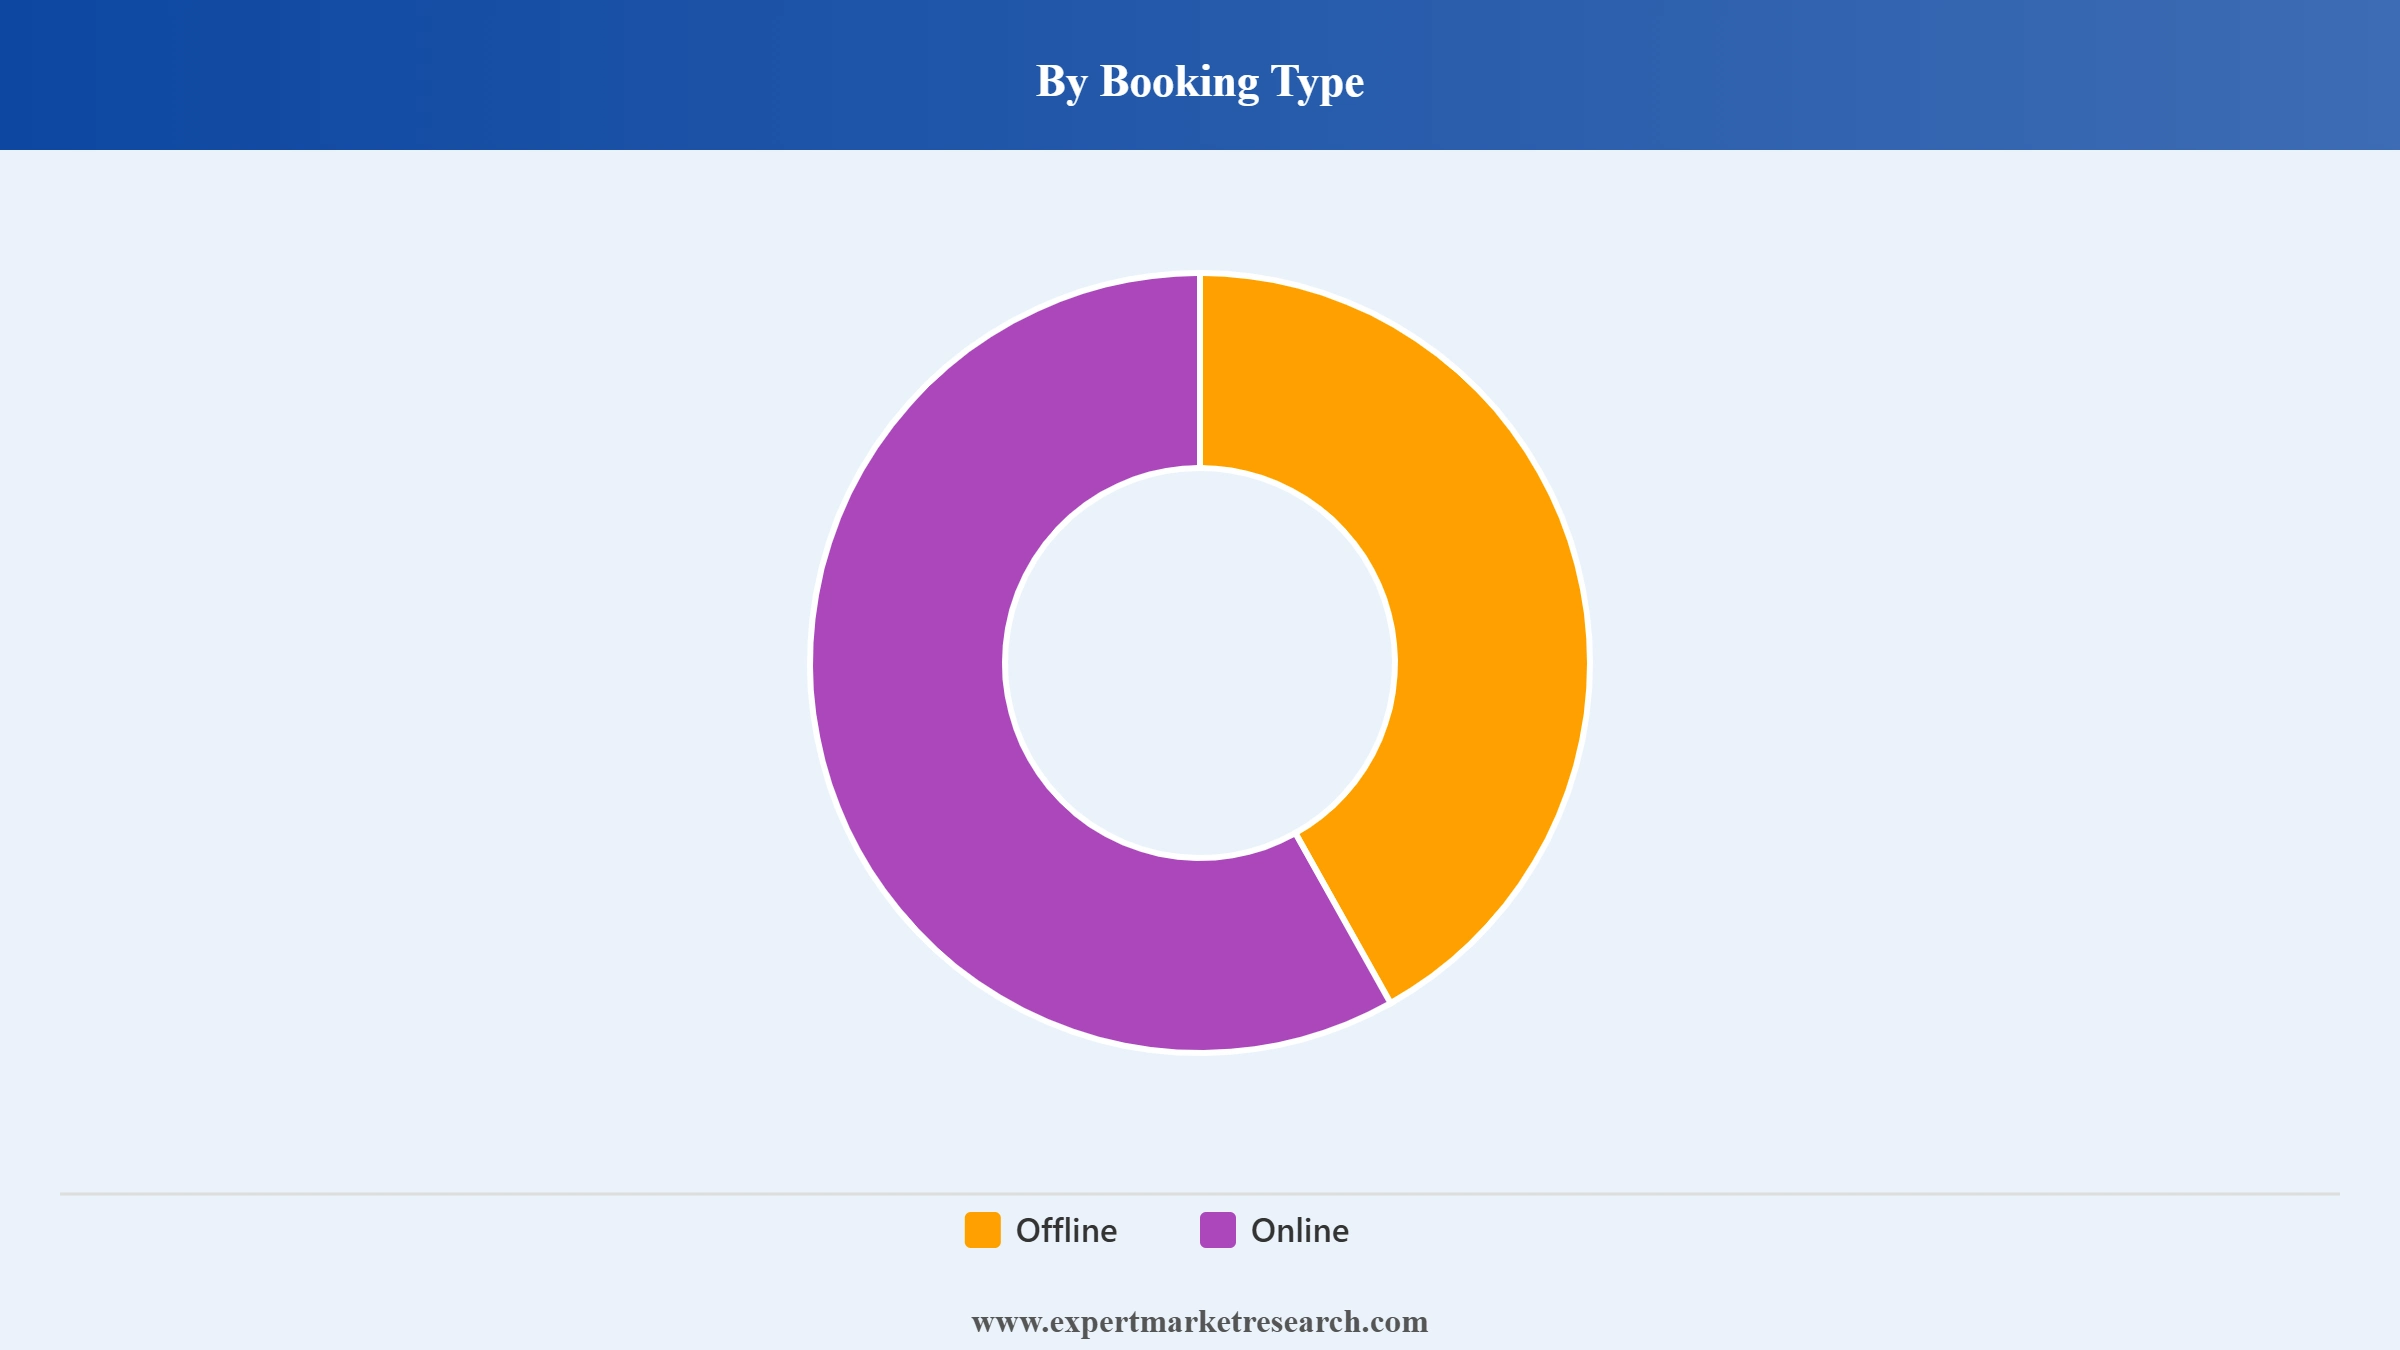
Rising urban mobility demand and expanding digital booking infrastructure continue to anchor steady demand across the India car rental market. Online bookings accounted for approximately 66.85 percent of the market in 2025, expanding at a projected 7.60 percent CAGR, as platforms streamline payments and real-time fleet tracking for time-pressed urban and business travellers nationwide.
The India car rental market is witnessing further developments as chauffeur-driven operators expand beyond traditional domestic corporate travel into global mobility partnerships. Eco Mobility partnered with SIXT in March 2026 to extend its corporate clients access to self-drive fleets across more than 105 countries, reflecting rising demand for consistent international mobility solutions among Indian corporate travellers.
In addition, self-drive platforms are increasingly diversifying beyond traditional four-wheeler rentals to capture higher-frequency, shorter-duration urban trips. Zoomcar expanded into motorcycle and scooter rentals within its existing app in Bengaluru in September 2026, targeting India's growing two-wheeler rental segment as a complement to its core self-drive car business.
Read more about this report - Request a Free Sample
Self-drive car rental platforms are increasingly diversifying into adjacent high-frequency mobility categories to capture daily commuting trips beyond occasional car use. Zoomcar Holdings added motorcycle and scooter rentals alongside its existing car inventory in Bengaluru in September 2026, targeting India's two-wheeler rental segment as a test market before evaluating expansion to other high-density cities through local partners and OEM collaborations. Companies can extend established self-drive platforms into adjacent vehicle categories to capture higher-frequency urban trip occasions beyond occasional car rental.
Peer-to-peer self-drive platforms continue integrating with established ride-hailing networks to offer travellers a single app for comparing ownership-free mobility options. Zoomcar Holdings announced a partnership with Uber Technologies in August 2026, letting users book both self-drive cars and Uber Intercity chauffeur-driven rides inside the Zoomcar app, launching in Bengaluru, Delhi NCR, and Mumbai with further city expansion planned. Companies can integrate complementary mobility networks to offer travellers a single platform for comparing ownership-free transportation choices.
Chauffeur-driven operators focused on domestic corporate travel are increasingly forming international partnerships to serve clients requiring consistent mobility solutions abroad. Eco Mobility partnered with SIXT in March 2026, granting its corporate clients access to SIXT's fleet of more than 350,000 vehicles across over 105 countries and 2,000 rental locations, marking a shift beyond its historical focus on domestic chauffeur-driven transportation. Companies can pursue international fleet-access partnerships to serve corporate clients whose mobility needs extend beyond domestic borders.
Automotive digital platforms with self-drive rental arms continue navigating consolidation pressure across India's crowded auto-tech landscape. Girnar Software, parent of the CarDekho platform and its Revv self-drive rental brand, and CarTrade Tech mutually terminated merger discussions in November 2025 that would have combined their automotive classifieds businesses, maintaining the current competitive landscape across the sector. Companies can maintain independent strategic flexibility by exiting merger discussions that no longer align with long-term business priorities.
Premium chauffeur-driven operators continue expanding beyond domestic corporate travel to capture high-value international limousine and airport transfer demand. Carzonrent introduced its Global Limousine Services offering across 30 cities worldwide in March 2026, extending its premium mobility solutions beyond India to serve corporate clients travelling internationally for business and leisure purposes. Companies can extend premium domestic service models into international markets to capture high-value corporate travel demand beyond home-market borders.
Government incentive programmes continue playing a central role in accelerating commercial electric vehicle adoption across India's car rental sector. The PM E-DRIVE scheme, running through March 2026, reimburses qualifying commercial EV operators up to Rs 10,000 per kilowatt-hour, offsetting between 15 and 20 percent of upfront vehicle costs and driving fleet electrification among rental operators seeking to reduce long-term operating expenses. Companies can leverage government incentive schemes to accelerate fleet electrification while offsetting the higher upfront cost of electric vehicles.
Self-drive rental platforms are increasingly capturing share from traditional chauffeur-driven formats as younger, digitally native consumers favour flexible, app-based access over full-service transportation. Industry data published in July 2026 showed self-drive rentals growing at a projected 7.92 percent CAGR, faster than the broader market's 7.27 percent rate, with long-term subscription formats accelerating even faster at 9.18 percent as consumers increasingly treat vehicle access as a flexible monthly commitment rather than a one-time transaction. Companies can prioritise flexible subscription-style offerings to capture the fastest-growing segment within the broader self-drive category.
Airport-linked car rental demand continues outpacing the broader market as domestic and international air travel volumes recover and expand across major Indian gateway cities. A July 2026 industry analysis placed airport rental growth at approximately 8.39 percent CAGR, well ahead of the broader market's 7.27 percent pace, as operators expand dedicated airport counters and strengthen pre-booking integrations with airline and travel-booking platforms nationwide. Companies can expand dedicated airport rental infrastructure to capture accelerating demand tied to rising domestic and international air travel volumes.
This Expert Market Research Report titled "India Car Rental Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Booking Type
Key Insight: Online accounts for the largest share of the market, reflecting rising smartphone penetration and consumer preference for transparent, real-time price comparison across platforms nationwide. Offline continues to serve customers in tier-2 and tier-3 cities where digital payment infrastructure and app-based platforms remain less established, alongside corporate accounts preferring direct negotiated arrangements. Online is also the fastest-growing booking type at a projected 7.60 percent CAGR, reinforced by Zoomcar's August 2026 partnership with Uber, integrating self-drive and chauffeur-driven booking within a single app.
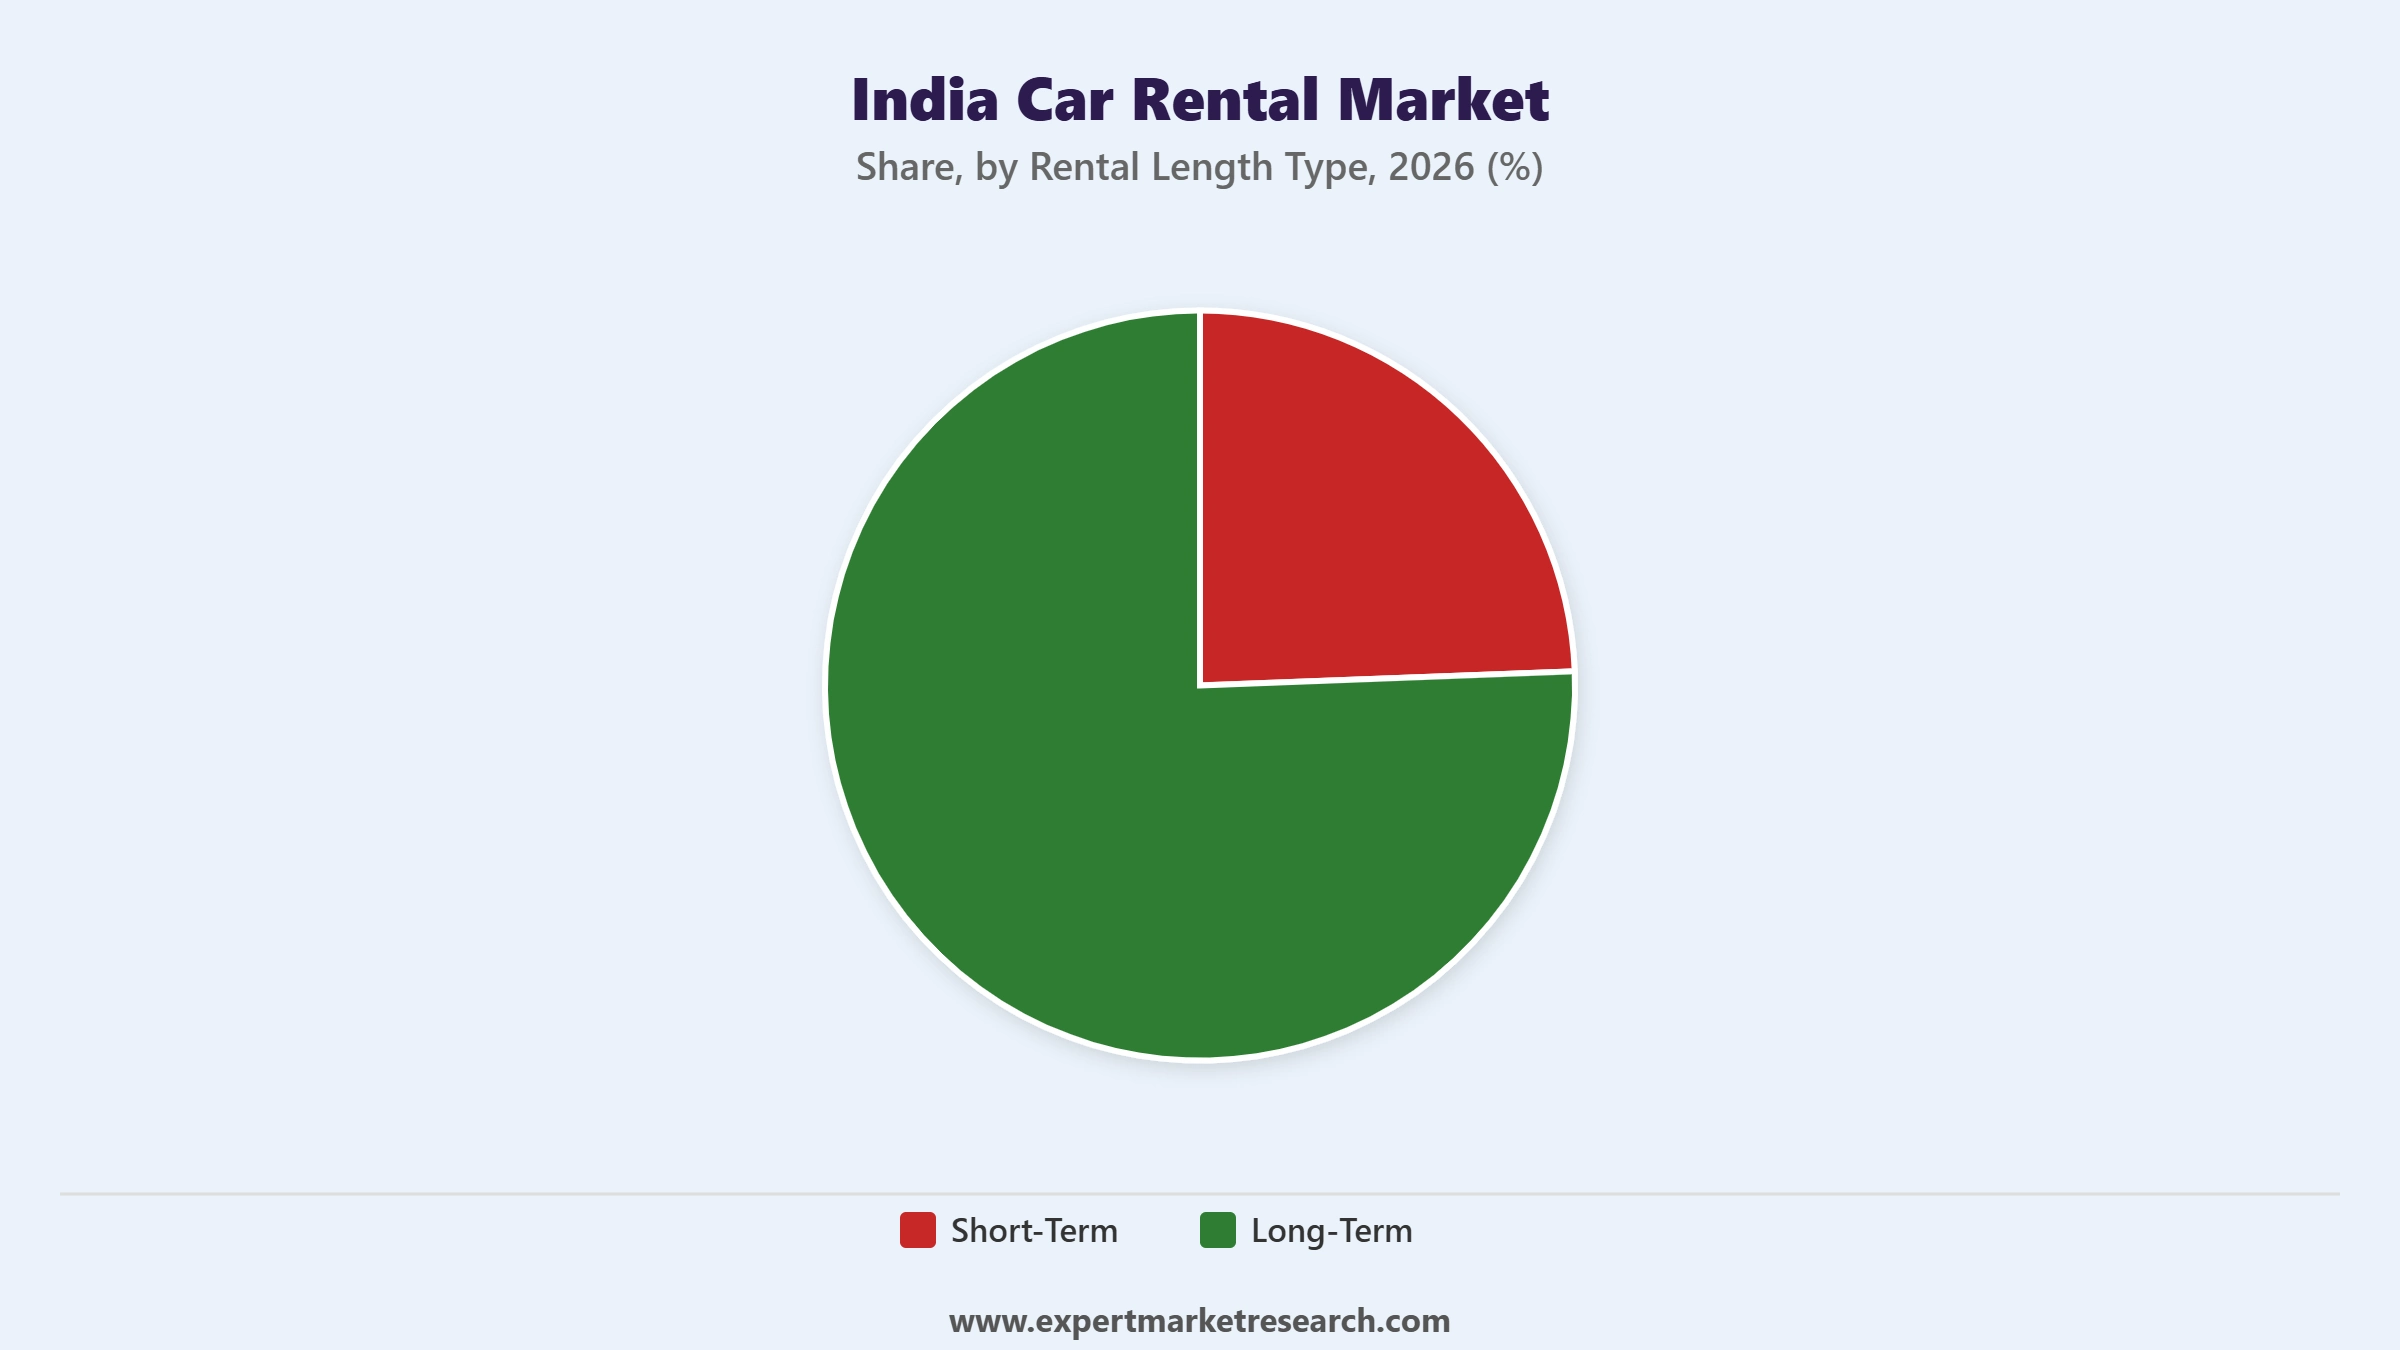
Market Breakup by Rental Length Type
Key Insight: Short-Term accounts for the largest share of the market, reflecting sustained demand for occasional trips, airport transfers, and short business or leisure travel needs across the country. Long-Term is growing fastest at a projected 9.18 percent CAGR as subscription-style vehicle access gains traction among consumers seeking ownership alternatives, illustrated by Eco Mobility's March 2026 partnership with SIXT extending long-term corporate mobility access to more than 105 countries.
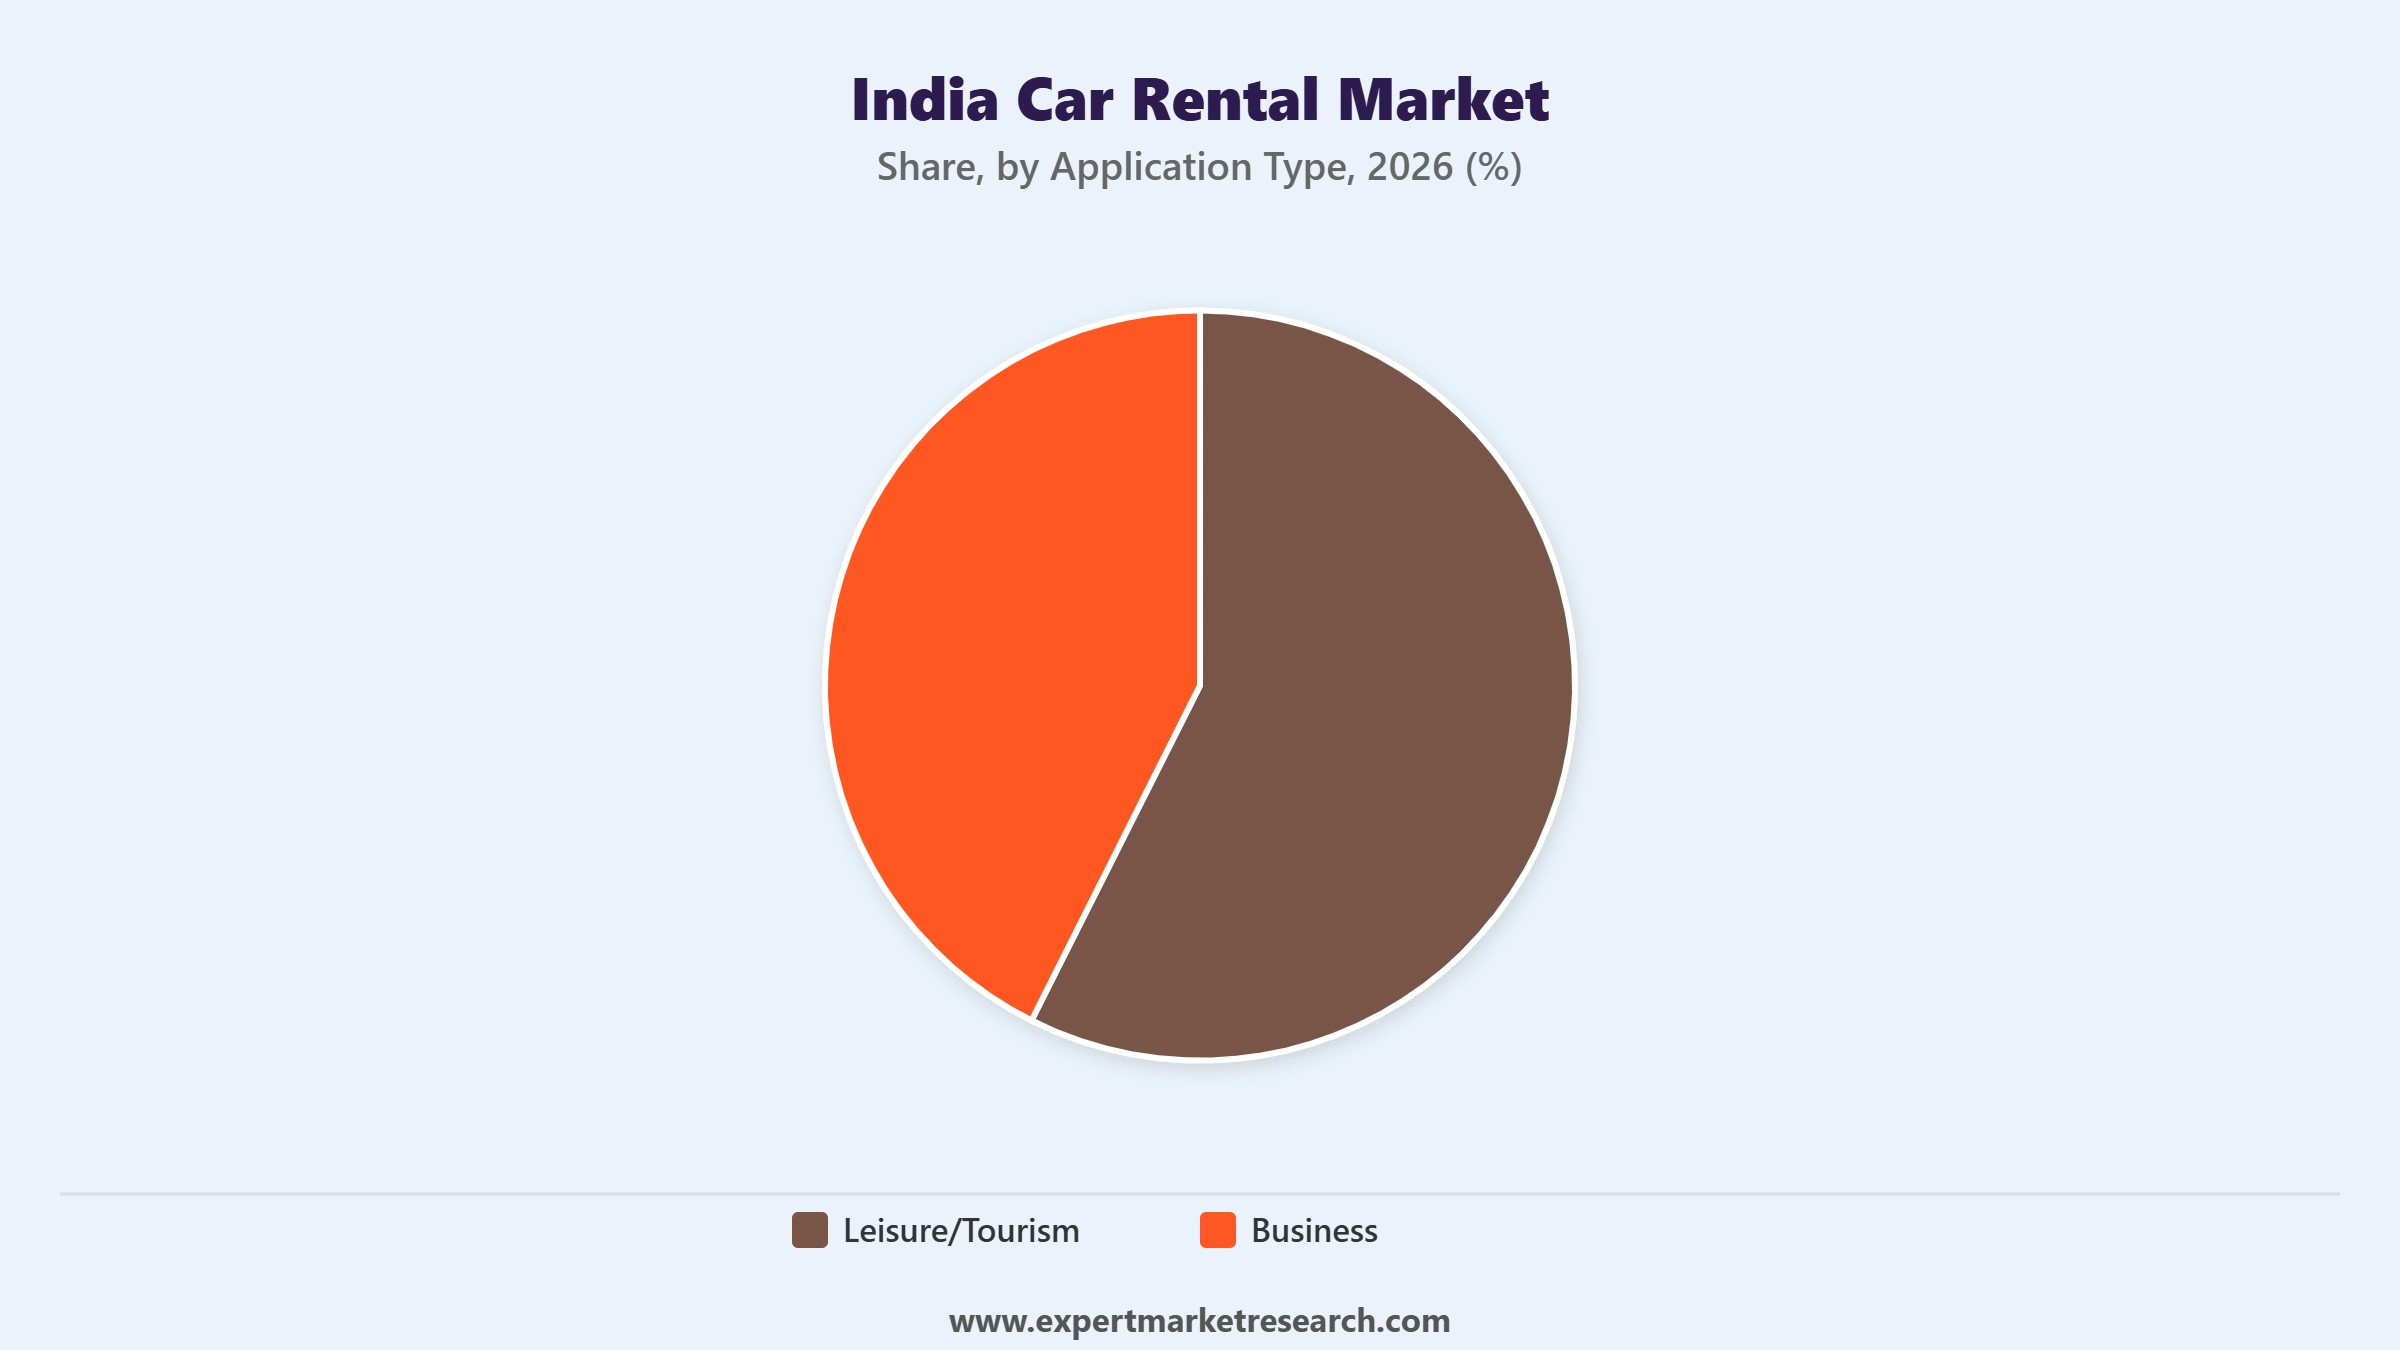
Market Breakup by Application Type
Key Insight: Leisure/Tourism accounts for the largest share of the market, supported by rising domestic travel volumes and expanding tourism infrastructure across popular Indian destinations. Business continues to represent substantial demand tied to corporate travel and airport transfers, reinforced by Carzonrent's March 2026 launch of Global Limousine Services across 30 cities worldwide, extending premium business travel solutions for corporate clients travelling internationally.
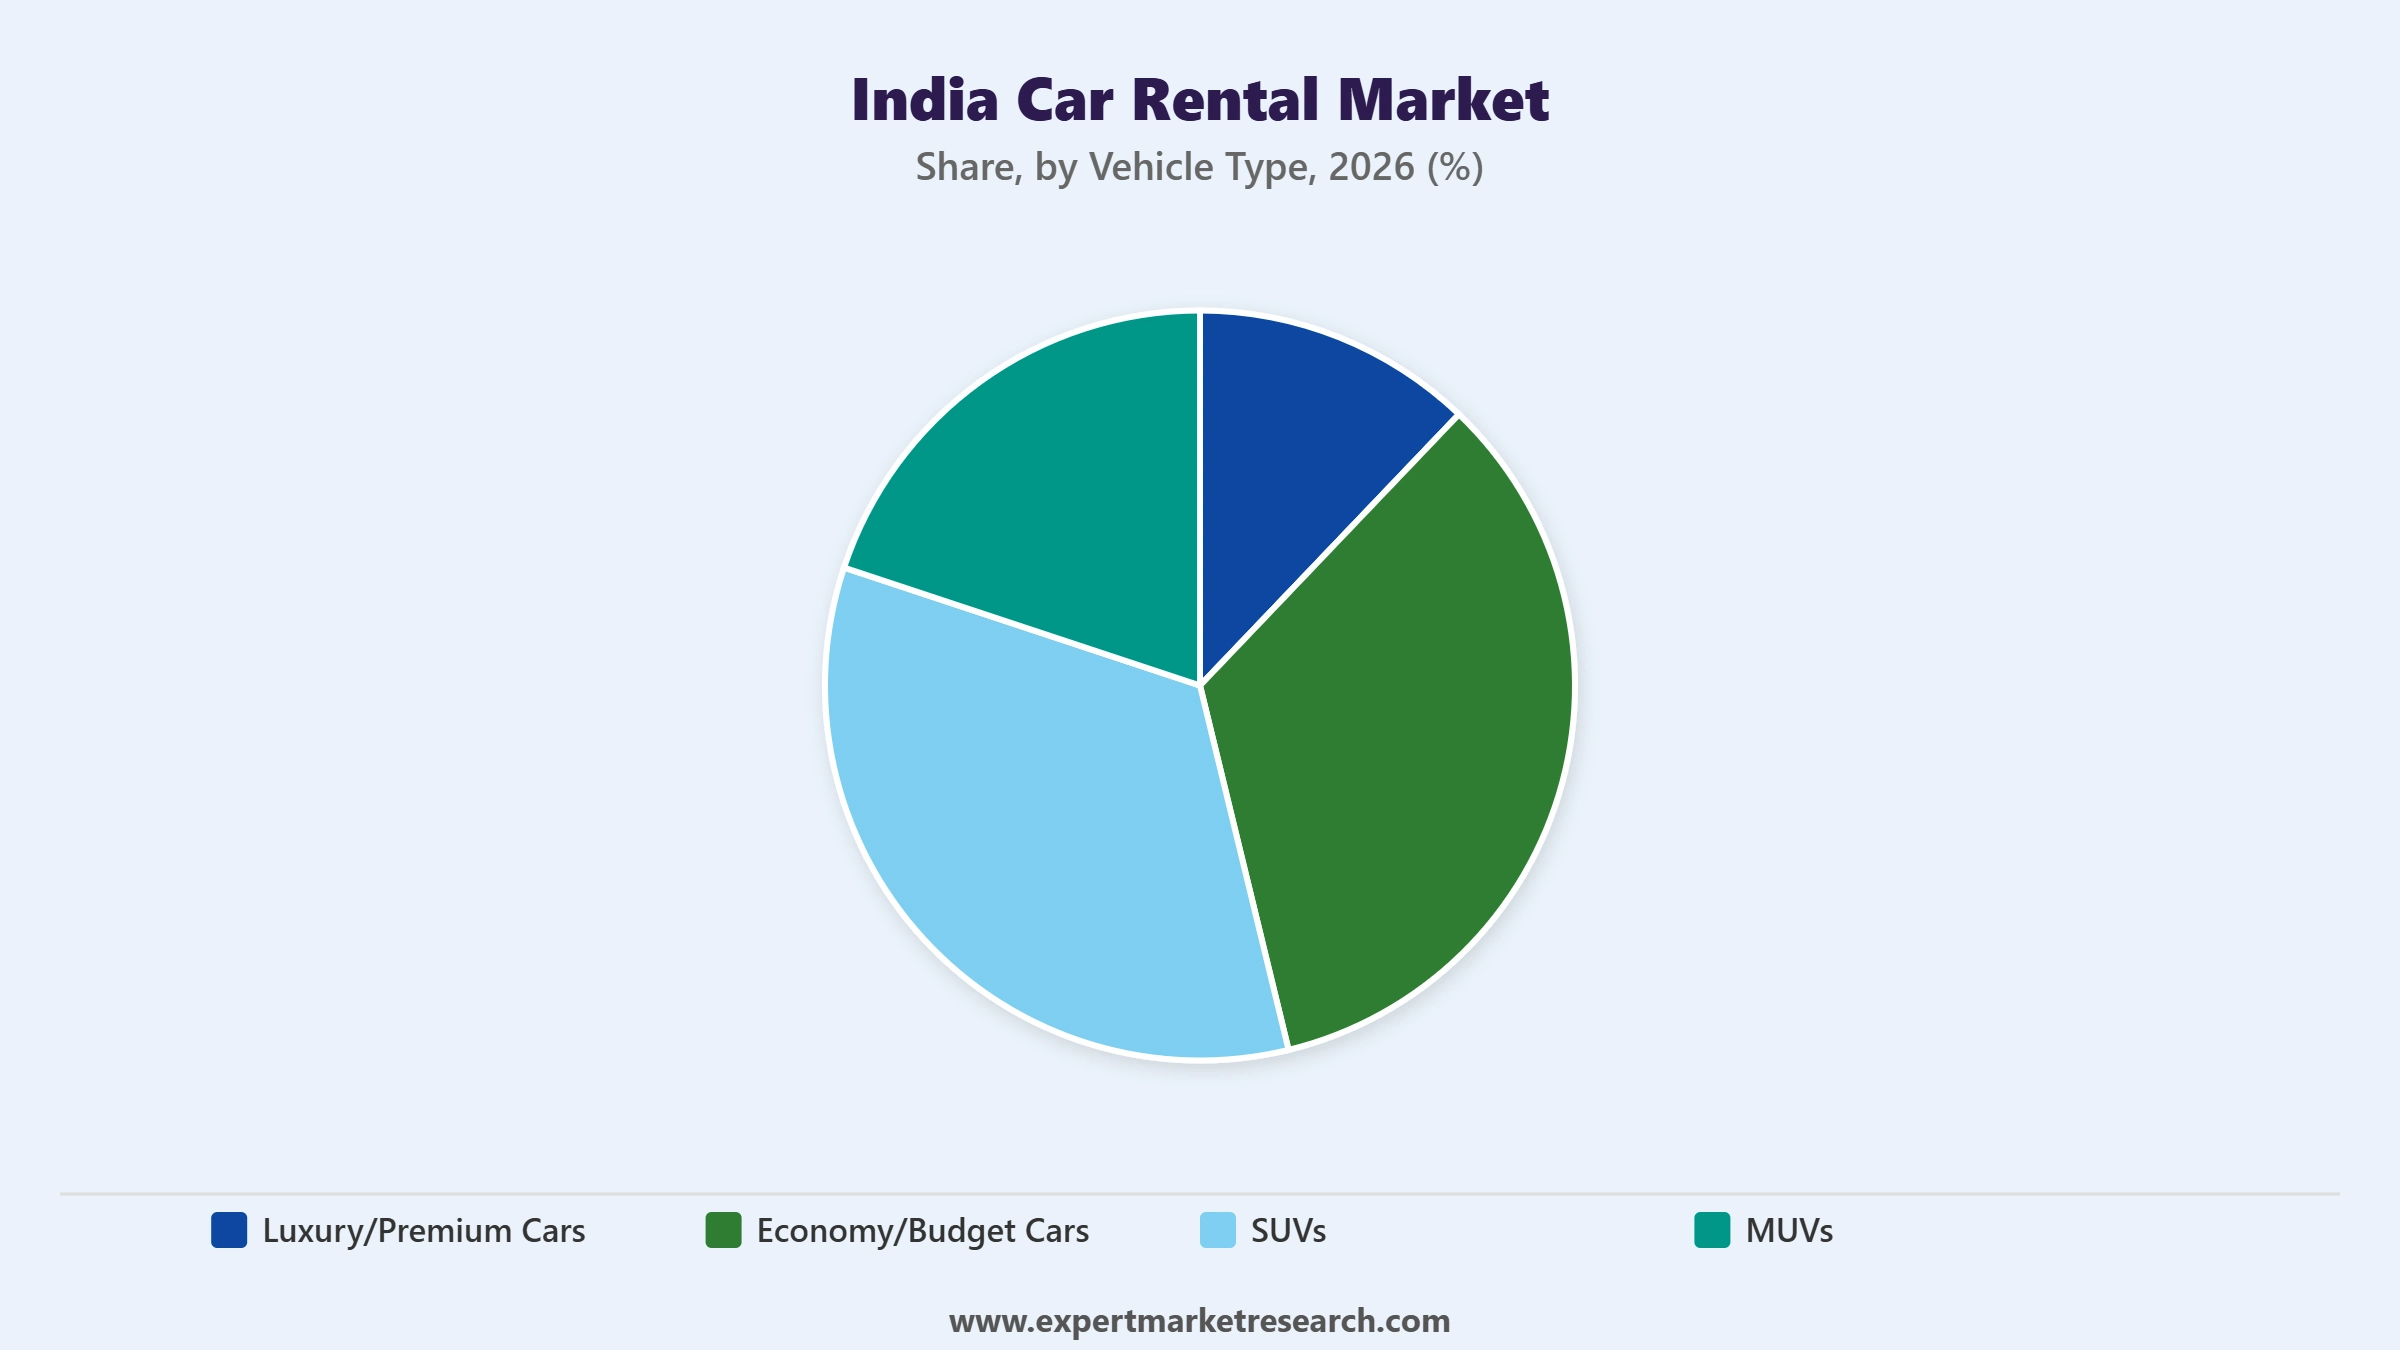
Market Breakup by Vehicle Type
Key Insight: Economy/Budget Cars accounts for the largest share of the market at approximately 71.88 percent, reflecting broad affordability across price-sensitive urban and tier-2 city consumers nationwide. Luxury/Premium Cars serves corporate and high-end leisure travellers through operators including Eco Mobility and Carzonrent's chauffeur-driven fleets. SUVs and MUVs continue to gain share as multi-passenger and outstation travel demand rises across family and group bookings, illustrated by Zoomcar's September 2026 expansion into motorcycle and scooter rentals in Bengaluru, reflecting the broader category's diversification across vehicle formats and passenger capacities.
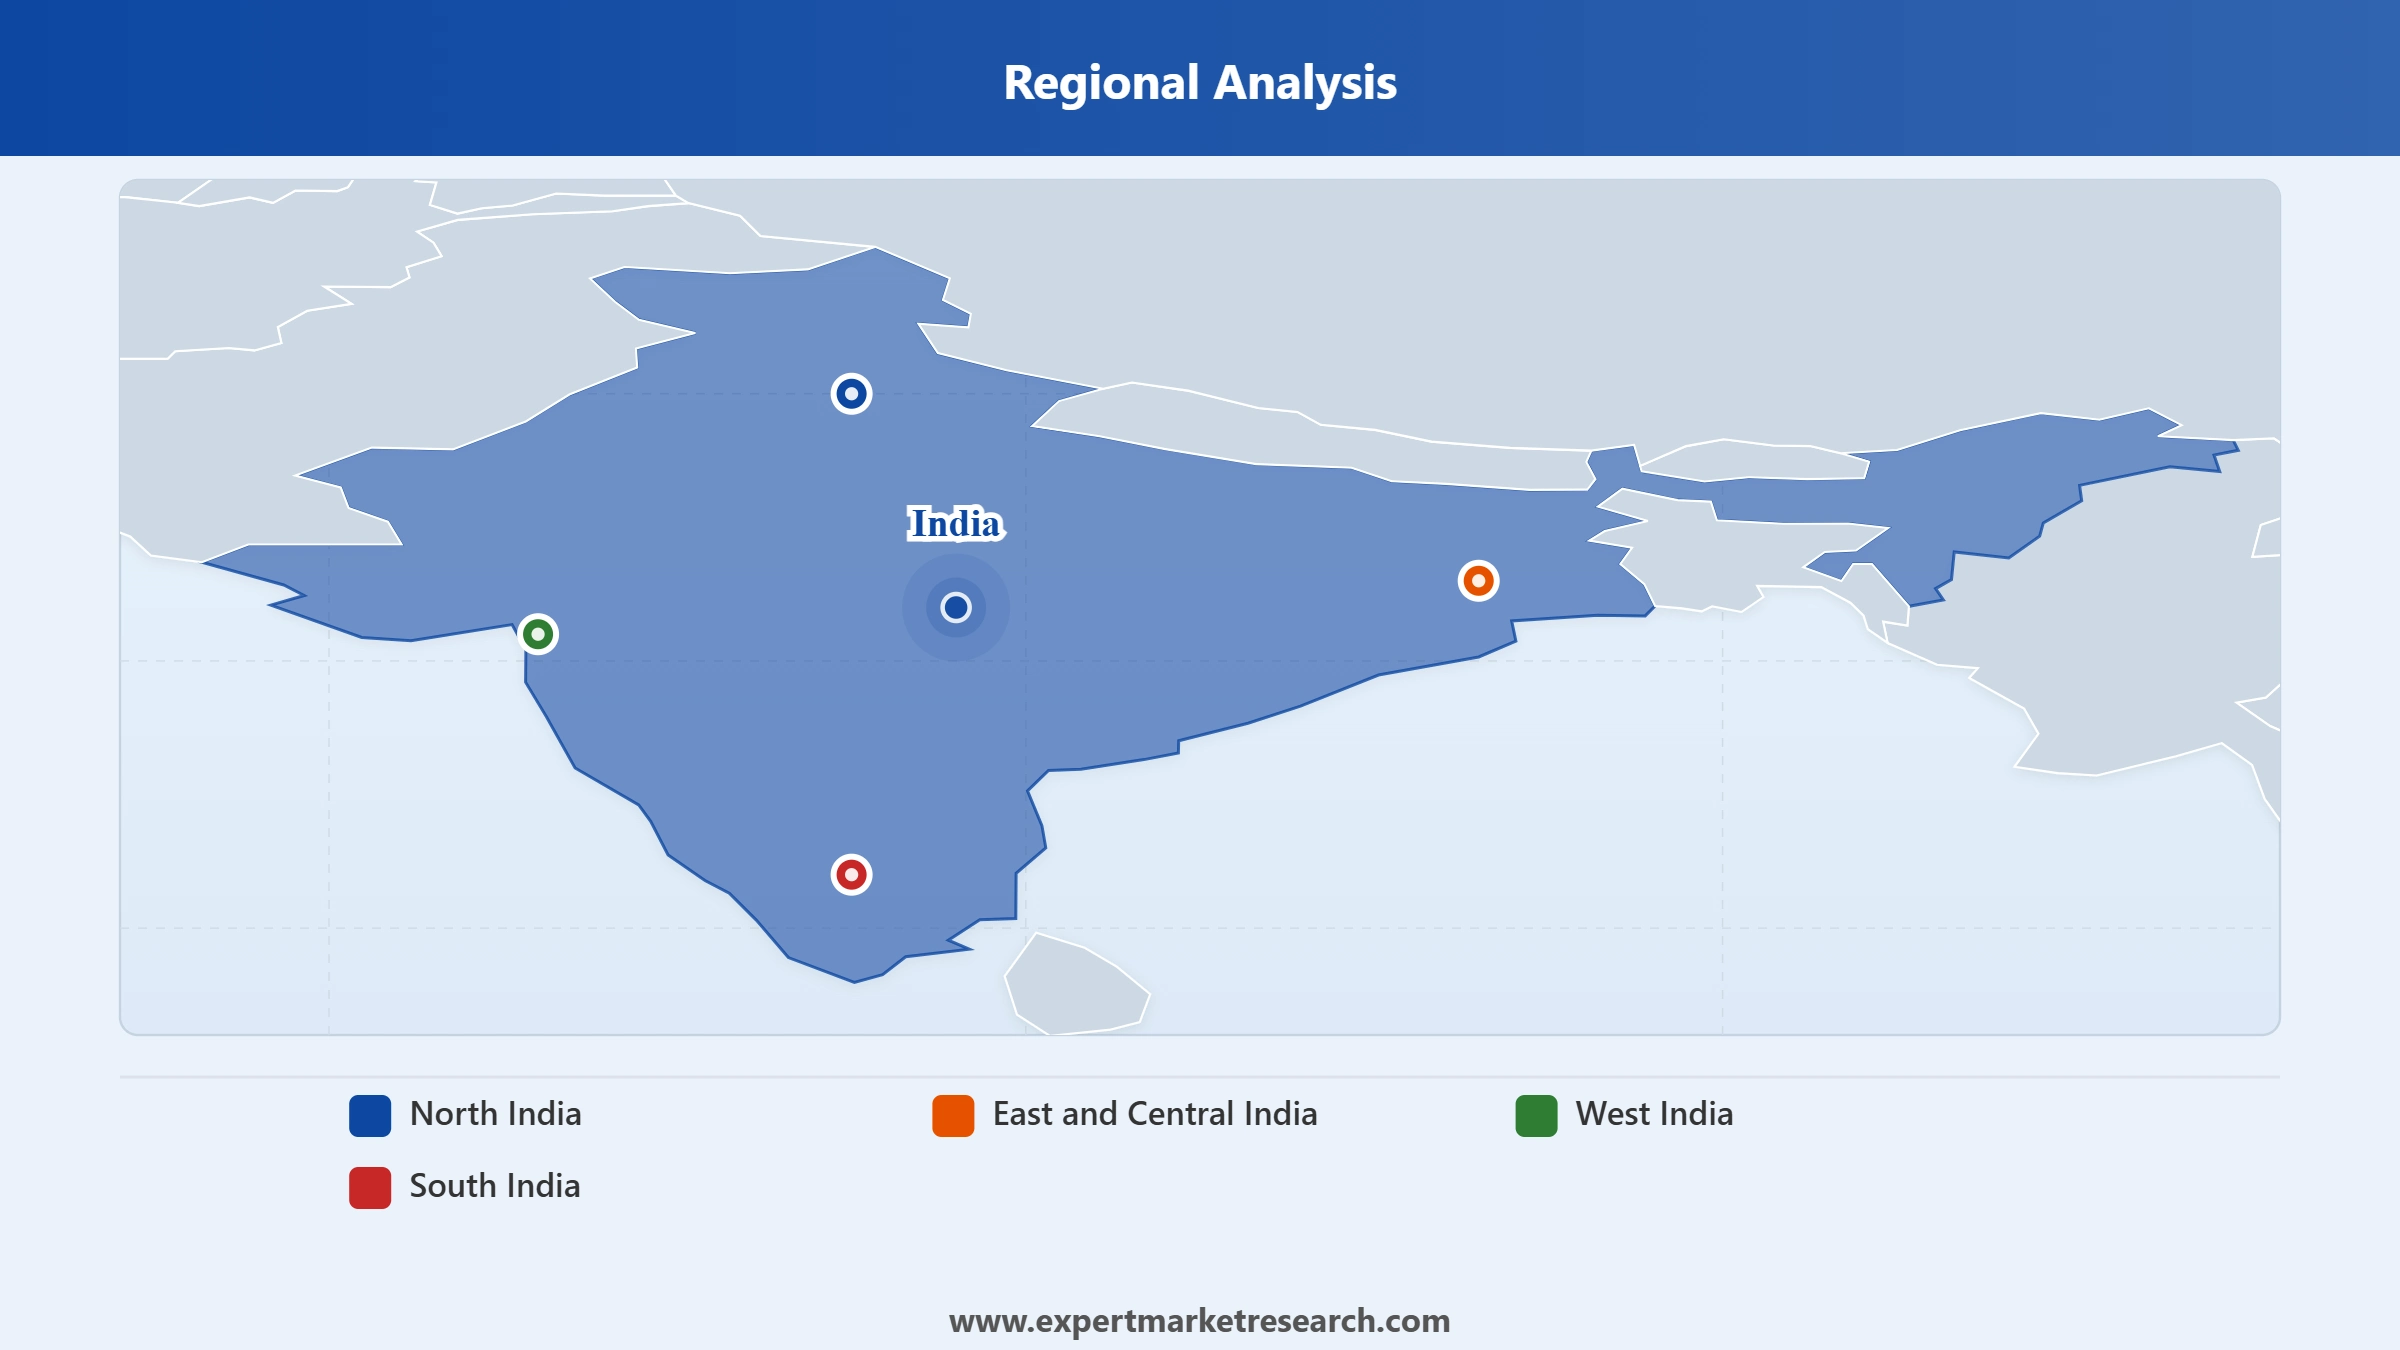
Market Breakup by Region
Key Insight: North India accounts for the largest share of the market, anchored by Delhi NCR's concentrated corporate travel and airport transfer demand across the National Capital Region, reinforced by heightened chauffeur-driven demand tied to the 18th BRICS Summit hosted in New Delhi in September 2026, which brought increased official delegation and business travel movement to the capital. West India continues to represent substantial demand tied to Mumbai and Pune's dense corporate and tourism travel corridors. East and Central India serves a smaller but steadily expanding base as tier-2 city infrastructure improves. South India is growing fastest at an estimated 8.10 percent CAGR, driven by concentrated IT-sector corporate travel demand and expanding tourism infrastructure across Bengaluru, Chennai, and Hyderabad.
Read more about this report - Request a Free Sample
Online continues to account for the largest share of the market, reflecting rising smartphone penetration and consumer preference for transparent, real-time price comparison across platforms. Online bookings held approximately 66.85 percent share of the market in 2025, according to industry data published in July 2026, underscoring the scale of the shift toward digital-first booking channels nationwide.
Read more about this report - Request a Free Sample
Offline is growing more slowly as digital adoption accelerates, though it continues to serve corporate accounts preferring negotiated arrangements. Girnar Software's Revv self-drive brand, operated under the same parent as CarDekho, continues to serve both online and offline booking channels following the November 2025 termination of merger talks with CarTrade Tech, preserving its independent distribution strategy.
Short-Term continues to account for the largest share of the market, reflecting sustained demand for occasional trips, airport transfers, and short business or leisure travel needs nationwide. Industry estimates published in July 2026 valued the overall India car rental market at approximately USD3.37 billion, with short-term formats continuing to anchor the bulk of transaction volume.
Read more about this report - Request a Free Sample
Long-Term is the fastest-growing rental length type at a projected 9.18 percent CAGR. Monthly subscription-based rentals, offered by platforms including Myles and Revv, have emerged as a distinct long-term format serving consumers who prefer flexible vehicle access without full ownership commitments, according to industry data published in June 2026.
Leisure/Tourism continues to account for the largest share of the market at approximately 57.74 percent, according to industry data published in July 2026, supported by rising domestic travel volumes and expanding tourism infrastructure across popular Indian destinations nationwide.
Read more about this report - Request a Free Sample
Business is growing fastest as airport-linked corporate travel accelerates, with industry data published in July 2026 showing airport rentals growing at a projected 8.39 percent CAGR, faster than the overall market, as operators expand dedicated airport counters and pre-booking integrations nationwide.
Economy/Budget Cars continues to account for the largest share of the market at approximately 71.88 percent, according to industry data published in July 2026, reflecting broad affordability across price-sensitive urban and tier-2 city consumers nationwide. Competitive daily rates starting from approximately Rs 800, offered by leading self-drive platforms, continue to anchor demand within this dominant price-sensitive vehicle tier.
Read more about this report - Request a Free Sample
SUVs and MUVs are growing fastest as multi-passenger and outstation travel demand rises across family and group bookings nationwide. ORIX's MyChoize brand offers more than 25 vehicle variants spanning hatchbacks, sedans, SUVs, MUVs, and crossovers across nine Indian cities as of 2026, reflecting sustained multi-passenger fleet investment supporting outstation and family travel occasions.
Major corporate hubs and Indira Gandhi International Airport continue to anchor the region's outsized contribution to national car rental demand, supported by dense highway connectivity linking Delhi NCR to surrounding tourist destinations across North India.
Read more about this report - Request a Free Sample
West India continues to represent substantial demand tied to Mumbai and Pune's dense corporate and tourism travel corridors, while East and Central India serves a smaller but steadily expanding base as tier-2 city infrastructure improves. South India is the fastest-growing region at an estimated 8.10 percent CAGR, driven by concentrated IT-sector corporate travel demand and expanding tourism infrastructure across Bengaluru, Chennai, and Hyderabad, reinforced by Zoomcar's continued platform expansion within the region.
The industry is fragmented, with India car rental market companies ranging from asset-light self-drive platforms to established chauffeur-driven operators competing across booking type, rental length, application, and vehicle type segments nationwide.
Competitive dynamics among India car rental players are increasingly shaped by the depth of digital booking integration, the breadth of fleet diversification beyond traditional four-wheelers, and the strength of international partnership networks. Operators are investing in app-based platforms, subscription models, and cross-border mobility alliances to secure long-term relationships with both individual and corporate customers.
Founded in 2013 and headquartered in Bengaluru, India, Zoomcar is India's largest peer-to-peer self-drive car-sharing marketplace, connecting private vehicle owners with renters across more than 100 cities in India, Indonesia, Vietnam, and Egypt. The company partnered with Uber in August 2026 to integrate self-drive and chauffeur-driven booking within a single app, and expanded into motorcycle and scooter rentals in Bengaluru in September 2026. Zoomcar's asset-light peer-to-peer model differentiates its offering from competitors operating owned vehicle fleets.
Founded in 1996 and headquartered in New Delhi, India, Eco Mobility (formerly Eco Rent A Car) is a chauffeur-driven transportation provider historically focused on corporate and premium travel within India. The company partnered with SIXT in March 2026, granting its corporate clients access to a fleet of more than 350,000 vehicles across over 105 countries, marking a strategic shift beyond its traditional domestic focus. Eco Mobility's international fleet-access partnership differentiates its offering from competitors serving only domestic chauffeur-driven demand.
Founded in 2000 and headquartered in New Delhi, India, Carzonrent is a premium mobility solutions provider specialising in chauffeur-driven car rental services for corporate and individual clients across 79 cities. The company introduced Global Limousine Services across 30 cities worldwide in March 2026, extending its premium offering beyond India's borders. Carzonrent's verified chauffeur network and global limousine expansion differentiate its offering from competitors focused solely on domestic self-drive rentals.
Founded in 2006 and headquartered in Jaipur, India, Girnar Software is the parent entity of the CarDekho automotive platform and its Revv self-drive car rental brand, alongside Gaadi and ZigWheels. The company and CarTrade Tech mutually terminated merger discussions in November 2025 that would have combined their automotive classifieds businesses, preserving Girnar's independent strategic direction. Girnar's integration of car rental within a broader automotive digital ecosystem differentiates its offering from standalone rental operators.
Other key players in the India car rental market include Avia Budget Group Inc., ORIX Corporation (MyChoize), Myles Automotive Technologies Private Limited, ANI Technologies Private Limited (Ola), Pluto Travels India Pvt. Ltd., and DriveEazy India Private Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our India car rental market trends 2026 report. Discover regional growth patterns, booking type and vehicle type adoption trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.
South Korea Car Rental Market
Philippines Car Rental Market
Brazil Car Rental Market
Germany Car Rental Market
Europe Car Rental Market
United States Car Rental Market
North America Car Rental Market
Vietnam Car Rental Market
United Kingdom Car Rental Market
Car Rental Market


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 12.60% between 2026 and 2035.
The car rental market is categorised according to booking type, which includes online modes of booking and offline modes of booking.
The key players in the market include Zoom Cars Ltd., Eco Mobility, Carzonrent India Private Limited, Girnar Software Private Limited, Avia Budget Group Inc., ORIX Corporation (MyChoize), Myles Automotive Technologies Private Limited, ANI Technologies Private Limited (Ola), Pluto Travels India Pvt. Ltd., and DriveEazy India Private Limited.
Based on the end use, the market is divided into leisure/tourism and business.
The market is broken down into luxury/premium cars, economy/budget cars, SUVs and MUVs.
The market is broken down into North India, East and Central India, West India, and South India.
In 2025, the market reached an approximate value of USD 3.10 Billion.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach about USD 10.16 Billion by 2035.
Operators face an unregulated and highly fragmented competitive landscape, thin margins amid intense price competition, and the capital intensity of maintaining and electrifying owned vehicle fleets.
Forming cross-border mobility partnerships, diversifying into adjacent vehicle categories such as two-wheelers, integrating with established ride-hailing networks, and expanding subscription-style long-term rental offerings.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Booking Type |
|
| Breakup by Rental Length Type |
|
| Breakup by Application Type |
|
| Breakup by Vehicle Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




