

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
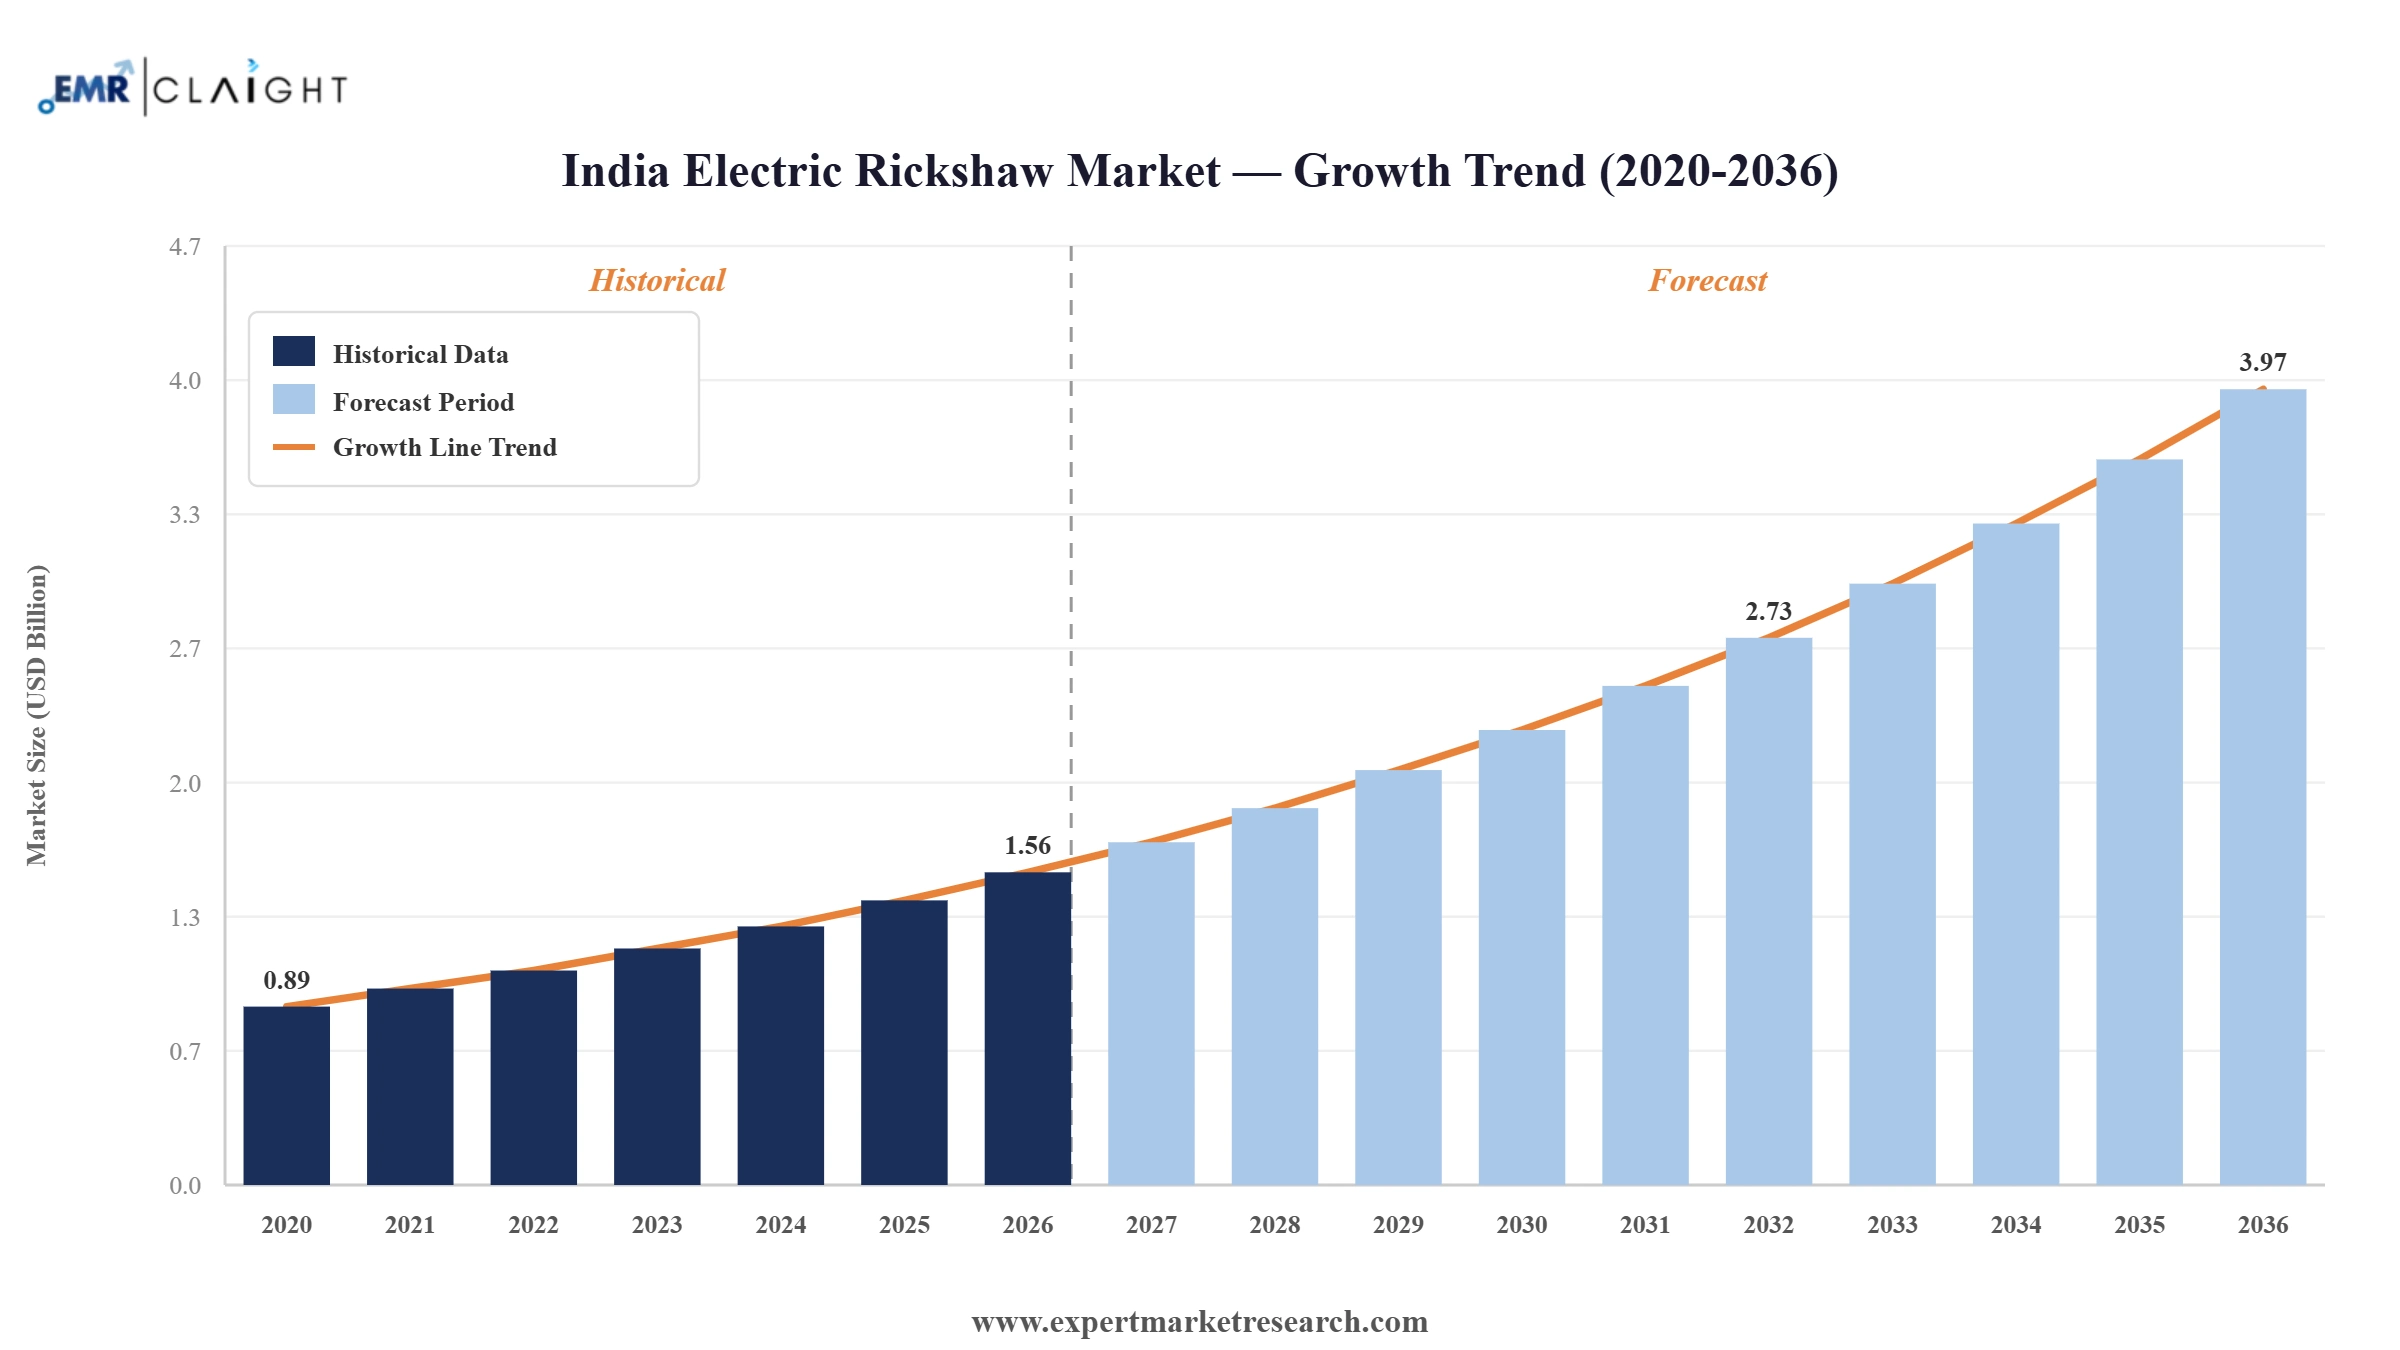
The India electric rickshaw market attained a value of USD 1.42 Billion in 2025 and is projected to expand at a CAGR of 9.80% through 2035. The market is further expected to achieve USD 3.62 Billion by 2035. Growing environmental concerns, favourable government policies including production-linked incentive schemes, and operational cost benefits over conventional fuel-powered vehicles continue to support demand for passenger and loader e-rickshaws across North, East and Central, West, and South India.
Growing environmental concerns continue to anchor steady demand across the India electric rickshaw market, as urban and semi-urban commuters increasingly favour zero-emission, low-maintenance alternatives to conventional fuel-powered three-wheelers. Manufacturers are also investing in premium, feature-rich models, reflecting the industry's ongoing pursuit of products that extend beyond basic last-mile connectivity toward differentiated design and battery performance.
The India electric rickshaw market is witnessing further developments as established manufacturers launch premium models targeting differentiated customer segments. Mahindra Last Mile Mobility, a subsidiary of Mahindra & Mahindra, launched the UDO electric auto-rickshaw at an introductory price of ₹3,58,999 in February 2026, featuring a monocoque construction, an 11.7 kWh lithium-ion battery pack delivering a 200-kilometre real-world range, and manufacturing at an upgraded Zaheerabad facility with automated battery assembly. This shift toward premium, technologically differentiated models is concentrated among manufacturers with sufficient design and manufacturing scale, while smaller specialists instead lean on price and regional dealer network depth.
In addition, established manufacturers are increasingly forming charging infrastructure partnerships to address range and downtime concerns for commercial fleet operators, reflecting the industry's recognition that rapid-charging capability increasingly determines competitiveness for high-utilisation passenger and cargo applications. Such infrastructure partnership activity is reshaping competitive positioning across the wider india electric rickshaw market as manufacturers with proven charging technology partnerships increasingly differentiate themselves from competitors relying on standard overnight charging alone.
Read more about this report - Request a Free Sample
Atul Auto and Exponent Energy announced a partnership to jointly develop and deploy rapid-charging electric passenger three-wheelers, committing to a minimum of 15,000 vehicles over three years integrated with Exponent Energy's 15-minute charging platform. Companies can partner with specialist charging technology providers to address range anxiety and downtime concerns for high-utilisation commercial fleet customers.
Mahindra Last Mile Mobility launched the UDO electric auto-rickshaw at an introductory price of ₹3,58,999, featuring a monocoque construction, 11.7 kWh lithium-ion battery, and a 200-kilometre real-world range, manufactured at an upgraded Zaheerabad facility with automated battery assembly. Companies can invest in premium design and battery technology to differentiate flagship models from value-focused competitors targeting the same last-mile transport segment.
In the February 2026 Union Budget, the Government of India reinforced incentive disbursement under its PM E-Drive scheme supporting electric three-wheeler adoption, reinforcing production-linked incentives and demand subsidies that have underpinned sustained market expansion. Companies can align production planning with ongoing government incentive scheme timelines to maximise subsidy capture for passenger and cargo e-rickshaw models.
Terra Motors launched the KYORO+ electric three-wheeler to strengthen its presence in the L5 passenger segment, building on its existing base of over 150,000 electric rickshaws sold in the L3 category across India. Companies can extend from established lower-power rickshaw categories into higher-power L5 segments to capture a broader share of the passenger three-wheeler market.
Vehicle downtime remains a persistent concern for fleet operators, and several manufacturers are now teaming up with specialist energy companies rather than building charging capability in-house. In April 2026, Atul Auto committed to deploying at least 15,000 rapid-charging vehicles over three years in partnership with Exponent Energy across the india electric rickshaw market. Such partnerships reflect manufacturers' recognition that fast-charging capability increasingly determines competitiveness for high-utilisation commercial and ride-hailing fleet customers.
Not every buyer is shopping on price alone, and a growing slice of manufacturers is betting on design and battery performance to win over customers who want more than a bare-bones commute vehicle. In February 2026, Mahindra Last Mile Mobility launched the UDO flagship model featuring monocoque construction and an extended-range lithium-ion battery pack manufactured at its upgraded Zaheerabad production facility. Such premium positioning reflects manufacturers' recognition that design differentiation and battery performance increasingly command price premiums among urban ride-hailing and personal-use buyers.
Much of the sector's growth still traces back to policy rather than pure market pull, with national subsidy programmes shaping purchasing decisions at the individual operator level. In March 2026, the Ministry of Heavy Industries extended PM E-Drive scheme incentives for electric three-wheelers through March 2028, even as parallel support for electric two-wheelers was capped at July 2026. Such sustained policy support reflects the government's recognition that electric three-wheeler adoption increasingly contributes to broader urban air-quality and last-mile transport electrification goals.
Having built a foothold in lower-power categories, several manufacturers are now pushing upmarket into higher-power passenger models to chase better margins. In May 2025, Terra Motors launched its KYORO+ three-wheeler model specifically targeting the higher-power L5 passenger category, building on an established base of over 150,000 lower-power L3 model sales. Such range extension reflects manufacturers' recognition that higher-power segments increasingly offer margin and differentiation opportunities beyond the more commoditised entry-level rickshaw category.
This Expert Market Research Report titled "India Electric Rickshaw Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Motor Type
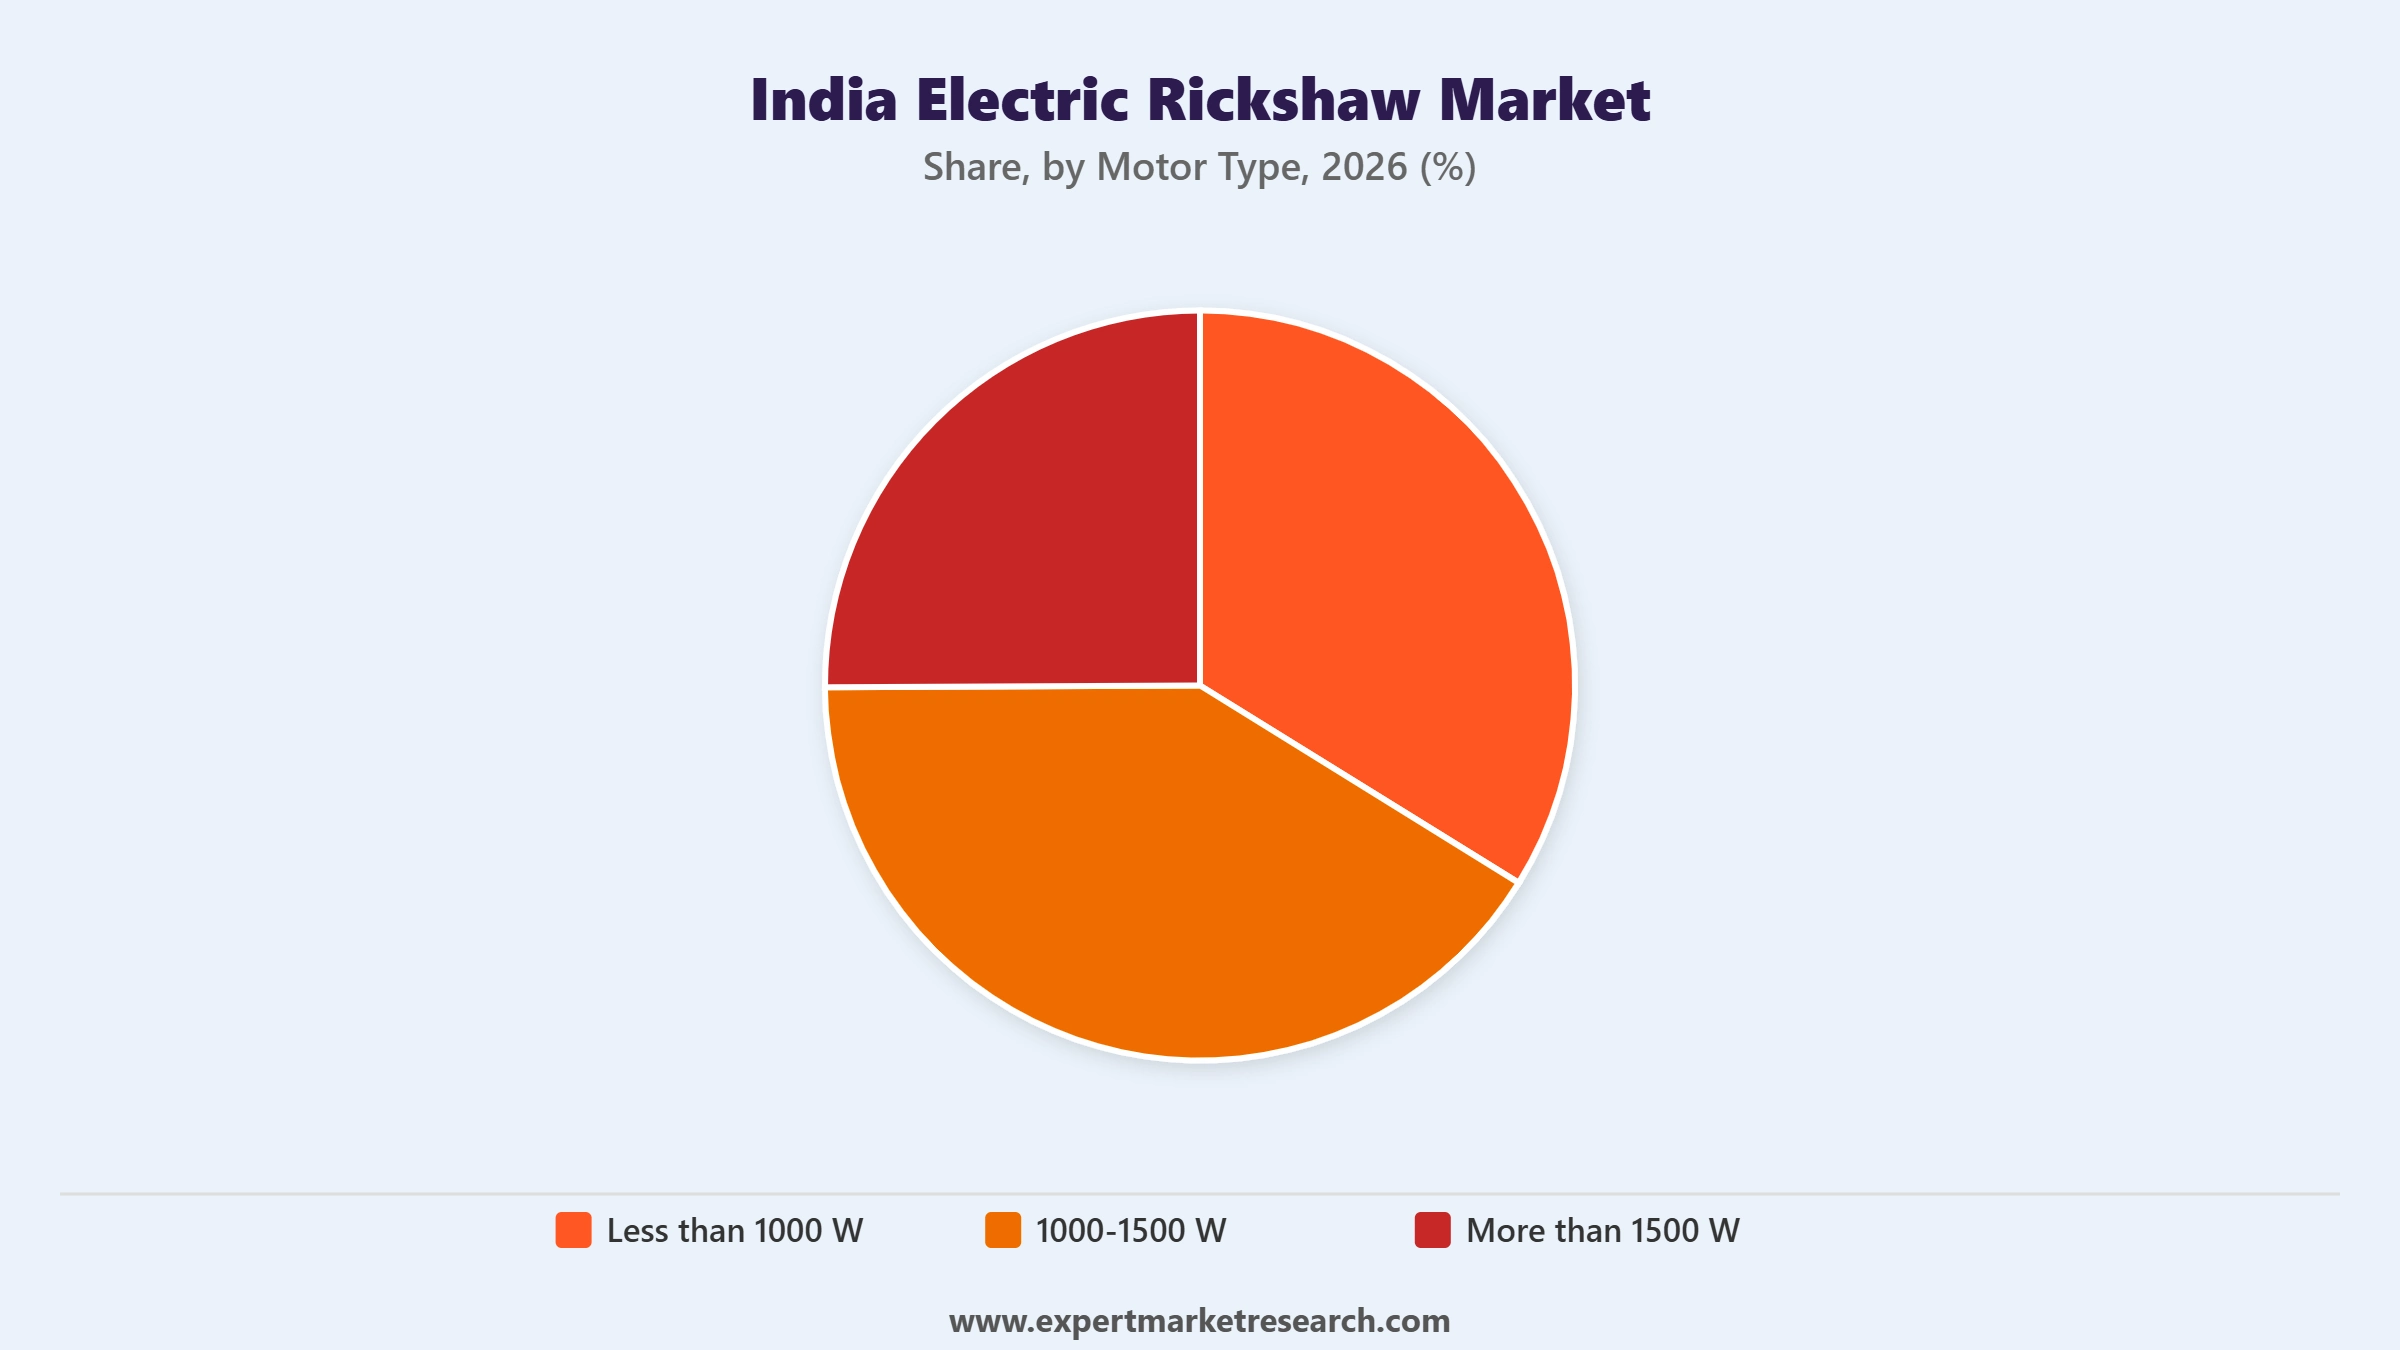
Key Insight: 1000-1500 W accounts for the largest share of the india electric rickshaw market, reflecting its balance of operational cost efficiency and adequate performance for standard passenger routes. More than 1500 W is growing at the fastest pace as rising payload and gradient-handling requirements drive adoption, illustrated by Atul Auto's April 2026 rapid-charging partnership targeting higher-utilisation commercial applications. Less than 1000 W continues to serve budget-conscious, entry-level operators.
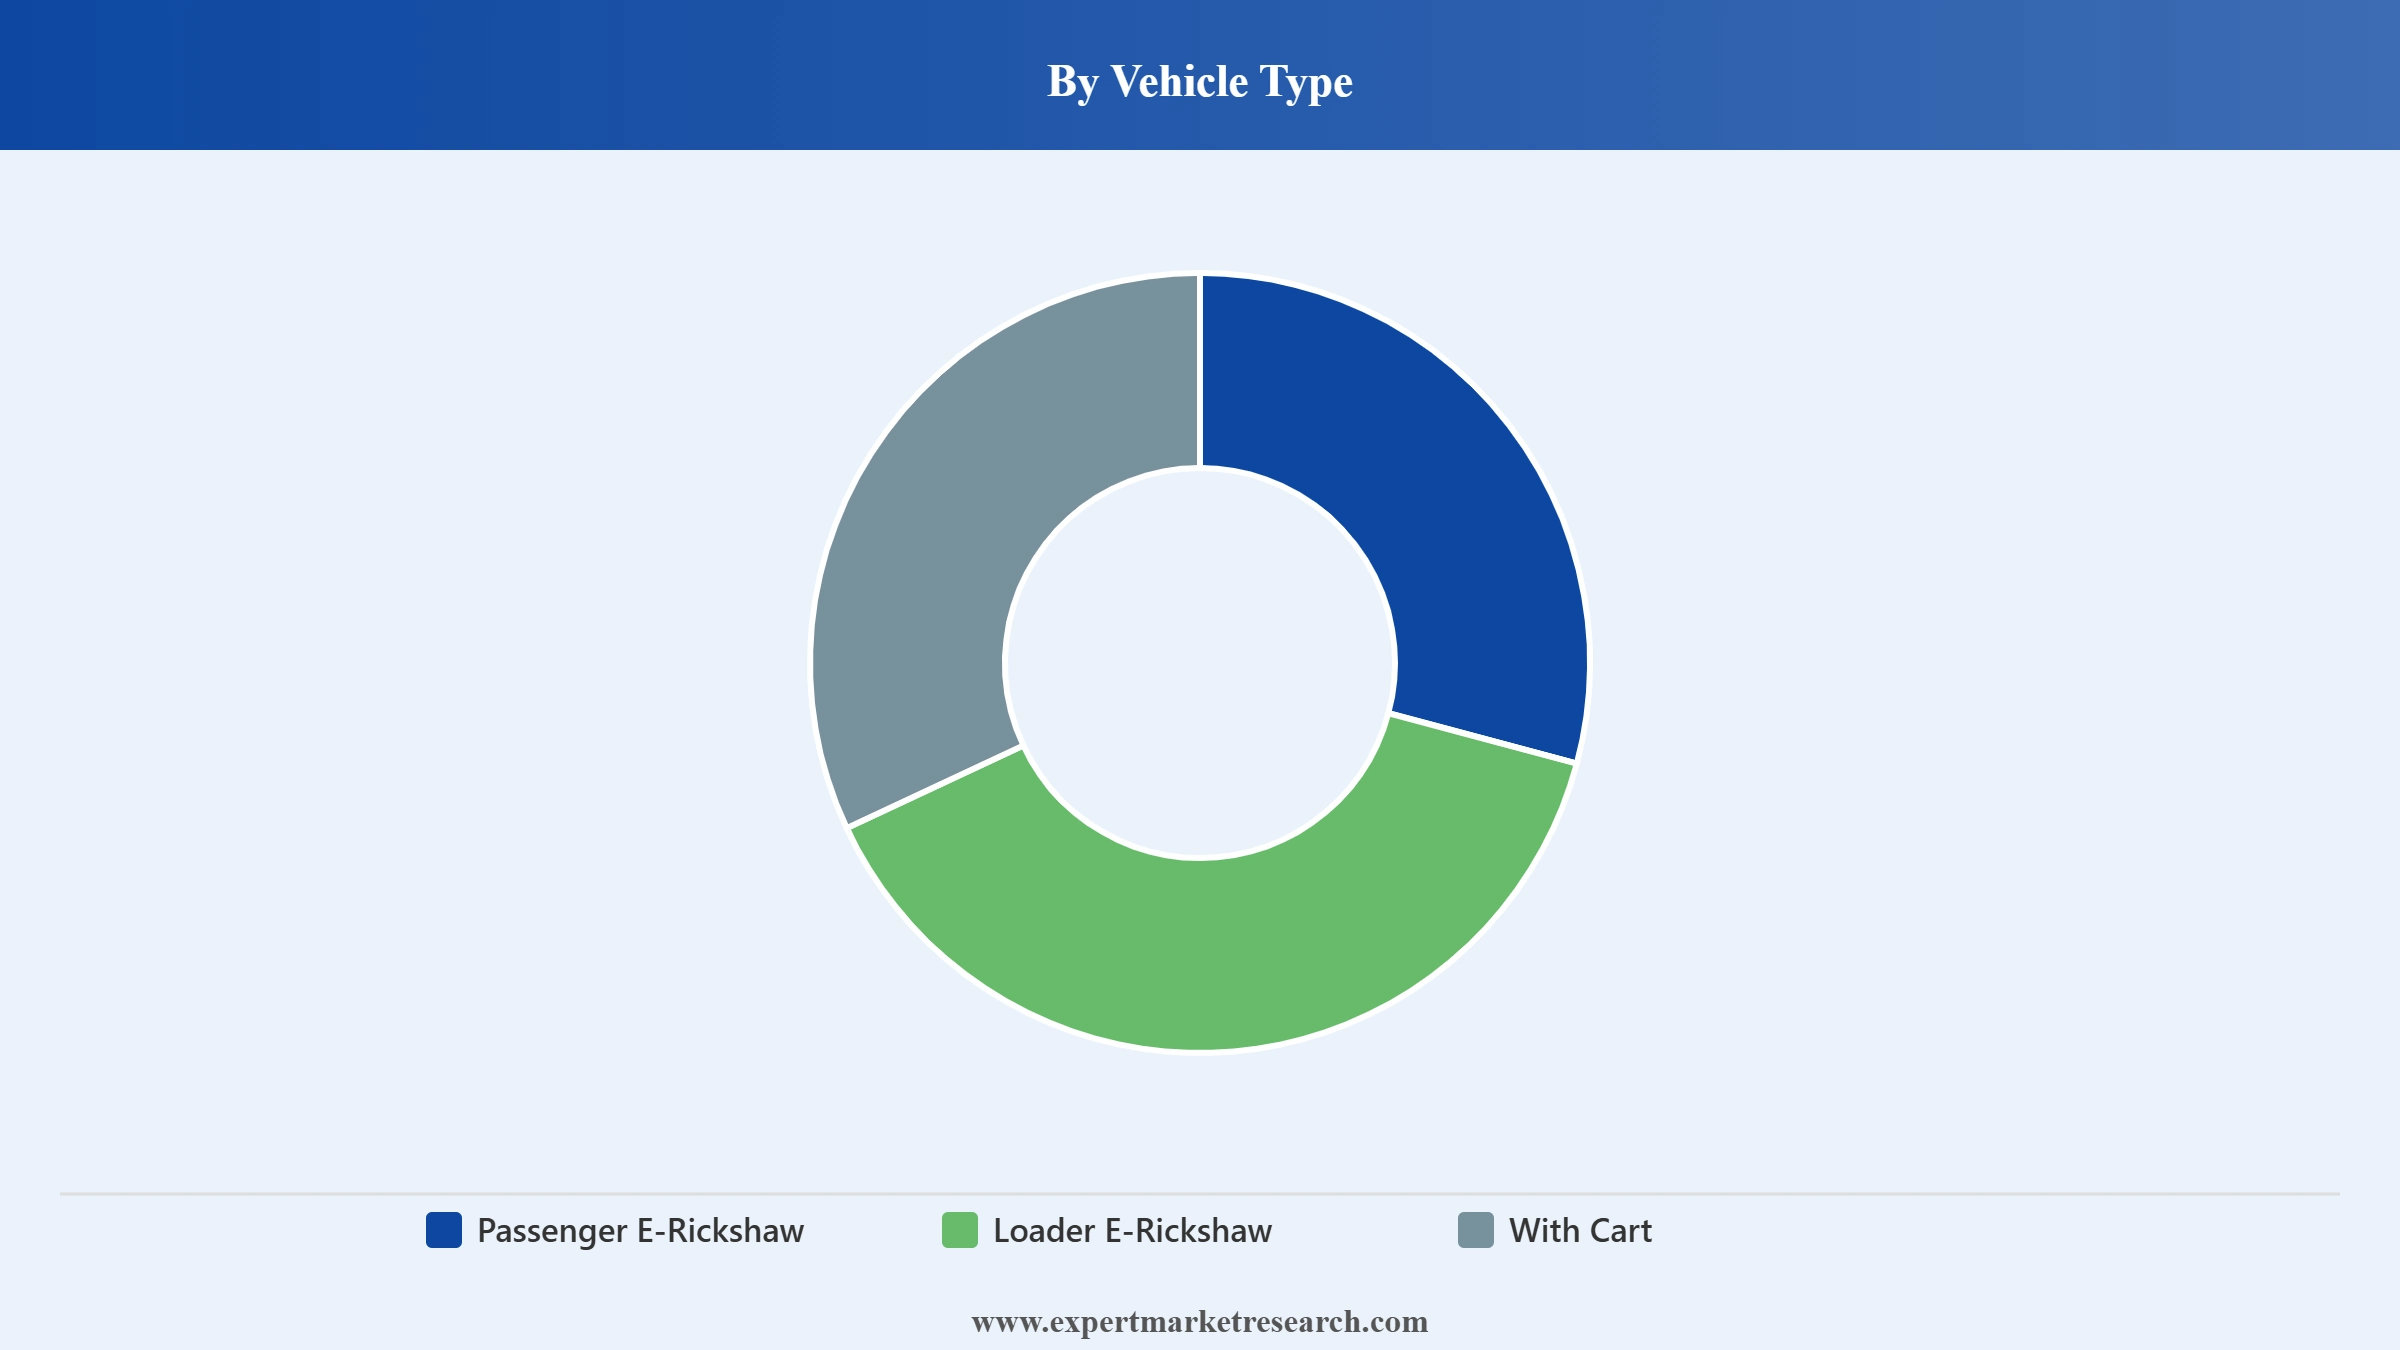
Market Breakup by Vehicle Type
Key Insight: Passenger E-Rickshaw accounts for the largest share of the india electric rickshaw market, reflecting strong urban and semi-urban demand for affordable last-mile passenger connectivity. Loader E-Rickshaw continues to represent growing demand tied to e-commerce and urban logistics expansion, with Udaan E Rickshaw's dedicated loader model, offering an 80-100 km range per charge, reflecting the segment's growing focus on cost-efficient last-mile goods delivery, while With Cart serves a smaller, more specialised category for localised goods transport; the March 2026 extension of PM E-Drive three-wheeler incentives through 2028 applies across both passenger and loader categories alike.
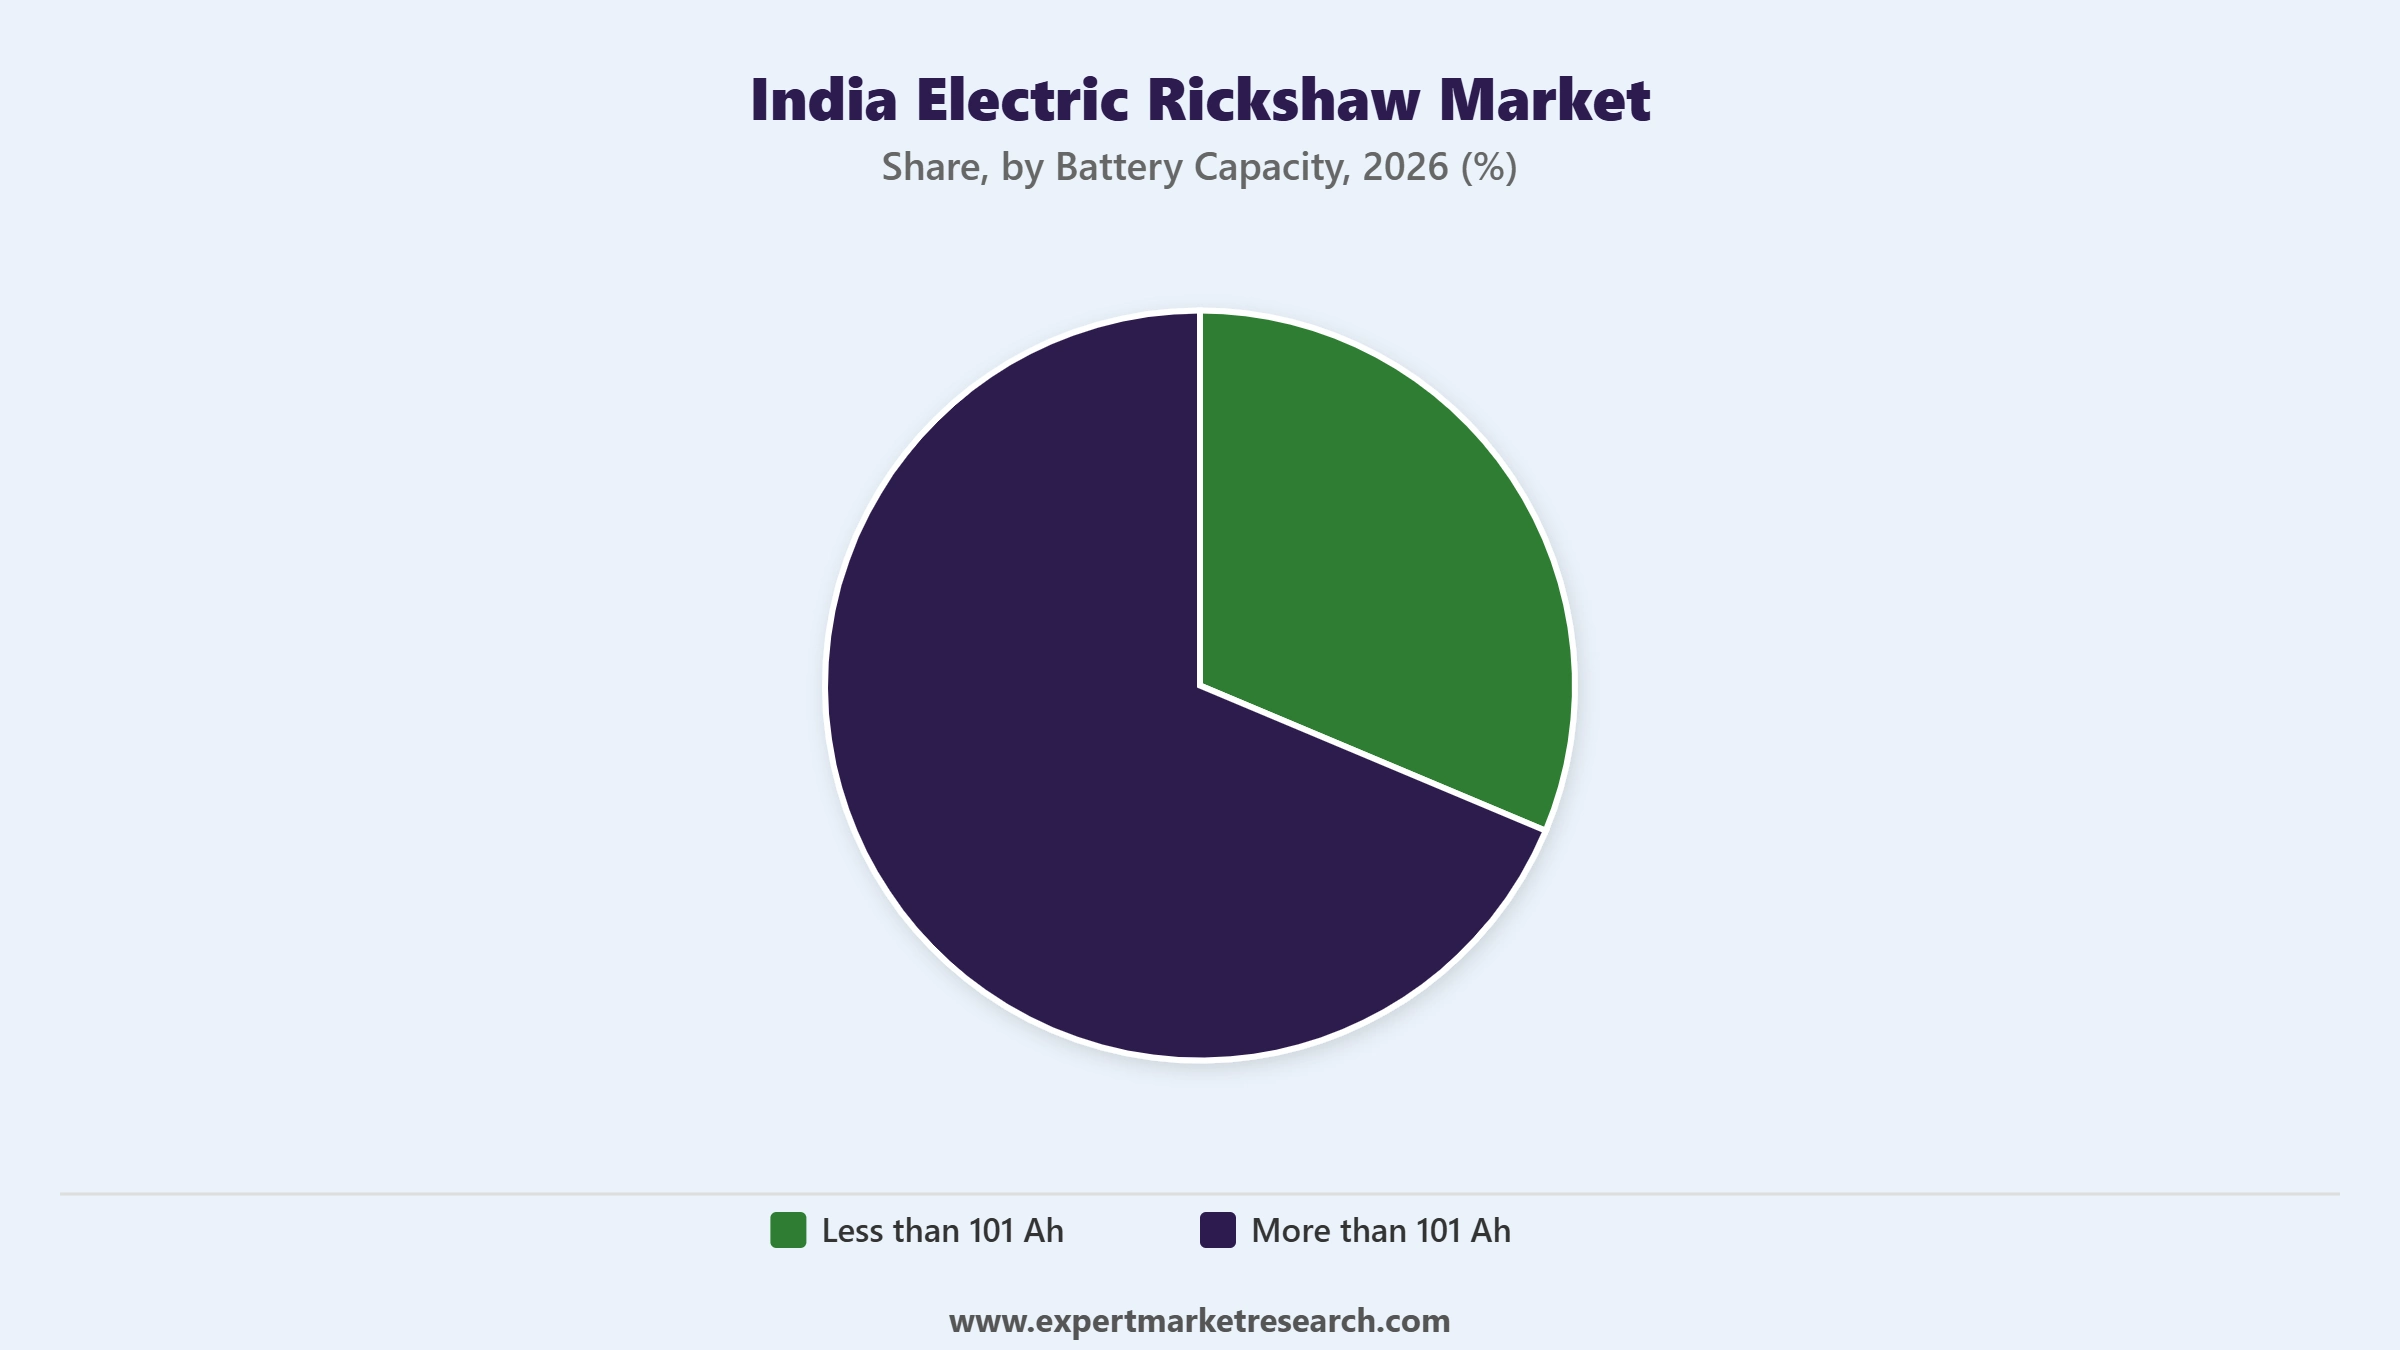
Market Breakup by Battery Capacity
Key Insight: Less than 101 Ah accounts for the largest share of the india electric rickshaw market, reflecting its lower upfront cost and adequate range for typical short-distance urban routes. More than 101 Ah continues to represent growing demand as operators increasingly prioritise extended range and reduced charging frequency, illustrated by Mahindra's February 2026 UDO launch featuring an 11.7 kWh battery pack rated for a 200-kilometre real-world range.
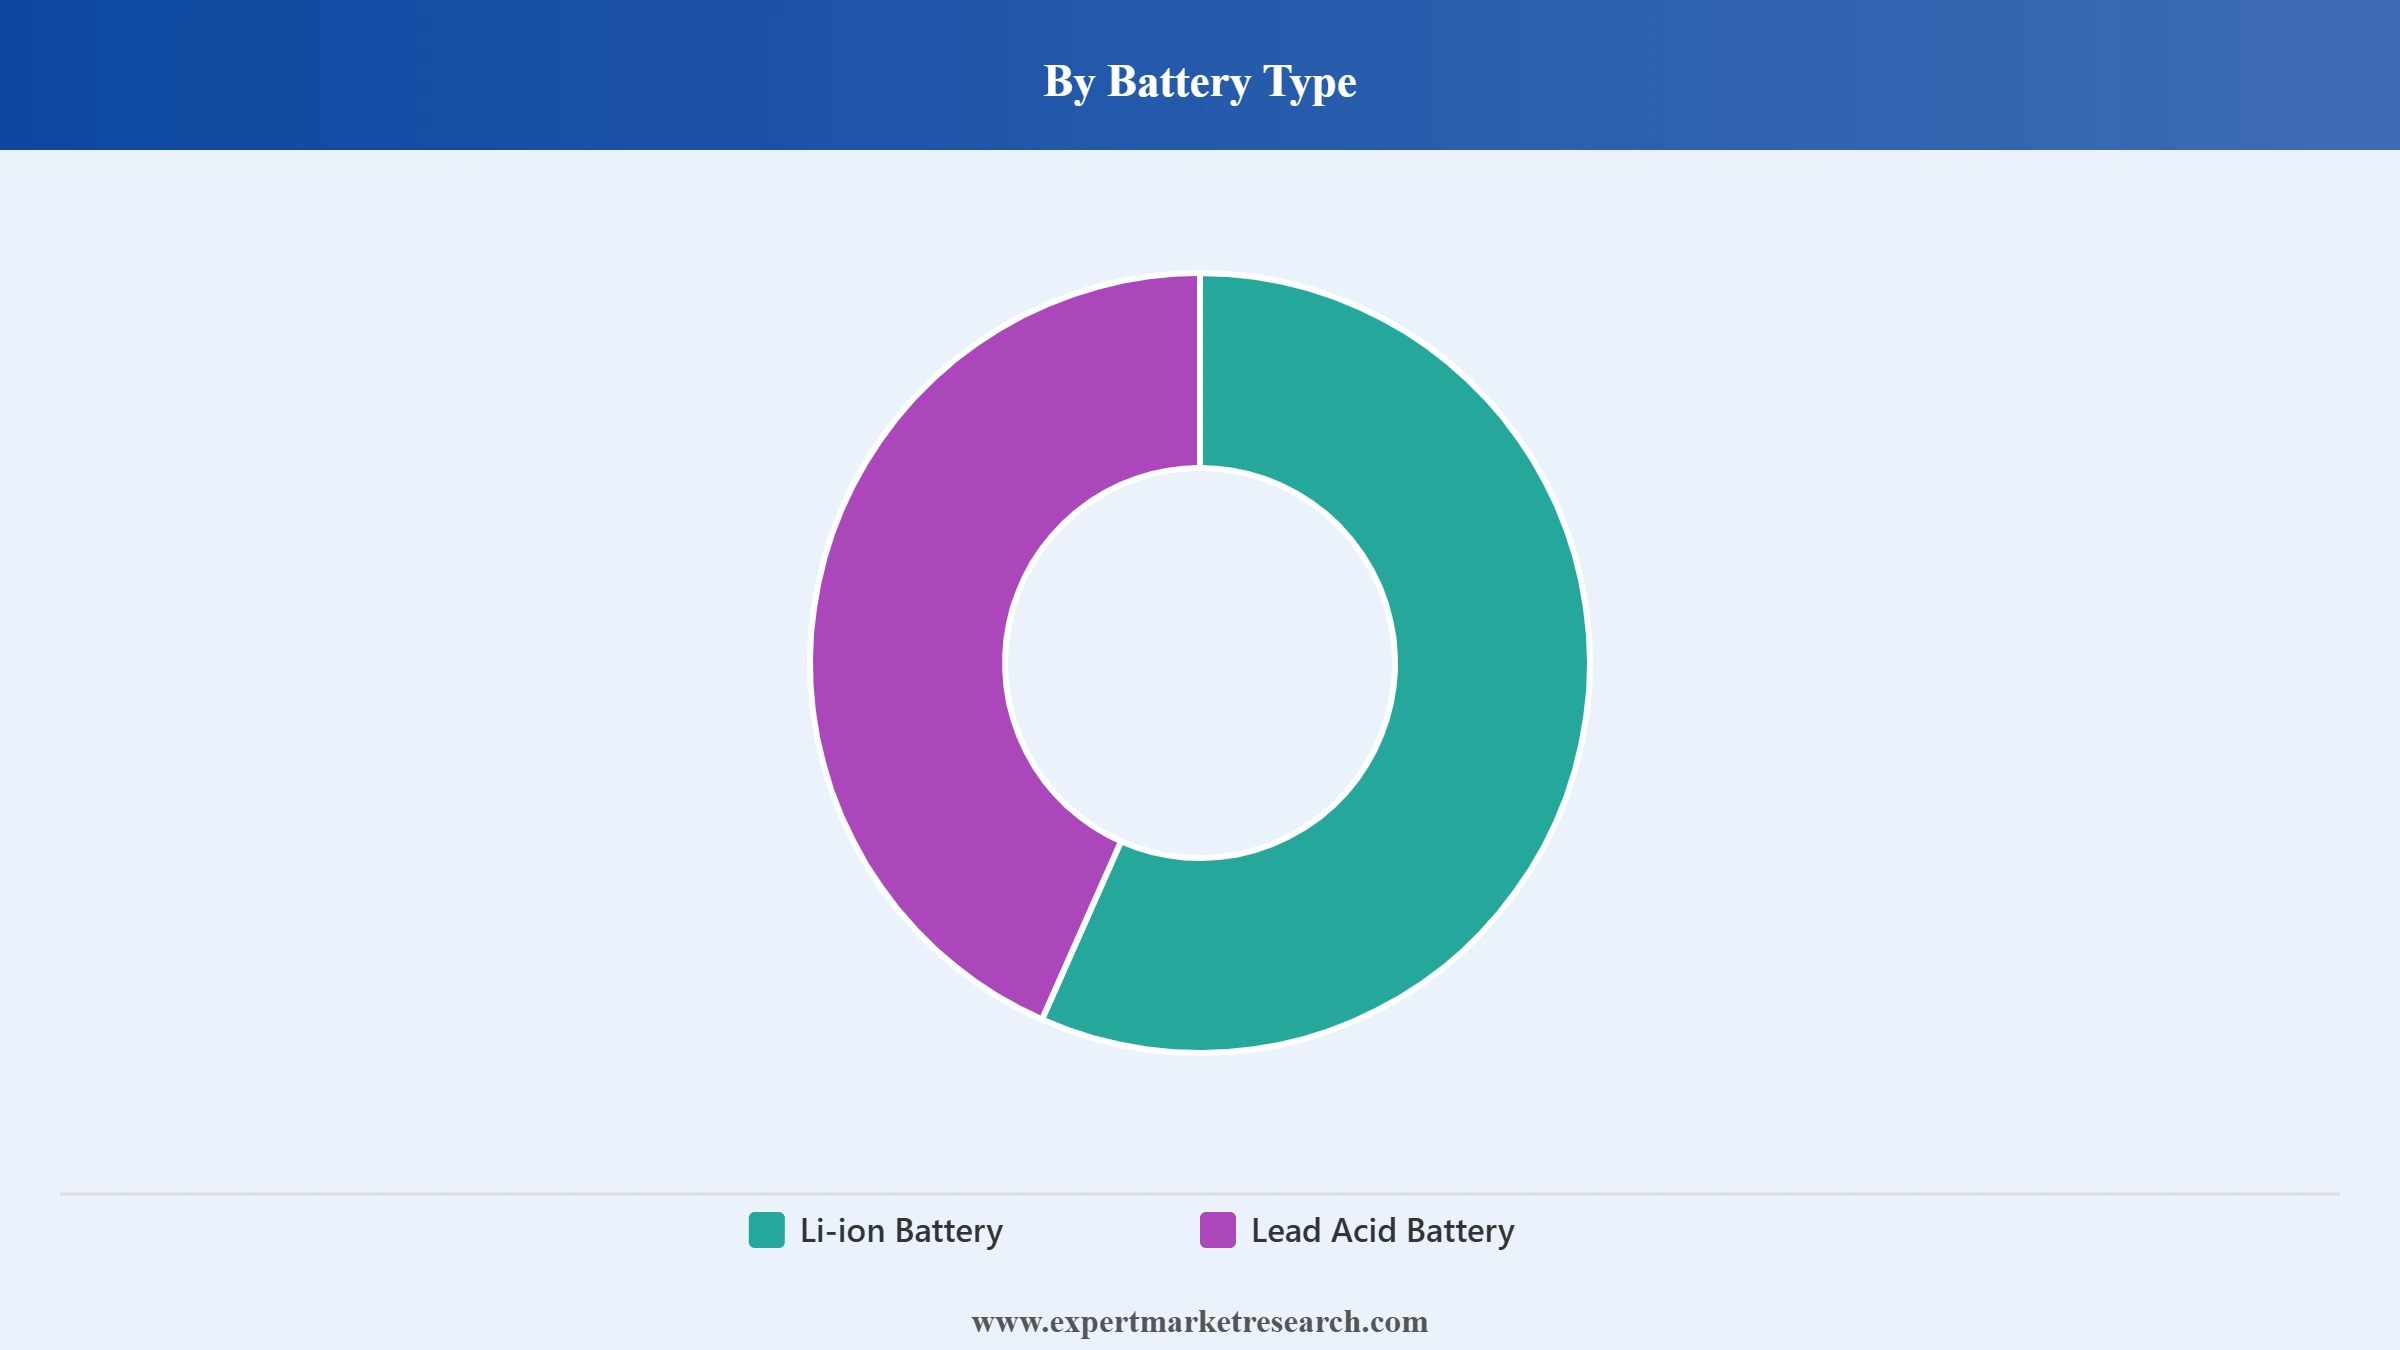
Market Breakup by Battery Type
Key Insight: Lead Acid Battery accounts for the largest share of the india electric rickshaw market, reflecting its lower upfront cost and established recycling infrastructure across India. Li-ion Battery is growing at a fast pace as manufacturers increasingly adopt lithium-ion technology for premium models, illustrated by Mahindra's February 2026 UDO launch featuring an 11.7 kWh lithium-ion battery pack.
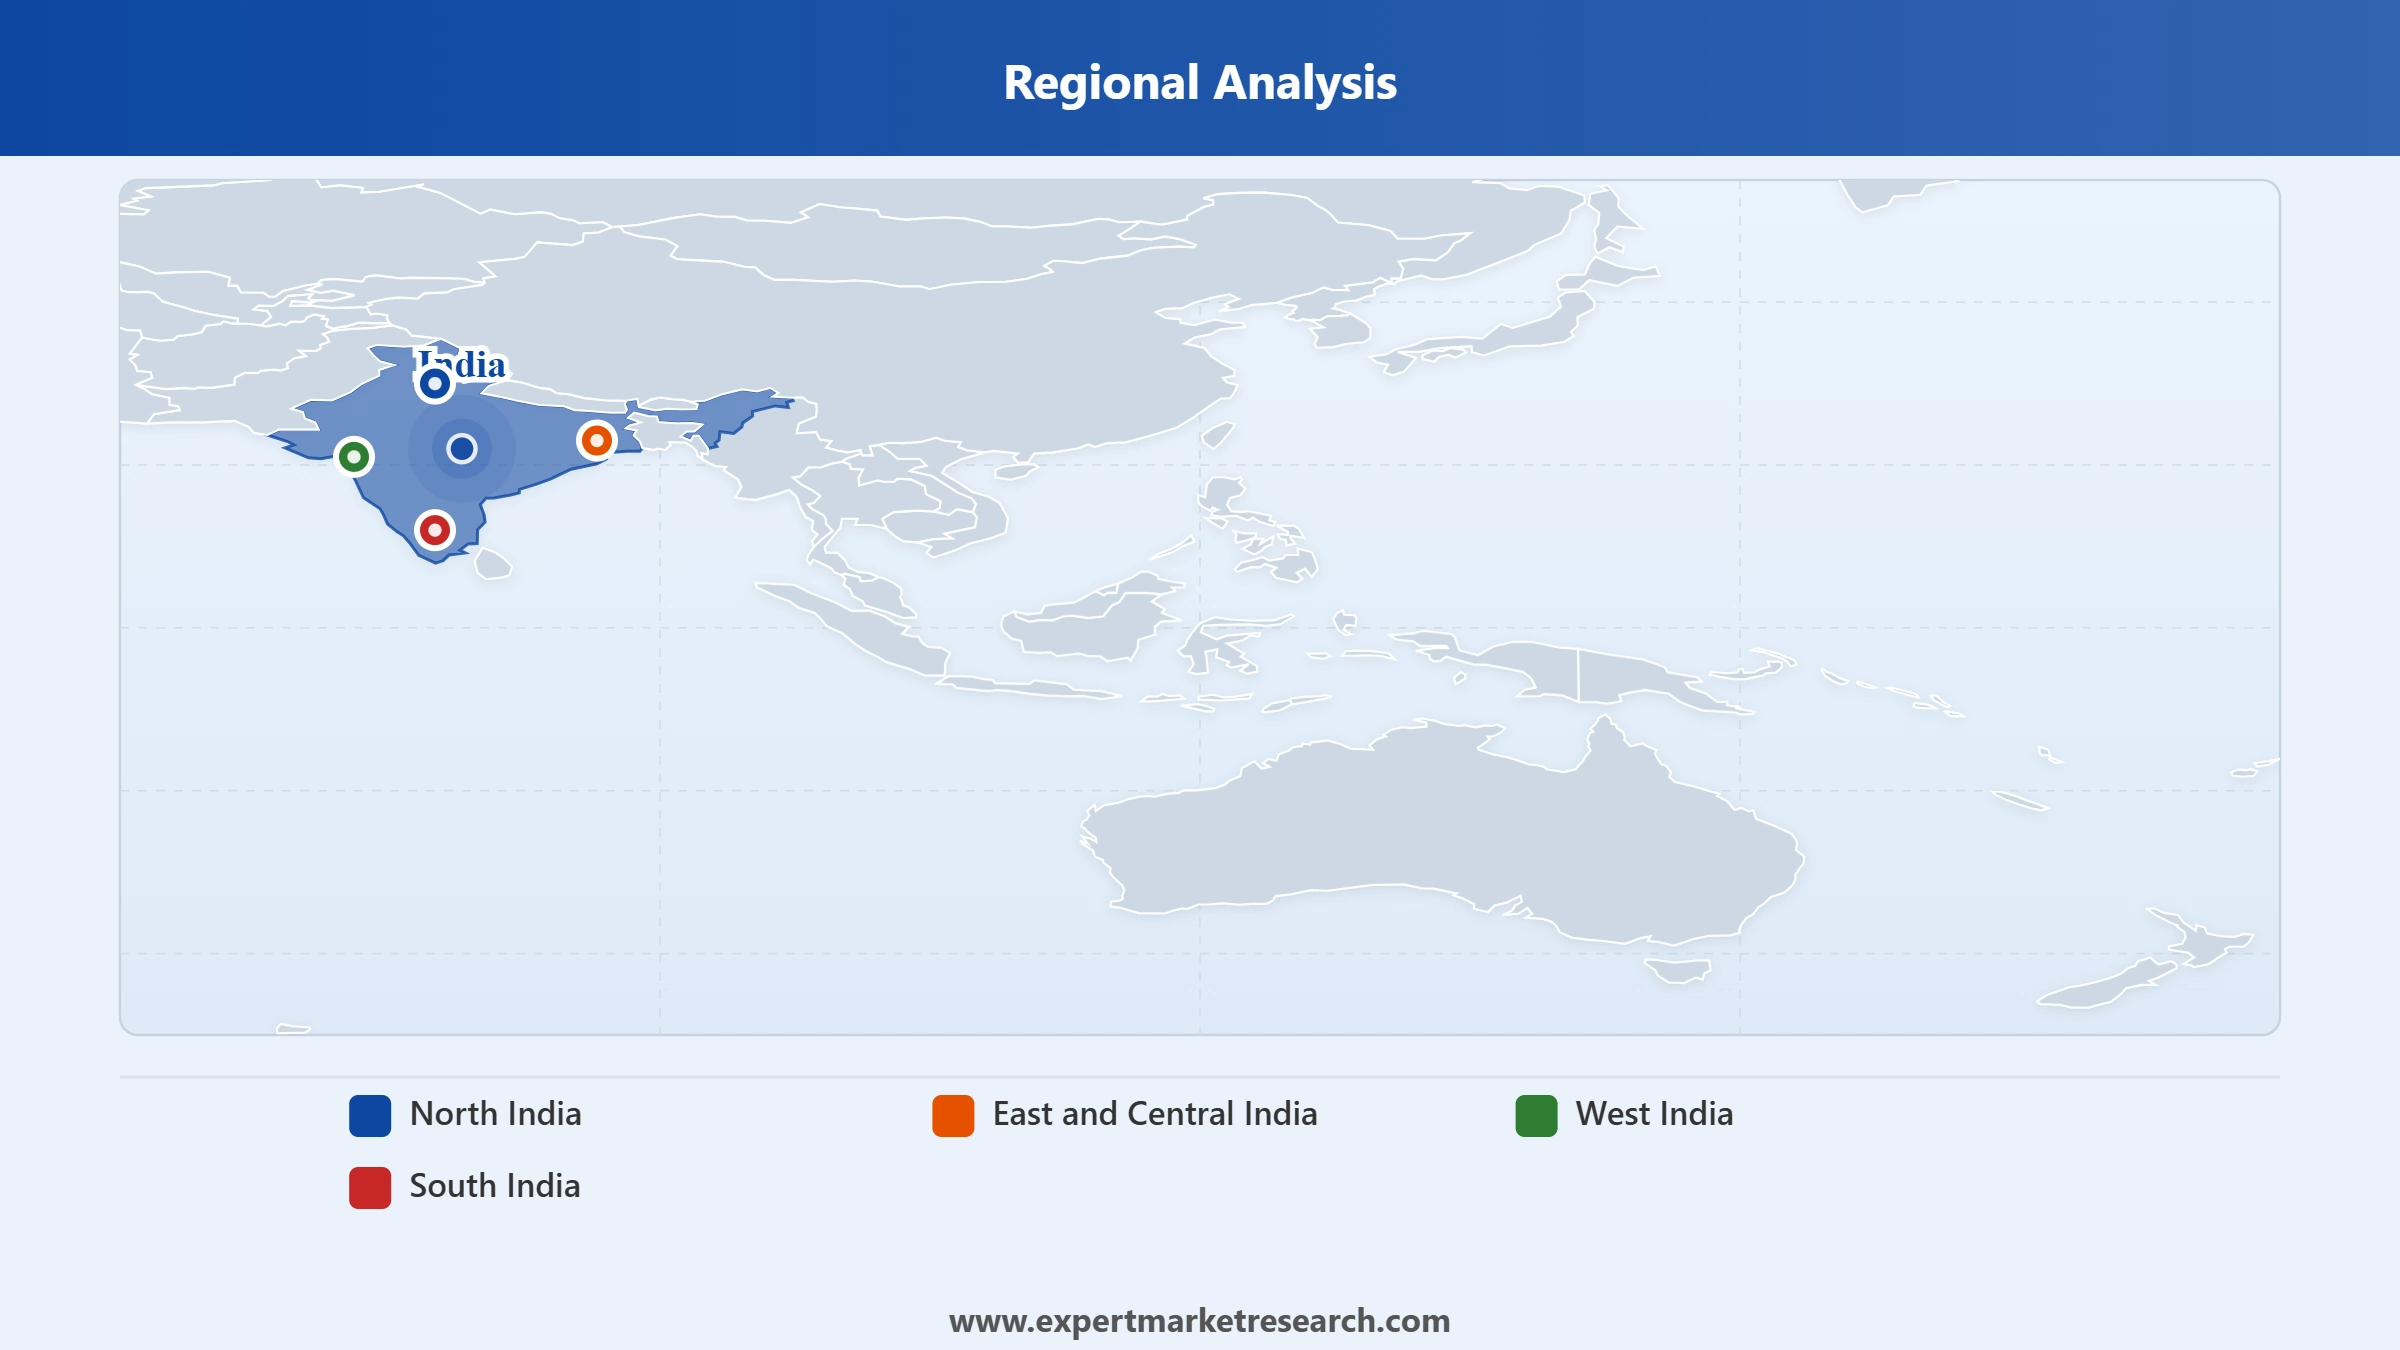
Market Breakup by Region
Key Insight: North India accounts for the largest share of the india electric rickshaw market, supported by high urbanisation rates and concentrated e-rickshaw fleets in cities such as Delhi, Lucknow, and Chandigarh. South India is emerging as a key growth region as urban logistics and ride-hailing demand continue to expand. West India benefits from Maharashtra's 2025-2030 EV Policy, which layered state road-tax waivers atop PM E-Drive's per-vehicle incentives for fleet operators as of April 2026, reinforcing the region's status as Atul Auto's home market. East and Central India continues to serve distinct regional demand, anchored by manufacturers such as Jezza Motors maintaining a multi-state presence across the eastern corridor, with the February 2026 Union Budget's reinforcement of PM E-Drive scheme incentives supporting adoption momentum nationwide.
Read more about this report - Request a Free Sample
By motor type, 1000-1500 W leads the market while more than 1500 W grows fastest given rising payload requirements
1000-1500 W continues to account for the largest share of the market, reflecting its balance of operational cost efficiency and adequate performance for standard passenger routes. The 1000-1500 W band hits a sweet spot manufacturers have settled into, and there is little commercial pressure pushing them toward alternative motor specifications.
Read more about this report - Request a Free Sample
More than 1500 W is growing at the fastest pace across the india electric rickshaw market as rising payload and gradient-handling requirements increase demand for higher-powered motors. In April 2026, Atul Auto's rapid-charging partnership with Exponent Energy targeted higher-power, higher-utilisation commercial three-wheeler applications.
By vehicle type, passenger e-rickshaw leads the market while loader e-rickshaw grows fastest given e-commerce expansion
Passenger E-Rickshaw continues to account for the largest share of the market, reflecting strong urban and semi-urban demand for affordable last-mile passenger connectivity. Operators show little appetite to move away from passenger e-rickshaws, sticking with proven vehicle models across successive fleet renewal cycles.
Read more about this report - Request a Free Sample
Loader E-Rickshaw is growing at a fast pace across the india electric rickshaw market as e-commerce and urban logistics expansion increasingly require cost-efficient, emission-free delivery vehicles for last-mile goods transport.
By battery type, lead acid battery leads the market while li-ion battery grows fastest given premium model adoption
Lead Acid Battery continues to account for the largest share of the market, reflecting its lower upfront cost and established recycling infrastructure across India. Lead acid battery suppliers remain the path of least resistance for manufacturers, since the sourcing relationships already in place cost less to maintain than to replace.
Read more about this report - Request a Free Sample
Li-ion Battery is growing at a fast pace across the india electric rickshaw market as manufacturers increasingly adopt lithium-ion technology for premium models. Rapid-charging technology, such as Atul Auto's April 2026 partnership with Exponent Energy, is engineered specifically around lithium-ion chemistry rather than lead-acid, reinforcing the shift toward this battery type among fleet-oriented models.
By battery capacity, less than 101 Ah leads the market while more than 101 Ah grows fastest given rising demand for extended range
Less than 101 Ah continues to account for the largest share of the market, reflecting its lower upfront cost and adequate range for typical short-distance urban routes. For routes under typical urban distances, less than 101 Ah batteries already do the job, which keeps manufacturers from paying a premium for capacity most riders will not use.
Read more about this report - Request a Free Sample
More than 101 Ah is growing at a fast pace across the india electric rickshaw market as operators increasingly prioritise extended range and reduced charging frequency. In May 2025, Terra Motors' KYORO+ launch targeted the higher-power L5 passenger segment, building on an established base of over 150,000 lower-power L3 rickshaws already sold across India.
Read more about this report - Request a Free Sample
North India commands the largest share of the market through its concentrated urban e-rickshaw fleets
North India holds the largest share of the India electric rickshaw market, supported by high urbanisation rates and concentrated e-rickshaw fleets in cities such as Delhi, Lucknow, and Chandigarh alongside strong state-level support for electric vehicle adoption. Dealer networks keep growing in step with passenger and cargo e-rickshaw demand, a sign manufacturers see no near-term ceiling on this corridor.
South India is emerging as a key growth region as urban logistics and ride-hailing demand continue to expand across the region. The March 2026 extension of PM E-Drive incentives for electric three-wheelers through 2028 underscored sustained national policy support extending well beyond North India's traditional market concentration across the wider india electric rickshaw market.
The industry is fragmented, with india electric rickshaw market companies ranging from diversified automotive manufacturers spanning multiple vehicle categories to specialist e-rickshaw producers competing across motor type, vehicle type, and regional segments. Established players operate across the full e-rickshaw value chain, from motor and battery sourcing through complete vehicle assembly and dealer network distribution for passenger and cargo applications.
Competitive dynamics among india electric rickshaw players are increasingly shaped by the pace of charging infrastructure partnerships, the scale of premium model development, and the strength of regional dealer network depth. Manufacturers are investing in lithium-ion battery technology, rapid-charging compatibility, and differentiated design to secure long-term relationships with individual operators and commercial fleet customers.
Founded in 1945 and headquartered in Mumbai, India, Mahindra & Mahindra manufactures electric rickshaws through its Mahindra Last Mile Mobility subsidiary, positioning itself as India's leading electric commercial vehicle manufacturer by registration volume. In February 2026, the company launched the UDO premium electric auto-rickshaw featuring monocoque construction and extended-range battery technology. Mahindra's extensive dealer network and diversified automotive manufacturing scale differentiate its offering from specialist e-rickshaw producers with narrower distribution reach.
Founded in 1986 and headquartered in Rajkot, India, ATUL Auto manufactures three-wheelers across passenger and cargo segments, including internal combustion and electric variants. In April 2026, the company partnered with Exponent Energy to deploy at least 15,000 rapid-charging electric three-wheelers over three years. ATUL Auto's established three-wheeler manufacturing heritage and export market presence differentiate its offering from newer, EV-focused entrants.
Citylife Electric Vehicles manufactures electric rickshaws and three-wheelers for passenger and cargo applications across Indian urban and semi-urban markets. The company serves individual operators and small fleet customers requiring affordable, low-maintenance last-mile transport solutions. Citylife's focused electric rickshaw specialisation differentiates its offering from diversified automotive manufacturers treating e-rickshaws as one product line among many.
Saera Electric Auto manufactures electric three-wheelers under its Saera Mayuri brand for passenger and cargo transport applications across India. The company serves individual operators and small business owners requiring reliable, low-cost electric mobility solutions. Saera's established regional dealer presence differentiates its offering from newer entrants with more limited distribution networks.
Other key players in the India electric rickshaw market include Adapt Motors Private Limited, GRD Motors LLP, Singham E Rickshaw, Jezza Motors, e-Ashwa Automotive, Udaan E Rickshaw, Terra Motors India Corp., Mini Metro EV LLP, and Lohia Auto Industries, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our India electric rickshaw market trends 2026 report. Discover regional growth patterns, motor type and vehicle type trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 1.42 Billion.
The market is projected to grow at a CAGR of 9.80% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 3.62 Billion by 2035.
Forming rapid-charging infrastructure partnerships to serve commercial fleet operators, launching premium models with extended-range battery technology, and extending established lower-power product ranges into higher-power passenger segments.
Key trends aiding the market are the increasing demand for customisation in e-rickshaws, advancements in battery technology, and high integration of smart features, such as GPS.
Major regions in the market are North, East and Central, West, and South India.
Less than 1000 W, 1000-1500 W, and more than 1500 W motor types are included in the market.
Electric rickshaws are adaptable to both urban and peri-urban areas. While urban demand remains high, there is potential for growth in rural areas as awareness and charging infrastructure improve.
The key players in the market include Mahindra & Mahindra Limited, ATUL Auto Limited, Citylife Electric Vehicles, Saera Electric Auto Pvt. Ltd., Adapt Motors Private Limited, GRD Motors LLP, Singham E Rickshaw, Jezza Motors, e-Ashwa Automotive, Udaan E Rickshaw, Terra Motors India Corp., Mini Metro EV LLP, and Lohia Auto Industries, among others.
Manufacturers face intense price competition from a highly fragmented, largely unorganised sector, limited access to formal financing for individual operators, and inconsistent charging infrastructure availability across semi-urban and rural areas.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Motor Type |
|
| Breakup by Vehicle Type |
|
| Breakup by Battery Capacity |
|
| Breakup by Battery Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




