

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The India radar market attained a value of USD 1.22 Billion in 2025 and is projected to expand at a CAGR of 4.30% through 2035. The market is further expected to reach USD 1.86 Billion by 2035. Rising border surveillance requirements, growing indigenous defence manufacturing under Make in India, and modernisation of civil air traffic and weather infrastructure are pushing government agencies and private manufacturers to expand radar production and induct advanced systems. Wide use of AESA and phased array technology in fighter aircraft, air defence, and naval platforms is further strengthening demand across military and civil applications.
Radar systems transmit radio waves and analyse their reflections to detect, locate, and track objects across air, land, and sea. The India radar market spans antennas, transmitters, and receivers built into ground-based, airborne, naval, and space-based platforms, supporting military surveillance, air traffic control, remote sensing, and ground traffic monitoring. Adoption is concentrated among defence public sector units, the armed forces, and civil aviation authorities, while private component makers are increasingly winning sub-system contracts. Border tensions, fighter modernisation programmes, and expanding airport infrastructure continue to support steady investment in radar production and induction.
Demand in the India radar market is concentrating around indigenous air defence and fire control systems as the armed forces replace ageing imported equipment with domestically designed radars. Public sector manufacturers are widening production lines to meet army and air force induction schedules while private component suppliers scale sub-assembly output. In July 2025, the Ministry of Defence signed a contract worth around INR 1,640 crore with Bharat Electronics for Atulya air defence fire control radars for the Indian Army, covering surveillance, target acquisition, and gun direction functions. Contracts of this scale are lifting order books across the radar supply chain.
Major India radar market players are directing investment toward AESA antenna arrays, transmit-receive modules, and multi-mode processing software that extend radar use across fighter upgrades, maritime patrol, and battlefield surveillance. Component manufacturers are winning sub-system contracts for exciter units, receivers, and beam control hardware, while system integrators are building dedicated regional production facilities. Public and private players are also widening portfolios into space-based and remote sensing radar applications, positioning the industry to serve defence, civil aviation, and disaster management customers through one expanding domestic base.

Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| India Radar Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 1.22 |
| Market Size 2035 | USD Billion | 1.86 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 4.30% |
| CAGR 2026-2035 - Market by Region | West India | 4.8% |
| CAGR 2026-2035 - Market by Region | East and Central India | 4.5% |
| CAGR 2026-2035 - Market by Radar Service | Support and Maintenance | 4.9% |
| CAGR 2026-2035 - Market by Platform | Space Based | 5.2% |
| 2025 Market Share by Region | South India | 20.7% |
The Bengaluru-based electronics manufacturer committed INR 500 crore to a new facility at the Hi-Tech Defence and Aerospace Park, with construction starting September 2026 and completion targeted within four years. The plant will build radar systems and electronic warfare equipment and is expected to create around 1,500 jobs. Component makers across the India radar market can use dedicated defence parks to scale radar sub-system output.
The Hyderabad-based radar component maker secured a new contract from Hindustan Aeronautics to supply 122 antenna array units and 121 interface frames for the indigenous Uttam AESA radar programme over five years. The order supports fighter aircraft upgrade programmes reducing reliance on imported radar hardware. Component suppliers across the India radar market can use multi-year AESA contracts to plan capacity and secure long-term revenue visibility.
The two space agencies launched NISAR aboard a GSLV rocket to map global land and ice surfaces using dual-frequency synthetic aperture radar, marking a major step in space radar imaging cooperation. The mission tracks subtle surface changes for disaster monitoring, agriculture, and infrastructure planning. Satellite programmes of this kind can widen the radar market into scientific and remote sensing applications.
The Electronics and Radar Development Establishment showcased a low-frequency VHF surveillance radar designed to detect stealth aircraft at ranges up to 400 kilometres, deployable in mountainous terrain within twenty minutes. The system is undergoing trials ahead of induction by the Indian Air Force within two years. Developers across the India radar market can use low-frequency detection to counter stealth threats conventional radars struggle to track.
Government agencies are steadily scaling weather radar and remote sensing infrastructure to improve extreme weather prediction and disaster preparedness across the country. Wider Doppler radar coverage is extending radar market applications into meteorology, agriculture, and aviation safety alongside traditional defence use, drawing sustained public investment. The Ministry of Earth Sciences proposed a INR 10,000 crore Mission Mausam expansion in September 2026 covering weather radars, satellites, and supercomputers, with Bharat Electronics developing radars domestically alongside the Indian Space Research Organisation.
Public sector defence manufacturers are reporting diversified order inflows spanning radar, communication, avionics, and cyber security equipment as procurement activity steadily broadens across the armed forces, spreading fresh demand widely across many distinct technology lines. This diversification is spreading radar market revenue across multiple technology categories instead of resting on single large contracts alone. Bharat Electronics secured orders worth INR 730 crore in August 2026 covering communication gear, radar systems, avionics, and cyber security solutions in one combined announcement.
India is steadily approving sweeping defence capital acquisition packages that bundle radar, air defence, and surveillance procurement into single sanctioning rounds, accelerating induction timelines across the armed forces and easing long-standing procurement backlogs over time. Such packages give manufacturers multi-year visibility into radar-linked demand across many air defence and surveillance categories going forward. The Defence Acquisition Council approved capital proposals worth roughly INR 2.38 lakh crore in March 2026, covering air defence tracked systems and runway-independent aerial surveillance systems.
Civil aviation authorities are steadily replacing and expanding airport surveillance radar coverage to keep pace with rising air traffic volumes and rapid new airport construction across the whole country. Combined primary and secondary surveillance radars are improving detection accuracy and reducing controller workload at both new and upgraded airports. A Czech manufacturer completed factory acceptance testing of twenty airport radars in August 2025, with installations beginning at Jewar, Navi Mumbai, and Varanasi airports under a civil aviation modernisation programme.
Domestic developers are steadily fielding transportable, indigenously designed mobile radars that give army and air force units strong mobile detection capability across varied and often difficult terrain, reducing reliance on imported mobile radar systems significantly over time. These systems combine electronic scanning with rapid deployment for forward operating areas near contested borders. The Indian Air Force placed a INR 2,463 crore order in March 2025 for Ashwini active electronically scanned array radars jointly developed by DRDO and Bharat Electronics.
The Expert Market Research's report titled "India Radar Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Component
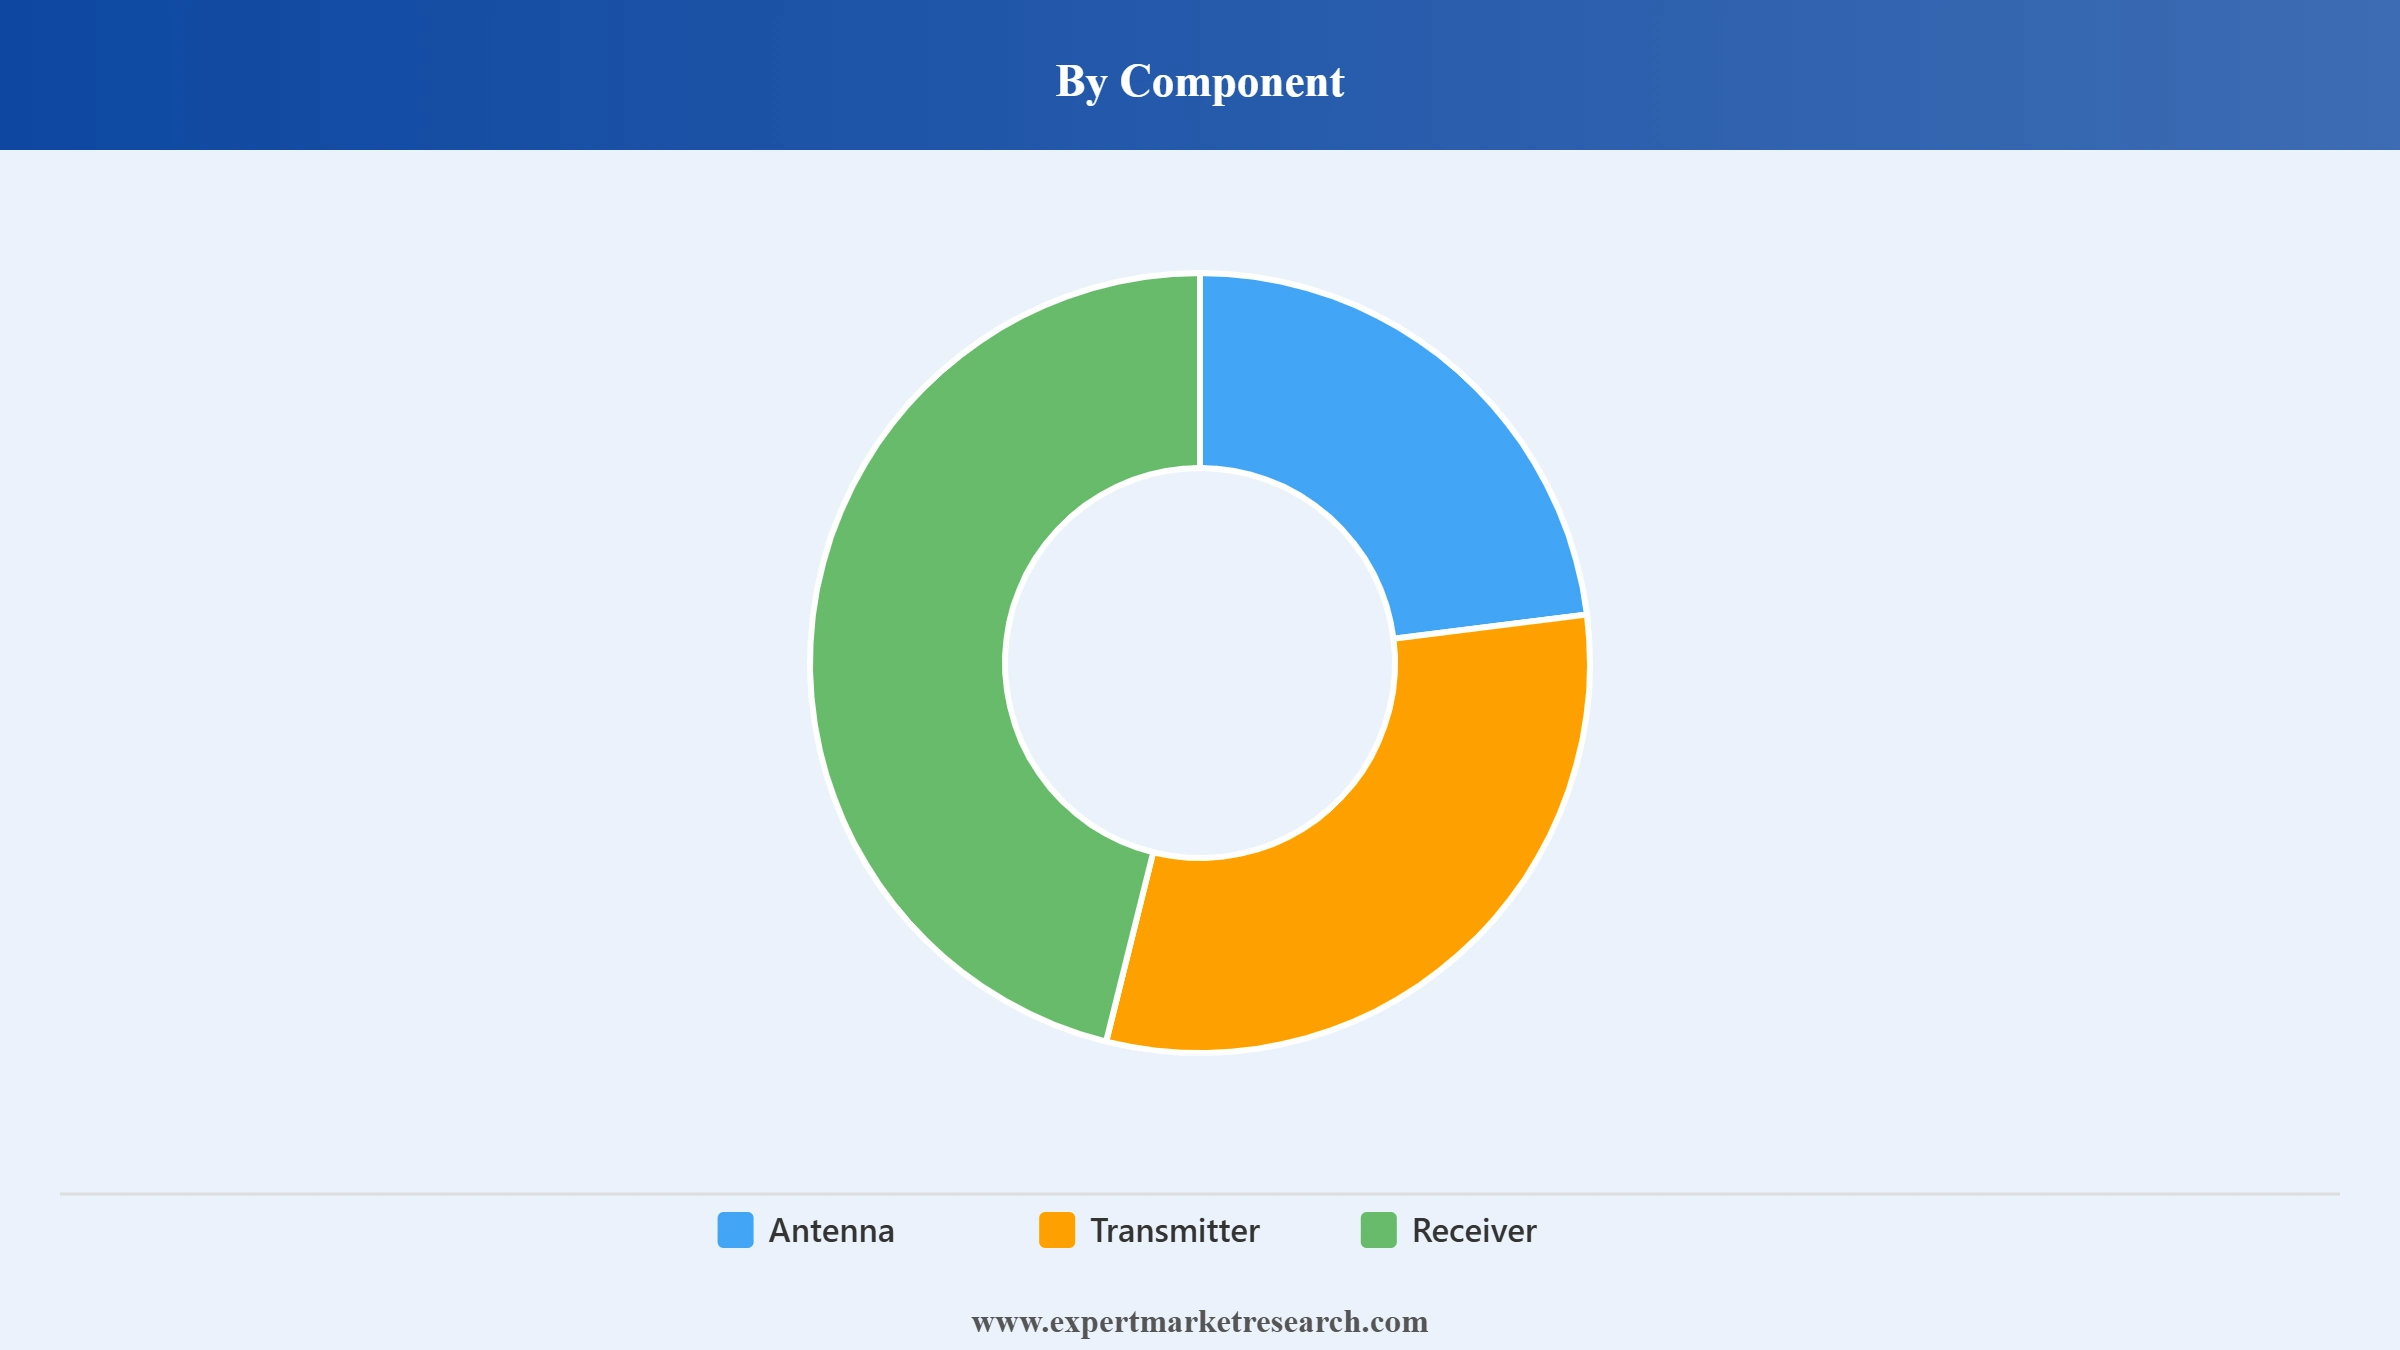
Key Insight: Antennas account for a large share of the India radar market as AESA and phased array designs require dense transmit-receive module arrays for fighter, air defence, and surveillance systems. Transmitters generate the radio frequency pulses that determine detection range and are central to high-power ground and naval radars. Receivers process reflected signals and are gaining importance as digital beamforming and signal processing software improve target discrimination. Others cover displays, power supplies, and cooling systems that support radar operation. In March 2026, Data Patterns secured a Rs 288 crore order from the India Meteorological Department to supply 32 Doppler weather radar transmitter and antenna units for storm and precipitation forecasting.
Market Breakup by Radar Service
Key Insight: Installation and integration services lead the India radar market as new systems require careful fitting onto aircraft, ships, and fixed sites alongside existing sensors and networks. Support and maintenance services are expanding as the installed base of indigenous and imported radars grows and requires sustained servicing over long operational lives. Training and consulting are gaining traction as manufacturers transfer technology and share operational knowledge with domestic partners. A Bengaluru-based firm unveiled tactical radar solutions in February 2025 under a technology transfer partnership with an Israeli defence electronics group, reflecting the wider knowledge-sharing trend.
Market Breakup by Platform
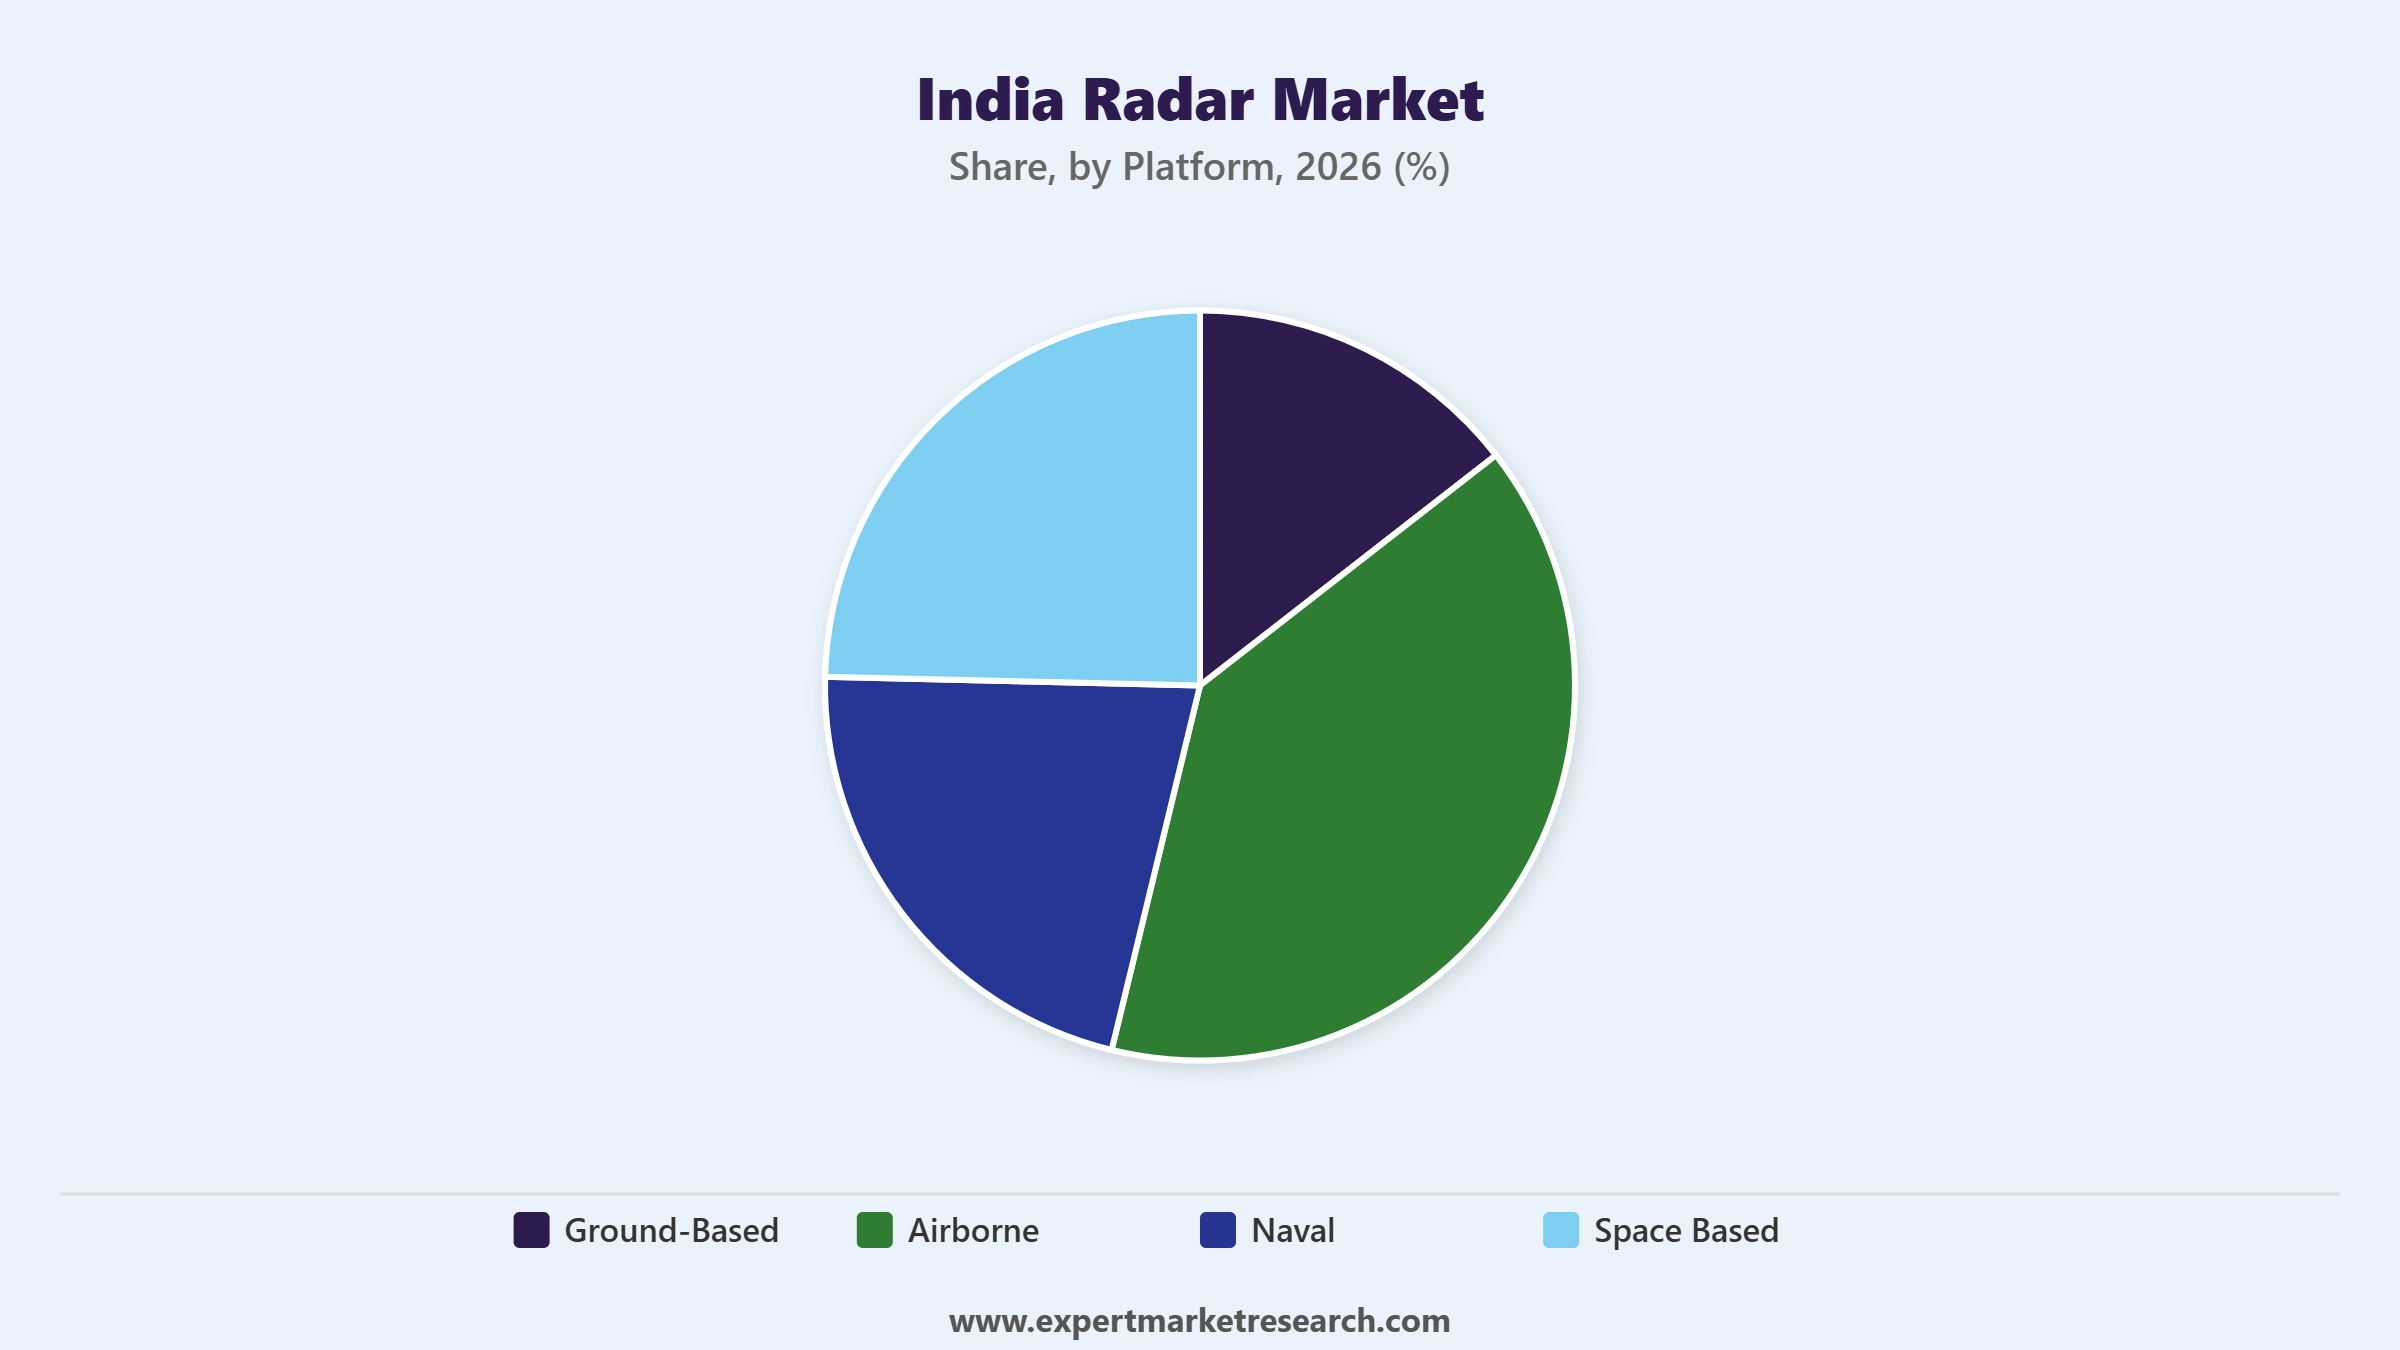
Key Insight: Ground-based radars dominate the India radar market, supporting air defence, border surveillance, and air traffic control from fixed and transportable installations across varied terrain. Airborne radars are expanding as fighter aircraft fleets are upgraded with indigenous AESA systems for improved detection and targeting. Naval radars support surface and air surveillance aboard warships and patrol vessels, while space-based radar is an emerging category tied to satellite earth observation. Tata Advanced Systems, working with Indra, was reported in September 2025 to have delivered India's first indigenously integrated next-generation naval surveillance radar for the Indian Navy.
Market Breakup by End Use
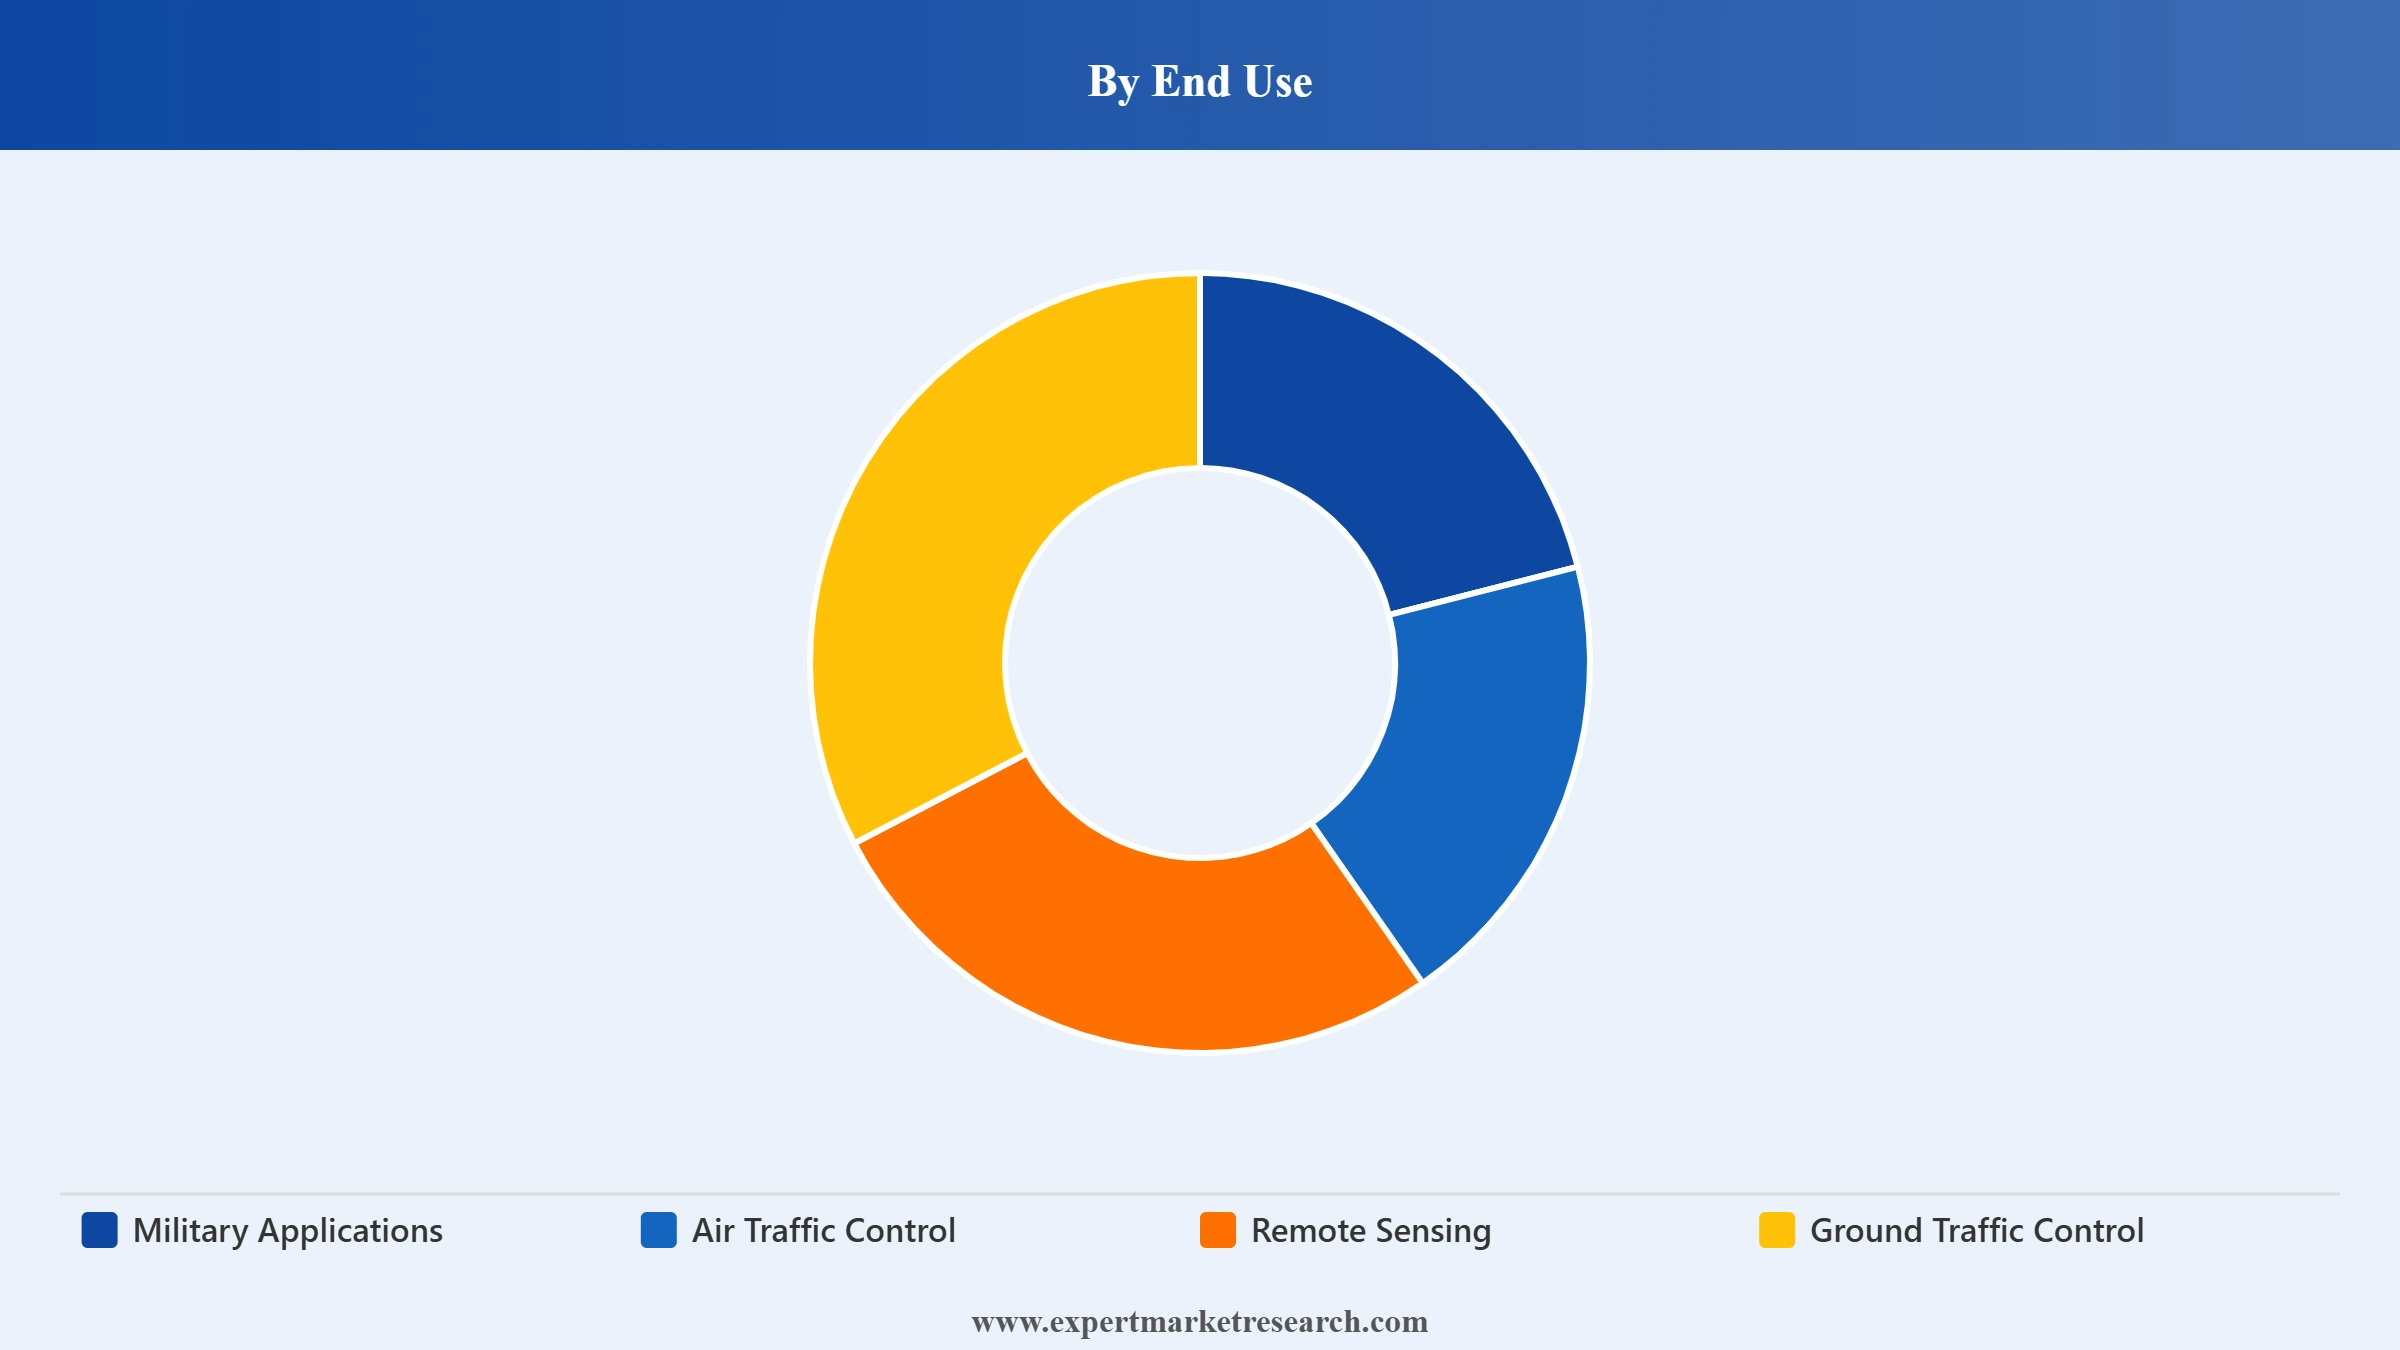
Key Insight: Military applications dominate the India radar market, covering air defence, battlefield surveillance, and naval detection needs tied to border security and fleet modernisation. Air traffic control is the fastest-growing end use as civil aviation authorities expand airport radar coverage to match rising passenger traffic. Remote sensing is gaining share through weather and earth observation programmes, while ground traffic control uses radar for highway and toll monitoring. In June 2025, South Korean radar firm bitsensing partnered with IKIO Technologies to pilot radar-based traffic monitoring sensors along the Delhi-Mumbai Expressway, widening ground traffic control adoption. Others include maritime port surveillance and scientific research applications supporting the segment's broadening base of civil users.
Market Breakup by Region
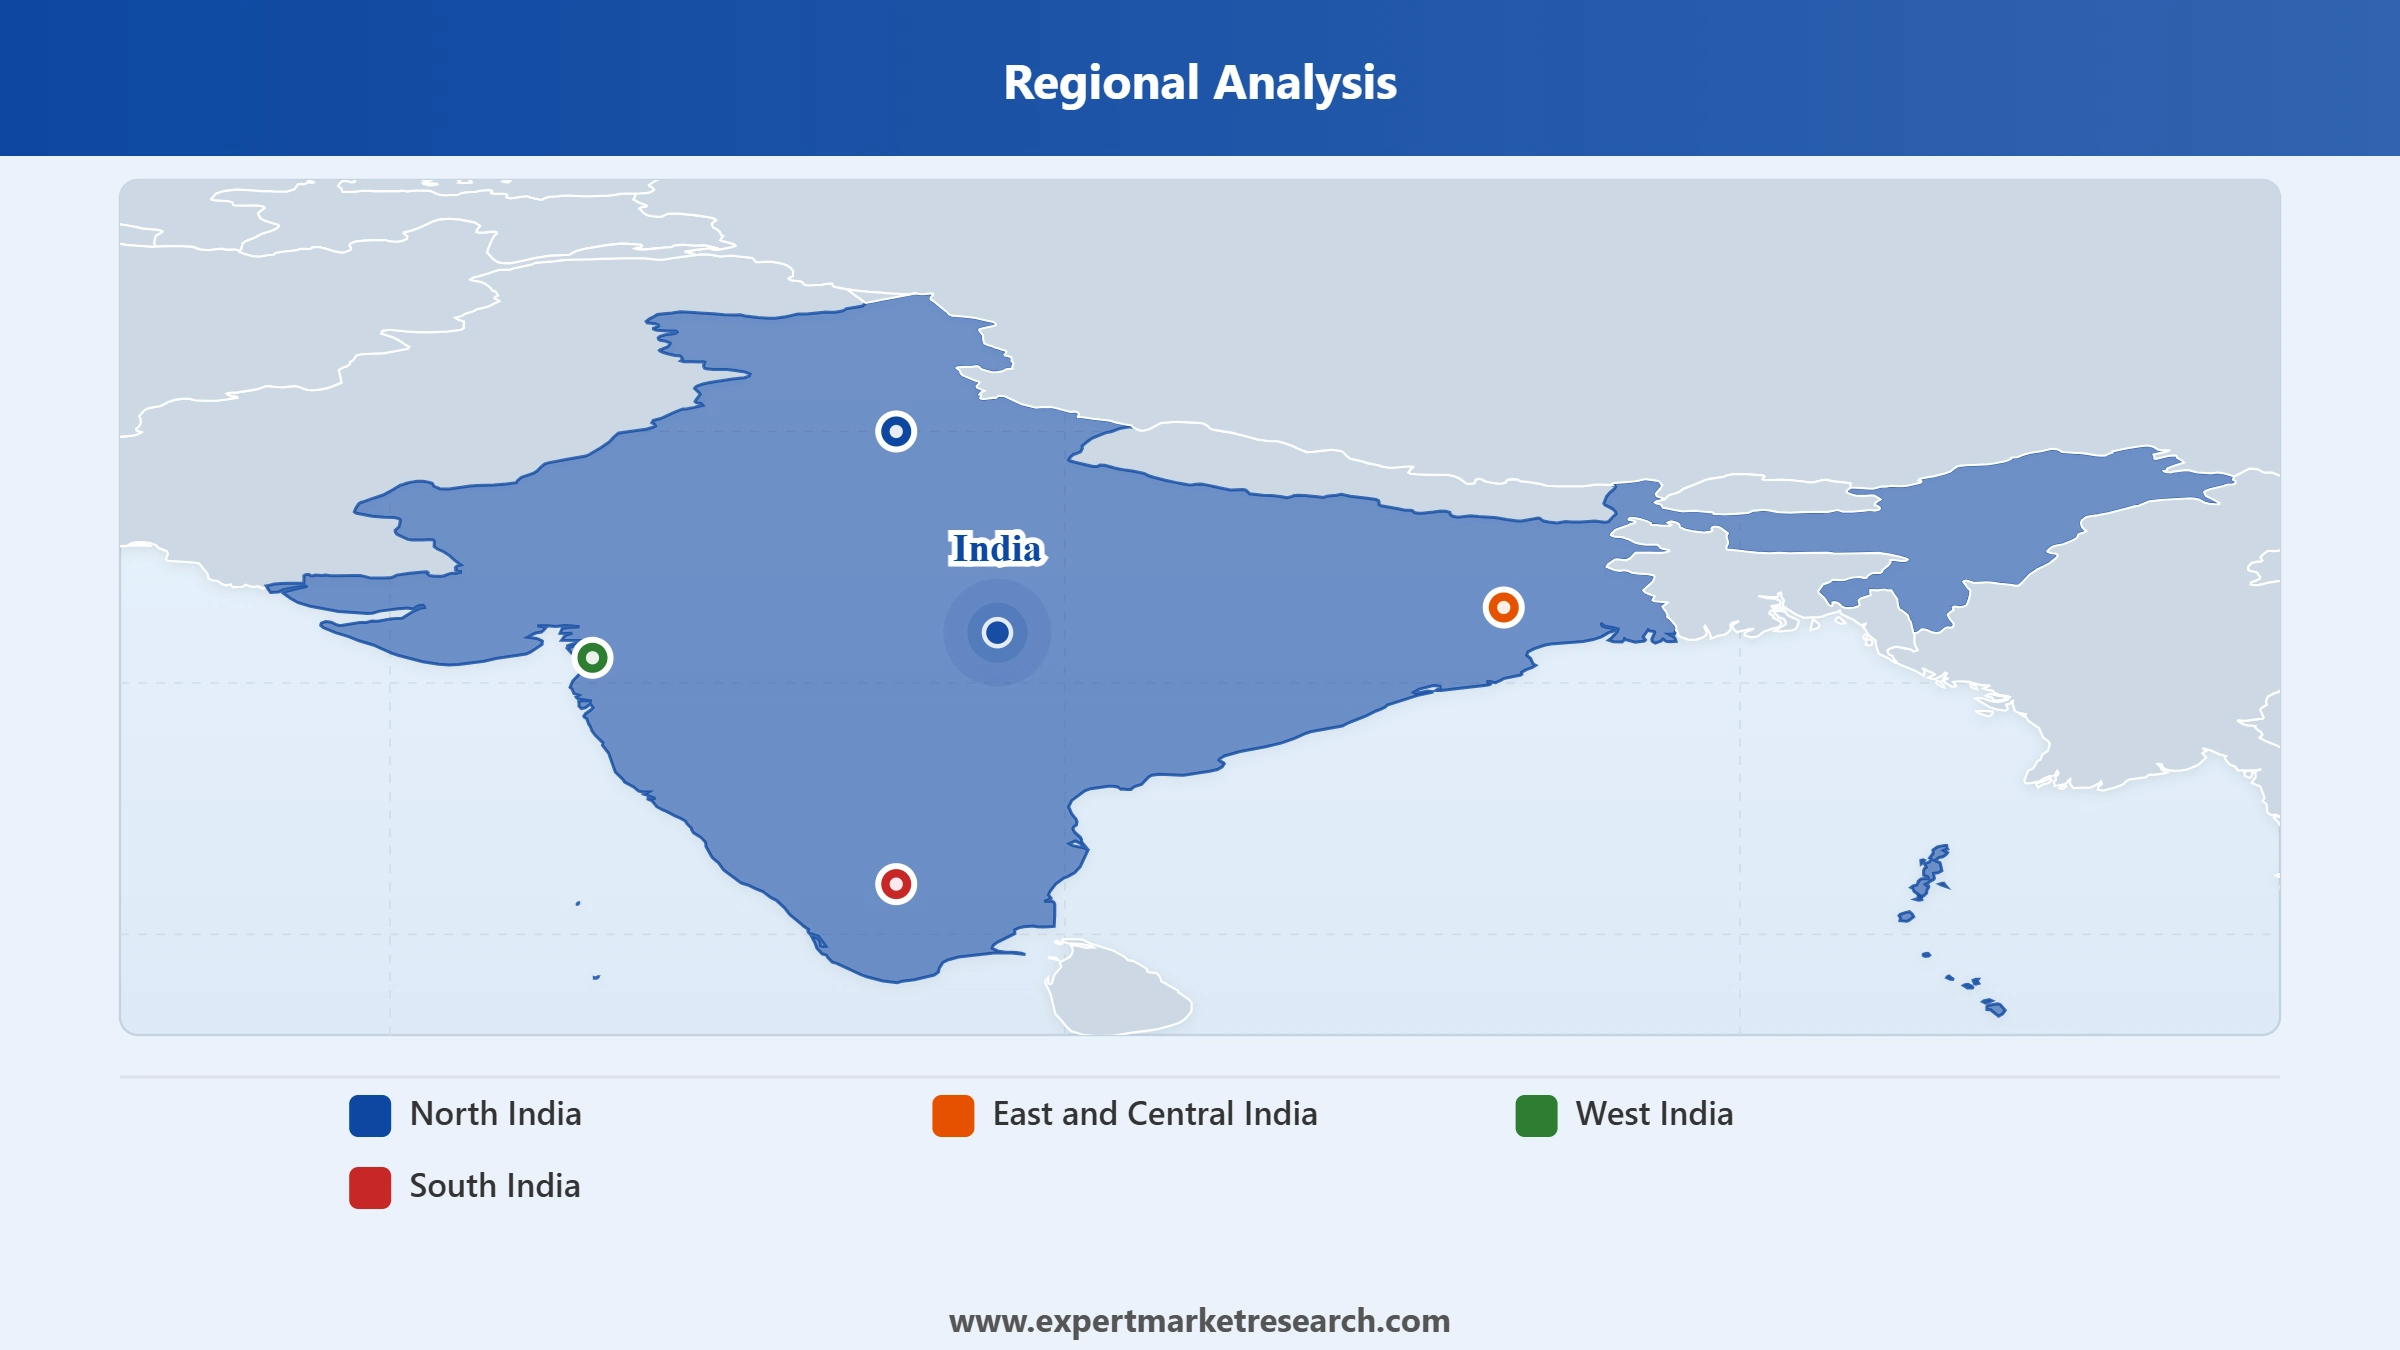
Key Insight: North India hosts major defence ministries, procurement bodies, and testing establishments that anchor radar programme decisions and induction schedules. East and Central India is building broader defence testing infrastructure that supports the wider radar and weapons development ecosystem. West India contributes through aerospace and shipbuilding clusters linked to naval and airborne radar integration. South India has emerged as a leading manufacturing base, with new component and sub-system plants concentrated around established electronics and aerospace corridors.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By component, antennas dominate the market owing to dense array requirements in AESA and phased array radar systems
Antennas account for the largest share of the India radar market because AESA and phased array systems require thousands of transmit-receive modules across large array surfaces for fighter, air defence, and surveillance applications. Suppliers are winning dedicated contracts for antenna beam control hardware as programmes move from imported to indigenous array technology. In July 2025, AXISCADES secured a defence electronics order worth around INR 600 crore for an antenna beam control motherboard on the indigenous Virupaksha AESA radar programme.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Receivers are expanding at a strong pace in the India radar market as digital beamforming and advanced signal processing steadily improve target discrimination in cluttered and congested environments across the country. Processing electronics increasingly determine radar performance as much as raw transmit power, pushing suppliers to invest in receiver and processing hardware. In August 2026, Data Patterns secured a radar electronics order worth INR 585.76 crore from Bharat Electronics, covering receiver and processing sub-systems for ongoing indigenous radar production programmes.
By radar service, installation and integration lead the market owing to the complexity of fitting new systems onto aircraft, ships, and fixed sites
Installation and integration hold the largest share of the India radar market because new radars must be carefully fitted onto aircraft, patrol vessels, and fixed installations alongside existing sensors, wiring, and command networks. Integration work is specialised and often ties suppliers into long-term programme relationships with the armed forces. In December 2025, Lotus Advanced Technologies signed a contract worth INR 640 crore with Hindustan Aeronautics and an Israeli radar maker to integrate maritime patrol radars onto Indian Navy Dornier aircraft.

Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Support and maintenance services are expanding steadily in the India radar market as the installed base of civil and defence radars grows and requires sustained servicing across long operational lifespans. Civil aviation authorities are budgeting heavily for radar and navigation system upkeep alongside new installations across the country. In January 2026, the Airports Authority of India outlined a INR 15,000 crore modernisation plan covering upgrades to air traffic control towers, radar, and navigational systems by the end of 2028.
By platform, ground-based radars dominate the market owing to their central role in air defence and border surveillance
Ground-based radars account for the largest share of the India radar market as they anchor air defence, border surveillance, and air traffic control networks across varied and often mountainous and difficult terrain across the country. Transportable ground systems allow rapid repositioning to contested border areas without relying on fixed supporting infrastructure. In March 2026, the Ministry of Defence signed a contract worth INR 1,950 crore with Bharat Electronics for indigenously developed mountain radar systems for the Indian Air Force.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Airborne radars are growing at a fast pace in the India radar market as fighter fleets are progressively upgraded with indigenous AESA systems that improve detection, tracking, and targeting accuracy substantially over time. Fleet modernisation programmes are creating sustained demand for radar-equipped aircraft over the coming decade across the armed forces. The first serially produced Tejas Mark 1A fighter, fitted with the indigenous Uttam AESA radar, rolled out from Nashik in July 2025 ahead of delivery to the Air Force.
By end use, military applications dominate the market owing to sustained air defence and battlefield surveillance procurement
Military applications hold the largest share of the India radar market as the armed forces continue large-scale procurement of air defence, fire control, and battlefield surveillance radars to replace ageing imported equipment across the country. Weapon locating and target acquisition systems remain a core defence procurement priority along contested and sensitive northern borders. In March 2025, Bharat Electronics delivered the 49th Swathi weapon locating radar to the Indian Army, completing a batch ordered to strengthen artillery detection along mountainous frontiers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Air traffic control is expanding quickly in the India radar market as new airports and rising passenger volumes push civil aviation authorities to steadily add and upgrade surveillance radar coverage across the whole country. Regional airports are increasingly receiving dedicated radar installations instead of relying solely on adjacent facilities elsewhere. An advanced radar system at an airport in Nagpur was reported in April 2026 to be on track for commissioning by September, improving approach and departure surveillance for the region.
South India leads the market through concentrated component and sub-system manufacturing investment
South India holds the largest overall share of the India radar market, anchored by established electronics and aerospace manufacturing clusters in Karnataka and Tamil Nadu that host component, sub-system, and integration facilities. Existing skilled workforces and supplier networks in the region continue to attract new radar-related investment. In May 2026, DCX Systems and Israel Aerospace Industries began construction of a radar manufacturing facility in the Tamil Nadu Defence Industrial Corridor to execute confirmed radar-related orders worth around INR 800 crore.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
East and Central India is registering strong growth in the India radar market as the region builds broader defence testing and research infrastructure that supports radar and weapons development programmes. New testing capacity is helping ease pressure steadily on existing facilities located in Odisha. In September 2026, the West Bengal government approved a DRDO proposal to set up a new weapons and missile testing range in Purba Medinipur district, expanding the country's wider defence testing and evaluation network further.
The industry is becoming more capacity driven as major India radar companies invest in AESA technology, indigenous component manufacturing, and dedicated production facilities to meet growing defence and civil demand. Suppliers are prioritising array design, signal processing, and system integration to stand out in a field where indigenisation is a key procurement criterion. A strategic focus on domestic manufacturing is helping firms secure long-term government contracts, while partnerships between Indian and global radar players are transferring technology into local production.
Leading India radar market players are also working on space-based sensing, naval surveillance, and multi-mode airborne systems to widen their addressable applications. Opportunities are emerging in weather radar, air traffic control modernisation, and battlefield surveillance as government agencies expand procurement budgets. Firms that combine strong indigenous design capability, dependable component supply chains, and established defence relationships are expected to strengthen their competitive position through the forecast period, supported by sustained government emphasis on self-reliant defence production.
Founded in 1906 and headquartered in Charlotte, North Carolina, United States, the company supplies aerospace radar and navigation systems alongside a broad portfolio of industrial automation and building technologies. Its aerospace division provides weather and surveillance radar systems for commercial and military aircraft, supported by a global network of manufacturing and engineering sites.
Founded in 2000 and headquartered in Paris, France, the company supplies ground, naval, and airborne radar systems alongside avionics, defence electronics, and space technology for military and civil customers worldwide. It maintains long-standing technology partnerships with Indian defence manufacturers covering radar and surveillance system co-development.
Founded in 1937 and headquartered in Linkoping, Sweden, the company develops airborne, ground-based, and naval radar systems alongside fighter aircraft, missile systems, and electronic warfare solutions. It supplies surveillance and fire control radar technology to armed forces and civil aviation authorities across multiple regions.
Founded in 1932 and headquartered in New Delhi, India, the company supplies scientific, geotechnical, and radar-linked instrumentation and represents several international defence and meteorological technology manufacturers in the domestic market. It supports weather radar and remote sensing deployments for government and research customers across the country.
Other key players in the market include Lockheed Martin Corporation, Northrop Grumman Corp., BAE Systems Plc, RTX Corp., General Dynamics Corp., and Leonardo S.p.A, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our India radar market trends 2026 report. Discover regional growth patterns, component preferences, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 1.22 Billion.
The market is projected to grow at a CAGR of 4.30% between 2026 and 2035.
The market is estimated to reach around USD 1.86 Billion by 2035.
Expanding indigenous AESA and component manufacturing, building dedicated regional production facilities, modernising civil air traffic and weather radar networks, integrating radar onto naval and airborne platforms, and forming technology transfer partnerships with global radar suppliers.
The key trends aiding the market expansion include the growing adoption of 3D and 4D radar technologies and rising indigenous manufacturing initiatives in the country.
The major end uses of the radar are military applications, air traffic control, remote sensing, and ground traffic control, among others.
The regions considered in the market are North India, East and Central India, West India, and South India.
The key players in the market include Honeywell International Inc., Lockheed Martin Corporation, Northrop Grumman Corp., BAE Systems Plc, RTX Corp., Thales S.A., Saab AB, Aimil Ltd., General Dynamics Corp., and Leonardo S.p.A, among others.
Companies face long defence procurement cycles, high development costs for AESA and phased array technology, strict indigenisation and testing requirements, dependence on government budget allocations, and competition from established global radar manufacturers.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment
|
| Breakup by Component |
|
| Breakup by Radar Service |
|
| Breakup by Platform |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




