

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
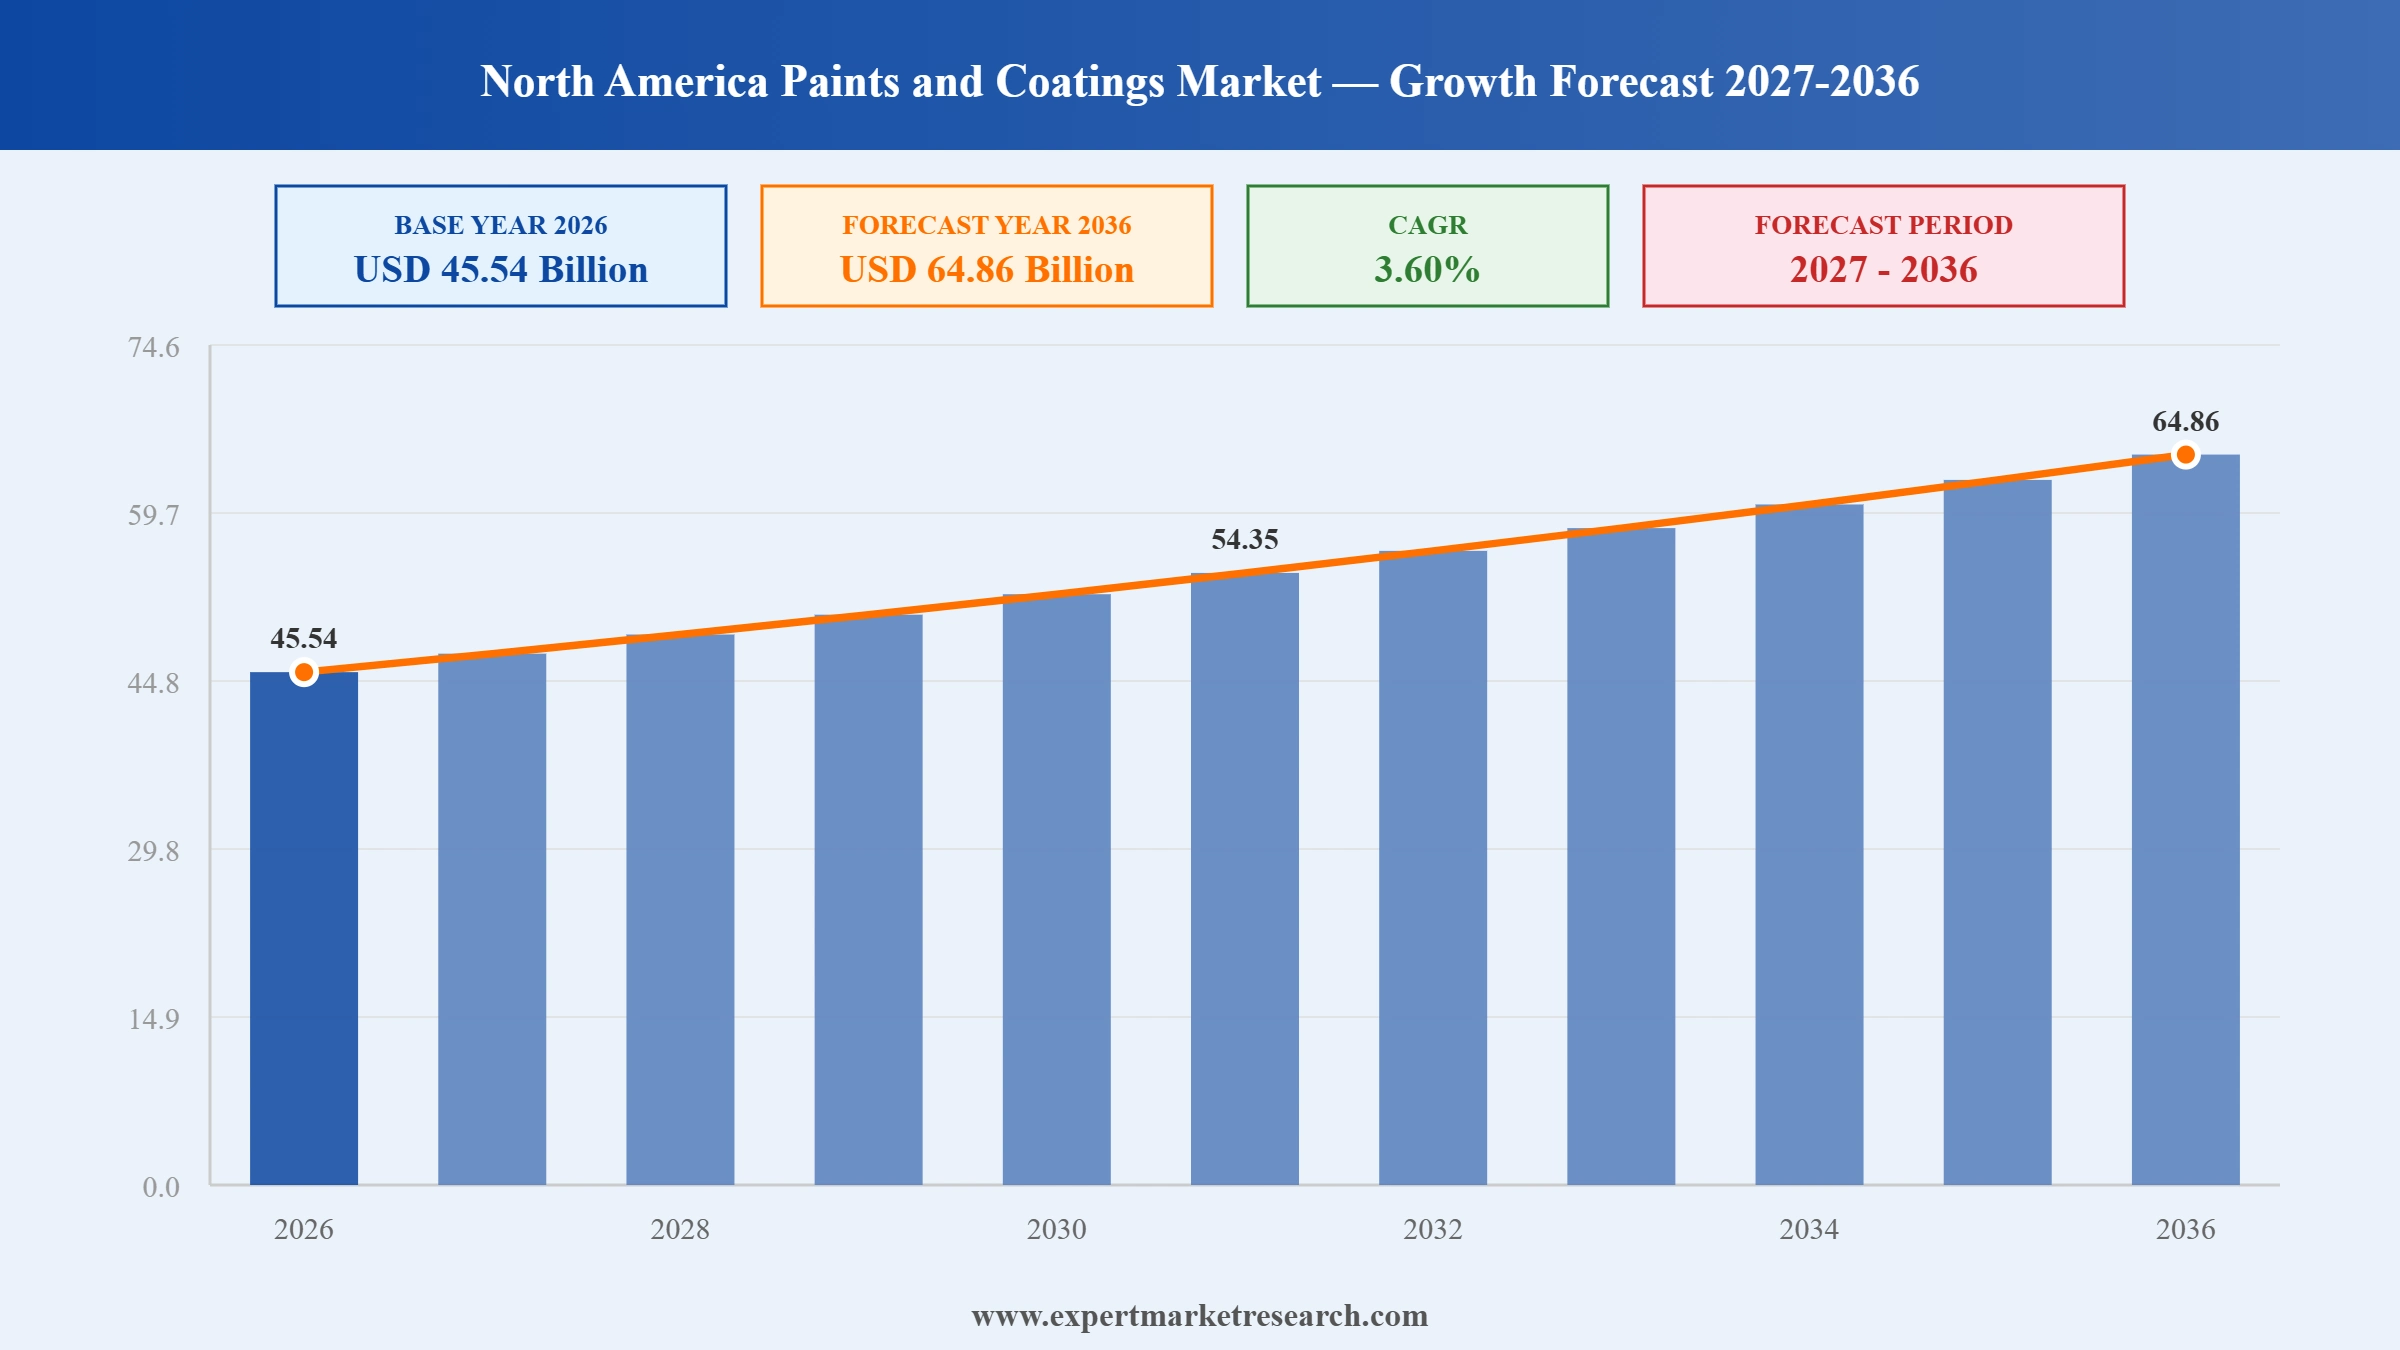
The North America paints and coatings market attained a value of USD 43.96 Billion in 2025 and is projected to expand at a CAGR of 3.60% through 2035. The market is further expected to reach USD 62.61 Billion by 2035. Rising construction activity, expanding automotive production, and growing demand for sustainable low VOC formulations are strengthening paints and coatings demand across the region. Expanding industrial manufacturing, alongside continued consolidation among major producers, is further encouraging companies to widen their product portfolios across every resin and technology category.
Paints and coatings refer to a broad category of surface protection and decorative products applied across architectural, automotive, industrial, and packaging applications. Acrylic resin systems hold a substantial share of the market owing to their balanced cost, weatherability, and colour retention across architectural and automotive finishes. Rising construction and automotive production activity continues to widen the customer base for paints and coatings among architectural, industrial, and original equipment manufacturers.
Demand is concentrating around companies able to combine sustainable formulation technology with established regional manufacturing capability. In January 2025, Cloverdale Paint announced a partnership with Celanese Corporation to use carbon capture and utilisation technology in new sustainable paint solutions, reflecting the industry shift toward lower carbon formulations. This sustainability driven positioning is converting rising demand for environmentally responsible coatings directly into expanded adoption across the North America paints and coatings market.
Companies across the North America paints and coatings market are converging on a common development direction, widening from standalone resin production toward integrated sustainability and performance technology platforms. Companies are increasingly pursuing large scale mergers and targeted acquisitions to broaden combined product portfolios and geographic reach. This shift is reshaping competitive dynamics among companies, favouring companies who can demonstrate diversified technology platforms over those offering single resin type solutions alone.
Read more about this report - Request a Free Sample
AkzoNobel and Axalta Coating Systems shareholders approved a proposed all stock merger of equals, creating a combined global coatings leader with dual headquarters in Amsterdam and Philadelphia. The combined entity is expected to generate approximately 17 billion dollars in annual revenue upon completion. Companies across the North America paints and coatings market can use large scale mergers of equals to combine complementary geographic footprints and technology platforms under one organisation.
RPM International acquired Kalzip, a global leader in the design and production of metal-based roofs and facades for building envelopes, adding the business to its Tremco Construction Products Group. The acquisition expanded RPM's protective and specialty coatings portfolio into metal building envelope systems. Companies across the North America paints and coatings market can use targeted acquisitions to extend specialty coatings portfolios into adjacent building envelope product categories.
Protech Group acquired LOES Enterprises, a Canadian industrial coatings provider, expanding its powder and liquid coating capabilities across additional manufacturing sites nationwide. The acquisition strengthened Protech's position in the Canadian powder coating market significantly. Companies across the North America paints and coatings market can use targeted regional acquisitions to expand powder coating manufacturing capacity without building new facilities from scratch across every region.
3M launched a next generation, electron beam curable epoxy structural adhesive for composite aircraft assembly in the United States, integrating electron beam technology to reduce curing time and minimise volatile organic compound emissions. The product targeted transportation and aerospace manufacturers seeking faster assembly cycles. Companies can use electron beam curing technology to reduce production cycle times while meeting tightening emissions standards.
Specialty chemical companies are increasingly divesting non-core coatings adjacent businesses to concentrate capital on higher margin specialty chemical operations. This is reshaping ownership of pavement marking and traffic solutions businesses across the North America paints and coatings market, favouring buyers who can integrate niche product lines into existing distribution networks. In April 2026, Ingevity Corporation completed the sale of Ozark Materials, a United States based pavement marking solutions provider, in a transaction valued at 65 million dollars.
Specialty materials companies are increasingly securing strategic capital partnerships that provide additional resources for circular economy and sustainability driven transformation strategies across every business segment. This is reshaping ownership structures across the North America paints and coatings market, favouring companies who can access long term-oriented investment capital. In December 2025, Covestro closed its strategic partnership with XRG, receiving a 1.17-billion-euro capital increase to support its Sustainable Future strategy.
Distributors are increasingly consolidating automotive refinish and specialty industrial coatings portfolios to expand geographic reach and customer breadth across the collision repair segment. This is reshaping distribution structure across the North America paints and coatings market, favouring distributors who can combine complementary regional coverage. In November 2025, Wesco Group agreed to acquire National Coatings and Supplies, a distributor of aftermarket automotive refinish and specialty industrial coatings, expanding its geographic reach and product portfolio.
Diversified chemical companies are increasingly acquiring specialty coatings businesses serving flexible materials applications to broaden portfolios beyond traditional adhesive and sealant offerings. This is reshaping ownership of specialty performance coating technology across the North America paints and coatings market, favouring acquirers who can integrate specialised treatment chemistry. In February 2026, Henkel agreed to acquire Stahl, a Dutch specialty coatings company serving leather, textile, and other flexible material applications, in a transaction valued at approximately 2.1 billion euros.
Coatings manufacturers are increasingly investing in domestic production capacity expansion to support localisation near original equipment manufacturer assembly platforms and shorten replenishment cycles. This is reshaping manufacturing footprint decisions across the market, favouring companies who can commit capital to new regional facilities. In October 2025, Benjamin Moore announced Silhouette AF-655 as its Color of the Year 2026, extending a decorative product cycle sold through more than 8,500 retail locations across the United States and Canada.
The Expert Market Research's report titled "North America Paints and Coatings Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Resin Type
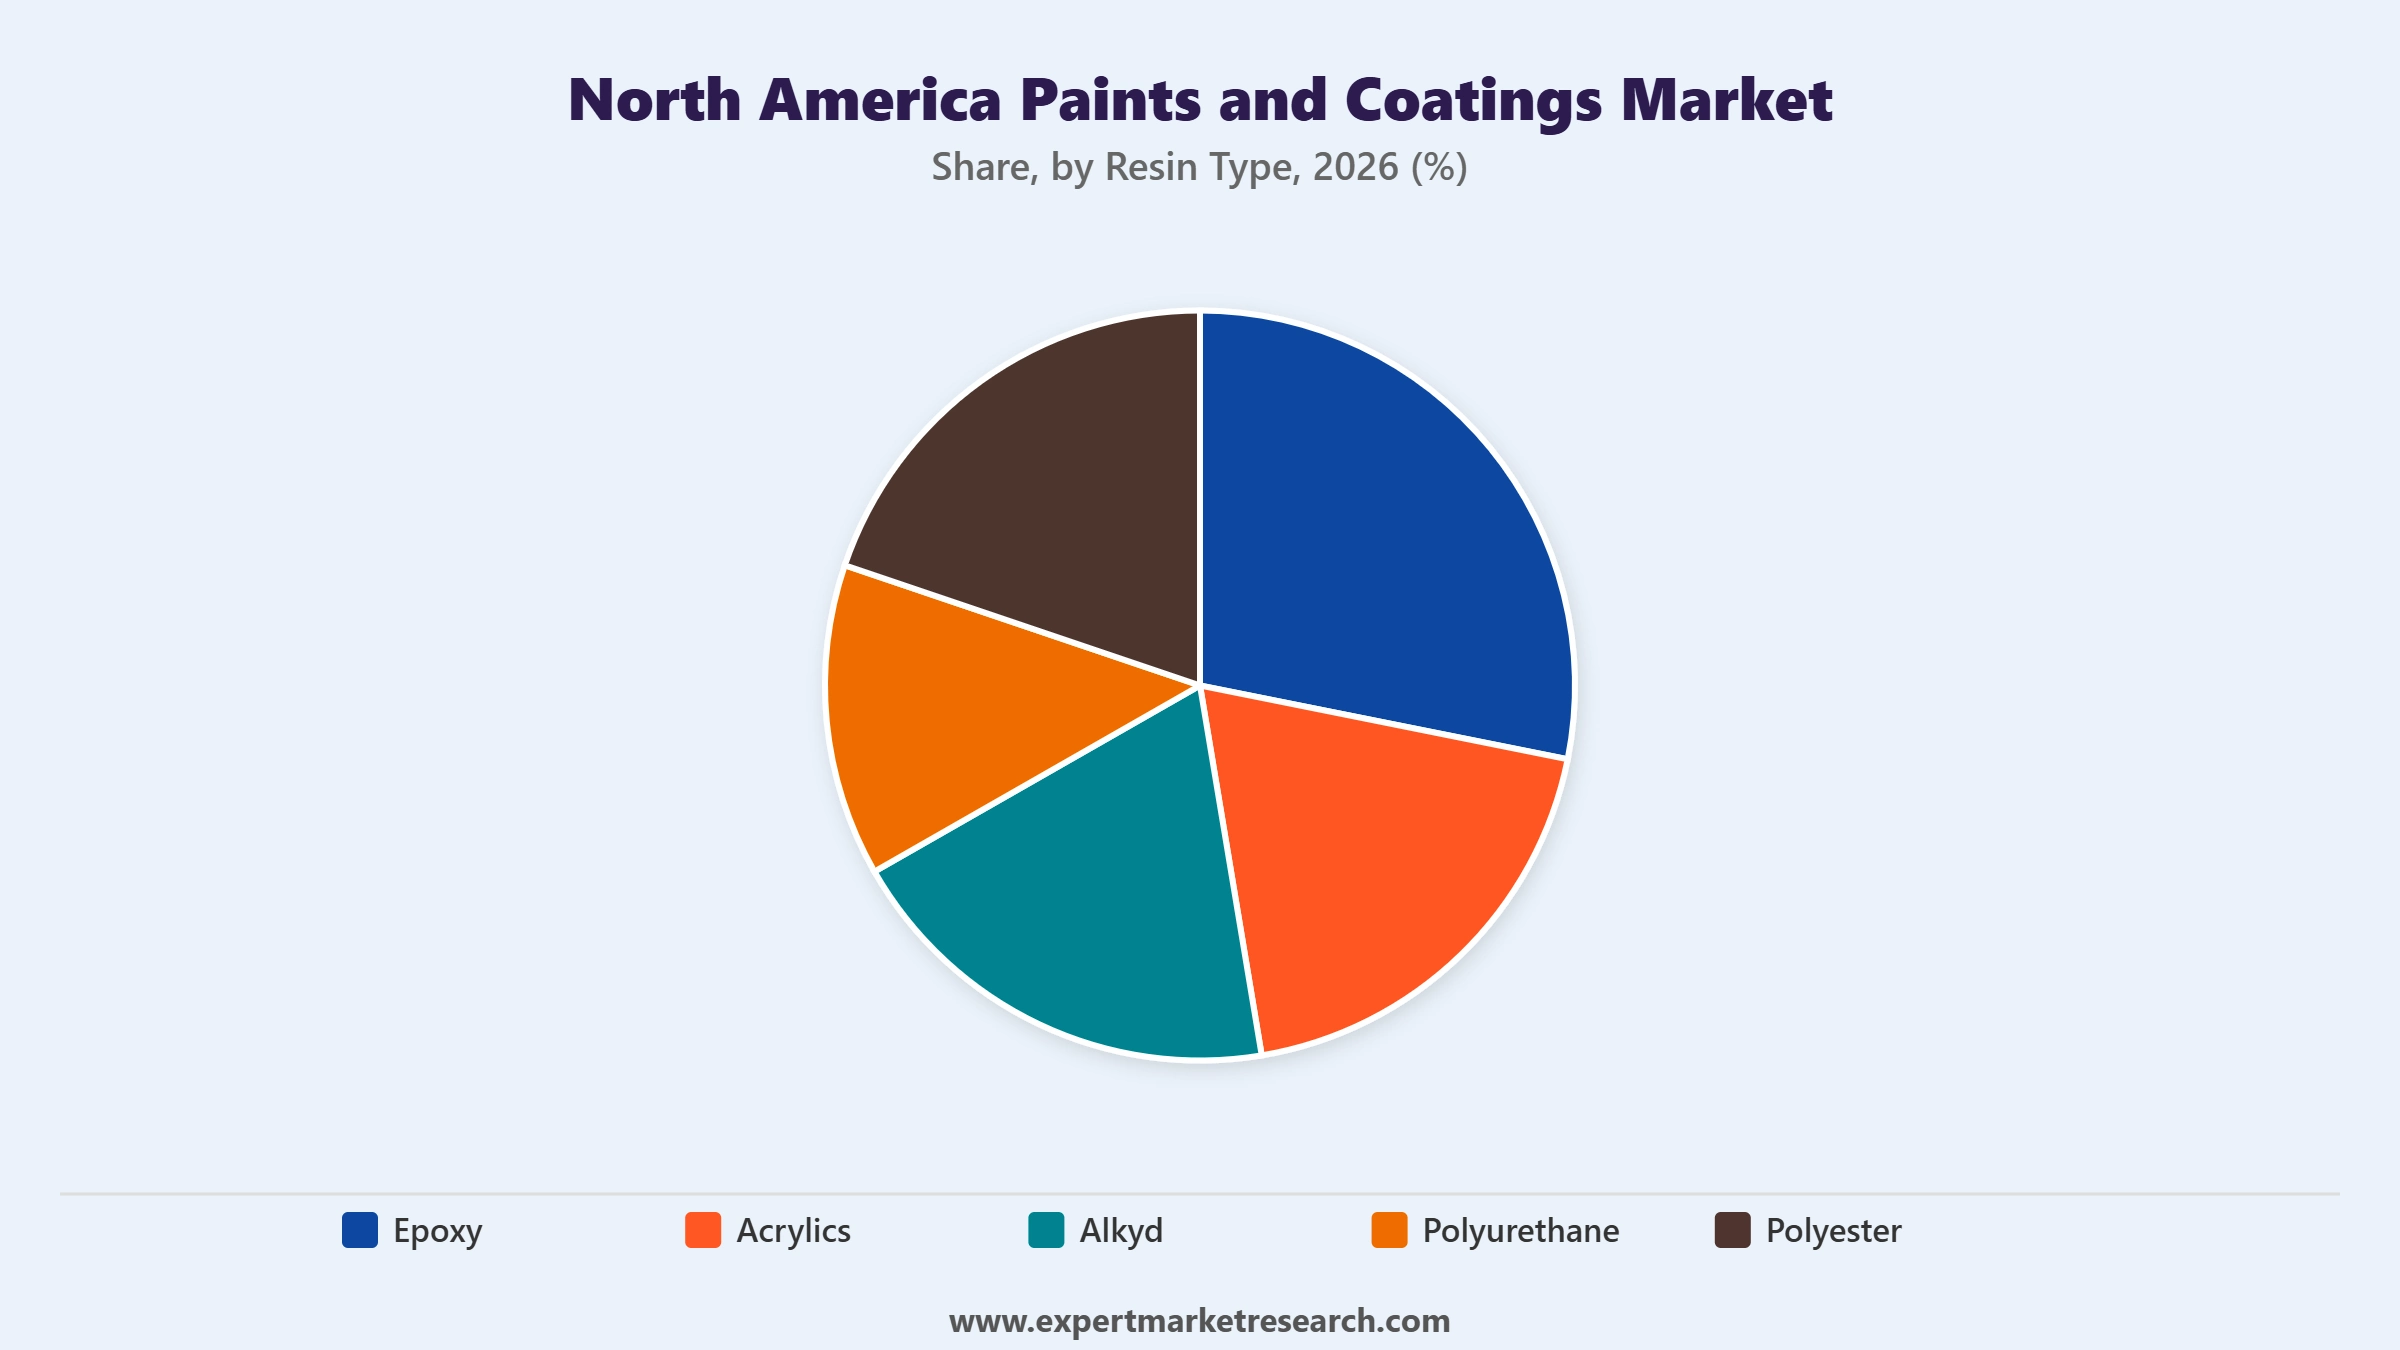
Key Insight: Acrylic resin systems dominate the resin type segment in the North America paints and coatings market given their balanced cost, weatherability, and colour retention across architectural and automotive finishes. Polyurethane grades are registering the fastest growth given rising demand for high abrasion durability in original equipment manufacturer assemblies. Epoxy resins remain indispensable in marine and infrastructure applications where chemical resistance outweighs initial cost concerns, while alkyd, polyester, and other resin types round out remaining demand across specialised applications.
Market Breakup by Technology
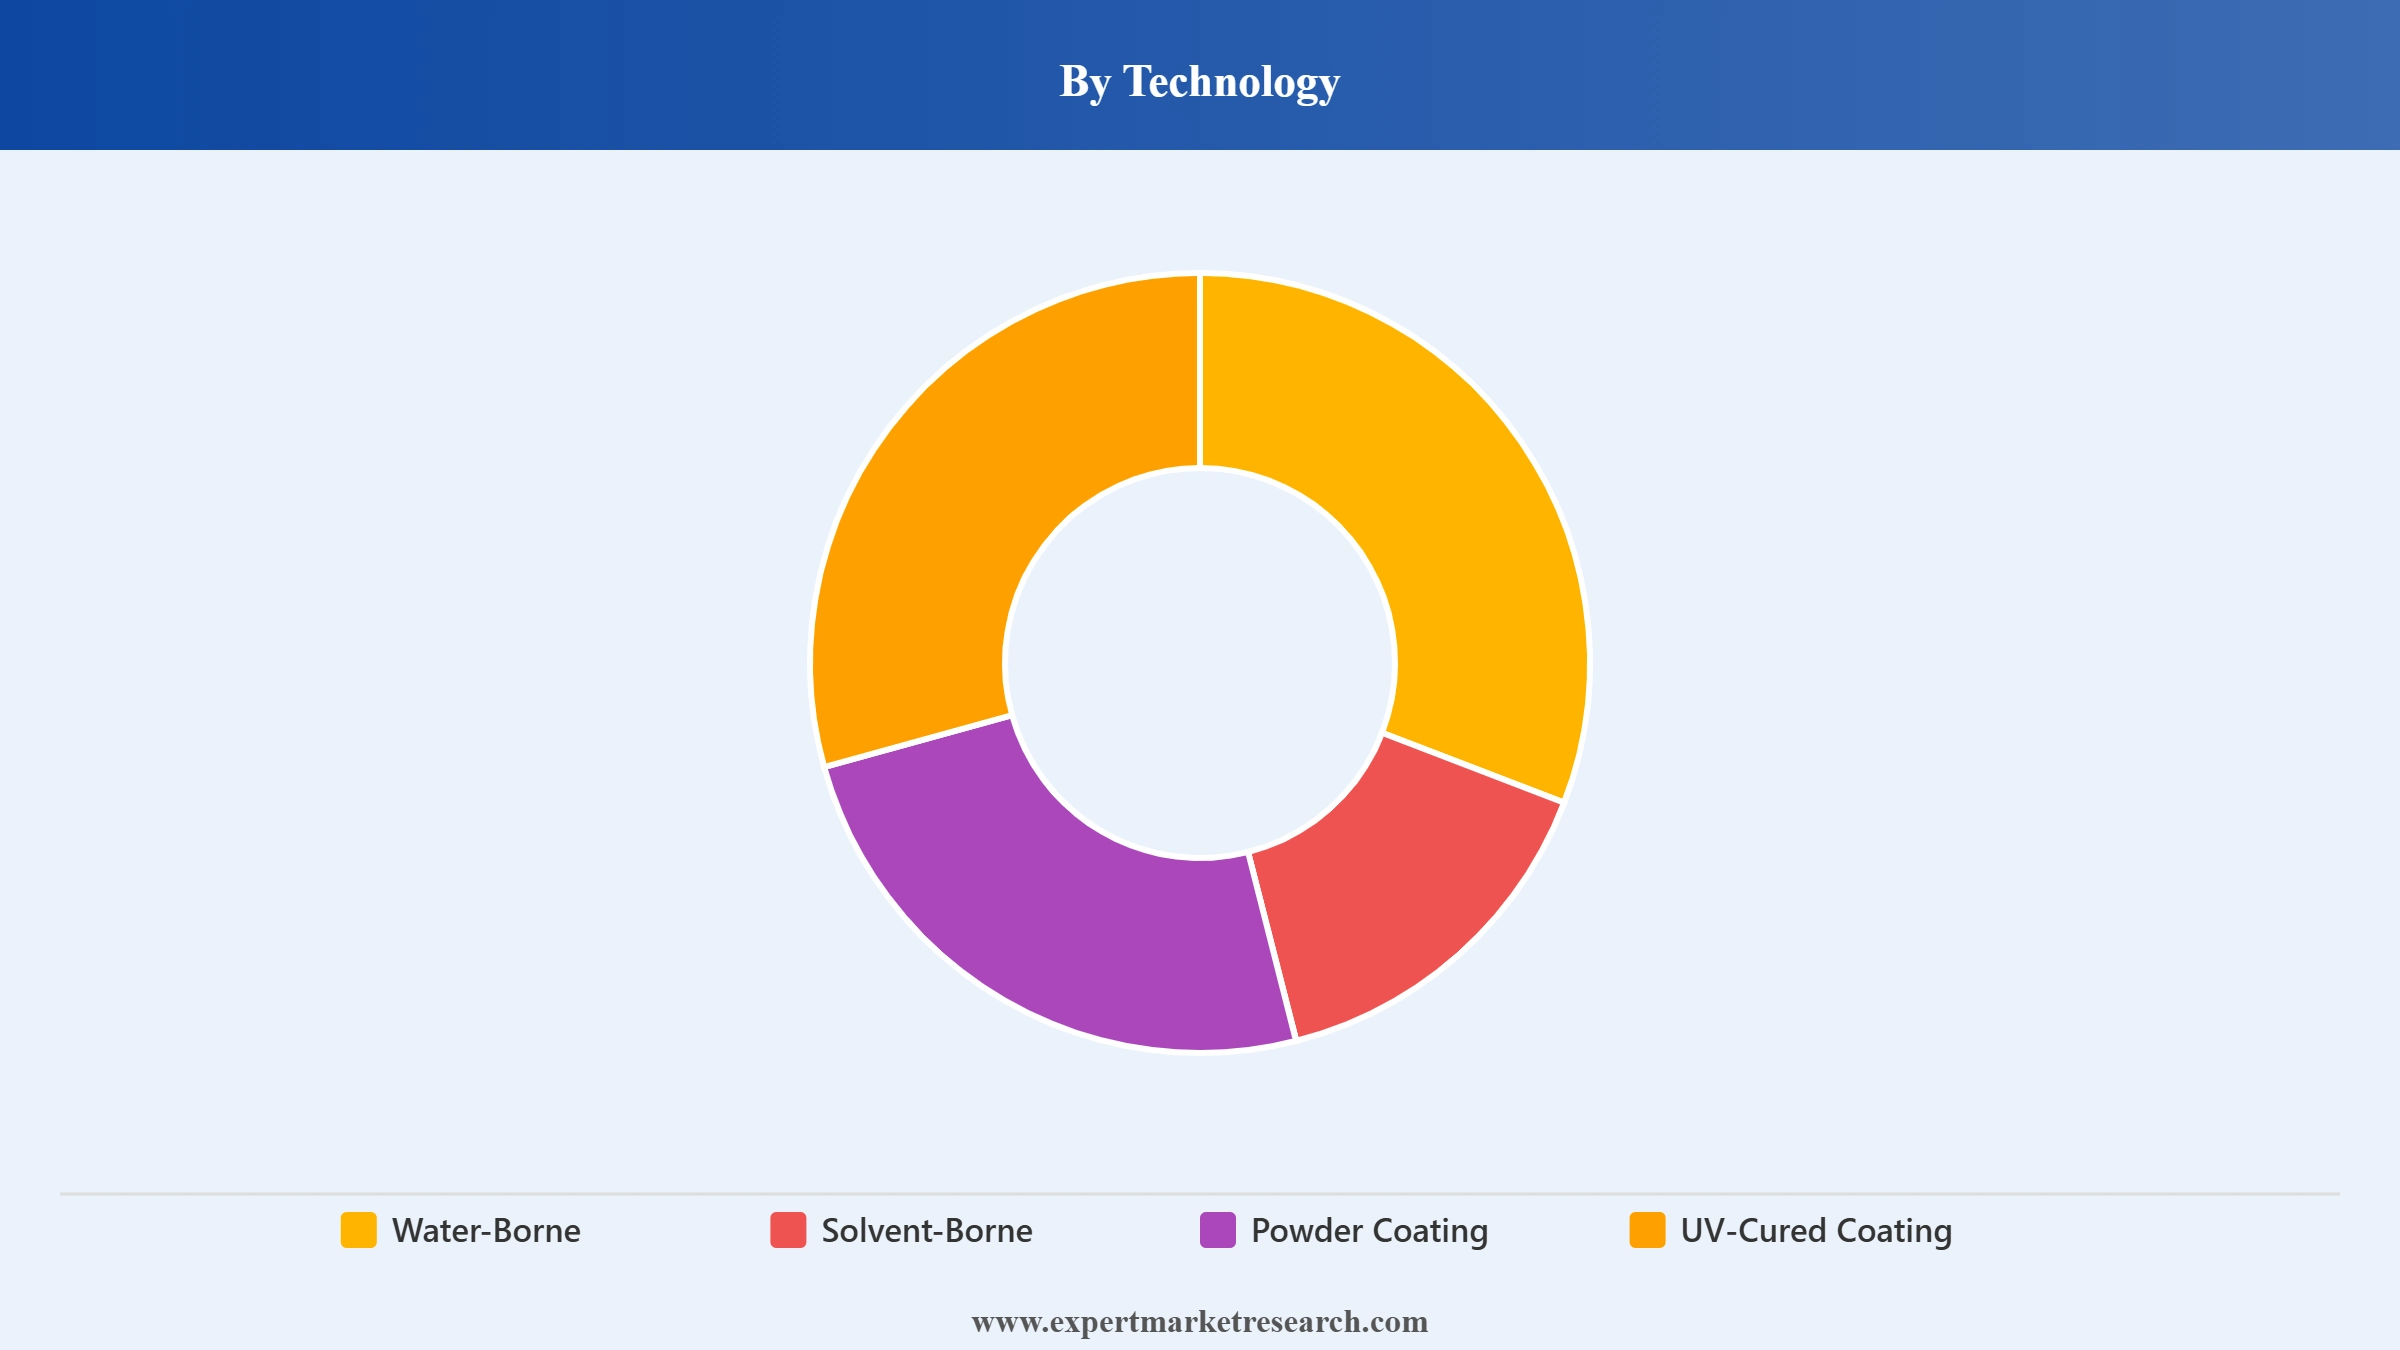
Key Insight: Water-borne technology dominates the technology segment in the North America paints and coatings market given tightening environmental regulations restricting volatile organic compound emissions across architectural and industrial applications. Powder coating technology is registering strong growth across both architectural and industrial applications given its durability and reduced environmental footprint compared with solvent-borne alternatives. Solvent-borne technology sustains steady demand across industrial and protective applications requiring superior adhesion on challenging substrates, while UV-cured coating technology serves specialised high speed production lines requiring rapid curing and minimal energy consumption.
Market Breakup by End Use
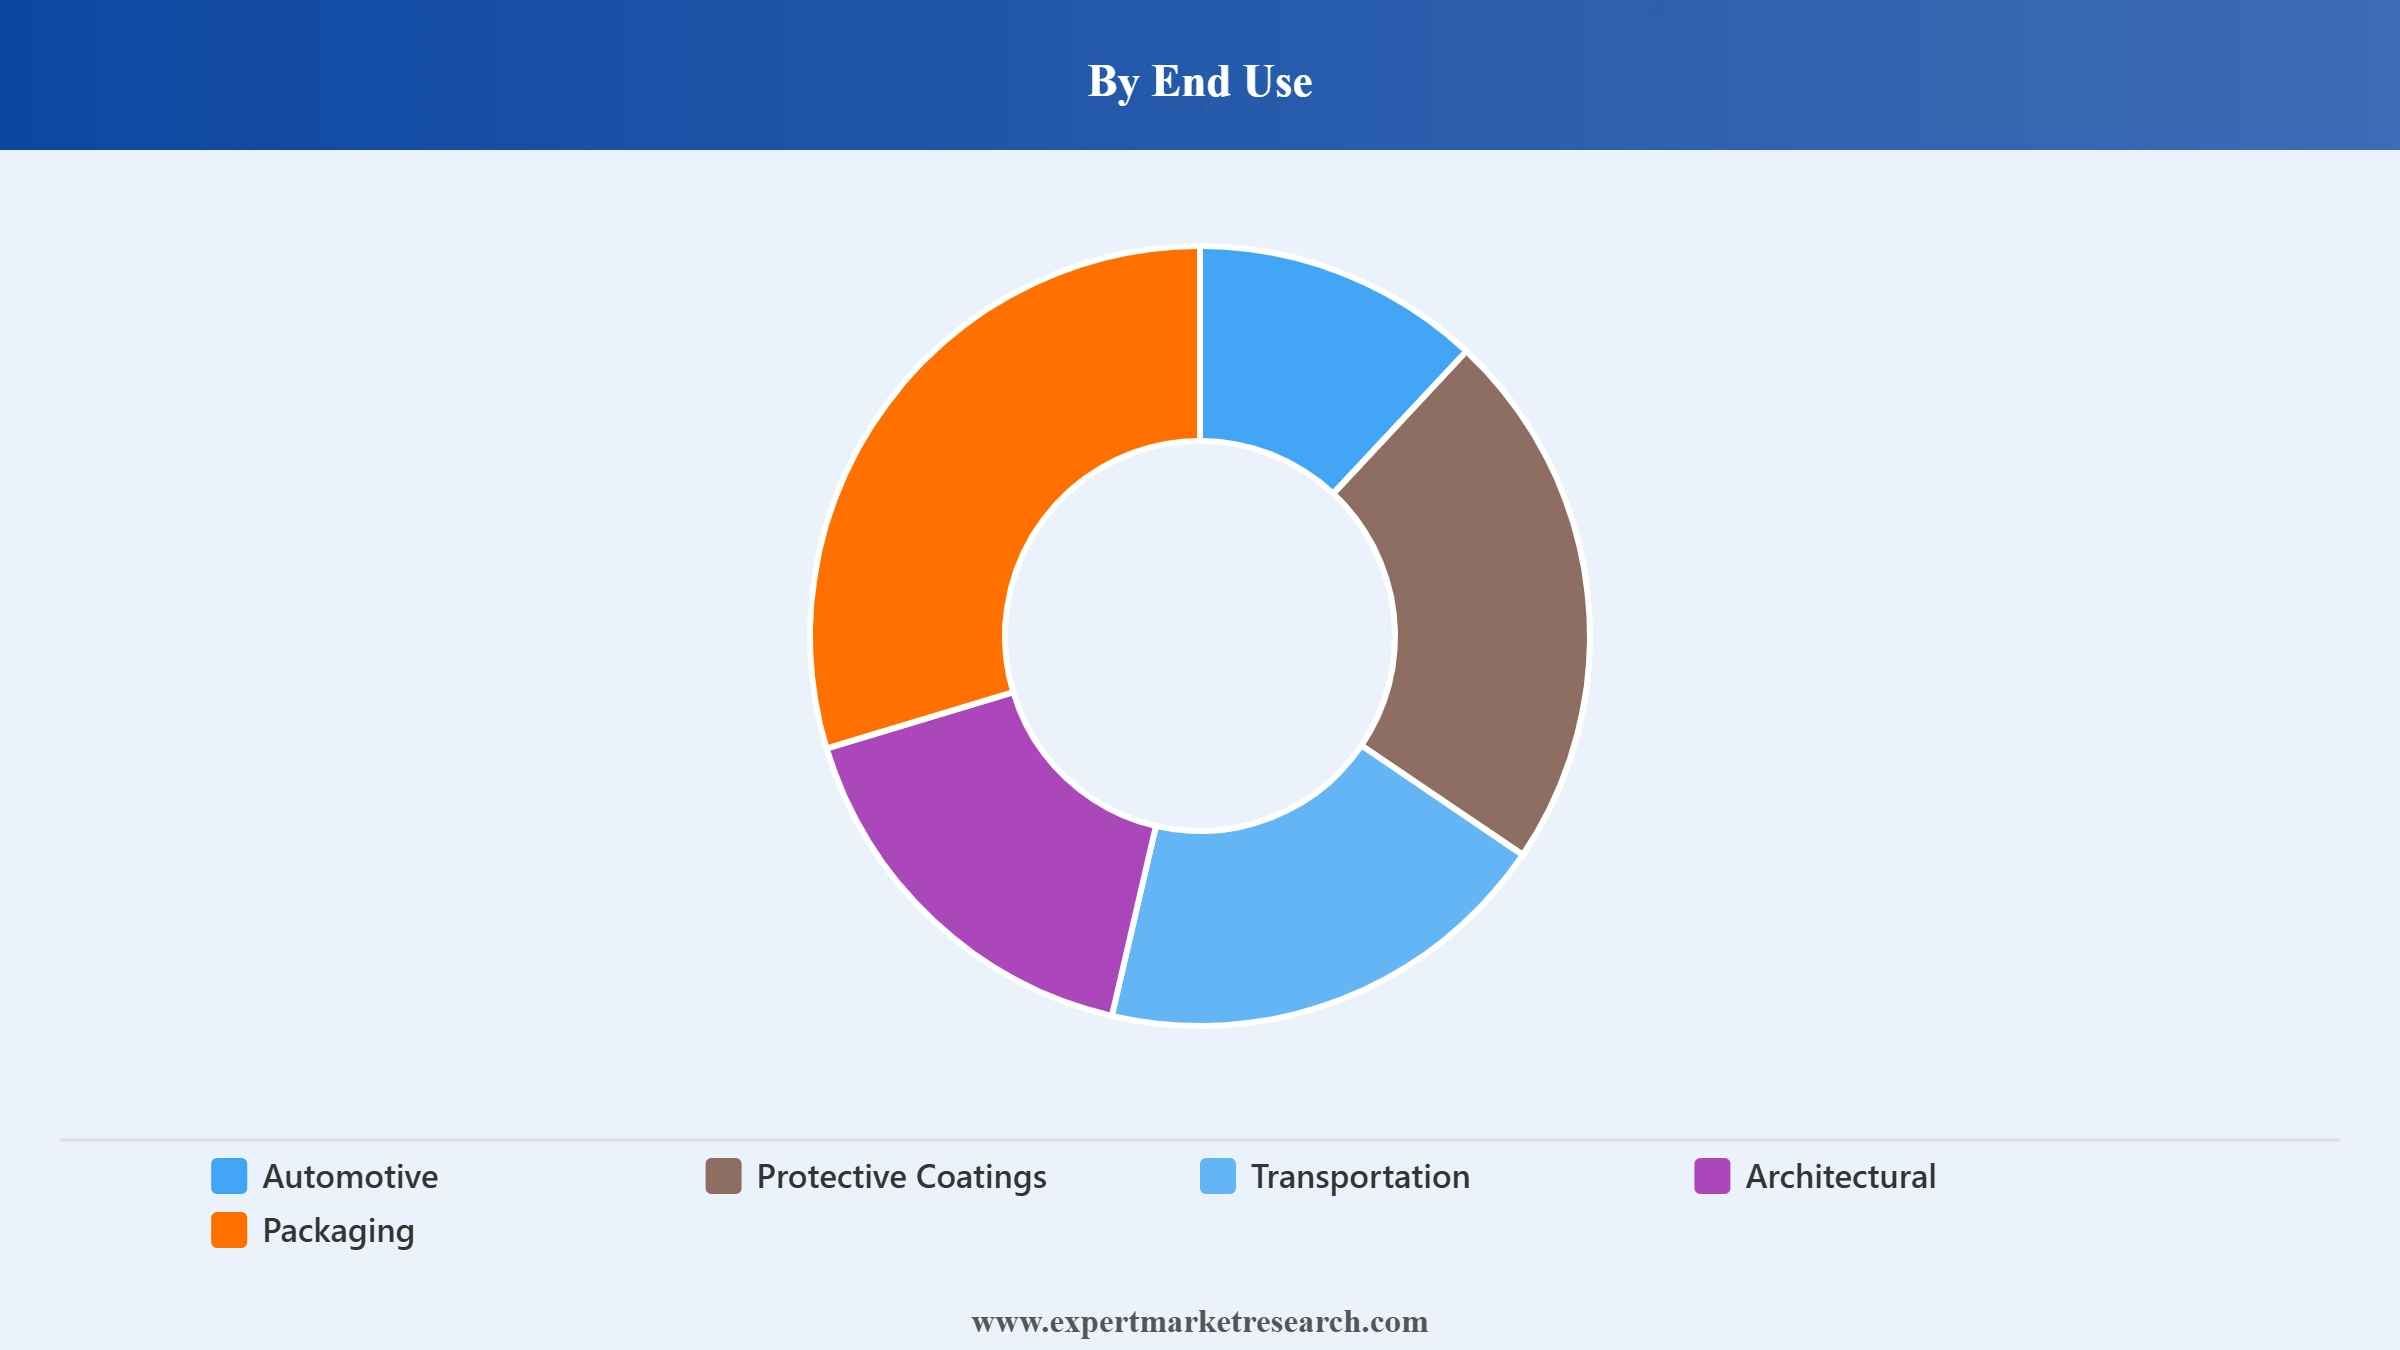
Key Insight: The architectural end use segment dominates given sustained residential and commercial construction activity across the North America paints and coatings market. Protective coatings and transportation applications, together comprising the industrial end use category, are registering the fastest growth given expanding manufacturing activity and infrastructure investment. In October 2025, Tnemec named a 2.5-million-gallon water tower in Fargo, North Dakota its Tank of the Year, protected by a fluoropolymer finish demonstrating protective coating durability. Automotive and packaging applications sustain steady demand, while other specialised end uses round out remaining market activity.
Market Breakup by Region
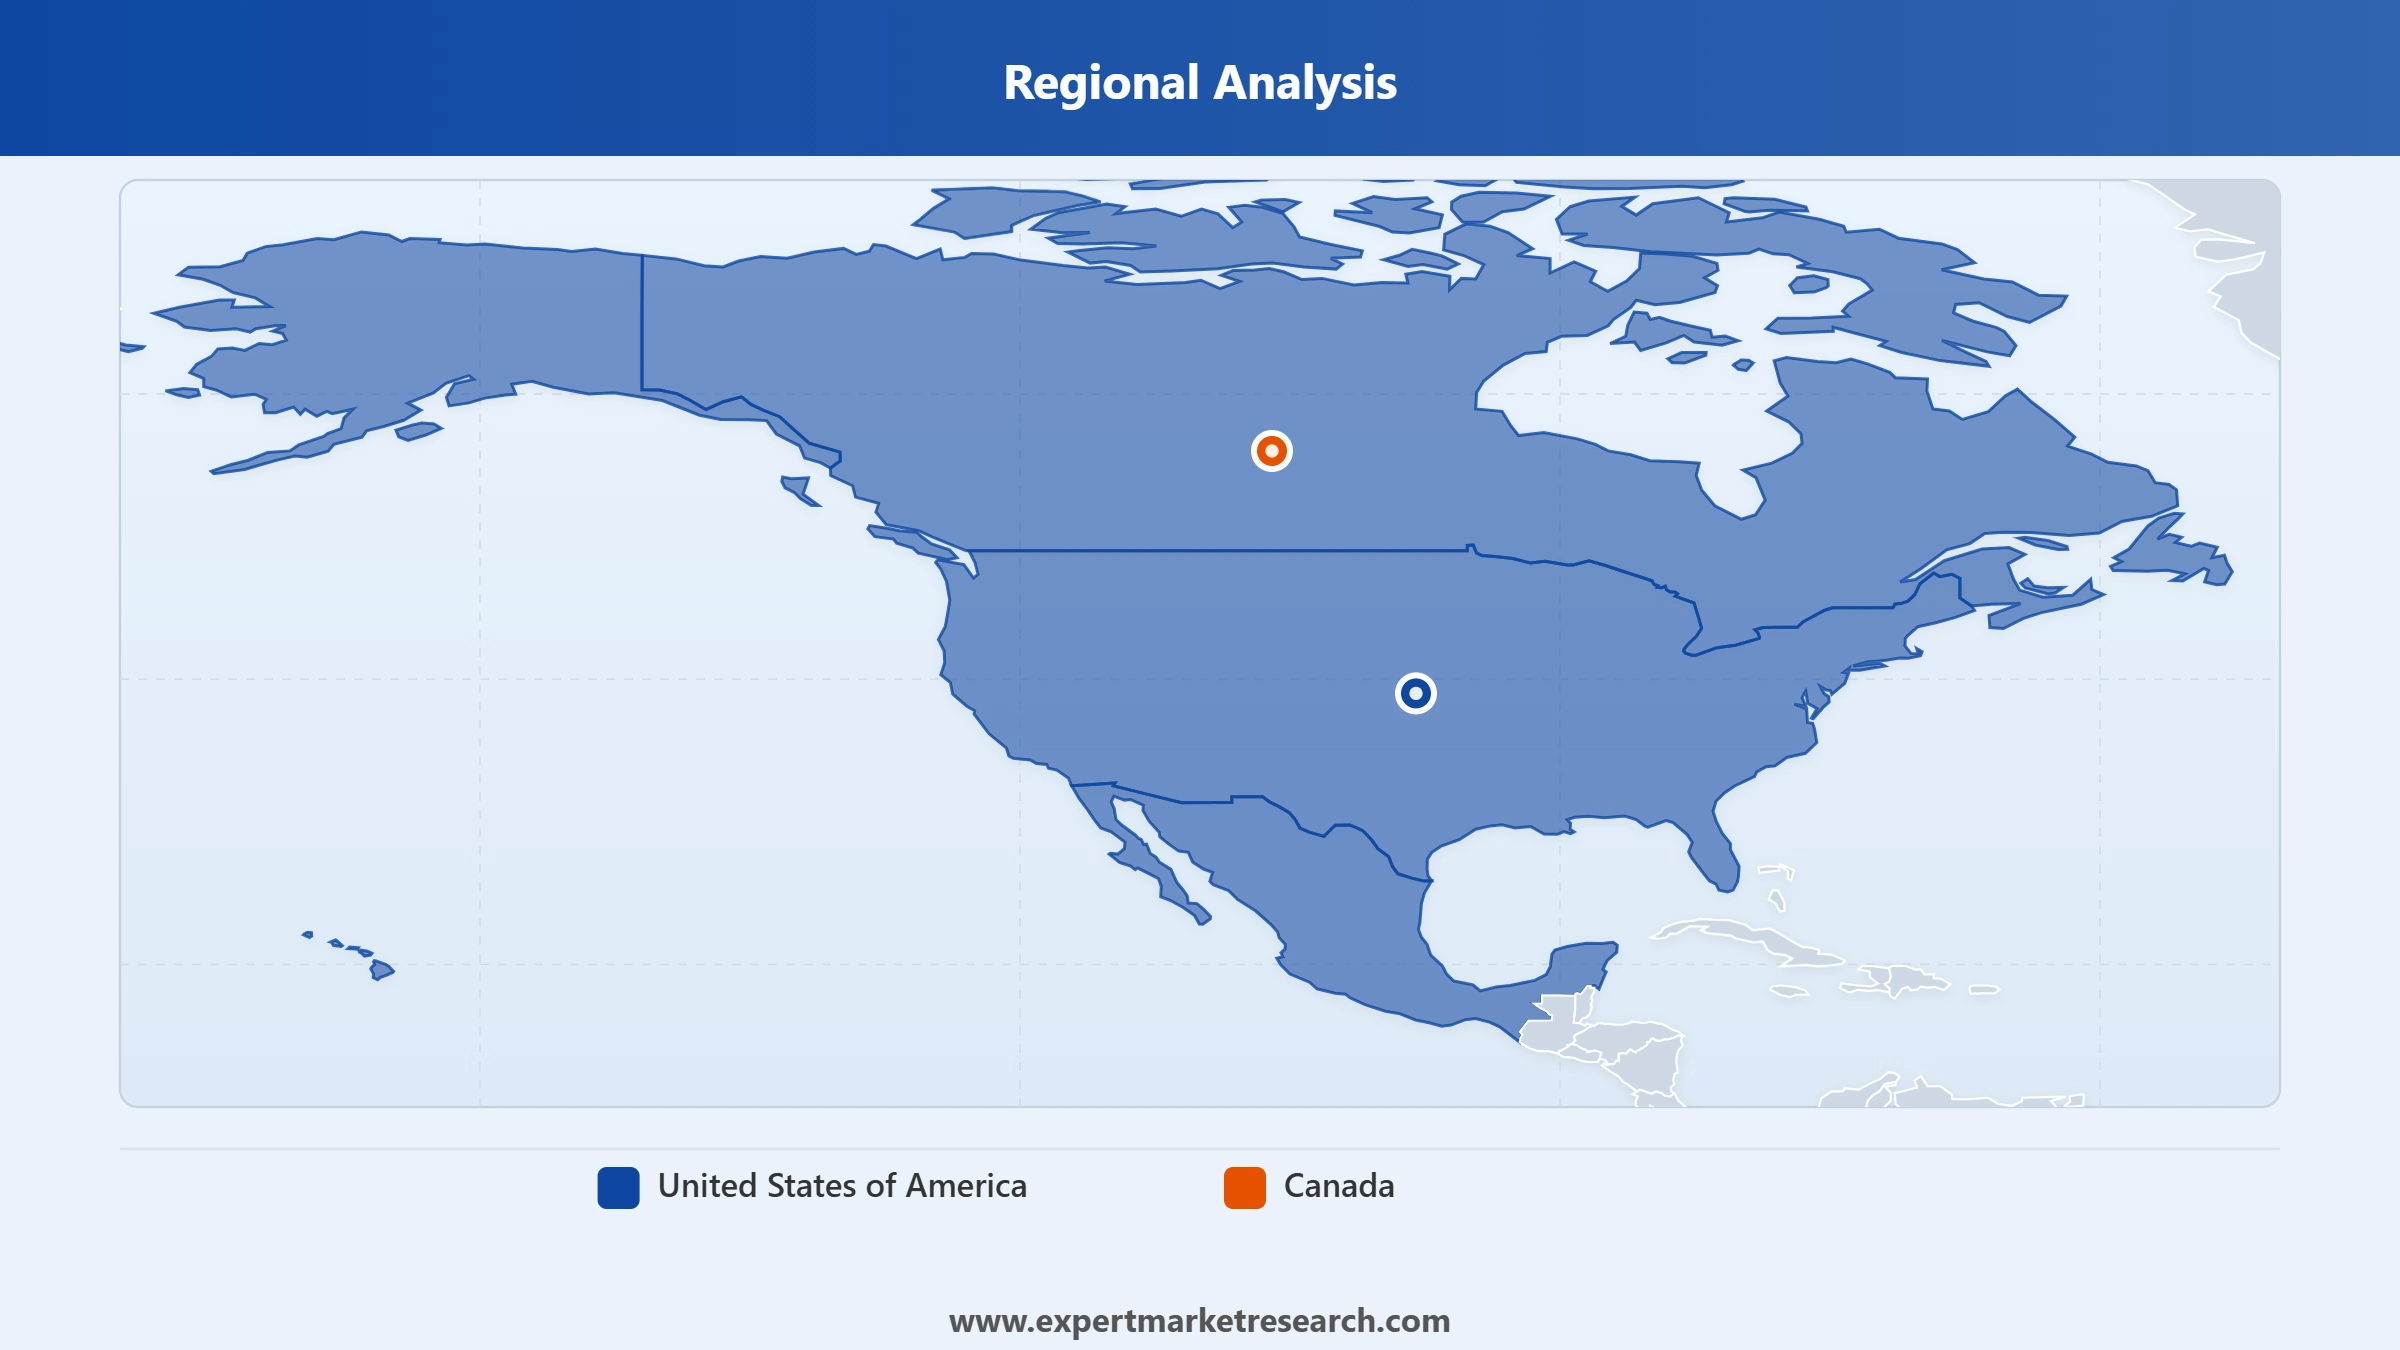
Key Insight: The United States dominates the country breakup given its extensive construction, automotive, and industrial manufacturing base. Canada sustains demand through its architectural coatings market and regional manufacturing presence, supported by established distribution networks across Western Canada and the Pacific Northwest.
Read more about this report - Request a Free Sample
By resin type, acrylics dominate the market owing to their balanced cost, weatherability, and colour retention across architectural and automotive finishes
Acrylic resin systems dominate the resin type segment of the North America paints and coatings market given their balanced cost, weatherability, and colour retention across architectural and automotive finishes, since these properties suit both decorative and functional applications equally well across every climate zone and region, from coastal humidity to inland temperature extremes. In May 2026, Westlake Epoxy achieved ISCC PLUS certification at its Deer Park, Texas site, expanding its EpoVIVE mass balance offering across Europe and the United States.
Read more about this report - Request a Free Sample
Polyurethane grades are registering the fastest resin type growth given rising demand for high abrasion durability in original equipment manufacturer assemblies across every automotive and industrial platform and application type, particularly where surfaces face repeated mechanical stress. In July 2025, MIPA SE transformed its long-standing United States distribution partner Fleetwood Products into a new subsidiary, Mipa USA, strengthening its direct presence across the North American coatings market and supply chain.
By technology, water-borne coatings account for the largest share owing to tightening environmental regulations restricting volatile organic compound emissions
Water-borne technology dominates the technology segment in the North America paints and coatings market given tightening environmental regulations restricting volatile organic compound emissions across architectural and industrial applications, since formulators increasingly need compliant alternatives that still meet performance expectations for durability and finish quality. In September 2025, Elementis introduced DAPRO BIO 9910, a defoamer with 96 percent biobased carbon content formulated specifically for water-based architectural, industrial, and wood coatings.
Read more about this report - Request a Free Sample
Powder coating technology is registering strong technology growth across both architectural and industrial applications given its durability and reduced environmental footprint compared with solvent-borne alternatives, since eliminating solvents entirely reduces both regulatory exposure and application waste. In September 2025, Union Coating and Chemical Industries announced plans to establish its first United States manufacturing facility in Glasgow, Kentucky, initially producing powder coating compounds with an investment of approximately 11.9 million dollars.
By end use, architectural coatings dominate the market owing to sustained residential and commercial construction activity across the region
The architectural end use segment dominates the North America paints and coatings market given sustained residential and commercial construction activity across the region, since ongoing renovation and new build cycles continue to generate steady replacement and specification demand for decorative coatings. In September 2025, Diamond Vogel announced a strategic shift away from company owned architectural paint retail, agreeing to sell its architectural paint business across 11 locations to Spectrum Paint while focusing on core manufacturing capabilities.
Read more about this report - Request a Free Sample
The industrial segment, encompassing protective coatings and transportation applications, is registering the fastest end use growth across the North America paints and coatings market given expanding manufacturing activity and infrastructure investment, particularly across sectors requiring corrosion resistant finishes for long service life equipment. In May 2026, WEG inaugurated a new coatings manufacturing facility and two distribution centres in the United States, strengthening its production of high-performance industrial coatings for HVAC, oil and gas, and water treatment applications.
Read more about this report - Request a Free Sample
The United States leads the market through its extensive construction, automotive, and industrial manufacturing base
The United States dominates the regional breakup of the North America paints and coatings market given its extensive construction, automotive, and industrial manufacturing base, since no other country in the region matches this combined scale of demand and manufacturing capacity across every end use category. In February 2026, Masco reported during its fourth quarter results that its Behr brand was recognised as supplier of the year for the paint department by a major home improvement retailer across the United States and Canada.
Canada sustains demand through its architectural coatings market and regional manufacturing presence, supported by established distribution networks across Western Canada and the Pacific Northwest, where long standing dealer relationships continue to anchor regional sales volume. Regional manufacturers continue to invest in sustainability partnerships and product innovation to serve both retail and industrial customer segments across the country, reflecting steady demand from renovation and new construction projects alike.
The North America paints and coatings market players are becoming increasingly consolidated as major paints and coatings companies pursue mergers and acquisitions to broaden combined technology platforms and geographic reach. Paints and coatings players are prioritising sustainable formulation technology, OEM approved supplier status, and expanded specialty product portfolios to differentiate themselves in an increasingly competitive landscape shaped by tightening environmental regulations across the region.
Major North America paints and coatings companies are also focusing on carbon capture feedstock technology and building envelope product diversification, pursuing partnerships that extend traditional coatings portfolios into adjacent categories. Opportunities are emerging in automotive refinish network agreements and industrial protective coatings investment. Companies that successfully combine sustainable technology with broad distribution reach are expected to strengthen their competitive position over the coming years.
Founded in 1865 and headquartered in Ludwigshafen, Germany, BASF SE supports the paints and coatings market through its automotive and industrial coatings technology portfolio, serving customers across major North American manufacturing hubs. The company continues to expand its waterborne coating capacity to support sustainability focused formulations. BASF draws on its position as one of the world's largest chemical companies to serve a broad customer base across coatings applications.
Founded in 1883 and headquartered in Pittsburgh, Pennsylvania, United States, PPG Industries, Inc. contributes to the paints and coatings market through its architectural, automotive, and industrial coatings product lines. The company continues to expand its sustainable packaging coatings and automotive refinish offerings. PPG draws on its position as one of the world's leading coatings companies to serve customers across every major end use category.
Founded in 1866 and headquartered in Cleveland, Ohio, United States, Sherwin-Williams Co. supports the paints and coatings market through its extensive architectural, industrial, and packaging coatings portfolio sold through company operated stores and distribution channels. The company continues to expand its non-BPA packaging coatings technology. Sherwin-Williams draws on its position as a leading global paint manufacturer to serve professional, industrial, and retail customers.
Founded in 1881 and headquartered in Osaka, Japan, Nippon Paint Holdings Co. Ltd. contributes to the market through its Dunn-Edwards Corporation subsidiary, serving architectural coatings customers across the region. The company continues to expand its decorative and industrial coatings offerings across international markets. Nippon Paint draws on its position as one of the world's largest paint manufacturers to serve customers across multiple regional markets.
Other key players in the market include Benjamin Moore & Co., RPM International Inc., 3M Co., Akzo Nobel N.V., Masco Corporation, and Cloverdale Paint Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our paints and coatings market trends 2026 report. Discover country level growth patterns, resin type economics, and key industry players. Stay ahead of the competition and identify emerging opportunities in the evolving North America paints and coatings market landscape.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 43.96 Billion.
The market is projected to grow at a CAGR of 3.60% between 2026 and 2035.
The North America paints and coatings market is expected to reach USD 62.61 Billion in 2035.
Pursuing large scale mergers and acquisitions, adopting carbon capture feedstock technology, securing OEM approved refinish supplier status, expanding building envelope product categories, and strengthening domestic production capacity are key strategies driving the market.
Based on the type of resin, the market includes epoxy, acrylics, alkyd, polyurethane, polyester, and various other types.
The key players in the market include BASF SE, PPG Industries, Inc., Sherwin-Williams Co., Nippon Paint Holdings Co. Ltd. (Dunn-Edwards Corporation), Benjamin Moore & Co., RPM International Inc., 3M Co., Akzo Nobel N.V., Masco Corporation, and Cloverdale Paint Inc., among others.
Based on technology, the paints and coatings market is divided into water-borne, solvent-borne, powder coating, and UV-cured coating.
The major regions include the United States of America and Canada.
Based on the end use, the paints and coatings market is divided into automotive, protective coatings, transportation, architectural, packaging and others.
Companies face competition from diversified chemical manufacturers, volatile raw material costs, tightening environmental regulations, and the capital intensity of transitioning toward sustainable formulation technology.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Resin Type |
|
| Breakup by Technology |
|
| Breakup by End Use |
|
| Breakup by Country |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




