

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
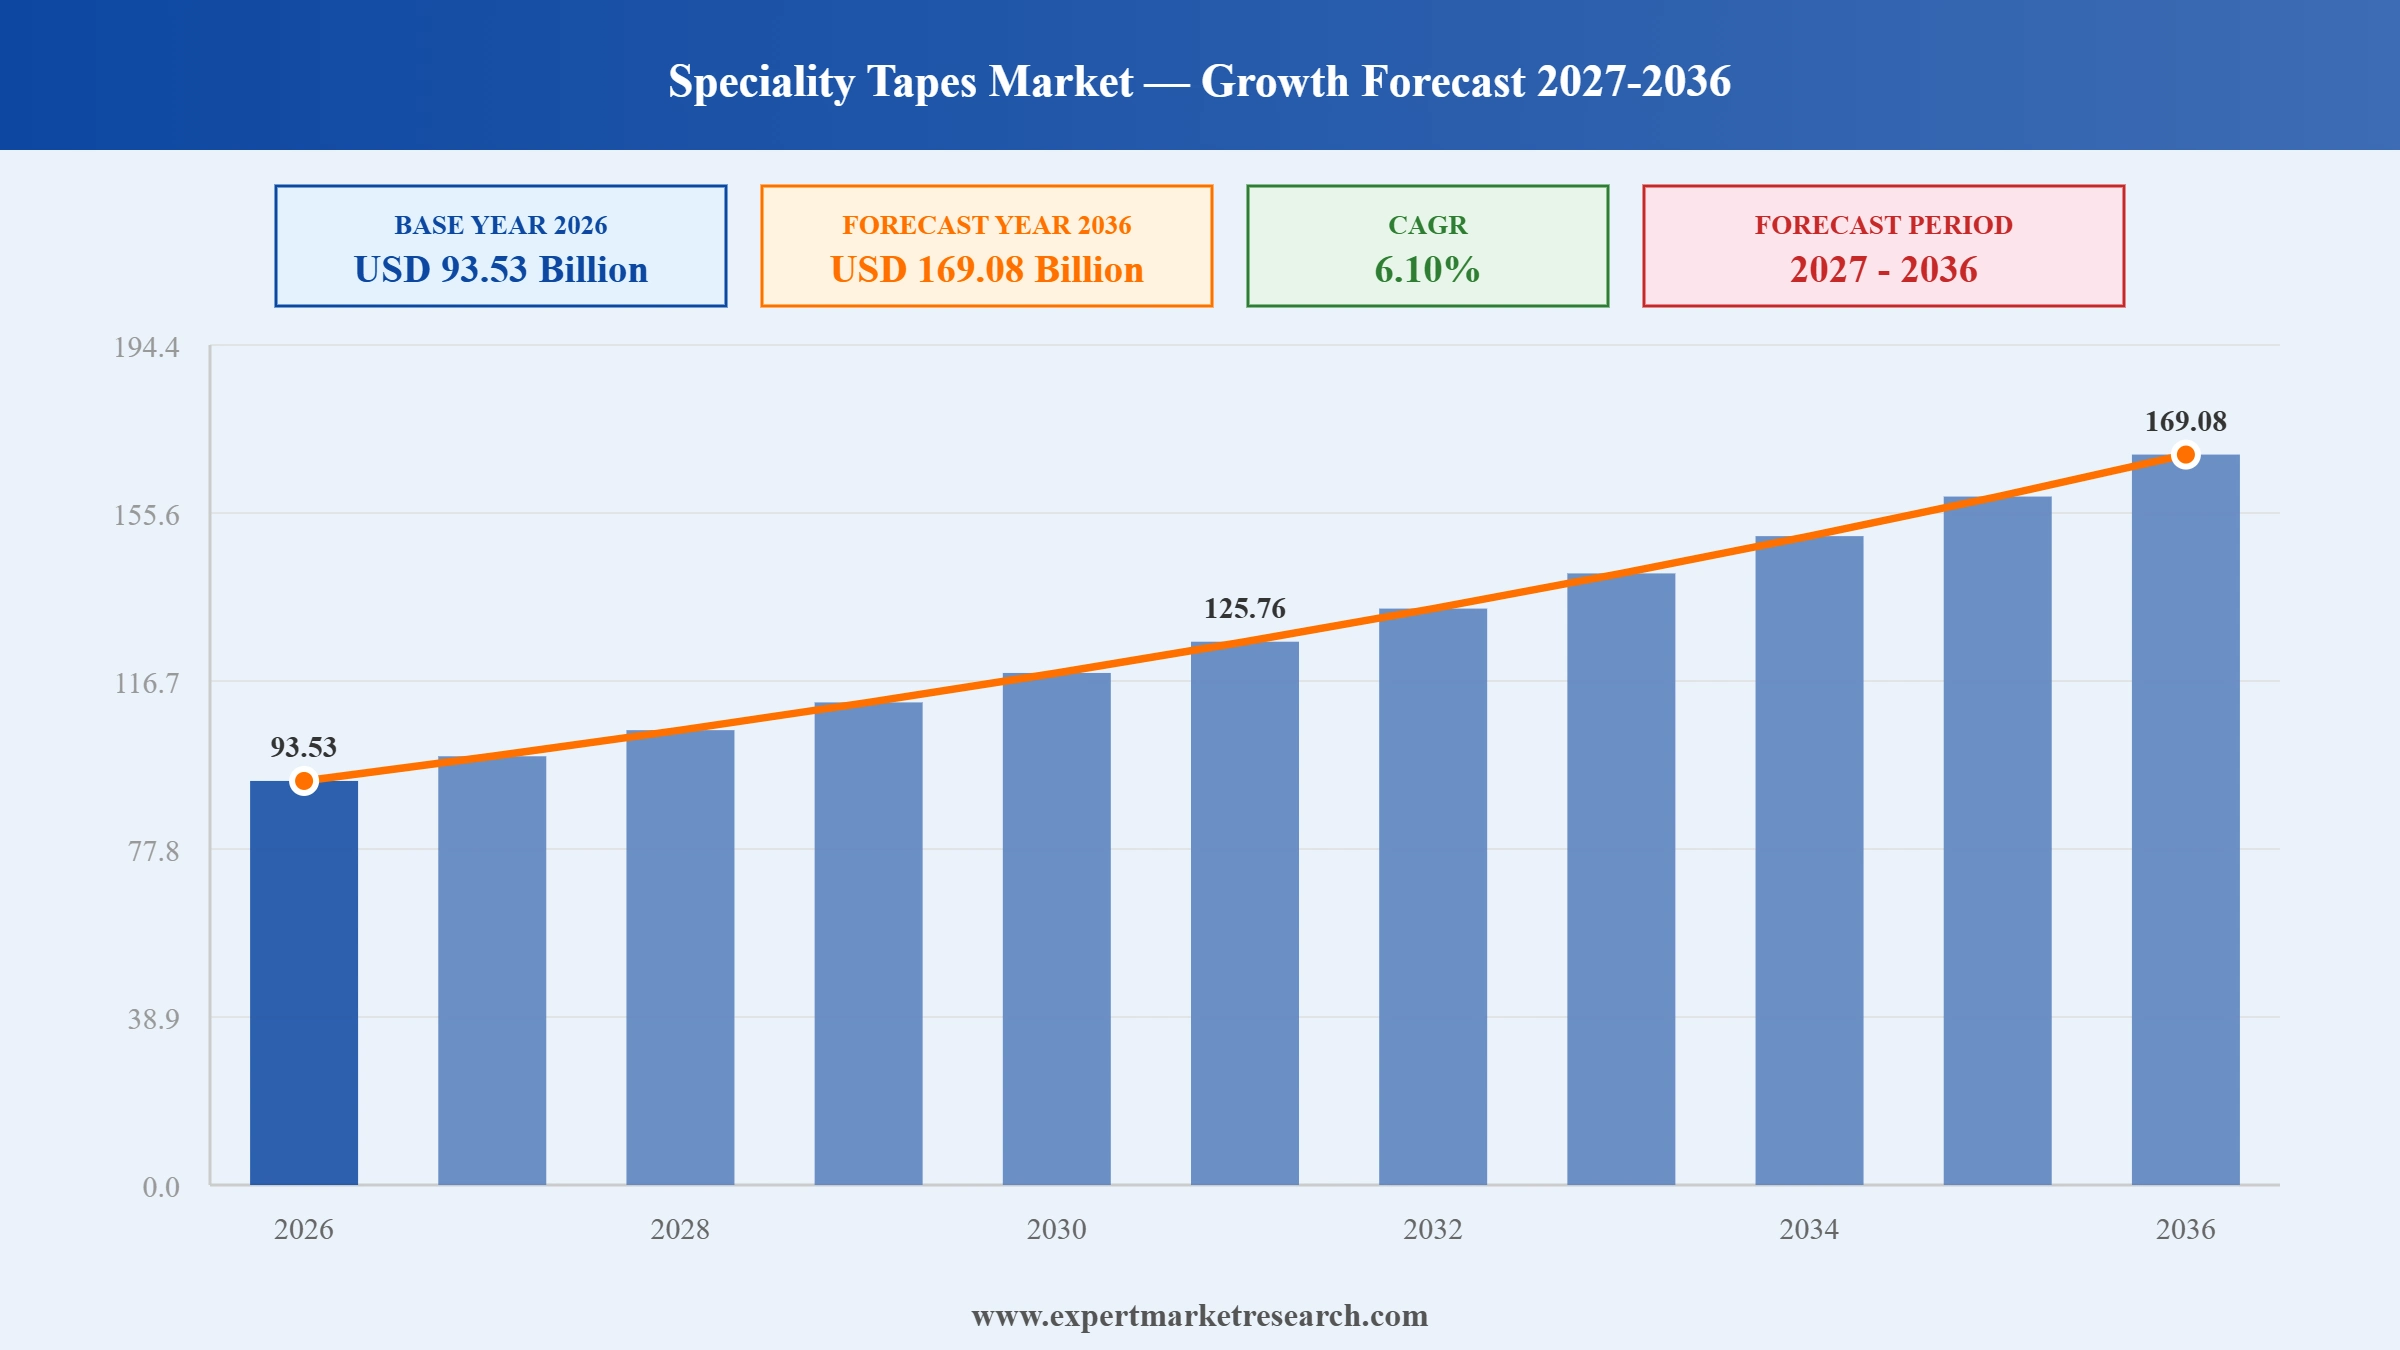
The global speciality tapes market attained a value of USD 88.15 Billion in 2025 and is projected to expand at a CAGR of 6.10% through 2035. The market is further expected to reach USD 159.36 Billion by 2035. Rising demand for acrylic and silicone adhesive tapes across electronics, healthcare, and automotive applications, together with capacity additions among backing material producers, is helping manufacturers broaden their product portfolios. Growing emphasis on high temperature resistance, skin friendly adhesion, and recyclable backing materials is further encouraging established players to expand capacity across Asia Pacific, Europe, and North America.
The products in the speciality tapes market extend beyond general purpose masking and packaging tape into application specific bonding, insulation, sealing, and protective solutions built around acrylic, rubber, and silicone adhesive chemistries matched to backing materials including polyvinyl chloride, woven and non-woven fabric, paper, polyester film, foam, and polypropylene. Electrical and electronics manufacturers rely on these tapes for wire harnessing, static shielding, and component assembly, while automotive producers use foam and structural bonding tapes to join body panels and trim without added fasteners. Healthcare and hygiene converters are expanding use of hypoallergenic and breathable formats for diagnostics, wound care, and wearable monitoring devices, broadening demand across mature and developing economies alike.
Demand is concentrating around manufacturers capable of supplying thin, high temperature, and low outgassing tape formats for battery modules, printed circuit boards, and display assemblies as electric vehicle output and consumer electronics volumes continue climbing across Asia Pacific. In September 2025, Polyplex Corporation Limited commissioned a new biaxially oriented polyester film line in Turkey aimed partly at speciality tape and label backing applications, adding capacity for thinner, higher clarity films used in electronics bonding tapes. Converters are responding to this film availability by qualifying thinner constructions that reduce device thickness while maintaining peel strength and dielectric performance in next generation electronic and automotive assemblies.
Manufacturers are directing investment toward widening adhesive chemistry portfolios, qualifying solvent free and water-based coating lines, and building regional converting capacity closer to electronics, automotive, and healthcare customers to shorten lead times. Portfolios are also broadening into pressure sensitive films for retail graphics and signage, reflecting diversification beyond traditional industrial bonding use cases for speciality tapes. Investment in automated slitting, die cutting, and quality inspection equipment is helping producers meet tighter tolerance and cleanliness requirements demanded by electronics and healthcare customers across the market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Henkel AG and Co. KGaA expanded engineering adhesives and tapes production lines at its Shanghai facility, adding capacity for high-performance bonding tapes used in electronics and automotive assembly across China. The expansion adds coating and slitting equipment for thinner, precision tape constructions in battery and display applications, helping converters across the speciality tapes market shorten delivery times for electronics customers across Asia Pacific.
Lohmann GmbH and Co. KG launched a silicone adhesive tape range for high temperature bonding inside electric vehicle battery packs, where cells and busbars must withstand sustained thermal cycling. The range replaces mechanical fasteners in cell stacking and module sealing applications, reducing assembly weight. Such launches across the speciality tapes market help battery makers secure reliable thermal and electrical insulation while trimming assembly time.
Intertape Polymer Group Inc. completed the acquisition of a speciality tape converting facility in Mexico, strengthening its footprint serving automotive and packaging customers across North America under nearshoring strategies. The facility adds slitting and custom die cutting capacity near assembly plants in the region. Such acquisitions let converters across the speciality tapes market respond faster to specification changes and cut cross border freight costs.
ORAFOL Europe GmbH opened a new precision die cutting line dedicated to optical grade speciality tapes used in display bonding and touch panel assembly. The line supports tighter dimensional tolerances needed for thinner smartphone and wearable device stacks. Such investment in precision converting equipment helps suppliers meet rising quality demands from consumer electronics assemblers while speeding new product qualification.
Automakers across the speciality tapes market are specifying thermal management and gap filling tapes to manage heat inside battery packs and power electronics as vehicle platforms add higher capacity cells. Suppliers are reformulating acrylic and silicone adhesive systems to combine thermal conductivity with electrical insulation in thin, die cuttable formats. In February 2026, Shurtape Technologies LLC introduced a double coated thermal transfer tape line for battery module assembly, giving pack designers a drop-in option for securing cells while managing heat dissipation across EV platforms.
Speciality tape producers across the speciality tapes market are under pressure from brand owners and regulators to cut volatile organic compound emissions and improve end of life recyclability of adhesive backed products. Converters are shifting coating lines toward water based and hot melt chemistries that avoid solvent carriers while matching peel and shear performance targets. In December 2025, Berry Global Inc. announced an expansion of its solvent free adhesive coating capacity, aimed at packaging and industrial bonding tape customers seeking lower emission product lines.
Hospitals, diagnostics firms, and wearable device makers are driving demand for hypoallergenic, breathable adhesive tapes that bond securely to skin without causing irritation during extended wear. Converters are adding cleanroom coating lines and qualifying medical grade release liners to meet biocompatibility and sterilization requirements. In October 2025, Mativ Holdings Inc. expanded medical tape converting capacity at its Mactac business, adding slitting lines dedicated to wound care and wearable sensor adhesive products across North America.
Speciality tape converters across the speciality tapes market are acquiring narrow web processing specialists to add contract converting and packaging capabilities without building new finishing lines. Such combinations let tape makers offer sheeting, perforating, slitting, and interleaving services alongside their core adhesive products. In September 2025, Elite Tape acquired Corydon Converting and rebranded it as Elite Converting, gaining converting capacity to better serve aerospace, automotive, electronics, and industrial customers. The acquisition broadens how speciality tape suppliers’ package and delivers finished products.
Vehicle makers across the speciality tapes market pursuing weight reduction targets are replacing welds, rivets, and mechanical fasteners with structural foam and acrylic bonding tapes across body panels, trim, and badge attachment points. These tapes distribute stress more evenly than point fasteners and allow use of mixed material substrates including aluminum and composite panels. In July 2025, CCT Tapes Inc. expanded its automotive bonding tape line with a new foam core acrylic tape rated for exterior trim attachment, supporting automakers' efforts to cut vehicle weight.
The Expert Market Research's report titled "Global Speciality Tapes Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Resin Type
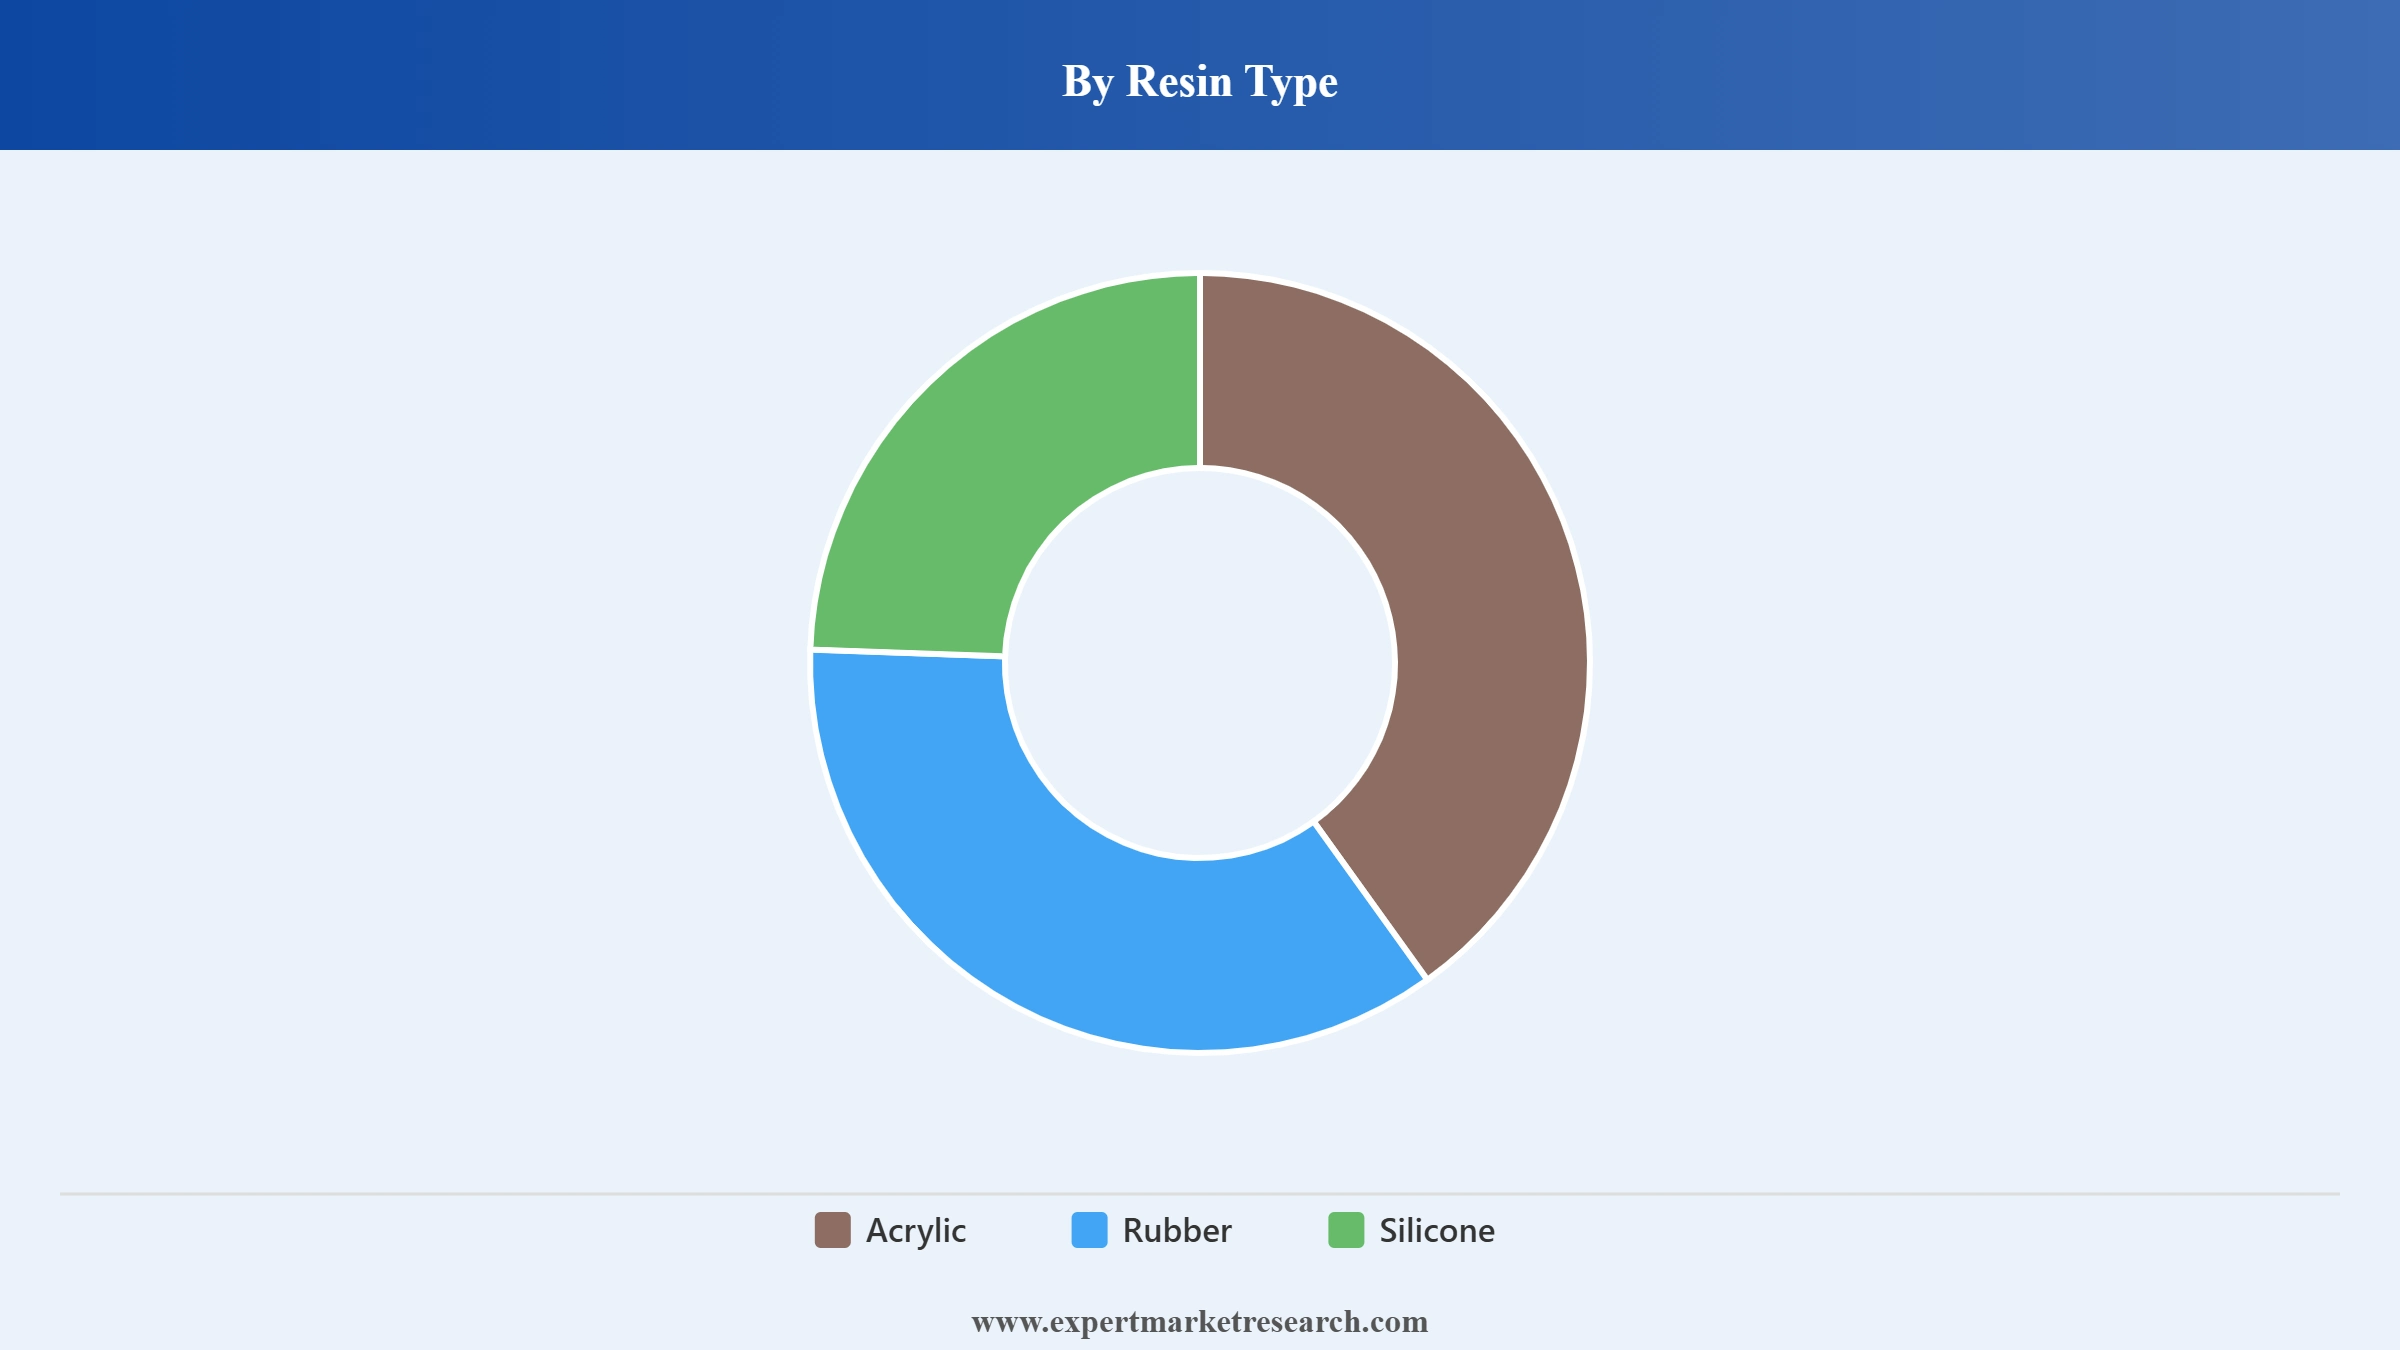
Key Insight: Acrylic resin dominates the speciality tapes market due to its balanced adhesion, ultraviolet resistance, and cost efficiency across electronics, automotive, and construction bonding applications. Rubber based tapes remain widely used for quick tack, general purpose bonding and packaging tasks where moderate temperature performance is sufficient. Silicone tapes are gaining share in high temperature and electronics applications requiring stable adhesion across wide temperature ranges; in June 2025, Achilles Corporation expanded production of silicone coated industrial tapes at its Japan facility to support growing electronics and automotive demand. The Others category, covering polyurethane and modified hot melt systems, serves niche bonding needs where specialized chemical resistance or removability is required.
Market Breakup by Backing Material
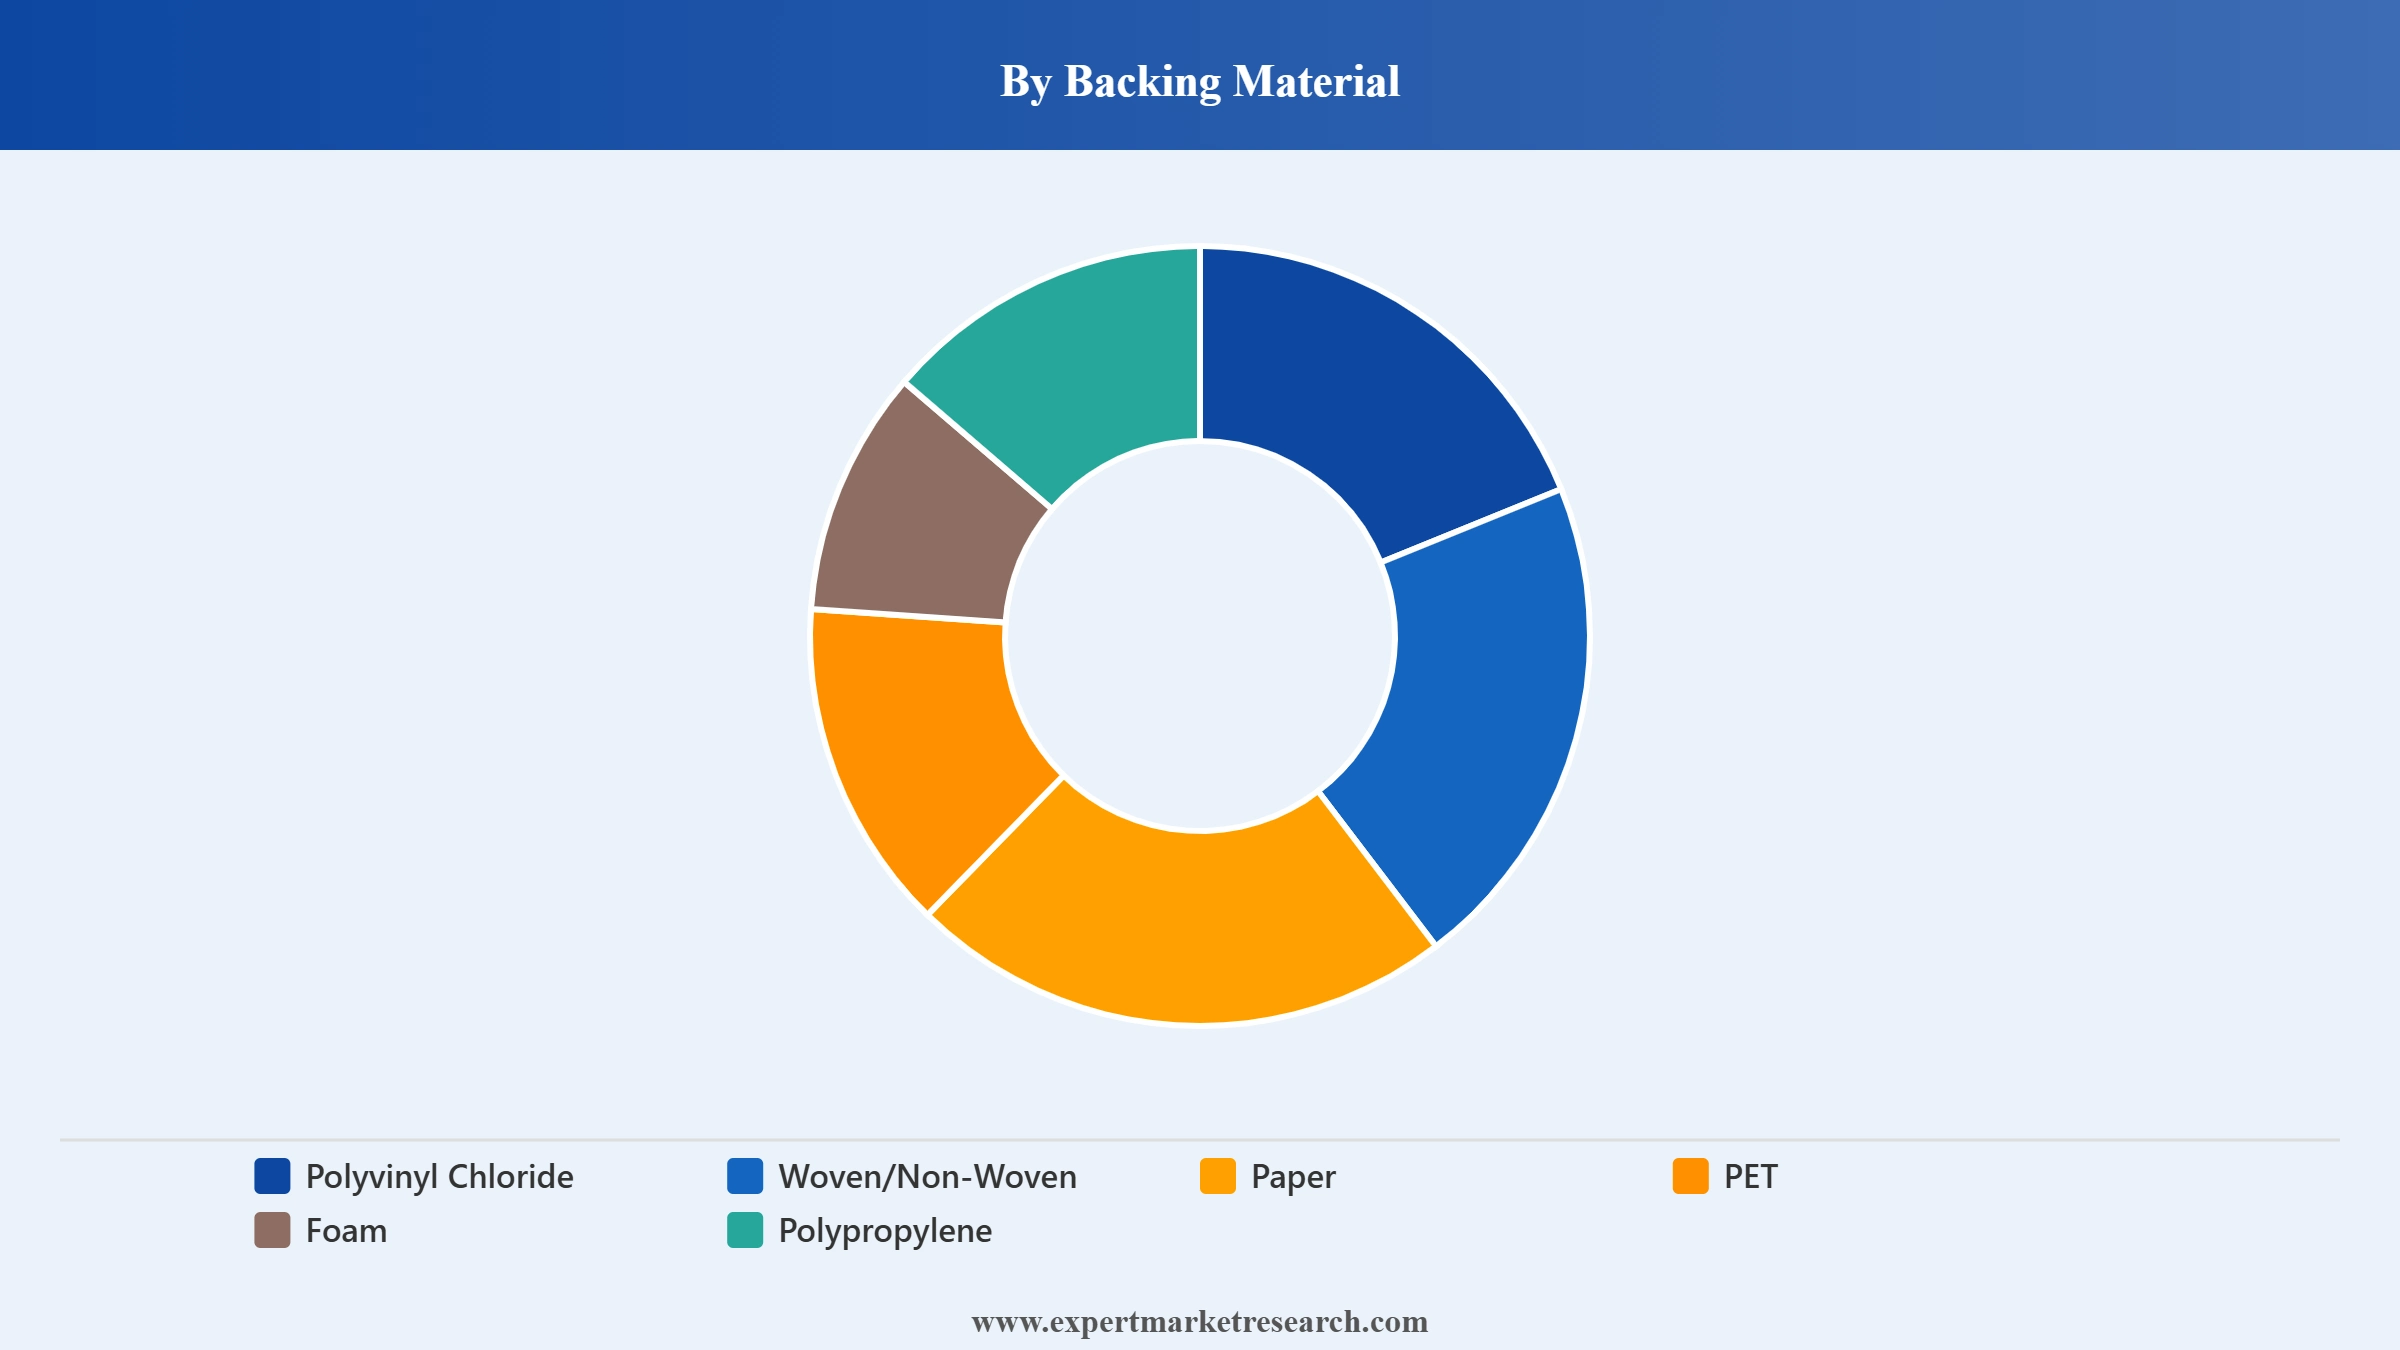
Key Insight: Polyvinyl chloride backing leads the speciality tapes market owing to its flexibility, conformability, and electrical insulation properties favored in wire harnessing and masking applications. Woven and non-woven backings provide tear resistance and hand tearability prized in packaging and surgical tape uses, while paper backing remains popular for low-cost masking and labeling tasks. Polyester film, PET, backing is expanding fastest given its thin profile and dimensional stability for electronics bonding. Foam backing supports cushioning and gap filling in automotive and construction uses, polypropylene backing serves packaging and strapping tasks, and the others category, including fabric blends and composite films, addresses specialized bonding requirements.
Market Breakup by End Use
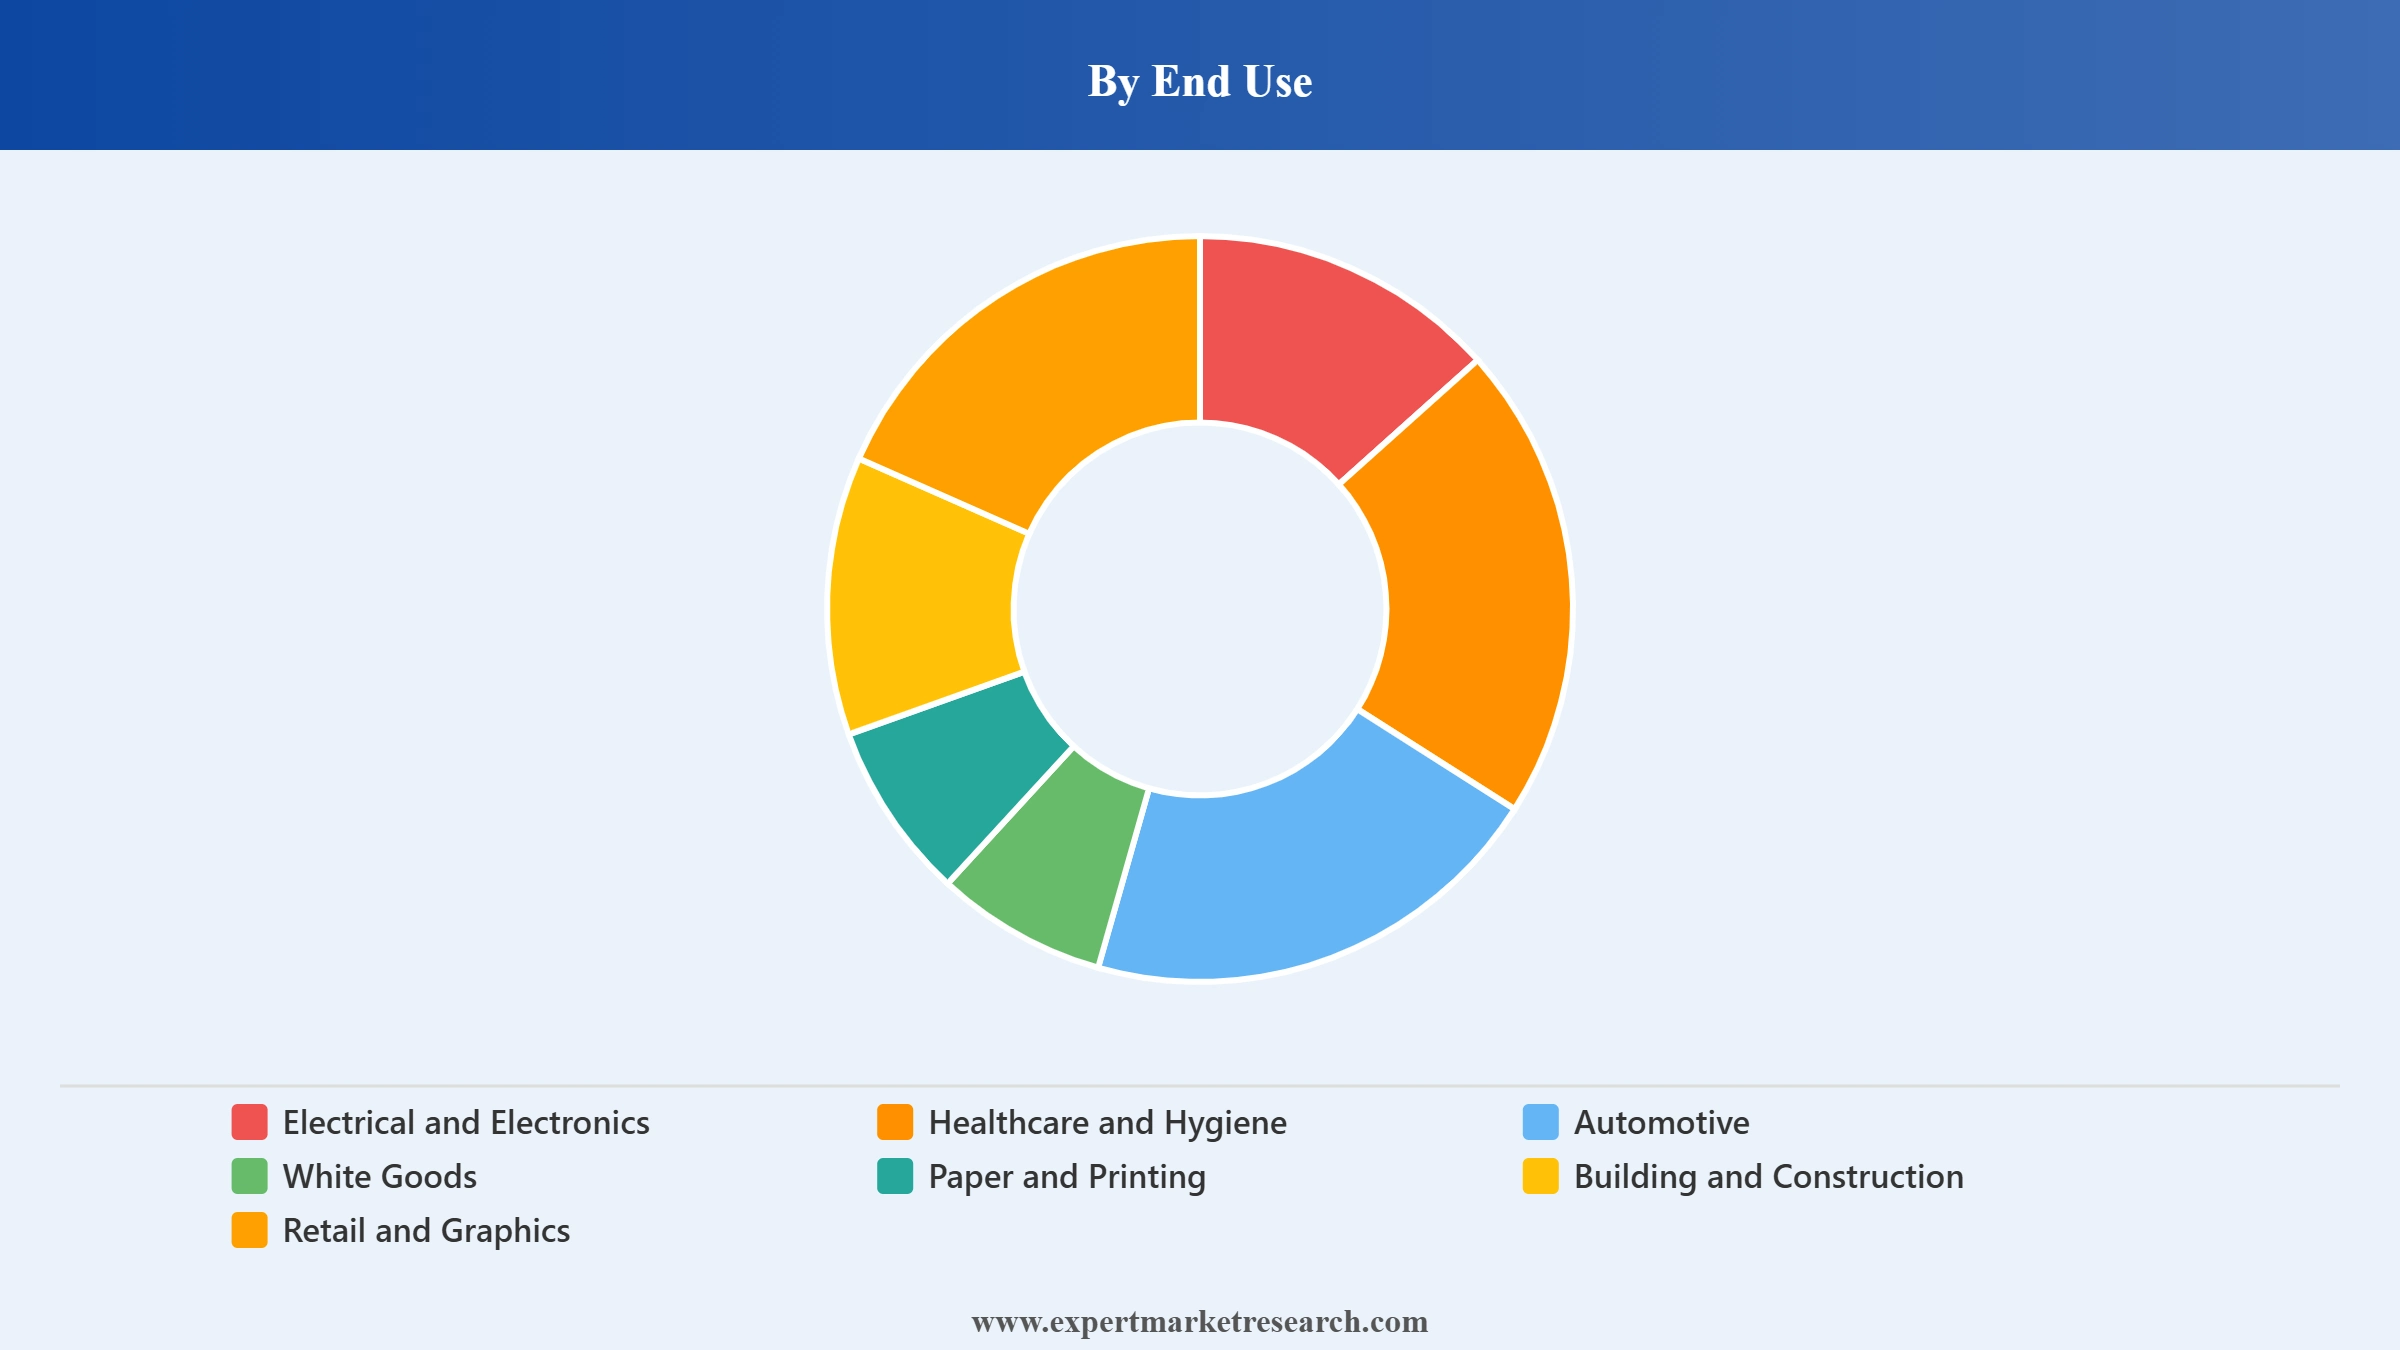
Key Insight: Electrical and electronics applications dominate the speciality tapes market as wire harnessing, static shielding, and component assembly consume high volumes of thin, precision die cut tapes. Healthcare and hygiene uses continue expanding through wound care, diagnostics, and wearable device bonding, and automotive demand centers on structural and foam bonding tapes that support vehicle lightweighting. White goods manufacturers use these tapes for insulation and panel assembly, while paper and printing applications rely on tapes for splicing and finishing tasks. Building and construction firms apply weatherproofing and sealing tapes across insulation and glazing projects. Retail and graphics uses are growing on demand for durable outdoor signage films, and the others category covers packaging and specialty industrial bonding needs.
Market Breakup by Region
Key Insight: Regional dynamics in the speciality tapes market continue to shape competitive strategies. Asia Pacific leads the market on the back of large-scale electronics and automotive manufacturing hubs across China, Japan, and South Korea, alongside expanding converting capacity in India and Southeast Asia. North America and Europe sustain steady demand from automotive, healthcare, and construction applications, supported by established converting infrastructure and strong regulatory compliance standards. Latin America remains a smaller but steadily growing market supported by expanding packaging and construction activity, while the Middle East and Africa region is registering the fastest growth as infrastructure investment and growing electronics assembly activity lift demand for speciality tapes across the region.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By resin type, acrylic adhesive systems dominate the market owing to their balanced adhesion, weathering resistance, and cost efficiency across end use applications
Acrylic adhesive systems account for the largest share of the speciality tapes market as converters favor their broad temperature tolerance, ultraviolet stability, and compatibility with multiple backing materials across automotive, electronics, and construction uses. This versatility allows acrylic tape producers to serve diverse customer specifications without maintaining separate dedicated production lines for each end use segment.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Silicone adhesive systems are registering the fastest growth in the speciality tapes market as electric vehicle battery assembly and dense electronics packaging demand adhesives that retain bond strength across extreme temperature cycling. In November 2025, Wevo introduced Wevosil 28015 FL, a two-component addition curing silicone adhesive combining high thermal conductivity with structural strength for electric vehicle battery modules and power electronics. Converters are qualifying such silicone formulations for module sealing and protection where acrylic and rubber systems fall short.
By backing material, polyvinyl chloride backing dominates the market owing to its flexibility, conformability, and reliable electrical insulation in wire harnessing and masking applications
Polyvinyl chloride backed tapes hold the largest share of the speciality tapes market given their flexibility, tear resistance, and consistent electrical insulation performance favored for wire harnessing, cable wrapping, and general-purpose masking tasks across electronics and automotive assembly lines. This backing material's low cost and easy hand tearability continue to support its broad adoption across mature industrial applications.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Polyester film, PET, backing is the fastest-growing backing material in the speciality tapes market as assemblers specify thinner constructions that maintain dimensional stability under heat and handling stress. In April 2026, Mitsubishi Polyester Film opened a Hostaphan production line at its Wiesbaden Industrial Park site in Germany, representing an investment of more than EUR 100 million and adding 27,000 tons of annual capacity serving automotive, electric vehicle battery, and medical film applications. The backing suits display bonding and masking tasks.
By end use, electrical and electronics applications dominate the market owing to high volume consumption of precision die cut tapes in wire harnessing and component assembly
Electrical and electronics applications account for the largest end use share of the speciality tapes market as consumer electronics, telecommunications equipment, and electric vehicle component assembly all rely heavily on precision die cut bonding, masking, and shielding tapes. Continued growth in device miniaturization and electric vehicle component counts is expected to sustain this segment's lead through the forecast period.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Healthcare and hygiene applications are the fastest-growing end use segment in the speciality tapes market as hospitals and wearable device makers specify hypoallergenic, breathable adhesive tapes for wound care and diagnostics. In October 2025, Tapecon partnered with the University at Buffalo to develop a stick-to-skin, wearable multichannel electromyography sensor built on Tapecon's medical grade adhesive technology for muscle performance assessment. Rising chronic disease monitoring and home healthcare adoption widen demand for biocompatible, long wear adhesive tape formats.
Asia Pacific leads the market through large scale electronics and automotive manufacturing hubs and expanding converting capacity
Asia Pacific commands the largest share of the speciality tapes market, underpinned by extensive electronics assembly, automotive production, and converting infrastructure across China, Japan, South Korea, and increasingly India and Vietnam. Rising consumer electronics output and electric vehicle component manufacturing continue to lift demand for precision die cut and high temperature tapes across the region. Continued investment in regional converting capacity is expected to reinforce Asia Pacific's lead through the forecast period.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The Middle East and Africa region is registering the fastest growth in the speciality tapes market as infrastructure investment, growing electronics assembly activity, and expanding automotive aftermarket demand lift consumption of bonding and insulation tapes. In January 2025, tesa marked 30 years of operations in Turkey, having grown its Istanbul office from seven to more than 40 employees and established it as a regional hub serving the Middle East, Turkey, and Africa with flexo, automotive, and appliance tape lines.
The global industry is becoming increasingly consolidated as leading speciality tapes companies invest in expanded converting capacity, broadened adhesive chemistry portfolios, and regional manufacturing footprints to serve electronics, automotive, and healthcare customers more efficiently. Producers are prioritizing precision coating, slitting, and die cutting capabilities to meet tightening tolerance and cleanliness requirements demanded by electronics and medical device assemblers. Strategic emphasis on nearshoring converting capacity is allowing speciality tapes companies to shorten delivery times and respond faster to customer specification changes across automotive and construction end uses.
Major speciality tapes market players are also focusing on sustainability credentials, pursuing solvent free coating technologies, recyclable backing materials, and lower emission manufacturing processes to align with tightening environmental regulation in Europe and North America. Opportunities are emerging in high temperature electronics bonding, electric vehicle battery assembly, and wearable healthcare device applications. Speciality tapes players that successfully combine broad chemistry portfolios with reliable regional supply and cleaner production processes are expected to strengthen their competitive position over the coming years.
Founded in 1902 and headquartered in Saint Paul, Minnesota, United States, 3M Company supports the market through its broad industrial adhesives and tapes portfolio spanning acrylic, foam, and structural bonding systems used across electronics, automotive, and construction applications. The company maintains extensive converting and coating infrastructure across North America, Europe, and Asia Pacific, supplying both original equipment manufacturers and industrial distributors.
Founded in 1918 and headquartered in Osaka, Japan, Nitto Denko Corporation is a long-established adhesive materials manufacturer whose speciality tape offerings span electronics process tapes, automotive masking films, and medical grade adhesive products. The company operates an extensive global network of coating and film production facilities supporting electronics and automotive customers across Asia Pacific, North America, and Europe.
Founded in 1936 and headquartered in Norderstedt, Germany, Tesa SE specializes in self-adhesive tape systems for automotive assembly, electronics bonding, and industrial applications, operating dedicated innovation and application development centers that work directly with customer engineering teams. The company maintains coating and converting facilities across Europe, Asia, and the Americas to support regional customer demand.
Founded in 1935 and headquartered in Mentor, Ohio, United States, Avery Dennison Corporation supplies pressure sensitive adhesive materials and speciality tape products through its Industrial and Healthcare Materials businesses, serving electronics, medical device, and graphics customers worldwide. The company continues to expand its specialty coating and converting capabilities to support growing demand for thinner, higher performance adhesive constructions.
Other key players in the global market include LINTEC Corporation, Scapa Group plc, and Compagnie de Saint-Gobain SA, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global speciality tapes market trends 2026 report. Discover regional growth patterns, adhesive chemistry economics, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 88.15 Billion.
The market is projected to grow at a CAGR of 6.10% between 2026 and 2035.
The major drivers of the market include the increasing number of companies in the automotive, building industry, technological advancements, growing chronic diseases, and ongoing product development.
The high demand for these tapes in the healthcare and hygiene, electrical and electronics, automotive, and construction industries and the strong demand from rubber industry are acting as important industry trends.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The major resin types in the market are acrylic, rubber, and silicone, among others.
The various backing materials in the market are polyvinyl chloride (PVC), woven/non-woven, paper, PET, foam, and polypropylene (PP), among others.
The end-use sectors include are electrical and electronics, healthcare and hygiene, automotive, white goods, paper and printing, building and construction, retail and graphics, among others.
The key players in the market include 3M Company, Nitto Denko Corporation, Tesa SE, Avery Dennison Corporation, LINTEC Corporation, Scapa Group plc, and Compagnie de Saint-Gobain SA, among others.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach about USD 159.36 Billion by 2035.
Companies face volatile raw material and resin costs, tightening environmental regulation on solvent emissions, competition from alternative bonding methods, and the capital intensity of expanding precision coating and converting capacity.
Expanding solvent free and high temperature adhesive formulations, broadening converting capacity near electronics and automotive hubs, investing in healthcare grade product lines, diversifying into the Middle East and Africa, and strengthening regional distribution networks.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Resin Type |
|
| Breakup by Backing Material |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




