

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
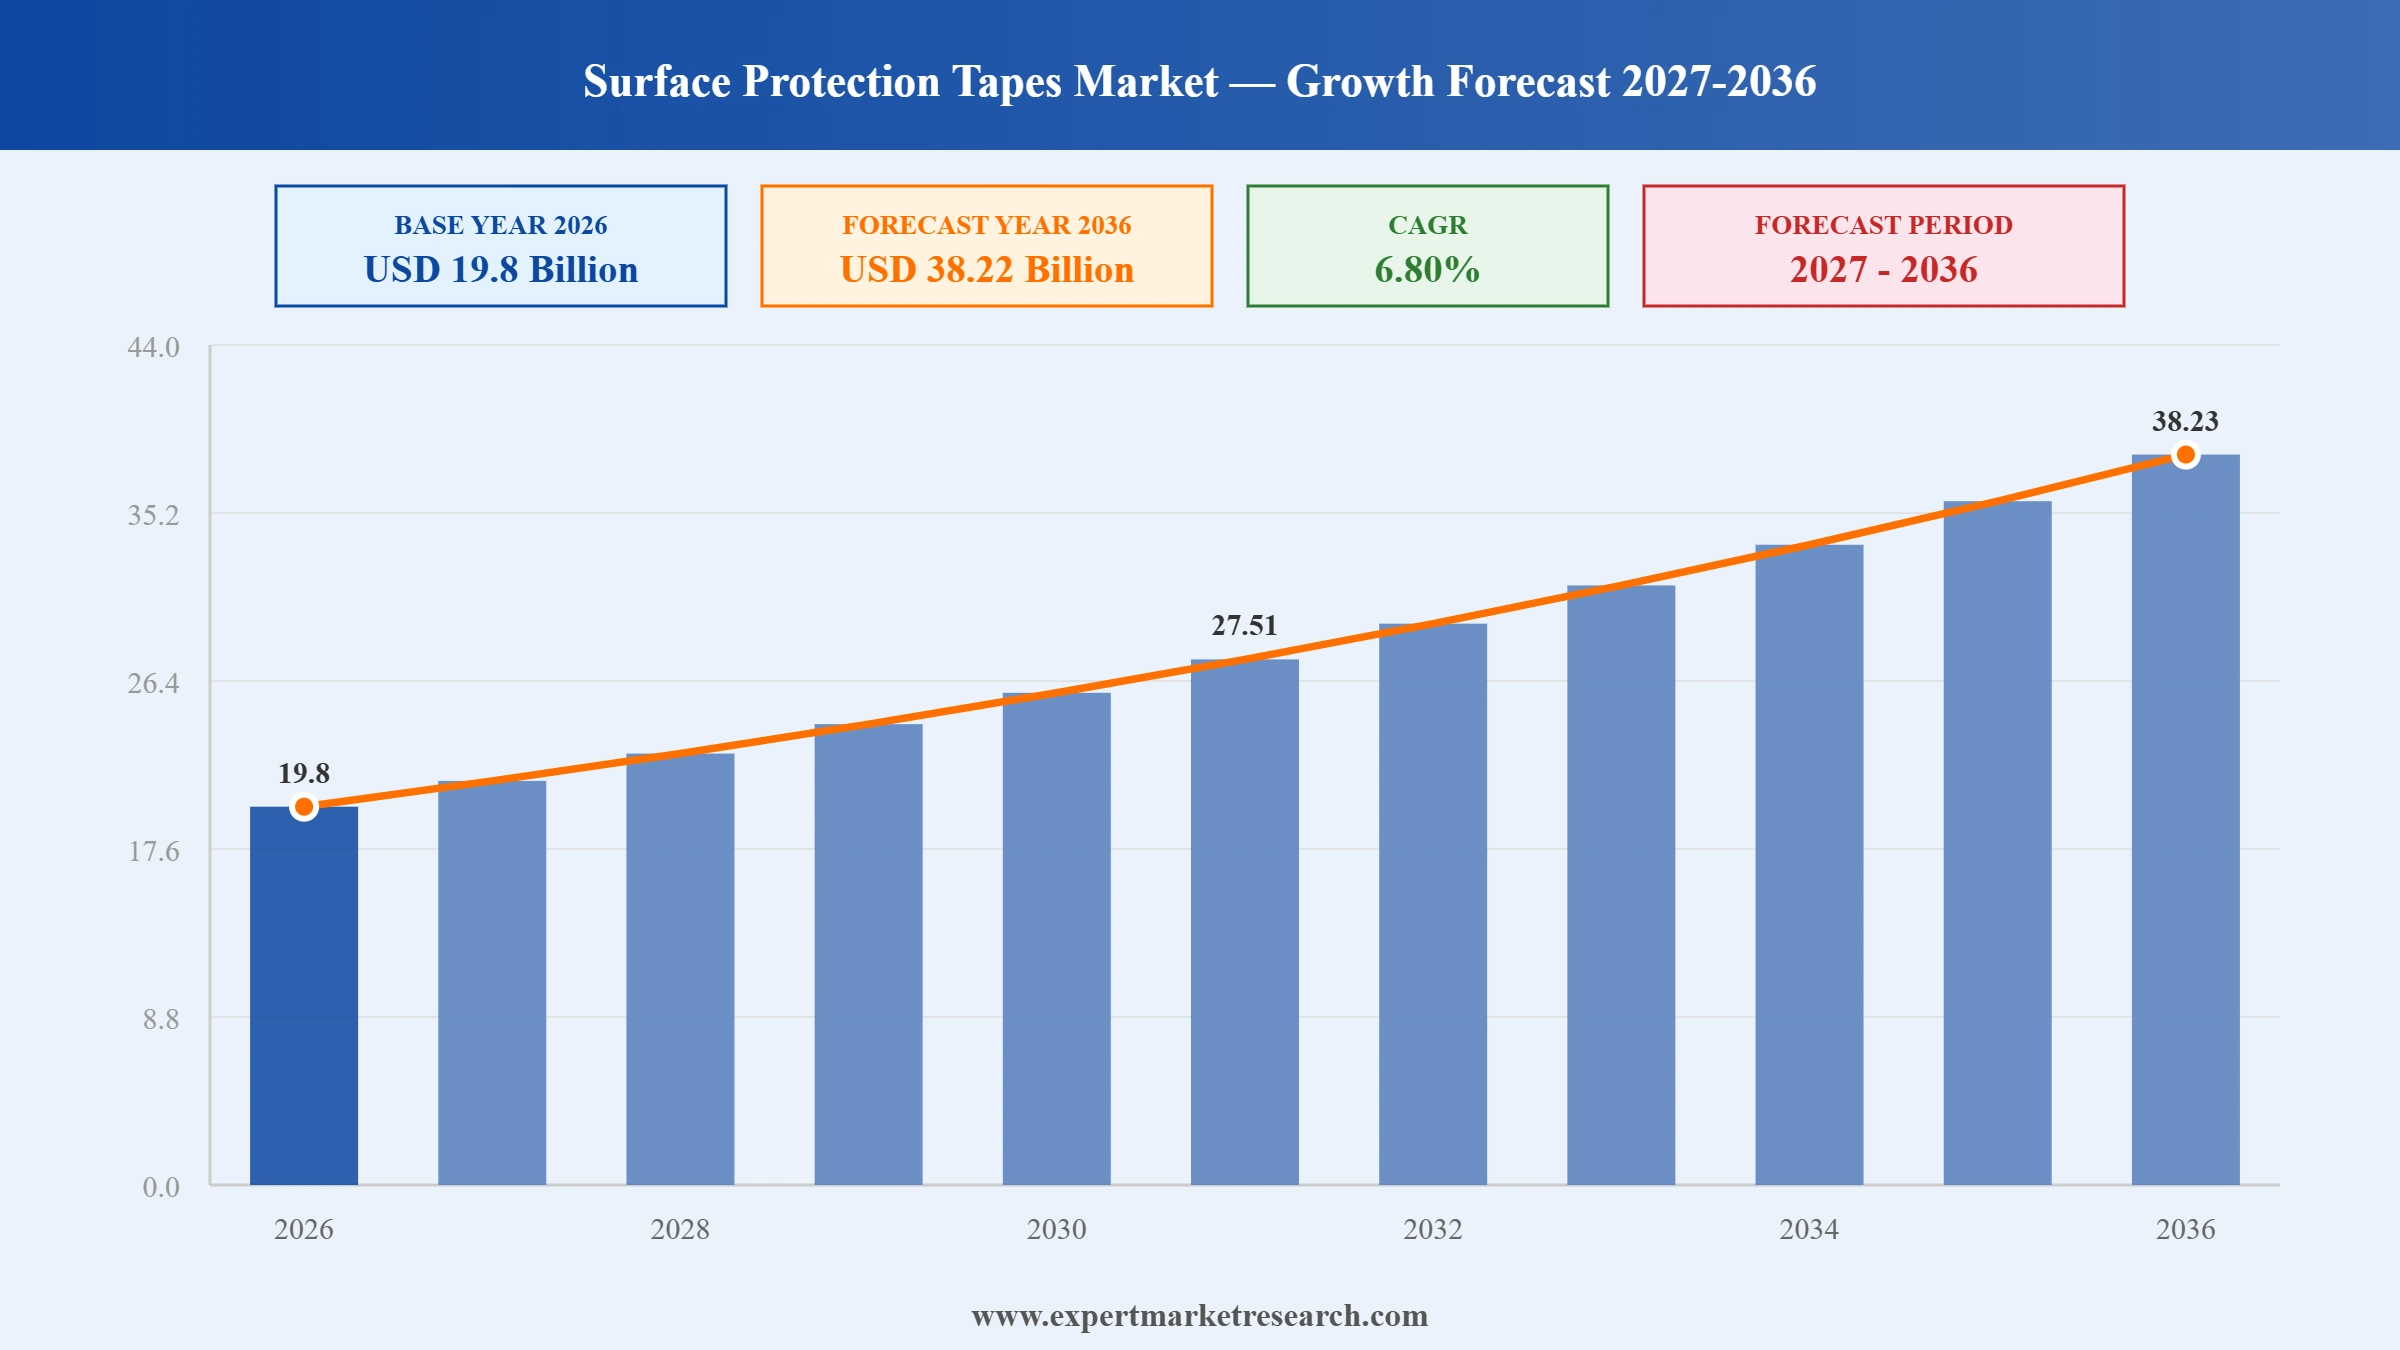
The global surface protection tapes market attained a value of USD 18.54 Billion in 2025 and is projected to expand at a CAGR of 6.80% through 2035. The market is further expected to reach USD 35.79 Billion by 2035. Rising demand for protective films across electronics, construction, and automotive applications, together with capacity additions among polyethylene and polypropylene film producers, is helping manufacturers broaden their product portfolios. Growing emphasis on residue free removal, scratch resistance, and recyclable backing materials is further encouraging established players to expand capacity across Asia Pacific, Europe, and North America.
The surface protection tapes market covers temporary adhesive films and backed tapes applied to polished metal, glass, and plastic surfaces to prevent scratches, dust, moisture, and chemical damage during manufacturing, fabrication, storage, and transit. Adoption spans electronics and appliance assembly, building and construction glazing and flooring, and automotive body and trim protection, where manufacturers rely on low tack, clean removing films to preserve cosmetic quality through handling stages. Demand concentrates among appliance makers, electronics assemblers, automakers, and construction contractors requiring consistent adhesion paired with residue free removal after extended exposure. Producers are widening polyethylene, polypropylene, and polyvinyl chloride backing options to match varied surface textures across end use industries.
Demand is concentrating around automotive and electronics manufacturers seeking consistent, residue free protection as production volumes and surface finish standards rise. In May 2025, Intertape Polymer Group launched a new Polyethylene Surface Protection Film tape offering low tack, highly conformable coverage with clean removability, ultraviolet resistance of up to thirty days, moisture resistance, and straight tear functionality for marine, automotive, appliance, transportation, and construction surfaces. Such launches show producers tailoring backing chemistry and release properties to specific handling conditions rather than one generic film. Installed capacity among converters is growing as appliance and electronics lines scale output, reinforcing demand for tapes combining dependable adhesion with fast, clean removal.
Manufacturers active in the surface protection tapes market are directing investment toward broader backing material portfolios, specialty coatings, and regional production capacity to serve customers closer to their manufacturing bases. Companies are widening polyolefin and polyvinyl chloride film ranges, improving adhesive consistency across temperature extremes, and adding printing and branding capabilities to differentiate commodity grade films from premium offerings. Portfolios are also expanding toward higher value, longer duration automotive and construction grades as customers seek tapes suited to extended outdoor exposure, reflecting a broader shift toward specialized, application specific protection solutions across converters and film producers worldwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Cosmo Films introduced Gold Plus and Silver paint protection film variants at Automechanika, alongside its Matte and Black grades, widening automotive surface protection portfolio. Gold Plus carries a seven-year warranty using premium thermoplastic polyurethane and advanced adhesive technology, while Silver carries a three-year warranty for cost conscious buyers. Such tiered launches help converters across the surface protection tapes market match protection grade to budgets.
Garware Hi-Tech Films began commercial output from a new paint protection film line at its Waluj facility in Maharashtra, backed by an investment of roughly INR 1.25 billion and annual capacity of 300 lakh square feet. The ISO certified line serves domestic and export automotive surface protection demand. Such capacity additions across the surface protection tapes market help converters reduce lead times for automotive customers.
Polifilm relocated and expanded its Vietnam operation to a new facility outside Ho Chi Minh City, marking the group's first production footprint outside Europe and adding laminating, label, and siliconization film capability for Southeast Asian customers. The move shortens delivery times and strengthens regional supply for converters sourcing protective and release film substrates, helping producers serve expanding Asian manufacturing customers.
Nautic Partners completed the acquisition of a specialty tapes business carved out from a diversified plastics group, relaunching it as the independent company Vybond, with facilities in Kentucky, New York, and Rhode Island covering more than fifteen hundred stock keeping units across construction, medical, aerospace, and automotive uses. Such carve outs let standalone tape platforms across the surface protection tapes market pursue sharper customer focus.
Film manufacturers across the surface protection tapes market are differentiating premium paint protection film lines with glossy finishes, warranty backed durability, and self-healing topcoats to capture rising aftermarket demand. Such positioning helps brands justify premium pricing against commodity grade films. In July 2025, 3M promoted its new Paint Protection Film Series 50, featuring a glossy finish, scratch resistant self-healing properties, and a manufacturer backed warranty for automotive surfaces. The launch illustrates how established film suppliers are reinforcing brand trust in this segment.
Film producers across surface protection tapes market continue adding biaxially oriented polyester and polypropylene capacity to support growing backing material demand from tape converters. Jindal Poly Films disclosed plans in May 2025 for new manufacturing lines at Nashik, Maharashtra: a biaxially oriented polypropylene line of up to 42,000 tonnes annually, a polyester line of up to 55,000 tonnes annually, and a cast polypropylene line of up to 18,000 tonnes annually, backed by investment above INR 700 crore, reflecting sustained regional tape demand.
Chemical suppliers across the surface protection tapes market are scaling thermoplastic polyurethane and specialty adhesive capacity dedicated to automotive paint protection film as vehicle owners increasingly specify aftermarket surface protection at the point of sale. Lubrizol opened a new Estane thermoplastic polyurethane production line at its Shanghai facility in February 2025 to meet growing Asia Pacific demand for high-quality car paint protection film. The investment underscores how upstream material suppliers are positioning closer to converter demand in the region's expanding automotive aftermarket.
Indian polyester and biaxially oriented film producers across the surface protection tapes market are adding capacity to meet rising backing material requirements from tape, label, and packaging converters. Polyplex Corporation's board approved an investment of roughly INR 558 crore in January 2025 for a new biaxially oriented polyethylene terephthalate film plant adding 52,400 tonnes of annual capacity, citing operations already running at full capacity across its existing lines. Such investment supports converters seeking dependable, regionally sourced film supply.
Protective film producers serving Latin America's construction sector are introducing formulations suited to demanding climate and handling conditions on building sites. Promaflex, described as the region's largest protective film manufacturer, presented a new FHT line at Expo Revestir in January 2025, offering greater resistance to high temperatures, lower permeability to water and steam, and up to fifty percent less material use than prior grades. The launch reflects growing regional emphasis on efficient, durable building surface protection.
The Expert Market Research's report titled "Global Surface Protection Tapes Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
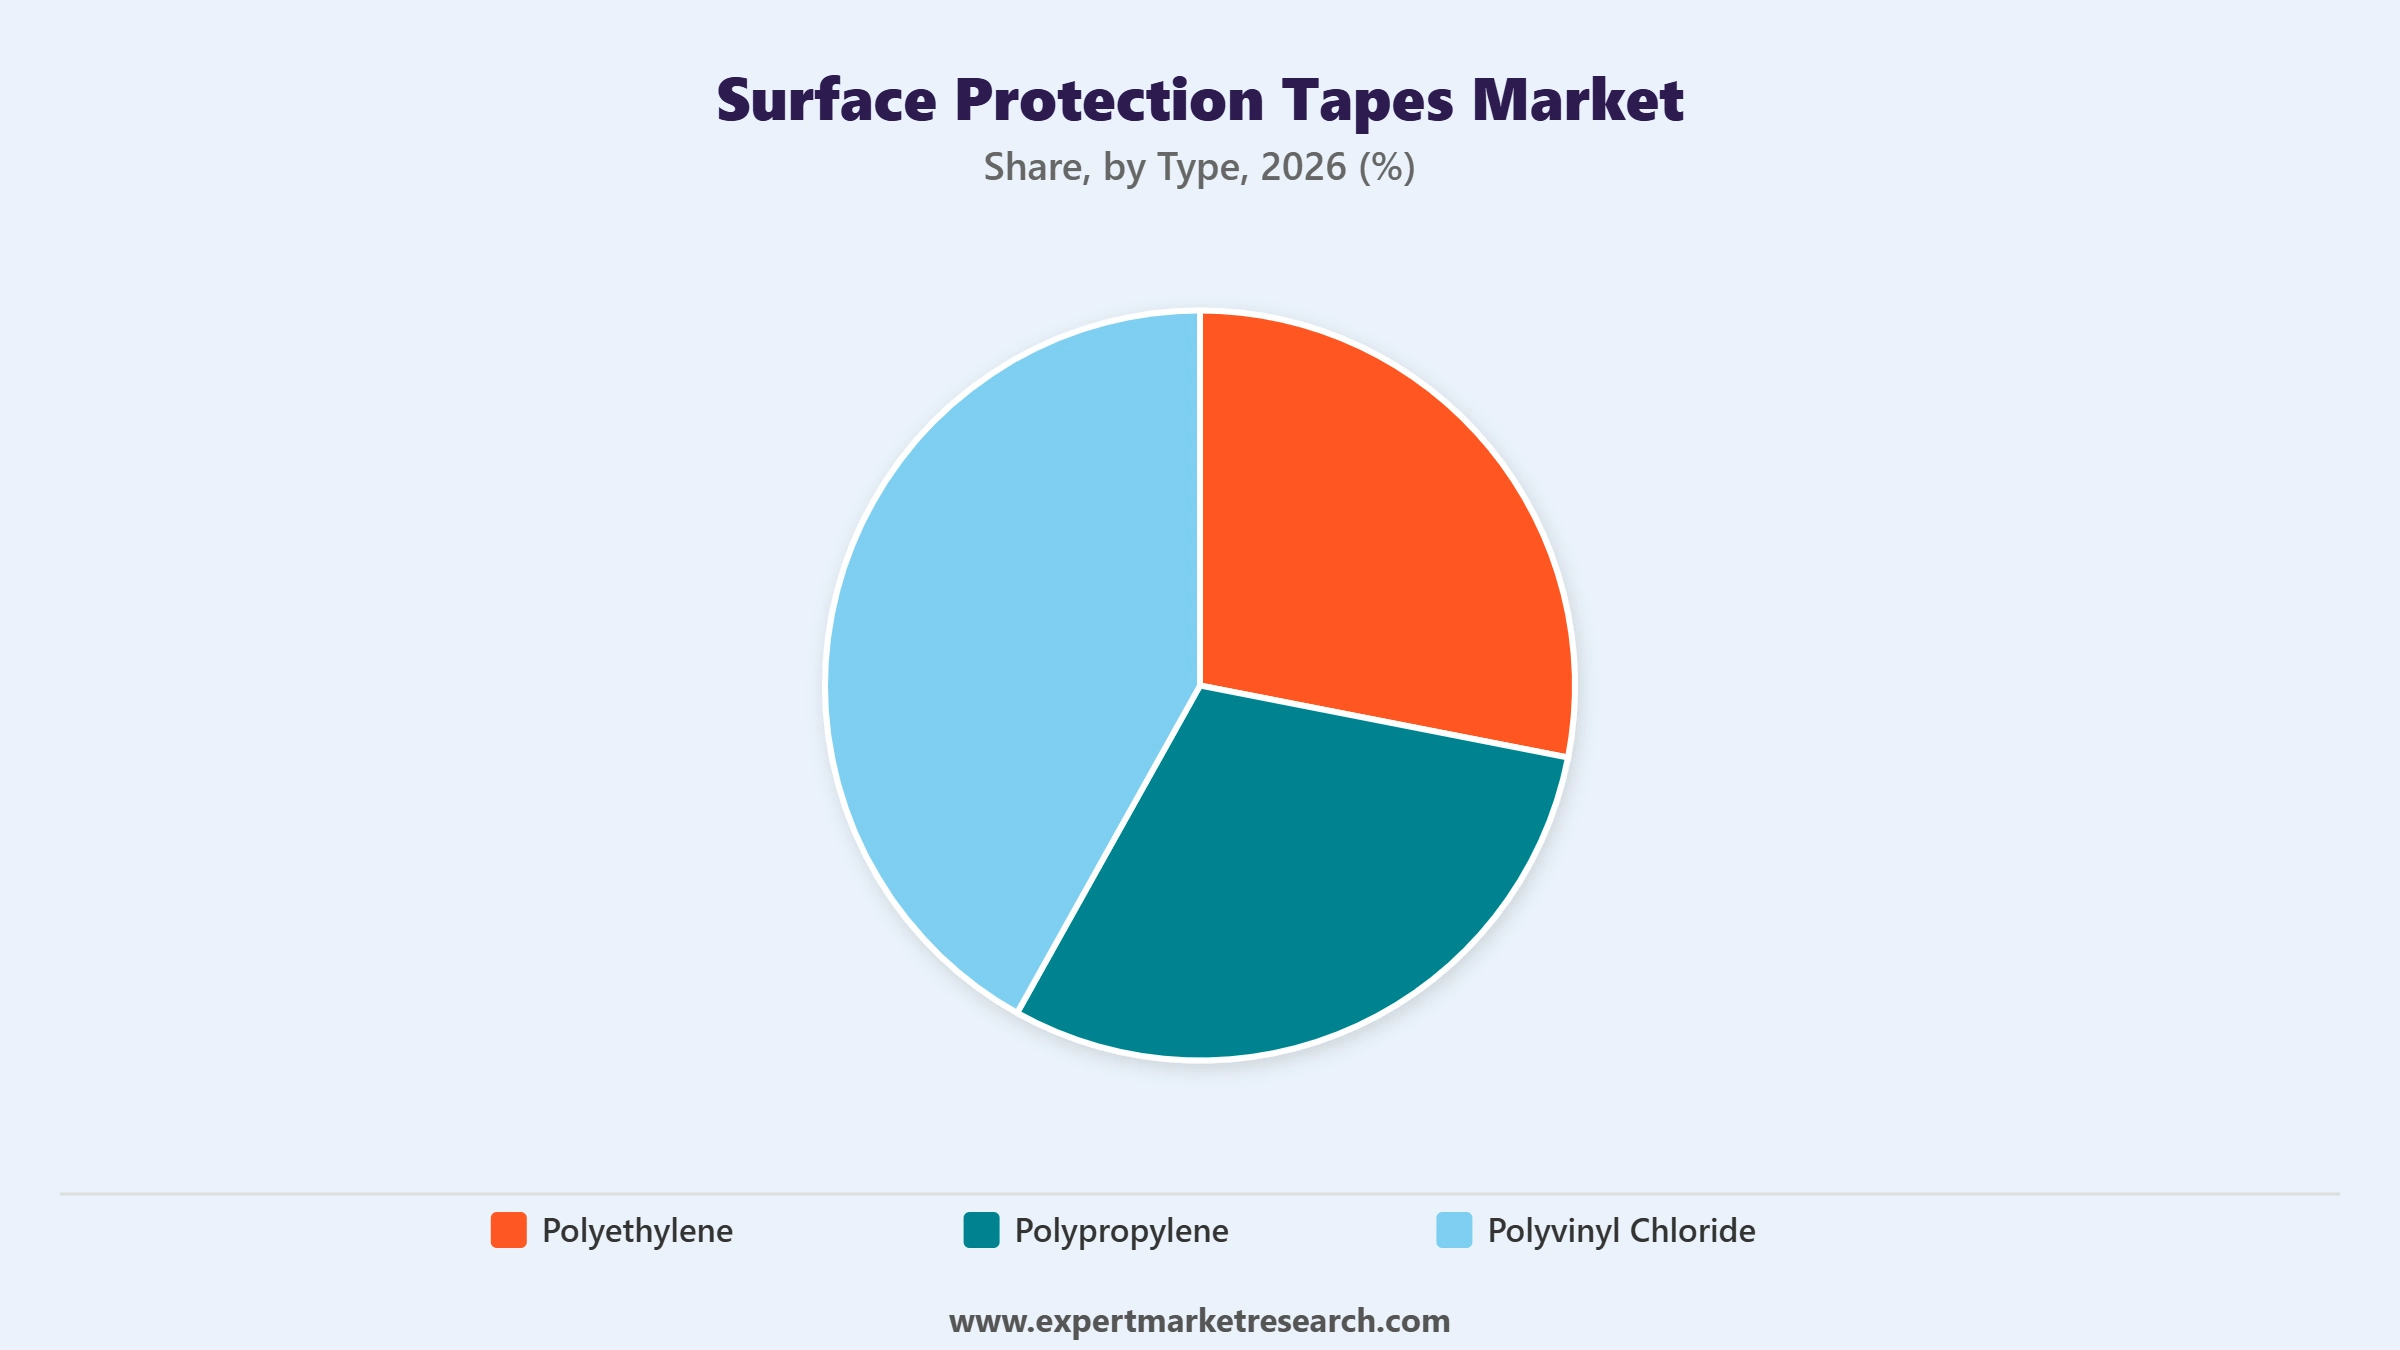
Key Insight: Polyethylene backed tapes dominate the surface protection tapes market owing to their low cost, high flexibility, and dependable low tack adhesion suited to appliance, metal, and glass protection across varied climates. Polypropylene backed tapes are gaining share in automotive and electronics applications that require higher temperature and chemical resistance during assembly and outdoor exposure. Polyvinyl chloride backed tapes offer strong puncture and abrasion resistance for heavy duty construction and flooring protection, while the others category, spanning polyester and specialty coated films, continues to serve niche applications requiring extended outdoor durability or precise optical clarity for display and glass surfaces.
Market Breakup by Surface Material
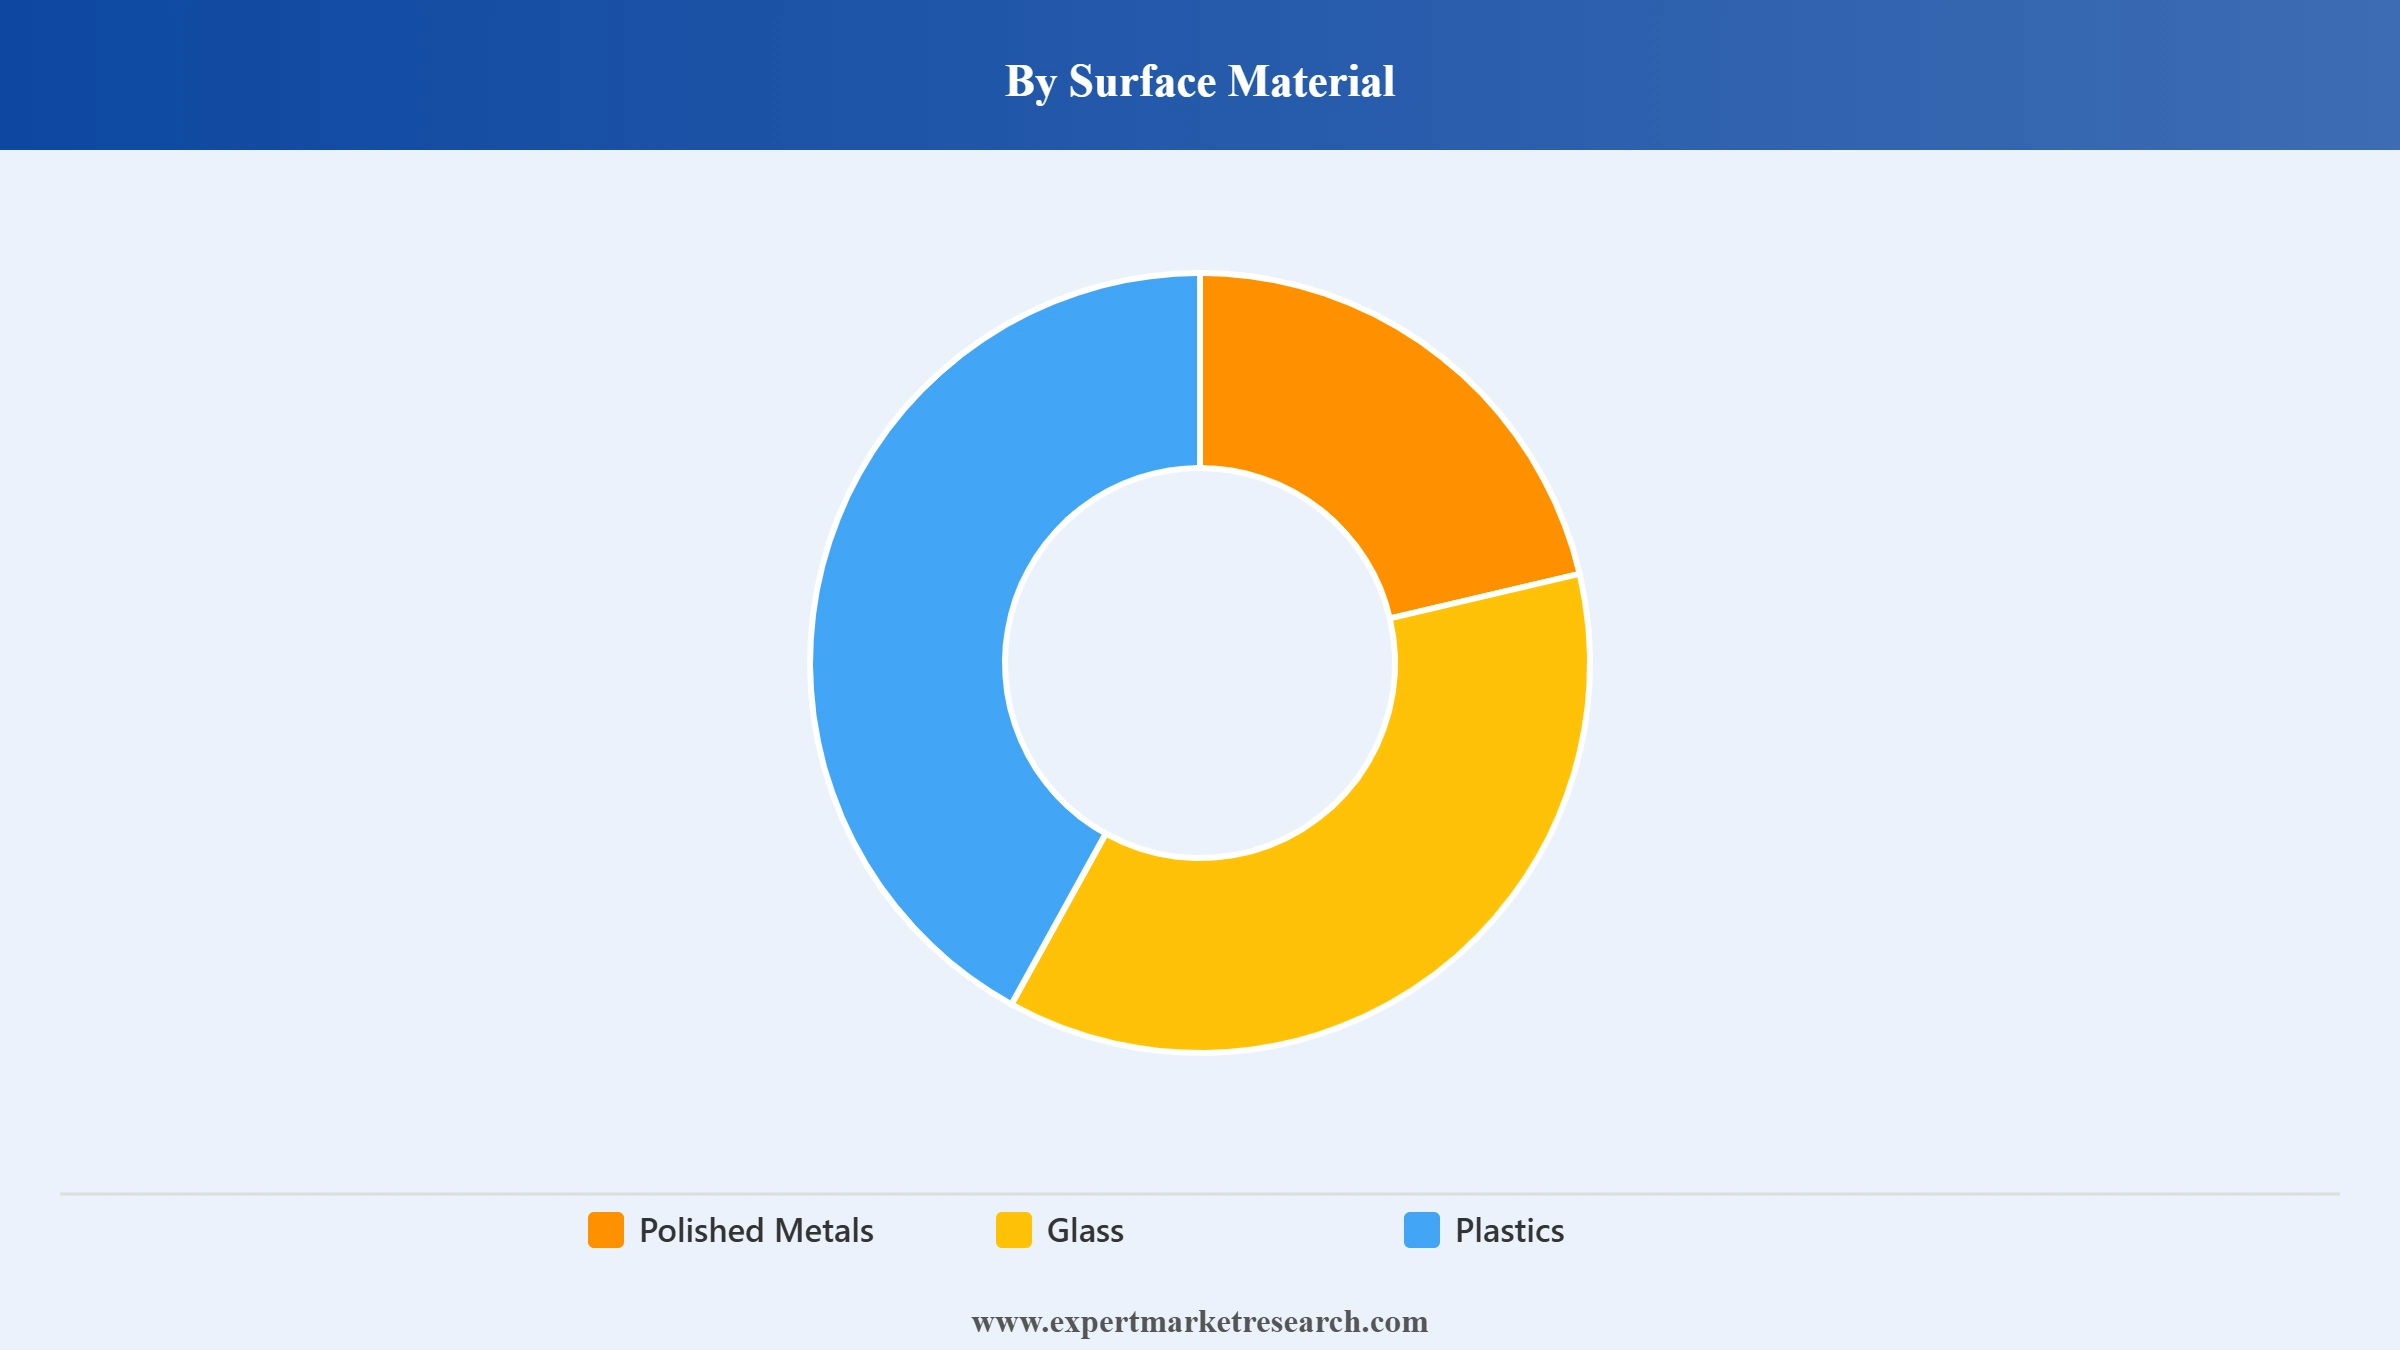
Key Insight: Polished metal surfaces account for the largest share of the surface protection tapes market as automotive bodies, appliance panels, and stainless-steel fixtures require consistent protection from scratches and fingerprints during fabrication, transit, and installation. Glass surfaces, including architectural glazing and display panels, depend on clean removing films that avoid residue and streaking. Plastic surfaces across automotive trim and electronic housings are seeing growing tape demand as component counts rise, while the others category, covering composites, painted surfaces, and wood veneers, continues to provide a smaller but steady source of specialty protection demand.
Market Breakup by End Use
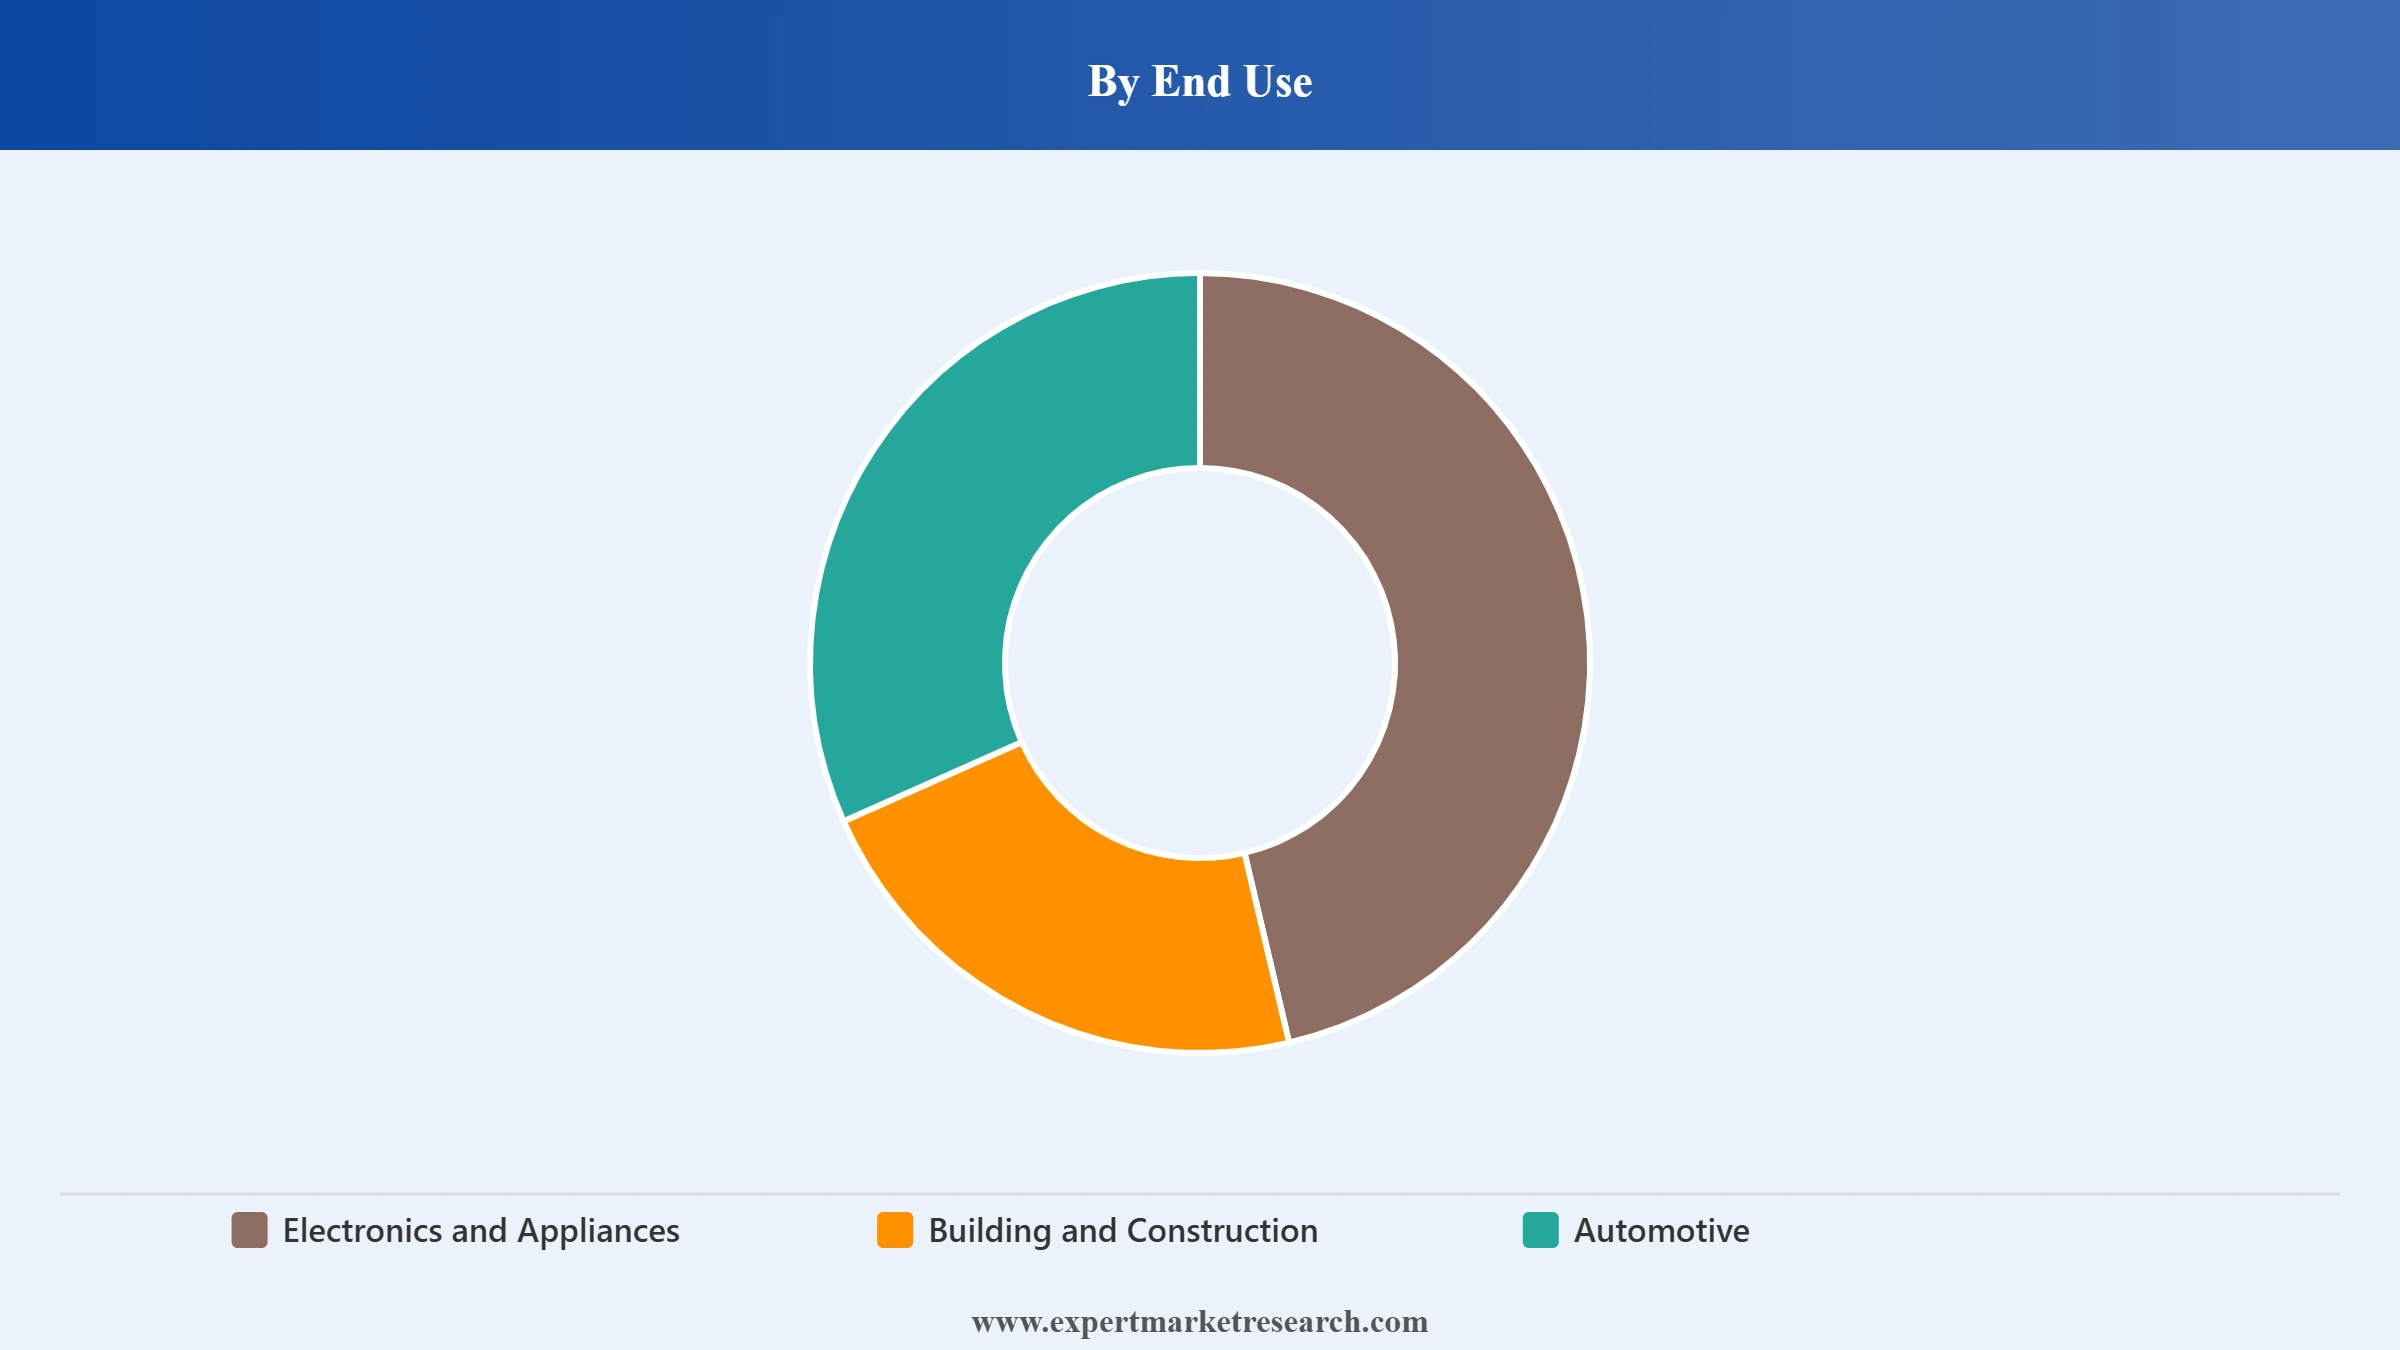
Key Insight: Electronics and appliances represent the largest end use segment in the surface protection tapes market, as manufacturers protect painted panels, touchscreens, and plastic housings throughout assembly, packaging, and retail display. Building and construction applications rely on tapes to shield glazing, flooring, and fixtures during installation and finishing work, supporting steady demand tied to renovation and new build activity. Automotive applications are registering the fastest growth as vehicle production volumes rise and paint protection film adoption expands across both original equipment and aftermarket channels, reinforcing demand for durable, long lasting film grades.
Market Breakup by Region
Key Insight: Regional dynamics in the surface protection tapes market continue to shape competitive strategies. Asia Pacific leads the market on the back of large-scale electronics, appliance, and automotive manufacturing across China, India, Japan, and South Korea. North America and Europe sustain steady demand from mature automotive and construction sectors, while the Middle East and Africa region is registering the fastest growth as backward integrated film capacity expands to serve regional packaging and protective film needs. Latin America remains a smaller but steadily growing market, supported by expanding construction and appliance manufacturing activity across Brazil and Mexico.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By type, polyethylene backed tapes dominate the market owing to their low cost and dependable low tack adhesion
Polyethylene backed tapes account for the largest share of the surface protection tapes market, supported by low material cost, high flexibility, and adhesion properties that suit appliance, metal, and glass surfaces across varied climates. Converters favor polyethylene backing for its ease of converting into varied widths and thicknesses without specialized tooling, letting producers serve fragmented end markets from a common film base. The backing's compatibility with rubber and acrylic adhesive systems further supports its adoption in general purpose protection applications.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Polypropylene backed tapes are registering the fastest growth as automotive and electronics converters seek higher heat resistance and chemical resistance during painting and coating operations. The backing's stiffness also supports cleaner, more precise die cutting for complex component shapes used in appliance and electronics assembly. Producers are expanding polypropylene grades alongside polyethylene lines to capture this shift without abandoning their established general purpose film base, reinforcing polypropylene's rising share across demanding industrial applications.
By surface material, polished metals dominate the market owing to extensive automotive and appliance fabrication demand
Polished metal surfaces command the largest share of the surface protection tapes market, driven by continuous demand from automotive body panels, appliance cabinets, and stainless-steel fixtures needing scratch and fingerprint protection. In January 2026, KPS Capital Partners agreed to acquire a controlling stake in Novacel, a French protection film maker serving building, appliance, industrial, and transportation customers, from Compagnie Chargeurs Invest. This high-volume demand from heavy manufacturing sectors anchors polished metal protection as the largest surface material category.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Plastic surfaces are the fastest-growing surface material segment as component counts rise across electronics and vehicles, with housings, automotive trim, and appliance panels increasingly relying on molded plastic components alongside metal parts. Rising plastic component counts in modern vehicles and consumer electronics are pushing converters to refine adhesive formulations that bond securely to low surface energy plastics without leaving residue on removal. This shift is encouraging tape producers to expand plastic compatible adhesive chemistries across their film portfolios.
By end use, electronics and appliances dominate the market owing to extensive surface protection needs through assembly and retail display
Electronics and appliances represent the largest end use segment in the surface protection tapes market, as manufacturers apply tapes across painted panels, touchscreens, and plastic housings throughout assembly, packaging, warehousing, and retail display. Consumer facing products demand clean, residue free removal since any adhesive trace or surface mark is highly visible to buyers. The segment's scale, spanning large appliances and compact electronics, continues to generate the highest overall volume demand for general purpose protective films.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Automotive is the fastest-growing end use segment as paint protection film adoption expands across aftermarket channels. Both original equipment manufacturers and aftermarket installers are expanding paint protection film adoption. In January 2025, ALP Group launched three paint protection film variants named Defender, Armor, and Ranger at the Bharat Mobility Global Expo, each incorporating self-healing technology for minor scratches and ultraviolet protection against discoloration. Such launches illustrate how converters are targeting vehicle owners seeking long lasting cosmetic protection.
Asia Pacific leads the market through large-scale electronics, appliance, and automotive manufacturing
Asia Pacific commands the largest share of the surface protection tapes market, underpinned by extensive electronics, appliance, and automotive manufacturing across China, India, Japan, and South Korea. Dense clusters of component assemblers and vehicle makers generate consistent, high-volume demand for general purpose and specialty protective films at every production stage. Regional film and tape converters continue widening backing and adhesive portfolios to serve this manufacturing base directly, reinforcing the region's cost and supply chain advantages through the forecast period.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The Middle East and Africa region is registering the fastest growth in the surface protection tapes market as producers invest in backward integrated film capacity. UFlex is allocating roughly USD 200 million toward expansion in Egypt, announced in July 2026, including a polyethylene terephthalate chip facility supplying raw material for biaxially oriented film production and a separate aseptic packaging unit supporting regional supply and duty-free export access to Europe. Growing construction and appliance activity is lifting backing material demand.
The global industry is becoming increasingly consolidated as major surface protection tapes companies invest in backing material diversification, adhesive formulation upgrades, and regional capacity expansion to defend their positions. Surface protection tapes players are prioritizing clean removal performance, consistent adhesion across temperature extremes, and faster converting speeds to differentiate otherwise standardized film offerings. Strategic emphasis on regional manufacturing footprints is allowing companies to serve growing Asia Pacific and Middle Eastern demand while managing logistics costs, with several producers also adding capacity closer to automotive and electronics assembly hubs to shorten delivery times.
Major surface protection tapes market players are also focusing on sustainability credentials, pursuing thinner recyclable films, solvent free adhesive systems, and reduced material use without sacrificing tear resistance or adhesion control. Surface protection tapes players are additionally widening automotive paint protection film and construction grade portfolios to capture higher value applications beyond commodity general purpose films. Companies that successfully combine cost competitive scale with cleaner production processes and reliable regional supply are expected to strengthen their competitive position over the coming years, particularly as converters place greater weight on supply chain resilience.
Founded in 1918 and headquartered in Osaka, Japan, Nitto Denko Corporation supports the market through its broad industrial tape portfolio spanning electronics, automotive, and general manufacturing protection applications. The company draws on decades of coating and adhesive formulation expertise across its global material science operations, serving customers through an extensive manufacturing and distribution network spanning Asia, the Americas, and Europe.
Founded in 2001 and headquartered in Norderstedt, Germany, Tesa SE contributes to the market through its industrial tape division, which supplies adhesive films for automotive, electronics, and general manufacturing surface protection. The company operates a global production network supporting customers across consumer and industrial segments, drawing on a long heritage in pressure sensitive adhesive technology.
Founded in 1935 and headquartered in Mentor, Ohio, United States, Avery Dennison Corporation supports the market through its performance films and specialty converting materials businesses, which supply film substrates and adhesive coated products to industrial converters. The company maintains an extensive global manufacturing footprint serving customers across packaging, labeling, and protective film applications.
Founded in 1665 and headquartered in Courbevoie, France, Saint-Gobain S.A. supports the market through its industrial tape solutions business, which supplies adhesive films and specialty tapes for manufacturing, construction, and transportation applications. The company draws on a long history of materials science innovation across its diversified global operations.
Other key players in the market include Toray Industries, Inc. and Berry Global Group, Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global surface protection tapes market trends 2026 report. Discover regional growth patterns, backing material economics, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 18.54 Billion.
The market is projected to grow at a CAGR of 6.80% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 35.79 Billion by 2035.
The rapid technological advancements in the product acts as a key trend for the market.
The rise in the demand for surface protection tapes is expected to be a key trend guiding the growth of the industry.
North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa are the leading regions in the market.
The types of the product can be categorised into polyethylene, polypropylene, and polyvinyl chloride, among others.
The significant surface materials used in the market are polished metals, glass, and plastics, among others.
The product finds extensive end-uses in electronics and appliances, building and construction, and automotive sectors.
The key players in the market include Nitto Denko Corporation, Tesa SE, Avery Dennison Corporation, Saint-Gobain S.A., Toray Industries, Inc., and Berry Global Group, Inc., among others.
Companies face volatile resin and adhesive raw material costs, tightening packaging waste regulation, competition from substitute protective materials, and the need to maintain consistent adhesion and clean removal across varied surfaces and climates.
Expanding polyethylene, polypropylene, and polyvinyl chloride backing portfolios, investing in automotive paint protection film grades, pursuing sustainable and recyclable film formulations, and strengthening regional manufacturing capacity across Asia Pacific and the Middle East and Africa.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Surface Material |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




