

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
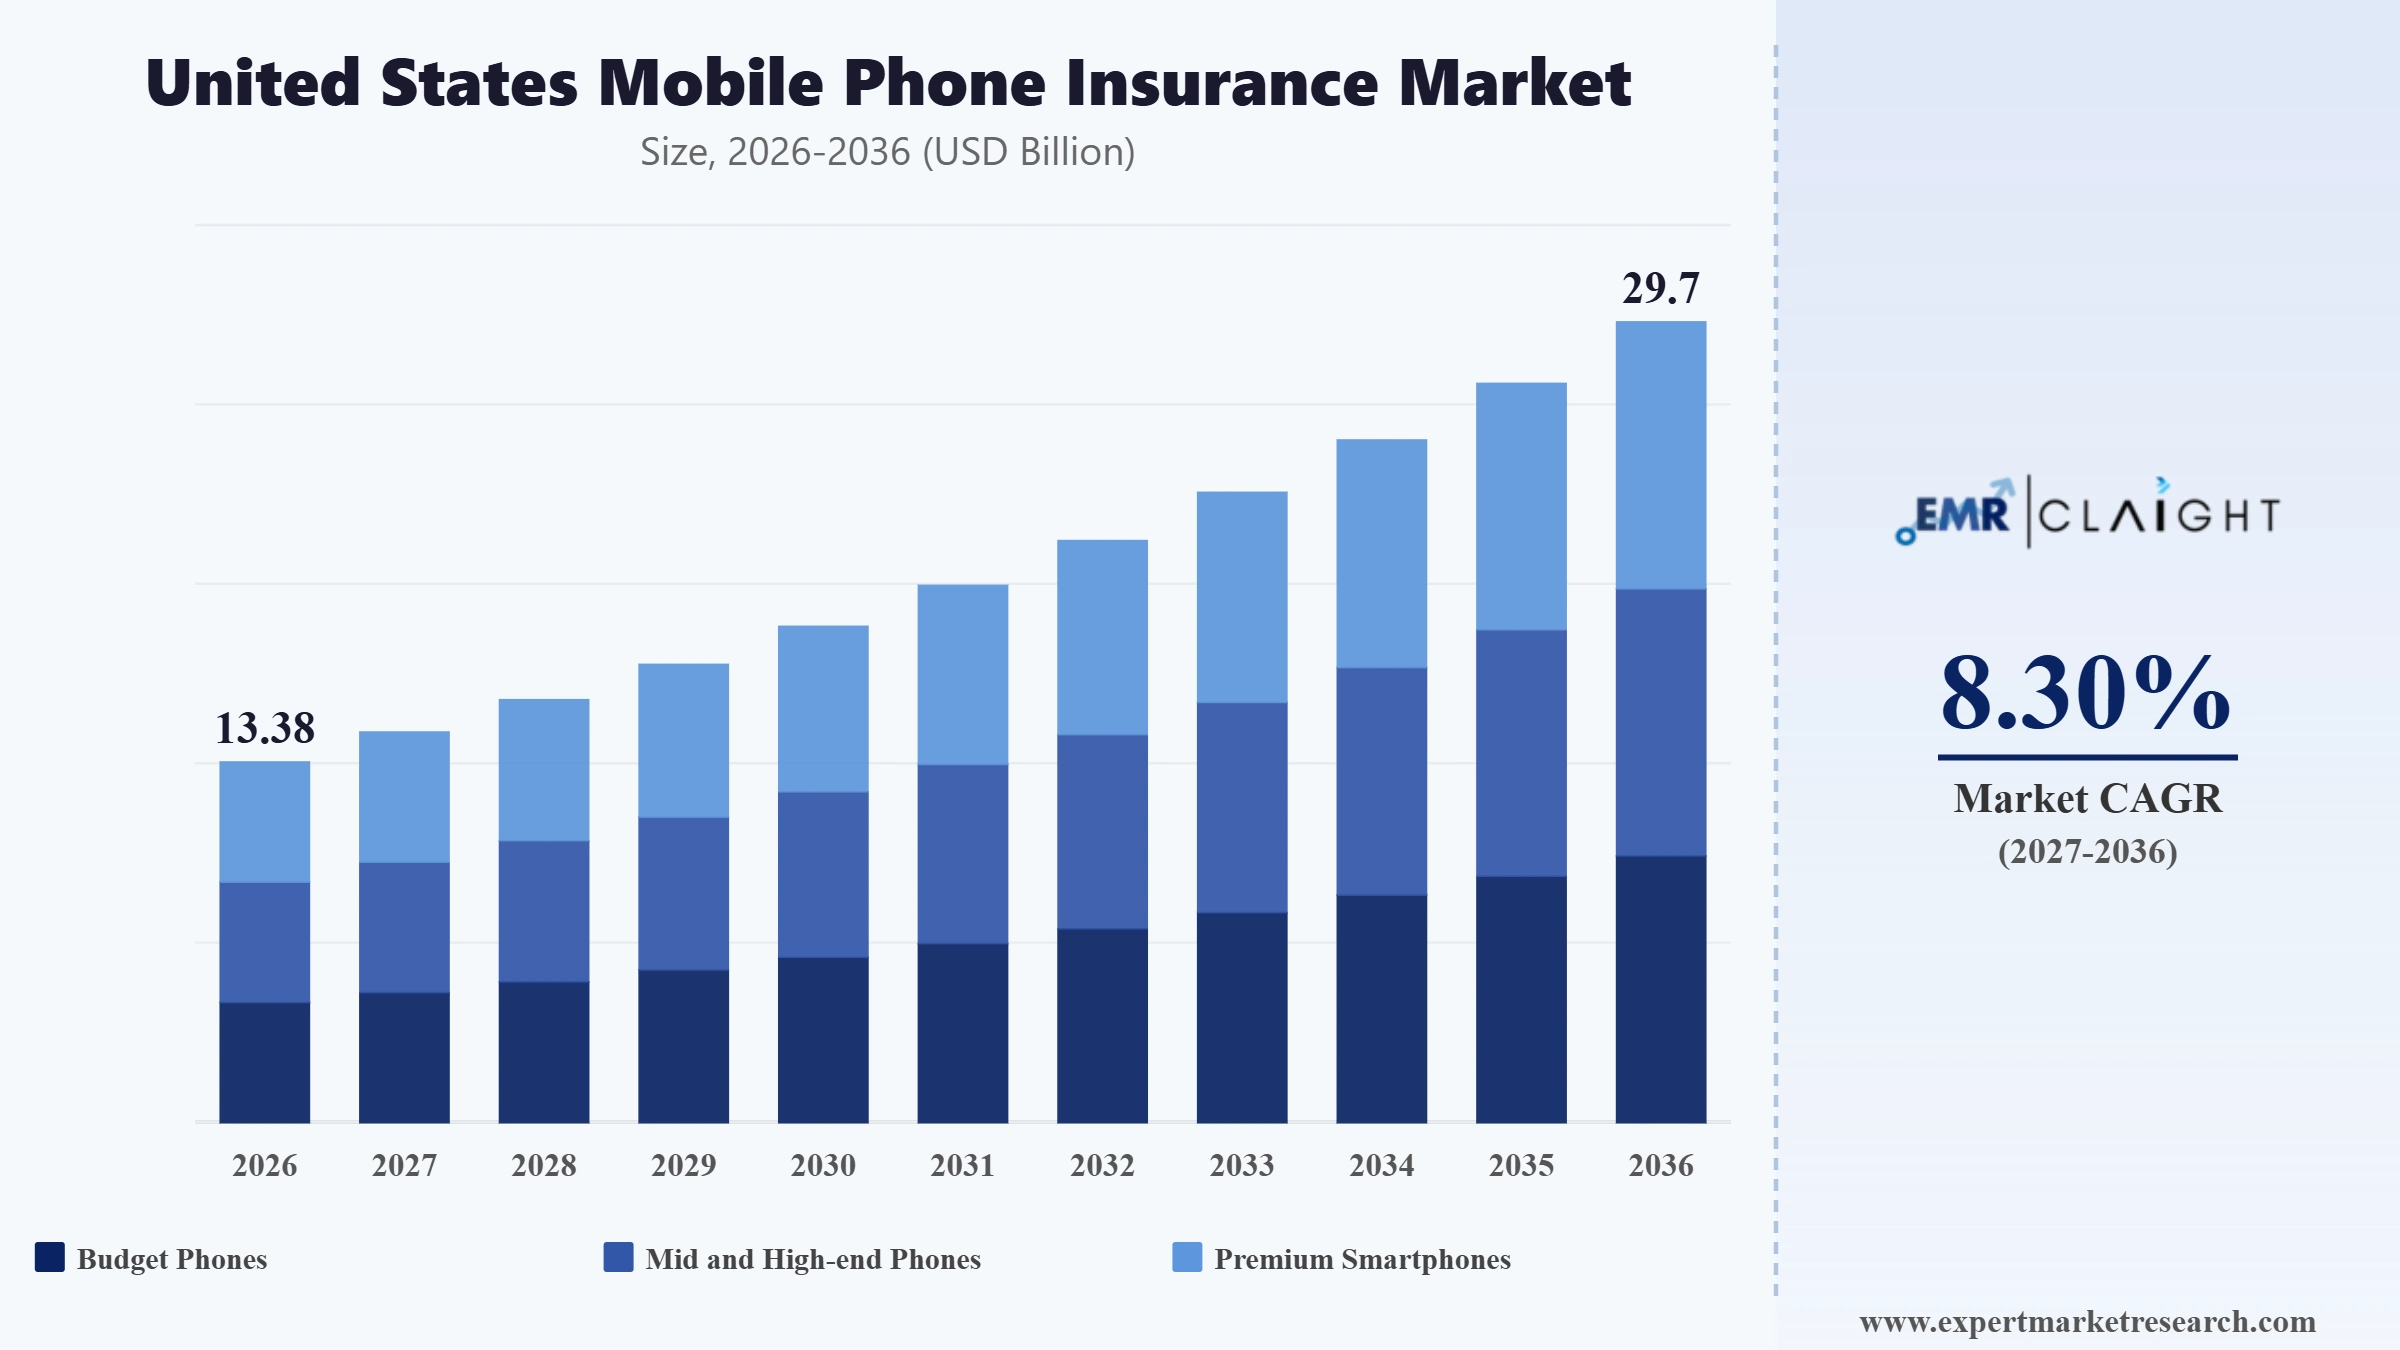
The United States mobile phone insurance market attained a value of USD 12.35 Billion in 2025 and is projected to expand at a CAGR of 8.30% through 2035. The market is further expected to reach USD 27.41 Billion by 2035. Rising smartphone prices, growing device financing programs, and increasing consumer awareness of device protection benefits are helping insurers and carriers differentiate their coverage offerings. Expanding partnerships between wireless carriers and protection providers, alongside growing adoption of app-based claims processing, is further encouraging providers to widen coverage across every phone category.
Mobile phone insurance serves as a preventive measure that enables users to mitigate substantial replacement costs associated with the loss or breakdown of their mobile phones. Premium smartphones hold a substantial share of the market owing to their high replacement costs, which make comprehensive coverage particularly valuable to their owners. Rising smartphone dependency for personal and professional use continues to widen the buyer base for device protection nationwide.
Demand is concentrating around providers able to combine broad carrier partnerships with fast, digital first claims processing. Between December 2025 and January 2026, Straight Talk transitioned device protection plan administration for enrolled customers, issuing cancellation notices ahead of a shift to an updated coverage structure. This partnership driven positioning is converting rising demand for affordable, accessible device protection directly into expanded adoption across the United States mobile phone insurance market.
Providers across the United States mobile phone insurance market are converging on a common development direction, widening from conventional carrier bundled plans toward flexible, multi device protection platforms covering phones alongside laptops, tablets, and wearables. Third party insurers are increasingly pursuing distribution partnerships with device repair networks to expand physical service access beyond mail in claims processing alone. This shift is reshaping competitive dynamics among providers, favouring insurers who can demonstrate broad device coverage and rapid repair access over those offering narrow, single device plans.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
AT&T, T-Mobile, and Verizon announced an agreement in principle to form a joint venture using satellite based direct to device technologies to address wireless coverage gaps in underserved regions. The initiative aims to extend connectivity for millions of customers across remote areas. Providers across the United States mobile phone insurance market can use expanded network reliability initiatives to strengthen the value proposition of bundled device protection plans.
Asurion announced enhancements to Asurion Complete Protect, its all-in-one protection plan covering Amazon eligible purchases, adding Norton 360 Deluxe cybersecurity protection and in person tech services at uBreakiFix by Asurion locations. The updated plan also introduced an annual product care credit for select categories. Providers across the United States mobile phone insurance market can use bundled cybersecurity features to differentiate device protection subscriptions beyond basic damage coverage.
Cellairis expanded its partnership with Delcom Group through a new alliance with AKKO, a technology driven device protection platform, broadening access to certified repair and protection services. The expanded alliance strengthens distribution across Cellairis retail locations across every major metropolitan market. Providers across the United States mobile phone insurance market can use retail partner networks to extend physical repair access beyond mail in claims processing and traditional carrier channels.
Apple introduced AppleCare One, a new subscription service allowing customers to cover up to three eligible Apple devices, including iPhone, iPad, and Apple Watch, under a single monthly plan starting at 19.99 dollars. The plan automatically transfers coverage when a device is traded in. Providers can use simplified multi device subscription pricing to compete against fragmented single device protection plans.
Device manufacturers are increasingly consolidating multiple legacy protection programs into single, unified plans to simplify customer choice and reduce coverage confusion at purchase. This is reshaping product positioning across the United States mobile phone insurance market, favouring manufacturers who can offer one comprehensive plan covering accidental damage, malfunction, and loss. In August 2025, Google launched Pixel Care Plus, replacing both Google Preferred Care and Fi Device Protection with a single program offering unlimited claims and zero-dollar screen repairs.
Repair franchise networks are increasingly expanding their physical footprint across underserved metropolitan areas to support faster, in person claims fulfillment for device protection subscribers. This is reshaping service accessibility across the United States mobile phone insurance market, favouring providers with dense, walk in repair coverage across every major region. In October 2025, uBreakiFix opened a new franchise location in Palmdale, California, extending its Los Angeles area repair network to a sixth nearby city.
Cable operators entering the wireless market are increasingly bundling device protection at no extra charge directly into premium tiers instead of selling it as a separate monthly add-on. This is reshaping plan transparency across the United States mobile phone insurance market, favouring providers who can fold coverage directly into headline pricing. In April 2026, Xfinity Mobile launched Mobile Plus and Mobile Select, including lifetime device protection at no additional cost on its higher tier plan.
Prepaid wireless providers are increasingly introducing low cost, digital first device protection plans to give budget conscious customers accessible coverage options previously reserved for postpaid subscribers. This is reshaping affordability standards across the market, favouring providers offering transparent, low monthly pricing. In February 2025, Total Wireless launched Total Wireless Protect powered by Assurant, offering eligible device coverage at 5 dollars per month with 24-hour online claims filing.
Mobile virtual network operators are increasingly entering the device protection market for the first time, having previously left insurance entirely to carriers and third-party providers. This is reshaping competitive breadth across the United States mobile phone insurance market, favouring MVNOs who can bundle protection directly into their own subscriber experience. In November 2025, US Mobile launched US Mobile Protect, its first ever phone insurance offering, with introductory pricing of 3 dollars per month for early signups.
The Expert Market Research's report titled "United States Mobile Phone Insurance Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Phone Type
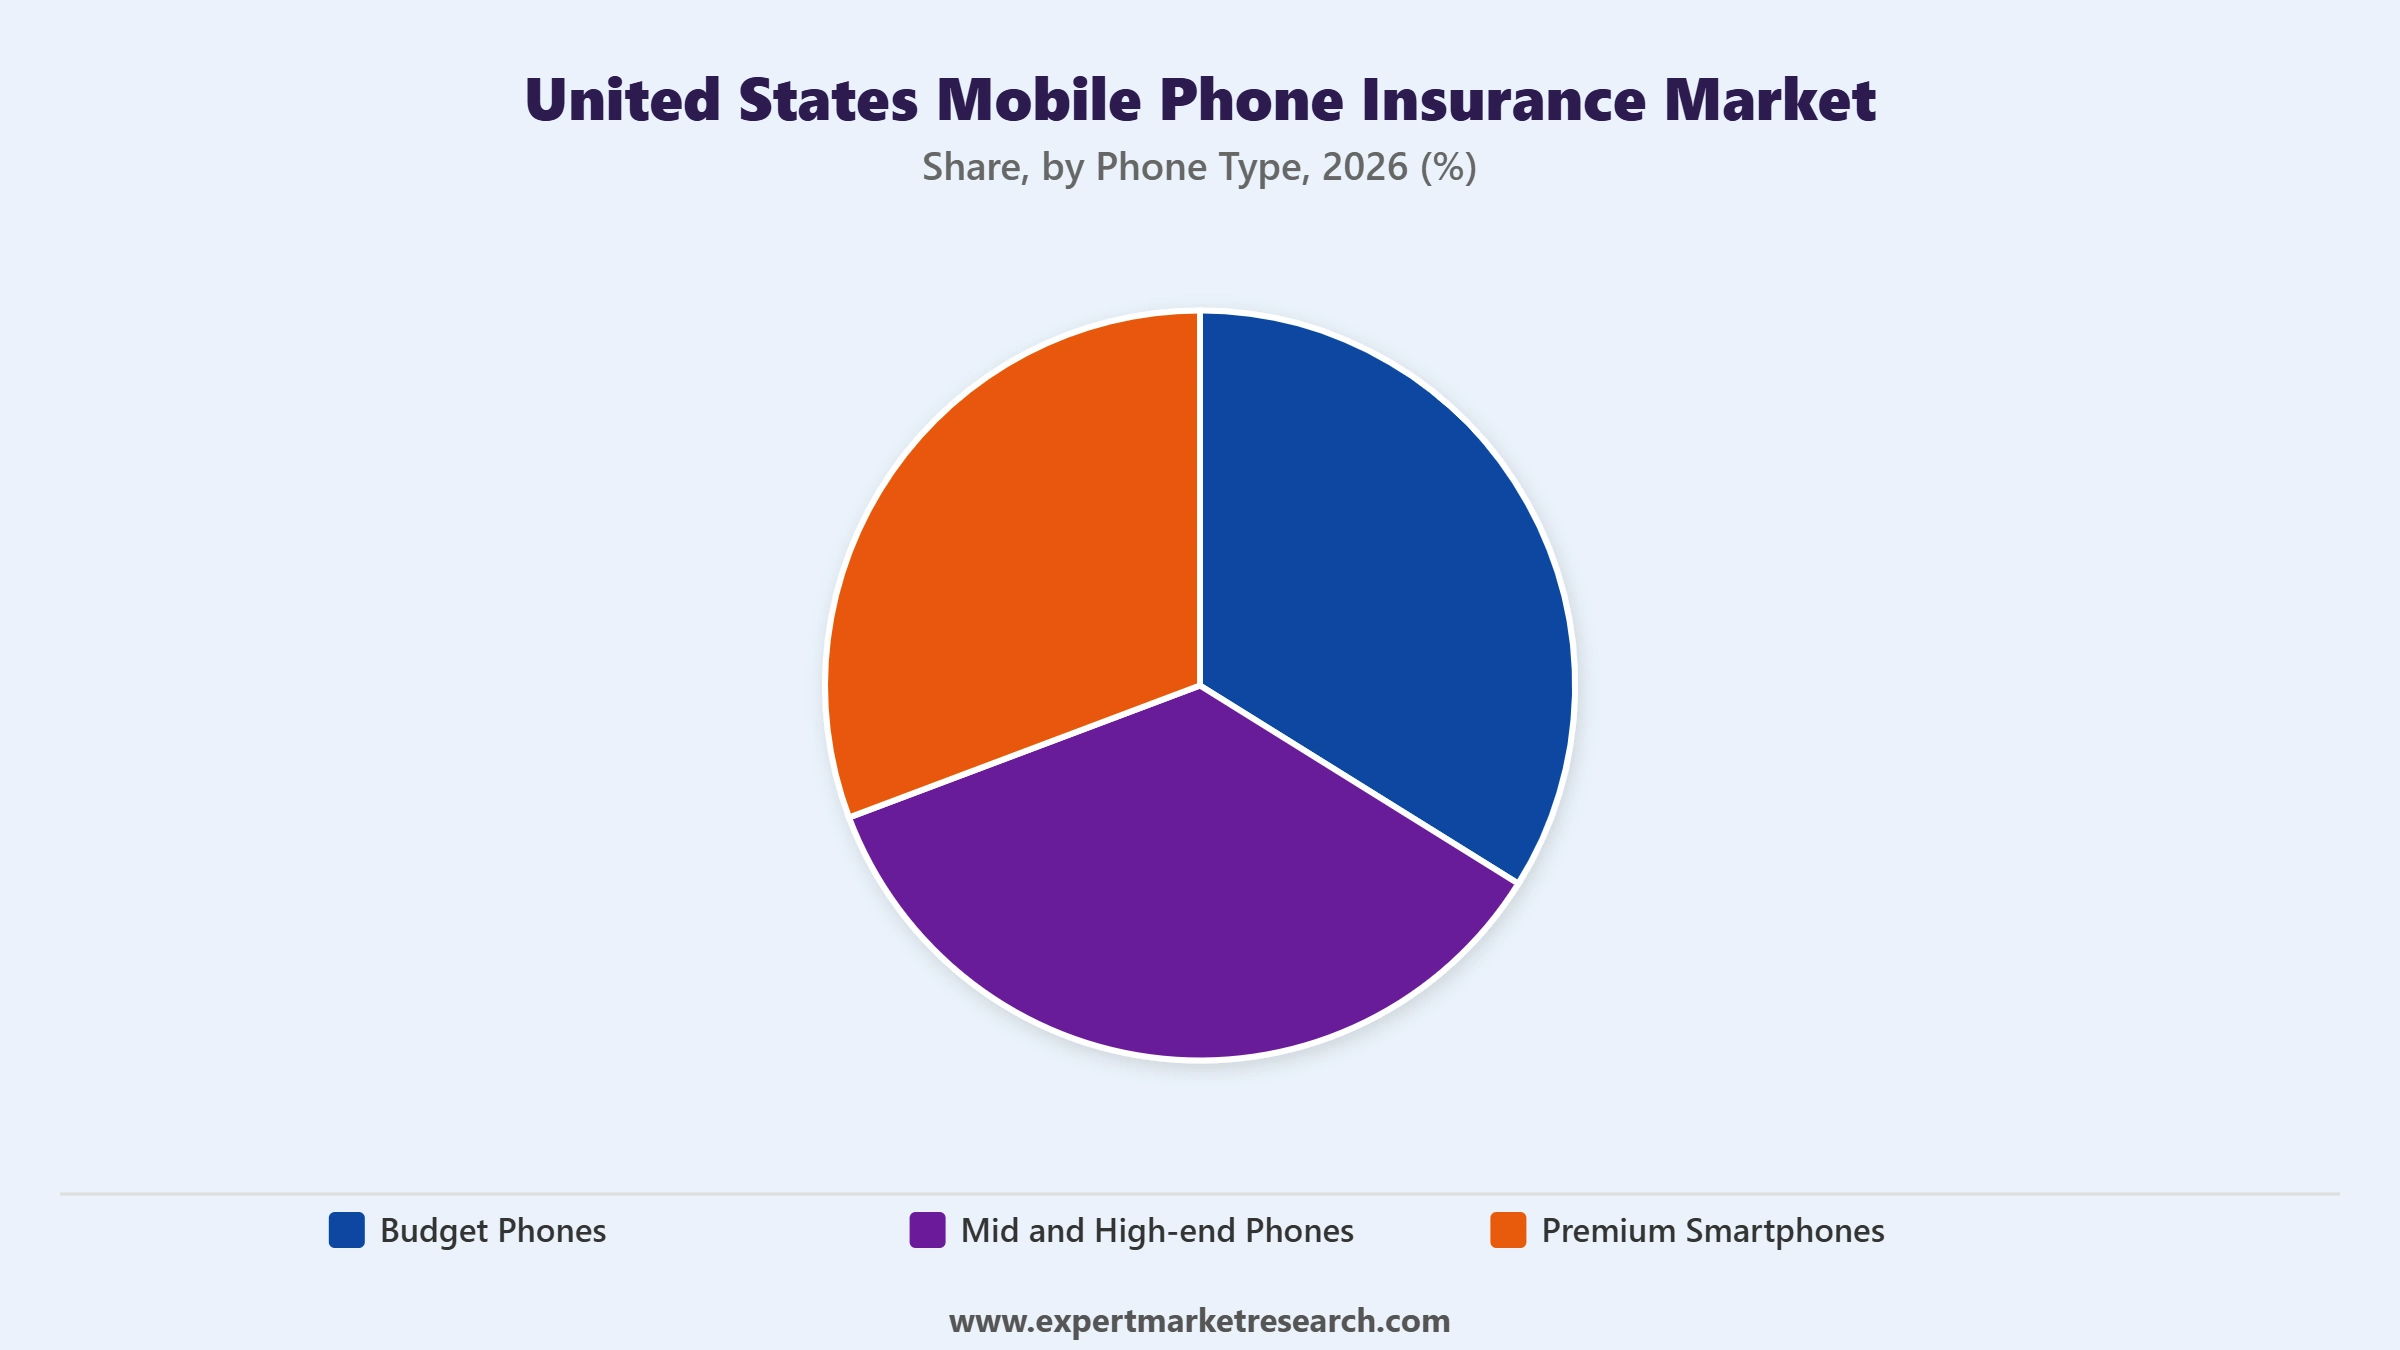
Key Insight: Premium smartphones hold a substantial phone type share in the United States mobile phone insurance market as their high replacement costs make comprehensive insurance coverage particularly valuable to device owners. Mid and high-end phones are registering steady growth as consumers increasingly seek protection for moderately priced devices with meaningful repair costs. As of January 2025, Samsung Care Plus began offering unlimited zero-dollar screen and back glass repairs on eligible Galaxy S devices, extending premium level benefits further into the mid-range segment. Budget phones represent a smaller but stable share of coverage demand, reflecting more limited replacement cost exposure for lower priced devices.
Market Breakup by Coverage Type
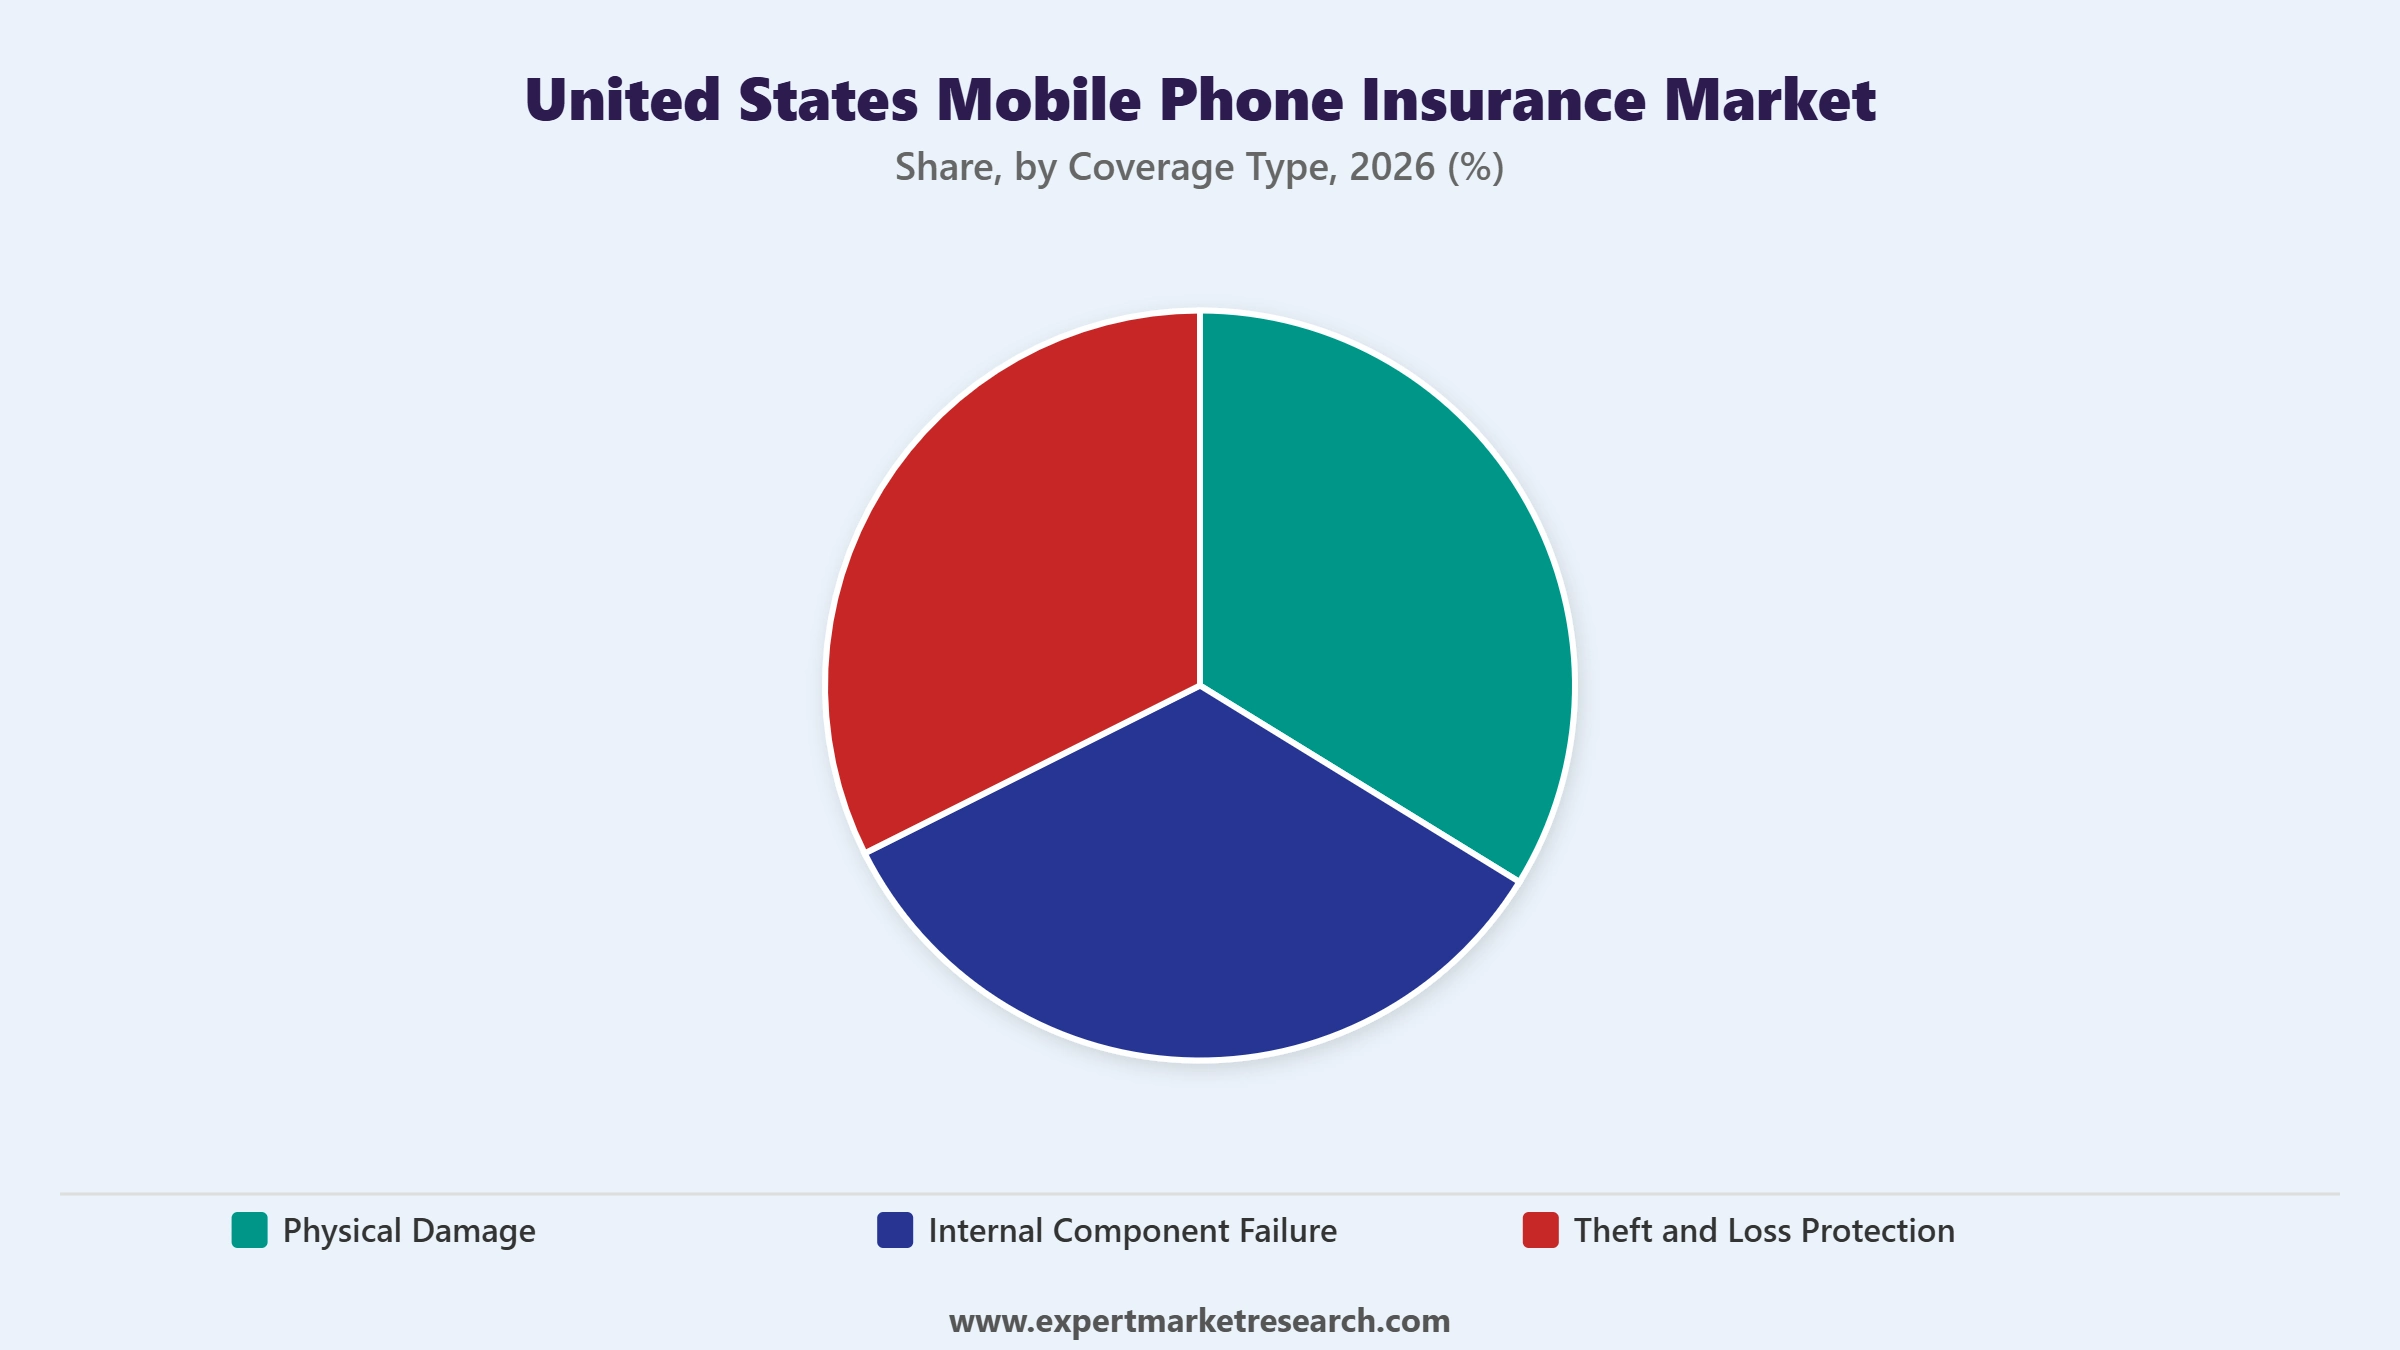
Key Insight: Physical damage coverage accounts for the largest coverage type share in the United States mobile phone insurance market as cracked screens and accidental drops remain the most common claim types among device owners. Theft and loss protection is registering the fastest growth as rising device values increase consumer concern over replacement costs following theft. Internal component failure coverage addresses mechanical and electrical breakdowns beyond manufacturer warranty periods, while other coverage types, including virus and data protection, round out remaining demand.
Market Breakup by Region
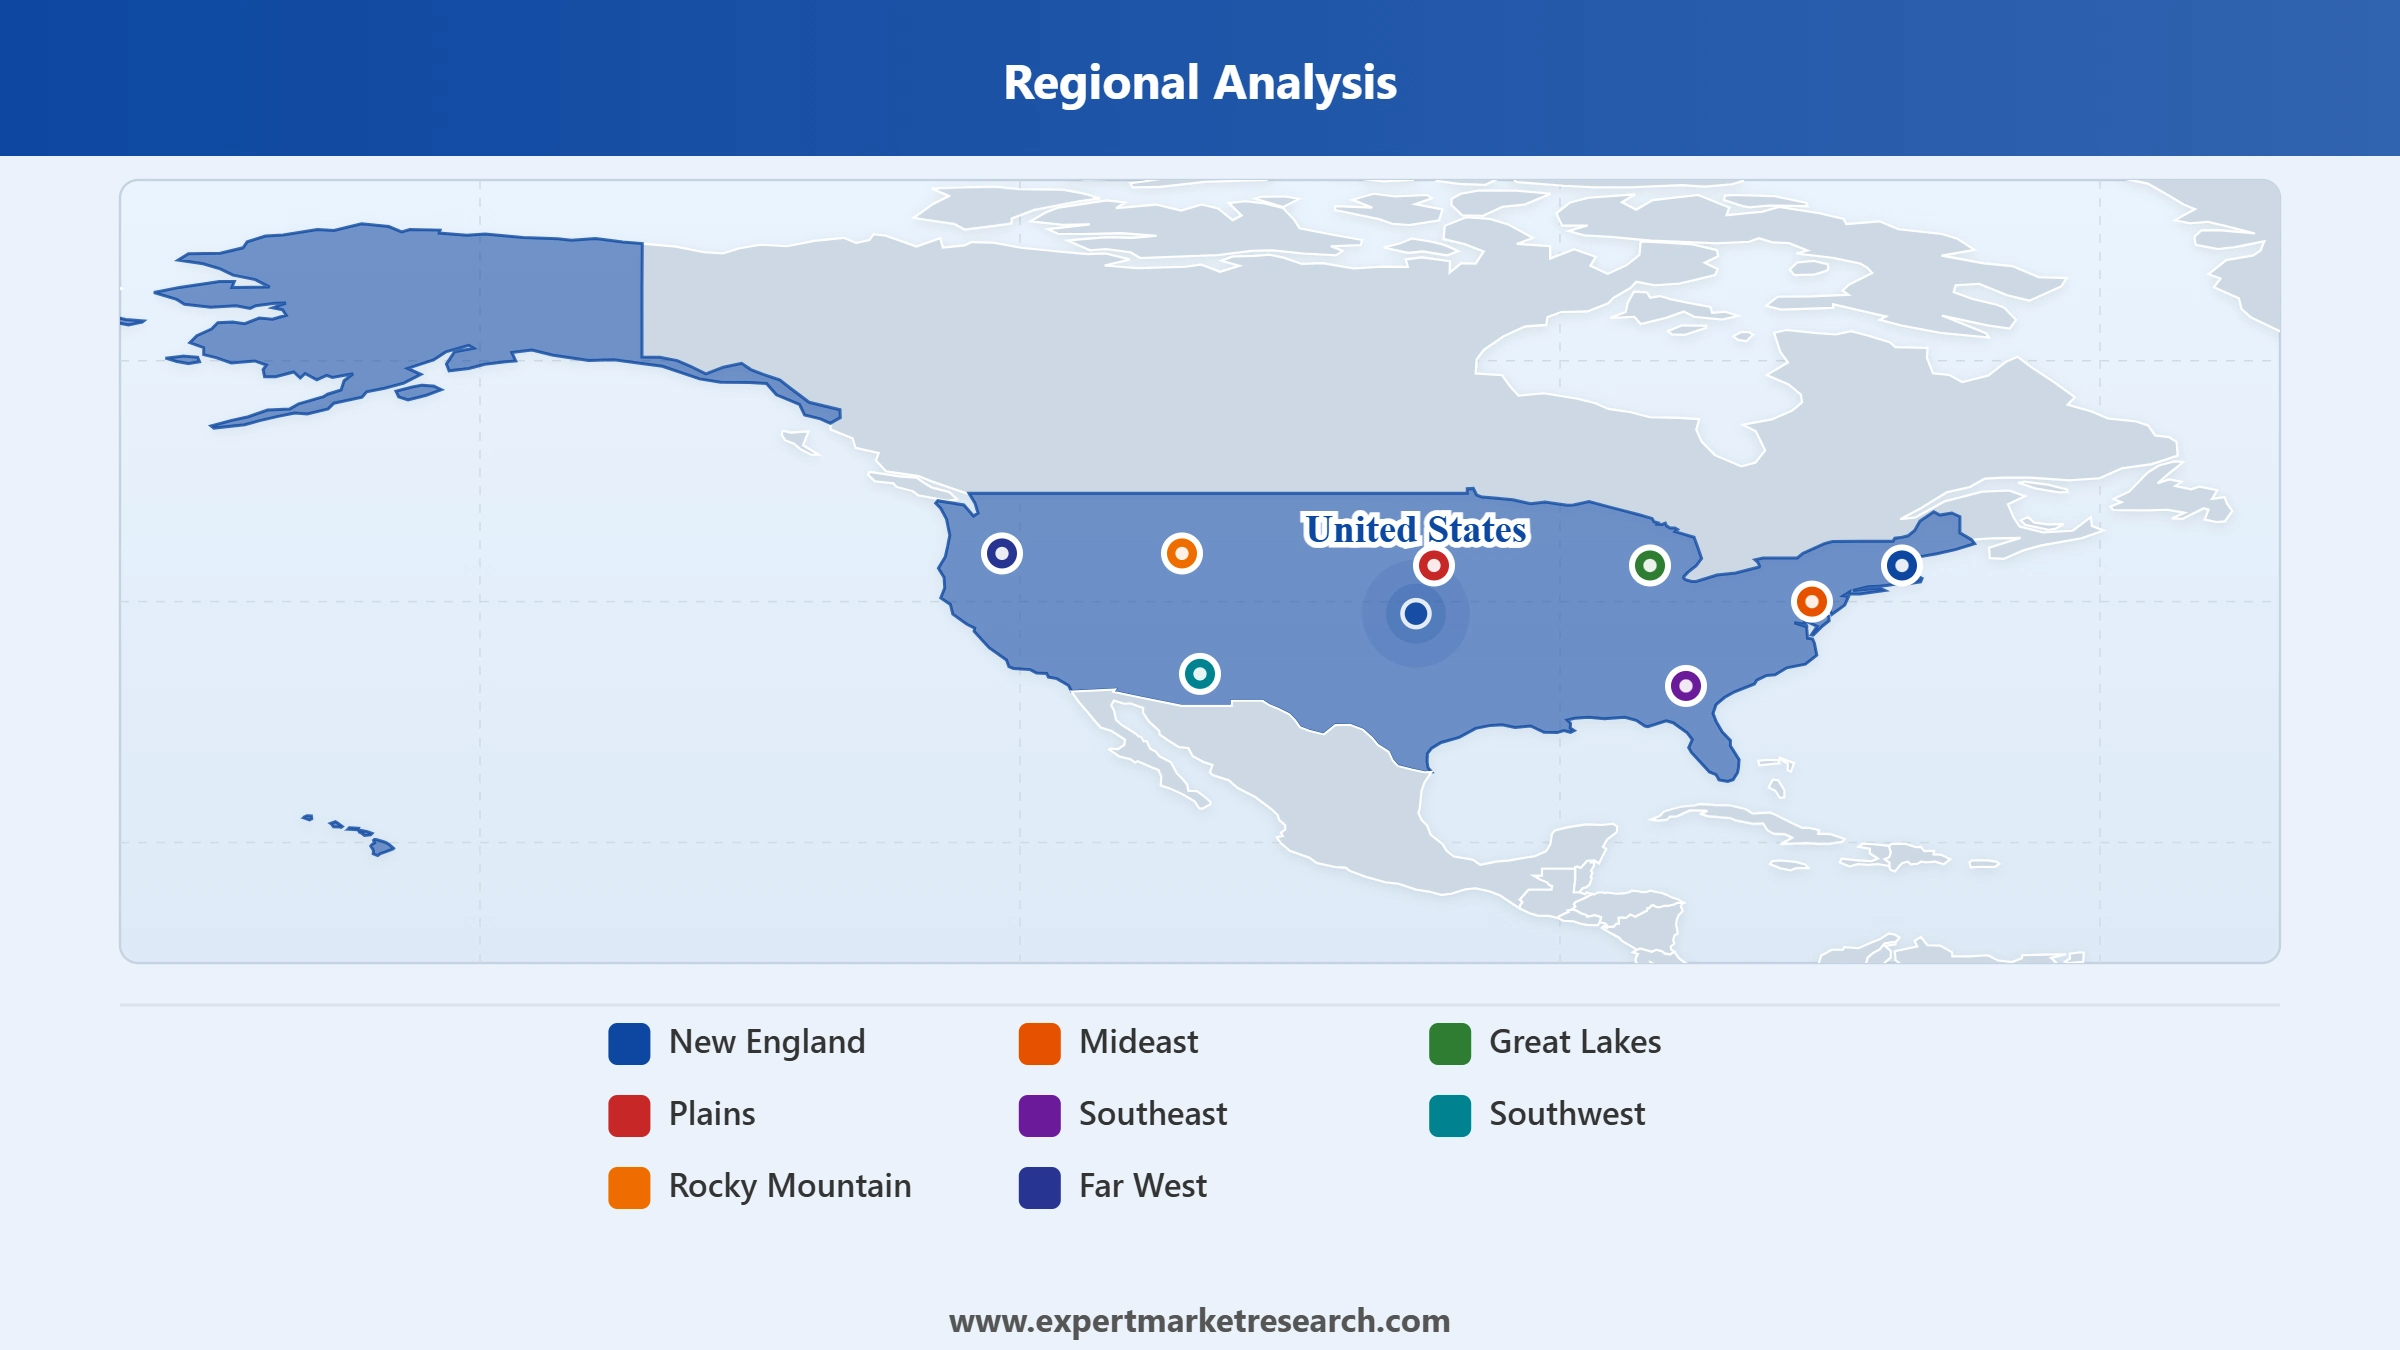
Key Insight: The Far West holds a substantial regional share in the United States mobile phone insurance market, supported by high smartphone penetration and strong consumer awareness of device protection across major metropolitan markets. The Southeast is registering strong growth as population expansion drives sustained smartphone adoption among new residents. The Southwest benefits from expanding wireless subscriber bases, while the Great Lakes and Mideast regions sustain steady demand from established urban populations. New England, Plains, and Rocky Mountain regions round out demand through smaller scale but consistent device protection adoption.
By phone type, premium smartphones dominate the market owing to their high replacement costs making comprehensive coverage particularly valuable
Premium smartphones dominate the phone type segment of the United States mobile phone insurance market owing to their high replacement costs, which make comprehensive insurance coverage particularly valuable to device owners and abroad today across every retail channel and distribution point. Providers serving this category continue to prioritise instant replacement guarantees accordingly, since premium device owners typically expect minimal downtime following a covered claim across every service channel and touchpoint available across every metropolitan market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Mid and high-end phones are registering steady growth across the United States mobile phone insurance market as consumers increasingly seek protection for moderately priced devices carrying meaningful repair costs relative to household budgets across every income tier and demographic segment nationwide. Through August 2025, regional carrier Cellcom ran an open enrollment window for its Allstate Total Coverage device protection plan, extending eligibility to existing customers who had previously declined coverage at the time of device purchase and activation.
By coverage type, physical damage protection accounts for the largest share owing to cracked screens and accidental drops remaining the most common claim types
Physical damage coverage accounts for the largest coverage type share of the United States mobile phone insurance market as cracked screens and accidental drops remain the most common claim types among device owners across every plan tier and price point nationwide. In January 2026, Boost Mobile discontinued bundled F-Secure Mobile Security from its Boost Protect plans, narrowing the offering to focus specifically on accidental damage and mechanical failure coverage for enrolled subscribers across every device category.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Theft and loss protection is registering the fastest coverage type growth across the United States mobile phone insurance market as rising device values increase consumer concern over replacement costs following theft or loss today across every device category and price segment nationwide. Effective February 2026, US Cellular introduced its new Device Protection Plus program, combining loss and theft insurance underwritten separately from its mechanical failure service contract for eligible enrolled customers every service region.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The Far West leads the market through high smartphone penetration and strong consumer awareness of device protection
The Far West holds a substantial share of the United States mobile phone insurance market, supported by high smartphone penetration and strong consumer awareness of device protection benefits across major metropolitan areas including Los Angeles and San Francisco and beyond the coastal corridor and surrounding valleys and communities. Providers serving this region continue to benefit from sustained demand tied to a large, technology engaged consumer base across the region's largest population centers and surrounding metropolitan communities across every market segment and demographic group.
The Mideast is strengthening its regional position as expanding regulatory clarity around wireless device protection plans improves consumer confidence in comprehensive coverage offerings across every major metropolitan market and surrounding suburban area and county. In April 2026, New York State Senate Bill S10081 advanced provisions requiring wireless equipment vendors to disclose standalone pricing for each protection product bundled into comprehensive coverage plans, building on the state's 2024 wireless equipment insurance law and regulatory framework overall and going forward.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The United States mobile phone insurance companies are becoming increasingly consolidated as major mobile phone insurance companies invest in digital claims platforms, expanded carrier partnerships, and broader device coverage to defend their market positions. Mobile phone insurance players are prioritising fast claims processing, retail repair network access, and flexible pricing to differentiate their offerings in a market where consumer expectations for convenience continue to rise. Strategic emphasis on bundled, multi device coverage is allowing them to capture growing demand from smartphone owners.
Major United States mobile phone insurance market players are also focusing on distribution partnerships, pursuing alliances with retail repair networks and wireless carriers to broaden physical service access and customer reach. Opportunities are emerging in low cost, digital first coverage for prepaid customers, as well as in multi device protection platforms extending beyond smartphones. Companies that successfully combine broad carrier partnerships with rapid claims processing and accessible repair networks are expected to strengthen their competitive position over the coming years.
Founded in 1976 and headquartered in Cupertino, California, United States, Apple Inc. supports the mobile phone insurance market through its AppleCare Plus protection plans covering accidental damage, theft, and loss for iPhone devices. The company continues to expand its device protection offerings alongside its hardware ecosystem. Apple draws on its extensive retail and service network to provide direct, in person device repair and replacement for covered customers.
Founded in 1983 and headquartered in Dallas, Texas, United States, AT&T Inc. supports the mobile phone insurance market through its bundled device protection plans offered alongside wireless service subscriptions. The company continues to expand network reliability initiatives that strengthen the value proposition of its protection offerings. AT&T draws on its carrier infrastructure to serve millions of wireless subscribers requiring accessible device coverage.
Founded in 1972 and headquartered in Stillwater, Oklahoma, United States, Worth Ave. Group supports the mobile phone insurance market through its electronic device insurance plans covering smartphones, tablets, and other consumer electronics. The company continues to expand its presence across educational institutions and small businesses. Worth Ave. Group draws on more than five decades of insurance industry expertise to serve individual consumers and organizations.
Founded in 1919 and headquartered in New York, New York, United States, American International Group supports the mobile phone insurance market through its broader property and casualty insurance portfolio serving consumers and businesses nationwide. The company continues to expand its specialty insurance offerings across multiple consumer electronics categories. AIG draws on more than a century of insurance industry expertise to serve customers across diverse coverage needs.
Other key players in the market include SquareTrade, Inc., Assurant, Inc., AKKO, LLC, and Asurion, LLC., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our United States mobile phone insurance market trends 2026 report. Discover regional growth patterns, coverage type adoption, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 12.35 Billion.
The market is projected to grow at a CAGR of 8.30% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach around USD 27.41 Billion by 2035.
Expanding digital claims platforms, pursuing retail repair network partnerships, introducing low-cost plans for prepaid customers, broadening multi device coverage options, and strengthening carrier partnerships ahead of rising smartphone adoption.
The key trends supporting the market expansion include rise in smartphone financing and lease programmes and increase in mobile phone ownership among the younger generation.
The market is broken down into New England, Mideast, Great Lakes, Plains, Southeast, Southwest, Rocky Mountain, and Far West.
Based on phone type, the market is divided into budget phones, mid and high-end phones, and premium smartphones.
The key players in the market include Apple Inc., AT&T Inc., Worth Ave. Group, L.L.C., American International Group, Inc., SquareTrade, Inc., Assurant, Inc., AKKO, LLC, and Asurion, LLC., among others.
Based on the coverage type, the market is divided into physical damage, internal component failure, theft and loss protection, and others.
Companies face rising costs of device repair parts, a shortage of certified repair technicians, high customer acquisition costs, and the ongoing challenge of managing fraud risk while maintaining fast, convenient claims processing.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Phone Type |
|
| Breakup by Coverage Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




