

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
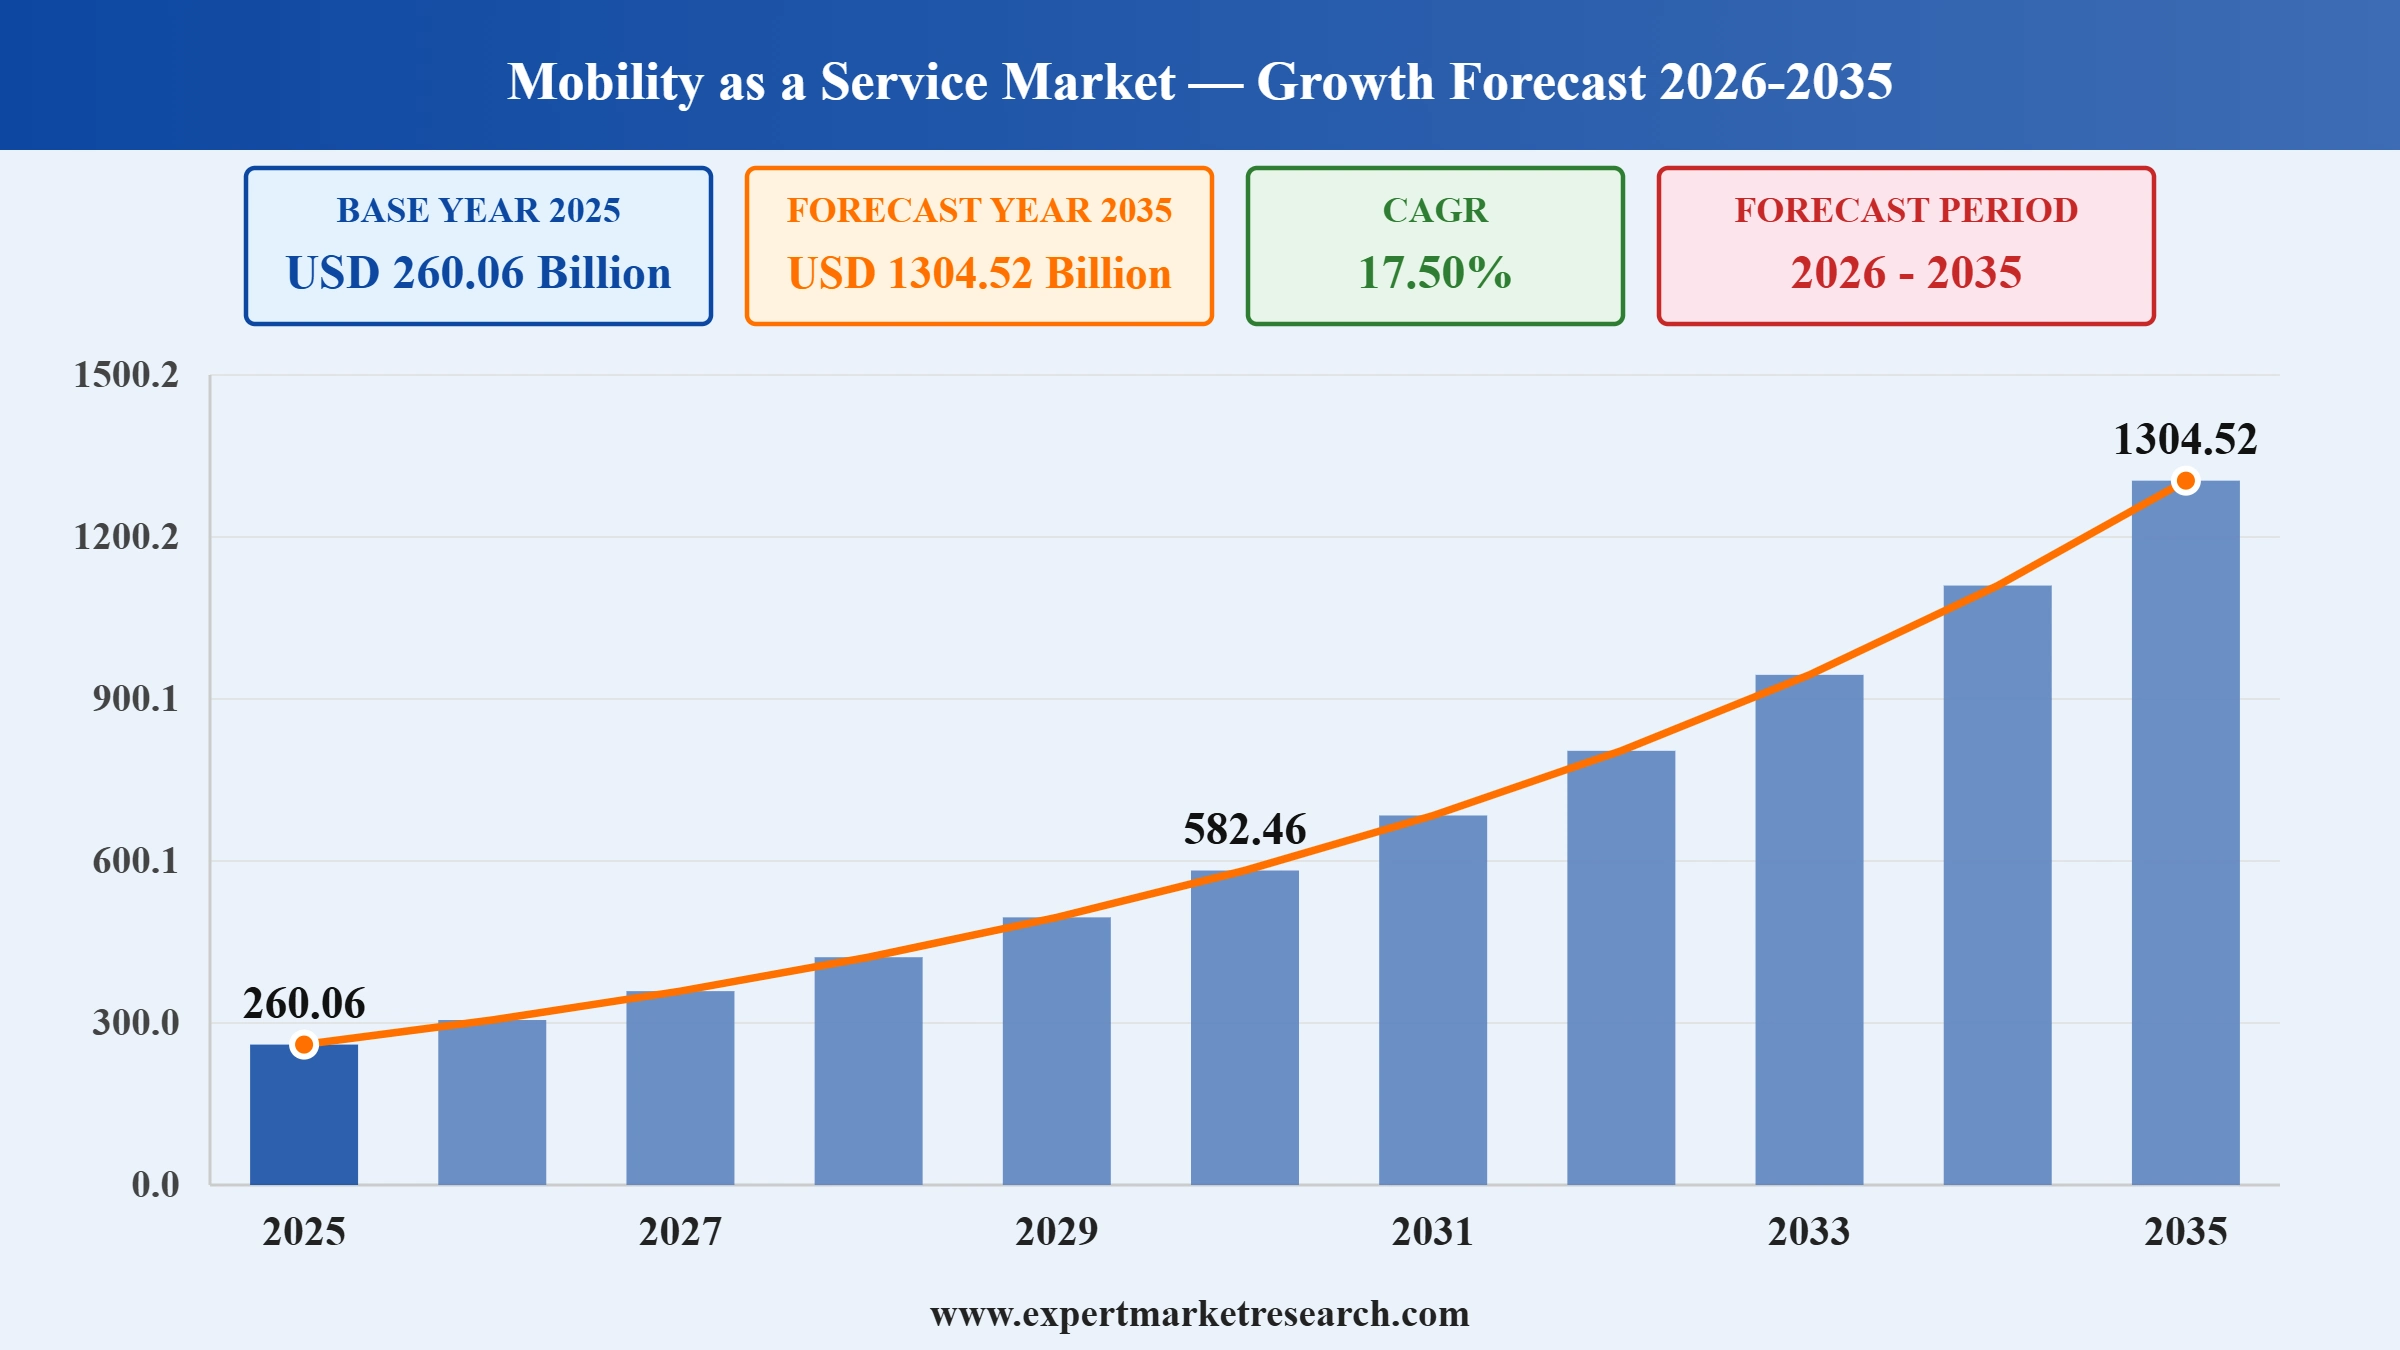
The global mobility as a service market attained a value of USD 260.06 Billion in 2025 and is projected to expand at a CAGR of 17.50% through 2035. The market is further expected to reach USD 1304.52 Billion by 2035. Rising urban congestion, growing smartphone penetration, and the shift toward integrated, app-based multimodal travel are propelling demand for unified journey planning, booking, and payment across ride hailing, micromobility, and public transit operators.
Urbanization and the resulting strain on road infrastructure are central to expansion of the mobility as a service market, as city planners increasingly favor shared and multimodal transport over private vehicle ownership. Municipal authorities across North America, Europe, and Asia Pacific are embedding open data and interoperability requirements into transit contracts, which is lowering the technical barriers for new entrants and encouraging established transit operators to open their networks to third-party journey planning applications. Growing federal and regional infrastructure funding is further accelerating this shift toward integrated, app-based mobility.
The mobility as a service market is also benefiting from expanding autonomous vehicle pilots, as transit agencies and private operators test driverless technology to extend service beyond traditional fixed routes and staffed operating hours. Regulatory bodies across major cities are opening pathways for supervised and unsupervised autonomous pilots, while operators continue refining safety protocols and public reporting standards. In October 2025, Berlin's BVG began operating five fully electric, Level 4 autonomous VW ID. Buzz minibuses across a 15 square kilometer zone in northwest Berlin under a EUR 9.5 million federally backed pilot, with passenger trials scheduled to begin in early 2026, illustrating how public operators are formally testing driverless last-mile connectivity.
Companies operating in the mobility as a service market are increasingly directing growth capital toward consolidating fragmented technology stacks rather than building every capability internally, favoring targeted acquisitions of complementary fleet management, ticketing, and journey-planning software over slower organic development. This consolidation trend is particularly visible among software vendors serving public transit agencies and corporate mobility programs, which continue to expand their agency relationships through acquisition rather than competing purely on new business development. In July 2025, Transit Technologies acquired commuter transportation platform TripShot to broaden its fleet management and shuttle-orchestration capabilities, reflecting this wider pattern of consolidation across the industry.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Lime partnered with the City of Bellevue to launch 500 shared e-bikes, e-scooters, and seated gliders, reintroducing electric micromobility after a prior operating gap. The rollout gives commuters an affordable first- and last-mile option. Operators can use phased municipal partnerships to rebuild ridership and strengthen coverage across the mobility as a service market.
BCAA's Evolve E-Bike and E-Scooter Share expanded into Colwood, distributing 60 new e-bikes and e-scooters across 15 parking stations. The expansion gives residents a flexible way to reach transit exchanges and university sites. Operators can pair phased station rollouts with existing fleets to extend coverage across the mobility as a service market.
NAVEE unveiled a broader product range at CES 2026, including a high-speed electric scooter, an AI-powered golf cart, and an off-road electric dirt bike, marking a strategic expansion beyond urban micromobility. The launch reflects heavy research and development investment and a growing patent portfolio. Manufacturers can use adjacent categories to diversify revenue.
Baidu's Apollo Go announced plans to expand its autonomous ride-hailing service into Europe, beginning with Switzerland testing ahead of broader deployment planned for 2026 and 2027. The move signals growing operator in the mobility as a service market confidence in driverless fleets as a scalable service layer. Companies can use staged testing to validate autonomous technology before commercial rollout.
Car-sharing services are increasingly being layered onto existing micromobility apps rather than launched as standalone products, letting operators cross-sell services to an existing user base instead of building acquisition channels from scratch. This bundling approach lets riders in the mobility as a service market manage several transport modes without switching accounts, particularly in dense urban markets already served by e-scooters and e-bikes. In February 2026, iPakket Corporation launched Ride by iPakett's car-sharing service in New York City, integrating vehicle access directly into its existing e-scooter and e-bike app to create a single, unified urban mobility platform for Manhattan riders.
Electric two-wheeler manufacturers are increasingly pursuing geographic diversification to offset saturation in home markets, investing heavily in research, manufacturing capacity, and patent portfolios to support entry into new regions. This shift is particularly visible among Asian manufacturers of the mobility as a service market targeting the North American e-bike market, where shared and personal micromobility demand continues to climb. In early 2026, Yadea expanded its presence in the North American e-bike market, backed by substantial research and development investment and a broad global patent portfolio, supporting wider availability of electric micromobility vehicles for shared fleets.
Consolidation among software vendors serving public transit agencies has accelerated as operators look to offer broader, end-to-end capabilities rather than point solutions for ticketing or scheduling alone. Larger transit-technology groups are acquiring specialized units from established players to expand their agency relationships and technical footprint quickly. In May 2026, Modaxo agreed to acquire Conduent's public transit business in a USD 164 million transaction, expected to close before the end of 2026, extending Modaxo's reach across fare collection, scheduling, and transit operations software for public agencies.
Municipal governments are increasingly running competitive proposal processes to select shared micromobility operators in the mobility as a service market, replacing informal or single-vendor arrangements with structured, multi-year procurement cycles. These processes typically weigh safety records, fleet management practices, and community engagement alongside pricing. After a competitive proposal process in early 2026, the City of Boulder selected Lime for renewal of its shared e-scooter operating contract, while also moving to award a separate bike-share contract to BCycle in mid-2026, reflecting continued municipal reliance on structured, multi-operator procurement.
Shared micromobility usage data collected across major North American cities in the mobility as a service market offers one of the clearest indicators of underlying demand for last-mile and short urban trips, independent of any single operator's performance. Industry associations track this ridership data annually to benchmark growth across member cities. According to NACTO's 2025 Trends report, shared e-scooter trips across NACTO member cities rose 29 percent year-over-year, climbing from approximately 45 million trips in 2024 to 58 million trips in 2025, underscoring sustained rider demand for short, on-demand urban trips.
The Expert Market Research's report titled “Mobility as a Service Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Service Type
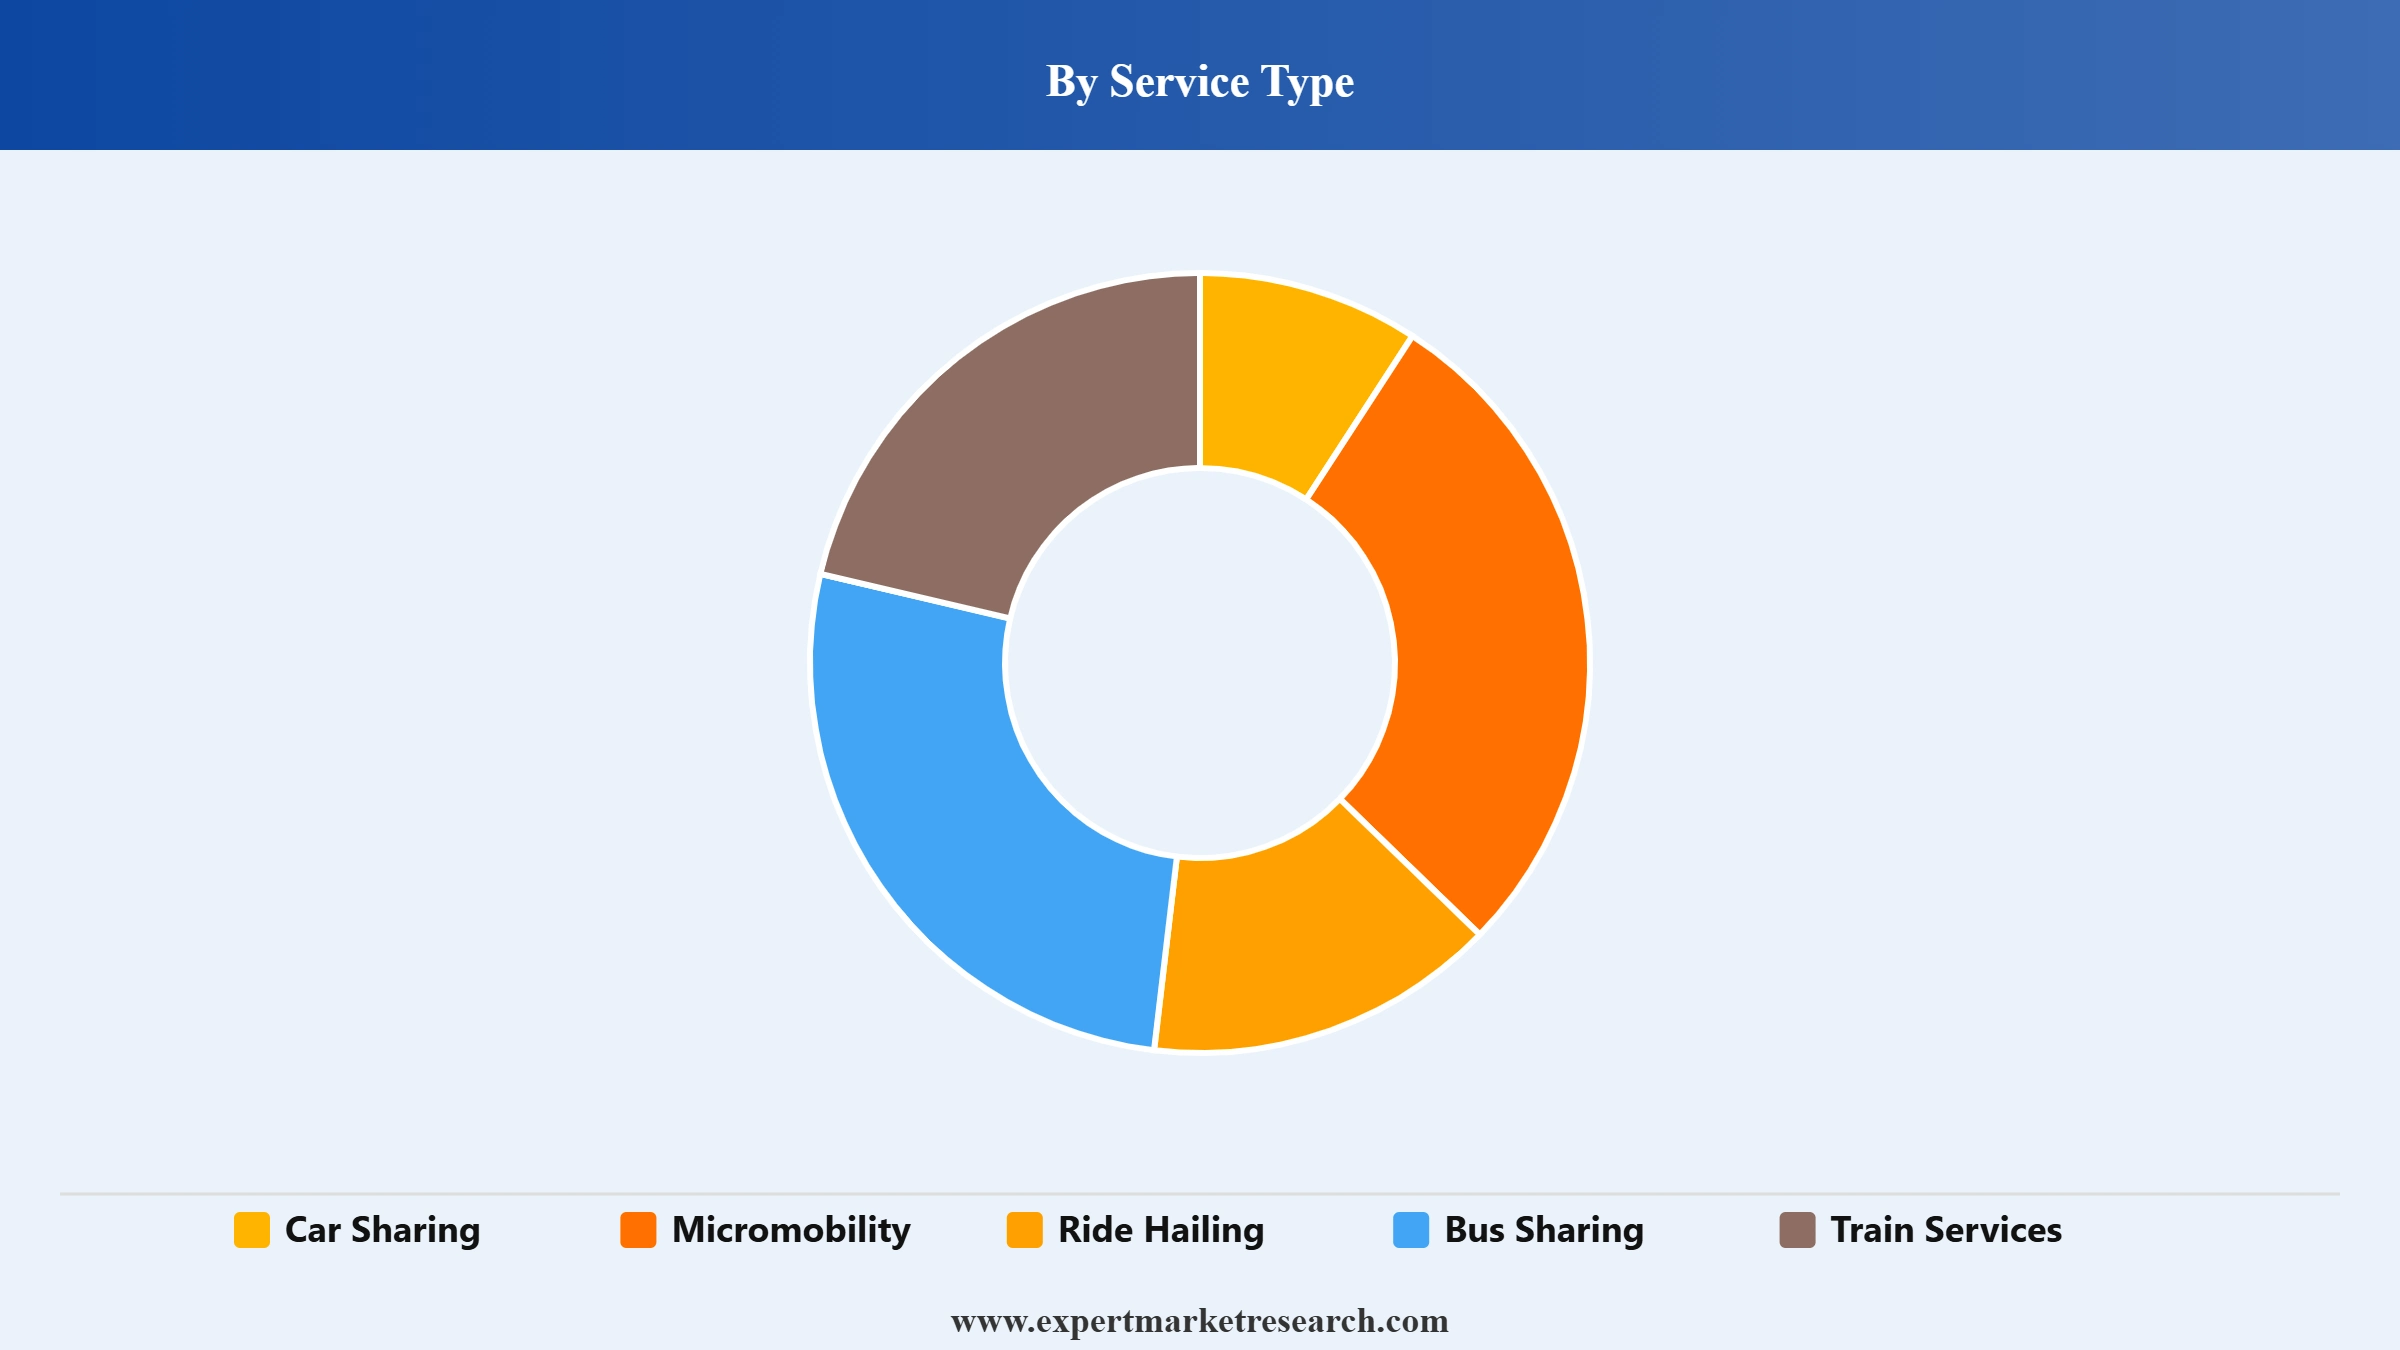
Key Insight: Ride hailing continues to draw the largest base of daily users in the mobility as a service market given its convenience and broad driver availability, while micromobility is expanding quickly as cities add dedicated bike and scooter infrastructure. Car sharing appeals to riders needing occasional vehicle access without ownership costs, bus sharing supports structured commuter routes in suburban corridors, and train services remain central to long-distance and intercity journeys. In April 2026, Forest secured a further EUR 31 million in Series B funding to expand shared e-bike operations across London, while Berlin-based Nox Mobility raised EUR 2 million in pre-seed funding the same month to prepare initial night-train routes planned for 2027, illustrating investment activity spanning both the micromobility and train services subsegments.
Market Breakup by Solution Type
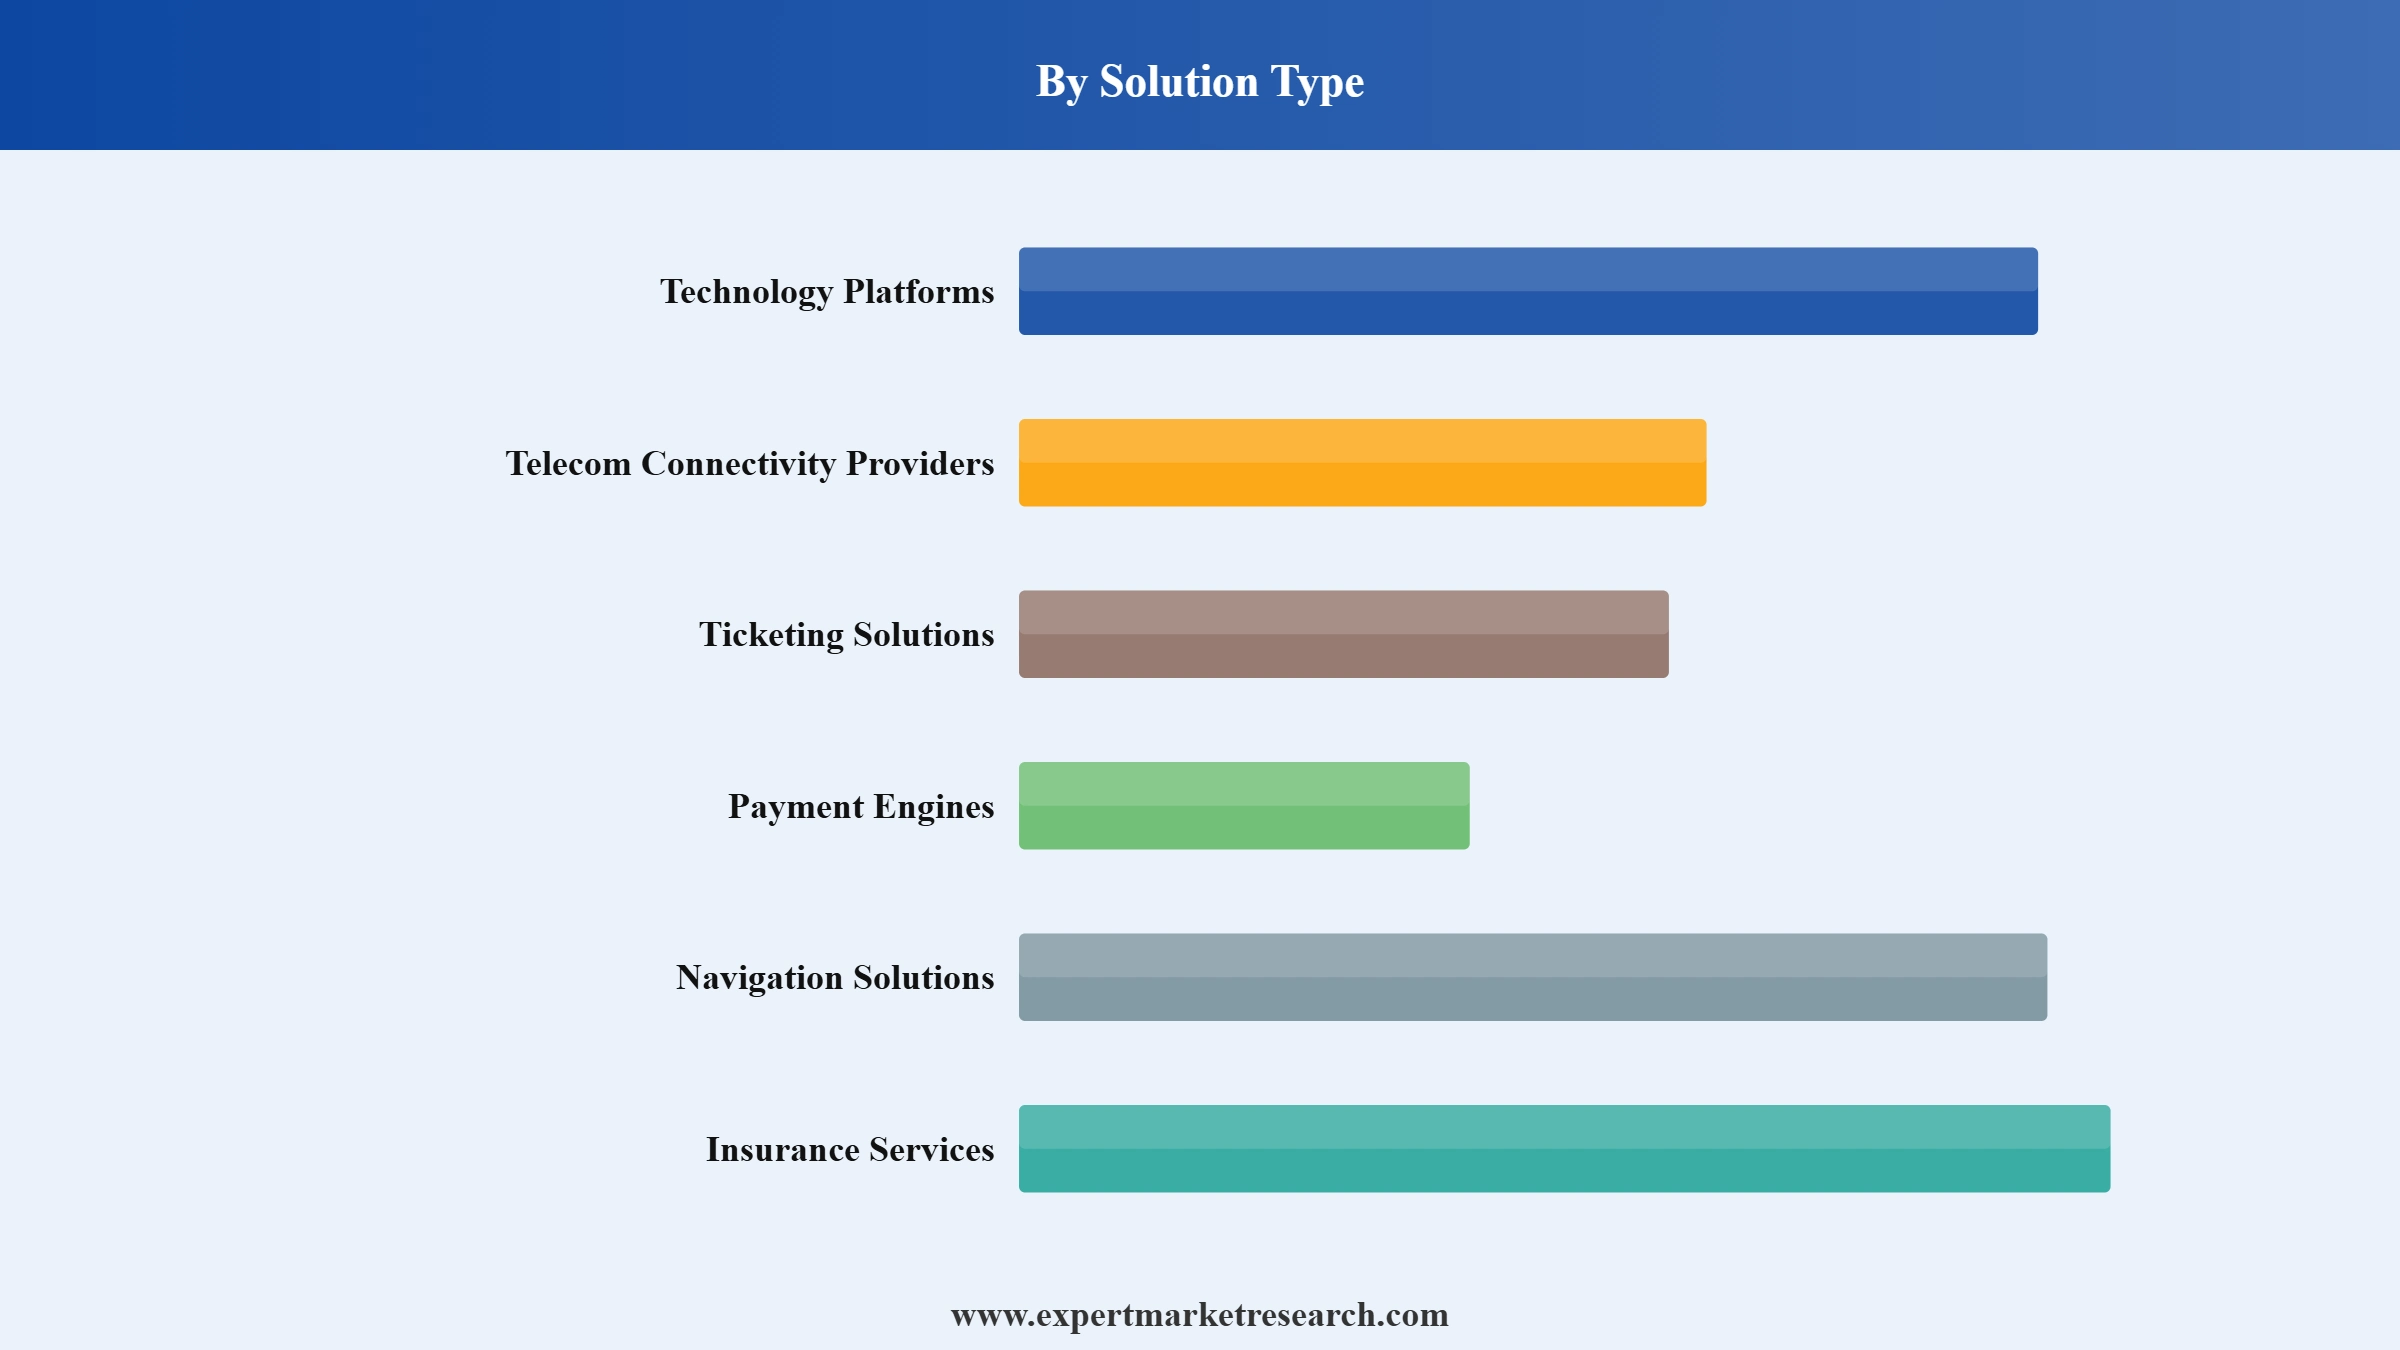
Key Insight: Technology platforms anchor most multimodal offerings by unifying routing, booking, and analytics in a single interface, while payment engines are becoming increasingly important as riders expect a single account across modes. Ticketing solutions streamline fare validation across bus, rail, and shared vehicle services, telecom connectivity providers keep real-time tracking reliable, navigation solutions support accurate routing, and insurance services are increasingly bundled into subscription packages. In April 2026, autonomous driving technology developer Wayve raised a EUR 1 billion Series D round to advance its AI-driven platform, and in November 2025 Siemens Mobility announced a partnership with a regional transit commission to deliver one of the first fully integrated regional mobility as a service platform in its market.
Market Breakup by Transportation Type
Key Insight: Public transportation remains the backbone of most integrated offerings in the mobility as a service market, carrying the largest share of daily multimodal trips, while private transportation, spanning ride hailing, car sharing, and emerging autonomous services, is growing quickly as riders seek flexible, on-demand alternatives to fixed-route travel. In November 2025, May Mobility launched its first commercial driver-out autonomous transport service in Peachtree Corners, and around the same period ALSO, a Palo Alto-based micromobility company, raised USD 200 million in Series C funding alongside a strategic partnership with DoorDash to develop autonomous last-mile delivery, both illustrating growing investment in private, on-demand mobility.
Market Breakup by Vehicle Type
Key Insight: Four-wheelers dominate vehicle-type usage given their central role in ride hailing and car sharing, while micromobility vehicles are seeing the fastest fleet growth as cities expand cycling and scooter infrastructure. Buses continue to serve high-capacity commuter corridors, and trains remain essential for longer regional and intercity journeys. In 2026, London-based GIN e-bikes raised EUR 215,000 in debt funding to purchase 160 new electric bicycles and expand its PLUTO e-bike subscription service, while in April 2025 LG Energy Solution entered a joint venture with Derichebourg Multiservices to strengthen closed-loop battery recycling for electric vehicle fleets in Europe.
Market Breakup by Application
Key Insight: Journey planning tools remain the most widely used application in the mobility as a service market, helping riders compare routes, costs, and travel times across modes before departure, while flexible payments and transactions are growing quickly as unified fare accounts spread across transit systems. Personalised application services tailor route and mode suggestions to individual rider preferences, and journey management tools help riders adjust plans in real time when delays occur. In August 2025, Siemens Mobility launched its HAFAS NextGen app, offering faster journey planning, real-time assistance, and customizable features for transport operators, reflecting continued investment in personalized, AI-enhanced trip planning.
Market Breakup by Region
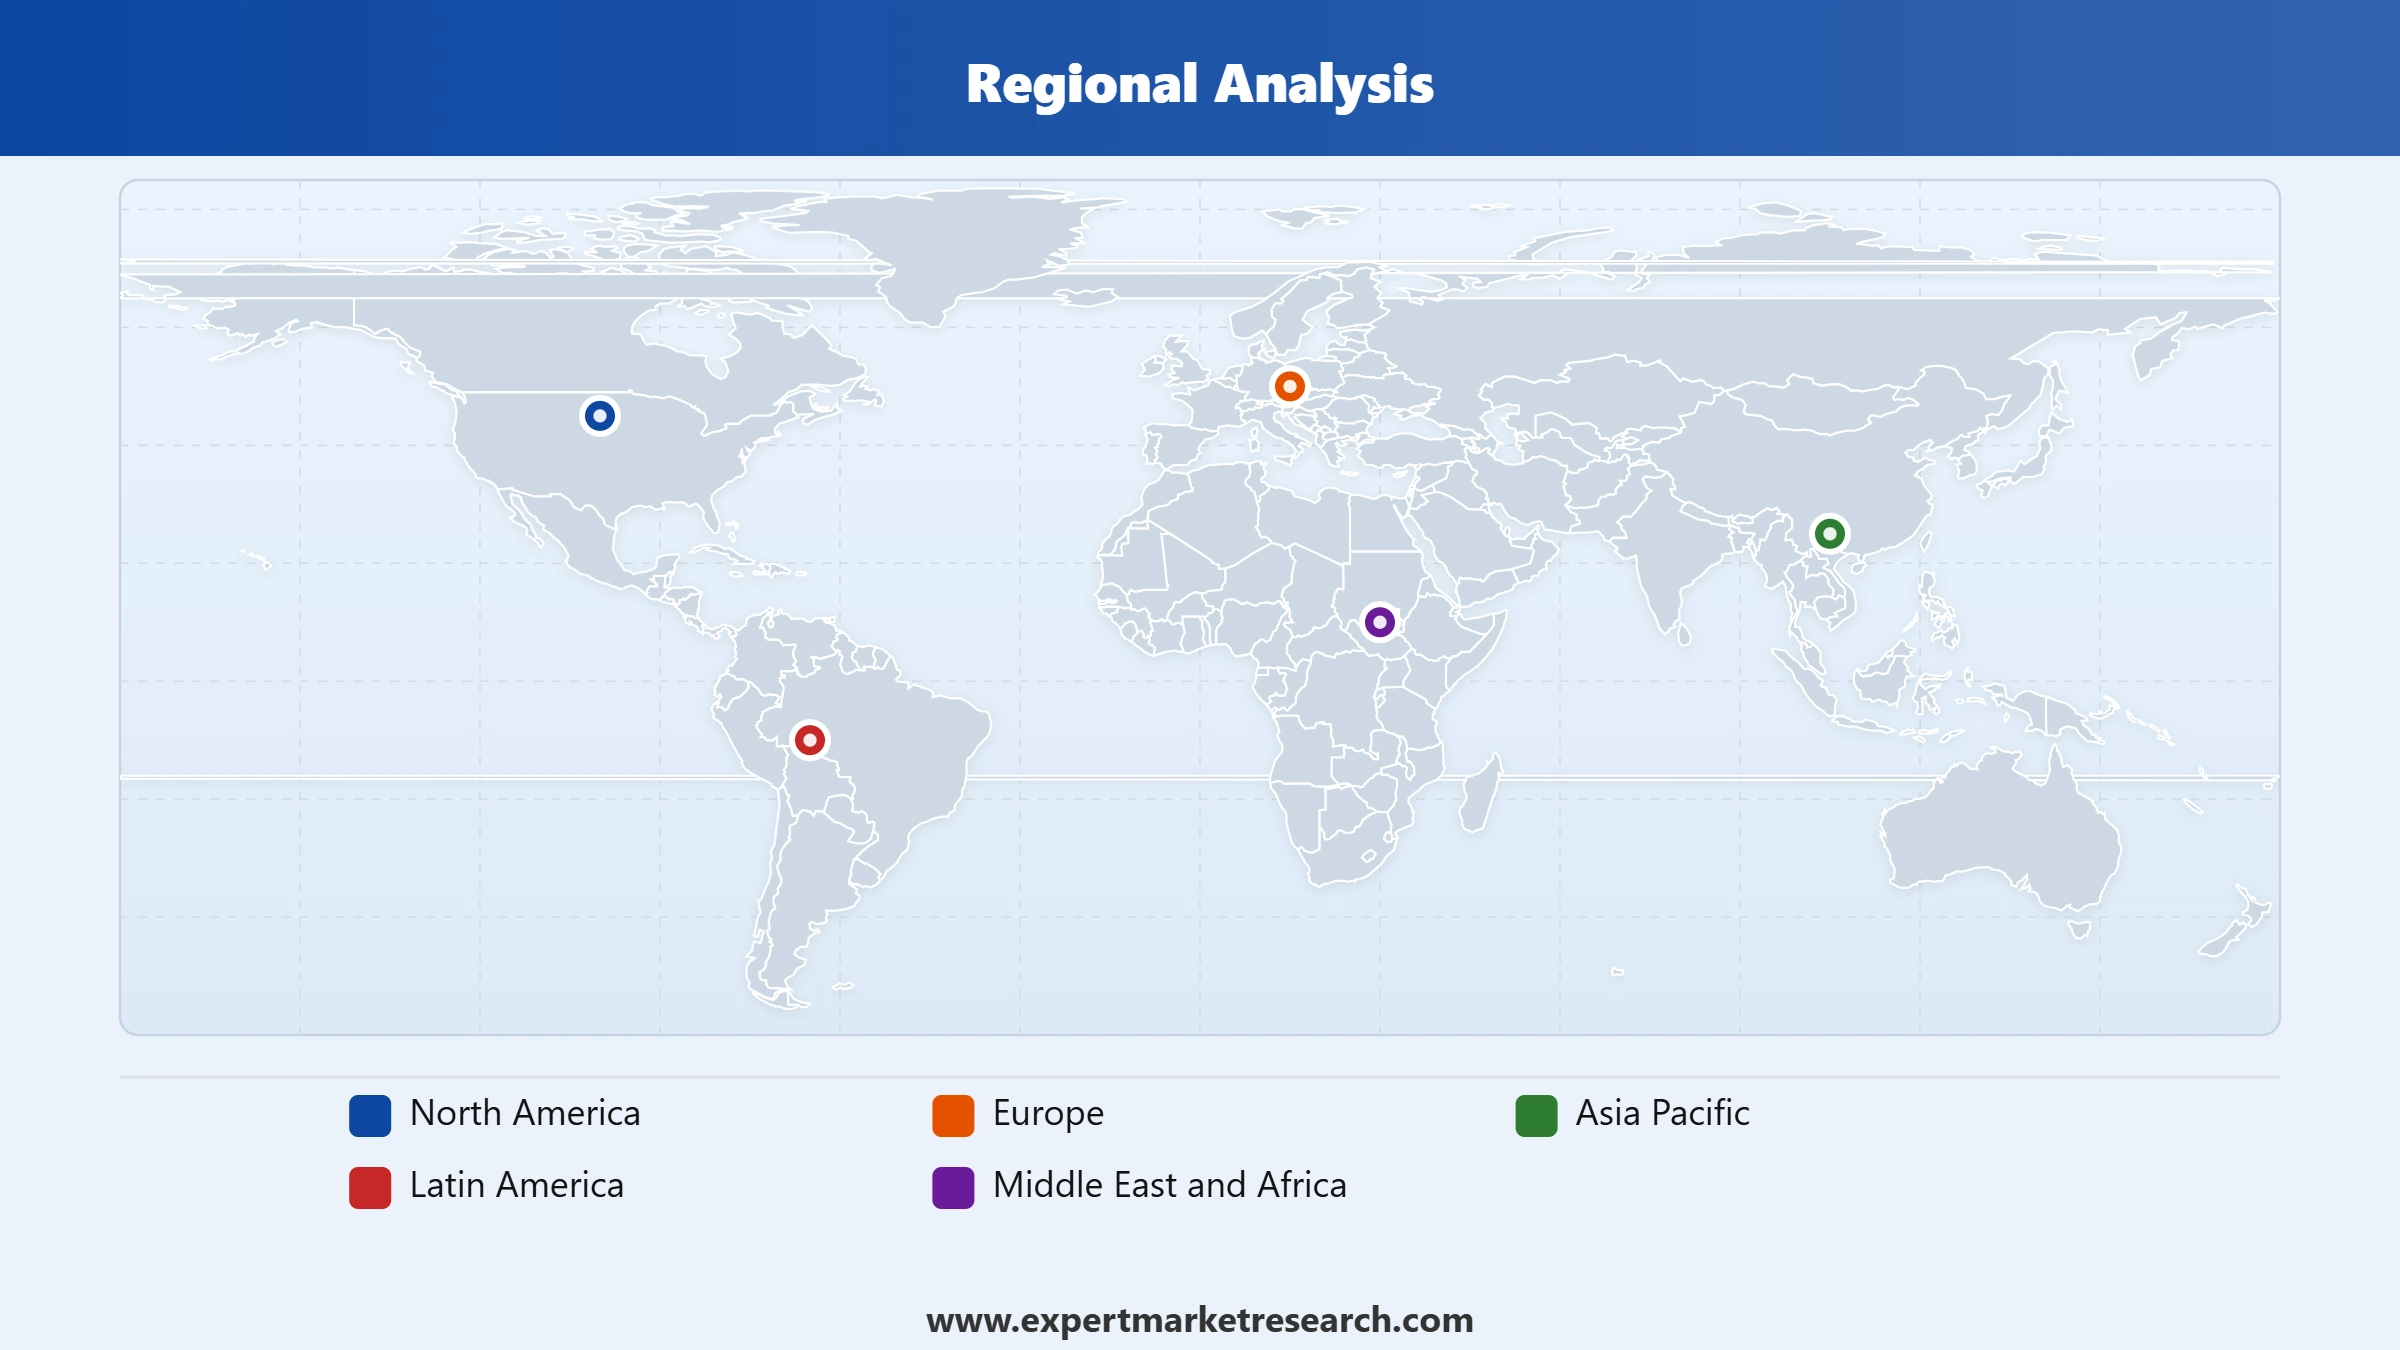
Key Insight: North America leads regional adoption on the strength of mature ride-hailing ecosystems and established transit-technology vendors, while Asia Pacific is expanding fastest as smart city programs and smartphone-based payments extend multimodal access to new metropolitan areas. In March 2026, the Japan-India Mobility Summit convened government and industry leaders to advance a Next-Generation Mobility Partnership covering digital and smart mobility, including mobility as a service and battery as a service.Europe benefits from strong regulatory support for interoperable, low-emission transport, Latin America is expanding shared micromobility and ride-hailing access in dense urban centers, and the Middle East and Africa are gradually building integrated ticketing and payment infrastructure,
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By service type, ride hailing dominates the market through extensive driver networks and deep app integration
Ride hailing holds the largest share of the mobility as a service market, supported by extensive driver networks, high smartphone penetration, and deep integration with broader multimodal apps that make it the anchor service around which car sharing and micromobility are bundled. This scale advantage is difficult for newer entrants to replicate quickly. Established operators continue investing in AI-based dispatching to widen this lead. In February 2026, DiDi Global expanded its AI-powered dispatching and traffic-prediction platform across major Chinese cities, cutting wait times and improving ride allocation efficiency for both drivers and riders.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Micromobility is the fastest-growing service type within the mobility as a service market, driven by rising demand for affordable, convenient first- and last-mile connectivity in dense urban corridors where parking and congestion make private vehicle use impractical. Cities across North America, Europe, and Asia Pacific continue expanding dedicated cycling and scooter infrastructure. Operators are expanding electric fleets and diversifying vehicle formats to capture this demand as adoption widens. In July 2026, Veo launched its Rover trike across Denver, introducing a stable, accessible micromobility option designed to serve a wider range of riders.
By solution type, technology platforms dominate the market through unified routing, booking, and analytics
Technology platforms account for the leading share of the mobility as a service market by solution type, reflecting strong demand for software that unifies routing, booking, fare payment, and analytics into a single rider-facing interface. This kind of unified interface improves rider retention and reduces friction from switching between separate apps. Journey-planning applications are increasingly layering AI features onto existing transit data feeds to offer personalized route recommendations. In spring 2026, Citymapper rolled out AI-powered journey assistant features that combine live transit data with personalized recommendations based on a rider's travel history.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Payment engines represent the fastest-growing solution type within the mobility as a service market, supported by rising rider demand for contactless, tokenized fare collection that removes the need for separate transit cards or cash payments. Legacy card-based systems are increasingly viewed as a barrier to ridership growth, particularly among riders accustomed to tap-to-pay elsewhere. Transit agencies are partnering with specialized payment technology vendors to modernize legacy fare systems rather than building replacement infrastructure internally. In 2025, Masabi launched its Open Payments system with Denver's Regional Transportation District, enabling riders to tap a bank card or mobile wallet directly at fare validators.
By transportation type, public transportation leads as the backbone of daily multimodal trips on policy-anchored integration
Public transportation continues to lead the mobility as a service market by transportation type, as transit agencies remain the structural backbone of most integrated mobility offerings and carry the largest share of daily multimodal trips. Public operators benefit from established route networks and typically lower per-trip costs for riders compared with private alternatives. Agencies are refreshing rider-facing technology, adding real-time tracking and unified trip planning to match the convenience riders expect from private-sector apps. In May 2026, Broward County Transit relaunched its RideBCT app with real-time vehicle tracking and unified trip planning across bus routes.
Private transportation is expanding at the fastest pace within the mobility as a service market by transportation type, fueled by growing consumer interest in on-demand and increasingly autonomous alternatives to fixed-route public transit. Riders are showing a willingness to pay a premium for the convenience and door-to-door service that private options provide. Autonomous vehicle operators are actively pursuing regulatory approval to expand private ride services into new metropolitan markets. In February 2025, Tesla sought regulatory approval to offer ride-hailing services in California, positioning the company to compete with established autonomous ride-hailing operators.
By vehicle type, four-wheelers dominate the market through their central role in ride hailing and car sharing
Four-wheelers hold the dominant share of the mobility as a service market by vehicle type, given their central role in ride hailing, car sharing, and private transportation across both dense urban centers and lower-density suburban markets where other vehicle types are less practical. Four-wheelers also carry a disproportionate share of longer trips and trips involving multiple passengers. Fleet operators are accelerating electrification of four-wheeler fleets to meet emissions targets and lower per-trip operating costs. In March 2025, Uber partnered with Refex Green Mobility to deploy 1,000 electric vehicles across its India fleet.
Micromobility is growing at the fastest rate within the mobility as a service market by vehicle type, supported by continued investment in e-bike and e-scooter fleets across major cities in North America, Europe, and increasingly Asia Pacific. Falling battery costs have made these fleets more cost-effective to operate at scale than in prior years. Operators are scaling fleet size ahead of seasonal demand peaks to capture ridership before competitors expand coverage. In April 2026, Dott deployed 45,000 new e-bikes and e-scooters across major European cities, including Helsinki, expanding shared micromobility capacity ahead of peak summer demand.
By application, journey planning leads as riders compare routes and costs before traveling
Journey planning accounts for the largest share of the mobility as a service market by application, as riders rely on integrated trip-planning tools to compare routes, transport modes, and total costs before beginning a journey. This category typically serves as the entry point into a broader mobility platform, driving downstream use of booking and payment features. Transit apps are increasingly opening their AI-enhanced planning tools to public GTFS-RT data feeds to widen adoption among agencies. In spring 2026, the Transit app began integrating AI-driven predictions into the Toronto Transit Commission's open GTFS-RT feed, improving the accuracy of real-time arrival estimates.
Flexible payments and transactions represent the fastest-growing application category within the mobility as a service market, as riders increasingly expect a single account and payment method to cover fares across every transport mode they use. This shift reflects broader consumer payment behavior outside of transportation, where tap-to-pay wallets have become the default expectation. Regional transit operators are launching unified payment apps that consolidate fare collection across multiple services. In 2026, Sacramento Regional Transit introduced its Transit Connect App, consolidating fare payment across bus, light rail, and paratransit services into a single rider account.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America registers the largest share of the market through mature ride-hailing ecosystems and transit modernization funding
North America leads the mobility as a service market, supported by mature ride-hailing ecosystems, high smartphone penetration, and continued federal investment in transit modernization under the Bipartisan Infrastructure Law, which has channeled tens of billions of dollars toward public transportation upgrades across major metropolitan areas. The region's dense network of established ride-hailing, micromobility, and transit operators gives riders access to some of the most mature multimodal platforms available. As of November 2025, Waymo's autonomous ride-hailing service was completing more than 250,000 paid rides per week across its US markets, reinforcing North America's leading position in the market.
Asia Pacific is the most rapidly developing regional mobility as a service market, powered by rapid urbanization, expanding smart city programs, and rising smartphone-based payment adoption across China, India, and Southeast Asia. Government-backed digital infrastructure initiatives are accelerating integration between ride-hailing, public transit, and micromobility operators. In April 2026, CATL unveiled its third-generation Qilin Battery alongside plans to build 4,000 integrated charge-and-swap stations across nearly 190 cities by the end of 2026, strengthening the electric fleet infrastructure that underpins mobility as a service deployment across the region.
The global industry is becoming innovation oriented as major mobility as a service companies engage in competition by leveraging AI-driven routing, unified payment integration, and broader modal coverage. Operators are enhancing automation in dispatching and fleet management, expanding partnerships with municipal transit authorities, and growing their capabilities in autonomous vehicle testing to enhance rider engagement. Partnerships with technology and payment providers are allowing businesses to leverage predictive demand forecasting, streamline fare collection, and accelerate expansion into new cities.
Major mobility as a service market players are focusing on subscription-based multimodal packages, autonomous fleet pilots, and consolidation of ticketing and fleet-management software through targeted acquisitions. The opportunities are growing in areas such as AI-enhanced journey planning, contactless payment infrastructure, electrified micromobility fleets, and regional transit-technology partnerships. The operators that manage to combine broad modal coverage with efficient payment and dispatching systems are expected to hold a competitive advantage over the coming years.
Founded in 2015 and headquartered in Helsinki, Finland, MaaS Global Ltd. created the Whim app, one of the first commercially available platforms to combine public transit, taxis, car rentals, and bike sharing into a single subscription-based service. The company operated across several European and Asian cities, including Vienna, Antwerp, and Tokyo. Following a 2024 acquisition by Dutch mobility platform umob, MaaS Global's underlying technology continues to support integrated multimodal trip planning and subscription-based mobility packages across the cities it originally served.
Founded in 2012 and headquartered in Ness Ziona, Israel, Moovit App Global Ltd. operates a public transit and journey-planning app that combines official transit data with crowdsourced rider input across thousands of cities worldwide. The company became part of Intel's Mobileye unit in 2020, aligning its transit-data expertise with autonomous vehicle mapping efforts. In spring 2026, Moovit introduced AI-assisted trip recommendations that draw on live vehicle positioning and historical commute patterns, extending its journey-planning tools to a broader base of urban riders.
Founded in 2009 and headquartered in San Francisco, California, Uber Technologies Inc. operates a ride-hailing, food delivery, and freight platform spanning several thousand cities globally, alongside a growing portfolio of micromobility and transit-ticketing integrations. The company has expanded its autonomous vehicle partnerships to broaden its private transportation offerings. In June 2025, Uber extended its autonomous ride-hailing partnership with Waymo to Atlanta, building on an earlier rollout in Austin, adding driverless vehicles to its broader mobility platform.
Founded in 2009 and headquartered in Sydney, Australia, SkedGo Pty Ltd provides journey-planning and trip-booking technology through its TripGo platform, serving transport operators, corporations, and government agencies across multiple continents. The company's software integrates public transport, cycling, walking, and shared mobility options into a single multimodal planner. In November 2025, SkedGo powered the launch of the Feonix Catch a Ride Network in the United States, connecting community transport participants to healthcare, work, and essential services through coordinated ride scheduling.
Other key players in the market include FOD Mobility UK Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our mobility as a service market trends 2026 report. Discover regional growth patterns, technology adoption, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$3999 $3599
$2499 $2249
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the global market for mobility as a service attained a value of nearly USD 260.06 Billion.
The market is projected to grow at a CAGR of 17.50% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 1304.52 Billion by 2035.
The major drivers of the market include the growing investments in smart transportation infrastructure, increased digitalisation, proliferation of the large number of OEMs into the market, and rising congestion of urban roads.
Increase in the number of vehicles, rising number of initiatives by various governments, and expansion of modes of transportation are the key trends propelling the growth of the market.
Regions considered in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
Ride hailing holds the largest share, supported by extensive driver networks and deep integration with broader multimodal apps.
Digital platforms known as Mobility as a Service (MaaS) platforms enable complete trip planning, electronic ticketing, and payment services for all forms of public and private transportation.
MaaS providers are integrators of various modes of transportation and mobility that offer a unified platform for consumer convenience.
Key players in the market are MaaS Global Ltd., Moovit App Global Ltd., Uber Technologies Inc., SkedGo Pty Ltd, and FOD Mobility UK Limited, among others.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Service Type |
|
| Breakup by Solution Type |
|
| Breakup by Transportation Type |
|
| Breakup by Vehicle Type |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




