

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The radiofrequency ablation devices market was valued at USD 4.60 Billion in 2025 and is expected to reach USD 11.72 Billion by 2035, expanding at a CAGR of 9.80% during 2026-2035. Growth is supported by rising atrial fibrillation procedures, wider use of image-guided tumour treatment, and increasing demand for minimally invasive pain and venous therapies.
Patent activity in radiofrequency ablation devices has gained momentum since 2020, with filings concentrated in catheter design, contact-force sensing, mapping integration and generator control. Regulatory clearances for pulsed field systems in 2024 and 2025 have pushed leading assignees to file dual-energy and hybrid inventions that sit beside thermal radiofrequency platforms.
This Radiofrequency Ablation Devices Patent Landscape Analysis Report maps assignee portfolios, jurisdictional filing trends and technology segments to guide R&D, licensing and freedom-to-operate decisions.
The radiofrequency ablation devices market is experiencing strong growth, driven by rising atrial fibrillation prevalence, expanding image-guided tumour treatment, and growing interventional pain procedures. Catheter ablation procedures for atrial fibrillation continue to rise each year, and thermal radiofrequency catheters with contact-force sensing remain a mainstay in electrophysiology labs worldwide.
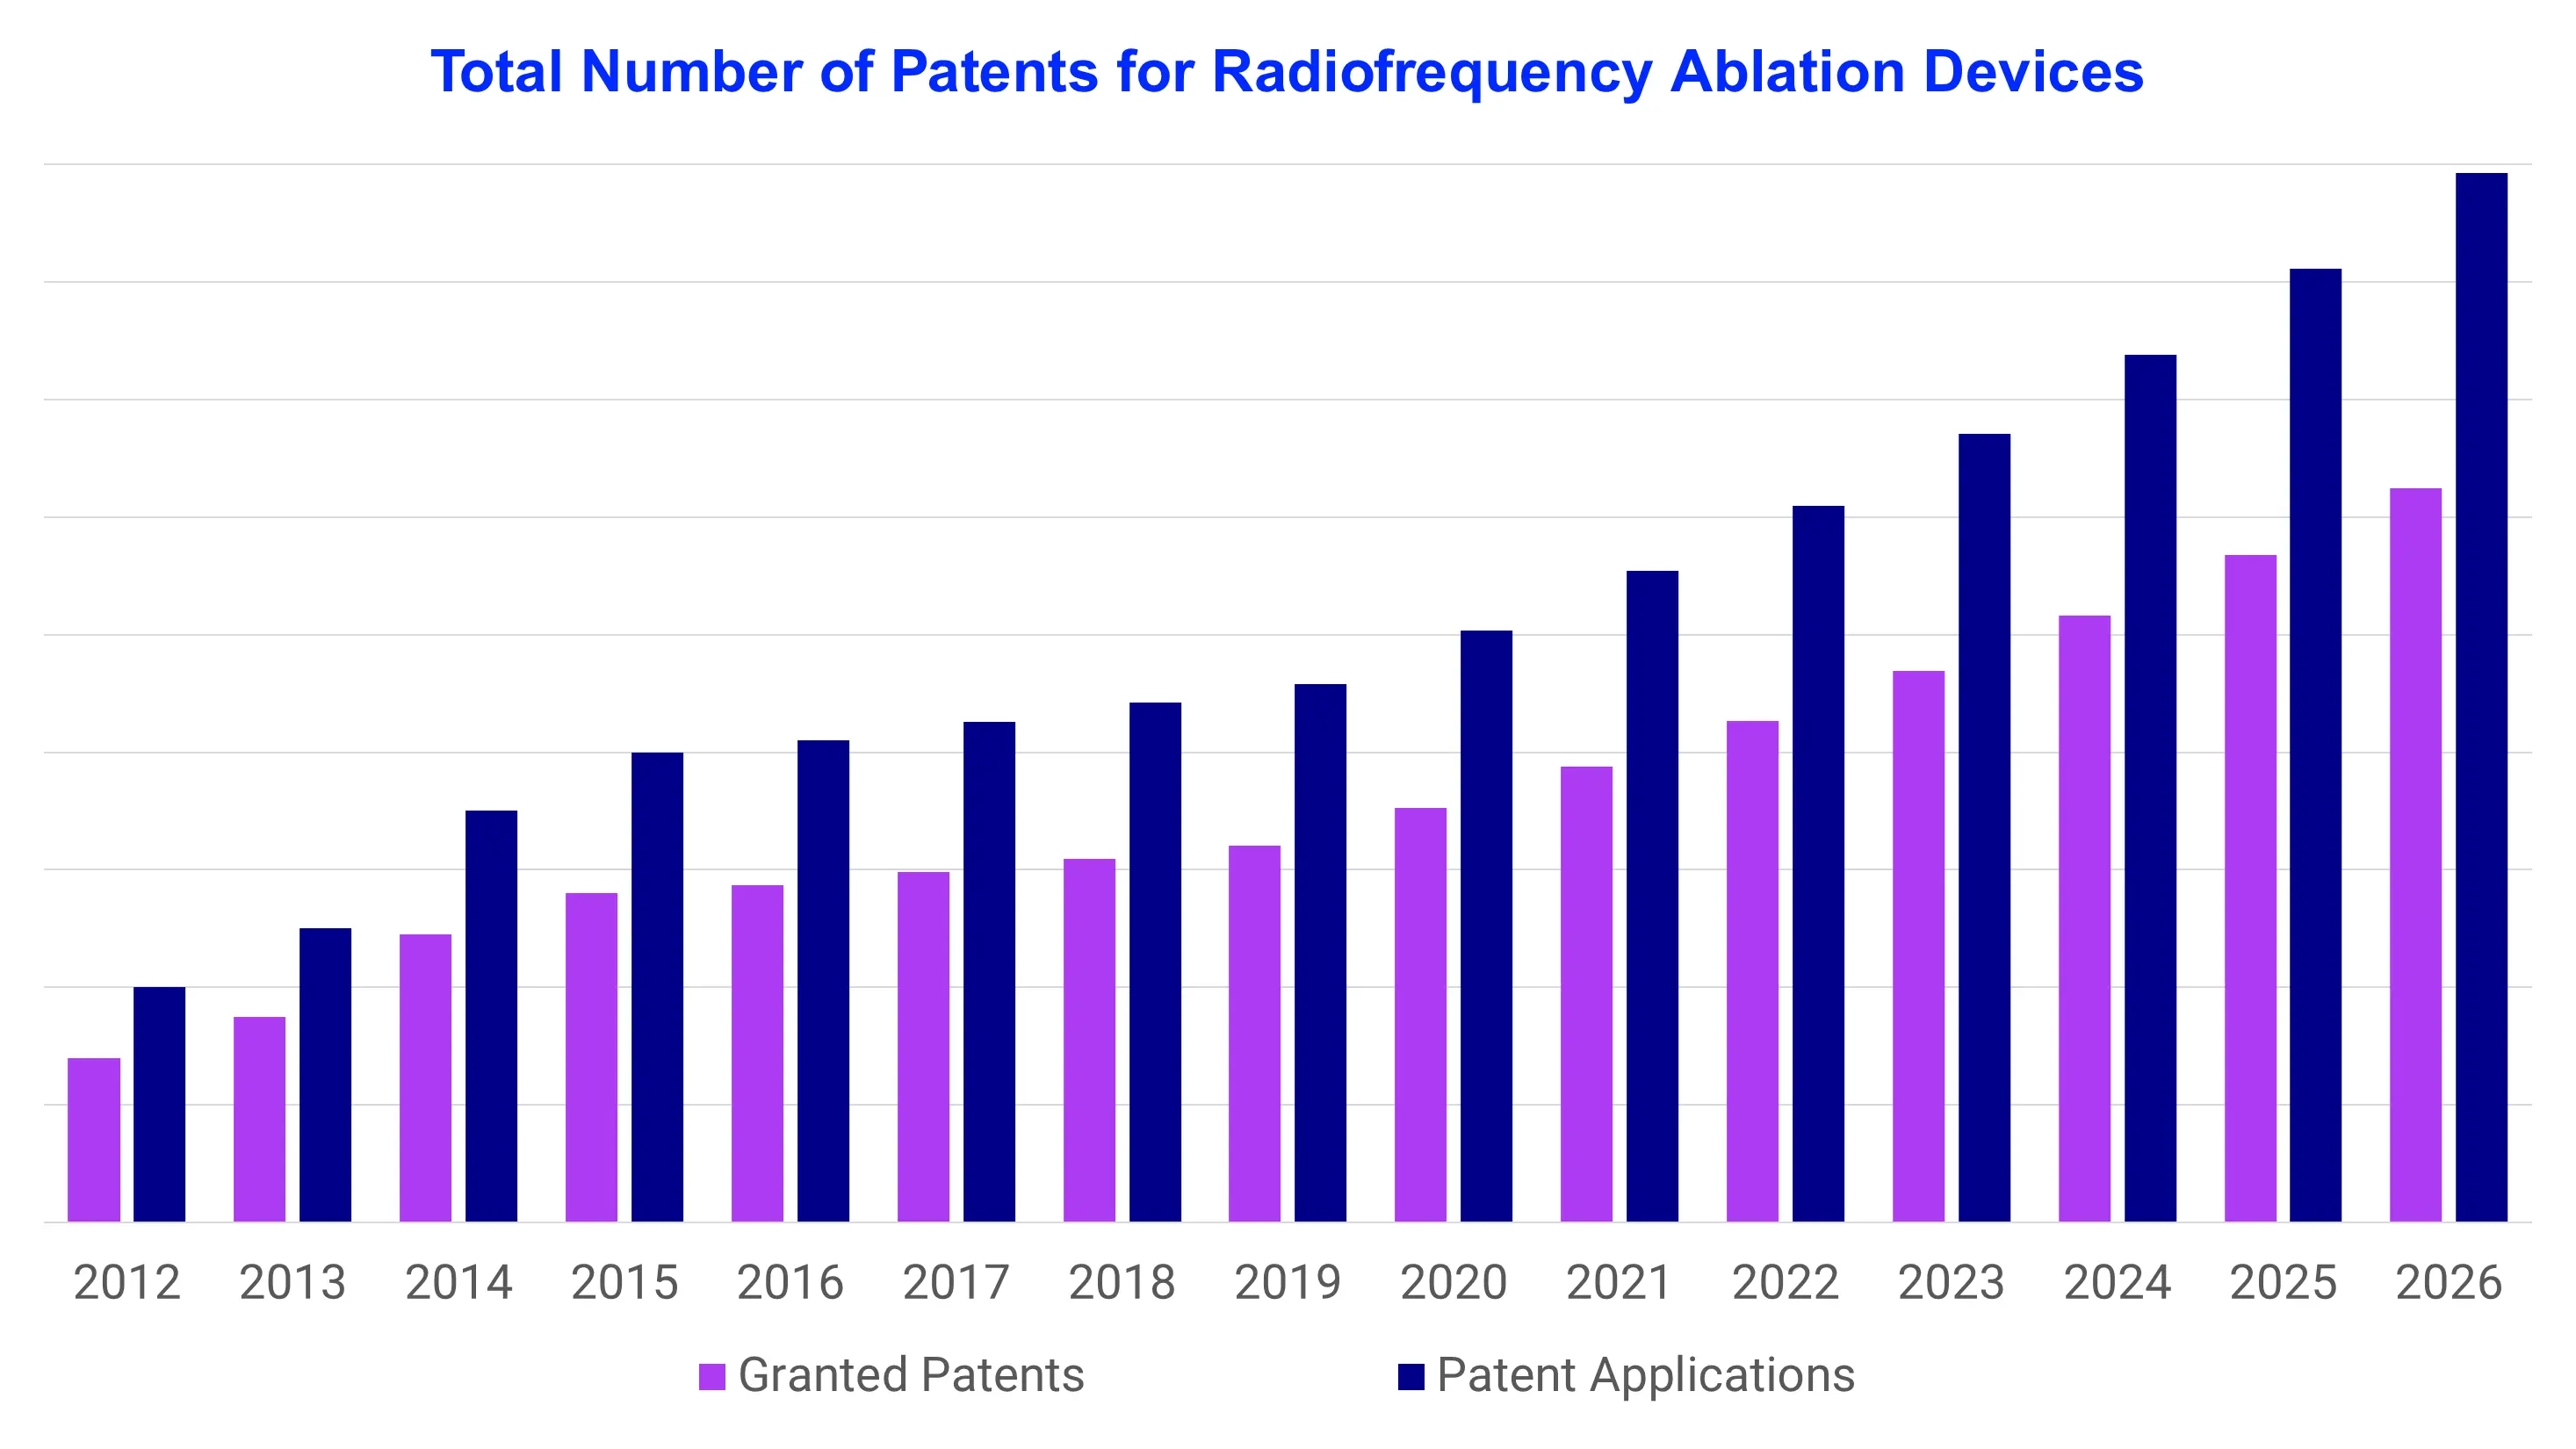
Patent activity is accelerating, with 1,900+ radiofrequency ablation devices patents granted in 2025, reflecting strong innovation momentum in contact-force sensing catheters, mapping system integration, pulsed field and hybrid energy delivery, and cooled and irrigated electrodes.
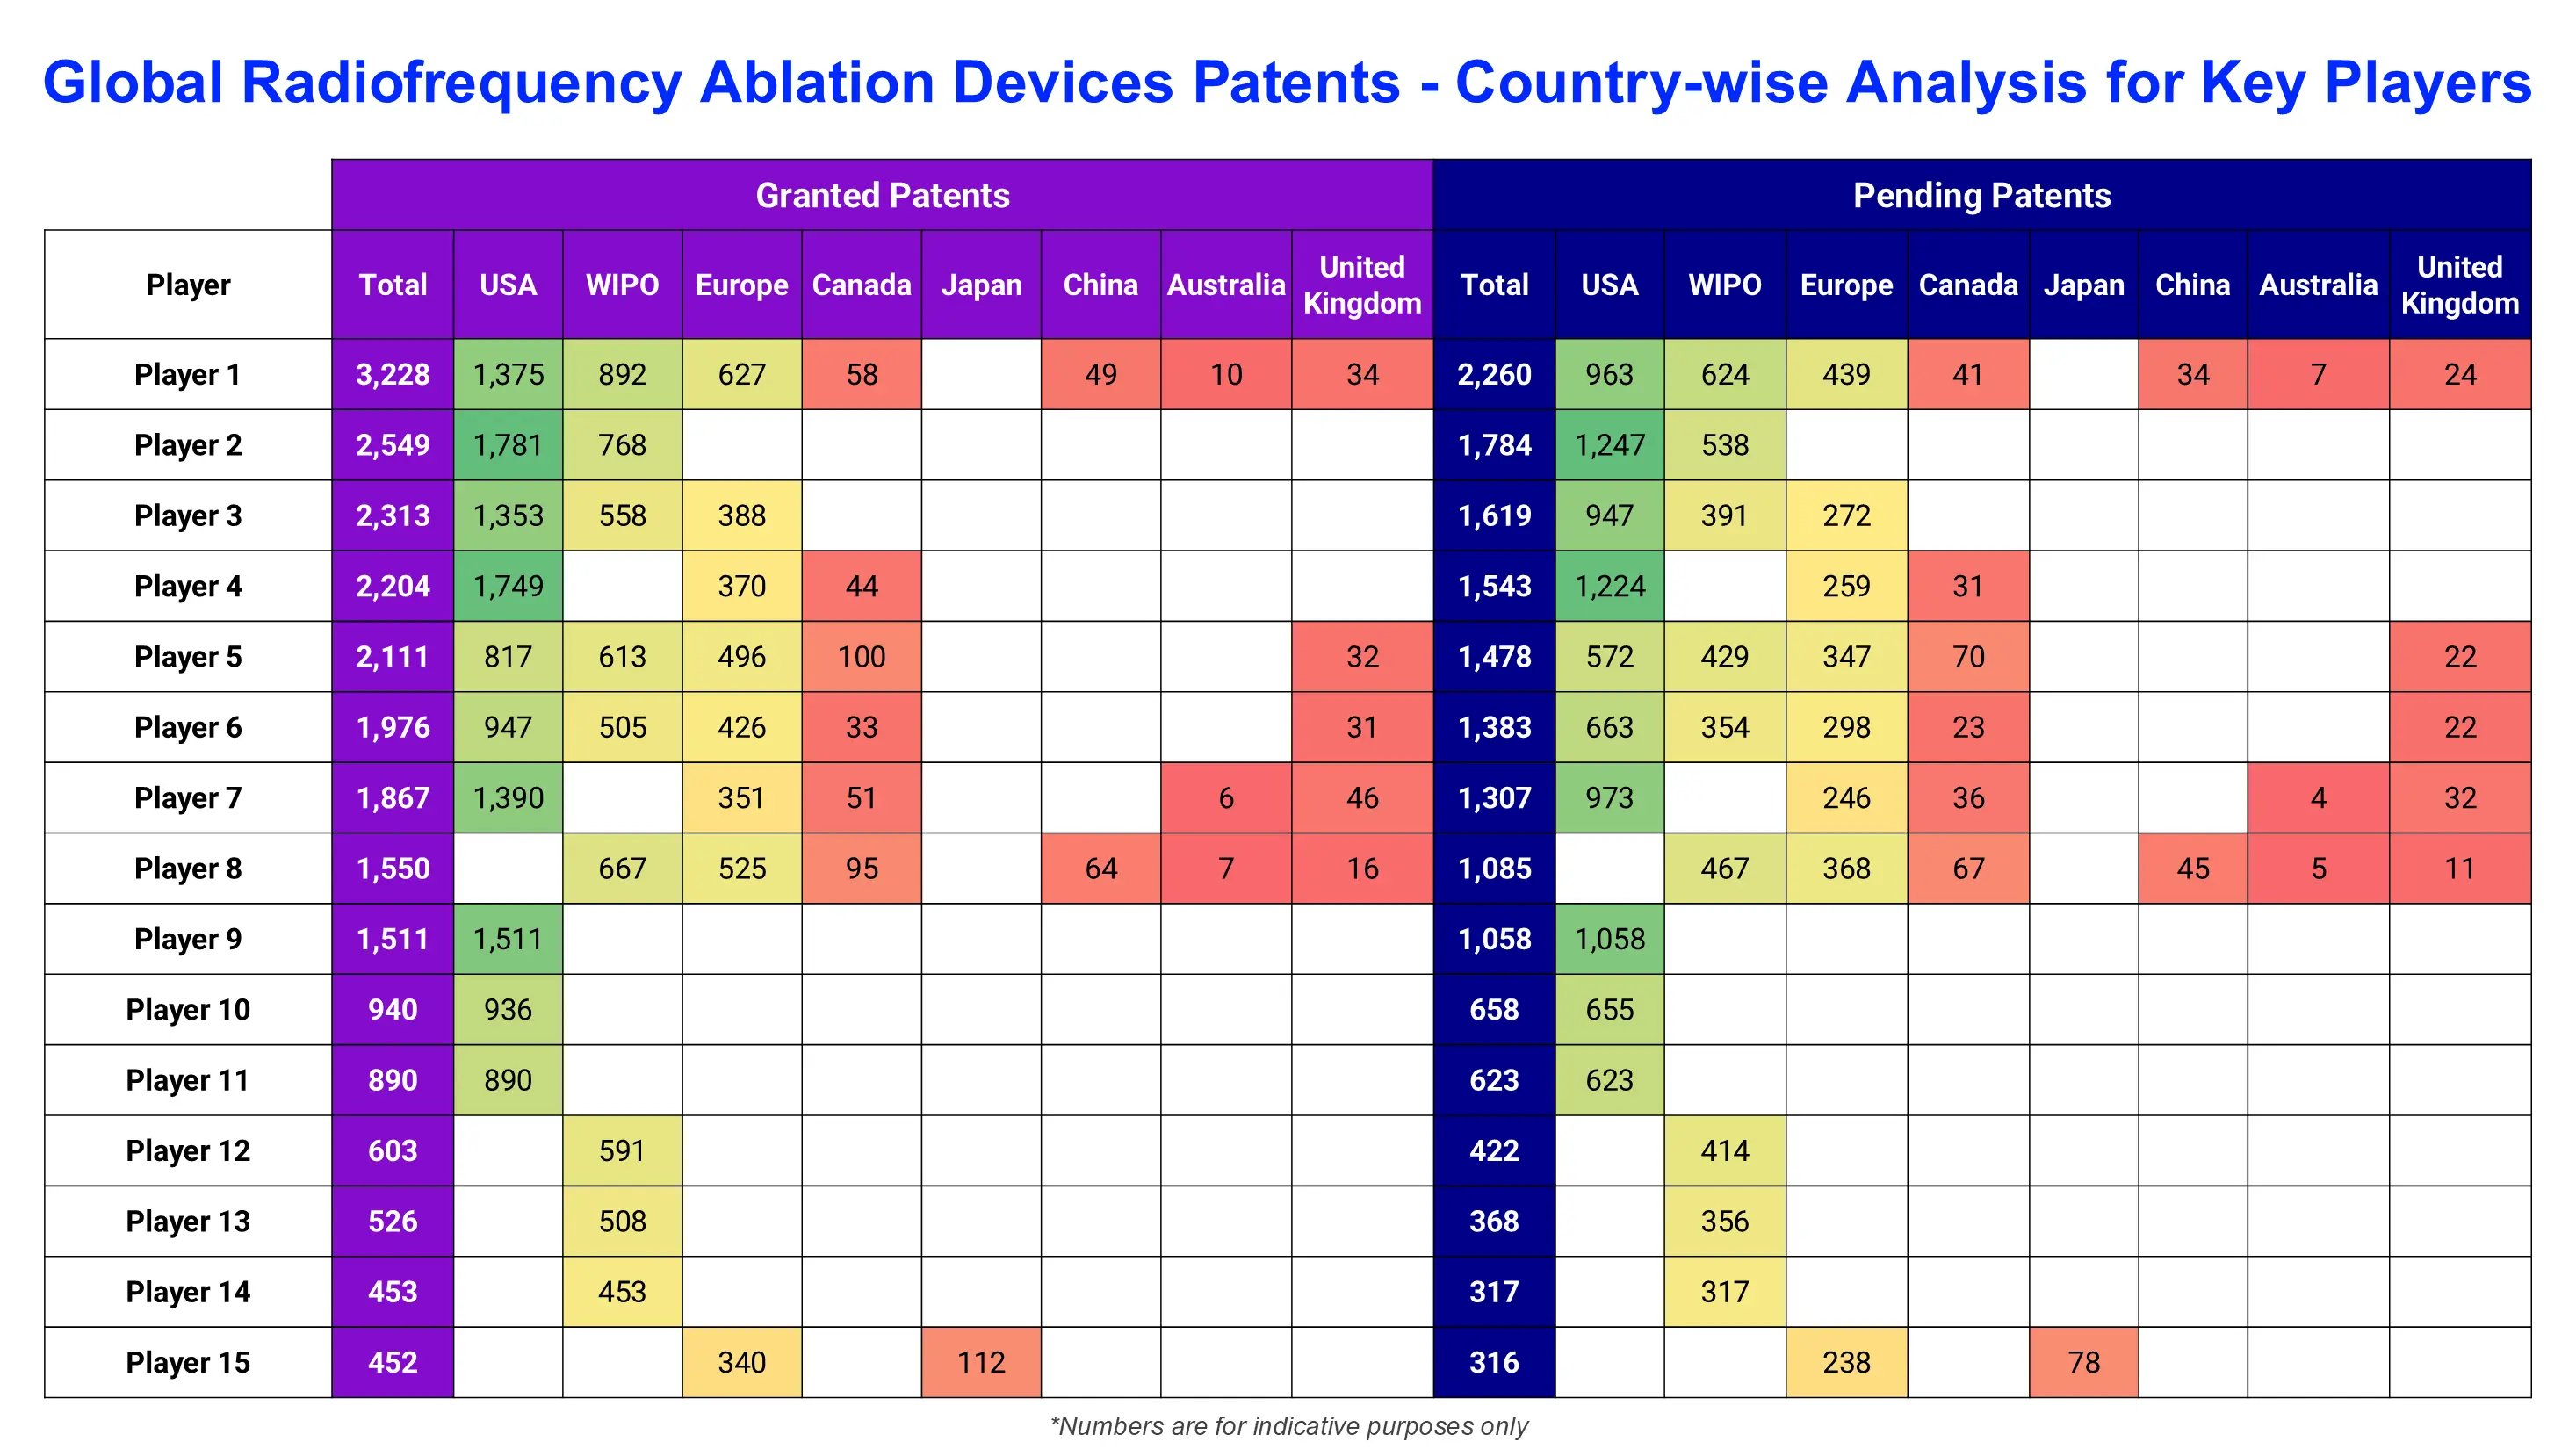
Top assignees in the radiofrequency ablation devices patent landscape include Medtronic, Johnson & Johnson MedTech, Boston Scientific, Abbott, and Olympus, with the United States, China, and Europe as the dominant patent jurisdictions.
Market growth is driven by the rising number of catheter ablation procedures for atrial fibrillation, which affects roughly 59 million people worldwide. Hospitals add electrophysiology capacity to meet this demand, which lifts catheter, generator and mapping consumable volumes. Liver cancer, with more than 800,000 new cases each year, adds a second procedure stream for percutaneous tumour ablation.
North America holds the largest regional market, led by the United States, where more than 5 million adults live with atrial fibrillation. High reimbursement for electrophysiology procedures and dense mapping system installations keep catheter utilisation high. Europe follows, supported by national screening programmes that identify patients earlier and feed ablation referrals. Asia Pacific records the fastest procedure growth as China and India expand cardiac catheterisation centres, which raises demand for domestic and imported devices.
The arrival of pulsed field ablation in 2024 and 2025 has shifted purchasing in atrial fibrillation, since several centres moved a share of paroxysmal cases to non-thermal energy. Thermal radiofrequency catheters keep a strong base in persistent atrial fibrillation, ventricular tachycardia and complex substrates where mapping guidance matters. Outside the heart, genicular, basivertebral and lumbar facet procedures expand the use of cooled electrodes, and this diversity of uses supports a steady growth rate for the category.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Patent filings in radiofrequency ablation devices follow clinical demand across cardiology, oncology and pain medicine. Catheter tip geometry, irrigation channels and force sensors dominate cardiac filings, while needle electrodes and cooled probes lead in tumour and pain applications. Generators with impedance and temperature control form a steady third stream.
The report identifies more than 14,000 patent families, with filing peaks in 2019, 2021 and 2023 as mapping integration and high-power short-duration protocols matured. Recent applications add pulsed field and dual-energy claims to thermal radiofrequency platforms.
Rising procedure volumes in atrial fibrillation and tumour treatment directly drive assignees to protect catheter, generator and software improvements in the largest reimbursed markets.
The report covers patents on generators, electrodes, catheters, needles and the software that guides energy delivery. Clinical areas include atrial fibrillation catheters, mapping integration, contact-force sensing and the shift toward pulsed field ablation, along with tumour ablation in liver, lung, kidney and thyroid.
Pain management applications such as genicular, basivertebral and lumbar facet denervation are included, as are Barrett's oesophagus, venous closure and aesthetic skin tightening. Each family is assigned to a technology, application and device component category.
Assignees reviewed include medical device manufacturers, electrophysiology specialists, universities, hospitals and emerging companies filing on energy delivery and lesion monitoring.
The report will cover the following sections in detail:
Analysis by Technology
Analysis by Application
Analysis by Device Component
Radiofrequency Ablation Devices Patent Filing Trend Analysis
Annual filings in radiofrequency ablation devices grew at an estimated 6 to 8% between 2020 and 2024. Growth came from contact-force sensing, high-power short-duration ablation and mapping software that predicts lesion quality.
Since 2022, hybrid claims combining radiofrequency and pulsed field energy have grown faster than any other topic. China contributes a rising share as domestic catheter makers file for 3D mapping and ablation catheters following local approvals.
Among the players with radiofrequency ablation devices patent families, new entrants have been identified, which can be either established companies or startups developing novel technology in the field. Some of the major companies mentioned in this report (a non-exhaustive list) are as follows:
Medtronic holds one of the largest radiofrequency ablation devices portfolios, spanning cardiac, venous, pain and oesophageal applications. Its Arctic Front cryoballoon sits beside the Affera mapping and Sphere-9 catheter platform, which brings radiofrequency and pulsed field energy together in one lattice-tip catheter. The HALO system treats Barrett's oesophagus, ClosureFast serves venous reflux, and the Cooled radiofrequency products address knee and spine pain. Affera received FDA approval in 2024, and the PulseSelect system gained US clearance in late 2023. Medtronic files across catheter structure, generator algorithms and mapping software, building overlapping claims around each platform.
Johnson & Johnson MedTech, through Biosense Webster, owns a deep portfolio in contact-force sensing and electroanatomical mapping. The THERMOCOOL SMARTTOUCH SF catheter and the CARTO 3 mapping system form the core of its thermal radiofrequency franchise, and the QDOT MICRO catheter adds temperature-controlled very high-power delivery. The VARIPULSE pulsed field catheter received FDA approval in November 2024, with integration into CARTO. Its IP strategy links catheter hardware, sensor design and mapping algorithms, so each new product reinforces claims on the CARTO workflow. The company holds a leading position in electrophysiology labs in the United States, Europe and Japan.
Other companies include Boston Scientific, Abbott, and Olympus.
The five leading assignees hold an estimated 30 to 35% of patent families, which indicates a moderately concentrated field. Medtronic and Johnson & Johnson MedTech lead on cardiac and mapping claims, while Boston Scientific and Abbott grow quickly through acquired pulsed field and mapping portfolios.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
The report assesses patent activity across major jurisdictions, including:
The United States leads in filing volume, followed by China and Europe through the European Patent Office. The United States attracts first filings from global manufacturers because of its reimbursement and procedure base. China shows the steepest growth rate in applications from domestic firms and universities.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The patent segmentation spans the following technology clusters:
Among these, cardiac ablation catheter design holds the largest share of patent filings, driven by atrial fibrillation procedure volumes.
Medtronic, Johnson & Johnson MedTech, Boston Scientific, Abbott and Olympus form the leading group of assignees. Cardiac electrophysiology specialists build dense families around catheters and mapping, while Olympus and AngioDynamics file mainly on tumour, endoscopic and vascular probes. Stryker and Merit Medical hold targeted positions in spine and pain applications.
Companies are focusing on:
Emerging innovation themes include dual-energy catheters that deliver radiofrequency and pulsed field energy from one tip, artificial intelligence for lesion prediction, and impedance-based tissue characterisation. Thyroid and lung tumour probes with real-time imaging fusion add a further growth path, and compact generators support outpatient pain clinics.
Large device makers protect full procedural workflows, from generator to catheter to mapping software. Smaller firms file narrow claims in tip geometry, sensors and energy waveforms, which creates acquisition targets. Overlap between thermal and pulsed field claims raises freedom-to-operate questions in the United States and Europe.
Technology segments, assignee portfolios and jurisdiction trends are mapped to show where new claims are forming. The report provides actionable intelligence supporting:
The study searched patent databases of the United States Patent and Trademark Office, the European Patent Office, the China National Intellectual Property Administration, the Japan Patent Office and WIPO. Queries combined keywords with CPC classes A61B 18/12, A61B 18/14, A61B 18/1492 and A61N 1/40, along with IPC equivalents.
Results were screened for relevance, de-duplicated and consolidated into patent families. Assignee names were harmonised across subsidiaries and acquired entities, and each family was tagged by technology, application and device component.
The market side draws on regulatory filings, company disclosures, clinical trial registries and peer-reviewed literature. Procedure volumes and approvals were cross-checked with FDA, European and national regulator records.


Upto 15% Off
USD
$2699 $2429
$4299 $3869
$5799 $4949
$6999 $5949


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
EMR’s Radiofrequency Ablation Devices Patent Landscape Analysis provides a comprehensive assessment of patent filings, innovation clusters, assignee portfolios, and geographic filing patterns across the radiofrequency ablation devices landscape. The report identifies 14,000+ patent families, evaluates leading jurisdictions including the United States, China, and Europe, and profiles the top assignees by portfolio size.
The global radiofrequency ablation devices market was valued at USD 4.60 Billion in 2025. The market is projected to reach USD 11.72 Billion by 2035, expanding at a CAGR of 9.80% during 2026-2035.
The report analyses approximately 14,000+ patent families related to radiofrequency ablation devices. These include filings from the United States, China, Europe, and international WIPO filings.
Key companies operating within the landscape include Medtronic, Johnson & Johnson MedTech, Boston Scientific, Abbott, and Olympus, among others. These organisations collectively account for a significant portion of patent activity analysed in this report.
The report evaluates patent activity across the United States, Europe, China, Japan, South Korea, India, and international WIPO filings. The United States leads patent filing activity, with an estimated 35 to 40% of all patent families in radiofrequency ablation devices.
Yes. The report scope can be customised based on geography, technology segment, assignee selection, time period, or specific innovation cluster focus. Please connect with the EMR team to define the customisation scope.
Patent landscape analysis helps organisations understand innovation trends, competitive activity, technology whitespace, and IP risk across a defined domain. For radiofrequency ablation devices, this report supports strategic decisions in R&D prioritisation, licensing evaluation, competitive benchmarking, and market entry planning.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Scope of the Report |
Details |
|
Analysis by Technology |
|
|
Analysis by Application |
|
|
Analysis by Device Component |
|
|
Analysis by End User |
|
|
Key Players Mentioned |
|
|
Geographies Covered |
|
Mini Report
One User
USD 2,699
USD 2,429
tax inclusive*
Single User License
One User
USD 4,299
USD 3,869
tax inclusive*
Five User License
Five User
USD 5,799
USD 4,949
tax inclusive*
Corporate License
Unlimited Users
USD 6,999
USD 5,949
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




