

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
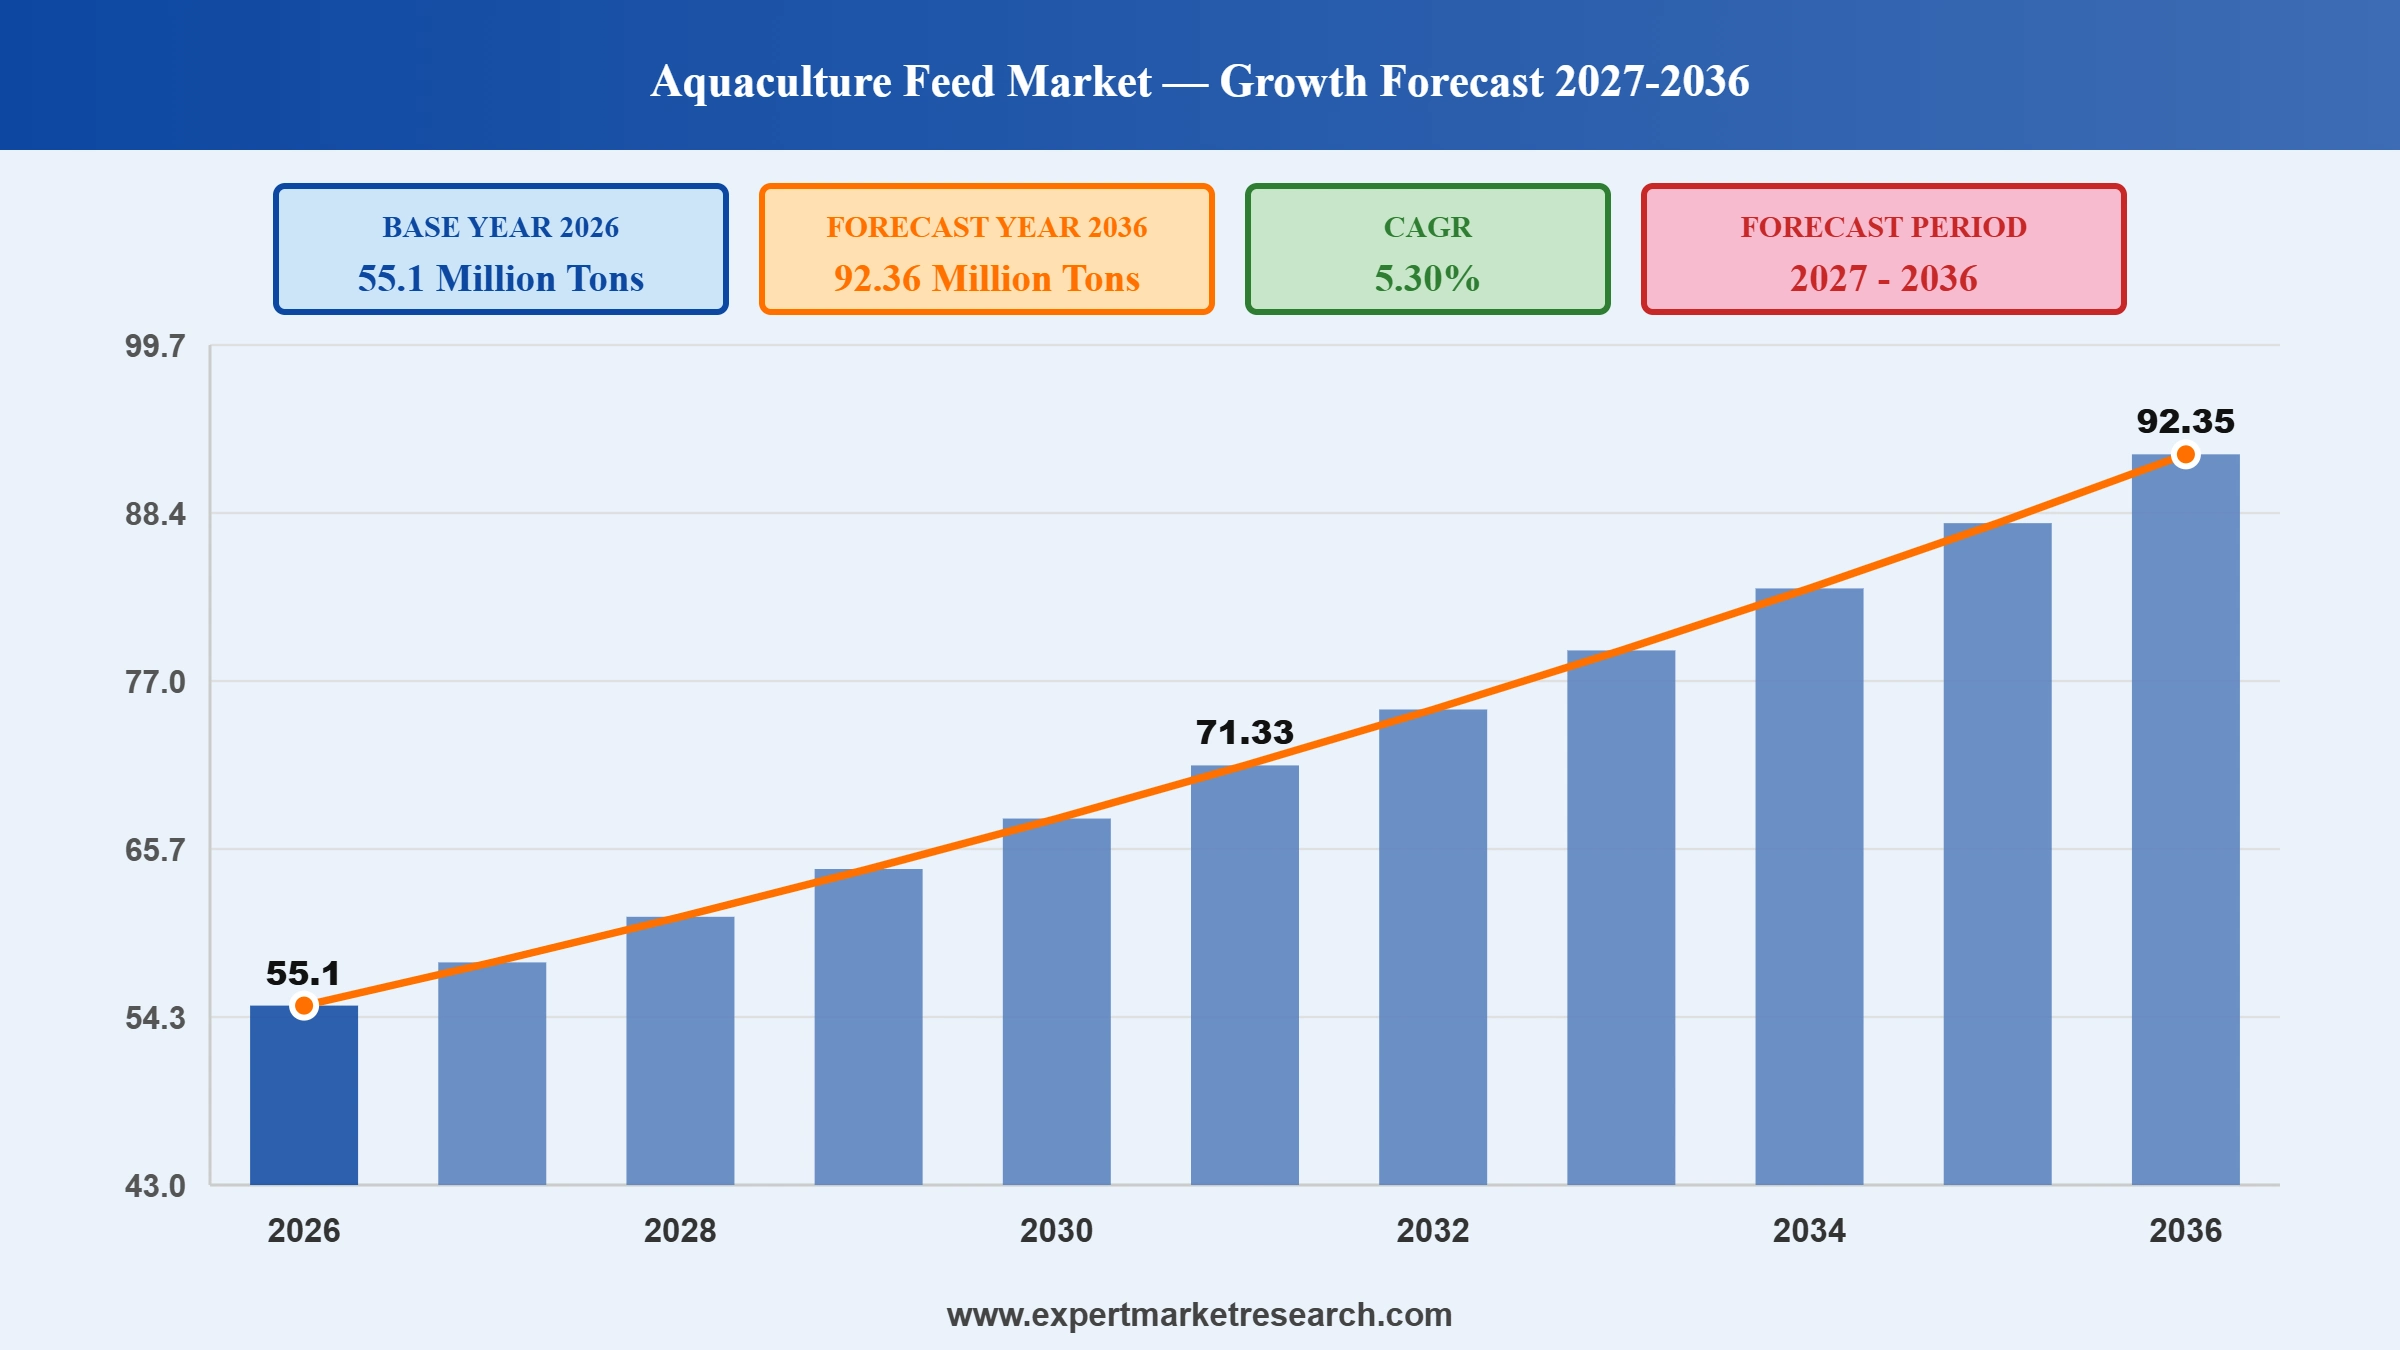
The global aquaculture feed market attained a volume of 52.33 Million Tons in 2025 and is projected to expand at a CAGR of 5.30% through 2035. The market is further expected to reach a volume of 87.71 Million Tons by 2035. Rising global fish and shrimp production and growing reliance on formulated diets over natural feeding are sustaining demand, supported by government backing for blue economy initiatives and recirculating farming infrastructure across major producing regions.
The aquaculture feed market covers formulated rations for farmed carp, shrimp, tilapia, catfish, salmon, and trout, spanning starter, grower, and finisher diets built on soybean, corn, fish meal, and specialty additives. Adoption continues broadening as pond operators shift from farm made feed toward manufactured rations, most visible across South and Southeast Asia's intensifying carp, tilapia, and catfish farming.
Demand is concentrating around shrimp and salmonid production, where feed is the largest input cost and formulators compete on digestibility and disease resistance support. In January 2025, Saudi Arabia's Ministry of Environment, Water and Agriculture opened the Excellence Center for Salmon Production in Hail with King Abdulaziz University, a recirculating facility reducing salmon import reliance under Vision 2030.
Manufacturers are directing investment toward backward integration into alternative proteins and region-specific extrusion lines as they widen portfolios beyond flagship species. Consolidation among regional producers is accelerating as companies seek secure raw material access, while formulators broaden technical support offering farm level feeding and disease management guidance alongside formulated diets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Industrial Pesquera Santa Priscila, Ecuador's largest shrimp exporter, acquired the Ecuaprotein assets to expand hydrolysate production feeding its integrated shrimp operations and strengthen access to marine protein derivatives amid tightening global fishmeal supply. The deal deepens backward integration into ingredient sourcing across the group's shrimp business, helping it stabilise ingredient costs and better protect feed quality through ongoing supply swings across the aquaculture feed market.
Innovafeed secured EUR 51 million from existing investors to move from building industrial capacity toward commercial deployment of insect-based ingredients for aquaculture and pet food applications. The round backs sales expansion, new product development, and efficiency gains across its production base. Such funding accelerates the shift toward alternative proteins as marine ingredient supply tightens and formulators across the aquaculture feed market seek scalable substitute inputs.
Haid subsidiary Yongfu Hailong Agricultural Feeds broke ground on a 200,000 metric ton feed plant in Phu Tho province, targeting local aquaculture, poultry, and pig farming demand across northern Vietnam. The company expects growth from export-oriented pangasius and whiteleg shrimp production to drive utilisation, and such capacity additions help secure formulated feed supply for Vietnam's expanding export-driven farming base overall.
NaturAlleva, a major Mediterranean aquaculture feed producer, signed a commercial partnership with Innovafeed in January 2026 to integrate Black Soldier Fly larvae ingredients into feed formulations for sea bass, sea bream, sturgeon, and trout. The agreement extended Innovafeed's insect protein supply into a major producer's formulations across the aquaculture feed market. The tie-up reflected growing commercial traction for alternative proteins.
Farmed fish output in Latin America is climbing as producers convert pond and cage operations to intensive feeding regimes, lifting regional feed consumption. Brazil illustrates this shift clearly, with tilapia accounting for the bulk of farmed output. According to the Brazilian Association of Pisciculture's tenth annual report, published in March 2026, farmed fish production passed 1 million metric tons for the first time in 2025, up 4.41 percent over 2024, with tilapia making up roughly 70 percent of that volume.
Regulatory clearance for new vitamin and mineral forms is widening the additive toolkit available to aquaculture formulators across the aquaculture feed market seeking better bone development and skeletal health in farmed species. Authorities are responding to a growing body of efficacy data built across terrestrial and aquatic species. DSM-Firmenich is securing this expansion directly: in December 2025, the company announced European Union authorisation of its Hy-D vitamin D3 metabolite for use across aquaculture and other animal species, widening its approved application base across the region.
Cold-water species producers across the aquaculture feed market are turning to land-based recirculating systems to de-risk production from sea lice, temperature swings, and escape risk, a shift lifting demand for extruded finisher diets formulated for closed-system rearing. Early-stage ventures are raising capital to fund design work ahead of construction. Big Akwa is one such venture: in December 2025, the company completed a SEK 7.85 million directed share issue to finance engineering work on a planned 6,000-tonne rainbow trout farm at Alby Industrial Park in Sweden.
Feed manufacturers across Asia in the aquaculture feed market are pursuing acquisitions to widen plant networks and secure distribution reach as farmers consolidate purchasing with fewer, larger suppliers across fragmented national markets. This is particularly visible among groups seeking faster market entry rather than building new capacity from scratch. De Heus is advancing this strategy: in October 2025, the company agreed to acquire CJ Feed & Care, adding seventeen feed plants across Asia and accelerating its regional growth strategy well beyond organic capacity expansion alone.
Norwegian salmon producers across the aquaculture feed market are funding new land and ocean-based rearing infrastructure to grow smolt output ahead of planned harvest increases, a trend lifting feed volume requirements across the broader value chain. Capital raises are increasingly tied to specific facility milestones rather than general expansion plans. Andfjord Salmon illustrates this pattern clearly: in September 2025, the company raised NOK 1.55 billion to advance its Kvalnes facility in Andoya, ahead of a planned second release of 1.1 million smolt into open water.
The Expert Market Research’s report titled "Global Aquaculture Feed Market Report and Forecast 2026-2035" delivers a comprehensive analysis of the market across the following segments:
Market Breakup by Species
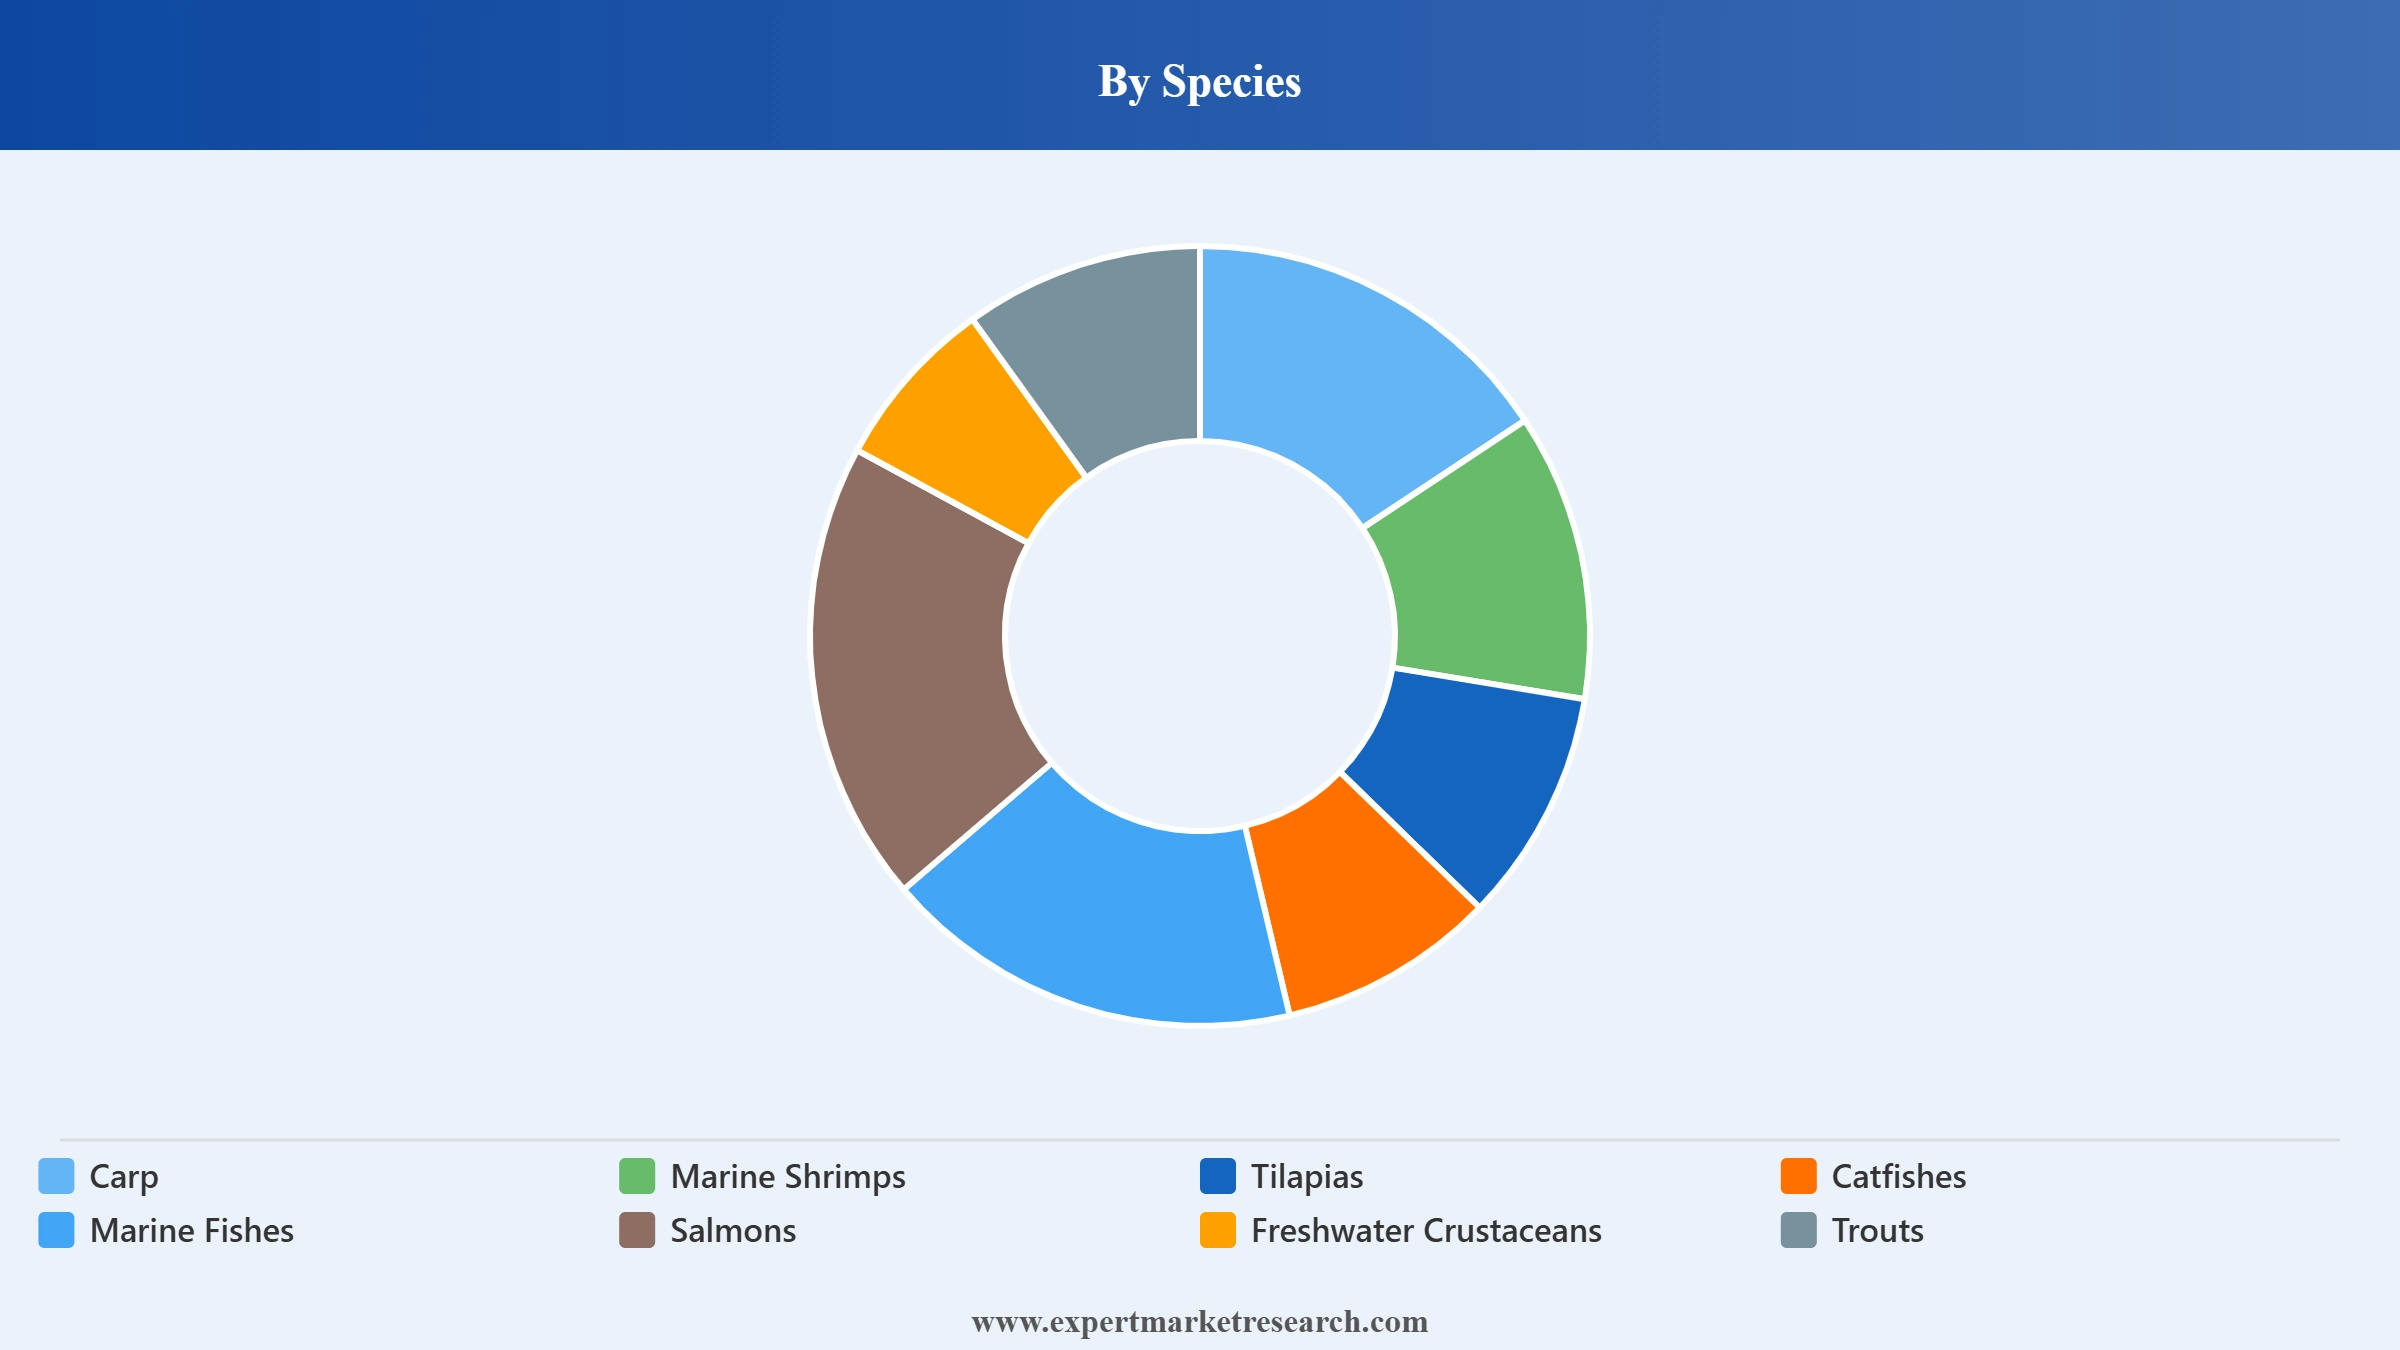
Key Insight: Marine shrimps lead species-wise consumption as intensive pond and cage culture spreads across Ecuador, India, Vietnam, and Indonesia. Carp and tilapia remain the volume backbone of freshwater farming across South and Southeast Asia, while catfishes support pangasius and catfish farming in Vietnam and the United States. Marine fishes and salmons drive premium demand in cooler waters, and trouts anchor cold-water farming in Europe and North America. Freshwater crustaceans add a smaller base, while others cover ornamental and emerging species that remain niche contributors.
Market Breakup by Ingredients
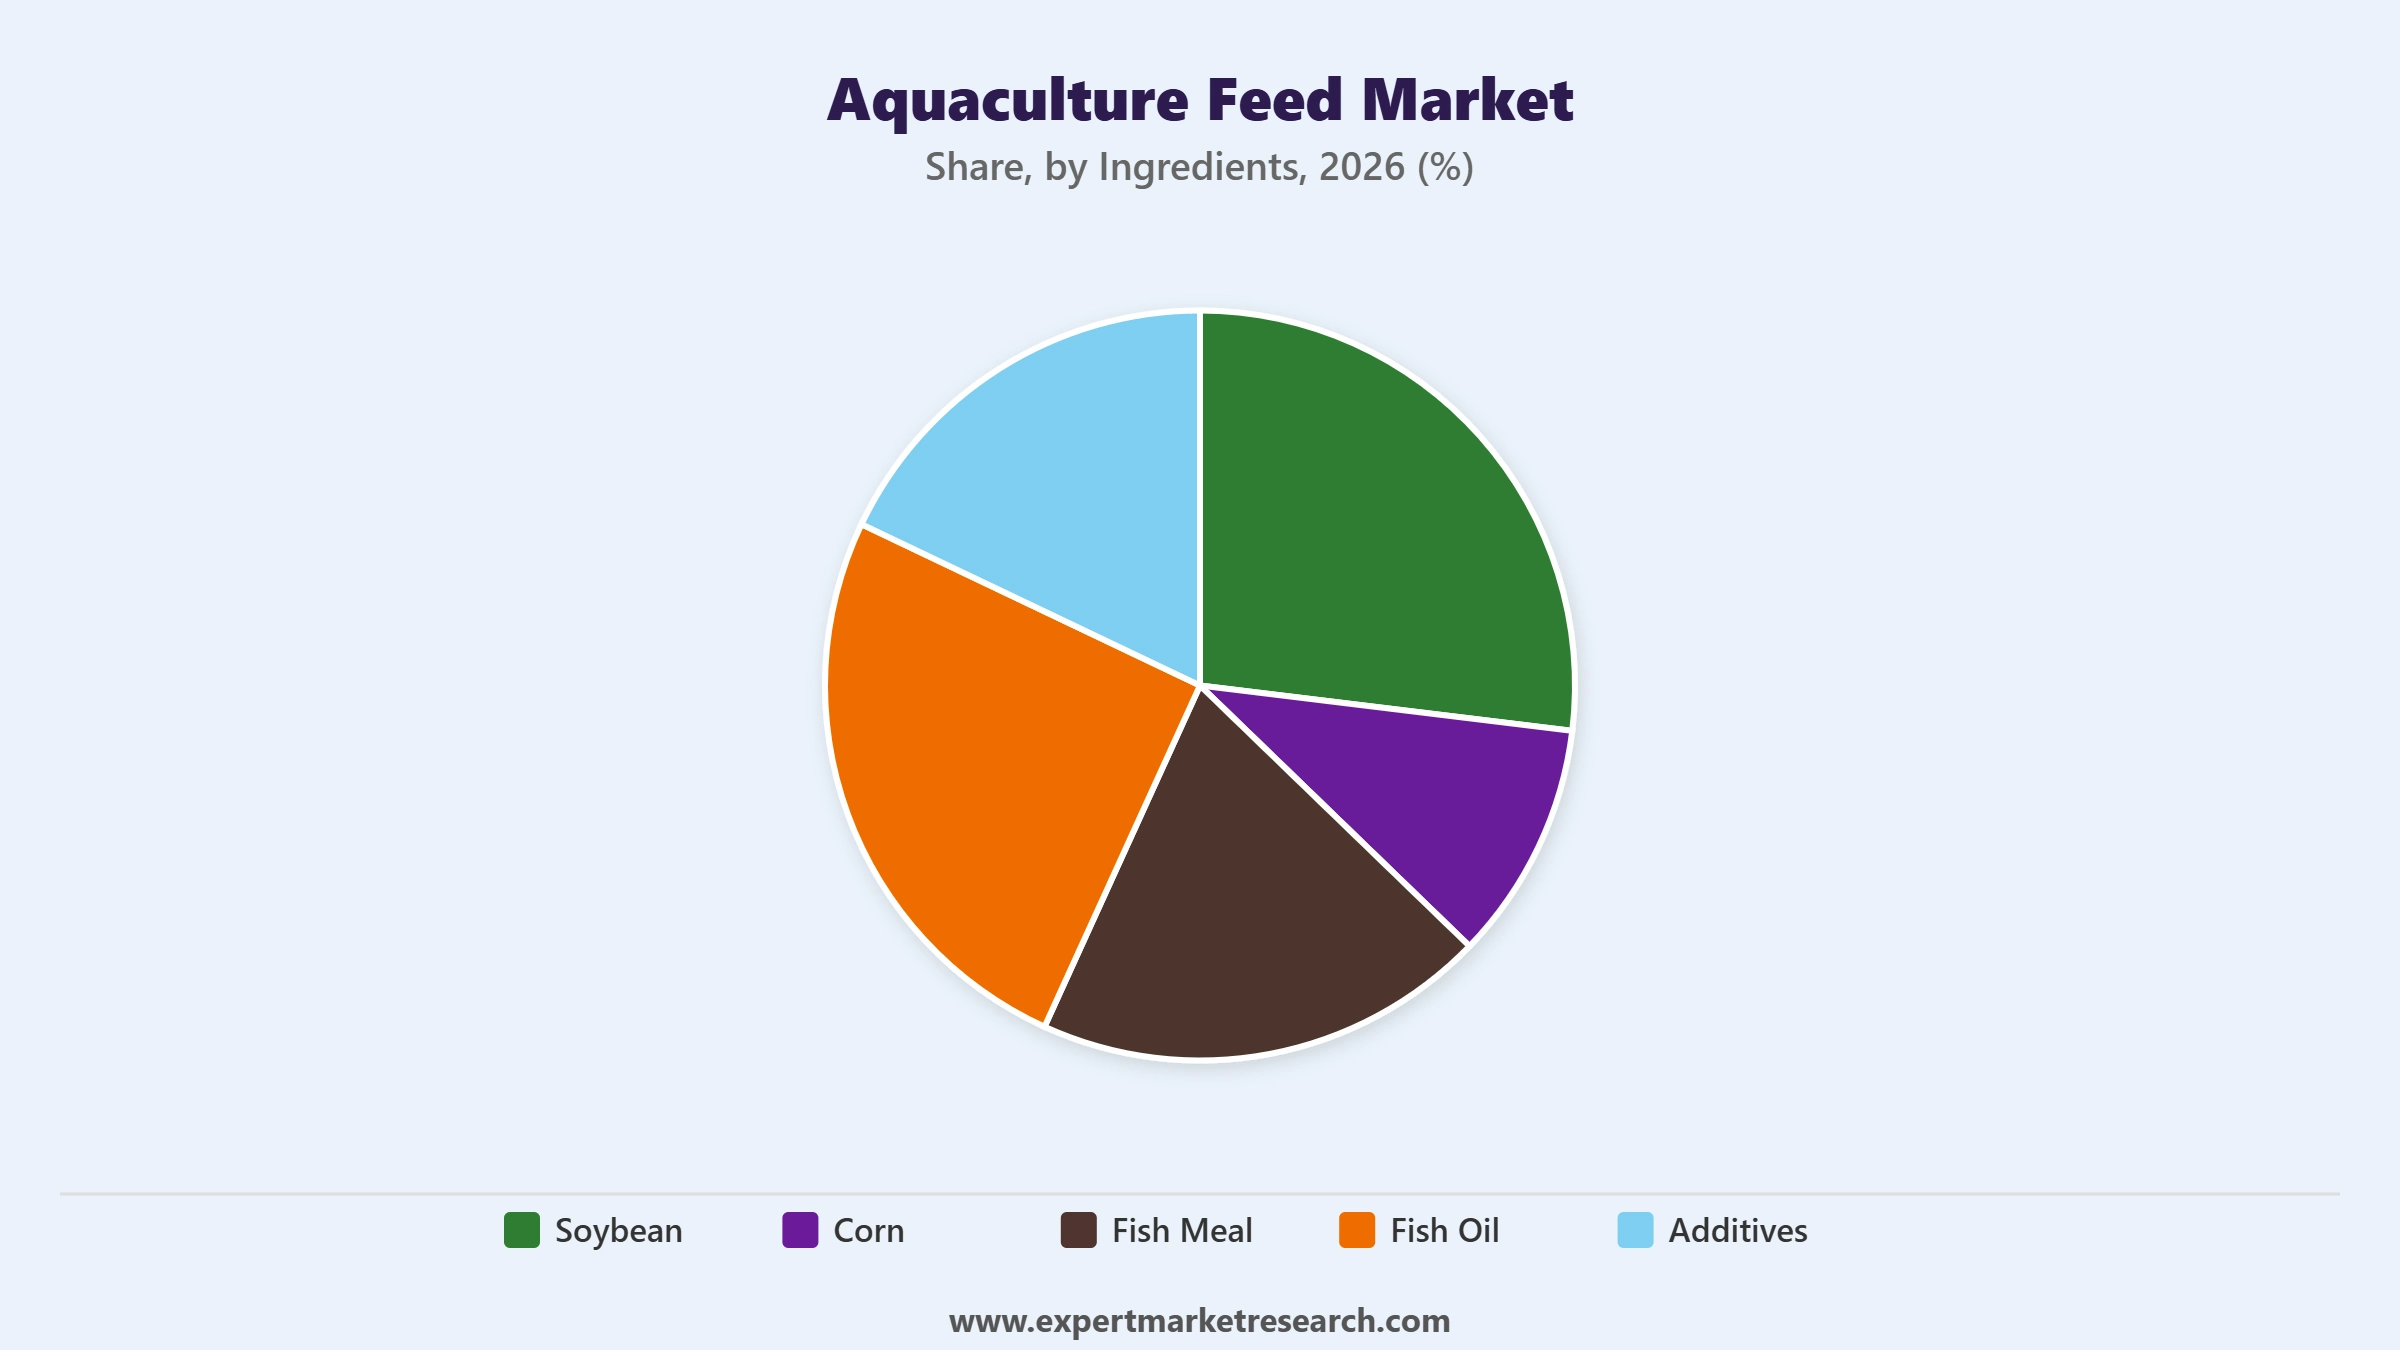
Key Insight: Soybean meal remains the largest plant-protein input owing to its favourable amino acid profile, consistent availability, and cost advantage over marine proteins. Corn supplies energy and binding properties that support pellet stability during extrusion. Fish meal and fish oil continue to anchor nutrition for carnivorous species despite tightening anchovy-based supply, pushing formulators toward partial substitution. Additives, covering vitamins, minerals, antioxidants, and enzymes, are gaining share as producers fine-tune diets, while others include wheat, rice bran, and emerging single-cell and insect-derived proteins.
Market Breakup by Additives
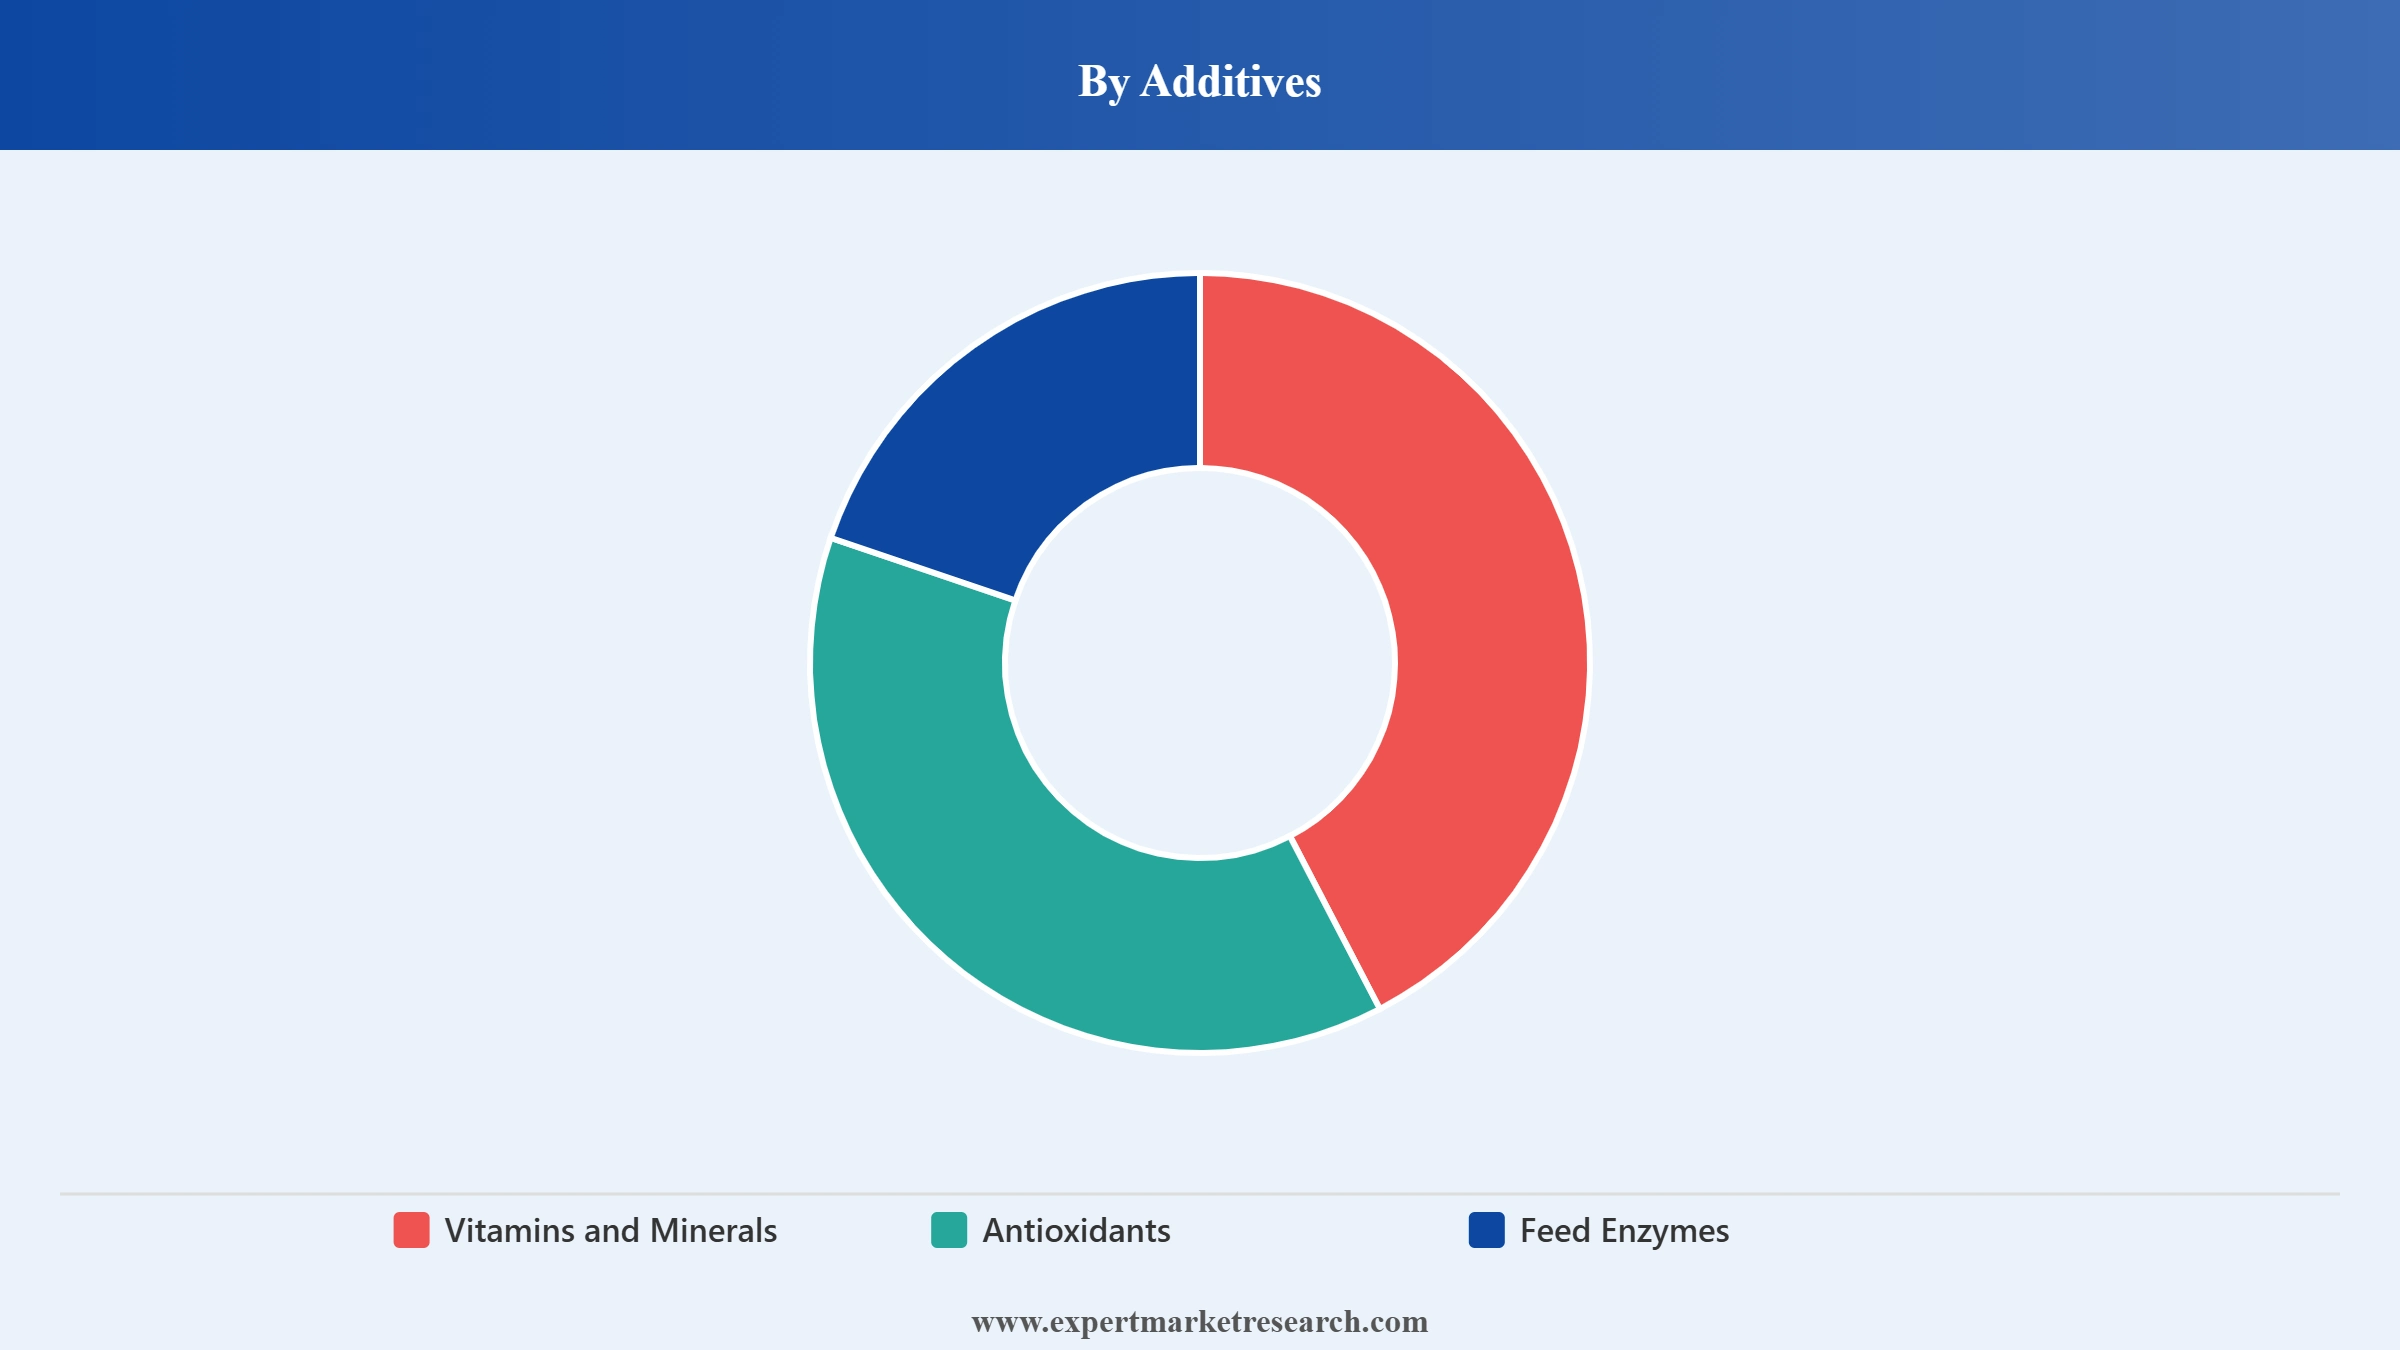
Key Insight: Vitamins and minerals form the largest additive category, supporting skeletal development, immune function, and reproductive performance across farmed species, with premix suppliers steadily widening the approved toolkit available to formulators. Antioxidants protect feed lipids and fish oil fractions from oxidative spoilage during storage and transport. Feed enzymes improve nutrient digestibility and feed conversion, particularly in plant-protein-heavy formulations. Others cover binders, pigments, and palatability enhancers used in smaller, species-specific volumes.
Market Breakup by Product Form
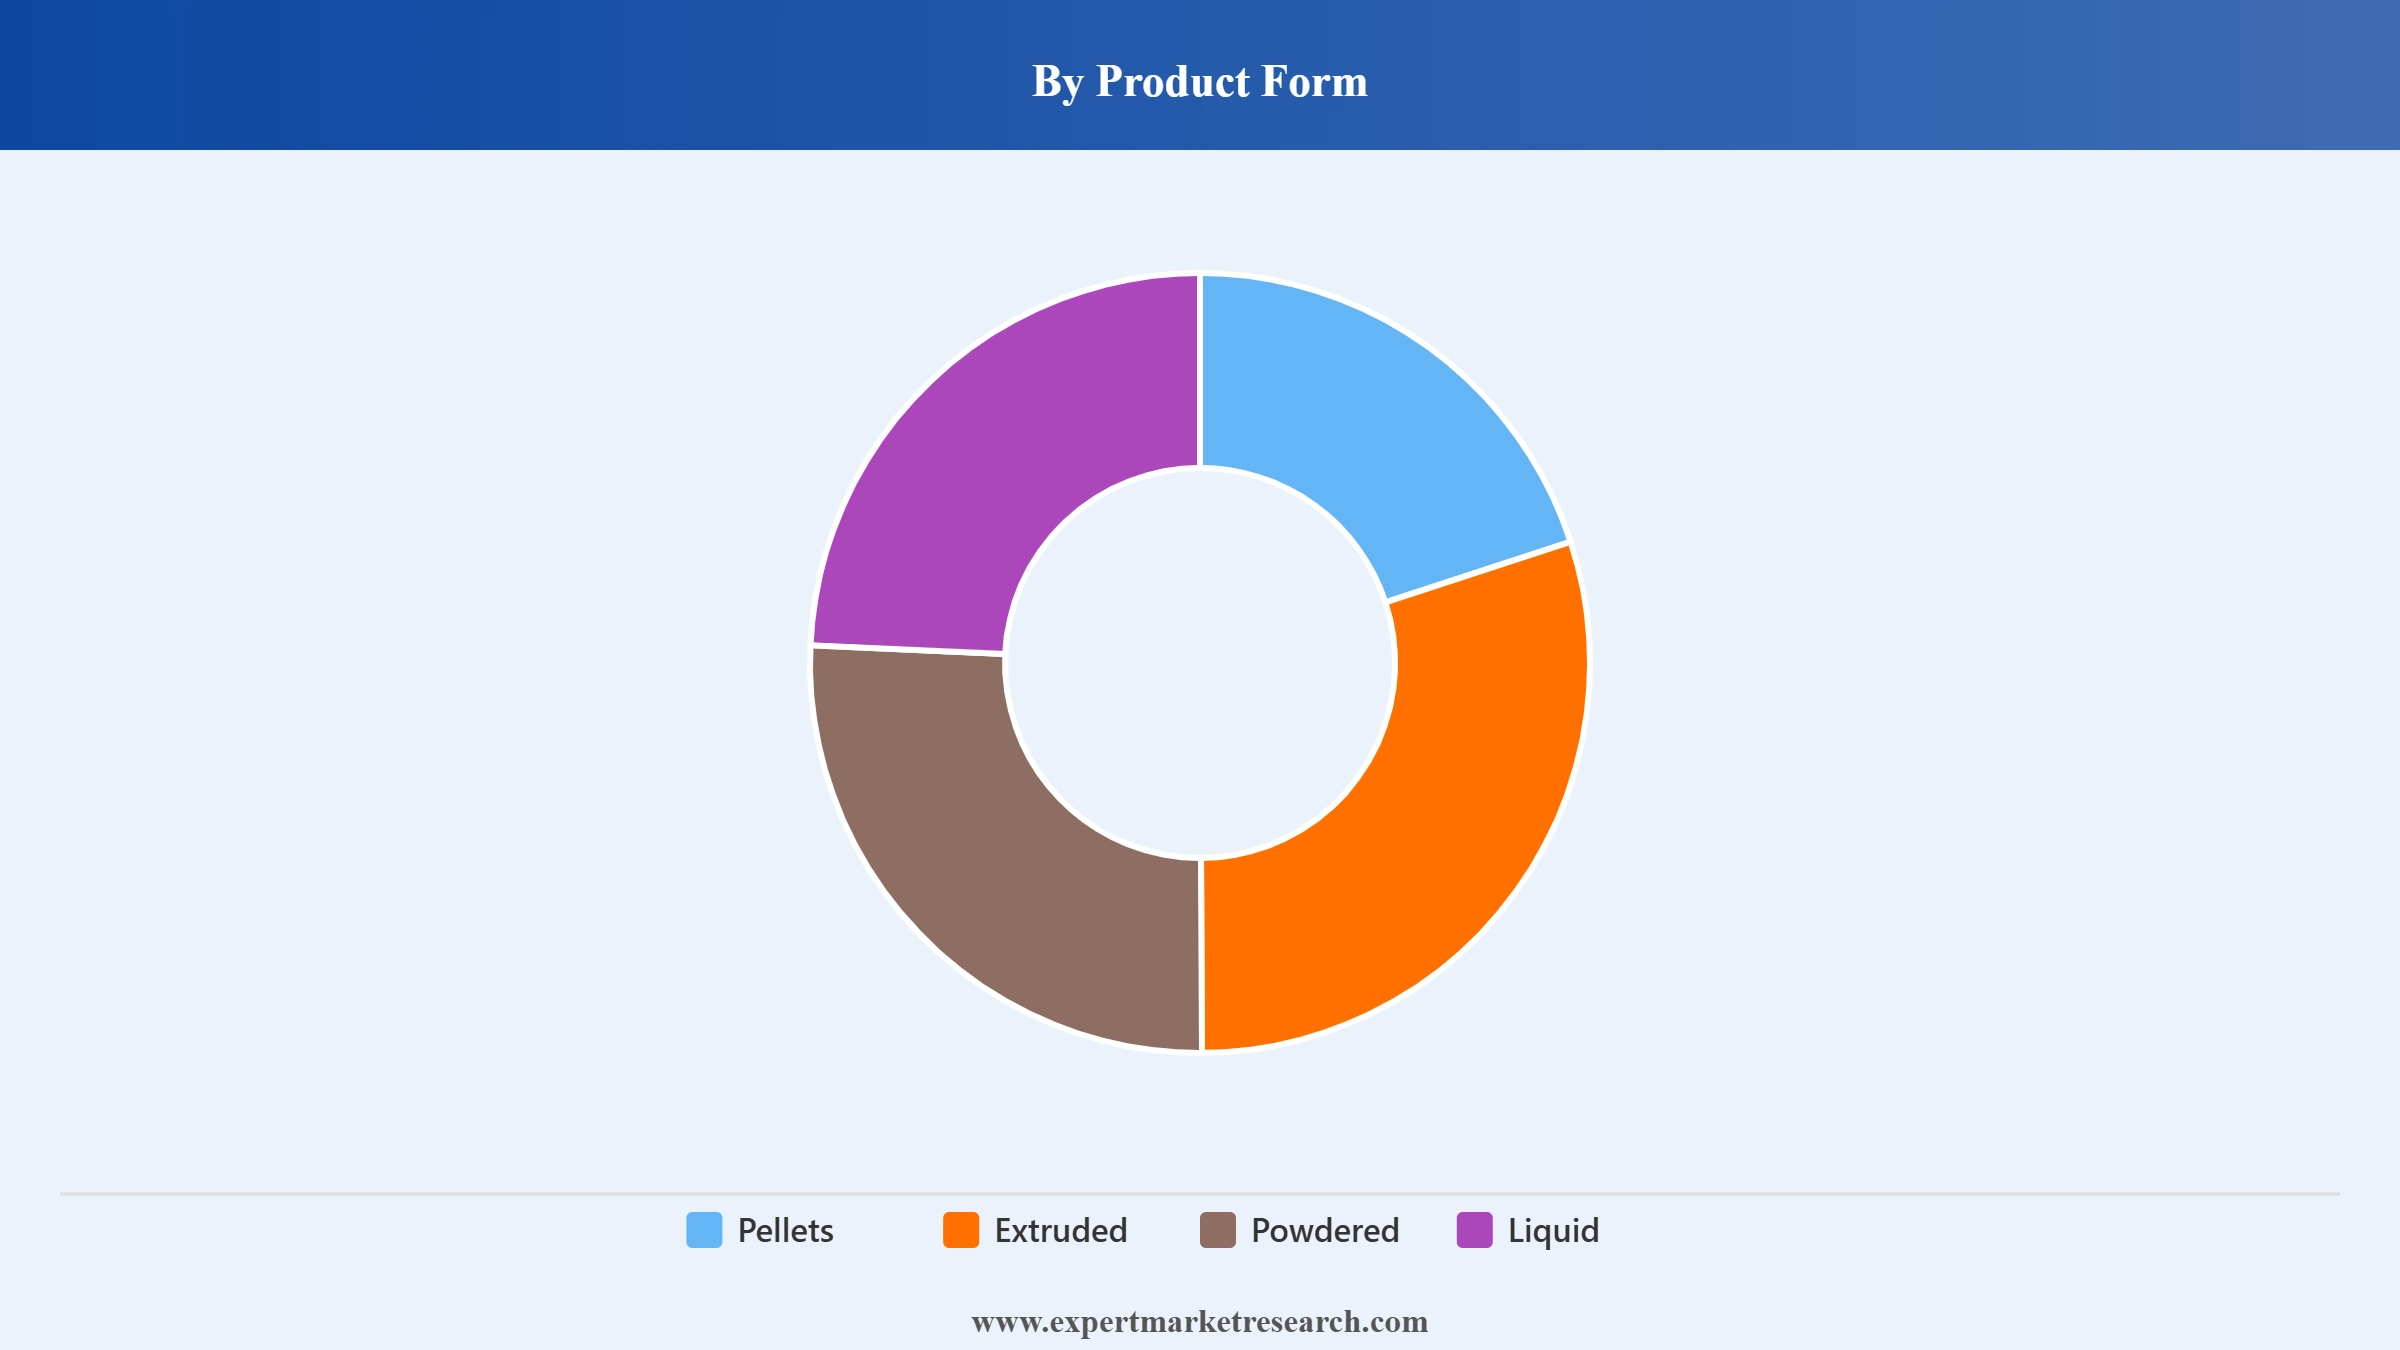
Key Insight: Pellets remain the most widely used product form owing to their low production cost, ease of handling, and suitability for a broad range of pond-reared species. Extruded feeds are gaining preference for carnivorous and high-value species because the process improves digestibility, floatation control, and water stability. Powdered feeds serve hatchery and larval-stage nutrition where fine particle size supports early feeding success. Liquid feeds remain a smaller category, used mainly as top-dressing supplements or nutrient carriers blended into base diets at the farm level.
Market Breakup by Region
Key Insight: Asia Pacific dominates on the strength of China, India, Vietnam, and Indonesia's combined freshwater and shrimp farming output, supported by dense feed mill networks and domestic ingredient supply chains. Latin America, anchored by Ecuador's shrimp exports and Brazil's tilapia production, is registering the fastest regional growth. Europe sustains premium demand through Norwegian salmon and trout farming, while North America combines catfish, trout, and land-based salmon projects. Middle East and Africa contribute a smaller but rising base as food security programmes fund new capacity.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By species, marine shrimps dominate the aquaculture feed market owing to high stocking densities and intensive pond and cage culture across major producing countries
Marine shrimp farming requires precisely formulated starter, grower, and finisher diets to sustain the high stocking densities used in intensive pond and cage systems, making it the largest single species category within the aquaculture feed market. Formulators compete on pellet water stability, digestibility, and disease-resistance support, since feed typically represents the largest variable cost in commercial shrimp operations. Ecuador, India, Vietnam, and Indonesia anchor global shrimp feed demand, supported by export-oriented processing industries that reward consistent, high-performance feed formulations overall.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Marine shrimps are also the fastest-growing species category as Latin American and Asian producers expand capacity to meet export demand. Thai Union Feedmill is backing this growth directly: in February 2026, the Bangkok-based group announced a USD 55 million aquaculture feed factory in Ecuador through its feed subsidiary, targeting an 80 percent increase in output by 2028 to support the country's fast-growing shrimp sector. Such capacity commitments reflect sustained investor confidence in shrimp farming's export trajectory across Latin America overall.
By ingredients, fish meal remains the leading protein input in the aquaculture feed market, though plant and alternative proteins are gaining ground amid tightening marine supply
Fish meal continues to anchor diets for carnivorous species such as shrimp, salmon, and marine fish because of its complete amino acid profile and high palatability, properties that plant proteins struggle to fully replicate. Formulators blend fish meal with soybean and corn-based ingredients to manage cost while preserving growth performance, and premium finisher diets for high-value species still carry meaningful fish meal inclusion rates. This dependence keeps fish meal the largest ingredient category by value within the aquaculture feed market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Alternative proteins are the fastest-growing ingredient category as marine supply tightens, and formulators qualify new inputs to protect feed conversion ratios across farmed species. Enthos is backing this shift directly: in May 2025, the Colombian insect producer secured a joint investment from S2G Investments and Ocean 14 Capital to build a large black soldier fly facility, converting organic waste into protein and oil for aquaculture feed. Such funding reflects growing confidence in insect-based substitutes for fish meal and fish oil.
By additives, vitamins and minerals lead the aquaculture feed market as formulators prioritise skeletal development and immune support across farmed species
Vitamins and minerals remain the largest additive category because they address fundamental nutritional requirements, skeletal mineralisation, immune competence, and reproductive performance that farmed species cannot otherwise meet from base ingredients alone. Premix suppliers continue refining delivery forms to improve stability through extrusion and storage, since heat and moisture exposure can degrade sensitive vitamin compounds before feed reaches the farm. This consistent, non-discretionary demand keeps the category central to formulation budgets across the major farmed species groups that formulators currently serve.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Feed enzymes remain the single fastest-growing additive category as formulators lean further into plant-based protein blends that require additional support for nutrient breakdown and absorption across farmed species. Novonesis is deepening this focus directly: in February 2025, the company acquired full ownership of the long-running Feed Enzymes Alliance joint venture for EUR 1.5 billion, consolidating enzyme development capacity that serves aquaculture alongside broader animal nutrition segments. Such consolidation underlines the commercial weight now attached to enzyme innovation across the category.
By product form, extruded feed is the fastest-growing format in the aquaculture feed market as producers prioritise digestibility and water stability for high-value species
Pellets remain the dominant product form across the aquaculture feed market because they are inexpensive to produce and suit the broad base of pond-reared carp, tilapia, and catfish farming that makes up the bulk of global feed volumes. Pelleting processes require lower capital investment than extrusion, making them accessible to small and mid-scale feed mills serving fragmented freshwater farming regions across Asia, Latin America, and Africa, where cost sensitivity remains a central purchasing consideration for most farmers operating at scale.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Extruded feed is gaining market share fastest as shrimp and salmonid producers prioritise the superior digestibility, floatation control, and water stability that extrusion delivers relative to conventional pelleting. Kazakhstan illustrates this pull: in July 2026, the government began construction of the country's first extruded aquafeed plant, a 25,000-tonne facility backed by its Ministry of Agriculture to supply trout and sturgeon diets previously met only through imports. Such projects reflect extrusion's reach into markets that still lack domestic high-protein feed capacity.
Asia Pacific leads the aquaculture feed market through dense feed mill networks and the world's largest combined freshwater and shrimp farming output
Asia Pacific commands the largest share of the aquaculture feed market, anchored by China, India, Vietnam, and Indonesia's combined freshwater and shrimp farming output. Dense feed mill networks, large domestic soybean and corn supply chains, and decades of farming intensification give regional producers consistent access to both raw materials and distribution reach. Government support for export-oriented shrimp and pangasius farming across Vietnam and Indonesia reinforces feed demand, while China's scale in carp and tilapia farming anchors broad freshwater feed consumption.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Latin America is registering the fastest regional growth as Ecuador's shrimp export industry and Brazil's tilapia production both scales rapidly. BioMar is backing this expansion directly: in February 2026, the company completed the acquisition of the remaining stake in BioMar Ecuador from its Lanec family partner, taking full ownership while planning to lift capacity from 300,000 to 410,000 tonnes in 2026 through debottlenecking and a new pelletised line. Such commitments underline the region's growing weight within the aquaculture feed market.
The competitive landscape among aquaculture feed companies is shaped by backward integration into ingredient sourcing, premix capability, and regional feed mill networks built close to farm clusters across Asia, Latin America, and Europe. Scale advantages in soybean, corn, and marine ingredient procurement let the largest companies manage raw material volatility more effectively than smaller regional producers facing tighter margins.
Aquaculture feed market players are investing in alternative protein qualification, enzyme and additive innovation, and extrusion capacity to serve premium shrimp and salmonid segments where formulation quality commands pricing power. Many are pursuing acquisitions of regional ingredient and feed mill assets to widen distribution reach rather than relying solely on organic expansion, while strengthening technical support offered to large commercial farm customers.
Founded in 1865 and headquartered in Wayzata, Minnesota, United States, Cargill supports the market through its animal nutrition and aqua nutrition divisions, supplying formulated diets and premix ingredients across major farmed species. Its international sourcing network spans grain, oilseed, and marine ingredient supply chains, giving it procurement scale.
Founded in 1902 and headquartered in Chicago, Illinois, United States, Archer Daniels Midland supports the market through its animal nutrition segment, supplying amino acids, premixes, and specialty ingredients. Its integrated grain processing and oilseed crushing operations give it direct access to soybean meal and corn-based inputs.
Founded in 1980 and headquartered in Nicholasville, Kentucky, United States, Alltech serves the market through yeast based and mycotoxin management technologies applied across shrimp, salmon, and freshwater fish nutrition. Its global bioscience centres support applied research into gut health and feed efficiency.
Founded in 1994 and headquartered in Amersfoort, Netherlands, Nutreco serves the market through its global aquafeed division, supplying formulated diets across salmon, shrimp, and marine fish production in more than a dozen countries. It combines premix manufacturing with species specific nutrition programmes.
Other key players in the market include Ridley Corporation Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global aquaculture feed market trends 2026 report. Discover revenue-critical shrimp, salmon, and tilapia growth drivers before competitors act. Explore EMR's full analysis of the global market and secure your copy today to assess ingredient sourcing, species demand, and regional expansion opportunities shaping the forecast period ahead.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate volume of 52.33 Million Tons.
The market is projected to grow at a CAGR of 5.30% between 2026 and 2035.
By 2035, the market is estimated to reach 87.71 Million Tons.
Expanding alternative protein qualification, investing in extrusion and premix capacity, pursuing regional feed mill consolidation, and strengthening species-specific nutrition programmes for shrimp, salmon, and tilapia production.
Key trends aiding market expansion include the rising use of natural resources and sustainable raw materials to produce aquaculture feed by manufacturers, rising aquaculture production in EU and APAC, and adoption of advanced technologies to produce quality aquafeed.
Regions considered in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
Based on species, the market is divided into carp, marine shrimps, tilapias, catfishes, marine fishes, salmons, freshwater (FW) crustaceans, and trouts, among others.
Soybean, corn, fish meal, fish oil, and additives are commonly used ingredients in aquaculture feed.
The significant product forms of aquaculture feed are pellets, extruded, powdered, and liquid.
The key players in the market include Archer Daniels Midland Company, Cargill, Incorporated, Ridley Corporation Limited, Nutreco N.V., and Alltech, among others.
Companies face volatile fish meal and fish oil supply, fluctuating soybean and corn input costs, tightening environmental regulation, and competition from informal, farm-made feed in price-sensitive markets.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Species |
|
| Breakup by Ingredients |
|
| Breakup by Additives |
|
| Breakup by Product Form |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




