

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
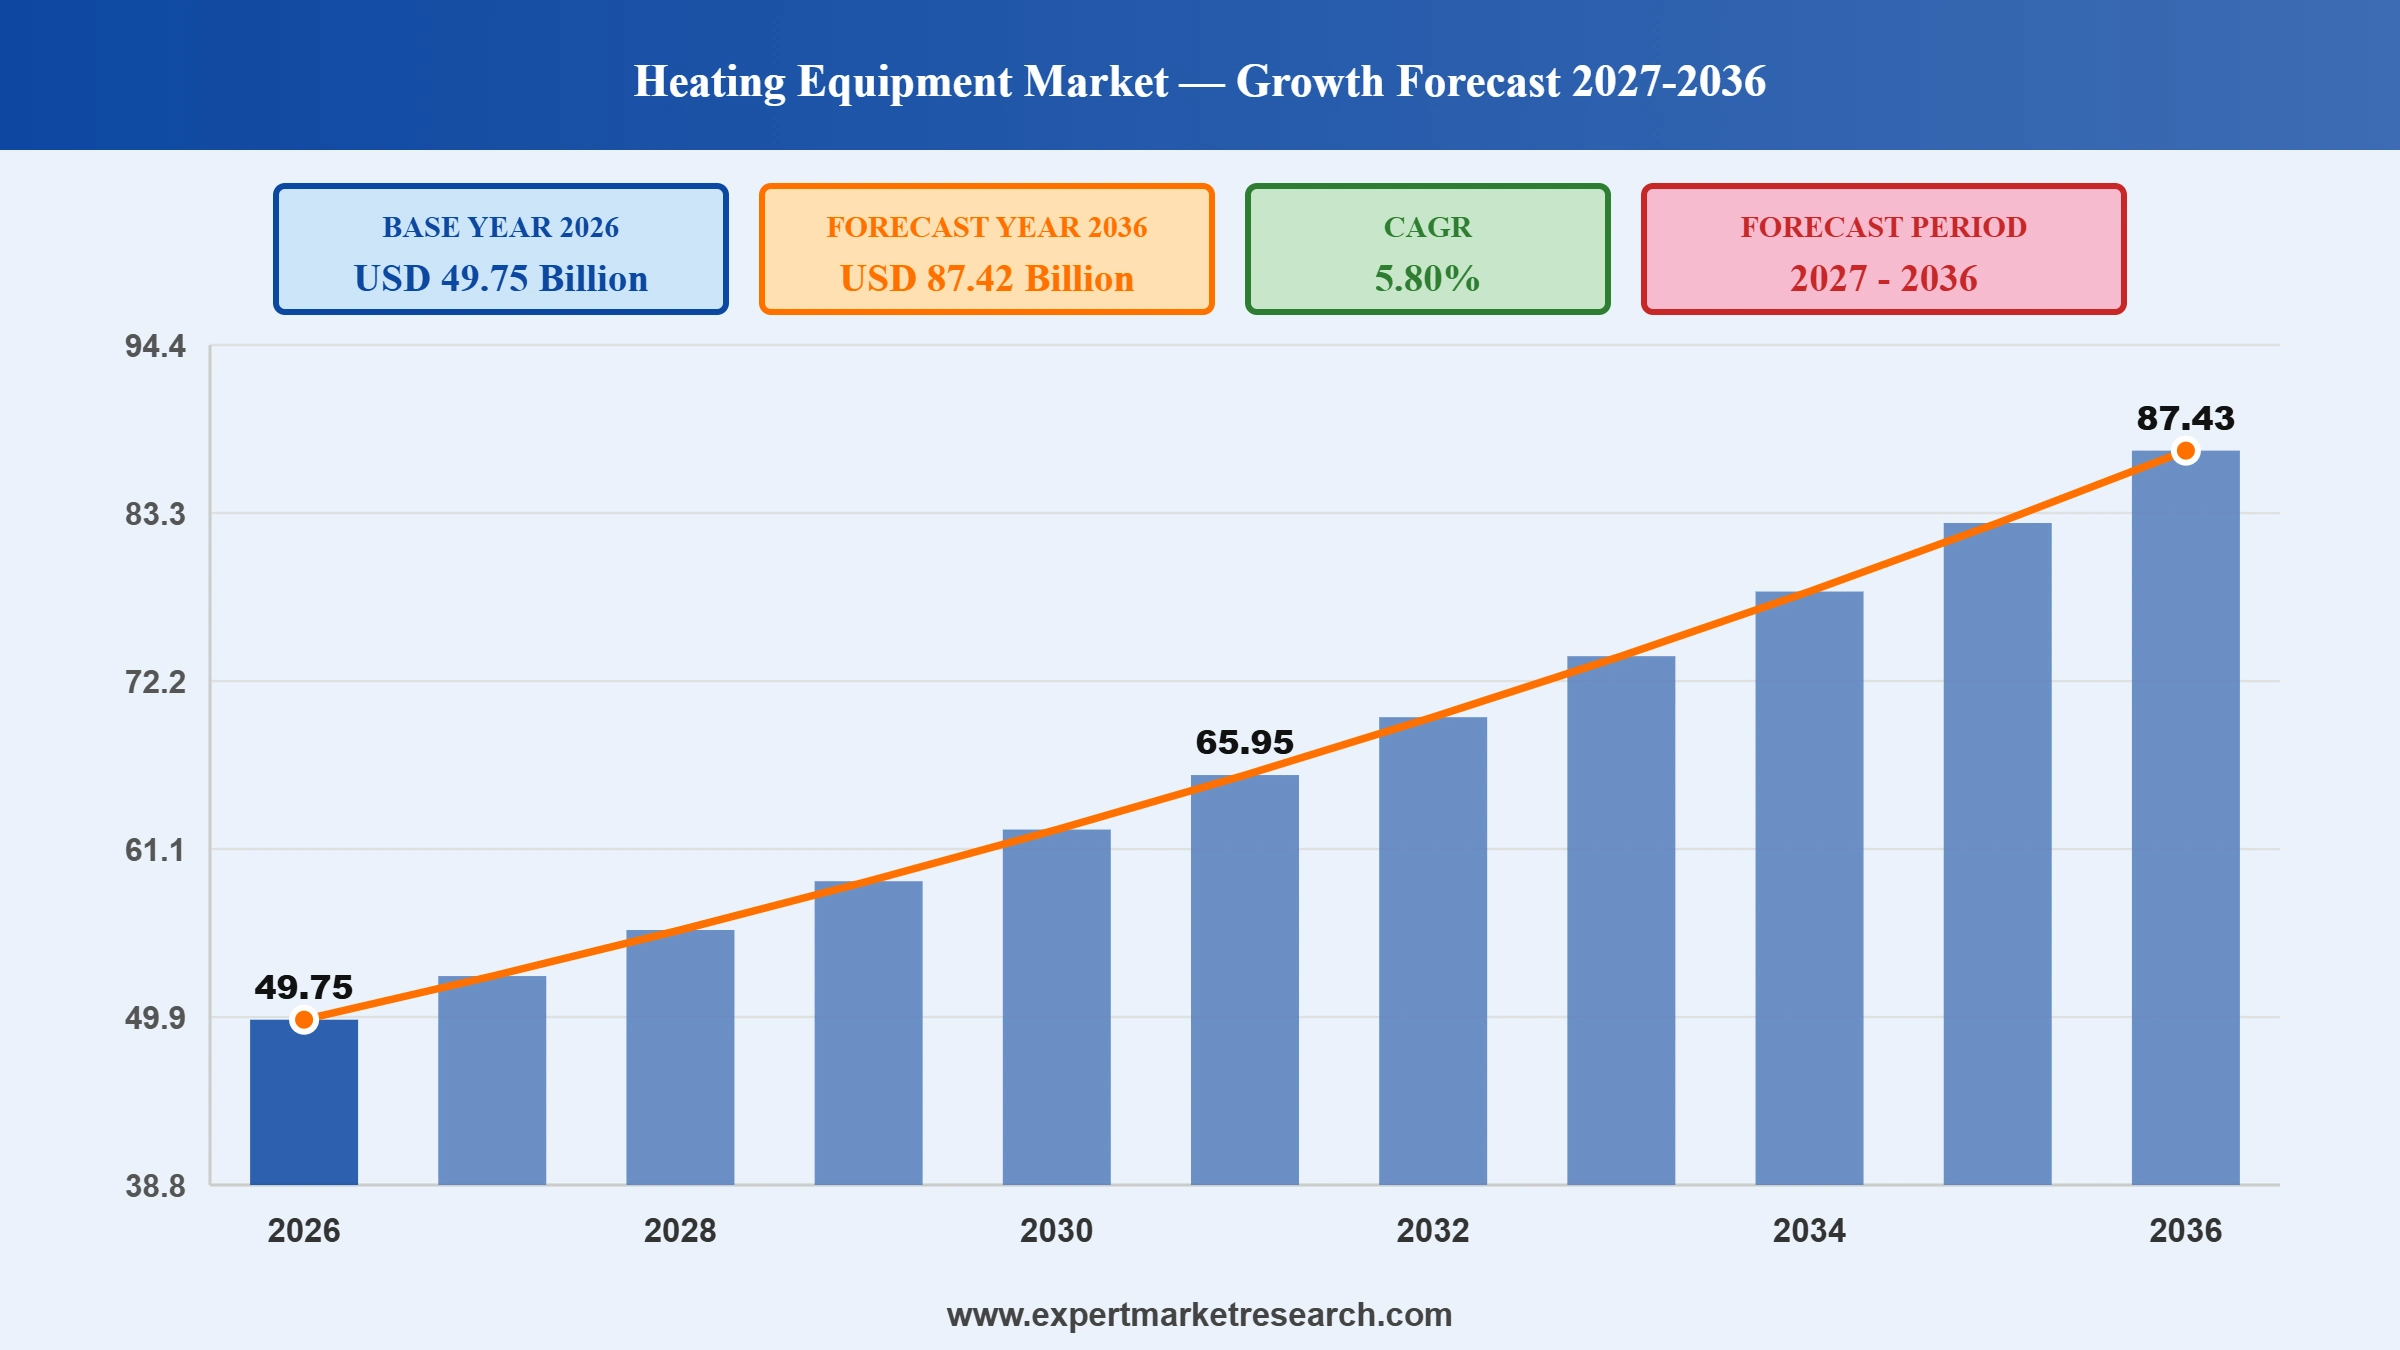
The global heating equipment market attained a value of USD 47.02 Billion in 2025 and is projected to expand at a CAGR of 5.80% through 2035. The market is further expected to achieve USD 82.63 Billion by 2035, driven by the shift toward electrified low-carbon heating, building decarbonisation rules, steady replacement demand for furnaces and boilers, and wider adoption of heat pumps across residential, commercial and industrial buildings.
Policy-backed demand can be uneven. The UK Department for Energy Security and Net Zero reported 10,693 retrofit heat pump installations in the three months ended March 2026, 22% fewer than a year earlier, against 53,265 for full-year 2025, as covered in June 2026. The government's target of at least 450,000 installations a year by 2030 sits far above that pace. Equipment makers therefore watch grant design closely, because stop-start support can delay purchases and distort order books even where long-term demand for low-carbon heating stays firm.
Regulation is being rewritten in Europe's largest heating market. Germany's governing coalition said it would abolish the current heating law and rename it the Building Modernisation Act, aiming for more technology openness and simpler procedures, with adoption targeted for the end of February 2026, as reported in January 2026. Manufacturers of boilers, heat pumps and controls are therefore planning around a framework that rewards flexibility rather than a single mandated technology, which in turn shapes investment in new product platforms, installer training and supply agreements across the region.
Grant schemes keep steering buyers toward heat pumps. Ofgem's annual report on the Boiler Upgrade Scheme for the scheme year ended March 2026, filed in July 2026, recorded 31,104 grant payments worth GBP 233.1 million, lifting the cumulative total to 80,098 low-carbon heating systems and GBP 560.3 million. Air source heat pumps took 97.6% of grants paid since launch, which shows how concentrated public support is on a single technology route and why manufacturers of air-to-water units, cylinders and controls benefit most from scheme funding.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Bosch announced in September 2026, ahead of IFA 2026, that its Bosch and Buderus heat pumps connect to Bosch Smart Home thermostats, so heat is generated only when rooms need it and compatible models can cool through the floor-heating system in summer. The company said every Bosch Home Comfort Group heat pump is already connectable. Companies can secure installer loyalty by pairing hardware with controls that cut running costs.
Danfoss announced in July 2026 that it will exhibit at Chillventa in Nuremberg in October 2026, showing propane (R290) commercial heat pump systems up to 700 kW built around new VPN variable-speed and PSN fixed-speed scroll compressors, alongside industrial heat pumps delivering process heat of up to 120 degrees Celsius. Companies can expand component portfolios for natural-refrigerant systems to win early design slots with heat pump makers.
Carrier reported in July 2026 that its exit from Riello was completed and that it had announced an exit from NORESCO, in results for the three months ended June 2026 in which it also returned about USD 640 million to shareholders. The moves narrow the group around core climate solutions. Companies can protect margins by pruning non-core units and redirecting capital toward heating and cooling growth.
Bosch Home Comfort Group made its AHR Expo debut in Las Vegas in February 2026, showing Bosch Ci and Ri water source heat pumps in 1.5, 3 and 5 ton sizes, the Hitachi air365 Max system using R-32 refrigerant, and the Bosch Inverter Ducted Split Edge heat pump for single-zone and multi-zone homes. Companies can leverage broader brand portfolios to cover residential and light commercial heat pump demand.
Carrier chairman and chief executive Dave Gitlin said in July 2026 that the US residential market should total about 7 million to 7.5 million units in 2026 as repair activity eases from unusually high levels and customers return to replacement. Carrier put residential field inventory about 25% below the prior year at the end of June 2026. Companies can leverage lean channel inventories to capture replacement demand as repair deferrals end.
Raytheon Technologies Corporation, which reports as RTX Corporation, disclosed in July 2026 sales of USD 24.7 billion for April to June 2026, up 14% reported and 16% organically, with a backlog of USD 289 billion, and lifted its 2026 adjusted sales guidance to USD 95.0 billion to USD 96.0 billion. Companies can leverage deep order backlogs to plan capacity, secure supplier commitments and fund new product programmes across industrial end markets.
Lennox announced in June 2026 that it signed a definitive agreement to acquire Heat Controller, a supplier of HVAC equipment to distributors across North America whose brands include Comfort-Aire and Century. The company said the deal should help it serve small and mid-size distributors with a wider range of equipment and could grow its share of the North American market. Companies can leverage distributor-focused brands to extend reach beyond core dealer networks.
Robert Bosch GmbH said in September 2026 that heat pump sales in Germany rose 40% to 194,500 units from January to June 2026, citing the Federal Association of the Heating Industry. The jump shows how quickly households are returning to heat pump purchases, and it gives the Bosch and Buderus brands a larger installed base for service upgrades. Companies can leverage connected products and installer training to convert rising heat pump demand into repeat customers.
This Expert Market Research's Report titled "Global Heating Equipment Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product
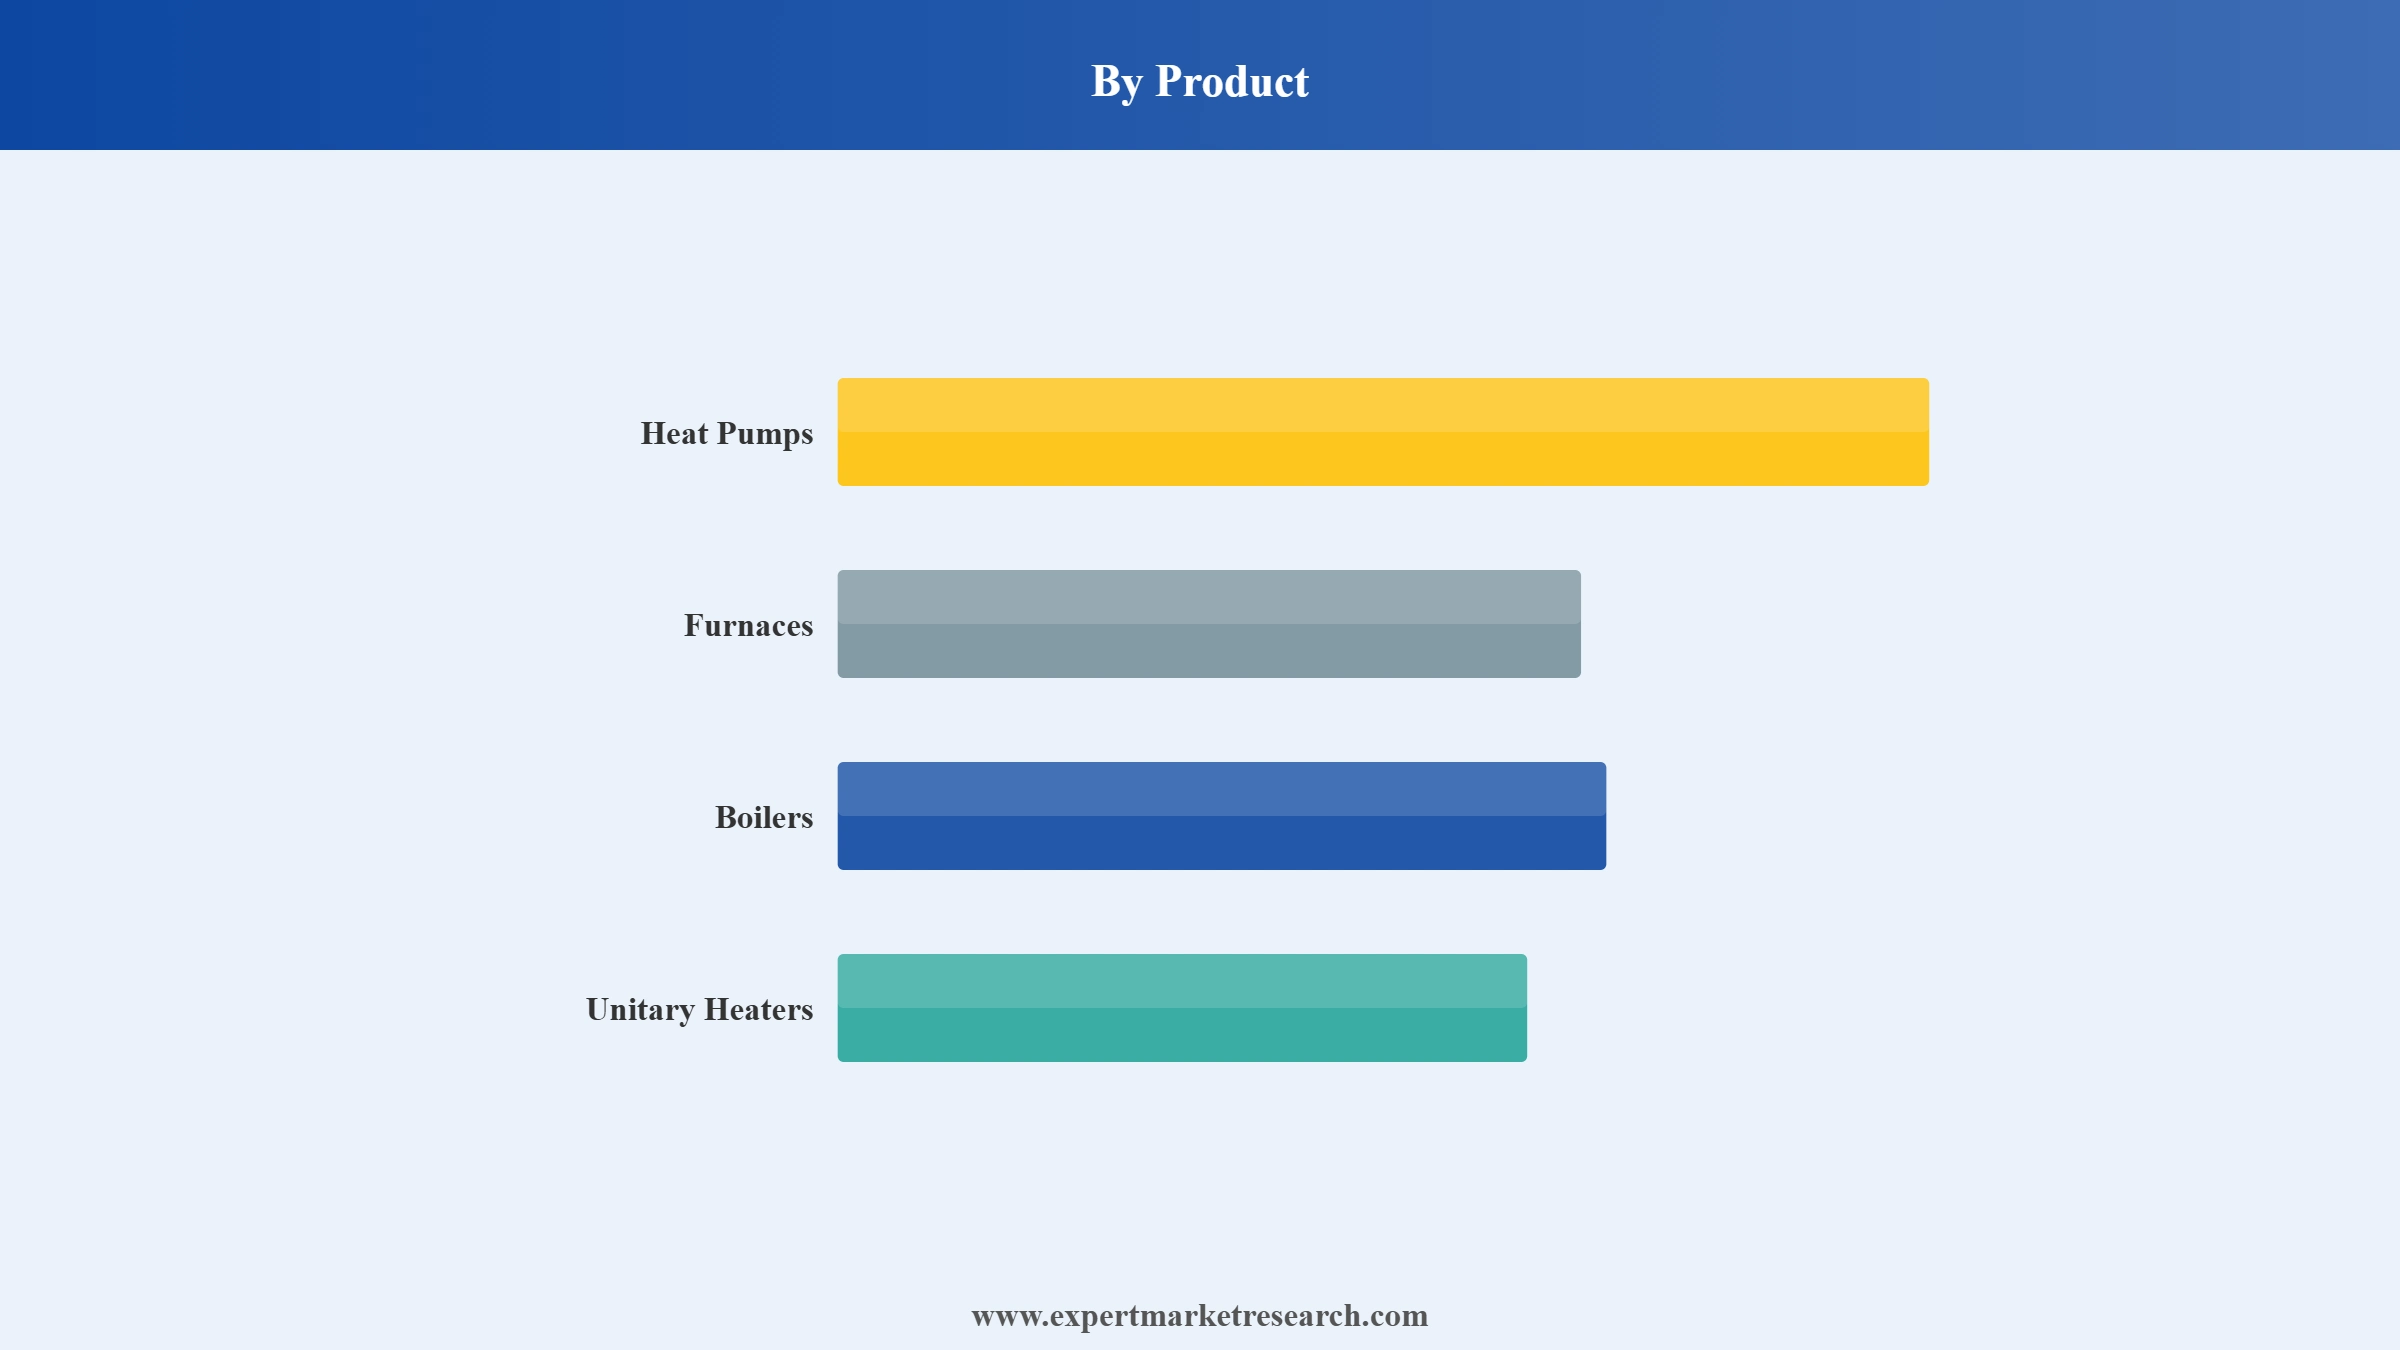
Key Insight: Heat Pumps is the leading product, with AHRI data released in June 2026 showing US air-source heat pump shipments up 1.2% in the four months ended April 2026 while central air conditioner shipments fell 7.5%; Furnaces anchor replacement demand, with AHRI reporting in August 2026 gas warm air furnace shipments of 320,281 units in June 2026, up 15.2%, although the six-month total of 1,552,934 units was down 6.2%; Boilers face changing fuel rules, with Ariston saying on its May 2026 results call that gas boiler sales in Germany were positive in the three months ended March 2026, an early recovery, while gas boilers stayed under pressure in Italy and France; Unitary Heaters are advancing in light commercial formats, with Daikin Comfort Technologies North America introducing its Nexio Max inverter-driven rooftop heat pump in July 2026 in 7.5, 8.5 and 10 ton sizes, delivering 85% of rated heating capacity at 14 degrees Fahrenheit; and Others covers water heating, where Ariston said in May 2026 that Lennox-branded water heater sales began in mid-March 2026, with significant sales expected from 2027.
Market Breakup by Application
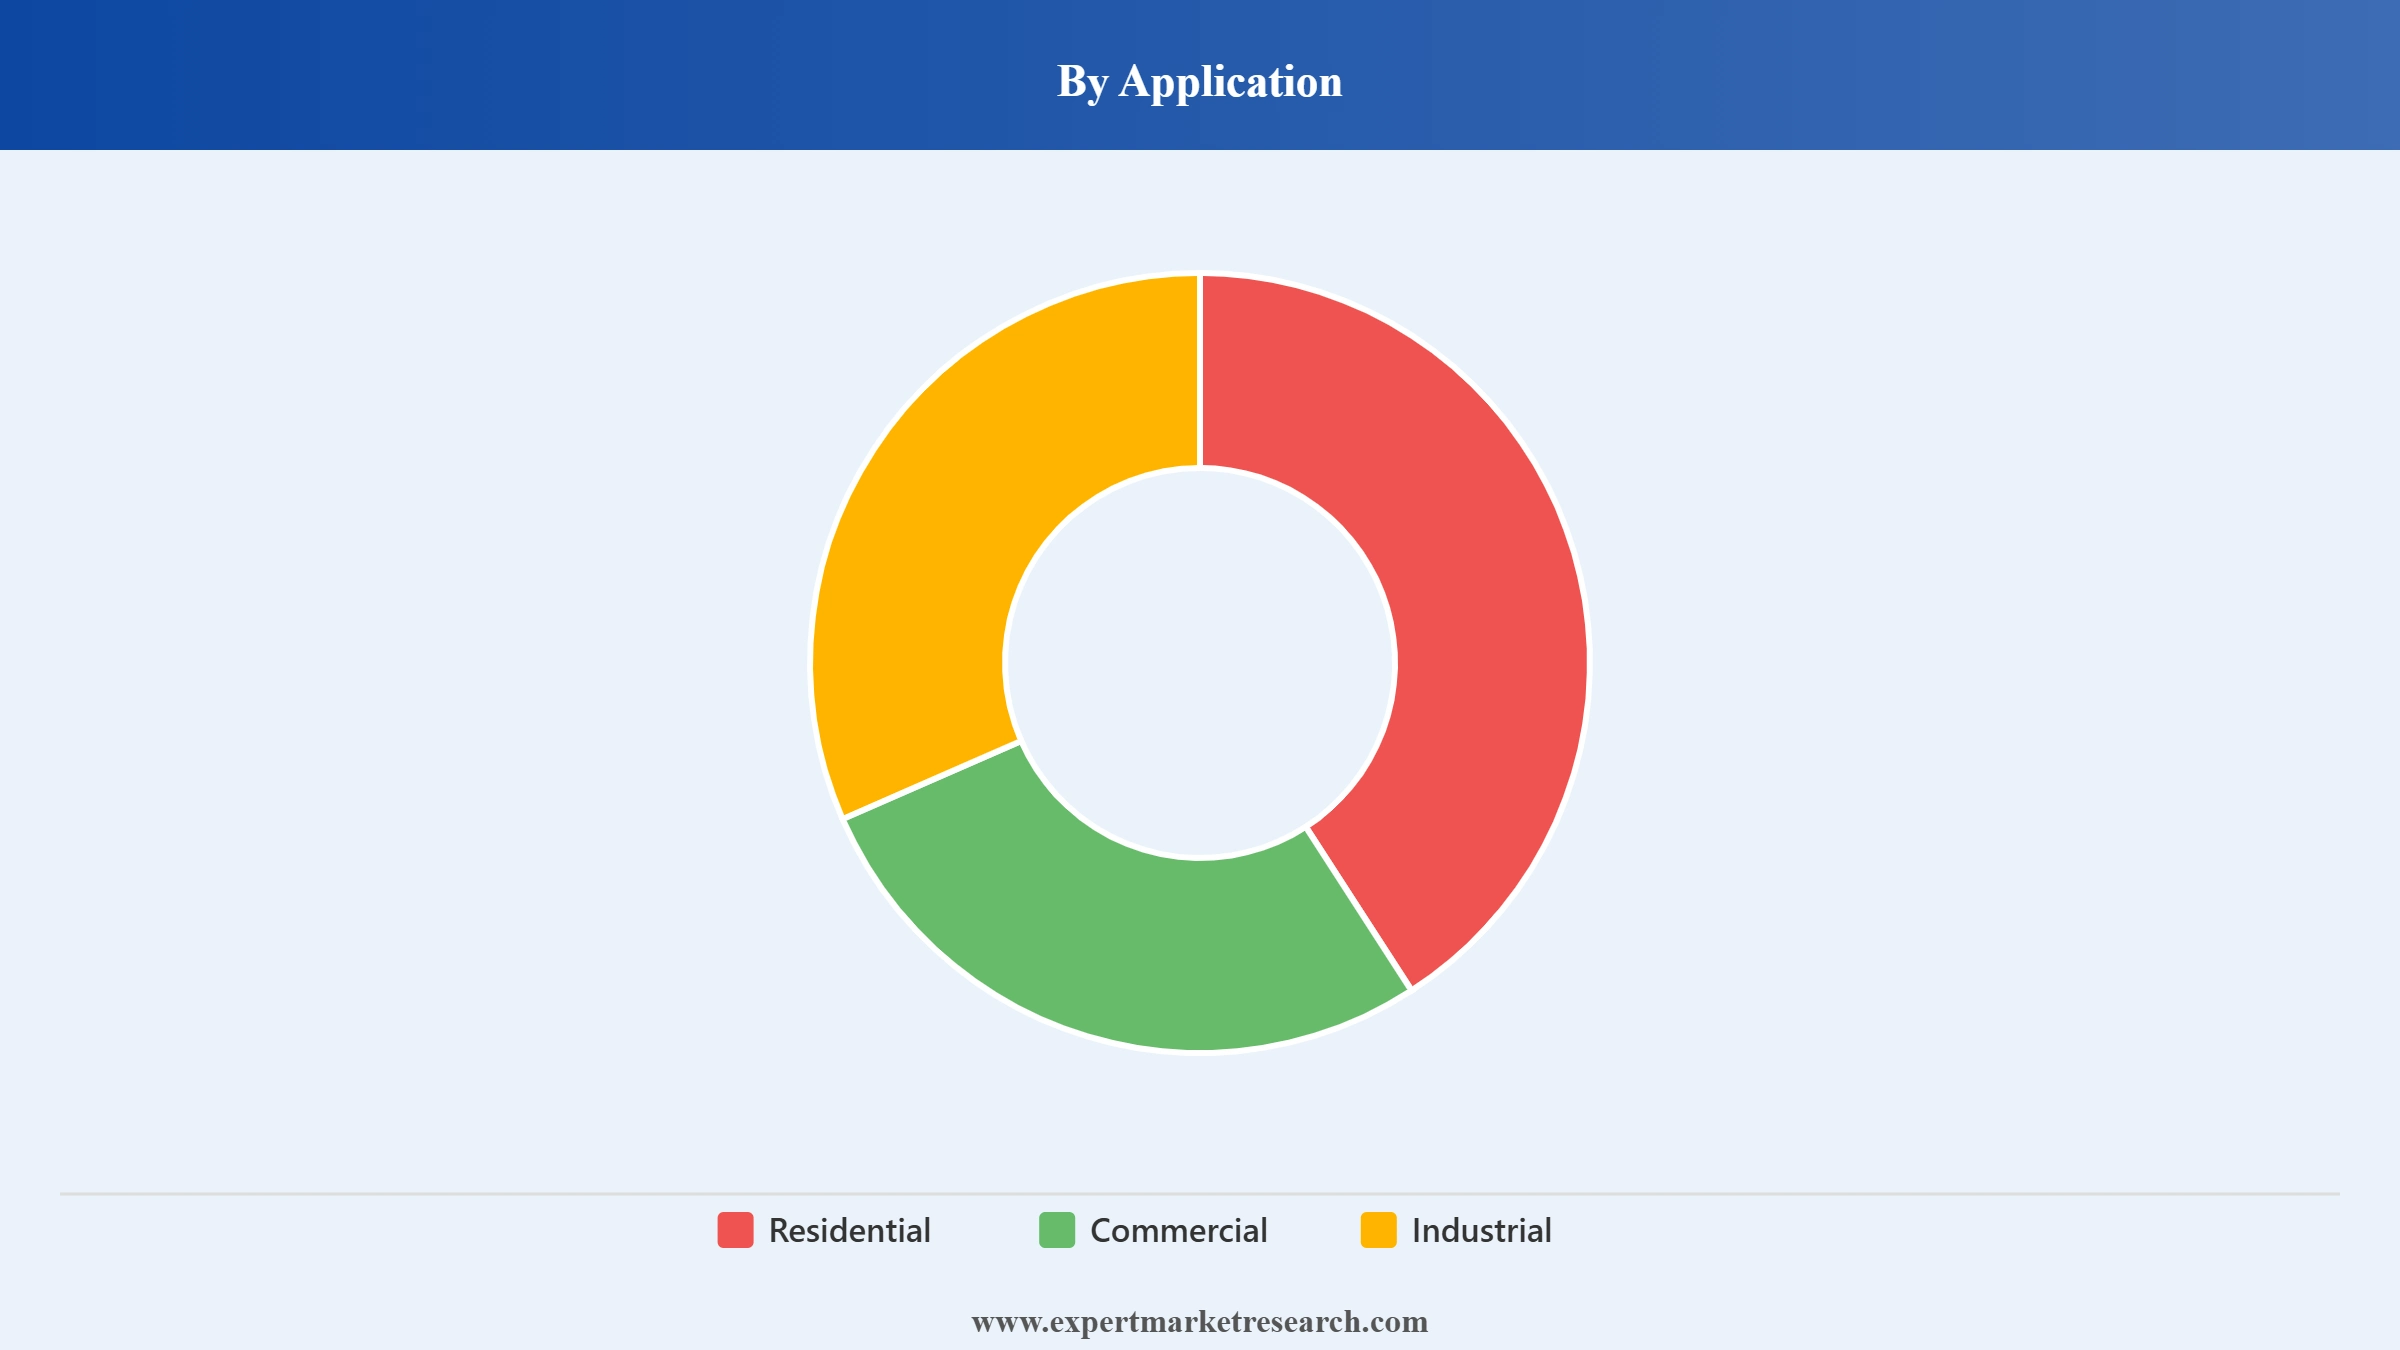
Key Insight: Residential is the leading application, with Rheem showing in February 2026 at the International Builders' Show its ProTerra hybrid heat pump water heaters, which it says use 75% less energy than standard electric water heaters, alongside a new Endeavor Line heat pump rated up to 17 SEER2; Commercial is growing on large projects, with Trane Technologies completing its acquisition of LiquidStack in March 2026, adding liquid cooling for mission-critical sites to its commercial HVAC business in the Americas; and Industrial is gaining from large-scale systems demand, with Daikin Industries announcing in June 2026 a new India research and development subsidiary, backed by INR 8 billion, to lead an R&D centre in Haryana for HVAC systems serving factories, data centers and commercial buildings.
Market Breakup by Region
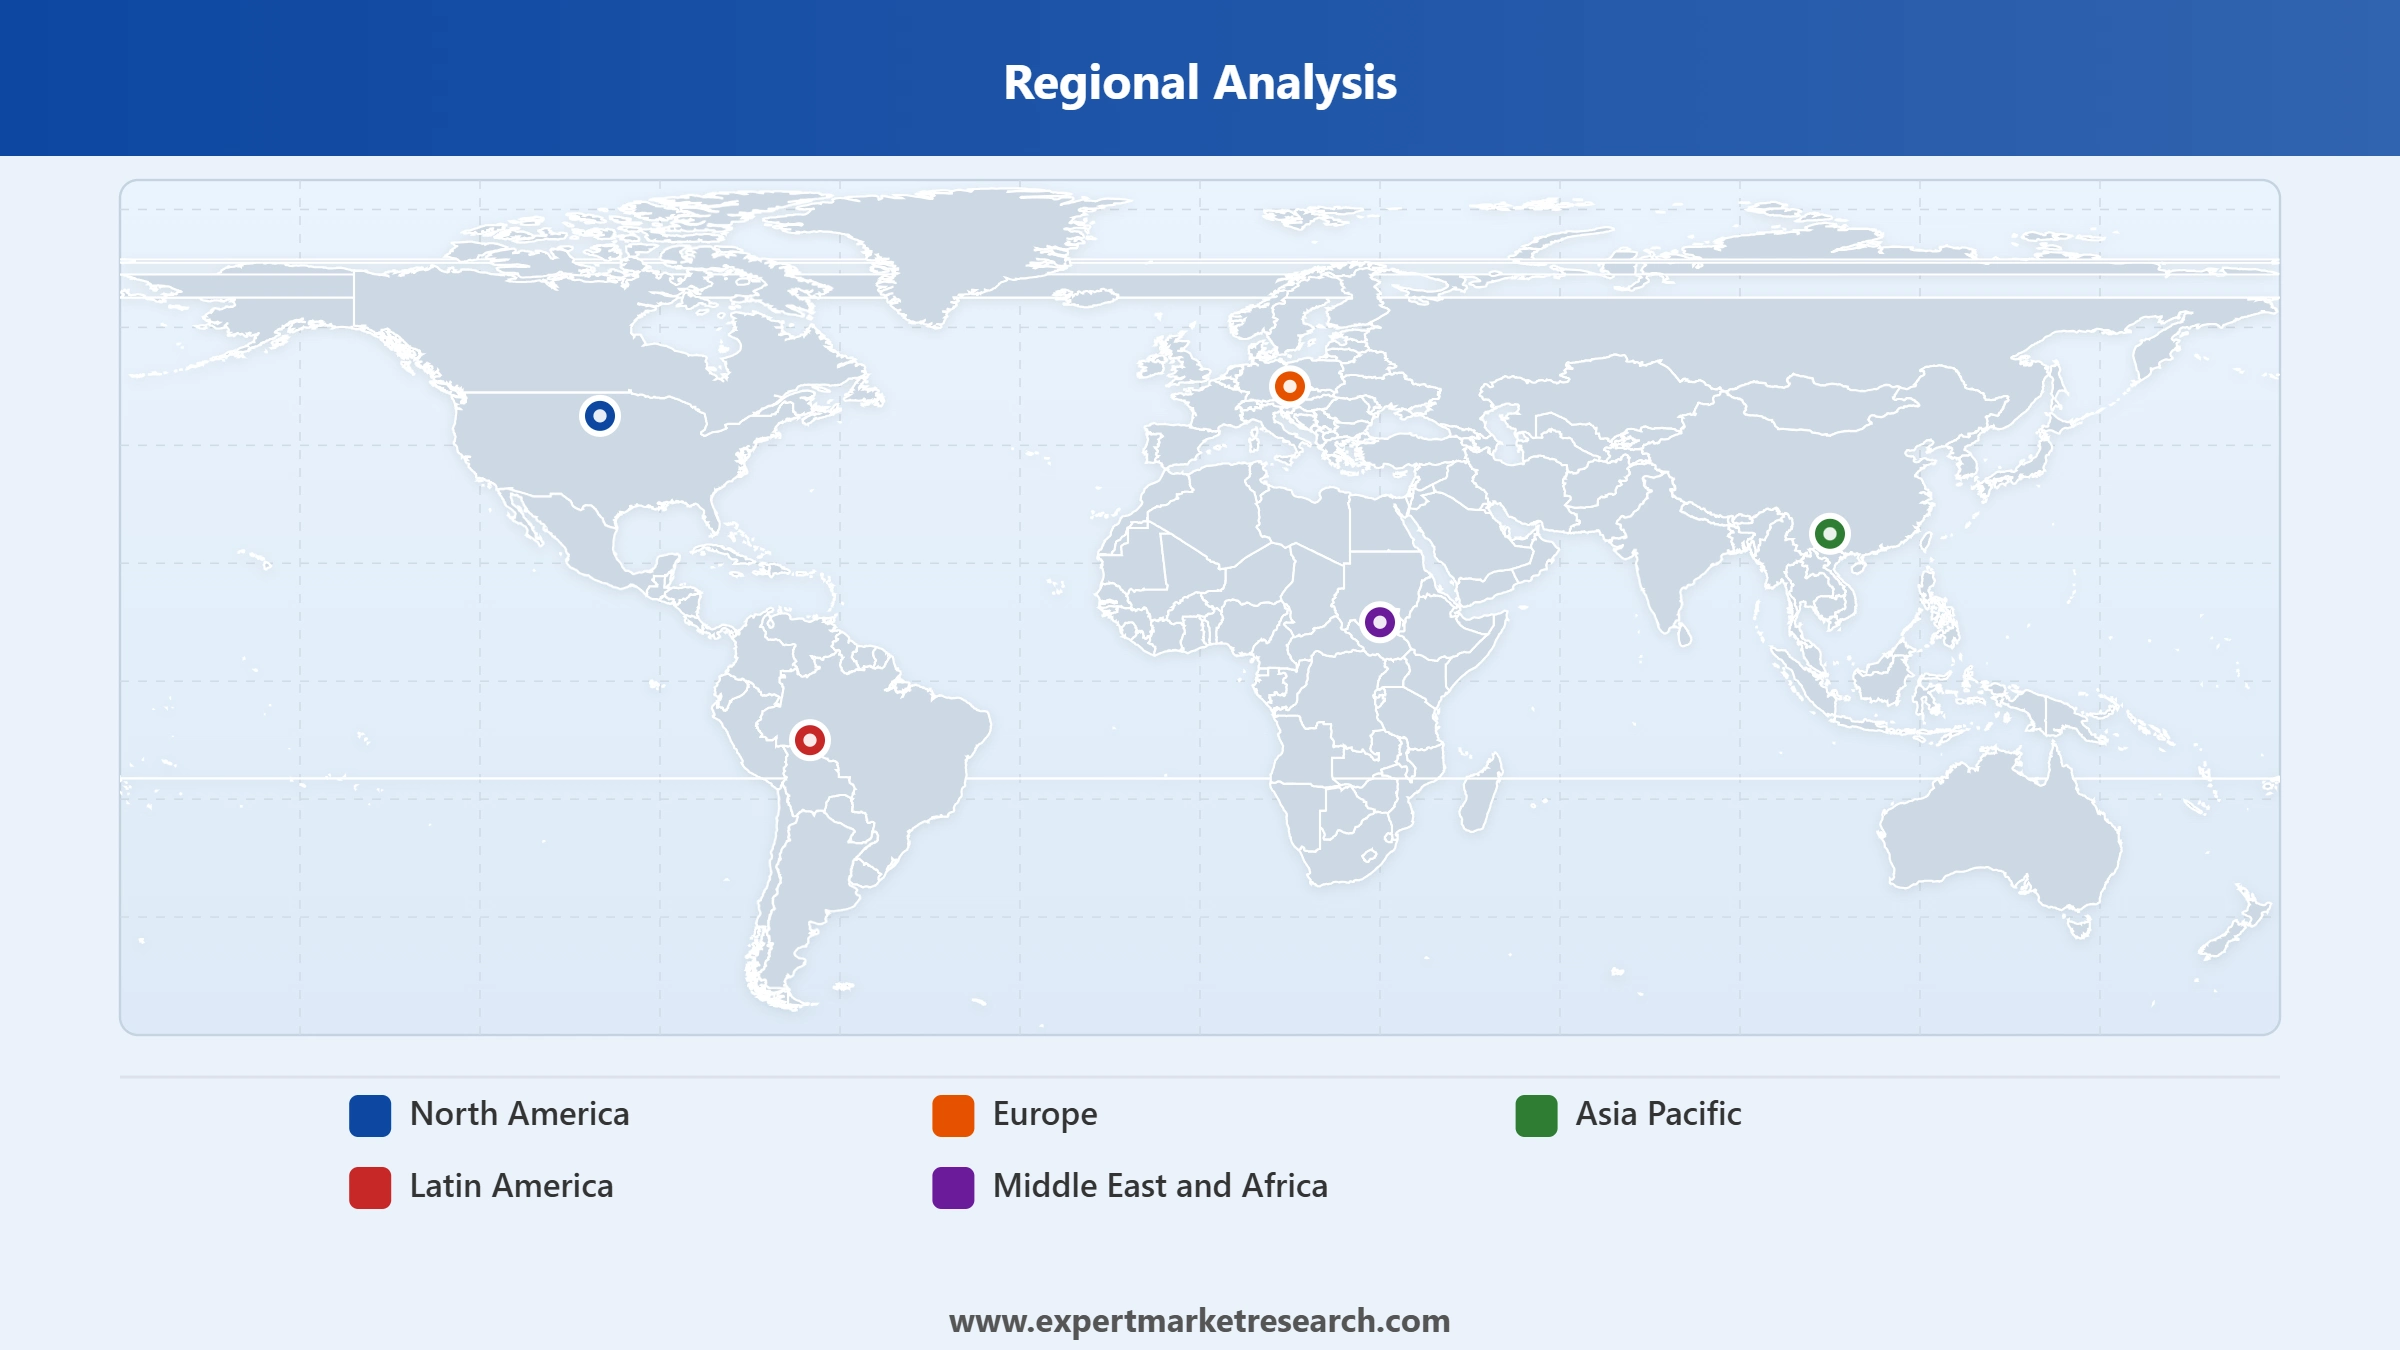
Key Insight: North America is a large replacement market, with AHRI data for January 2026, released in March 2026, showing 440,819 combined shipments of central air conditioners and air-source heat pumps, down 29.2% from a year earlier; Europe is rebuilding, with the European Heat Pump Association's figures, covered in August 2026, showing a 17% rise in heat pump sales across the three months ended March 2026 and French air-to-air units up 25%; Asia Pacific is the fastest-growing region, with Trane Technologies reporting in July 2026 Asia Pacific bookings of USD 503 million, up 33%, over April to June 2026; Latin America is turning to efficient heating, with Daikin saying in a press release carried by BNamericas in June 2026 that Chile must heat and cool more with less energy and fewer emissions; and the Middle East and Africa is adopting industrial heat pumps, with Johnson Controls introducing in September 2026 its Sabroe HitemHP range for process heat above 100 degrees Celsius in the Middle East.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By Product, Heat Pumps leads the market while Furnaces remains a steady replacement segment because heat pumps combine heating and cooling in one efficient electric unit while furnaces still serve cold-climate replacement demand.
Heat Pumps leads because one electric unit supplies both heating and cooling, which fits building decarbonisation policies. AHRI reported in May 2026 that combined US central air conditioner and air-source heat pump shipments reached 856,674 units in March 2026, up 4.6%, while heat pump shipments alone were up 0.96% for the three months ended March 2026. That points to steady rather than explosive uptake, so makers, distributors and installers should plan for a gradual conversion of existing homes and apartments.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Furnaces remains a steady replacement segment because many cold-climate homes and small buildings still depend on forced-air systems. Lennox reported in July 2026 that Home Comfort Solutions revenue fell 7% to USD 935.6 million in the three months ended June 2026 on lower residential volumes, although demand improved sequentially. The decline shows how sensitive furnace replacement is to consumer confidence and distributor stocking. Suppliers should therefore expect uneven shipments, while the ageing installed base keeps the long-term replacement pipeline intact.
By Application, Residential leads the market while Commercial grows fastest because homes account for the largest installed base while large buildings are adding heating and cooling capacity at pace.
Residential leads because homes account for the largest installed base of furnaces, boilers and heat pumps. The Ariston results call of May 2026 put approved German heat pump incentives at an average of about 27,000 units per month in the three months ended March 2026, up about 28% from a year earlier, with the scheme confirmed through 2029. That visibility helps households commit to upgrades and lets installers, distributors and equipment makers plan inventory, training and production with greater confidence.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Commercial grows fastest because large buildings are adding heating and cooling capacity, and orders are building quickly. Carrier said in July 2026 that its Commercial HVAC orders rose about 65% in the three months ended June 2026, while data centre orders rose more than 300%. Such order growth feeds later shipments and service work, so suppliers of commercial heat pumps, rooftop units and related controls can reasonably expect a much fuller backlog and steadier factory loading in coming periods ahead.
Europe leads the policy-driven shift to low-carbon heating, with subsidy schemes, building rules and fuel-switching targets steering buyers toward heat pumps across its largest national markets.
Germany shows the scale of that shift. Euronews reported in May 2026 that heat pumps made up 48% of new heating systems sold in Germany in 2025, or 299,000 units. Such a share of new sales shows how quickly buyers have moved away from fossil boilers, and it enlarges the addressable base for compressor, heat exchanger and controls suppliers serving European heat pump assemblers, installers and distributors, who must also meet tighter efficiency and refrigerant requirements.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is the fastest-growing regional market, with Danfoss reporting in March 2026 that its sales in China grew 13% in 2025, while sales in Europe ended the year down 2%, according to its annual results. Local manufacturing and service networks help suppliers capture that growth. North America, Europe, Latin America and the Middle East and Africa are expanding mainly through replacement cycles, regulation and building renovation rather than new construction, which keeps demand steadier but slower than in Asia.
The global heating equipment market is moderately fragmented, with a small group of multinational climate and building-technology groups competing alongside many regional boiler, furnace and heat pump manufacturers.
Competitive dynamics are increasingly shaped by the shift to natural refrigerants, connected controls, portfolio reshaping through acquisitions and disposals, and the ability to serve both replacement and new-build demand across several regulatory regimes.
Danfoss supplies heating and cooling components, including compressors, valves, controls and heat exchangers used in heat pumps and district energy. In May 2026, its HydronicS division, part of Danfoss Climate Solutions, signed a distribution agreement with SD Heat Exchangers B.V. extending the Benelux partnership to control valves, motorised control valves and energy meters for district heating, data centre and geothermal uses.
Carrier reports through Climate Solutions segments for the Americas, Europe, Asia Pacific with Middle East and Africa, and Transportation. For the three months ended June 2026, reported in July 2026, it posted net sales of USD 6,351 million, up 4%, and adjusted earnings per share of USD 0.86, and it raised its 2026 sales outlook to about USD 23 billion from about USD 22 billion.
Trane Technologies reports through Americas, EMEA and Asia Pacific segments. Its July 2026 report showed revenue of USD 6.35 billion for April to June 2026, up 11%, bookings of USD 7.8 billion, up 39%, and a record backlog of USD 12.1 billion, and it raised 2026 adjusted earnings guidance to USD 15.20 to USD 15.30 per share.
Lennox supplies heating, cooling, indoor air quality, refrigeration and water heating systems through its Home Comfort Solutions and Building Climate Solutions segments. In July 2026 it reported revenue of USD 1,545.3 million for the three months ended June 2026, up 3%, with diluted earnings per share of USD 7.72 and USD 132 million of share repurchases.
Other key players in the heating equipment market include Raytheon Technologies Corporation, Rotex Heating Systems GmbH, and Robert Bosch GmbH, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
For a detailed assessment of opportunities across the heating equipment market's product, application and regional segments through 2026 and beyond, connect with Expert Market Research for a customized consultation.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The global heating equipment market attained a value of USD 47.02 Billion in 2025.
The heating equipment market is projected to grow at a CAGR of 5.80% from 2026 to 2035.
The major drivers of the market include technological developments, along with government initiatives to improve energy efficiency across sectors.
The growing expenditure in the building sector is expected to be a key trend guiding the growth of the market.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
The types of heating equipment available are heat pumps, furnaces, boilers, and unitary heaters, amongst others.
Heating equipment finds applications in residential, commercial, and industrial sectors.
Key players in the heating equipment market include Danfoss A/S, Carrier Global Corporation [United Technologies Corporation], Trane Technologies plc (Ingersoll-Rand plc), Raytheon Technologies Corporation, Lennox International Inc., Rotex Heating Systems GmbH, and Robert Bosch GmbH, among others.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 82.63 Billion by 2035.
Key challenges include changing and sometimes uncertain subsidy and building rules, the higher upfront cost of heat pumps against fossil boilers, shortages of trained installers, and the shift to new refrigerants that requires redesign of products.
Key strategies include expanding heat pump ranges using natural refrigerants, adding connected controls, acquiring complementary brands and channels, and pruning non-core businesses to focus on core climate solutions.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




