

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
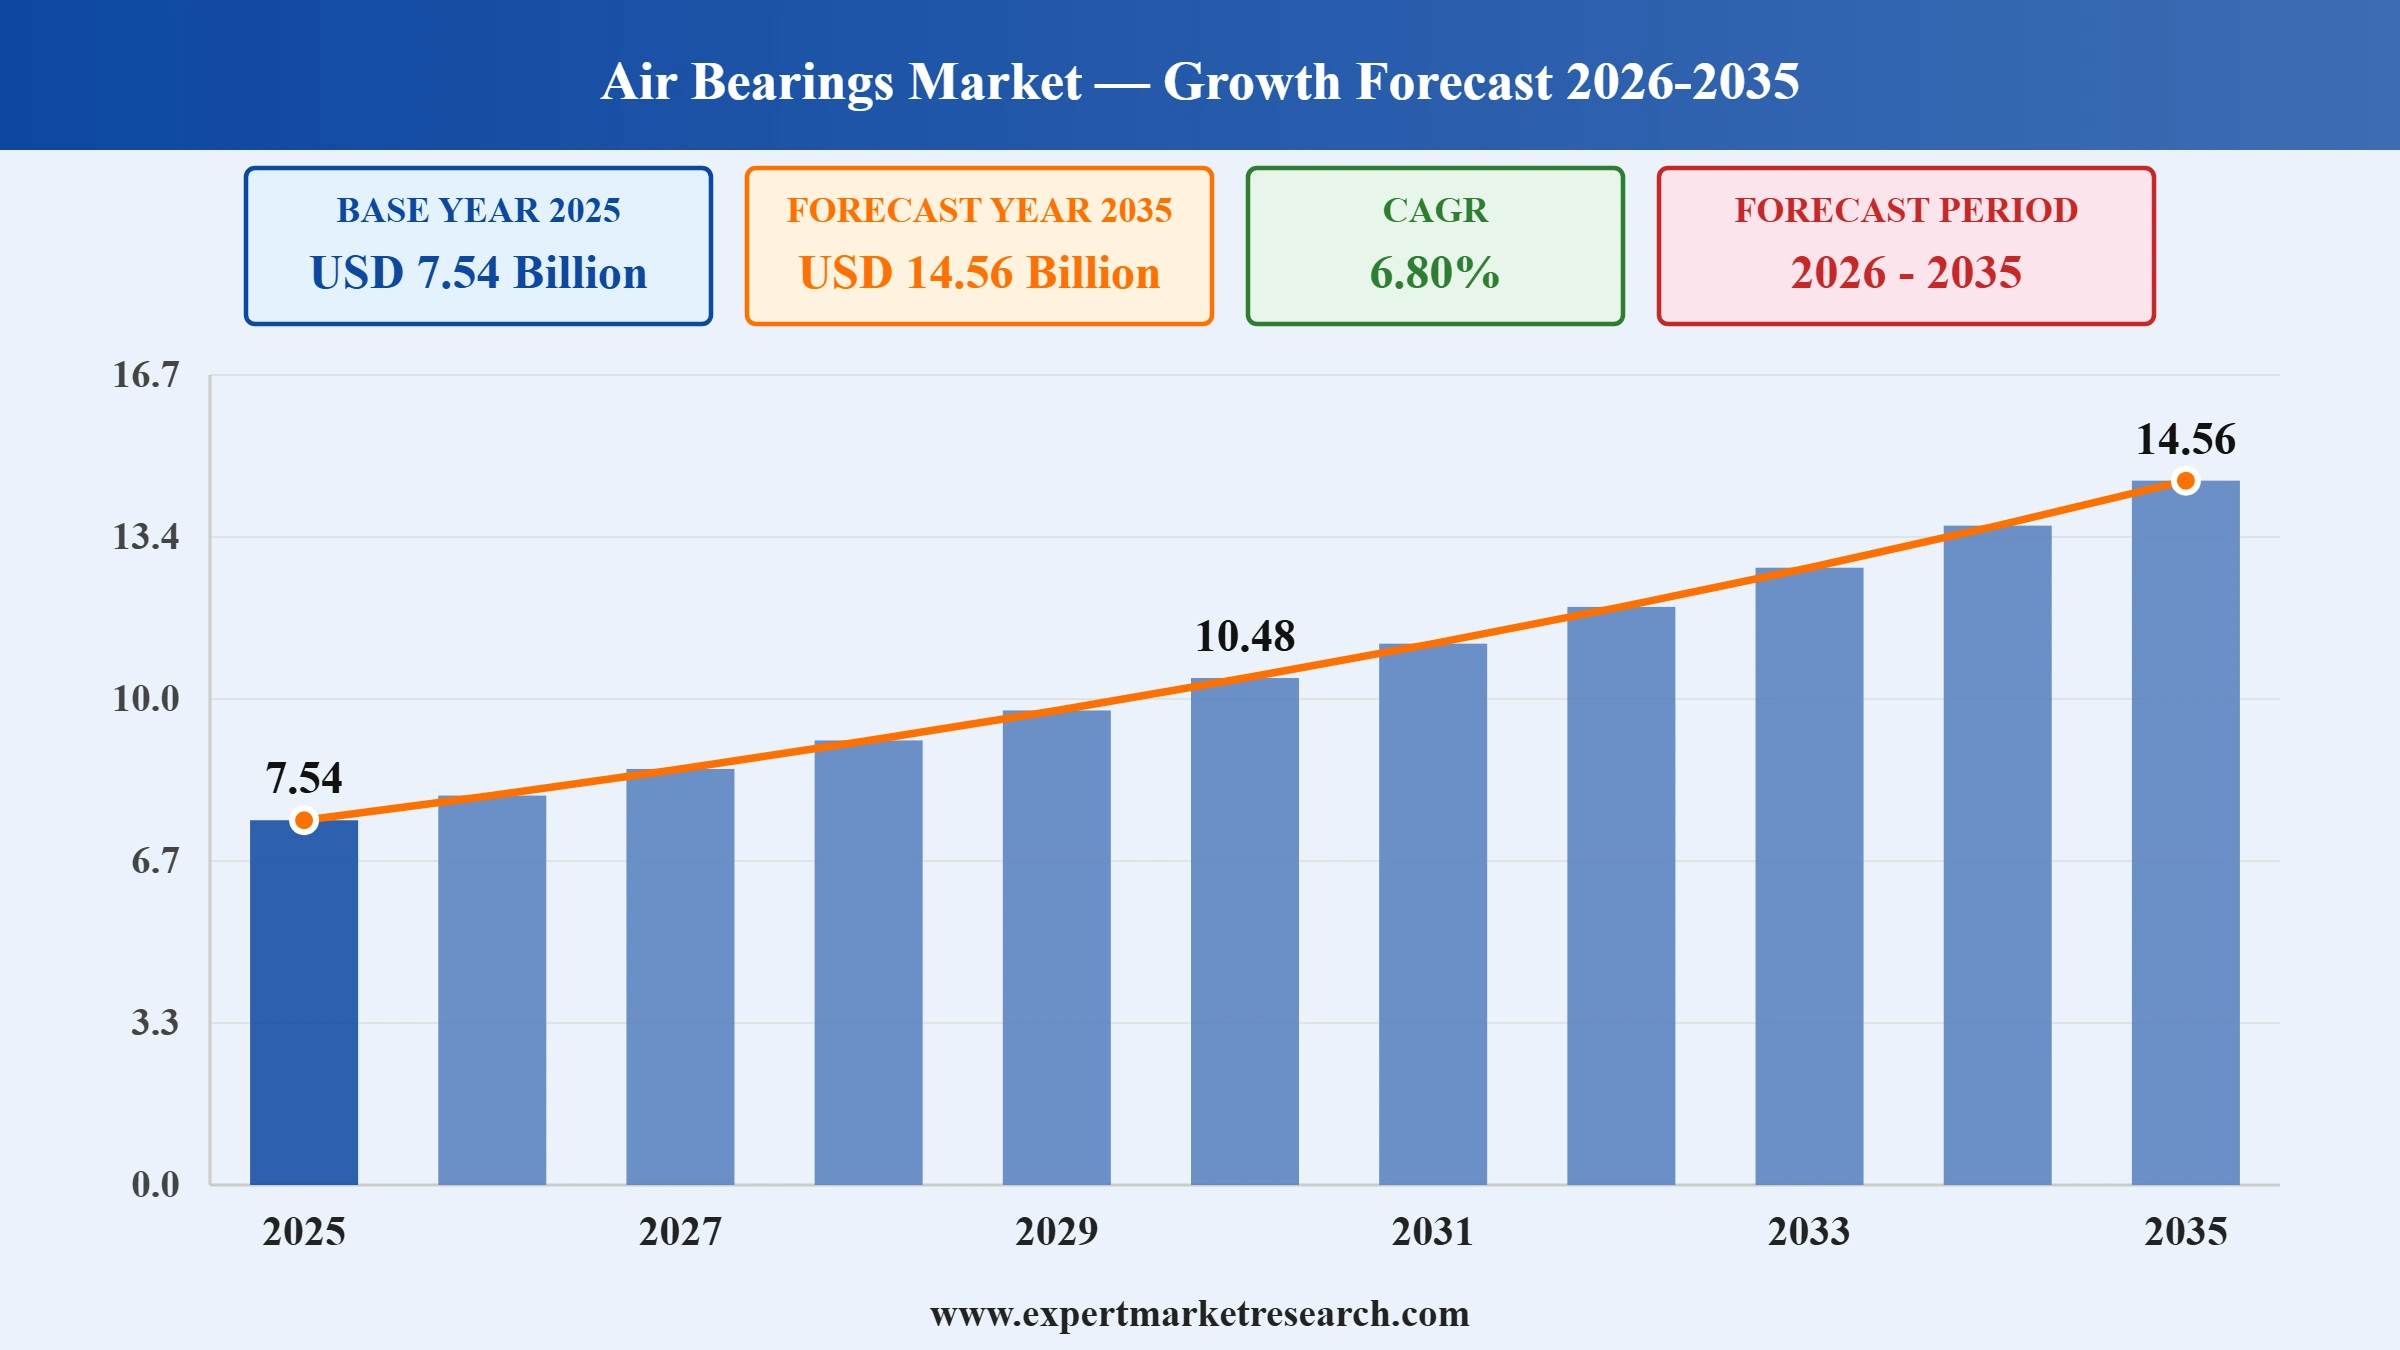
The global air bearings market attained a value of USD 7.54 Billion in 2025 and is projected to grow at a CAGR of 6.80% through 2035. The market is further expected to reach USD 14.56 Billion by 2035. Rising semiconductor equipment investment, demand for ultra precise machining and metrology, and the shift to oil free rotating machinery are supporting growth in the market.
Air bearings support loads on a thin film of pressurized air, which removes contact, wear, and lubricant. They are used in precision stages, spindles, rotary tables, measuring machines, and turbomachinery that need smooth motion with very low friction and no contamination. Aerostatic designs use external compressed air, while aerodynamic designs build pressure through motion. Demand follows semiconductor, metrology, machine tool, medical, and aerospace investment. Suppliers earn revenue from standard components, custom assemblies, repair, and engineering services for industrial buyers worldwide.
Buyers across the air bearings market choose air bearings when accuracy, cleanliness, speed, and life matter more than the cost of clean dry air supply. Parts last long because surfaces do not touch, and growth depends on equipment makers integrating stages into inspection tools. In August 2026, Physik Instrumente presented the A-725, a five-axis stage with XY travel up to 300 by 400 millimeters, 8-kilogram payload, and tip tilt of 2 degrees, aimed at semiconductor test and metrology. Testing capability creates real barriers.
Capital spending by chip makers is a key driver. In October 2026, SEMI reported in its 300mm Fab Outlook that global 300mm fab equipment spending would reach USD 149 billion in 2026, up 31%, and USD 227 billion by 2029, with the Americas rising from USD 18.1 billion to USD 40.6 billion. Equipment builders use air bearing stages in wafer handling and inspection, so rising tool orders lift component demand. Tool makers usually qualify suppliers for years before volume orders.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The launch added a full air bearing planar platform for step and scan semiconductor applications, with accuracy of 150 nanometers, acceleration up to 20 meters per second squared, and panels up to 600 millimeters square, open to OEM integrators. Stage makers across the air bearings market can leverage this trend by offering wafer and panel platforms to integrators, which helps them win design slots early.
The launch added an air bearing linear slide with travel from 50 to 750 millimeters, payload up to 40 kilograms, flatness within 0.25 micrometers, and EtherCAT connectivity. Machine builders across the air bearings market can leverage this trend by choosing longer strokes with direct drive motors, so inspection and metrology tools gain a standard high precision axis for faster and cleaner production in many plants.
The agreement moved a maker of piezoelectric drives and multi axis positioning systems into an industrial group as a new independent Positioning Division, showing how precision motion suppliers are consolidating. Industrial groups across the air bearings market can leverage this trend by buying precision motion firms, which gives access to semiconductor and photonics customers and lets the parent group share engineering skills across several markets.
The launch opened ordering for a coordinate measuring machine with digital sensors, a single cable system, a new controller, and a digital rack that tracks occupancy and sensor supply health, aimed at automated multi sensor work in aerospace and automotive plants. Measurement suppliers can leverage this trend by upgrading machines, which keeps demand very healthy for precise guideway bearings worldwide.
Oil free compressors across the air bearings market rely on gas bearings, so fuel cell growth is opening a new use. In April 2026, Celeroton presented the CTE-400x at Hannover Messe, a turbo compressor with an inverter for fuel cells of 100 to 200 kilowatts net output aimed at heavy duty use, plus the second generation CTi-110x for material handling, range extenders, and drones. Bearings built in house are shortening development cycles, and gas bearing know how is becoming a selling point for compressor makers.
Metrology vendors across the air bearings market are widening their buyer base beyond large quality labs, and smaller workshops are buying their first measuring machines. In September 2026, Hexagon launched ENSPEC, positioned to bring professional grade coordinate measuring machine measurement within reach across EMEA. Wider adoption is supporting demand for precise guideways and air bearing components, while vendors add training, financing, and service packages that help first time buyers adopt the machines faster and with less risk across smaller workshops, university laboratories, and contract manufacturers.
Motion control makers across the air bearings market are adding local capacity, and domestic supply chains are gaining attention among chip equipment buyers. In April 2025, a Massachusetts based maker announced a 140,000 square foot plant in Shrewsbury to produce precision motion systems, air bearings, piezoelectric transducers, and nanopositioning components. The facility is expected to triple the combined space of its existing sites, shortening delivery times for chip and photonics buyers, and placing engineering teams closer to chip equipment makers and photonics firms and universities.
Semiconductor equipment makers across the air bearings market are shipping more tools, and chipmakers are adding capacity in several regions. In September 2026, SEMI reported global equipment billings of USD 40.53 billion in the second quarter of 2026, up 23% from a year earlier and up 11% from the previous quarter, with growth across Asia, North America, and Europe. Higher billings are lifting orders for air bearing stages, spindles, and rotary tables used in wafer positioning, inspection, and testing, while tool makers qualify suppliers early.
Machine tool demand is climbing, and builders of precision tools are expanding air bearing use as accuracy needs rise across electronics, medical, and aerospace parts. In June 2026, Japanese machine tool orders reached JPY 203.38 billion, up 52.7% from a year earlier, with domestic orders up 45.5%. For the first half of 2026, orders totaled JPY 1,055.14 billion, up 35.7%, lifting purchases of spindles and bearings, and overseas orders rising too also supports builders of precise guides, spindles, and slides.
“Air bearings Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
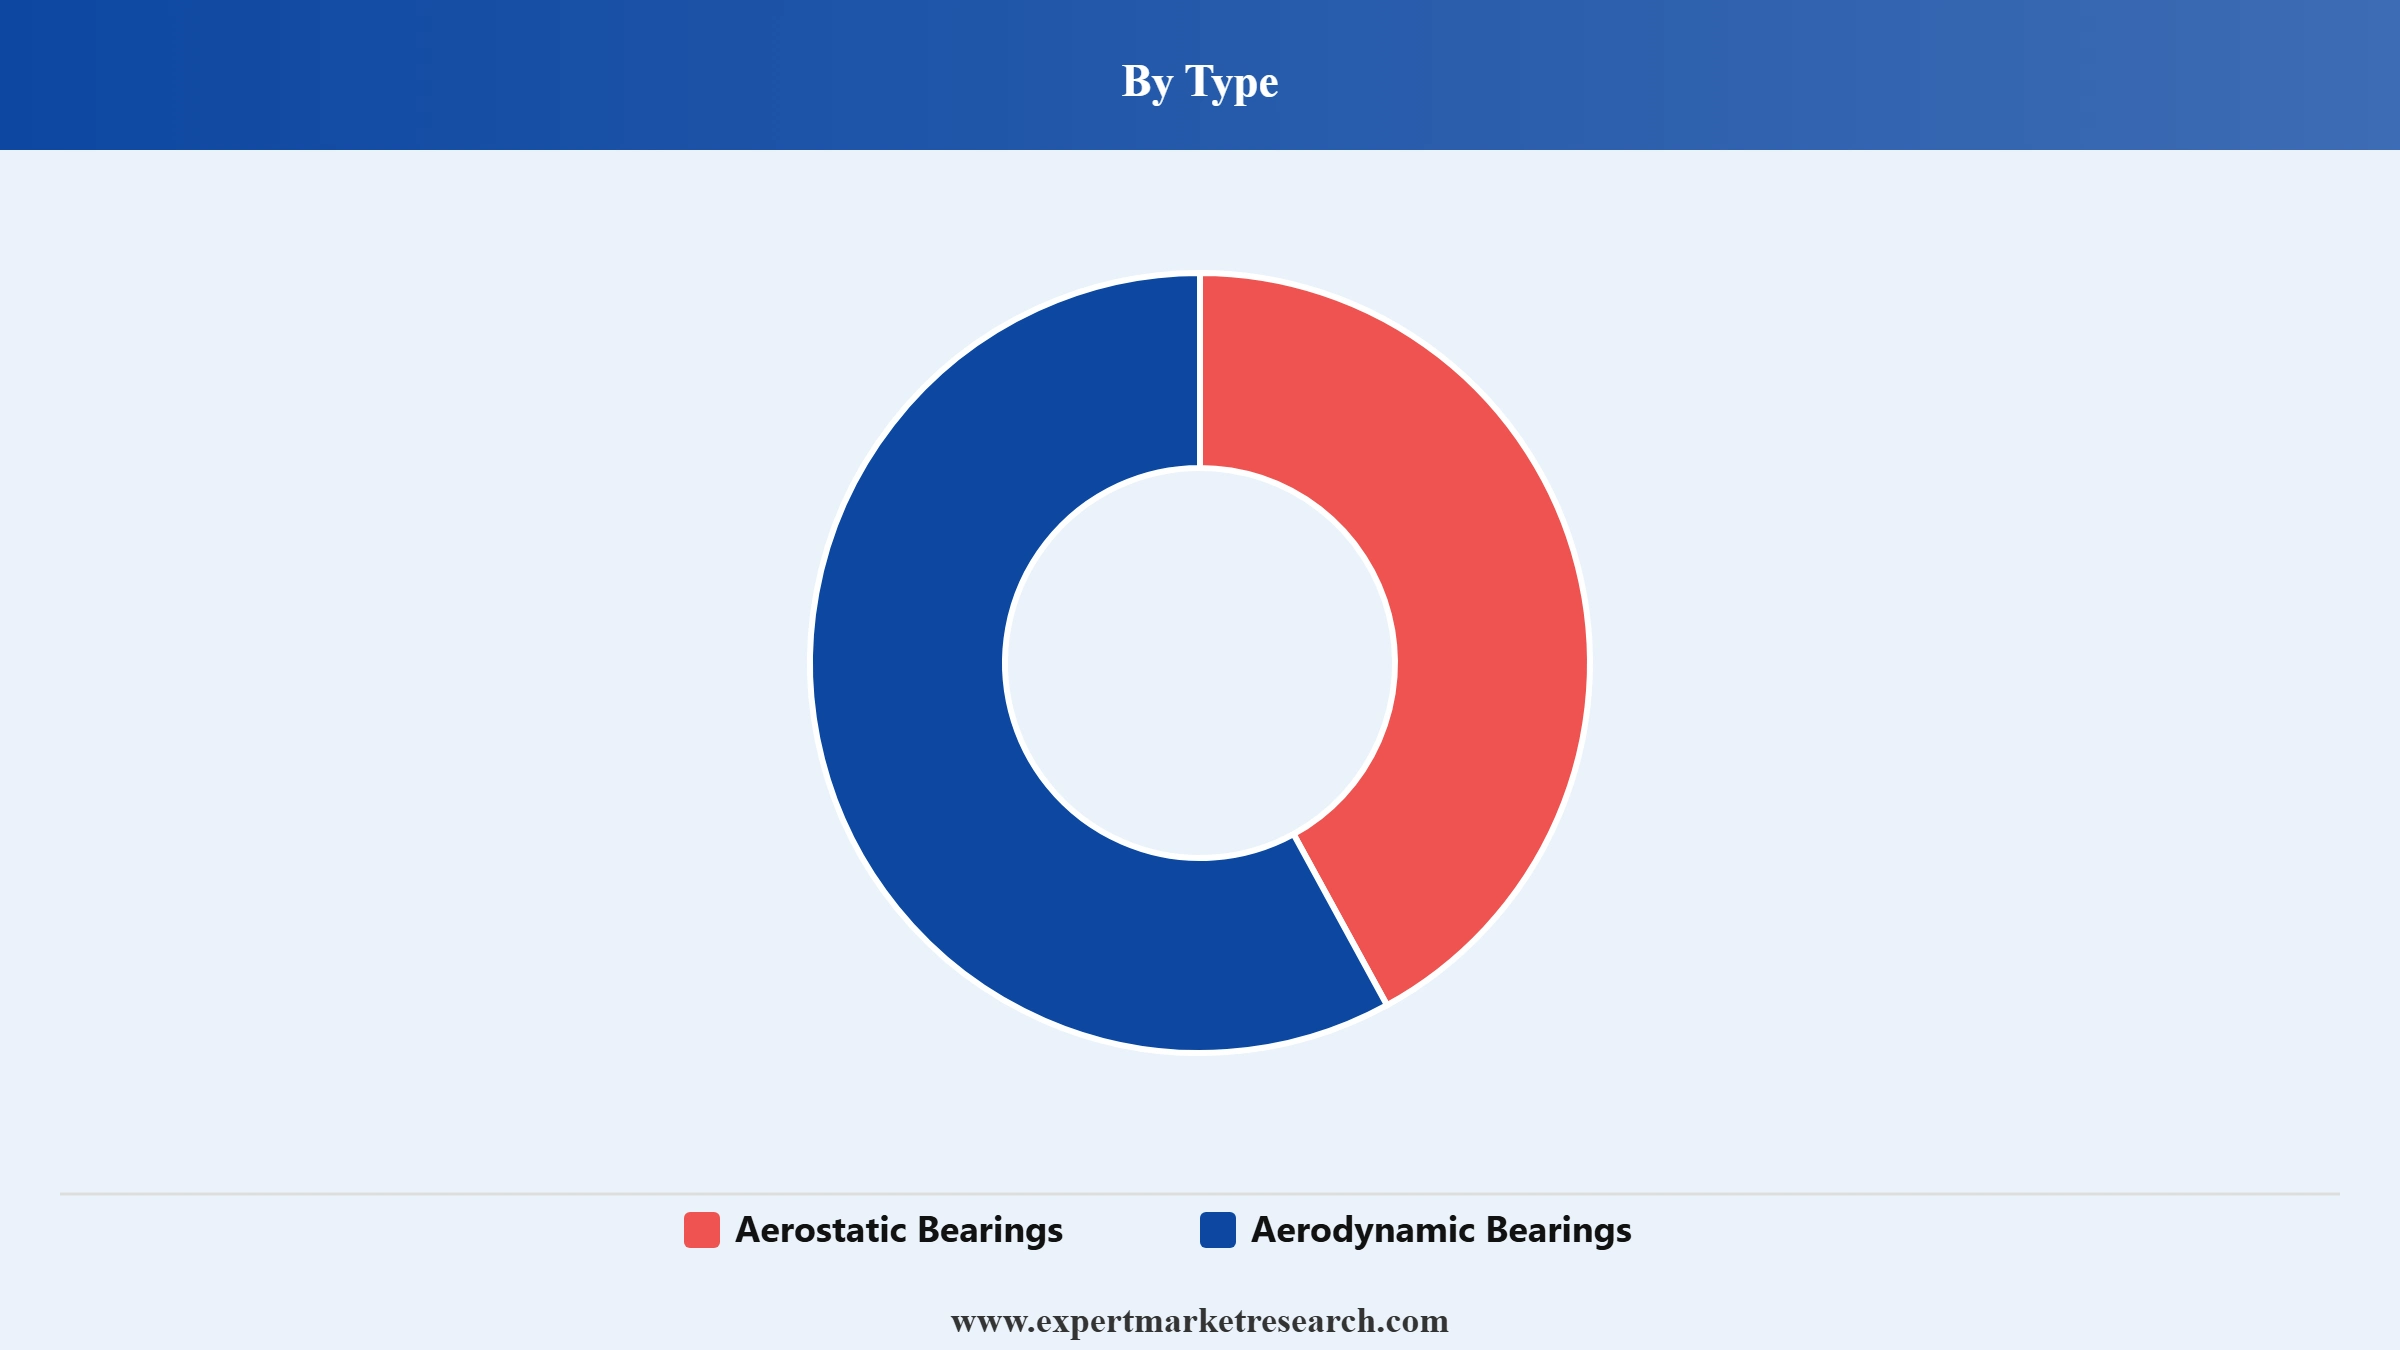
Key Insight: Aerodynamic leads the type segment of the air bearings market, since self-acting designs need no external air supply and suit spindles, scanners, and turbomachinery. Aerostatic is expected to grow fastest, as chip, display, and metrology tools need frictionless stages with stiff, controllable air films. Aerodynamic bearings lift only once motion begins, so start and stop wear must be managed, while aerostatic bearings need clean dry compressed air. Buyers decide by load, stiffness, speed, and the cost of air supply equipment. Service life and spare parts also matter.
Market Breakup by Speed Capacity
Key Insight: The 1000 to 60000 rpm range leads the speed capacity segment of the air bearings market, because most machining and grinding spindles, rotary tables, and measuring machines operate within it. Below 1000 rpm is expected to grow fastest, as precision rotary stages for inspection and optics expand. Above 60000 rpm serves printed circuit board drilling, micro machining, and dental tools, where rigid, low vibration spindles matter. Speed, stiffness, thermal growth, and balance needs guide the design of each bearing. Balancing quality and vibration control also matter.
Market Breakup by Application
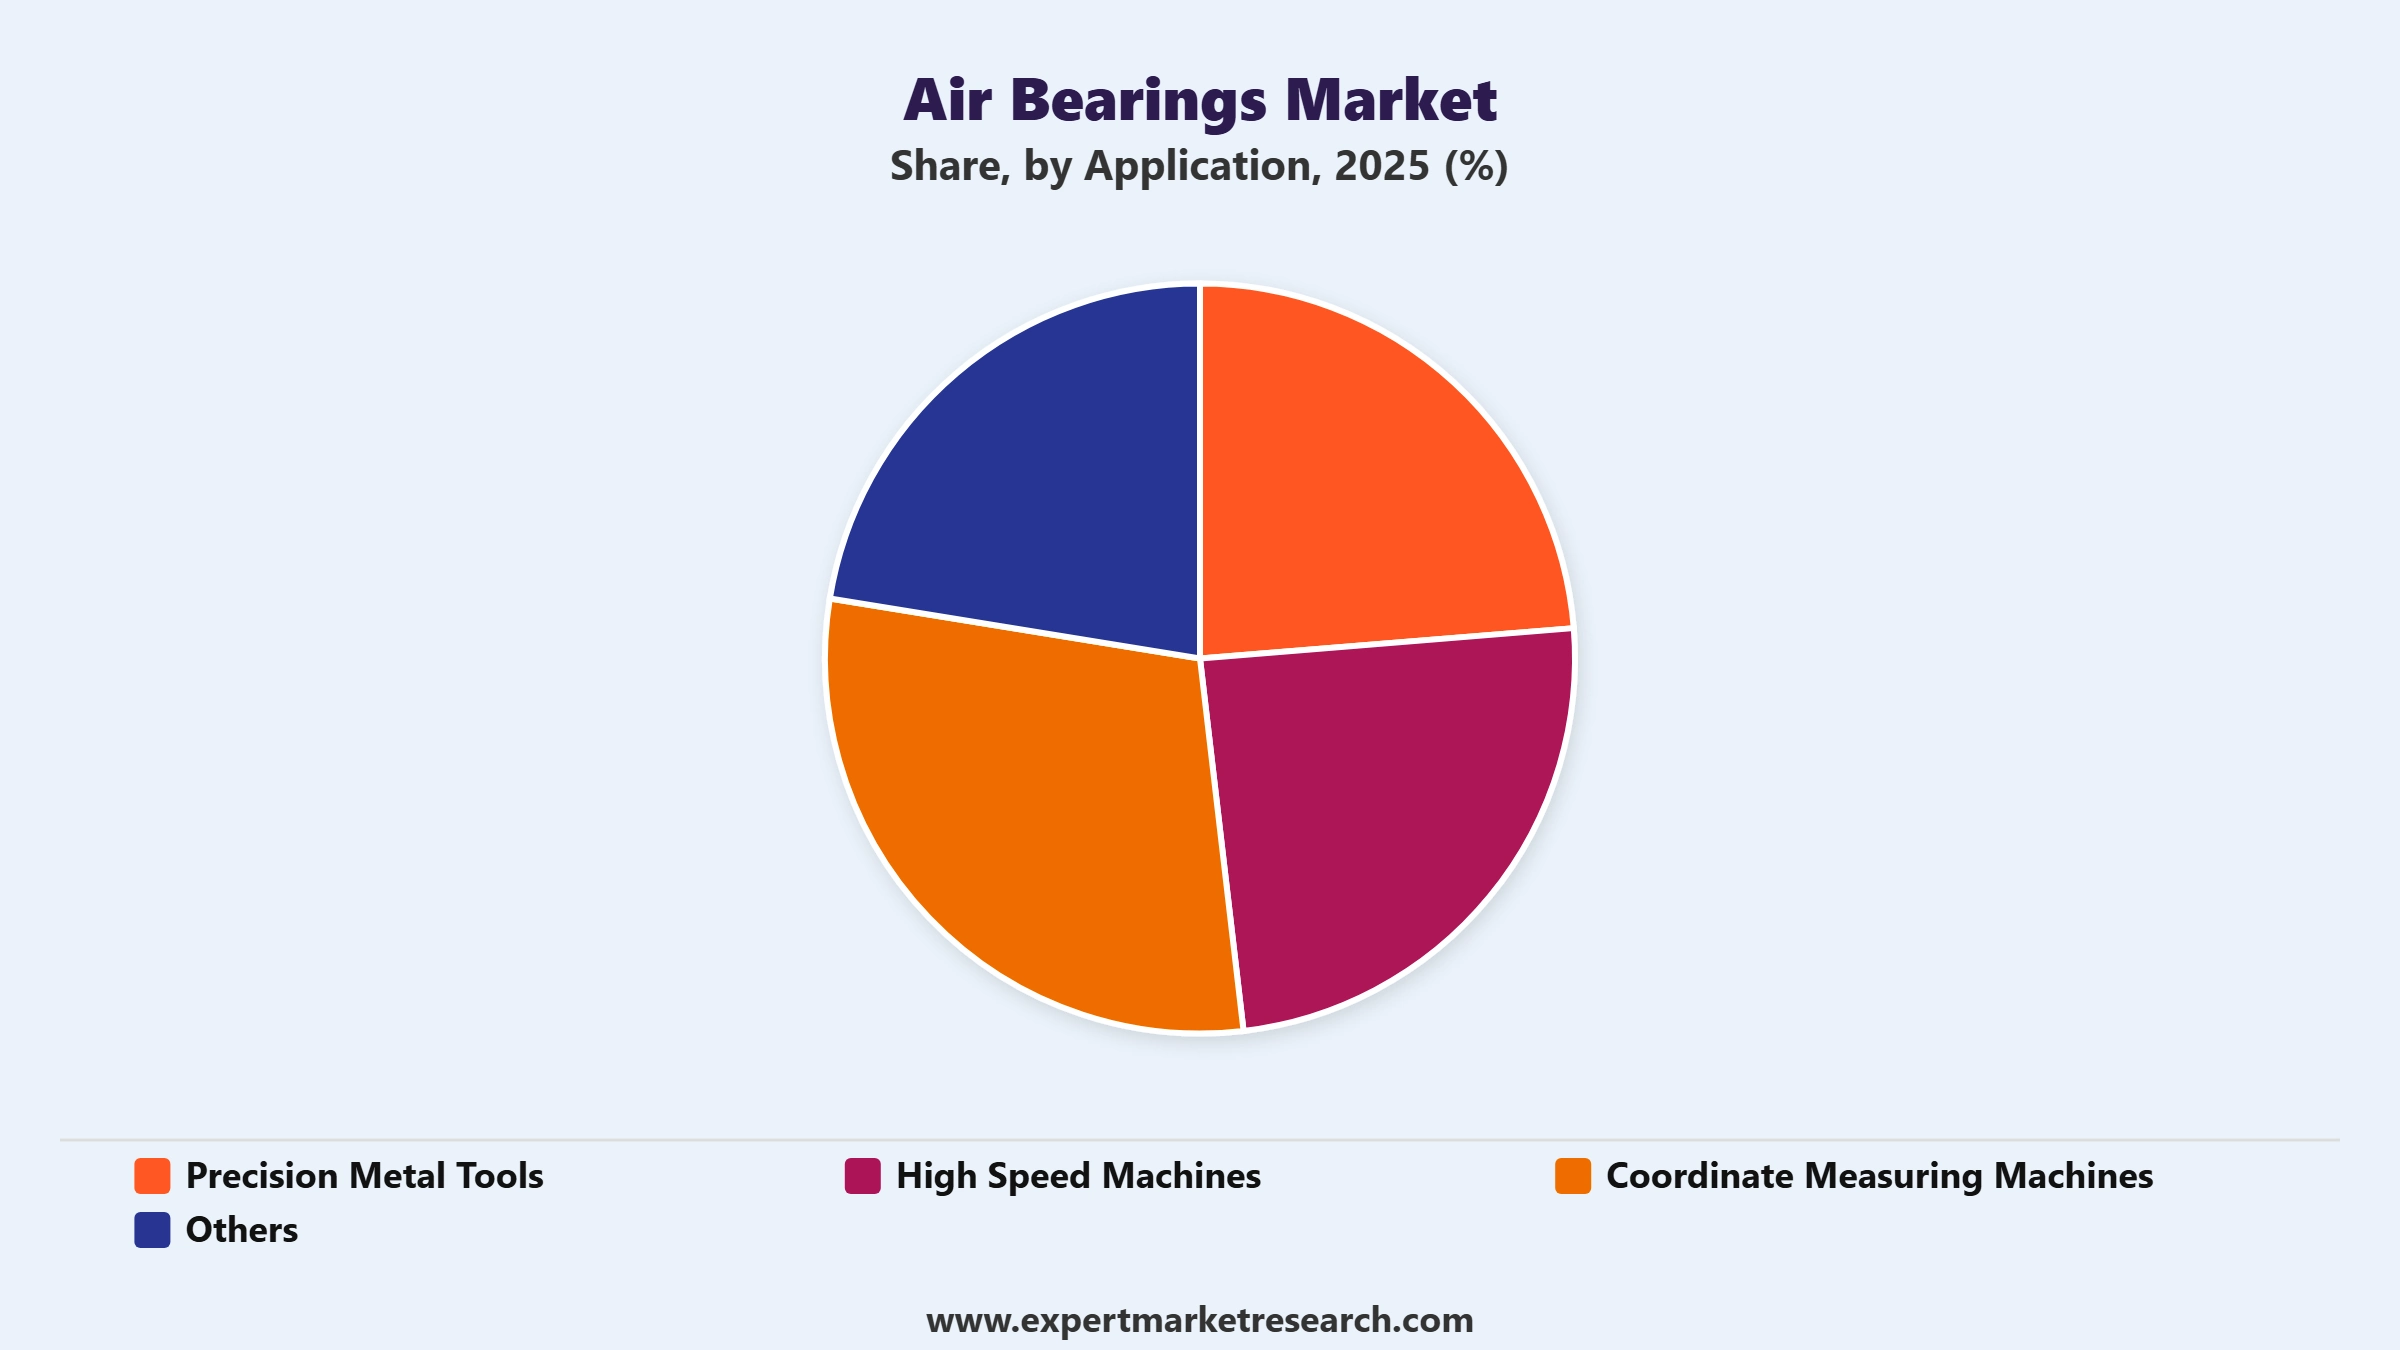
Key Insight: High speed machines lead the application segment of the air bearings market, as spindles for drilling, grinding, and micro machining depend on stable, low friction rotation. Precision metal tools are expected to grow fastest, as makers of cutting and finishing equipment adopt air bearings for finer surface quality. Coordinate measuring machines use air bearing guideways for smooth, repeatable probing, while others include optics, wafer handling, and testing equipment. Accuracy targets, cleanliness, and maintenance access decide which design suits each machine. Service teams also value standard parts.
Market Breakup by End Use
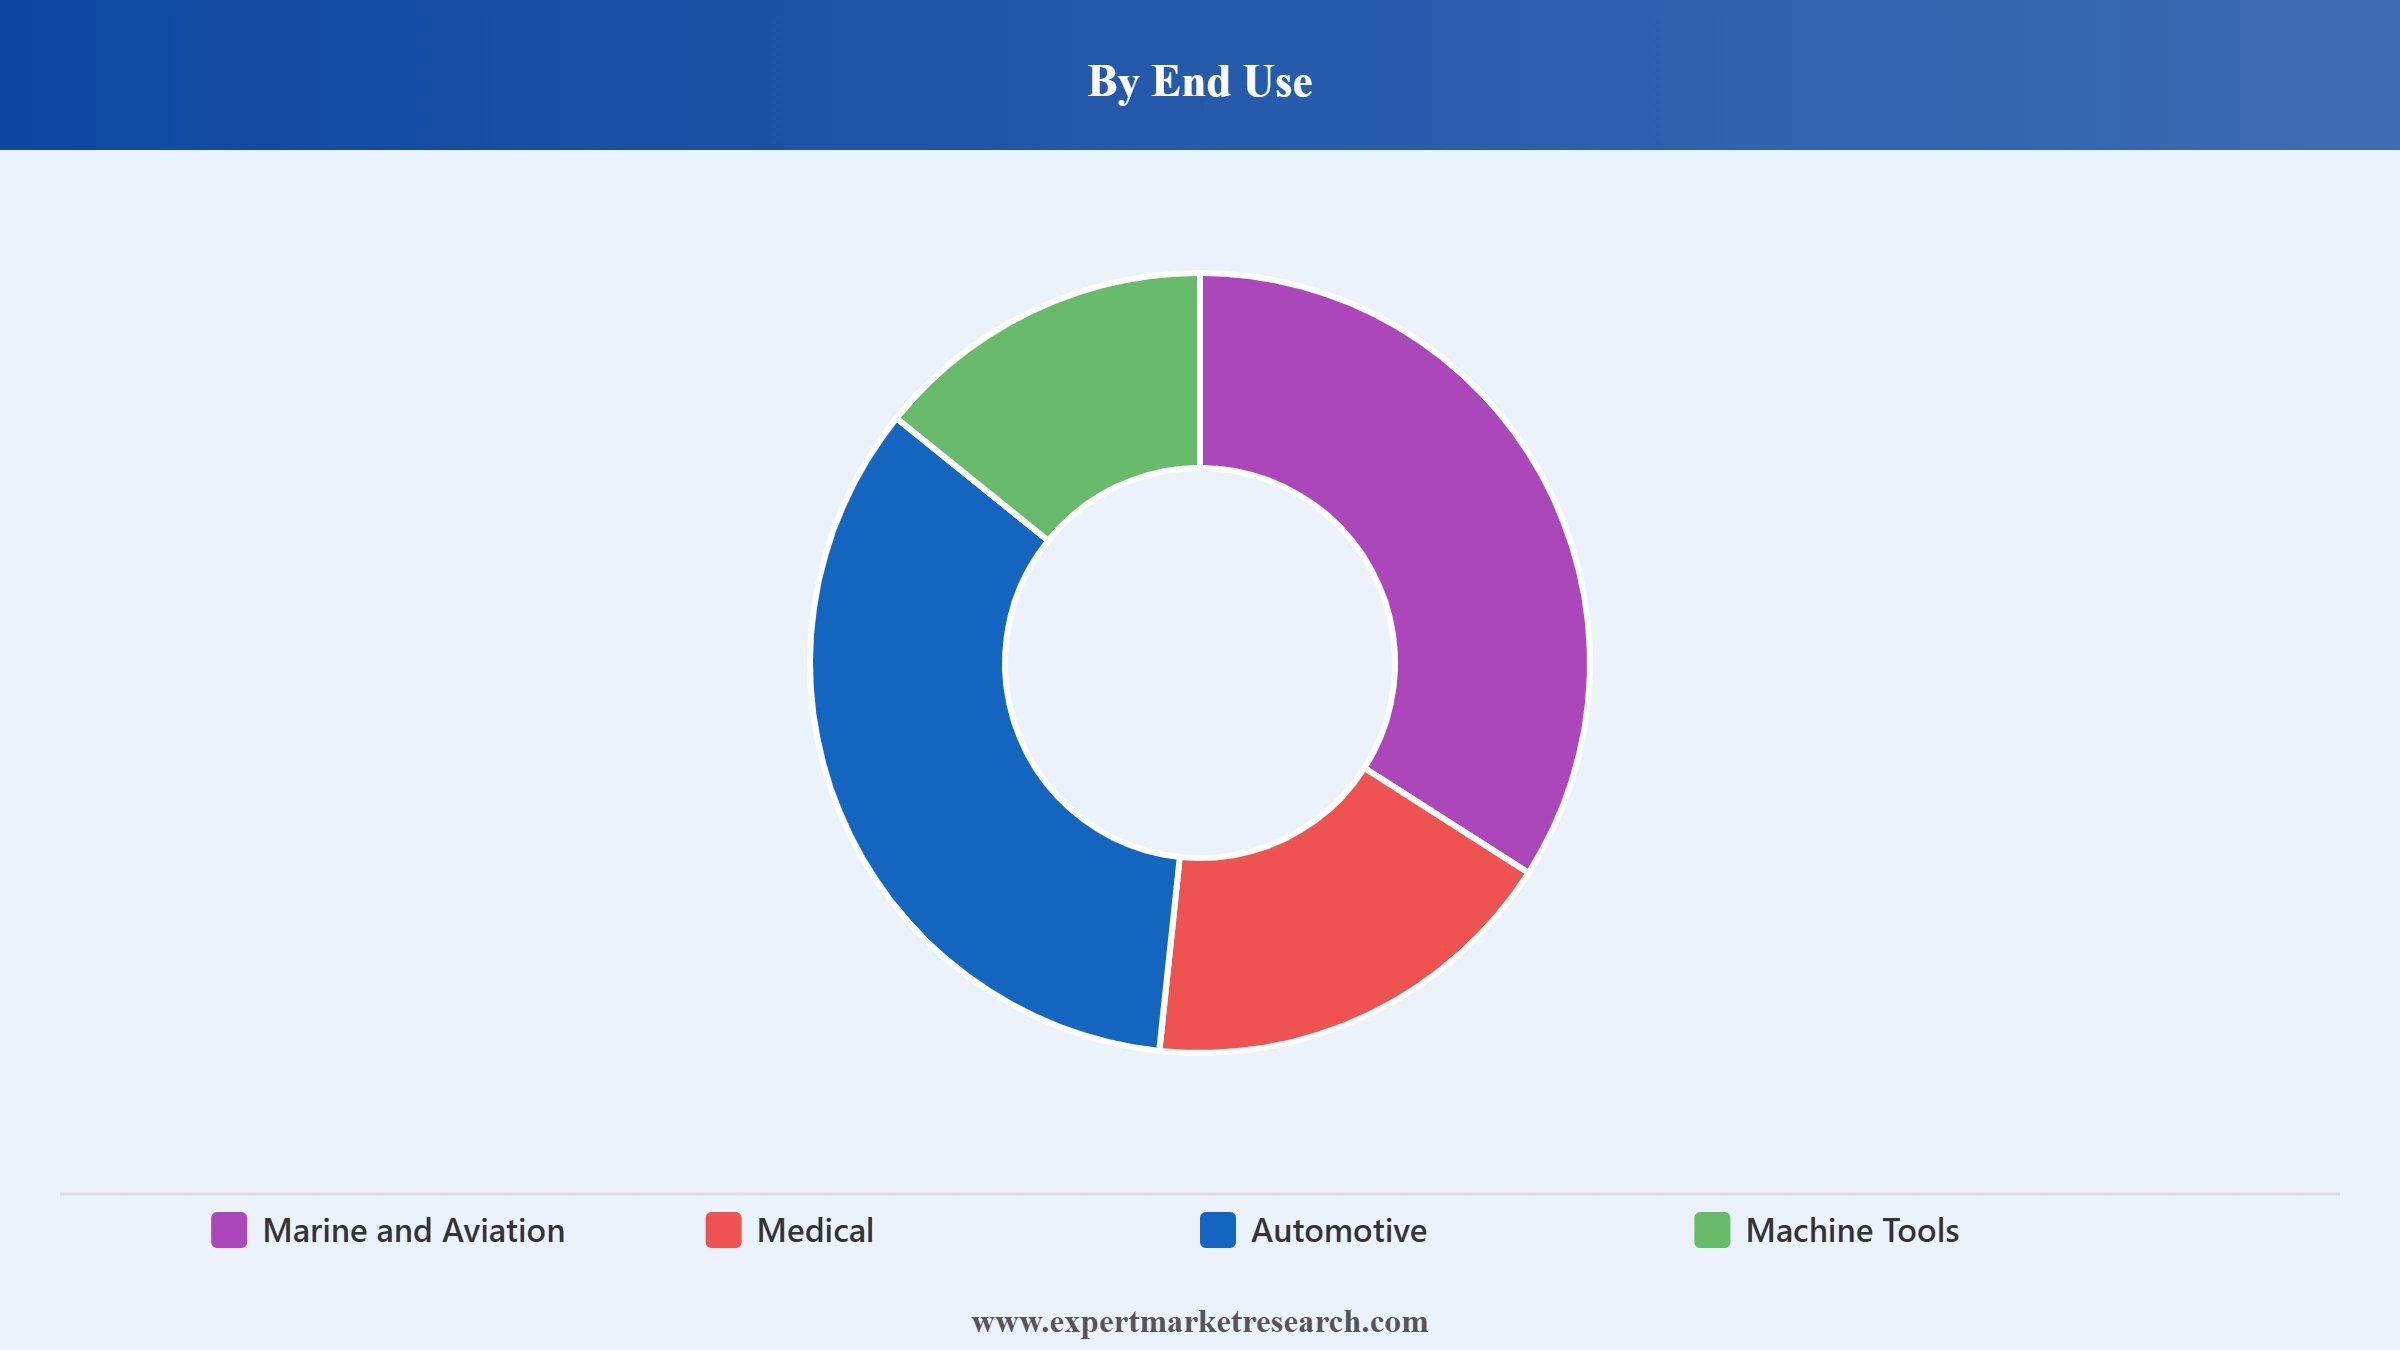
Key Insight: Machine tools lead the end use segment of the air bearings market, as spindles and slides sit at the core of precise machining work. Marine and aviation is expected to grow fastest, as parts makers need tighter tolerances and inspection tools for engines and structures. Medical users rely on air bearings in imaging gantries and lab automation for smooth, quiet motion, automotive makers use them in testing and fuel cell compressors, and others include electronics and research. Cleanliness, reliability, and low noise shape purchasing. Qualification takes time.
Market Breakup by Region
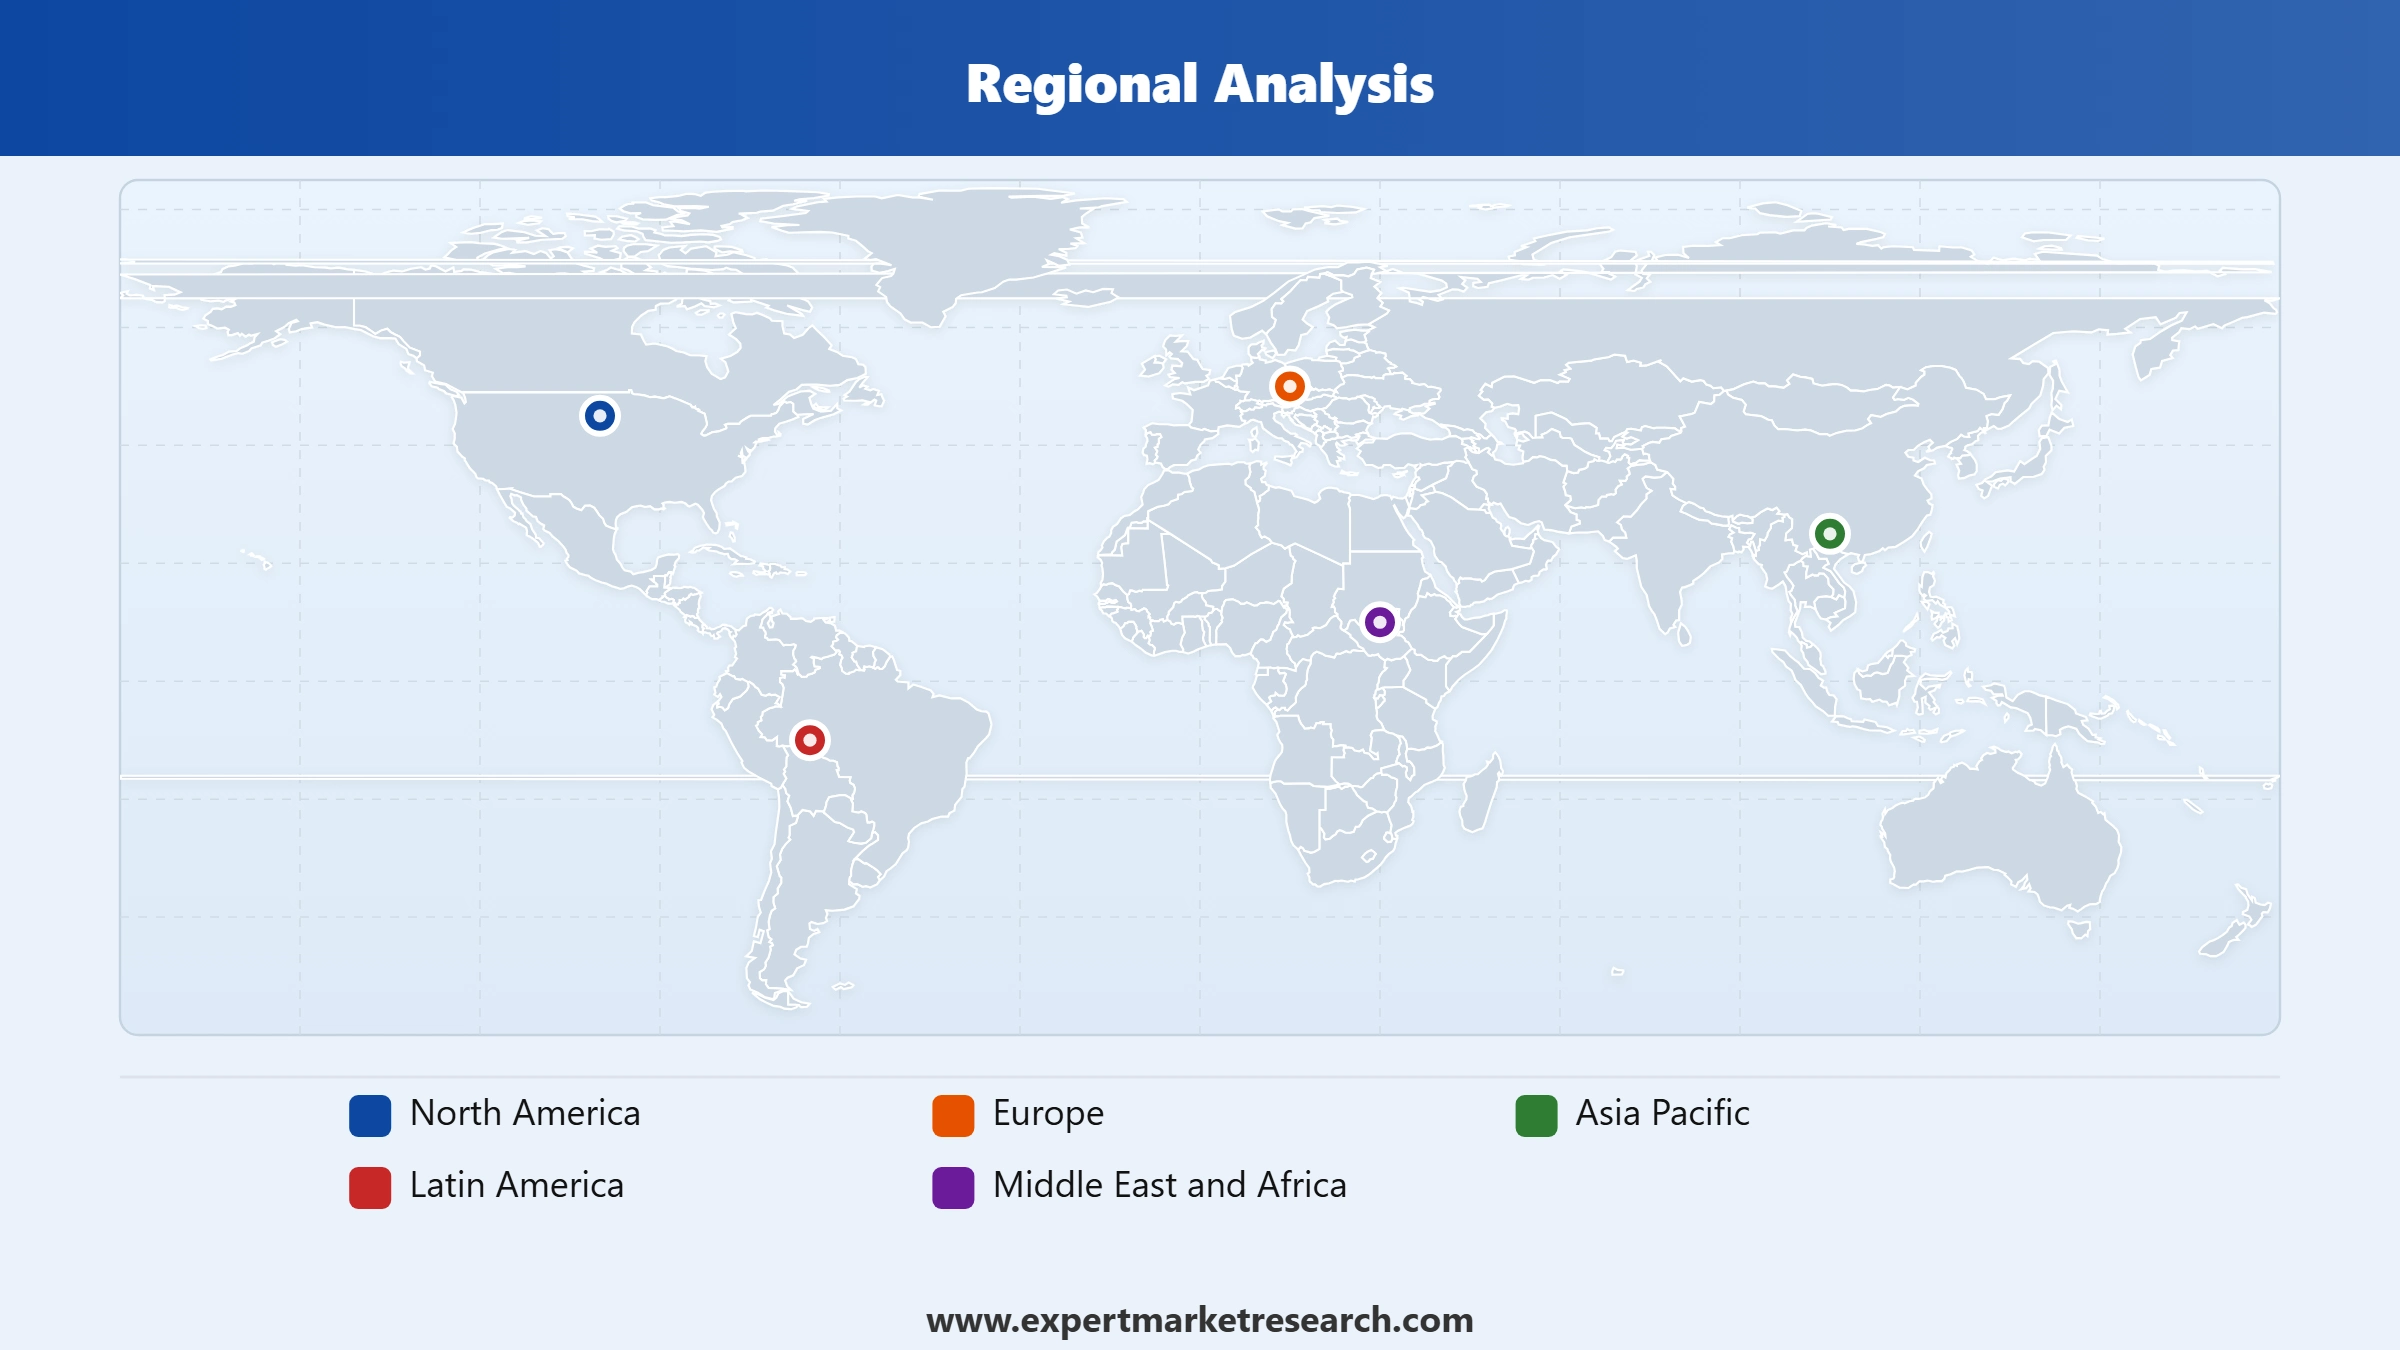
Key Insight: Asia Pacific leads the regional landscape of the air bearings market, backed by chip fabs, electronics plants, and machine tool builders across East Asia, Southeast Asia, and India. North America is expected to grow fastest, as new chip plants and defense and aerospace investment raise demand for precision stages and measuring tools. Europe is home to many precision engineering firms and metrology groups, and LAMEA grows from a smaller base through industrial investment and imports of specialist tools and equipment. Local engineering support also influences supplier selection.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By type, aerodynamic dominates the air bearings market owing to simple self-acting designs that need no external air supply
Aerodynamic holds the largest share of the type segment, because these bearings generate their own air film through motion and need no compressed air supply, filters, or regulators. They suit spindles, polygon scanners, small motors, and turbomachinery where speeds are high and operation is continuous. Fewer parts mean lower cost and simpler installation, and designs with foils or grooves are well established. Makers of fans, compressors, and rotating equipment choose them where contamination from lubricants must be avoided in service.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Aerostatic is registering the fastest growth within the type segment, as semiconductor, display, and metrology tools need stiff air films that work at zero speed. Externally supplied air gives precise control of load and gap, which suits nanometer level stages. In September 2025, a Massachusetts based motion specialist introduced the A-361 air bearing XY rotation stage, only 39.5 millimeters tall, with a 200-millimeter platform and a built-in vacuum chuck for wafers and other delicate substrates in wafer inspection.
By speed capacity, the 1000 to 60000 rpm range dominates the air bearings market owing to wide use in spindles and rotary tables
The 1000 to 60000 rpm range holds the largest share of the speed capacity segment in the air bearings market, because most machining spindles, grinding heads, rotary tables, and measuring machine axes operate in this range. Designs are mature, with proven stiffness and thermal behavior, and suppliers offer standard sizes that shorten delivery. Machine builders can reuse the same bearing family across several tool models, and service teams know how to maintain them. Demand tracks machine tool and electronics production, which supplies steady repeat orders.
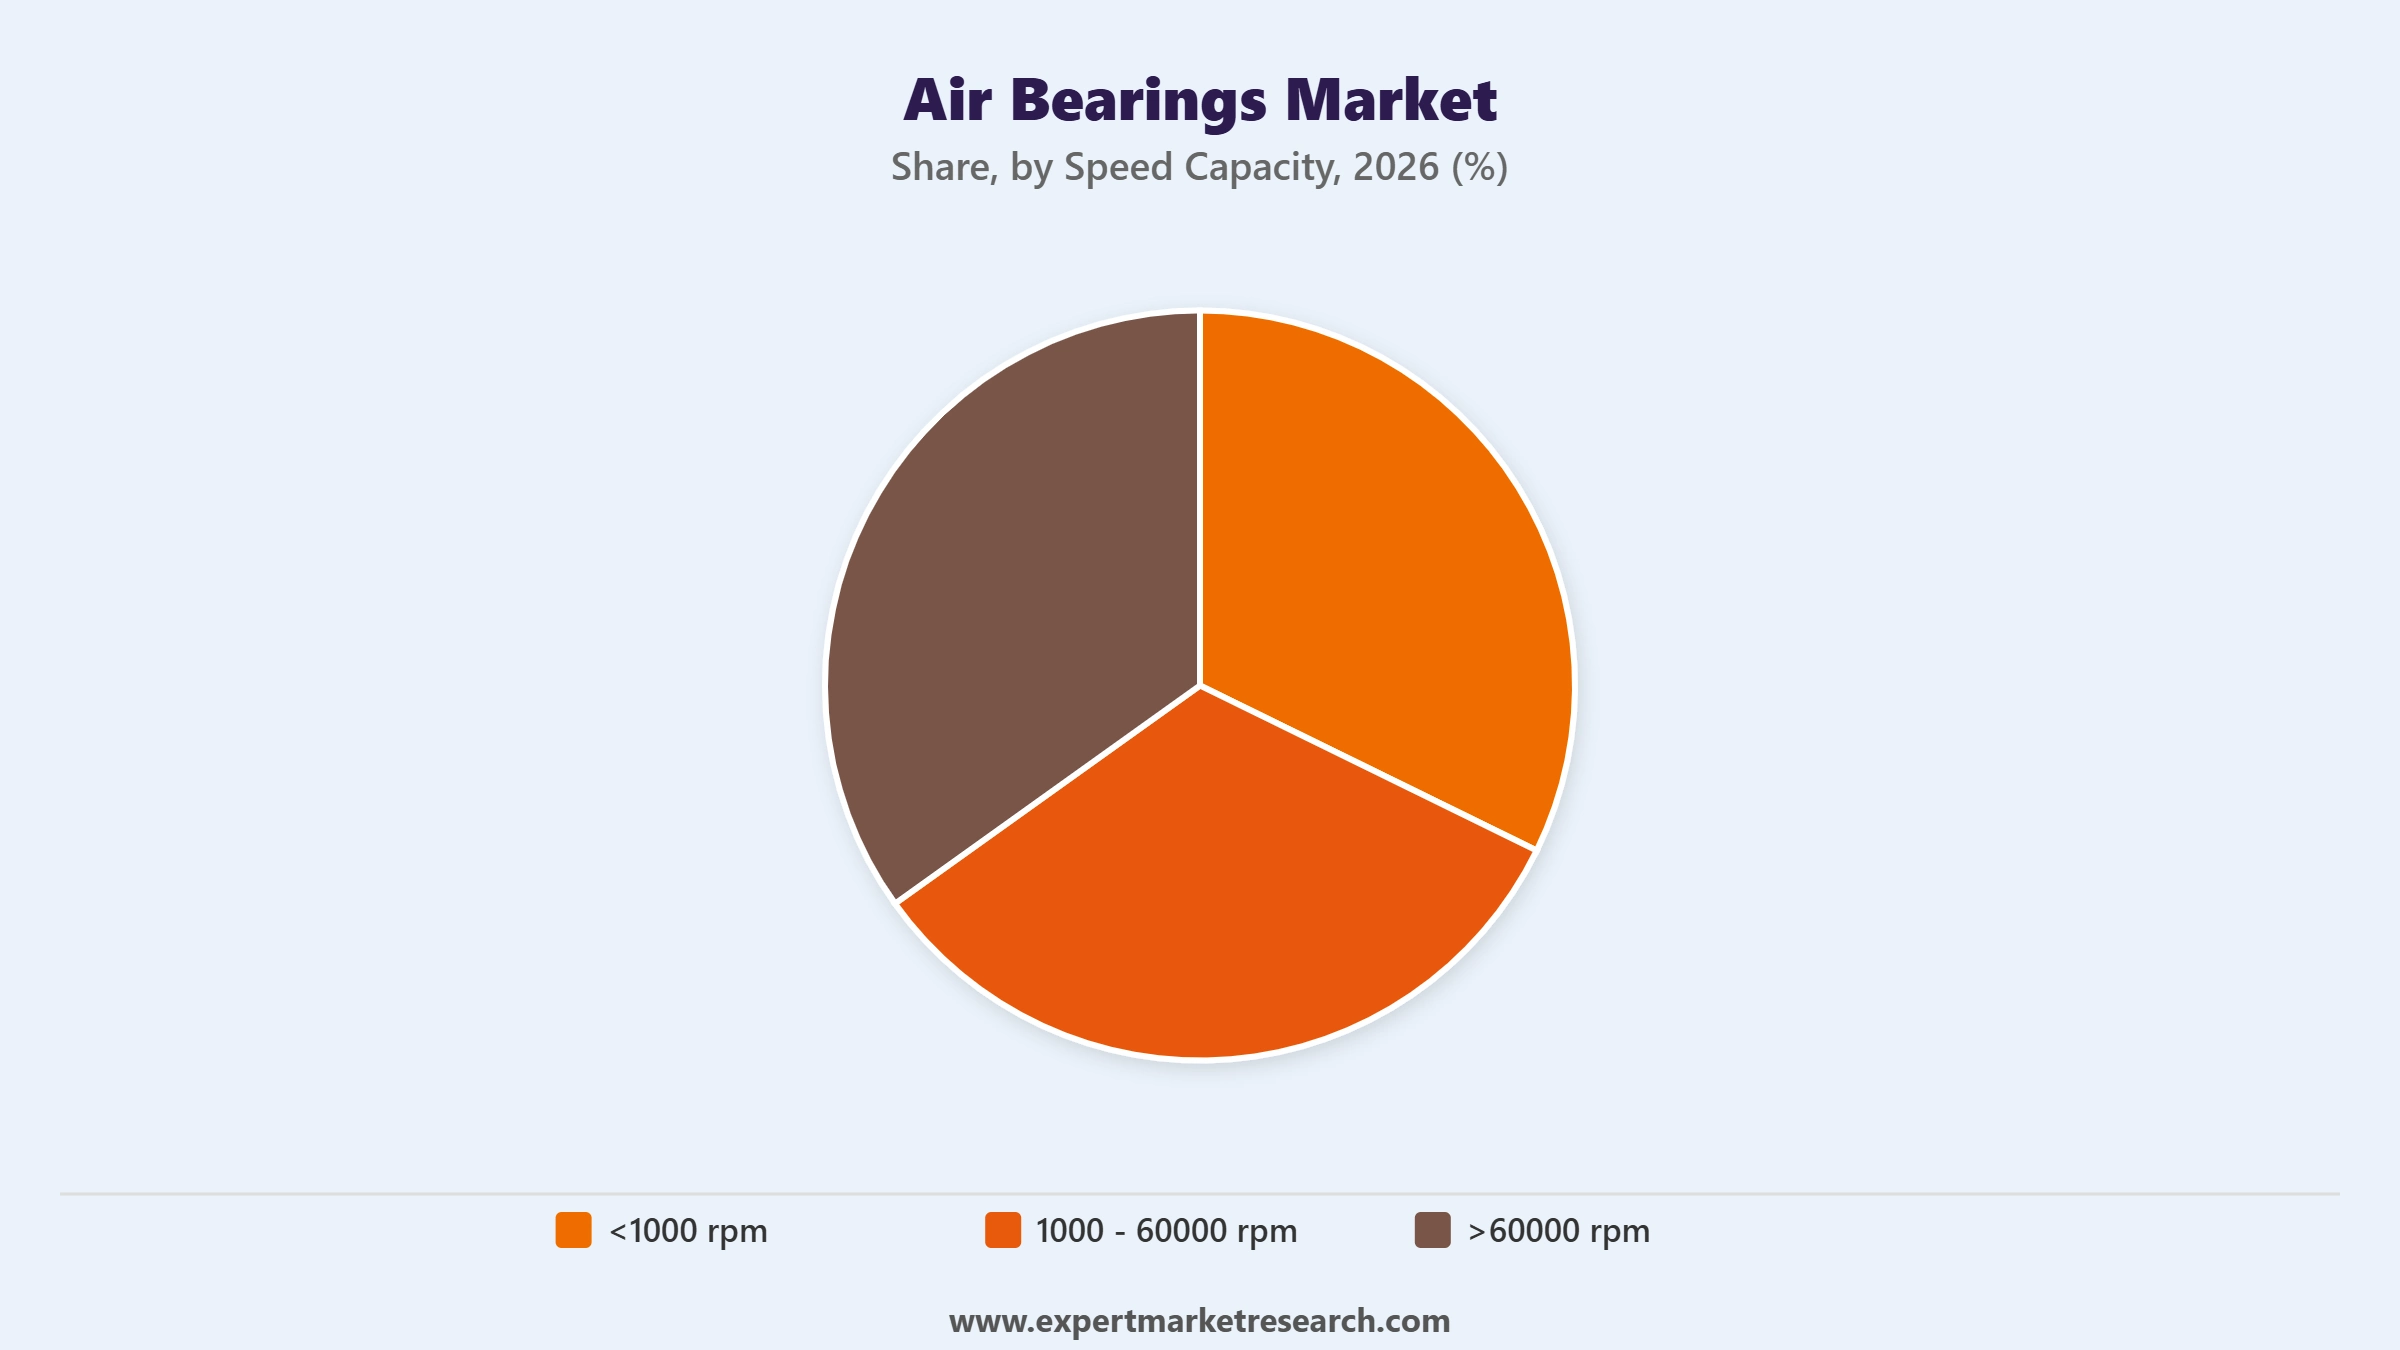
Below 1000 rpm is registering the fastest growth within the speed capacity segment, as rotary stages for inspection, optics, and wafer handling spread. These stages turn slowly but need very low wobble and fine positioning. In October 2025, a motion control supplier announced the A-688 rotation stage with a 260-millimeter clear aperture, speeds up to 500 rpm, radial error within 0.15 micrometers, and angular resolution up to 0.0015 microradians, with absolute encoder options and flexible mounting in any orientation.
By application, high speed machines dominate the air bearings market owing to stable, low friction rotation for drilling and grinding
High speed machines hold the largest share of the application segment, because drilling, grinding, and micro machining spindles need stable rotation with low vibration and little heat. Air films avoid contact, so spindles keep accuracy over long runs and need less maintenance than rolling bearings. Printed circuit board makers, dental tool makers, and optics shops buy such spindles in volume. Spindle makers differentiate through stiffness, runout, speed, and thermal control, and they often sell replacement units to existing customers worldwide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Precision metal tools are registering the fastest growth within the application segment, as makers of cutting and finishing equipment seek finer surface quality and tighter tolerances. Machine tool investment is recovering strongly. In July 2026, Japan's machine tool builders booked orders worth JPY 193.09 billion, up 50.4% year on year, with domestic orders of JPY 53.24 billion and foreign orders of JPY 139.85 billion, according to the national builders’ association. Rising orders point to more spindle and bearing purchases ahead.
By end use, machine tools dominate the air bearings market owing to wide use of spindles and slides in precision cutting
Machine tools hold the largest share of the end use segment, because spindles, slides, and rotary tables are central to precise cutting, grinding, and measuring. Builders adopt air bearings for ultra precision lathes, grinders, and inspection axes where surface finish and repeatability are priorities. Machine tool demand follows factory investment cycles in automotive, electronics, and aerospace, and large builders place repeat orders with qualified suppliers. Long machine life also creates a need for service, repair, and replacement bearings over time.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Marine and aviation is registering the fastest growth within the end use segment, as makers of engines, structures, and instruments need tighter tolerances and better inspection. In September 2026, the German machine tool builders association VDW reported that German machine tool orders rose 12% in the second quarter of 2026 from a year earlier, with aviation and defense described as strong, electronics and medical technology healthy, and automotive under the most pressure. Precision inspection demand remains tied to aerospace programs.
Asia Pacific commands the largest regional share of the air bearings market, supported by semiconductor fabs and machine tool production
Asia Pacific commands the largest regional share of the air bearings market, supported by semiconductor fabs, electronics plants, and machine tool makers in China, Japan, South Korea, and India. Local spindle and stage makers serve domestic equipment builders, while global suppliers sell high end stages to wafer and display factories. Investment in artificial intelligence chips and advanced packaging lifts demand for inspection and handling tools, and government support for local equipment supply chains adds momentum to regional orders each year.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America is registering the fastest growth among the regional markets, driven by new chip plants, aerospace and defense programs, and reshoring of precision manufacturing. In August 2026, the Association for Manufacturing Technology reported that United States manufacturing technology orders for the first half of 2026 reached USD 3.44 billion, up 36.0% from the first half of 2025, a half year record. Local stage and spindle makers benefit from tool demand in the region and from continued reshoring programs nationwide.
The competitive landscape is fragmented, with specialist air bearing makers, precision motion groups, and in house suppliers at large equipment builders. Established air bearings companies compete on accuracy, stiffness, cleanliness, delivery time, and engineering support. Standard catalog bushings, pads, and spindles are sold widely, while custom assemblies for semiconductor and metrology tools command higher margins. Know how in porous media, machining, and testing creates barriers, and long qualification cycles favor suppliers with proven references.
Leading air bearings market players are pursuing acquisitions, new stage and slide launches, and added production capacity to defend share. Several air bearings players are also expanding into integrated motion systems with controllers and encoders to capture more value per tool. Investment in clean assembly, automated testing, and application engineering is rising as customers seek faster design cycles. Partnerships with equipment builders in Asia Pacific and North America help suppliers reach fast growing semiconductor and machining projects.
Founded in 1993 and headquartered in Ferndown, Dorset, United Kingdom, the company supplies the market through air bearing components and precision motion assemblies. It serves equipment builders and research users in several countries.
Founded in 1994 and headquartered in Aston, Pennsylvania, United States, the company supplies the market through porous media air bushings, pads, and spindles. It serves semiconductor, metrology, and machine tool customers.
Founded in 1964 and headquartered in Princeton, New Jersey, United States, the company supplies the market through air bearing spindles, slides, and rotary tables. It serves precision manufacturing and research customers.
Founded in 2005 and headquartered in Leuven, Belgium, the company supplies the market through aerostatic air bearing products and precision spindles. It serves customers in precision engineering and equipment manufacturing.
Other key players in the market include IBS Precision Engineering BV and Mohawk Innovative Technology, Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global air bearings market trends 2026 report. Discover regional growth patterns, types, speed capacities, applications, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market. Request a customised quote to align the findings with your own business planning.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of USD 7.54 Billion in 2025.
The market is projected to grow at a CAGR of 6.80% between 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach a value of USD 14.56 Billion by 2035.
The speed capacities include <1000 rpm, 1000 – 60000 rpm , and >60000 rpm.
The key regional markets for air bearings are North America, Europe, the Asia Pacific, and LAMEA.
The end uses include marine and aviation, medical, automotive, machine tools, and others.
The applications include precision metal tools, high-speed machines, coordinate measuring machines, and others.
The key players in the market include Air Bearings Limited, New Way Air Bearings, Inc., OAV Air Bearings, IBS Precision Engineering BV, Leuven Air Bearings Nv, and Mohawk Innovative Technology, Inc., among others.
Aerodynamic leads the market by type, while aerostatic is expected to grow fastest.
Asia Pacific leads the market by region, while North America is registering the fastest growth.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Speed Capacity |
|
| Breakup by Application |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




