

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
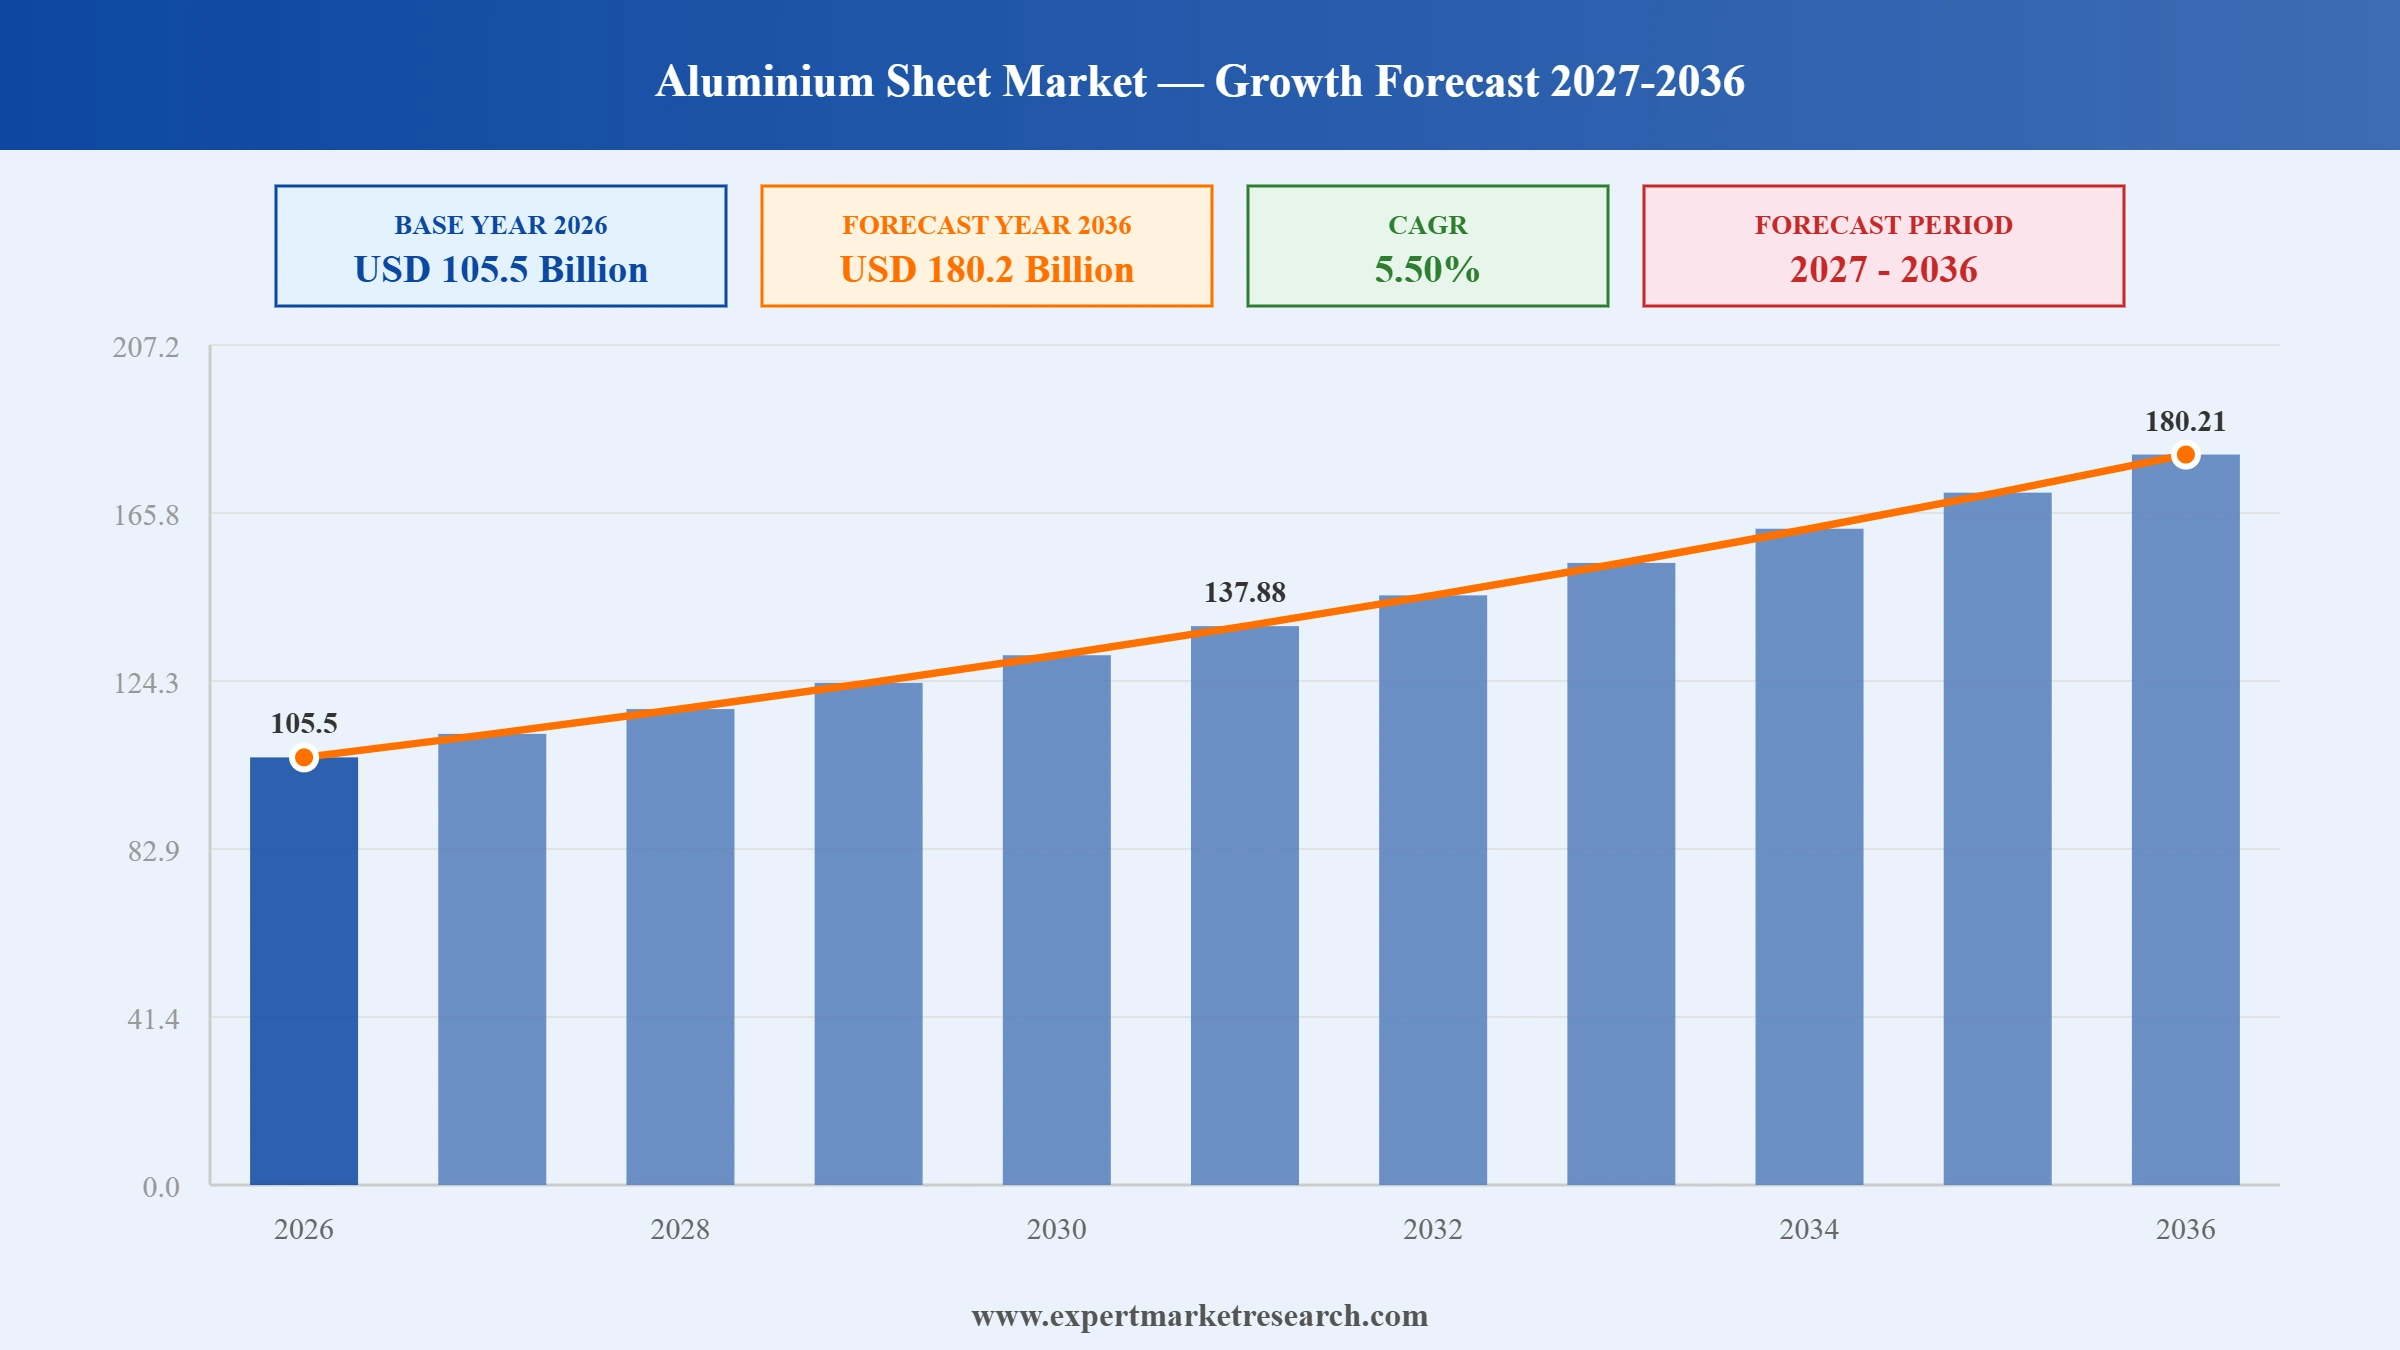
The aluminium sheet market was valued at USD 100.00 Billion in 2025. The market is expected to grow at a CAGR of 5.50% during the forecast period of 2026-2035 to reach a value of USD 170.81 Billion by 2035. Rising demand for lightweight automotive components, sustained beverage packaging consumption, and expanding construction activity are collectively driving demand for aluminium sheet worldwide.
The current aluminium sheet market dynamics reflect sustained investment in rolling and recycling capacity, as producers respond to elevated aluminium pricing and strong demand from beverage packaging, automotive, and construction customers even as individual facilities face operational disruptions. This investment reflects growing recognition that reliable, scaled sheet capacity has become a competitive differentiator as global aluminium prices and premiums remain elevated across most major consuming regions today. In March 2025, JW Aluminum Continuous Cast Company priced a 350 million dollar senior secured notes offering, refinancing existing debt to support continued operations at its South Carolina and Arkansas flat rolled aluminium facilities.
The overall aluminium sheet industry through 2025 continues to be shaped by capacity expansion across major consuming economies, as domestic manufacturers pursue new flat rolled product facilities to reduce reliance on imports and capture rising demand from electric vehicle, packaging, and renewable energy customers. Producers are simultaneously navigating volatile scrap and primary metal input costs, with premiums and pricing remaining elevated through much of the period on supply disruption concerns across the broader industry. In February 2026, Ball Corporation reported aluminium can volumes grew approximately 2 percent in 2025 even as other packaging materials declined, confirming its new Oregon can plant remains on track to start up in the second half of 2026 as North American capacity stays fully committed.
Read more about this report - Request a Free Sample
|
Aluminium Sheet Market Report Summary |
Description |
Value |
|
Base Year |
USD Billion |
2025 |
|
Historical Period |
USD Billion |
2019-2025 |
|
Forecast Period |
USD Billion |
2026-2035 |
|
Market Size 2025 |
USD Billion |
100.00 |
|
Market Size 2035 |
USD Billion |
170.81 |
|
CAGR 2019-2025 |
Percentage |
XX% |
|
CAGR 2026-2035 |
Percentage |
5.50% |
|
CAGR 2026-2035 - Market by Region |
Asia Pacific |
6.1% |
|
CAGR 2026-2035 - Market by Alloy Type |
6000 Series |
5.9% |
|
CAGR 2026-2035 - Market by Application |
Automotive |
6.0% |
|
2025 Market Share by Region |
Asia Pacific |
38.4% |
The aluminium sheet market is being reshaped by major capacity expansion and rebuilding efforts following operational disruptions, growing certification of low carbon rolled products, and expanding recognition for recycled content innovation in automotive applications.
Norsk Hydro certified its Karmoy rolling mill to supply REDUXA low carbon aluminium in finished strip and sheet form in August 2026, covering several 6000 series alloys used mainly in building applications, alongside Alcoa's parallel low carbon Ecolum offering for the building products sector. Manufacturers can point to this certification when responding to regulatory pressure to document their embodied carbon.
Constellium authorised a 300 million dollar share buyback programme starting May 21, 2026, as its shares rallied alongside industry peers amid broader optimism that reduced global aluminium supply could lift prices and improve producer margins across the sector. Other manufacturers can look to this kind of capital return signal to demonstrate confidence in sustained future margin improvement to their shareholders.
Novelis received the Munchner Management Kolloquium Award of Excellence 2026 in March 2026 for an aluminium sheet made entirely from end of life vehicle scrap, developed specifically for exterior car body applications across its European operations. This closed loop, car to car recycling achievement gives other automotive sheet suppliers a clear benchmark to pursue as customers increasingly value recycled content.
Hindalco Industries commissioned a new Flat Rolled Products facility with 170,000 tonnes per annum capacity at its Aditya Aluminium complex in Sambalpur in January 2026, alongside a battery grade aluminium foil manufacturing unit representing an investment of 4,500 crore rupees for domestic supply chains. Producers elsewhere in the market can pursue similarly integrated smelter-to-sheet expansion to capture value added margins.
Aluminium sheet manufacturers are increasingly developing automotive body sheet with higher recycled content rather than relying primarily on primary metal, reflecting automaker sustainability commitments and the significantly lower energy intensity of recycling versus primary production across most fielded manufacturing programmes today worldwide. In August 2025, Kaiser Aluminum advanced a 25 million dollar investment to expand aerospace and general engineering plate production capacity, targeting completion by the end of 2025 to meet rising demand for high performance aluminium plate products globally.
Aluminium producers are increasingly modernising existing rolling and casting facilities to expand recycling capacity rather than building entirely new primary production lines, reflecting the substantially lower capital cost and energy footprint of recycled aluminium processing compared to primary smelting operations across the broader industry today across the world. In March 2026, Arconic announced a 131 million dollar aluminium casting complex at its Davenport Works campus in Iowa, expanding ingot capacity with first metal targeted for the third quarter of 2027.
Aluminium producers are increasingly securing long term renewable power purchase agreements to stabilise energy costs and reduce the carbon footprint of primary and recycled aluminium production, reflecting the energy intensive nature of smelting and rolling operations across the broader global industry landscape today across the world. In July 2025, UACJ received the twelfth annual Best Performance Award from Kawasaki Heavy Industries, recognising sustained supply reliability and quality performance across its rolled aluminium product lines serving the automotive and industrial sectors.
Aluminium sheet manufacturers are increasingly developing dedicated battery enclosure and structural sheet products for electric vehicle platforms, reflecting automakers' need for lightweight, crash resistant materials that also provide thermal management properties for battery packs across their global vehicle platforms and production lines worldwide today across the entire wider industry. In May 2026, Aperam acquired Magnetec, a German producer of soft magnetic materials, extending its electrical steel and specialty alloy portfolio to serve growing electric vehicle and renewable energy component demand.
Aluminium producers are increasingly securing long term bauxite mining leases to support upstream alumina and primary metal capacity growth feeding downstream sheet production, reflecting the raw material security concerns that accompany expanding rolled product demand across major consuming economies worldwide today across the wider world. In December 2025, National Aluminium Company secured a fifty year mining lease for the Pottangi bauxite deposit in Odisha, India, supporting a planned fifth production stream adding 1 million tonnes of annual alumina refining capacity.
The Expert Market Research's report titled “Aluminium Sheet Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Alloy Type
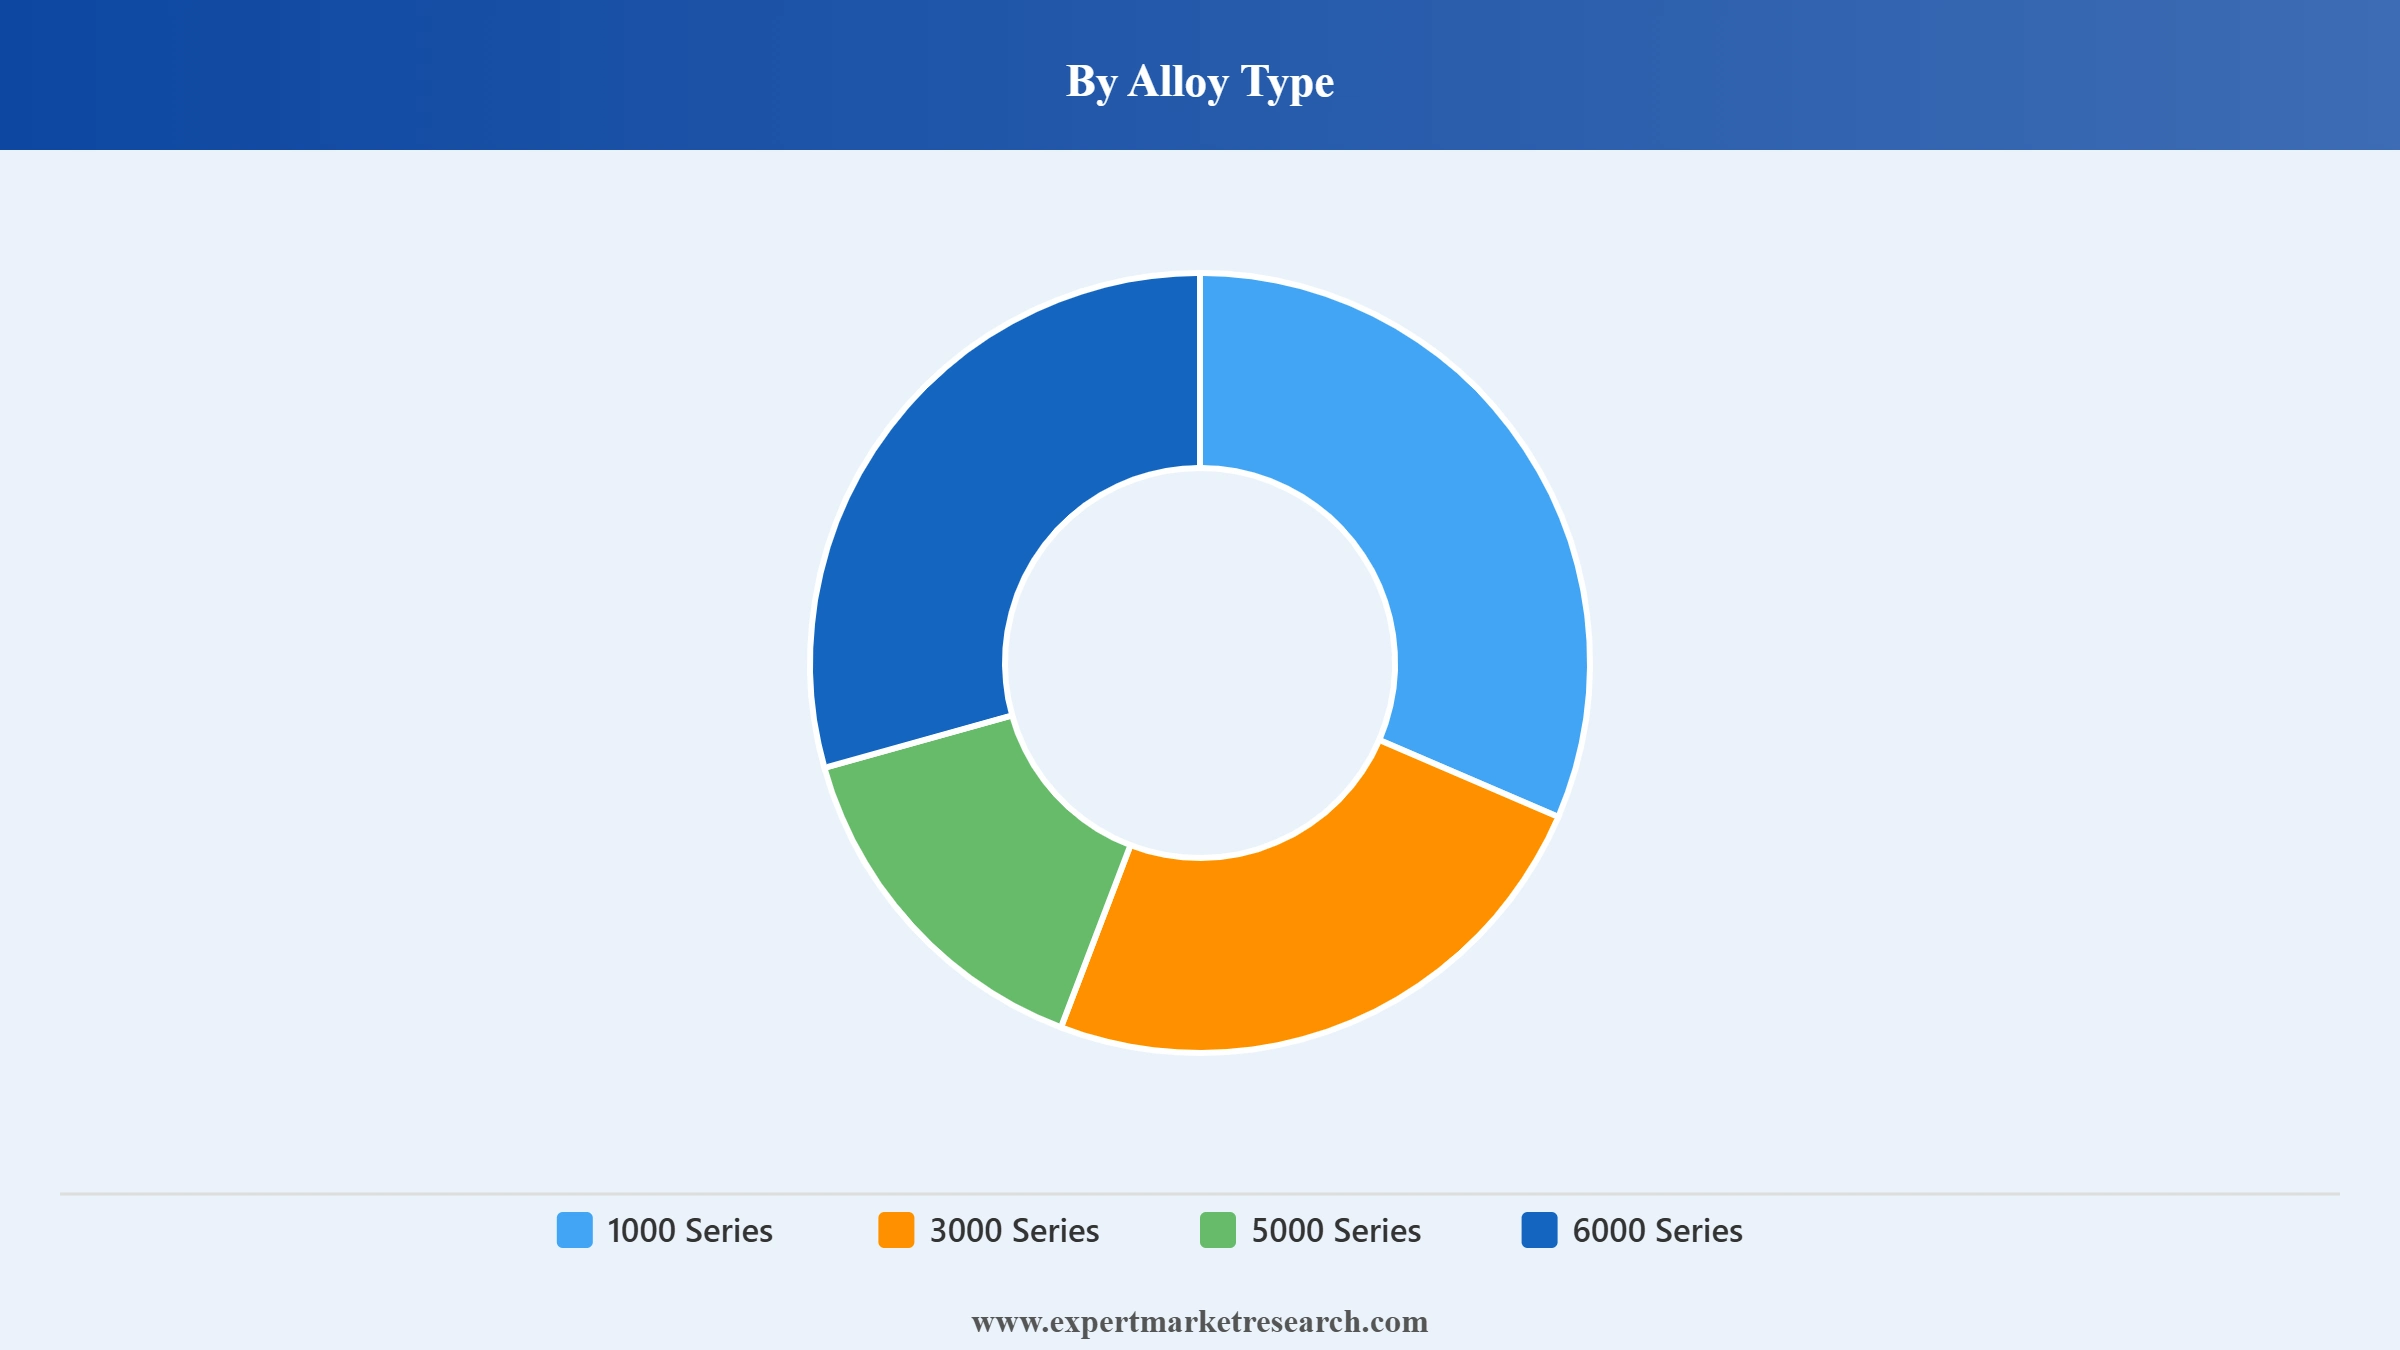
Key Insight: 3000 Series aluminium sheets account for a leading share of the aluminium sheet market by alloy type, valued for their corrosion resistance and moderate strength in beverage can and general sheet metal applications. In April 2026, Speira published Environmental Product Declarations covering all major cold and hot rolled alloy categories in its Specialities business, independently verified by the Tetis Institute, supporting sustainable construction certifications including BREEAM, LEED, and DGNB. 6000 Series aluminium sheets are the fastest-growing alloy type as automotive lightweighting programmes increasingly specify their superior strength to weight ratio. 5000 Series alloys serve marine, automotive, and structural applications. 1000 Series remains suited to applications prioritising corrosion resistance and electrical conductivity. The Others category includes 2000, 7000, and 8000 series specialty alloys.
Market Breakup by Application
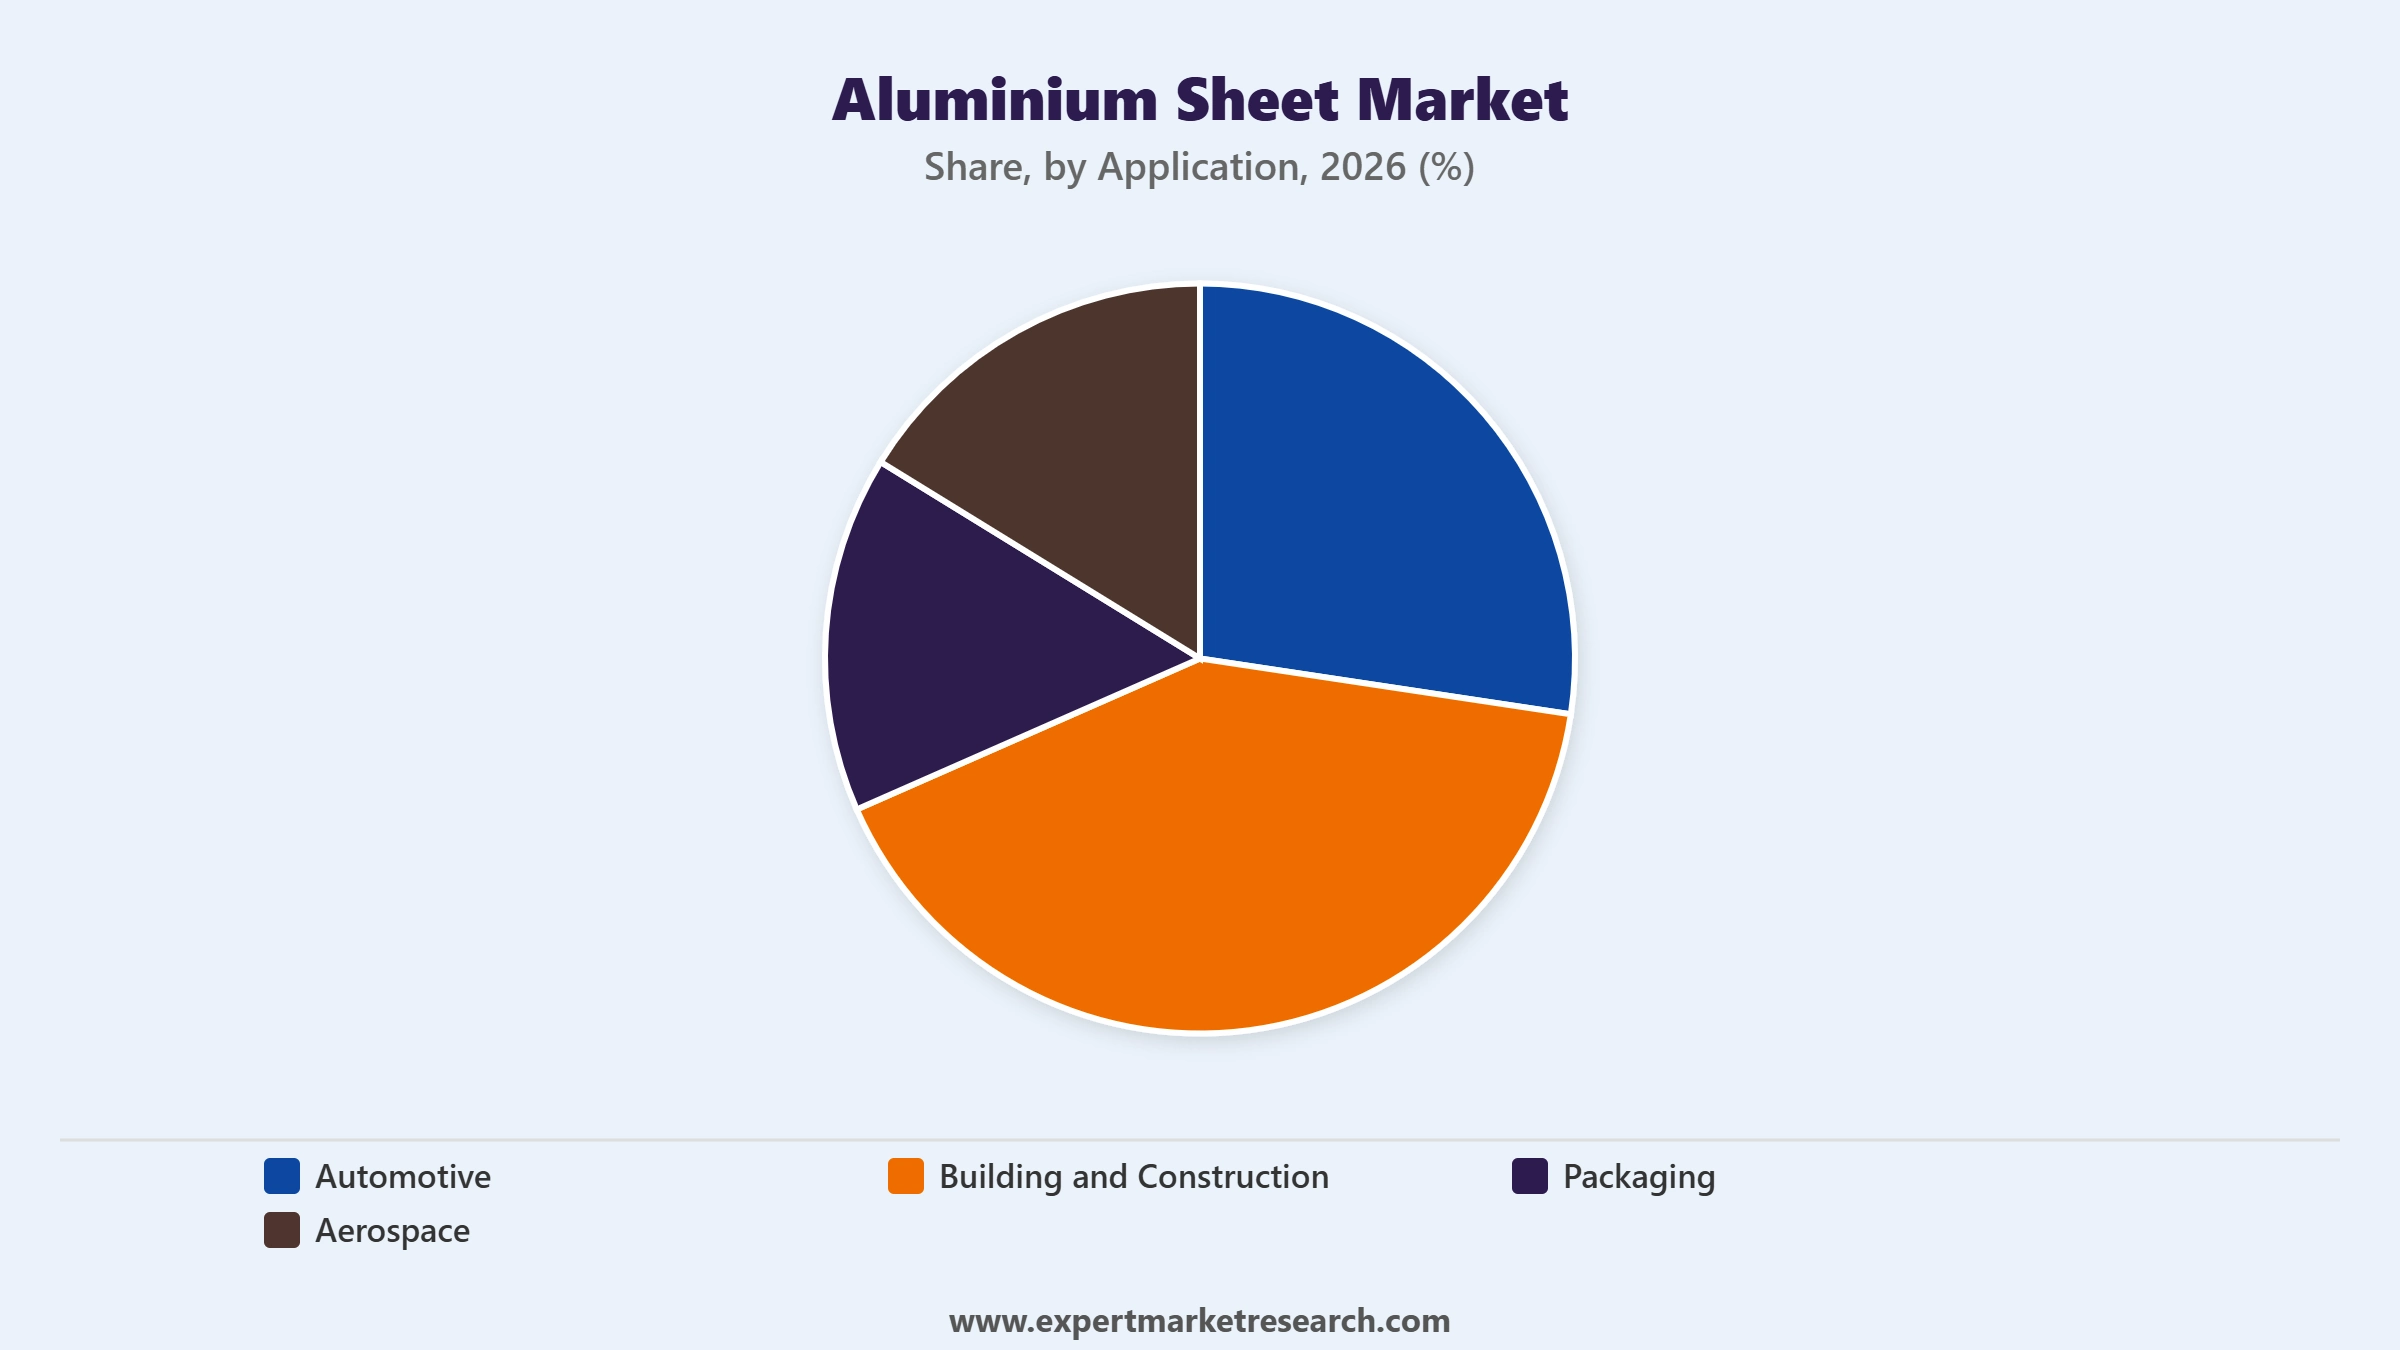
Key Insight: Packaging accounts for the largest share of the aluminium sheet market by application, supported by the material's moisture barrier properties, infinite recyclability, and cost effective formability in beverage cans and food containers. Automotive is the fastest-growing application as vehicle lightweighting programmes expand aluminium sheet use in body panels, structural components, and battery enclosures. Building and Construction relies on aluminium sheet for roofing, cladding, and interior fittings. Aerospace uses aluminium sheet for its high strength to weight ratio in aircraft structures. The Others category includes consumer durables and industrial equipment applications.
Market Breakup by Region
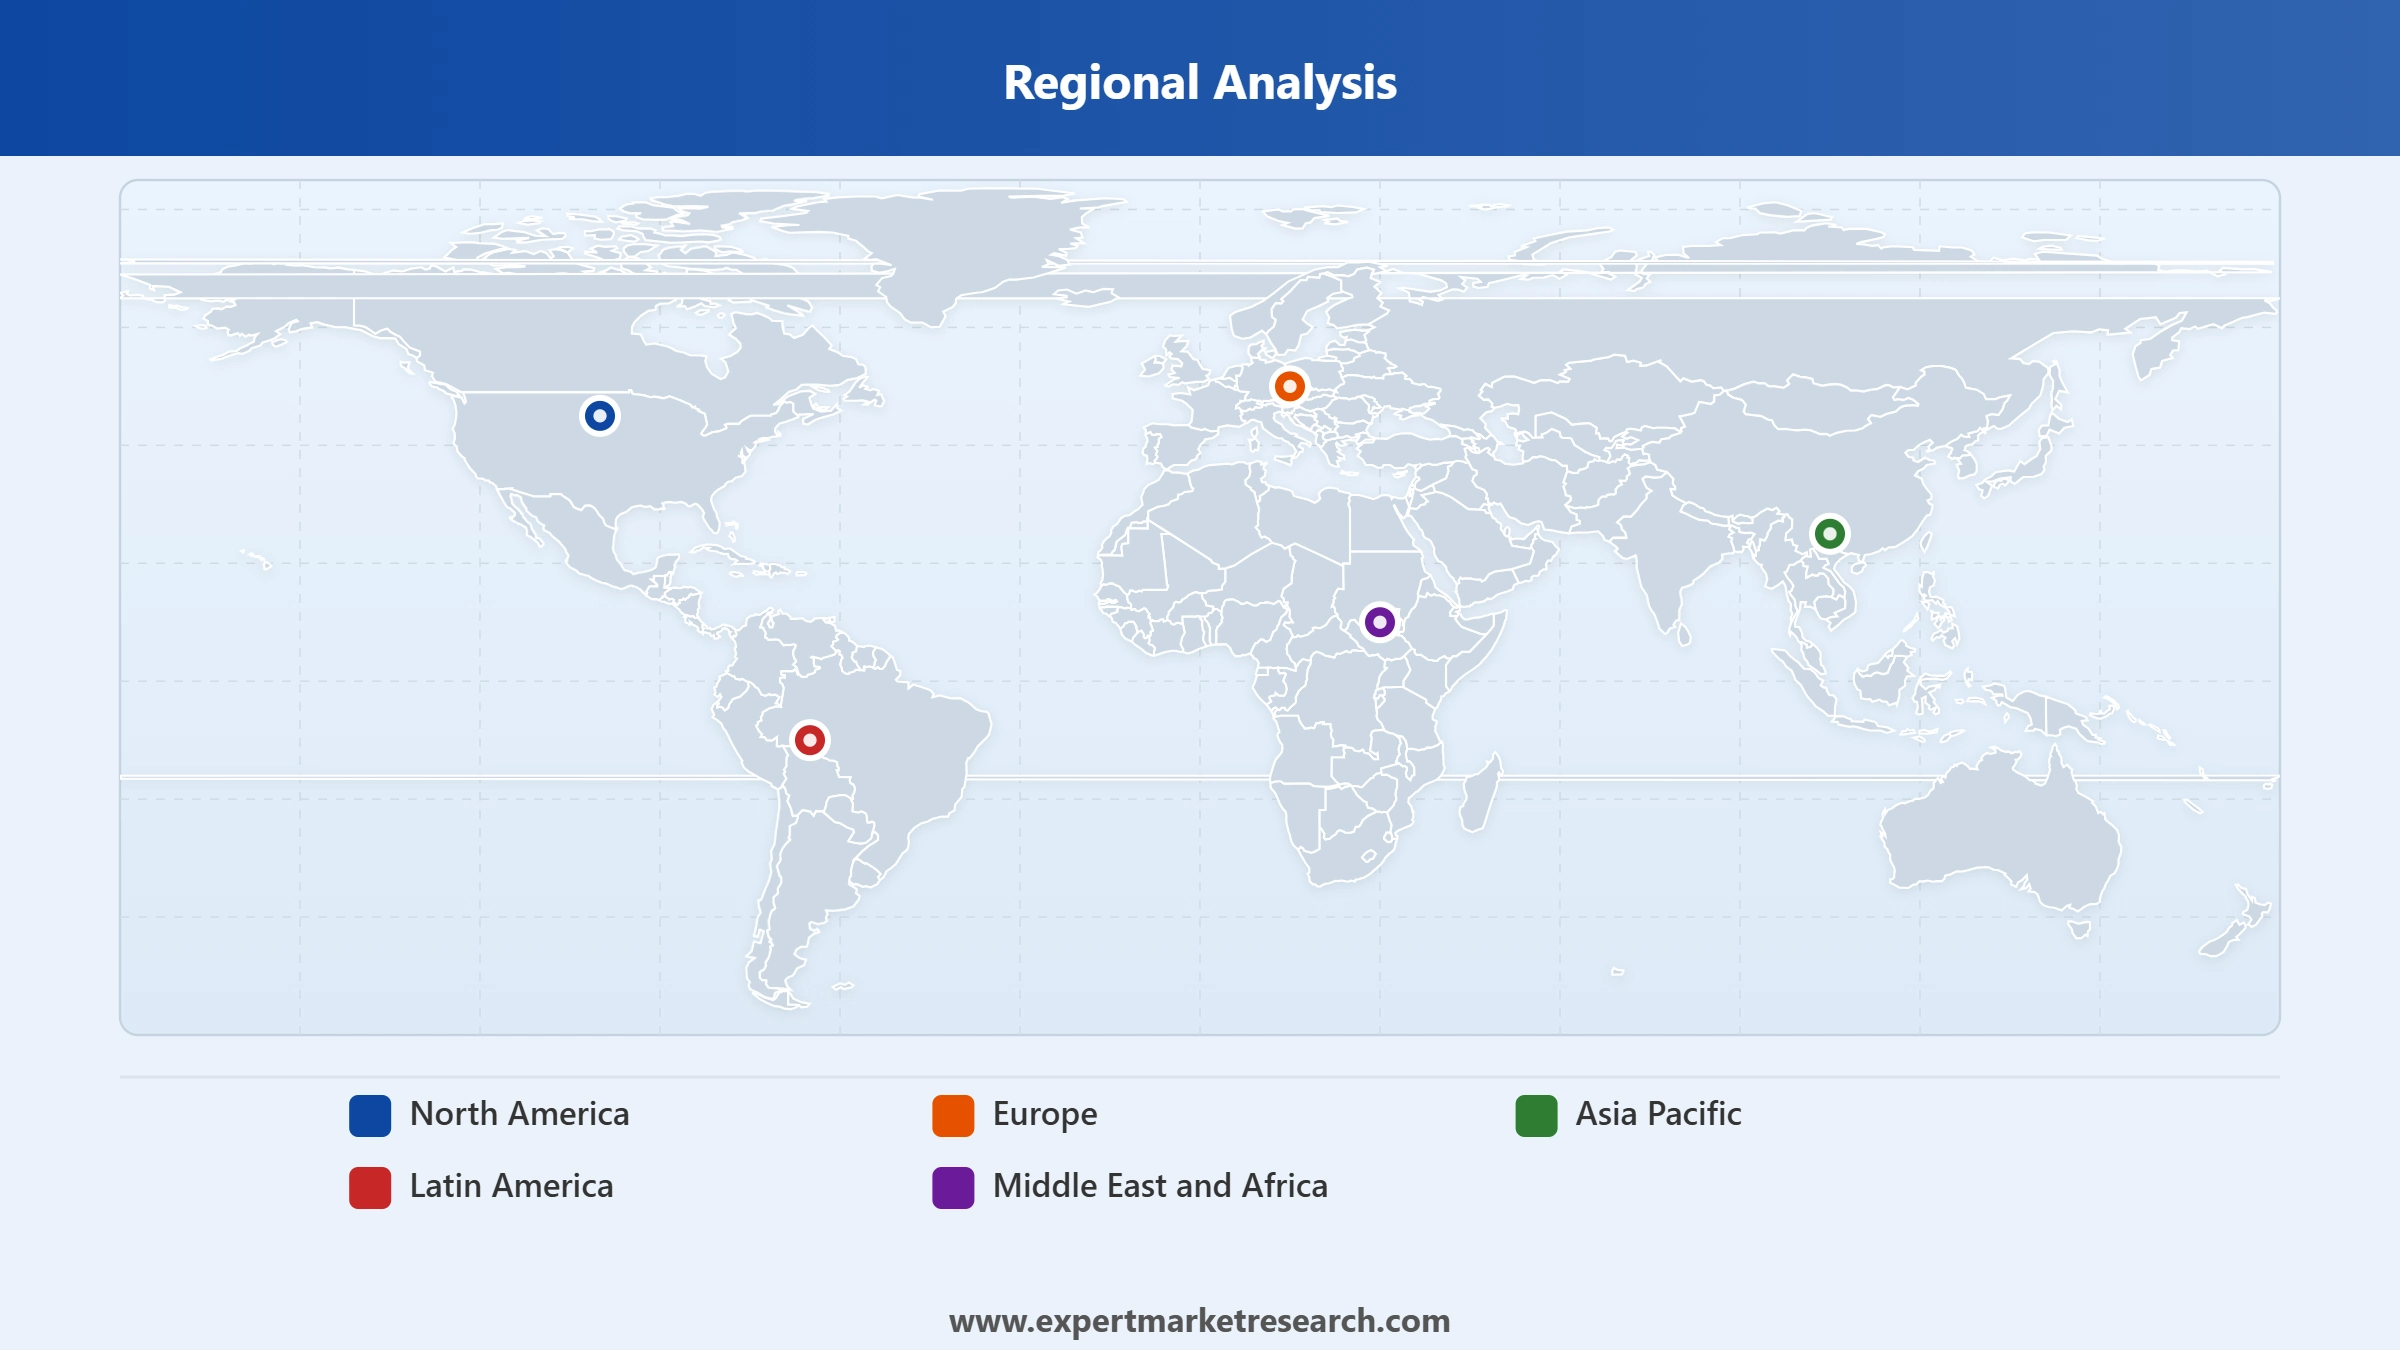
Key Insight: Asia Pacific dominates the aluminium sheet market, driven by rapid industrialisation and infrastructure growth concentrated in China and India. Asia Pacific is also the fastest-growing region as new rolling capacity and downstream investment continue expanding regional production. Europe focuses on lightweight automotive manufacturing and renewable energy projects, while North America benefits from advancements in aerospace and electric vehicle production. Latin America and the Middle East and Africa remain smaller markets tied to broader industrial and construction investment.
Read more about this report - Request a Free Sample
By alloy type, 3000 series leads the market due to its corrosion resistance and moderate strength in beverage can and general sheet metal applications
3000 Series aluminium sheets account for a leading share of the aluminium sheet market by alloy type, valued for their corrosion resistance and moderate strength in beverage can and general sheet metal applications across most fielded programmes today and established supply chains across the world. In April 2025, Chalco Shanxi New Materials Aluminum Processing Plant achieved mass production of a high performance 5052 wrought aluminium alloy, illustrating continued domestic alloy development investment supporting China's broader flat rolled sheet manufacturing base.
Read more about this report - Request a Free Sample
6000 Series aluminium sheets are the fastest-growing alloy type as automotive lightweighting programmes increasingly specify their superior strength to weight ratio and formability for body panels and structural components across major global vehicle platforms and production lines today worldwide overall across all markets. In June 2026, Rio Tinto began commissioning its 1.5 billion dollar AP60 low carbon smelter expansion at Complexe Arvida in Quebec, alongside a co-located recycling centre, to supply lower carbon aluminium for transportation, construction, and electrical applications.
By application, packaging leads the market due to its moisture barrier properties, infinite recyclability, and cost effective formability
Packaging accounts for the largest share of the aluminium sheet market by application, supported by the material's moisture barrier properties, infinite recyclability, and cost effective formability in beverage cans and food containers worldwide today across most major global markets overall today. In April 2026, Crown Holdings announced plans to construct a new two line, high speed beverage can plant in Northern India, partnering with United Breweries Limited to serve rising demand for aluminium cans across alcoholic and non-alcoholic beverage segments.
Read more about this report - Request a Free Sample
Automotive is the fastest-growing application as vehicle lightweighting programmes expand aluminium sheet use in body panels, structural components, and battery enclosures across major global manufacturing hubs and production platforms today across the wider industry overall and across all markets. In January 2026, Aluminium Bahrain announced a historic 2025 production record of 1,623,139 metric tonnes, supplying rolling slabs used by downstream mills to manufacture automotive sheet products despite an industrial fire disruption earlier in the year at one of its facilities.
Asia Pacific dominates the market due to rapid industrialisation and infrastructure growth in China and India
Asia Pacific dominates the aluminium sheet market, driven by rapid industrialisation and infrastructure growth concentrated in China and India and their broader manufacturing supplier ecosystems and downstream customer bases today. New rolled product capacity is also emerging outside the region, with Emirates Global Aluminium confirming in February 2026 that first metal charging had begun at its Al Taweelah recycling plant, with first production expected by the end of the first quarter of 2026, extending Middle Eastern value added aluminium capacity.
Read more about this report - Request a Free Sample
Asia Pacific is also the fastest-growing region as new rolling capacity and downstream investment continue expanding regional production across several key national markets pursuing manufacturing sector growth and export capability worldwide overall today across the wider region. In January 2026, Press Metal, Southeast Asia's largest integrated aluminium producer, announced it had hedged approximately 40 percent of its 2026 alumina requirements through forward contracts, insulating margins from raw material price volatility ahead of continued regional capacity expansion plans across its operations.
|
CAGR 2026-2035 - Market by |
Region |
|
North America |
5.2% |
|
Europe |
5.0% |
|
Asia Pacific |
6.1% |
|
Latin America |
5.6% |
|
Middle East and Africa |
5.8% |
The global aluminium sheet companies feature a moderately consolidated competitive structure led by established rolling and recycling companies with broad alloy portfolios and integrated smelter-to-sheet operations. Manufacturers including Novelis and Norsk Hydro are competing primarily through recycling capacity and low carbon certification, while producers including Constellium and Hindalco differentiate through specialised aerospace and automotive alloy expertise and integrated domestic supply chains.
Leading aluminium sheet market players are focusing on expanding recycled content in automotive and packaging sheet, pursuing facility modernisation to improve recycling capacity, and securing long term renewable power agreements to stabilise costs and reduce carbon footprint. Increasing investment in battery enclosure and electric vehicle structural sheet capacity is also reshaping product development priorities across the industry.
Novelis Inc., founded in 2005 and headquartered in Atlanta, Georgia, United States, is the world's leading producer of rolled aluminium products and the largest recycler of aluminium globally, serving automotive, beverage can, aerospace, and specialty markets. The company continues to expand recycling capacity and recycled content across its automotive sheet portfolio while rebuilding and expanding production capacity at its North American facilities.
Norsk Hydro ASA, founded in 1905 and headquartered in Oslo, Norway, is a fully integrated aluminium company spanning bauxite mining, alumina refining, primary production, recycling, and rolled and extruded products. The company continues to expand its REDUXA and CIRCAL low carbon aluminium offerings, certifying additional rolling mills to supply low carbon sheet and strip for building and automotive applications.
Constellium SE, founded in 2011 and headquartered in Paris, France, is a global leader in specialty rolled and extruded aluminium products, serving aerospace, automotive, and packaging customers through dedicated business segments. The company continues to invest in its Aerospace and Transportation and Packaging and Automotive Rolled Products segments while returning capital to shareholders through share repurchase programmes.
Hindalco Industries Limited, founded in 1958 and headquartered in Mumbai, India, is the metals flagship of the Aditya Birla Group and one of the world's leading aluminium and copper producers by revenue. The company continues to expand its integrated aluminium value chain in India, commissioning new flat rolled products and battery grade foil manufacturing capacity to support domestic electric vehicle and clean energy supply chains.
Other key players in the market report include Alcoa Corporation, UACJ Corporation, Kaiser Aluminum Corporation, Arconic Corporation, and Aperam S.A., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Explore the latest trends shaping the aluminium sheet market 2026-2035 with our in-depth report. Gain strategic insights, future forecasts, and key market developments that can help you stay competitive. Download a free sample report or contact our team for customised consultation on the market trends 2026.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the aluminium sheet market reached an approximate value of USD 100.00 Billion.
The market is projected to grow at a CAGR of 5.50% between 2026 and 2035.
The key players in the market include Novelis Inc., Norsk Hydro ASA, Constellium SE, Alcoa Corporation, Hindalco Industries Limited, UACJ Corporation, Kaiser Aluminum Corporation, Arconic Corporation, and Aperam S.A., among others.
Leading manufacturers are focusing on expanding recycled content in automotive and packaging sheet, pursuing facility modernisation to improve recycling capacity, and securing long term renewable power agreements.
Key challenges include elevated aluminium pricing and premiums, scrap feedstock availability constraints, and exposure to trade tariff policy changes across major consuming economies.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
|
Report Features |
Details |
|
Base Year |
2025 |
|
Historical Period |
2019-2025 |
|
Forecast Period |
2026-2035 |
|
Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
|
Breakup by Alloy Type |
|
|
Breakup by Application |
|
|
Breakup by Region |
|
|
Market Dynamics |
|
|
Competitive Landscape |
|
|
Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




