

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
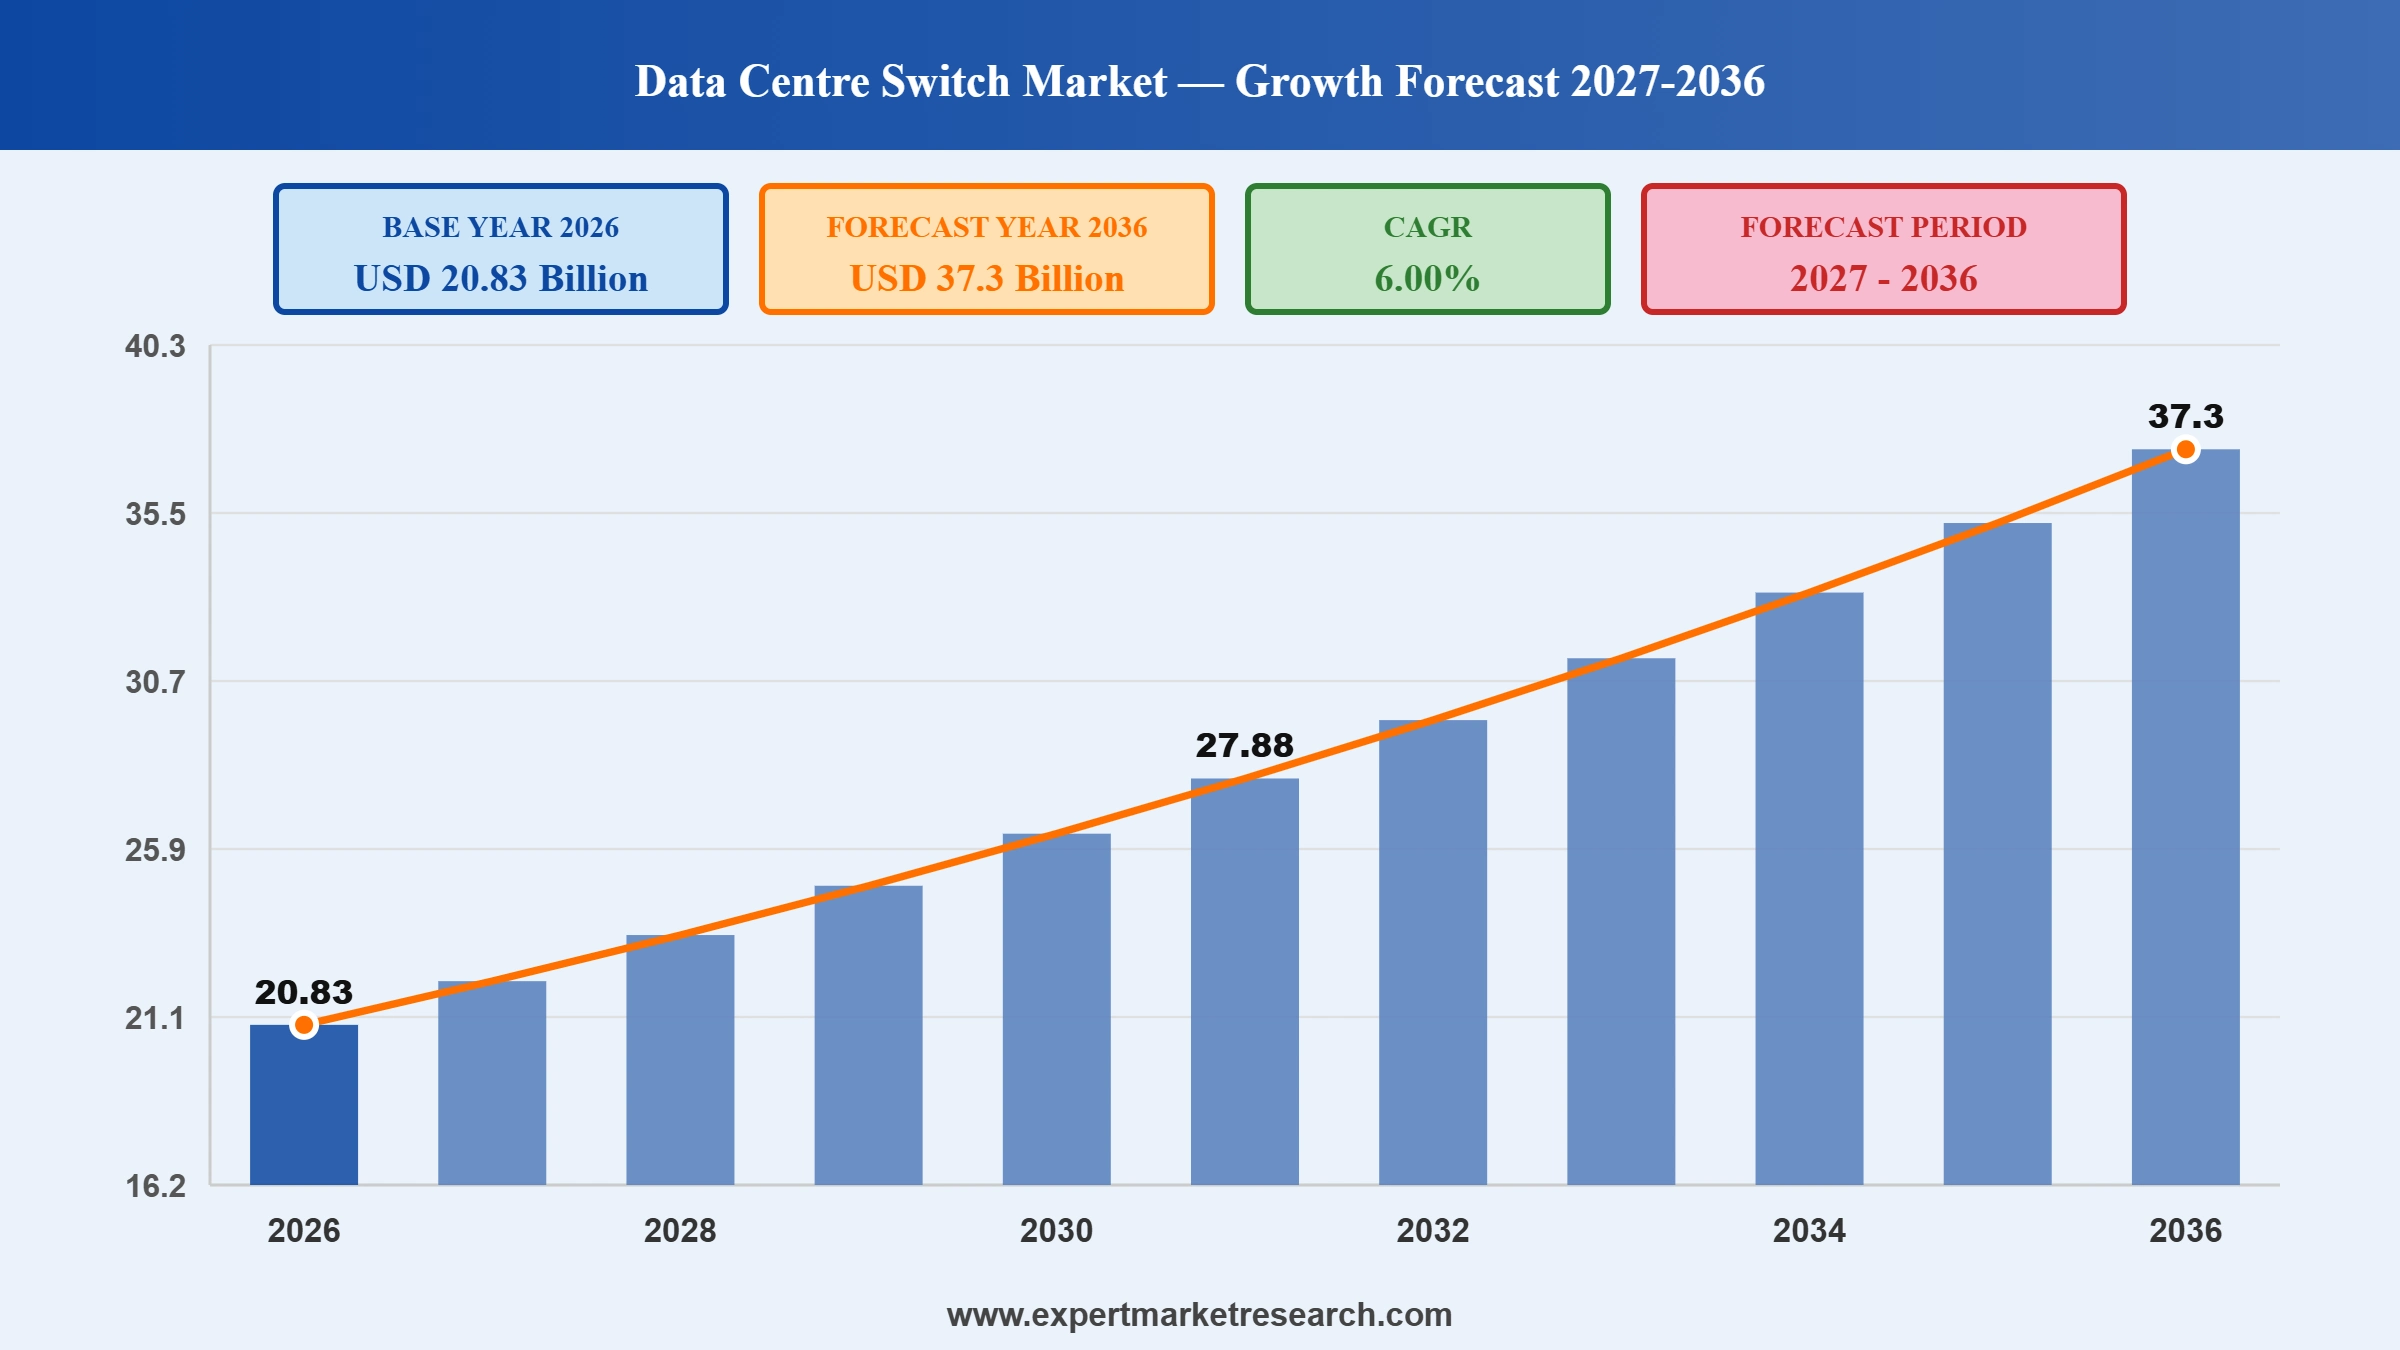
The global data centre switch market attained a value of USD 19.65 Billion in 2025 and is projected to expand at a CAGR of 6.00% through 2035. The market is further expected to achieve USD 35.19 Billion by 2035, driven by rising AI cluster build-outs, the migration to 400G and 800G Ethernet, and sustained cloud, telecom, enterprise, and government investment in data centre capacity worldwide.
Standards work is setting the pace for higher port speeds. In January 2026, the Ethernet Alliance said IEEE 802.3dj, which enables 200G, 400G, 800G, and 1.6T operation at 200G per lane, is on track for completion in late 2026, with early products expected during 2026. The Ultra Ethernet Consortium released its v1.0 specification in June 2025, giving switch makers a common path for AI and high-performance computing networks.
Hyperscale spending remains the largest single pull on switch capacity. Alphabet said in July 2026 that its second-quarter capital expenditure reached USD 44.9 billion, double the level of a year earlier, and raised its 2026 guidance to a range of USD 195 billion to USD 205 billion, a commitment that flows directly into spine, leaf, and aggregation switch purchases for new data centre halls and AI clusters.
Enterprise demand is also firming. Cisco said in May 2026 that enterprise data centre switching orders rose more than 40% in its fiscal third quarter, while campus networking orders grew more than 25% year on year, which suggests that refresh cycles and private AI deployments are adding to hyperscale demand rather than simply following it, and that switch makers with broad portfolios can serve both buyer groups.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
In September 2026, HPE and Oracle announced a multi-year expansion of their collaboration to deploy HPE Juniper Networking across Oracle's AI data centres worldwide, covering QFX and EX switching alongside PTX and MX routing. The latest QFX switches will support RoCEv2 AI back-end networks for large GPU clusters. Companies can leverage Ethernet-based fabrics and multi-year support services to win hyperscale AI network deployments.
Cisco reported fourth-quarter fiscal 2026 revenue of USD 17.3 billion, up 18%, in August 2026, with AI infrastructure orders of USD 4 billion in the quarter and USD 9.3 billion for the full year. About 60% of those orders were for Silicon One routing and switching systems, with the rest in optics. Companies can secure silicon-to-system design wins with hyperscalers to capture AI network spending.
Extreme Networks reported fiscal 2026 revenue of USD 1,283.6 million, up 12.6%, in August 2026, with fourth-quarter revenue of USD 338.6 million, up 10.3%, its sixth consecutive quarter of double-digit growth. Product revenue rose 14.9% for the year to USD 809.6 million, and management expects double-digit product growth in fiscal 2027. Companies can expand AI-ready platform subscriptions to turn switching demand into recurring revenue.
In June 2026, Arista Networks announced its 7060XE7 Series, a 1.6T switch portfolio delivering 100 terabits per second of switching capacity with 224G SerDes technology, built on Broadcom's Tomahawk 6 silicon and including a liquid-cooled model. Linear pluggable optics are intended to cut interconnect power by roughly 60%. Companies can leverage liquid-cooled, high-radix platforms to lower power per bit in AI clusters.
In February 2026, Cisco announced the Silicon One G300, a 102.4 Tbps switching chip that powers new Cisco N9000 and Cisco 8000 systems in liquid-cooled and air-cooled designs, alongside 800G linear pluggable optics and 1.6T OSFP modules. Cisco cited a 28% reduction in job completion time and nearly 70% better energy efficiency with full liquid cooling. Companies can leverage integrated silicon, systems, and optics to differentiate on efficiency in AI networks.
At the Huawei Network Summit 2026 in Cairo in April 2026, Huawei launched its Xinghe AI Fabric 2.0 solution and more than ten new CloudEngine data centre switches, including the XH9330-128EO, described as the industry's highest-density 100T fixed switch with 128 ports of 800GE, and a 51.2T liquid-cooled model. Companies can leverage dense 800GE hardware paired with intelligent operations software to serve AI training and inference builds.
Arista Networks reported first-quarter 2026 revenue of USD 2.709 billion in May 2026, up 35.1% year on year, and guided to about USD 2.8 billion for the next quarter. The company also introduced a universal AI spine built on its 7800 platform and XPO liquid-cooled pluggable optics that it says reduce networking racks by up to 75%. Companies can leverage rack-scale designs to cut floor space and power in large AI deployments.
Dell Technologies reported record second-quarter fiscal 2027 revenue of USD 47.0 billion, up 58%, in September 2026, with record AI server orders of USD 60.9 billion and an AI backlog of USD 95 billion, and raised full-year revenue guidance to USD 192.0 billion. Each AI server cluster pulls through large volumes of switching. Companies can pair server, storage, and networking offers to capture the network share of AI cluster budgets.
This Expert Market Research Report titled "Global Data Centre Switch Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
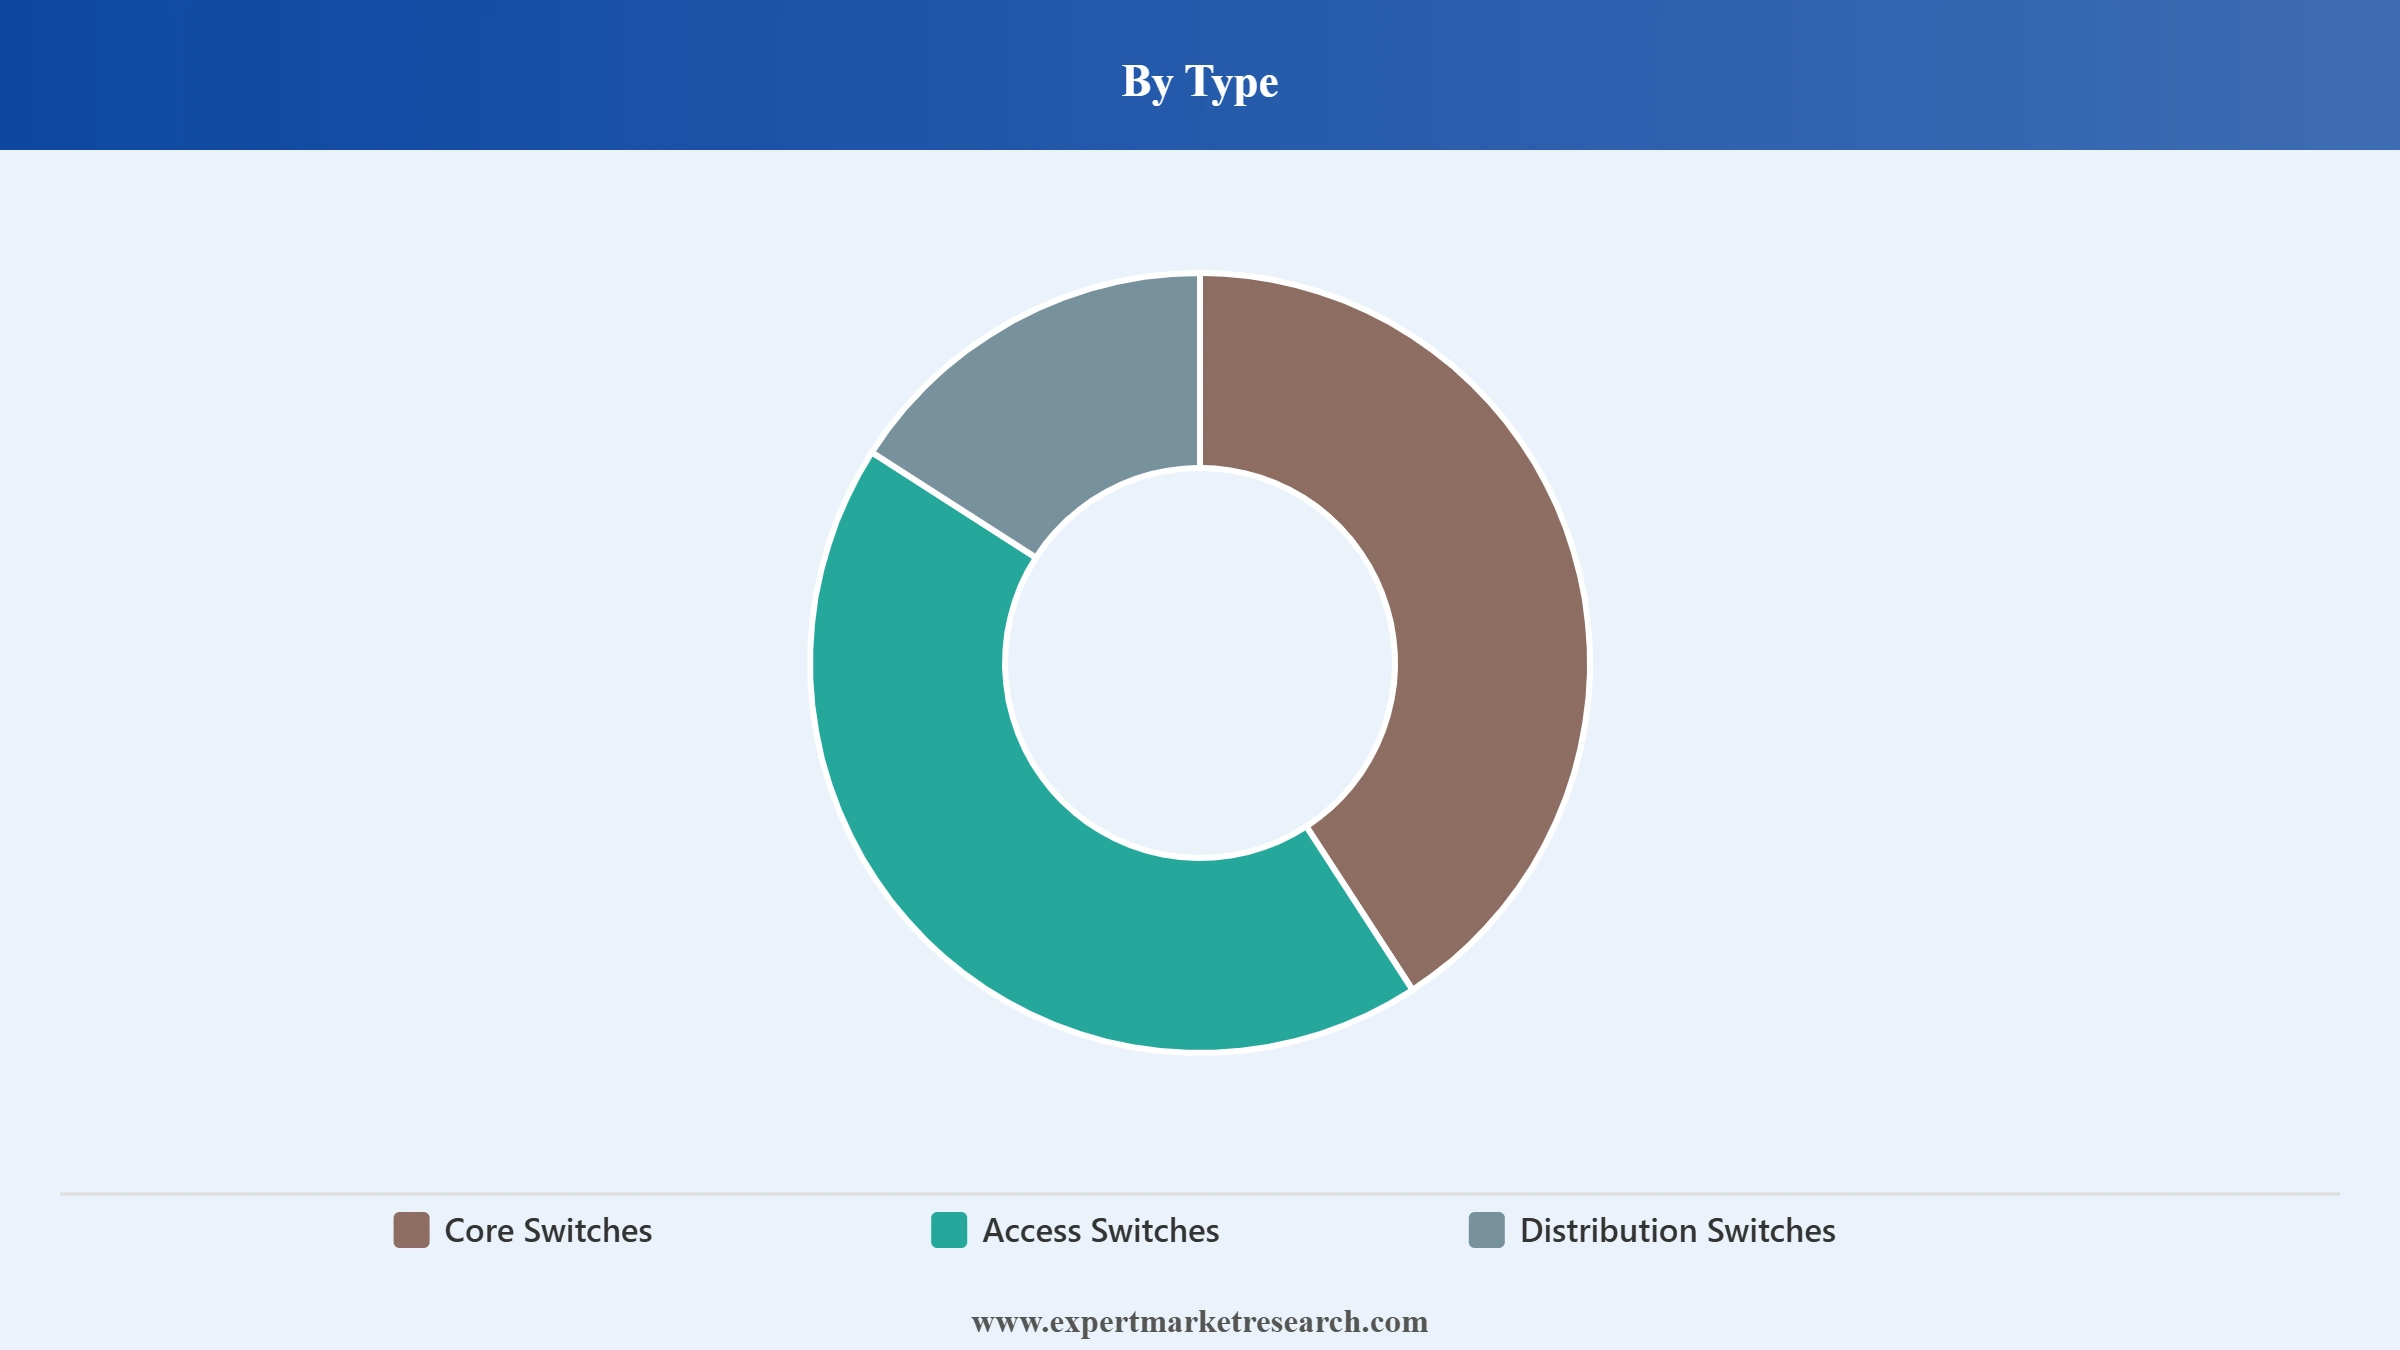
Market Breakup by Type
Key Insight: Access Switches are the leading type because every rack and campus edge needs them, and Extreme Networks said in August 2026 that its Platform ONE exceeded 30% of subscription bookings in its first year; Core Switches are the fastest-growing type as AI clusters demand spine capacity, shown by Huawei's April 2026 launch of a 100T fixed switch with 128 ports of 800GE; and Distribution Switches provide the aggregation layer, with HPE's September 2026 agreement with Oracle covering QFX and EX switching platforms across AI data centres.
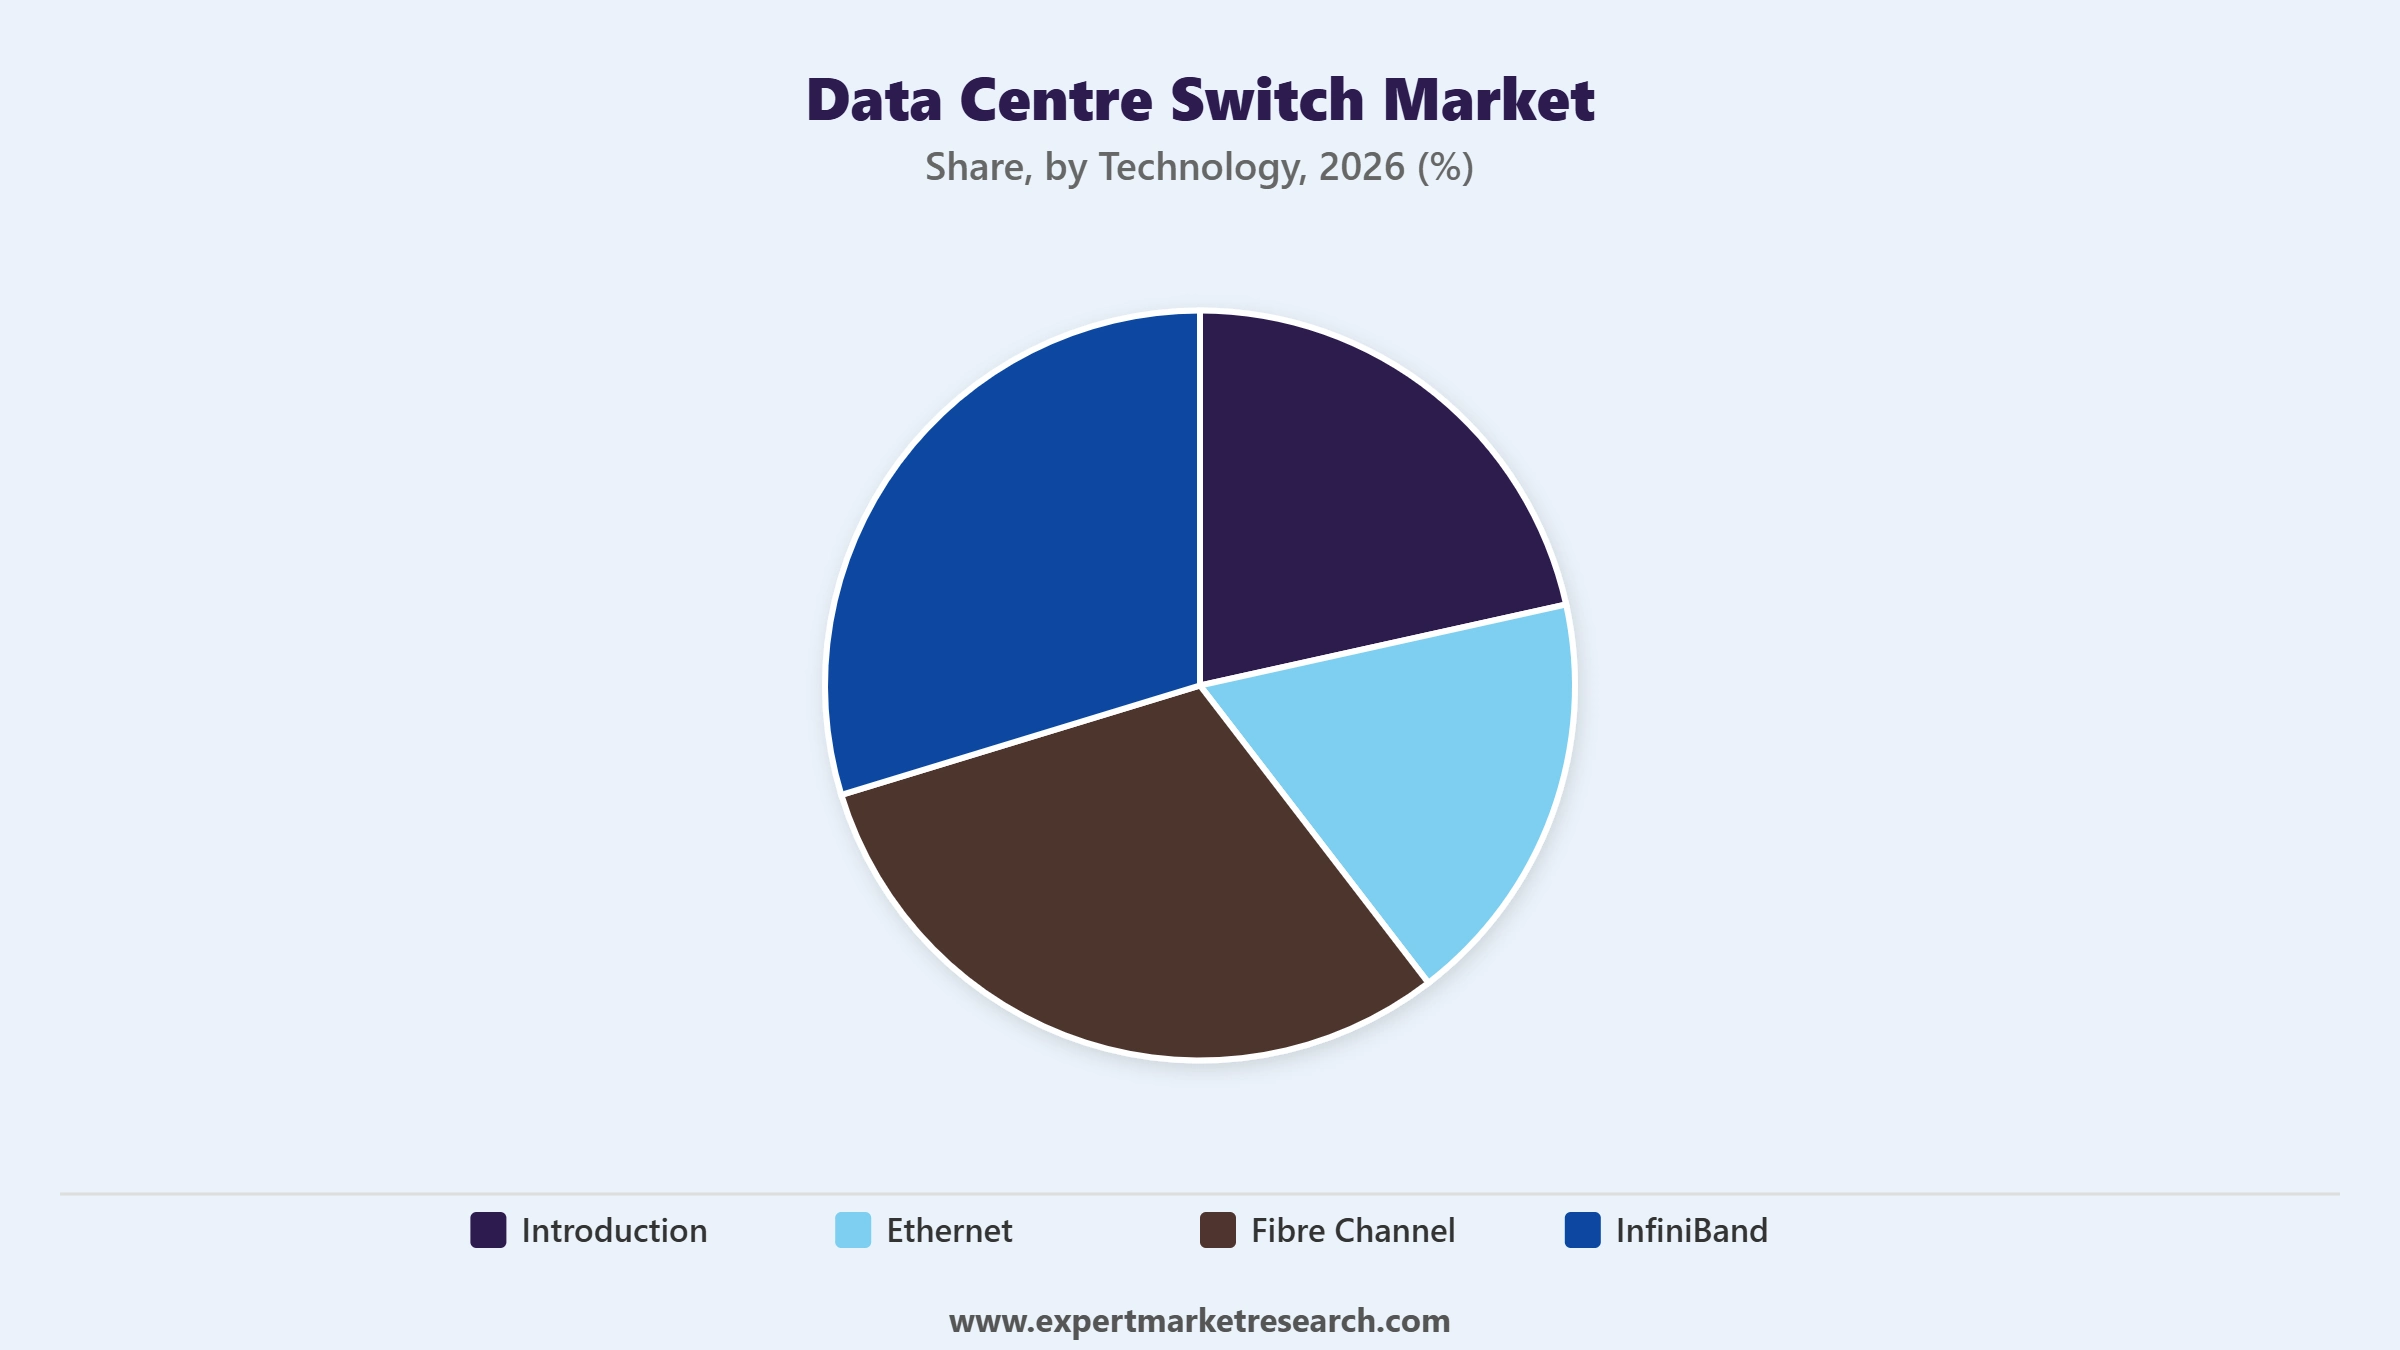
Market Breakup by Technology
Key Insight: Introduction frames the technology scope of the market, covering the switching fabrics used to connect servers, storage, and accelerators; Ethernet is the leading technology, with the Ethernet Alliance saying in January 2026 that IEEE 802.3dj is on track for late 2026 completion at 200G per lane; Fibre Channel remains the storage-network standard, with Broadcom introducing its Gen 8 128G Fibre Channel platforms in November 2025; and Infiniband remains the lossless fabric used in tightly coupled GPU training clusters, with NVIDIA, which owns Mellanox Technologies, rating its Quantum-X800 platform at 800 Gb/s of throughput.
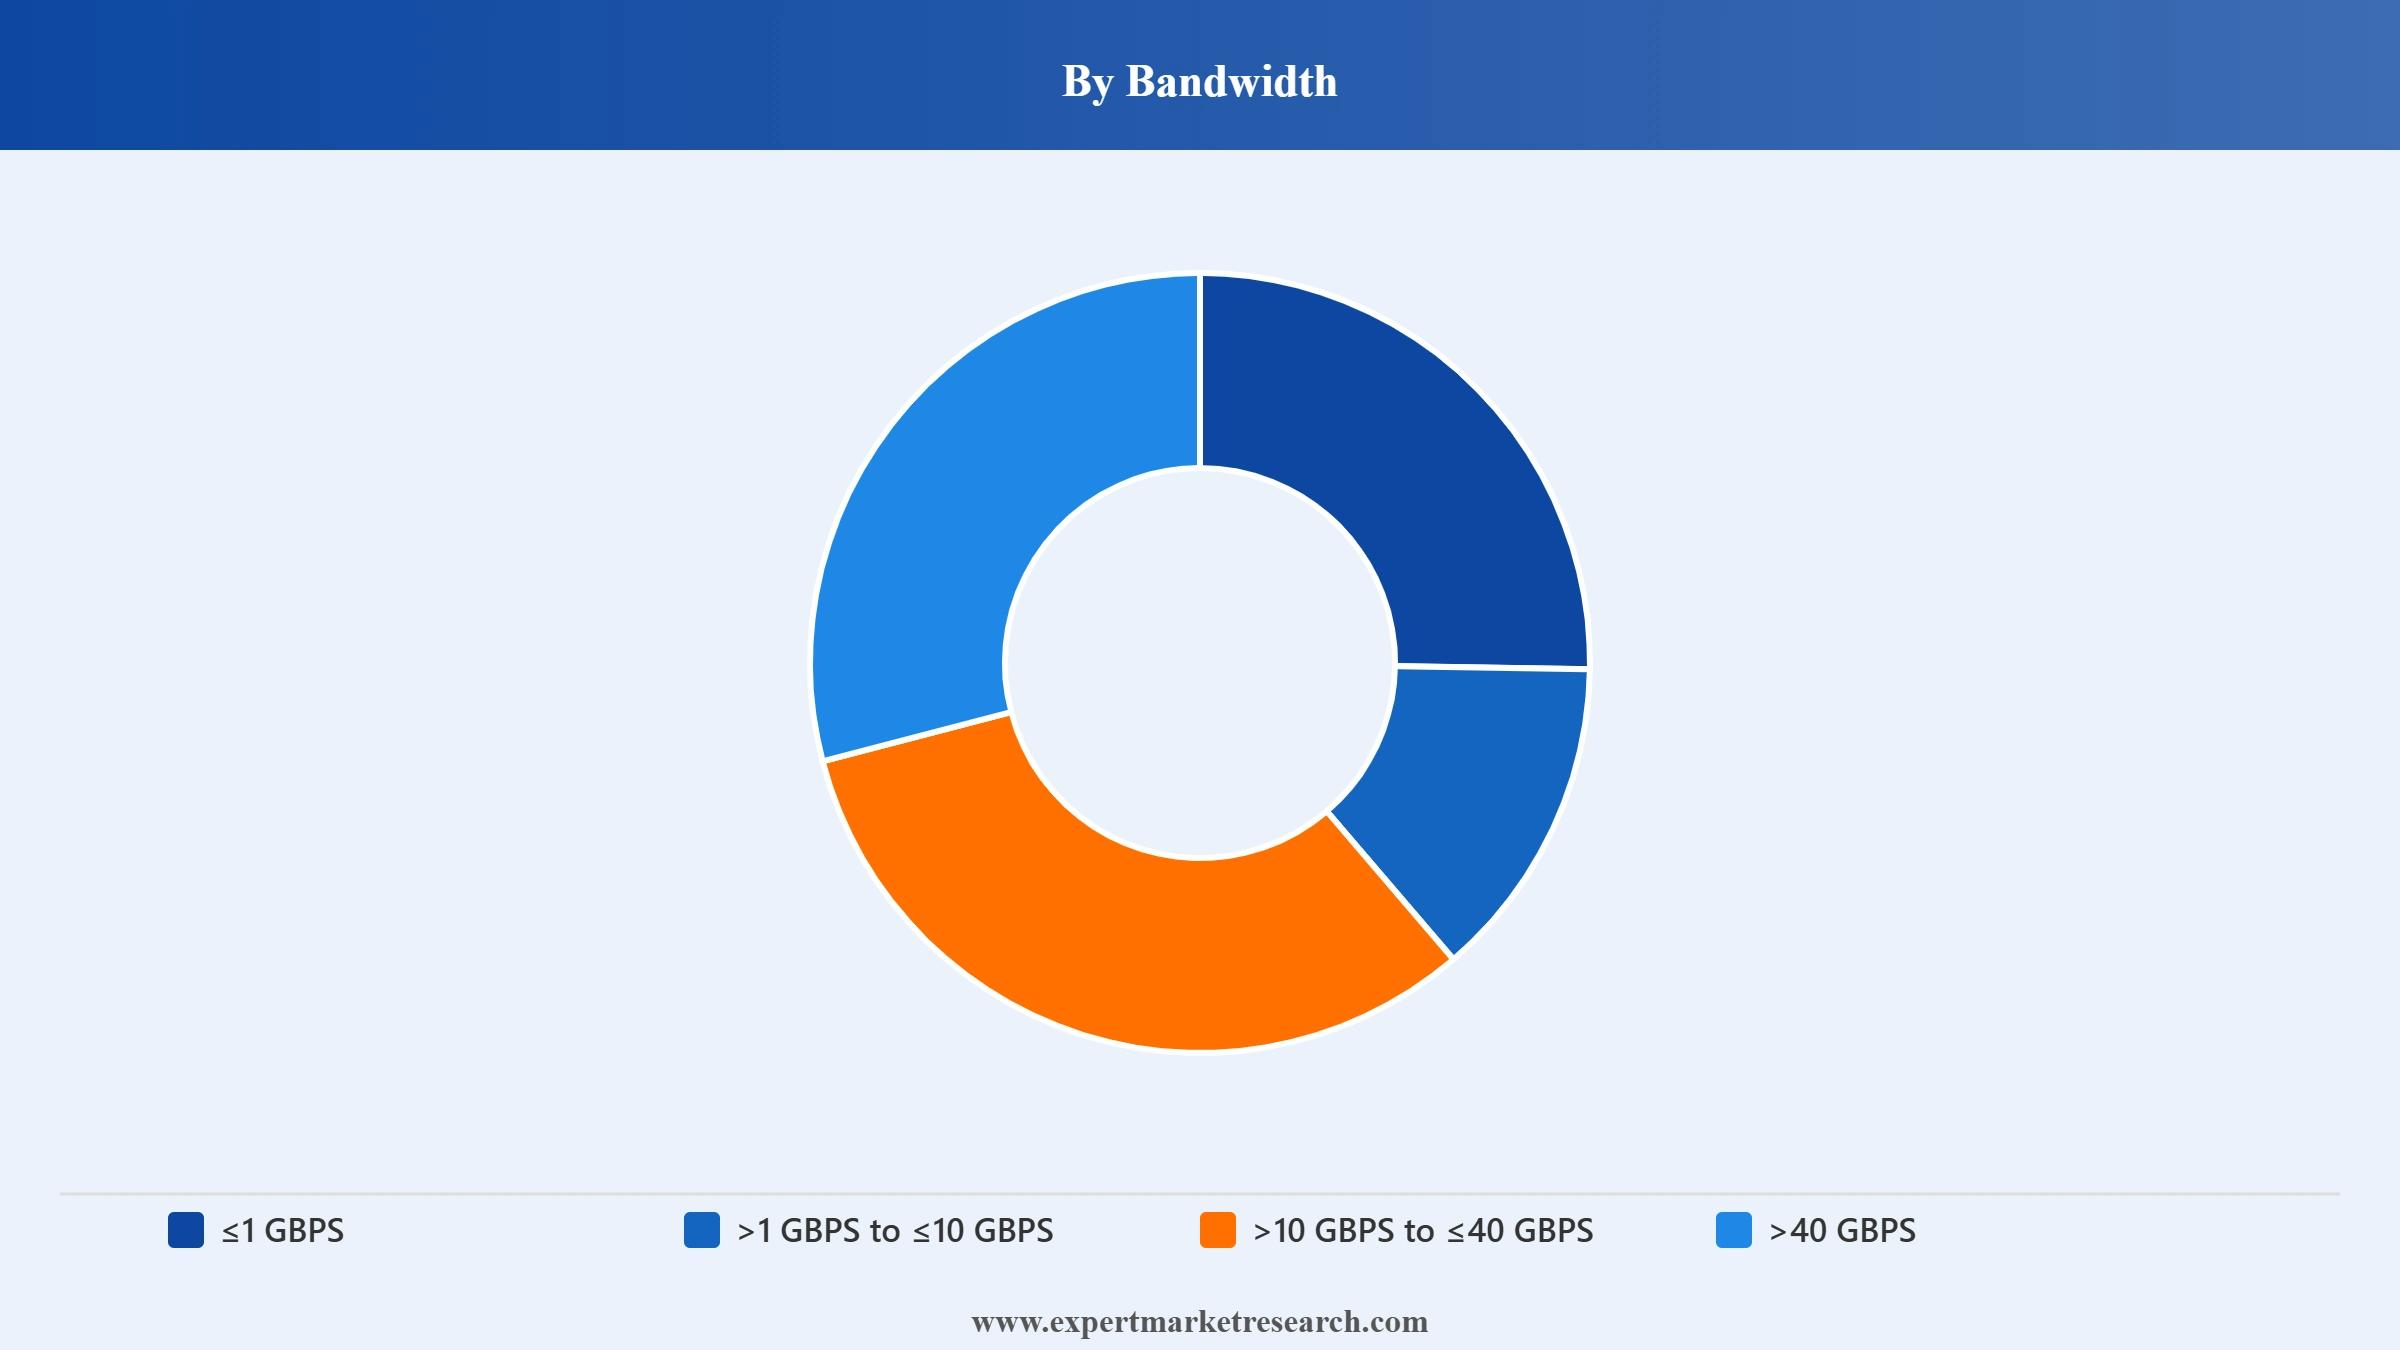
Market Breakup by Bandwidth
Key Insight: ≤1 GBPS covers legacy and management-plane access ports, where Cisco reported in May 2026 that campus networking orders grew more than 25% year on year; >1 GBPS to ≤10 GBPS is the leading tier, as D-Link showed in October 2025 when it launched 2.5G switches to fill the gap between standard 1 GbE and costly 10 GbE; >10 GBPS to ≤40 GBPS is the mid-range server and aggregation tier that enterprises are migrating upward from as workloads grow; and >40 GBPS is the fastest-growing tier, supported by Huawei's April 2026 launch of a 51.2T liquid-cooled switch built on 400GE ports.
Market Breakup by End Use
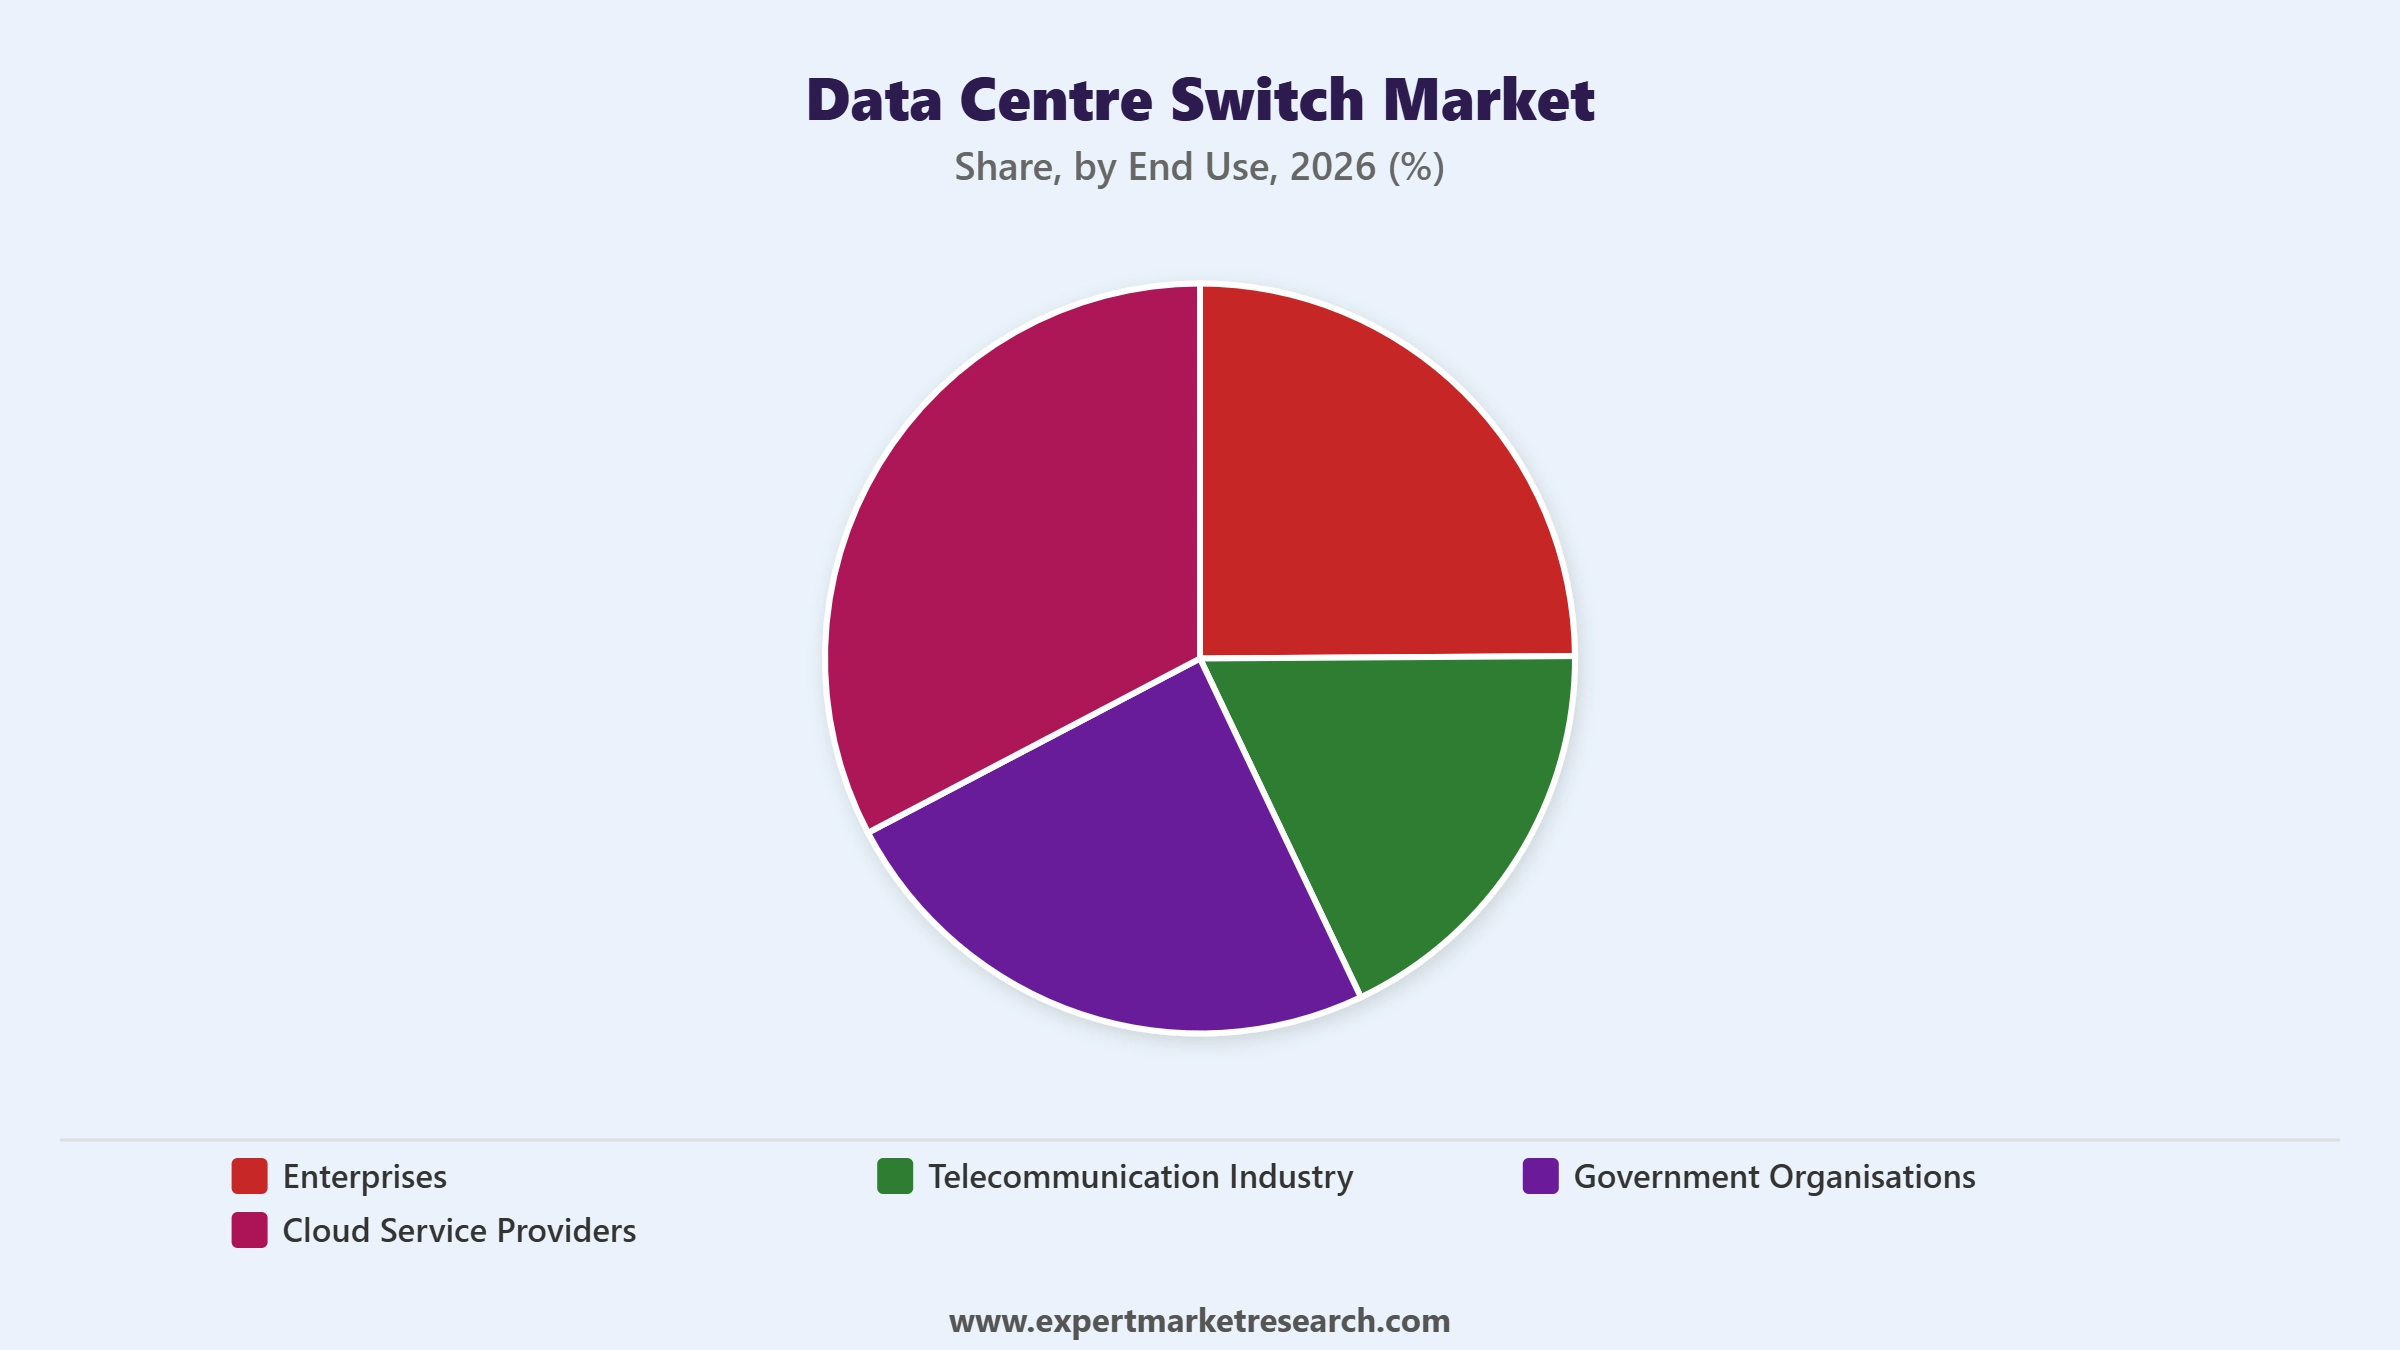
Key Insight: Cloud Service Providers are the leading end use, with Alphabet raising its 2026 capital expenditure guidance to USD 195 billion to USD 205 billion in July 2026; Government Organizations are the fastest-growing end use as sovereign infrastructure gains priority, shown by Cisco's August 2026 launch of Sovereign Critical Infrastructure in Canada for air-gapped, on-premises deployment; Enterprises are adding capacity, with Cisco reporting in May 2026 that enterprise data centre switching orders rose more than 40%; and the Telecommunication Industry is investing in AI computing networks, with ZTE Corporation showing SuperPod racks of 128 GPUs for operators at MWC Shanghai in June 2026.
Market Breakup by Region
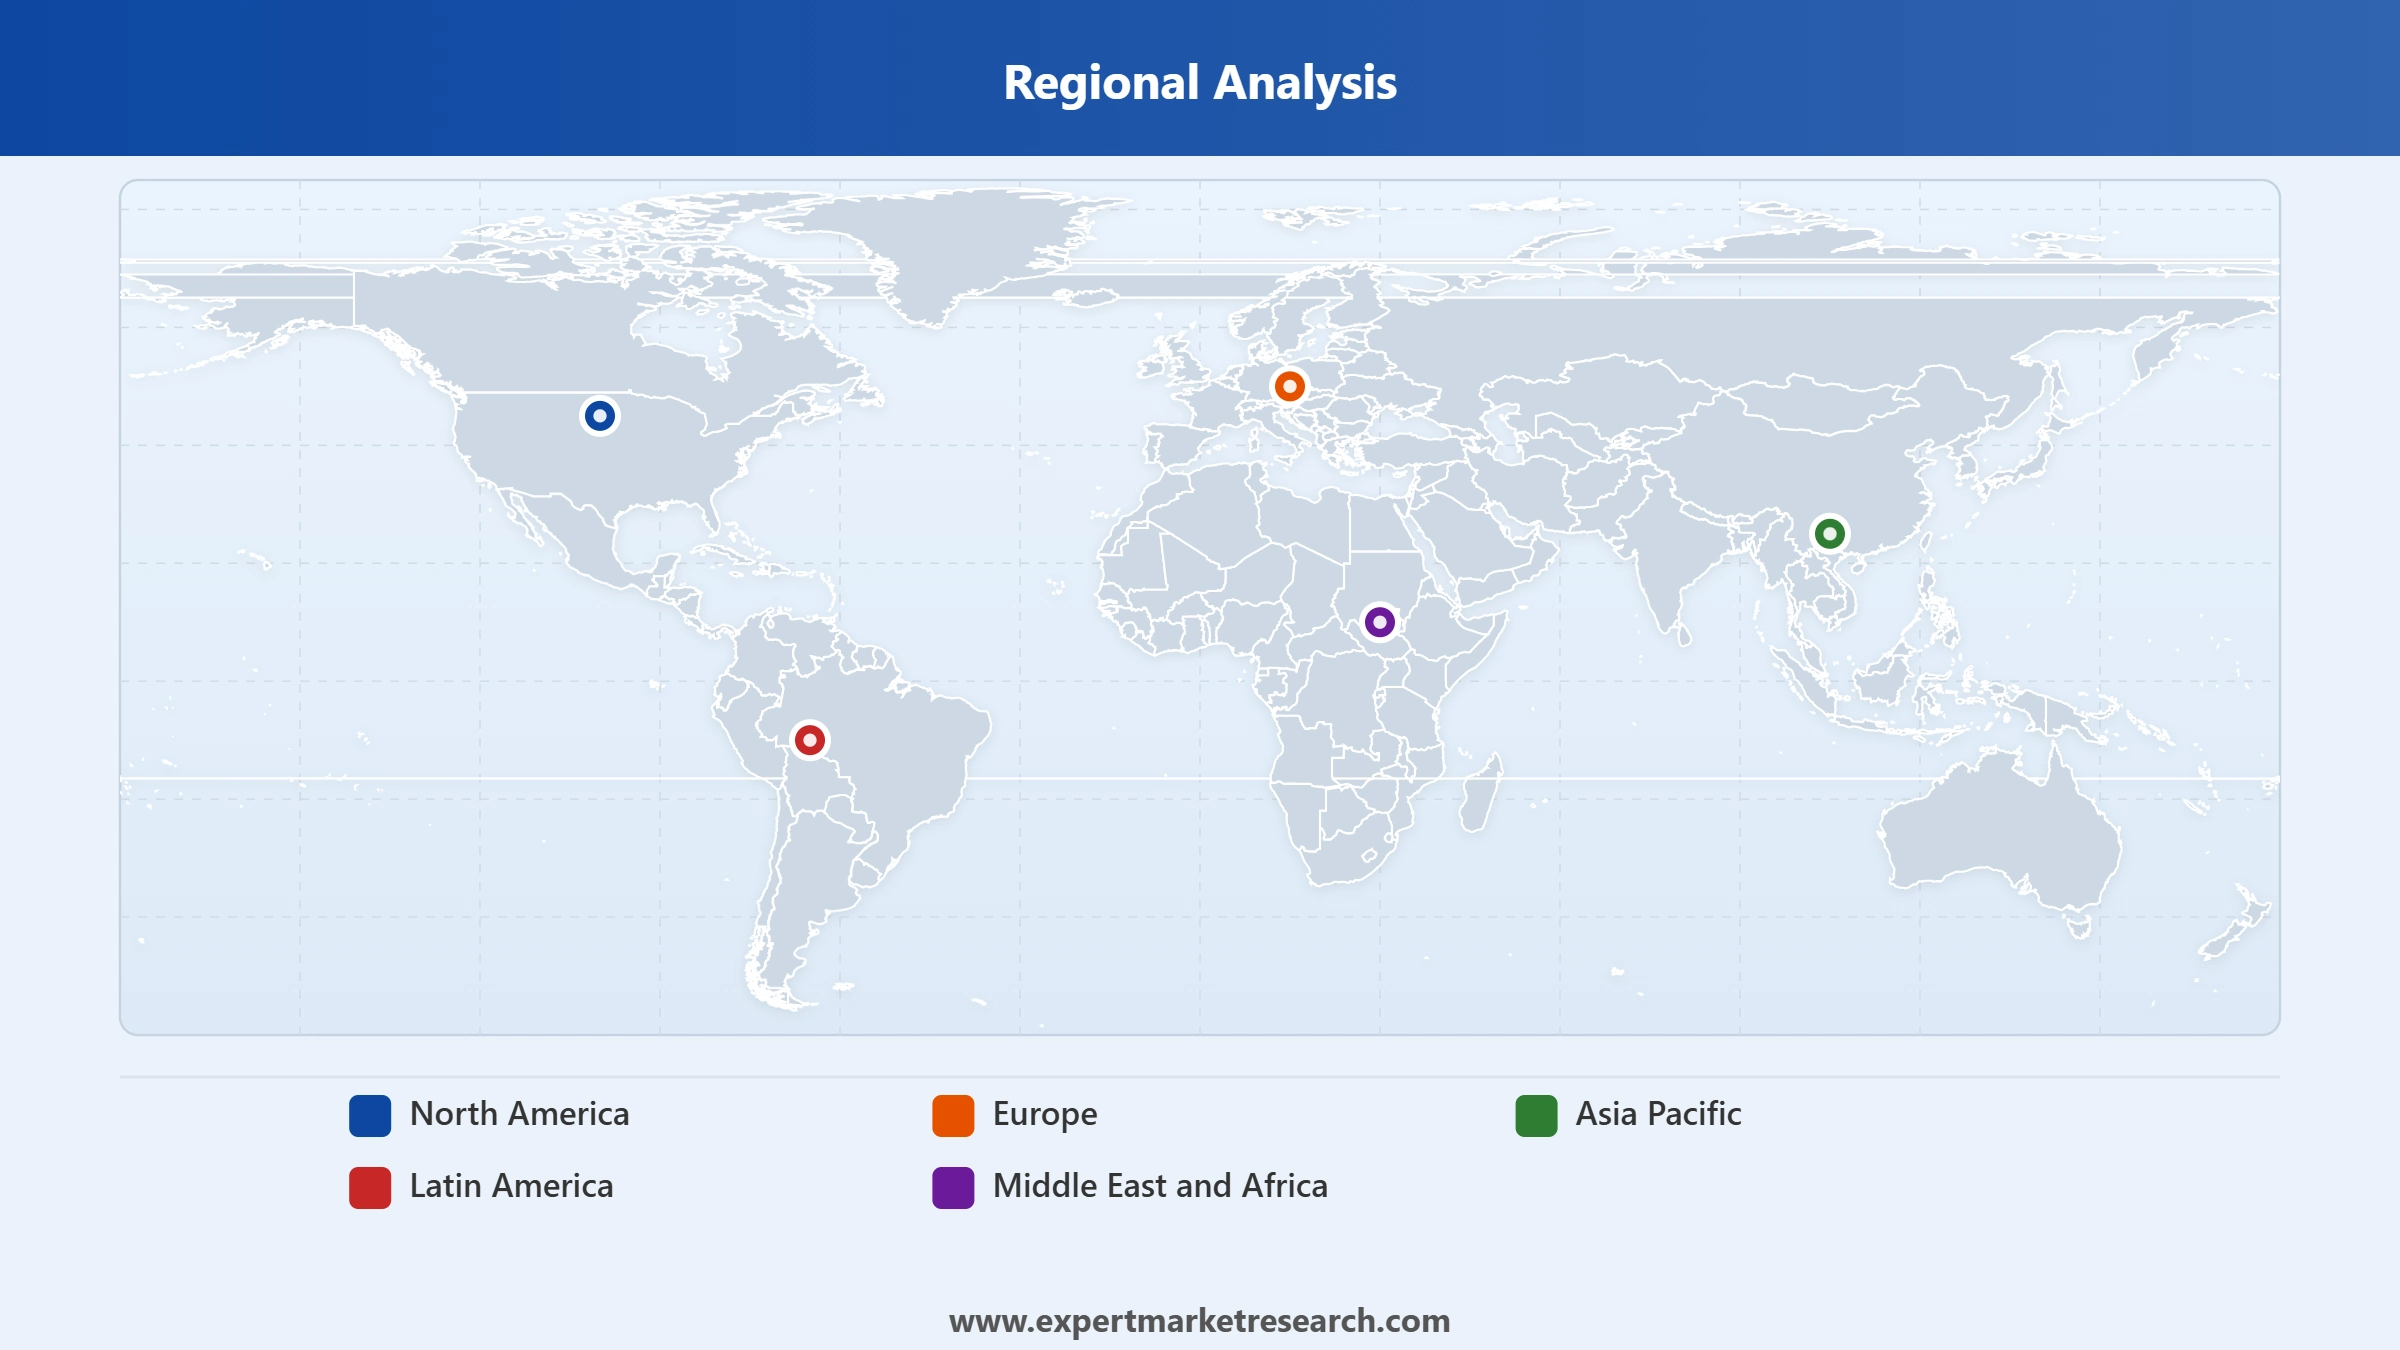
Key Insight: North America is the leading regional market, anchored by Alphabet's July 2026 capital expenditure increase and Cisco's August 2026 report of USD 9.3 billion in fiscal 2026 AI infrastructure orders; Europe is investing in sovereign AI capacity, with EuroHPC launching a call in July 2026 for up to seven AI Gigafactories; Asia Pacific is the fastest-growing region, with India expecting 220 MW of new colocation capacity in 2026; Latin America is gaining from Brazil's September 2026 Senate approval of the Redata tax regime for data centres; and the Middle East and Africa is building large campuses, including the Stargate UAE project that G42 said in October 2025 would deliver its first 200 MW in 2026.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By Type, Access Switches lead the market while Core Switches grow fastest because AI clusters need higher-capacity spine layers with more ports per box
Access Switches lead because every server rack, campus floor, and edge site needs port density at the point where devices connect. Extreme Networks said in August 2026 that Platform ONE adoption passed 30% of subscription bookings in its first year, and that product revenue grew 14.9% in fiscal 2026, showing that edge and campus switching remains a dependable volume base even as spending shifts toward AI fabrics.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Core Switches grow fastest as operators concentrate bandwidth in fewer, larger boxes. Cisco announced its 102.4 Tbps Silicon One G300 in February 2026 for new N9000 and 8000 systems, and Arista Networks introduced a universal AI spine on its 7800 platform in May 2026. Distribution Switches sit between these layers and benefit from the same upgrade cycle, as HPE's QFX and EX platforms in the Oracle agreement show.
By Technology, Ethernet leads the market while Infiniband holds a specialist position in GPU clusters because open Ethernet ecosystems are scaling faster than closed fabrics
Ethernet leads because it combines multi-vendor supply with a clear speed roadmap. Cisco said in August 2026 that about 60% of its USD 4 billion in quarterly AI infrastructure orders were for Silicon One routing and switching systems, and the Ultra Ethernet Consortium's v1.0 specification of June 2025 targets AI and high-performance computing traffic, which widens the range of workloads that Ethernet can serve.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Infiniband remains the specialist fabric for tightly coupled GPU training, where NVIDIA, the owner of Mellanox Technologies, rates its Quantum-X800 switches at 800 Gb/s of throughput. Fibre Channel stays embedded in storage networks, with Broadcom introducing 128G Gen 8 platforms in November 2025. The Introduction category frames both, as buyers weigh lossless performance against open-standard cost, ecosystem breadth, and supply choice across training and storage networks.
By Bandwidth, >1 GBPS to ≤10 GBPS leads the market while >40 GBPS grows fastest because 400G and 800G ports are being specified for every new AI build
>1 GBPS to ≤10 GBPS leads because server access, storage, and enterprise aggregation still run largely on 10G-class ports. D-Link introduced 2.5G switches in October 2025 to bridge the gap between 1 GbE and 10 GbE, while Cisco reported in May 2026 that campus orders grew more than 25%, which keeps ≤1 GBPS ports in steady demand and supports the >10 GBPS to ≤40 GBPS tier as an upgrade path.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
>40 GBPS grows fastest as AI training clusters adopt 400G and 800G links. Huawei launched 800GE-dense CloudEngine switches in April 2026, and Arista Networks said in May 2026 that its XPO liquid-cooled pluggable optics can cut networking racks by up to 75%, a sign that higher speeds are driving changes in optics, cooling, and rack design as well as the switches themselves.
By End Use, Cloud Service Providers lead the market while Government Organizations grow fastest because sovereign and national AI programmes need locally controlled infrastructure
Cloud Service Providers lead because hyperscale operators buy switches in the largest volumes. Alphabet raised its 2026 capital expenditure guidance in July 2026, and Dell Technologies reported in September 2026 an AI backlog of USD 95 billion, evidence that server and network orders are being placed years ahead, and that Enterprises and the Telecommunication Industry follow with smaller but growing deployments.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Government Organizations grow fastest as public bodies fund sovereign capacity. Cisco launched its Sovereign Critical Infrastructure portfolio in Canada in August 2026 for air-gapped deployments, and EuroHPC opened a call in July 2026 for up to seven AI Gigafactories backed by more than EUR 20 billion in expected private investment, creating demand for switches that meet national certification and control requirements.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America commands the largest regional share of the global data centre switch market in 2025, shaped by hyperscale cloud capital spending and early adoption of 400G and 800G switching in AI clusters
This is supported by Alphabet's July 2026 increase in its 2026 capital expenditure guidance to USD 195 billion to USD 205 billion, and by Cisco's August 2026 report of USD 9.3 billion in fiscal 2026 AI infrastructure orders, much of it Silicon One switching, while Cisco's August 2026 Canadian sovereign portfolio extends demand to public-sector buyers across the region, and HPE's September 2026 Oracle agreement adds multi-year switching volume for AI data centres.
Asia Pacific is the fastest-growing regional market, with India expecting to add 220 MW of colocation capacity in 2026 and ZTE Corporation presenting SuperPod AI computing racks at MWC Shanghai in June 2026. Europe is advancing through EuroHPC's July 2026 AI Gigafactories call, Latin America through Brazil's September 2026 Redata approval, and the Middle East and Africa through Stargate UAE, where first capacity was expected in 2026, as well as Huawei's April 2026 summit in Cairo that promoted 800GE data centre switching to regional operators.
The global data centre switch market is moderately concentrated at the top, with a handful of large networking vendors competing alongside server-led suppliers, security specialists, and white-box manufacturers that sell open hardware to hyperscale buyers.
Competitive dynamics are increasingly shaped by in-house switching silicon, 800G and 1.6T product cycles, liquid-cooled system designs, and alliances with cloud and AI infrastructure operators, as vendors seek to secure design wins early in each build cycle.
Founded in 1984 and headquartered in San Jose, California, Cisco Systems Inc. sells switching, routing, security, and optics products for data centres, campuses, and service providers. In February 2026 it announced the 102.4 Tbps Silicon One G300, and in August 2026 it reported USD 9.3 billion in AI infrastructure orders for fiscal 2026.
Founded in 1987 and headquartered in Shenzhen, China, Huawei Investment & Holding Co., Ltd makes telecom, enterprise network, and computing equipment, including its CloudEngine data centre switch family. In April 2026 it launched the Xinghe AI Fabric 2.0 solution and more than ten new CloudEngine switches at its Network Summit in Cairo.
Formed in 2015 as an enterprise technology company, Hewlett Packard Enterprise Co offers servers, storage, and networking, including HPE Juniper Networking switching and routing for AI data centres. In September 2026 it announced a multi-year expansion with Oracle to deploy QFX and EX switches and PTX and MX routers across Oracle's AI data centres.
Founded in 2004 and headquartered in Santa Clara, California, Arista Networks Inc provides client-to-cloud networking for AI, data centre, campus, and routing environments. In May 2026 it reported first-quarter revenue of USD 2.709 billion, up 35.1%, and in June 2026 it announced 1.6T switches delivering 100 Tbps.
Other key players in the data centre switch market include Juniper Networks Inc., Dell Inc., ODM white-box makers, Mellanox Technologies, Ltd., Extreme Networks, Inc., Fortinet, ZTE Corporation, and D-Link, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
For a detailed assessment of opportunities across the data centre switch market's type, technology, bandwidth, end-use, and regional segments through 2026 and beyond, connect with Expert Market Research for a customized consultation.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The global data centre switch market attained a value of USD 19.65 Billion in 2025.
The data centre switch market is projected to grow at a CAGR of 6.00% from 2026 to 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 35.19 Billion by 2035.
Key strategies include launching 800G and 1.6T platforms, developing in-house switching silicon, offering liquid-cooled and rack-scale designs, forming alliances with cloud and AI infrastructure operators, and bundling software-driven network operations with hardware.
The key data centre switch market trends include rising demand for high speed data transfers, need for simplified data centre management, advancements in technology, and growing demand for cloud services.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The primary types of data centre switches in the market are core switches, access switches, and distribution switches.
The significant technologies in the market for data centre switches are introduction, ethernet, fibre channel, and InfiniBand.
The different bandwidths of data centre switches in the market are ≤1 GBPS, >1 GBPS to ≤10 GBPS, >10 GBPS to ≤40 GBPS and >40 GBPS.
The various end uses of data centre switches in the market are enterprises, telecommunication industry, government organisations, and cloud service providers.
Key players in the data centre switch market include Cisco Systems Inc., Huawei Investment & Holding Co., Ltd, Hewlett Packard Enterprise Co, Arista Networks Inc, Juniper Networks Inc., Dell Inc., ODM white-box makers, Mellanox Technologies, Ltd., Extreme Networks, Inc., Fortinet, ZTE Corporation, and D-Link, among others.
Key challenges include supply constraints for advanced switching silicon and optics, rising power and cooling demands as port speeds climb, interoperability between Ethernet and Infiniband fabrics in AI clusters, and the cost of migrating legacy 10G and 40G estates to 400G and 800G.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Technology |
|
| Breakup by Bandwidth |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




