

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
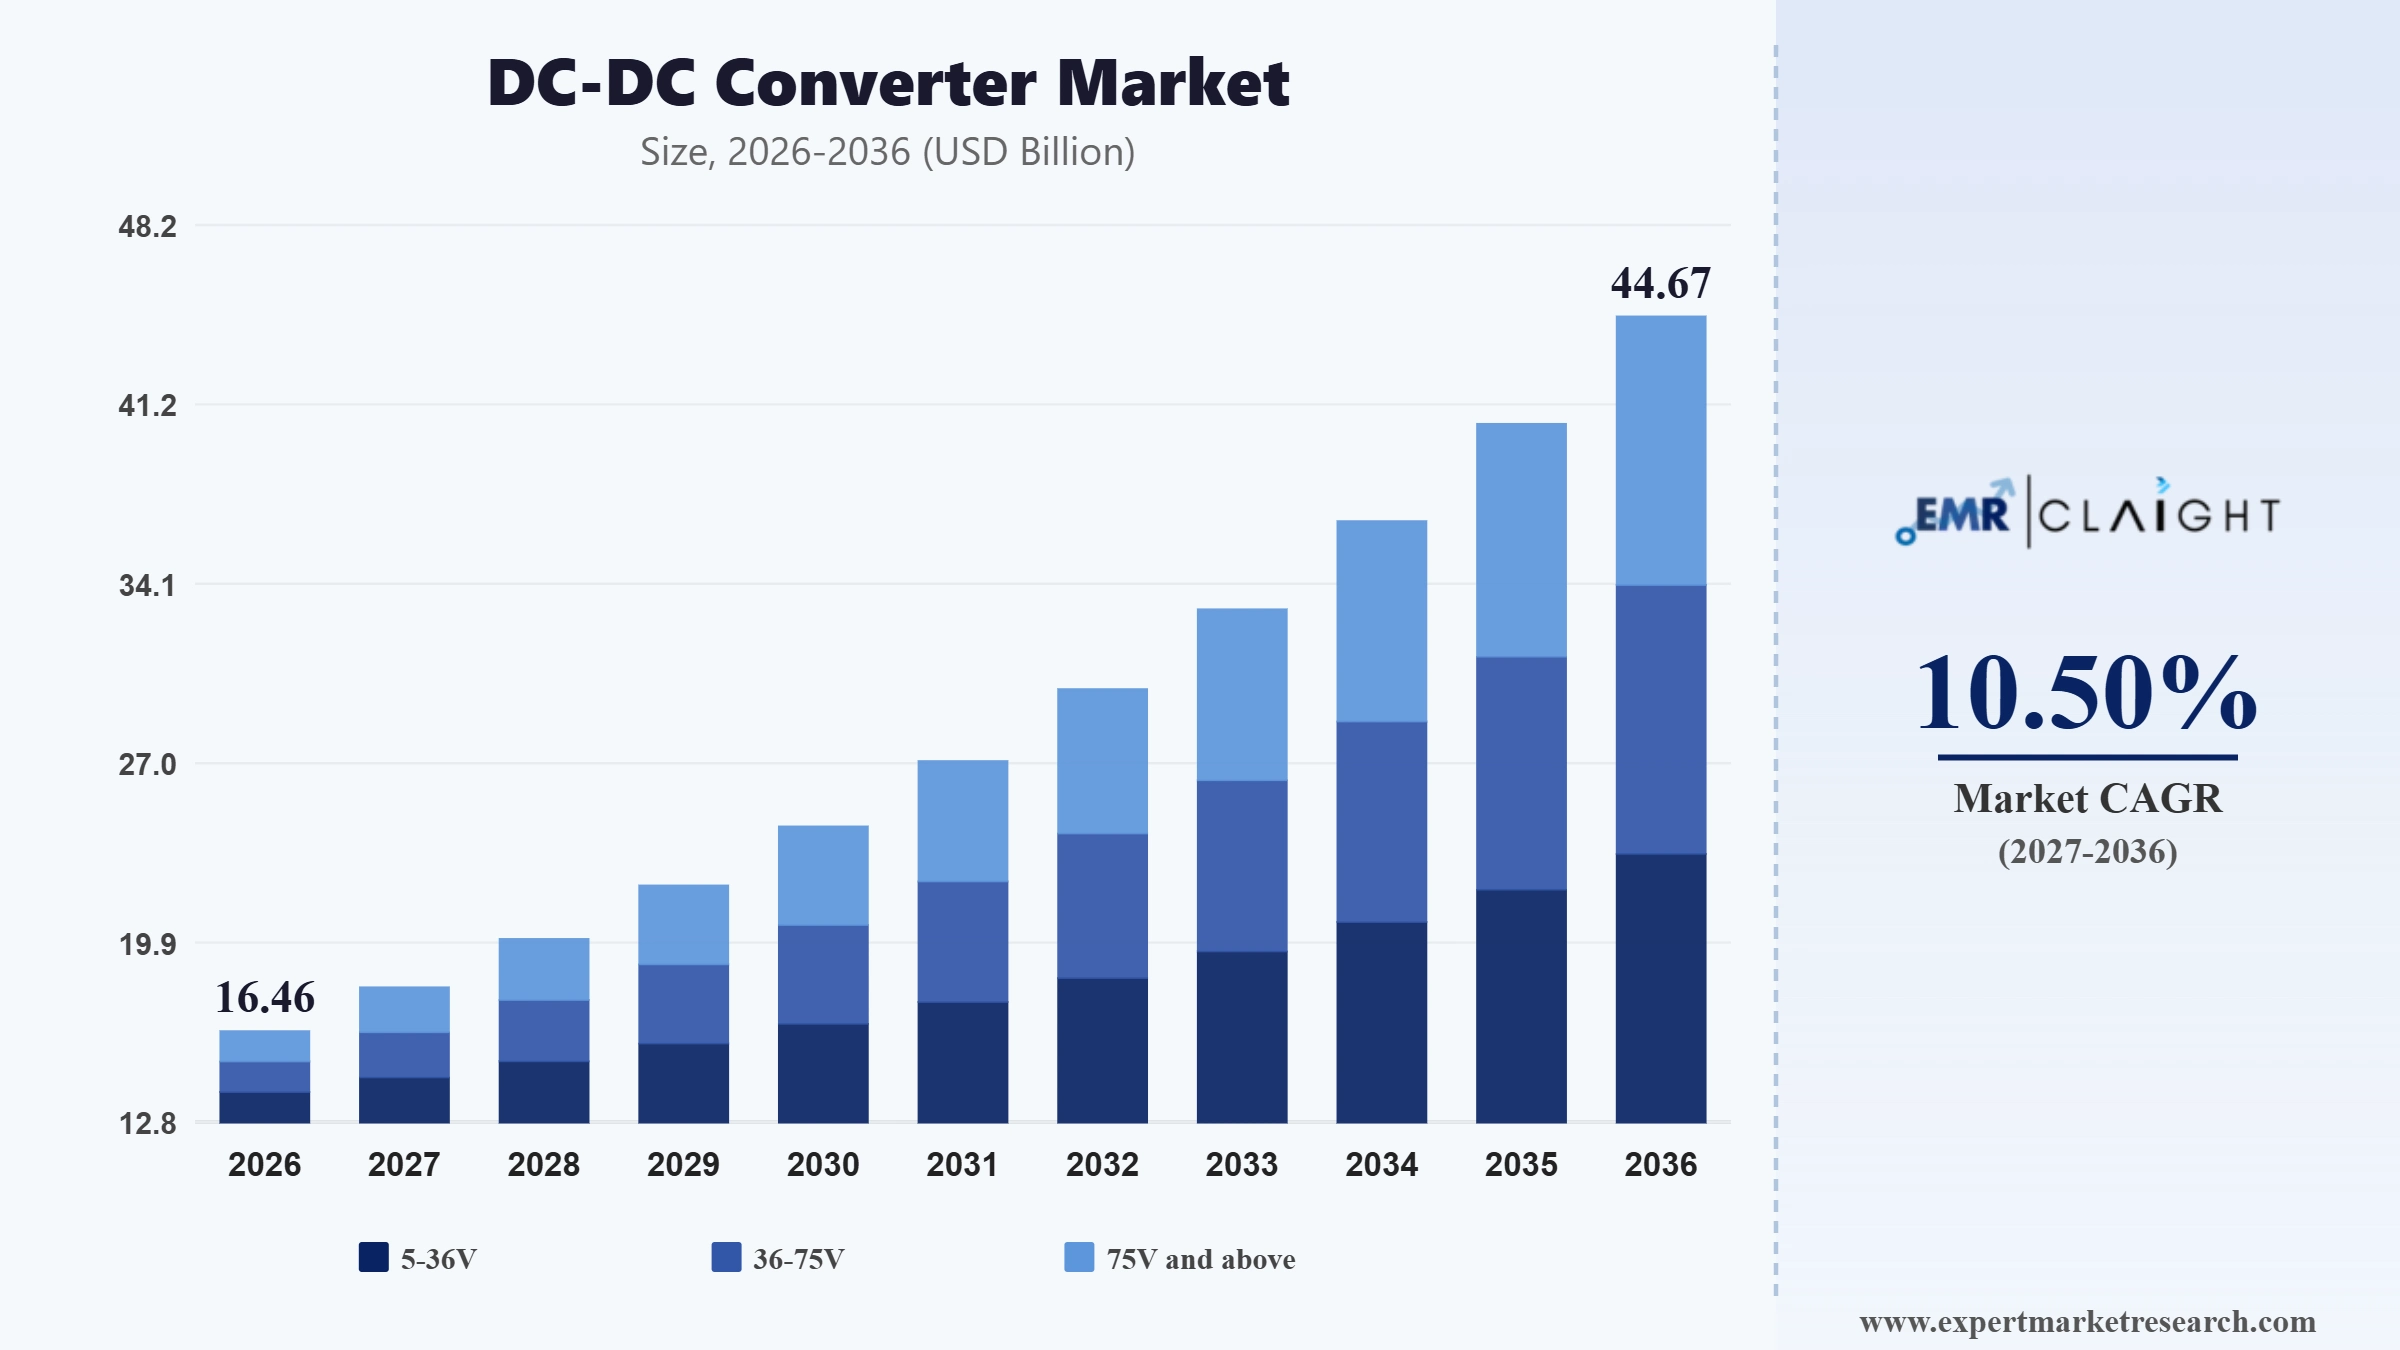
The global DC-DC converter market attained a value of USD 14.90 Billion in 2025 and is projected to grow at a CAGR of 10.50% through 2035. The market is further expected to reach USD 40.44 Billion by 2035. Demand from smartphones, servers, electric vehicles, railways, and medical equipment, along with the shift to higher voltage power architectures, is supporting growth in the market.
Demand for DC-DC converters rests on nearly every electronic product that runs from a battery or a shared power bus. Smartphones, servers, vehicles, trains, hospital equipment, and factory machines all need stable voltages at different levels, and converters supply them inside compact boards and modules. Growth in artificial intelligence computing, electrification, and connected devices keeps raising both the number of converters per system and the performance expected from each one. Upgrade cycles keep DC-DC converter market orders recurring across industries.
Power semiconductor results show how strong demand has become. In July 2026, Monolithic Power Systems reported second quarter revenue of USD 980.6 million, with enterprise data revenue of USD 380.6 million, up 164.3%, and guided third quarter revenue to USD 1,140 million to USD 1,160 million. Data center power is now the main growth driver for converter chips and modules. Suppliers to the DC-DC converter market are expanding capacity as customers place larger orders with longer lead times.
Leading suppliers are directing investment toward wide bandgap devices, vertical power delivery, and higher voltage architectures rather than single products. Acquisitions, new fabs, and partnerships with computing and vehicle makers are now central to competitive positioning in the market, as firms seek higher efficiency, smaller footprints, and secure supply for customers building artificial intelligence servers, electric vehicles, and rail systems. Customers qualify parts slowly, so suppliers with proven reliability records keep winning repeat business across several product generations.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| Global DC-DC Converter Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 14.90 |
| Market Size 2035 | USD Billion | 40.44 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 10.50% |
| CAGR 2026-2035 - Market by Region | Asia Pacific | 11.3% |
| CAGR 2026-2035 - Market by Country | India | 11.8% |
| CAGR 2026-2035 - Market by Country | Canada | 10.9% |
| CAGR 2026-2035 - Market by Output Voltage | 15V and above | 12.2% |
| CAGR 2026-2035 - Market by Mounting Style | Surface Mount | 11.4% |
| Market Share by Country 2025 | Japan | 4.1% |
XP Power launched the QAM60T quarter-brick and HBM150C half-brick medical converters, rated at 60 W and 150 W with efficiency up to 93.5% and 91.5%, and 5 kVAC isolation with 2 x MOPP protection. Companies across the DC-DC converter market can leverage this trend by certifying converters for patient connected equipment, which opens hospital demand and shortens approval time for device makers.
OmniOn Power launched the QODN Osprey bus converters, converting 40 to 60 volts to 12 volts at 1,300 to 2,600 W with full load efficiency of 97.9% to 98.1%. Companies across the DC-DC converter market can leverage this trend by offering compact, high efficiency bus converters, which cut heat in dense racks and help server builders add more computing power per cabinet.
Aimtec launched 2 x 1 inch, 80 W regulated converters, with 9 to 36 volt and 18-to-75-volt inputs, outputs from 3.3 to 24 volts, and efficiency up to 91%. Companies across the DC-DC converter market can leverage this trend by standardizing footprints across inputs and outputs, which reduces design effort and lets customers switch between industrial and transport projects.
TDK-Lambda launched the DDSM programmable DIN rail converters, offering 120 W and 240 W with 12-to-48-volt inputs, adjustable 5-to-55-volt outputs, and efficiency of up to 93.0%. Companies can leverage this trend by adding programmable outputs to rail units, which lets panel builders use one product for many loads and reduces inventory.
Electrical groups across the DC-DC converter market are widening product ranges for next generation data centers. Solid-state components can shrink power rooms. In September 2026, ABB introduced its Infinitus 800 VDC portfolio, including a solid-state transformer, solid-state circuit breakers, and a static medium voltage UPS, with rack power of about 200 kW today and a path toward 1 MW. Components are expected to enter production within 12 months. Operators gain simpler power paths. Competitors may soon unveil similar portfolios to remain relevant in this field.
Equipment makers across the DC-DC converter market are preparing complete power chains for higher voltage racks. Fewer conversion stages cut losses and copper use. In March 2026, Delta Electronics announced an 800 VDC portfolio at a computing conference, including a 660 kW in-row power rack with six 110 kW shelves, a 1RU 90 kW DC-DC shelf, and a solid-state transformer rated at up to 98.5% efficiency. Operators gain a path to denser racks with lower energy loss. Competing suppliers are preparing similar portfolios for customers.
Large fabs give power chip suppliers more room to serve converter makers. Local production also reduces supply risk for European customers. In July 2026, Infineon opened its EUR 5 billion Dresden Smart Power Fab, doubling capacity at the site and creating 1,000 new jobs. The plant supports power chips used in converters. Buyers gain steadier supply for automotive and data center projects. Shorter supply chains help carmakers and server builders plan launches. Local jobs also strengthen the regional electronics ecosystem.
Chip makers across the DC-DC converter market are buying specialists that place power conversion close to processors. Shorter paths reduce losses in dense systems. In August 2026, Navitas agreed to acquire Claros, a vertical power delivery and integrated voltage regulator company, for up to about USD 232.8 million, with closing expected before the end of 2026. Navitas says the deal adds more than USD 3.5 billion of serviceable market. Customers gain a broader power portfolio from one supplier. Rivals may respond with similar deals soon.
Specialist module makers across the DC-DC converter market are adding capacity to meet demand from computing customers. Long lead times for equipment make early planning important. In July 2026, Vicor reported second quarter revenue of USD 143.4 million, net income of USD 49.8 million, and backlog of USD 380 million, up 145% from a year earlier, and said it was taking steps toward a second chip fab for next generation vertical power delivery parts. Investors gain visibility into future output. Rivals may plan new fabs.
The Expert Market Research's report titled "Global DC-DC Converter Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Input Voltage
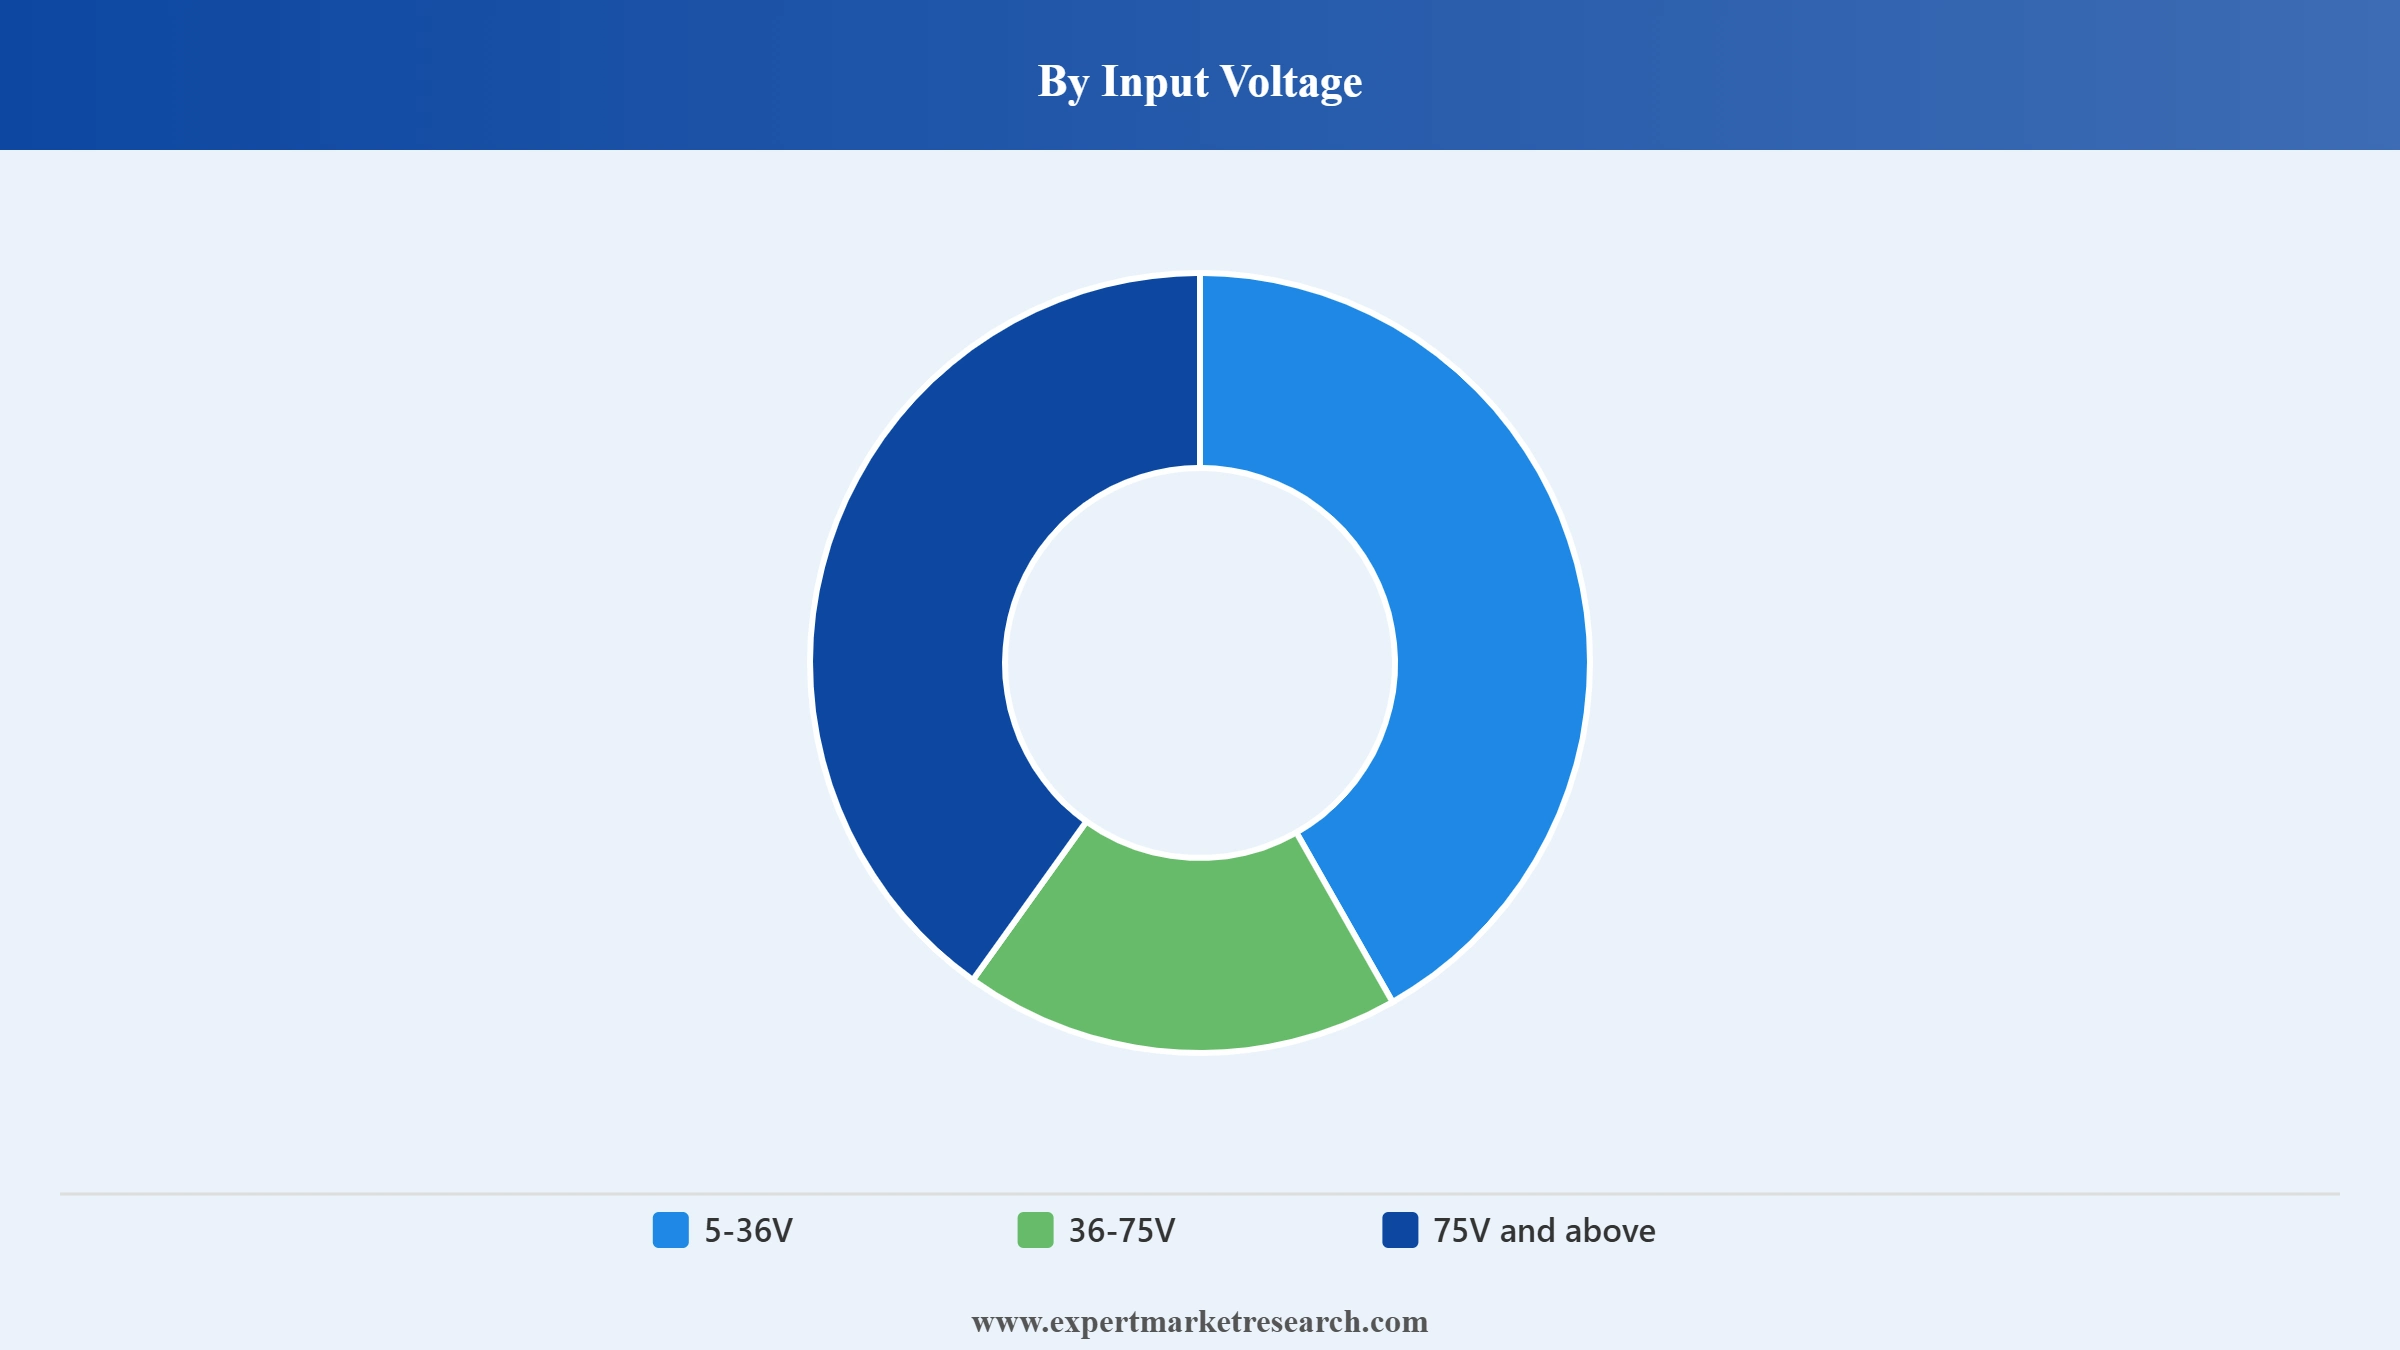
Key Insight: 5-36V holds the largest share of the input voltage segment, as batteries, vehicles, and consumer devices mostly run on low voltage rails. The 75V and above range is expected to expand quickly as 800-volt architectures, electric vehicles, and high voltage data center systems spread. The 36-75V range serves telecom, rail, and industrial equipment that needs wider input tolerance and isolation. Designers choose among these ranges based on bus voltage, safety rules, and efficiency targets. In March 2026, STMicroelectronics launched the DCP3603 buck converter with 3 A output and a 3 mm by 1.6 mm footprint.
Market Breakup by Output Voltage
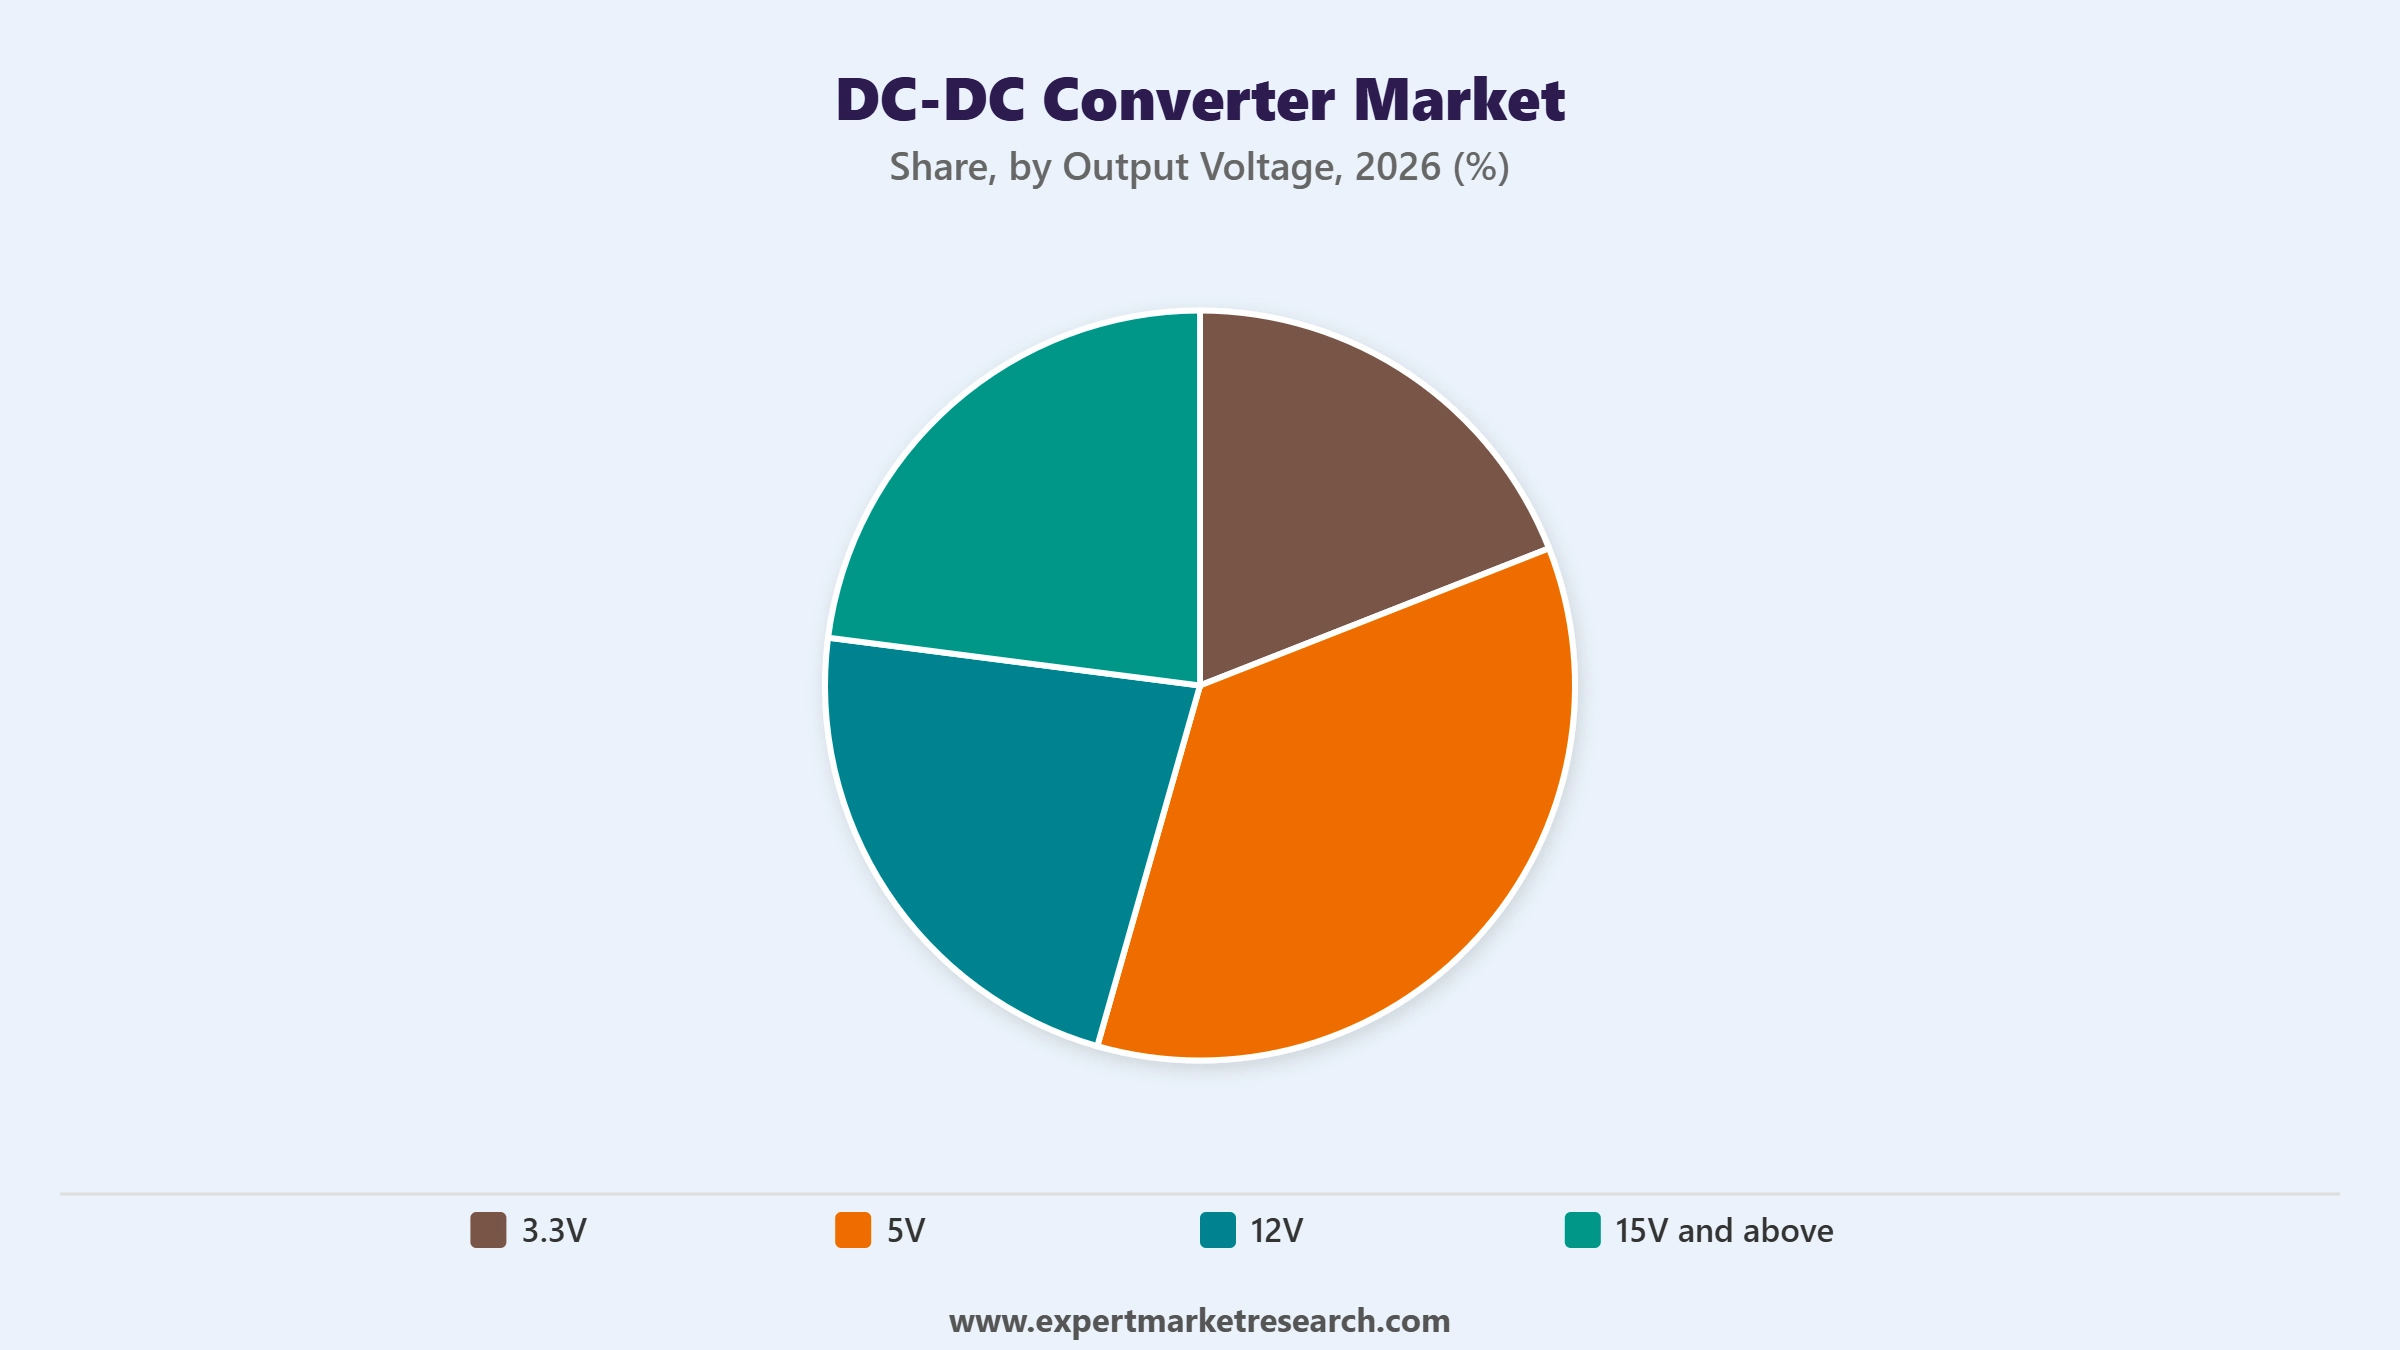
Key Insight: 5V holds the largest share of the output voltage segment, as consumer electronics and Internet of Things devices rely on this rail for logic, sensors, and interfaces. The 15V and above range is the fastest growing output, as industrial, vehicle, and space systems need higher rails for motors, actuators, and sensors. The 3.3V output supports microcontrollers, memory, and communication chips in compact devices, while 12V serves computing, telecom, and industrial loads such as fans, storage drives, and network equipment. Designers often combine several of these rails inside one product.
Market Breakup by Mounting Style
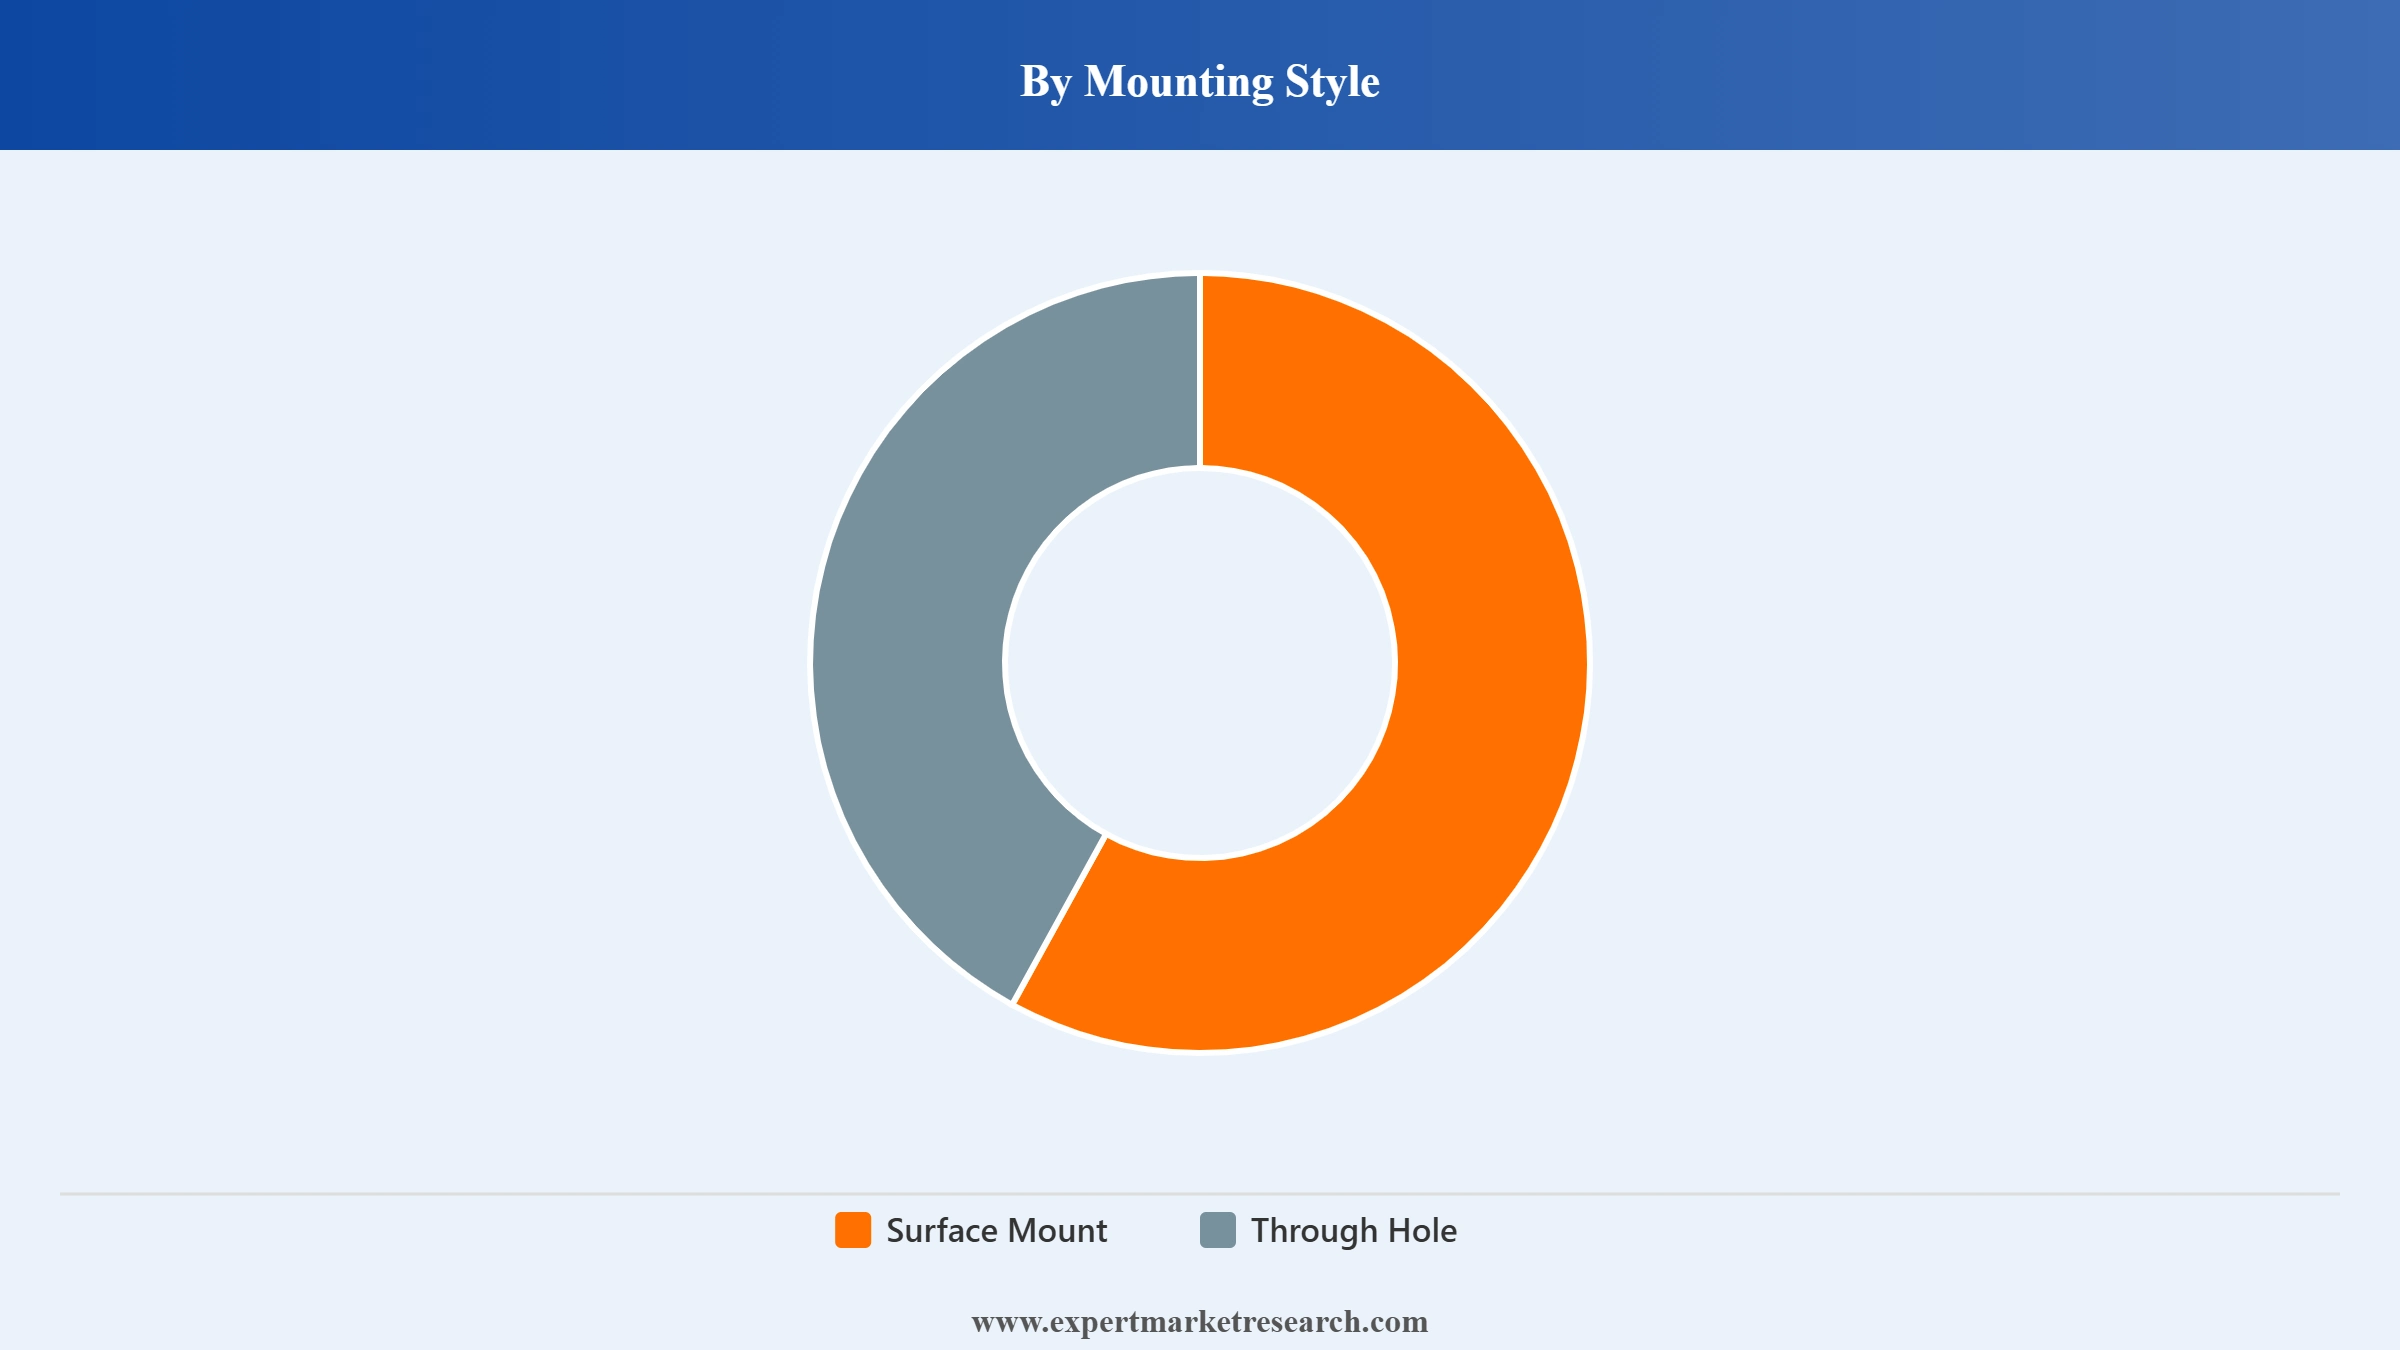
Key Insight: Surface mount holds the largest share of the mounting style segment and is growing, as compact boards and automated assembly favor small packages. These parts suit smartphones, wearables, servers, and drones, where board area and assembly cost matter most. Through hole remains relevant in industrial, rail, and aerospace equipment that needs strong mechanical bonds under vibration, and it suits products that technicians repair by hand during field maintenance. Many designers in the DC-DC converter market now pair surface mount control stages with through hole power parts when a product needs both density and ruggedness.
Market Breakup by Application
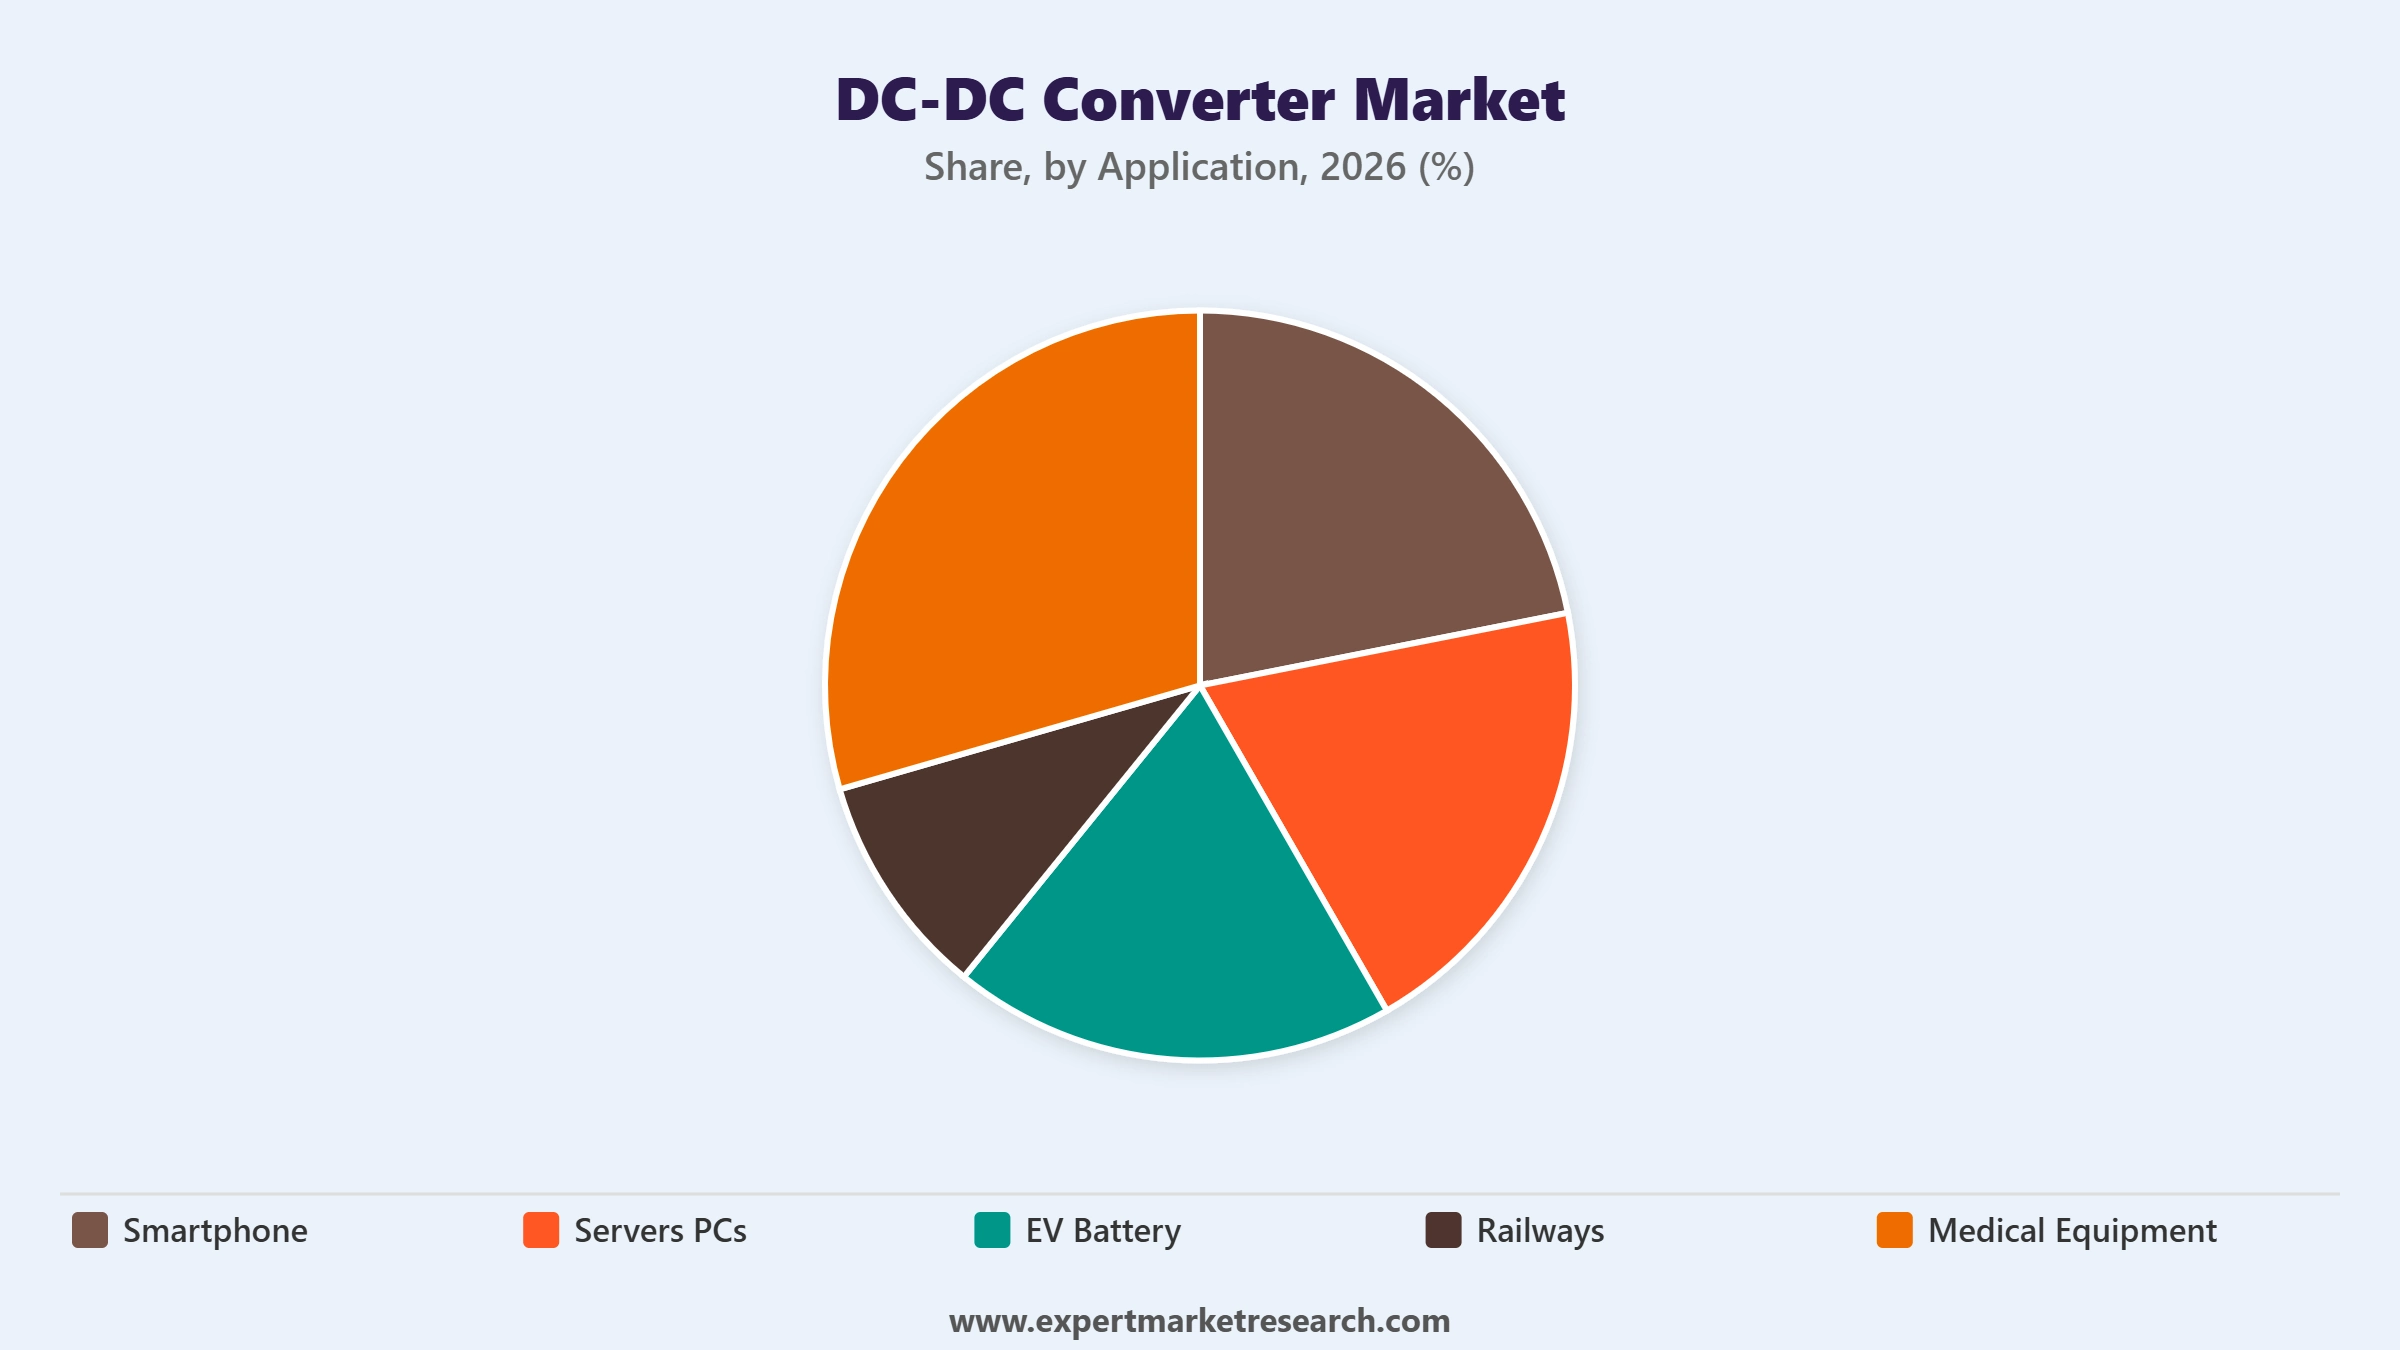
Key Insight: Smartphones hold the largest share of the application segment in the DC-DC converter market, as every handset needs several conversion stages for charging, displays, and processors. EV battery is the fastest growing application, as electric vehicles need converters between high voltage packs and low voltage systems. Servers and PCs add steady demand from data centers, workstations, and personal computers that need efficient power at many voltage levels. Railways require rugged, isolated converters with wide input ranges and long service life, and medical equipment needs certified, low noise supplies for patient safety. In October 2026, Toshiba introduced a 3,300 V silicon carbide module for railway traction.
Market Breakup by Region
Key Insight: North America holds the largest regional share, supported by data center investment, defense electronics, and a strong base of power semiconductor firms. Asia Pacific is the fastest growing region, as phone, vehicle, and electronics manufacturing concentrate there. Europe adds demand to the DC-DC converter market through industrial automation, rail, and automotive electronics. Latin America grows from a smaller base through consumer electronics assembly and industrial upgrades, while the Middle East and Africa gain from telecom, energy, and infrastructure projects that need dependable power conversion in demanding climates.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By input voltage, 5-36V dominates the DC-DC converter market owing to its use in batteries, vehicles, and consumer devices
5-36V converters hold the largest share of the input voltage segment, because batteries, vehicles, and portable devices mostly operate in this range. Standard approvals for industrial and medical equipment widen its reach. Designers value flexible slot sizes, which allow many output combinations from one platform. Buyers also benefit from shorter qualification, since approved platforms can be reused across product lines. Reliable supply matters, as long product lifecycles in industrial and medical equipment favor suppliers with stable catalogs and multiple factories.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
75V and above converters across the DC-DC converter market are expected to expand quickly within the input voltage segment, as 800-volt architectures and electric vehicle systems need higher input ranges. In July 2025, onsemi announced a collaboration with NVIDIA on 800 VDC power architectures covering solid-state transformers, power supplies, and distribution. Silicon carbide devices handle high voltage with lower losses. Partnerships between chip makers and computing leaders speed up reference designs, so customers can plan racks with confidence. Early designs lower future retrofit costs.
By output voltage, 5V dominates the DC-DC converter market owing to logic and interface rails in consumer electronics
5V outputs hold the largest share of the output voltage segment, because consumer electronics and Internet of Things devices use these rails for logic, sensors, and interfaces. Charging standards push more power through compact ports, and every port need conversion stages to produce stable low voltage rails inside the device. Efficiency matters greatly, since wasted energy becomes heat in small enclosures. Wearables, routers, and smart speakers also rely on tightly regulated low voltage supplies, which keeps volumes high all year.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Outputs of 15V and above are registering the fastest growth within the output voltage segment, as industrial, vehicle, and space systems need higher rails. In July 2025, Microchip Technology launched the SA15-28 radiation hardened DC-DC converter rated at 15 W, designed for a 28 V satellite bus with 100 krad total ionizing dose tolerance. Space electronics demand reliable converters. Higher rails also feed motors, actuators, and sensors in factory equipment. Reliable converters reduce maintenance visits and protect equipment.
By mounting style, surface mount dominates the DC-DC converter market owing to compact boards and automated assembly
Surface mount holds the largest share of the mounting style segment and is growing, because compact boards and automated assembly favor small packages. In April 2026, EPC introduced 100 V gallium nitride power stage ICs rated at 35 A and 20 A in thermally enhanced QFN packages for DC-DC conversion, robotics, and drones. Smaller parts cut board area. Assembly lines also save cost through automated placement and fewer manual steps. Higher density also supports thinner consumer products overall.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Through hole mounting remains relevant within the mounting style segment, as industrial, rail, and aerospace equipment needs strong mechanical bonds under vibration. Isolated modules protect sensitive circuits and meet safety rules in harsh settings. Engineers can also replace parts by hand during field maintenance, which suits equipment that stays in service for decades. Longer service lives reduce replacement costs for operators, and wave soldering lines in many factories still handle these packages efficiently, and technicians service them with basic tools.
By application, smartphone dominates the DC-DC converter market owing to the number of conversion stages in each handset
Smartphones hold the largest share of the application segment, because each handset needs several conversion stages for charging, displays, and processors. Fast charging raises power levels inside phones, and efficient conversion limits heat, which protects batteries and screens and keeps devices comfortable to hold. Brands compete on charging speed, so design teams scrutinize power stages closely. Annual refresh cycles and large unit volumes make handsets the biggest single source of converter orders for component suppliers across Asia and other regions.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
EV battery is registering the fastest growth within the application segment in the DC-DC converter market, as electric vehicles need converters between high voltage packs and low voltage systems. In October 2025, Littelfuse launched the IX4352NEAU AEC-Q100 gate driver for silicon carbide devices in electric vehicle powertrains and DC-DC converters. Automotive qualification matters to carmakers. Rising vehicle output and higher voltage packs keep adding converters per car. Carmakers also require long warranty periods, so suppliers invest in testing and traceability across plants. Demand stays steady.
North America commands the largest regional share of the DC-DC converter market, supported by data center investment and a strong power semiconductor base
North America commands the largest regional share of the DC-DC converter market, supported by data center investment, defense electronics, and a strong base of power semiconductor firms. Cloud spending keeps demand strong, and large operators keep expanding server capacity yearly. Aerospace and defense programs also require rugged, qualified converters, while domestic chip incentives encourage new capacity. Close ties between chip designers, module makers, and hyperscale customers shorten development cycles and keep the region at the center of high-power computing.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is registering the fastest growth among the regional markets, driven by phone, vehicle, and electronics manufacturing that concentrate in the region. In September 2026, Renesas of Japan introduced a 650 V gallium nitride device with 20 milliohm resistance in an 8 mm by 8 mm package for 800 V to 48 V stages. Local production of servers and vehicles also supports steady demand for converters. Governments in the region also support domestic chip production through incentives.
The competitive landscape remains moderately fragmented, with established DC-DC converter companies competing on efficiency, power density, reliability, certifications, and supply security across consumer, industrial, transport, and computing applications. Leading DC-DC converter companies continue to invest in wide bandgap devices, vertical power delivery, and higher voltage ranges to retain loyal customers while capturing demand from artificial intelligence servers and electric vehicles in faster growing regions. Supply security has become a central buying criterion.
Major DC-DC converter market players are also pursuing acquisitions, new fabs, and partnerships with computing and vehicle makers to strengthen their footprint across both mature and emerging regions. Continued emphasis on efficiency, smaller size, and industry approvals is allowing established brands to defend their position with design engineers while building deeper presence in newer applications such as 800-volt data center racks and electric vehicle systems. Customers increasingly demand dependable local support.
Founded in 1930 and headquartered in Dallas, Texas, United States, the company supplies the market through a broad portfolio of converters, controllers, and power modules for automotive, industrial, personal electronics, and data center customers. The company sells through direct channels, distributors, and online stores across North America, Europe, and Asia.
Founded in 1944 and headquartered in Nagaokakyo, Kyoto, Japan, the company supplies the market through board mount converters and power integrated circuits. The company sells through distributors and direct channels to telecom, medical, industrial, and consumer electronics customers across Asia, Europe, and the Americas.
Founded in 1892 and headquartered in Evendale, Ohio, United States, the company is a long-established name in power conversion and electrical equipment for industrial, rail, and energy customers. The company reaches the market through legacy power electronics technology and sells through direct sales and industrial partners across North America, Europe, and Asia.
Founded in 1969 and headquartered in Gmunden, Austria, the company supplies the market with a wide range of board mount, rail, and medical converters, for industrial, transport, and medical uses. The company sells through distributors and direct sales to industrial, transport, and medical customers across Europe, Asia, and North America.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global DC-DC converter market trends 2026 report. Discover regional growth patterns, input voltage shifts, application trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market. Request a customised quote to align the findings with your own business planning.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of USD 14.90 Billion in 2025.
The market is projected to grow at a CAGR of 10.50% between 2026 and 2035, reaching USD 40.44 Billion by 2035.
Key strategies driving the market include the adoption of GaN and SiC technologies for higher efficiency and power density, product miniaturization to meet space-constrained applications, expansion of modular and high-voltage DC-DC portfolios, strategic partnerships and collaborations for local manufacturing, and investments in R&D and regional production facilities to support EVs, renewable energy, and industrial automation sectors.
The key trends guiding the market include the increasing use of DC-DC converters in electric aircraft, the growing incorporation of new power-saving modes in DC-DC converters, and the rising use of thick film DC-DC converters in space applications.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
5-36V leads the market by input voltage, while 75V and above is expected to expand quickly.
3.3V, 5V, 12V, and 15V and above are the various output voltages considered in the market report.
The major mounting styles of DC-DC converter considered in the market report include surface mount and through hole.
Smartphone, servers PCs, EV battery, railways, and medical equipment are the significant applications of DC-DC converter in the market.
The key players in the market include Texas Instruments Inc., Murata Manufacturing Co., Ltd., General Electric Company, and RECOM Power GmbH, among others.
North America leads the market by region, while Asia Pacific is registering the fastest growth.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Input Voltage |
|
| Breakup by Output Voltage |
|
| Breakup by Mounting Style |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




