

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
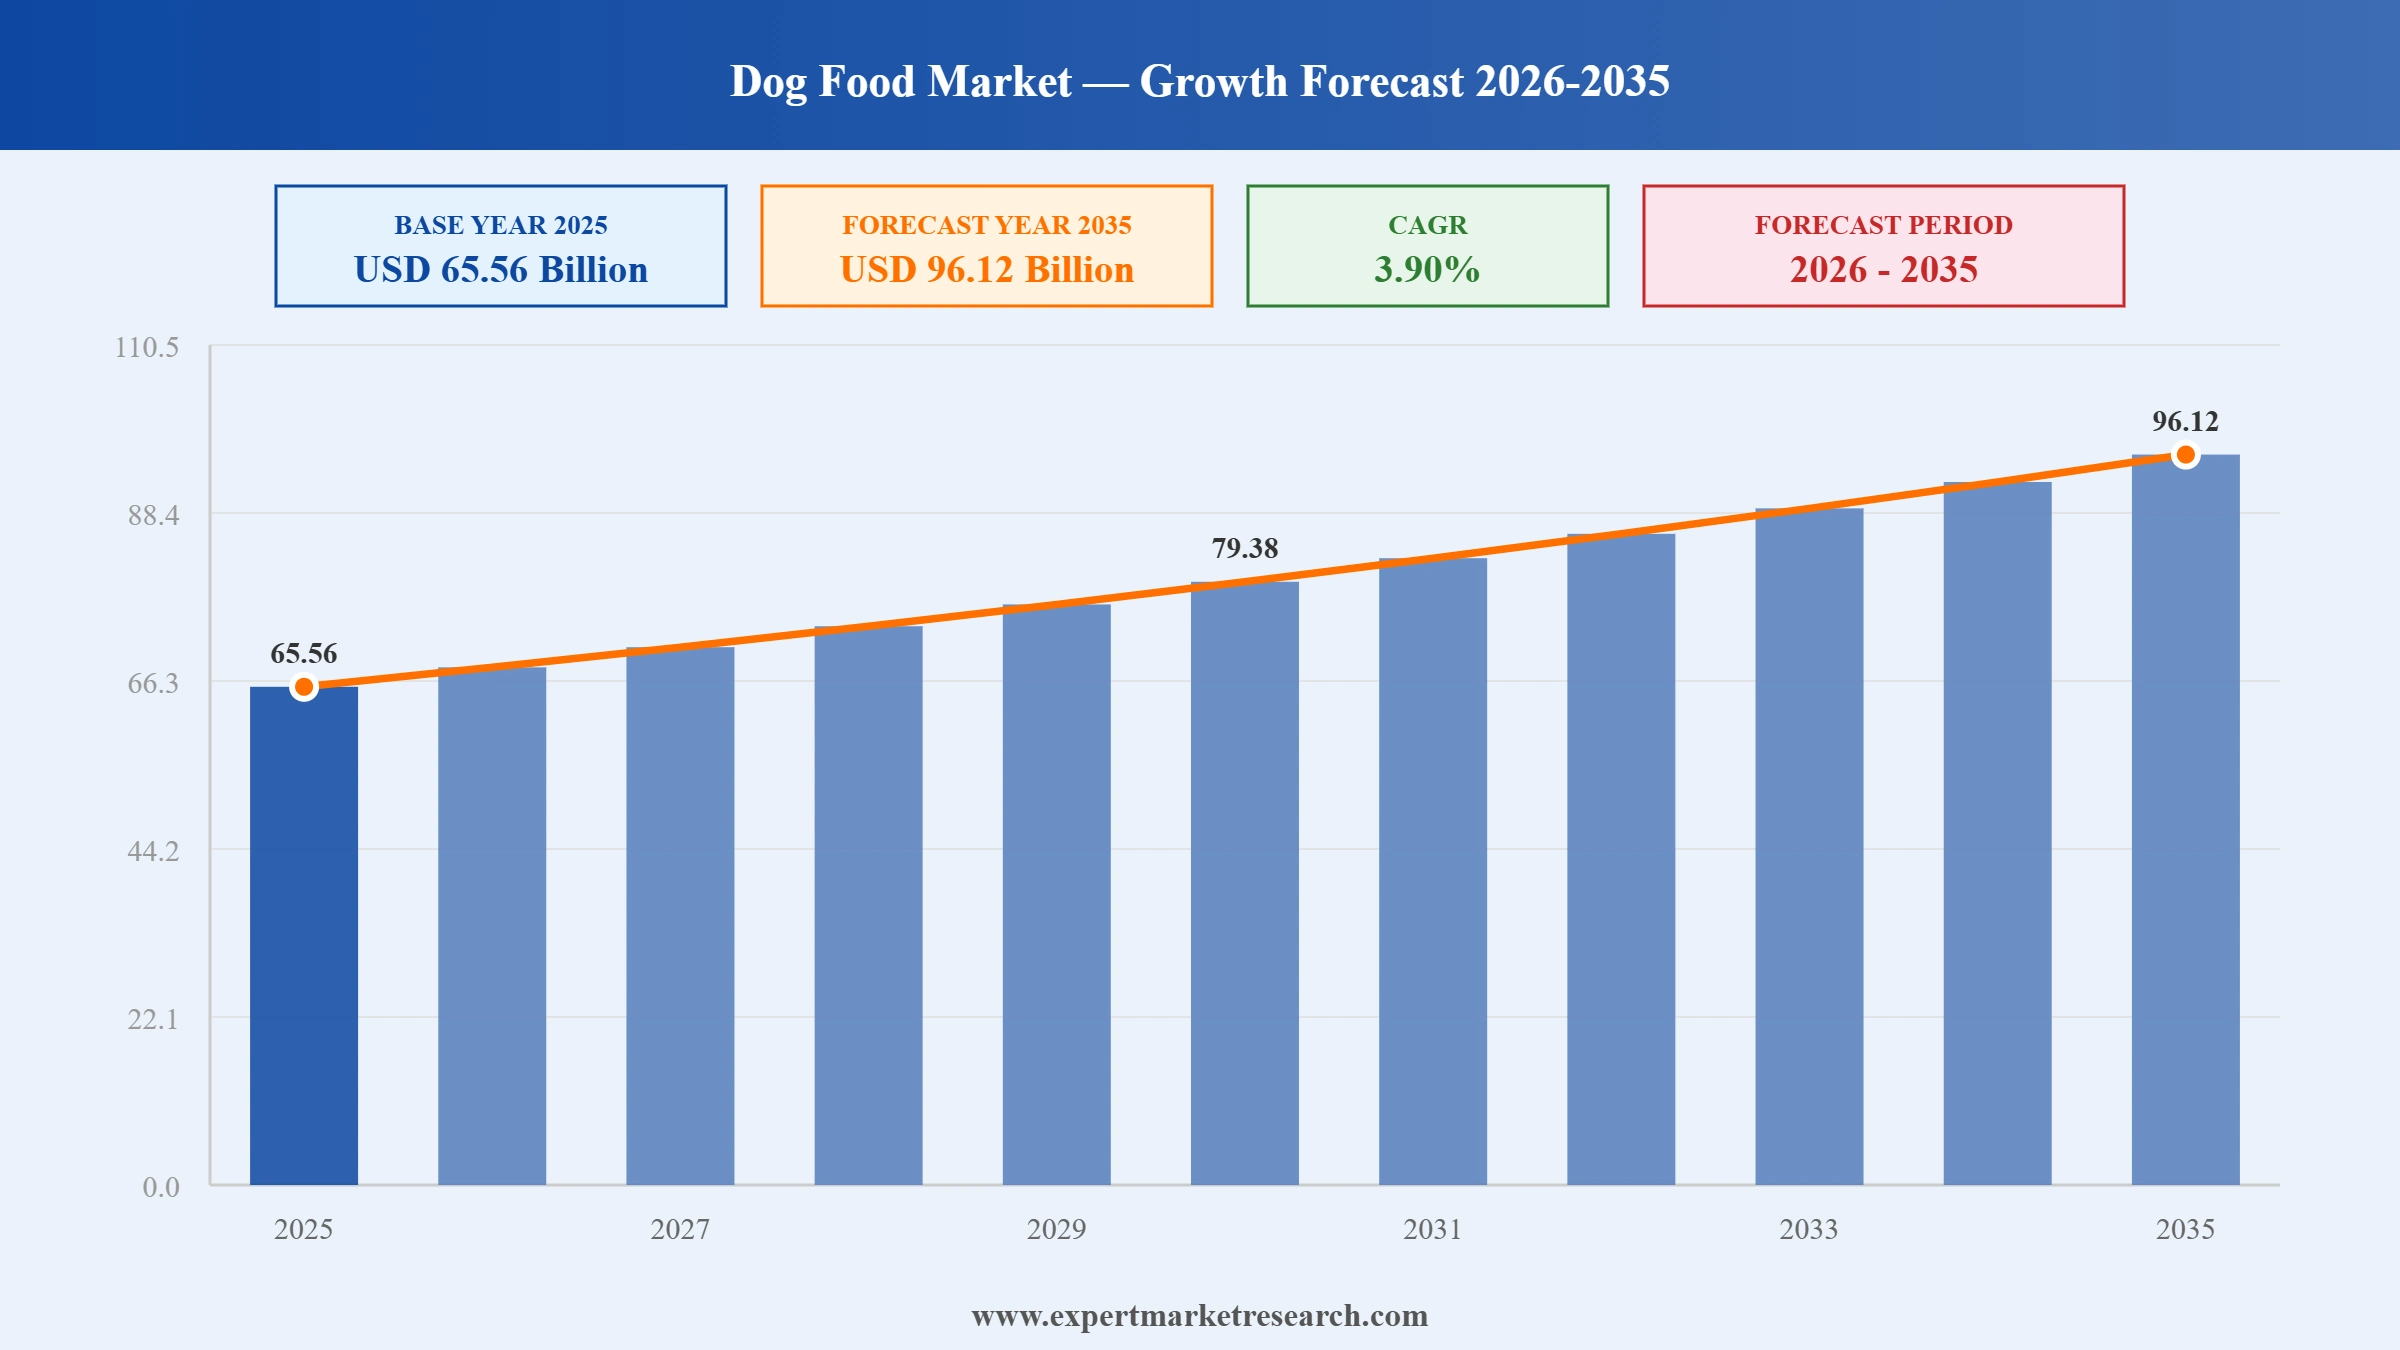
The global dog food market attained a value of USD 65.56 Billion in 2025 and is projected to expand at a CAGR of 3.90% through 2035. The market is further expected to achieve USD 96.12 Billion by 2035. Rising pet humanisation, premiumisation toward functional and health-focused nutrition, and the rapid expansion of online and subscription distribution channels are encouraging manufacturers to broaden their product portfolios and expand production capacity.
Dog food manufacturers are adapting to a market in which owners increasingly treat pet diets as an extension of their own health and wellness choices. Sustained growth in dog ownership, particularly among younger households in urban markets, is supporting steady volume demand, while willingness to pay for premium, functional, and fresh formats is lifting value growth ahead of volume growth across developed economies.
This momentum was underscored in April 2026, when Capstone Partners reported an uptick in merger and acquisition activity across the pet sector as transactions delayed from 2025 began closing, with strategic buyers and financial sponsors targeting premium nutrition platforms. Such consolidations signal confidence in sustained category demand and are expected to fund capacity, formulation, and channel expansion across the dog food market.
In addition, dog food market is allocating capital toward manufacturing capacity, functional formulation, and digital distribution, with Nestlé, Mars, General Mills, Colgate-Palmolive, and Wellness Pet Company among those investing in production expansion and premium portfolio development. Similarly, in June 2026, Nestlé Purina Petcare Europe relaunched and expanded its Gourmet Perle wet food range to address growing European demand, illustrating how established players are refreshing core product lines to defend share.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Nestlé announced an investment of over CHF 157 million to expand its pet food manufacturing capacity in Thailand, supporting Purina's growth across Asian markets where pet ownership and premiumisation are rising together. The expansion adds production flexibility for dry and moist formats serving regional demand. Companies can replicate such regional capacity plays to shorten lead times and hedge supply risk across the dog food market.
Pet food manufacturers are adopting enWave's vacuum microwave drying (REV) technology to produce minimally processed, shelf-stable, and dual-texture premium dog snacks that align with humanisation trends. The technology supports clean-label positioning without refrigeration logistics. Snack producers across the dog food market can leverage such processing innovations to differentiate premium treat lines and command higher price points.
Nestlé Purina announced a CHF 520 million investment in a new integrated pet food manufacturing plant and logistics platform in Mantova, Italy, focused on super-premium wet food for cats and dogs. The facility strengthens European supply for high-value moist formats amid growing demand. Competitors across the dog food market can respond with comparable wet-food capacity investments to defend share in Europe's premium segment.
Mars Petcare and Big Idea Ventures launched their 2026 global pet food innovation programme to accelerate start-ups working on breakthrough processing technologies, precision fermentation, and sustainable protein solutions, including animal-identical proteins and functional mushroom delivery systems. The initiative signals corporate appetite for next-generation ingredients. Emerging brands can use such programmes to secure funding and scale novel formulations within the market.
Dog owners increasingly treat food as preventive healthcare, pushing manufacturers toward gut-health, antioxidant, and functional ingredient claims across premium ranges. In October 2026, industry coverage reported that plant-based pet food is transitioning into a mainstream commercial category, split between price-sensitive options and benefit-led premium formulations with verified health claims. This shift is encouraging established brands and start-ups alike to invest in clinically supported recipes, positioning functional nutrition as a core growth engine for the dog food market over the forecast period.
After several subdued years, strategic buyers and private equity firms are returning to pet nutrition, focusing on premium brands, consumables, and fresh formats. In July 2026, industry reporting noted that merger and acquisition activity was rebounding, with buyers prioritising premium nutrition and differentiated portfolios as delayed transactions from prior years began closing. Renewed deal flow is expected to fund capacity expansion, faster innovation cycles, and broader channel reach, intensifying competition across the dog food market and could reshape the competitive hierarchy among mid-sized brands.
Owners across the dog food market increasingly scrutinise labels, sourcing origins, and environmental footprints, prompting manufacturers to invest in traceable supply chains and cleaner ingredient decks. In December 2025, industry guidance for manufacturers highlighted ingredient transparency, automated processing efficiency, and sustainable sourcing as defining priorities for meeting growing consumer demand. Companies that can document sourcing integrity and reduce processing additives are likely to earn durable trust and price premiums, making transparency a competitive requirement rather than a marketing option. Third-party verification and clearer labelling standards are expected to spread across mainstream tiers as well.
As dogs are increasingly treated as family members, owners across the dog food market are supplementing core diets with toppers, broths, and fresh mix-ins that add variety and perceived health benefits. In October 2026, the global dog food topper market was reported at USD 4.0 billion, with forecasts projecting expansion to USD 8.6 billion by 2036 and dry toppers leading product categories. This fast-growing adjacent format gives manufacturers a premiumisation lever, encouraging bundle strategies that attach toppers to core kibble ranges. Subscription bundles and veterinary endorsement are expected to accelerate adoption further.
Subscription commerce is becoming a defining feature of pet food retail as brands prioritise recurring revenue over one-time transactions. In March 2026, industry coverage reported that autoship orders accounted for over 80% of Chewy's net sales, which reached USD 12.6 billion in fiscal 2025, up 8.3% year-on-year, with discounts of up to 35% used to convert first-time buyers into repeat subscribers. This retention-driven model is expected to deepen brand loyalty and provide manufacturers with predictable demand signals, encouraging further investment in direct-to-consumer subscription infrastructure across the dog food market.
The Expert Market Research's report titled "Global Dog Food Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product
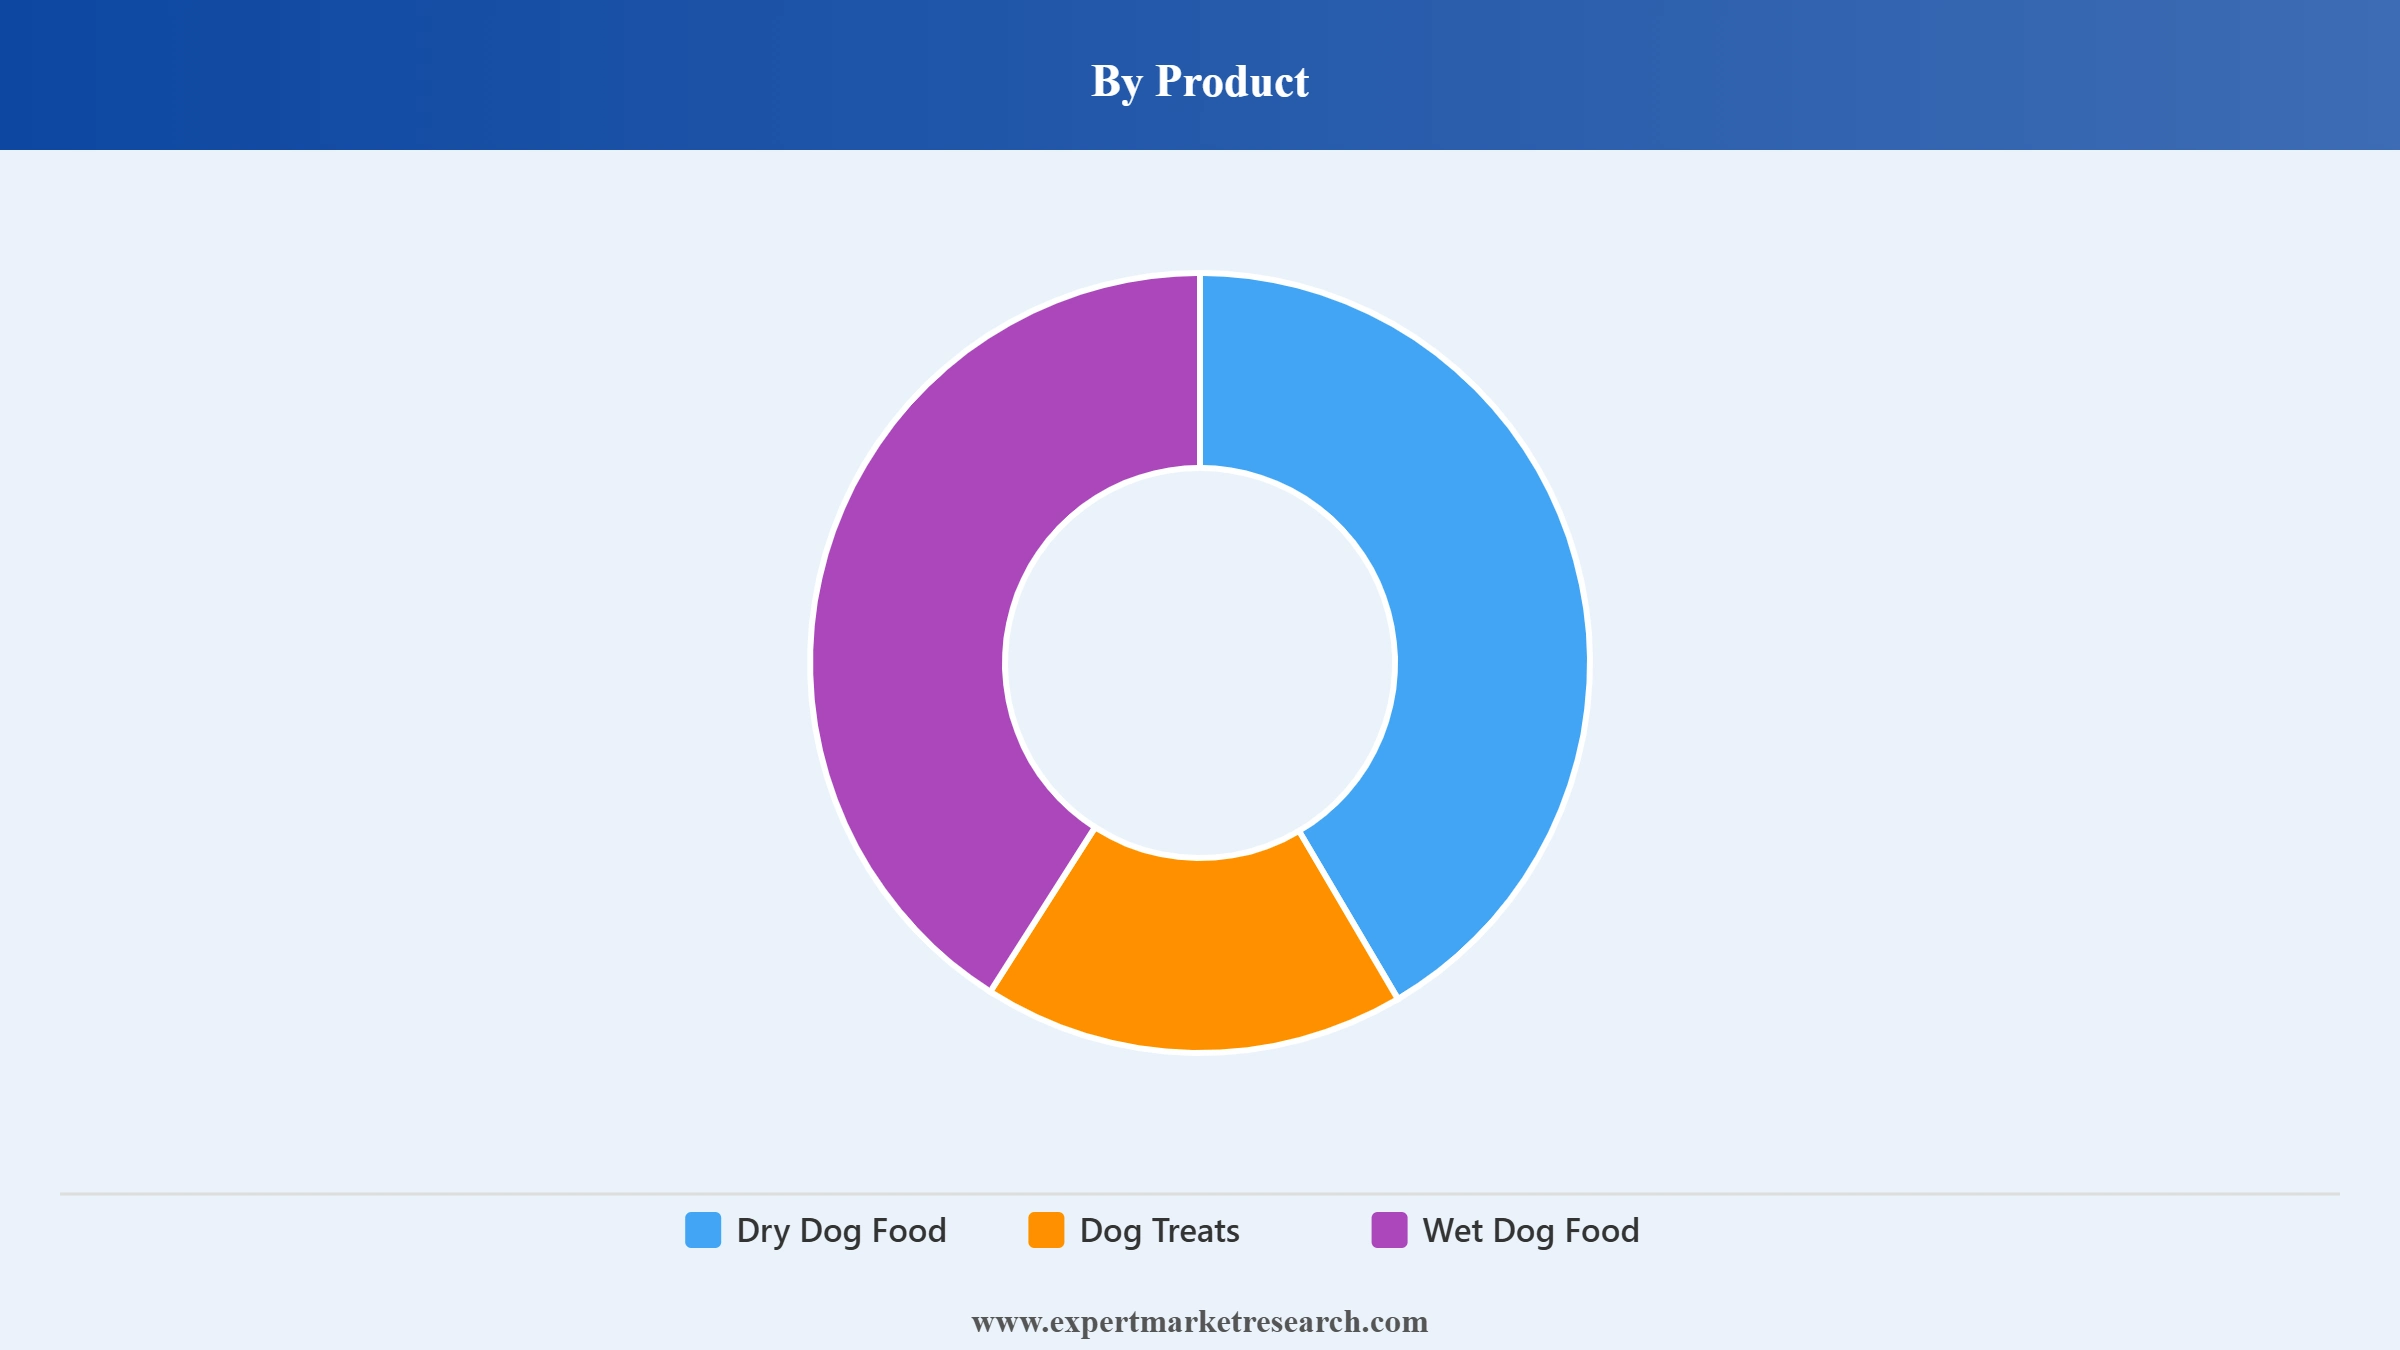
Key Insight: Dry dog food accounts for the largest share of the market, supported by its convenience, affordability, long shelf life, and status as the default daily feeding format across most households. Dog treats are the fastest-growing product segment, propelled by humanisation, training routines, and functional snack formats such as dental chews and freeze-dried morsels. Wet dog food continues to expand steadily on the back of palatability, hydration benefits, and premium texture-led formats.
Market Breakup by Pricing
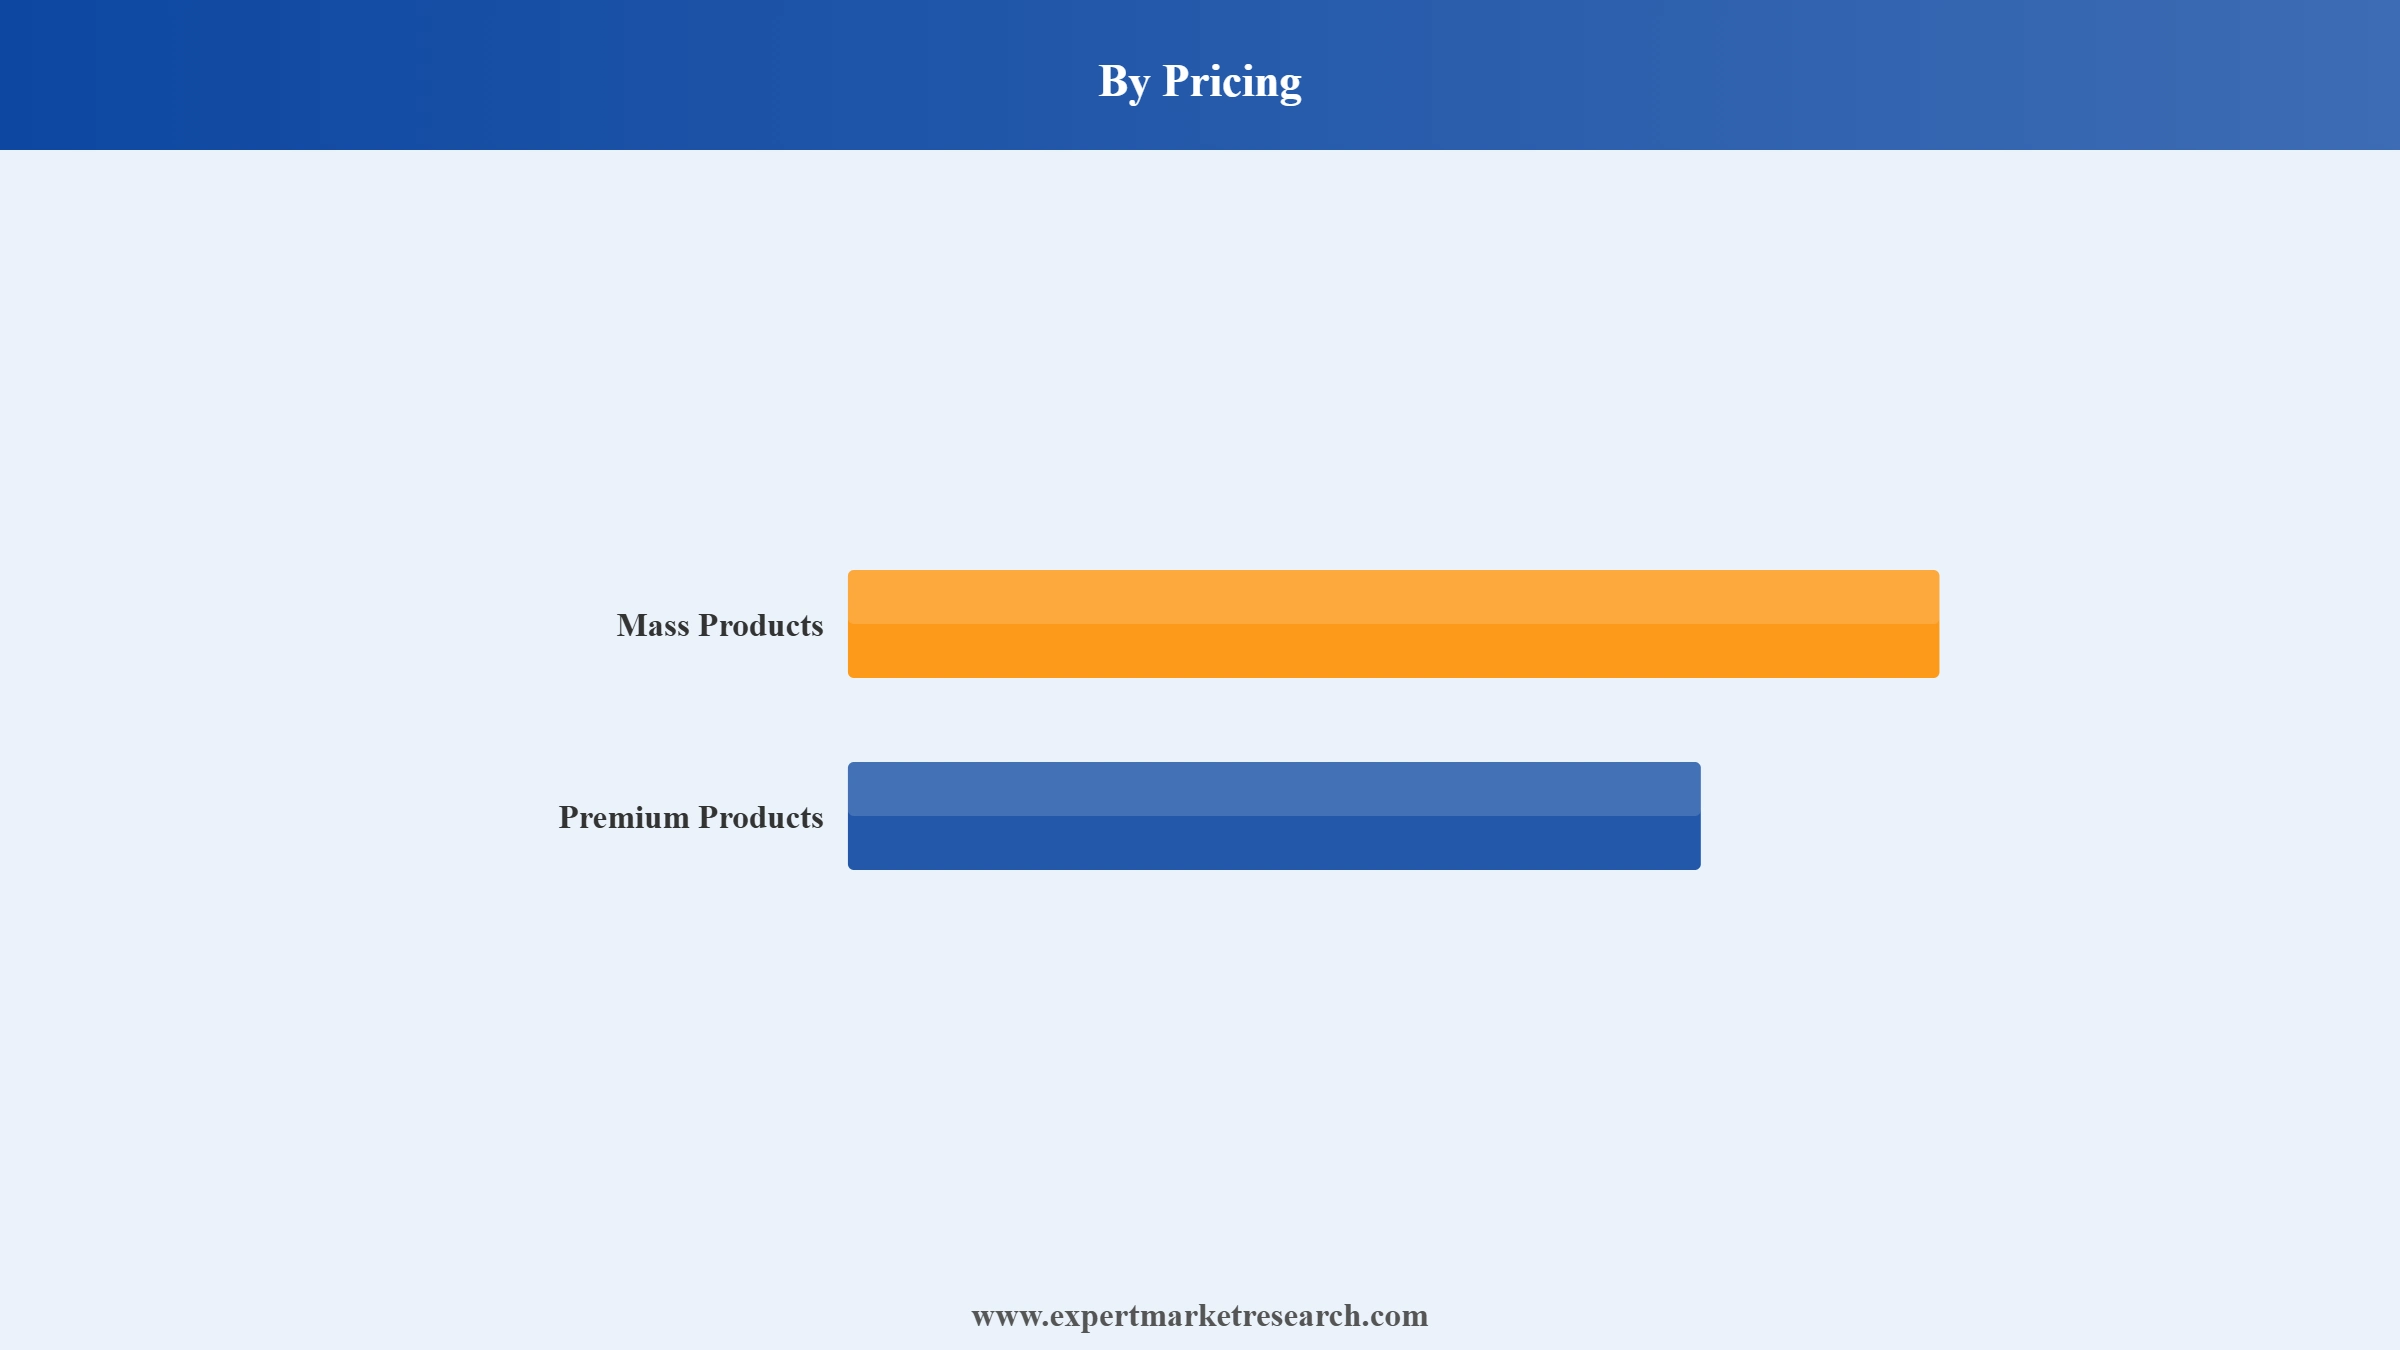
Key Insight: Mass products hold the largest share of the dog food market, anchored in their affordability and deep penetration across grocery channels and price-sensitive emerging economies. Premium products are growing at the fastest pace as owners increasingly equate diet quality with pet health, favouring limited-ingredient, grain-free, and functional recipes supported by veterinary endorsement and transparent sourcing claims.
Market Breakup by Ingredient
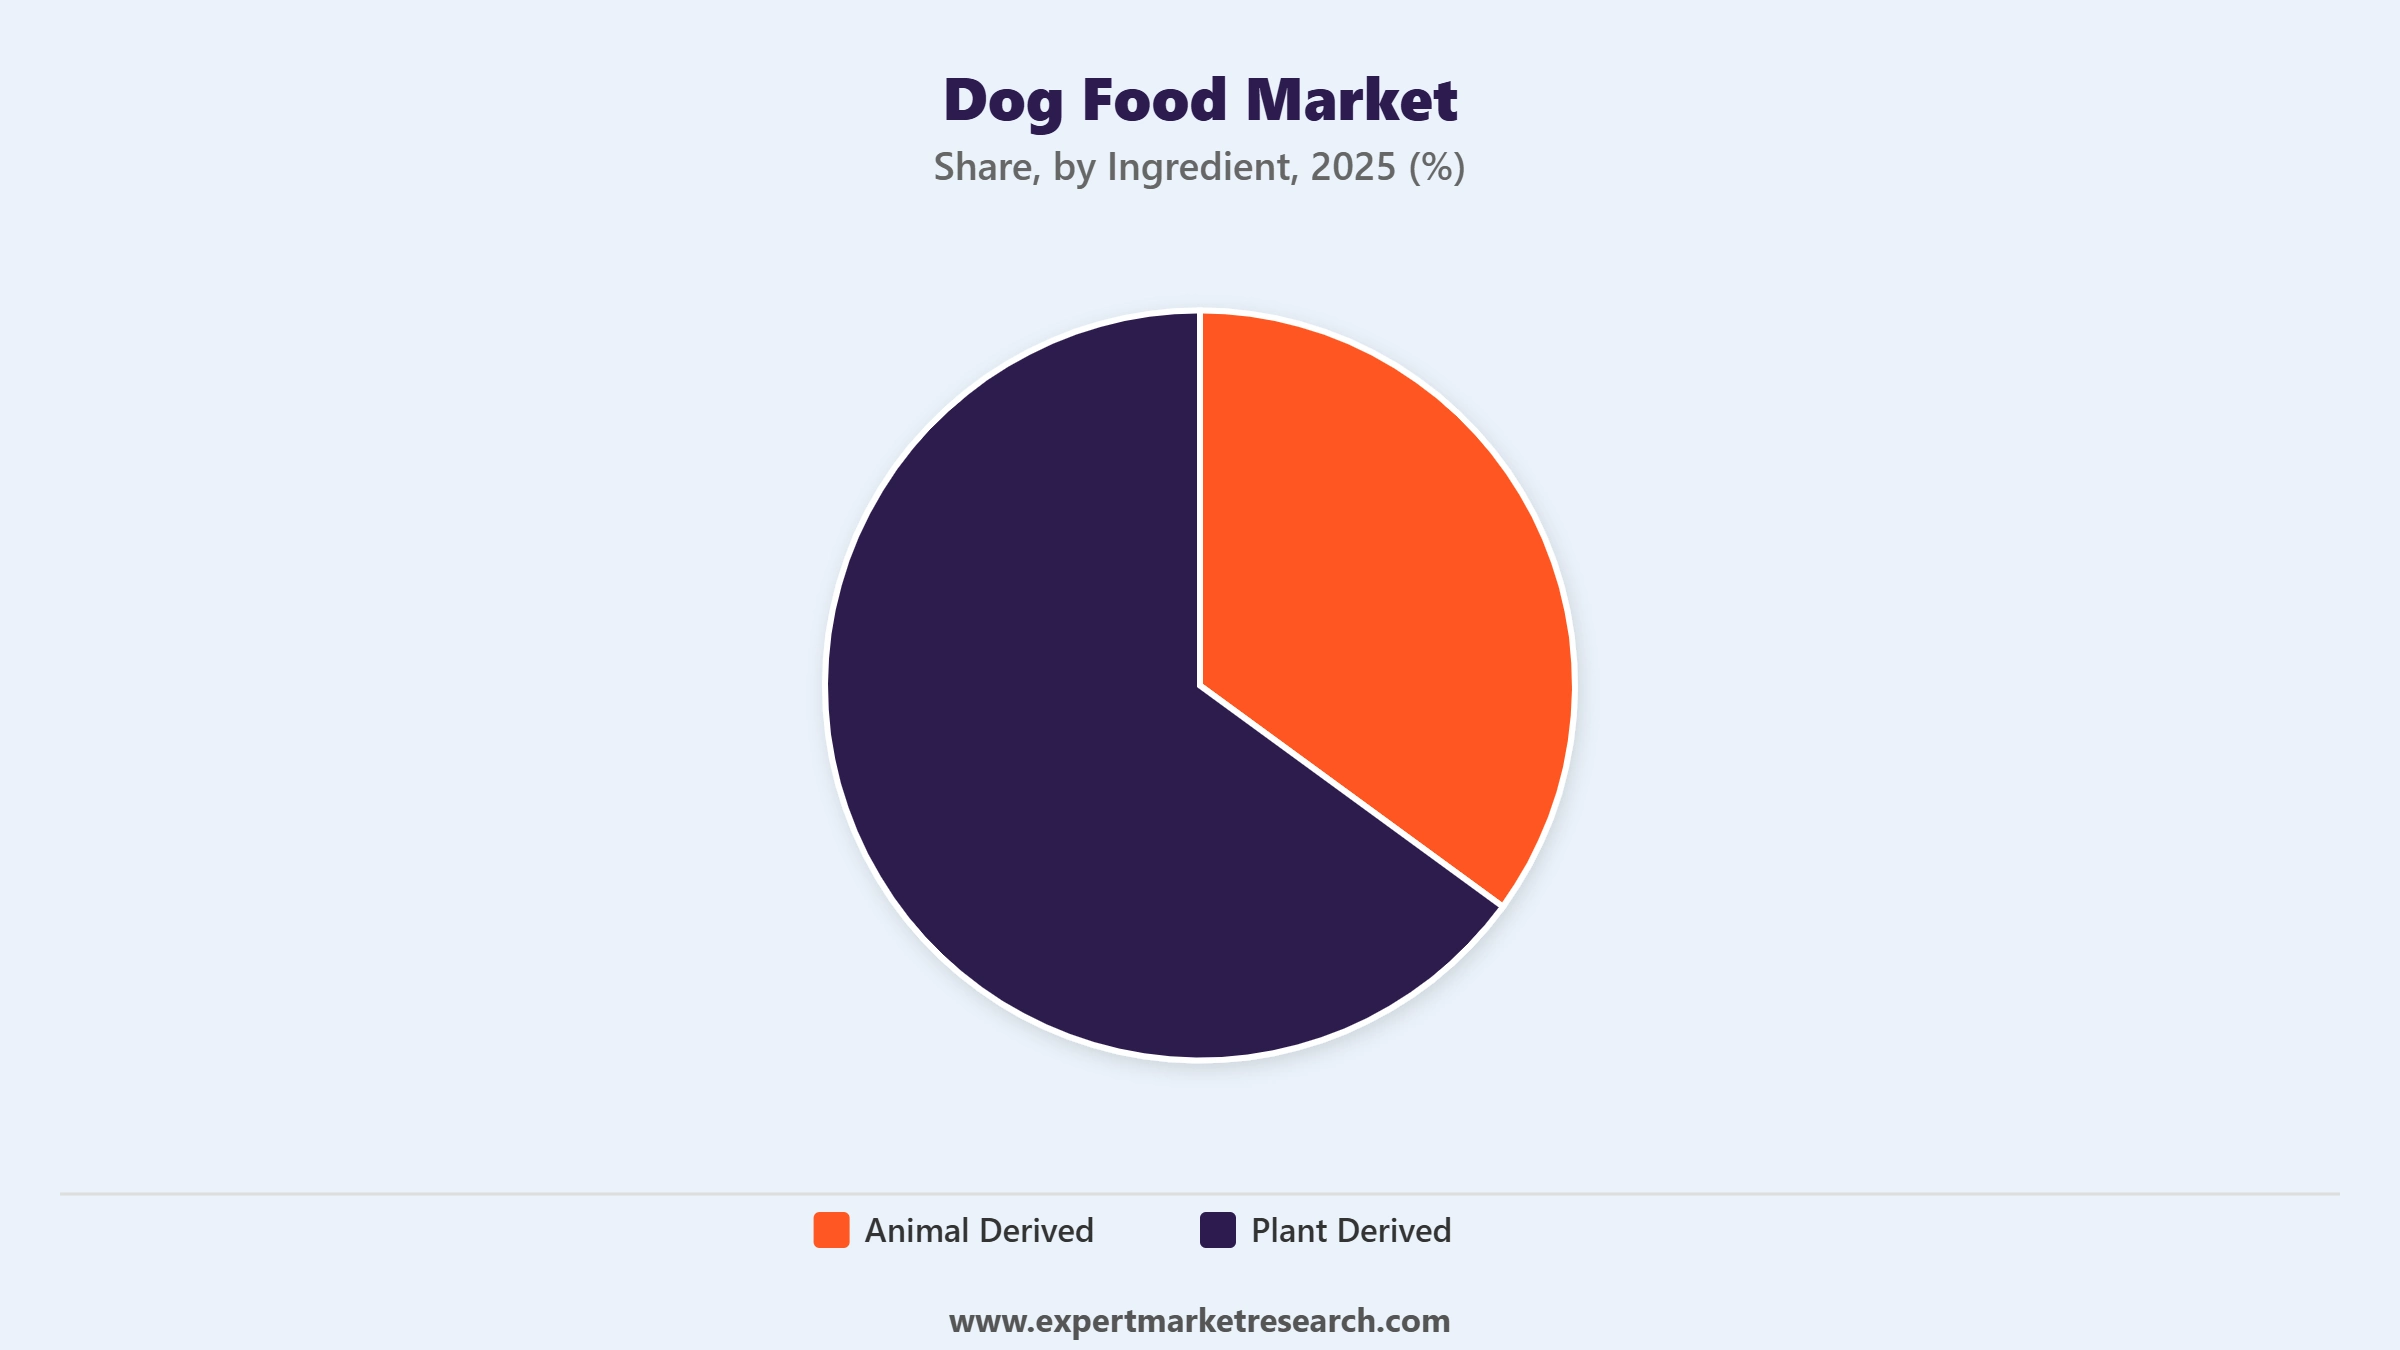
Key Insight: Animal-derived ingredients dominate the dog food market, consistent with dogs' carnivorous dietary requirements and the centrality of meat meals, poultry proteins, and fish-based inputs across kibble and wet formulations. Plant-derived ingredients are the fastest-growing category as formulators respond to sustainability pressures, protein cost volatility, and rising owner interest in botanicals, grains, and supplemental plant-based nutrition.
Market Breakup by Distribution Channel
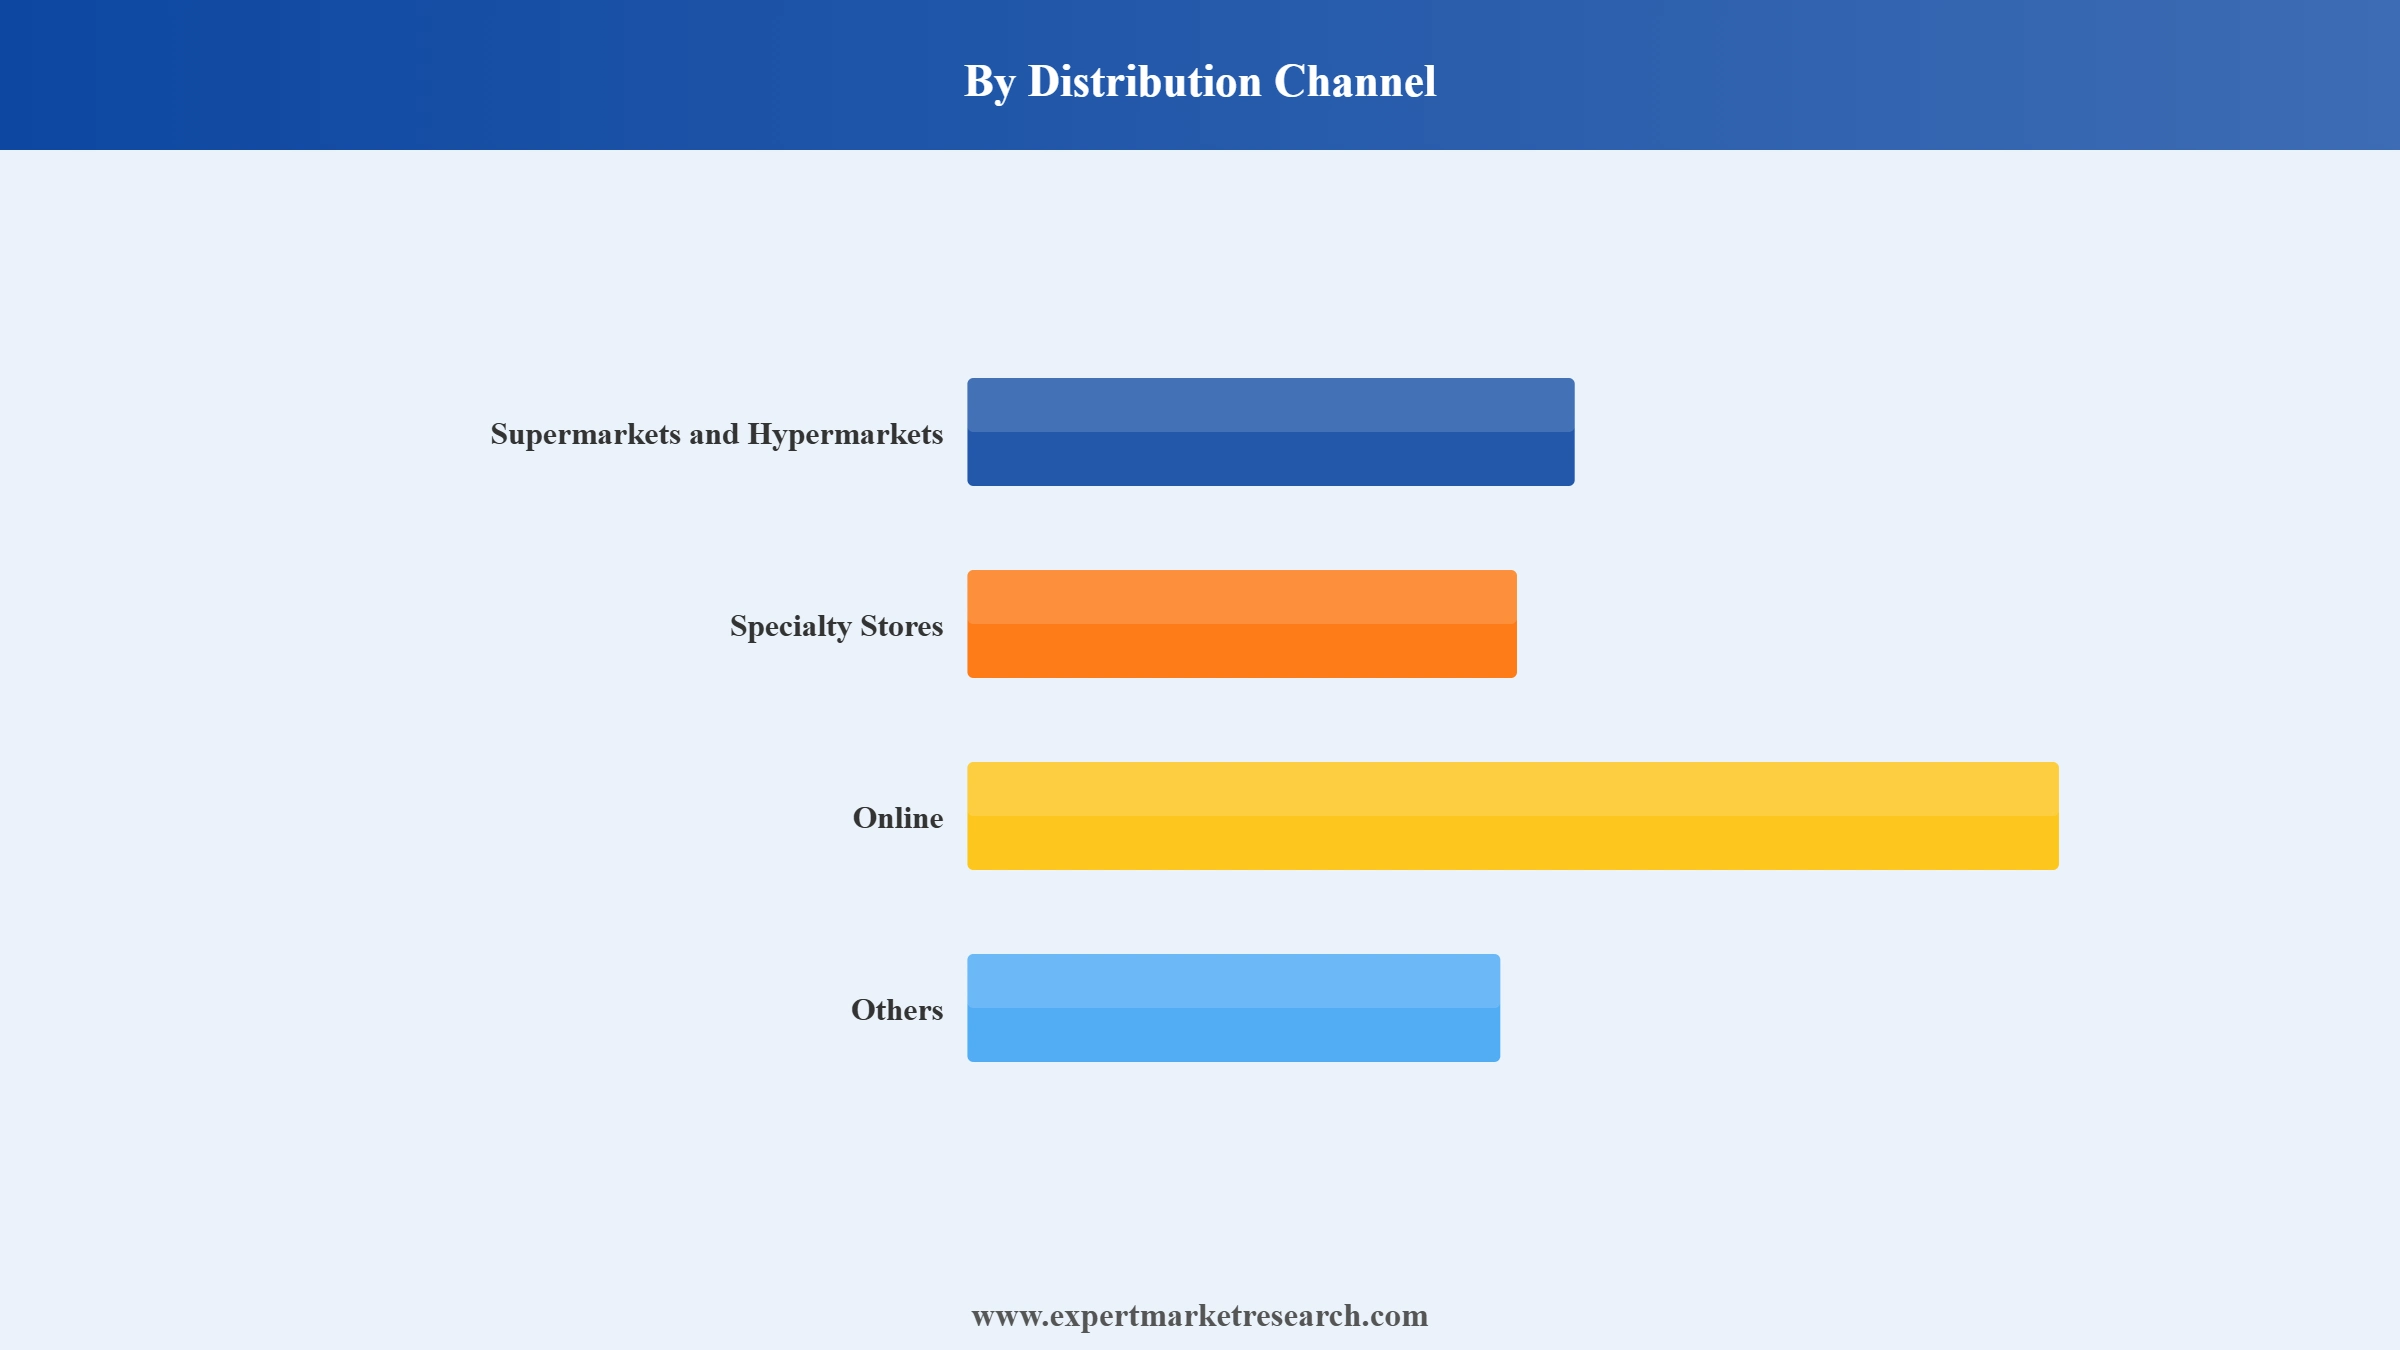
Key Insight: Supermarkets and hypermarkets account for the largest share of the dog food market, offering one-stop convenience, promotional visibility, and the broadest mass-brand availability for routine repurchase. Online is the fastest-growing channel, driven by subscription auto-ship services, wider premium assortments, and home delivery of bulky bags. Specialty stores serve premium and prescription diets with expert advice, while other channels, including veterinary clinics and farm supply retailers, address niche demand.
Market Breakup by Region
Key Insight: North America accounts for the largest share of the dog food market, reflecting high pet ownership rates, mature premium segments, and the strong presence of leading manufacturers. Asia Pacific is expected to grow at the fastest pace, supported by urbanisation, rising disposable incomes, and growing pet adoption across China, India, and Southeast Asia. Europe sustains steady demand anchored in premiumisation and stringent quality standards, while Latin America and the Middle East and Africa represent emerging opportunities as pet humanisation spreads into developing markets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By product, dry dog food leads the market as the default daily feeding format for households worldwide
Dry dog food accounts for the largest share of the dog food market, supported by its convenience, longer shelf life, and lower cost per serving, which make it the default choice for daily feeding across households. Kibble's established manufacturing base and wide availability across supermarkets, specialty retailers, and online channels continue to anchor steady replacement demand, while fortified and breed-specific formulations are helping manufacturers defend volume in the face of rising interest in fresh and wet alternatives.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Wet dog food is growing at the fastest pace, supported by rising demand for hydration-rich, palatable formats and premium textures that mirror human-grade meals. In April 2026, Nestlé reported continued organic growth across its Petcare category, citing improved dog food performance, as capacity investments across Europe and the Americas aimed to relieve supply constraints in moist formats. Manufacturers can extend wet ranges with functional gravies and single-serve trays to capture premiumisation-led trading up.
By pricing, mass products lead the market on affordability and deep grocery penetration
Mass products account for the largest share of the market, reflecting their affordability and deep penetration across supermarkets, hypermarkets, and value-focused online channels. Volume-driven staples remain the entry point for the majority of dog-owning households, particularly in price-sensitive emerging economies where pet ownership is expanding fastest. Manufacturers defend share in this tier through multi-pack formats, private-label supply agreements, and loyalty programmes, using scale efficiencies to protect margins as input costs fluctuate across meat meals, grains, and packaging materials.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Premium products are the fastest-growing pricing tier as pet owners increasingly treat food as preventive healthcare, seeking limited-ingredient, grain-free, and functional recipes. In February 2026, Pure Treats Inc., maker of PureBites, acquired Primal Pet Foods from Kinderhook Industries, combining raw and freeze-dried premium manufacturing across Texas, Colorado, and Montreal facilities. Companies can pursue similar premium consolidation, veterinary endorsement, and subscription models that lock in recurring revenue.
By ingredient, animal-derived inputs lead the market given dogs' carnivorous dietary requirements
Animal-derived ingredients account for the largest share of the market, consistent with dogs' carnivorous dietary requirements and the dominance of meat meals, poultry by-products, and fish-based proteins in mainstream kibble and wet formulations. Established supply chains for animal proteins give manufacturers reliable cost structures and palatability performance, and most mass-tier and premium recipes continue to be built around named meat firsts. Freeze-dried raw and high-meat content lines are extending this ingredient base further into the premium end of the market.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Plant-derived ingredients are the fastest-growing ingredient category as formulators respond to sustainability pressures, protein cost volatility, and owner interest in supplemental botanicals and grains. In June 2025, Vegdog, a German plant-based dog food maker, raised EUR 9 million in Series A funding after reporting 66% sales growth in 2024, funding European expansion of its vegan recipes. Companies can build differentiation around verified plant protein blends and clinically supported botanical inclusions to capture sustainability-minded buyers.
By distribution channel, supermarkets and hypermarkets lead the market on routine grocery convenience
Supermarkets and hypermarkets account for the largest share of the market, offering one-stop convenience, promotional visibility, and the broadest mass-brand availability for routine grocery-driven pet food purchases. Their established shelf space and private-label programmes give manufacturers dependable volume, particularly for dry food and multi-pack treats, and in-store veterinary or pet care aisles continue to expand in major chains across North America and Europe, reinforcing the channel's role as the default point of repurchase for mainstream households.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Online is the fastest-growing distribution channel, propelled by subscription auto-ship services, wider premium and specialty assortment, and home delivery of heavy bulk bags. In August 2026, Freshpet reported that digital sales rose 41% year-on-year to reach 16.7% of total net sales, as direct-to-consumer platforms helped brands personalise recommendations and gather first-party data without retail gatekeeping. Manufacturers can use digital channels to trial innovations, bundle toppers with core diets, and convert one-time buyers into recurring subscribers.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America accounts for the largest share of the market due to high pet ownership and advanced premiumisation
North America holds the largest share of the dog food market, supported by high pet ownership rates, strong humanisation trends, and the presence of leading global manufacturers with extensive premium portfolios. Mature retail infrastructure spanning mass grocery, specialty pet chains, and e-commerce sustains high repurchase frequency, while functional and therapeutic diets continue to deepen value growth across the United States and Canada.
Asia Pacific is expected to register the fastest growth during the forecast period, driven by urbanisation, rising disposable incomes, and growing pet adoption across China, India, Japan, and Southeast Asia. In September 2026, Thai producer Betagro reported 25% year-on-year growth in its pet business to THB 2.7 billion, targeting a 54% premium-segment revenue share by 2028 while expanding into Bahrain, the UAE, Brunei, Hong Kong, and South Korea. Local brands are scaling similar premium offerings tailored to regional tastes and smaller living spaces.
The global industry is moderately consolidated at the top and fragmented at the tail, with dog food companies ranging from diversified multinationals such as Nestlé and Mars to specialised premium and fresh-format producers. Established players compete across product, pricing, and ingredient segments, leveraging scale manufacturing, brand portfolios, and veterinary endorsement to defend share, while challenger brands differentiate through transparency, sustainability, and direct-to-consumer models.
Competitive dynamics among dog food players are increasingly shaped by premiumisation, functional ingredient innovation, and the shift of volume toward online and subscription channels. Companies are investing in capacity expansion, start-up acceleration programmes, and acquisitions of premium nutrition brands to secure growth, while supply chain resilience and ingredient traceability have become key determinants of long-term competitive positioning across the market.
Founded in 1866 and headquartered in Vevey, Switzerland, Nestlé serves the dog food market through Nestlé Purina PetCare, one of the world's largest pet nutrition businesses, whose portfolio spans dry and wet dog food, treats, and veterinary diets under brands such as Purina ONE, Pro Plan, and Beneful. The company operates an extensive global manufacturing network dedicated to science-based pet nutrition.
Founded in 1911 and headquartered in McLean, Virginia, United States, Mars serves the dog food market through Mars Petcare, whose brands include Pedigree, Royal Canin, Iams, and Cesar. The company combines large-scale manufacturing with veterinary health services and research-driven nutrition platforms, positioning it across mass, premium, and therapeutic dog food segments worldwide.
Founded in 1970 and headquartered in Meta, Missouri, United States, Schell & Kampeter operates as Diamond Pet Foods, producing dry dog food and treats under the Diamond, Diamond Naturals, and Taste of the Wild brands. The company supplies both premium private-label and branded products through multiple US manufacturing facilities serving domestic and international markets.
Founded in 1997 and headquartered in Tewksbury, Massachusetts, United States, Wellness Pet Company serves the dog food market with natural, nutrient-dense dry and wet recipes, treats, and toppers under its Wellness and Old Mother Hubbard brands. The company positions its portfolio around whole-food ingredients, life-stage nutrition, and functional health support.
Other key players in the market include Colgate-Palmolive Company, General Mills, Inc, Champion Petfoods USA Inc., RUSSO MANGIMI SP, H&H Group, Open Farm Inc., Annamaet Pet Foods Inc., Pets Global Inc., Primal Pet Group, Inc., Stella & Chewy's, LLC, Fromm Family Foods, LLC, Affinity Petcare S.A, Canidae, LLC, Petfood Saladillo S.A., and PremieRpet, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our dog food market trends 2026 report. Discover regional growth patterns, product and pricing trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.
United States Dog Food Market
South Korea Pet Food Market
Asia Pacific Pet Food Market
Vietnam Pet Food Market
Mexico Dog Food Market


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 65.56 Billion.
The market is projected to grow at a CAGR of 3.90% between 2026 and 2035.
The market is likely to reach a value of about USD 96.12 Billion by 2035.
Expanding regional manufacturing capacity, developing functional and limited-ingredient premium formulations, investing in transparent and sustainable sourcing, accelerating e-commerce and subscription distribution, and pursuing acquisitions of differentiated premium nutrition brands.
The growing consumer perception of natural and organic pet food products has pushed producers to change their emphasis from conventional to natural foods, which was one of the major trends influencing the global dog food market growth.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa, with North America leading the market.
The major products in the market are dry dog food, wet dog food, and dog treats.
The pricings in the market are mass products and premium products.
The major ingredients for dog food are animal derived and plant derived.
The leading distribution channels in the market include supermarkets and hypermarkets, speciality stores, and online, among others.
The key players in the market include Nestlé S.A., Mars, Incorporated, Schell & Kampeter, Inc., Wellness Pet Company, Inc., Colgate-Palmolive Company, General Mills, Inc, Champion Petfoods USA Inc., and H&H Group, among others.
Manufacturers face volatile raw material and protein ingredient costs, tightening sustainability and labelling regulations, supply chain disruptions affecting ingredient sourcing, and intense competitive pressure from both multinational brands and agile premium start-ups.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product |
|
| Breakup by Pricing |
|
| Breakup by Ingredient |
|
| Breakup by Distribution Channel |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




