

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
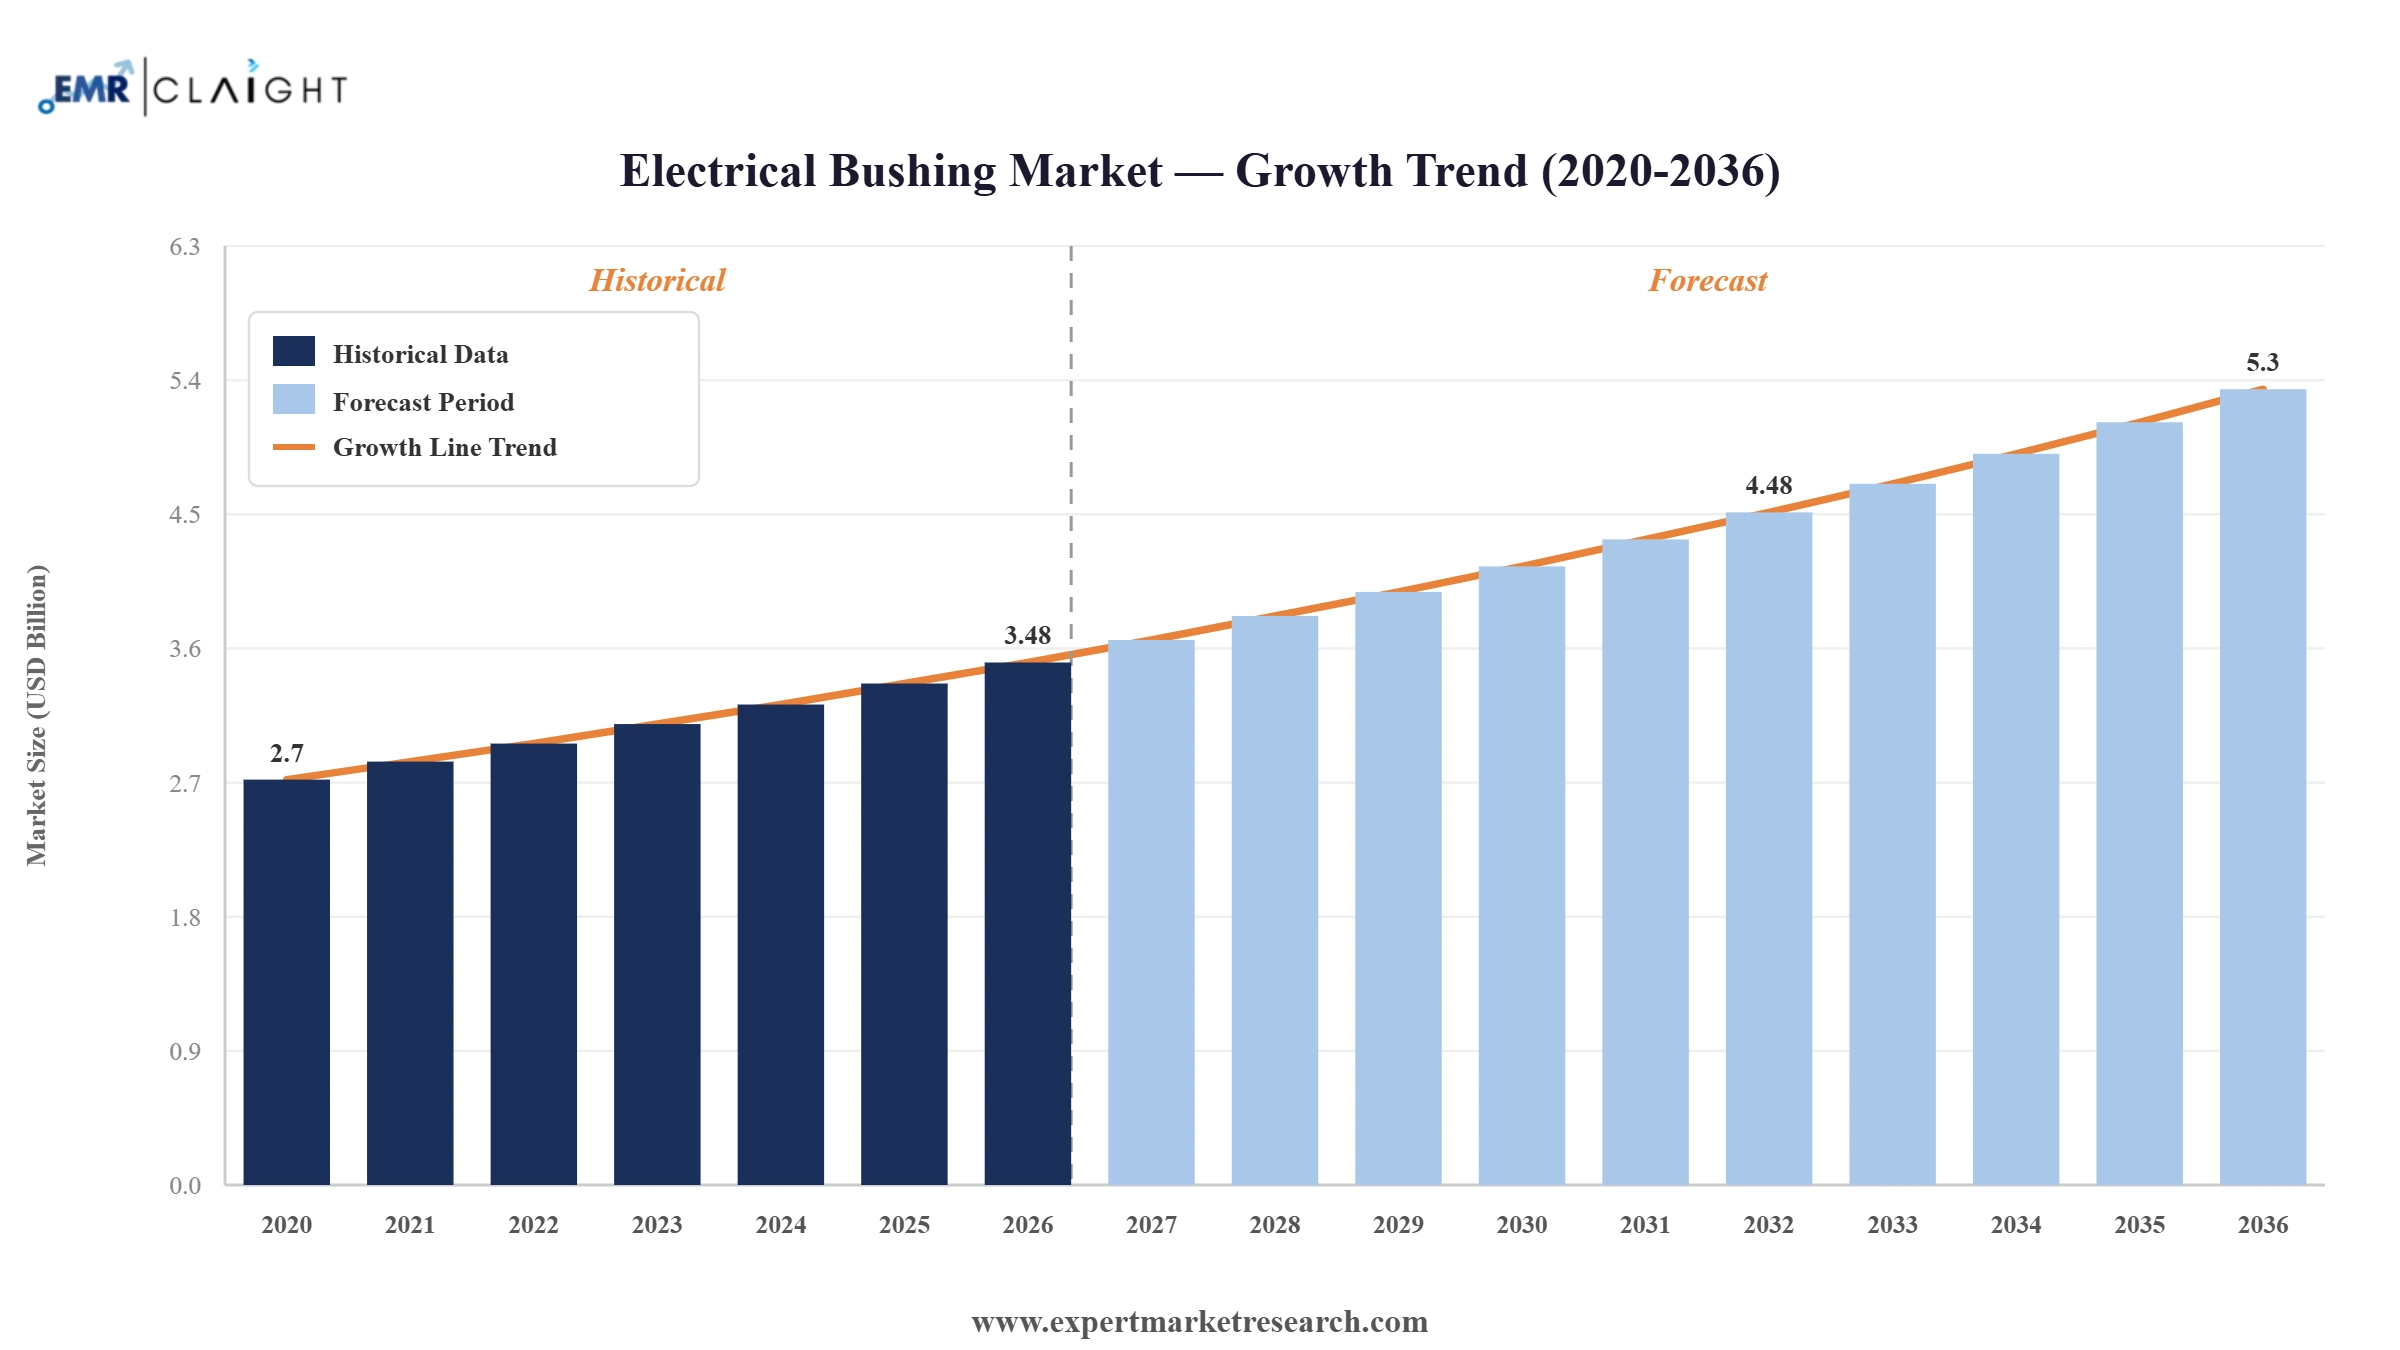
The global electrical bushing market attained a value of USD 3.34 Billion in 2025 and is projected to expand at a CAGR of 4.30% through 2035. The market is further expected to achieve USD 5.09 Billion by 2035. Increasing demand for electricity, expansion of power distribution networks, and introduction of government safety policies for the utility sector continue to support demand for oil impregnated paper and resin impregnated paper bushings across transformer and switchgear applications.
Increasing demand for electricity continues to anchor steady demand across the electrical bushing market, as expanding power distribution networks and grid modernisation initiatives require reliable insulation components capable of withstanding higher voltage loads. Manufacturers are also investing in expanded transformer and bushing manufacturing capacity, reflecting the industry's ongoing pursuit of supply chain resilience amid persistent global transformer shortages.
The electrical bushing market is witnessing further developments as established manufacturers expand dedicated transformer manufacturing capacity to address persistent supply shortages. In February 2025, Eaton Corporation established a new dedicated three-phase transformer manufacturing facility in South Carolina, its third such US plant, targeting growing demand from utility and data centre sectors. This shift toward expanded domestic manufacturing capacity is concentrated among manufacturers with sufficient capital investment scale, while smaller specialists continue to compete on regional distribution relationships and application-specific engineering expertise.
In addition, established manufacturers are increasingly forming strategic collaborations to deliver integrated power infrastructure solutions for data centre and AI campus customers, reflecting the industry's recognition that modular, rapidly deployable grid infrastructure increasingly determines competitive positioning beyond standalone bushing and transformer components alone. Such collaboration activity is reshaping competitive positioning across the wider electrical bushing market as manufacturers with proven integrated infrastructure partnership capabilities increasingly differentiate themselves from competitors offering only standalone insulation components.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
GE Vernova completed the acquisition of the remaining 50 percent stake in Prolec GE for 5.275 billion dollars, bringing full ownership of the transformer manufacturer after a 30-year joint venture and integrating the business into GE's Electrification segment. Companies can consolidate long-standing joint venture transformer businesses into wholly owned subsidiaries to streamline manufacturing and component supply chains including bushings.
Siemens committed 2 billion euros to expand its global transformer and switchgear manufacturing base by 2028, placing grid infrastructure at the centre of its growth strategy alongside a 20 percent increase in capital expenditure and research and development during 2026 to 2028. Companies can commit multi-year capital expenditure increases to transformer and switchgear manufacturing to capture accelerating electrification demand across advanced and emerging markets.
Eaton and Siemens formed a strategic collaboration to deliver modular power plants for new data centre campuses, integrating on-site renewable energy generation with grid infrastructure components. Companies can form cross-manufacturer collaborations to deliver integrated, rapidly deployable power infrastructure solutions for hyperscale data centre and AI campus customers.
Eaton Corporation established a new dedicated three-phase transformer manufacturing facility in South Carolina, its third such US plant, targeting growing demand from utility and data centre sectors amid persistent transformer supply shortages. Companies can establish dedicated regional transformer manufacturing facilities to address persistent supply shortages and reduce delivery lead times for utility and data centre customers.
Manufacturers continue consolidating long-standing joint venture transformer businesses into wholly owned subsidiaries. In February 2026, GE completed acquisition of the remaining stake in a multi-billion dollar transformer joint venture, integrating the business fully into its electrification segment across the electrical bushing market. Such consolidation reflects manufacturers' recognition that full ownership increasingly enables streamlined manufacturing and component supply chain integration compared with shared joint venture governance structures.
Manufacturers continue committing substantial multi-year capital expenditure increases to transformer and switchgear manufacturing capacity. In November 2025, Siemens announced a multi-billion dollar investment plan to expand its global transformer and switchgear factories by 2028. Such capital expenditure commitments reflect manufacturers' recognition that accelerating electrification and grid modernisation demand increasingly justifies sustained, multi-year manufacturing capacity investment beyond incremental facility upgrades.
Manufacturers continue forming cross-company collaborations to deliver integrated power infrastructure for hyperscale data centre customers. In June 2025, Eaton and Siemens formed a strategic collaboration to deliver modular power plants integrating renewable energy generation with grid infrastructure components. Such cross-company collaboration reflects manufacturers' recognition that rapidly deployable, integrated infrastructure solutions increasingly determine competitive positioning for AI campus and data centre contracts beyond standalone component supply.
Manufacturers continue establishing dedicated regional transformer manufacturing facilities to address persistent global supply shortages. In February 2025, Eaton established its third US three-phase transformer manufacturing plant, targeting growing utility and data centre sector demand. Such regional facility establishment reflects manufacturers' recognition that dedicated domestic manufacturing capacity increasingly reduces delivery lead times amid sustained transformer supply shortages affecting utility and industrial customers.
This Expert Market Research Report titled "Electrical Bushing Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
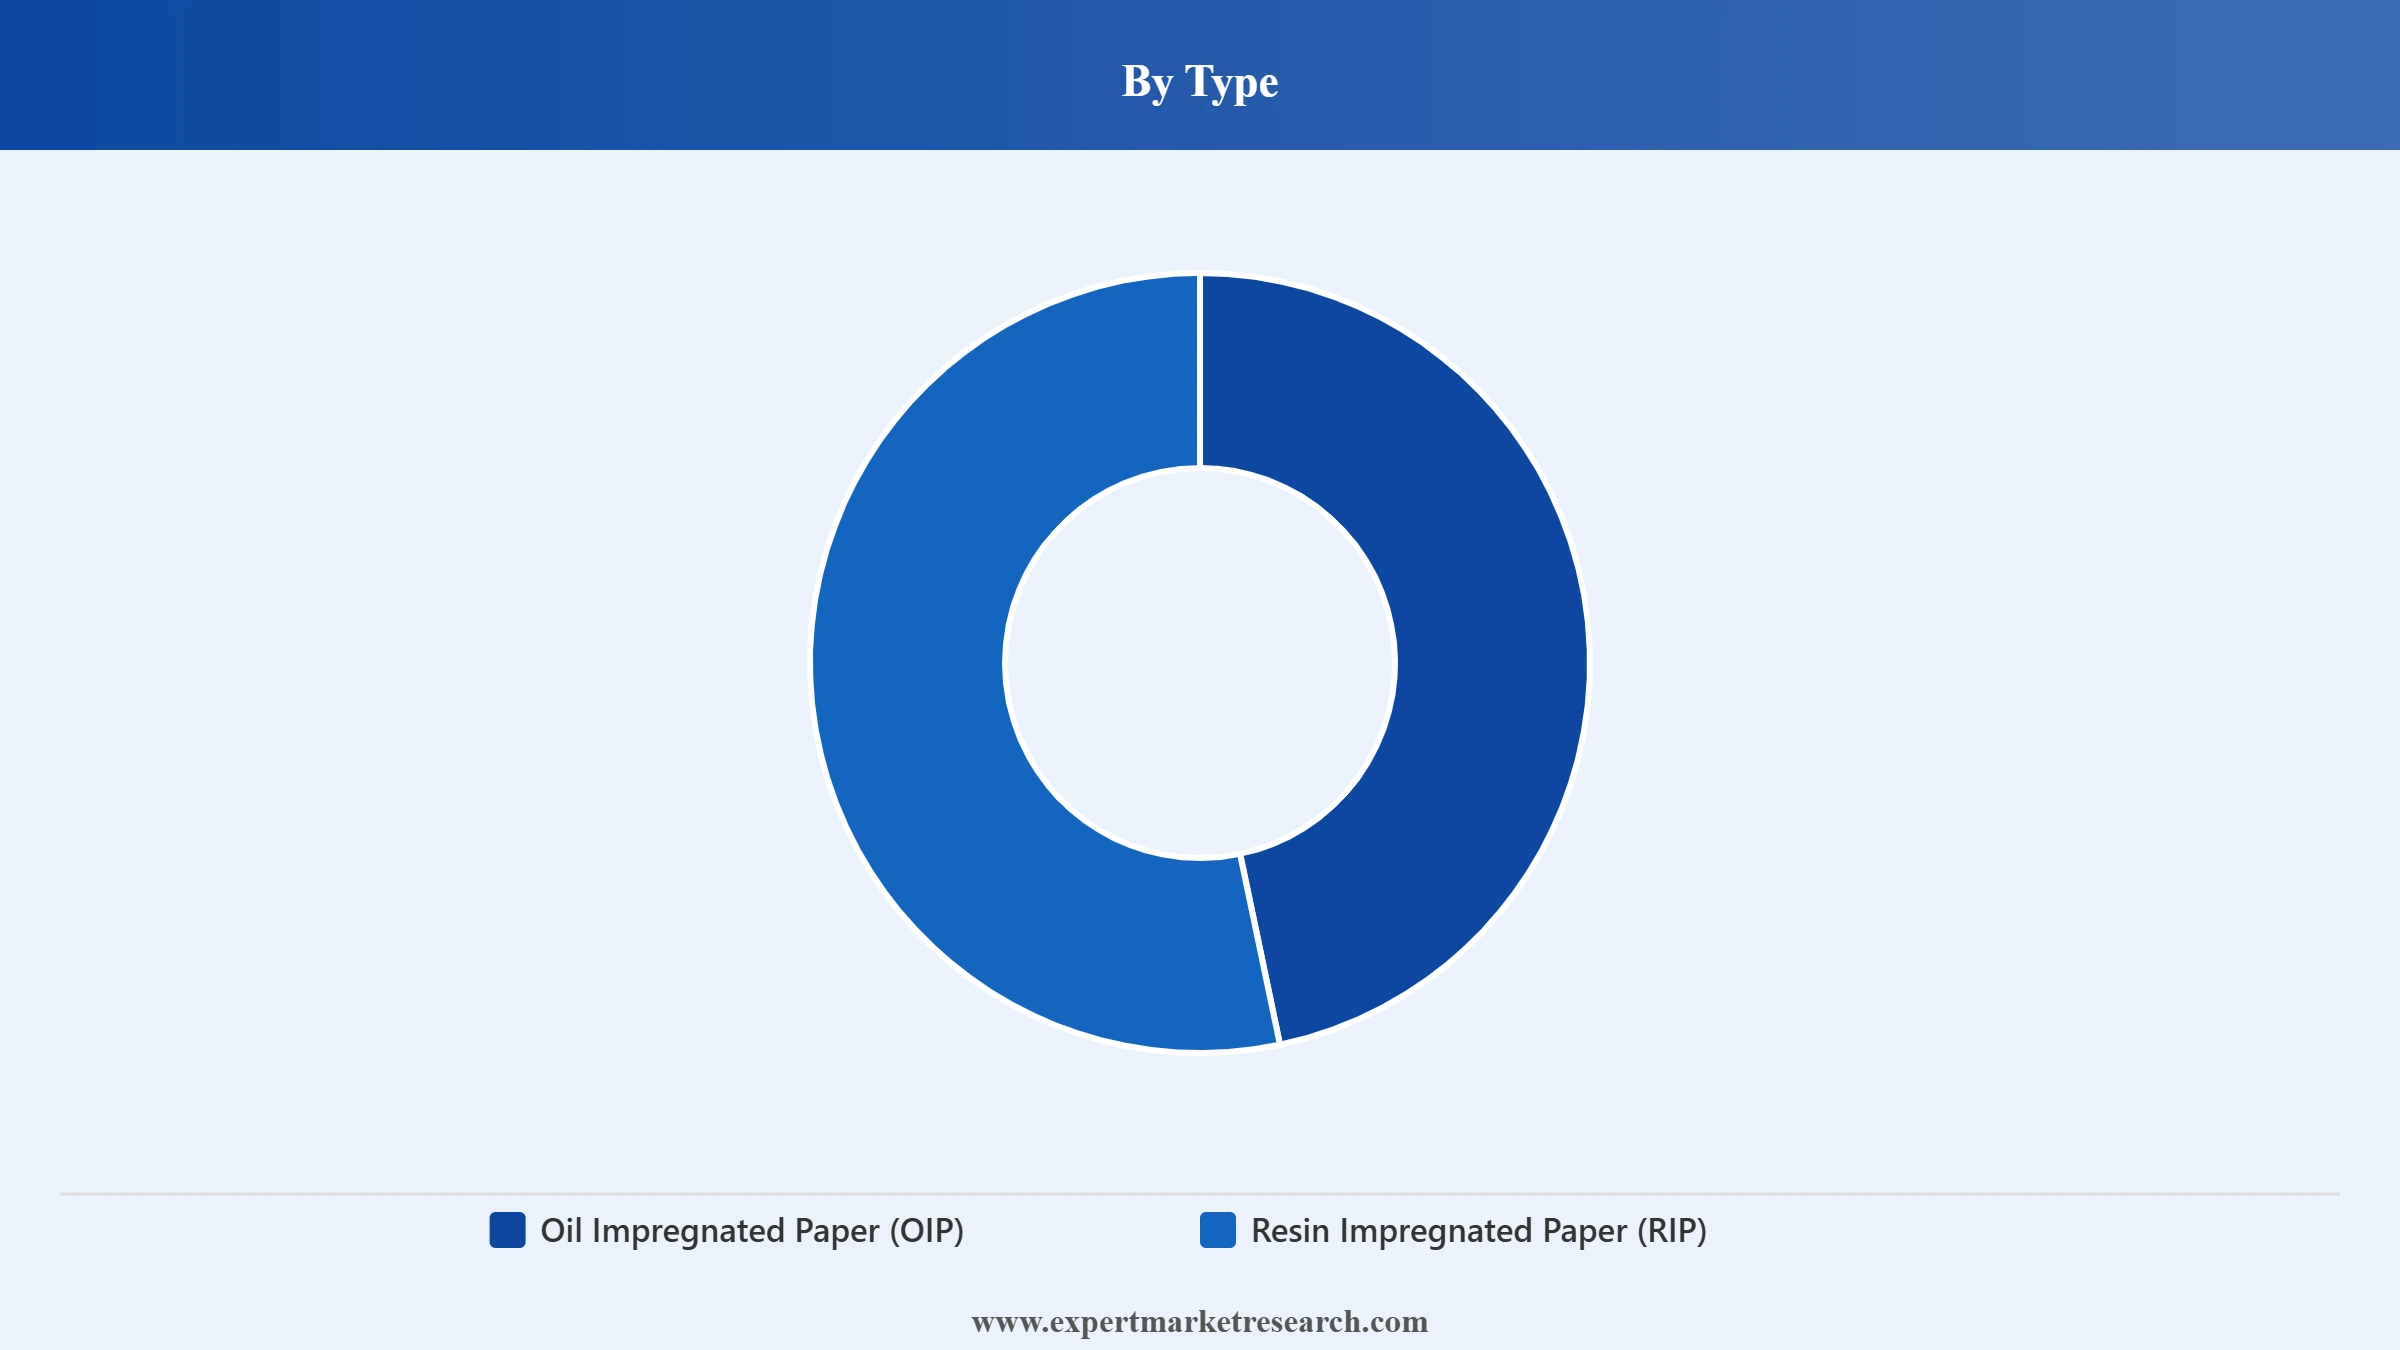
Key Insight: Oil Impregnated Paper accounts for the largest share of the electrical bushing market, reflecting its proven reliability and cost-effectiveness in high-voltage transformer applications. Resin Impregnated Paper is growing at the fastest pace as void-free insulation and superior dielectric strength drive adoption, illustrated by continued manufacturer capacity investment supporting advanced bushing technology development. Other bushing types continue to serve specialised, niche applications rounding out the remaining category. In November 2025, Siemens' 2.3 billion dollar commitment to expand global transformer and switchgear manufacturing included continued investment in advanced resin impregnated paper bushing technology.
Market Breakup by Voltage
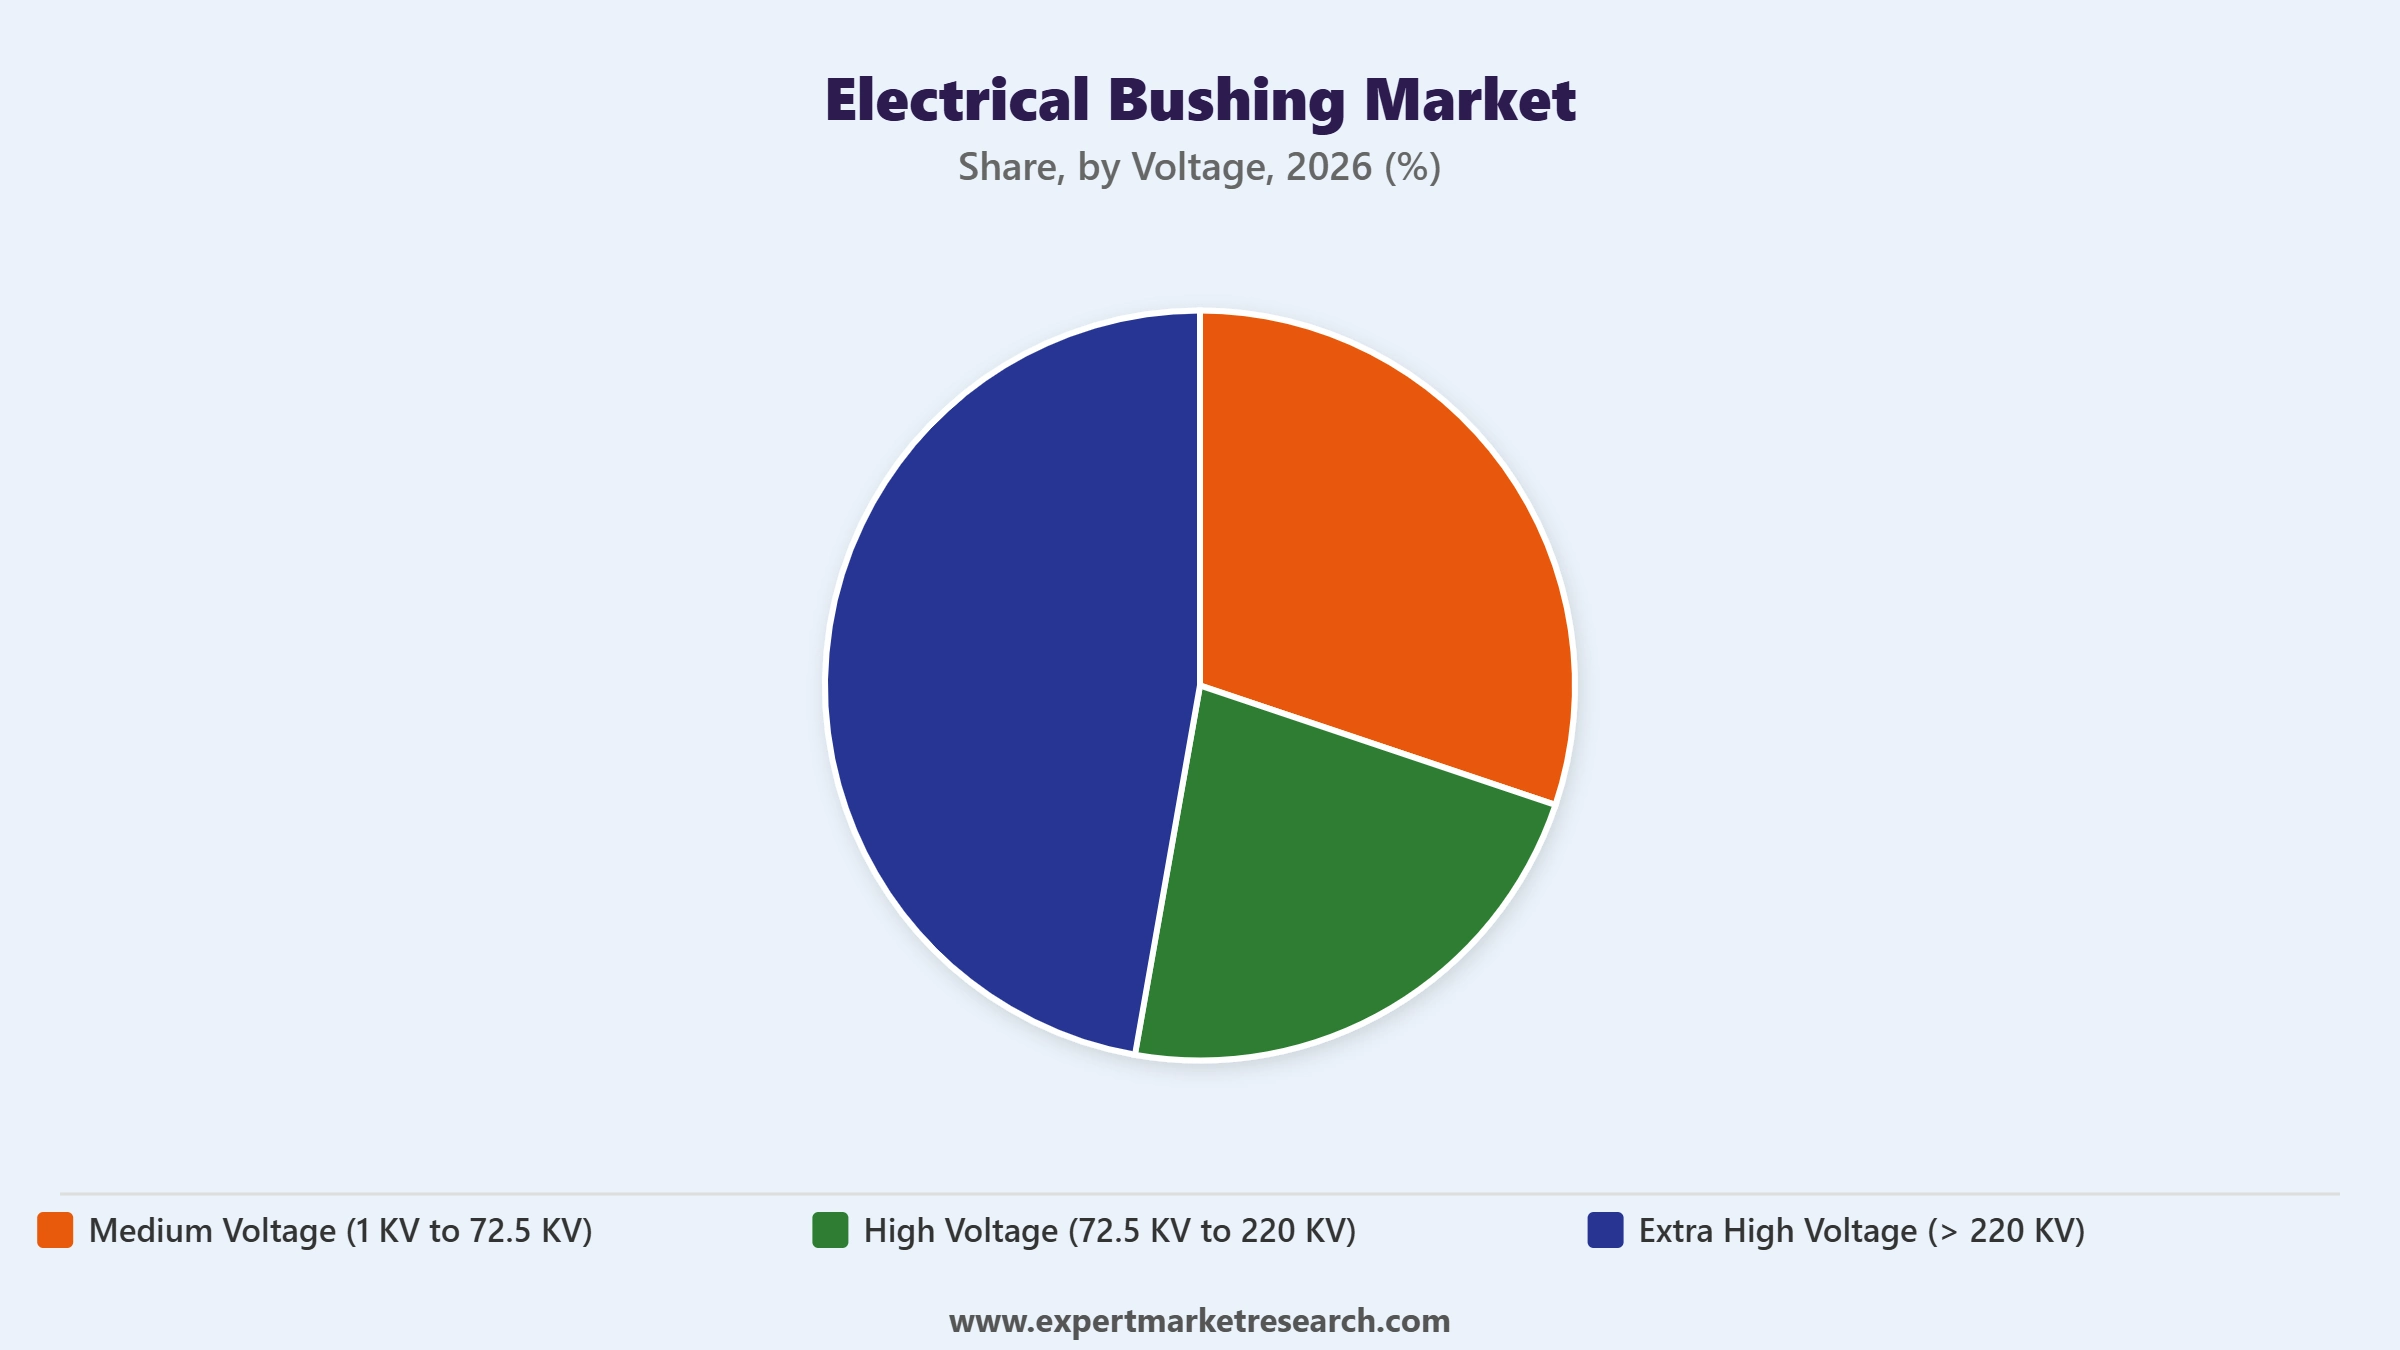
Key Insight: Medium Voltage accounts for the largest share of the electrical bushing market, reflecting extensive distribution network deployment requiring reliable insulation components across utility grids. High Voltage continues to represent substantial and growing demand as transmission infrastructure investment and grid modernisation projects increasingly require components capable of withstanding higher voltage loads. In February 2026, GE's completed acquisition of full ownership in its transformer joint venture reinforced continued investment in high-voltage grid infrastructure components. Extra High Voltage continues to serve a smaller, more specialised category supporting ultra-high-voltage transmission applications above 220 KV.
Market Breakup by Insulation
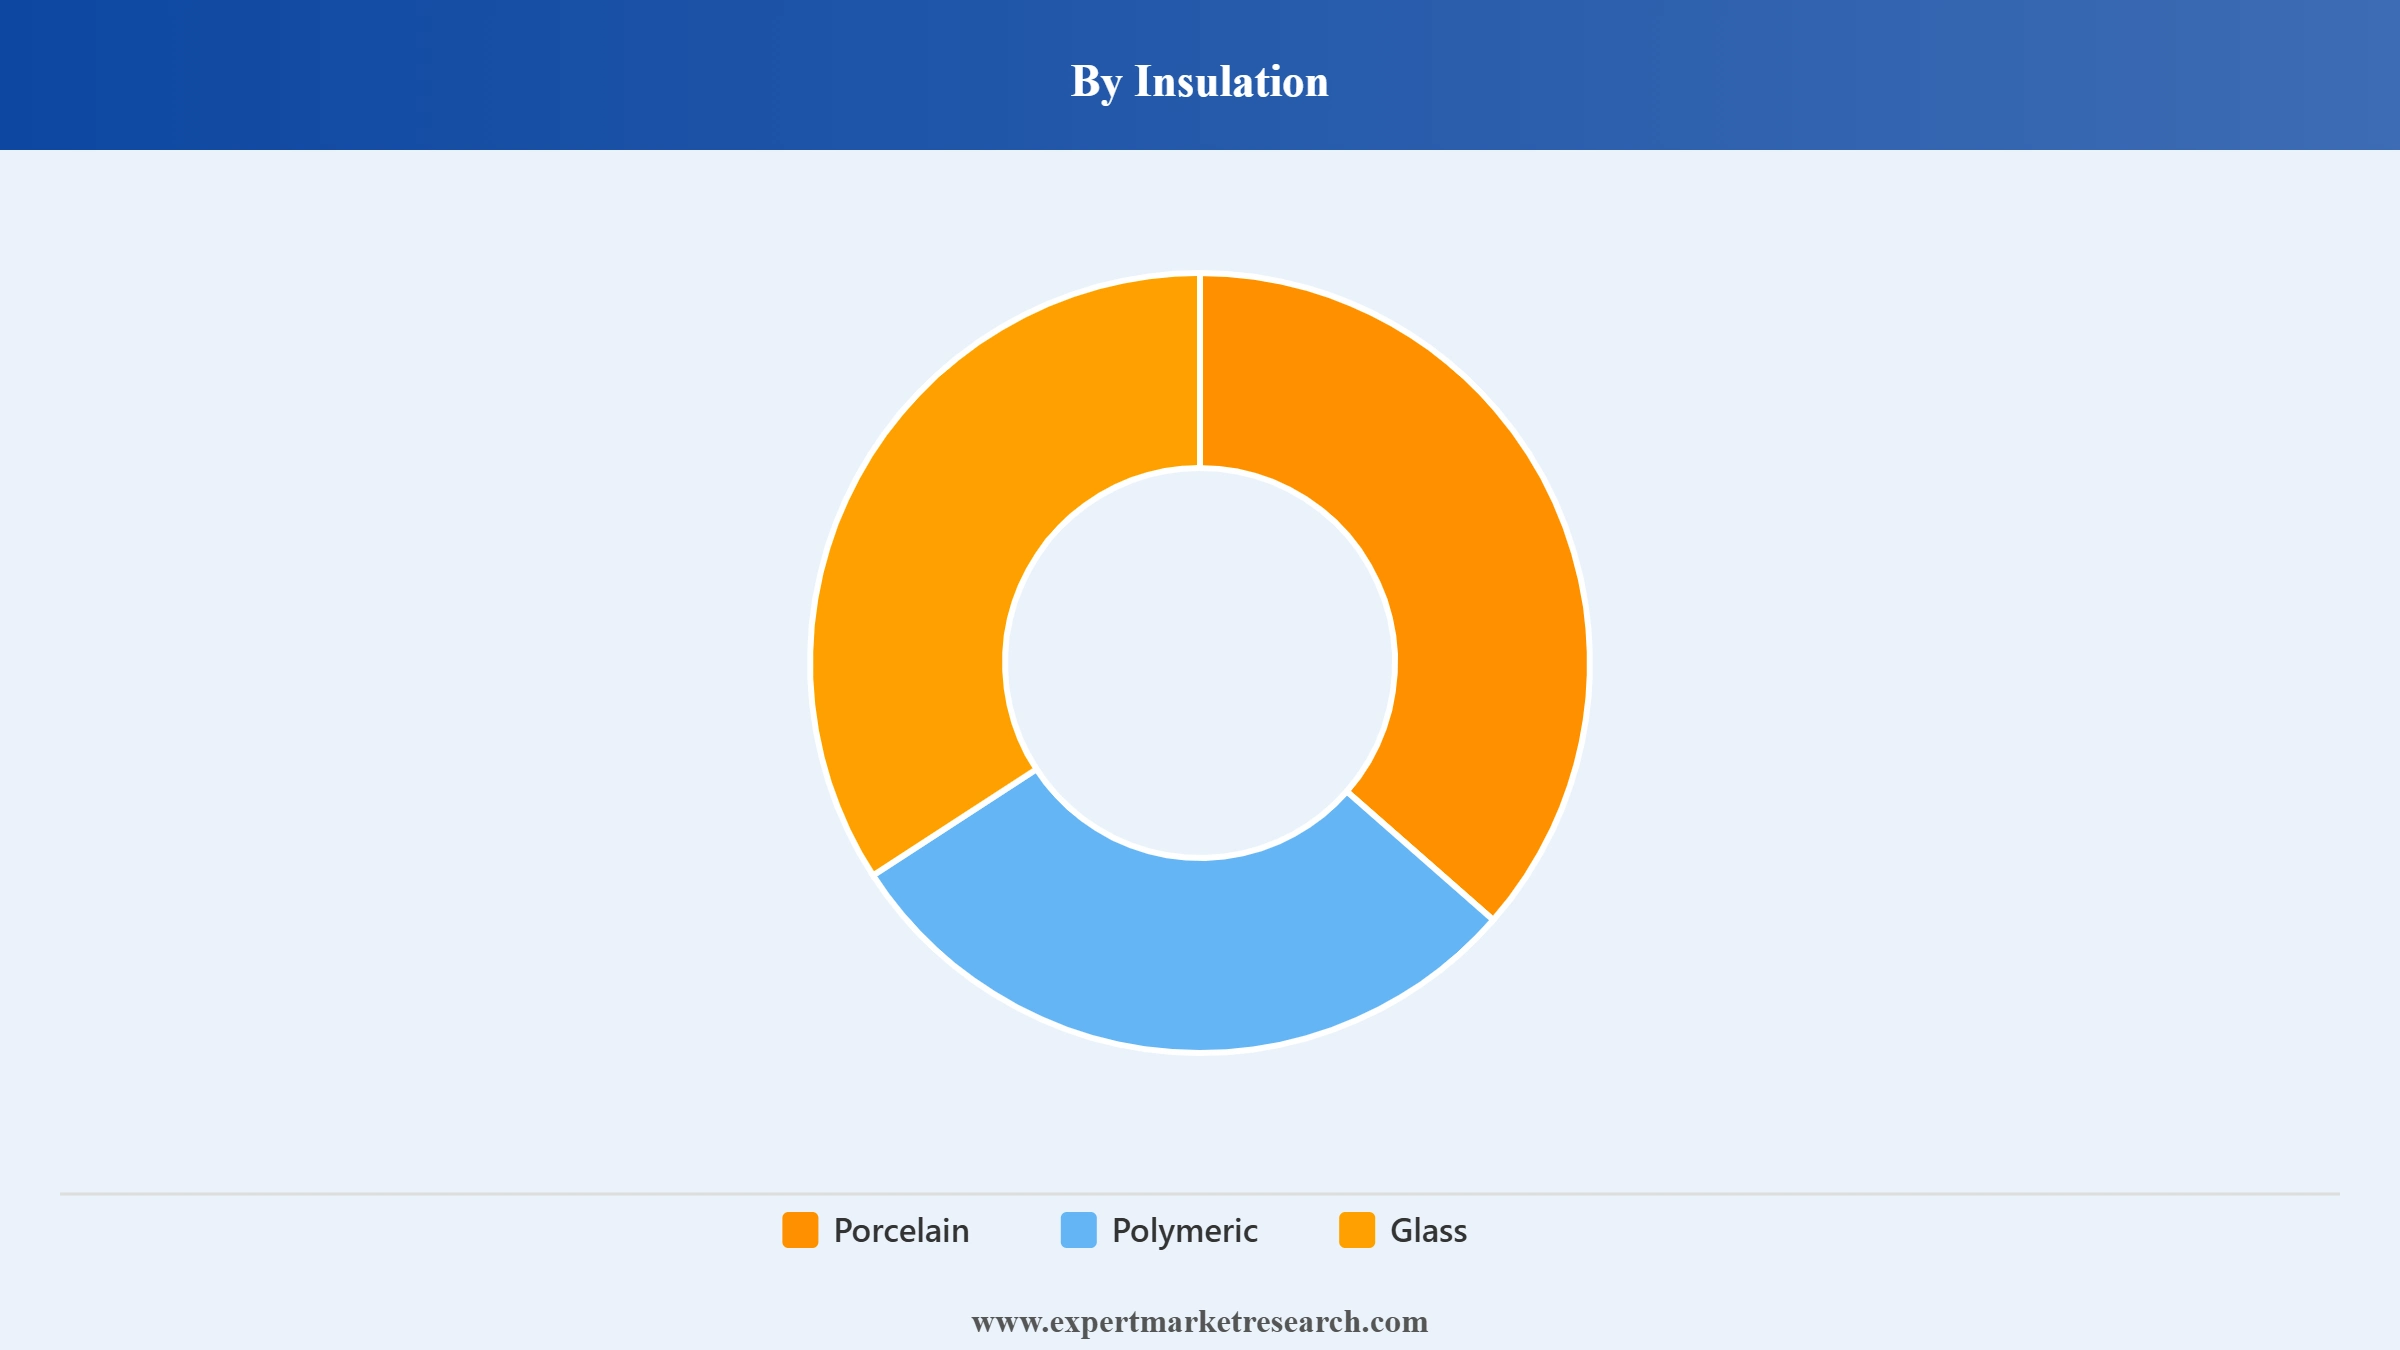
Key Insight: Porcelain accounts for the largest share of the electrical bushing market, reflecting its proven high dielectric strength, thermal stability, and long-term durability in high-voltage applications. Polymeric is growing at a fast pace as lighter, more impact-resistant materials increasingly appeal to manufacturers seeking reduced installation complexity. Glass continues to serve specialised applications requiring specific optical and electrical property combinations. In February 2025, Eaton's establishment of its third US transformer manufacturing facility underscored sustained investment in porcelain and polymeric insulation material sourcing for domestic production.
Market Breakup by Application
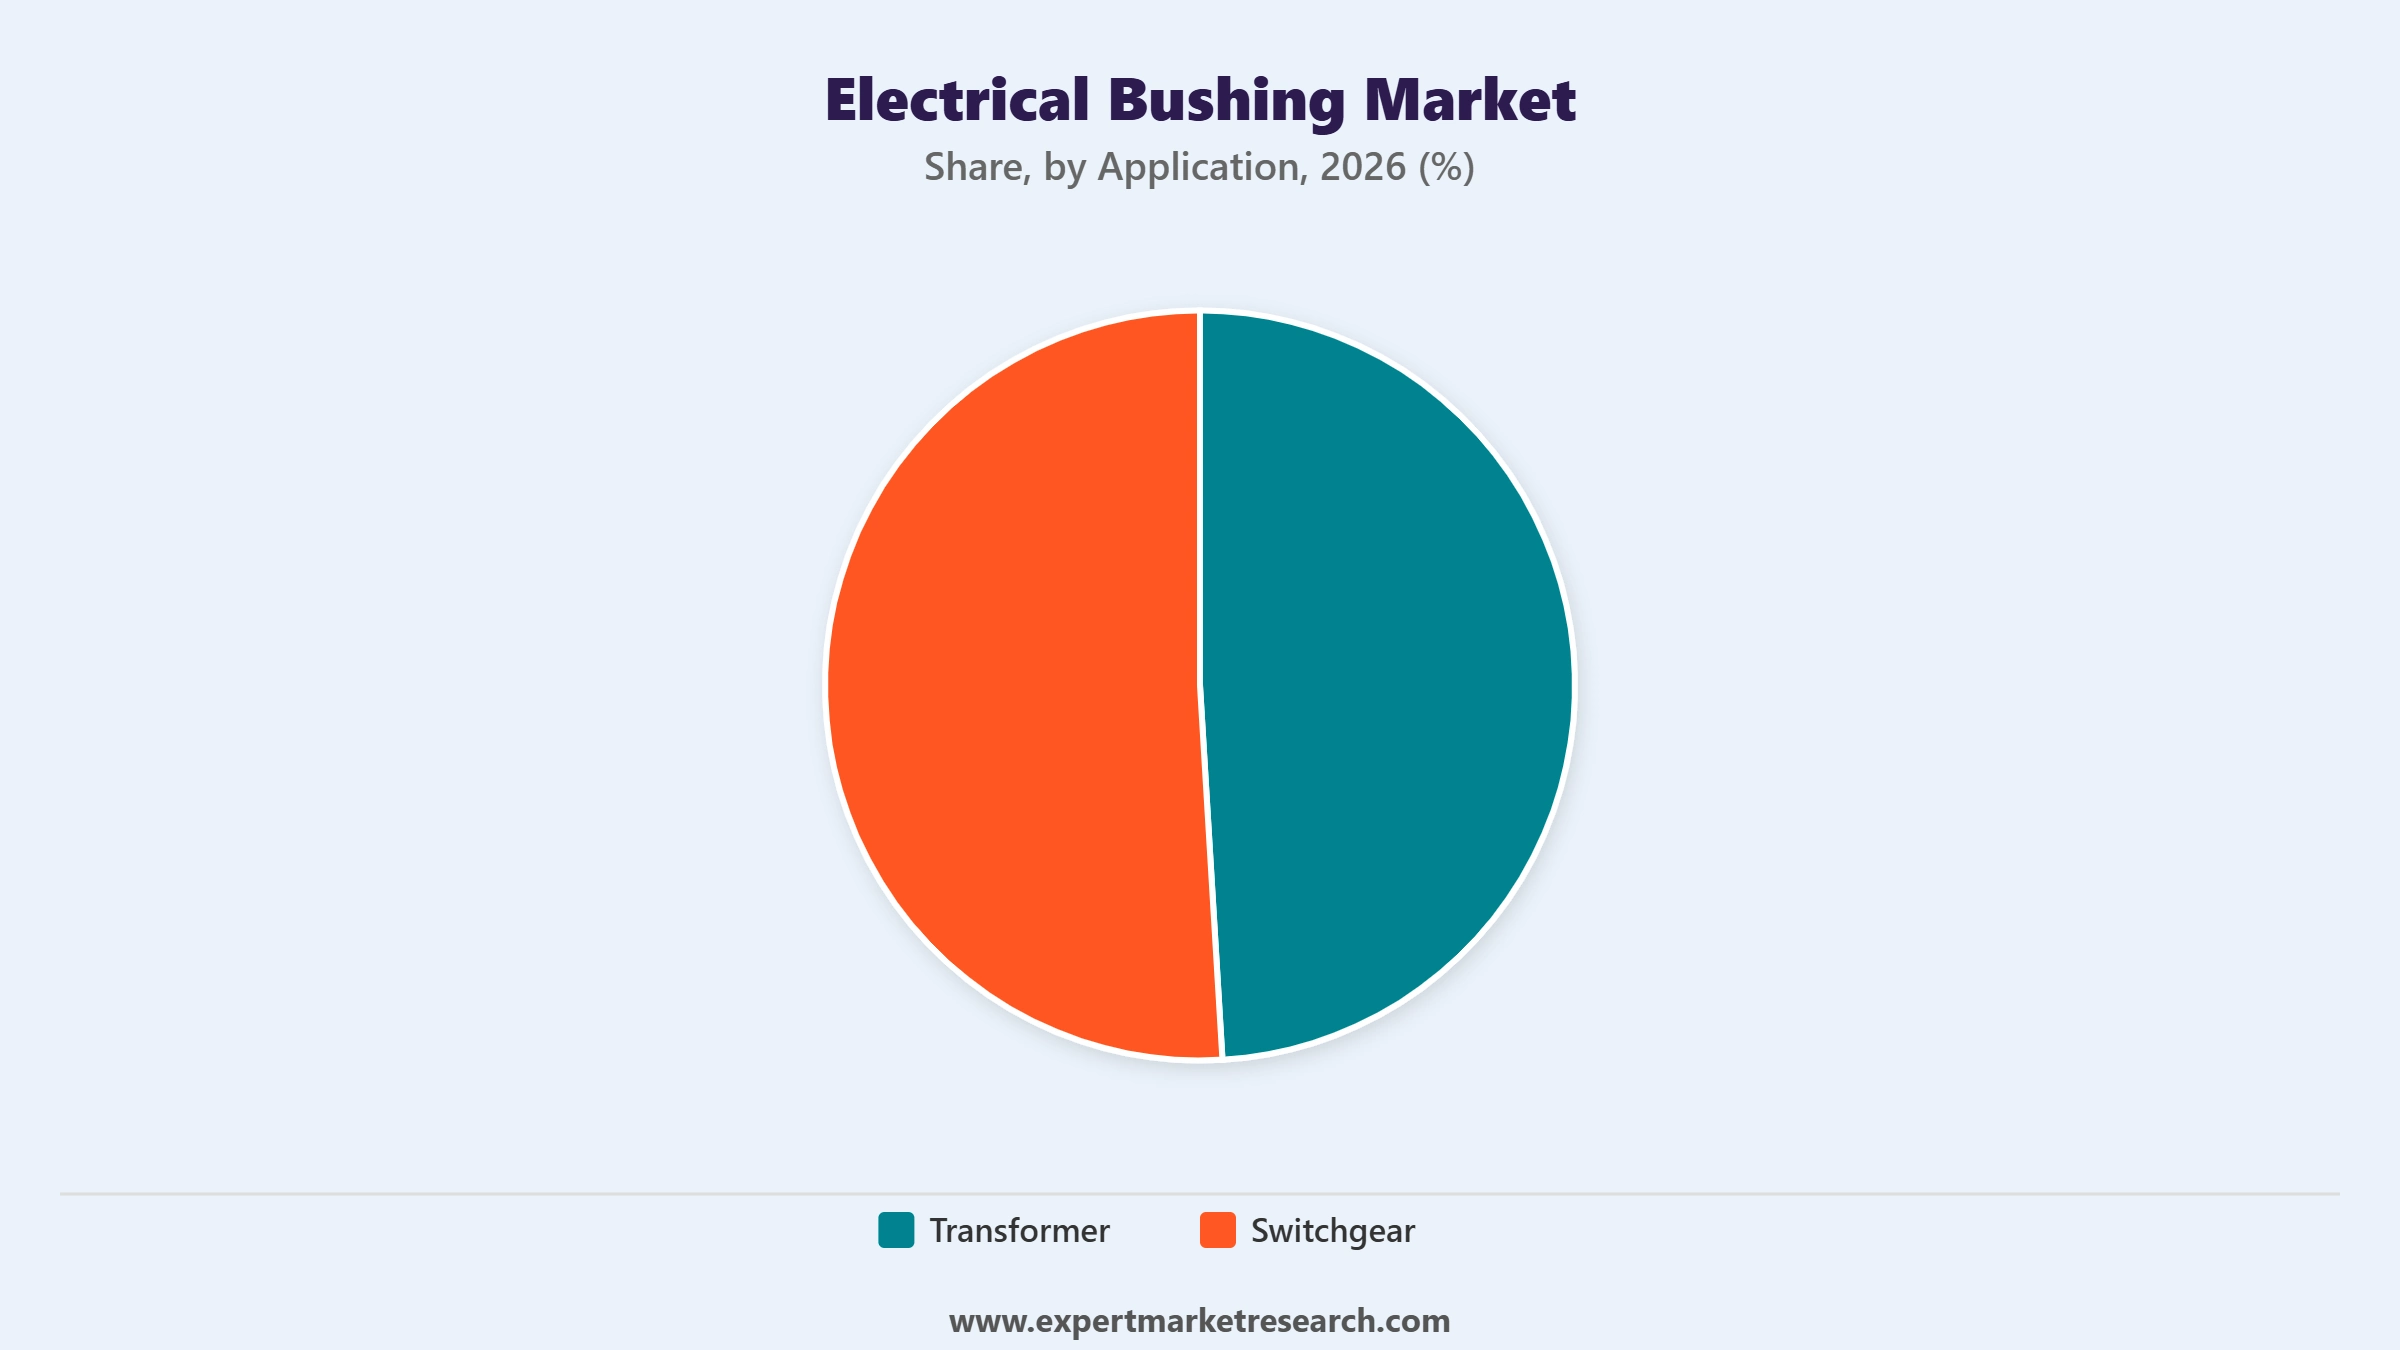
Key Insight: Transformer accounts for the largest share of the electrical bushing market, reflecting sustained demand for reliable insulation components across power generation, transmission, and distribution transformer applications. Switchgear continues to represent substantial demand tied to grid protection and control infrastructure, illustrated by continued manufacturer collaboration on integrated power infrastructure for data centre and industrial customers, with other applications rounding out the remaining category. In June 2025, Eaton and Siemens formed a strategic collaboration integrating transformer and switchgear components for data centre power infrastructure customers.
Market Breakup by Region
Key Insight: Asia Pacific accounts for the largest share of the electrical bushing market, supported by the region's rising electricity demand and substantial grid expansion investment across China, India, and Southeast Asia. North America is emerging as a key growth market as grid modernisation and AI data centre infrastructure investment continue to drive demand. Europe, Latin America, and the Middle East and Africa each continue to serve distinct regional grid infrastructure and regulatory patterns.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By type, oil impregnated paper leads the market while resin impregnated paper grows fastest given superior dielectric performance
Oil Impregnated Paper continues to account for the largest share of the market, reflecting its proven reliability and cost-effectiveness in high-voltage transformer applications. Established oil impregnated paper supply relationships continue to anchor steady demand as manufacturers maintain proven production processes across successive product generations.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Resin Impregnated Paper is growing at the fastest pace across the electrical bushing market as void-free insulation and superior dielectric strength drive adoption, supported by sustained manufacturer capacity investment in advanced bushing manufacturing technology. In February 2026, GE's completed acquisition of full ownership in its Prolec GE transformer joint venture reinforced continued investment in advanced bushing production capability.
By application, transformer leads the market while switchgear grows fastest given expanding grid protection infrastructure demand
Transformer continues to account for the largest share of the market, reflecting sustained demand for reliable insulation components across power generation, transmission, and distribution applications. Established transformer application relationships continue to anchor steady demand as utilities maintain proven suppliers across successive infrastructure investment cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Switchgear is growing at a fast pace across the electrical bushing market as grid protection and control infrastructure investment expands. In June 2025, Eaton and Siemens formed a strategic collaboration integrating switchgear and transformer components for data centre power infrastructure.
By voltage, medium voltage leads the market while high voltage grows fastest given expanding transmission infrastructure
Medium Voltage continues to account for the largest share of the market, reflecting extensive distribution network deployment requiring reliable insulation components across utility grids. Established medium voltage supply relationships continue to anchor steady demand as distribution utilities maintain proven suppliers across successive grid maintenance cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
High Voltage is growing at a fast pace across the electrical bushing market as transmission infrastructure investment expands. In November 2025, Siemens committed 2.3 billion dollars toward expanding global transformer and switchgear manufacturing supporting higher-voltage grid infrastructure.
By insulation, porcelain leads the market while polymeric grows fastest given rising demand for lighter, impact-resistant materials
Porcelain continues to account for the largest share of the market, reflecting its proven high dielectric strength, thermal stability, and long-term durability in high-voltage applications. Established porcelain insulation relationships continue to anchor steady demand as manufacturers maintain proven material sourcing across successive production cycles.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Polymeric is growing at a fast pace across the electrical bushing market as lighter, more impact-resistant materials increasingly appeal to manufacturers seeking reduced installation complexity. In November 2025, Siemens' 2.3 billion dollar grid manufacturing expansion included continued investment in advanced insulation material research supporting next-generation bushing designs.
Asia Pacific commands the largest share of the market through its rising electricity demand
Asia Pacific holds the largest share of the electrical bushing market, supported by the region's rising electricity demand and substantial grid expansion investment across China, India, and Southeast Asia. Regional manufacturers continue to expand production capacity to meet both domestic grid infrastructure demand and rising export volumes to international markets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America is emerging as a key growth market as grid modernisation and AI data centre infrastructure investment continue to drive demand across the region. In February 2026, GE's completed acquisition of full ownership in a major transformer manufacturer reinforced sustained North American investment in domestic electrification supply chains across the wider electrical bushing market.
The global industry is moderately consolidated, with electrical bushing market companies ranging from diversified global electrical equipment groups spanning multiple grid infrastructure categories to specialist bushing manufacturers competing across type, voltage, and application segments. Established players operate across the full electrical bushing value chain, from insulation material sourcing and precision manufacturing through complete component testing and distribution for utility, industrial, and data centre customers.
Competitive dynamics among electrical bushing players are increasingly shaped by the pace of manufacturing capacity expansion, the scale of cross-company infrastructure collaboration, and the race to consolidate joint venture businesses into wholly owned operations. Manufacturers are investing in advanced insulation materials, expanded regional manufacturing footprints, and integrated power infrastructure partnerships to differentiate their offering and secure long-term utility and data centre customer relationships.
Founded in 1892 and headquartered in Boston, Massachusetts, United States, General Electric manufactures electrical bushings and transformer components through its GE Vernova electrification business. In February 2026, the company completed acquisition of the remaining stake in its Prolec GE transformer joint venture, bringing full ownership after a 30-year partnership. General Electric's extensive electrification and grid infrastructure portfolio differentiates its offering from specialist bushing-only manufacturers.
Founded in 1988 and headquartered in Zurich, Switzerland, ABB manufactures electrical bushings as one of the world's largest suppliers, producing OIP and RIP bushings for high-voltage power transformers up to 1,200 kV from its flagship plant in Ludvika, Sweden. The company serves utility and industrial customers requiring high-performance insulation components. ABB's extensive manufacturing scale and over a century of bushing engineering experience differentiate its offering from smaller, regionally focused competitors.
Founded in 1847 and headquartered in Munich, Germany, Siemens manufactures electrical bushings and transformer components through its Siemens Energy business, providing RIP and OIP bushings with advanced field grading technology. In November 2025, the company committed 2.3 billion dollars to expand its global transformer and switchgear manufacturing base by 2028. Siemens' combined digital grid technology and extensive manufacturing investment differentiate its offering from competitors with more limited capital expenditure commitments.
Founded in 1911 and headquartered in Dublin, Ireland, Eaton manufactures electrical bushings and transformer components serving utility, industrial, and data centre customers. In February 2025, the company established its third US three-phase transformer manufacturing facility in South Carolina, and in June 2025 formed a strategic collaboration with Siemens for data centre power infrastructure. Eaton's combined power management and integrated infrastructure partnership capability differentiate its offering from competitors providing standalone components alone.
Other key players in the electrical bushing market include Hitachi Ltd., Hubbell Inc., CG Power and Industrial Solutions Ltd., GIPRO GmbH, Webster-Wilkinson Ltd., RHM International, LLC, and POLYCAST International, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our electrical bushing market trends 2026 report. Discover regional growth patterns, type and voltage trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market reached a value of nearly USD 3.34 Billion in 2025.
The market is estimated to grow at a CAGR of 4.30% in the forecast period of 2026 and 2035.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach a value of around USD 5.09 Billion by 2035.
Expanding dedicated regional transformer manufacturing capacity to address supply shortages, consolidating joint venture businesses into wholly owned operations, and forming cross-company collaborations to deliver integrated power infrastructure for data centre and AI campus customers.
The key trends in the market include the technological advancements including development of non-metallic split bushings, split grounding bushings, and cable bushings, among others, and the expansion of power infrastructure due to rising urbanisation and digitalisation.
The different types of electrical bushings include oil impregnated paper (OIP), and resin impregnated paper (RIP), among others.
The applications of electrical bushing include transformer and switchgear, among others.
General Electric Company, ABB Ltd., Siemens AG, Hitachi Ltd., Hubbell Inc., CG Power and Industrial Solutions Ltd., Eaton Corporation Plc, GIPRO GmbH, Webster-Wilkinson Ltd., RHM International, LLC, and POLYCAST International, among others, are the key market players.
Manufacturers face persistent global transformer supply shortages affecting delivery timelines, raw material price volatility for insulation materials, and intensifying competition to expand manufacturing capacity fast enough to meet accelerating grid modernisation and data centre infrastructure demand.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Voltage |
|
| Breakup by Insulation |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




